CA Final Group 2: ICAI Model Test Papers
Question Paper with Suggested Answers
Inside This Paper
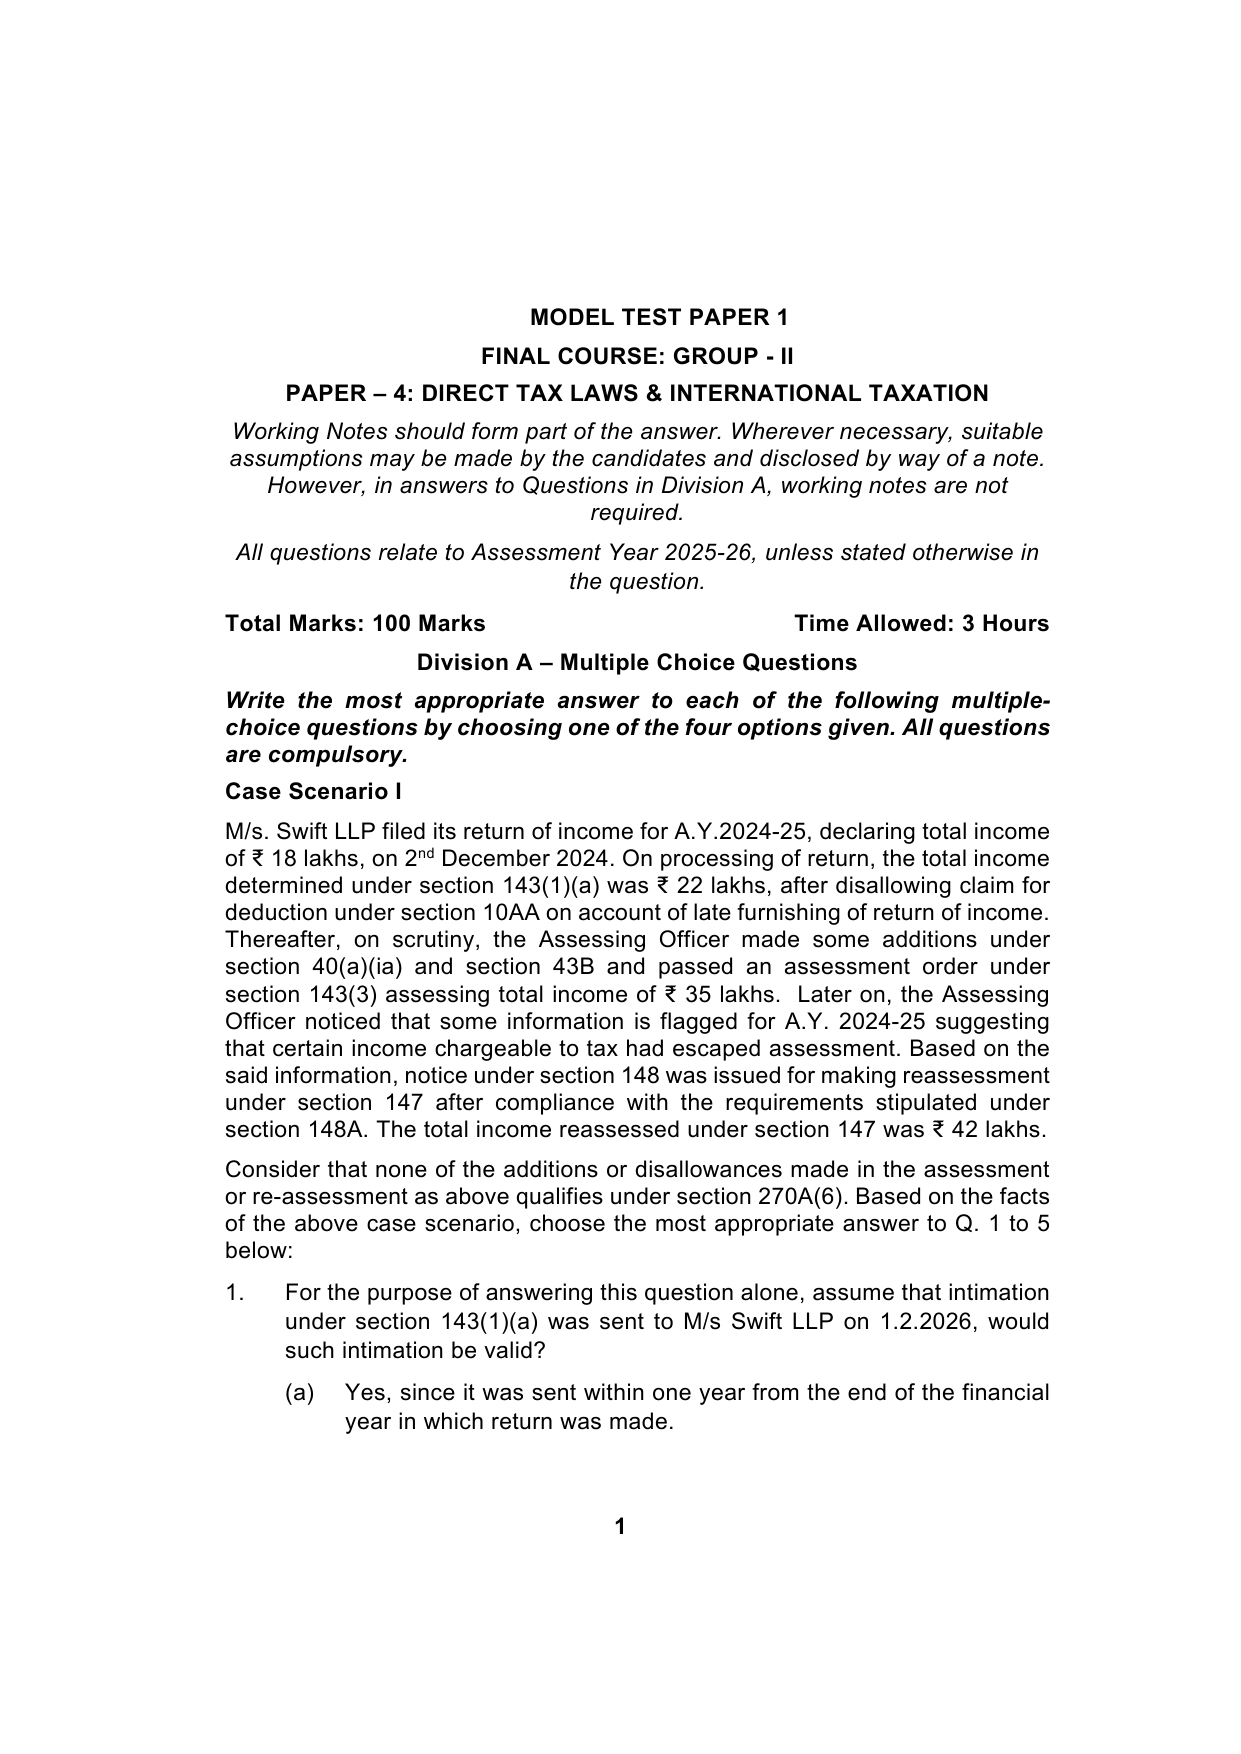
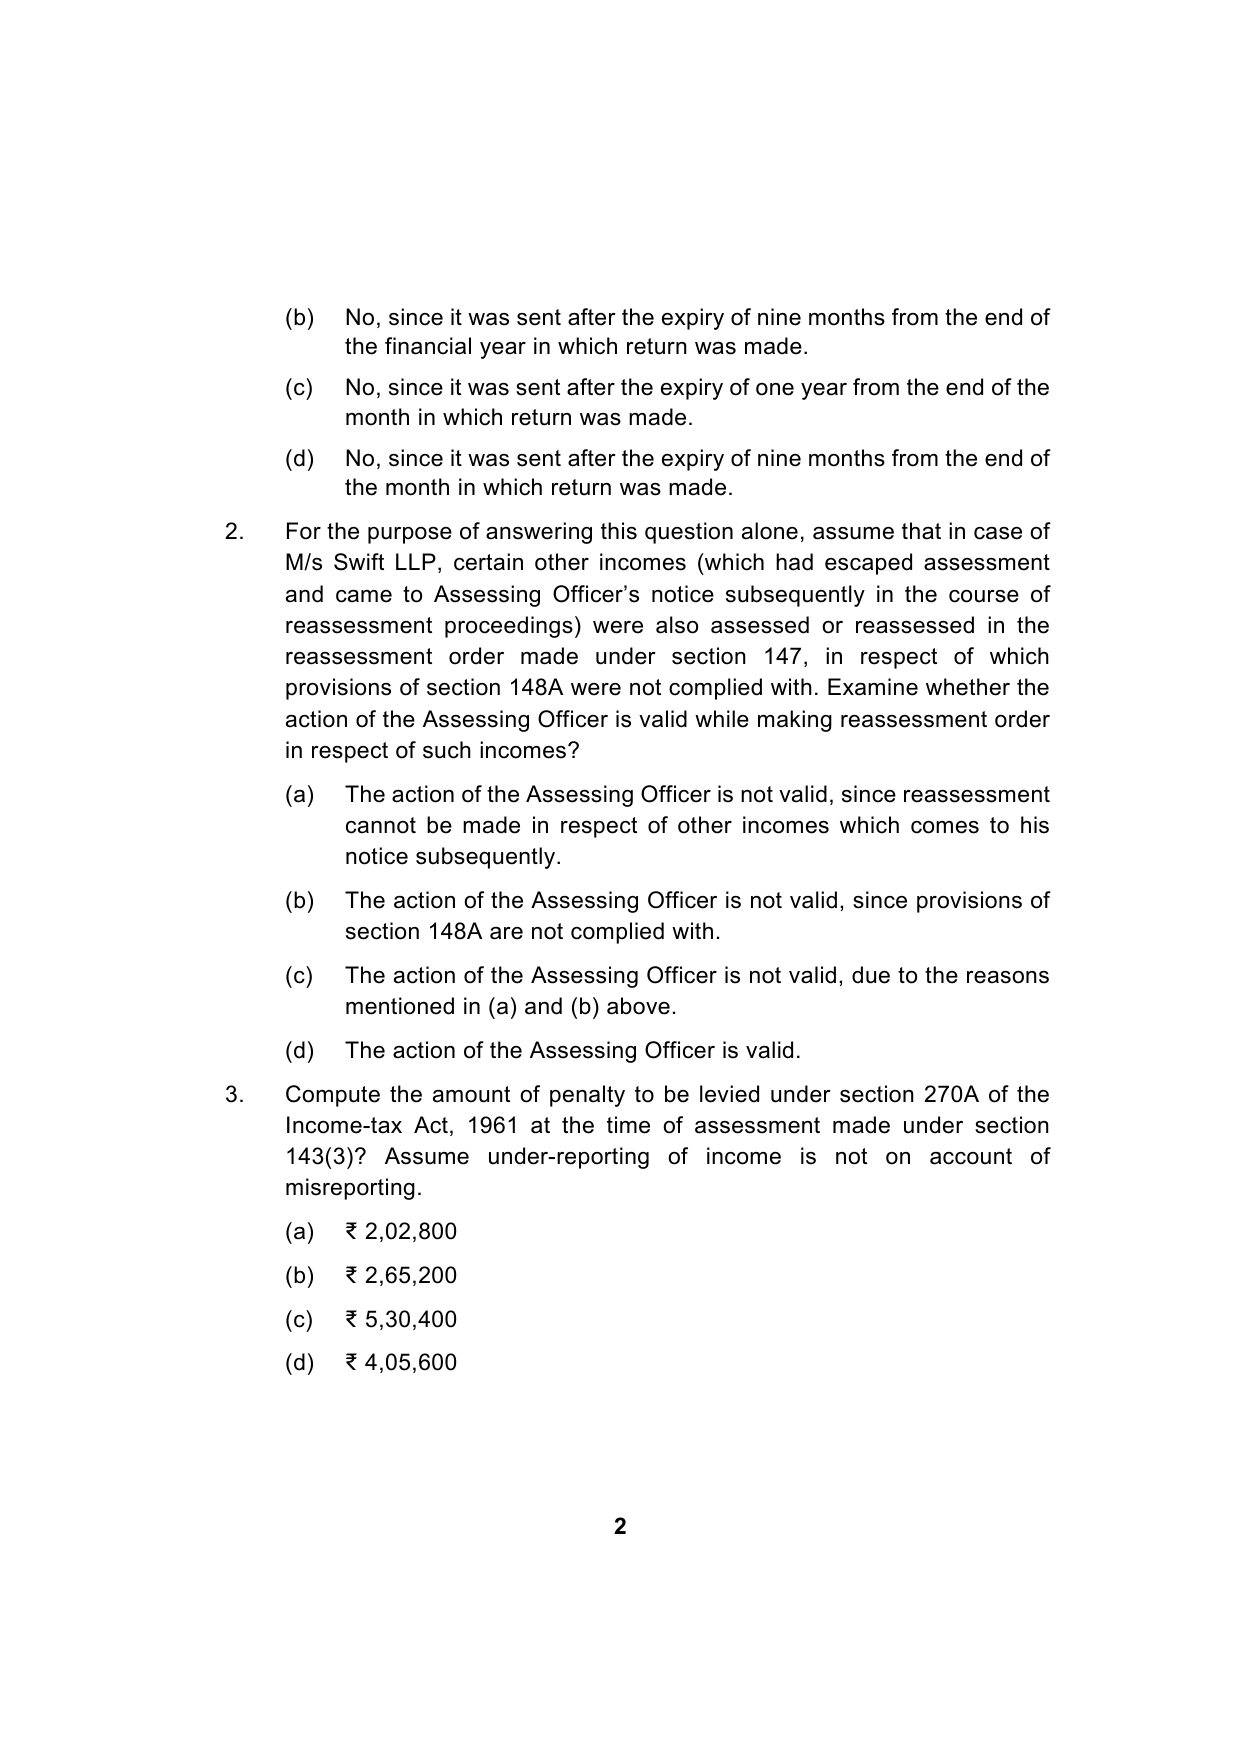
Case Scenario I M/s. Swift LLP filed its return of income for A.Y.2024-25, declaring total income of ₹ 18 lakhs, on 2nd December 2024. On processing of return, the total income determined under section 143(1)(a) was ₹ 22 lakhs, after disallowing claim for deduction under section 10AA on account of late furnishing of return of income. Thereafter, on scrutiny, the Assessing Officer made some additions under section 40(a)(ia) and section 43B and passed an assessment order under section 143(3) assessing…
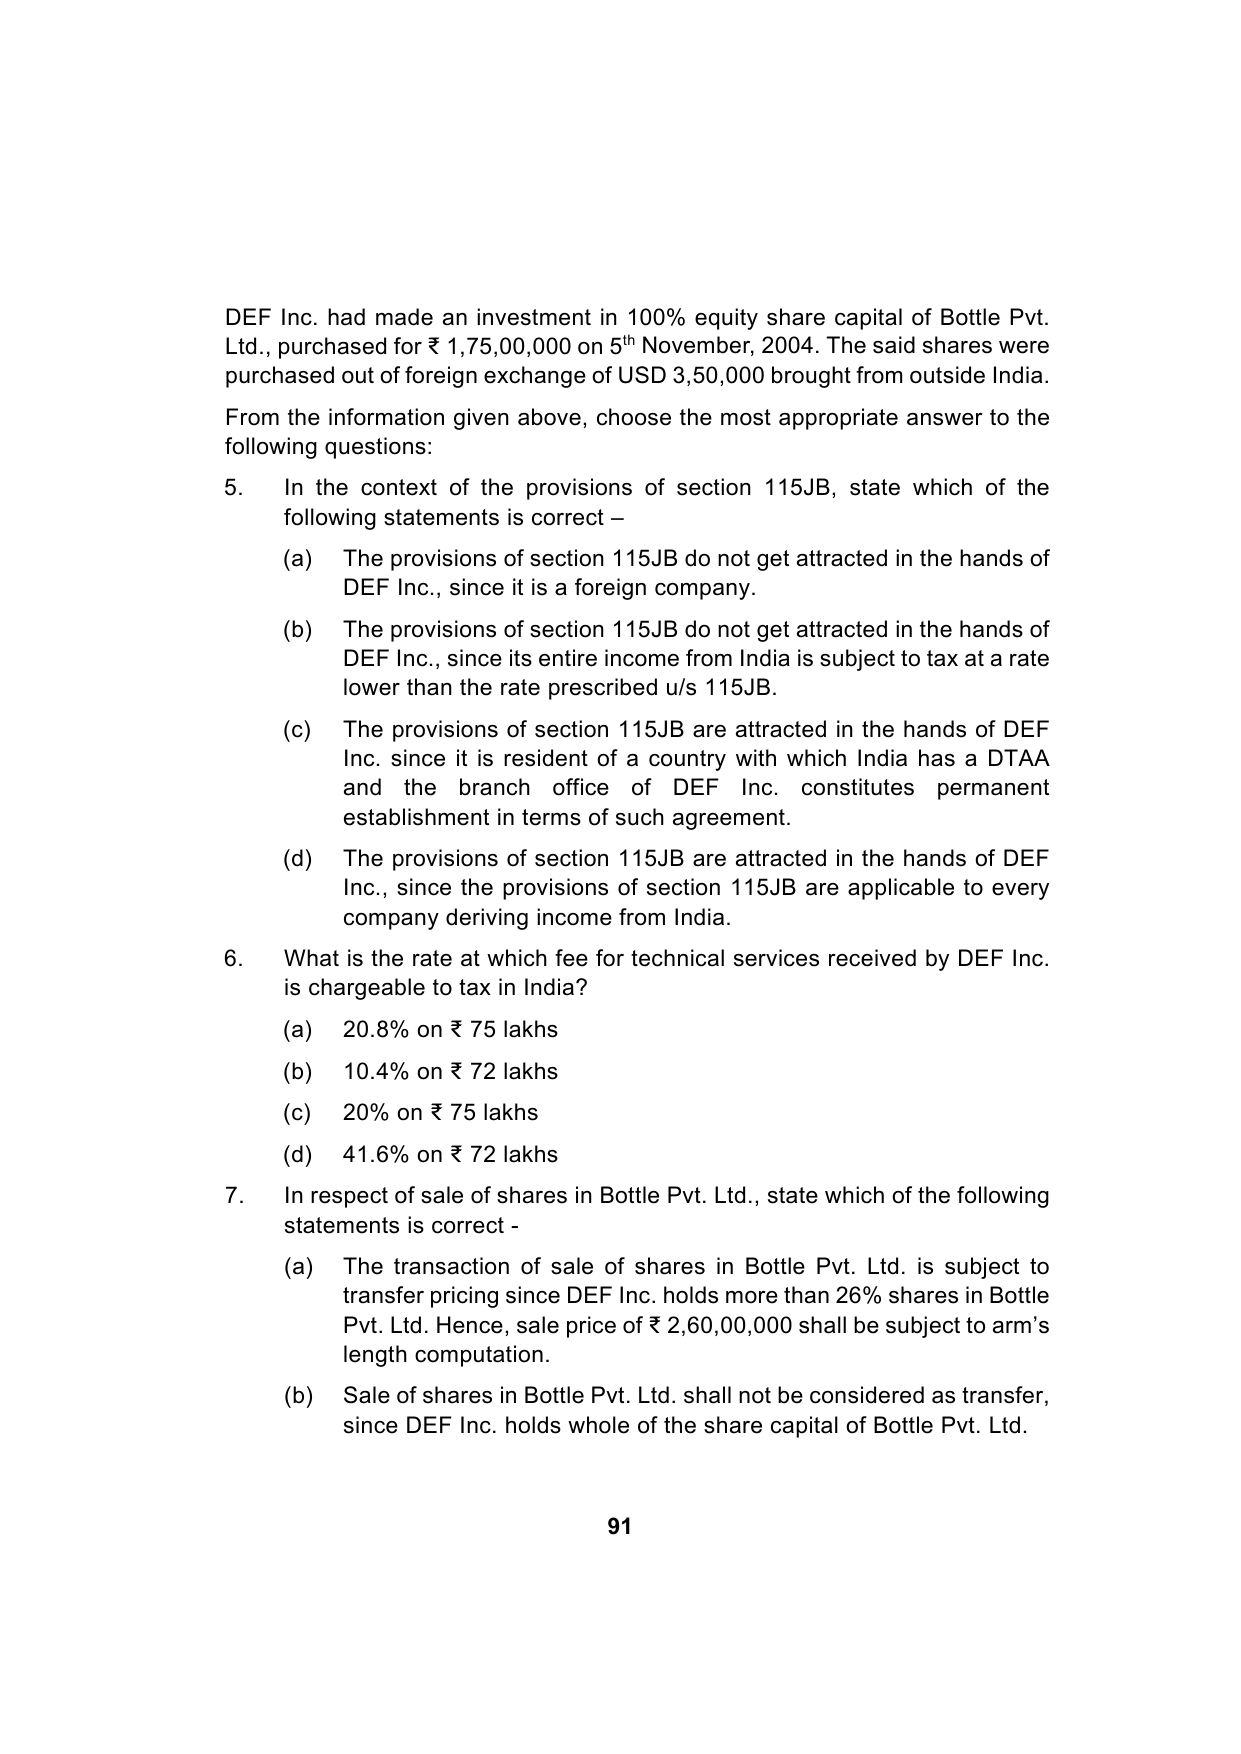
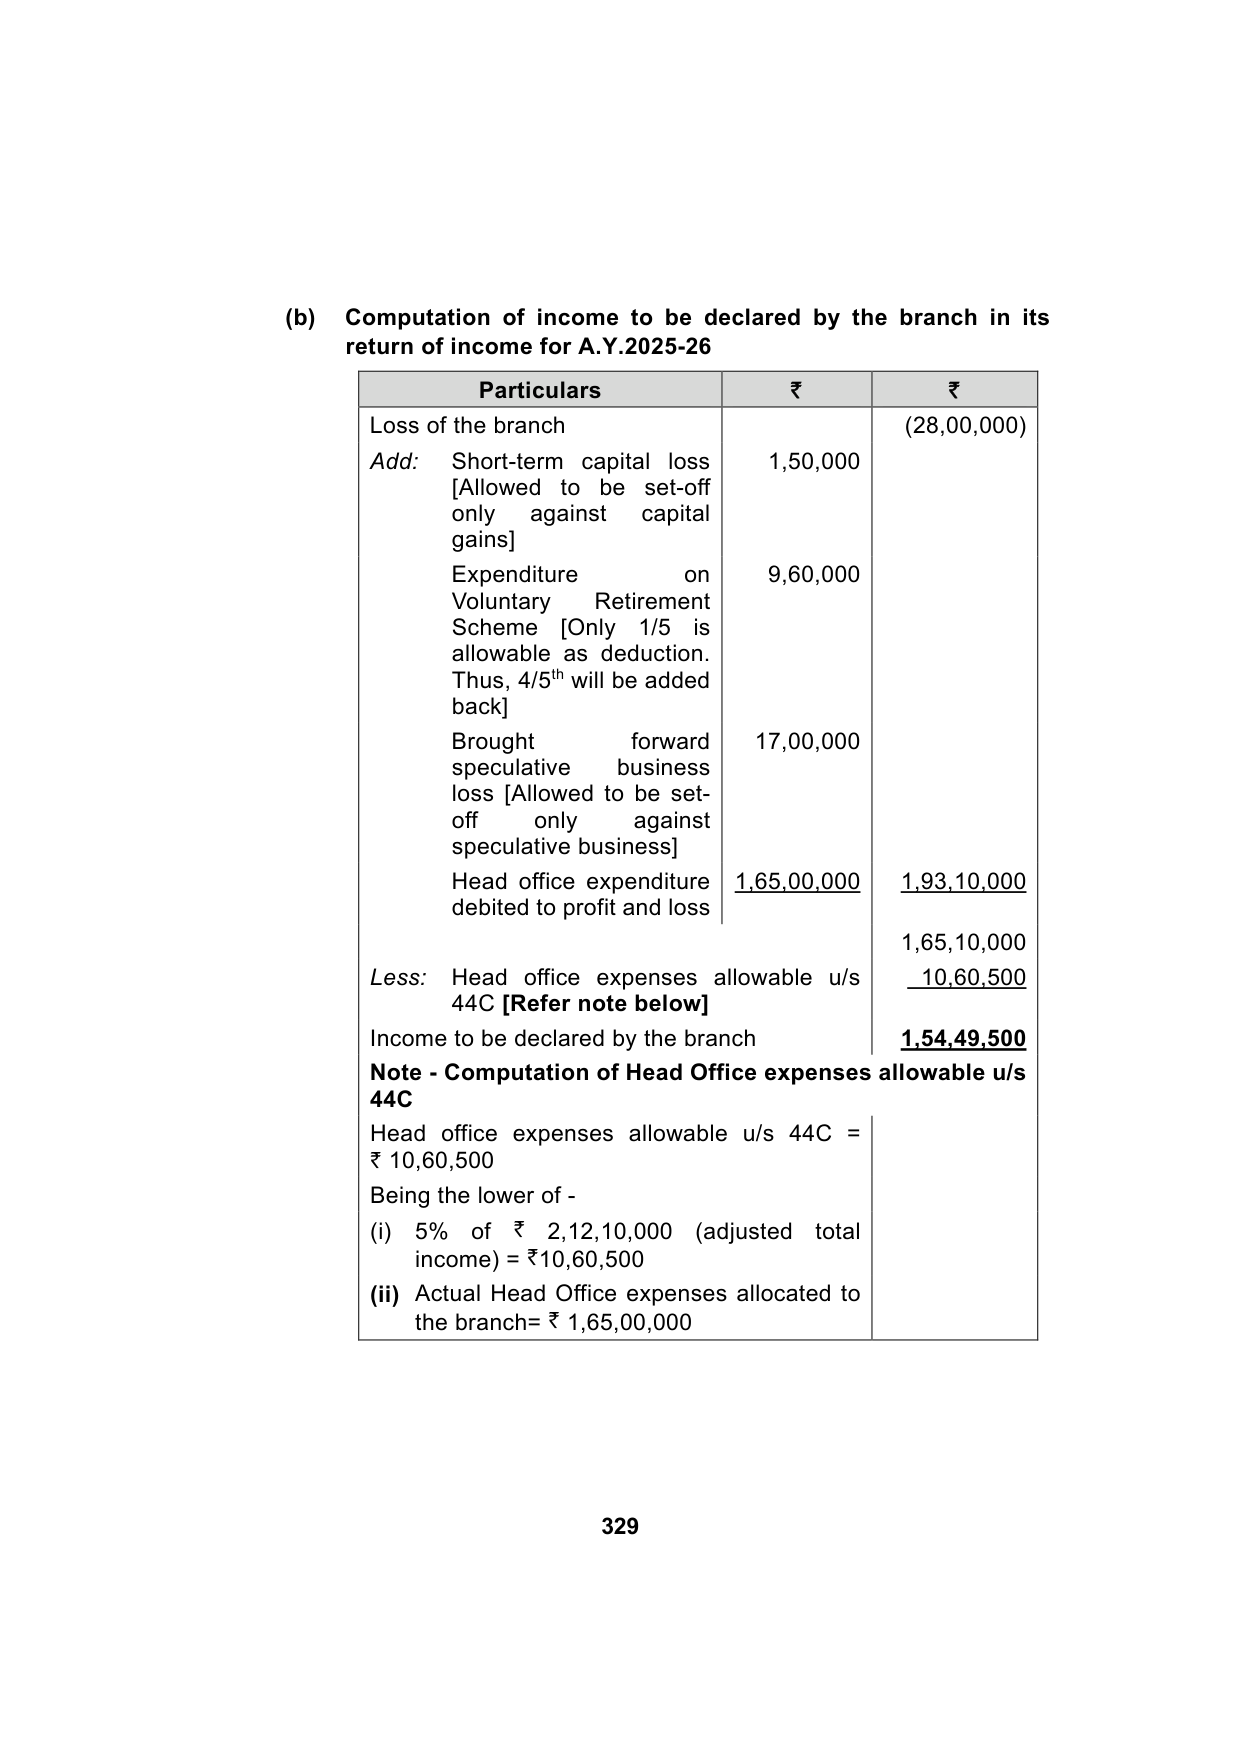
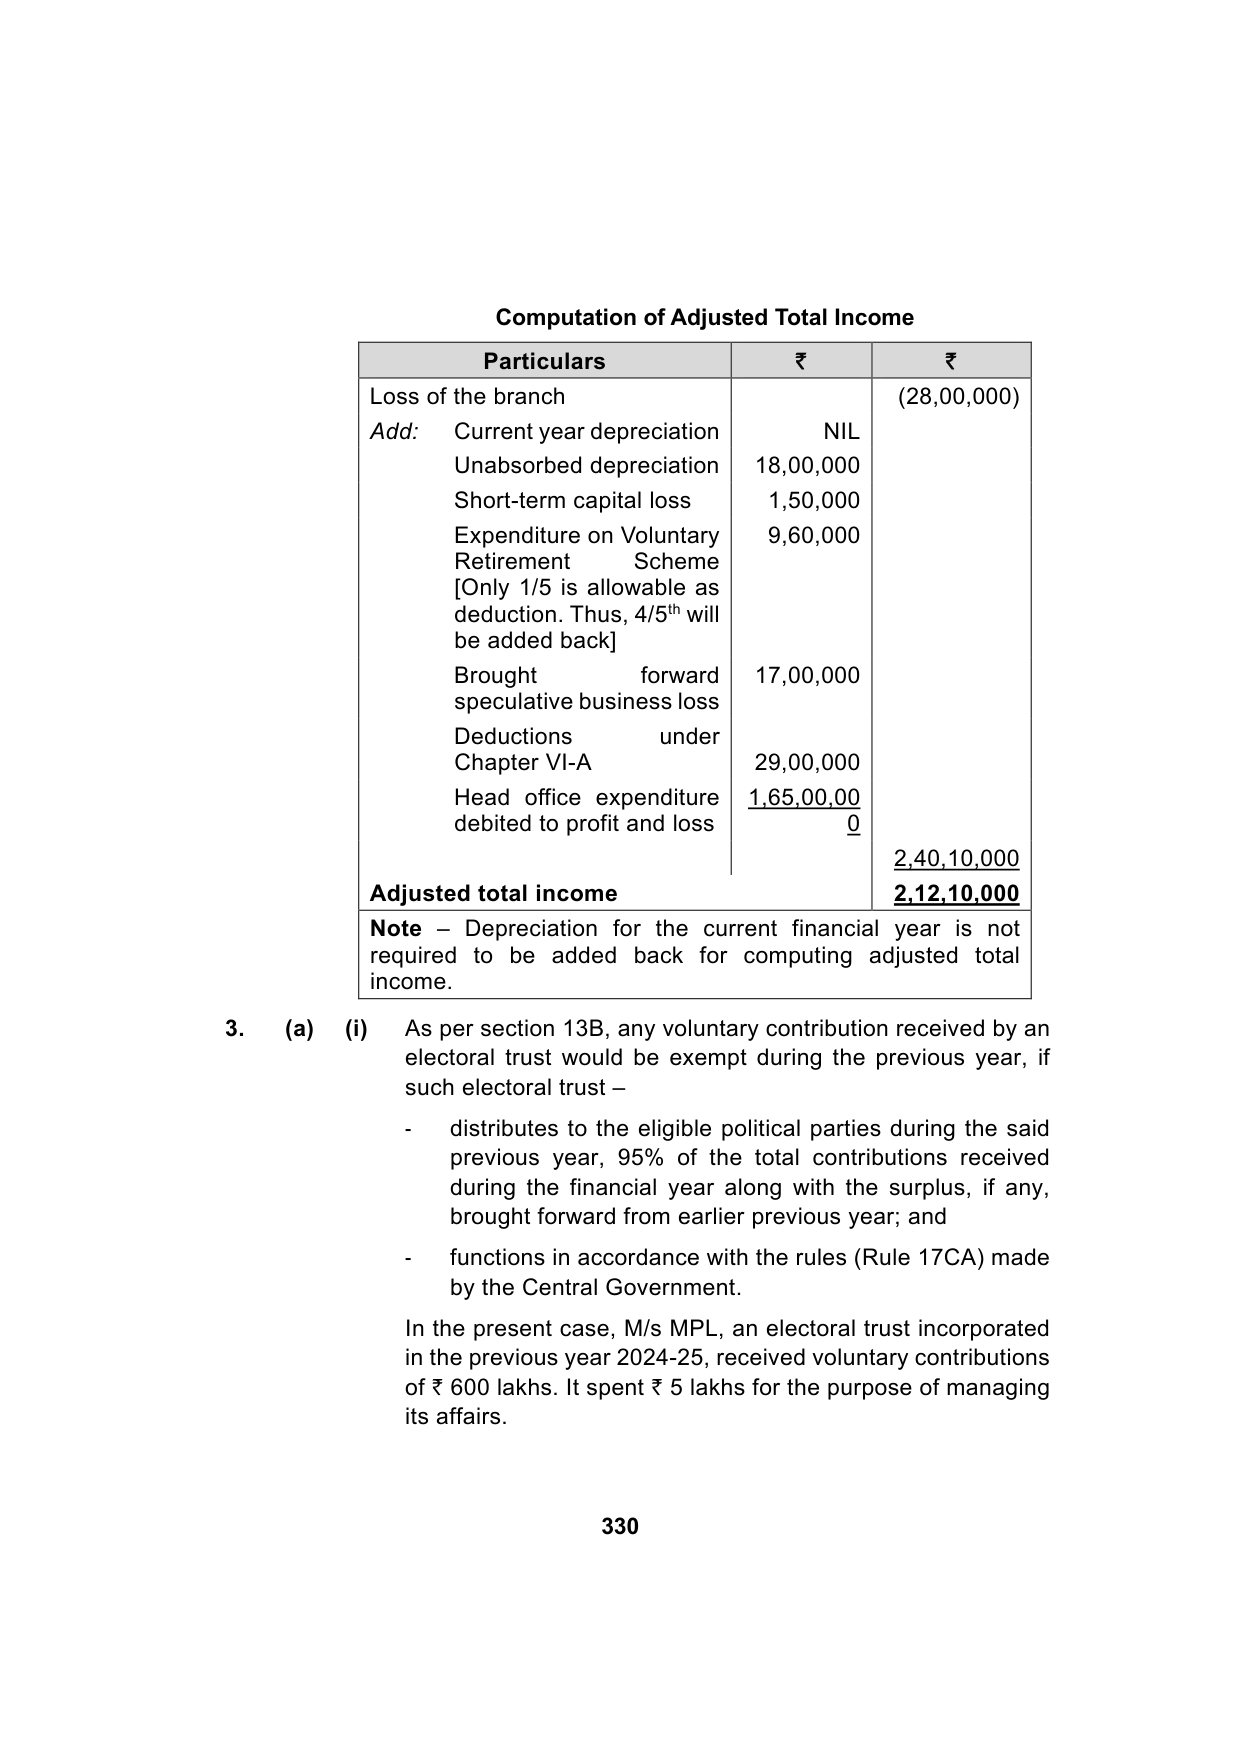
Case Scenario I Falcon Ltd of Country X is an associated enterprise of Max Inc. of USA. Falcon Ltd. has a branch in India since 2010. It was selling goods to Indian customers by importing from various countries besides sale in India of goods manufactured by it in Country X. The adjusted total income of the Indian branch of Falcon Ltd for the year ended 31st March, 2025 is ₹80 lakhs. The branch incurred ₹12 lakhs by way of executive…
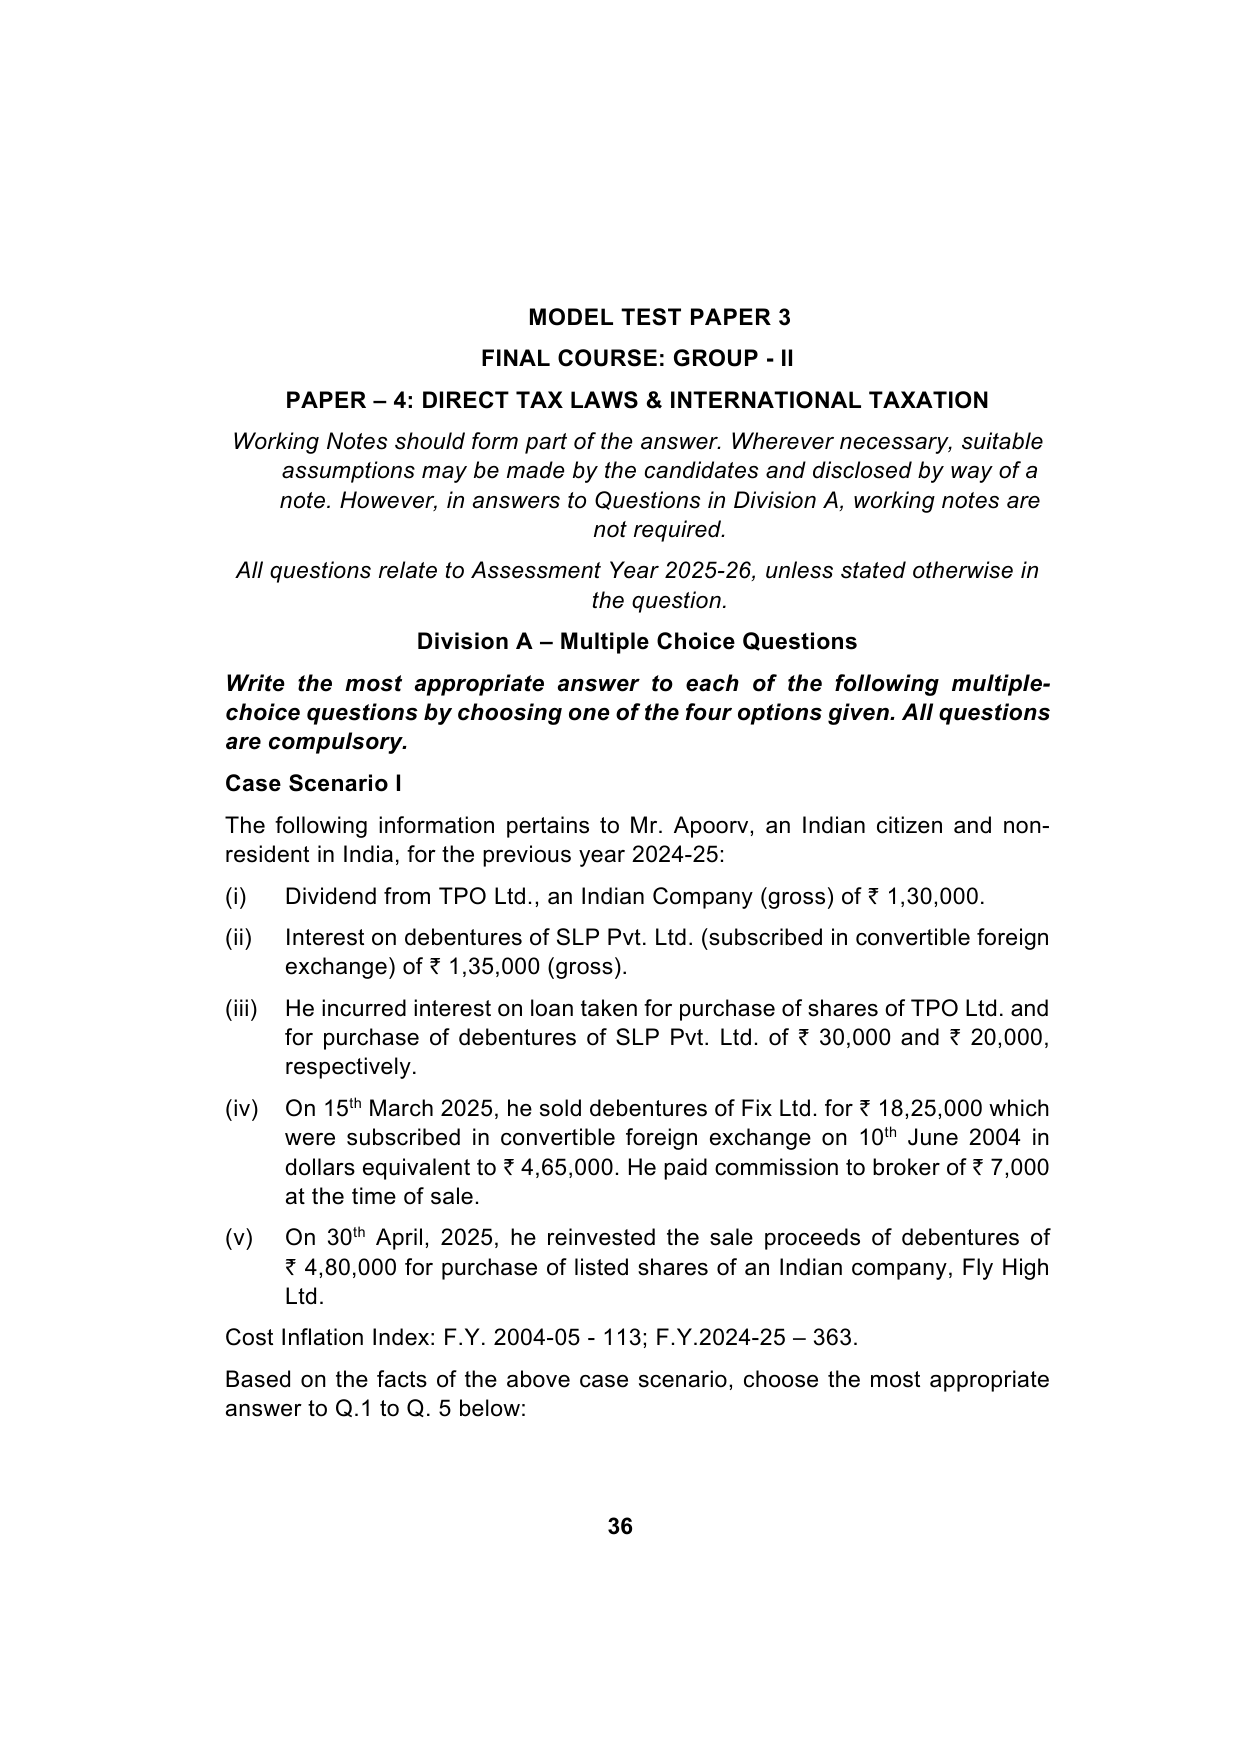
Case Scenario I The following information pertains to Mr. Apoorv, an Indian citizen and non- resident in India, for the previous year 2024-25: (i) Dividend from TPO Ltd., an Indian Company (gross) of ₹1,30,000. (ii) Interest on debentures of SLP Pvt. Ltd. (subscribed in convertible foreign exchange) of ₹1,35,000 (gross). (iii) He incurred interest on loan taken for purchase of shares of TPO Ltd. and for purchase of debentures of SLP Pvt. Ltd. of ₹30,000 and ₹20,000, respectively. (iv) On…
Case Scenario I On 1.4.2024, Focus Ltd., an Indian company, borrowed ₹50 crores@ 9.5% p.a. from Max Inc., a US entity, thereby increasing its total borrowings to ₹65 crores. The said loan is guaranteed by Hik Inc., another US entity. The place of effective management of both Max Inc. and Hik Inc. is in the USA. The book value of total assets of Focus Ltd. is ₹180 crores. Focus Ltd. imported turbo equipment worth ₹30 crores from Hik Inc. Import…
Case Scenario I M/s Gamma Ltd. is an Indian company engaged in providing consultancy and business advisory services. During the previous year 2024-25, it received the following loans in cash from various vendors due to some business exigency: ₹3,00,000 availed from Mr. Arun on 20.04.2024. ₹19,500 availed from Mr. Raj on 20.05.2024. ₹20,500 availed from Mr. Sunil on 20.06.2024 Further, the company made the following loan repayments during the year: ₹18,000 to Mr. Arun on 15.07.2024 in crossed cheque. ₹1,25,000…
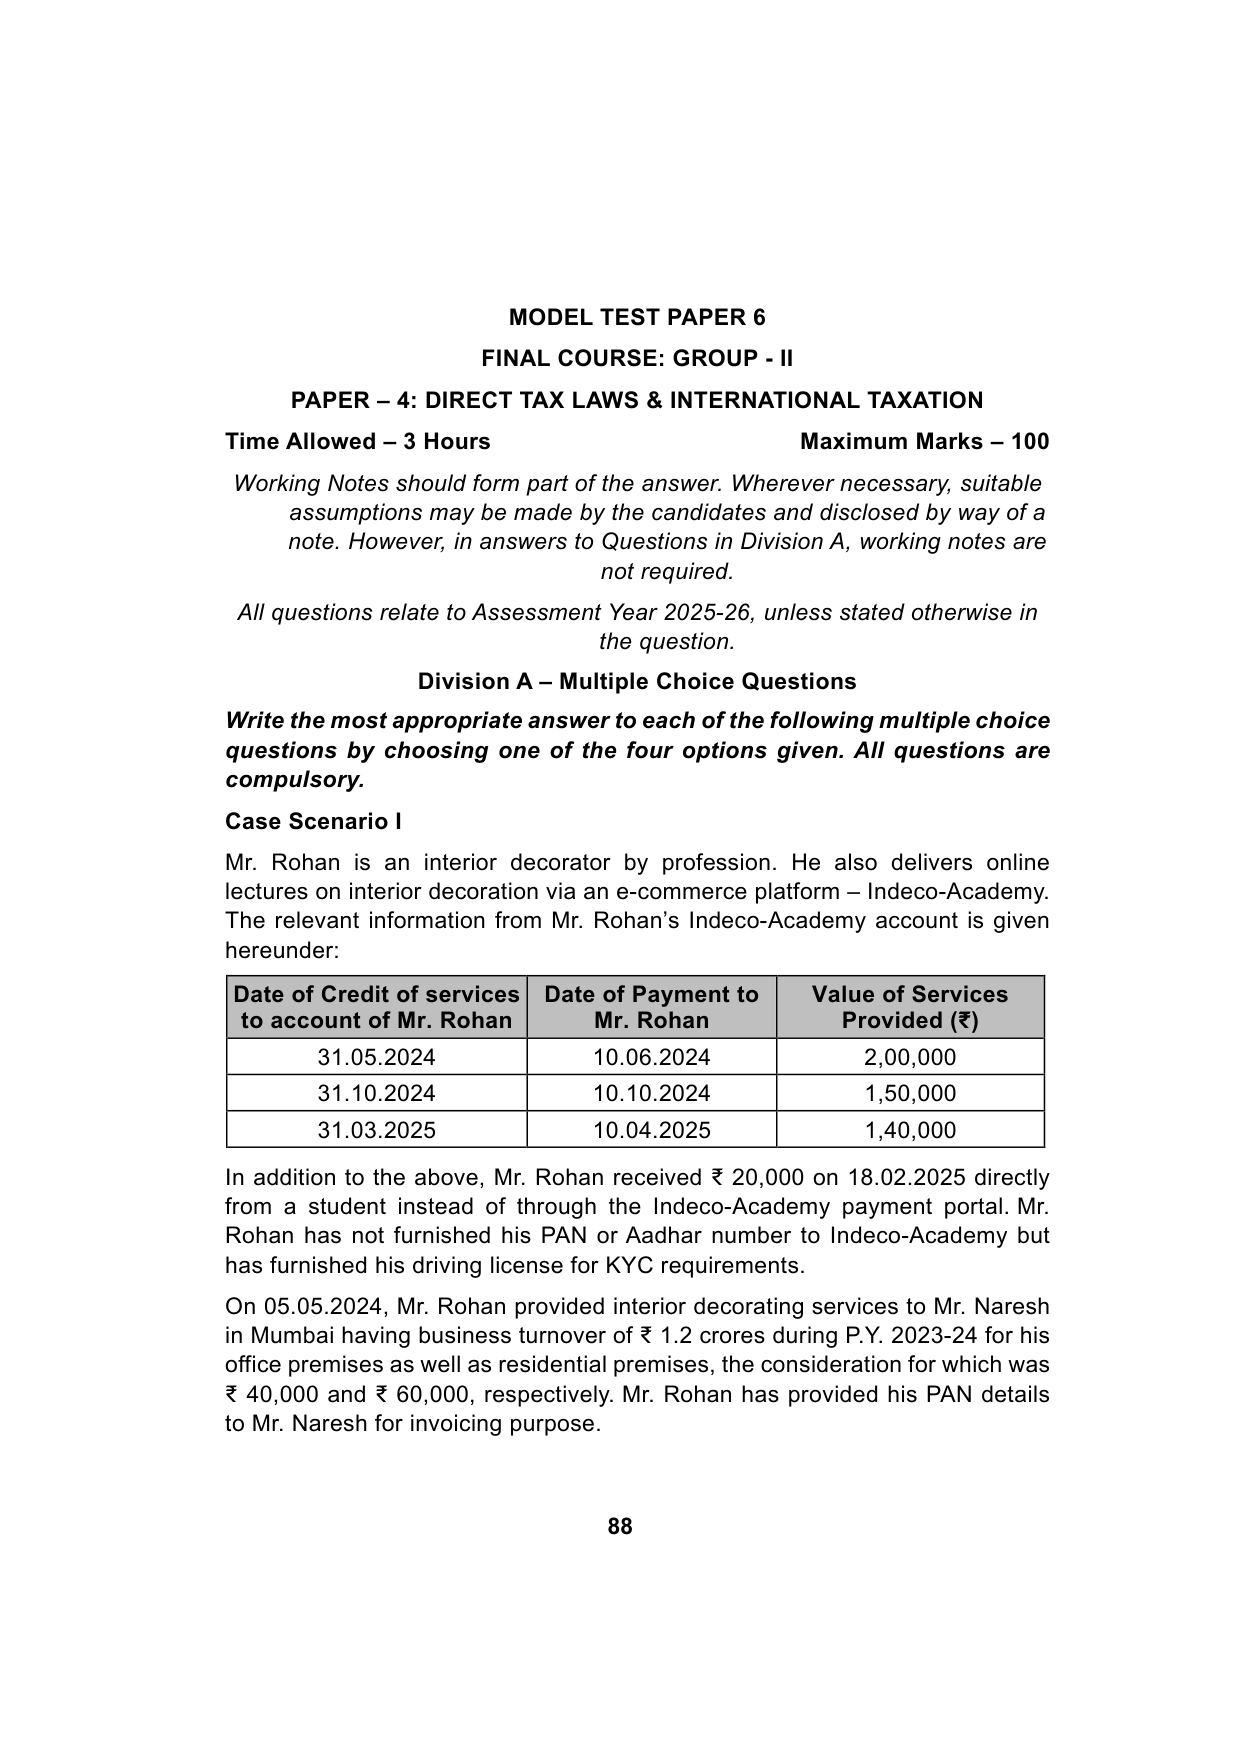
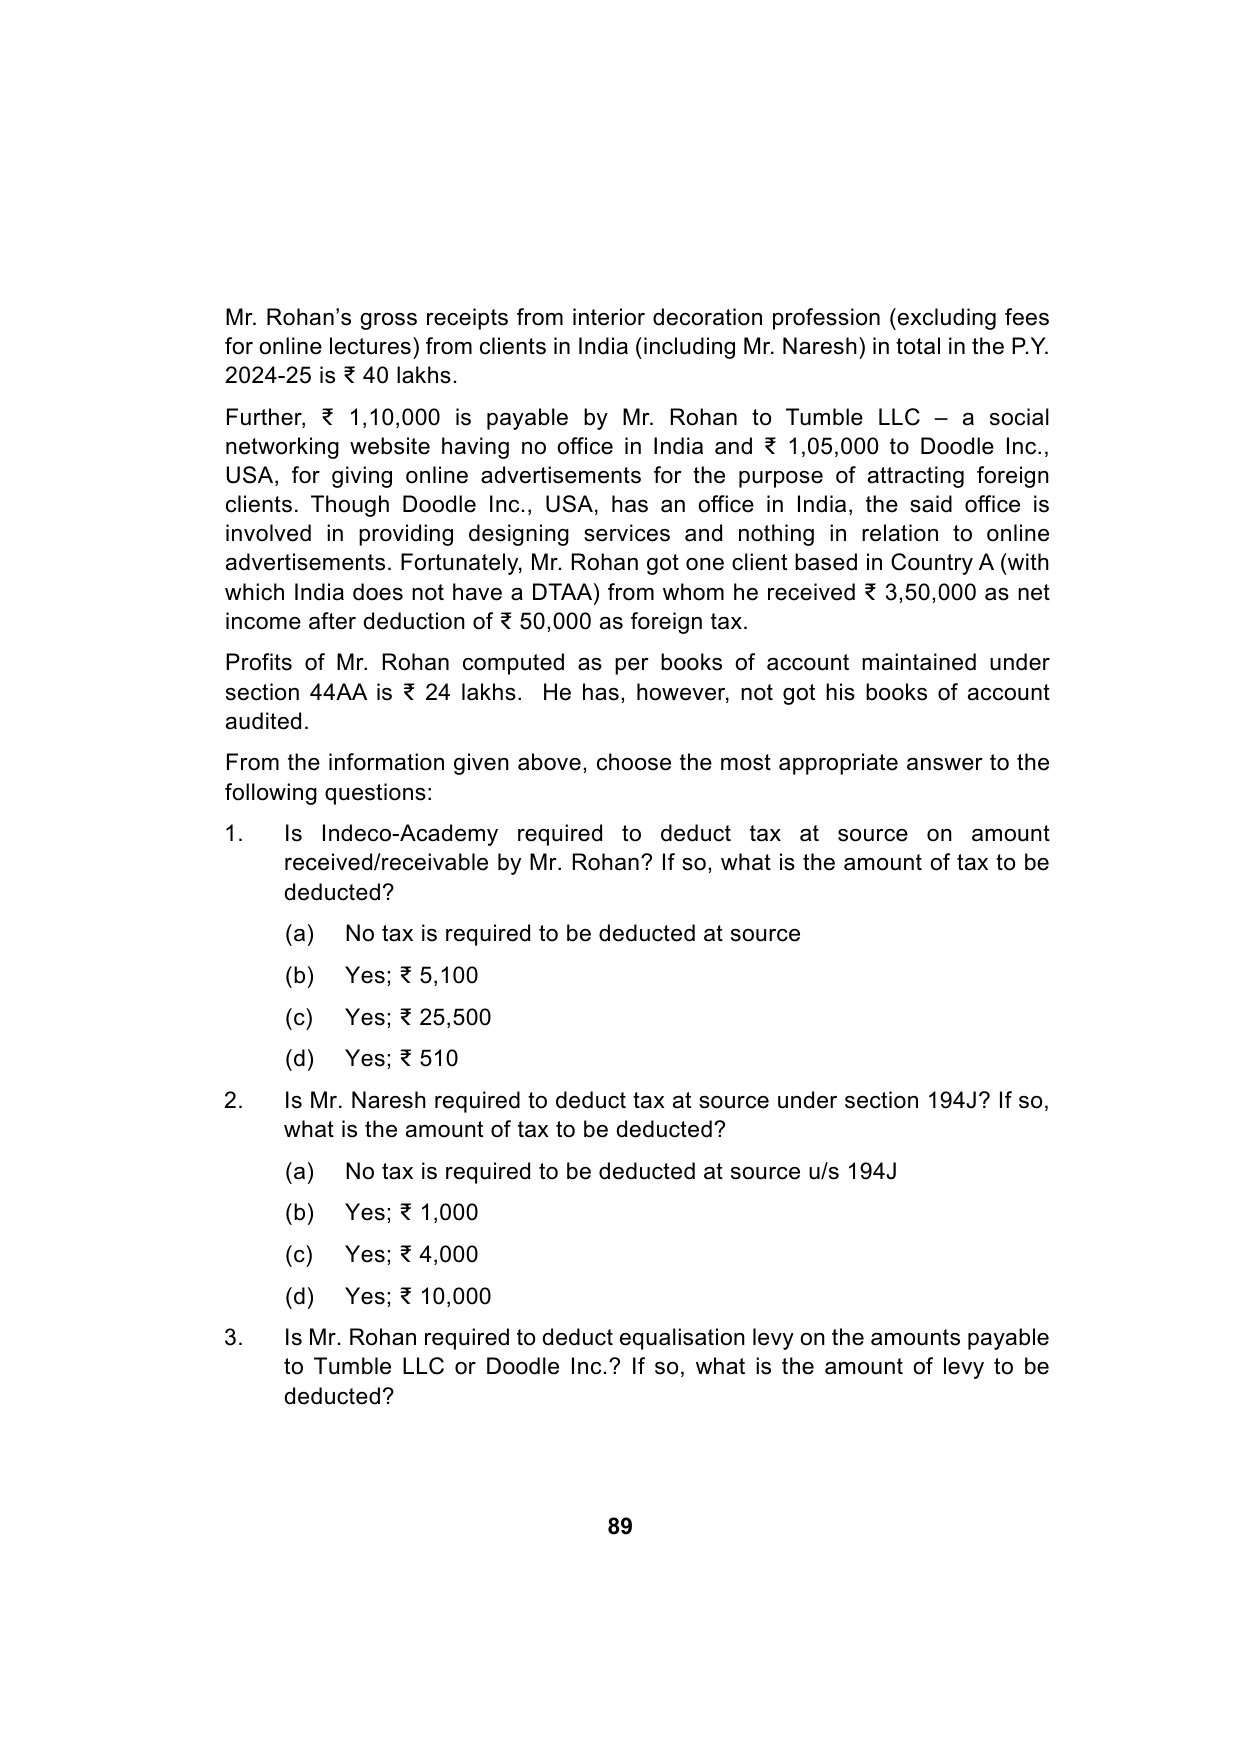
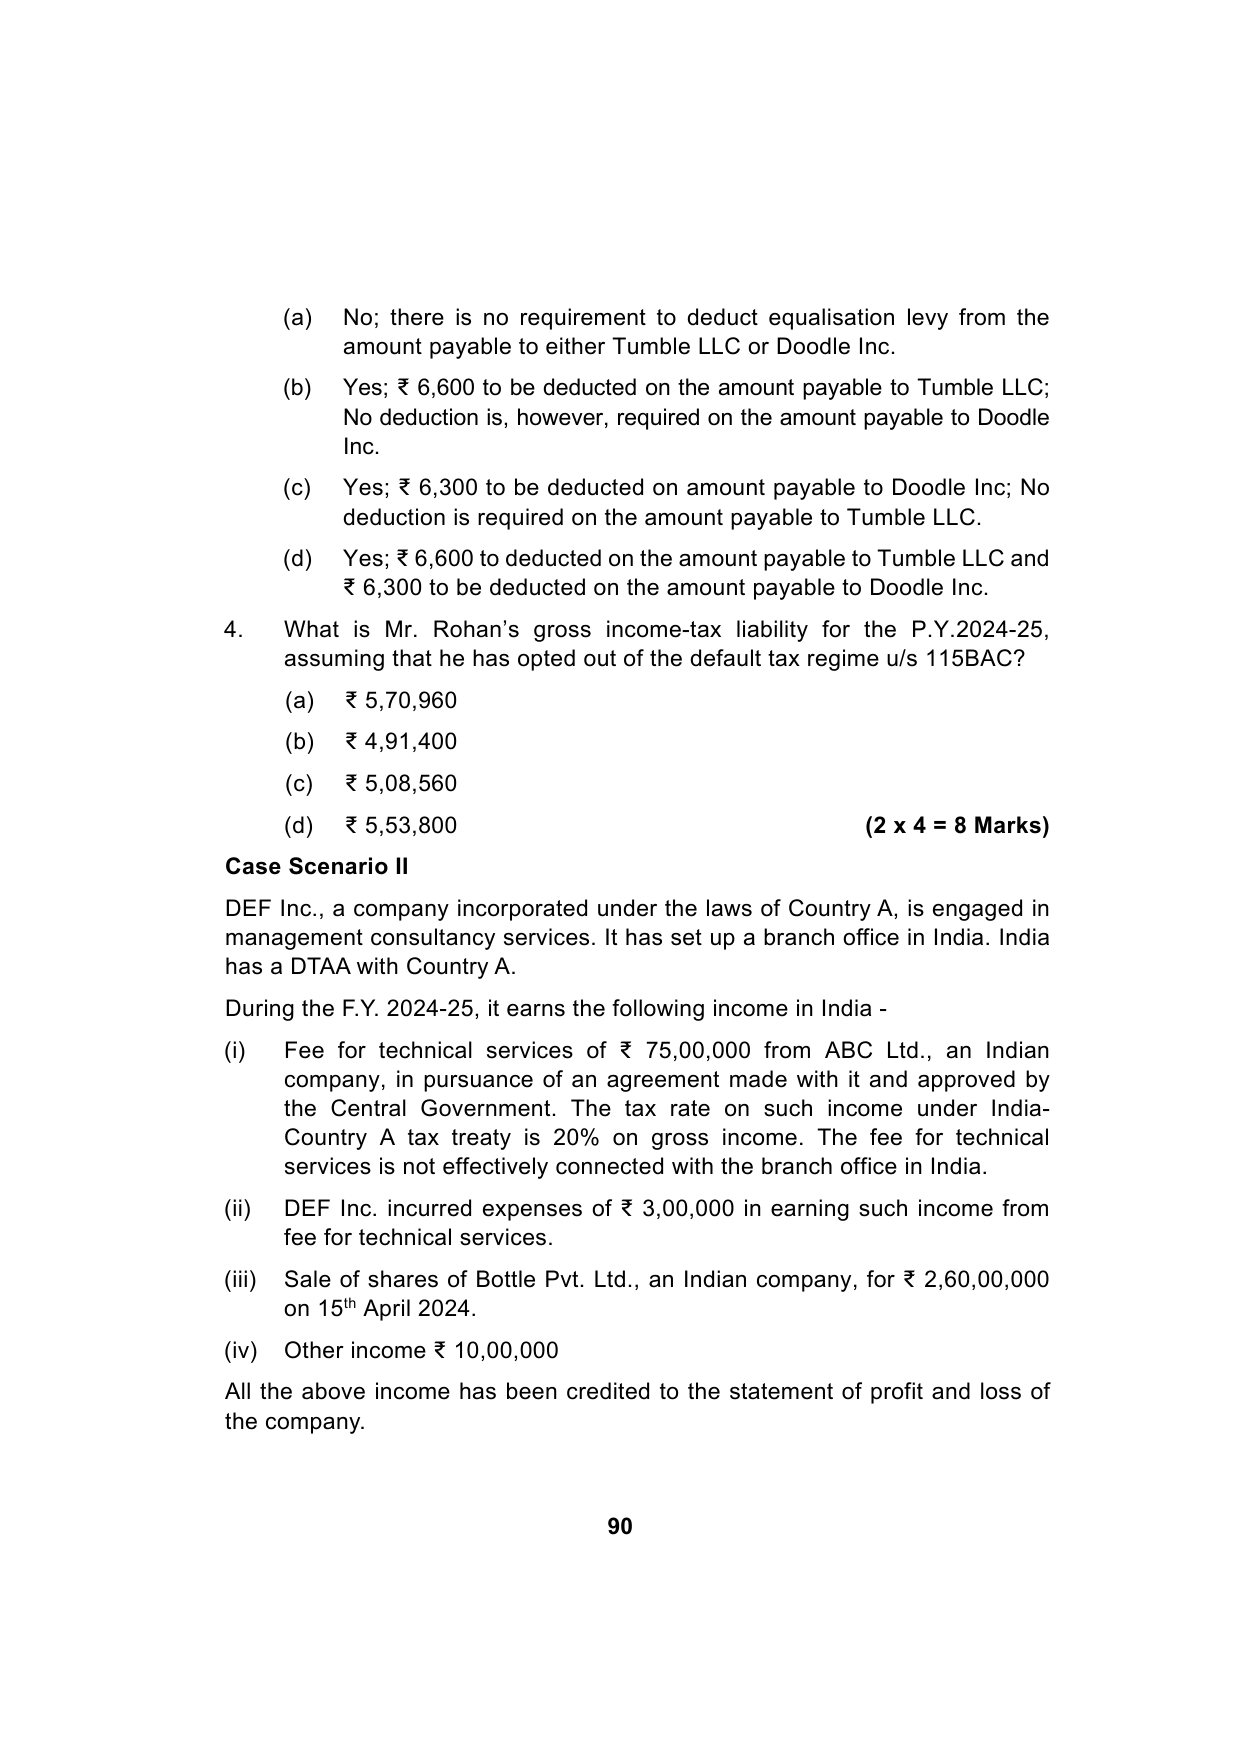
Case Scenario I Mr. Rohan is an interior decorator by profession. He also delivers online lectures on interior decoration via an e-commerce platform – Indeco-Academy. The relevant information from Mr. Rohan’s Indeco-Academy account is given hereunder: Date of Credit of services Date of Payment to Value of Services to account of Mr. Rohan Mr. Rohan Provided (₹) 31.05.2024 10.06.2024 2,00,000 31.10.2024 10.10.2024 1,50,000 31.03.2025 10.04.2025 1,40,000 In addition to the above, Mr. Rohan received ₹ 20,000 on 18.02.2025 directly from…
Case Scenario-I ‘Galgotia Travels Ltd.’ (GTL) is established on 3 rd April in the city of Bangalore (Karnataka) and the primary objective of the company is to provide air- conditioned contract-based passenger transportation services at affordable fares. The company obtains the voluntary registration under GST from 1st May. On 1 st July, the company purchased motor vehicles (omnibus) of various seating capacities as follows: Seating capacity No. of Purchase price Rate of GST (including driver) vehicles (per vehicle- exclusive of…
Case Scenario-I Swash Enterprise Pvt Ltd. is a financial service company having its offices in Kolkata, West Bengal and Mumbai, Maharashtra. The company is registered under GST in both the States. The company operates through two segments (a) banking services and (b) advisory & consulting services. The aggregate turnover of the company during the previous year was (i) ₹80 lakh in West Bengal & (ii) ₹60 lakh in Maharashtra. The bouquet of services provided under each of the two segments…
Case Scenario-I Nirav Ltd. is registered with the jurisdictional GST authorities in the State of Rajasthan and operates in multiple businesses. The principal business of Nirav Ltd. is works contract service being provided to the customers by way of fabricating and installing the body for large transportation vehicles. The chassis of the vehicles are provided by the customers to Nirav Ltd. Nirav Ltd. procures the material for fabrication and installs the same on the chassis against a lumpsum agreed amount…
Case Scenario-I Abhivyakti Pvt Ltd. is engaged in the supply of food products under the brand name “Super Foods”. It has a plant at Howrah, West Bengal. It is a registered supplier under GST and is a monthly return filer. It has allotted residential quarters to its employees within the plant premises. The aggregate turnover of the company during the preceding financial year was ₹7.50 crore. Following details are provided by the company for the month of September: Particulars Amount…
Case Scenario-I Sudershan Transport Agency (P) Ltd. (hereinafter referred to as “STAL”), registered under GST in Jaipur, Rajasthan, is providing services by way of transportation of goods by road for which it issues consignment notes, to all the sectors of industries. It maintains trucks, trollers, advance carriages for heavy loads, lorries and small tractors, for the purpose of transportation and renting purposes. It also maintains special vehicles which has special storage features and other advance facilities for transporting defence equipments…
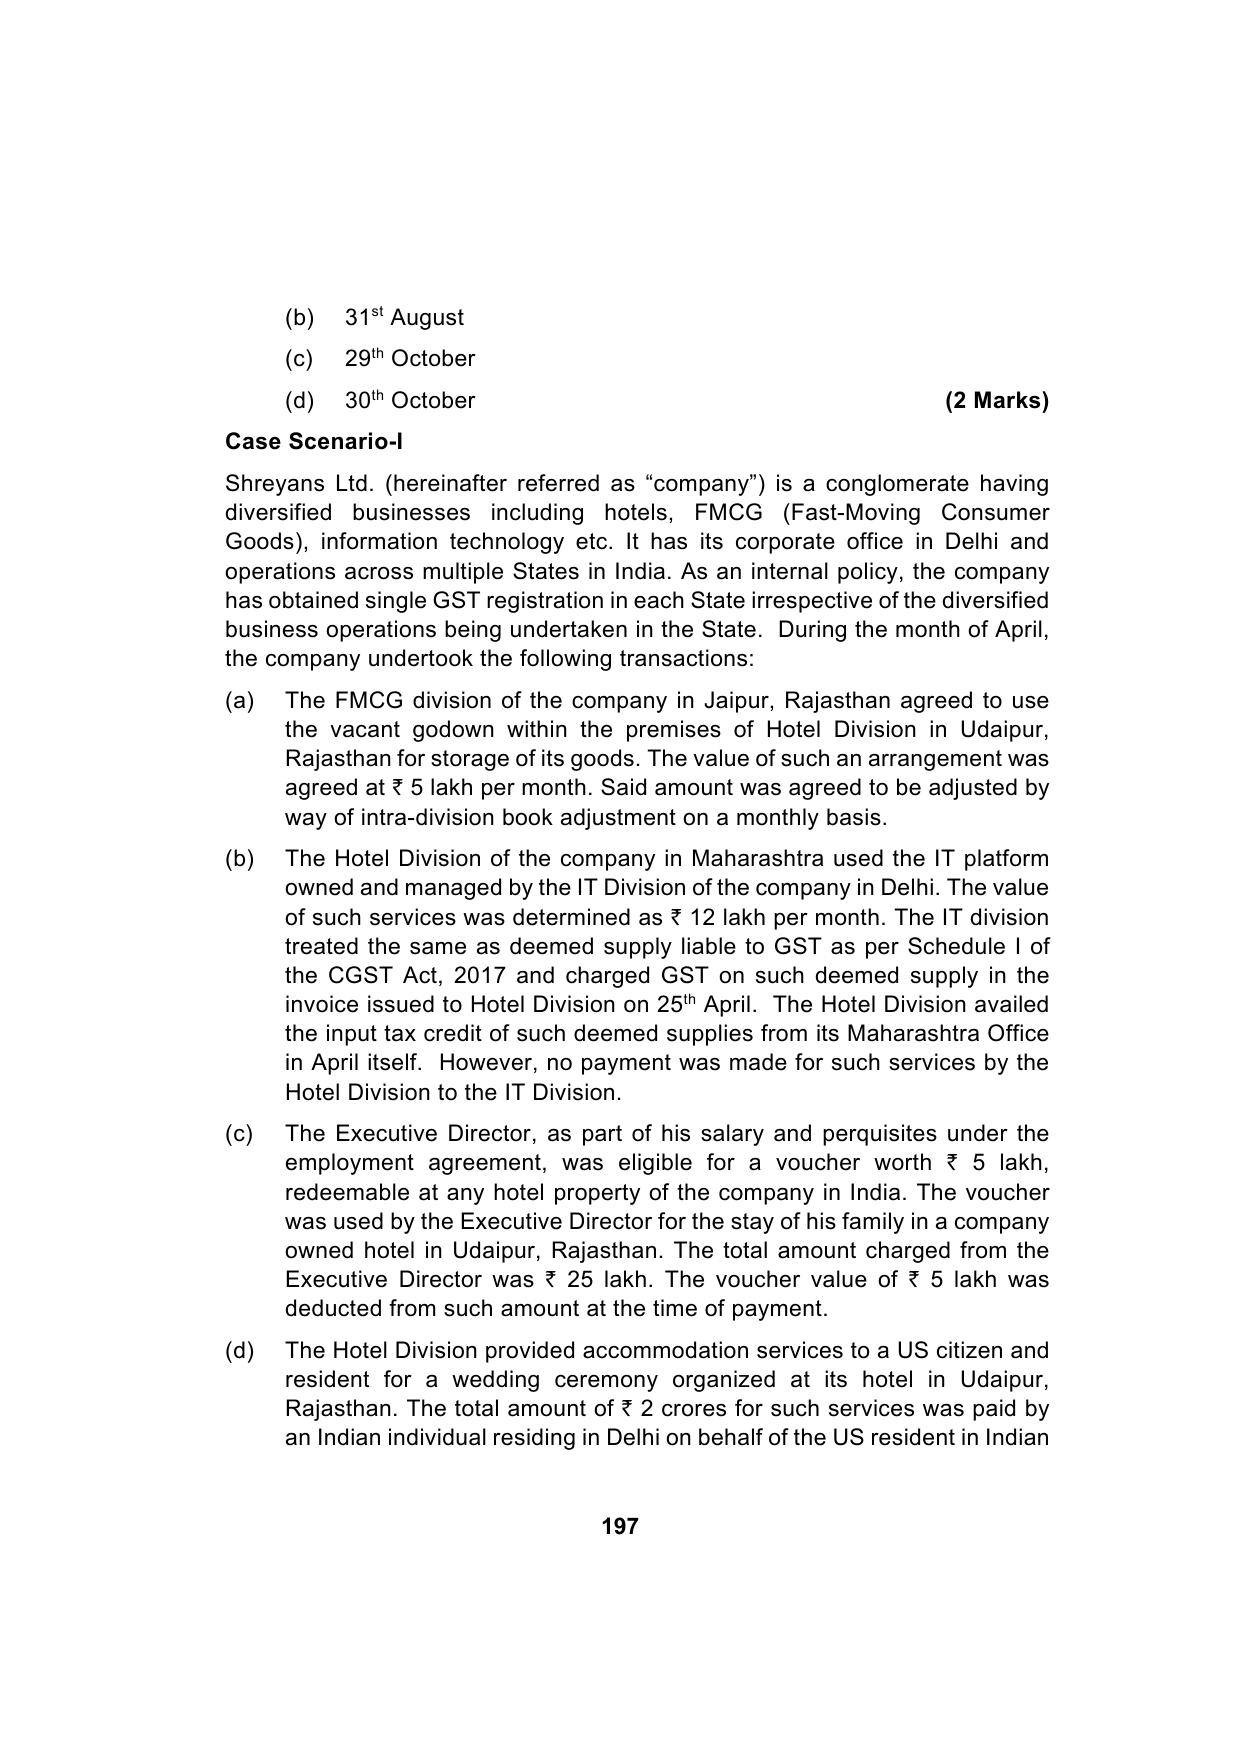
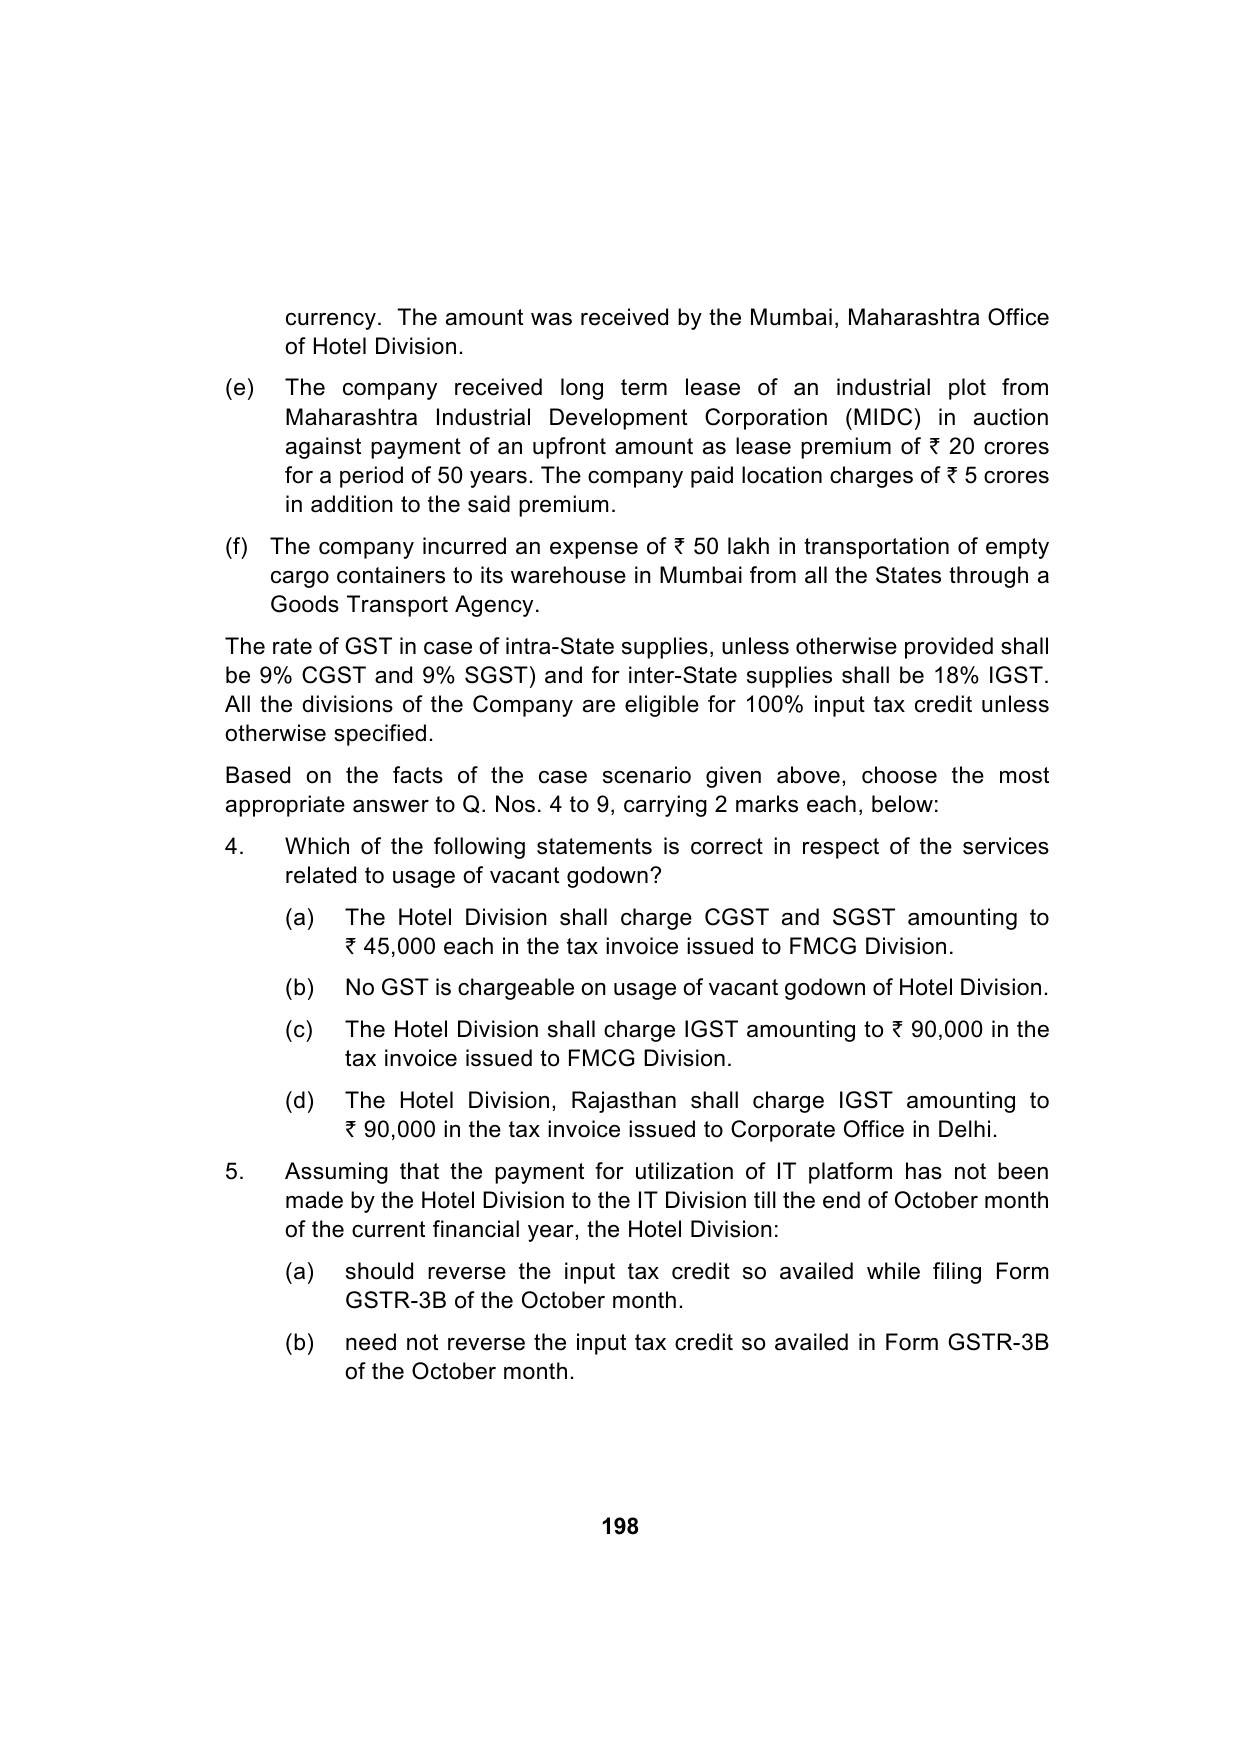
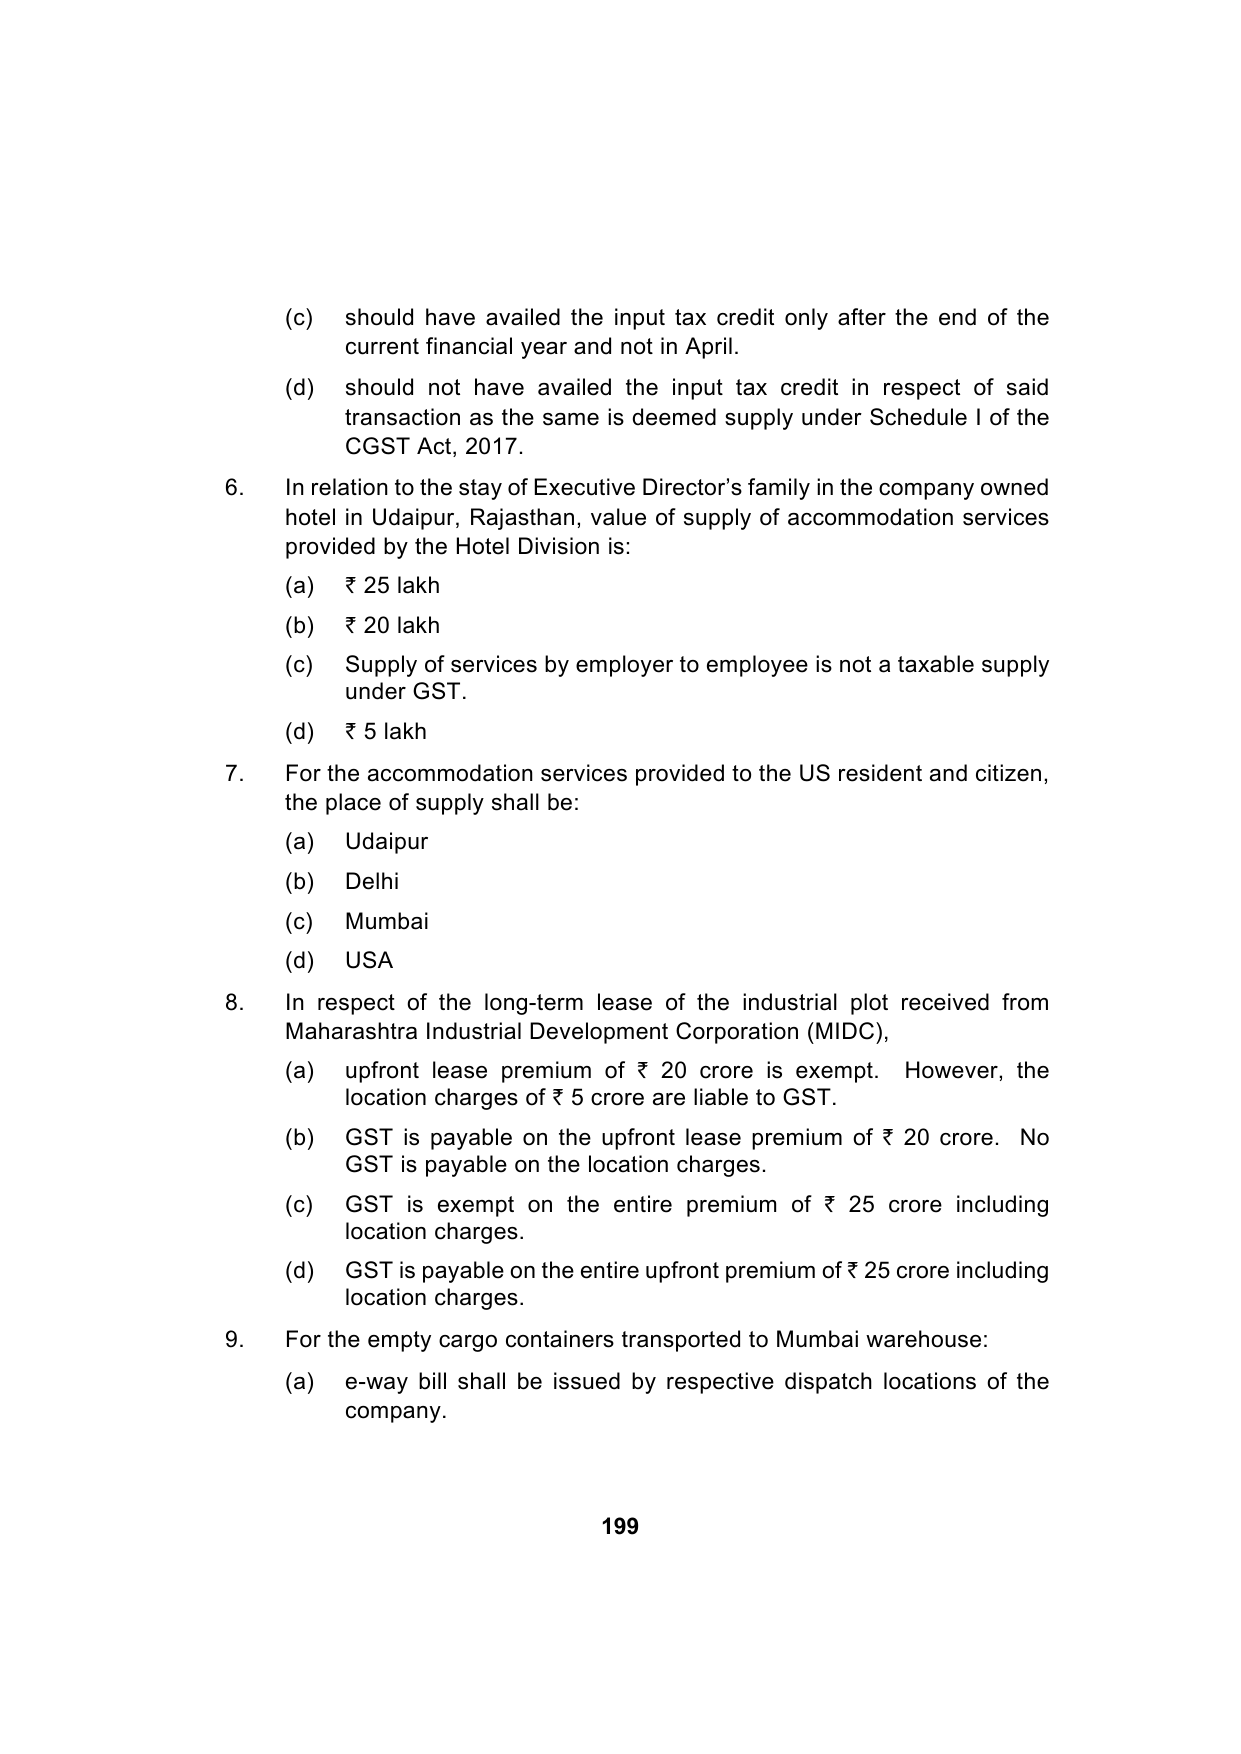
Case Scenario-I Shreyans Ltd. (hereinafter referred as “company”) is a conglomerate having diversified businesses including hotels, FMCG (Fast-Moving Consumer Goods), information technology etc. It has its corporate office in Delhi and operations across multiple States in India. As an internal policy, the company has obtained single GST registration in each State irrespective of the diversified business operations being undertaken in the State. During the month of April, the company undertook the following transactions: (a) The FMCG division of the company…
Question previews auto-extracted from the official ICAI paper. Full scanned pages below.
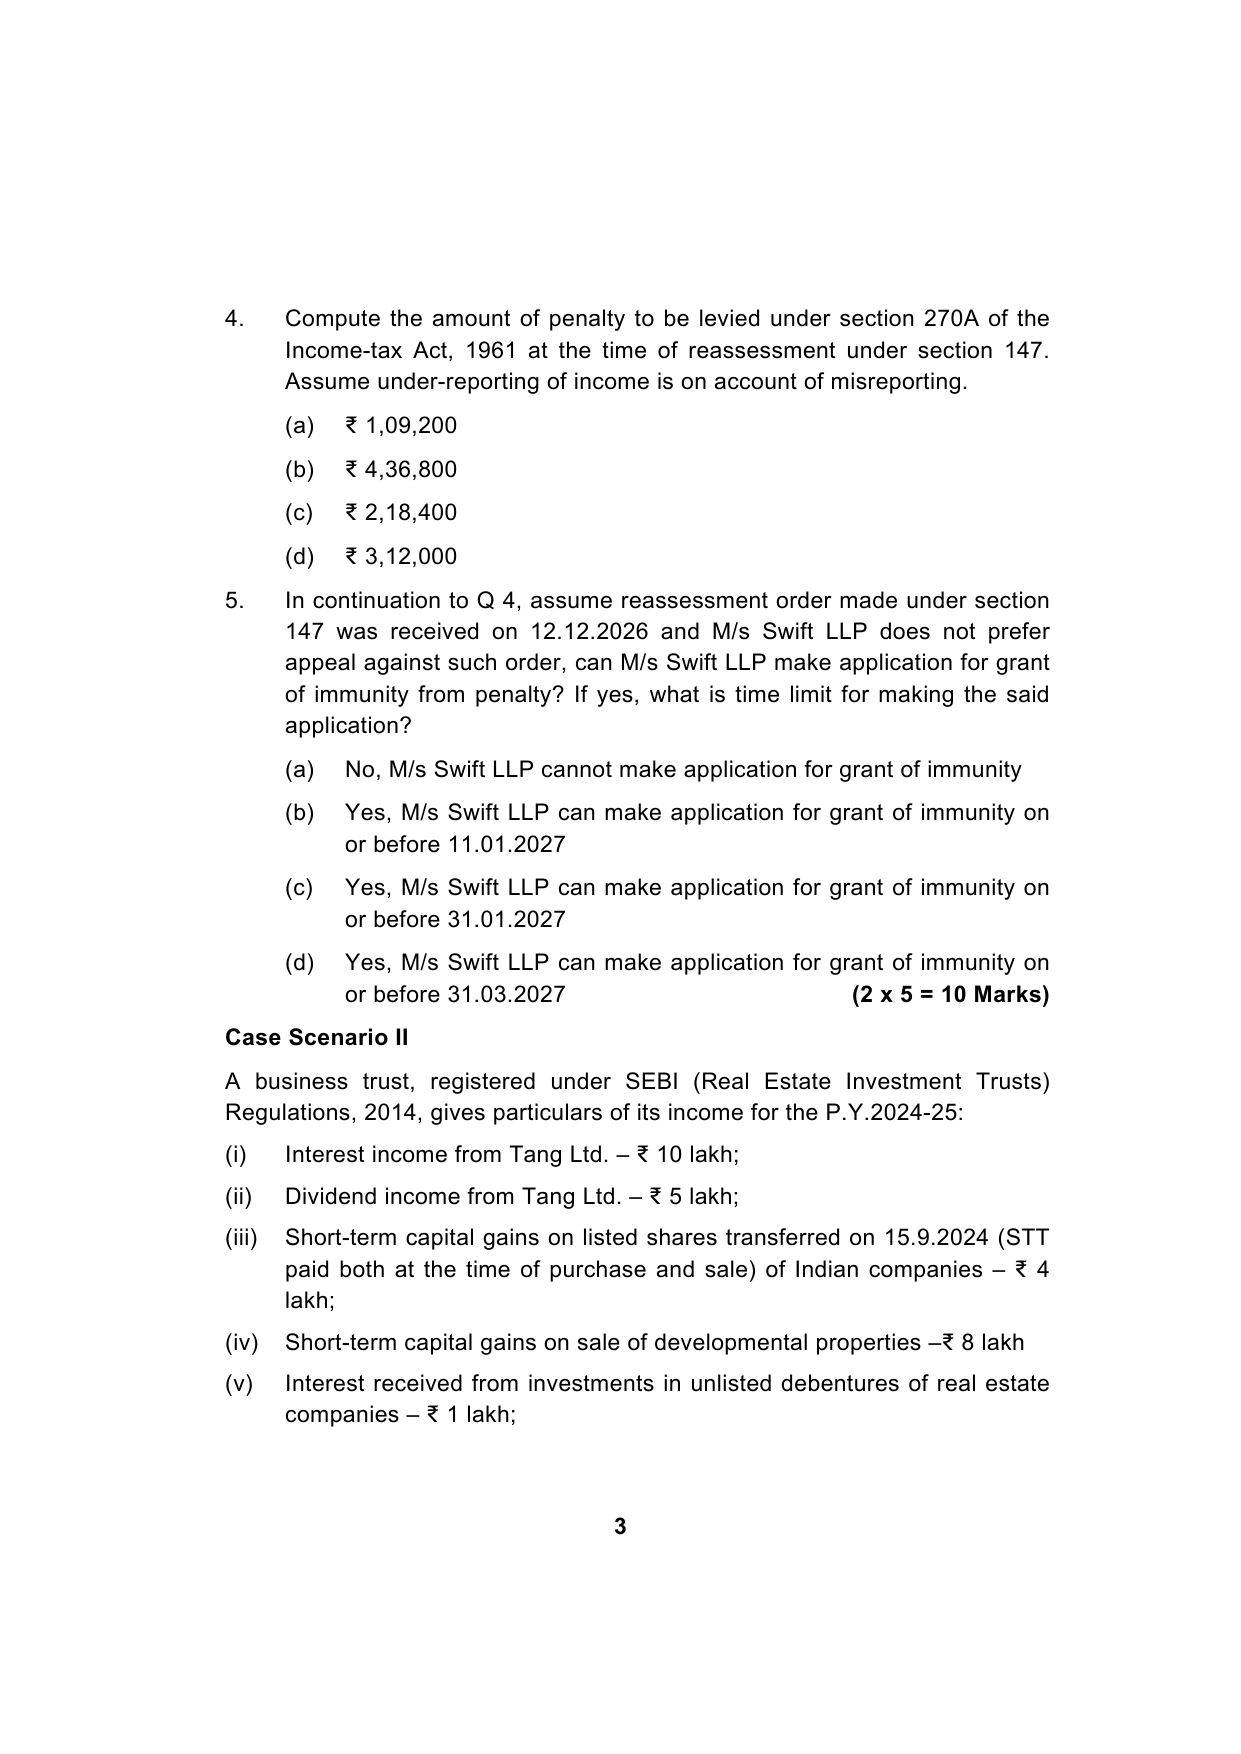
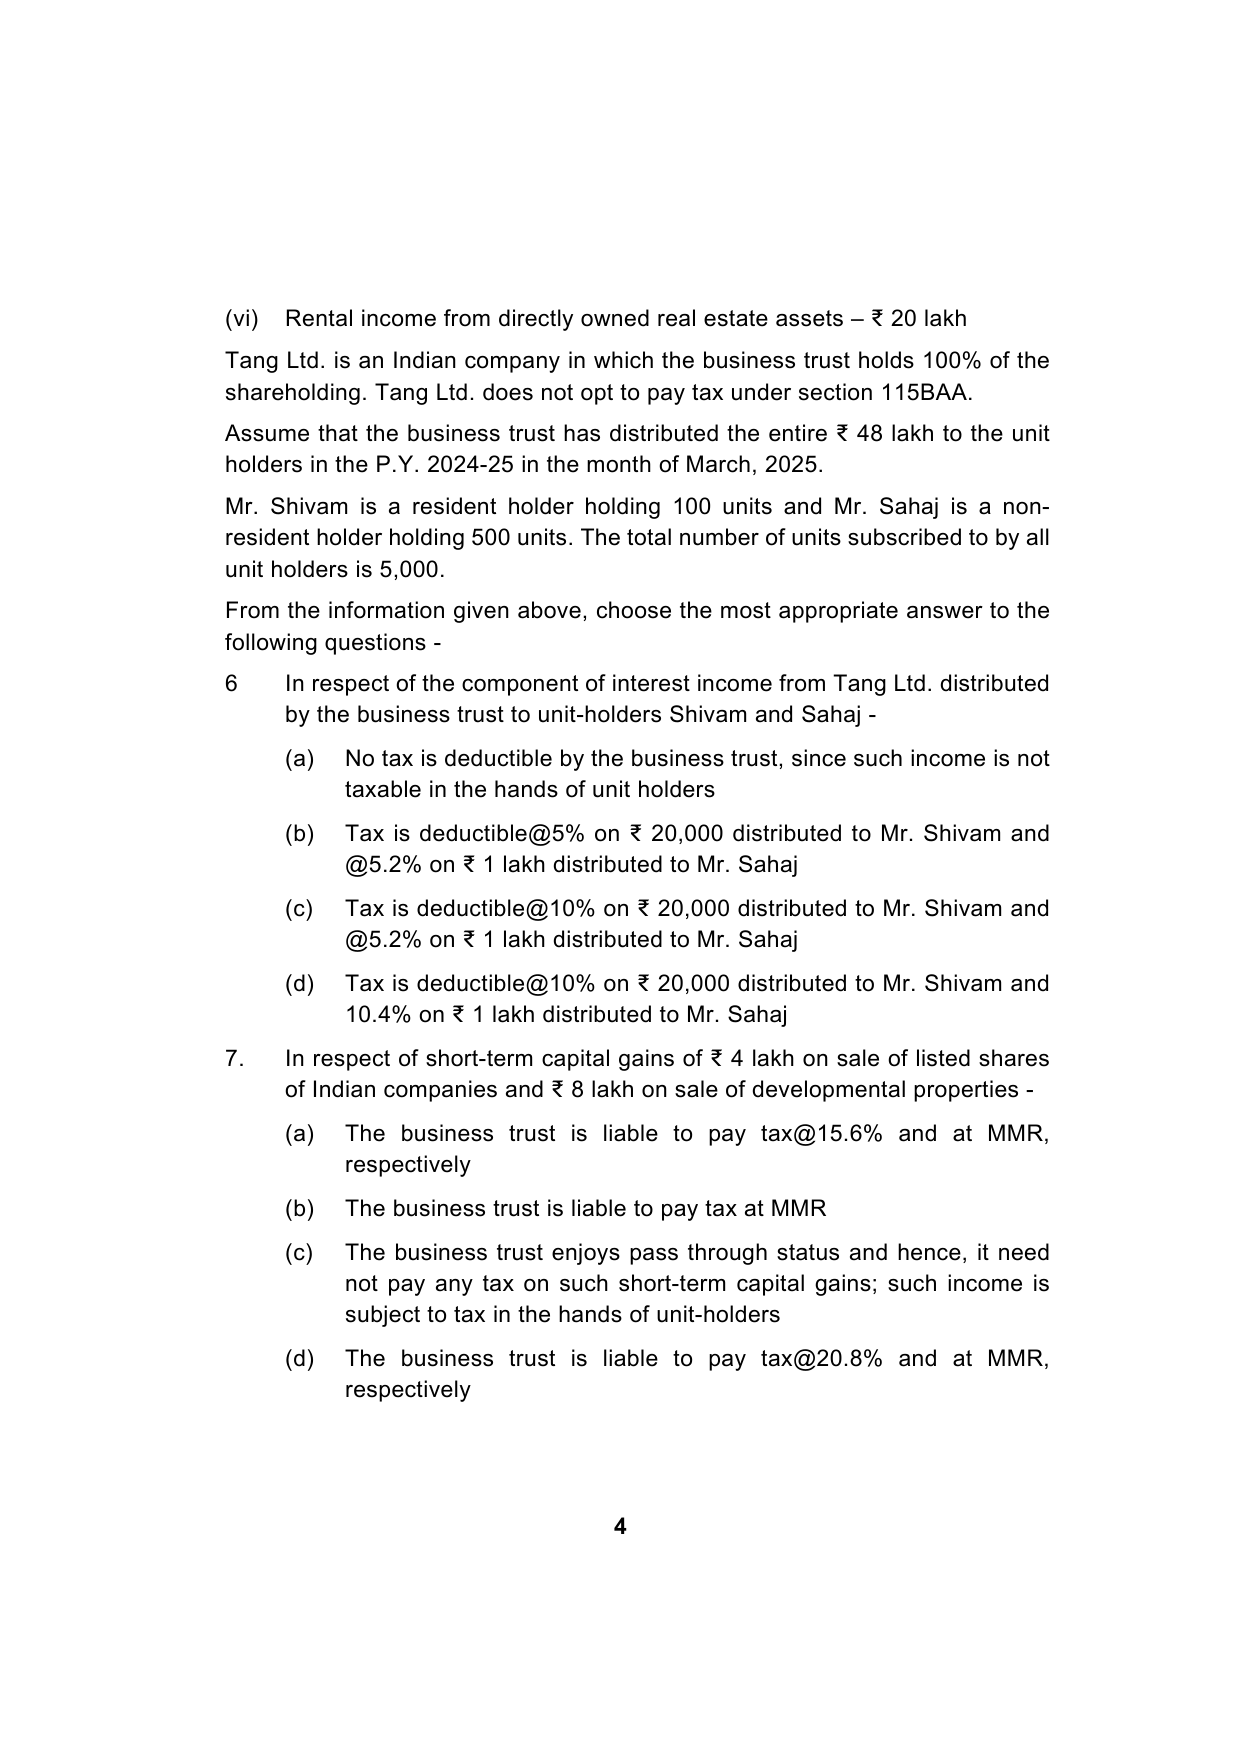
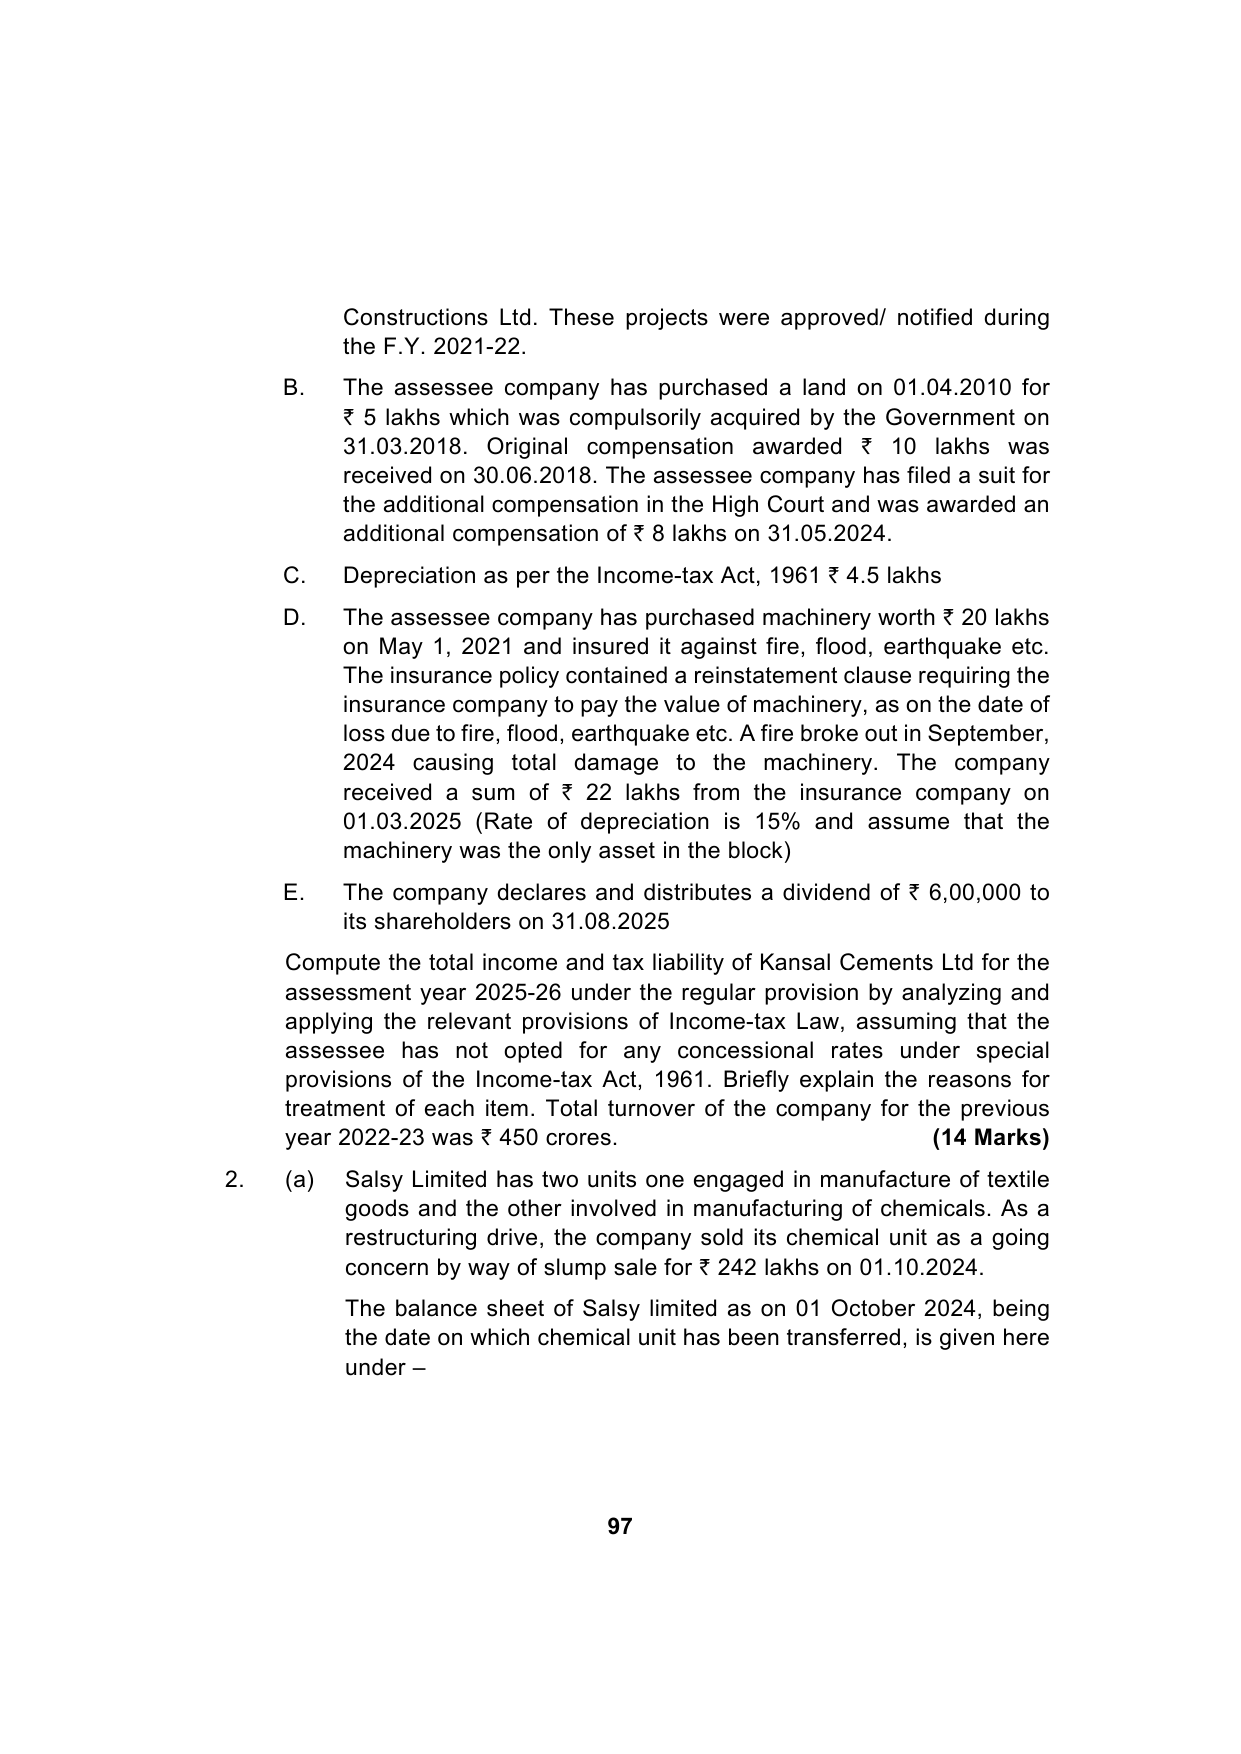
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 1 (100 marks)
Question
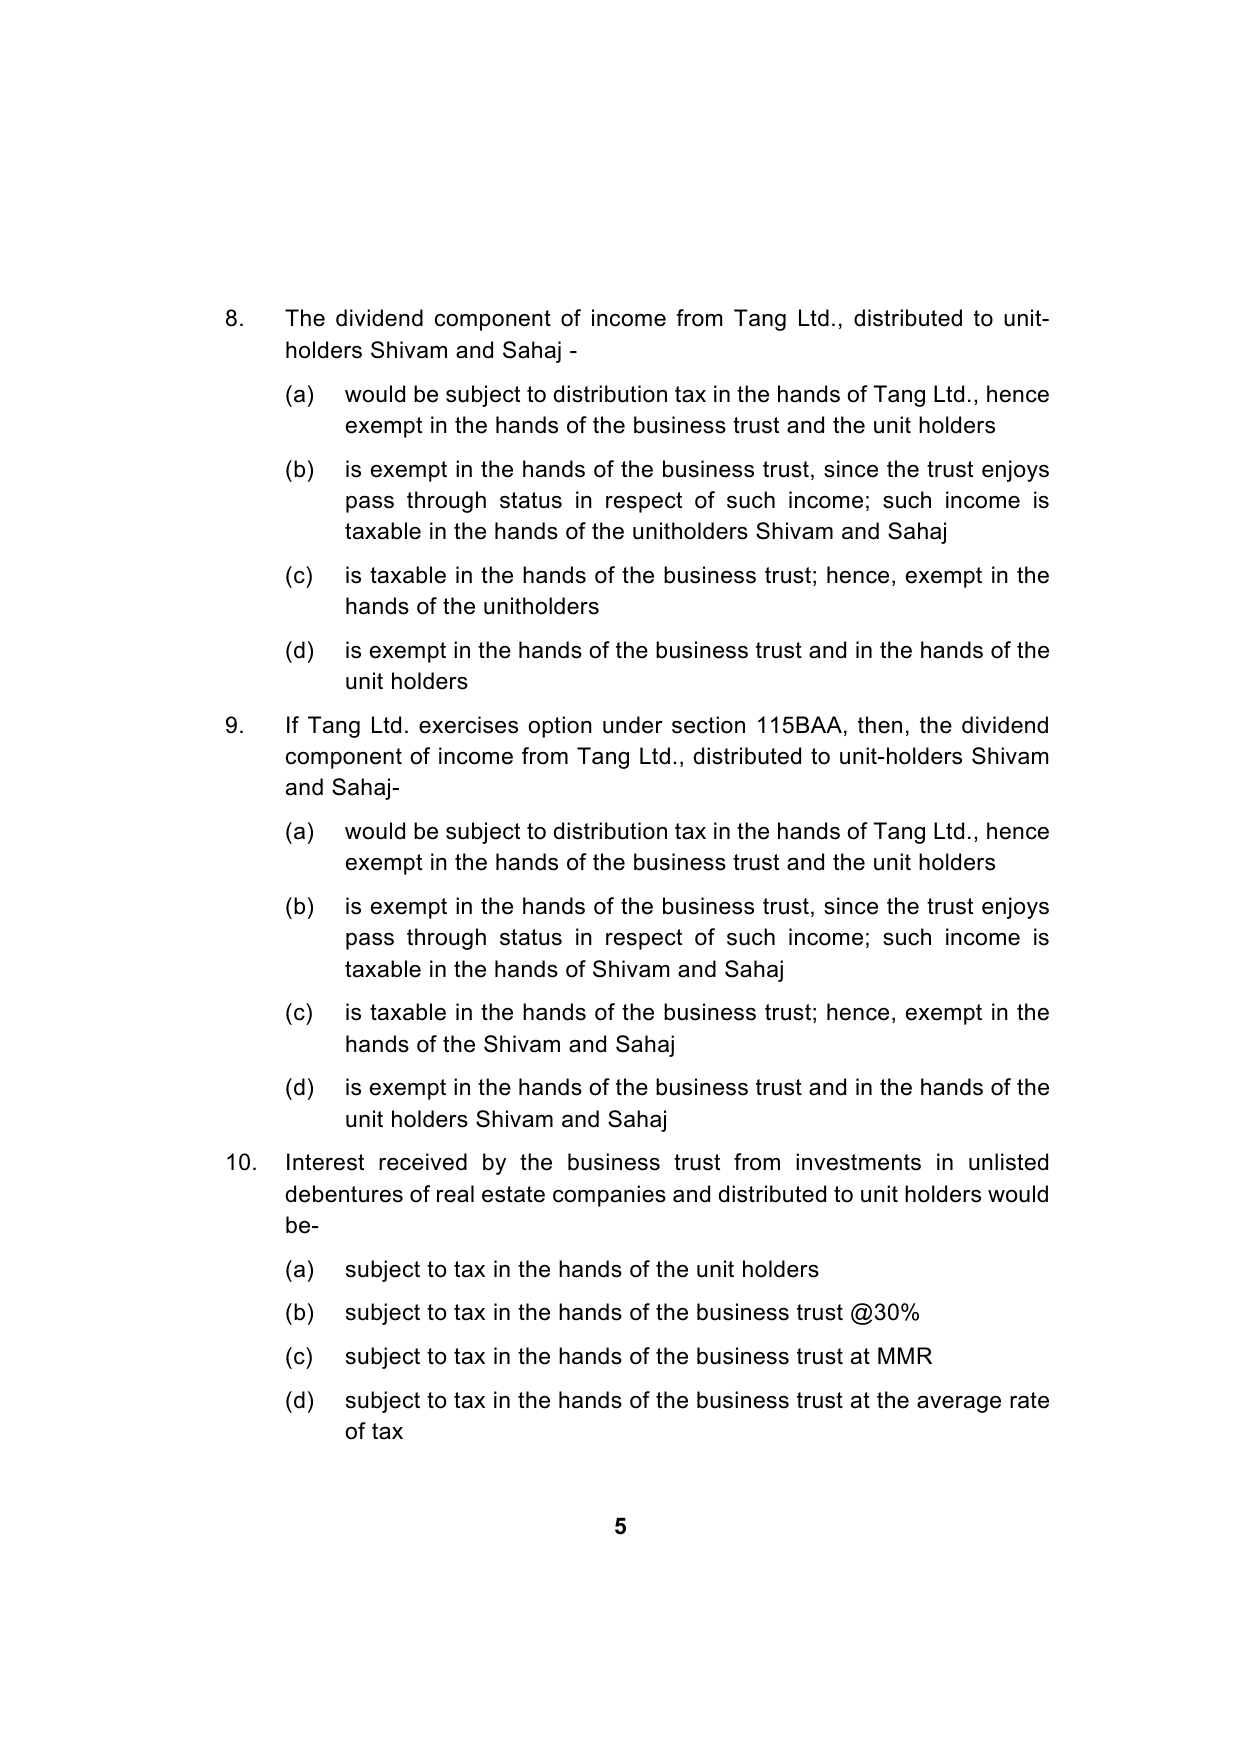
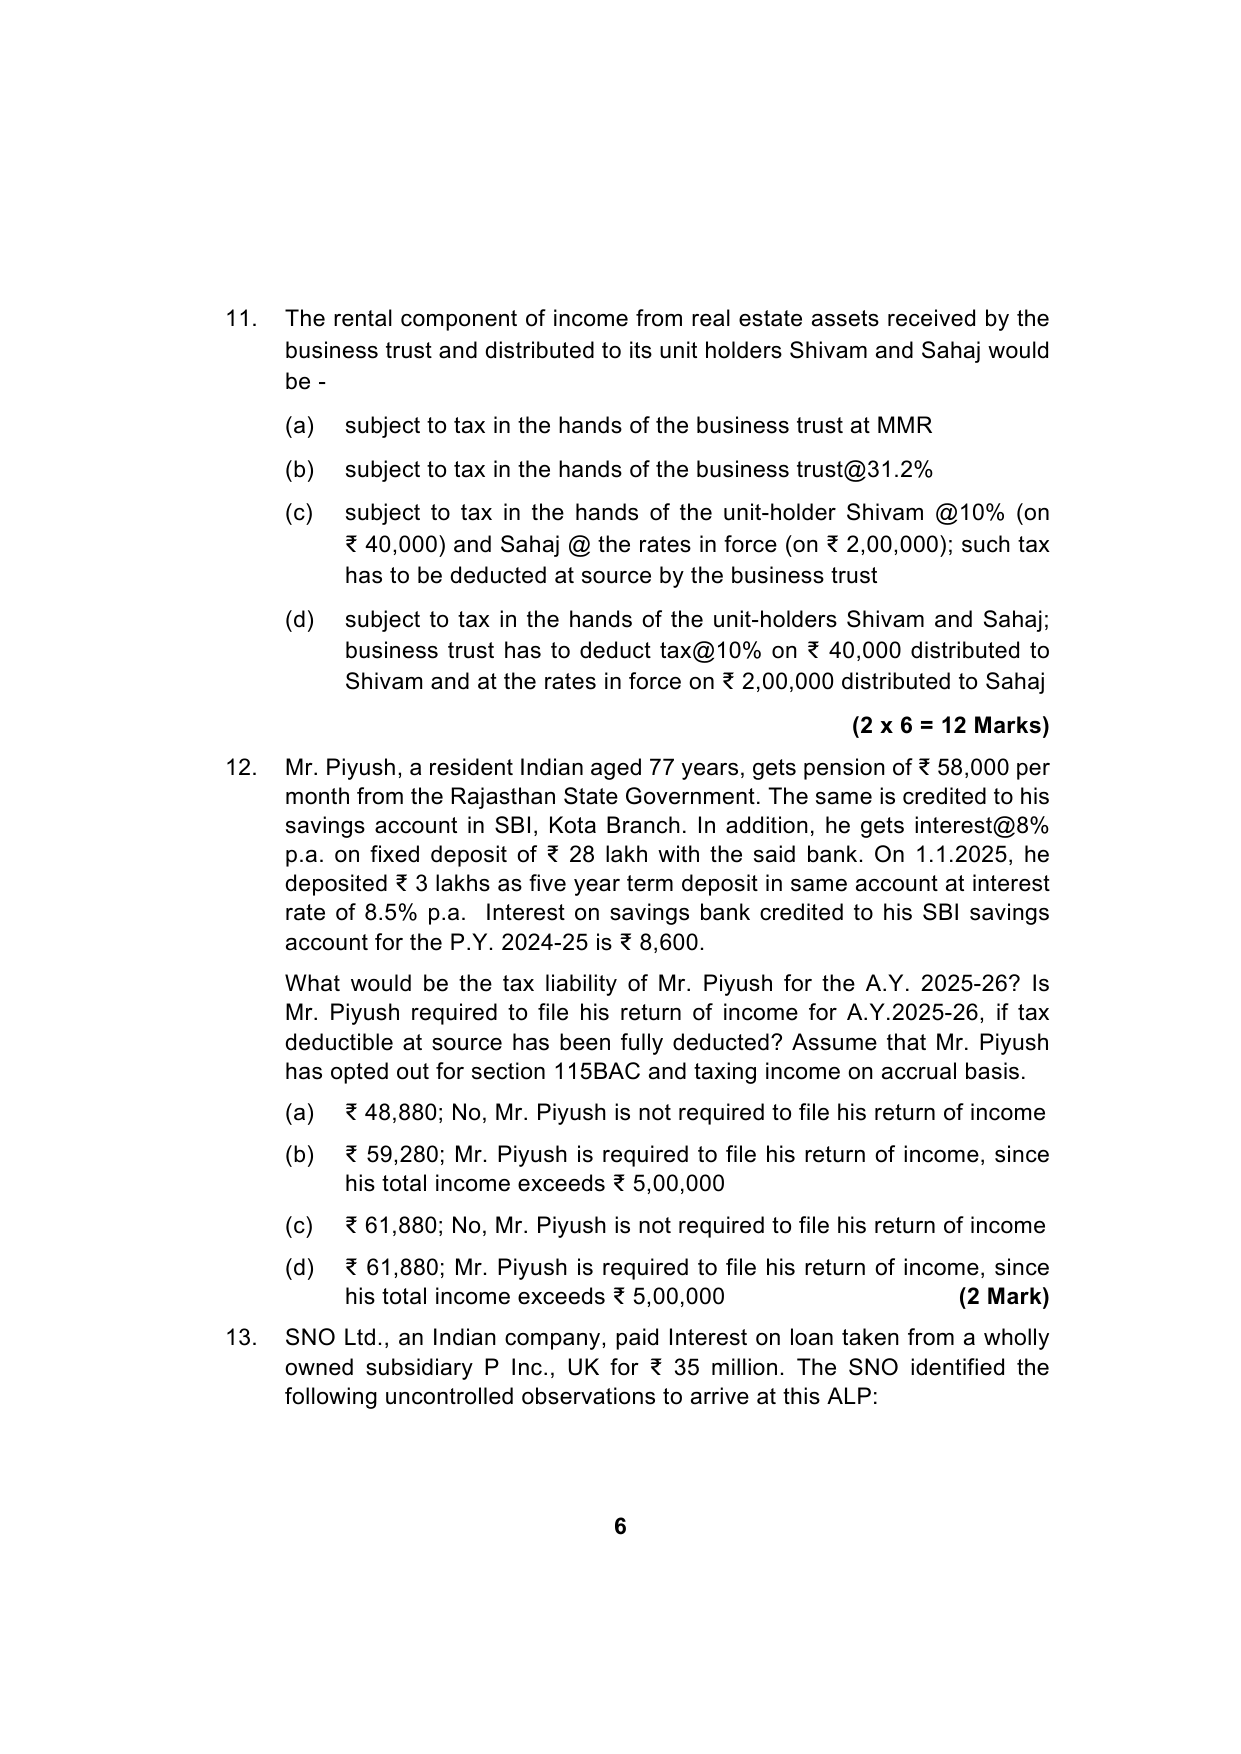
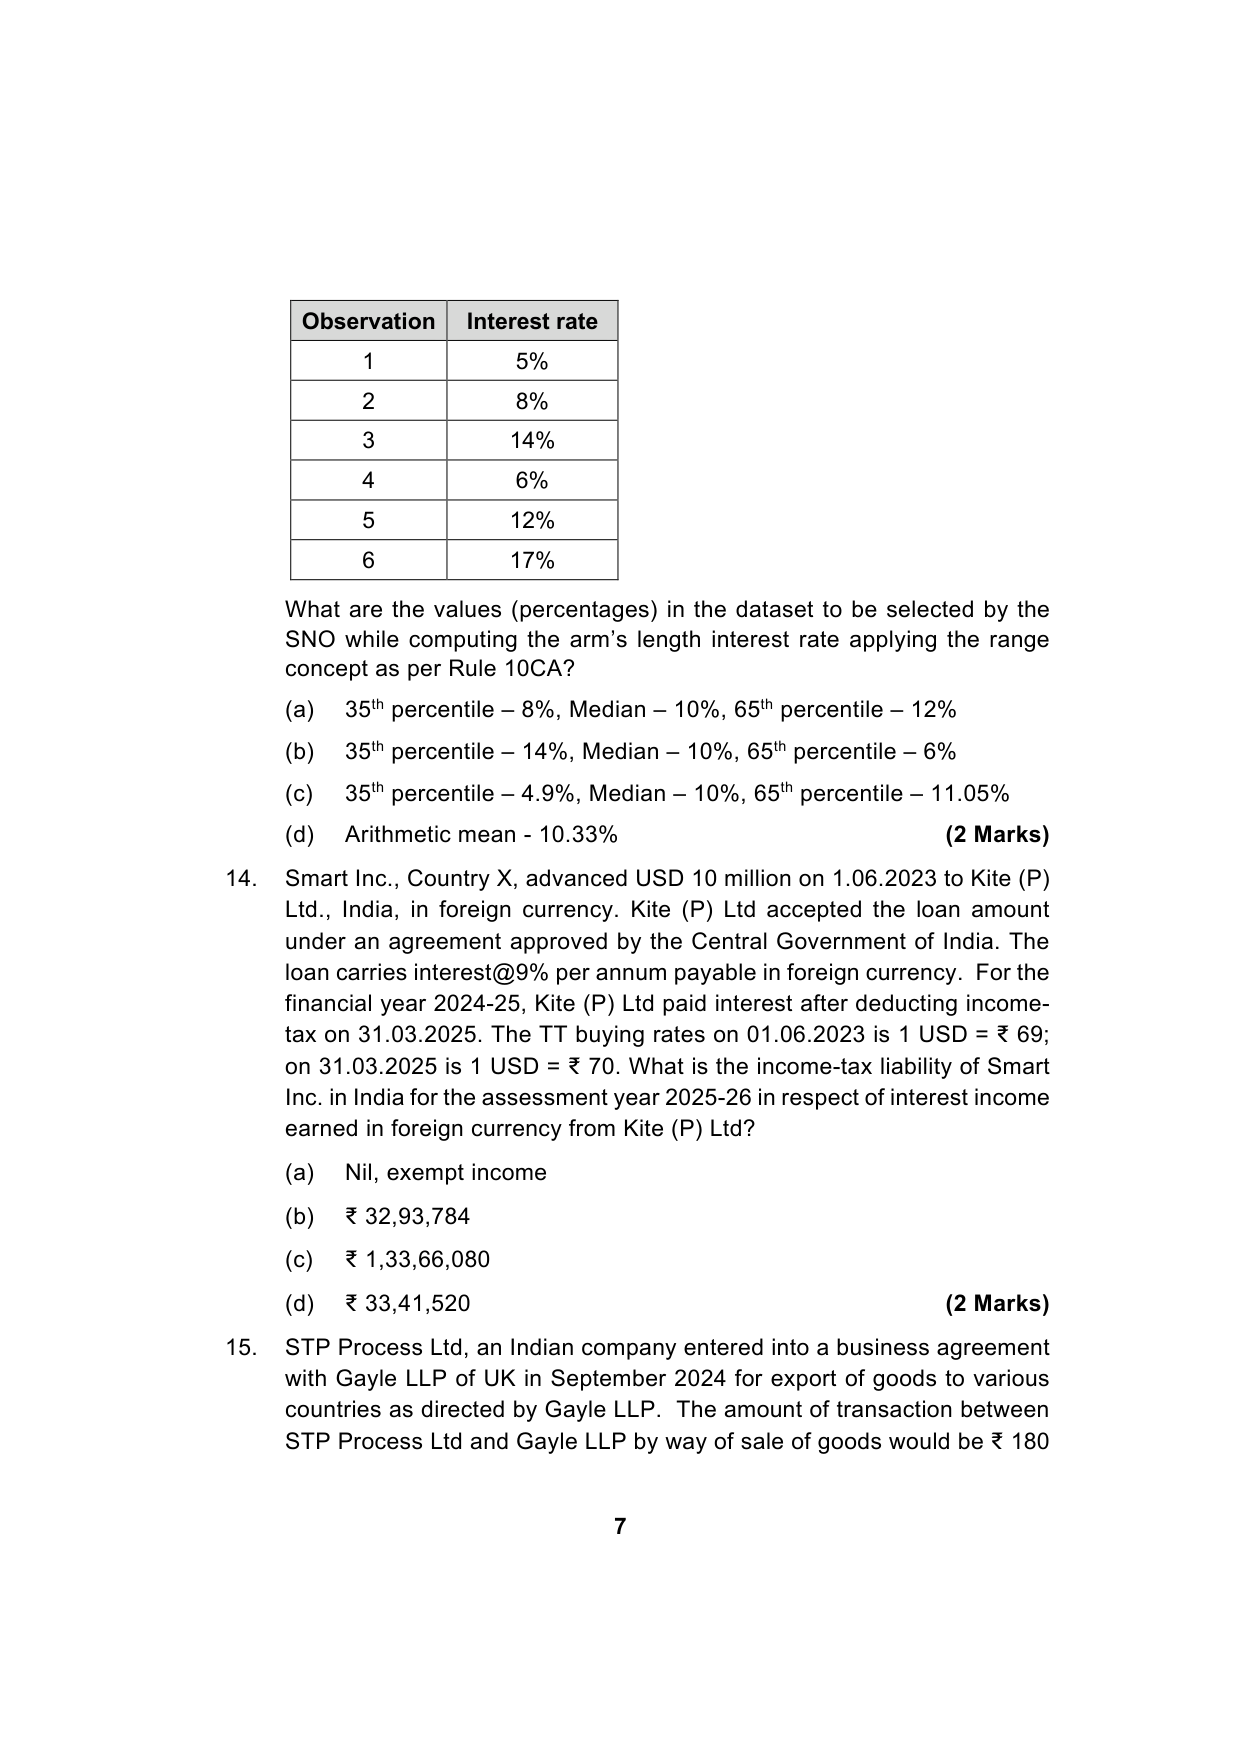
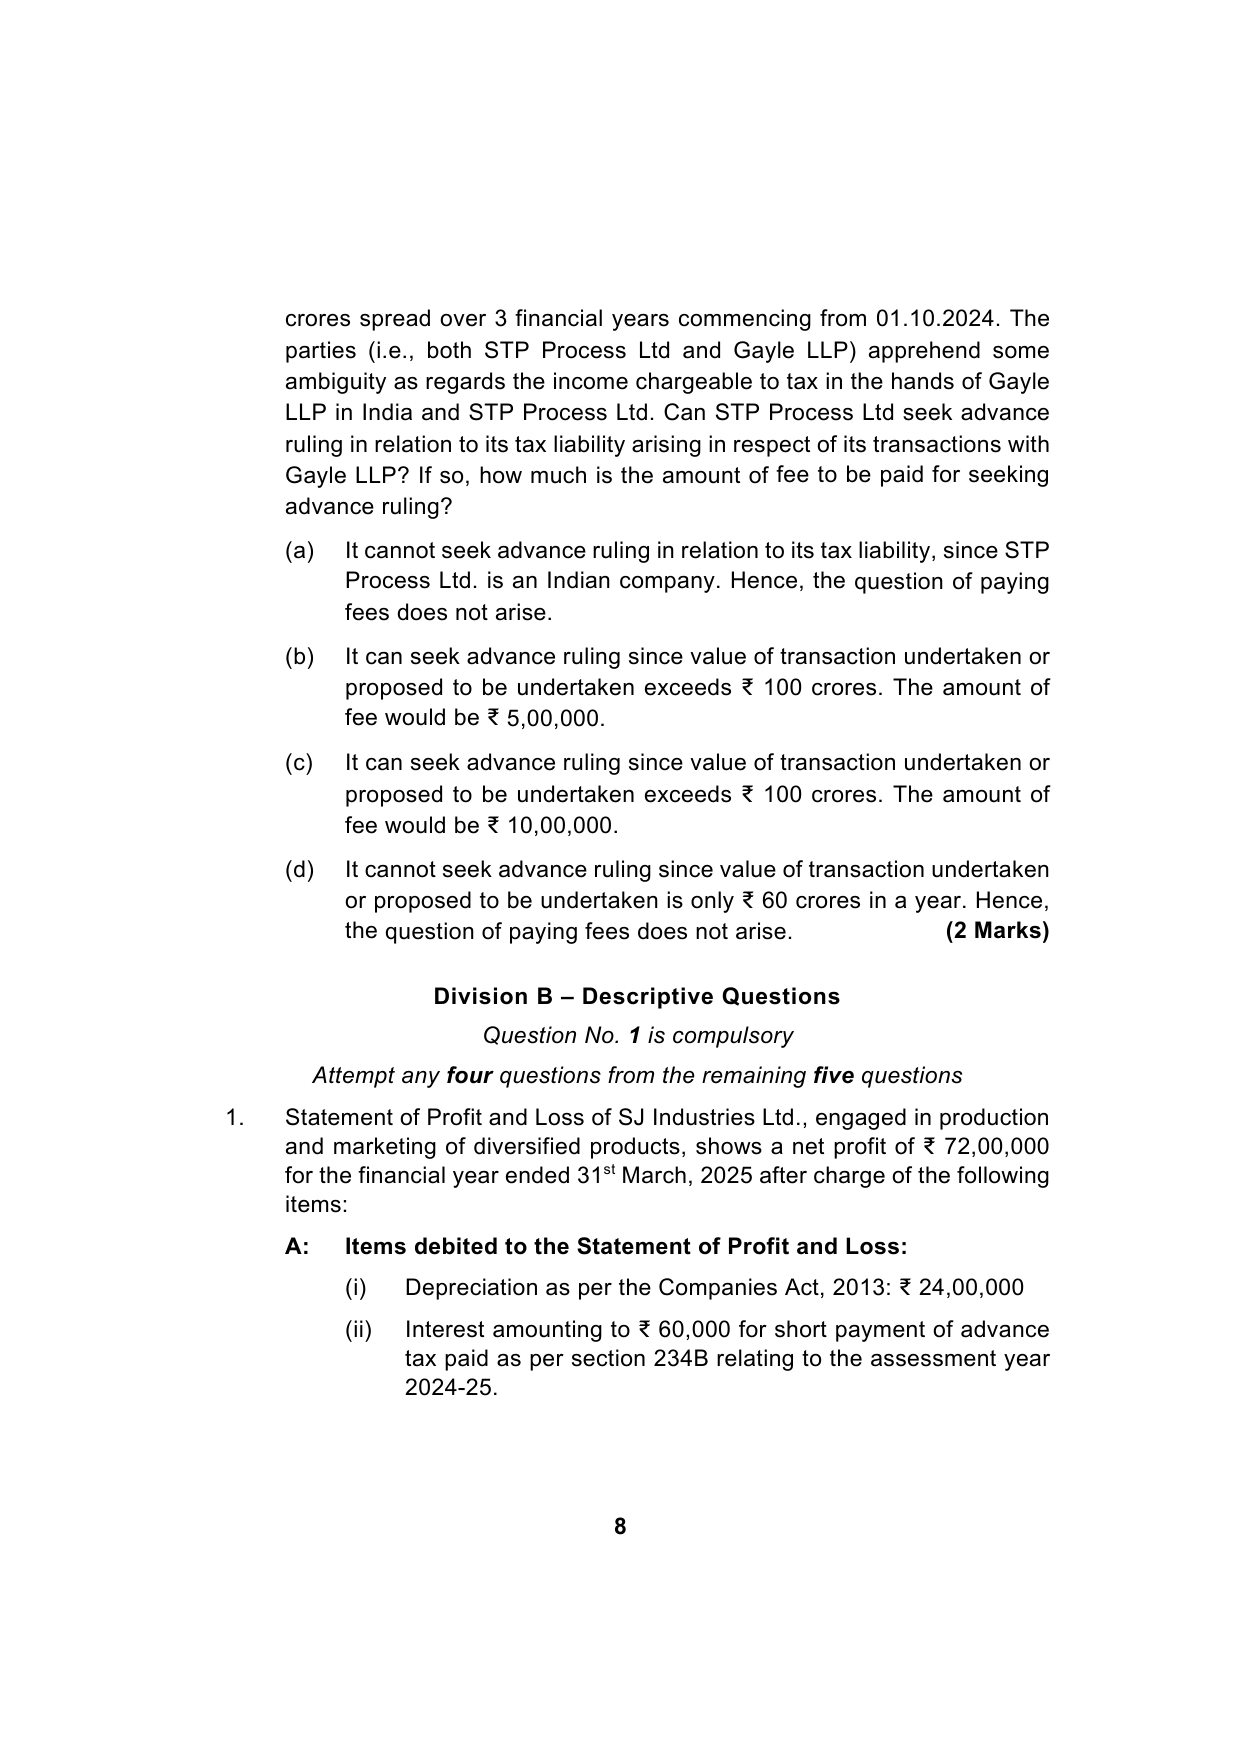
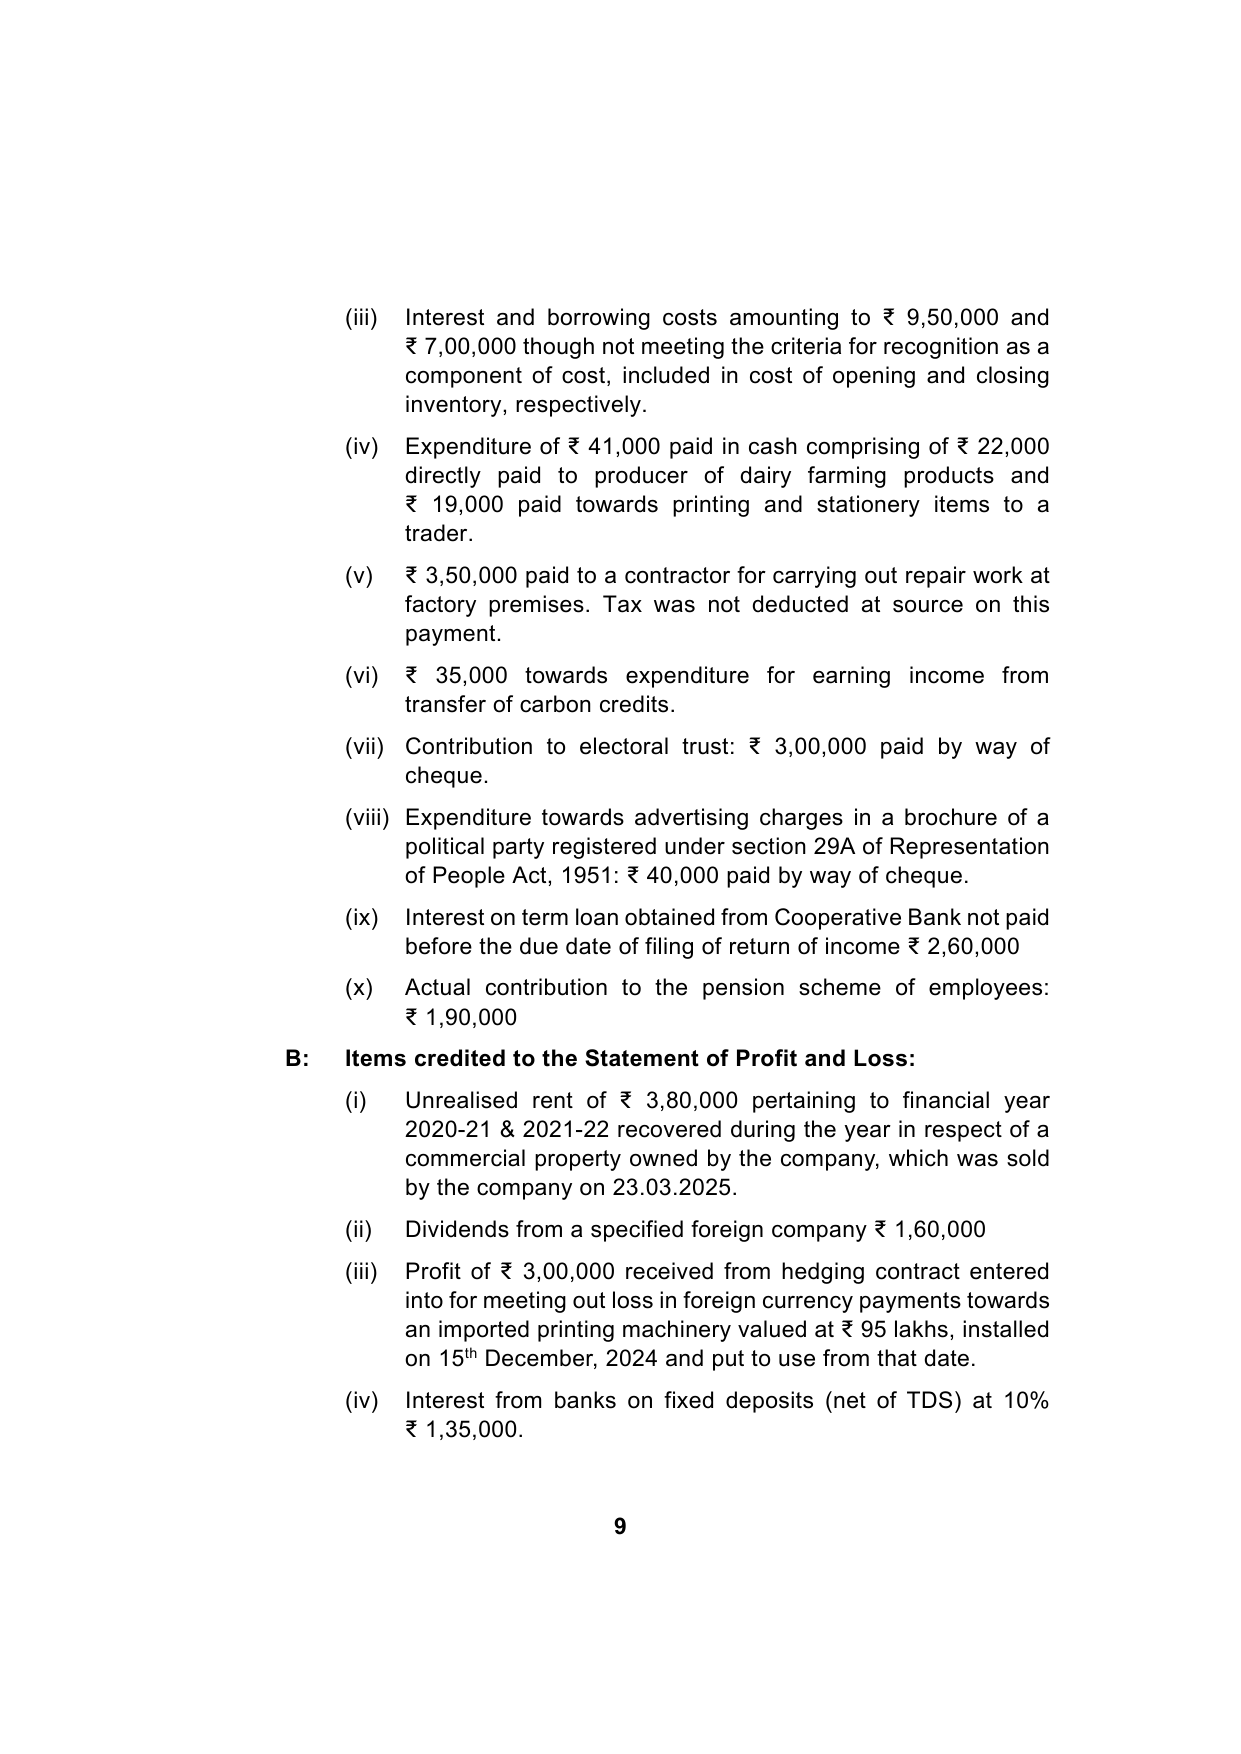
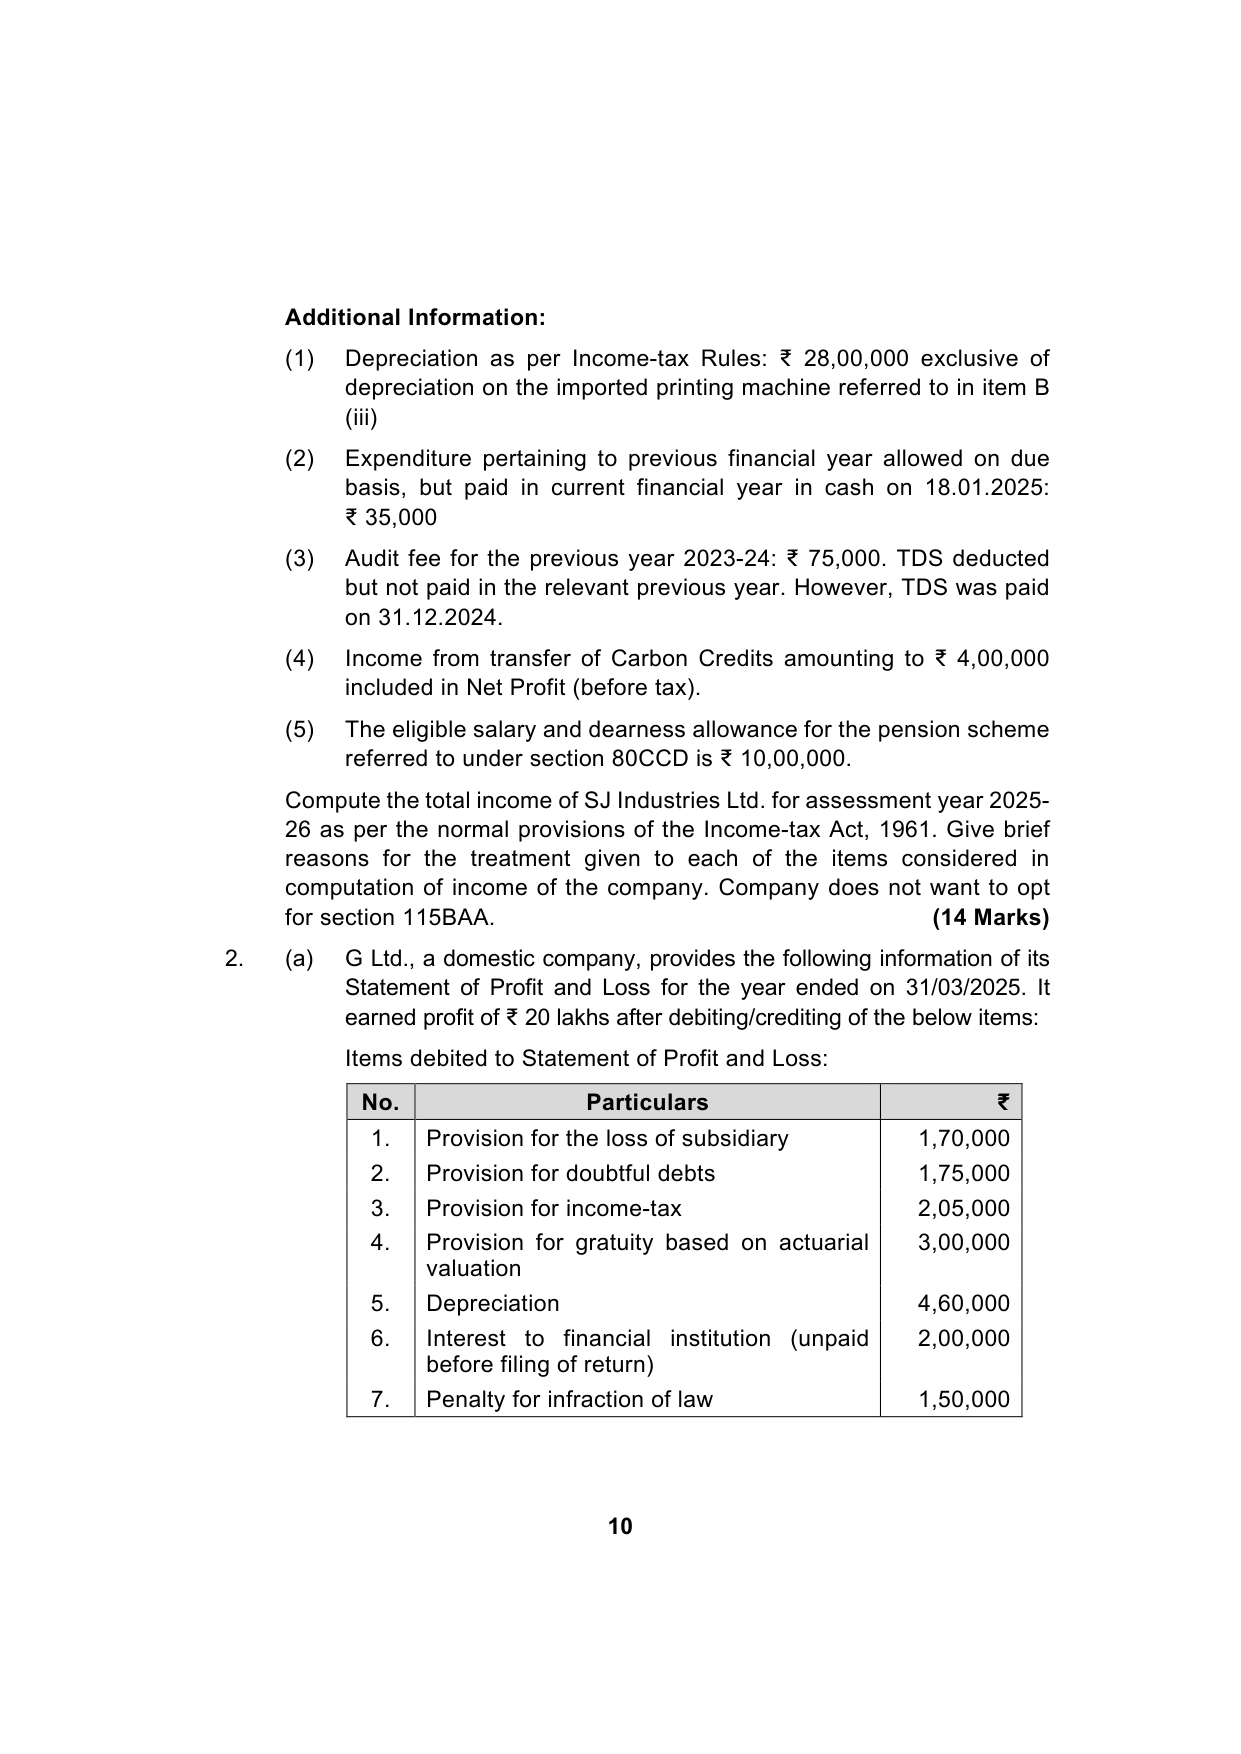
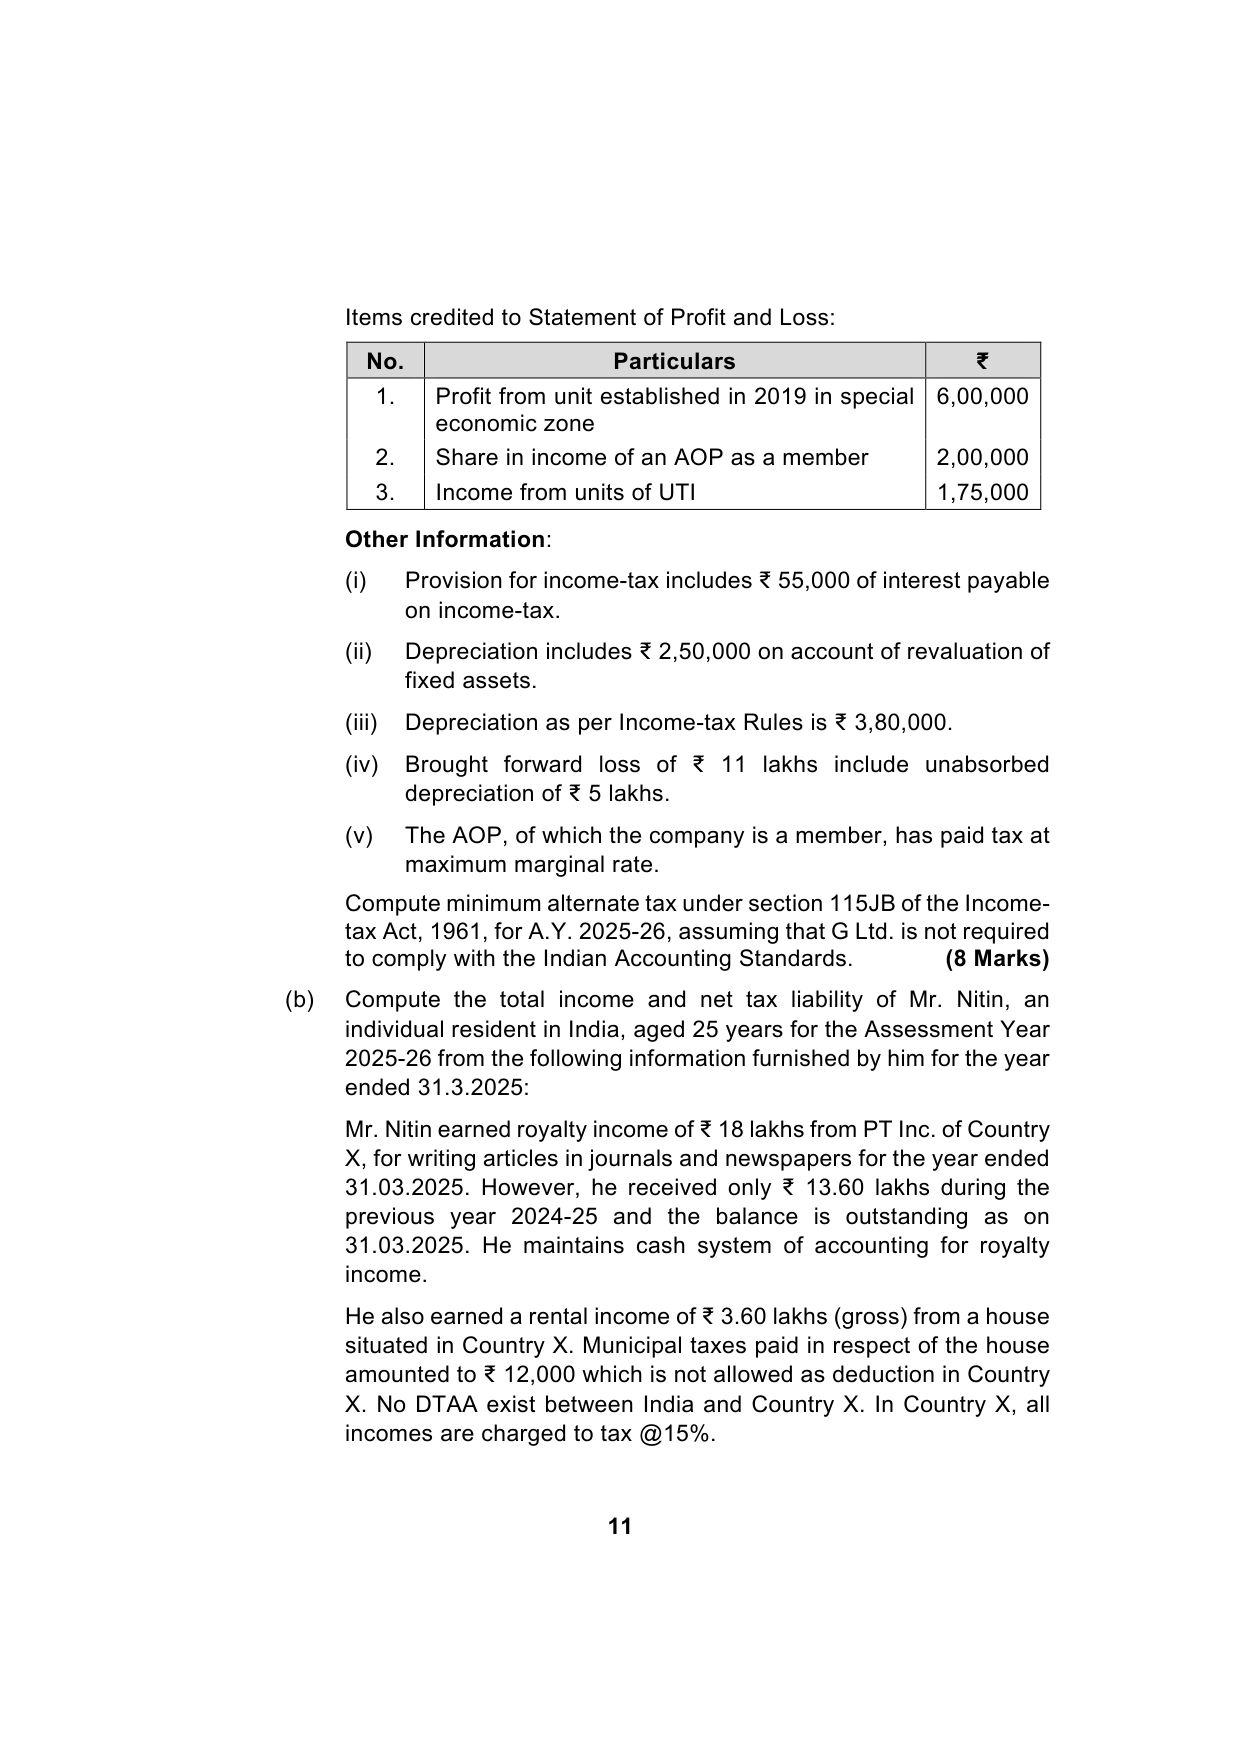
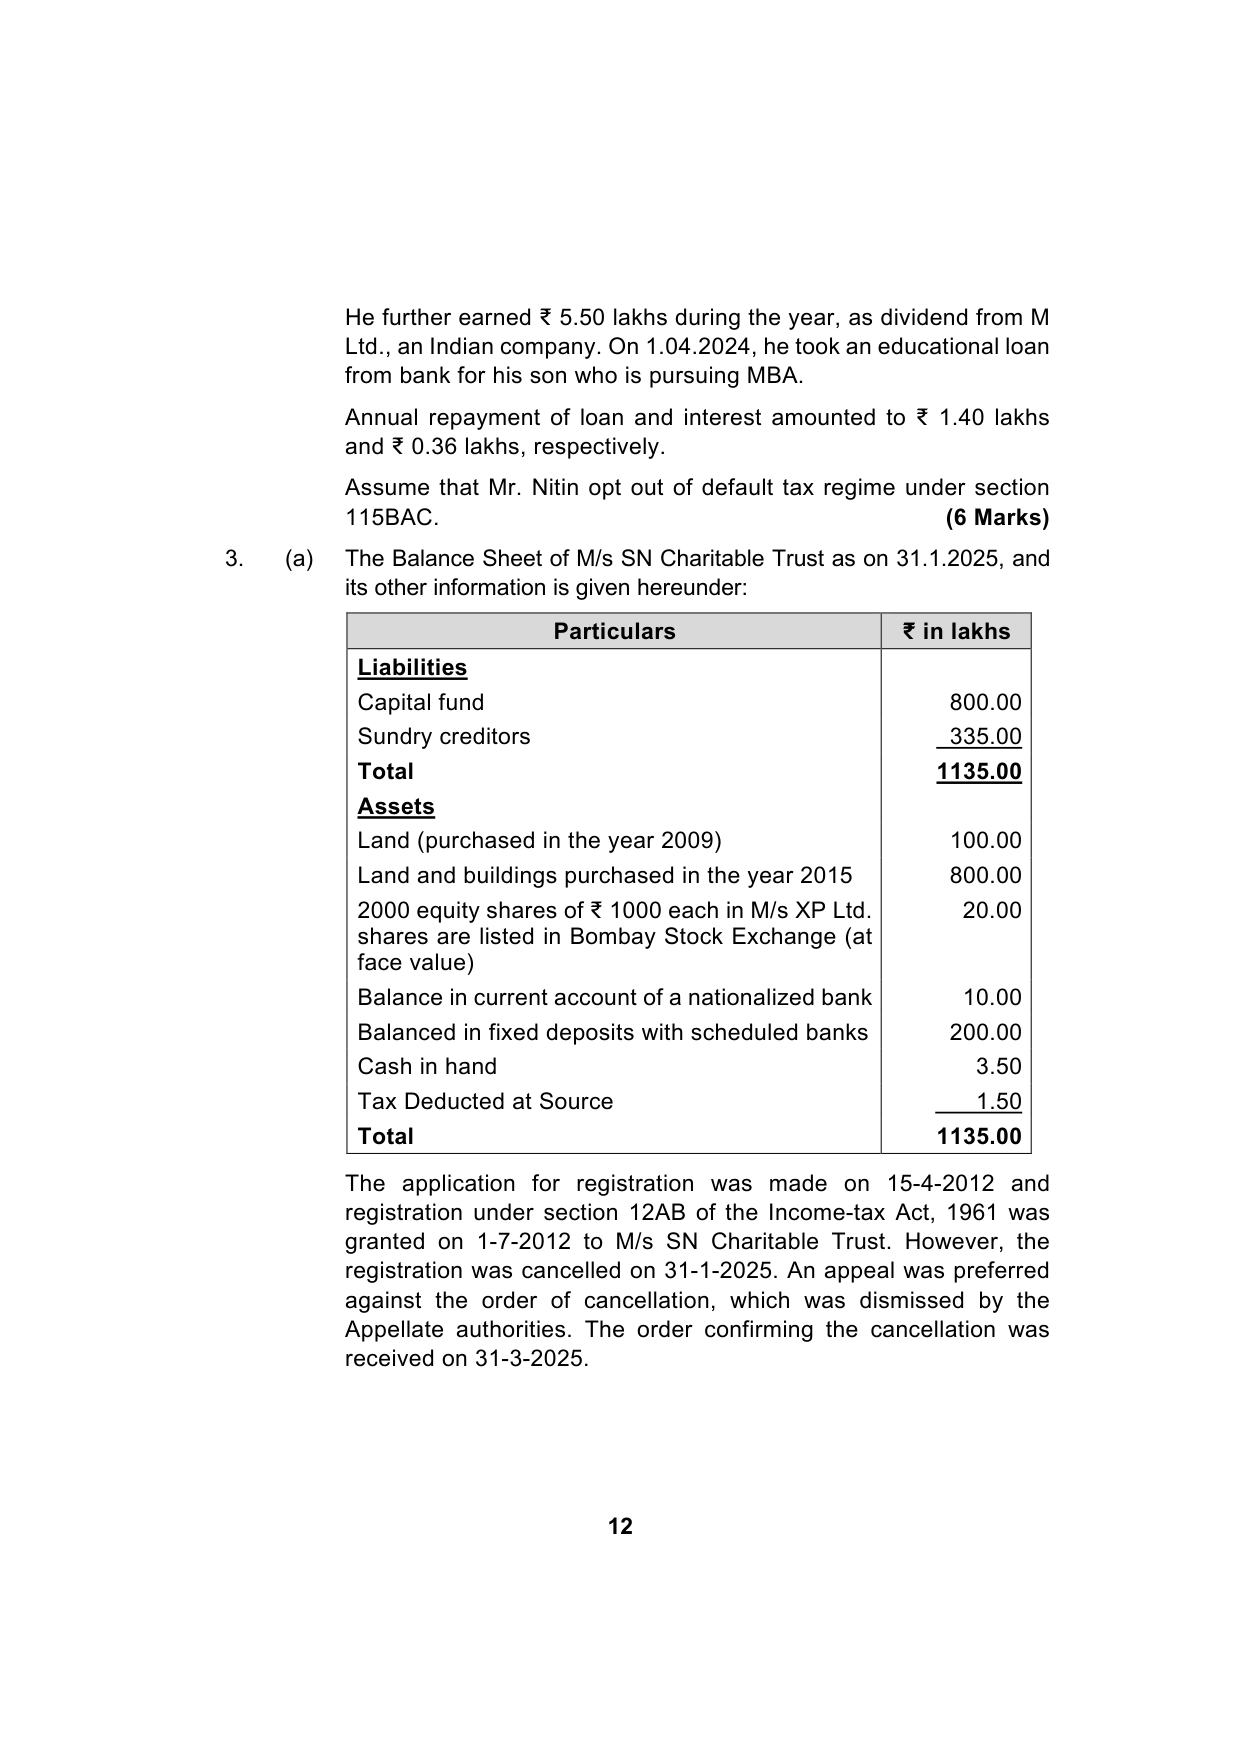
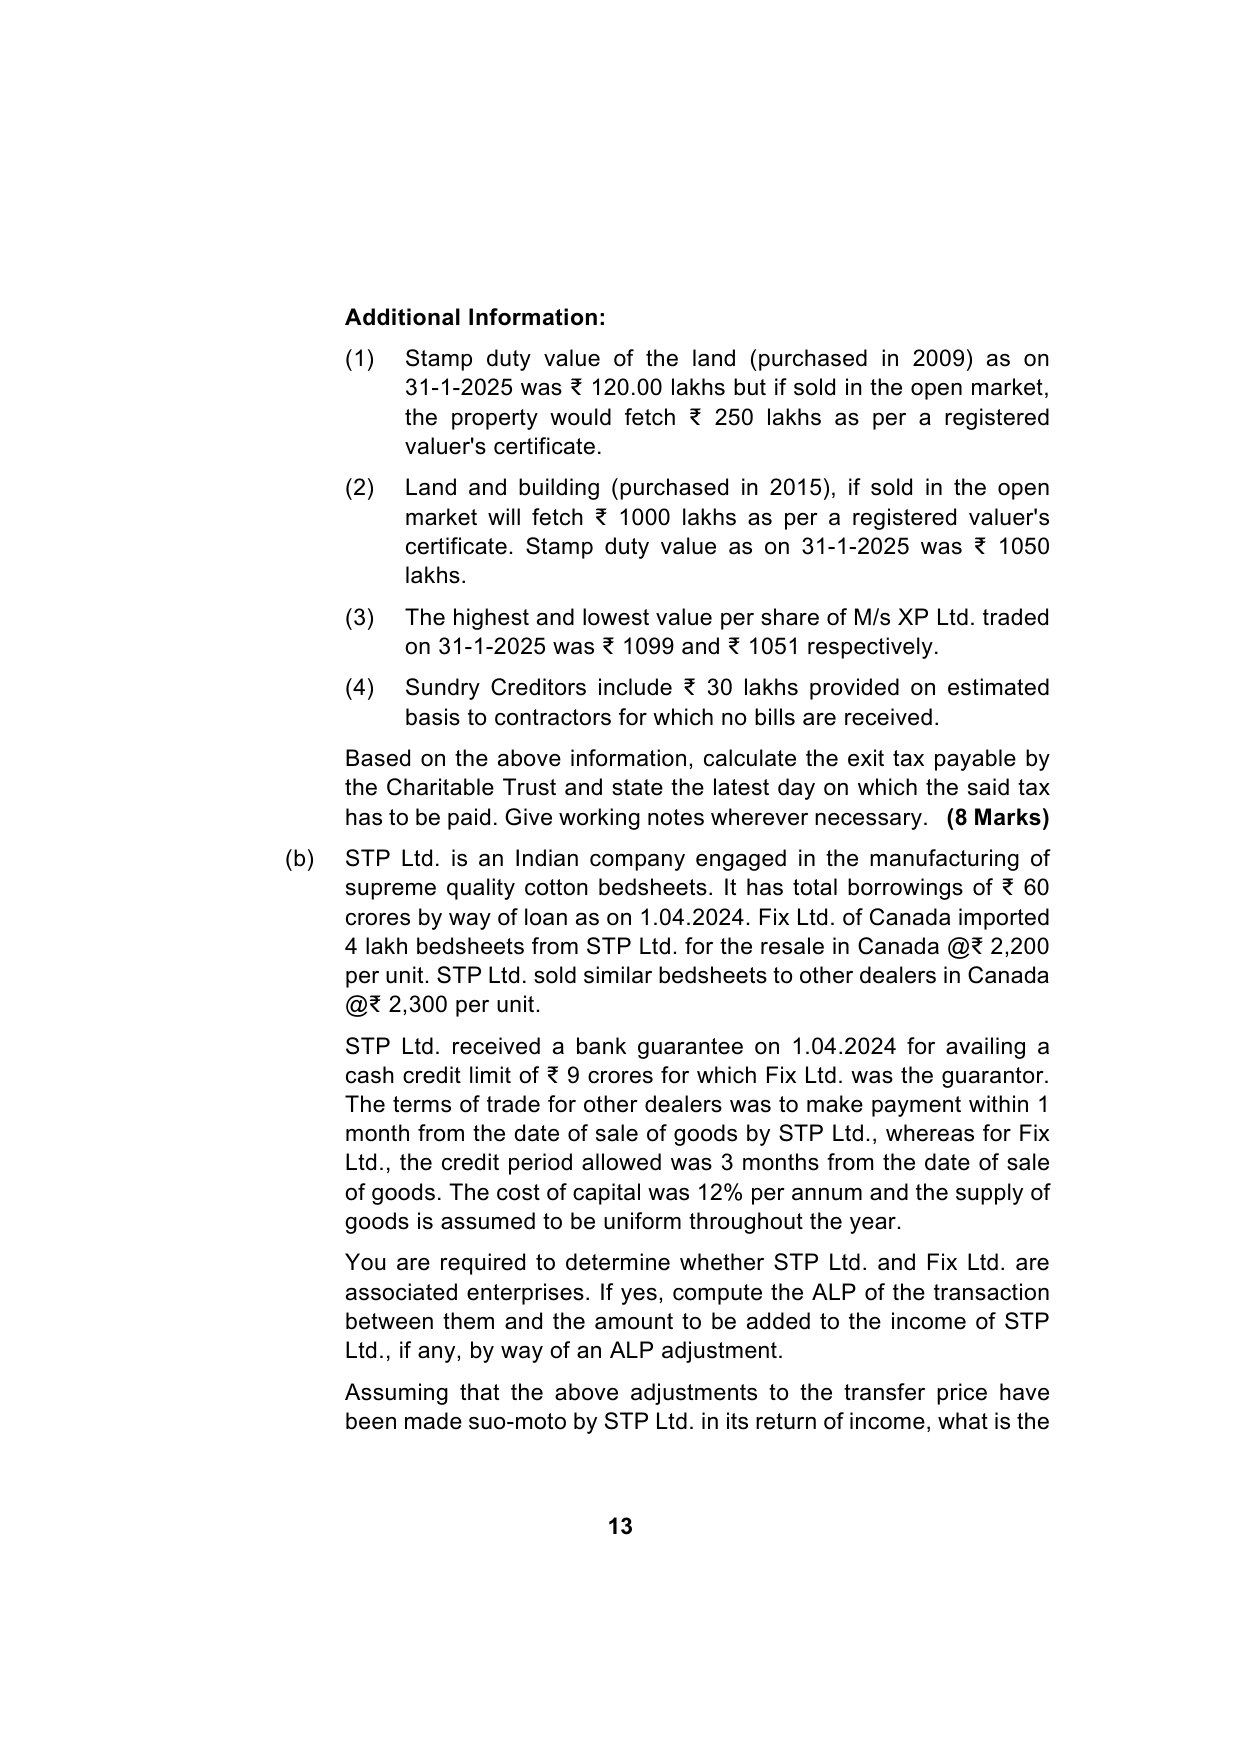
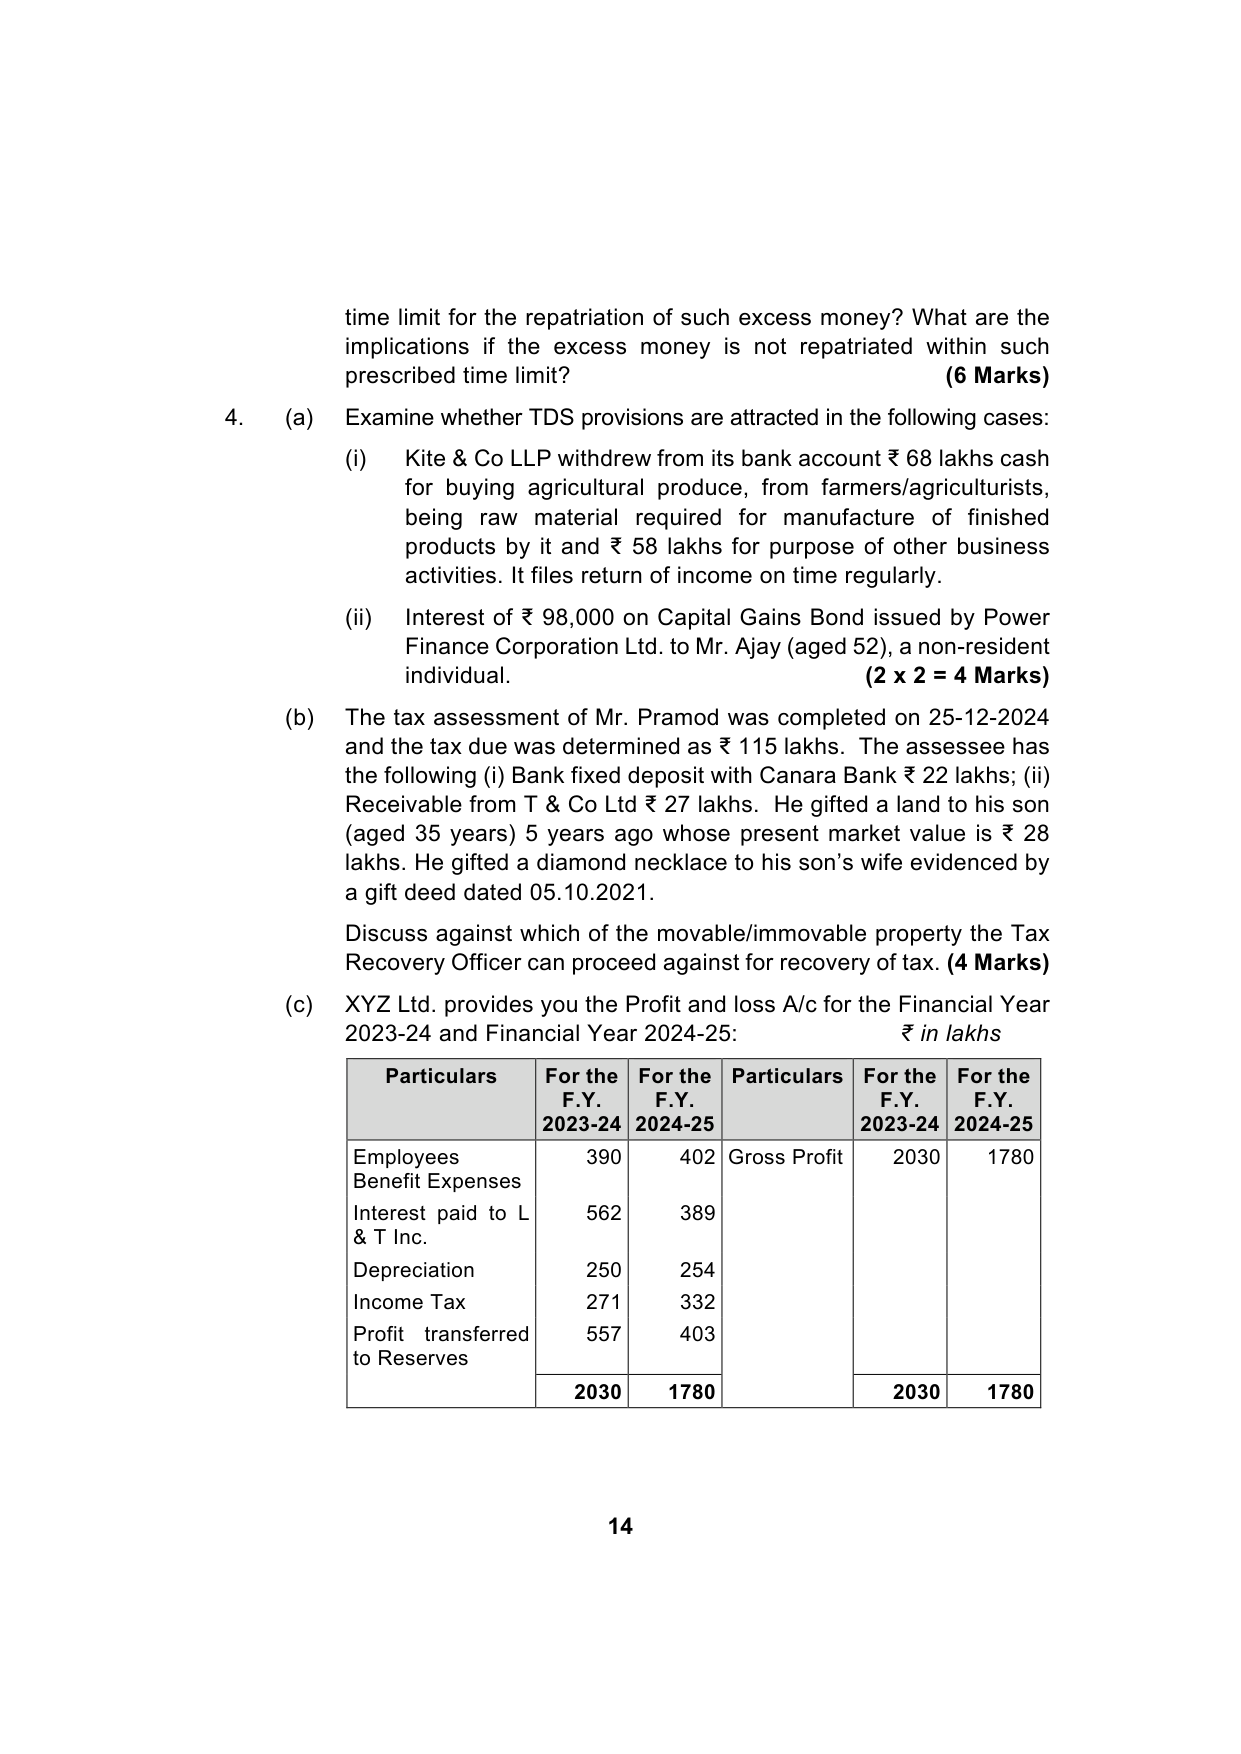
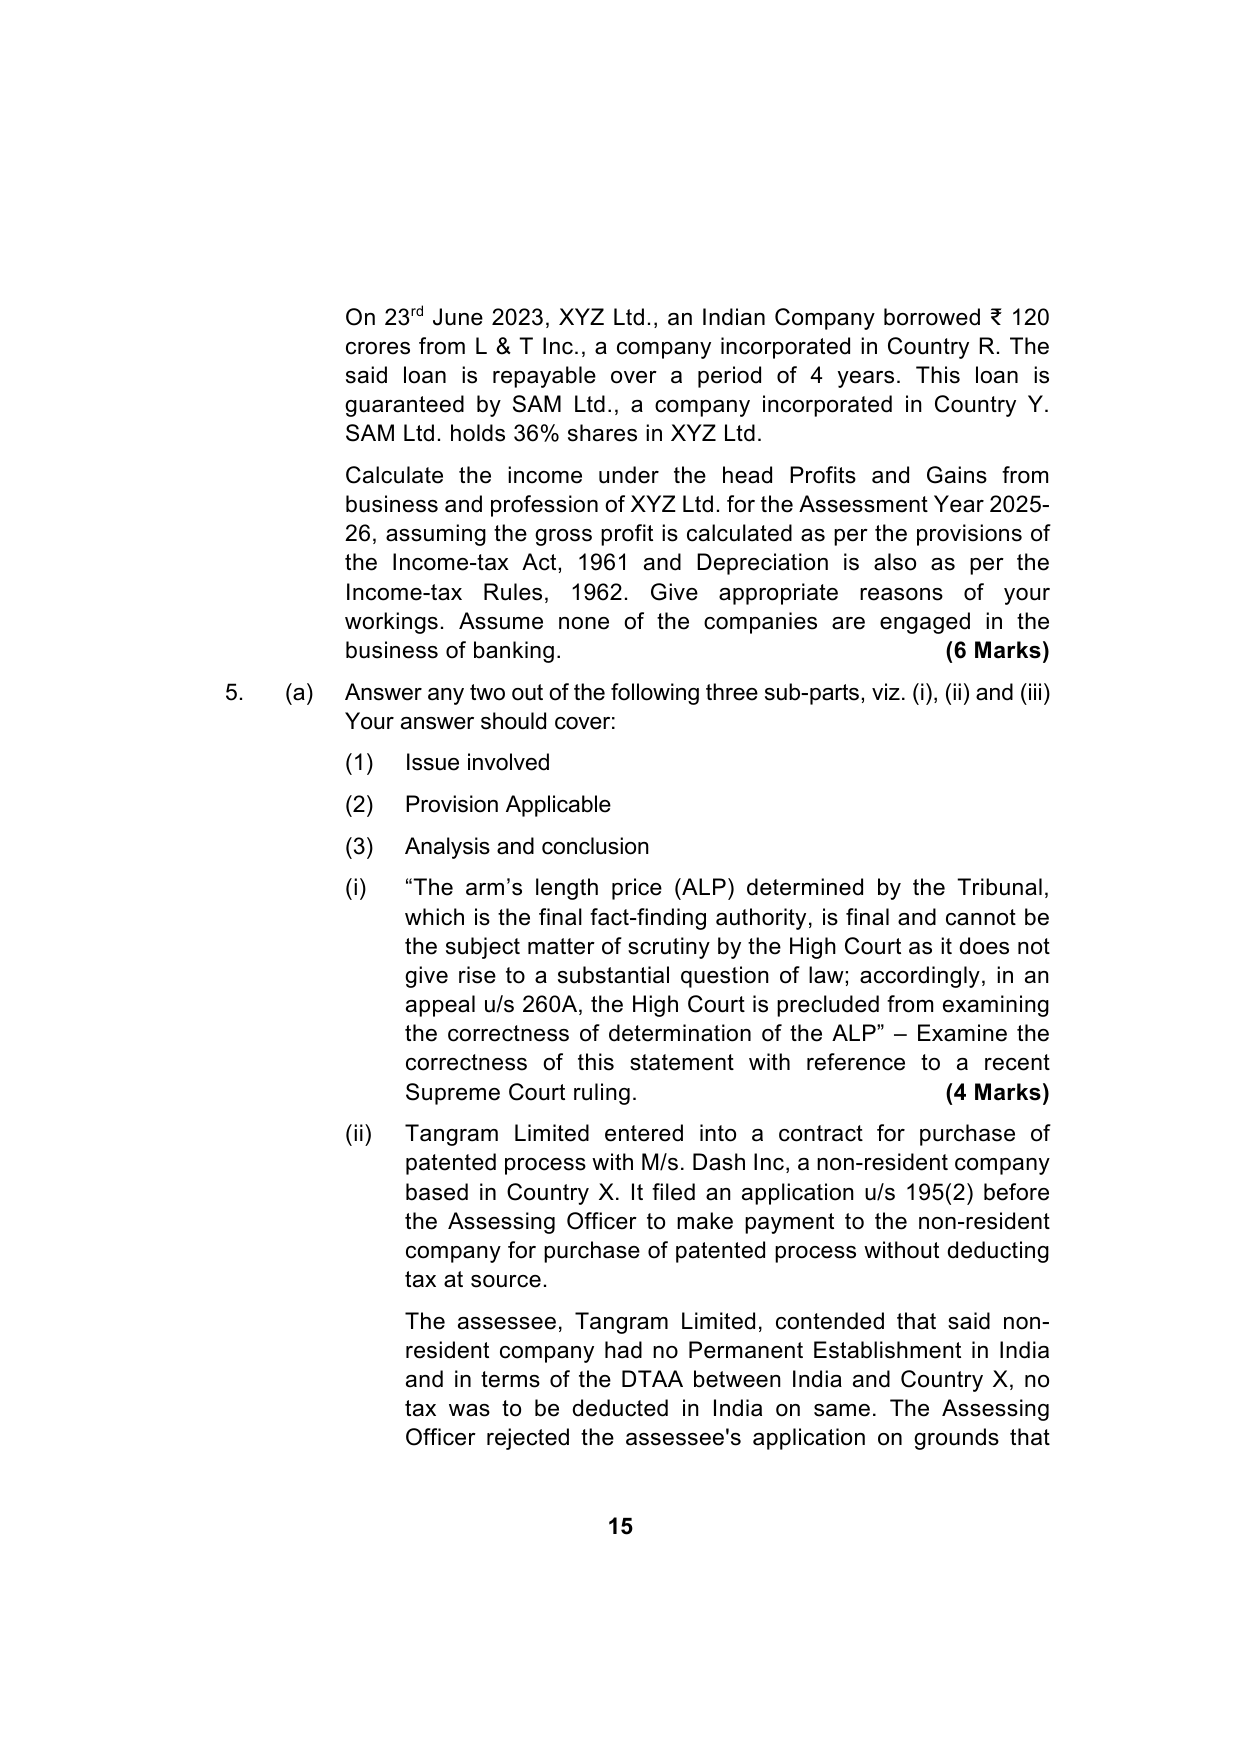
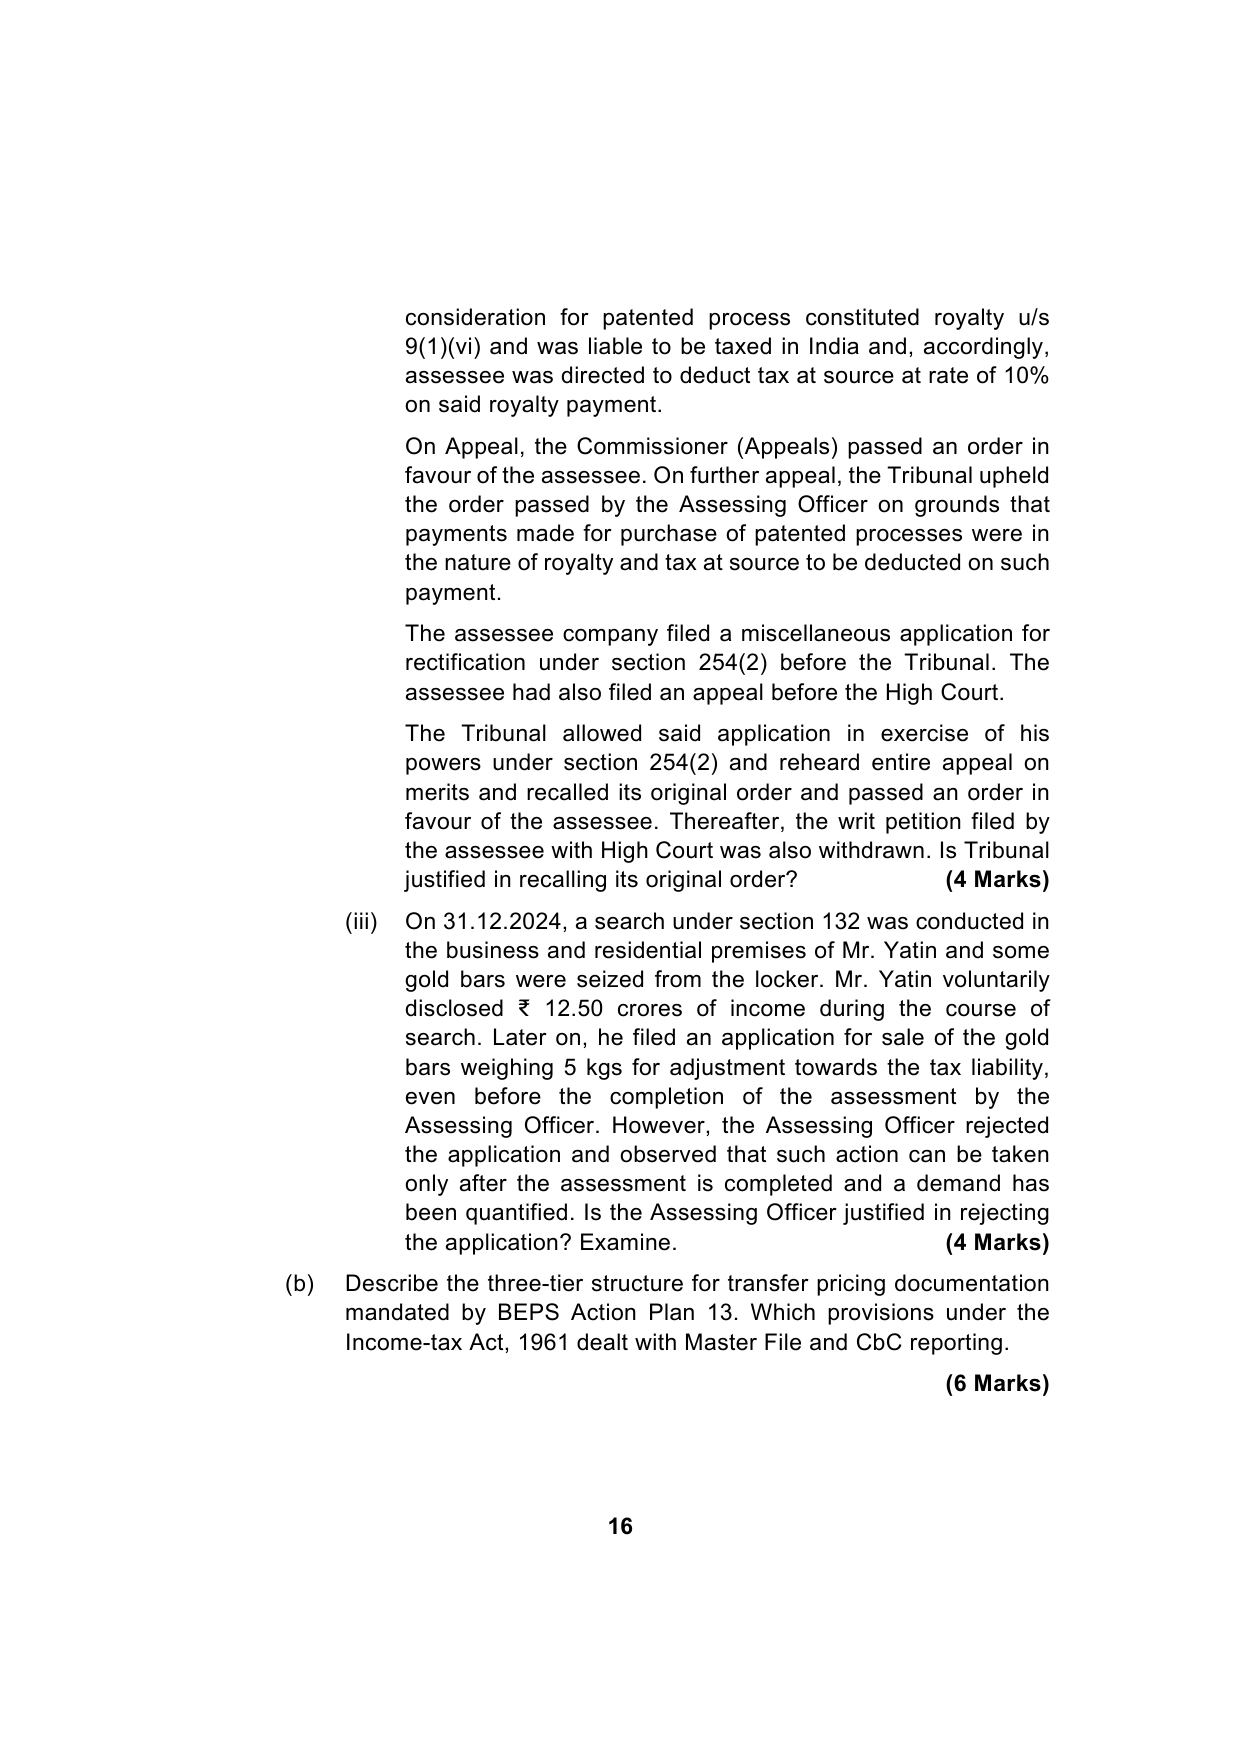
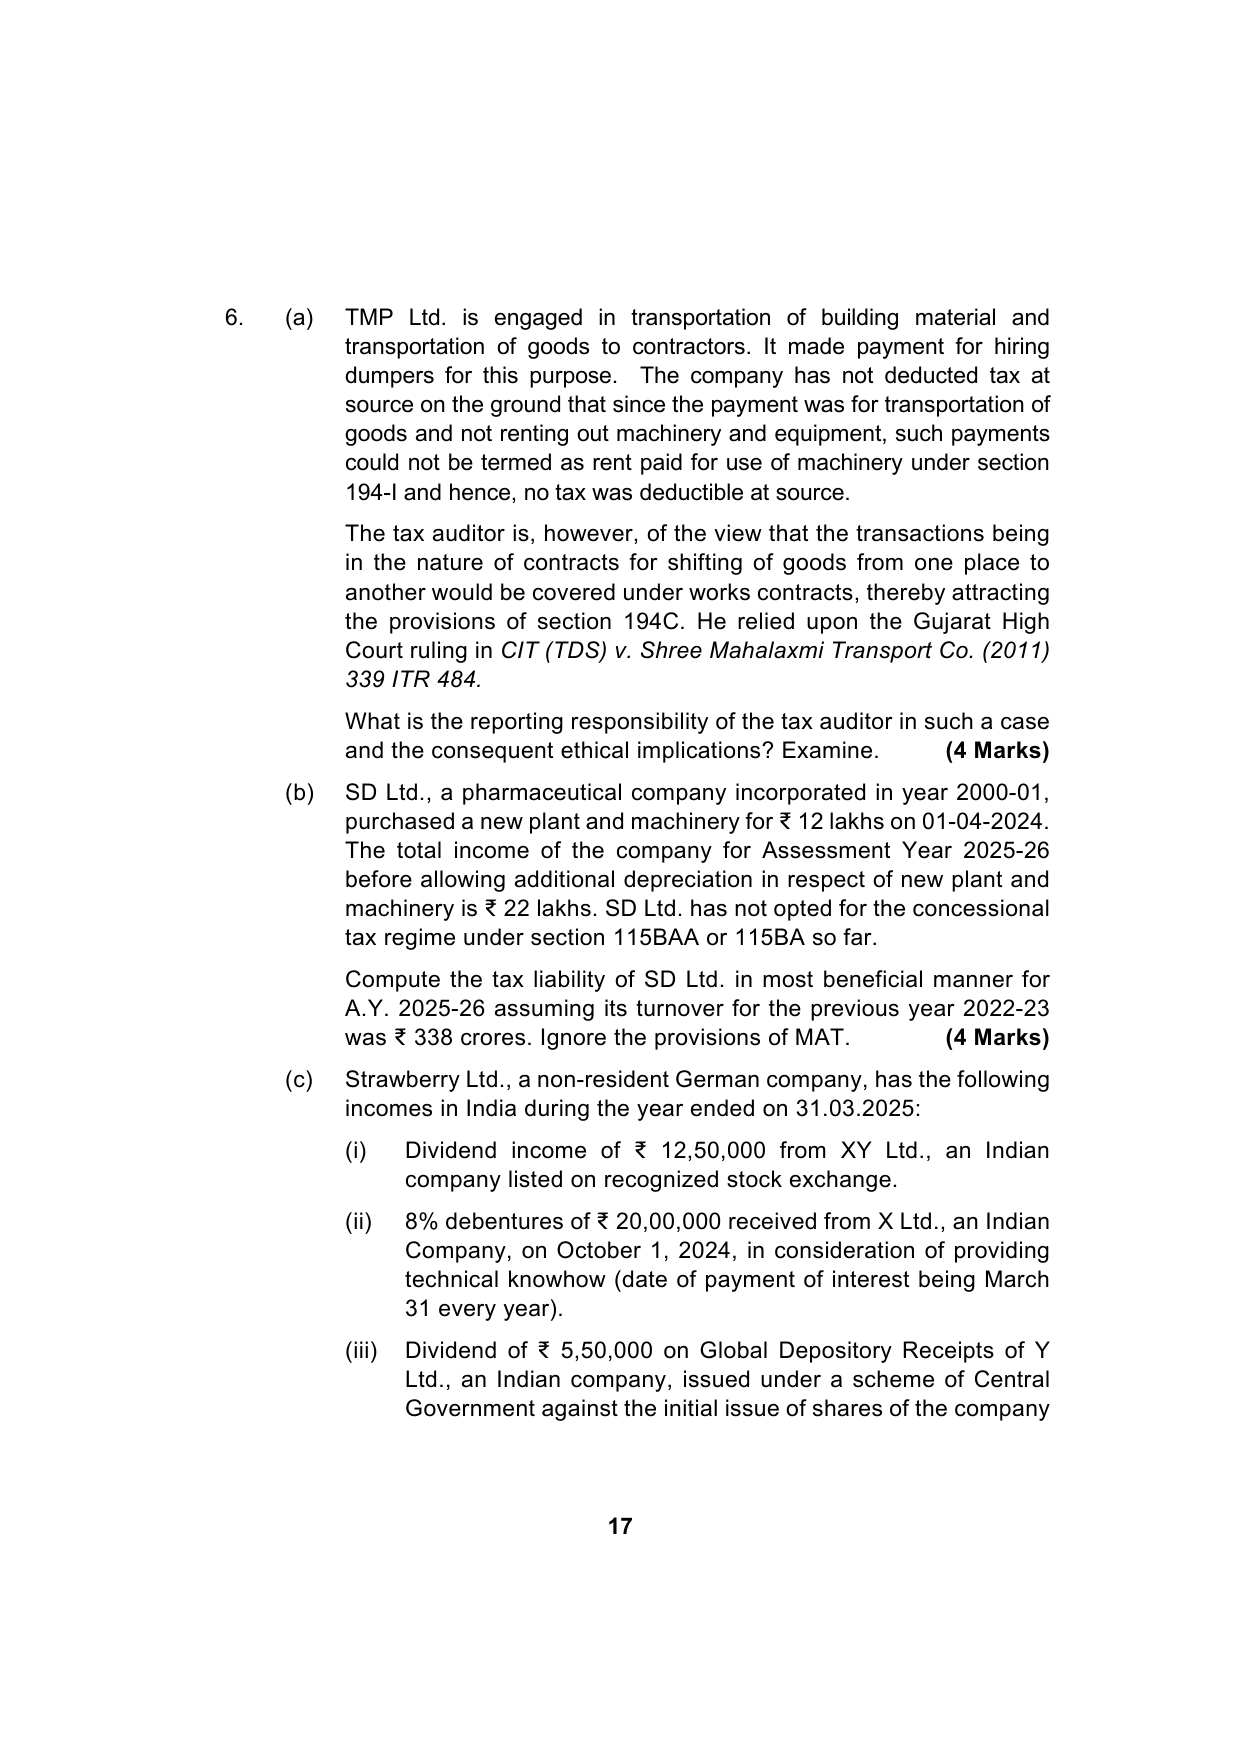
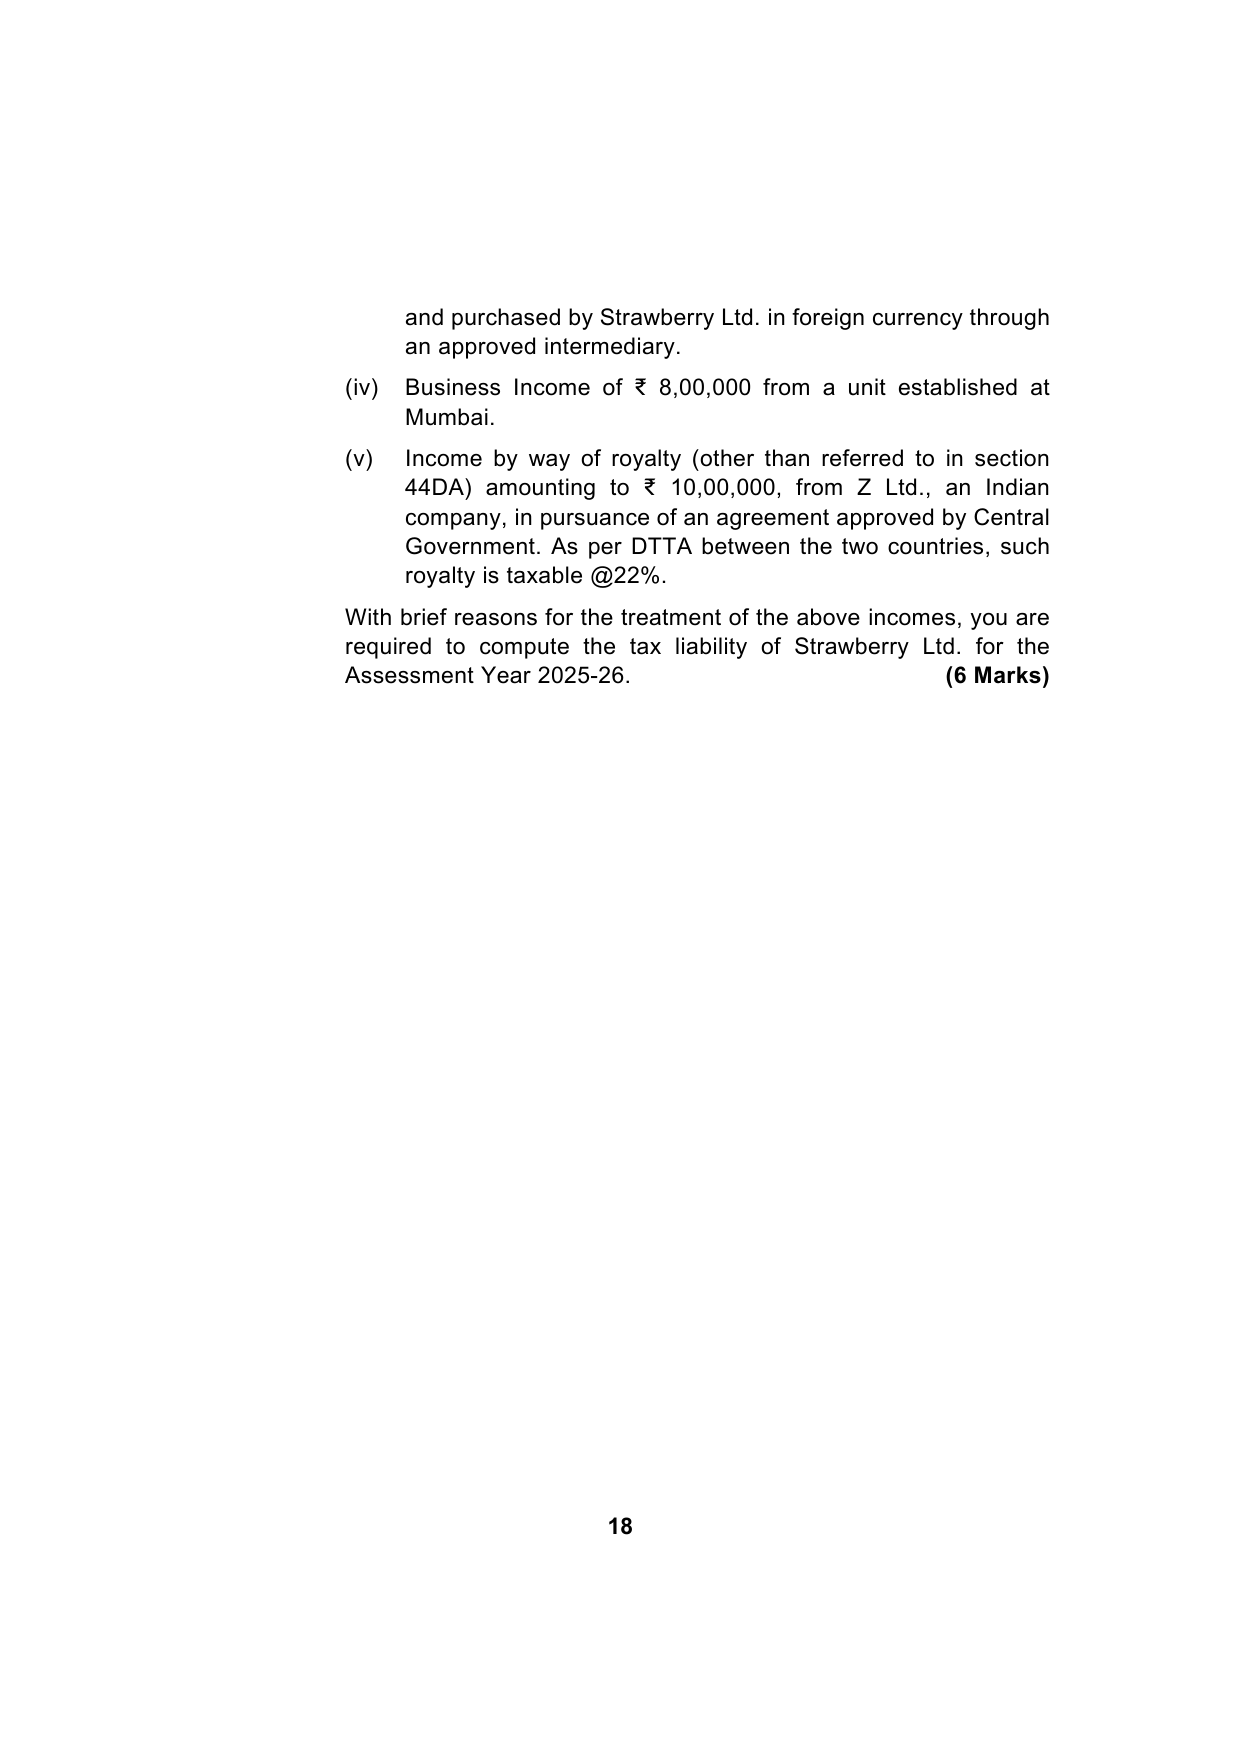
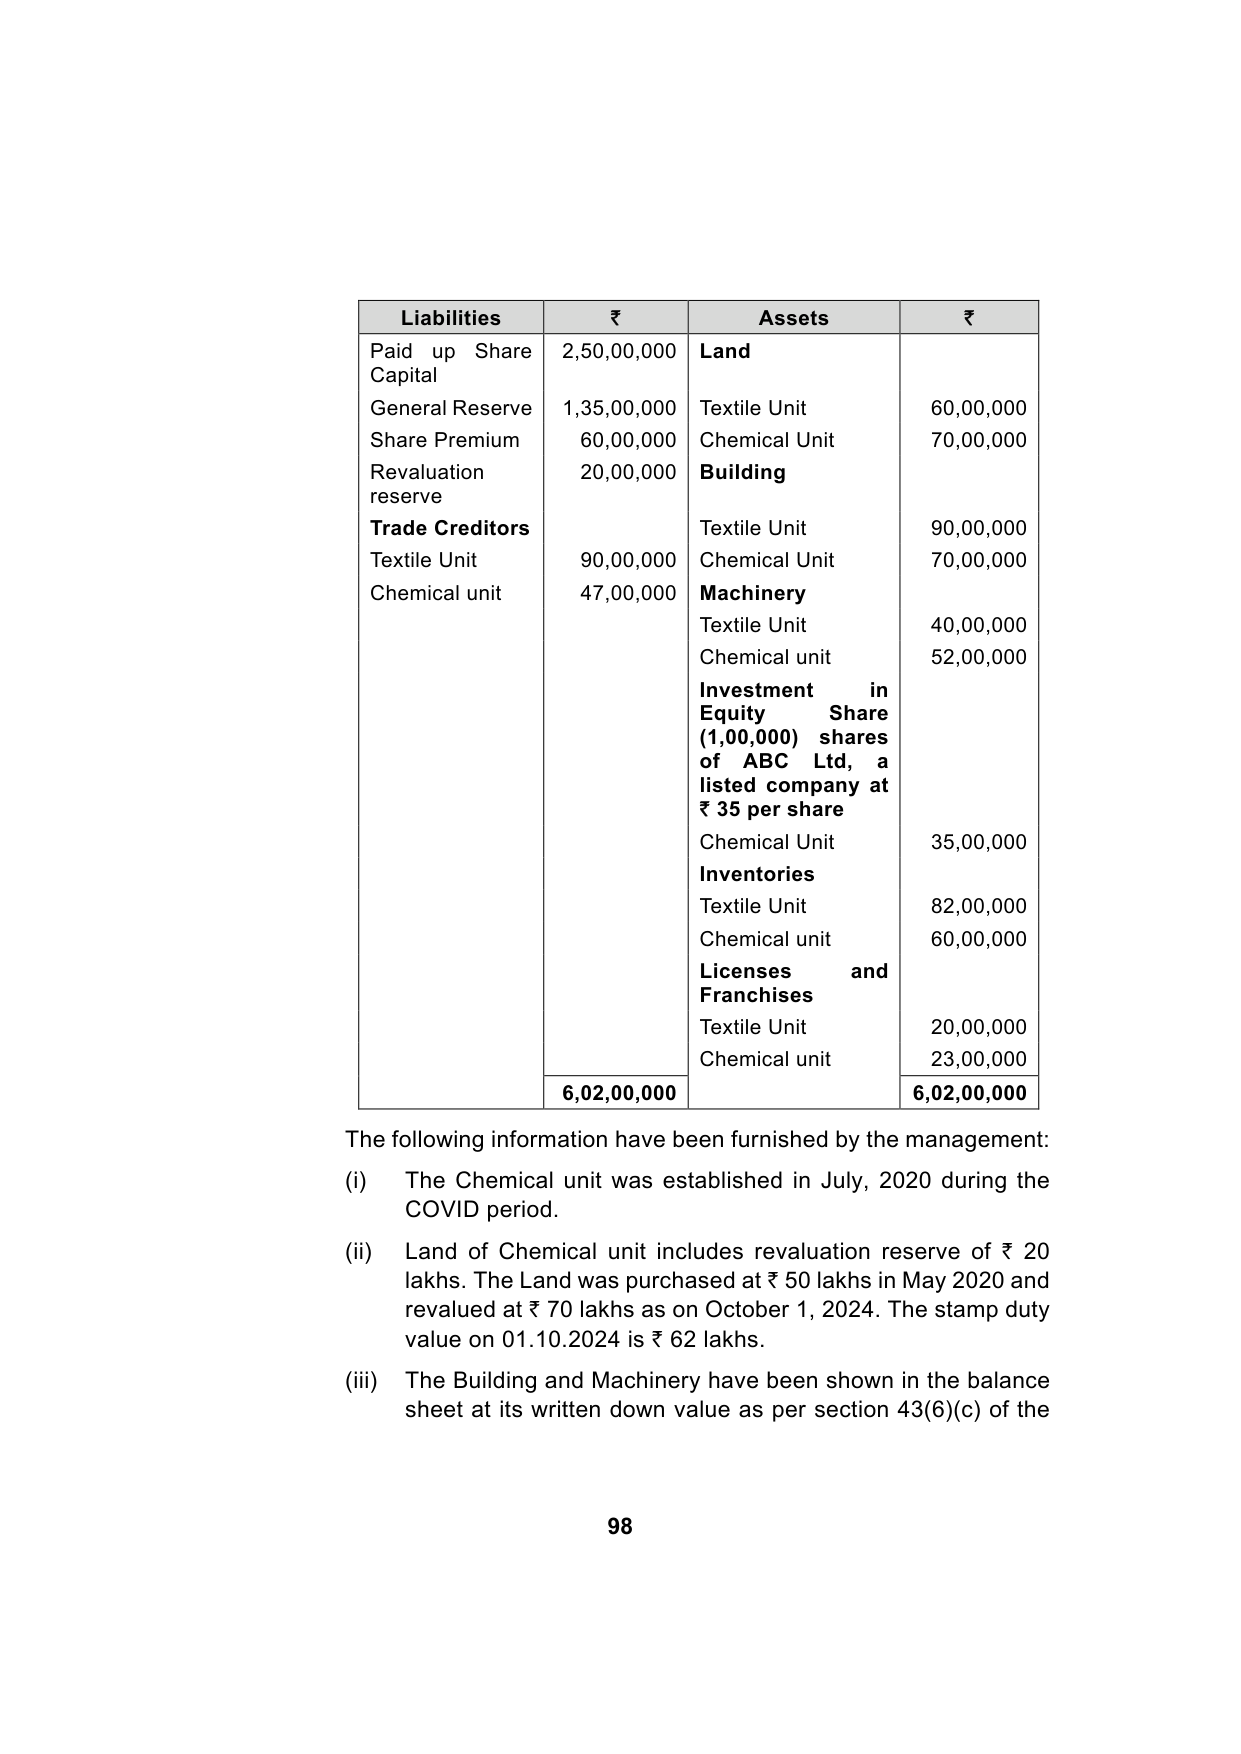
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 2
Question
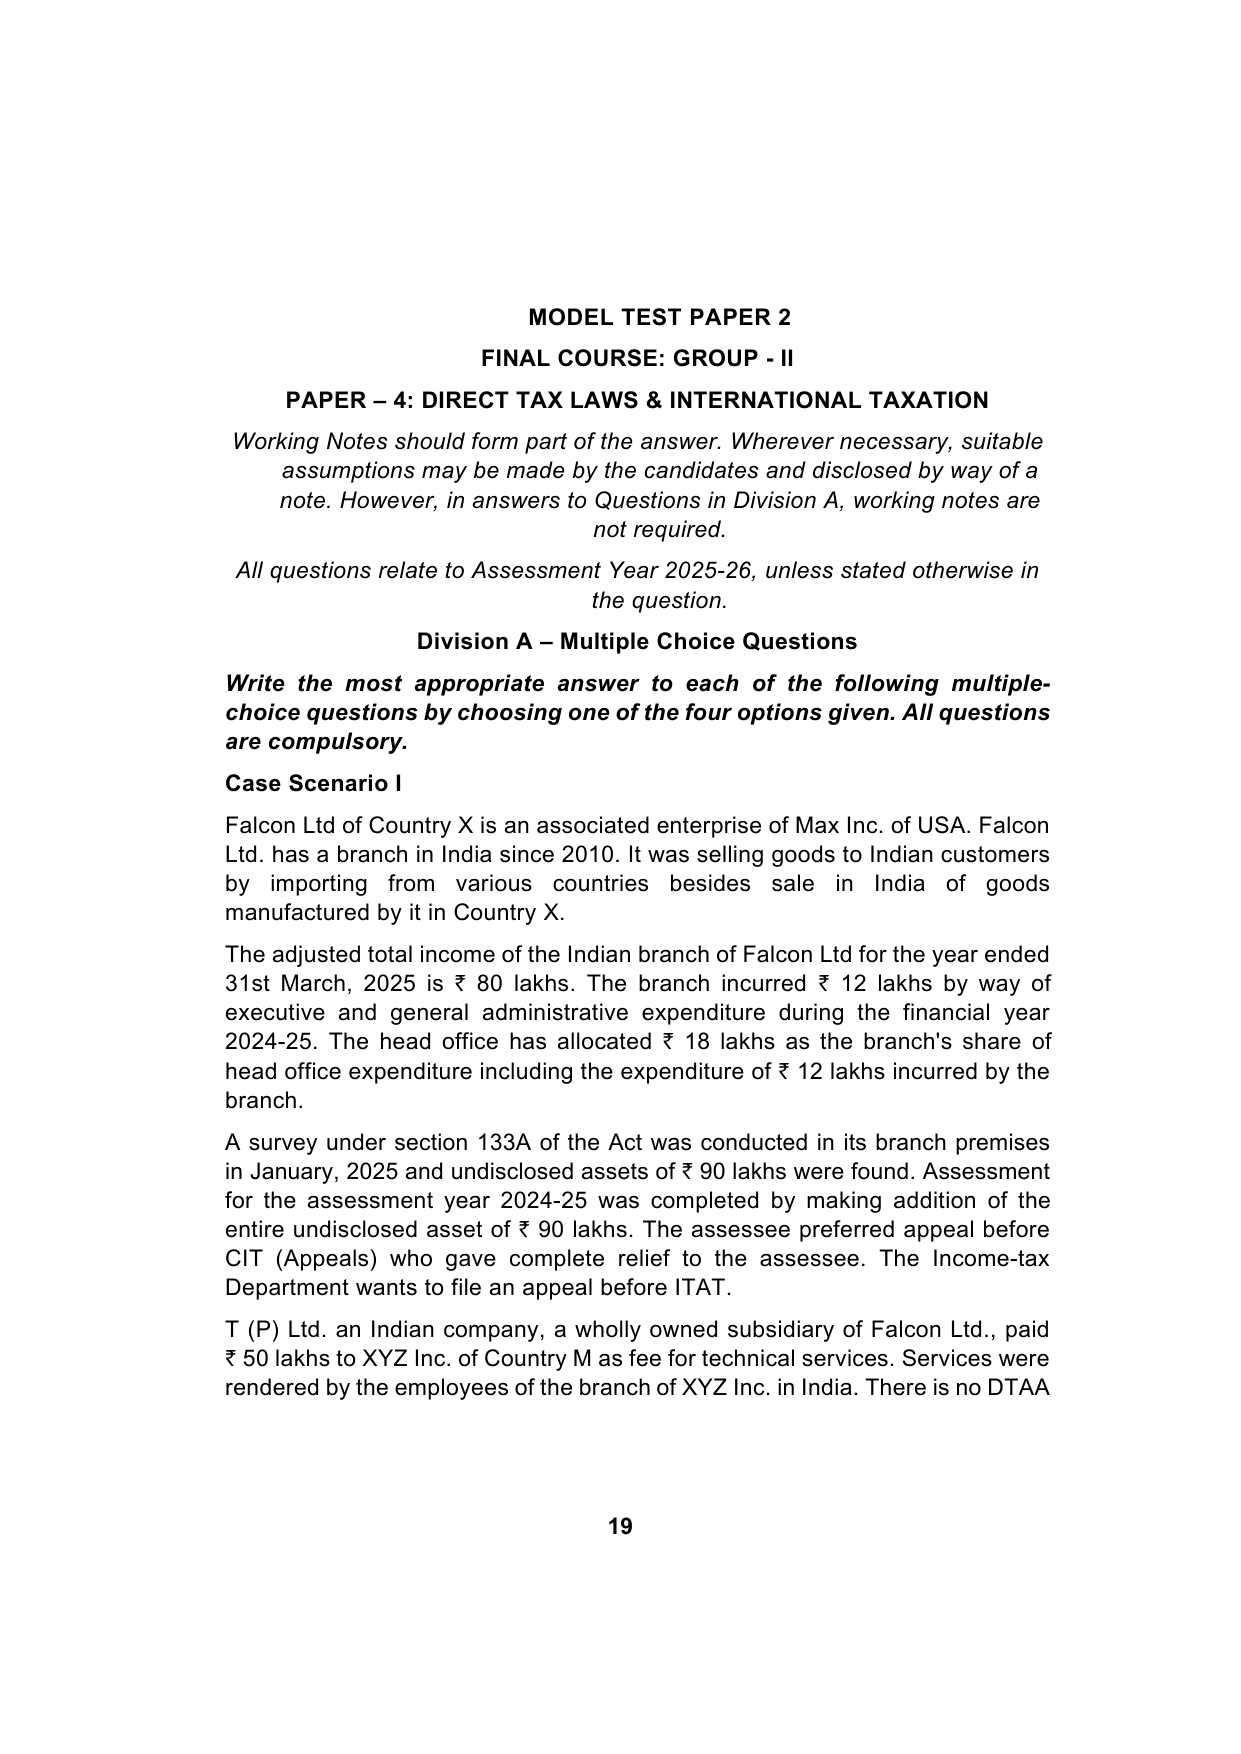
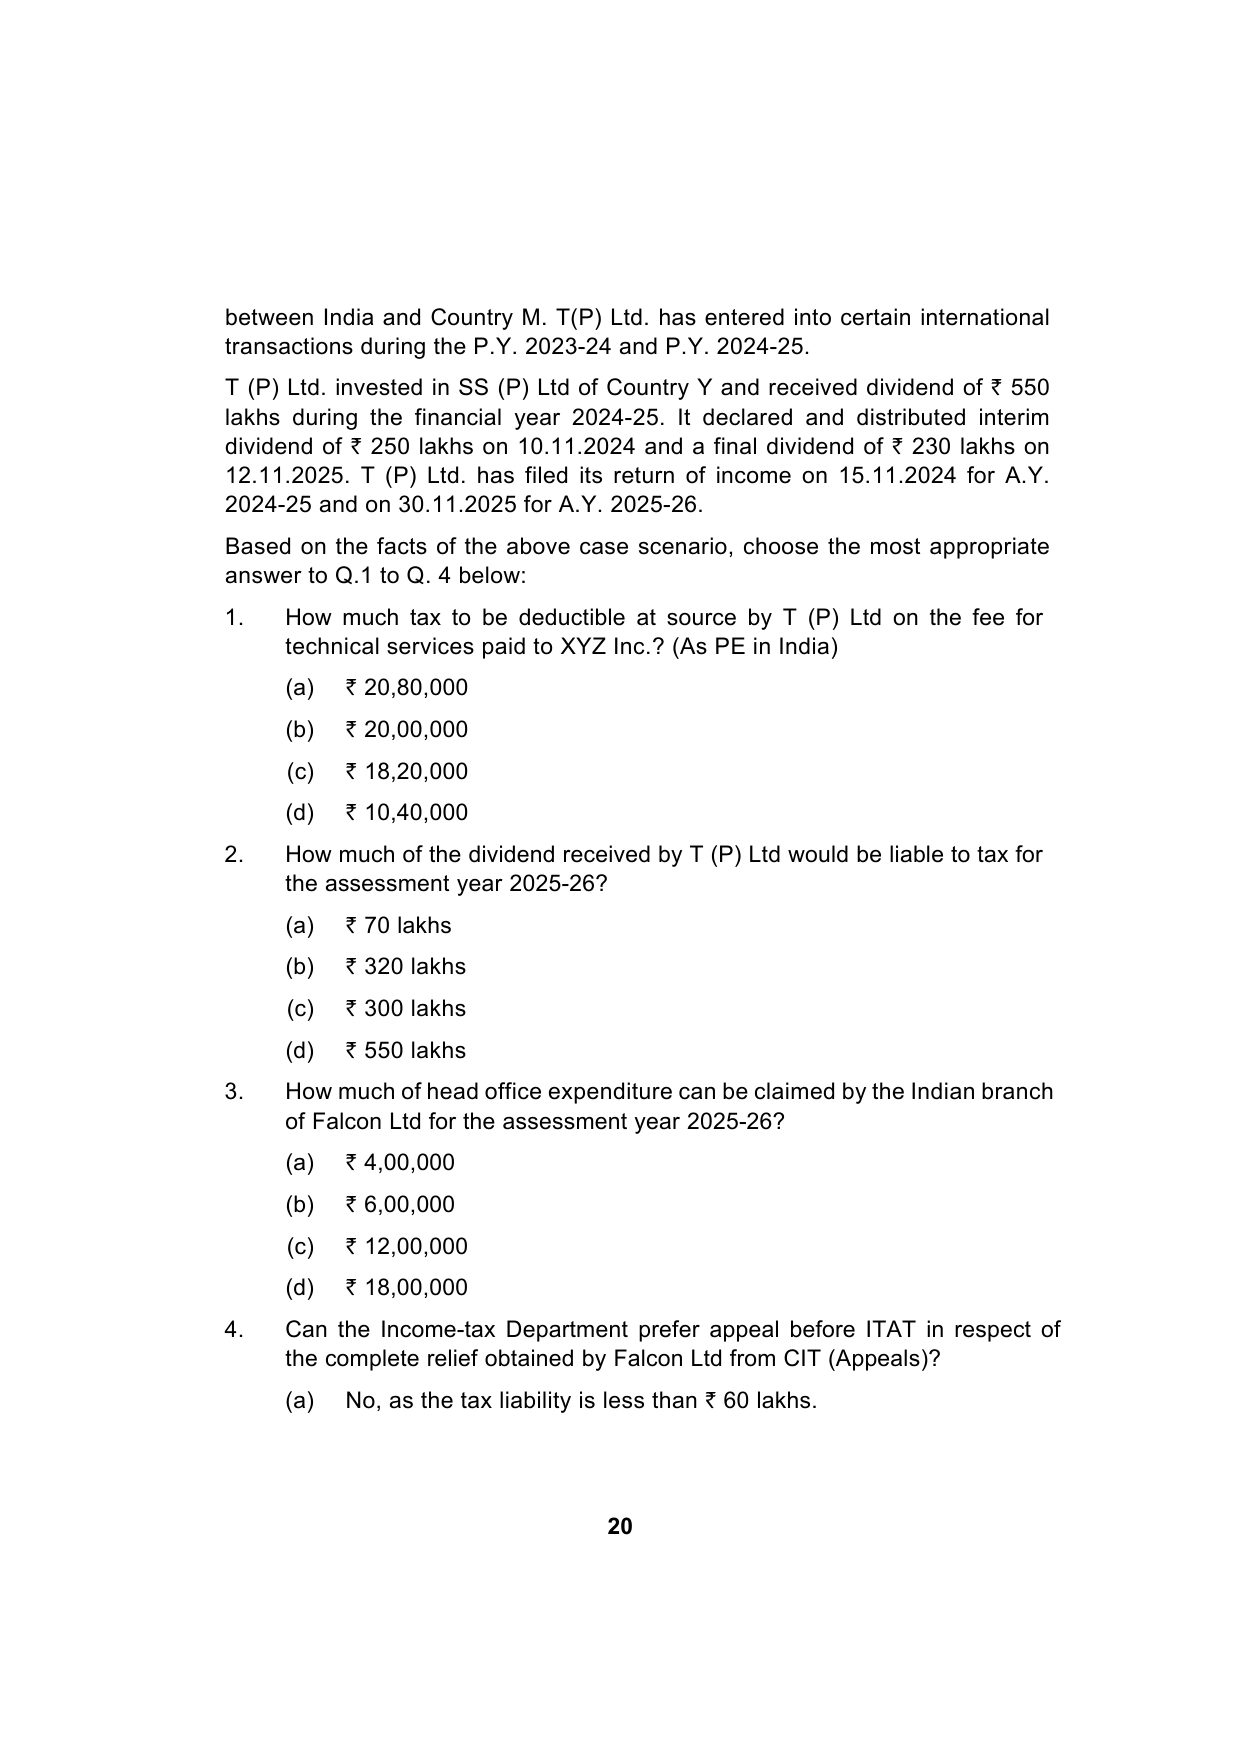
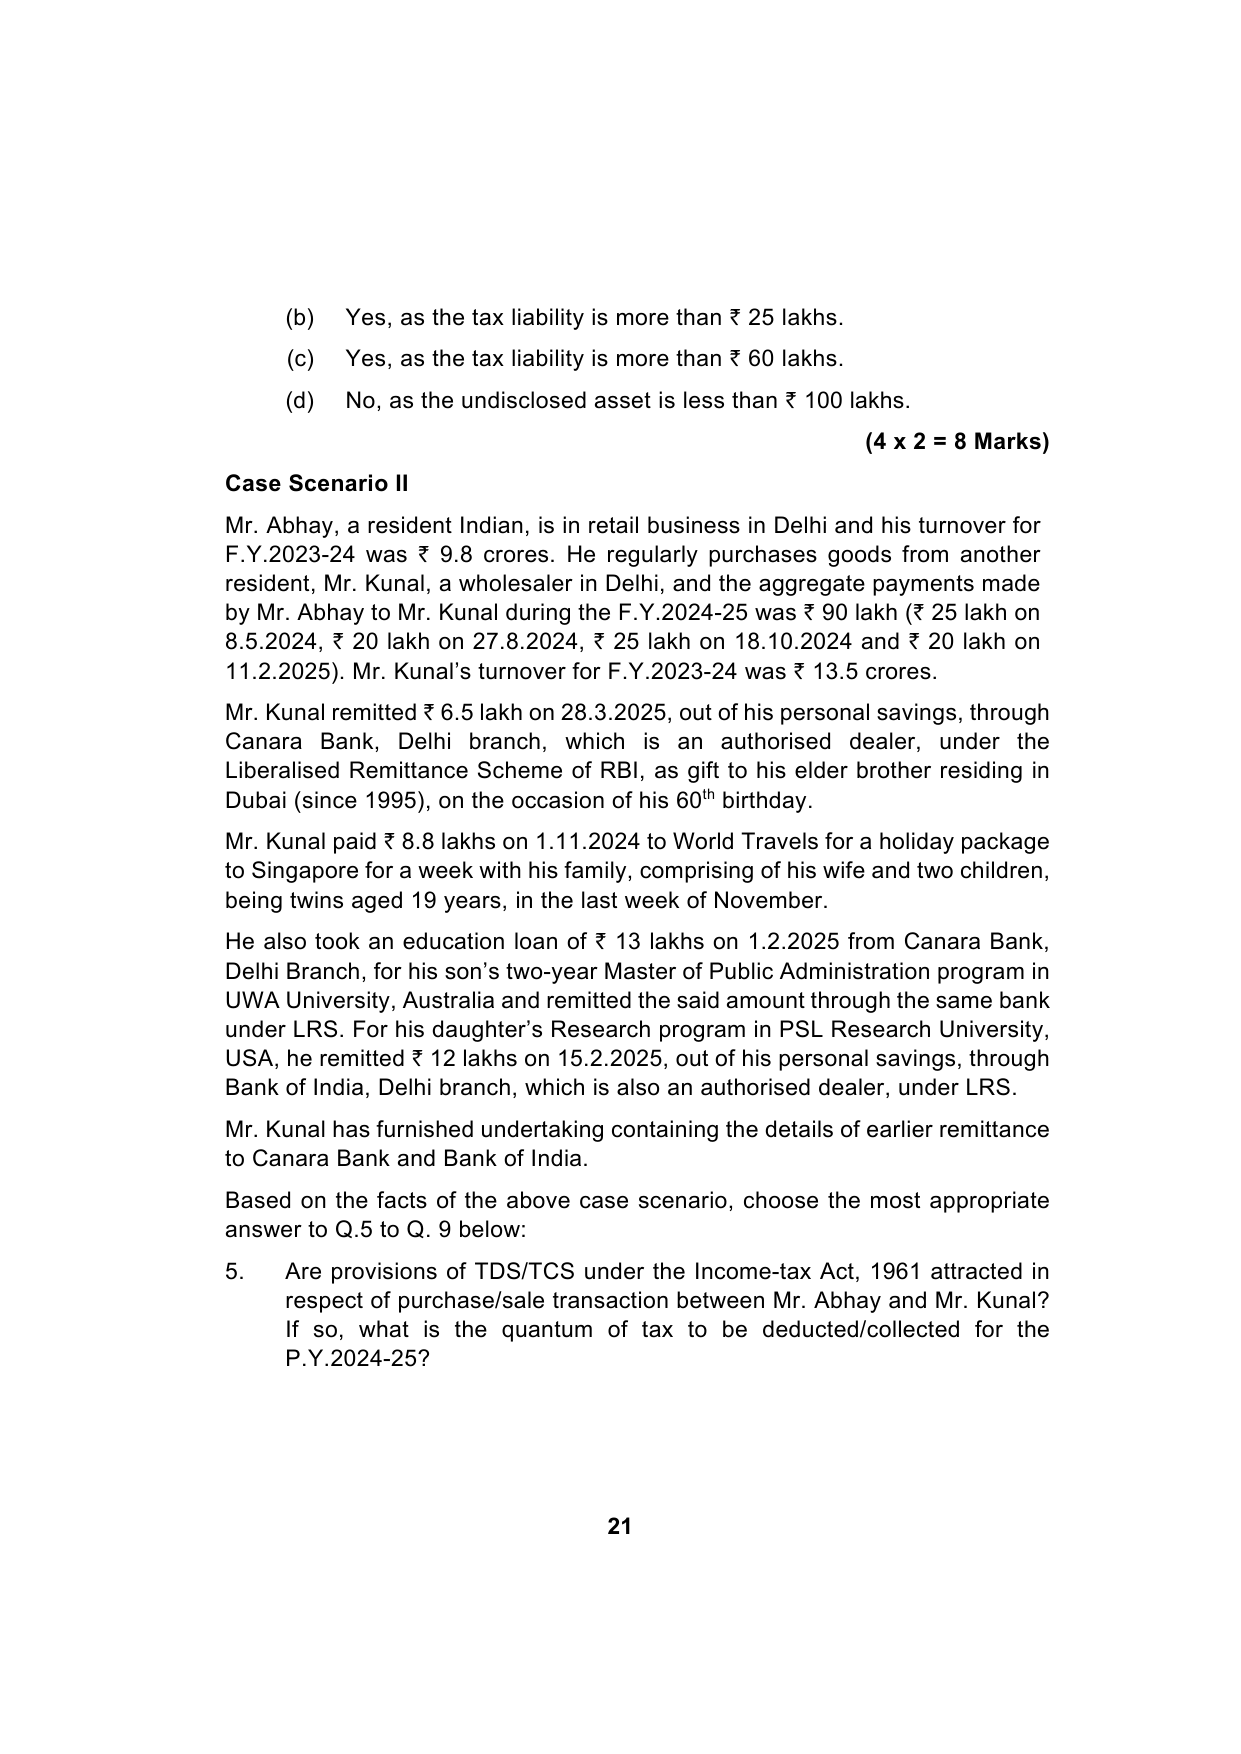
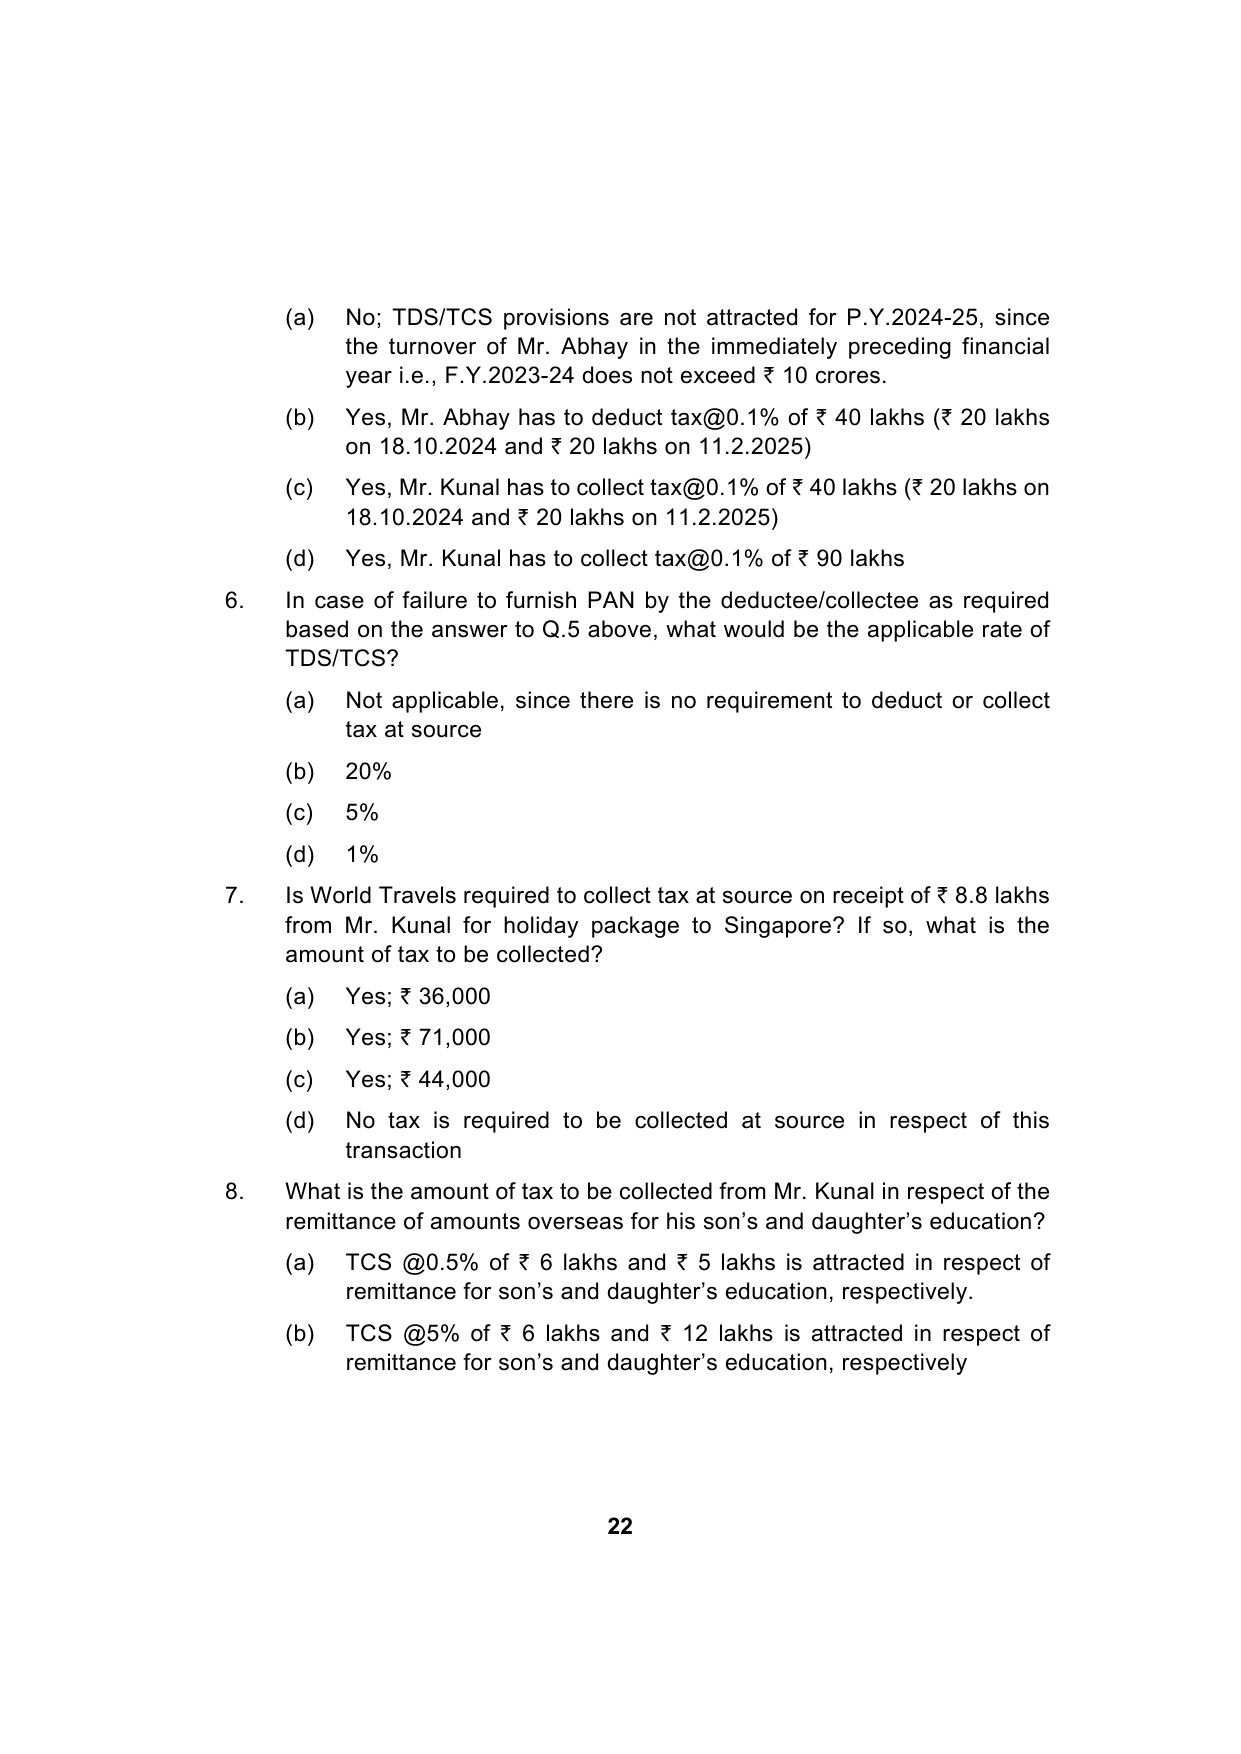
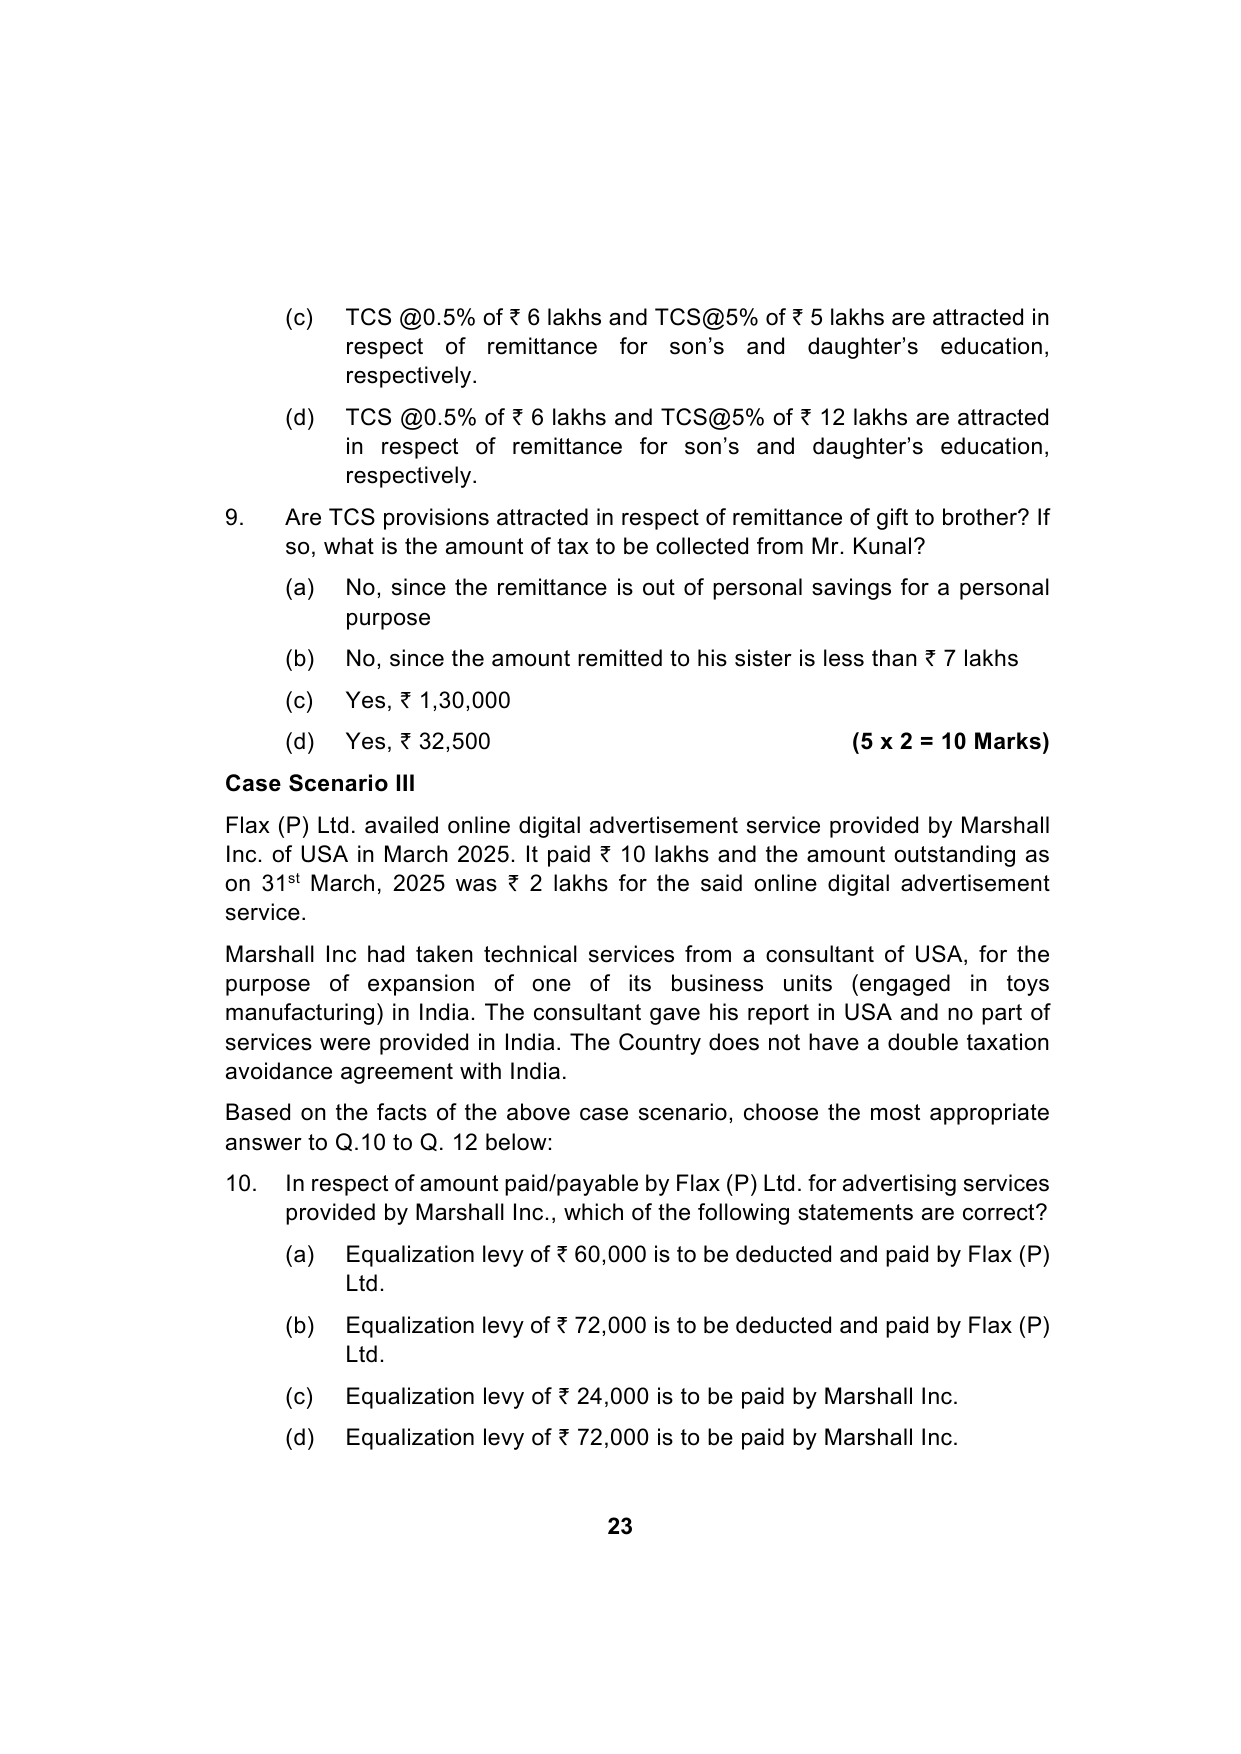
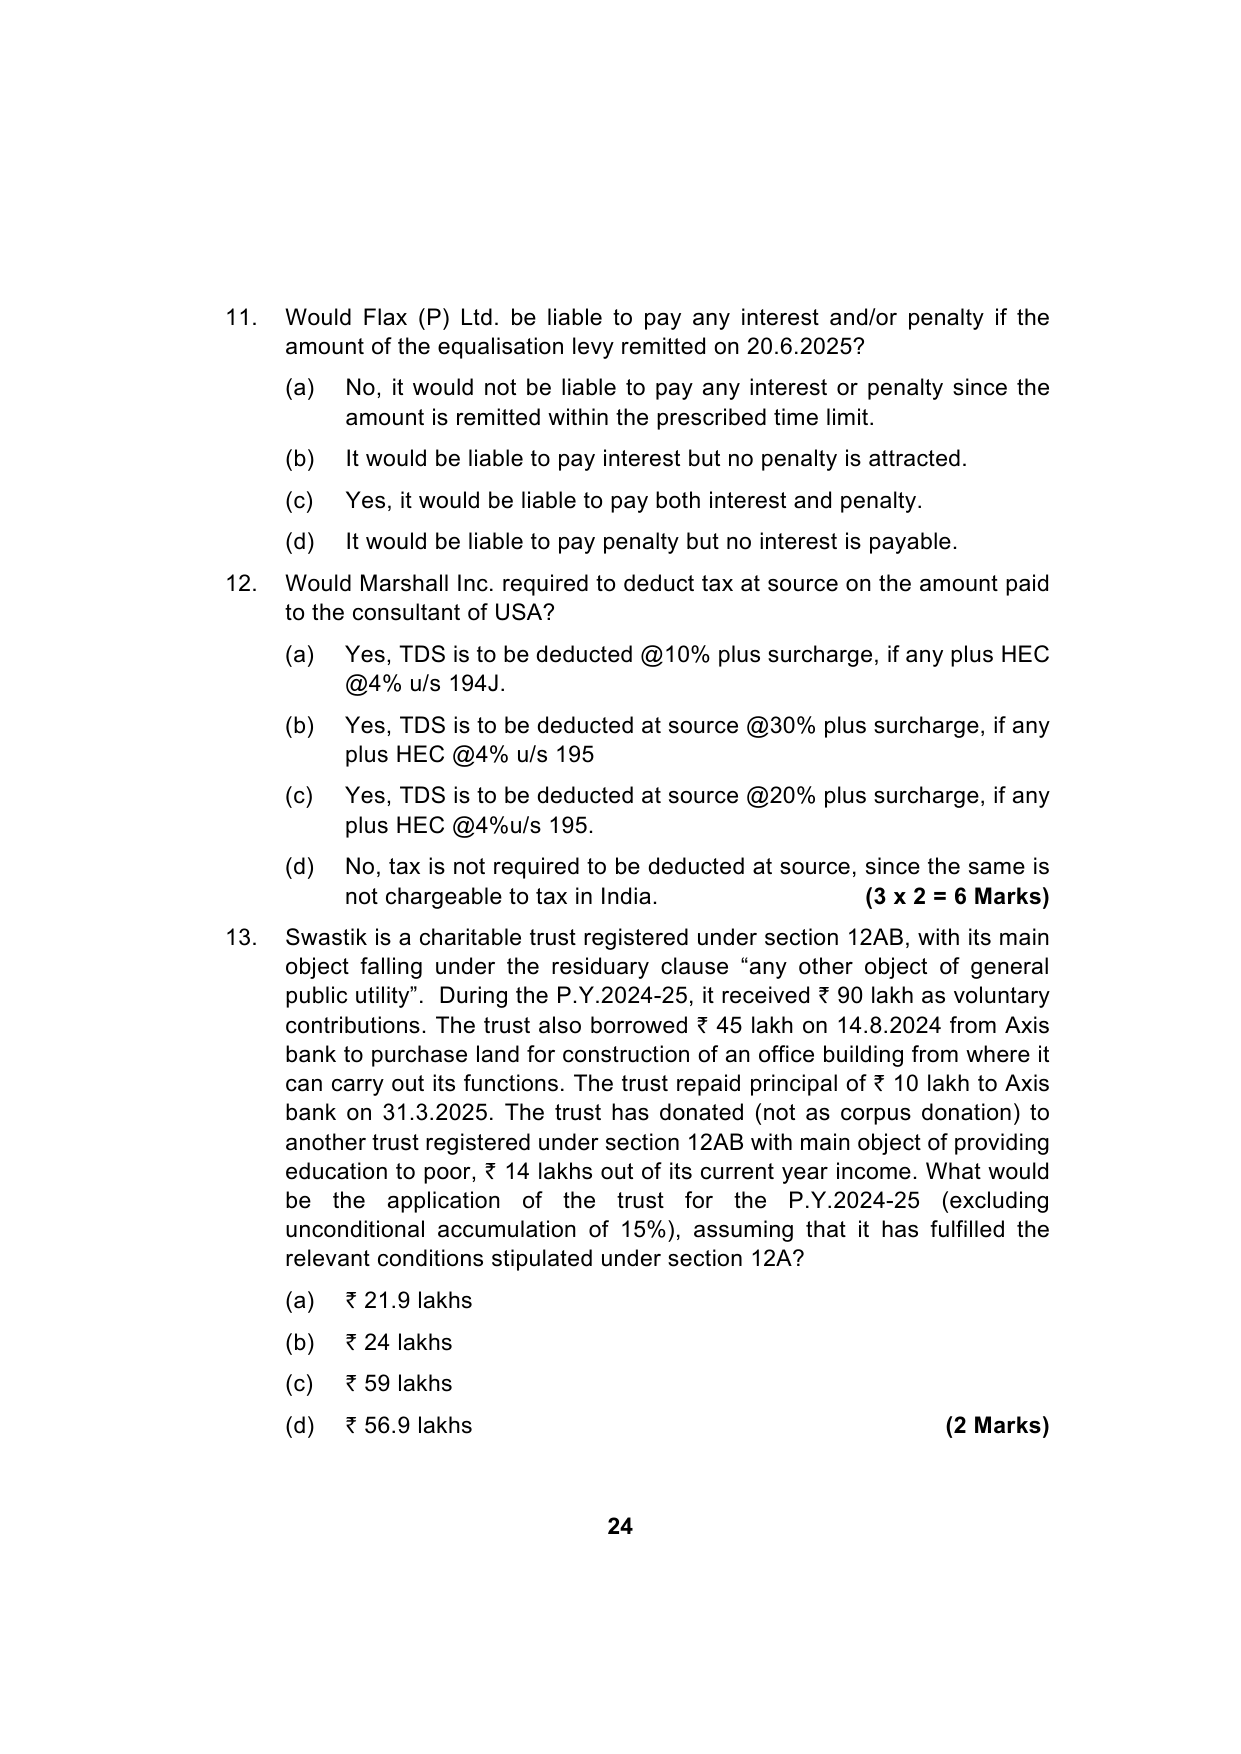
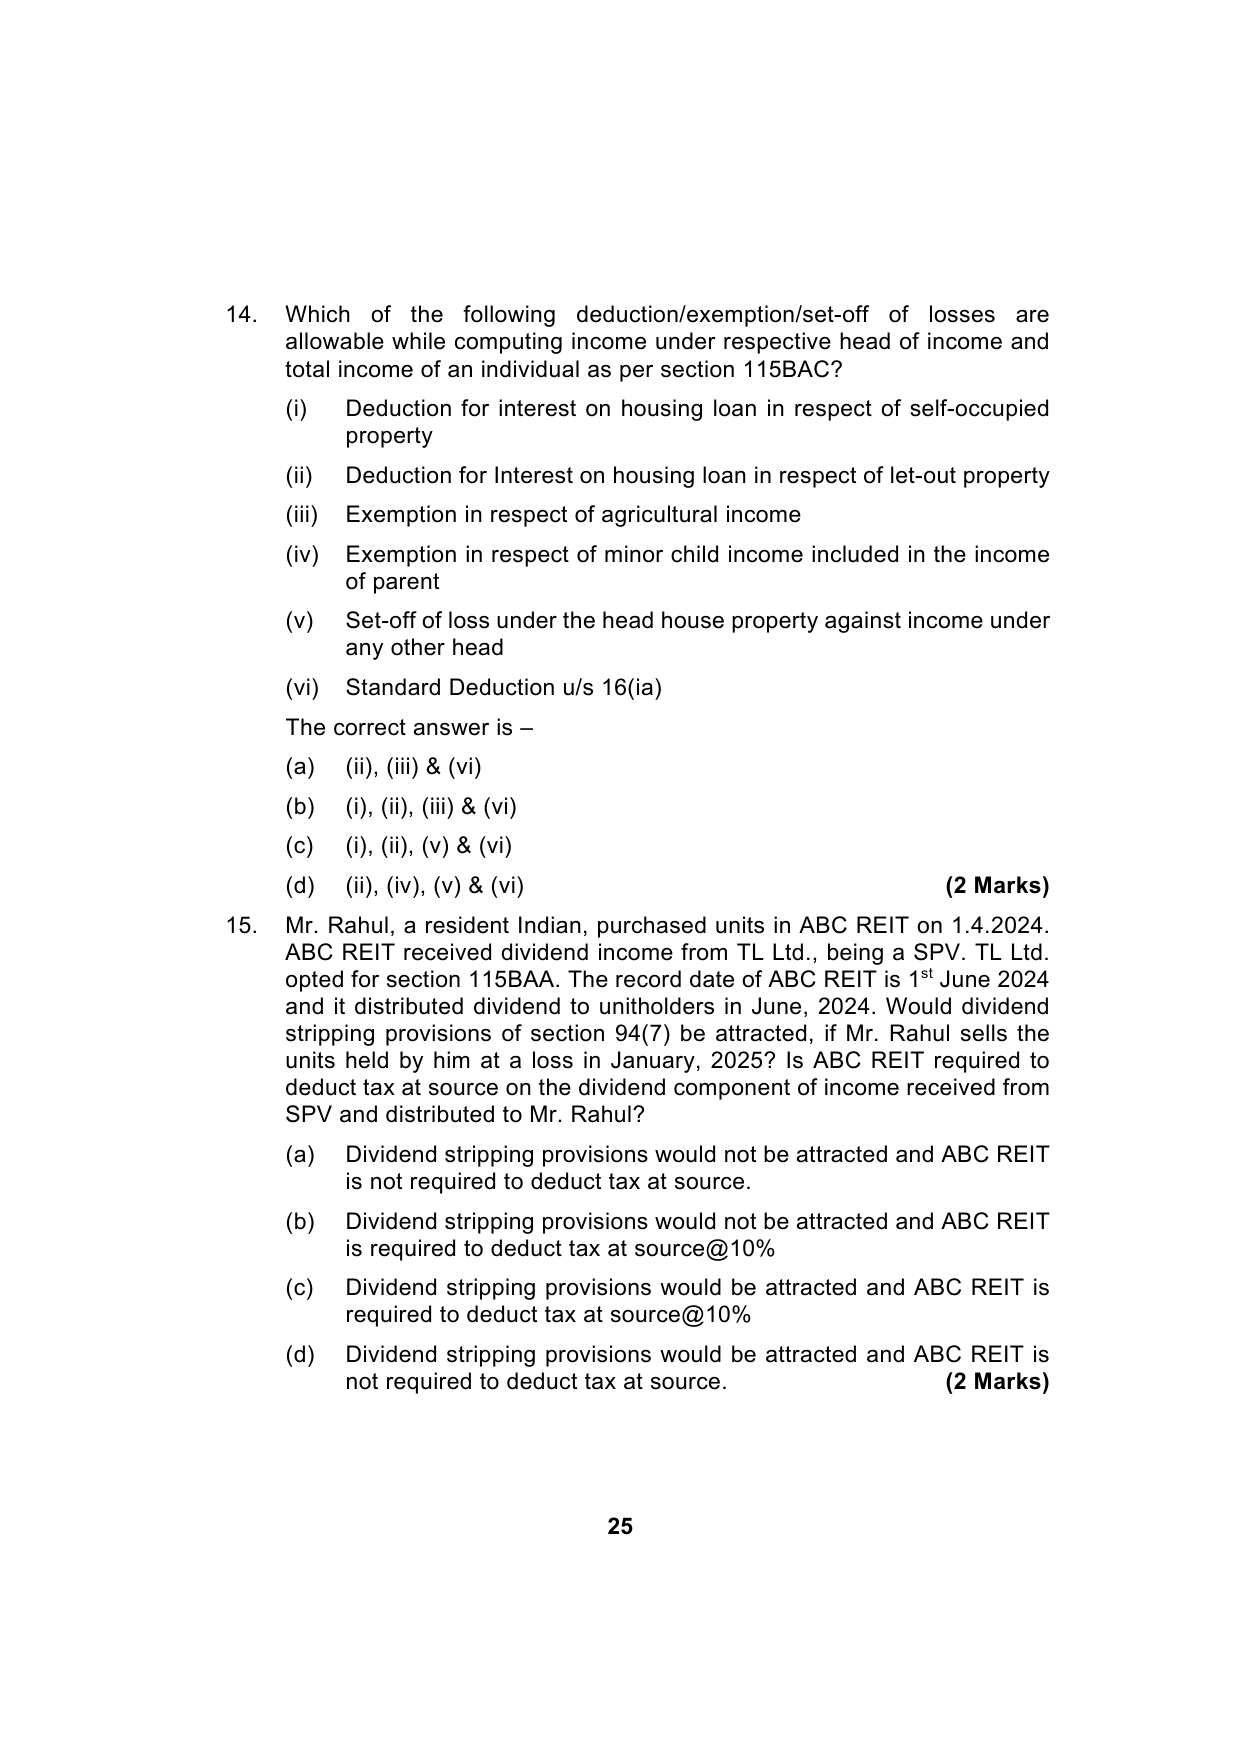
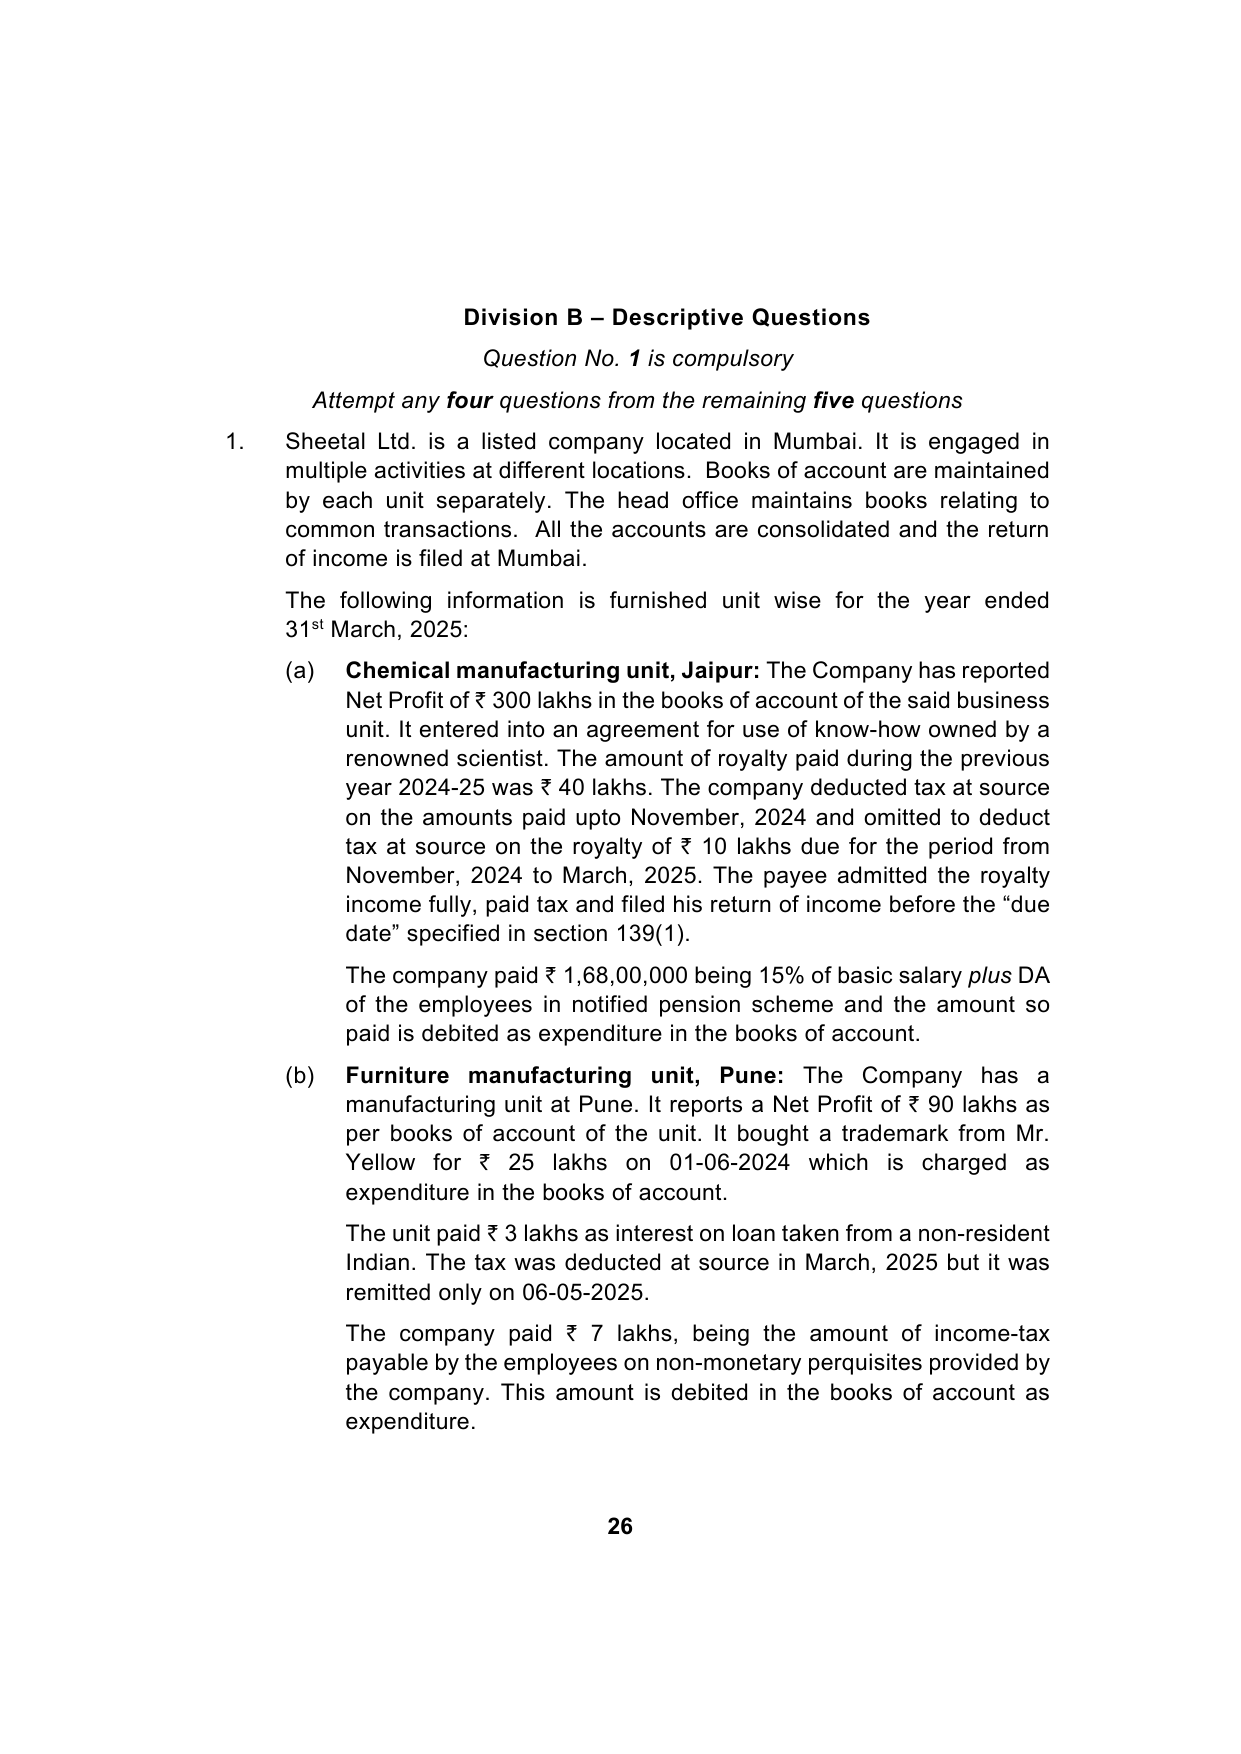
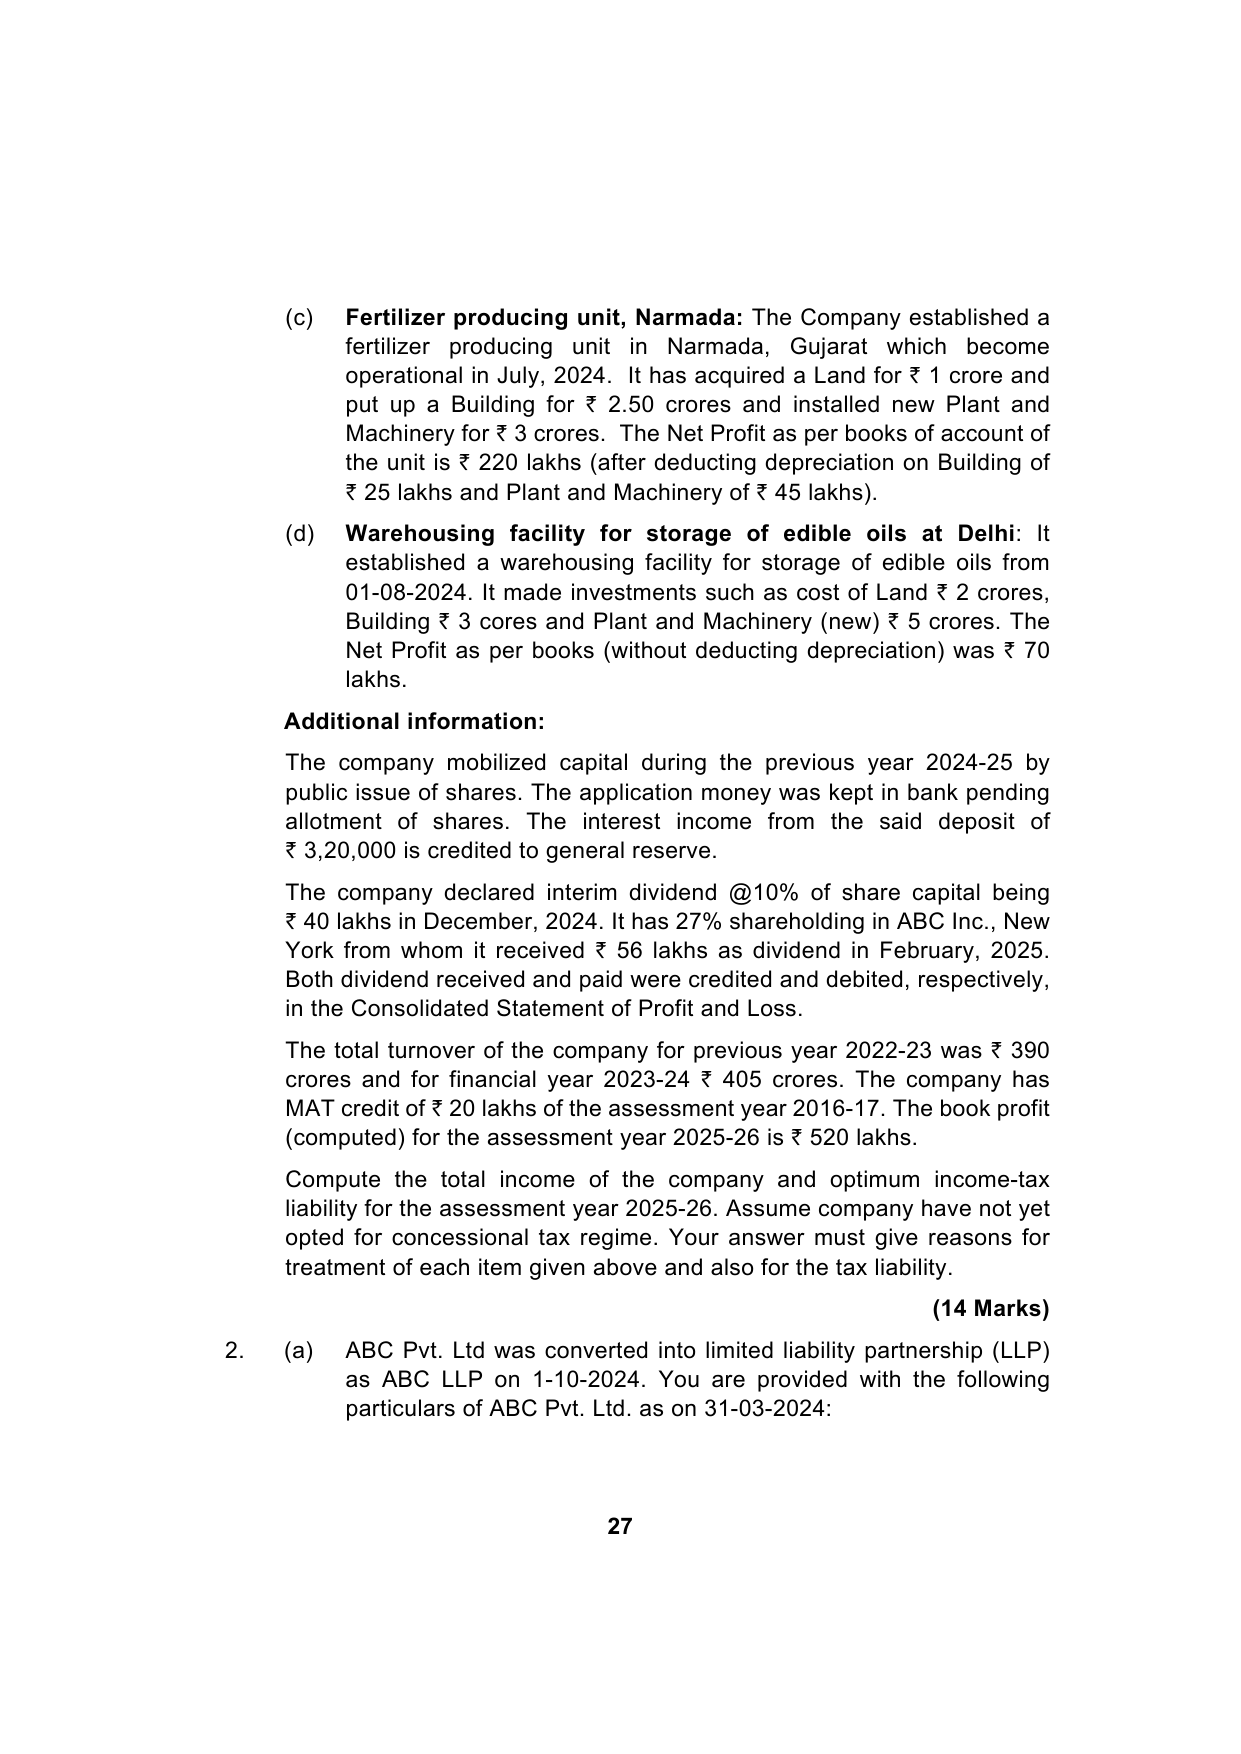
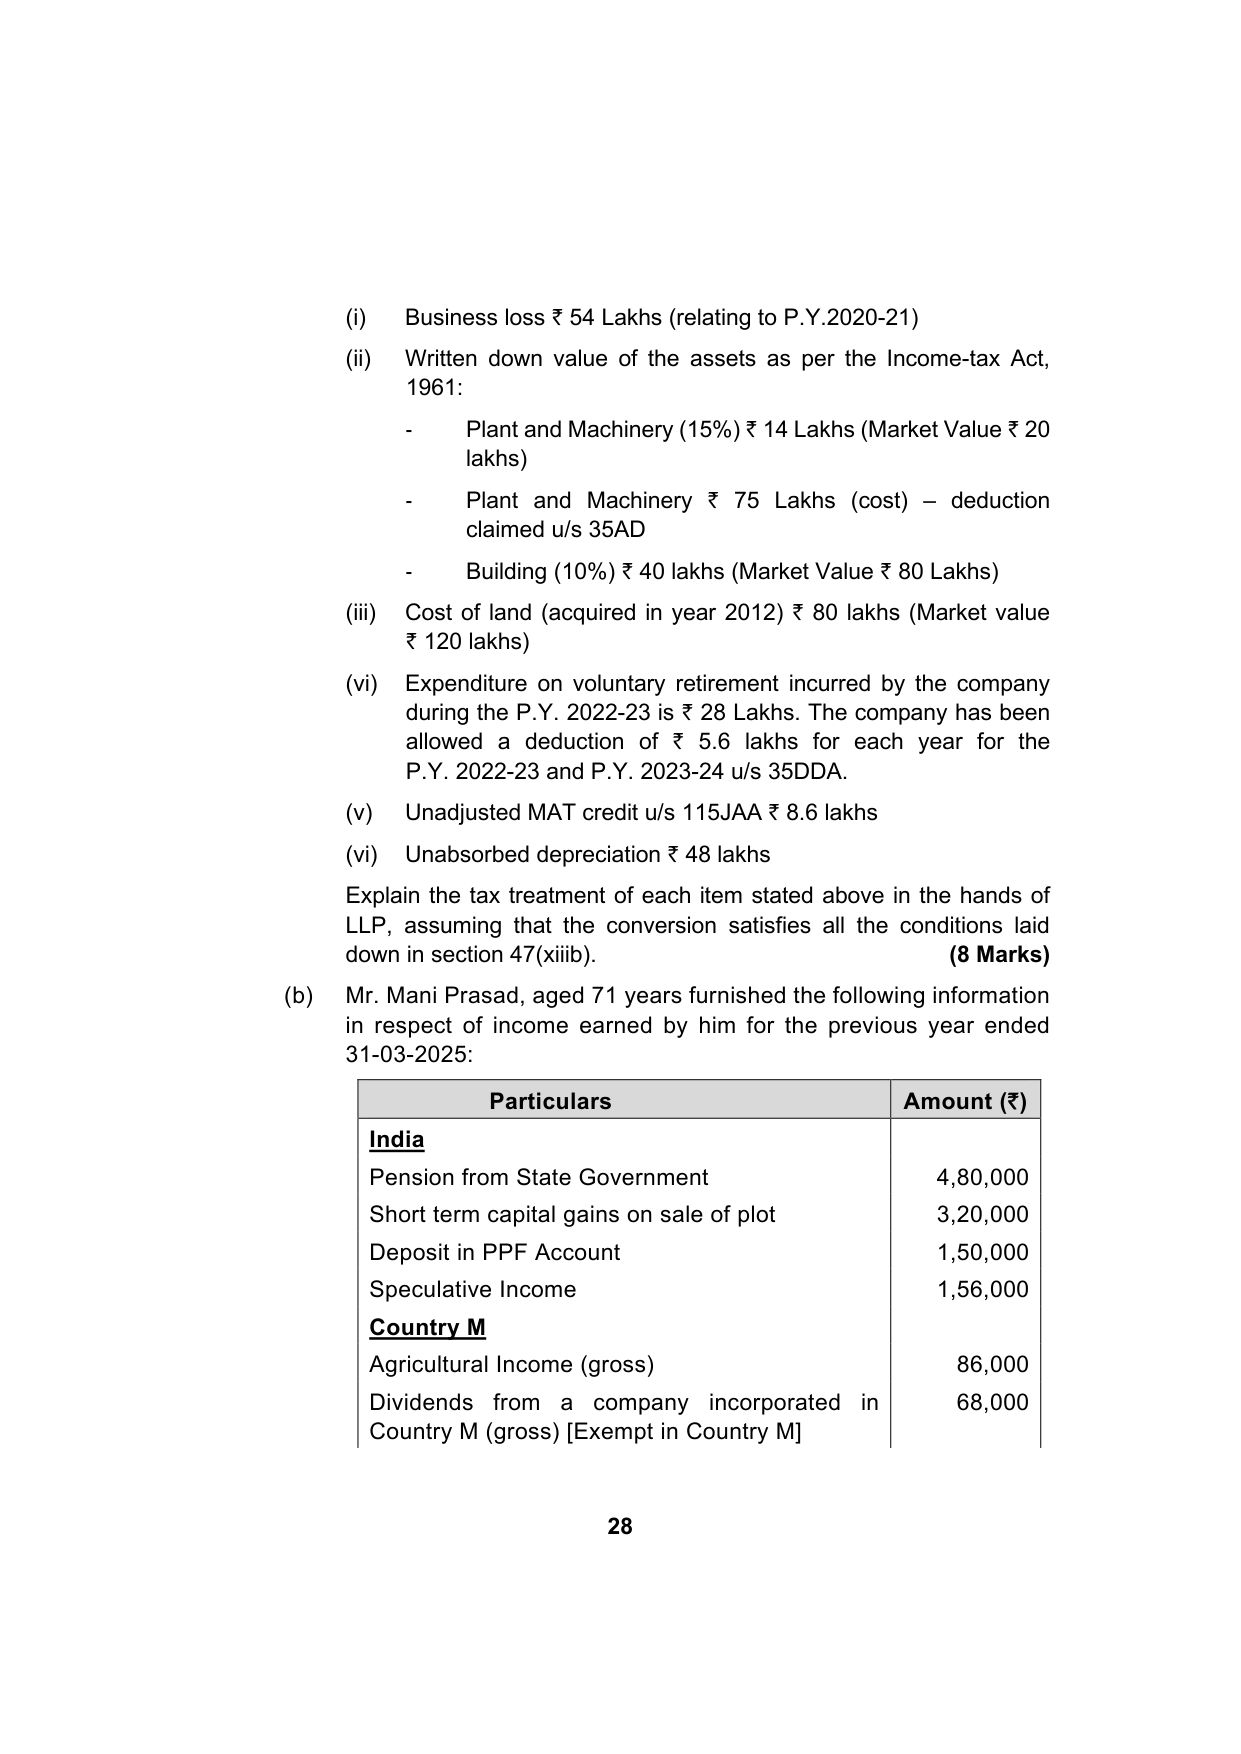
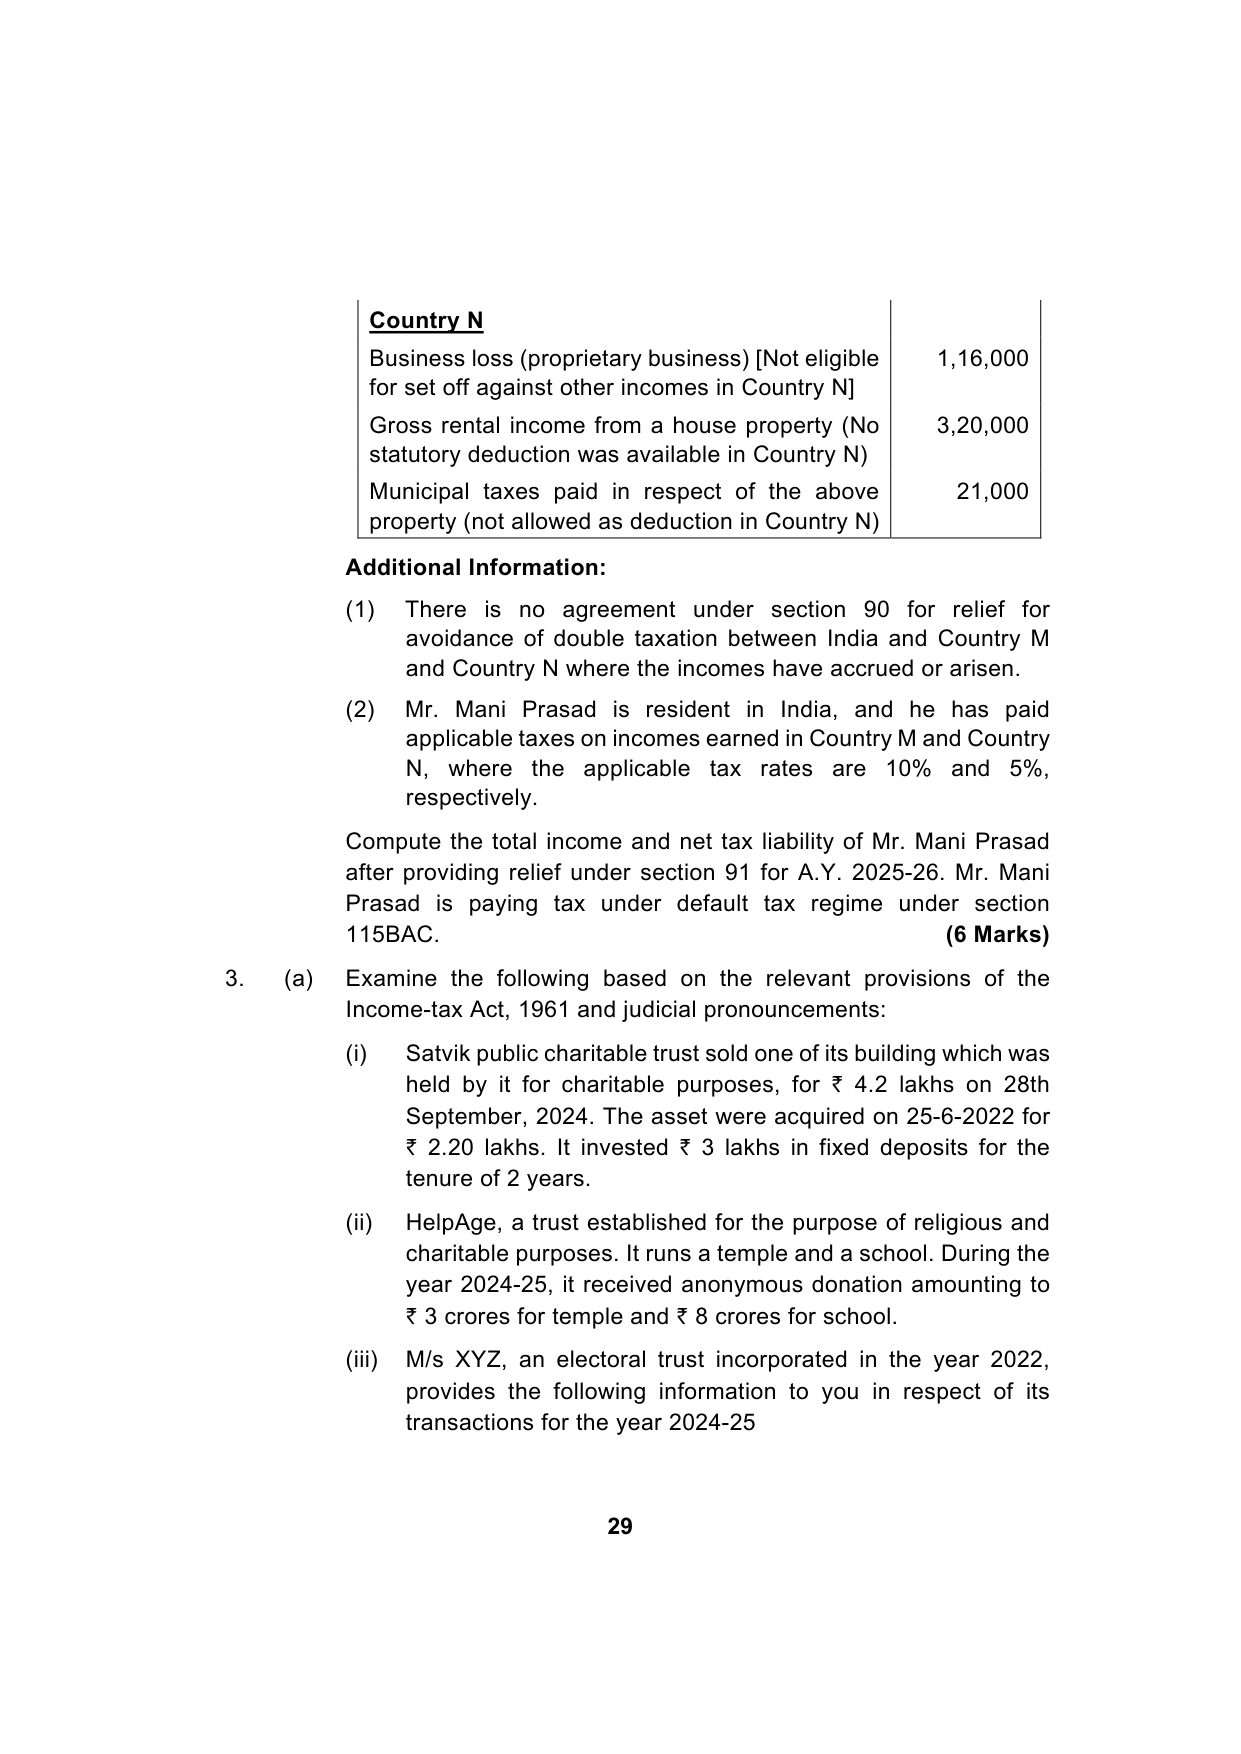
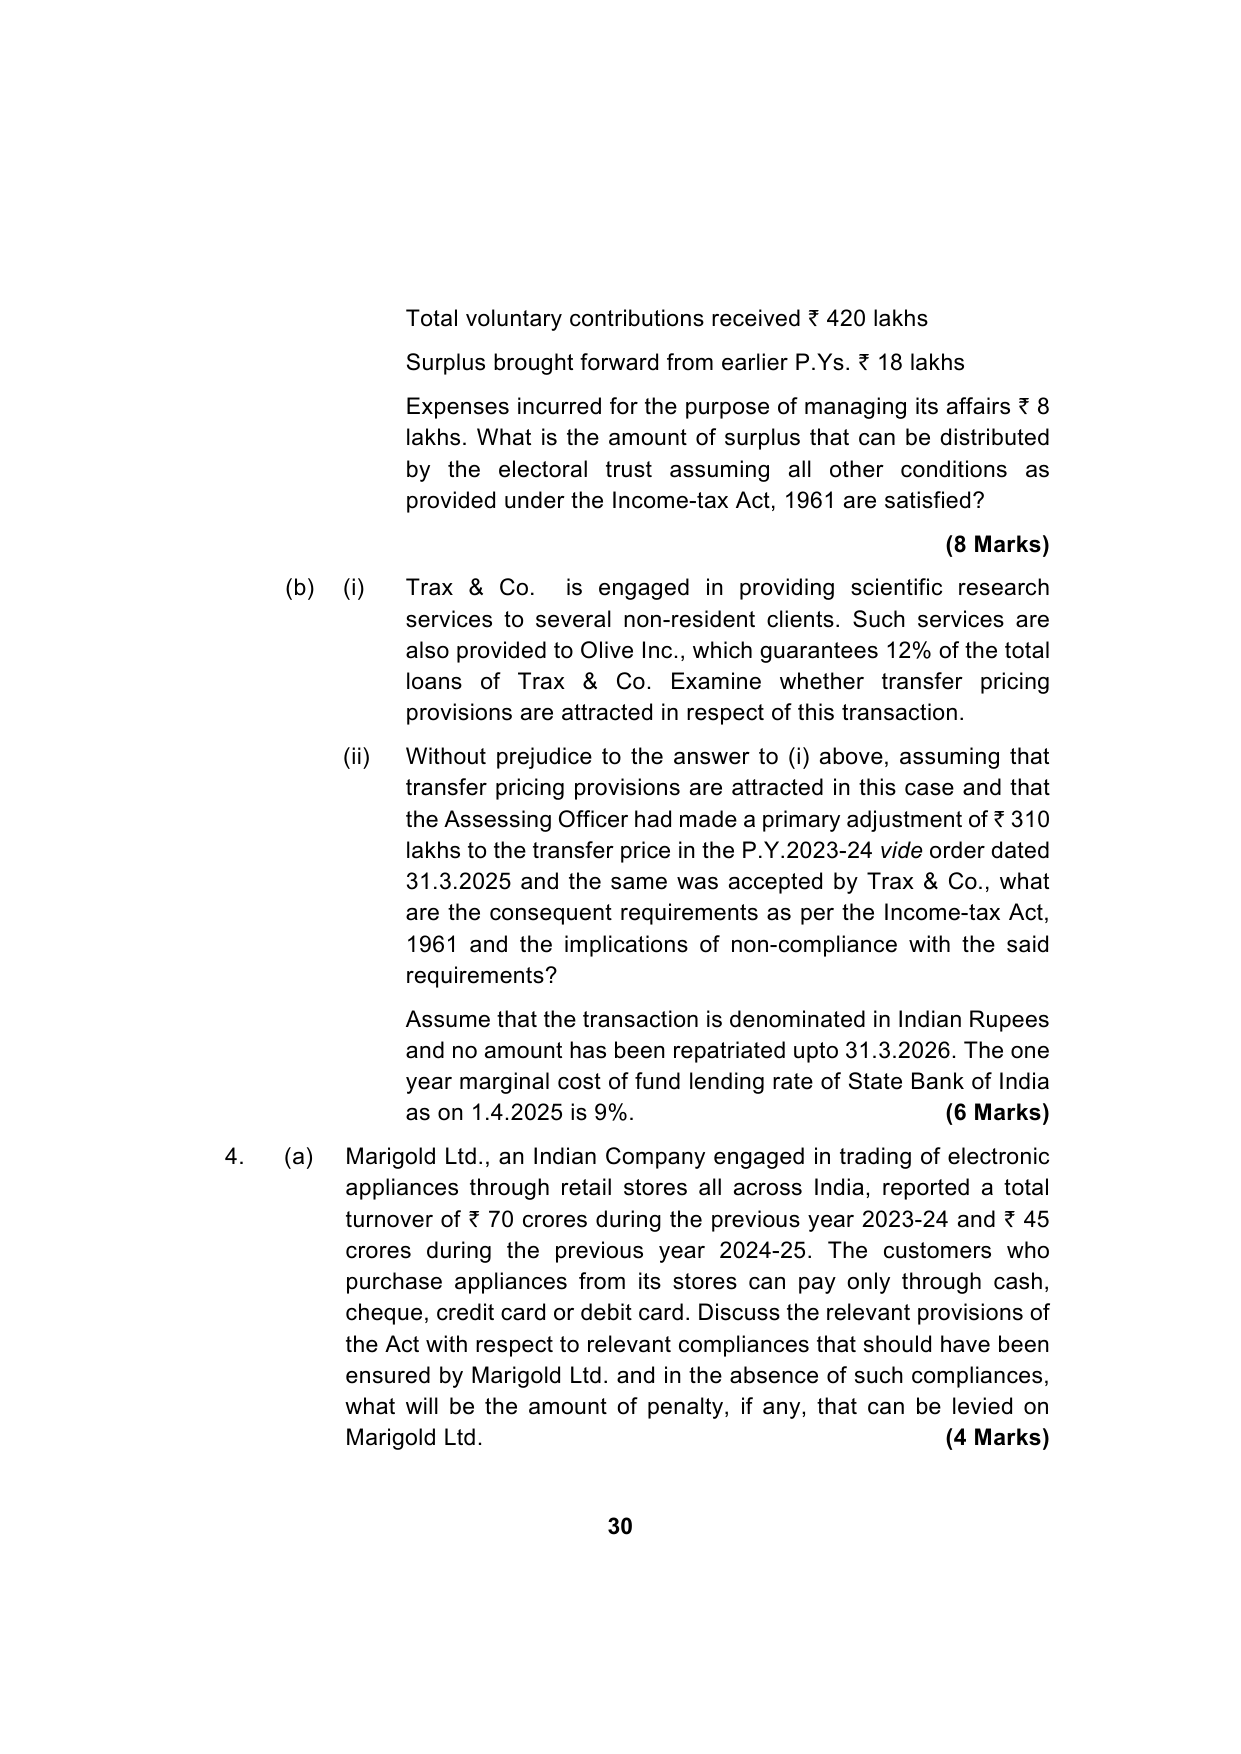
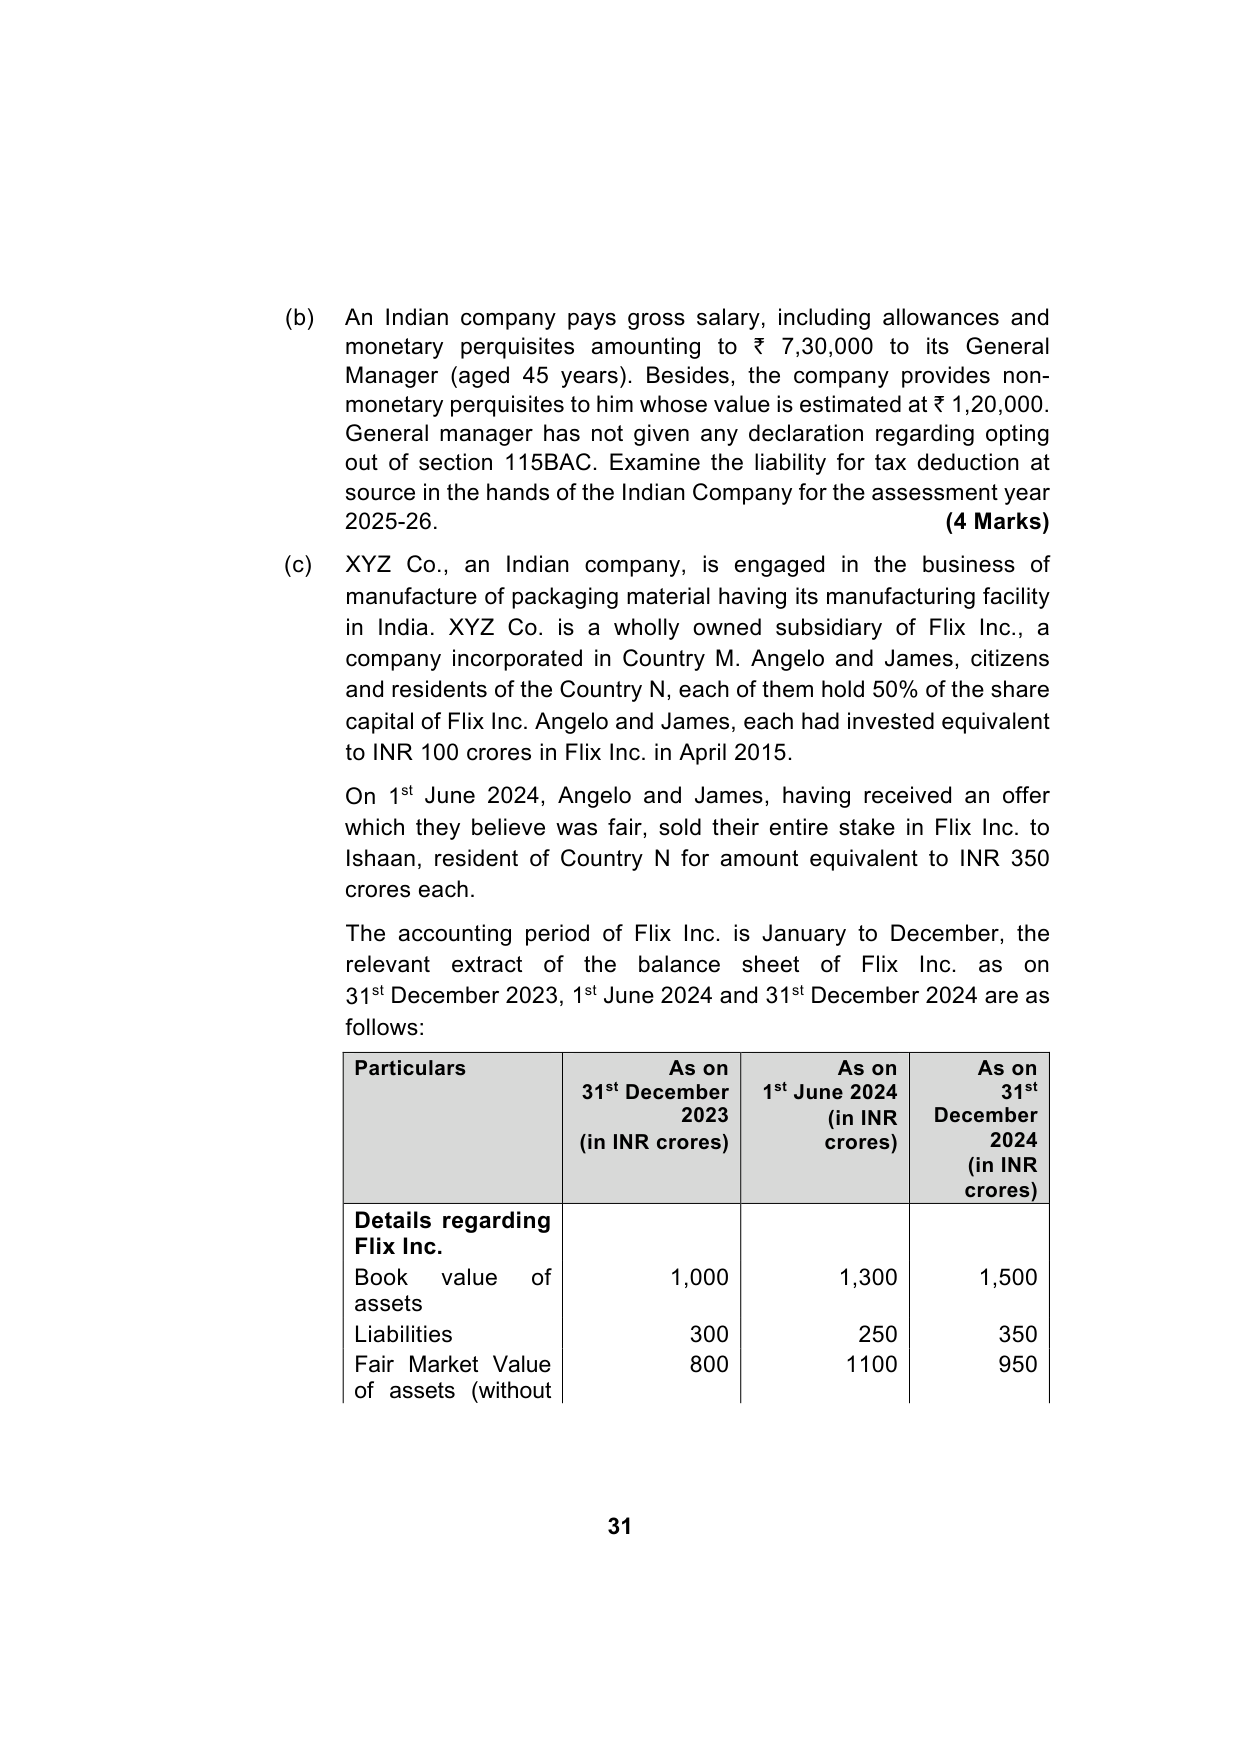
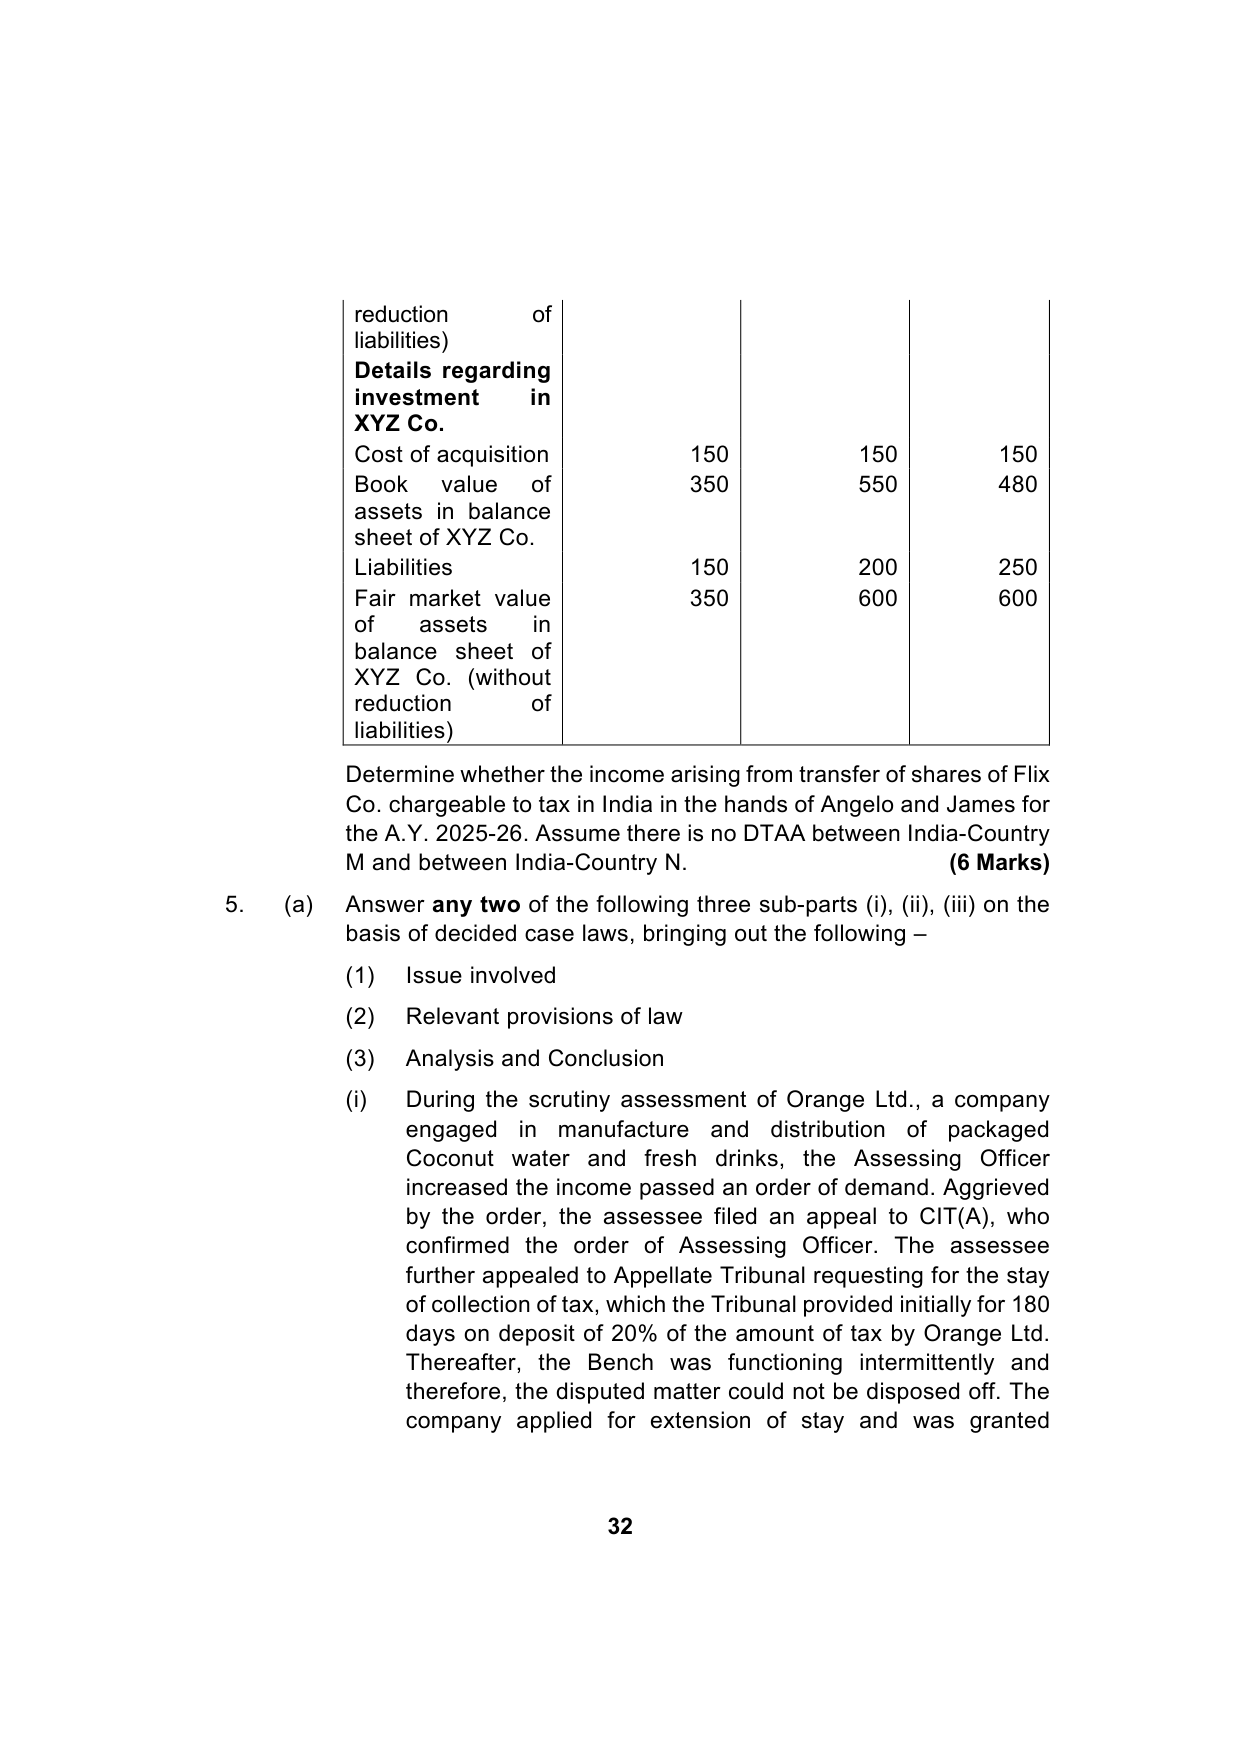
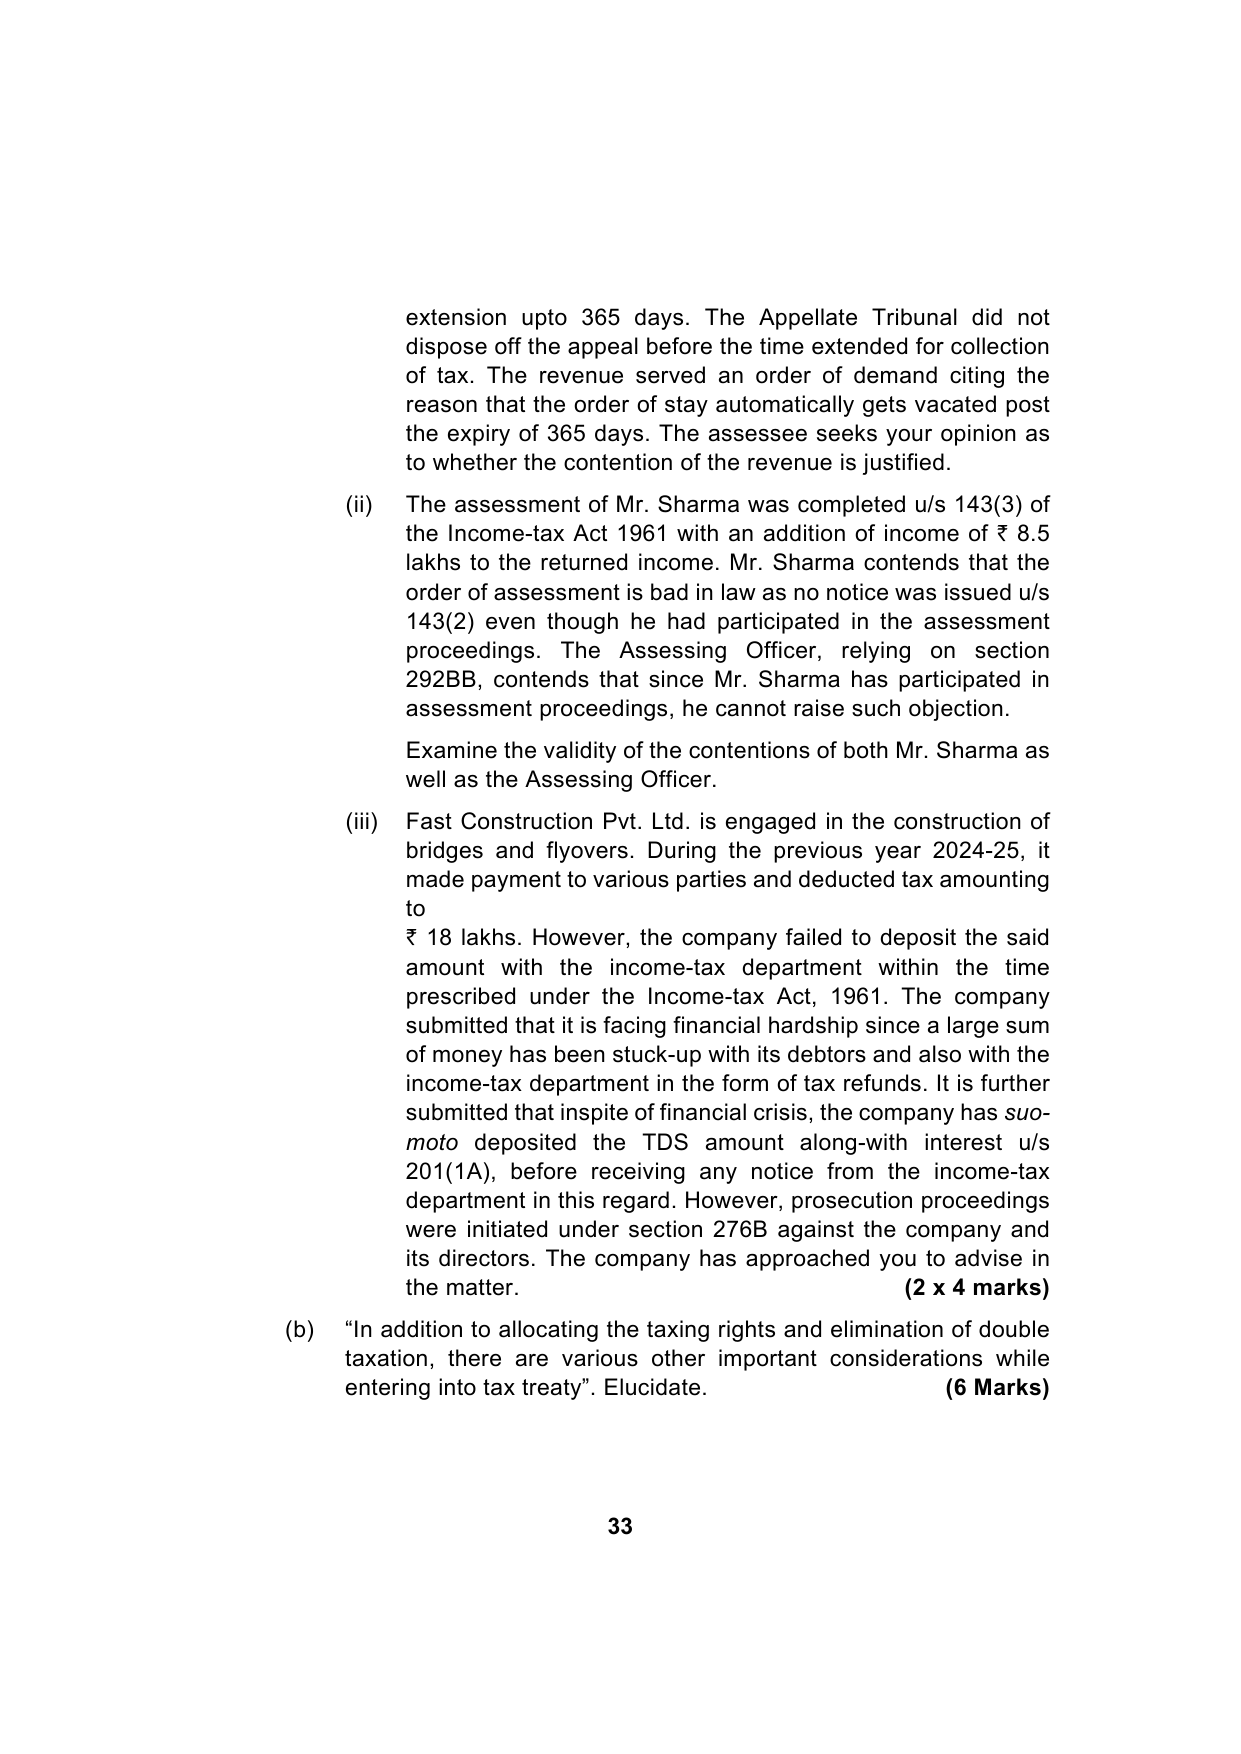
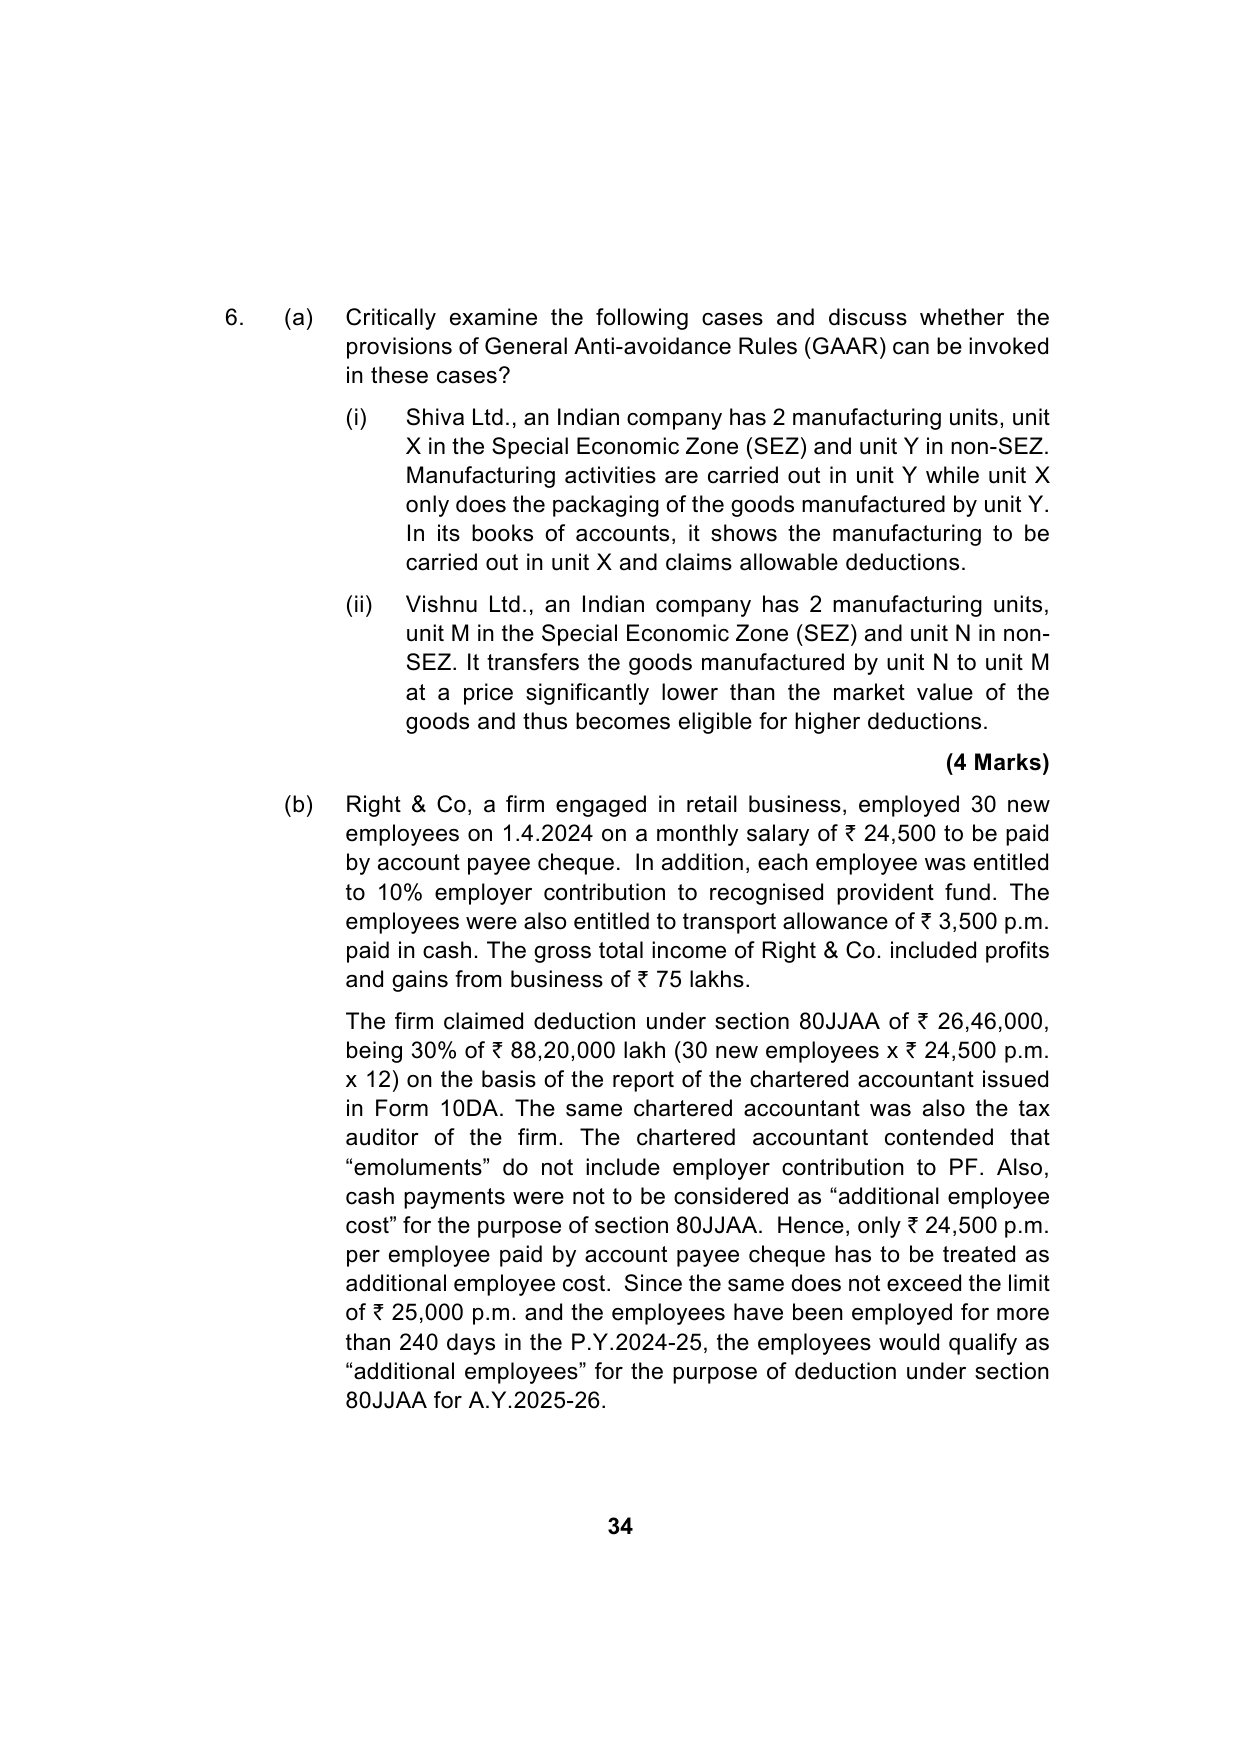
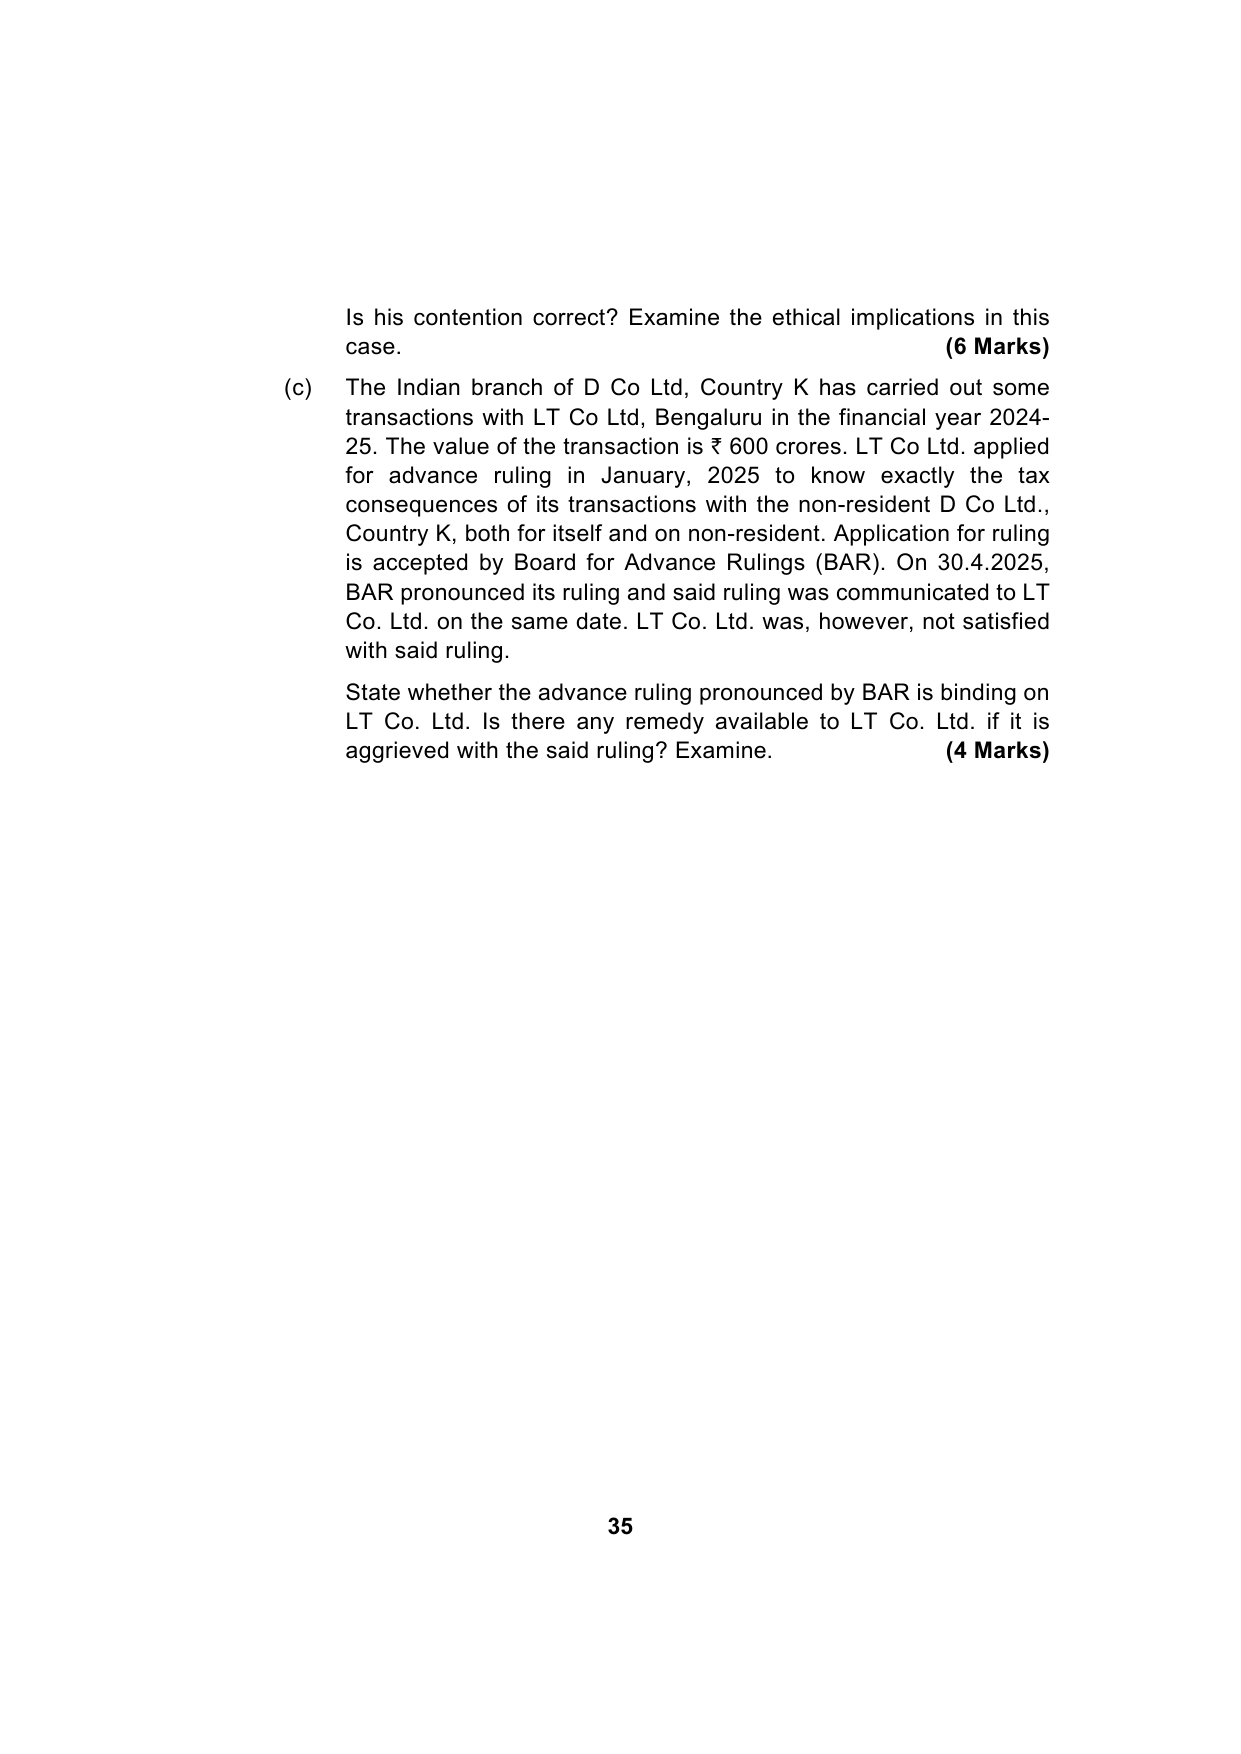
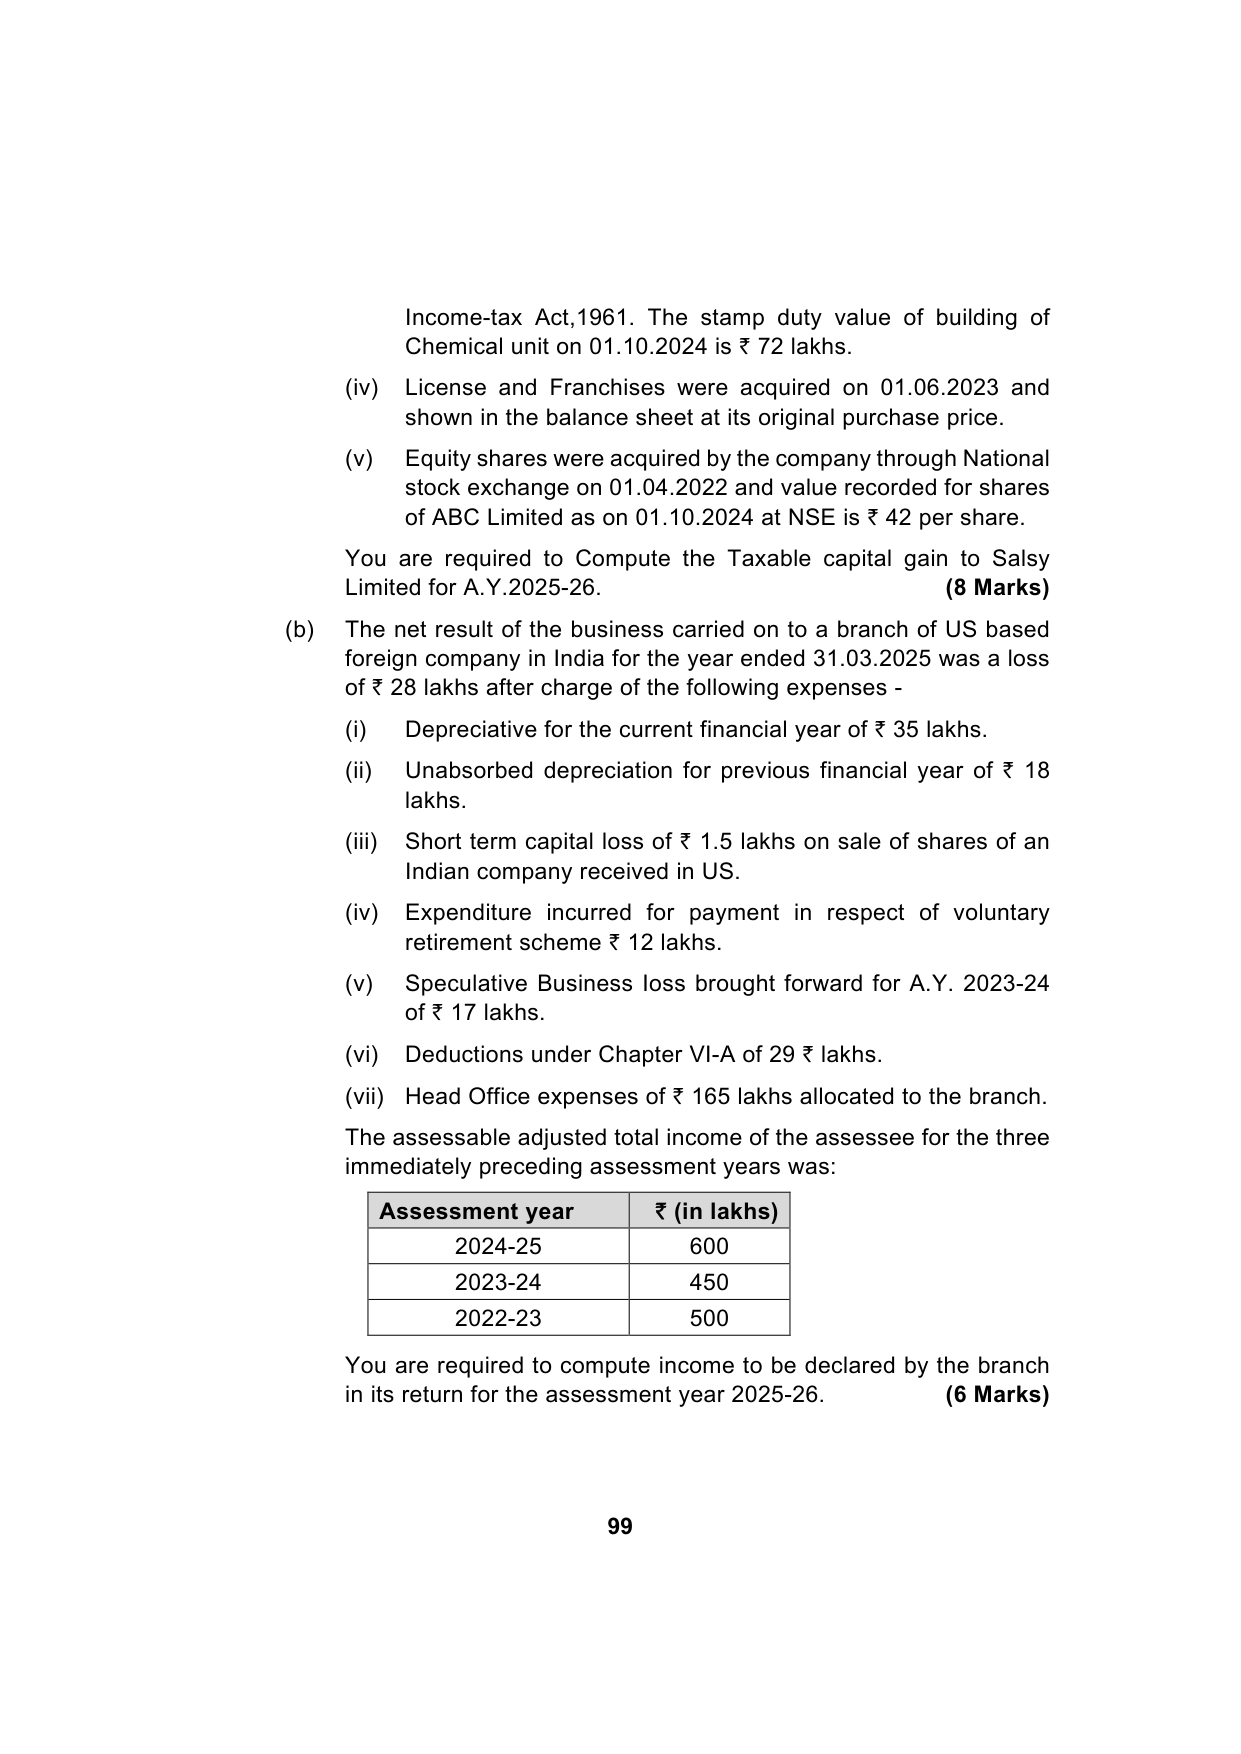
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 3
Question
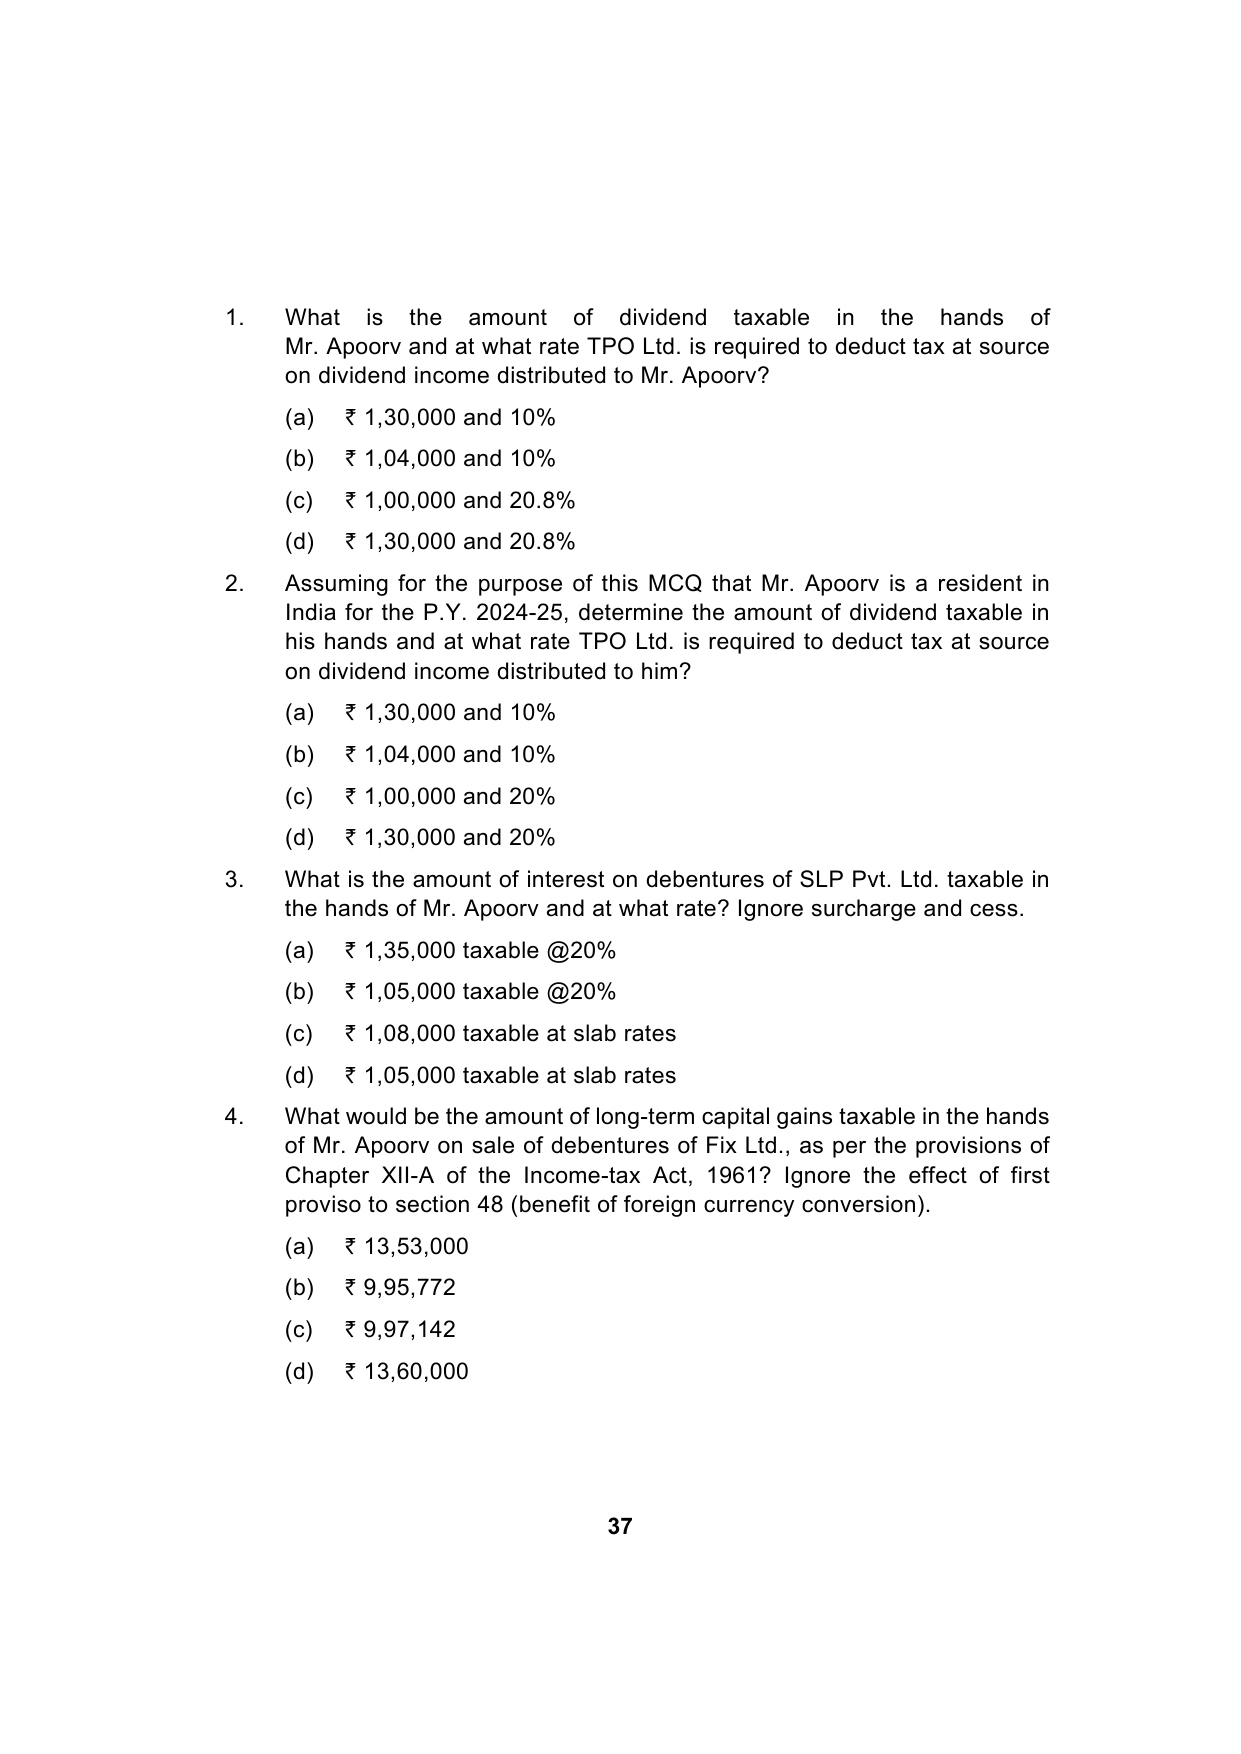
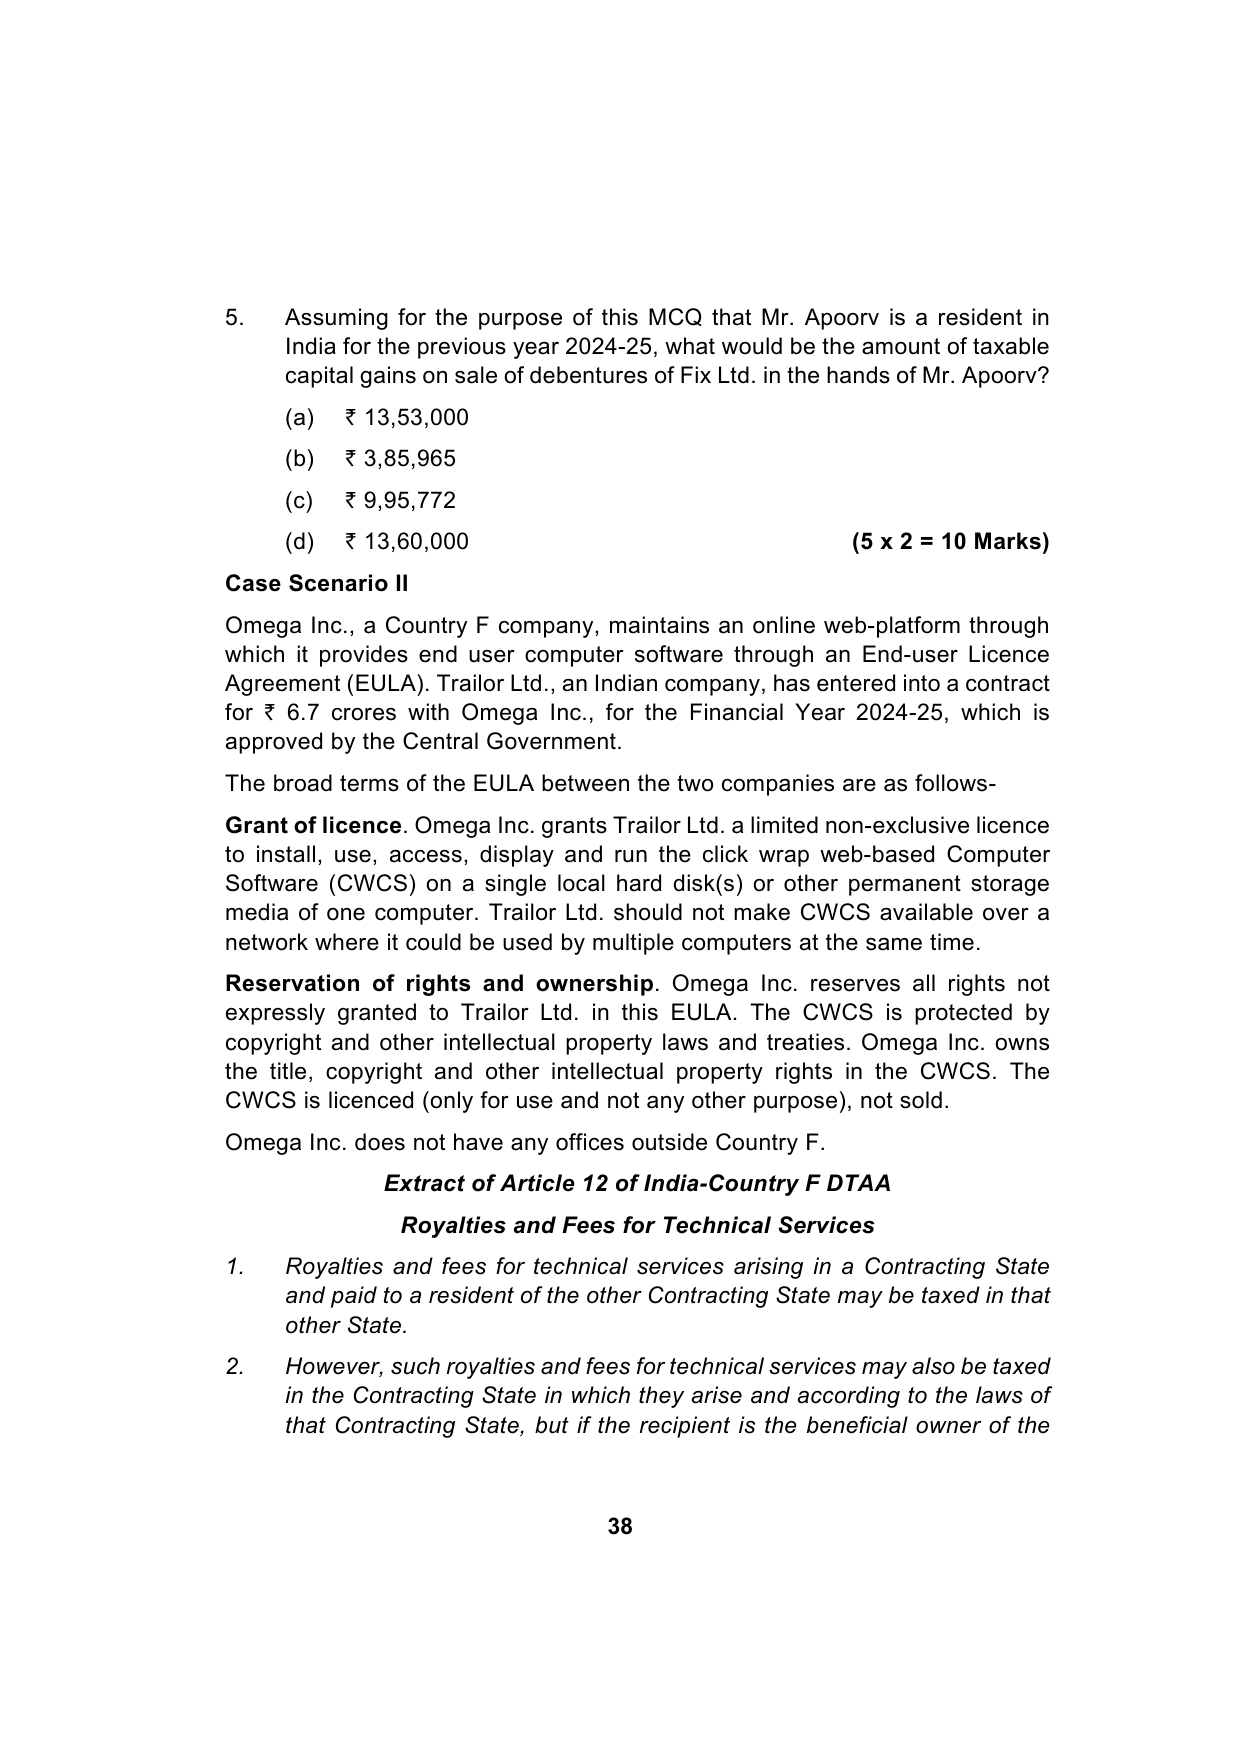
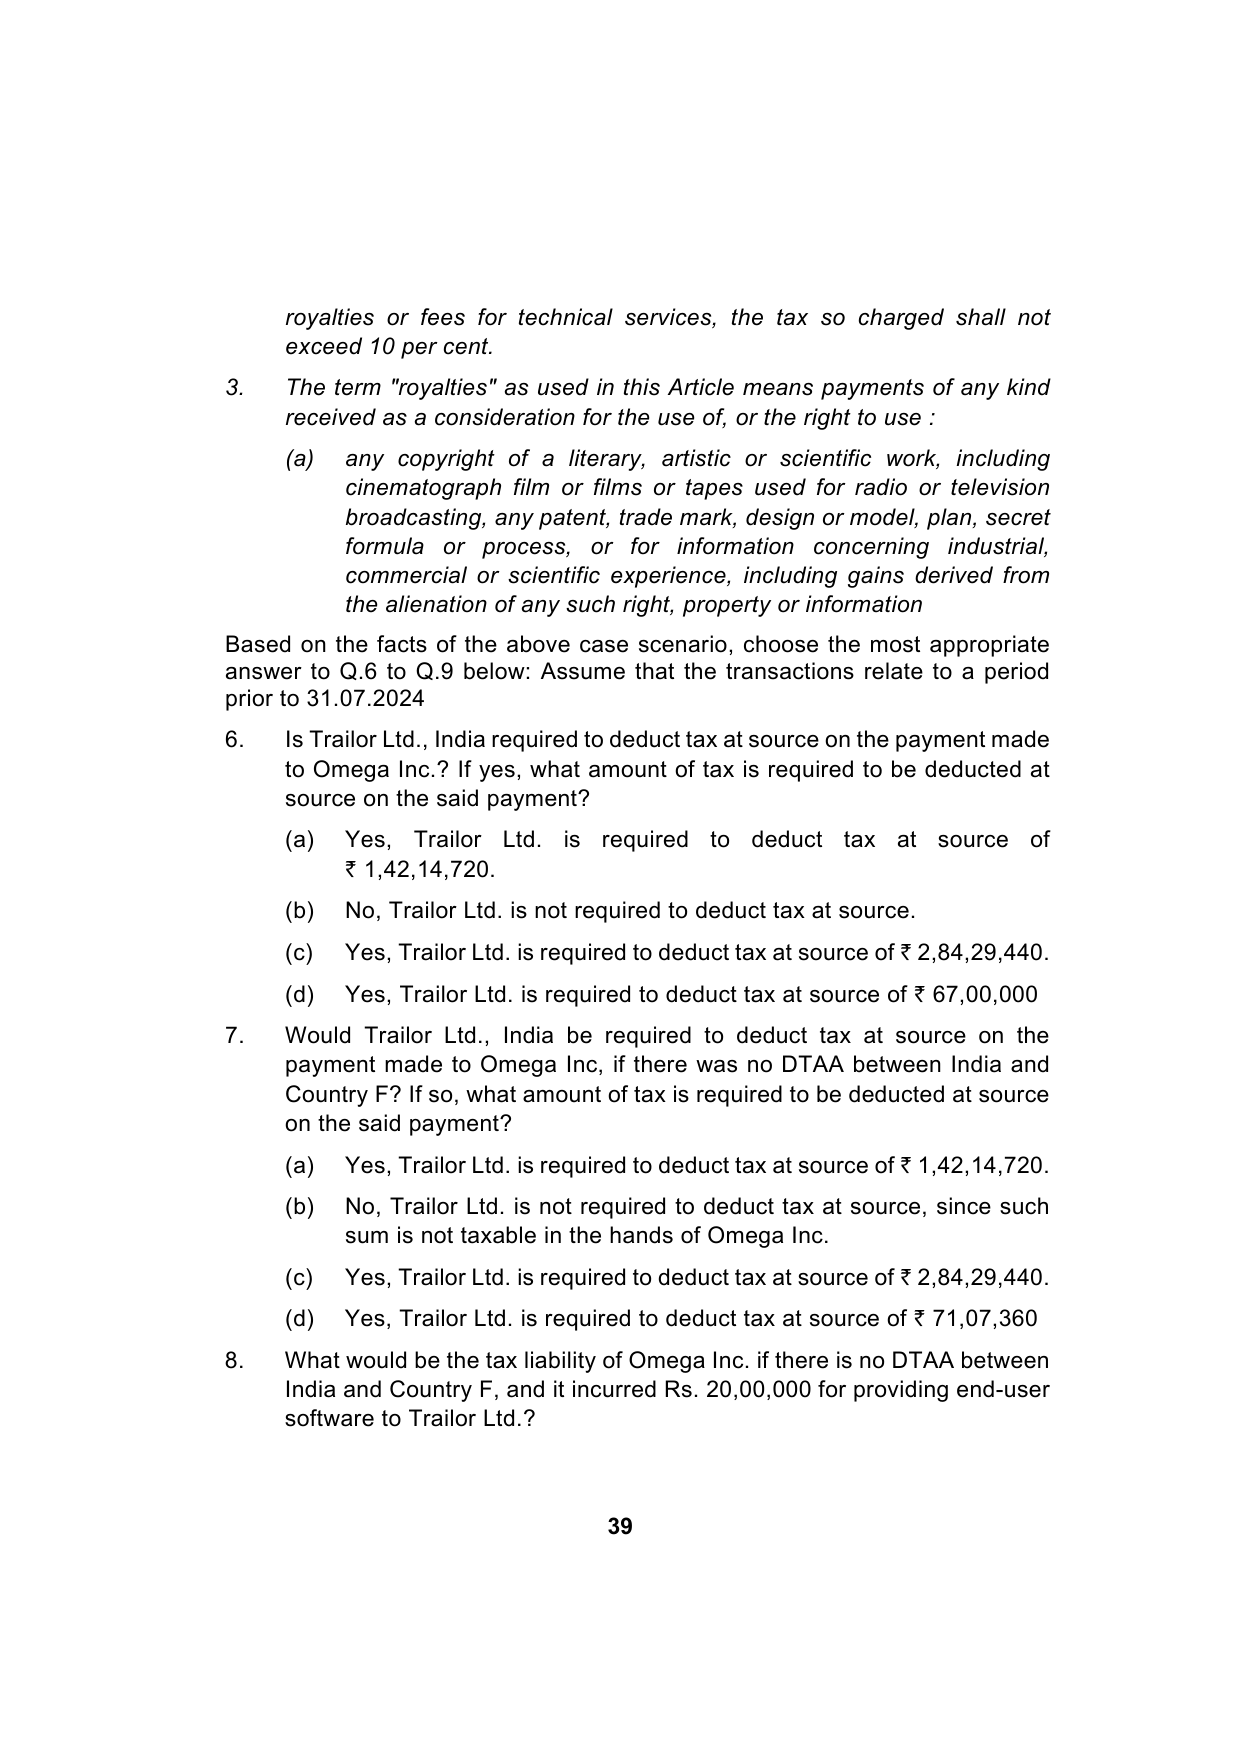
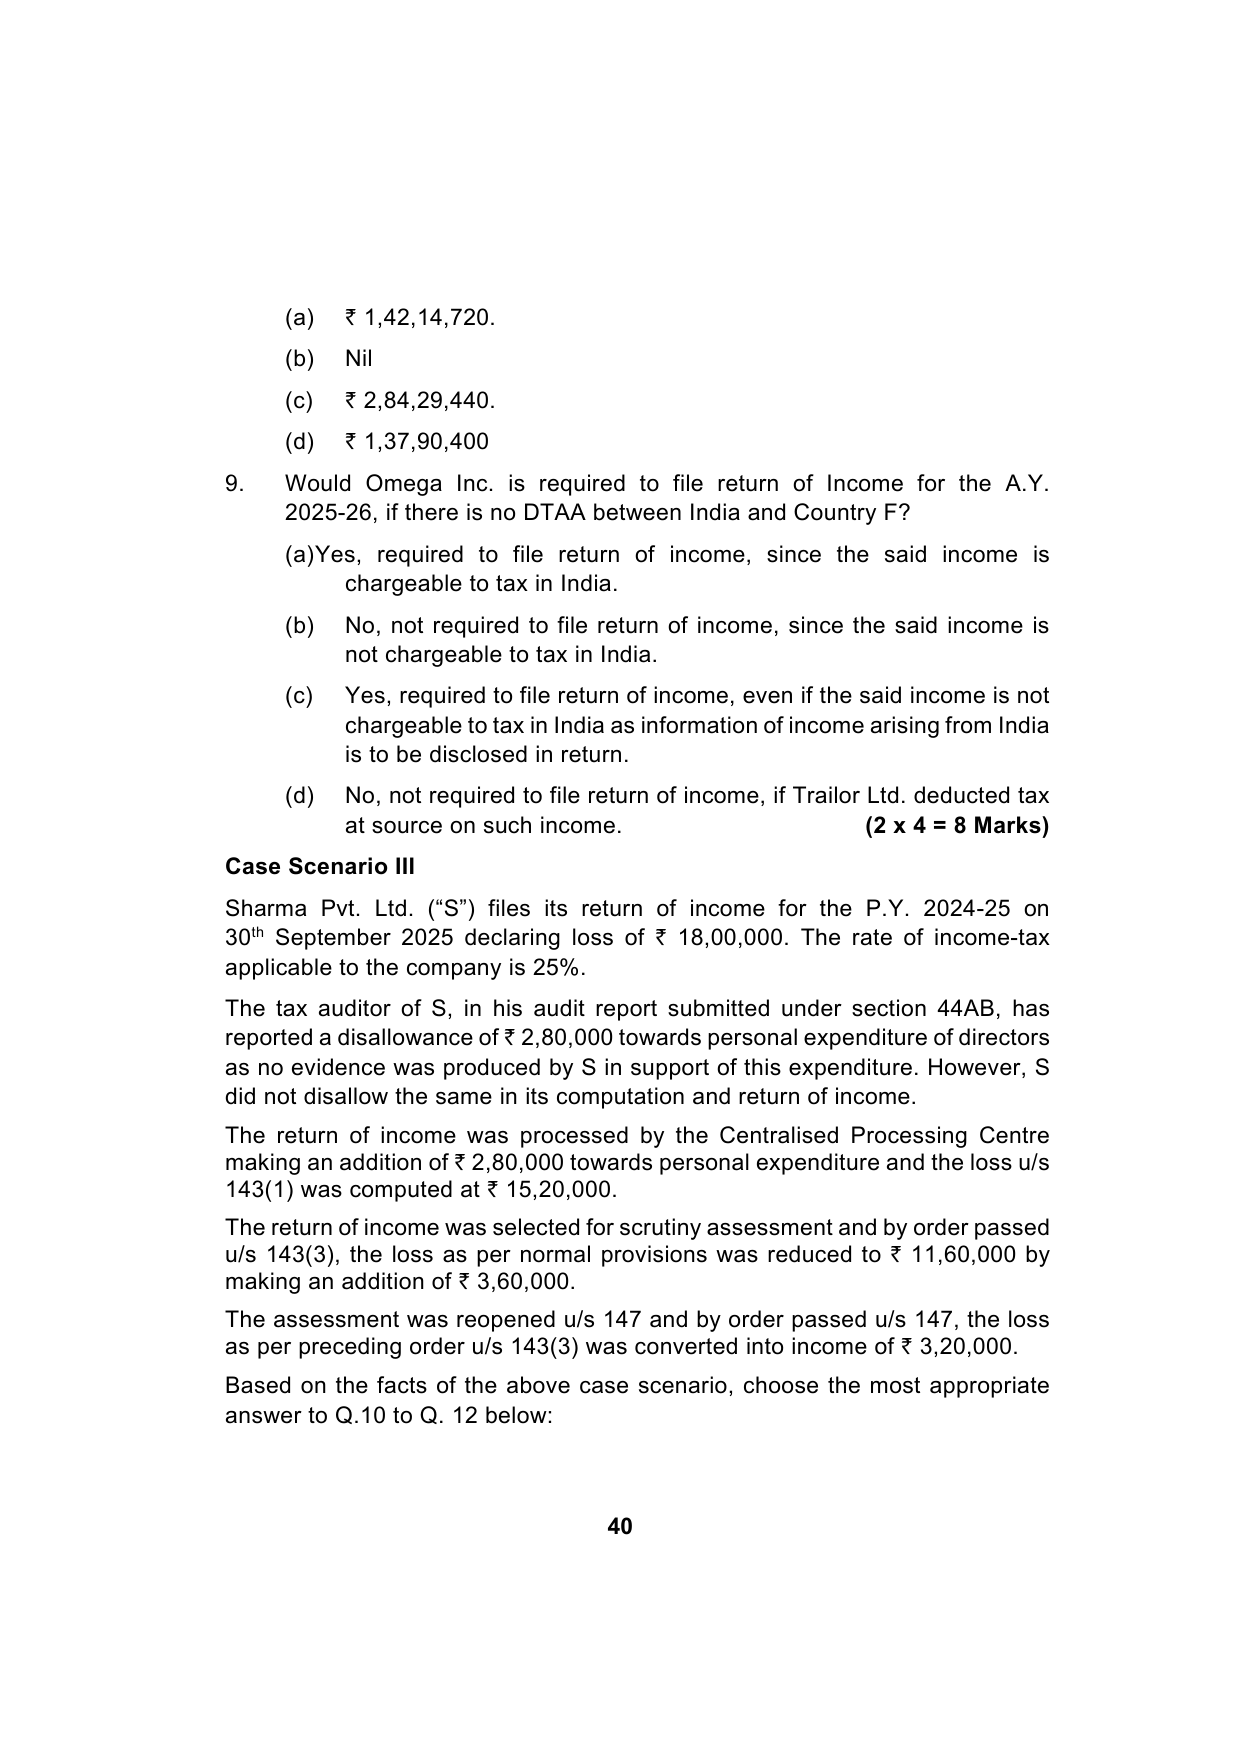
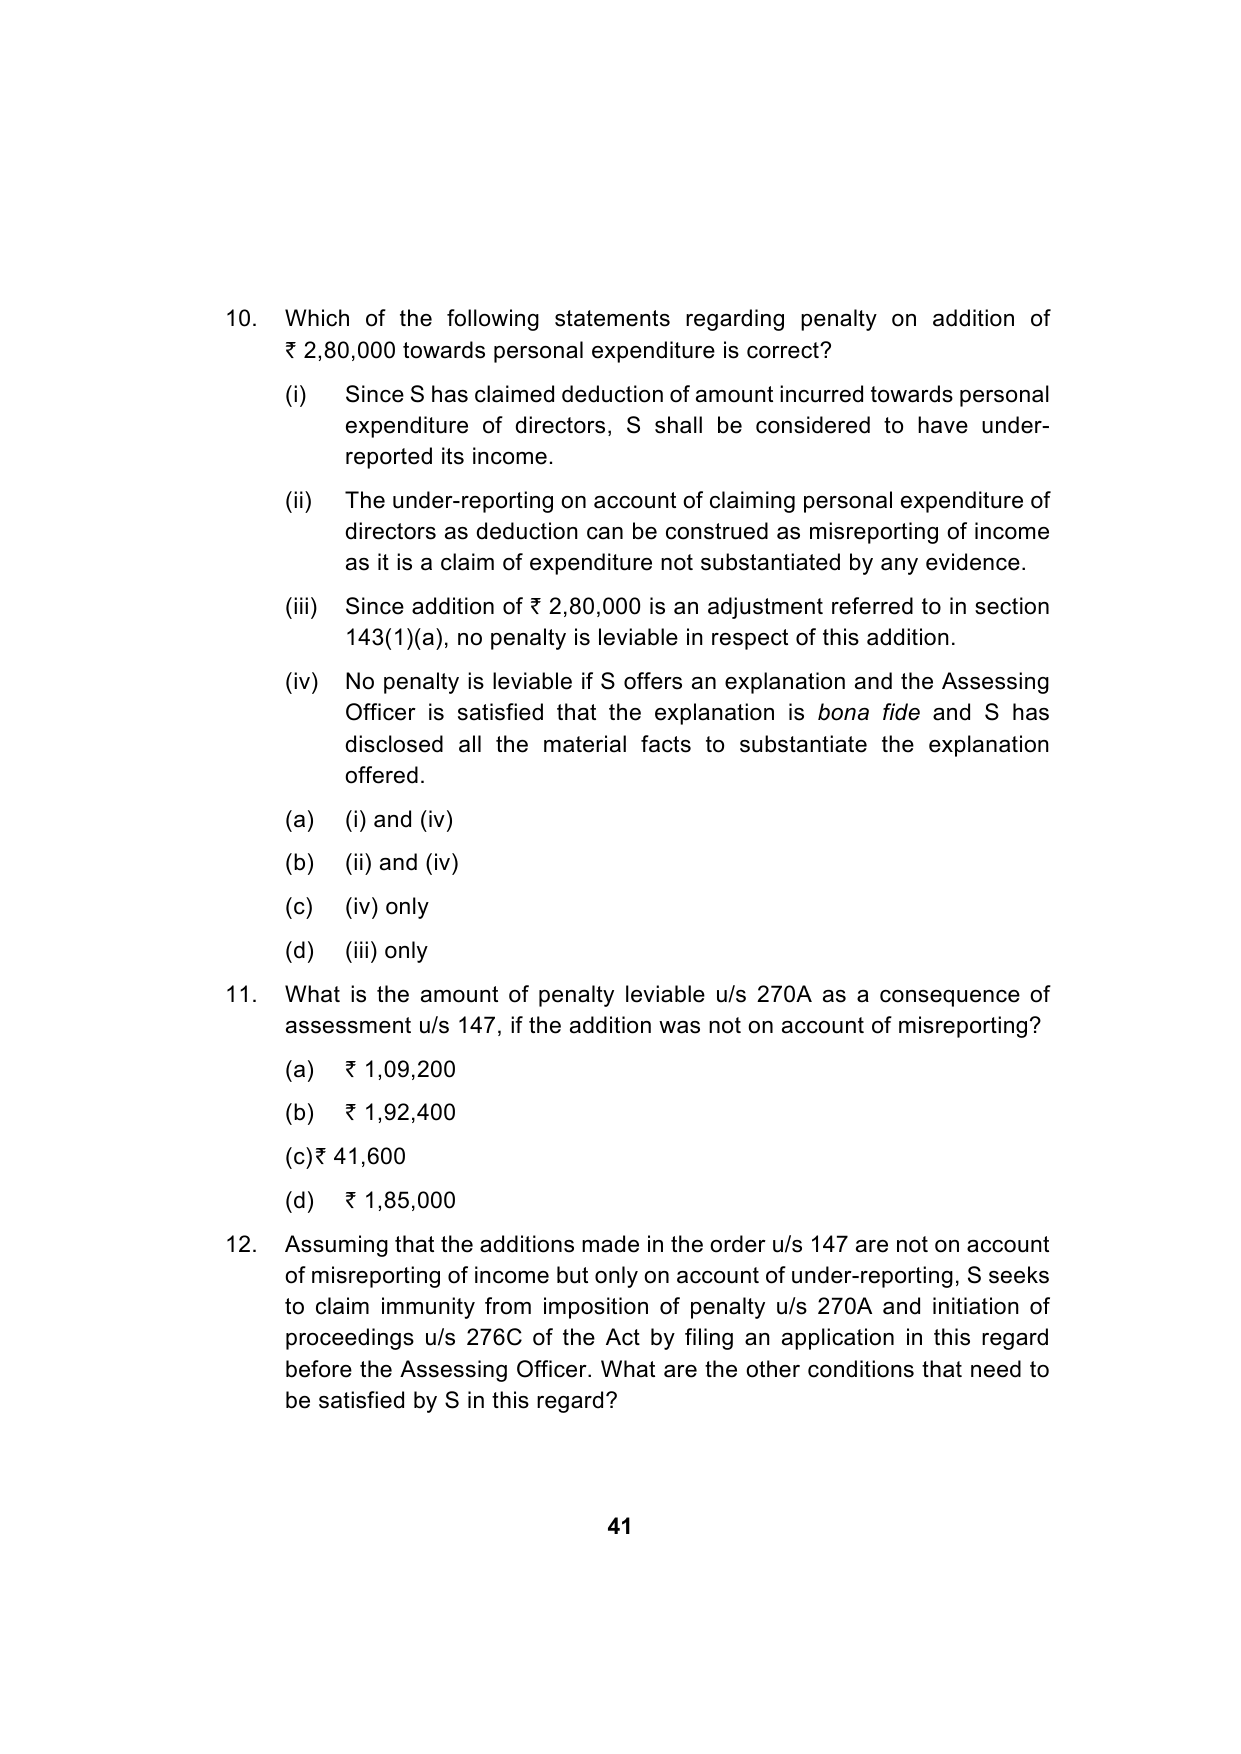
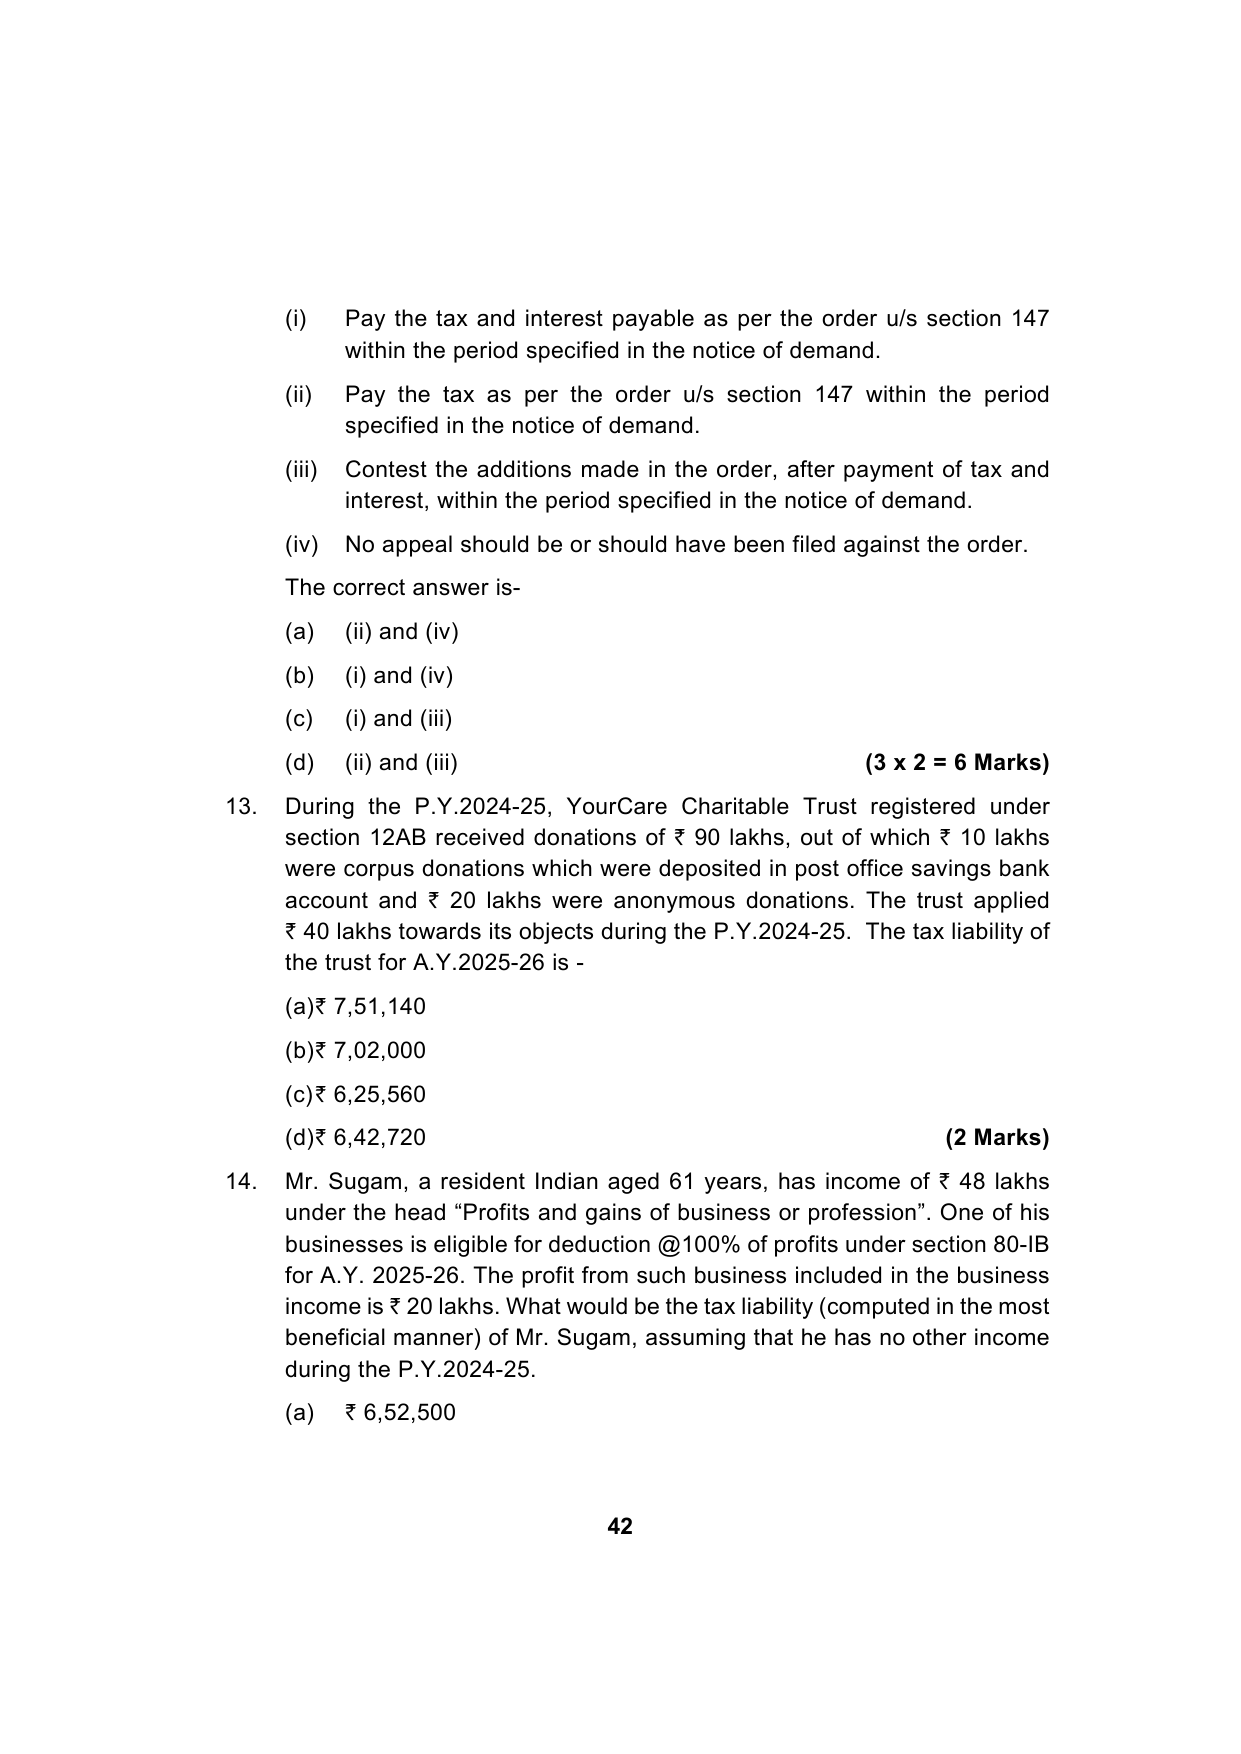
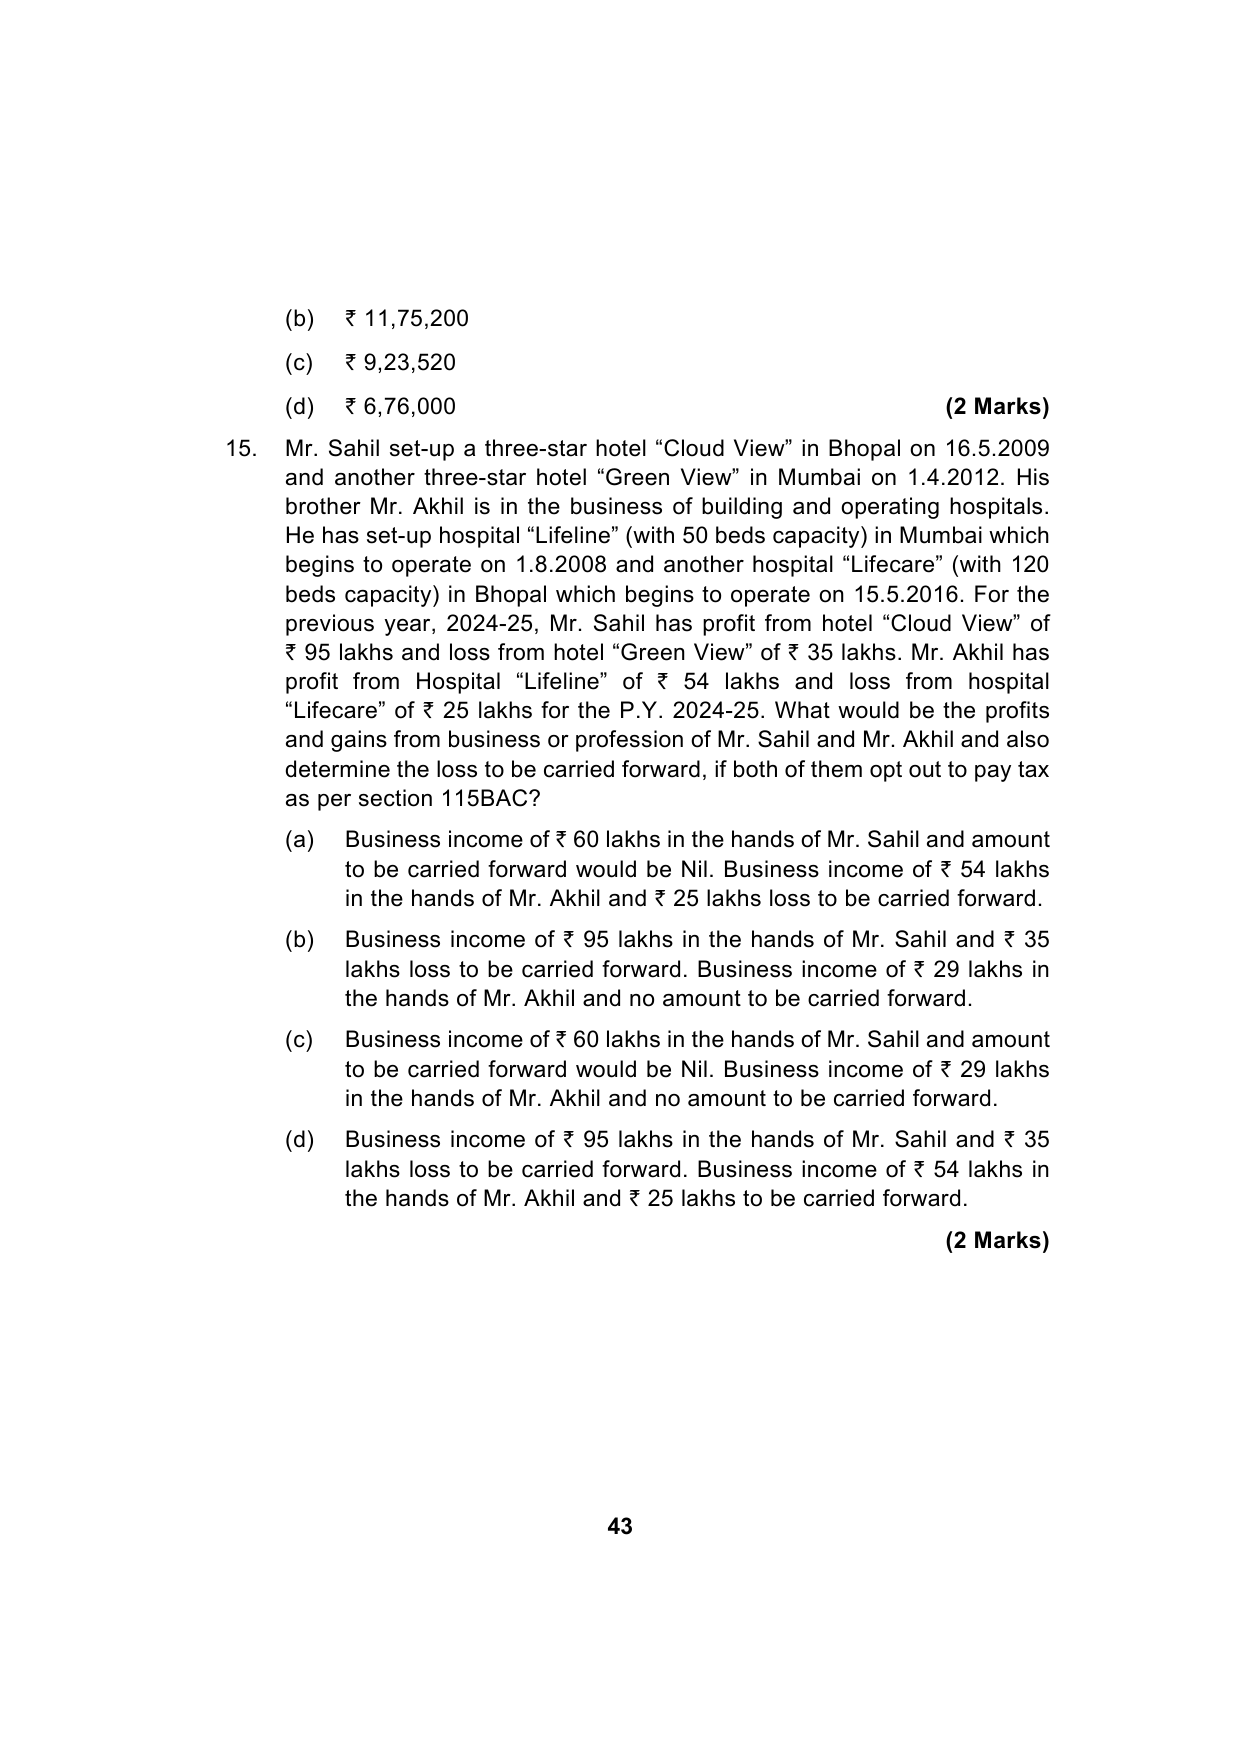
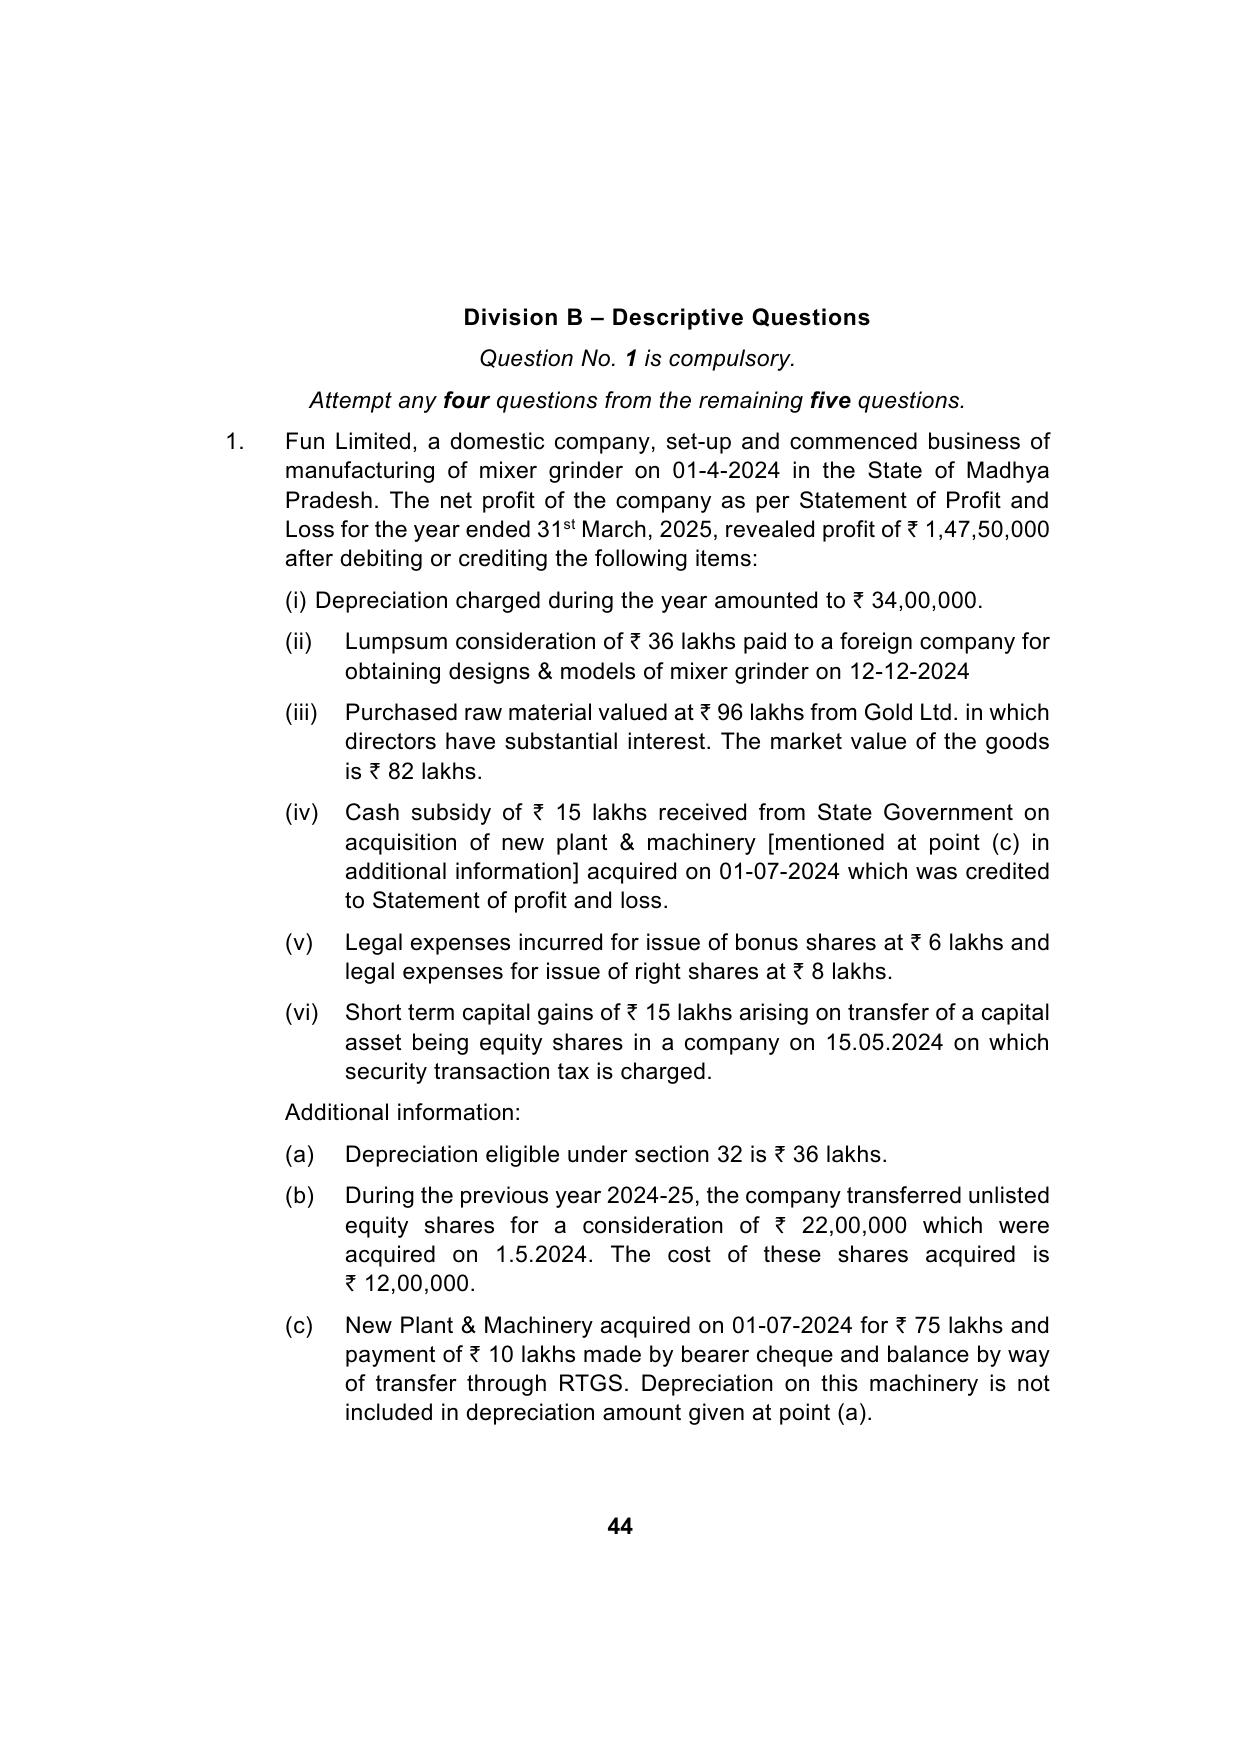
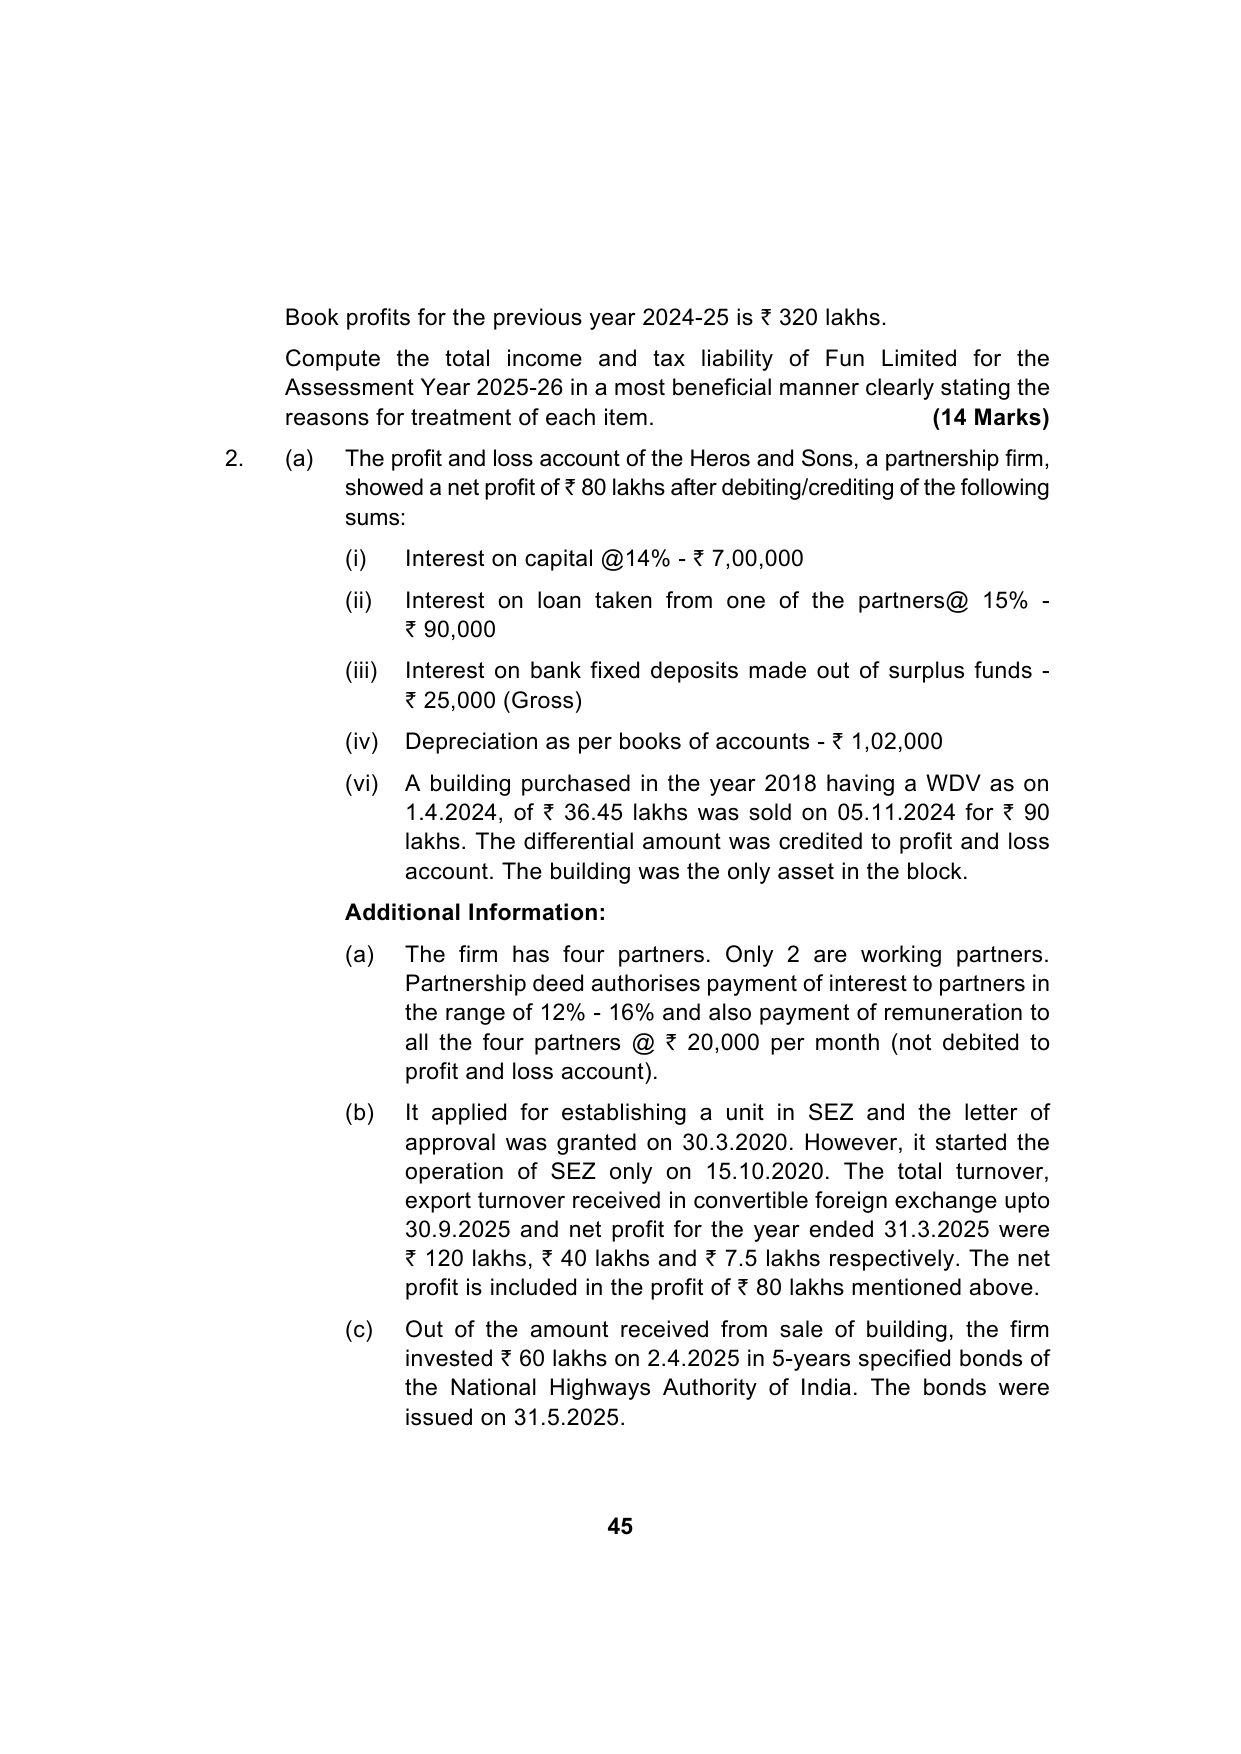
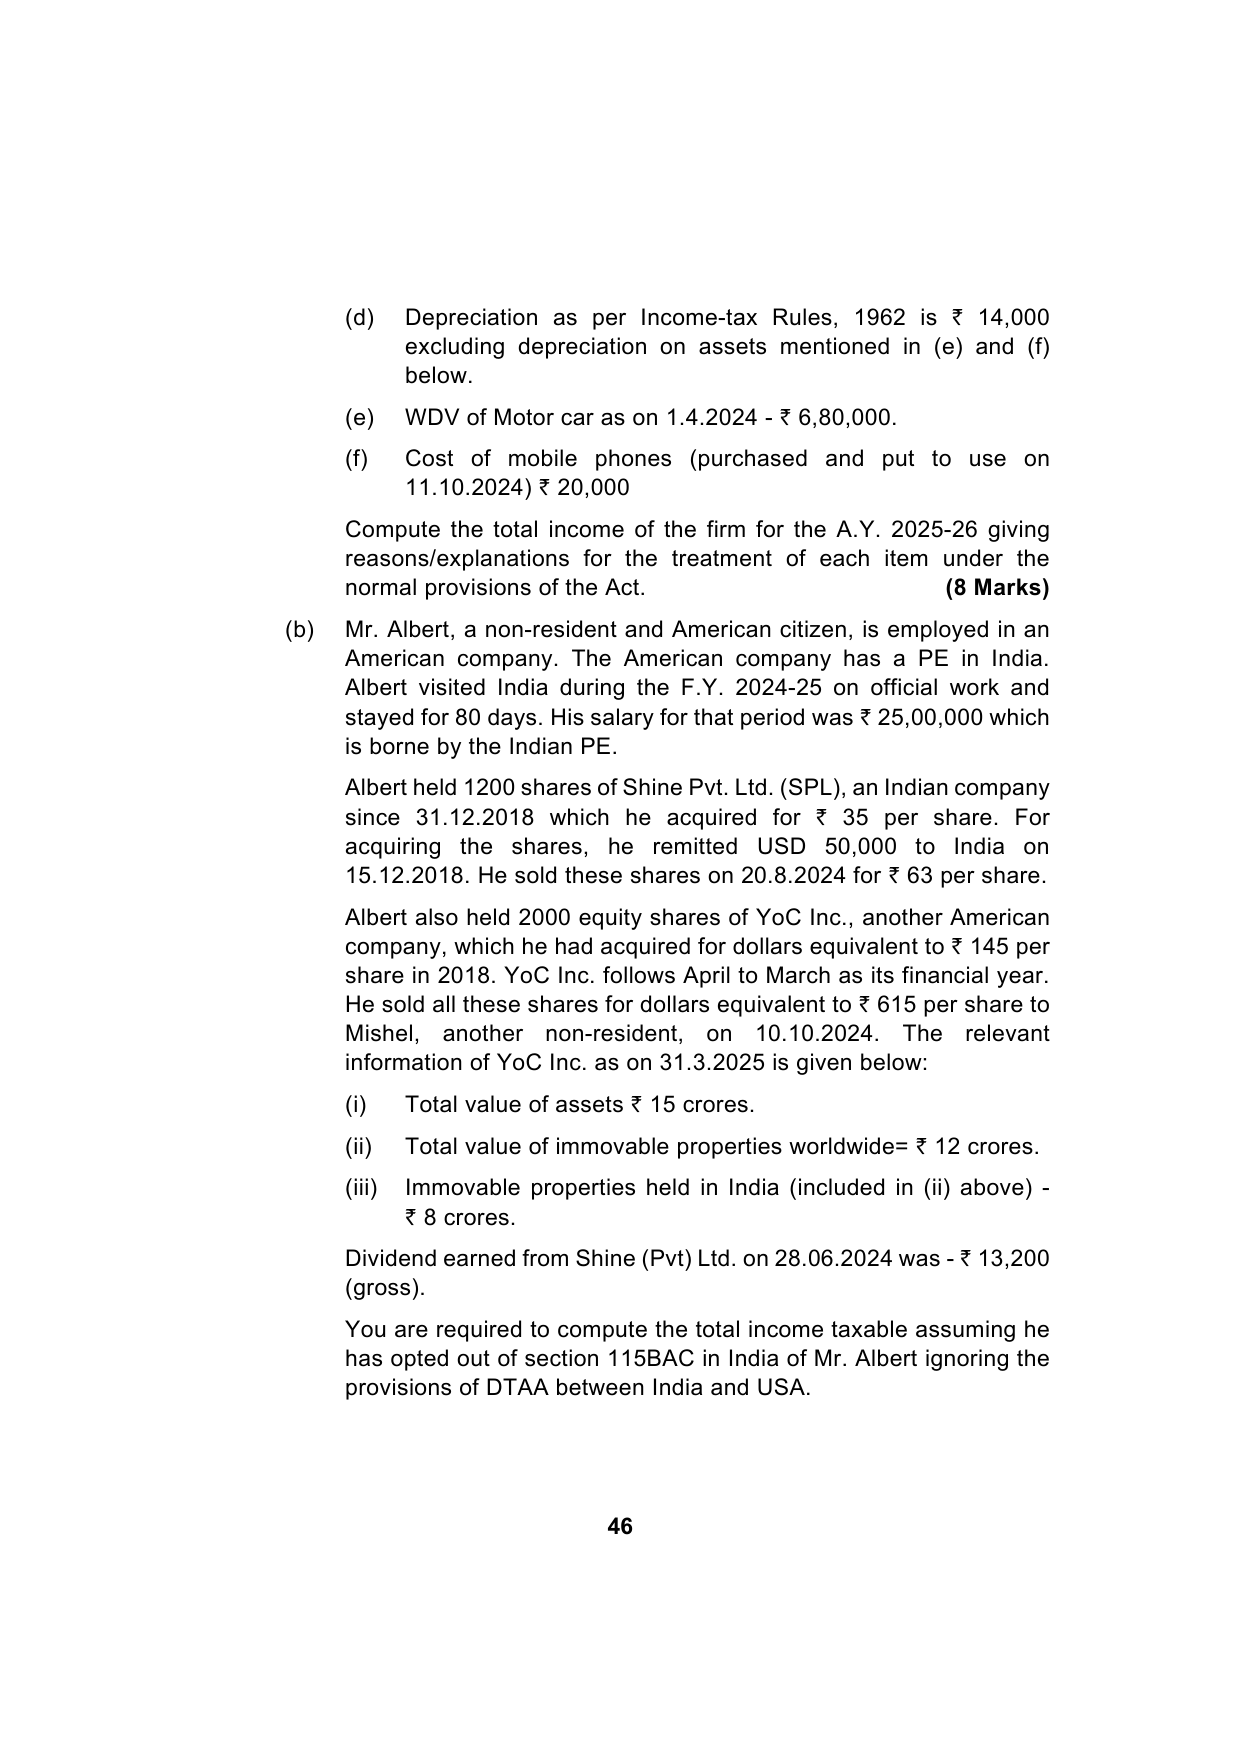
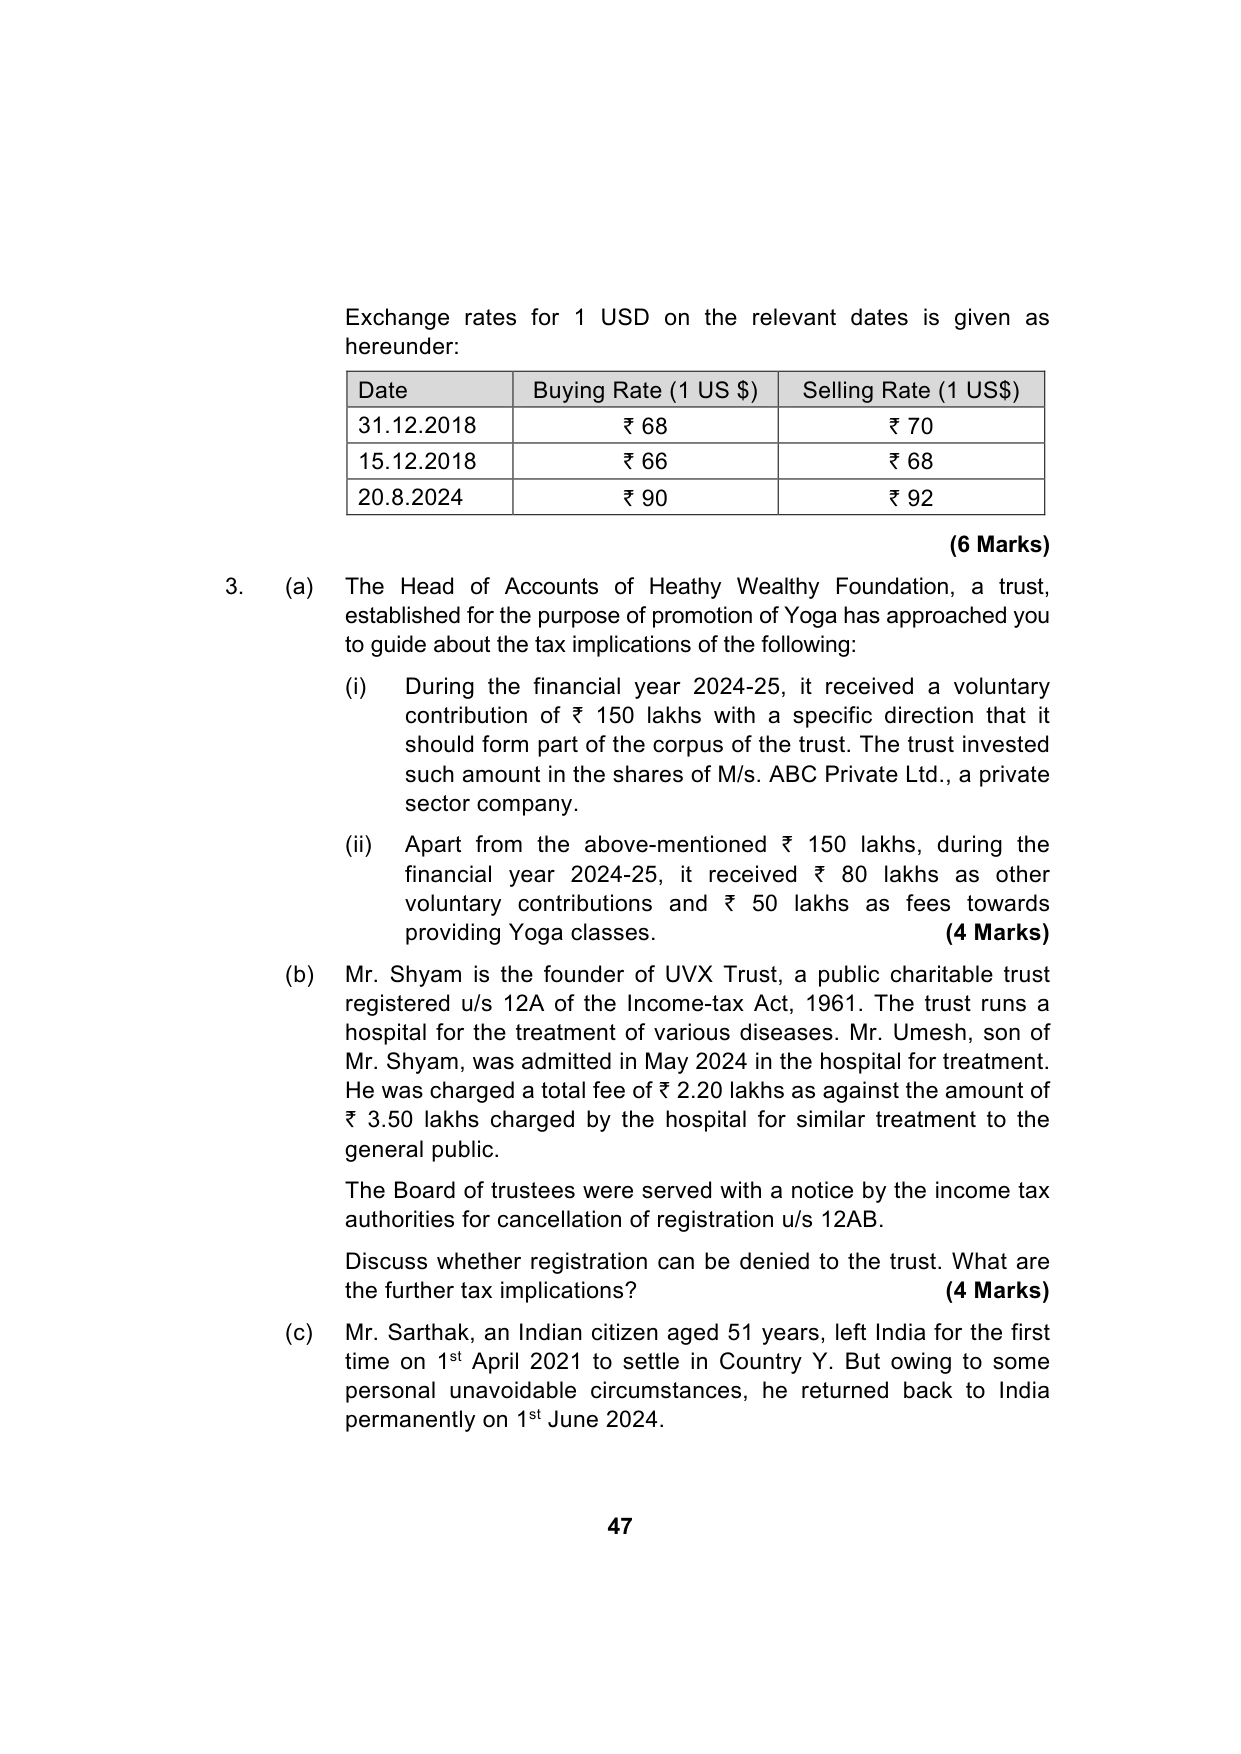
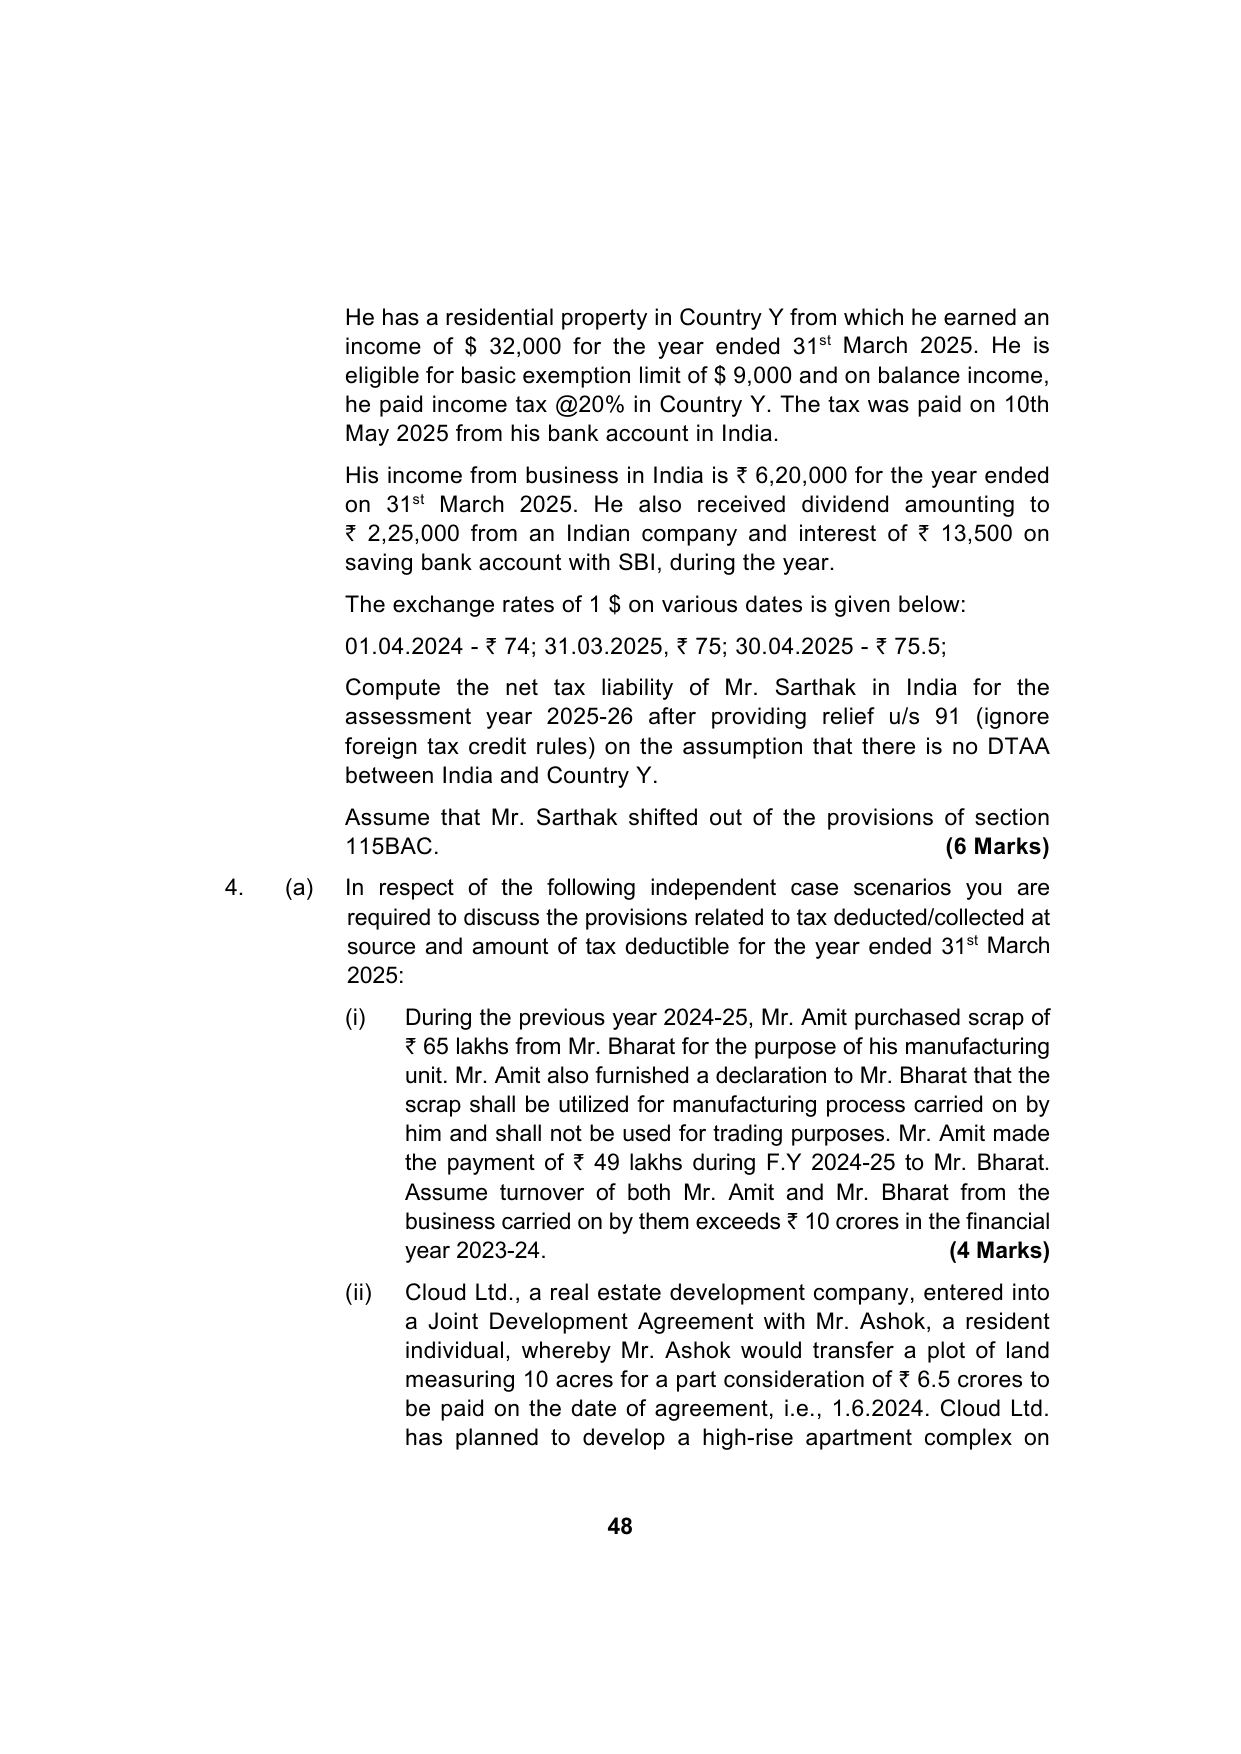
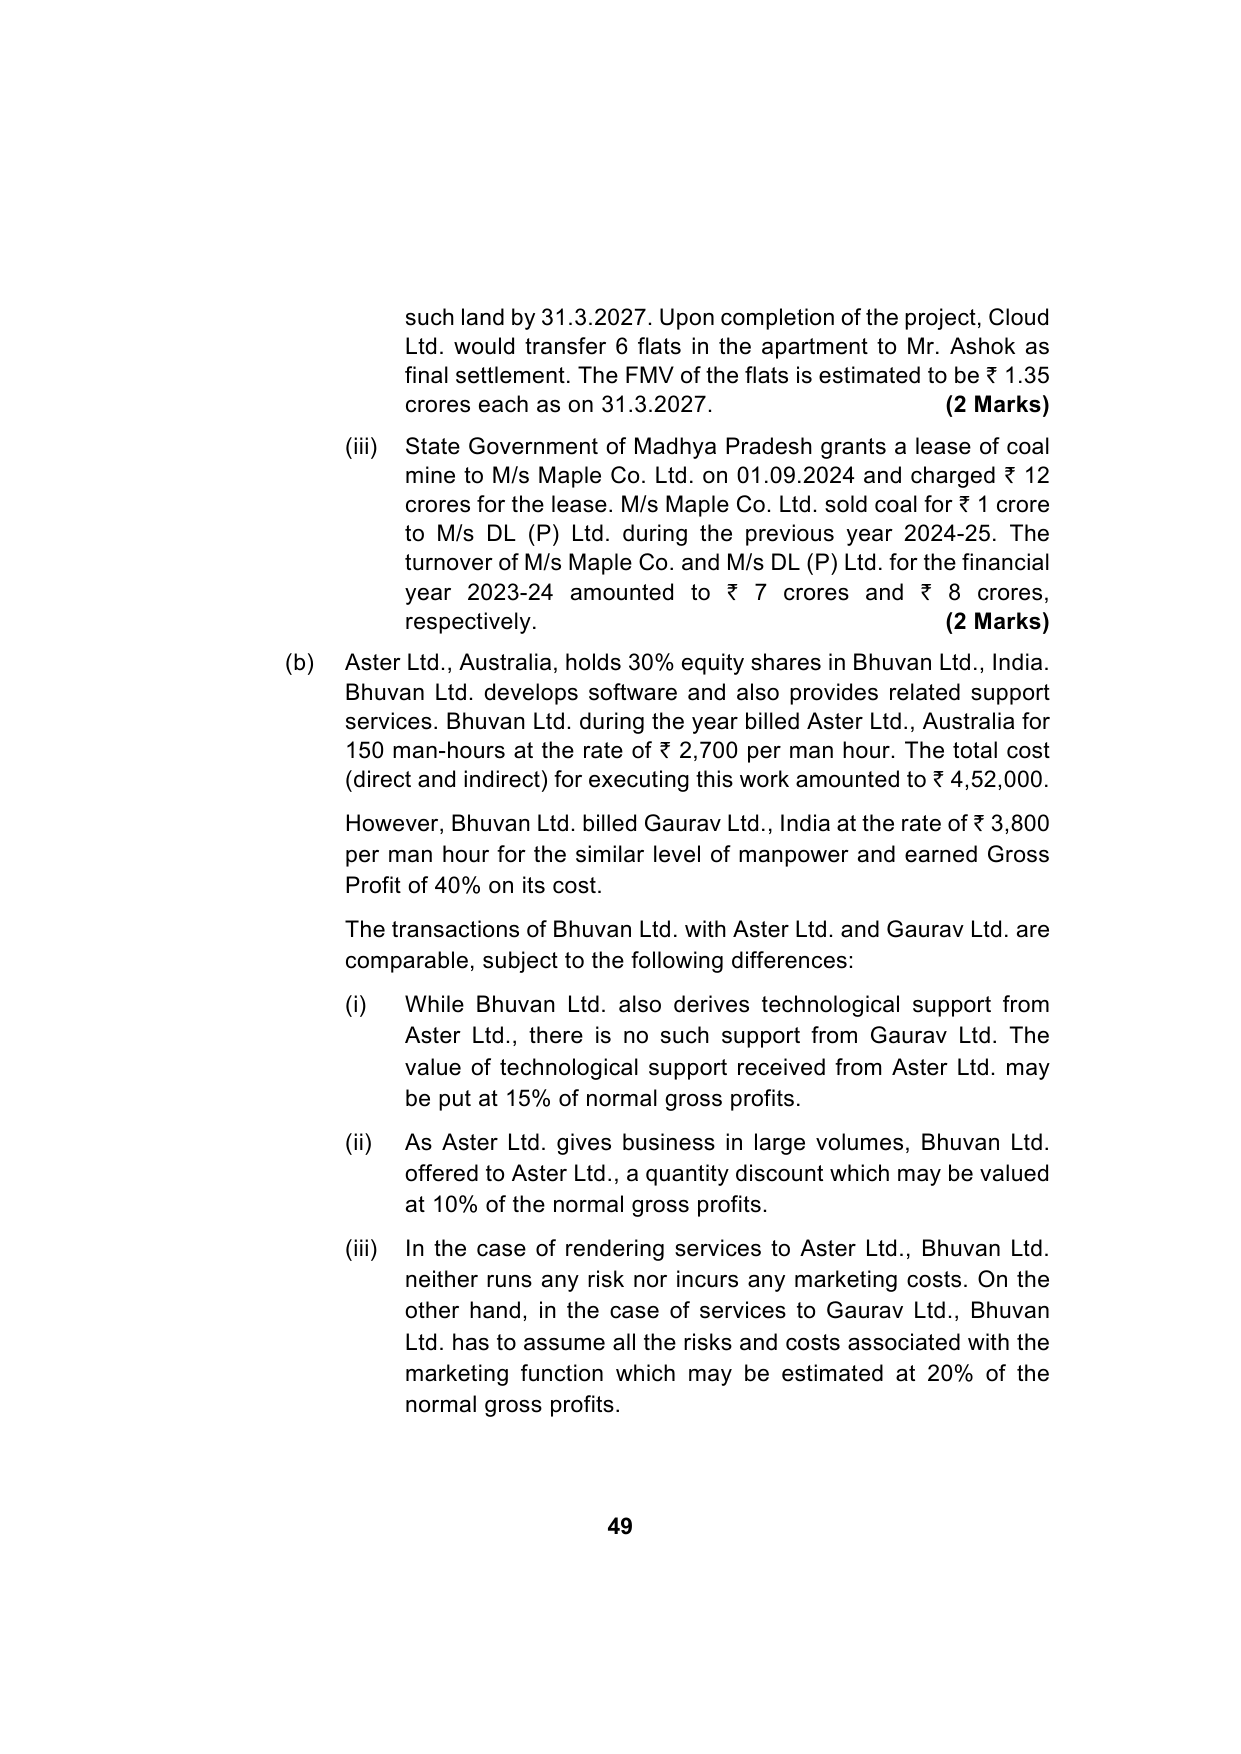
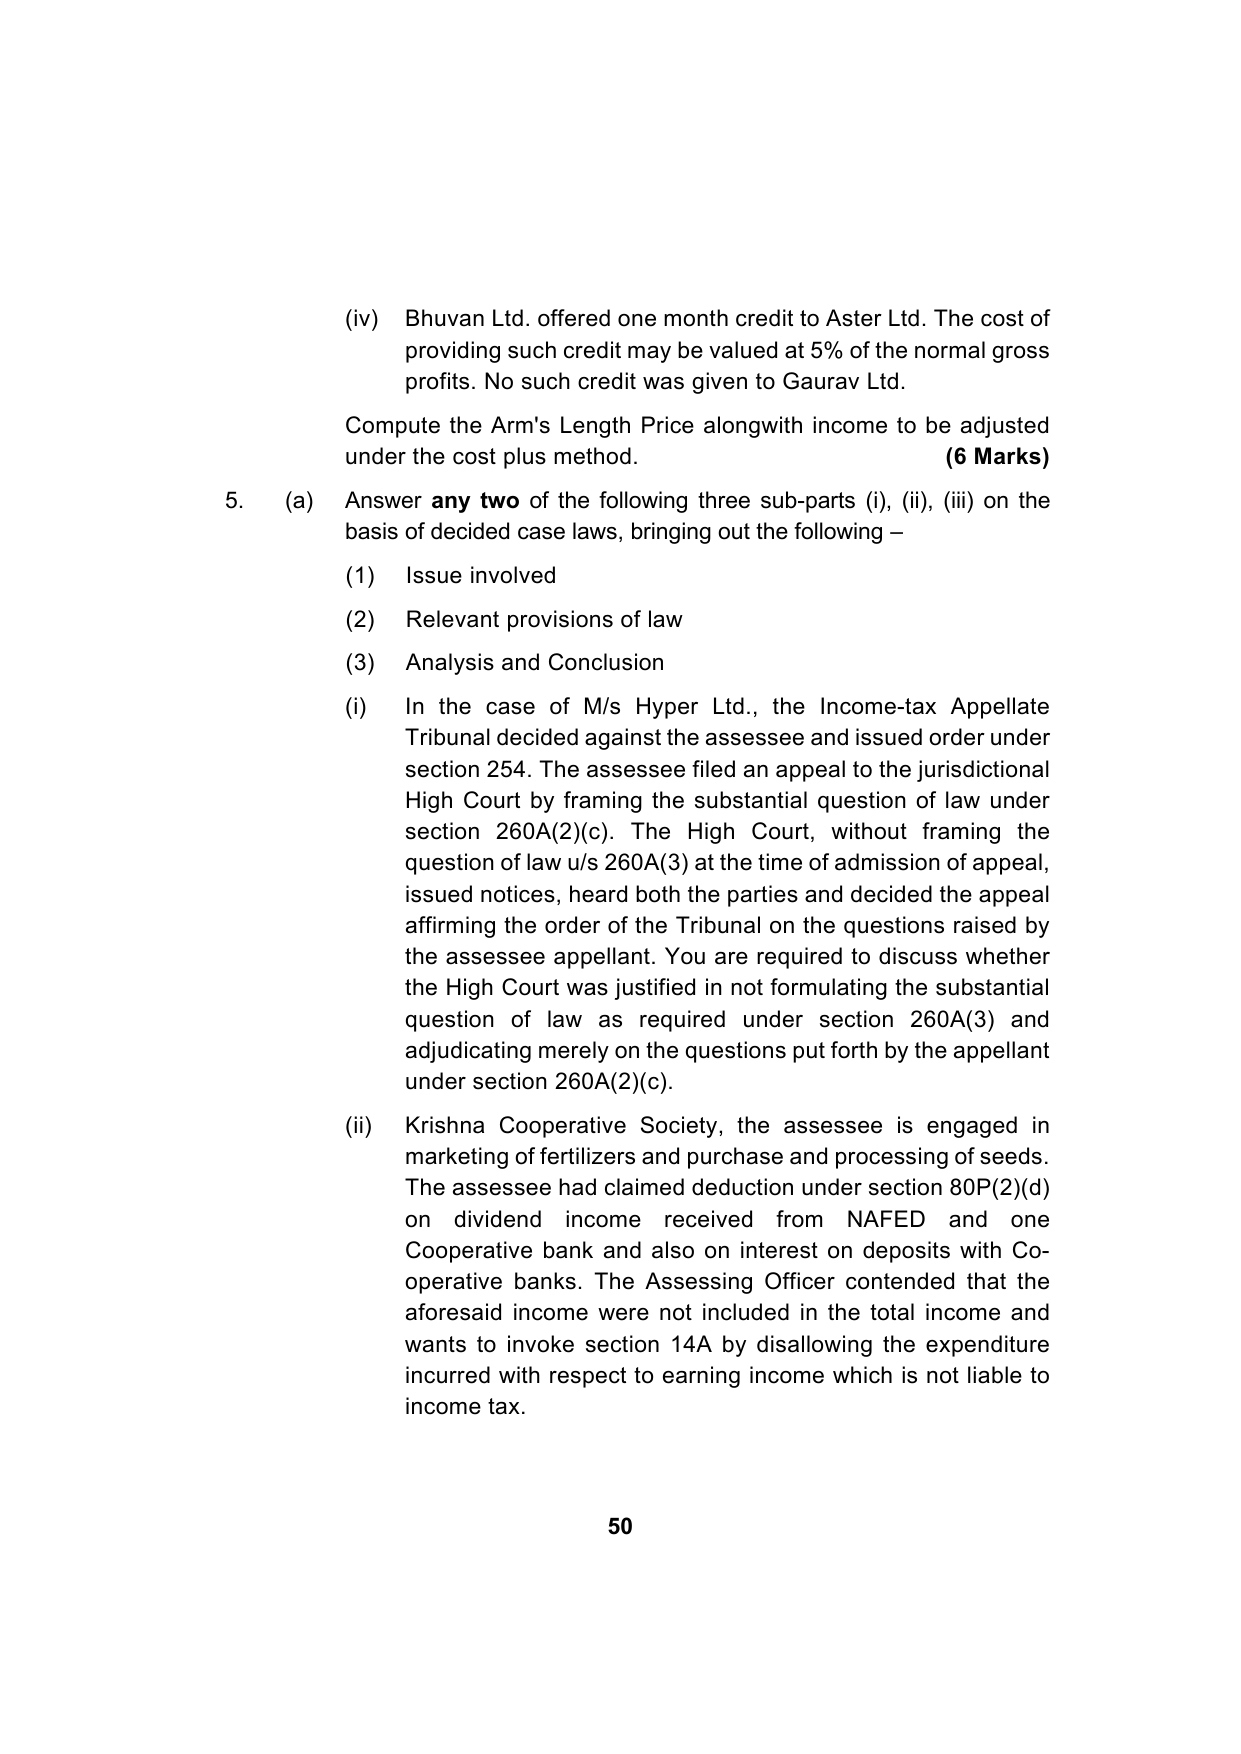
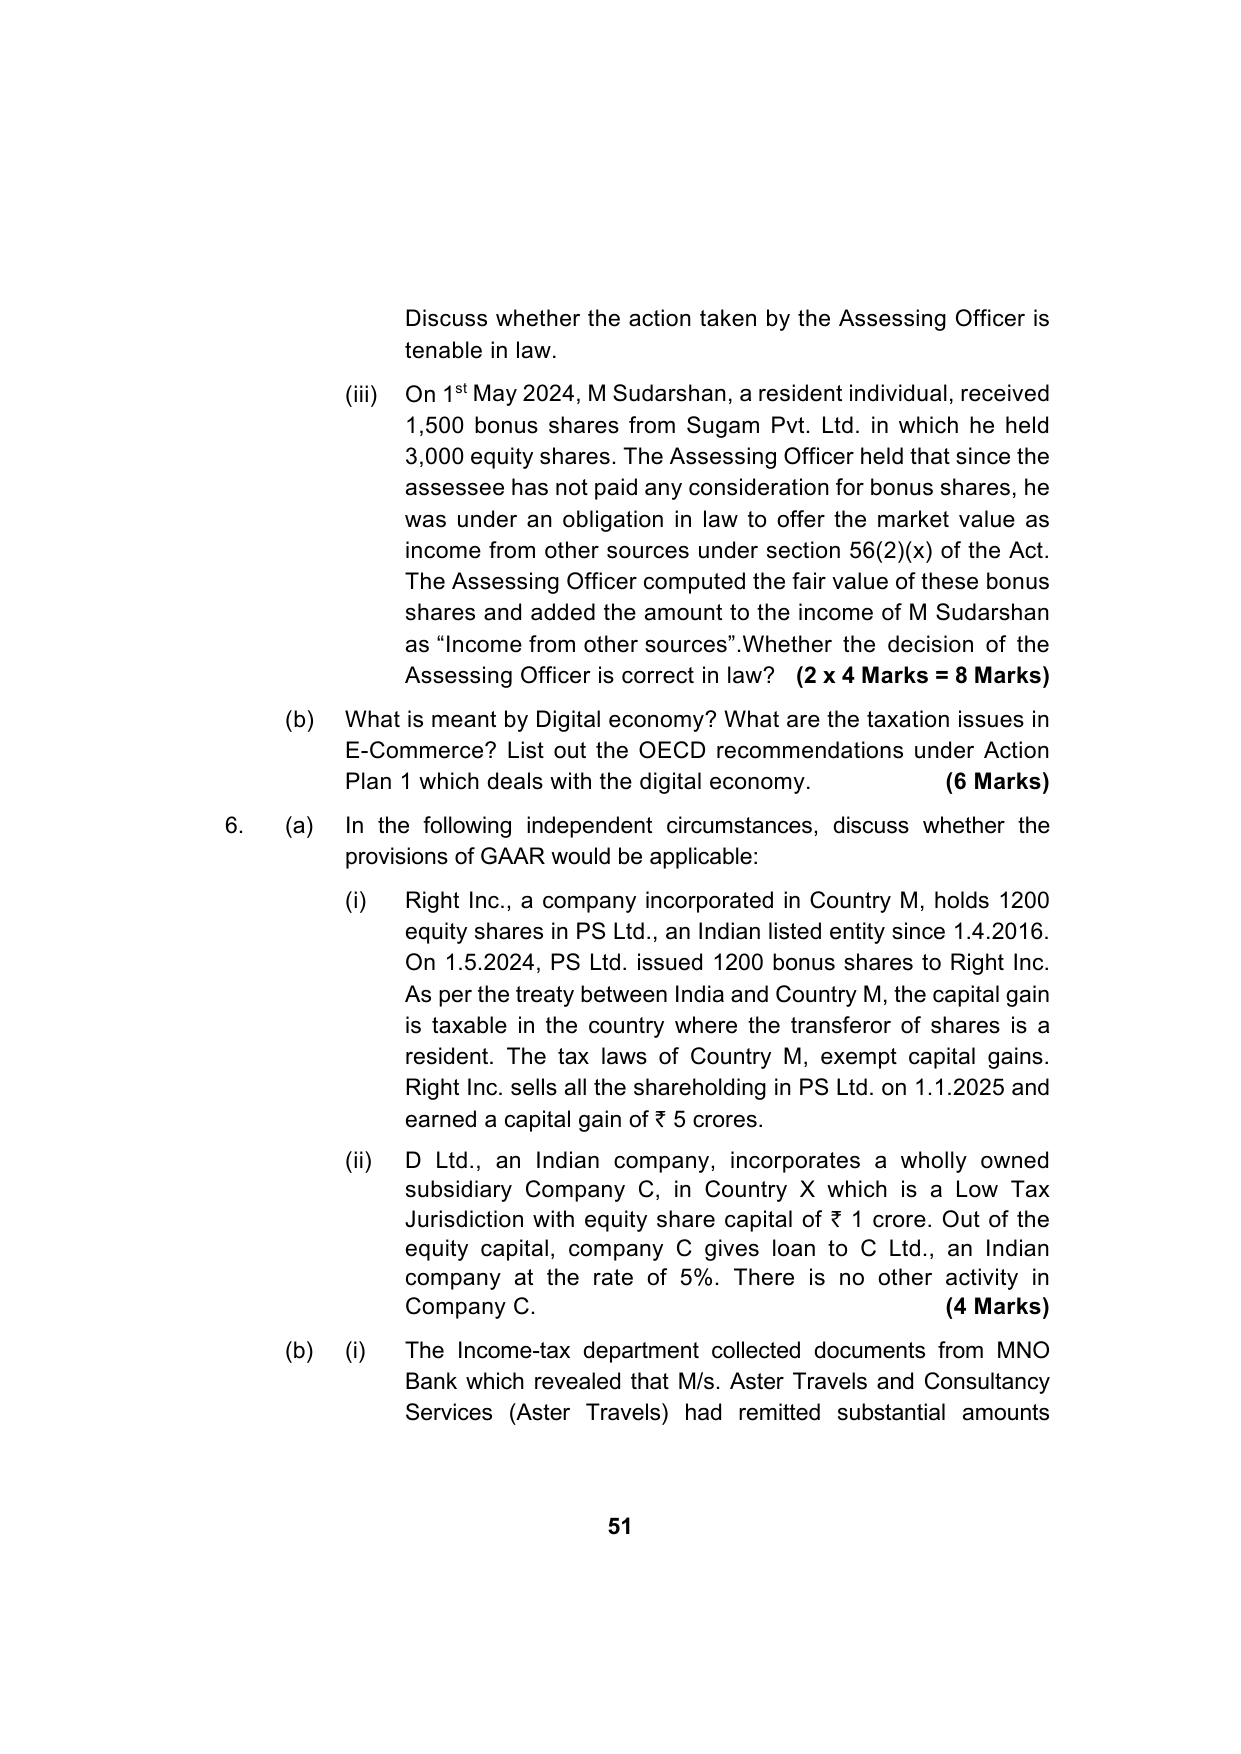
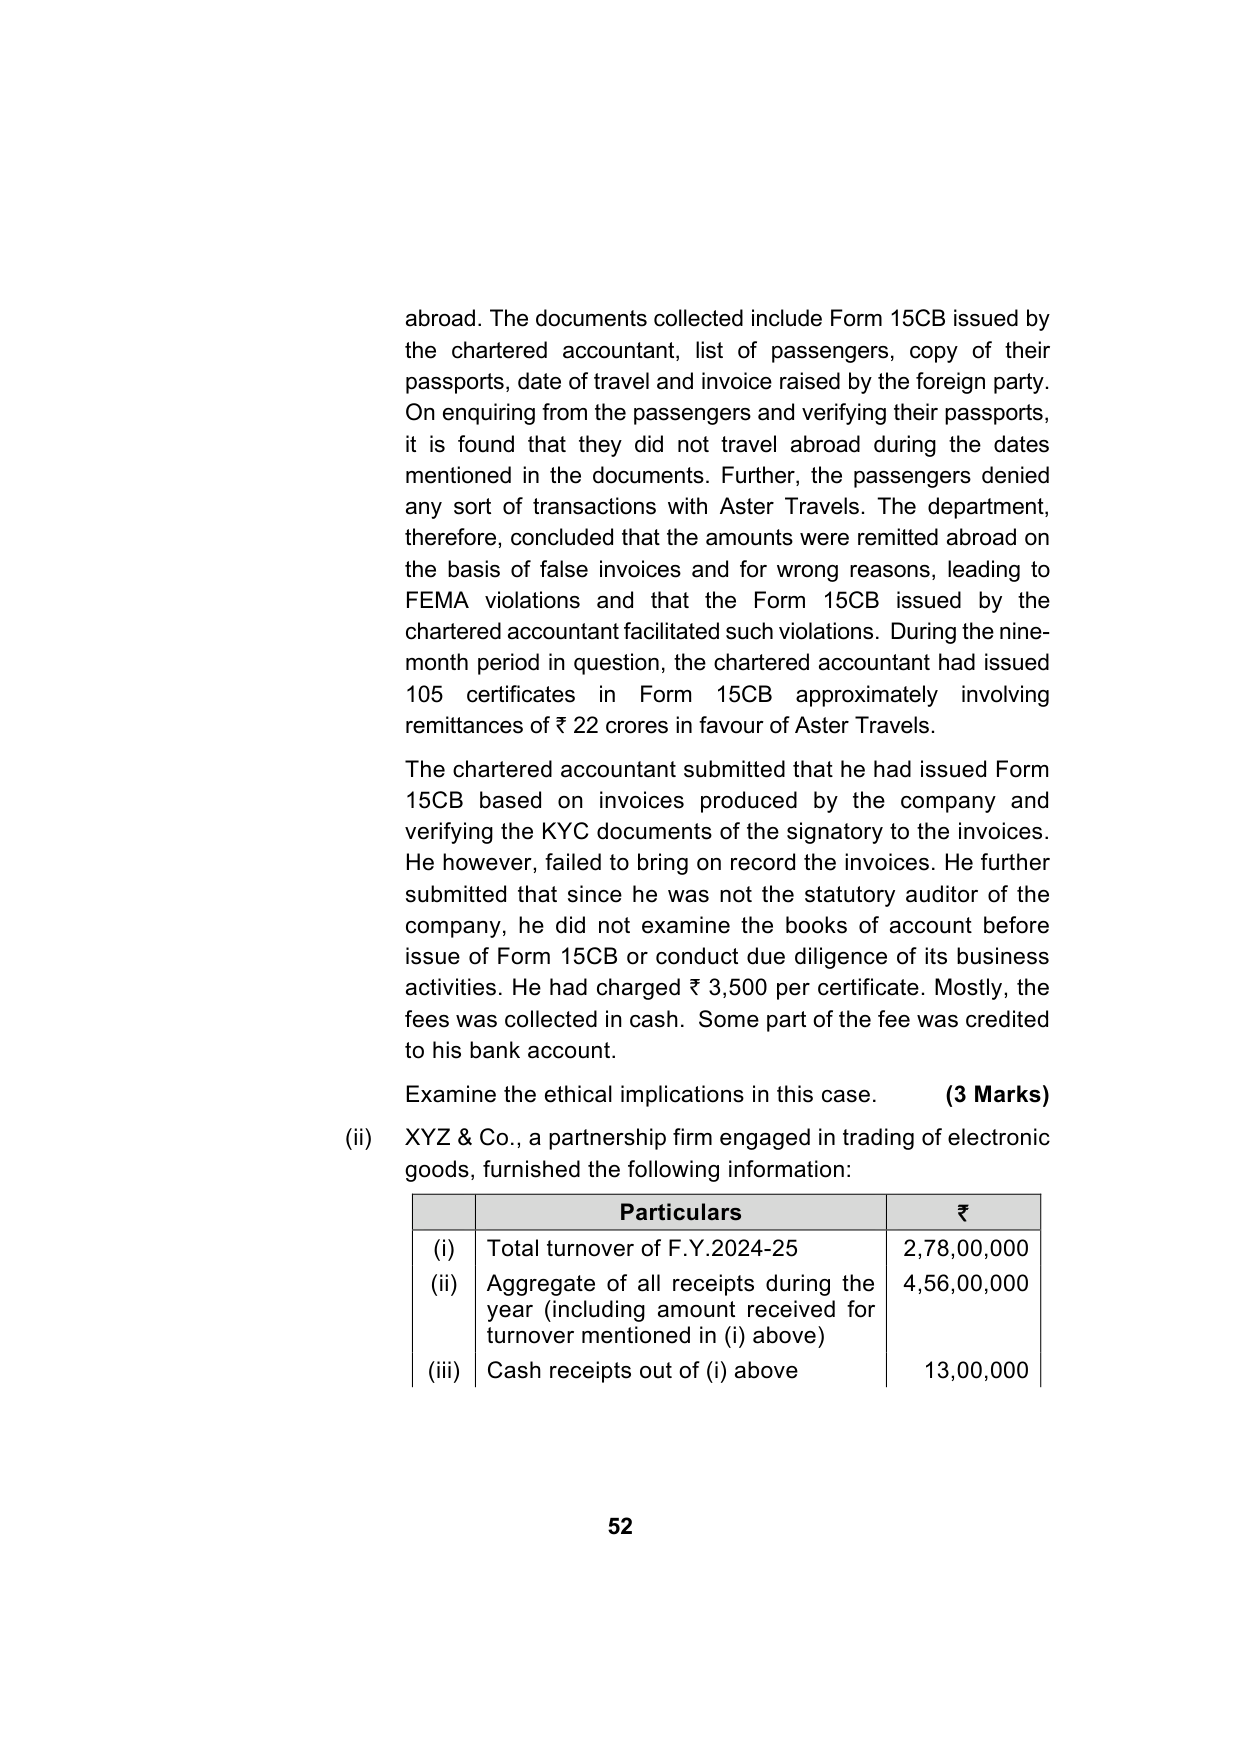
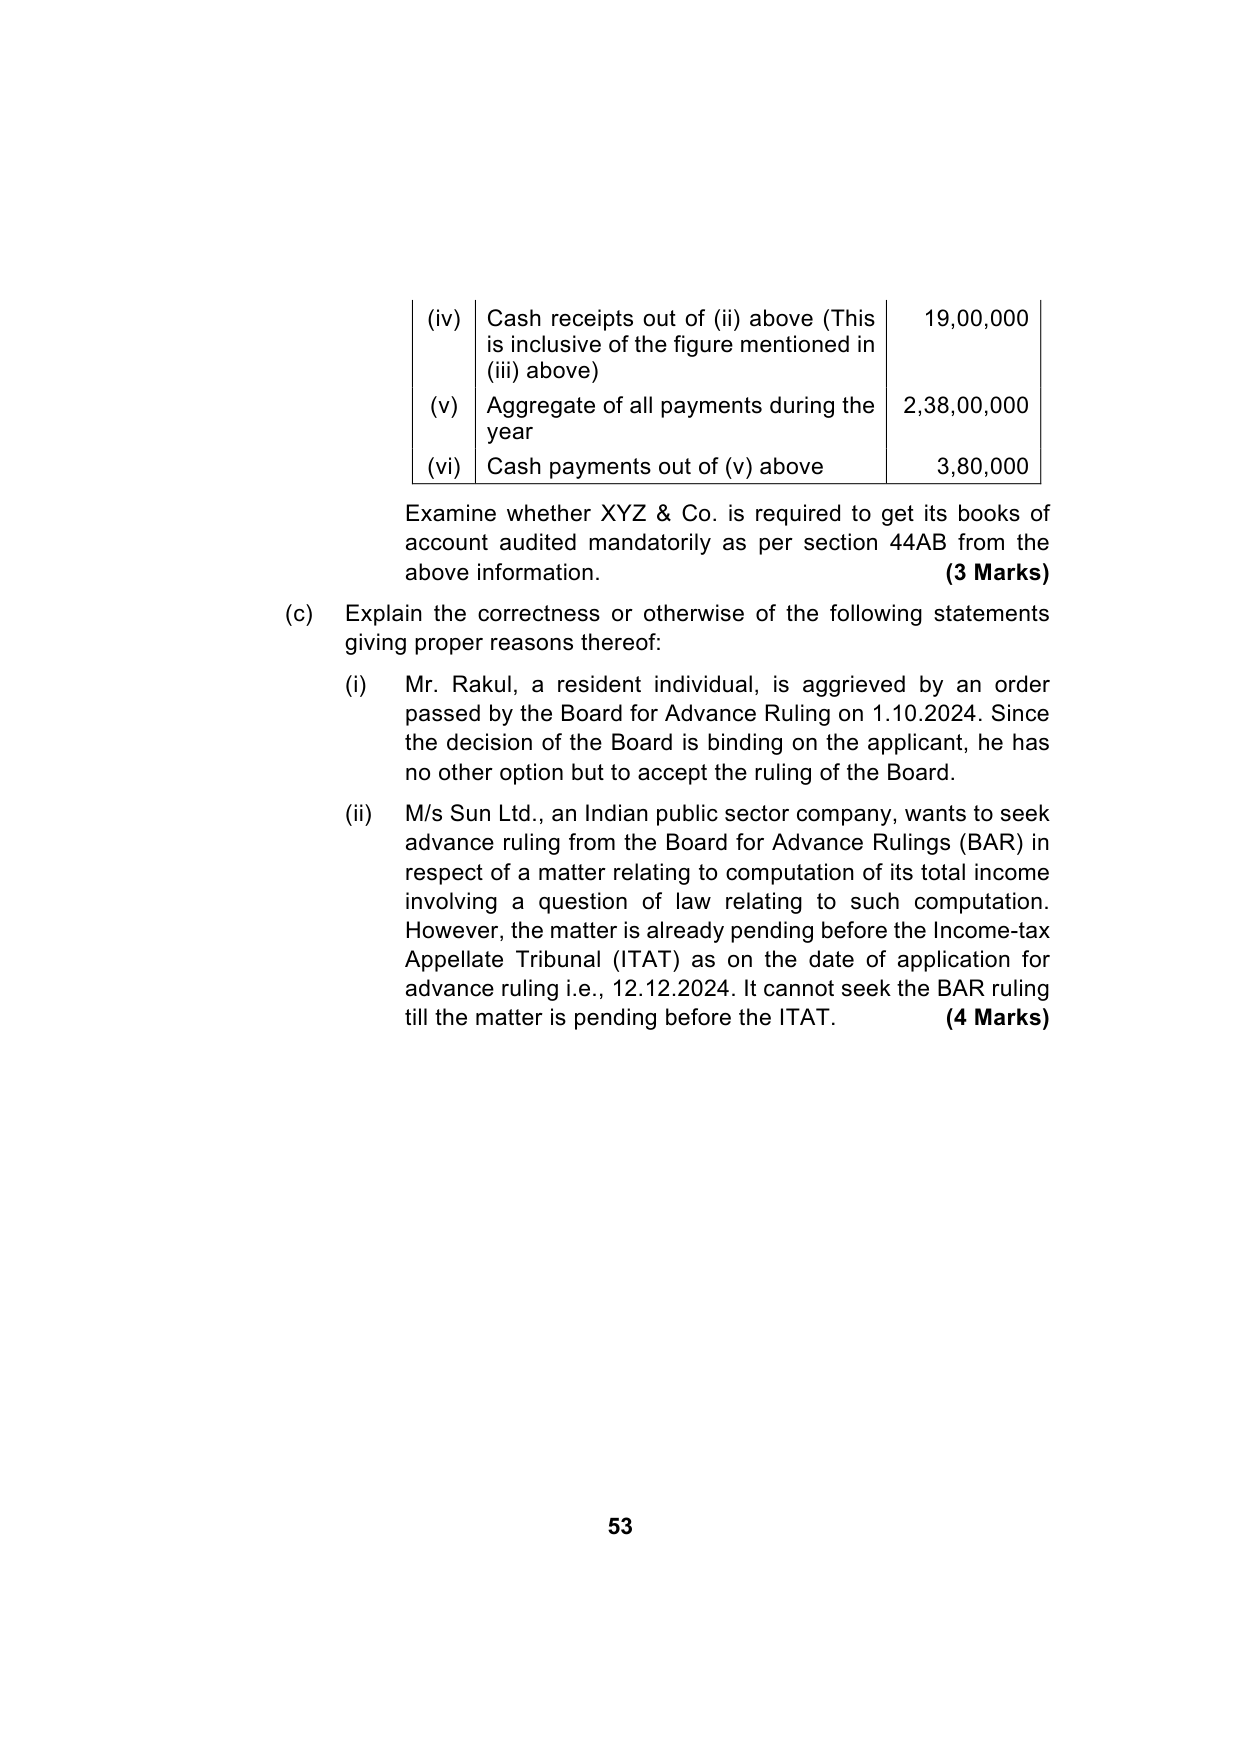
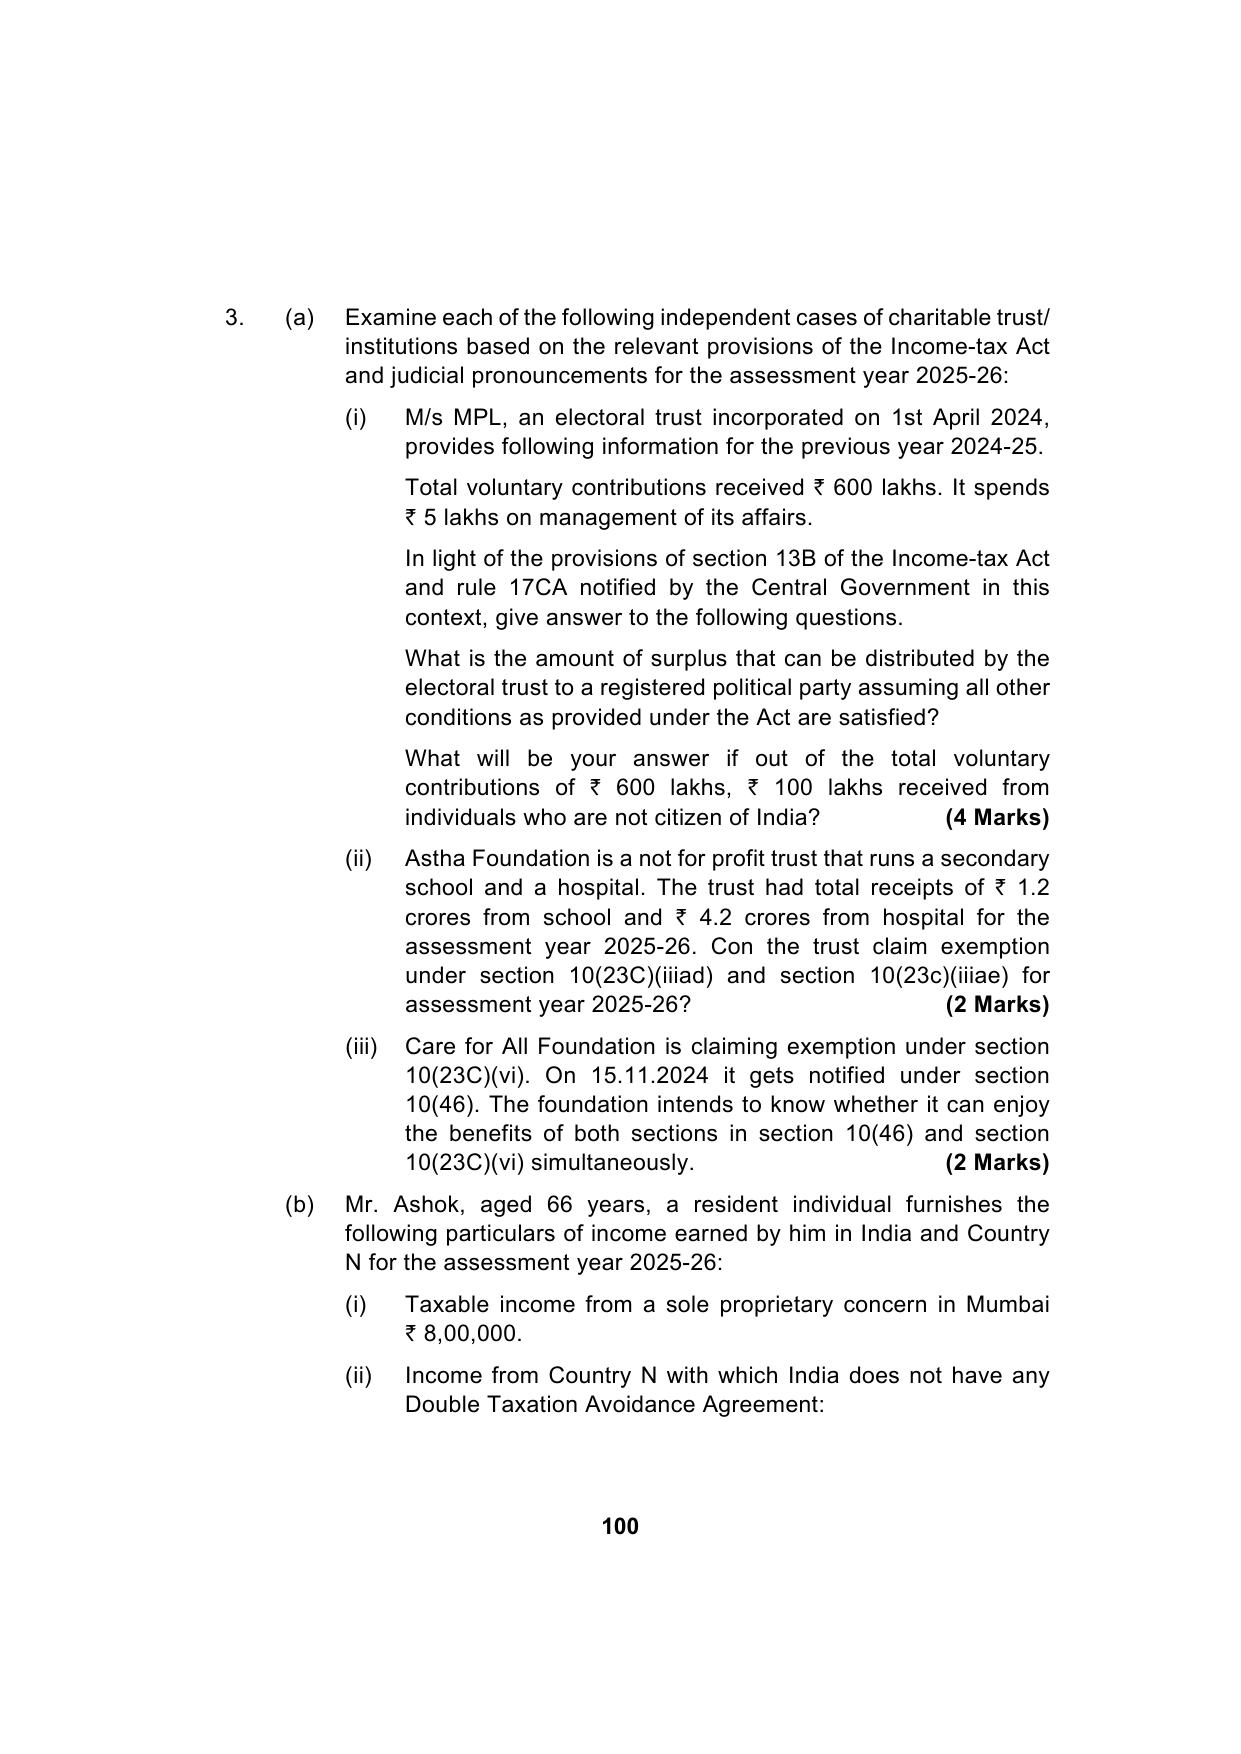
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 4 (100 marks)
Question
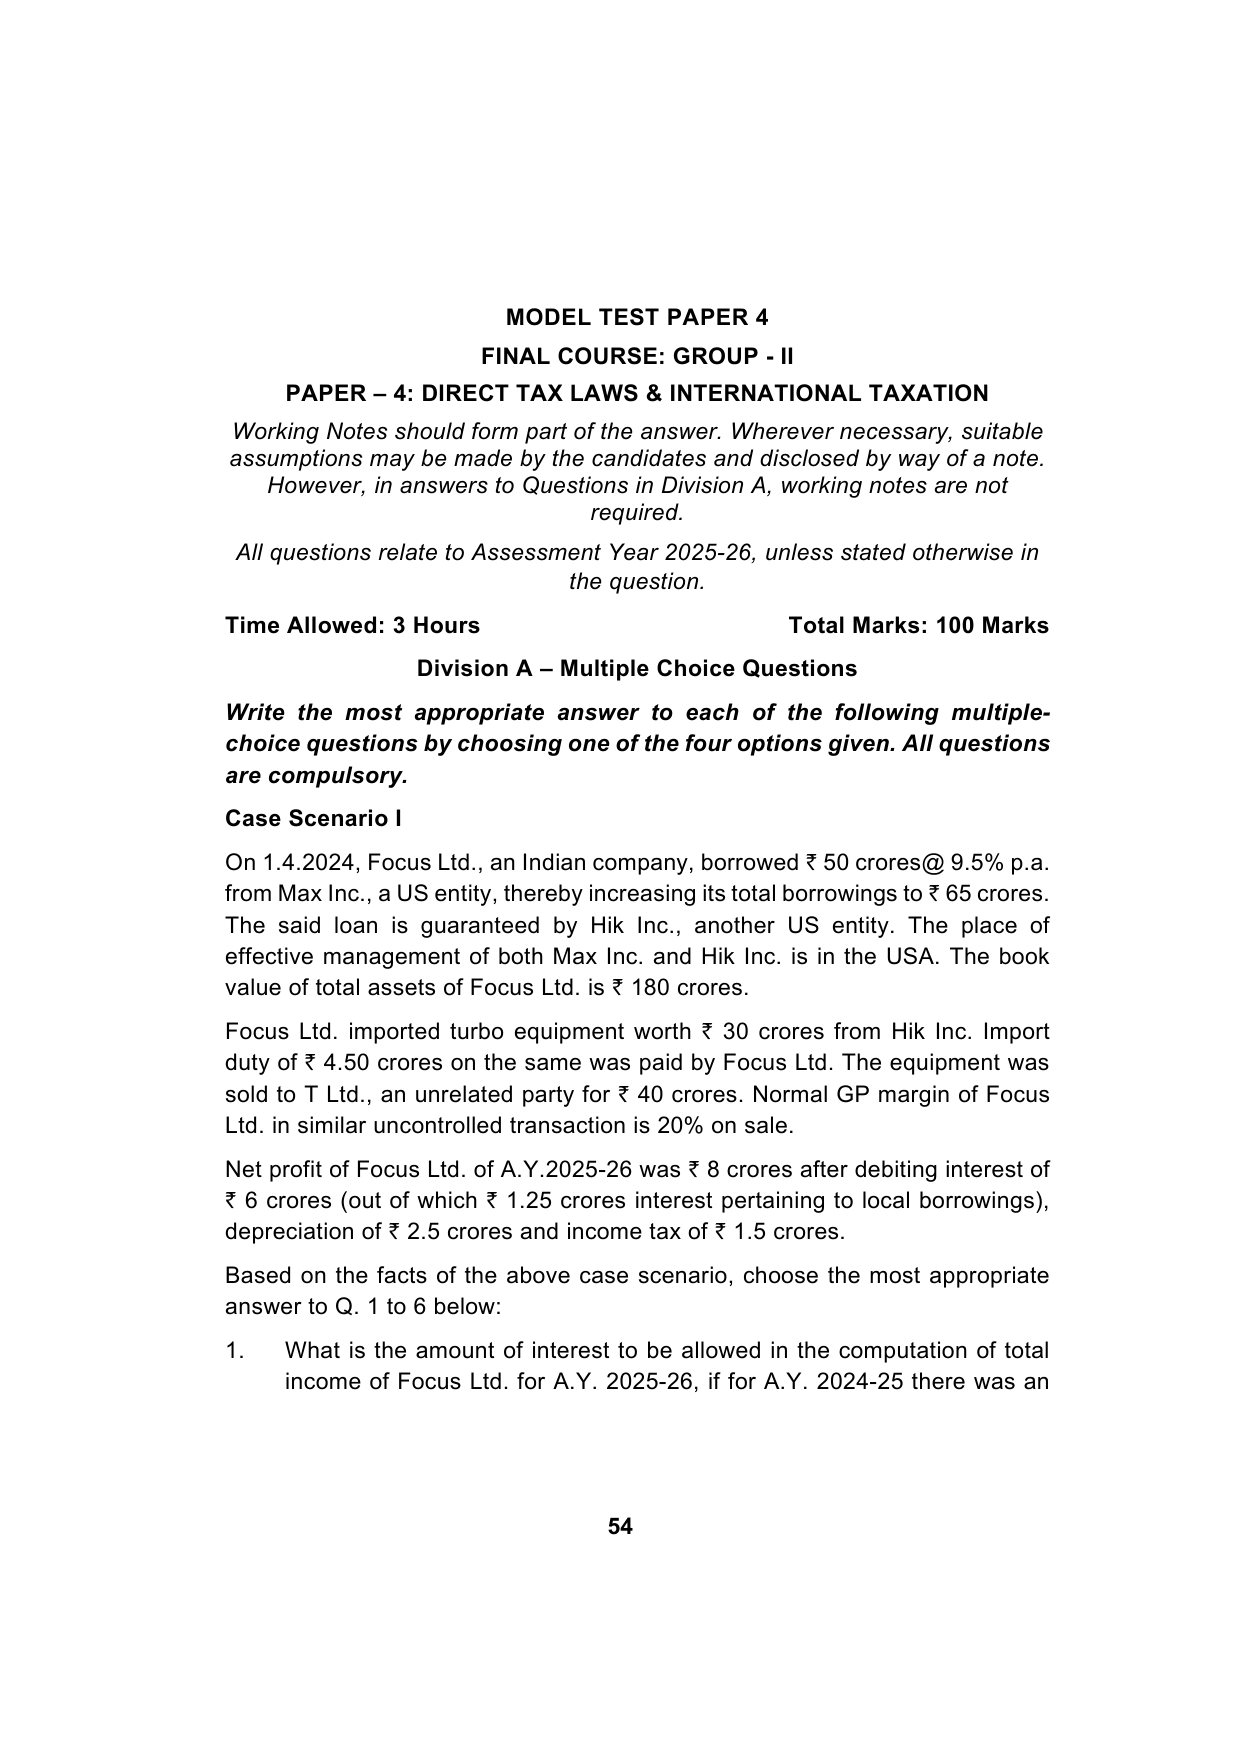
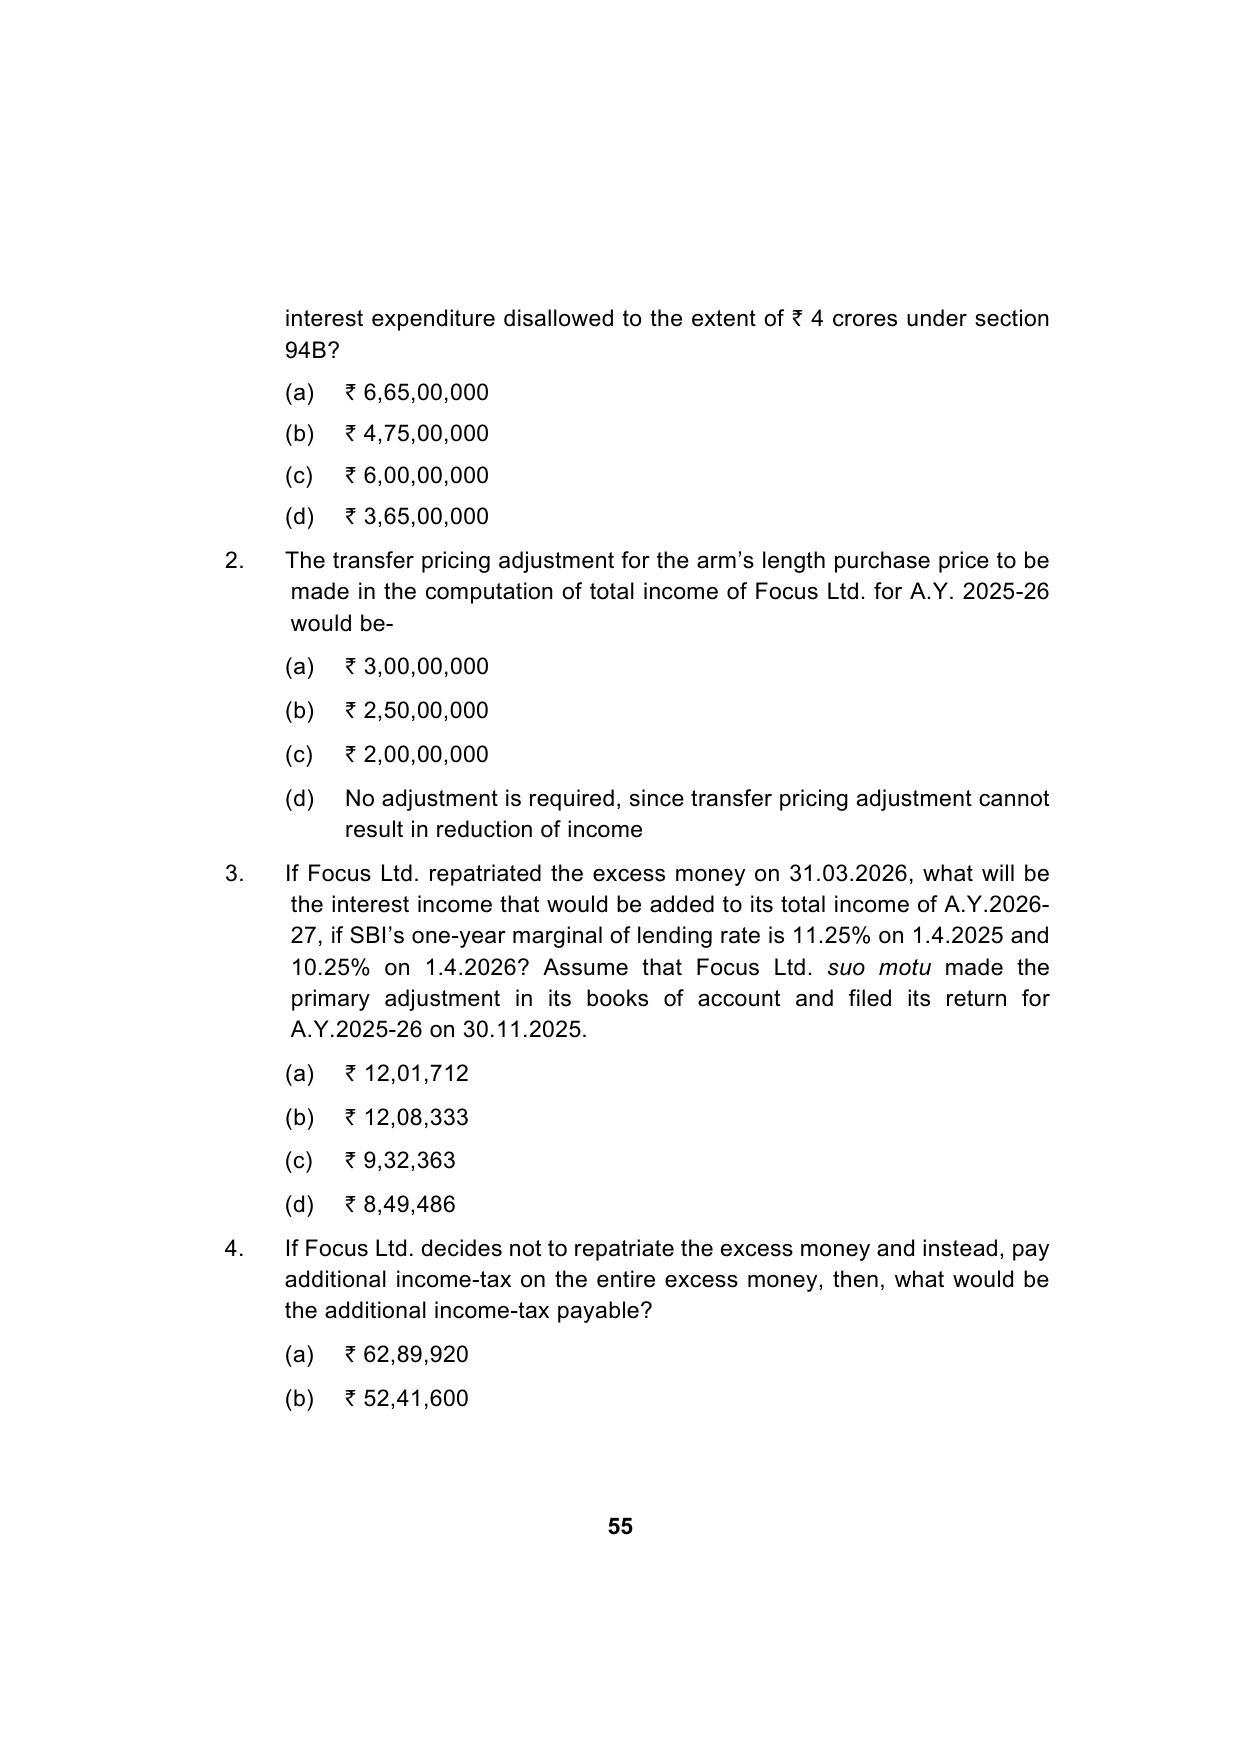
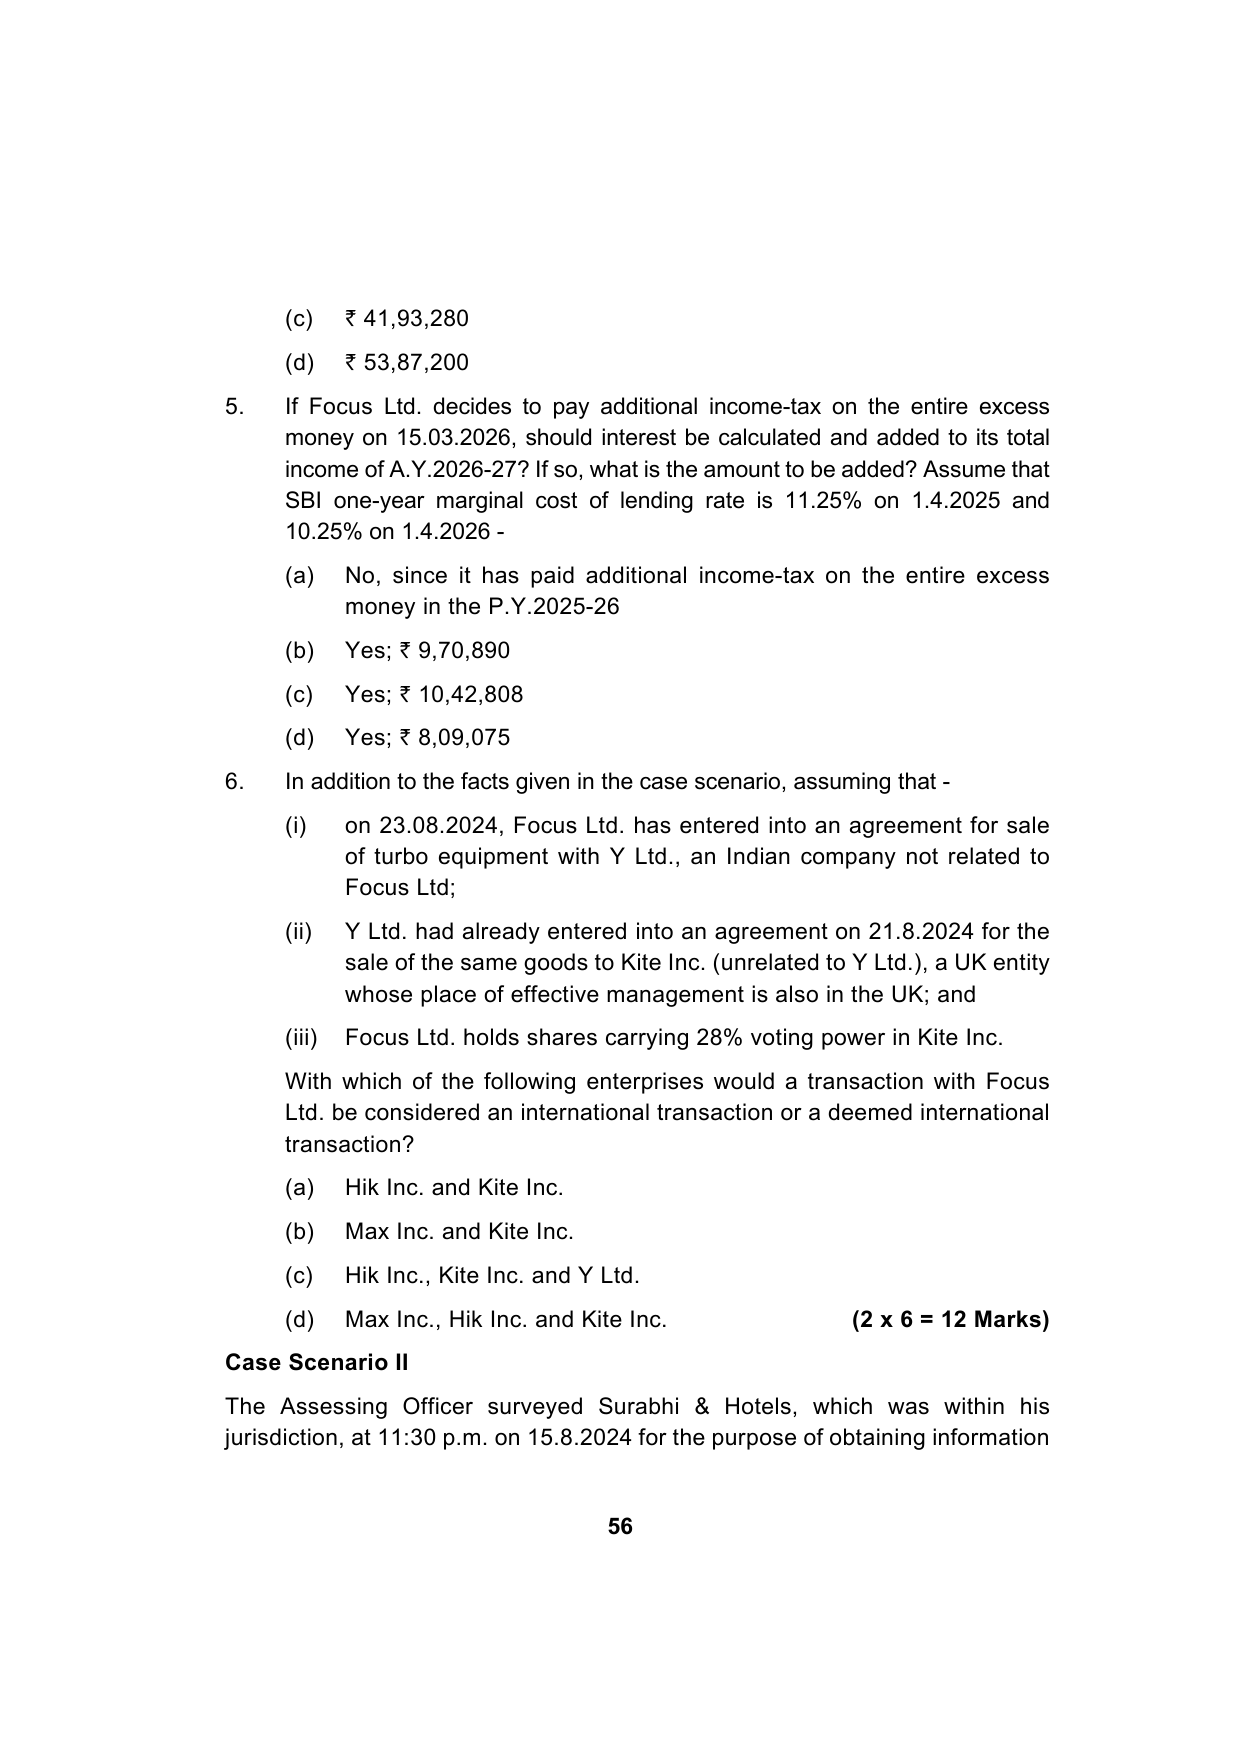
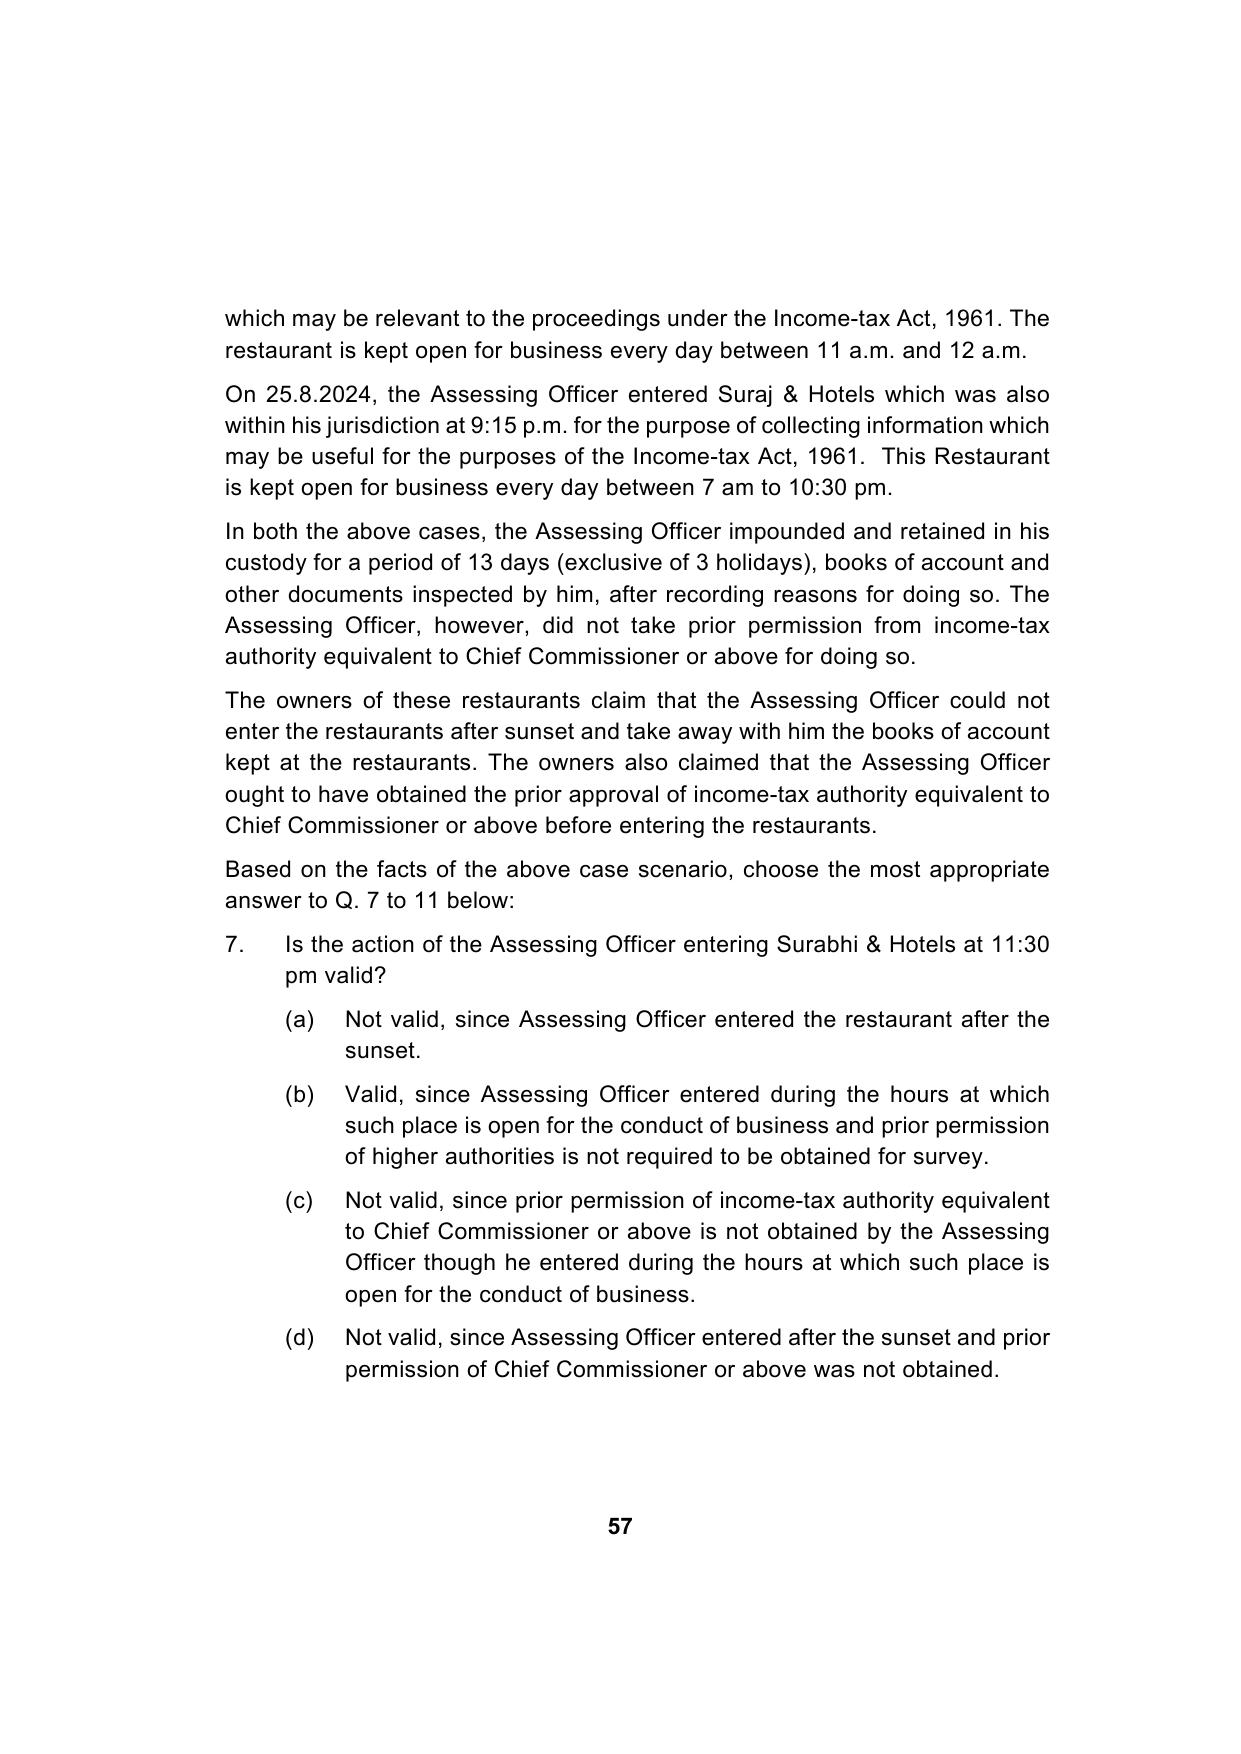
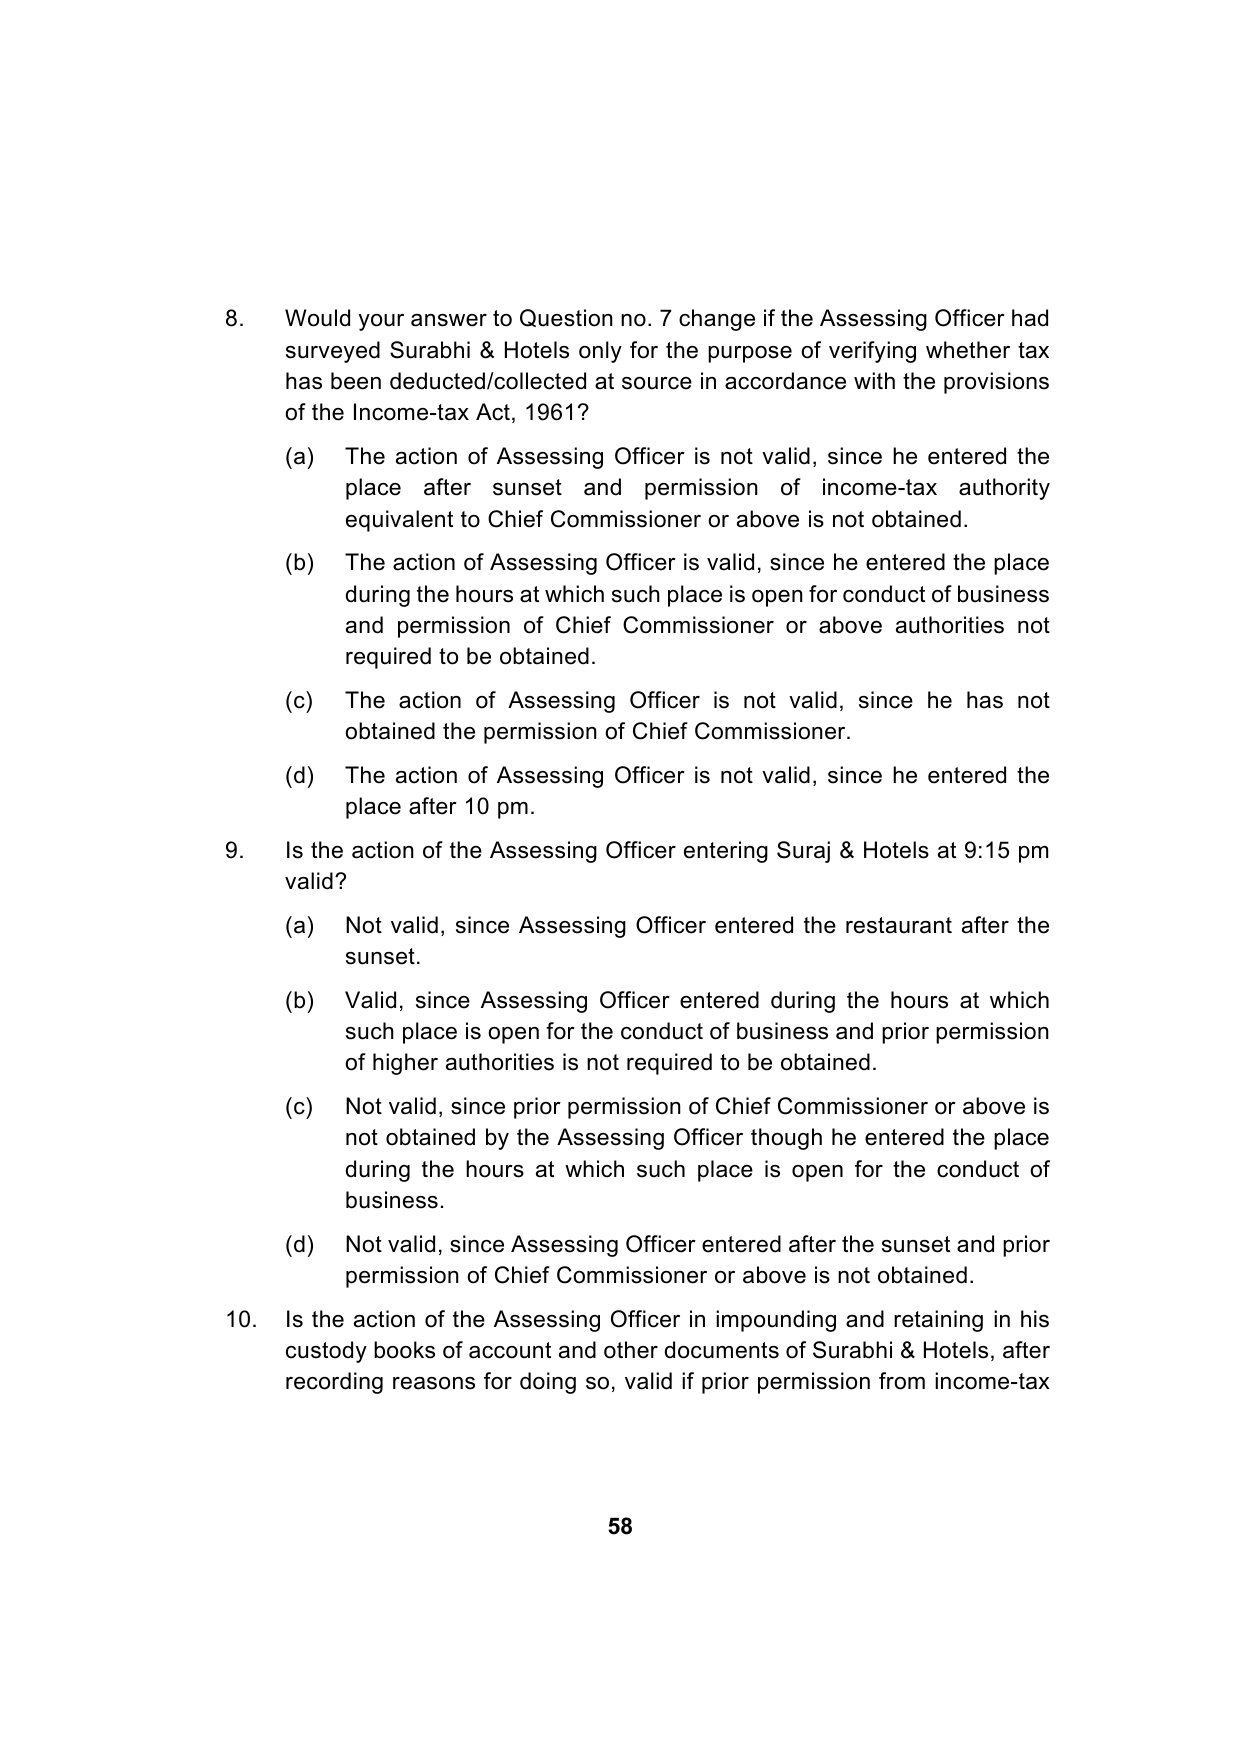
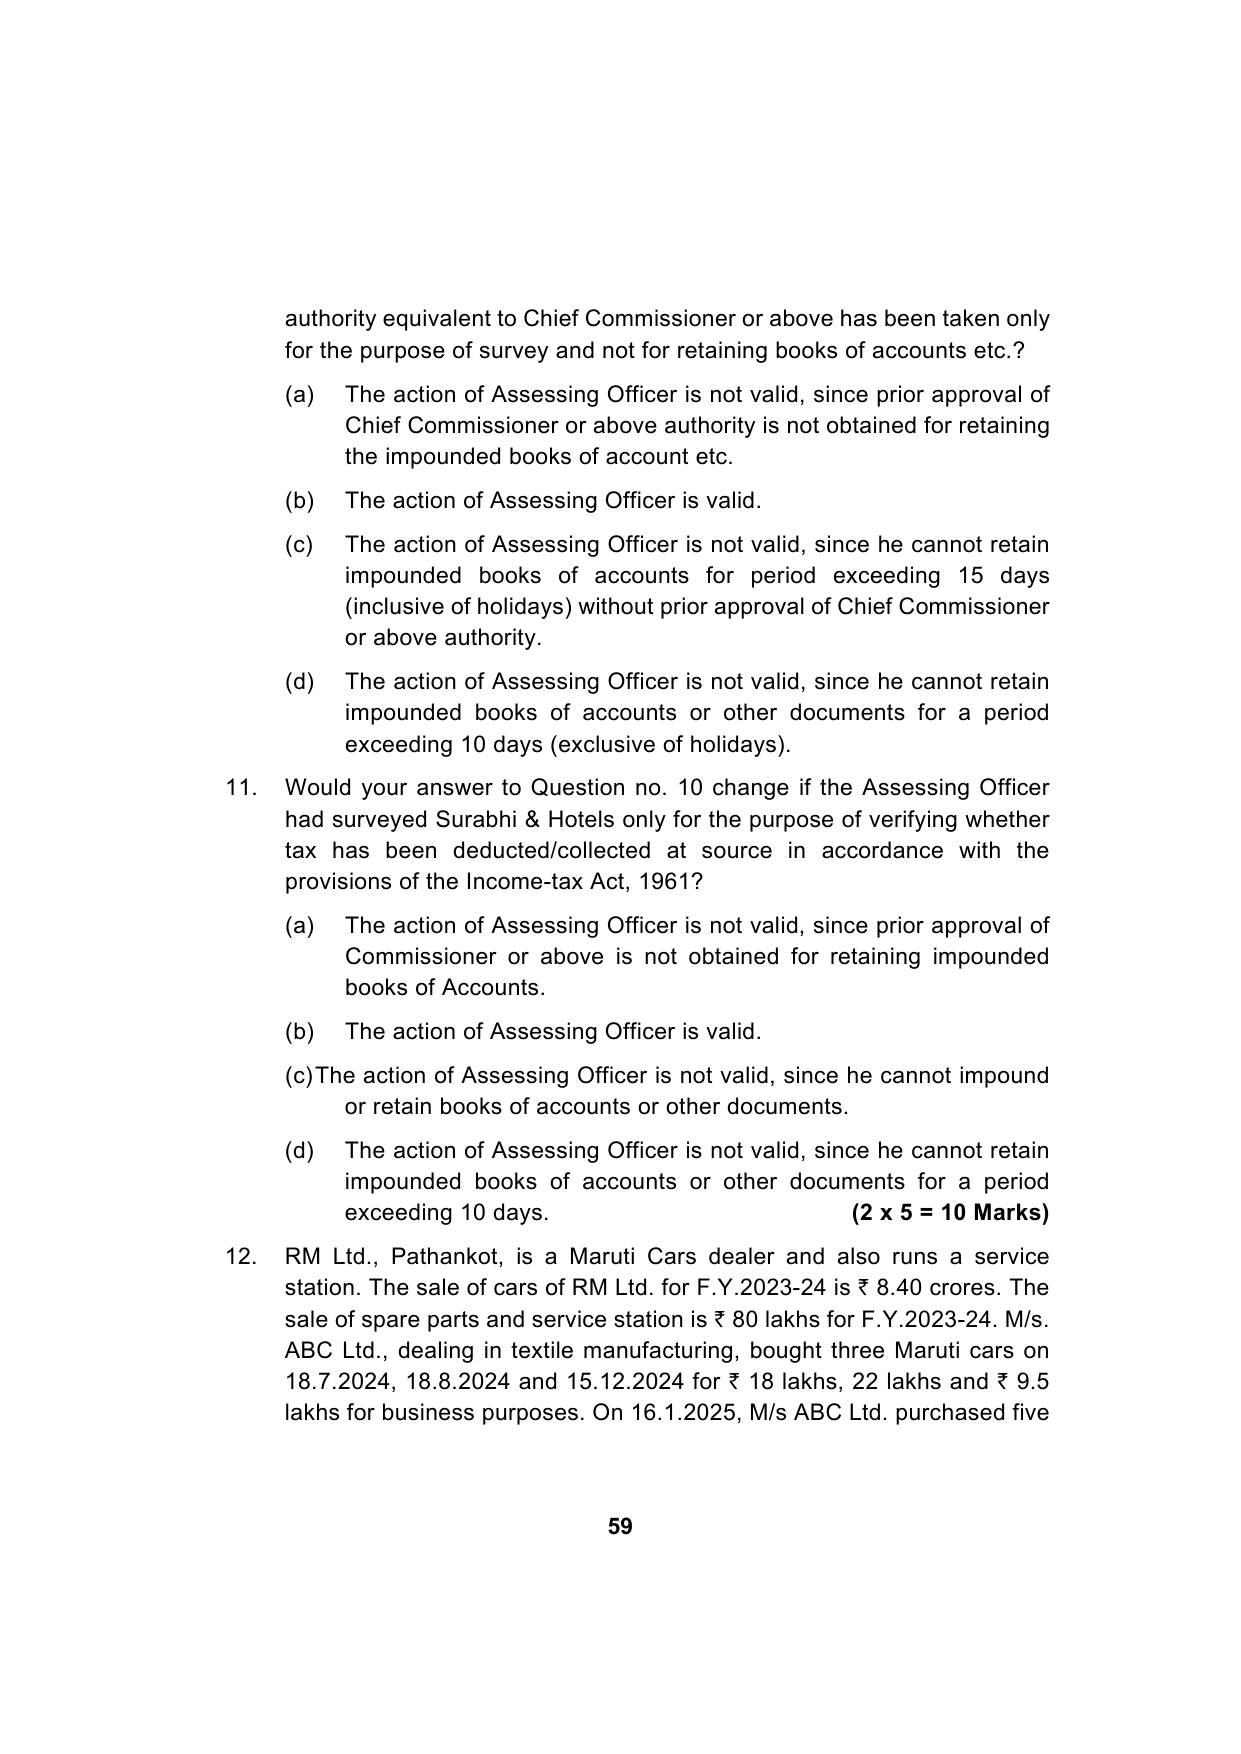
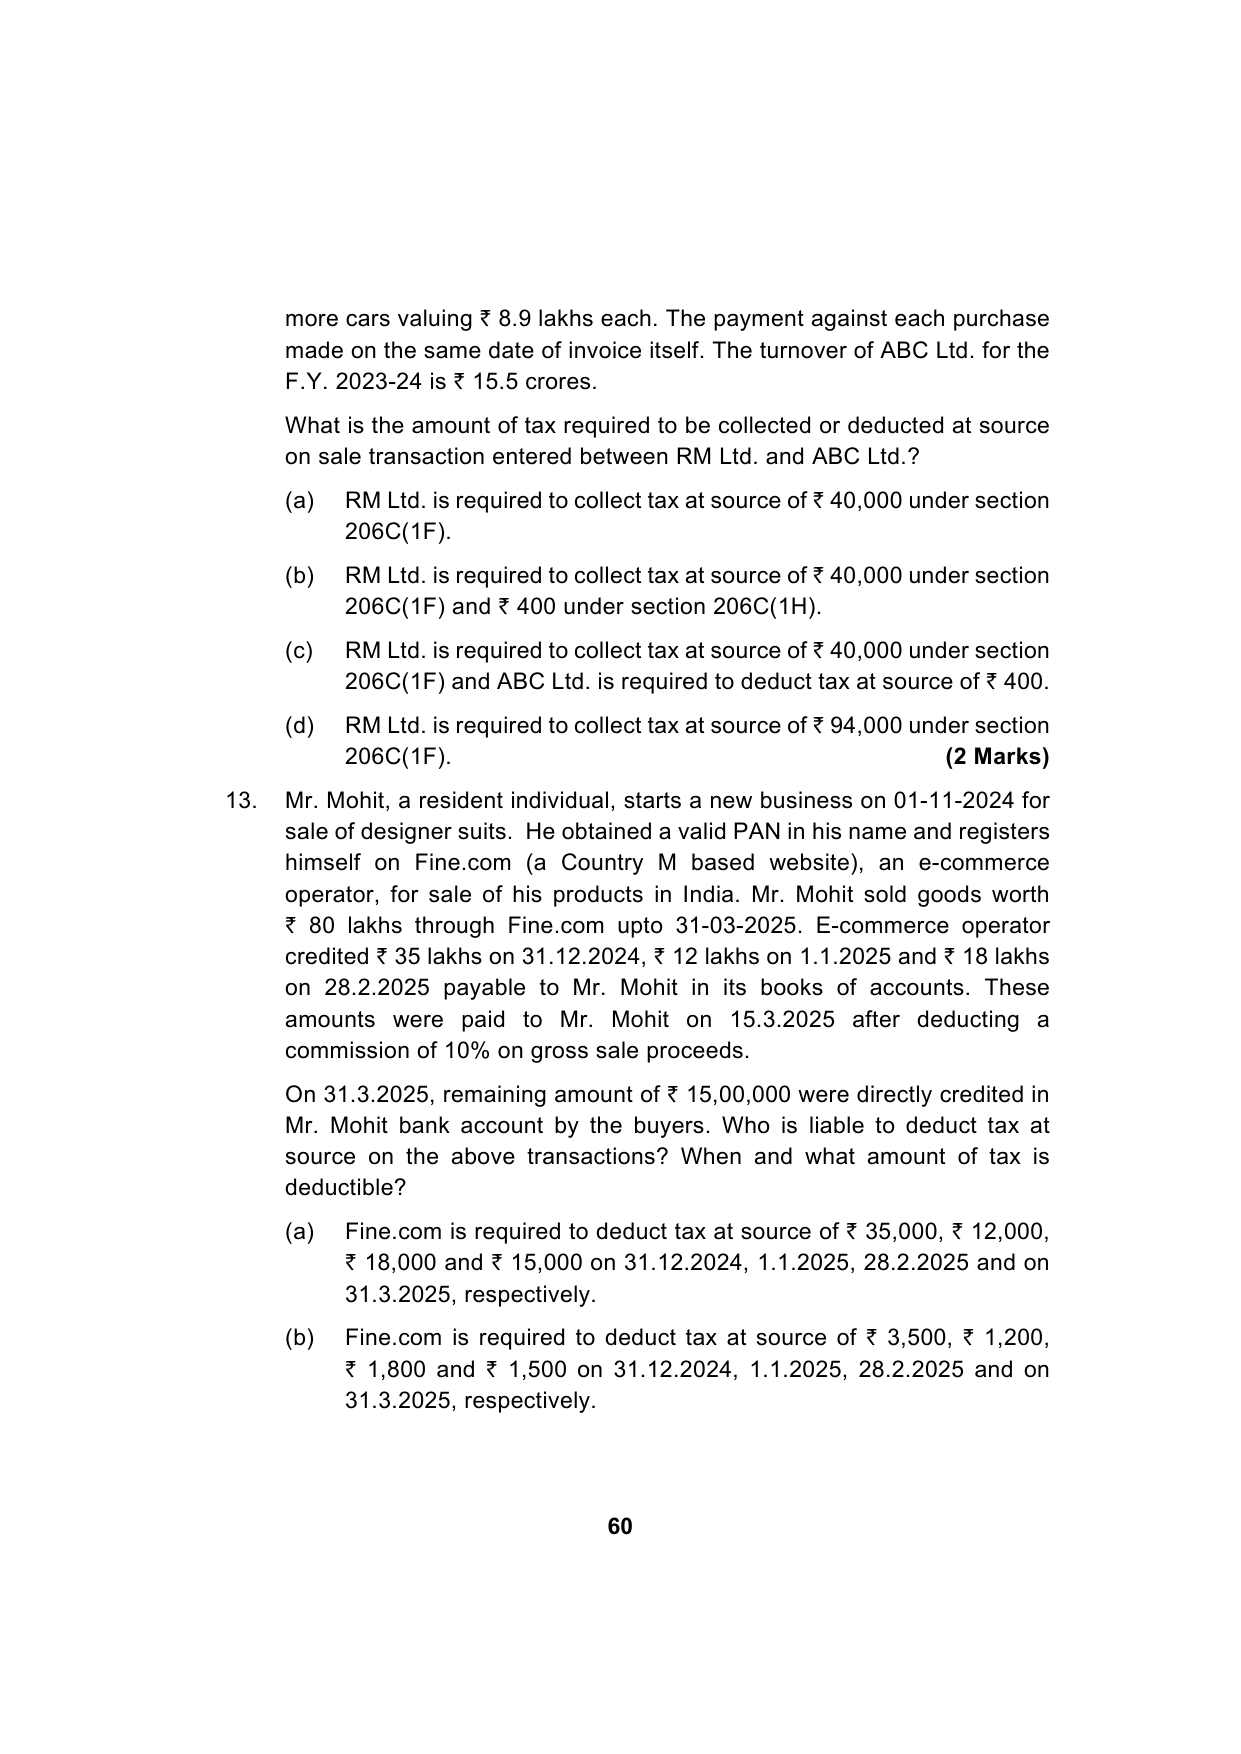
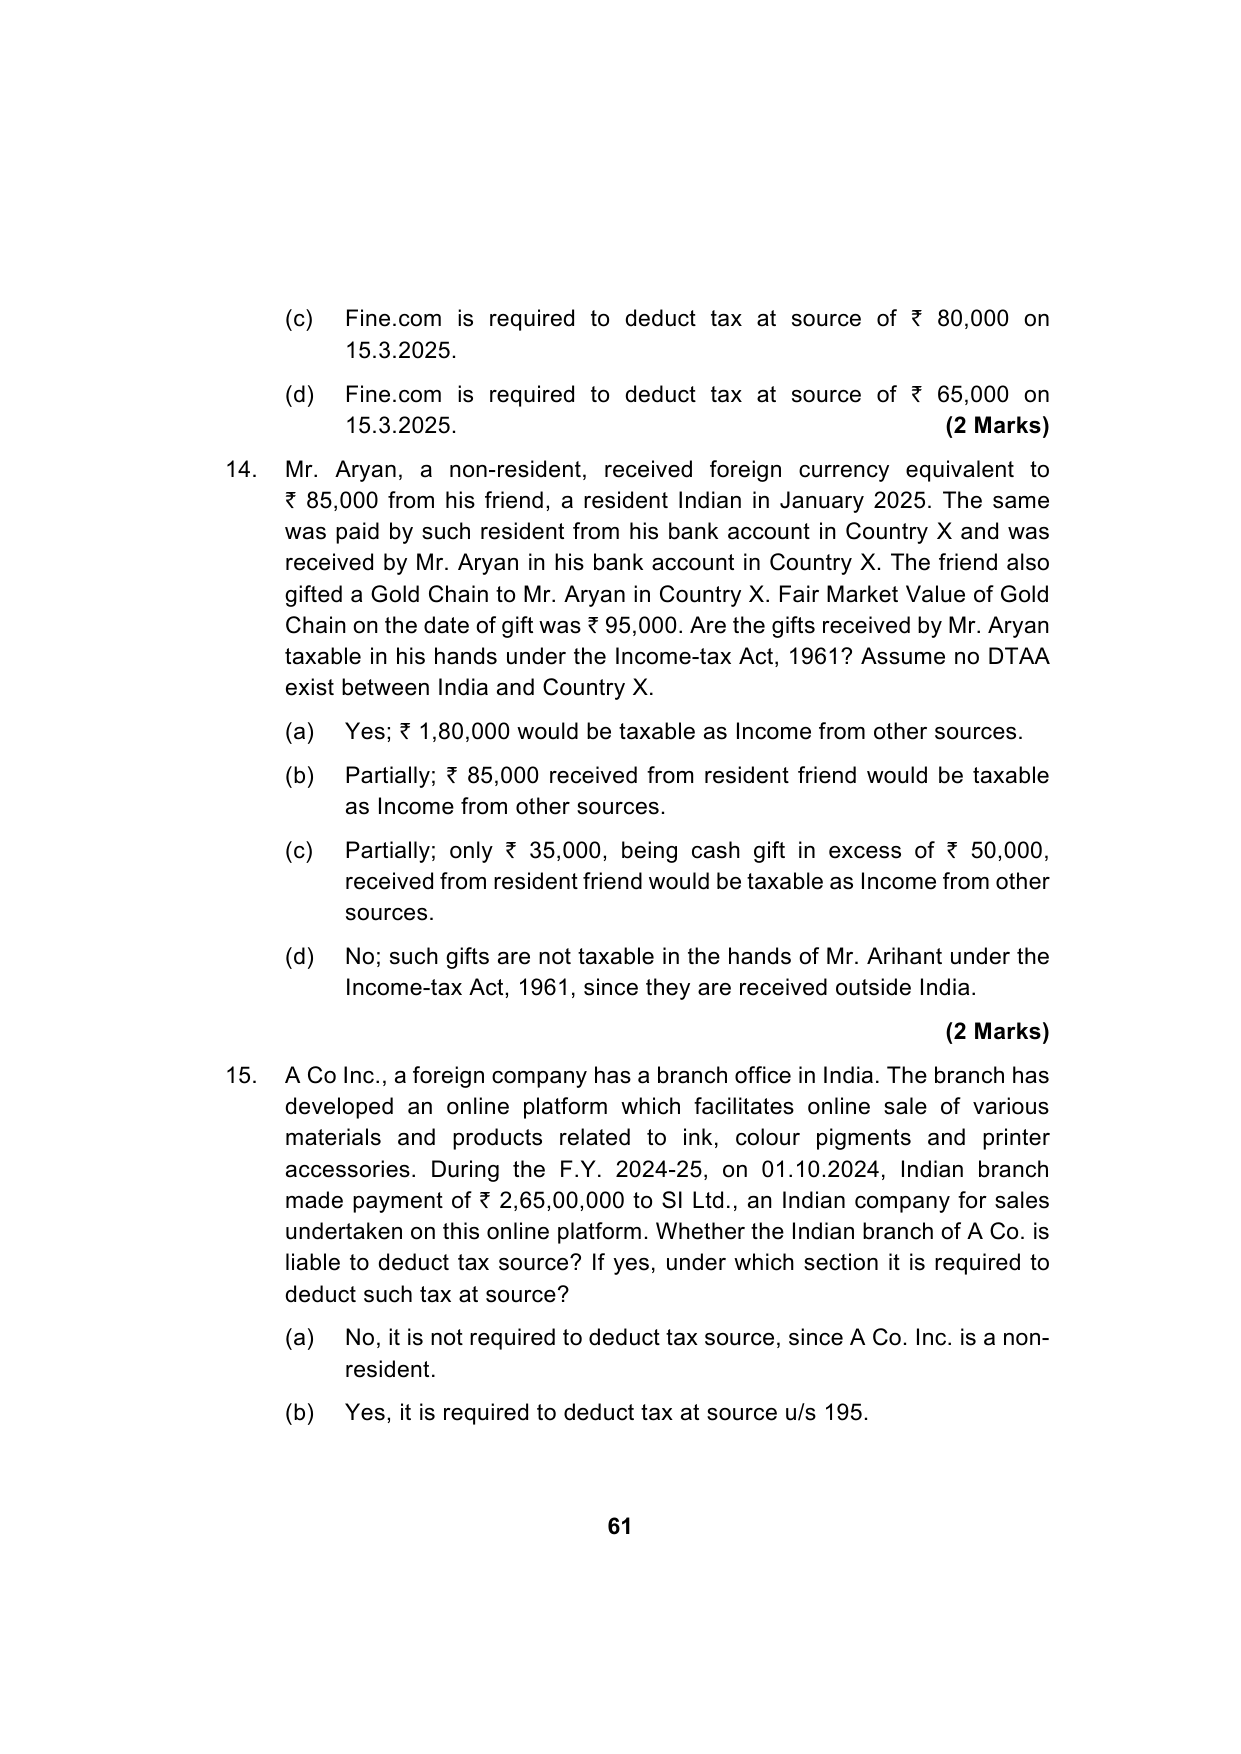
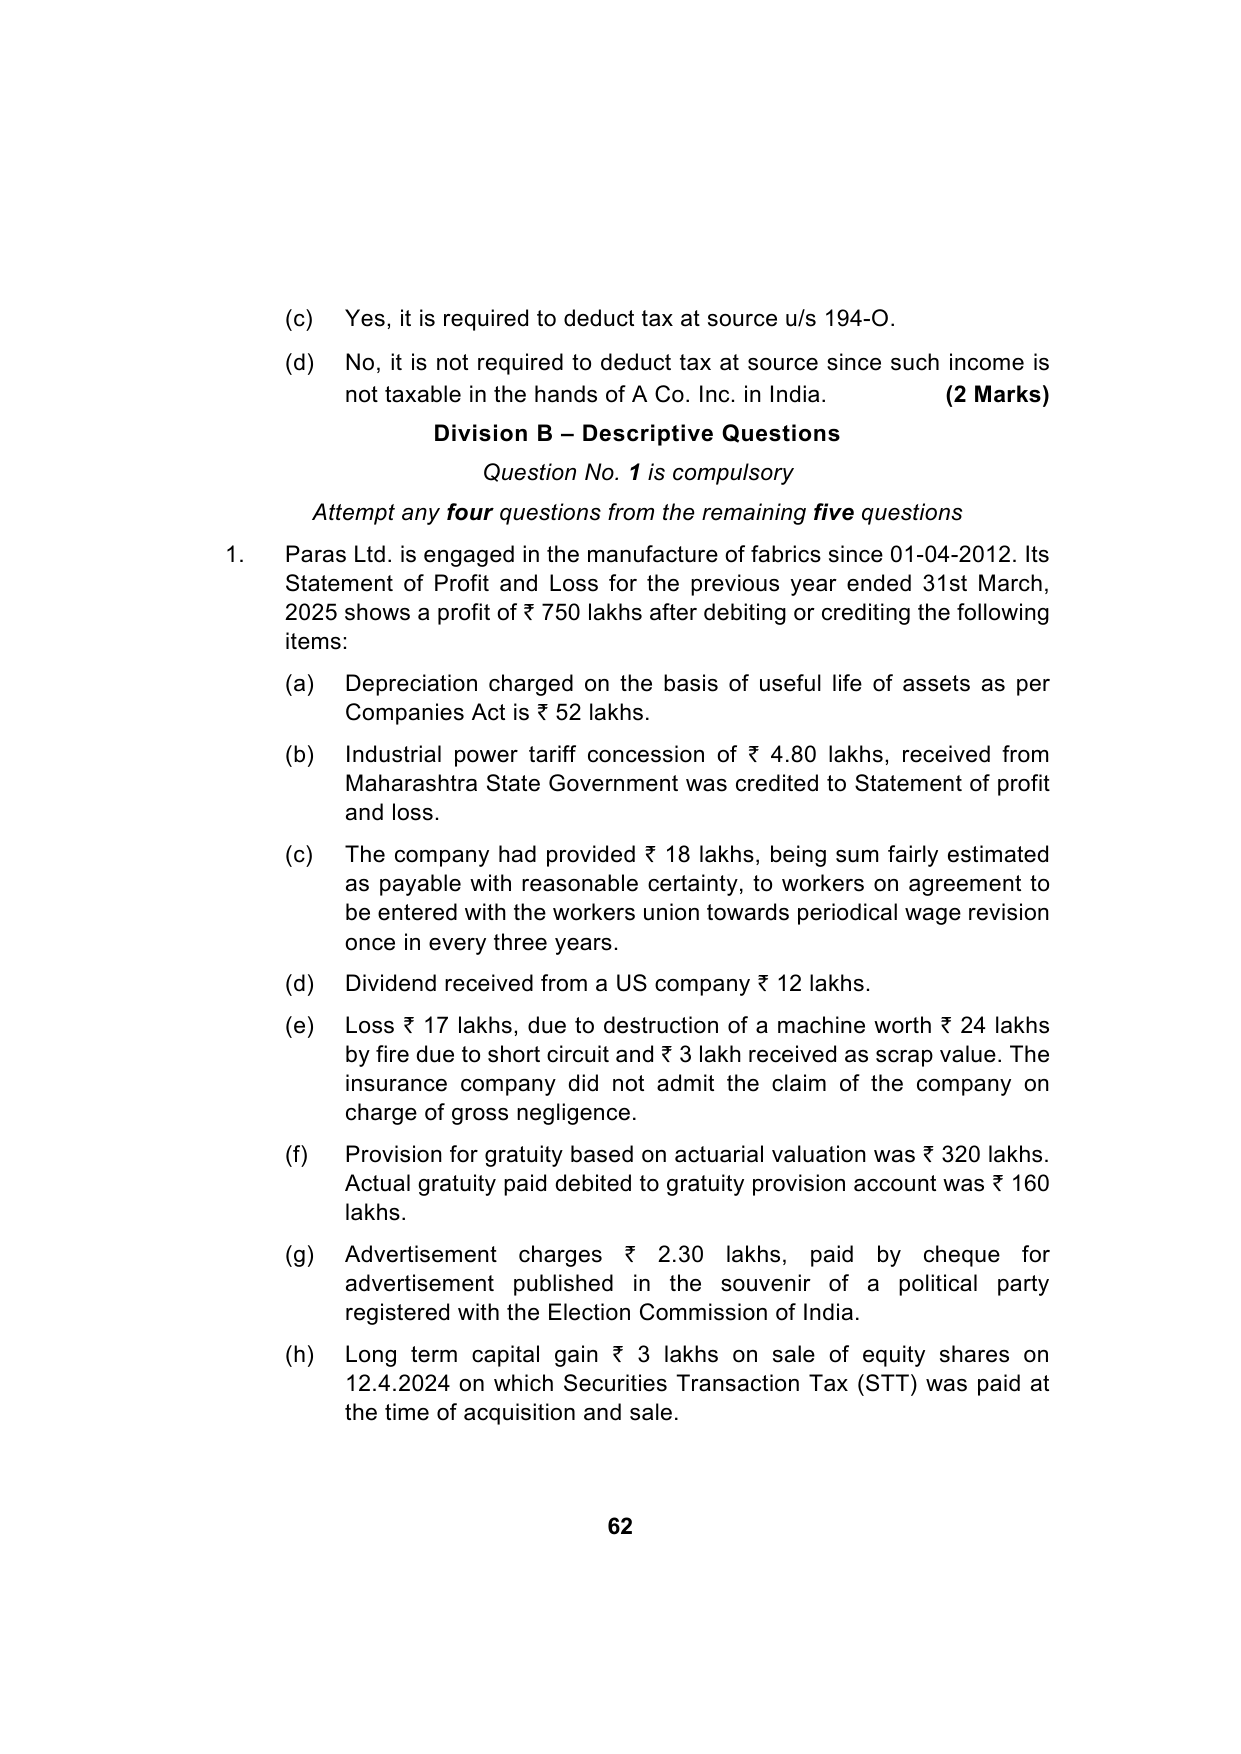
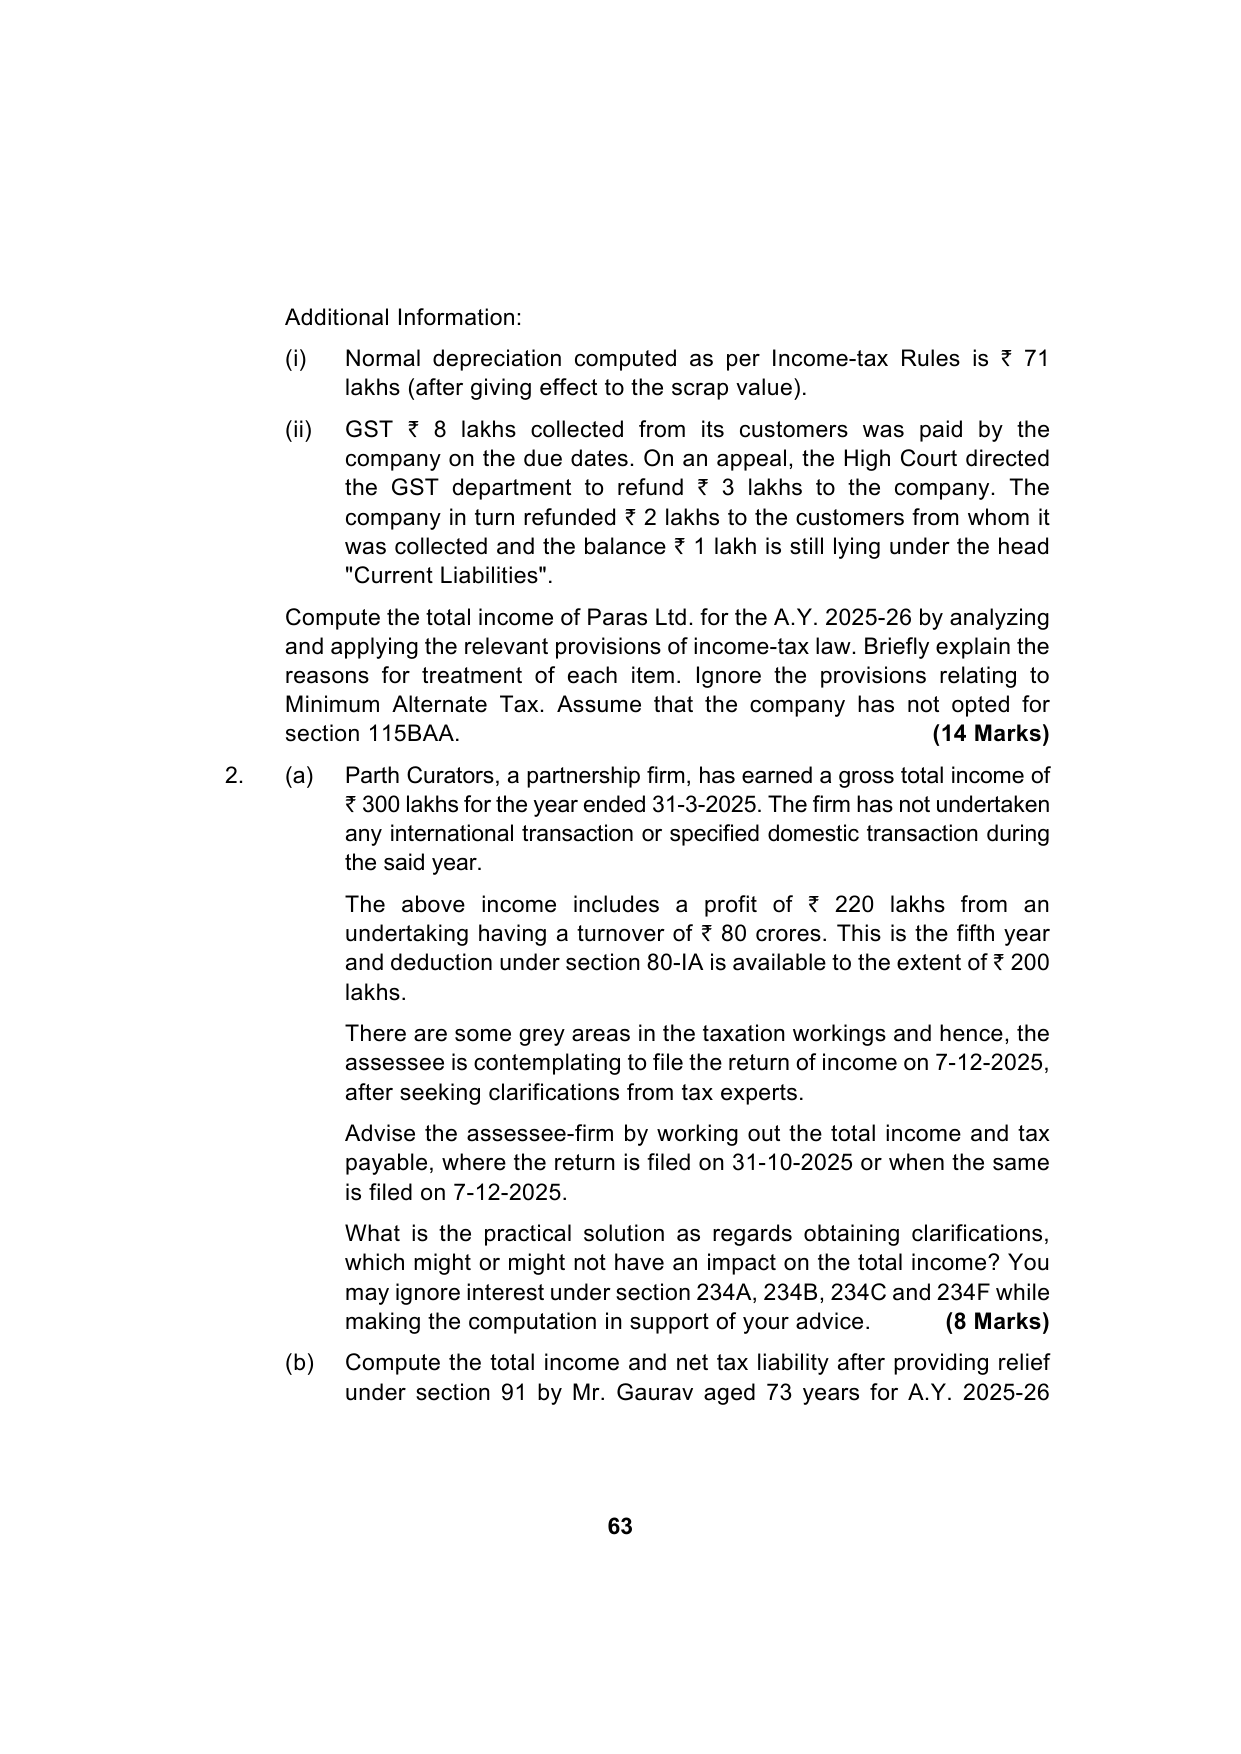
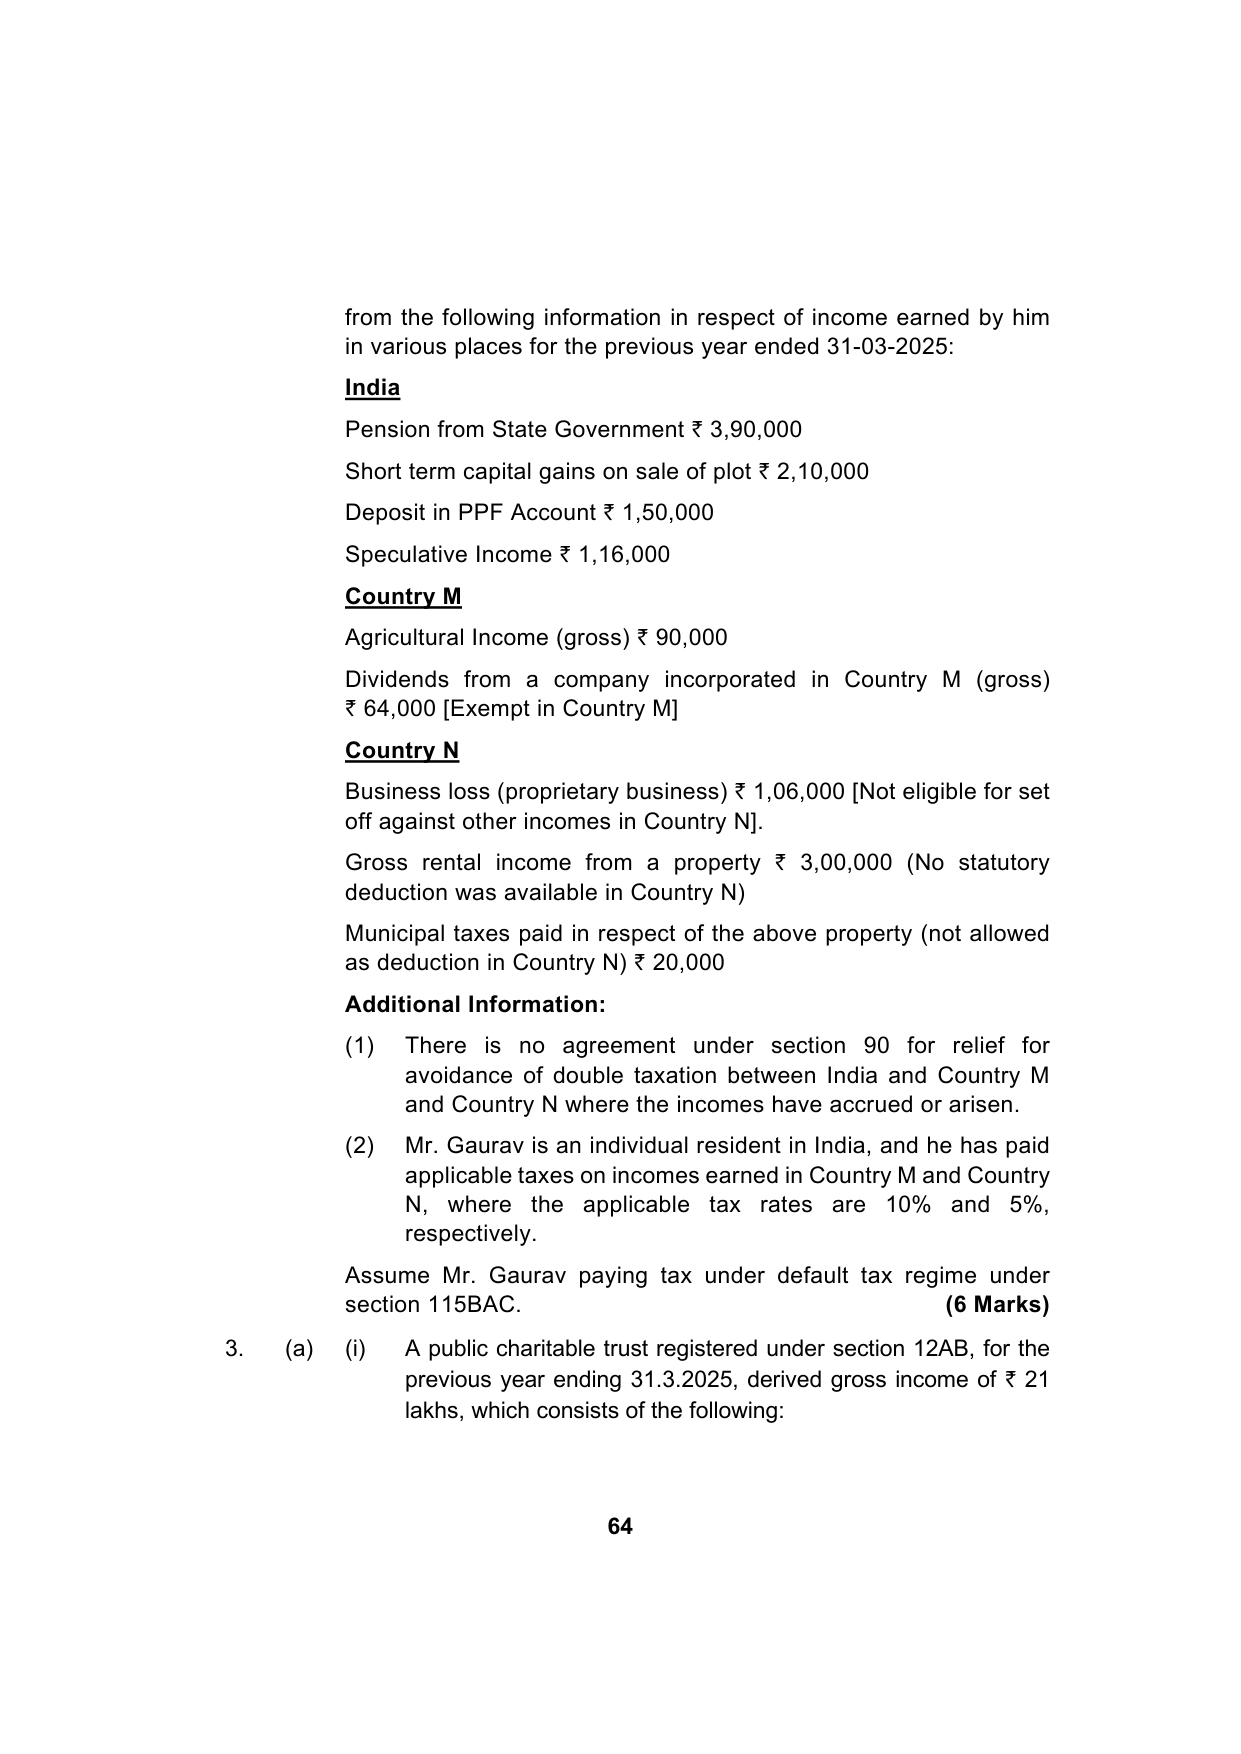
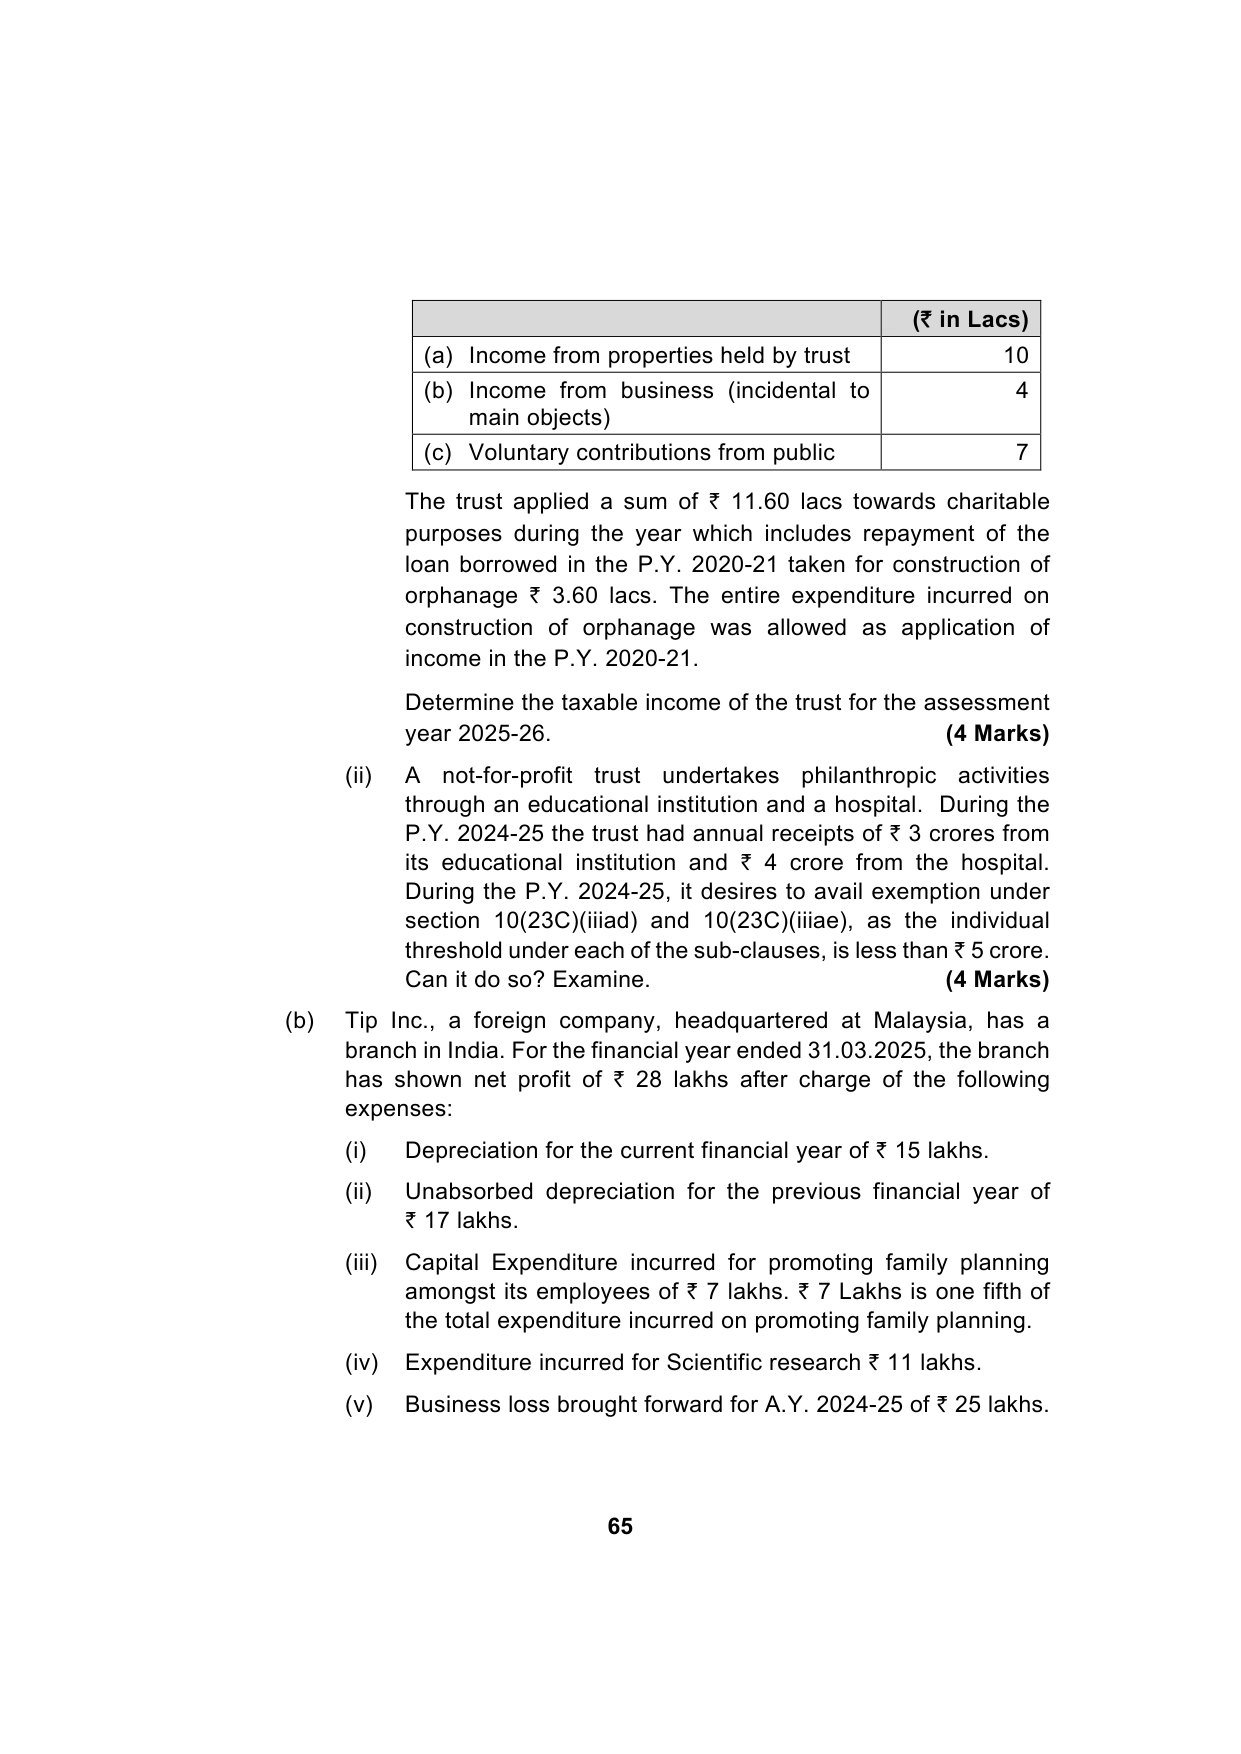
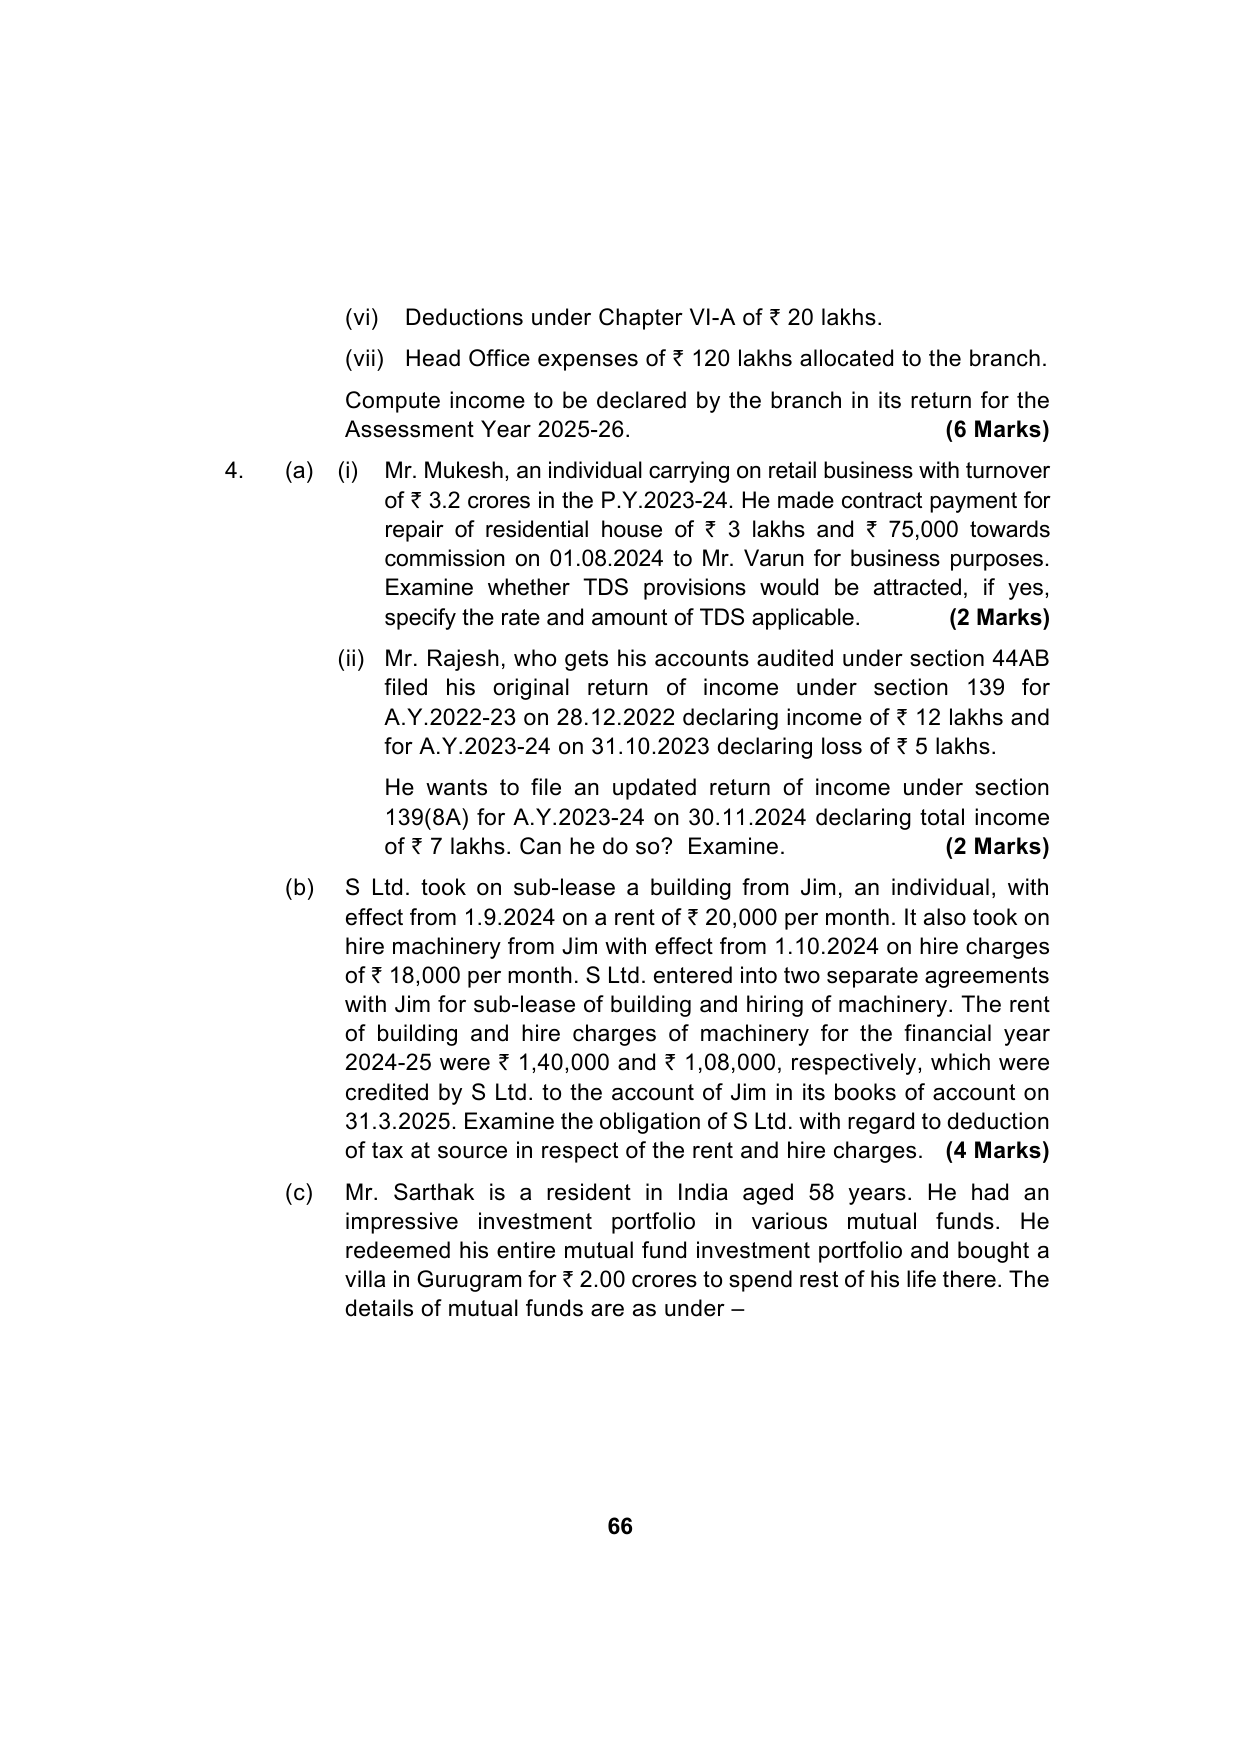
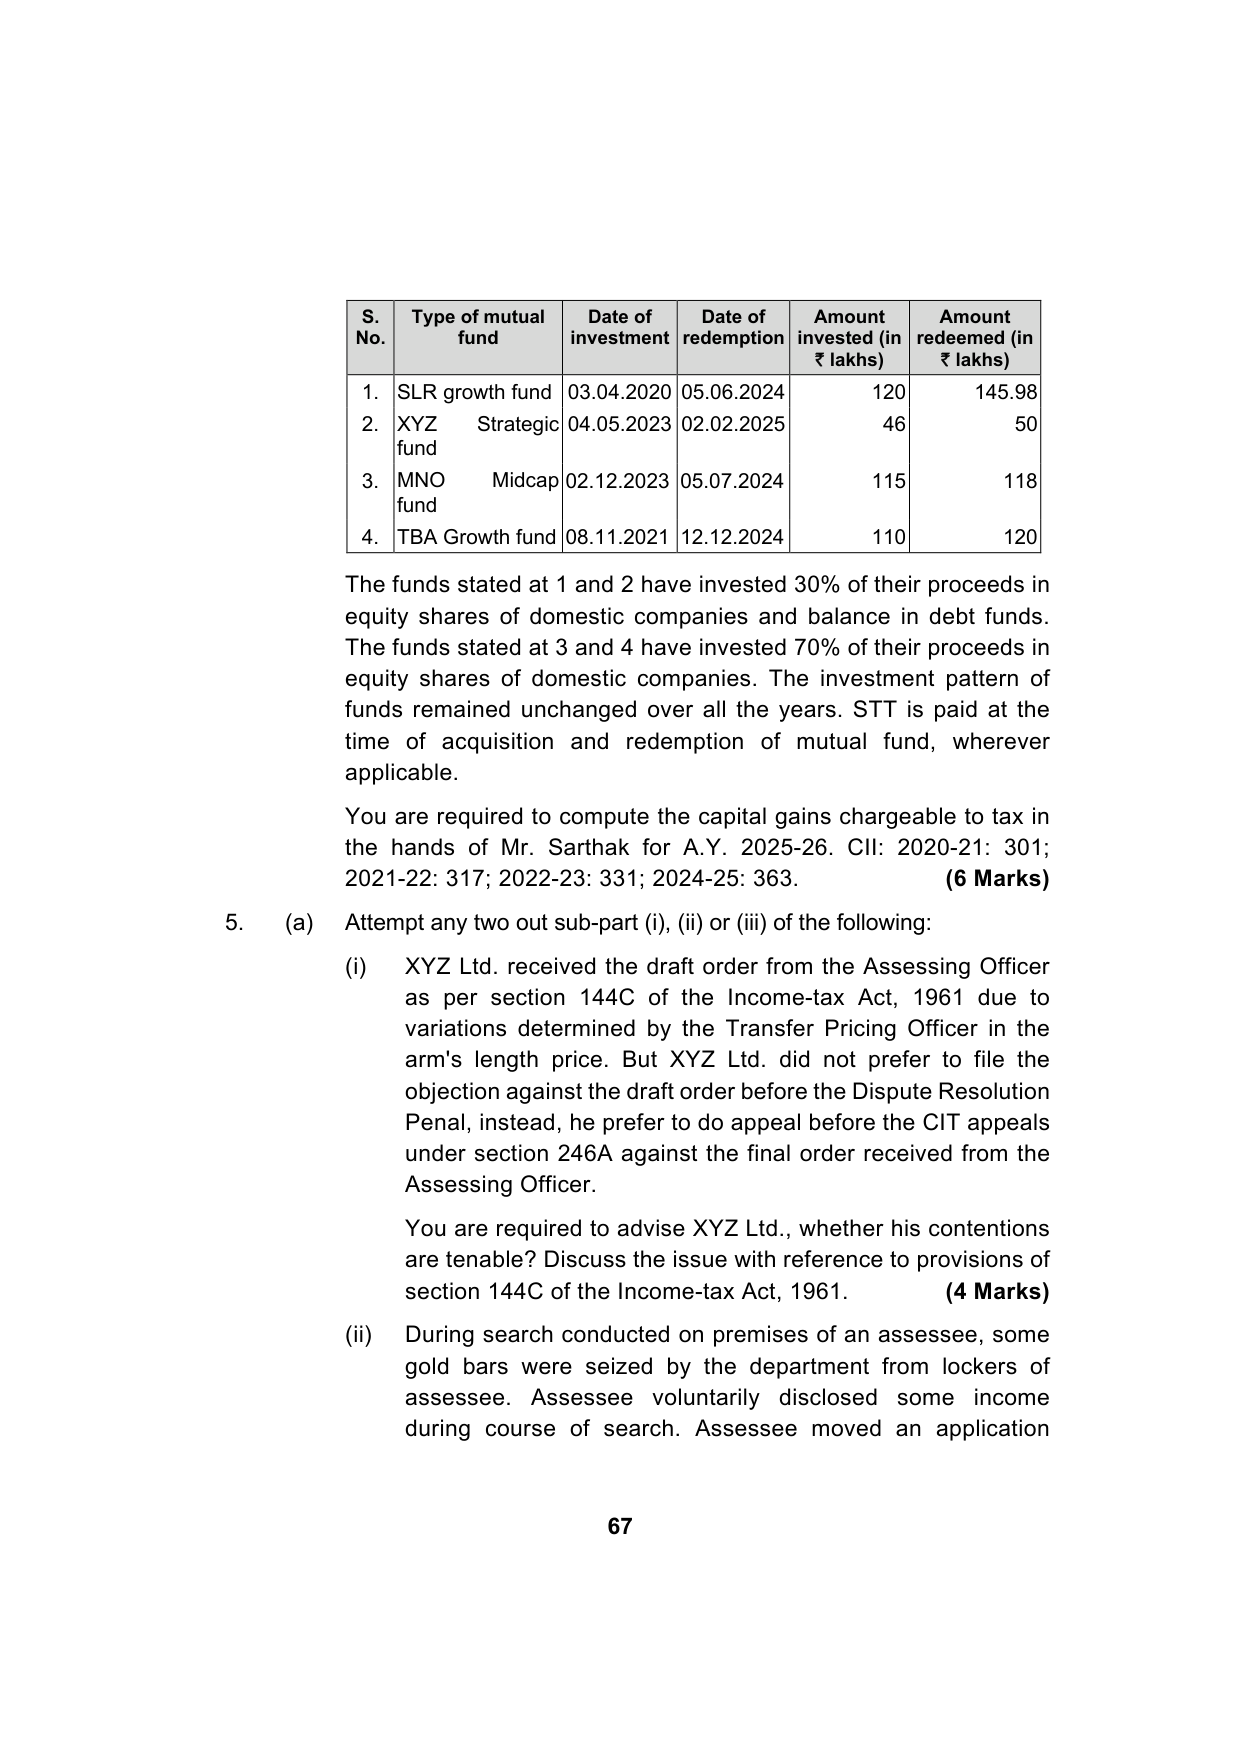
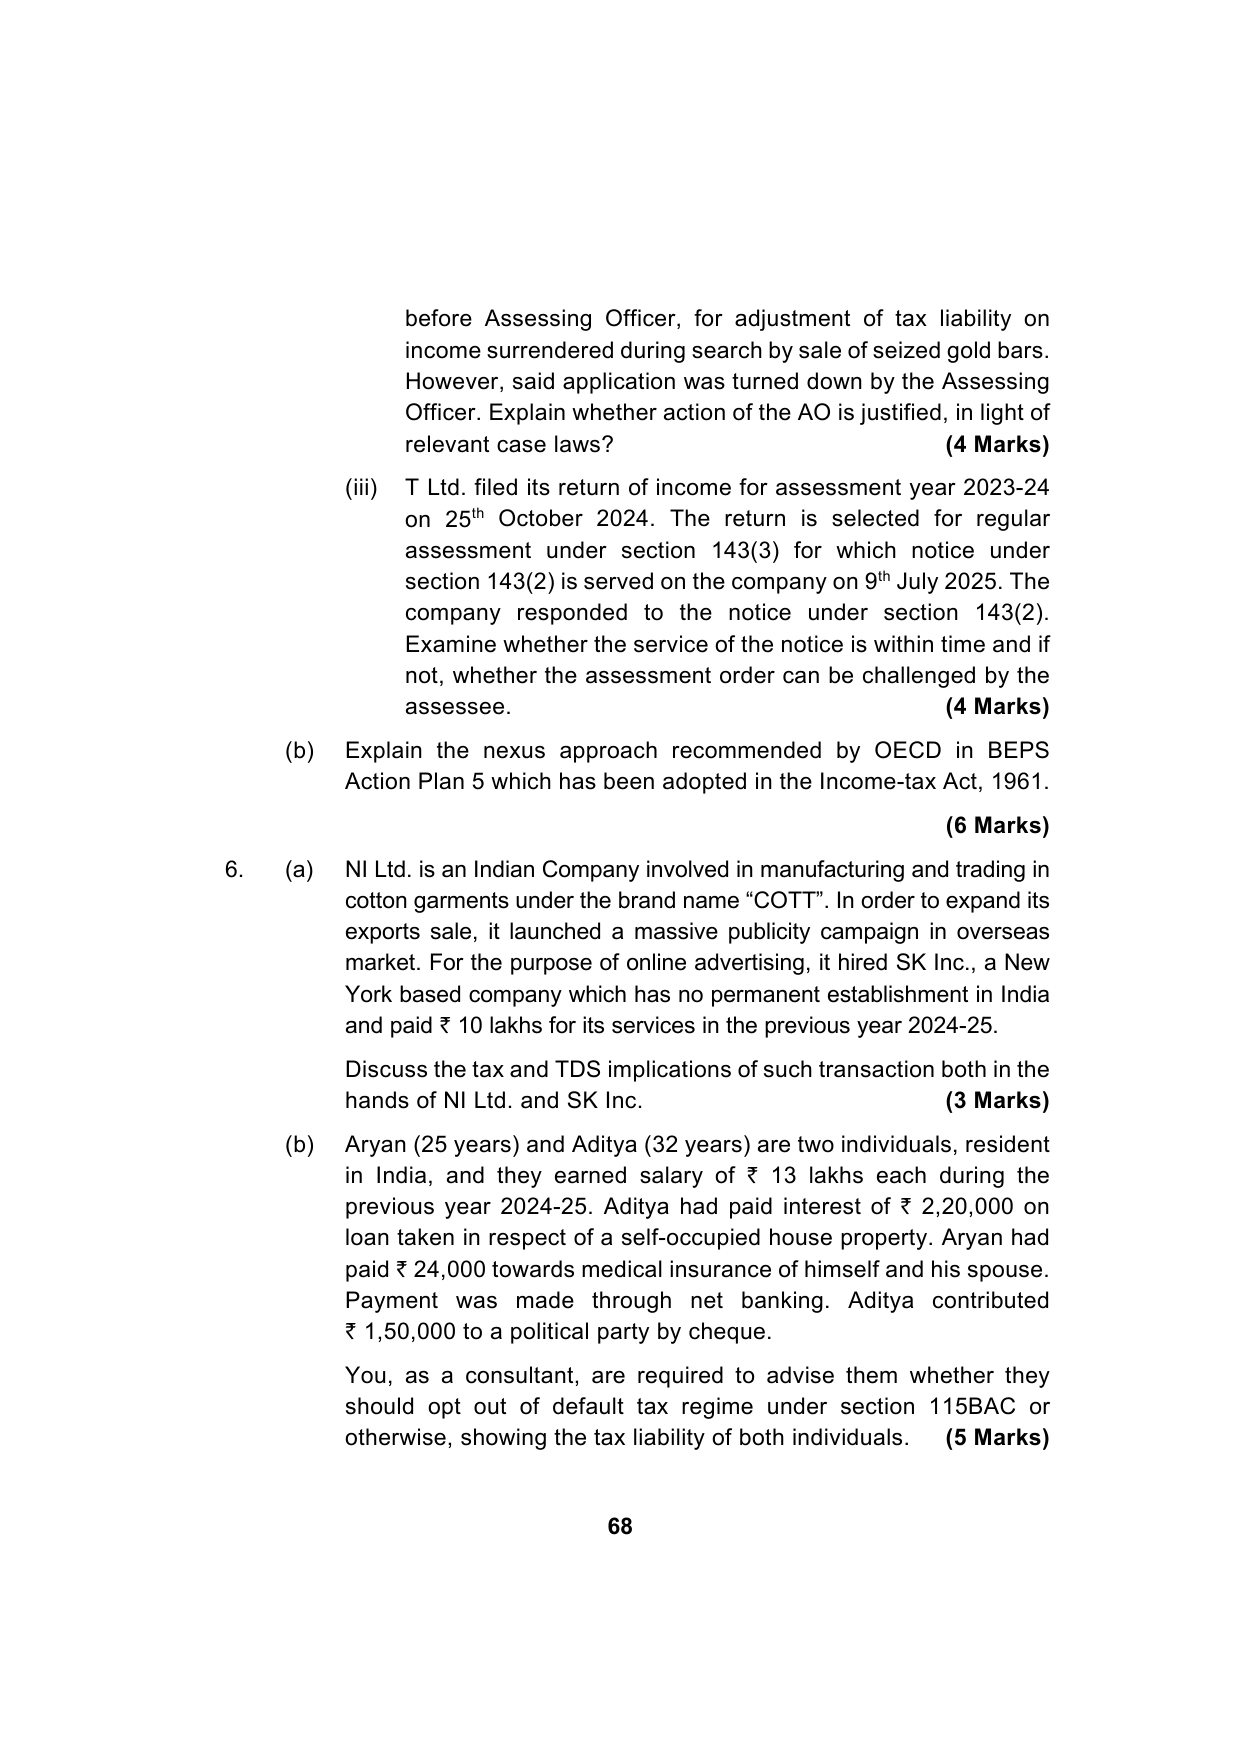
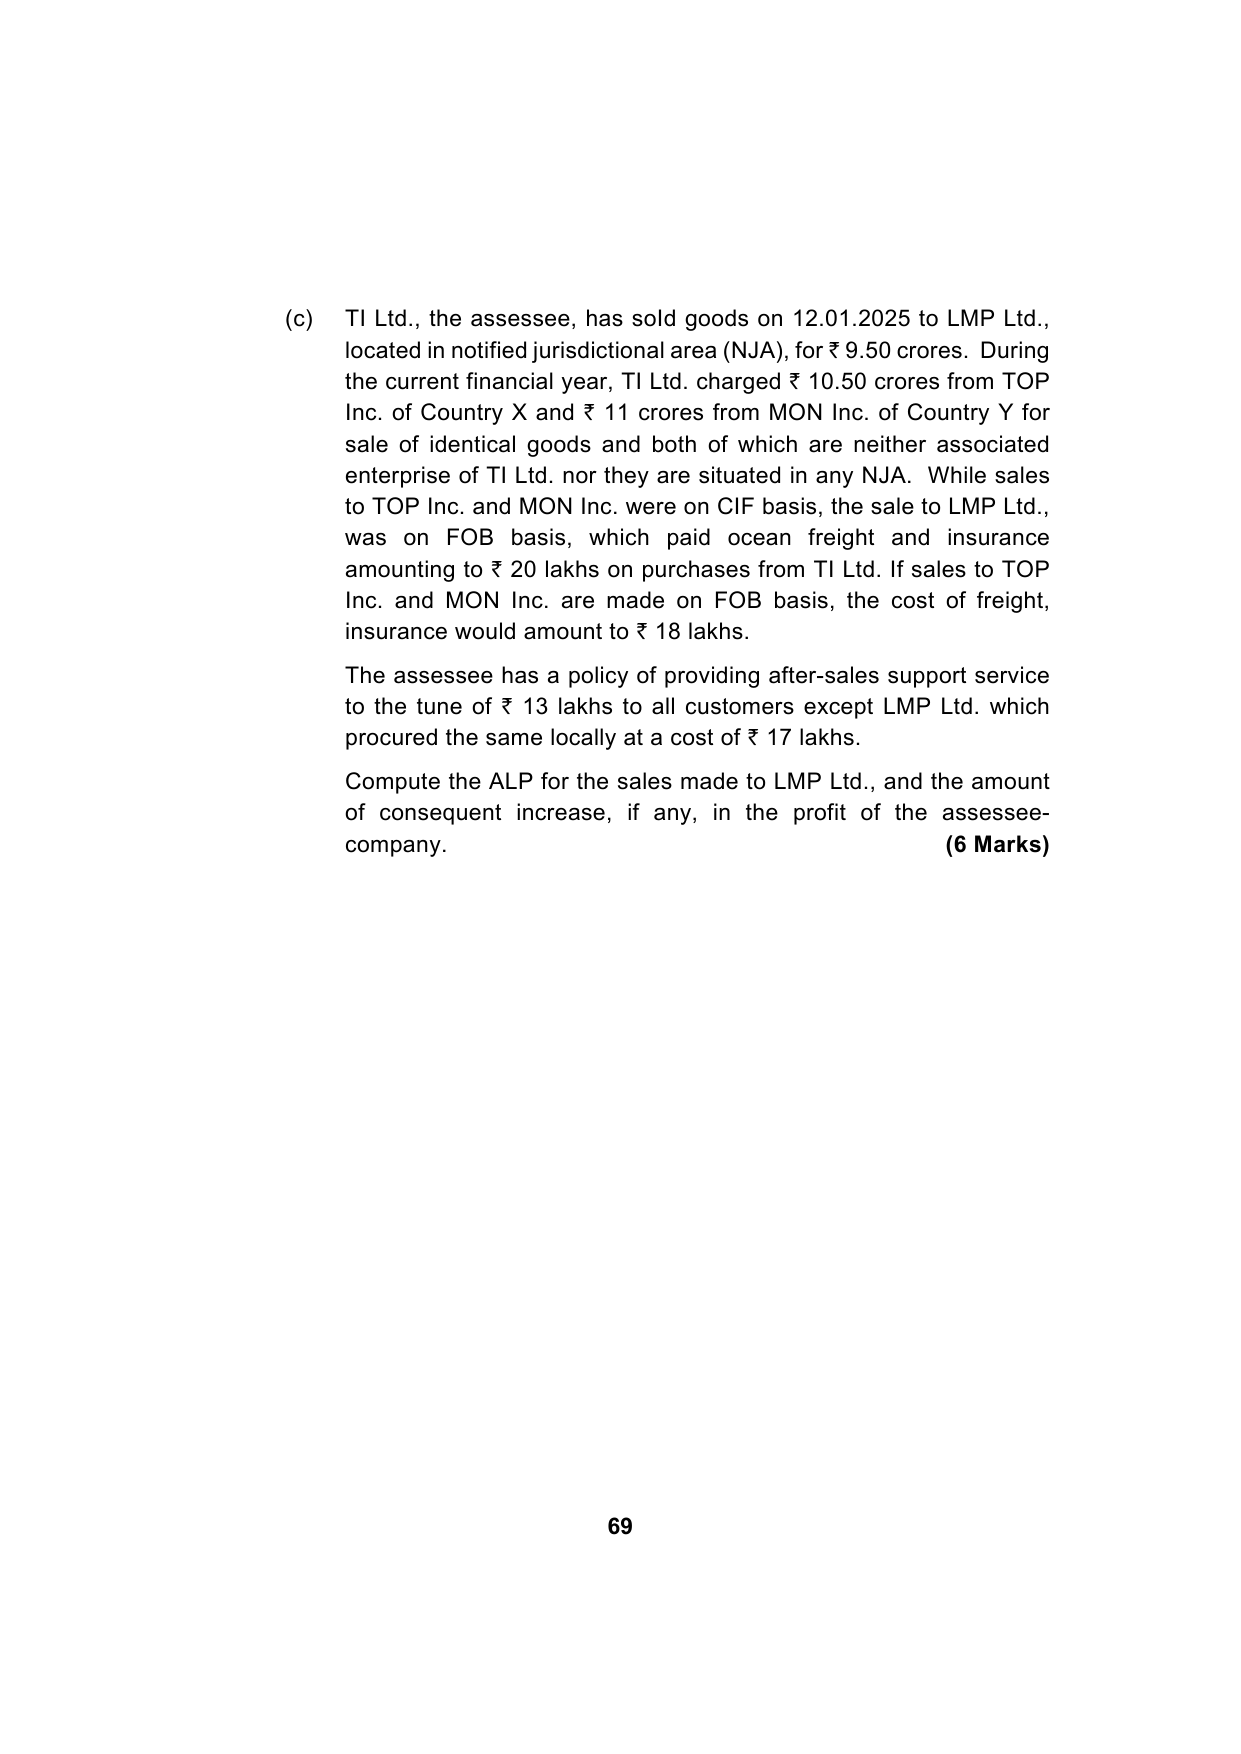
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 5 (100 marks)
Question
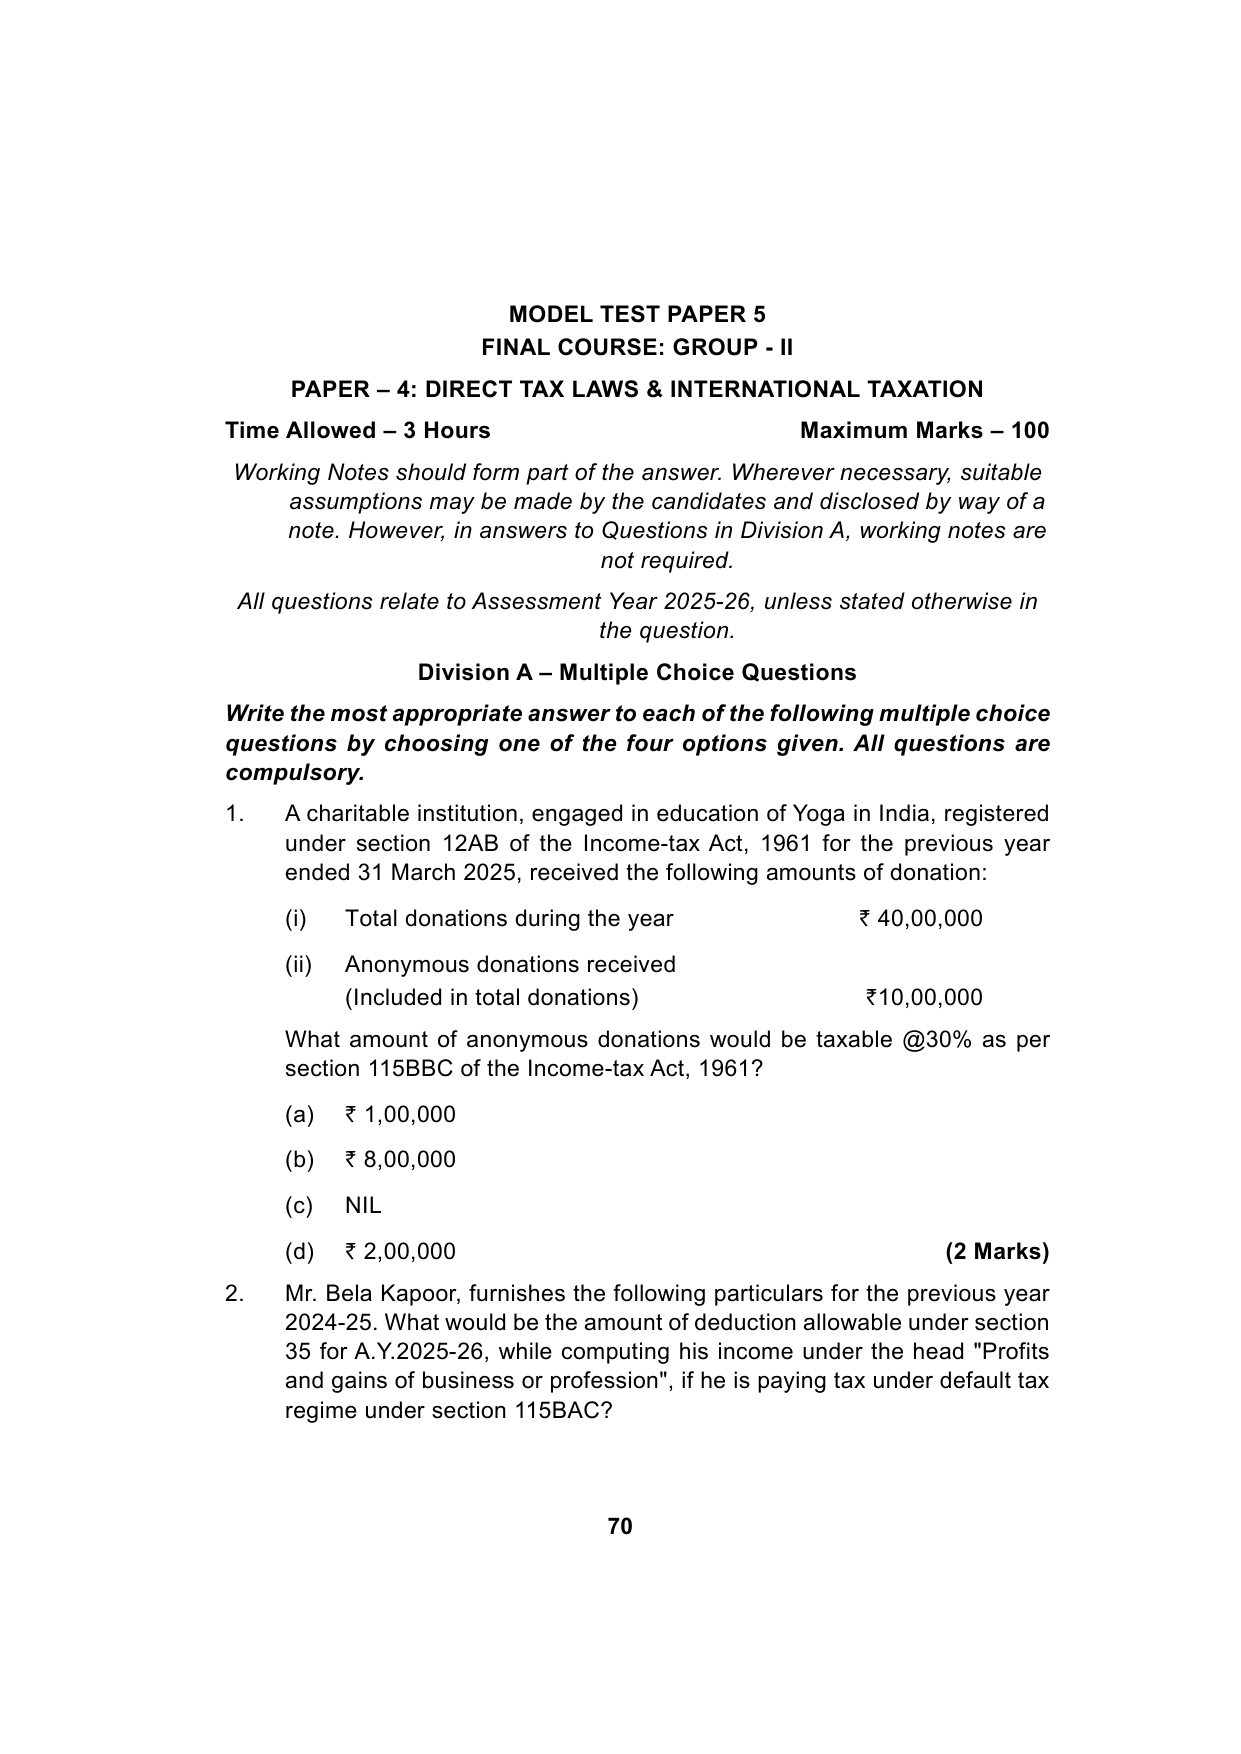
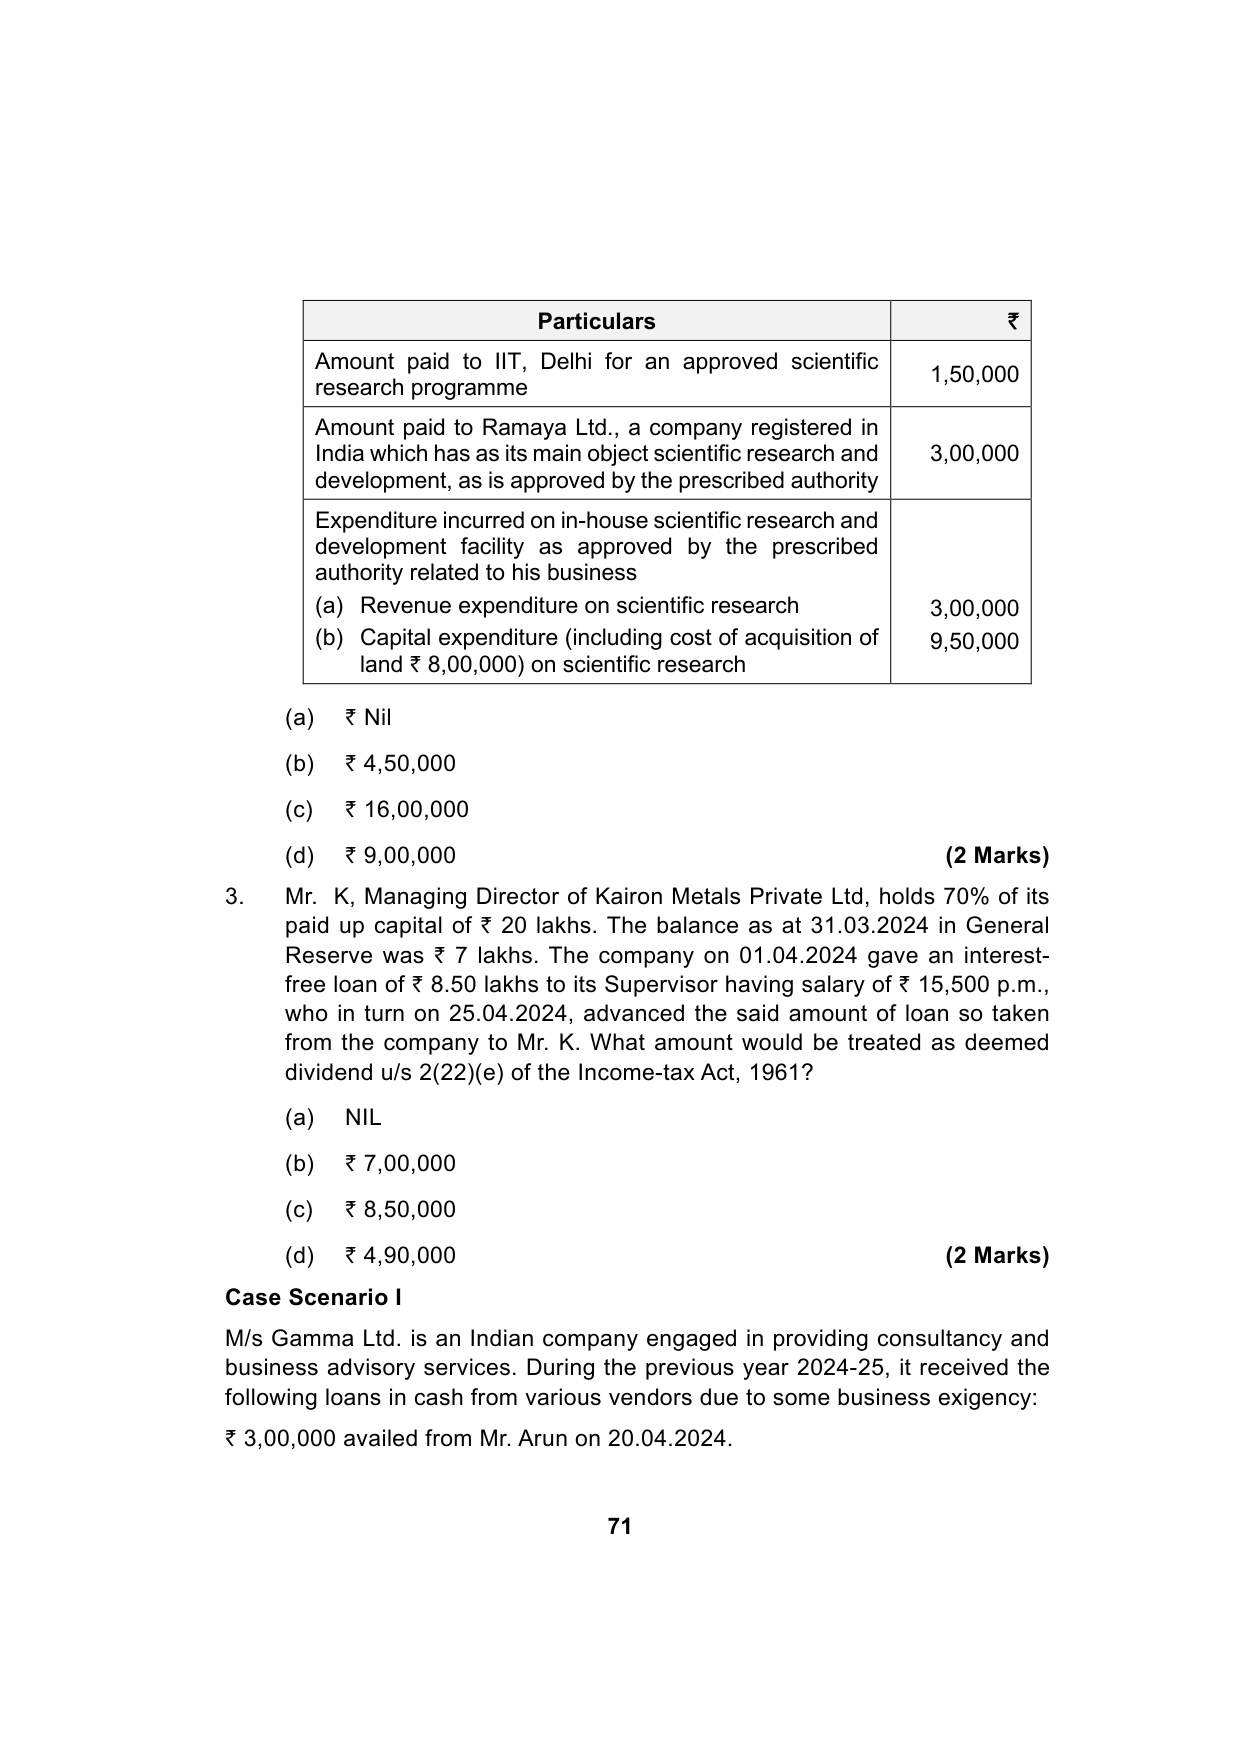
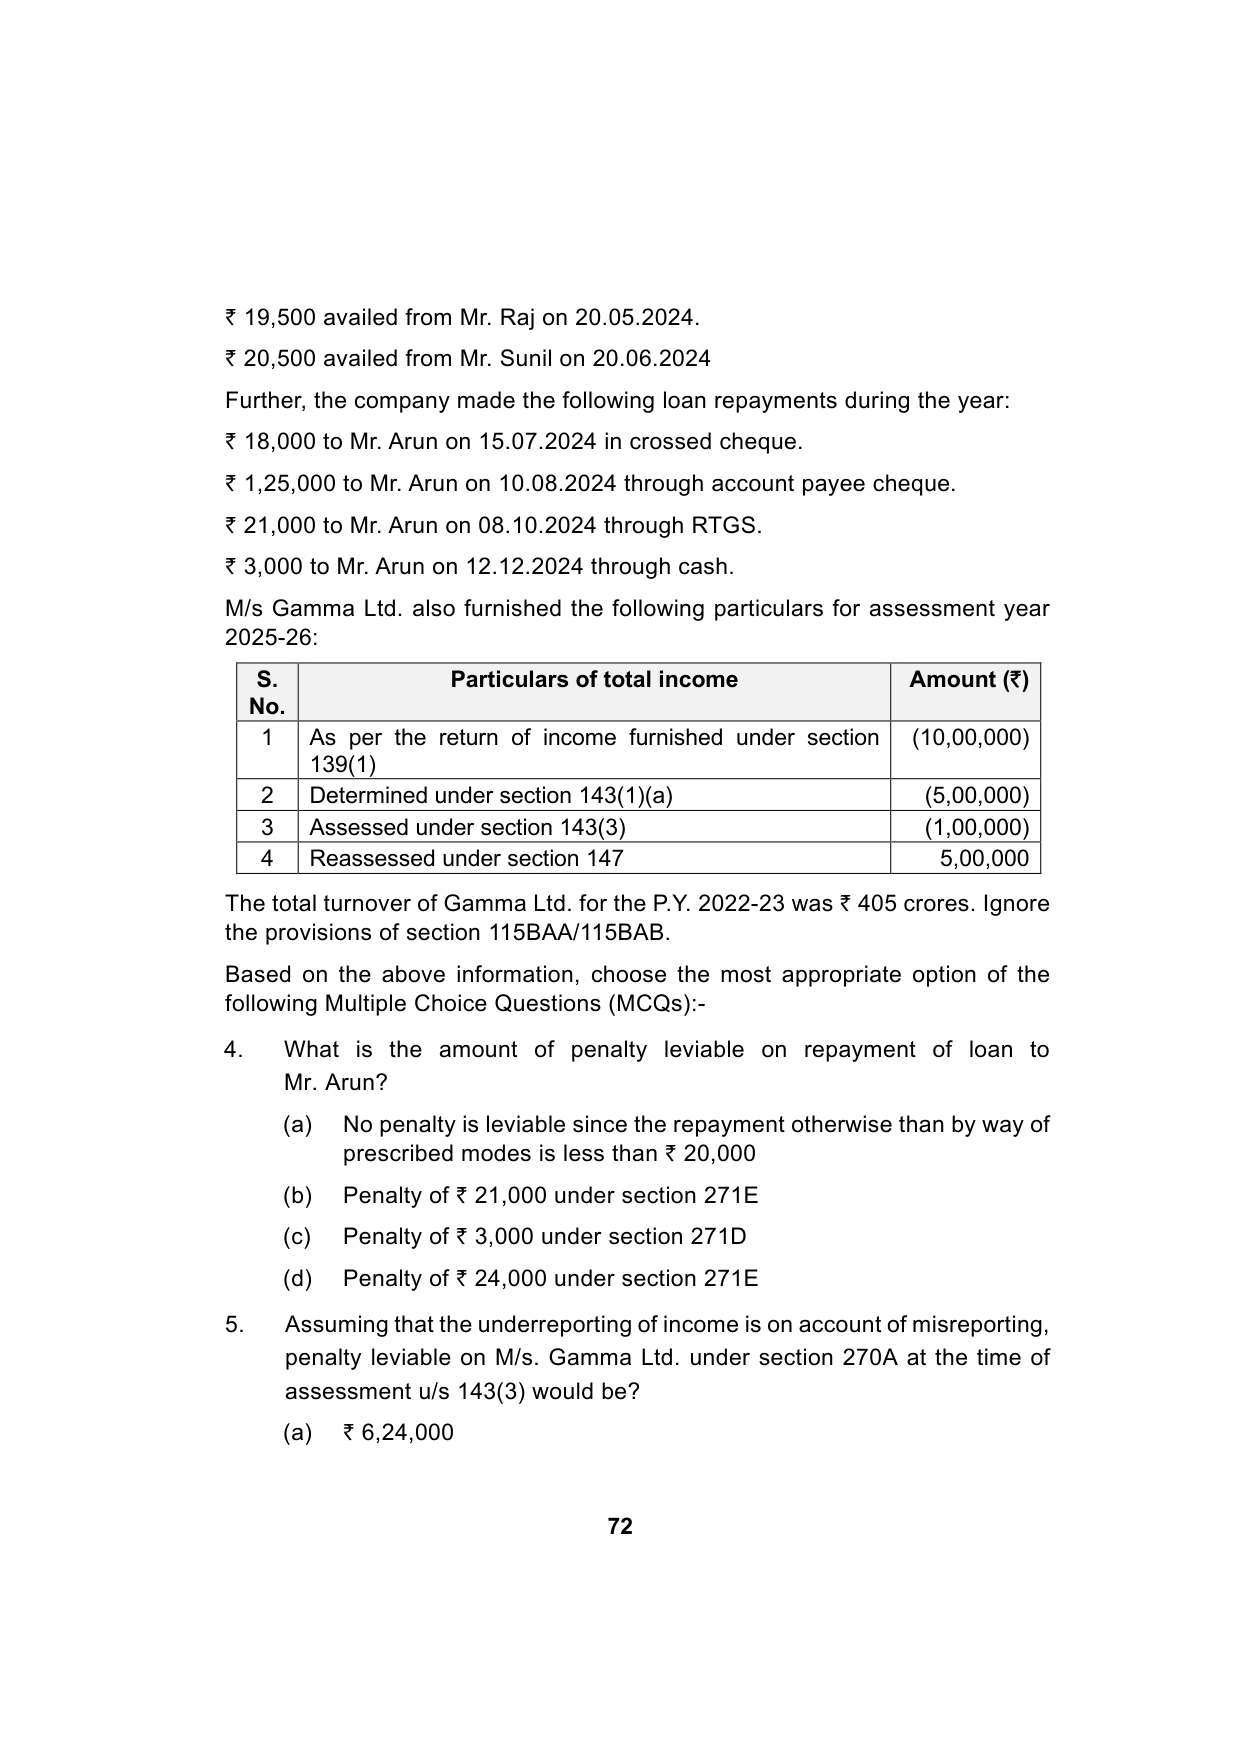
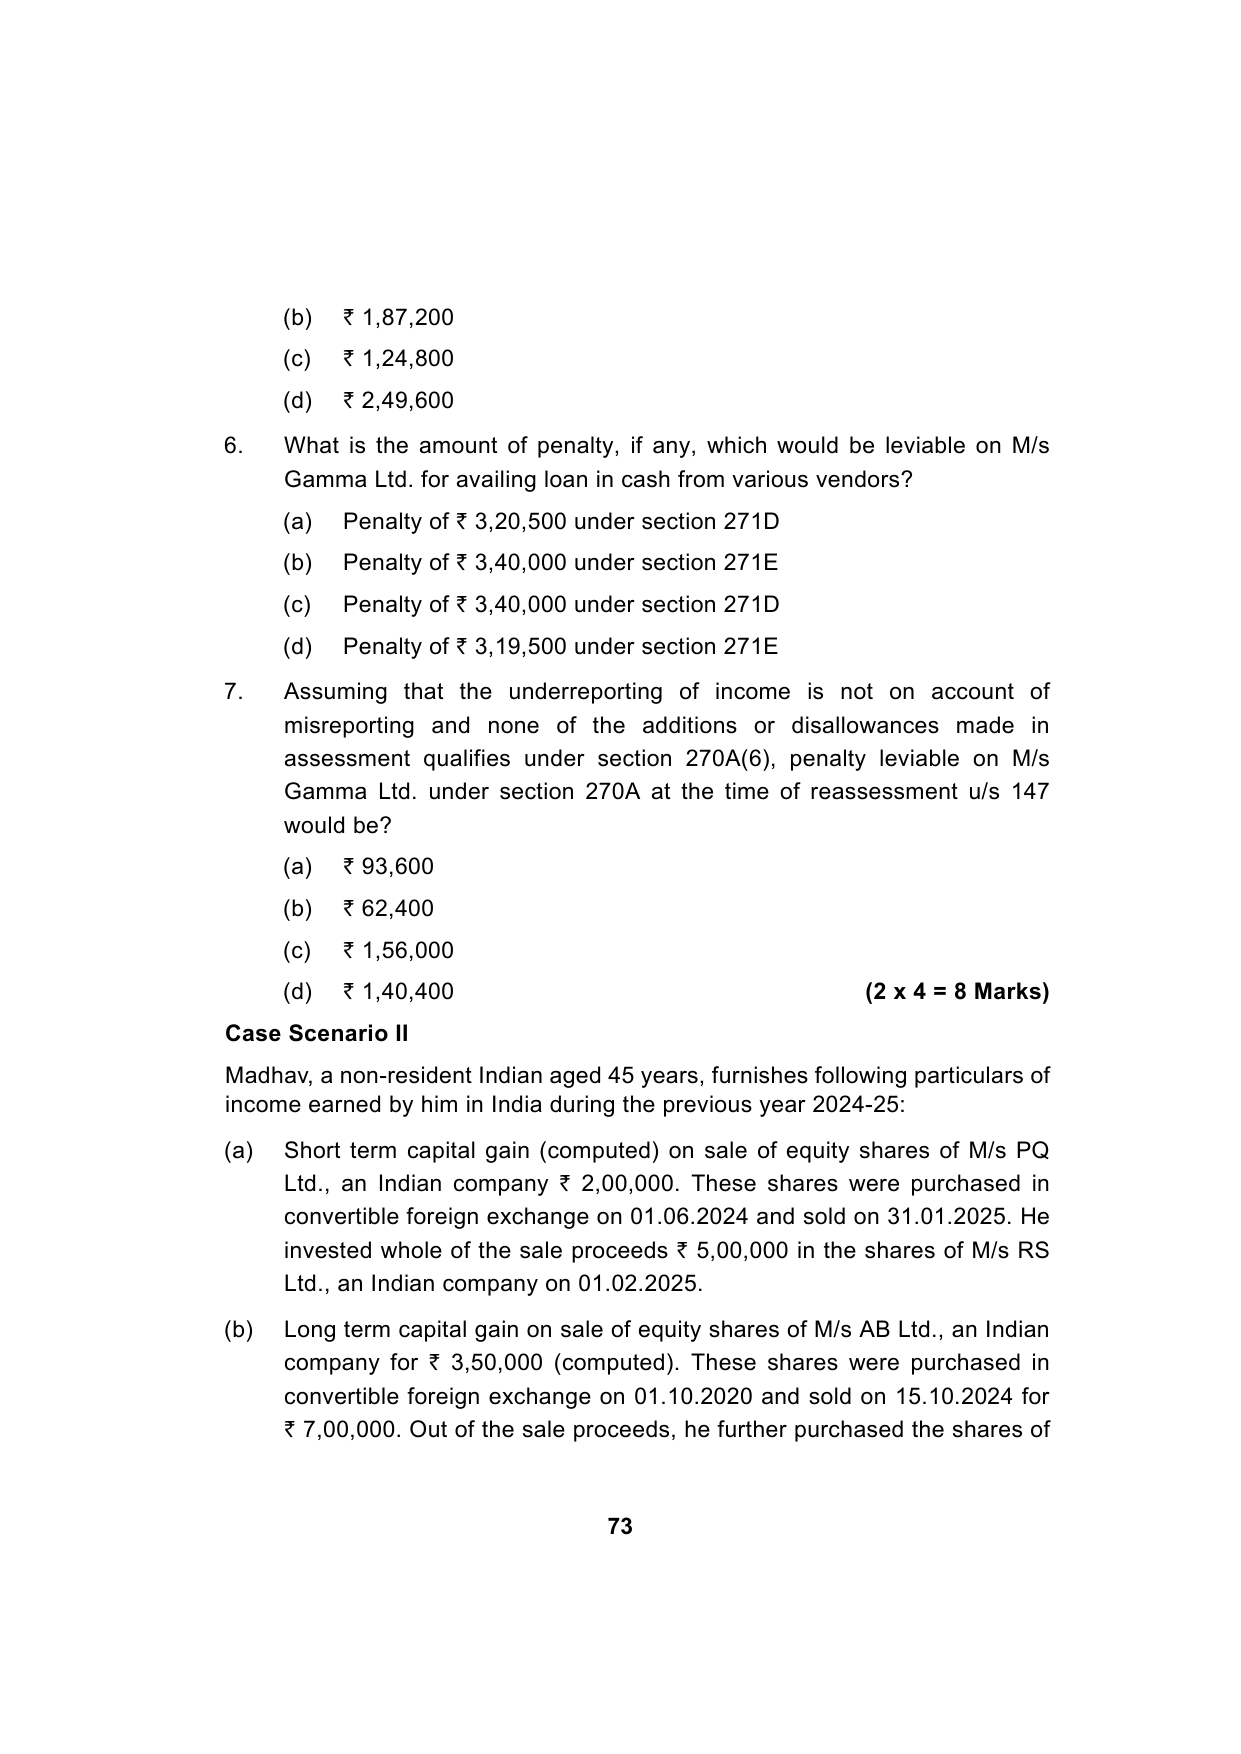
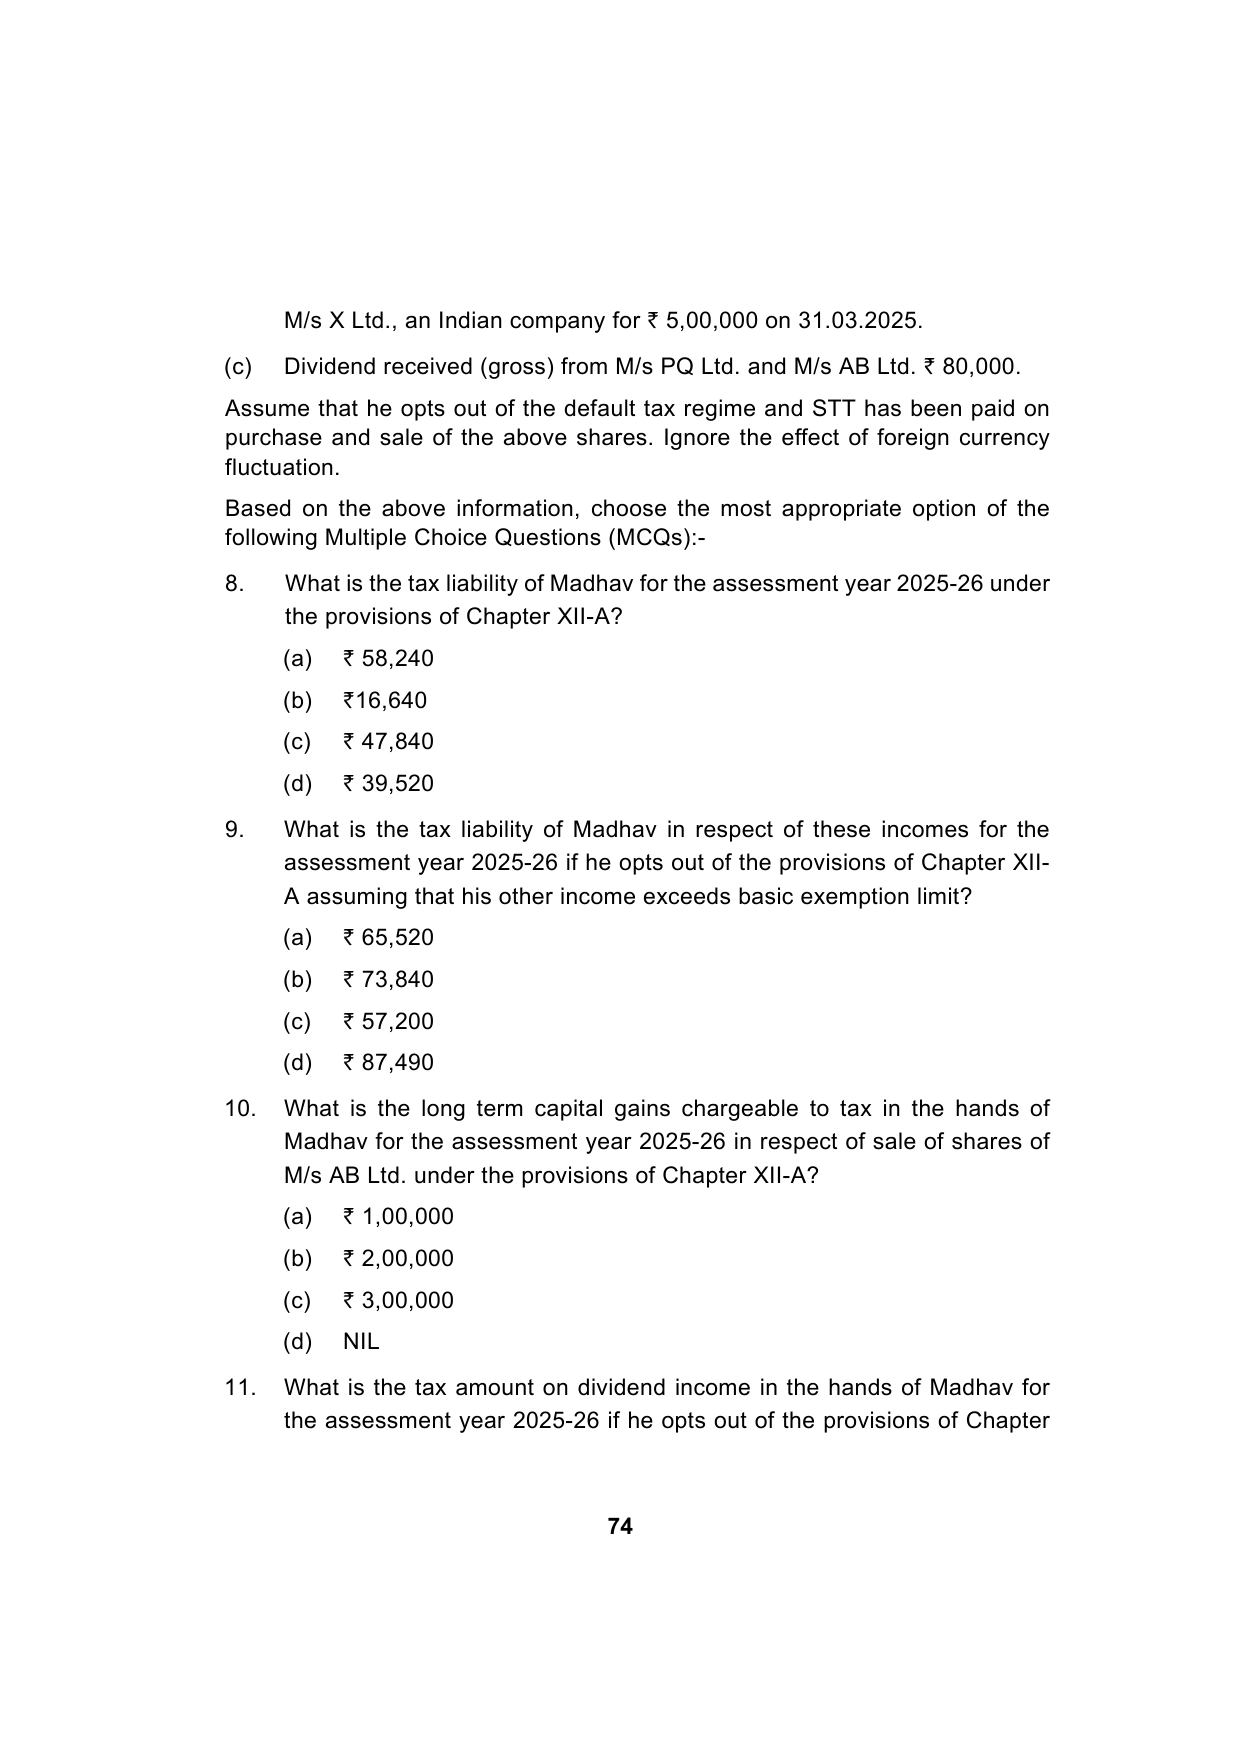
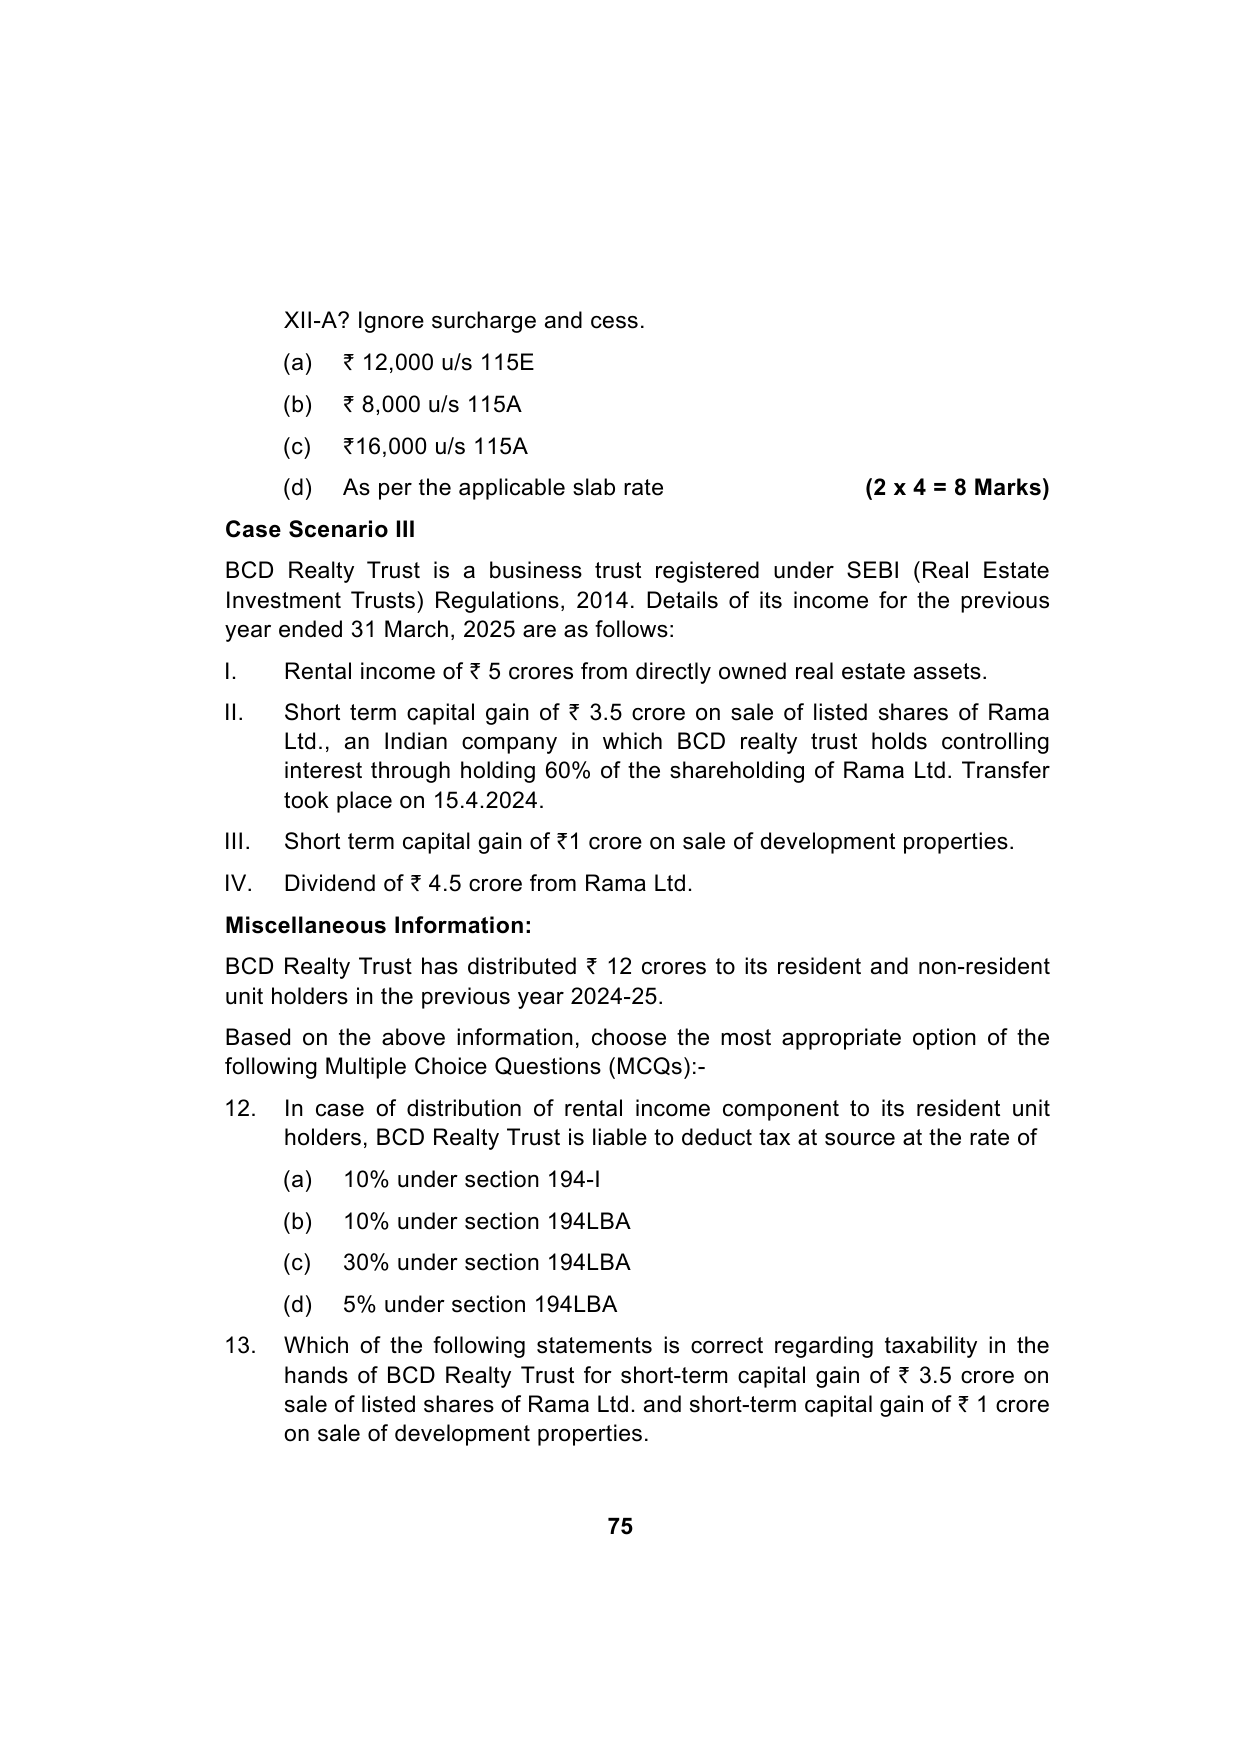
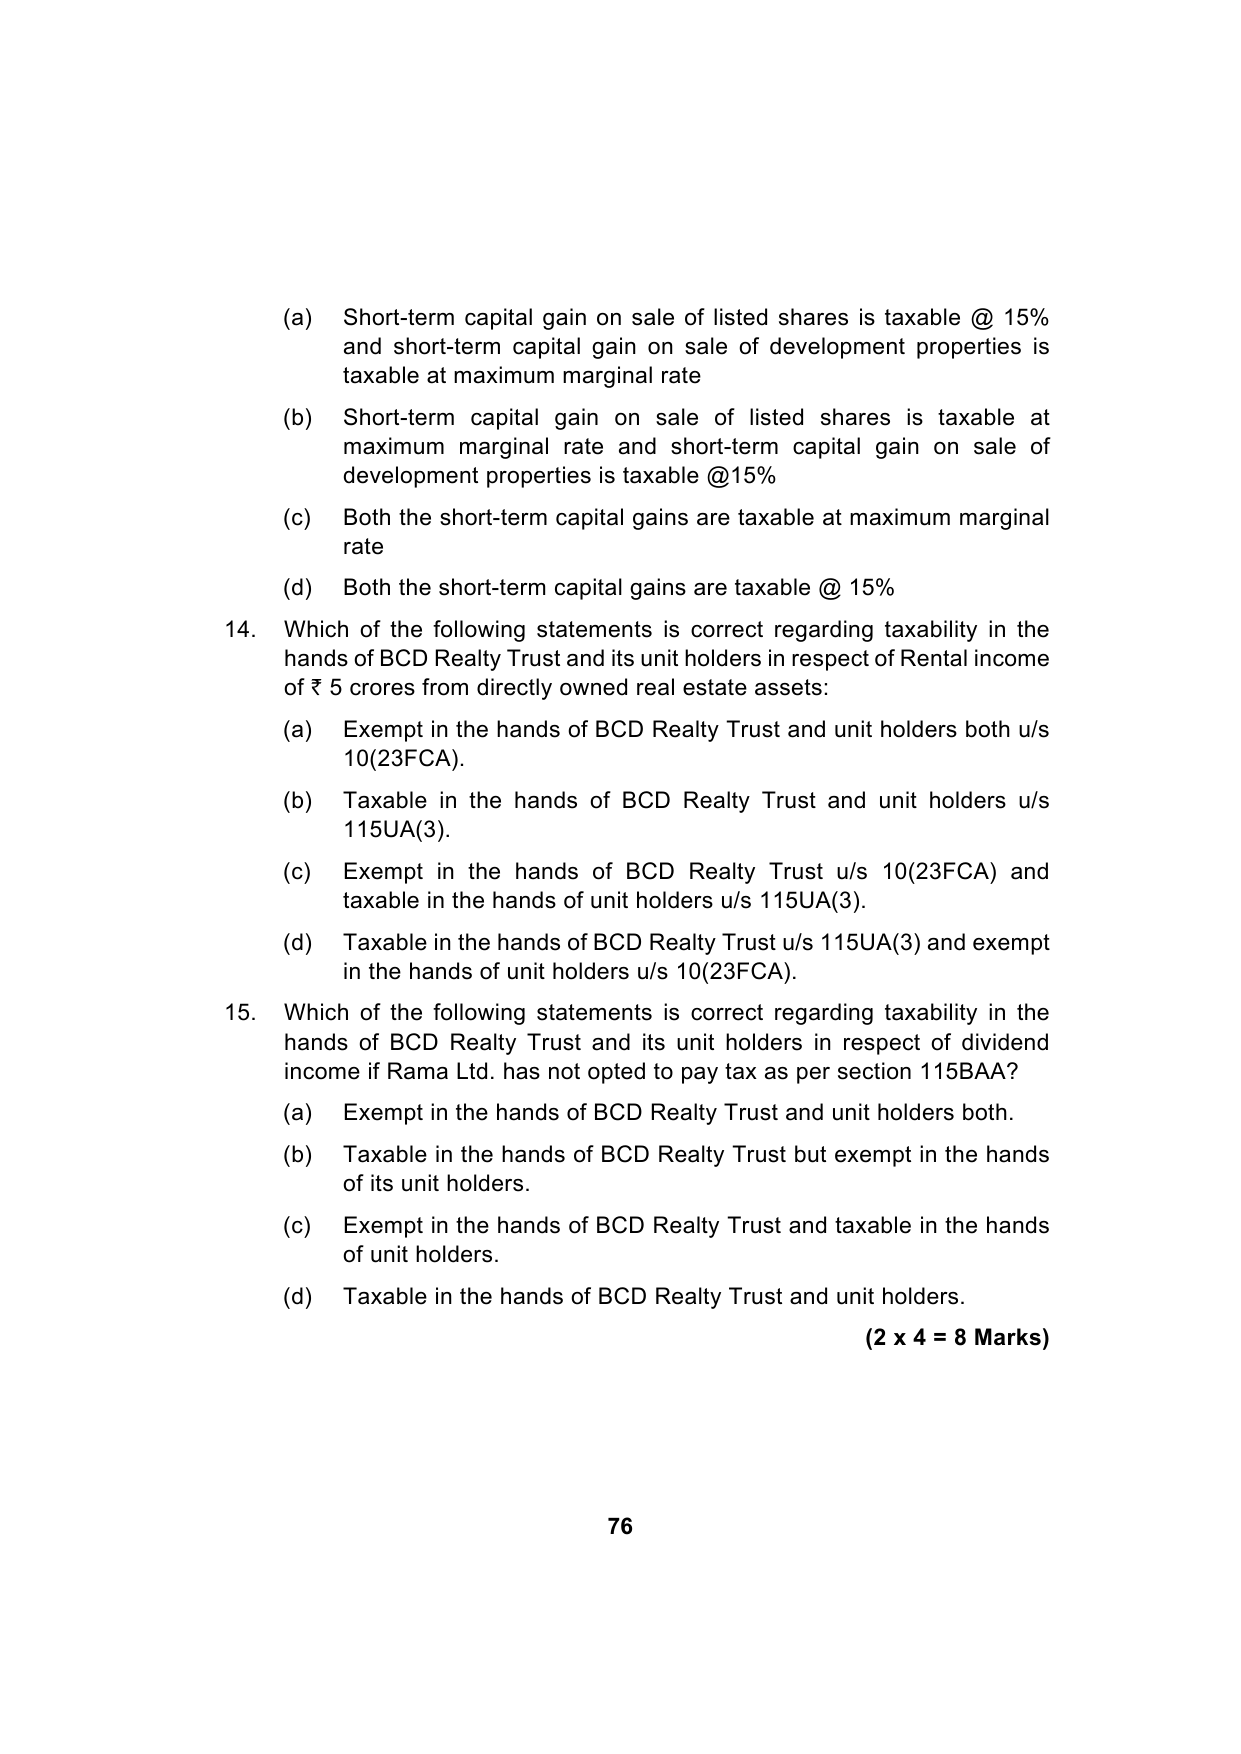
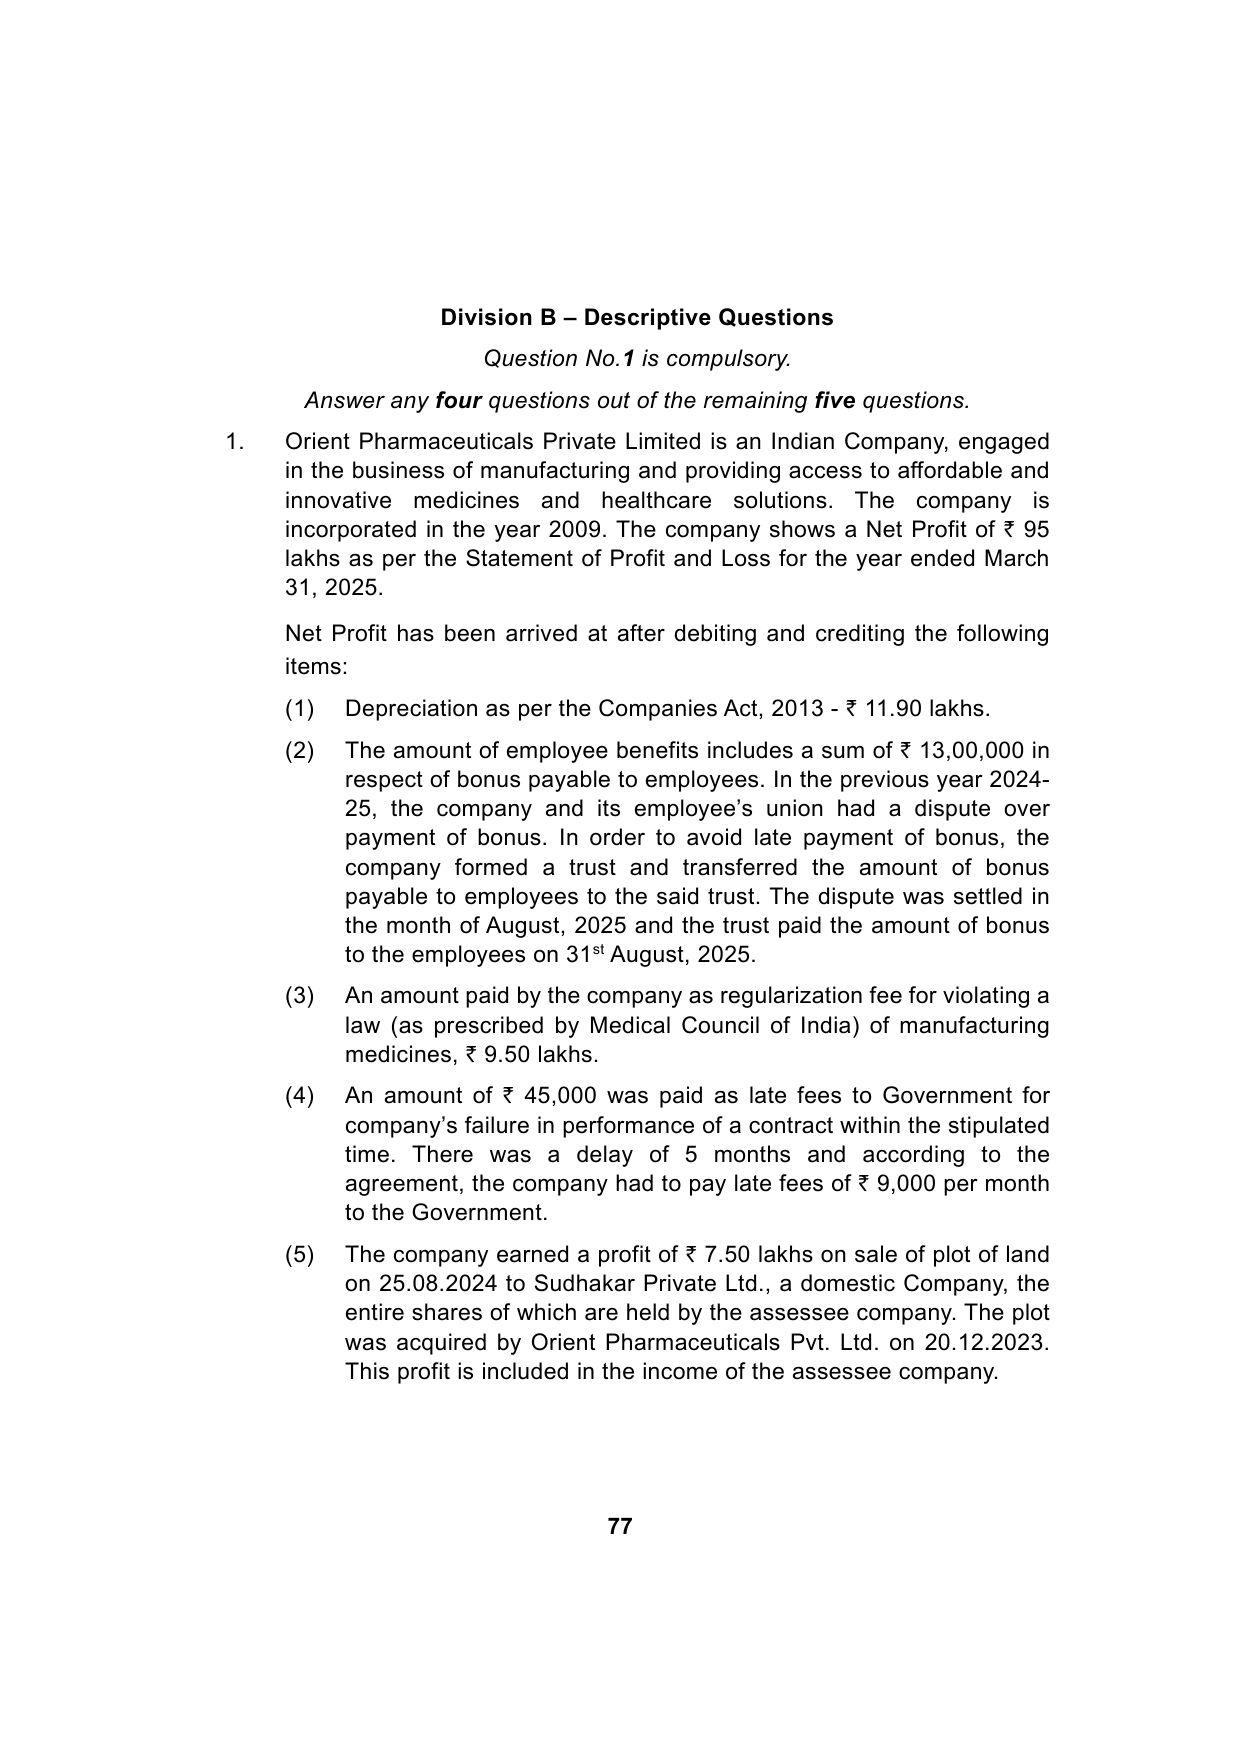
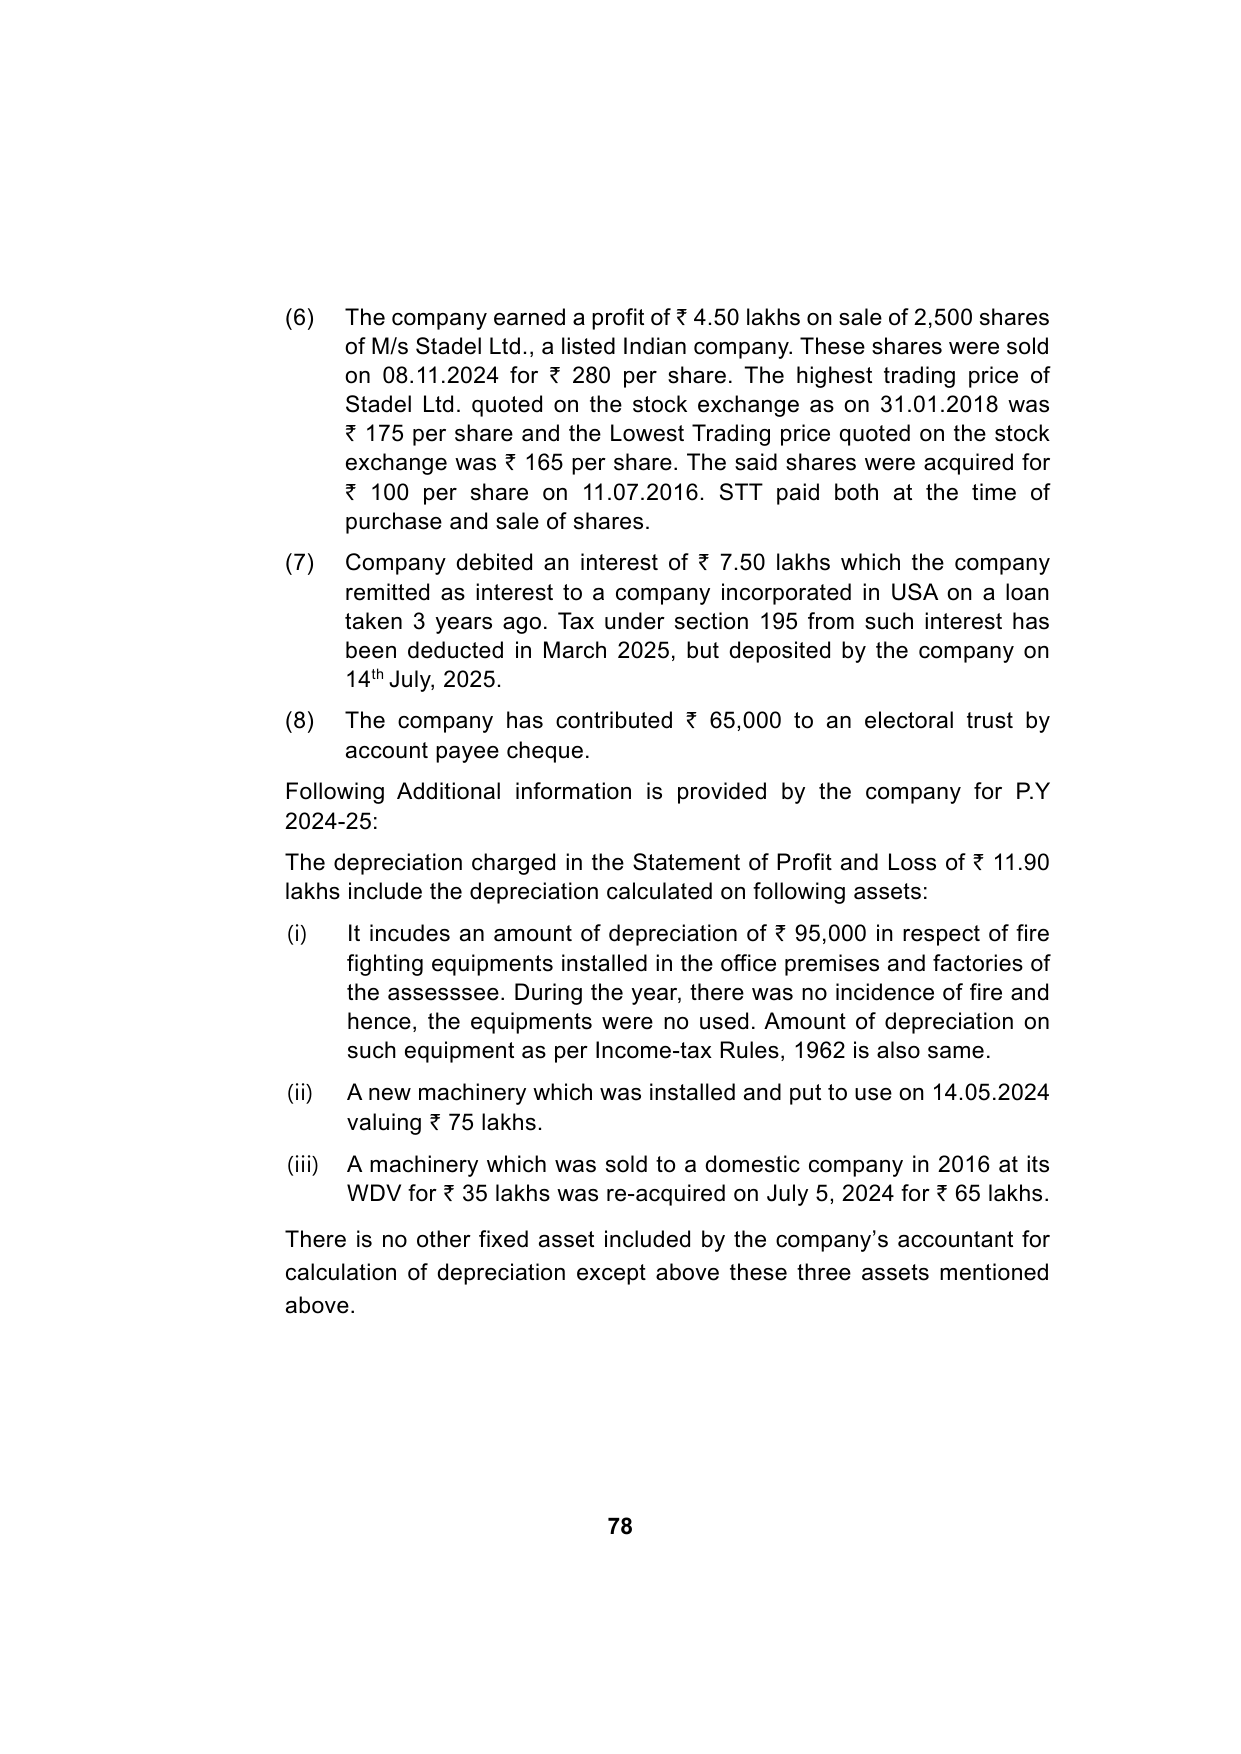
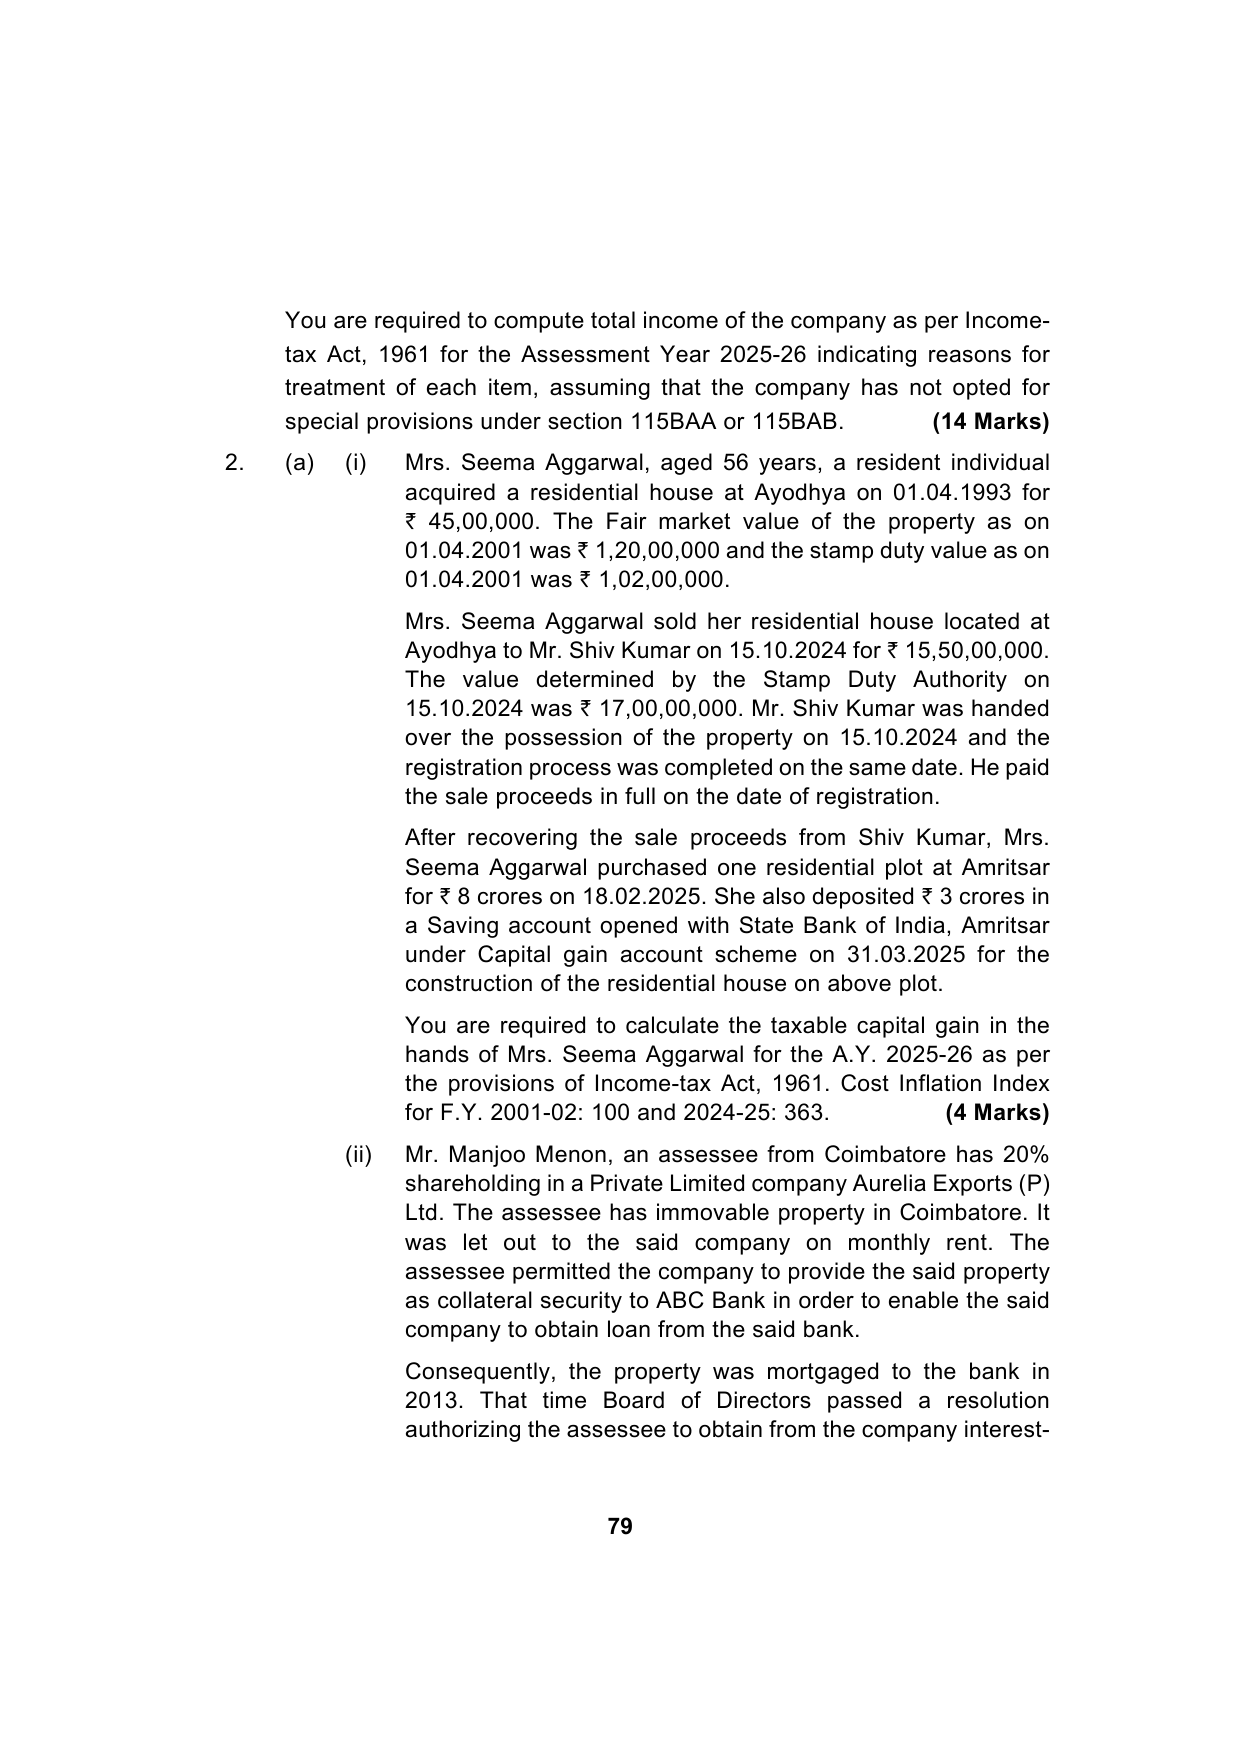
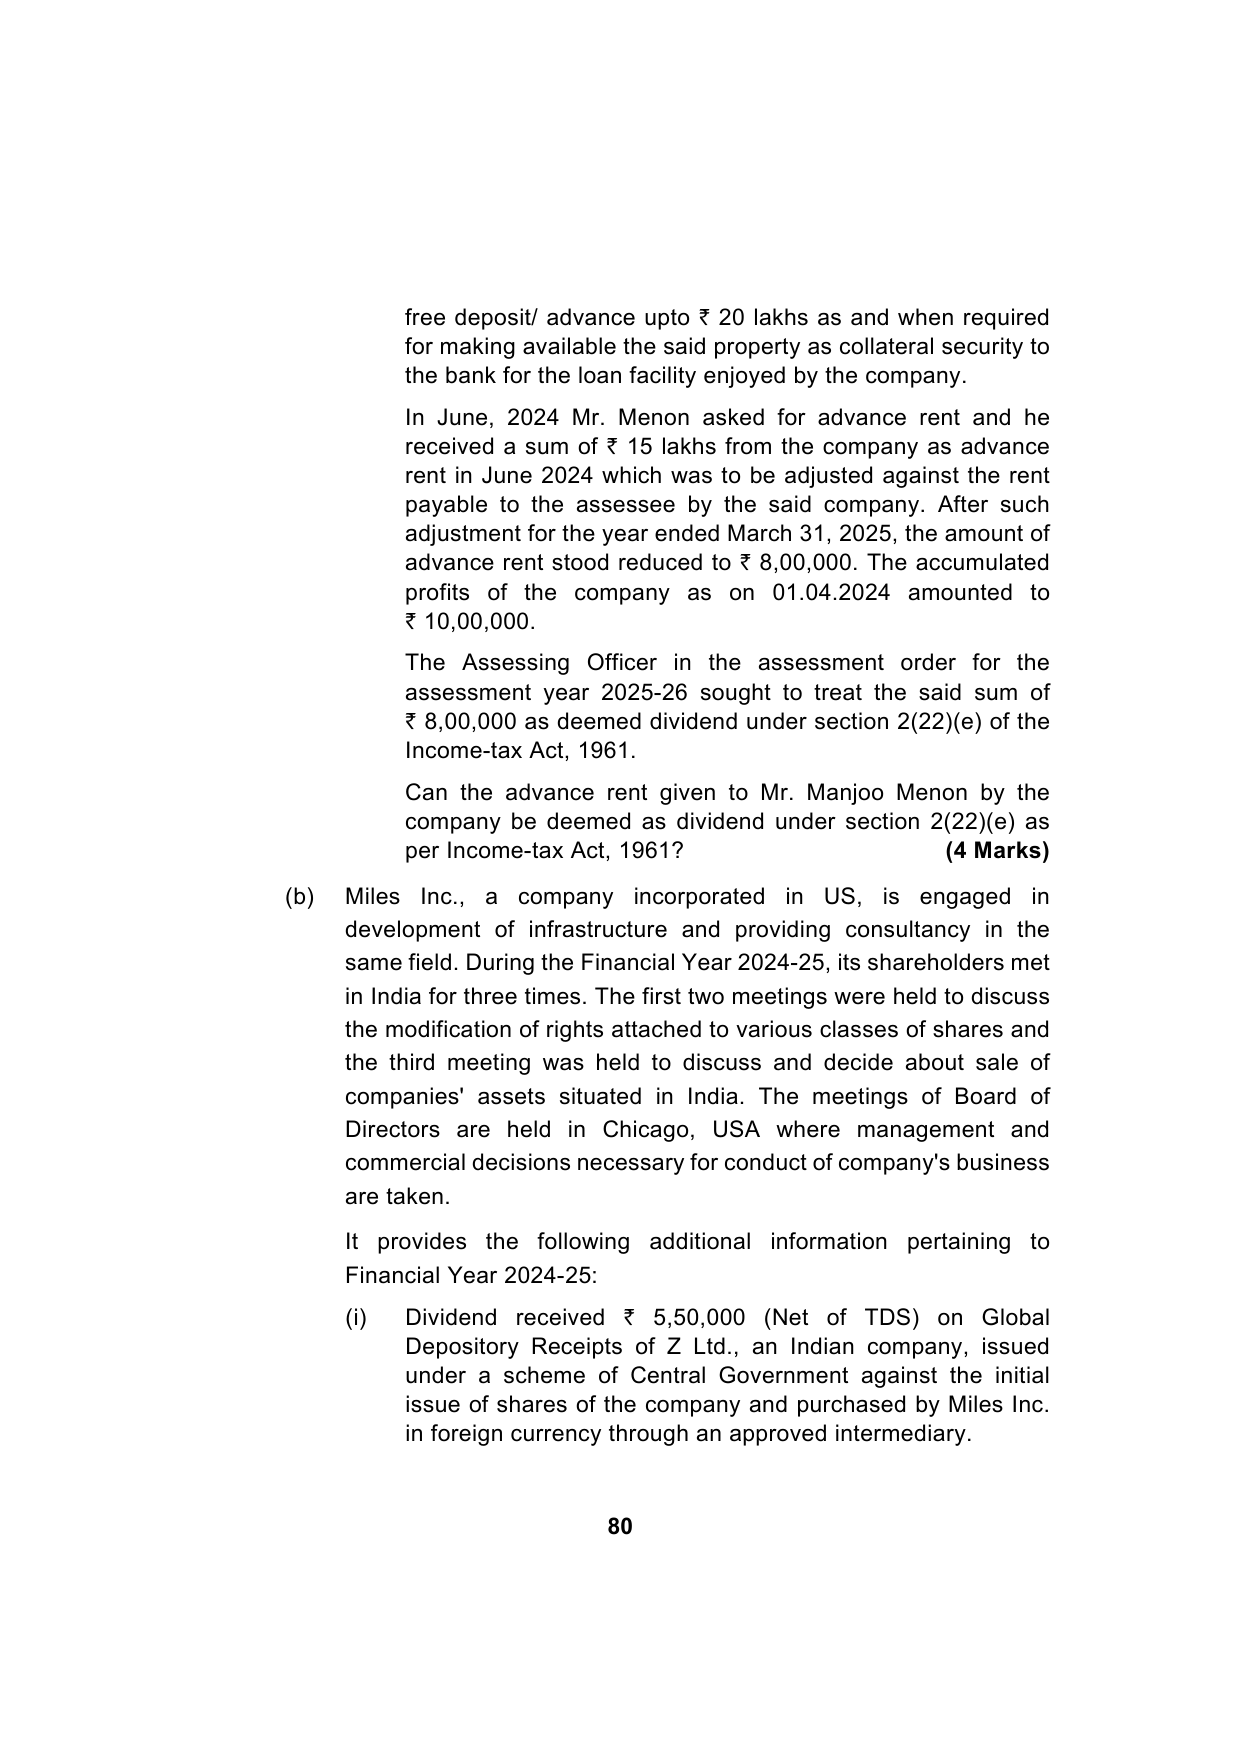
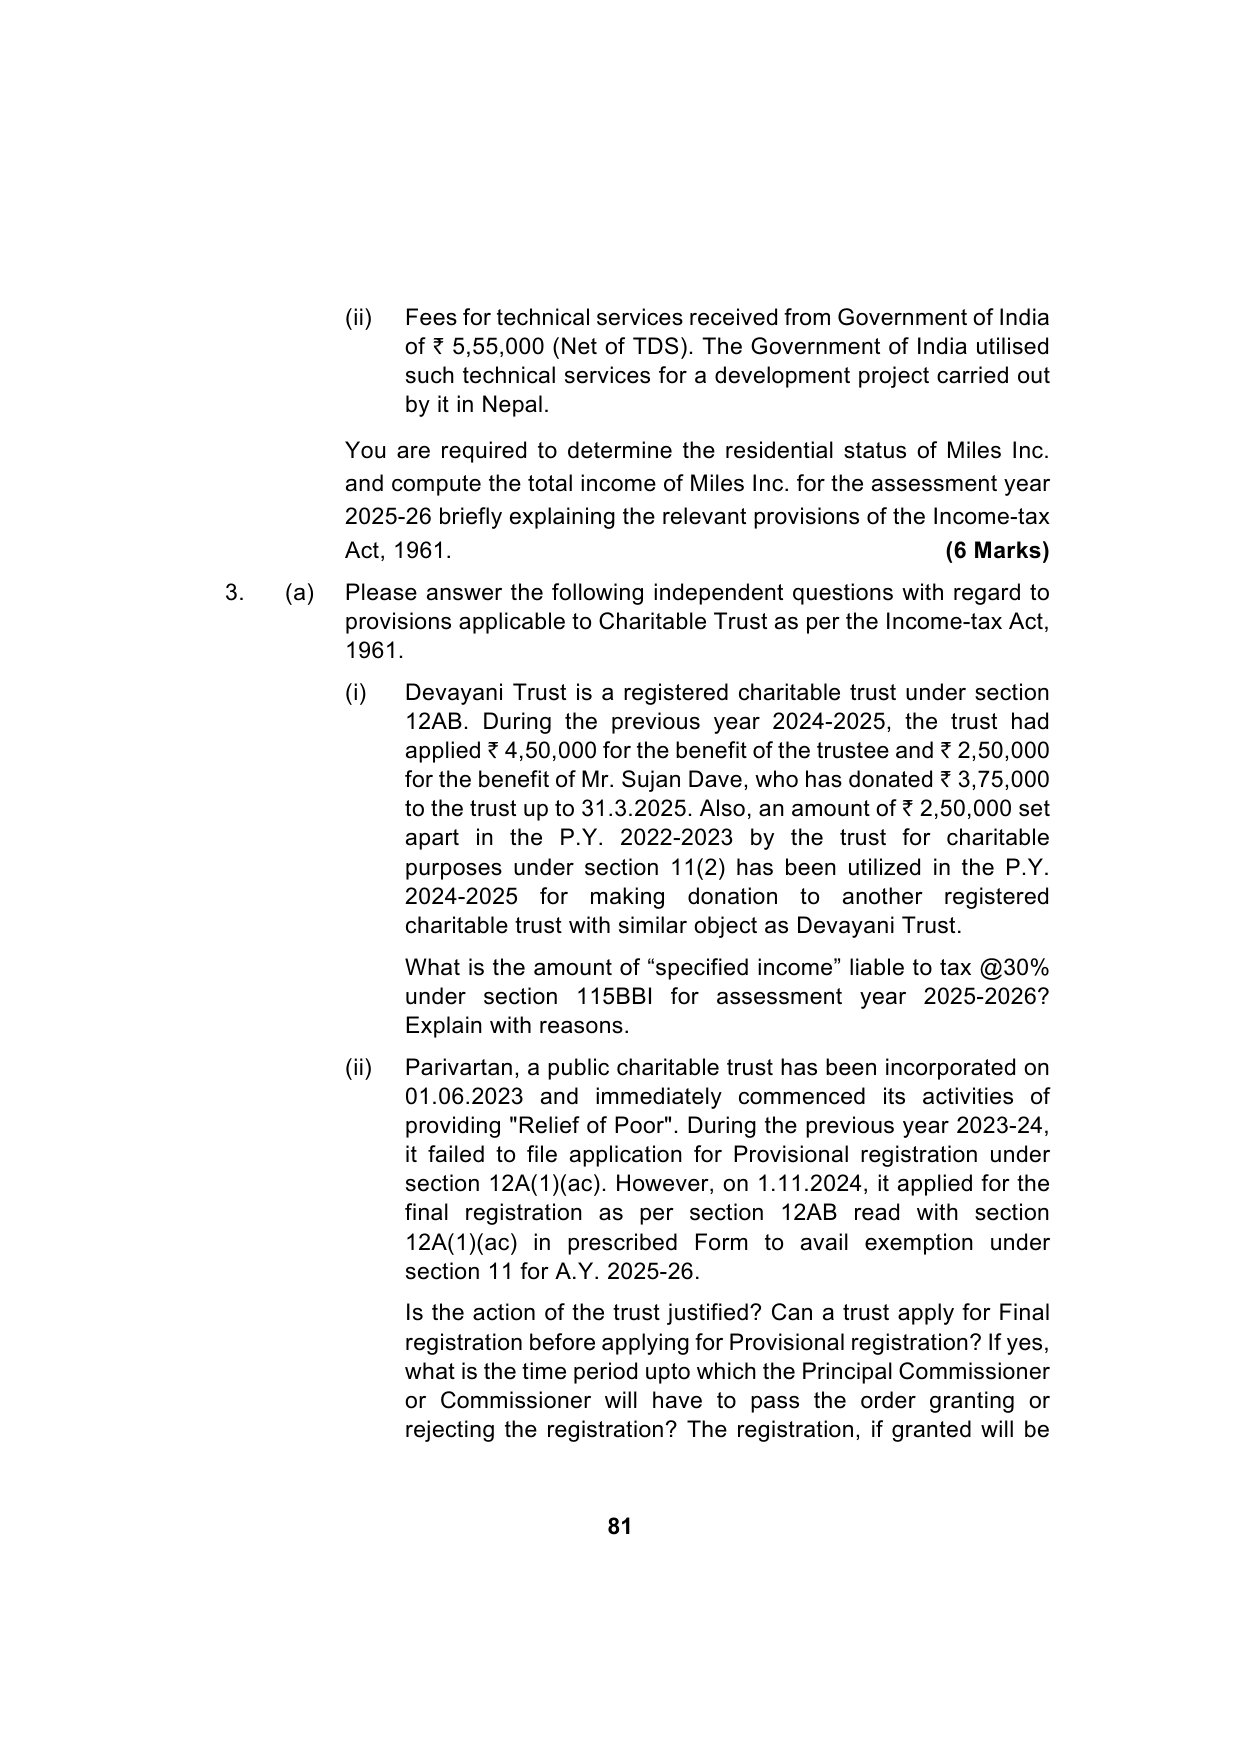
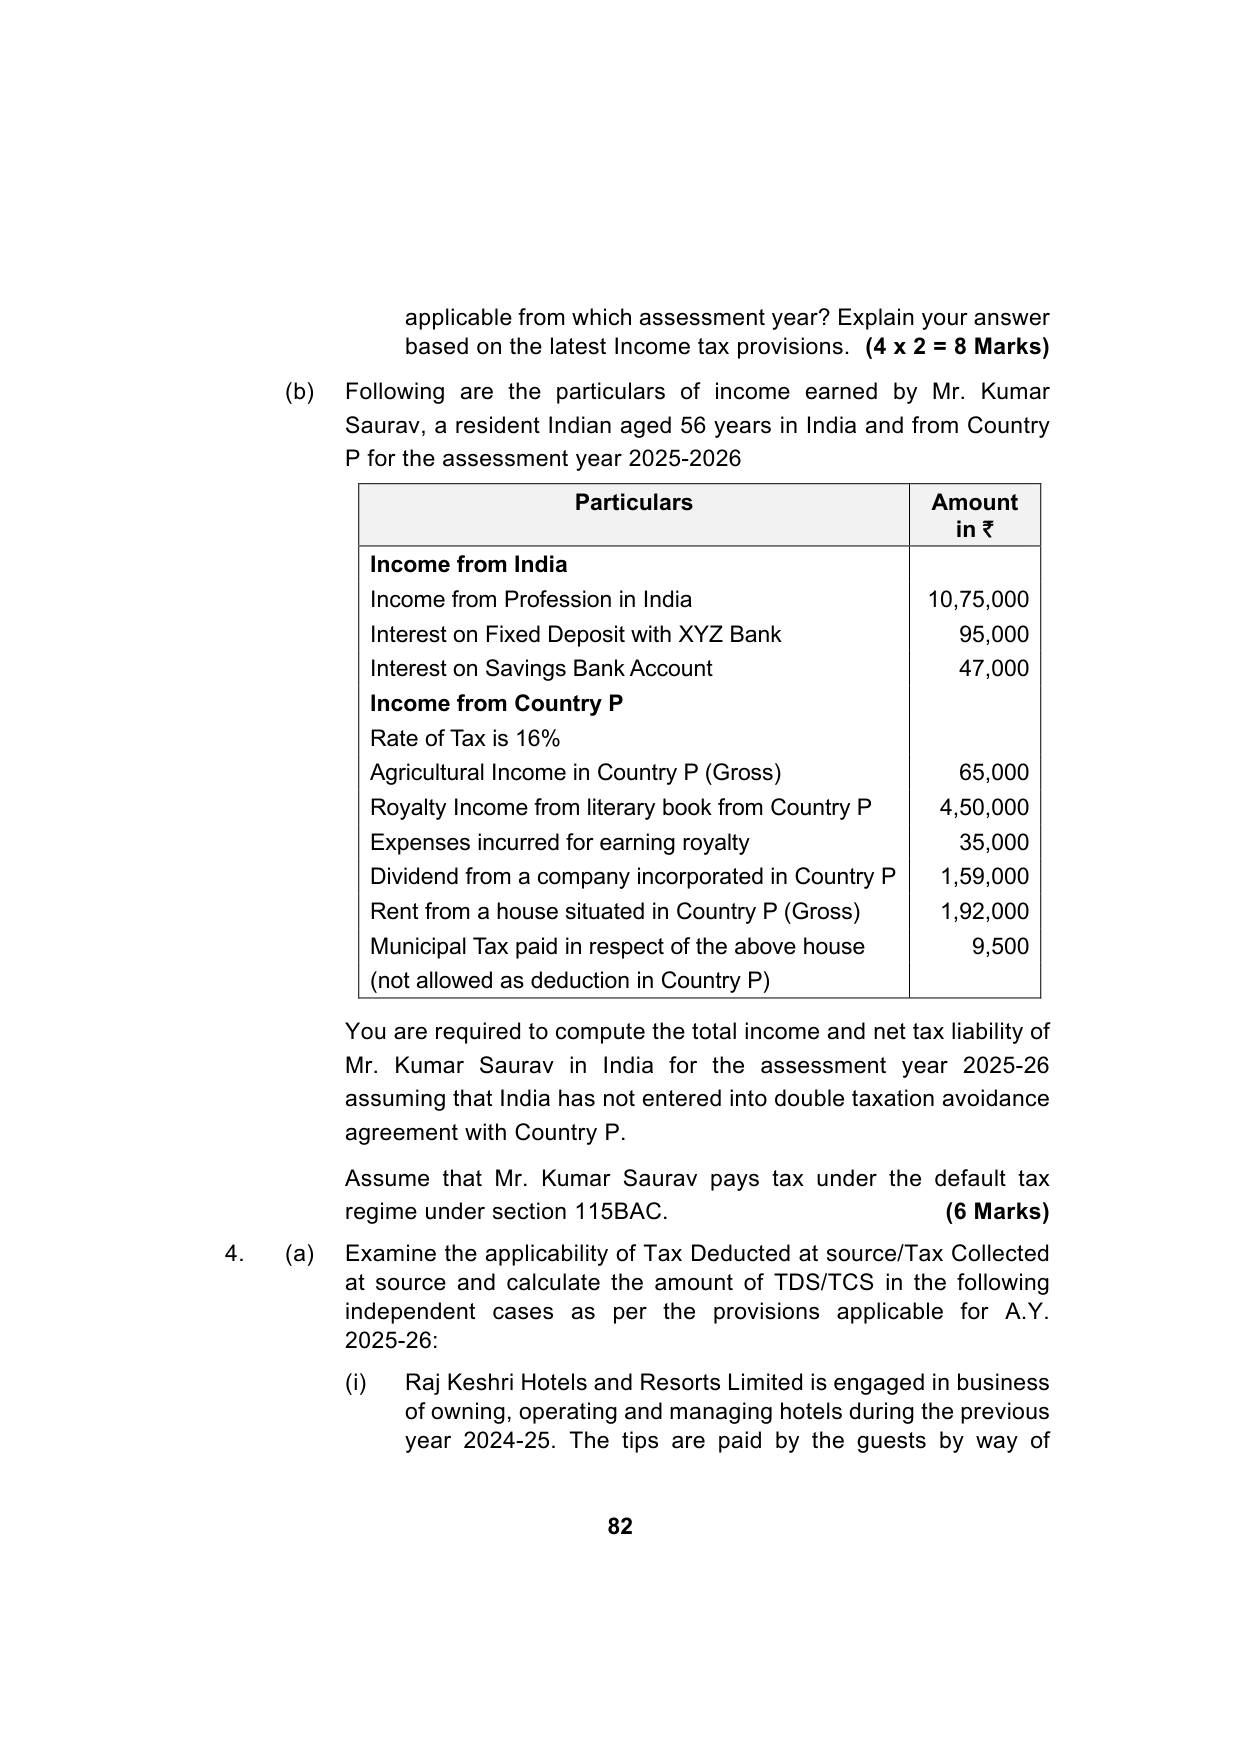
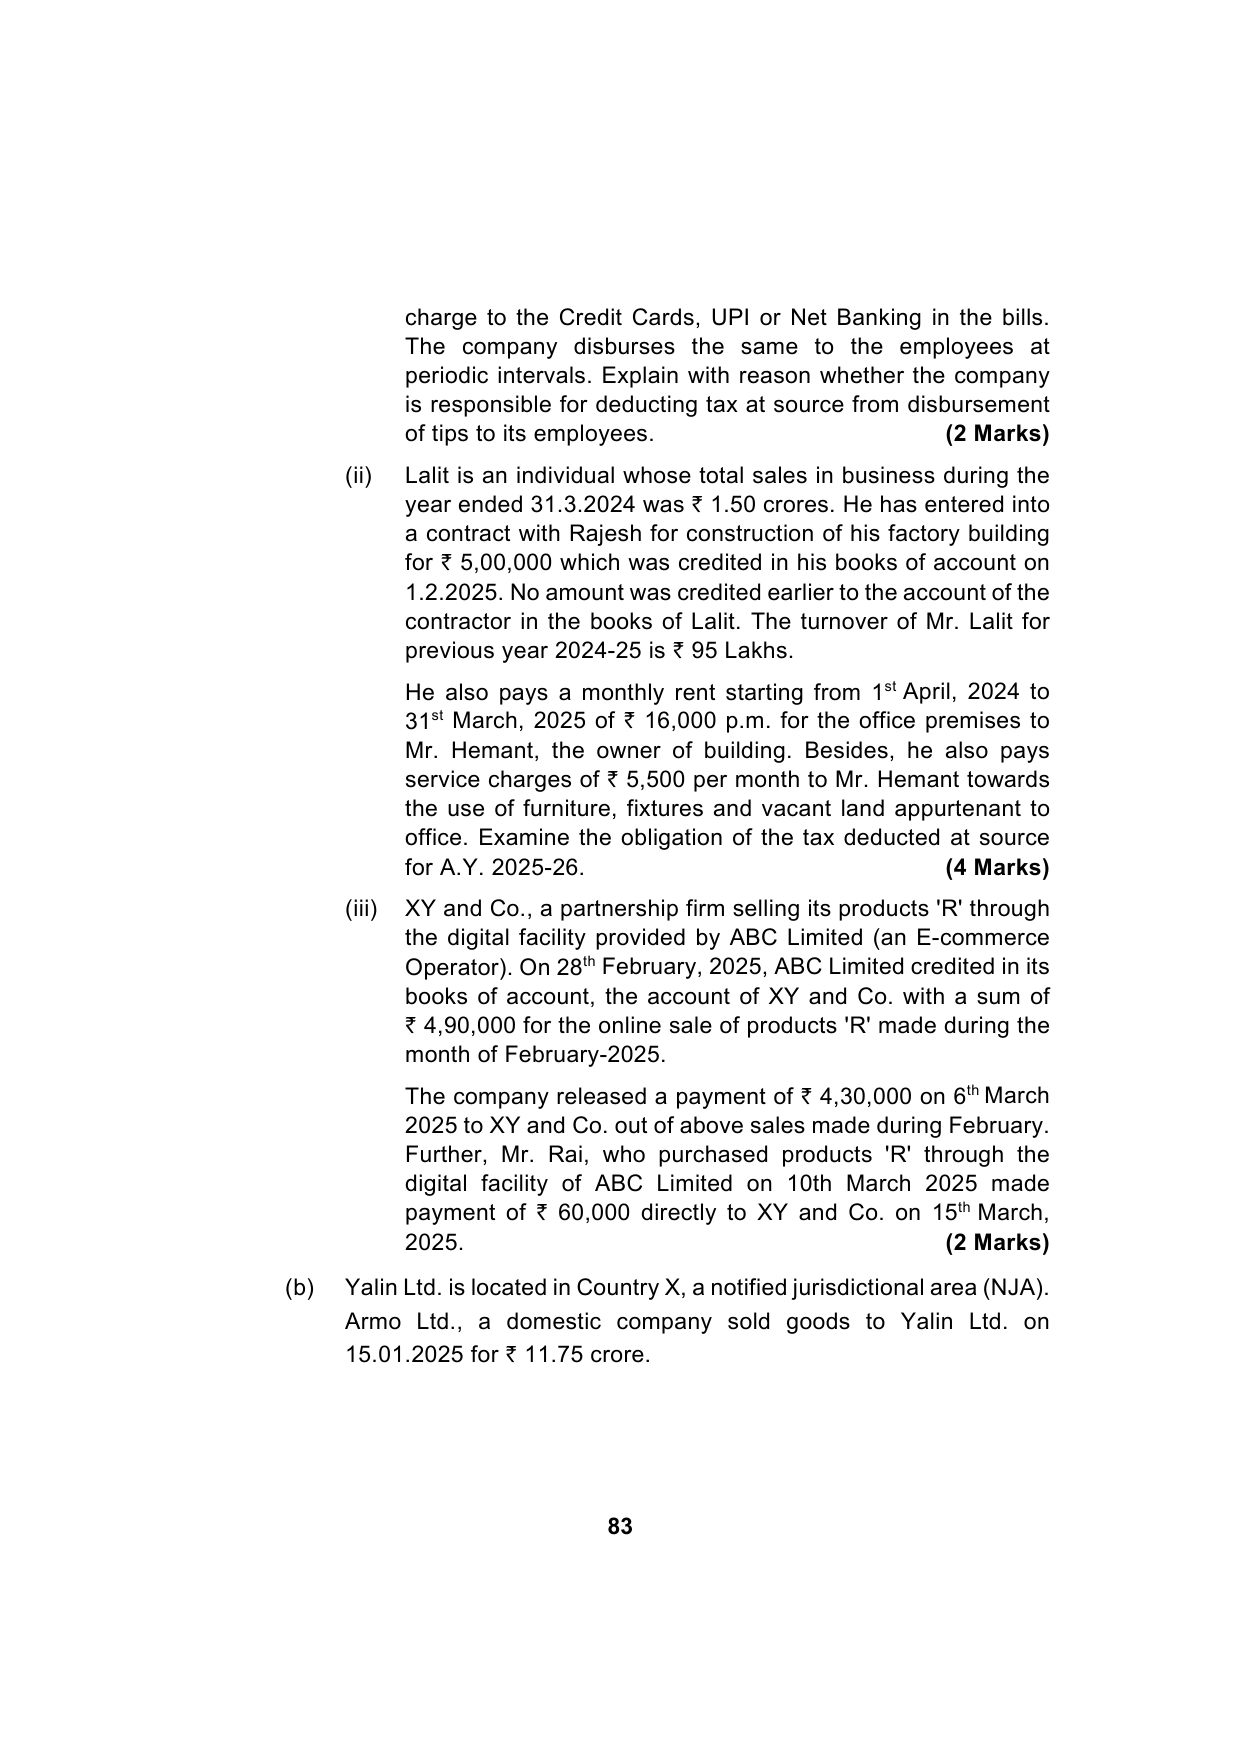
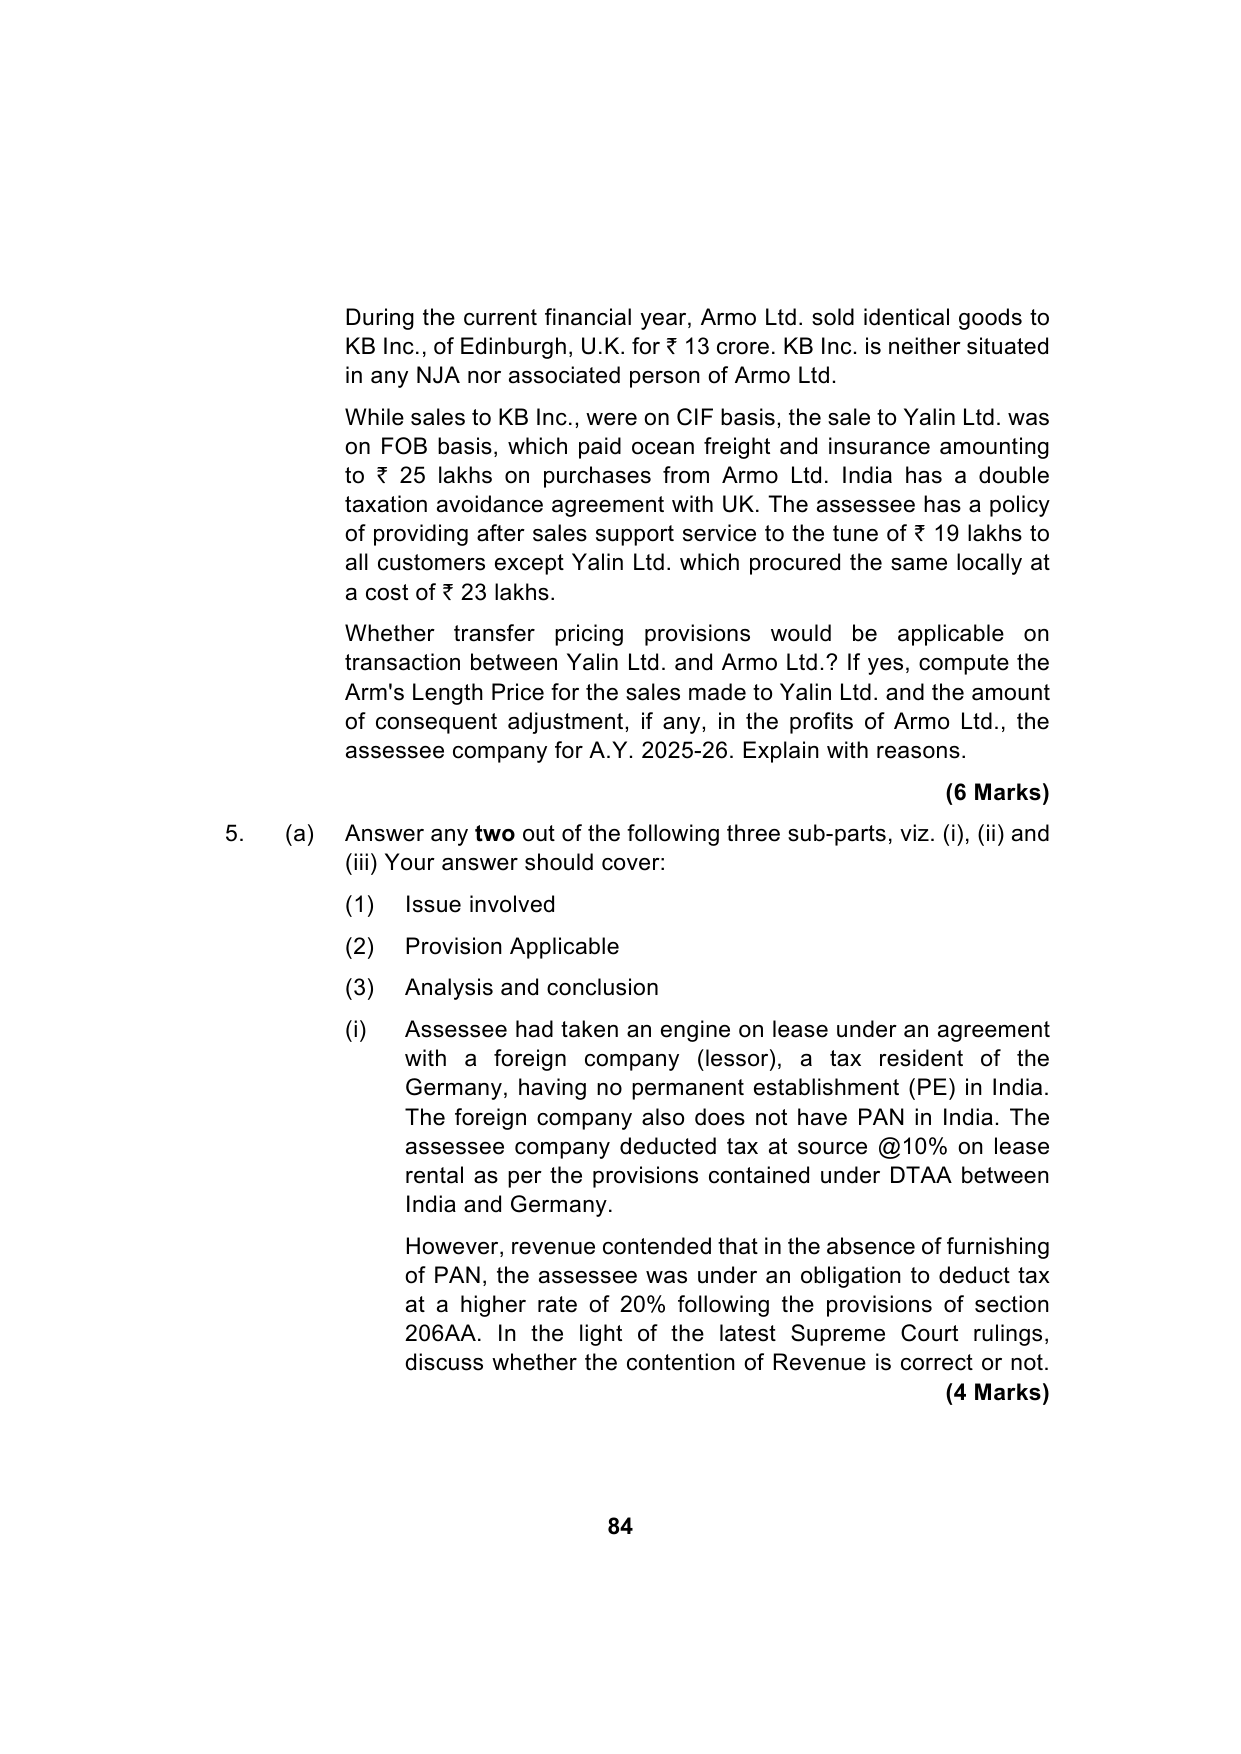
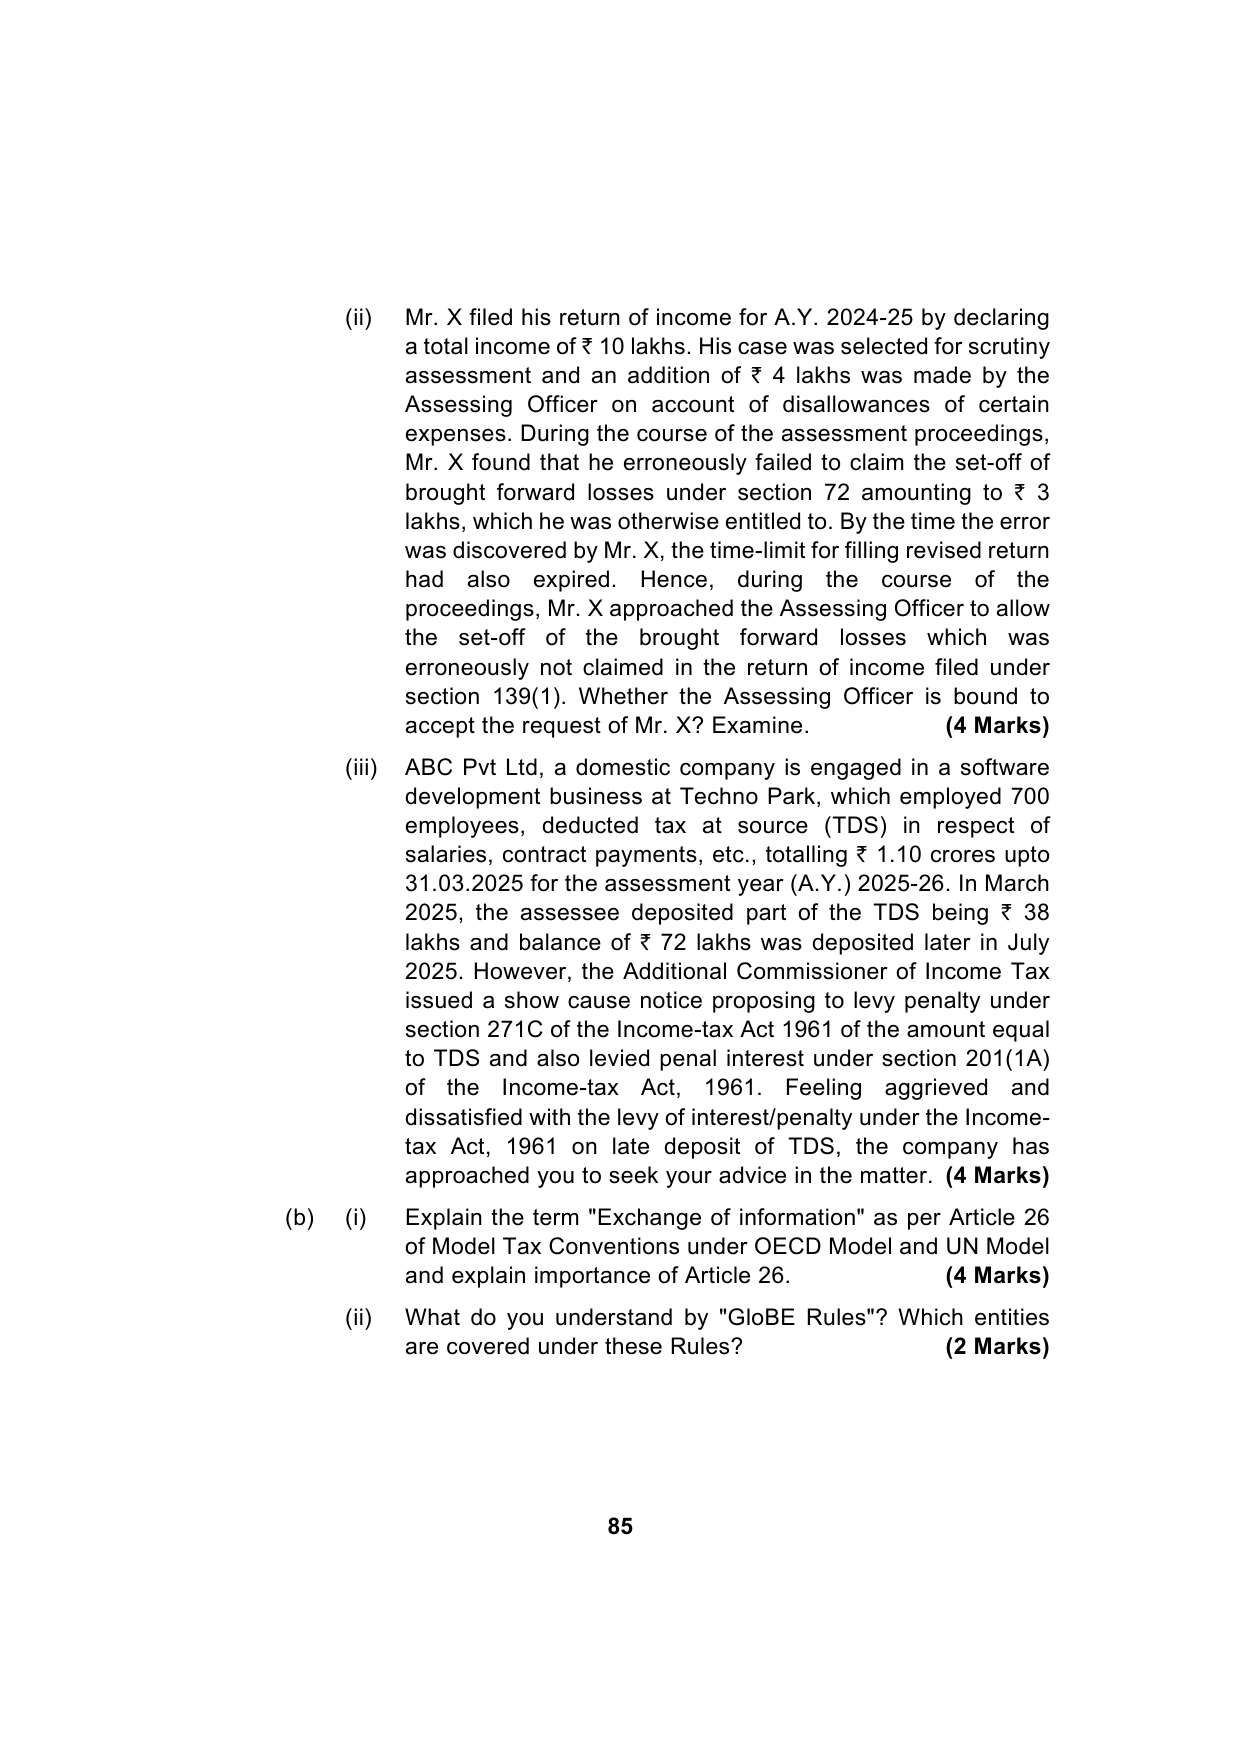
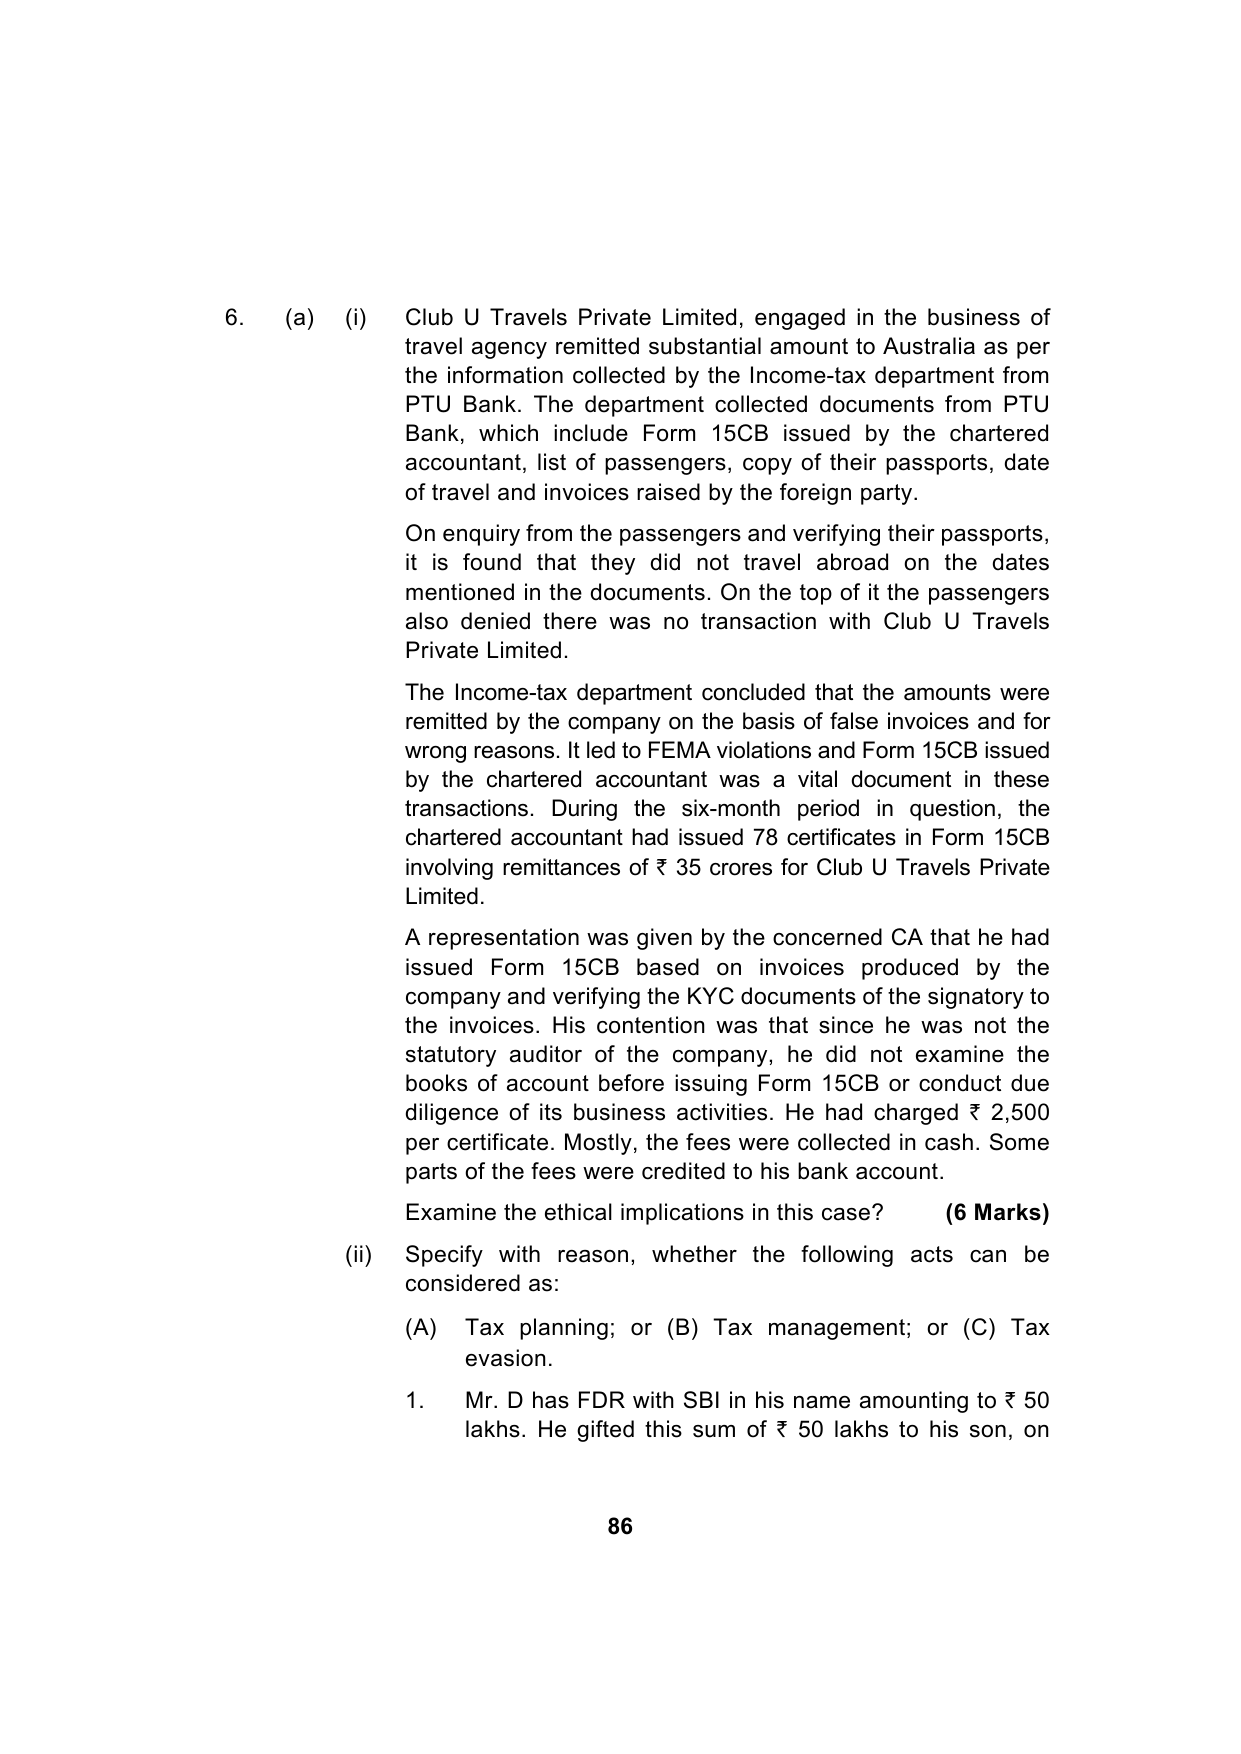
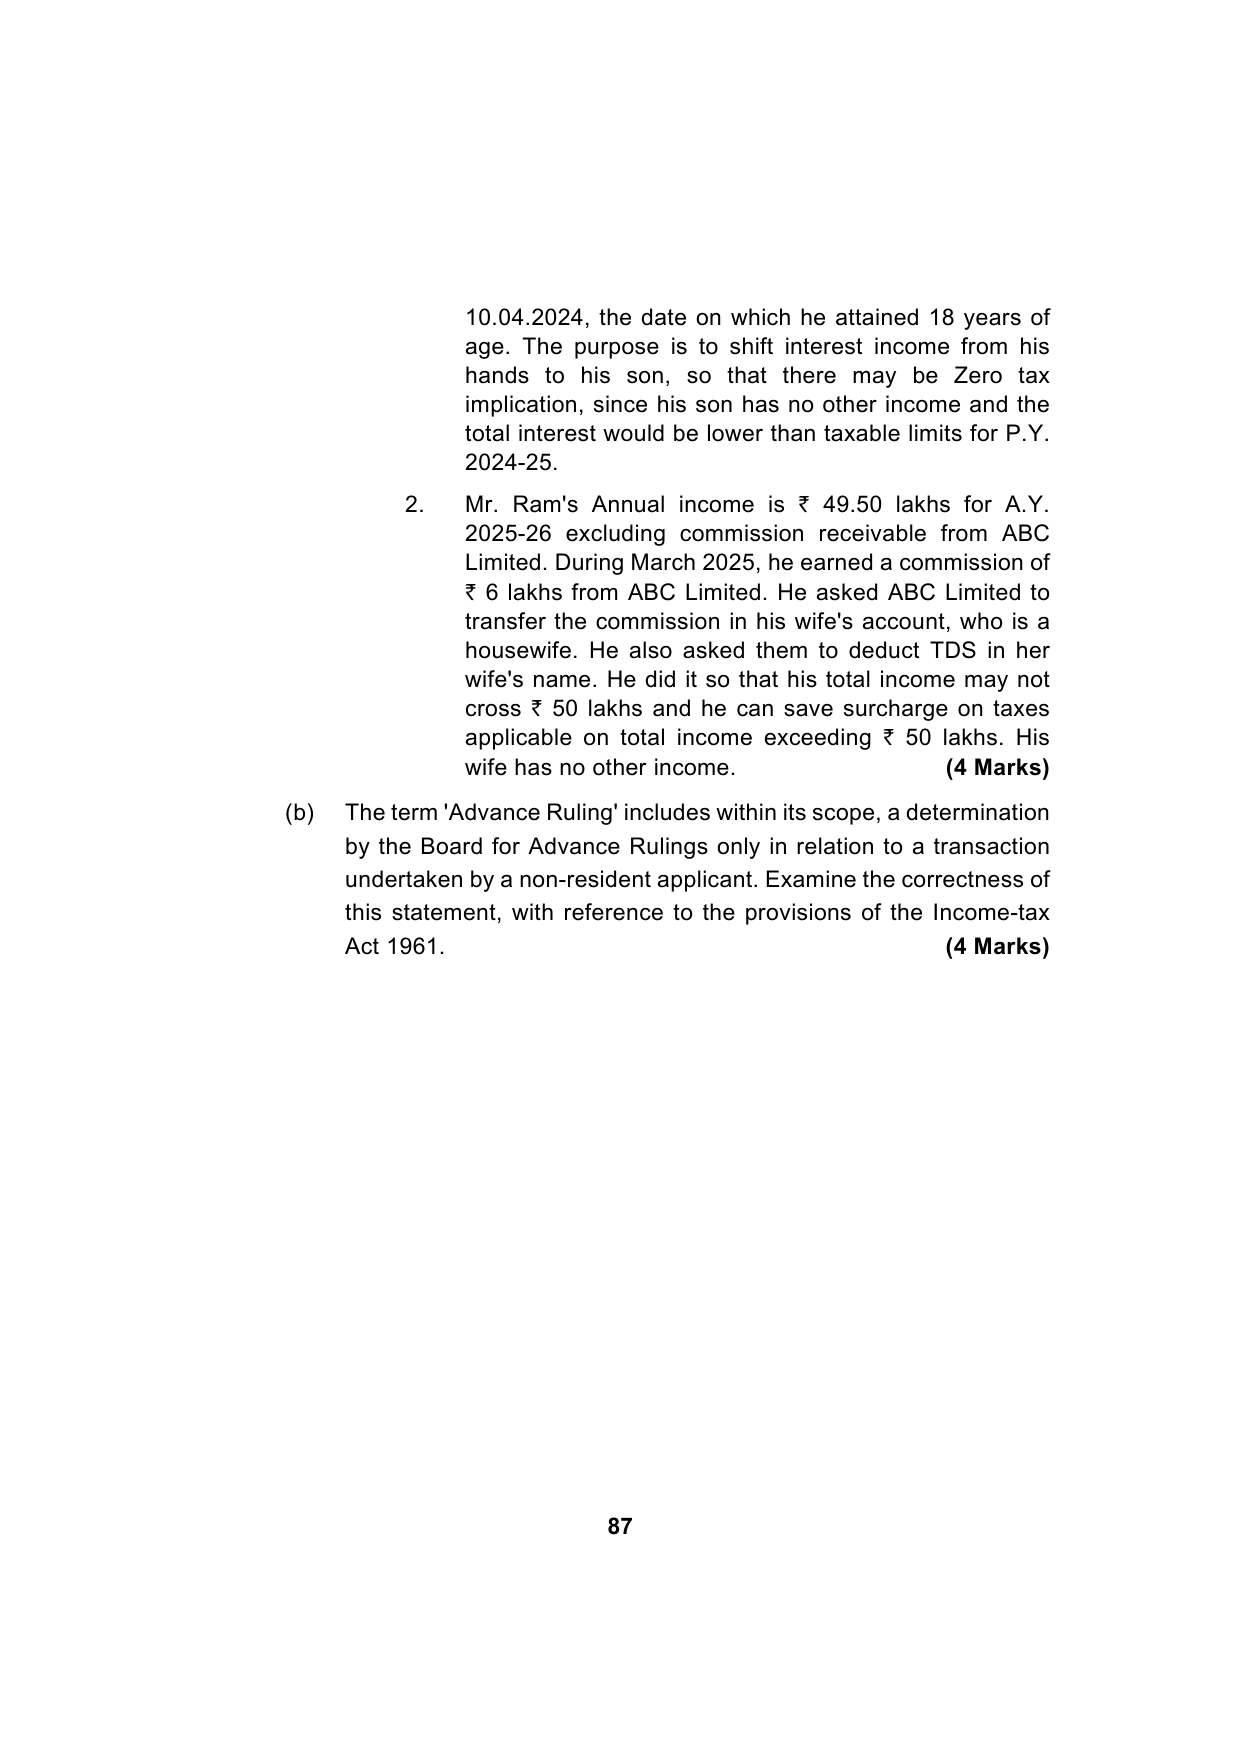
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 6 (100 marks)
Question
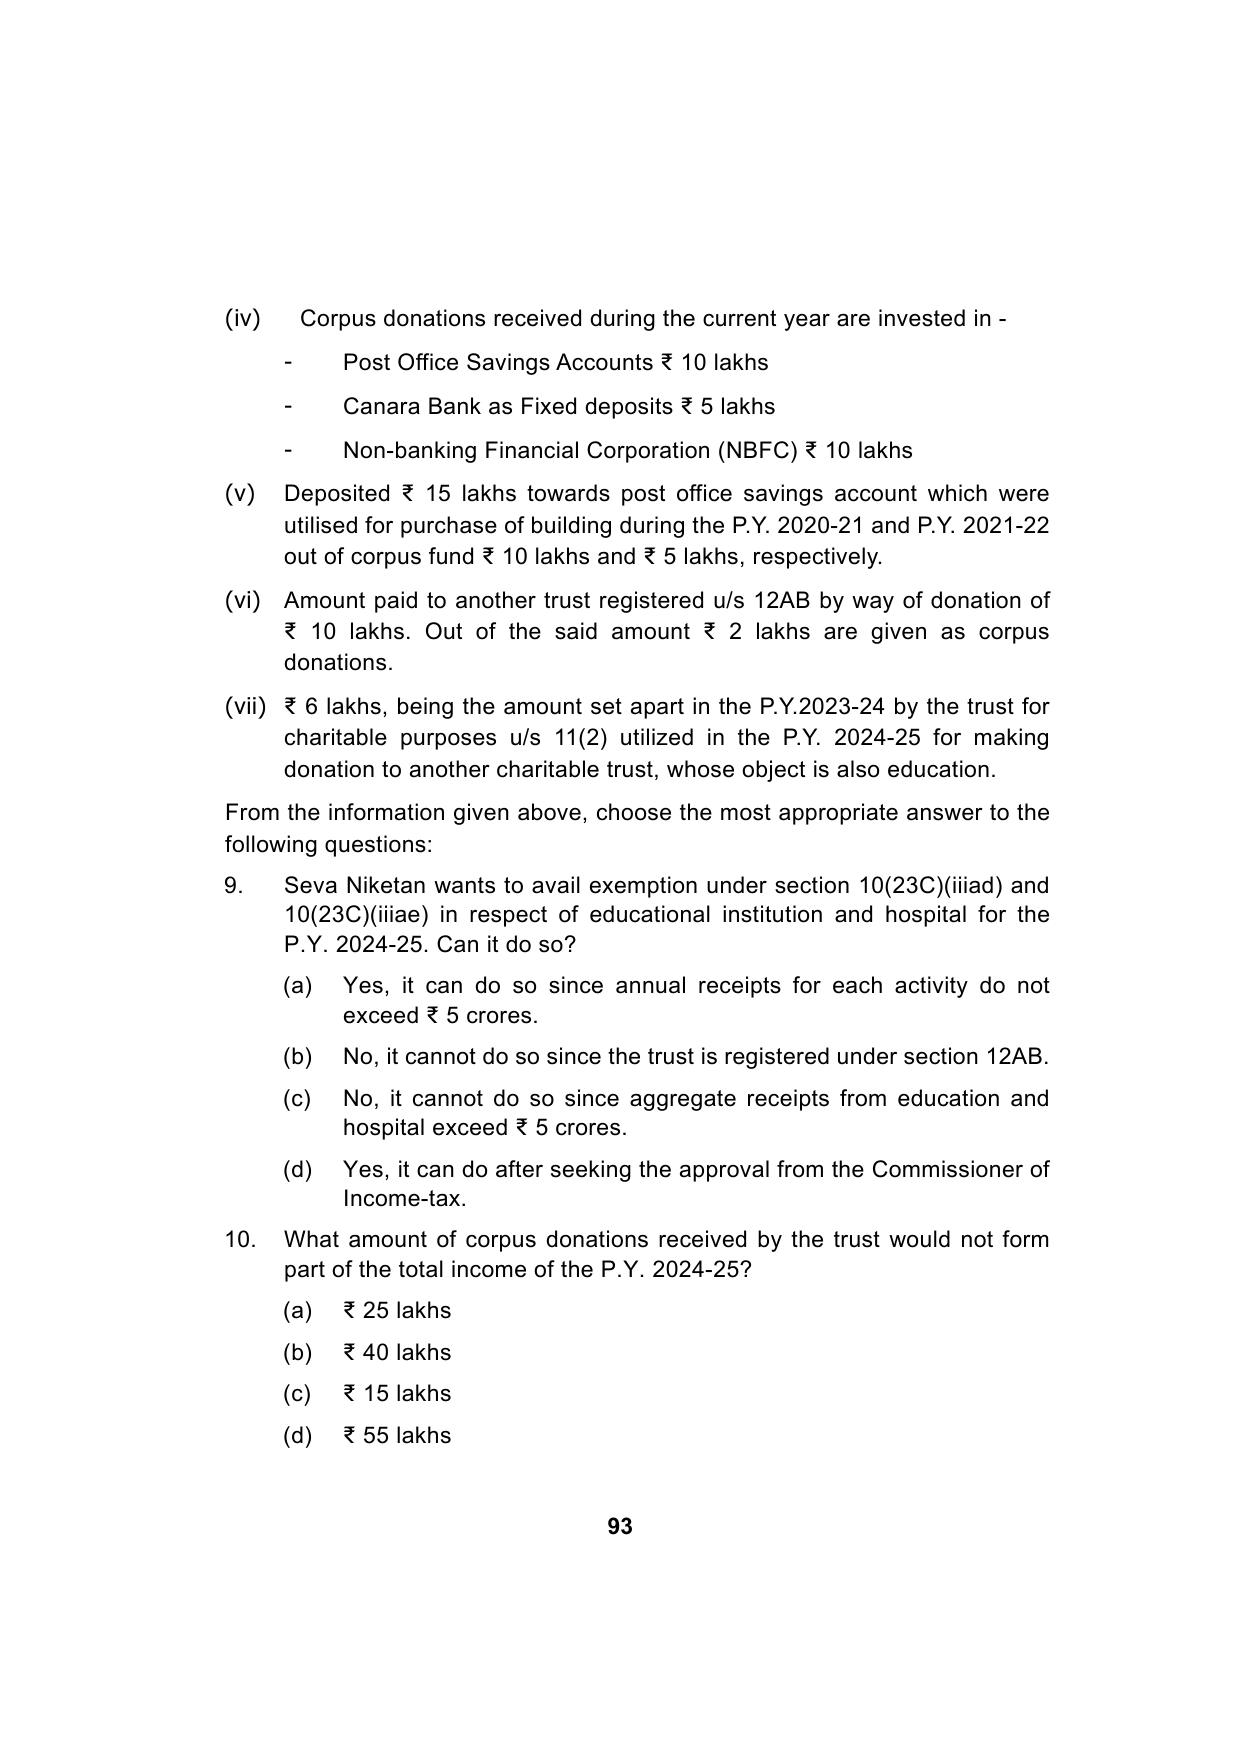
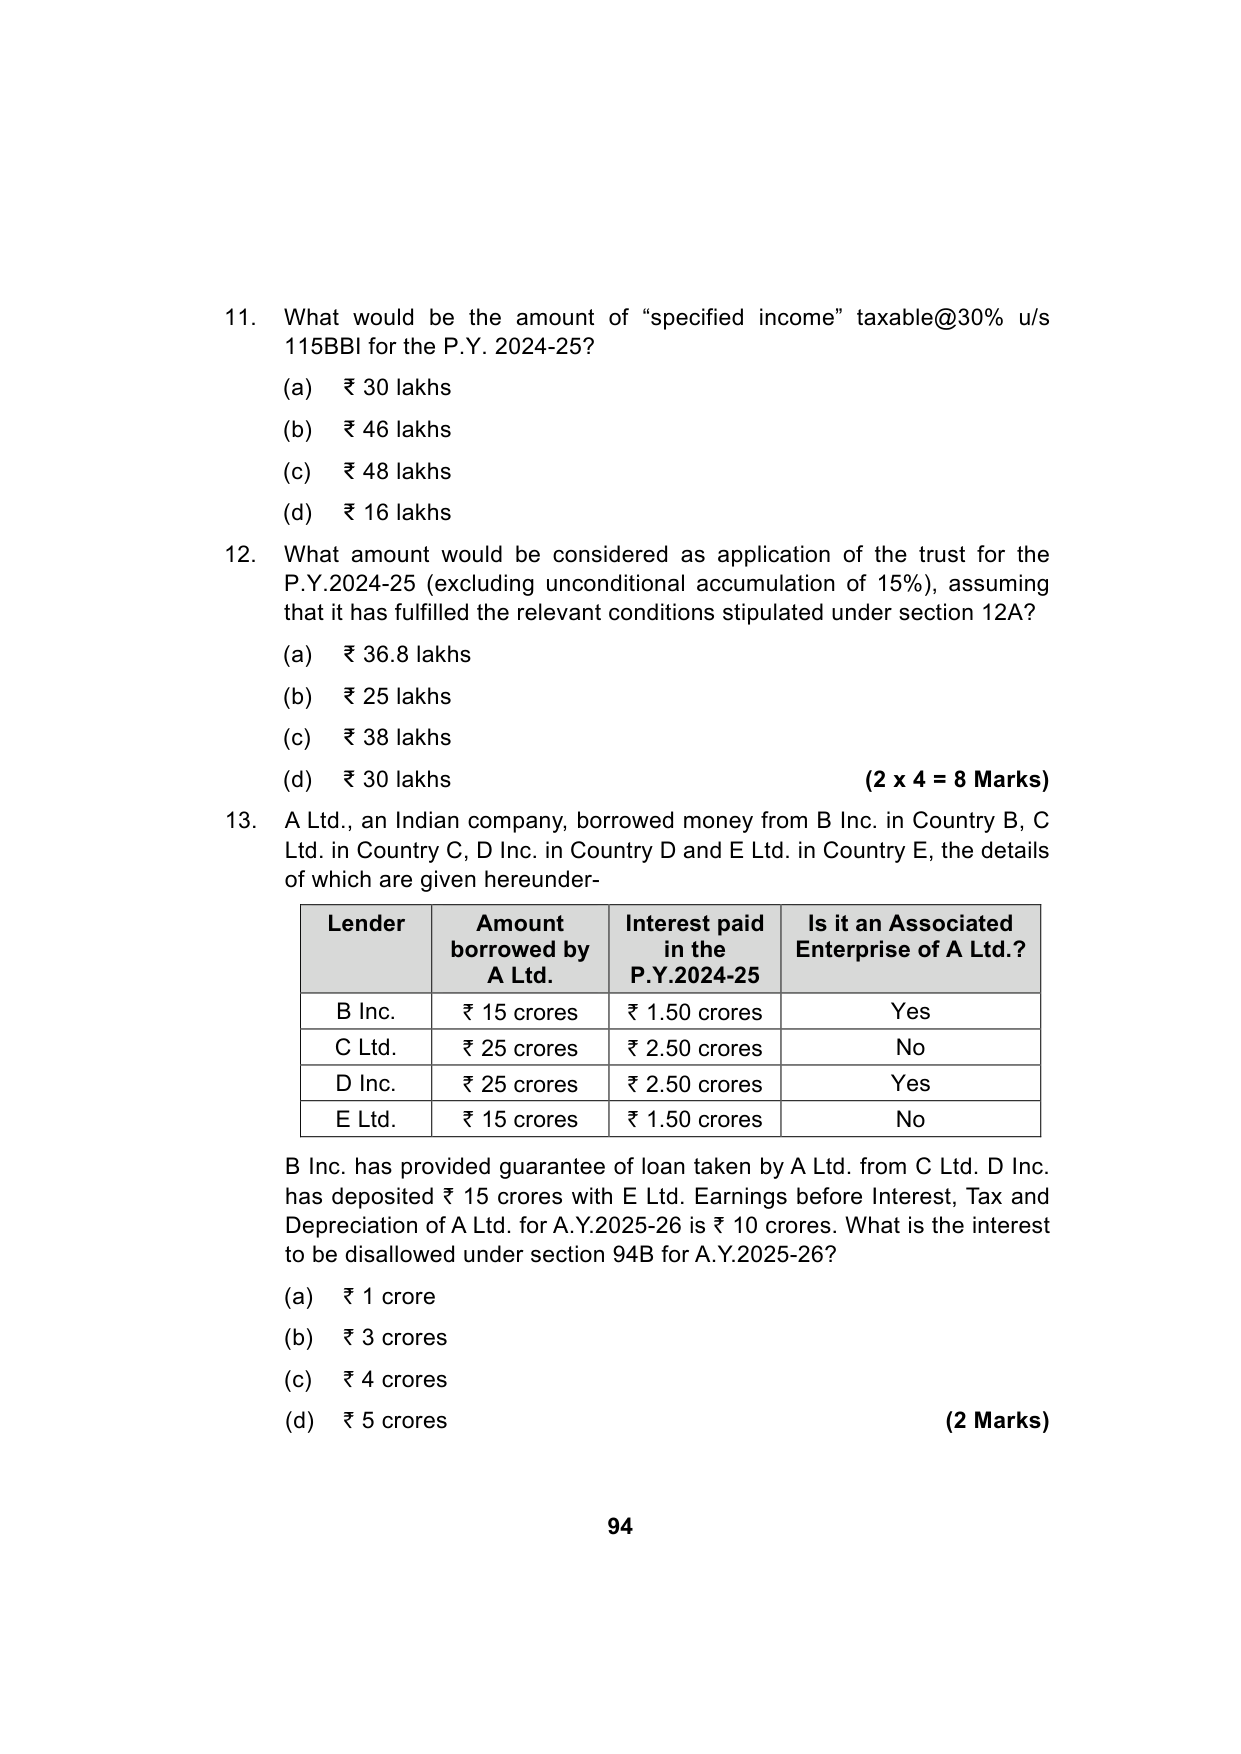
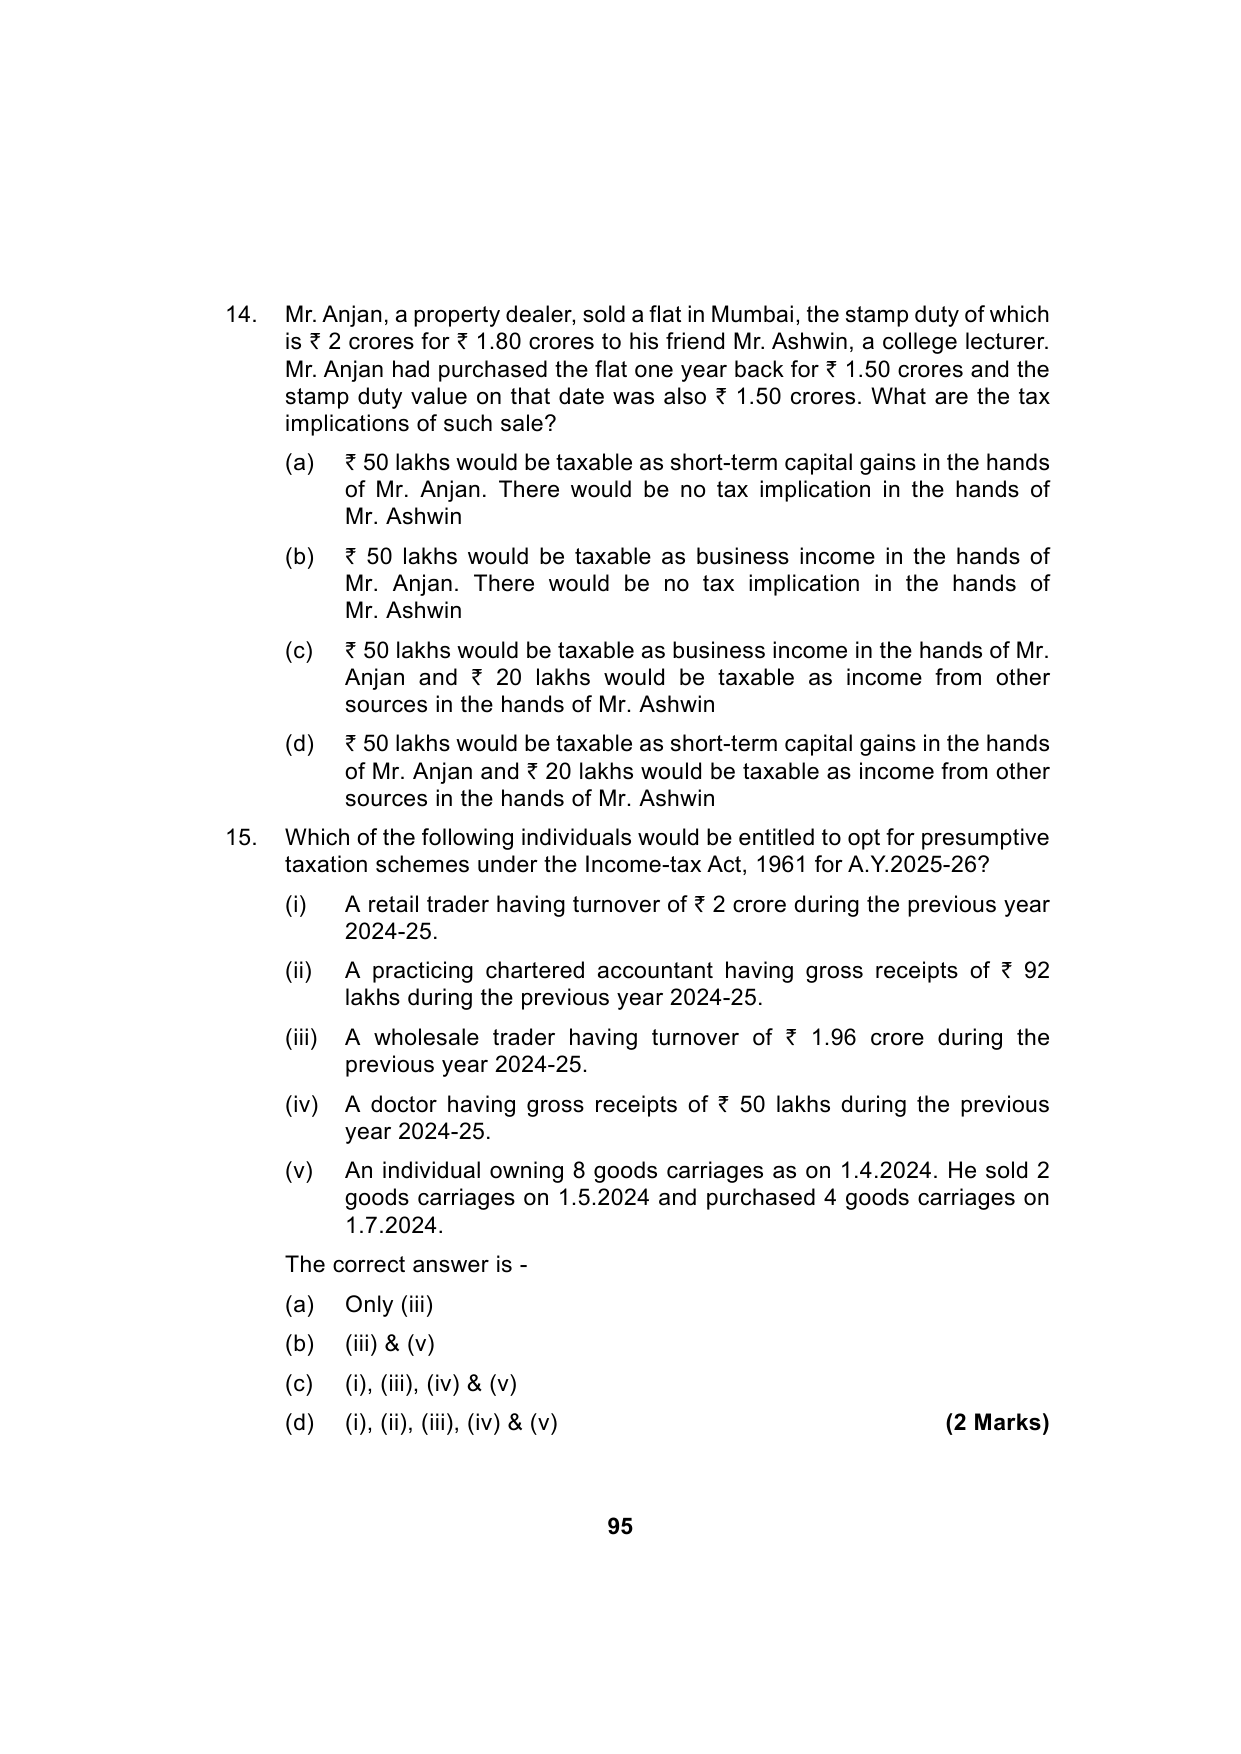
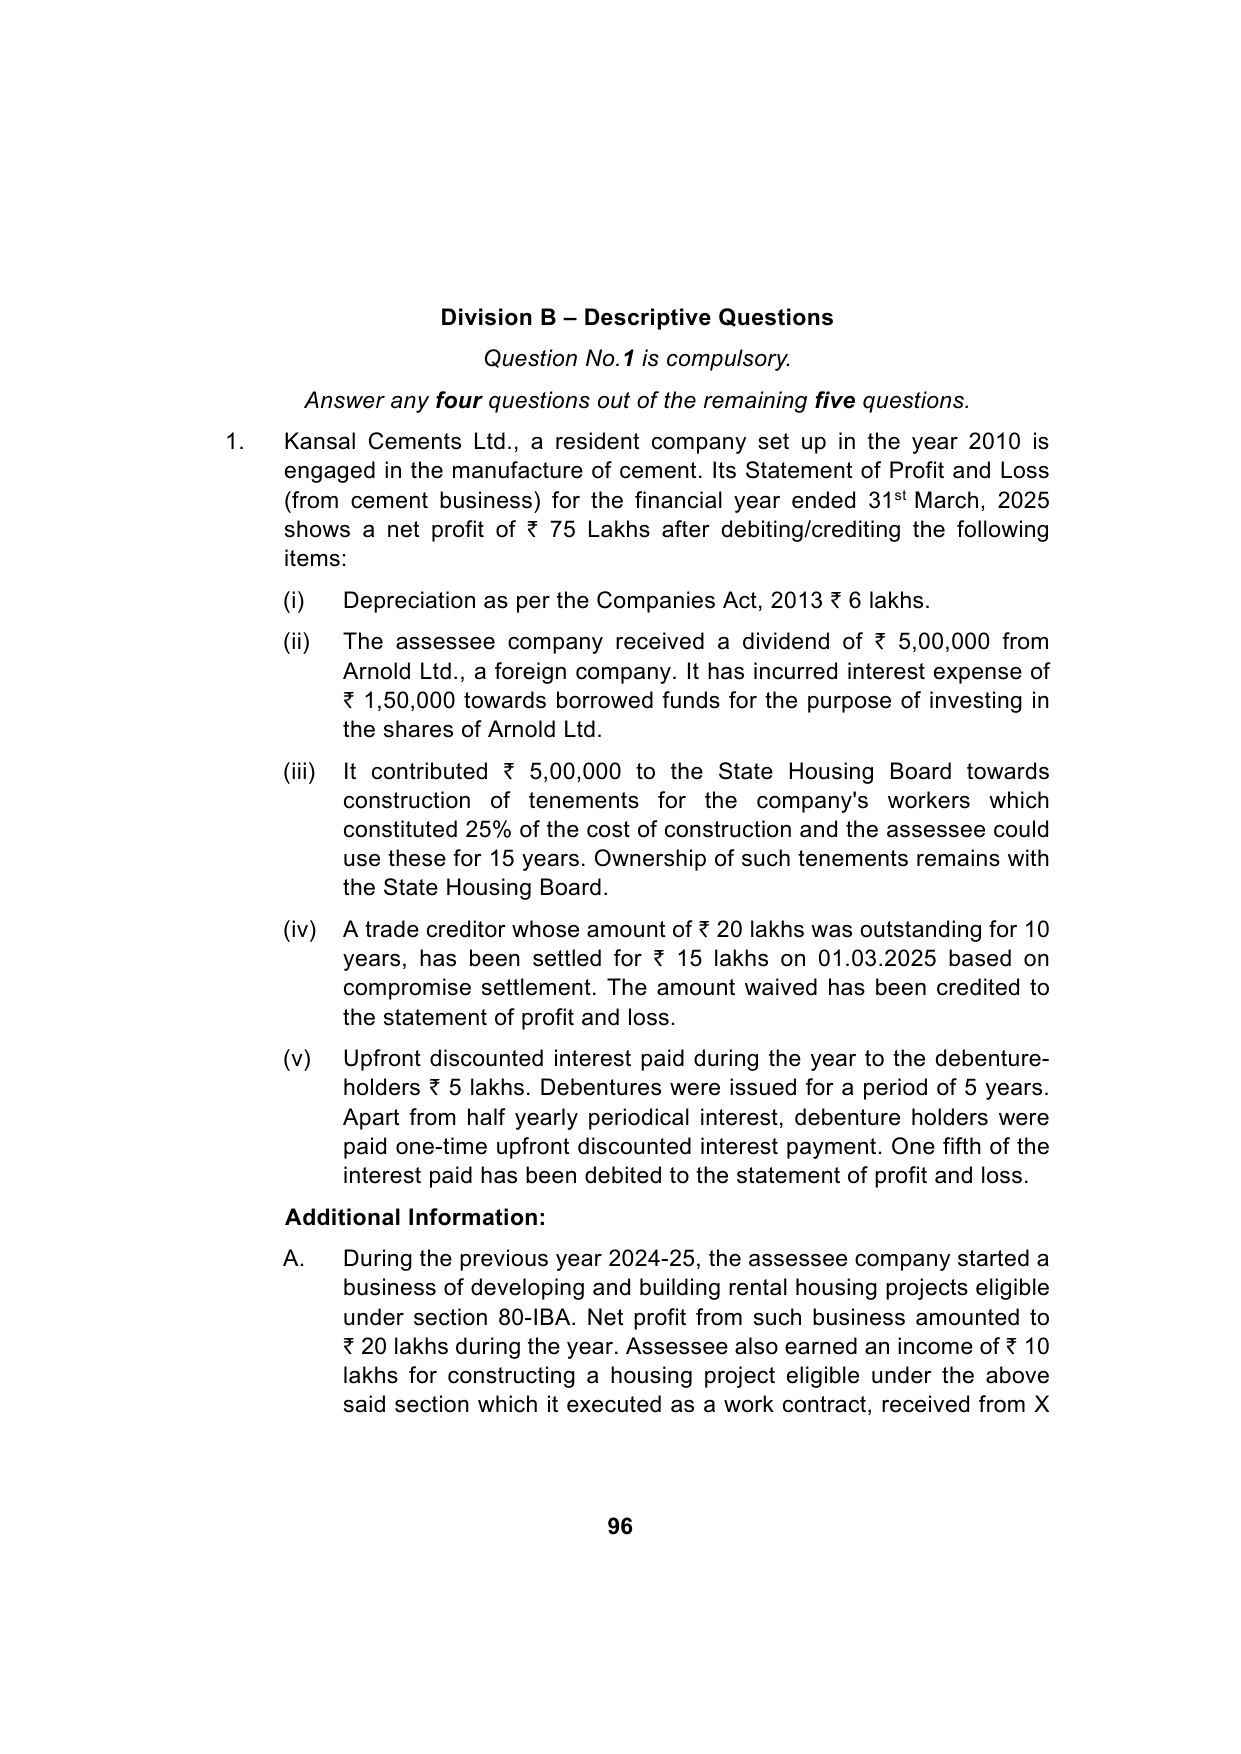
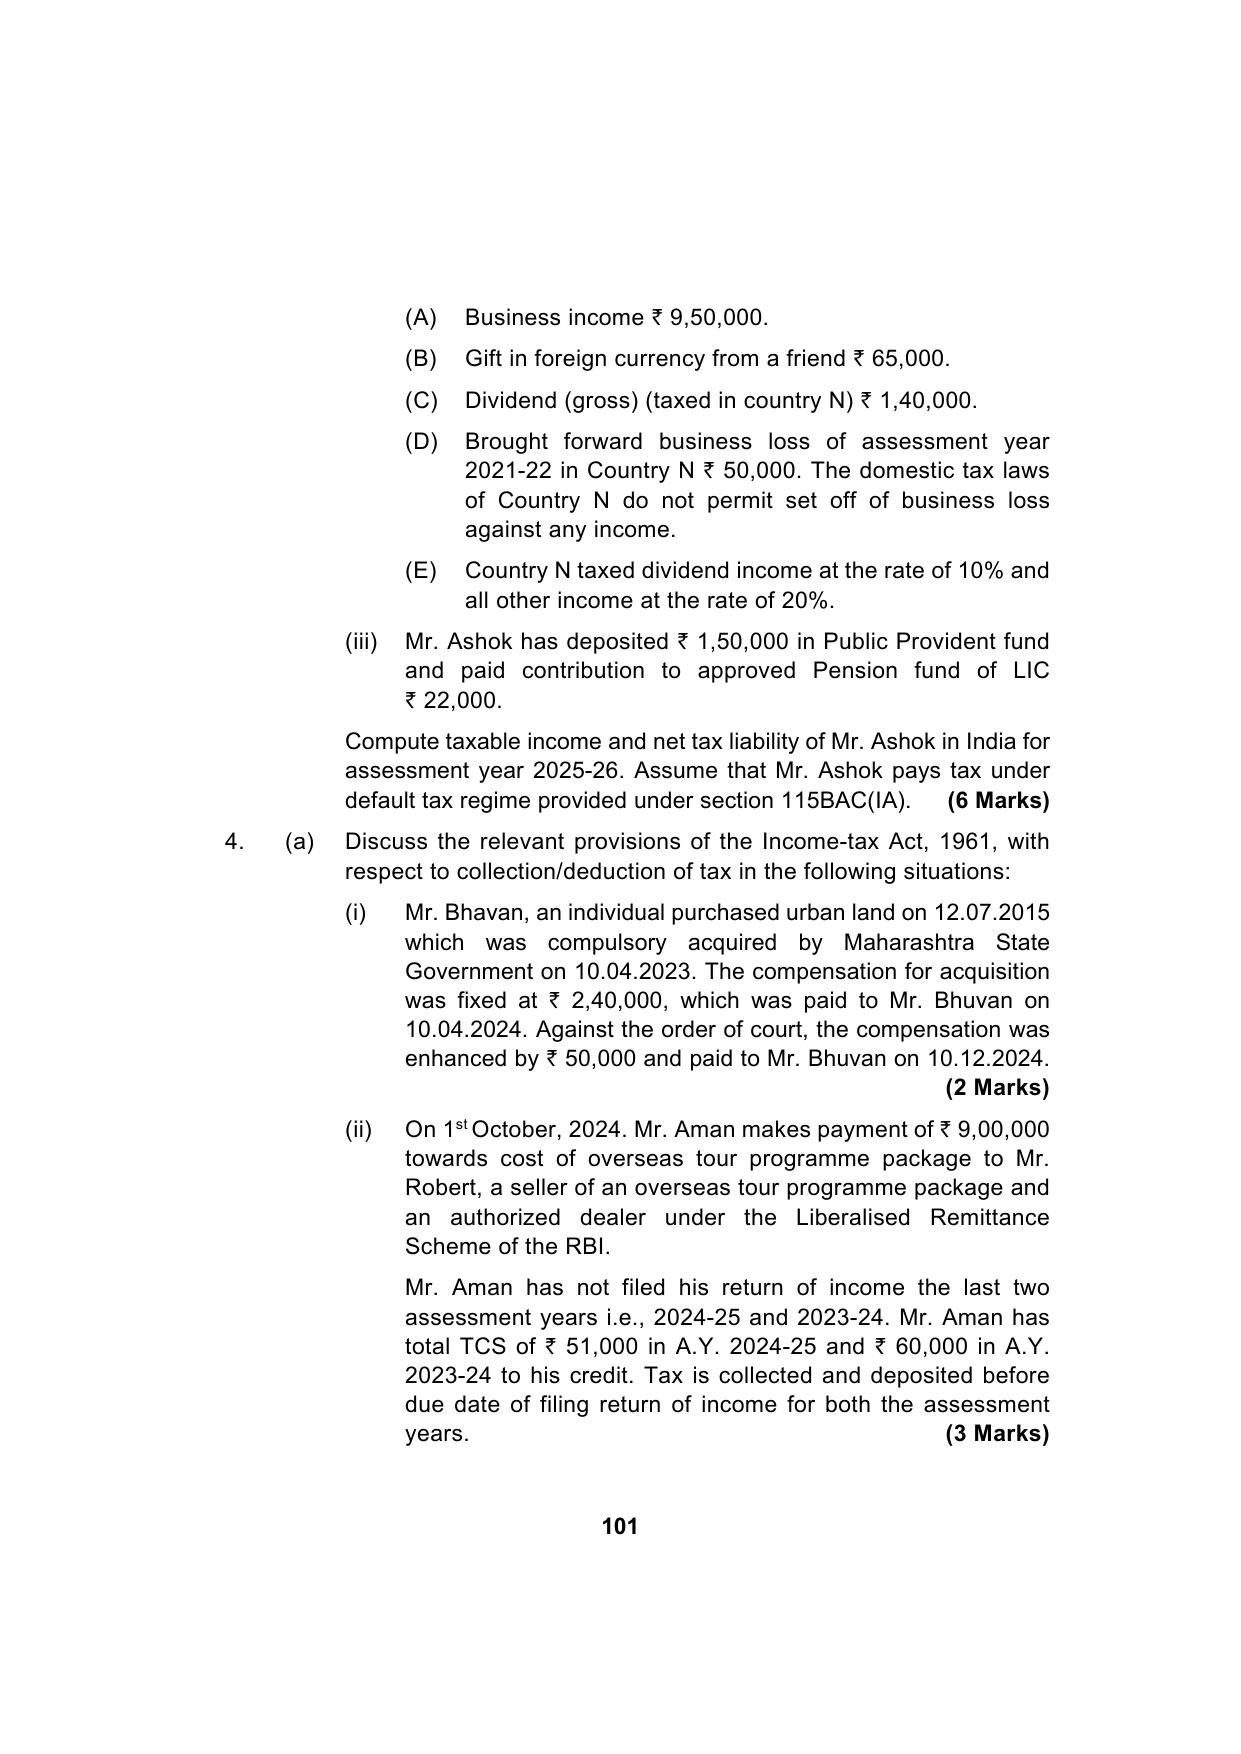
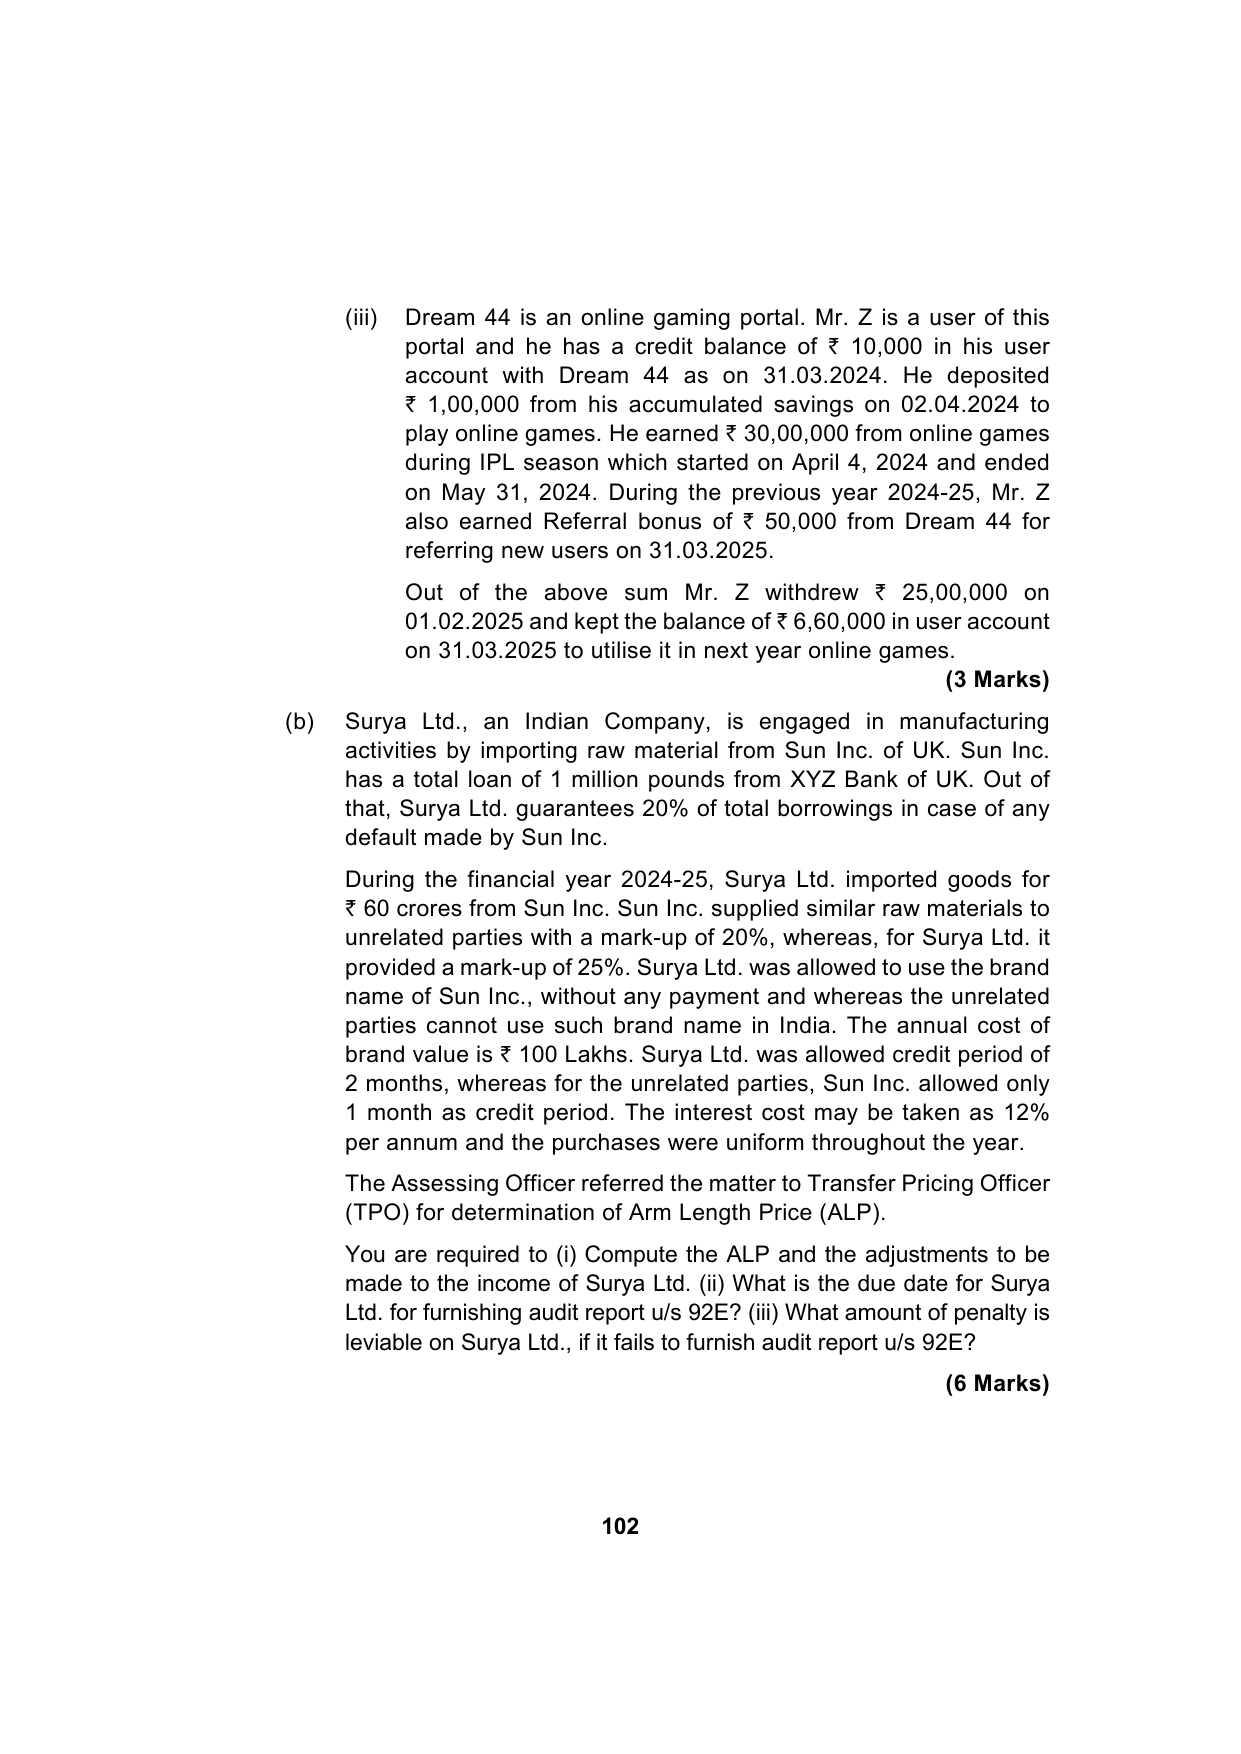
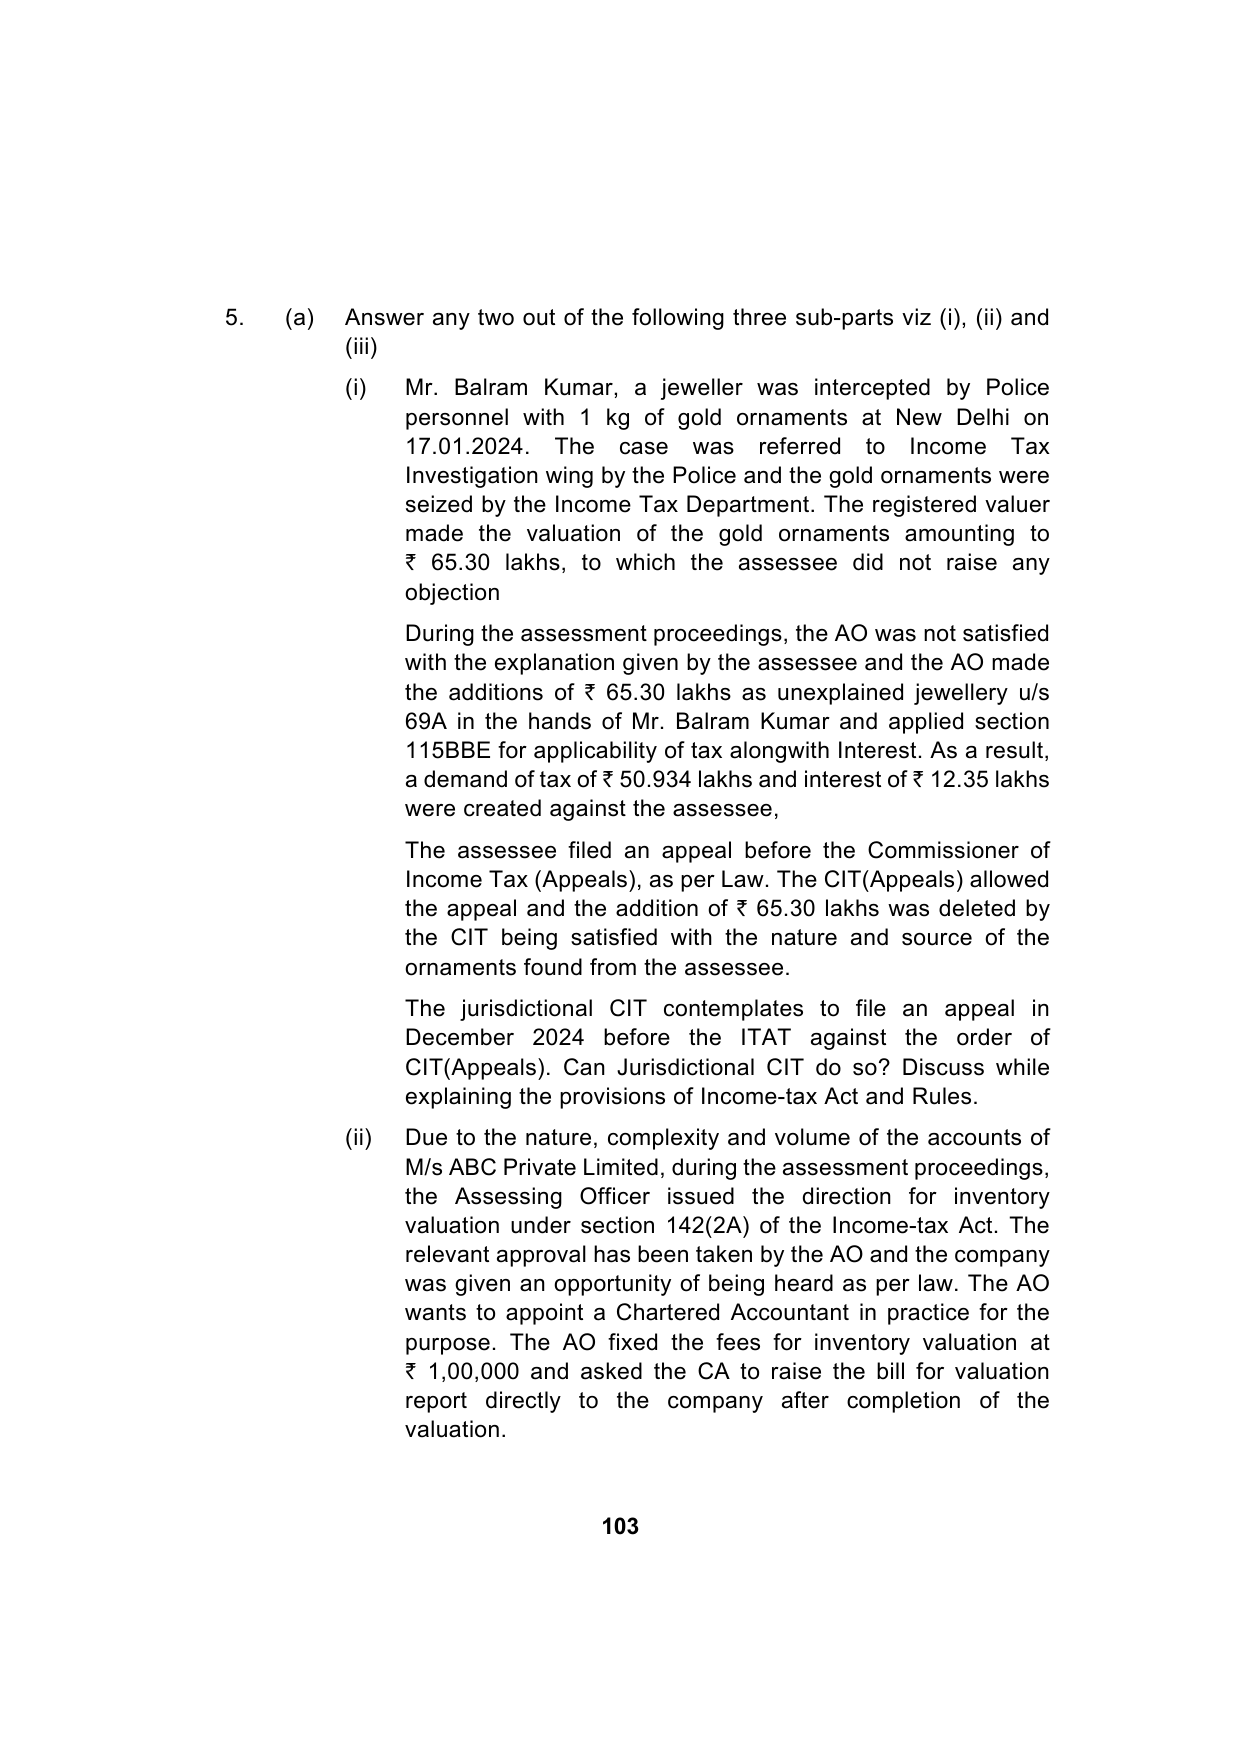
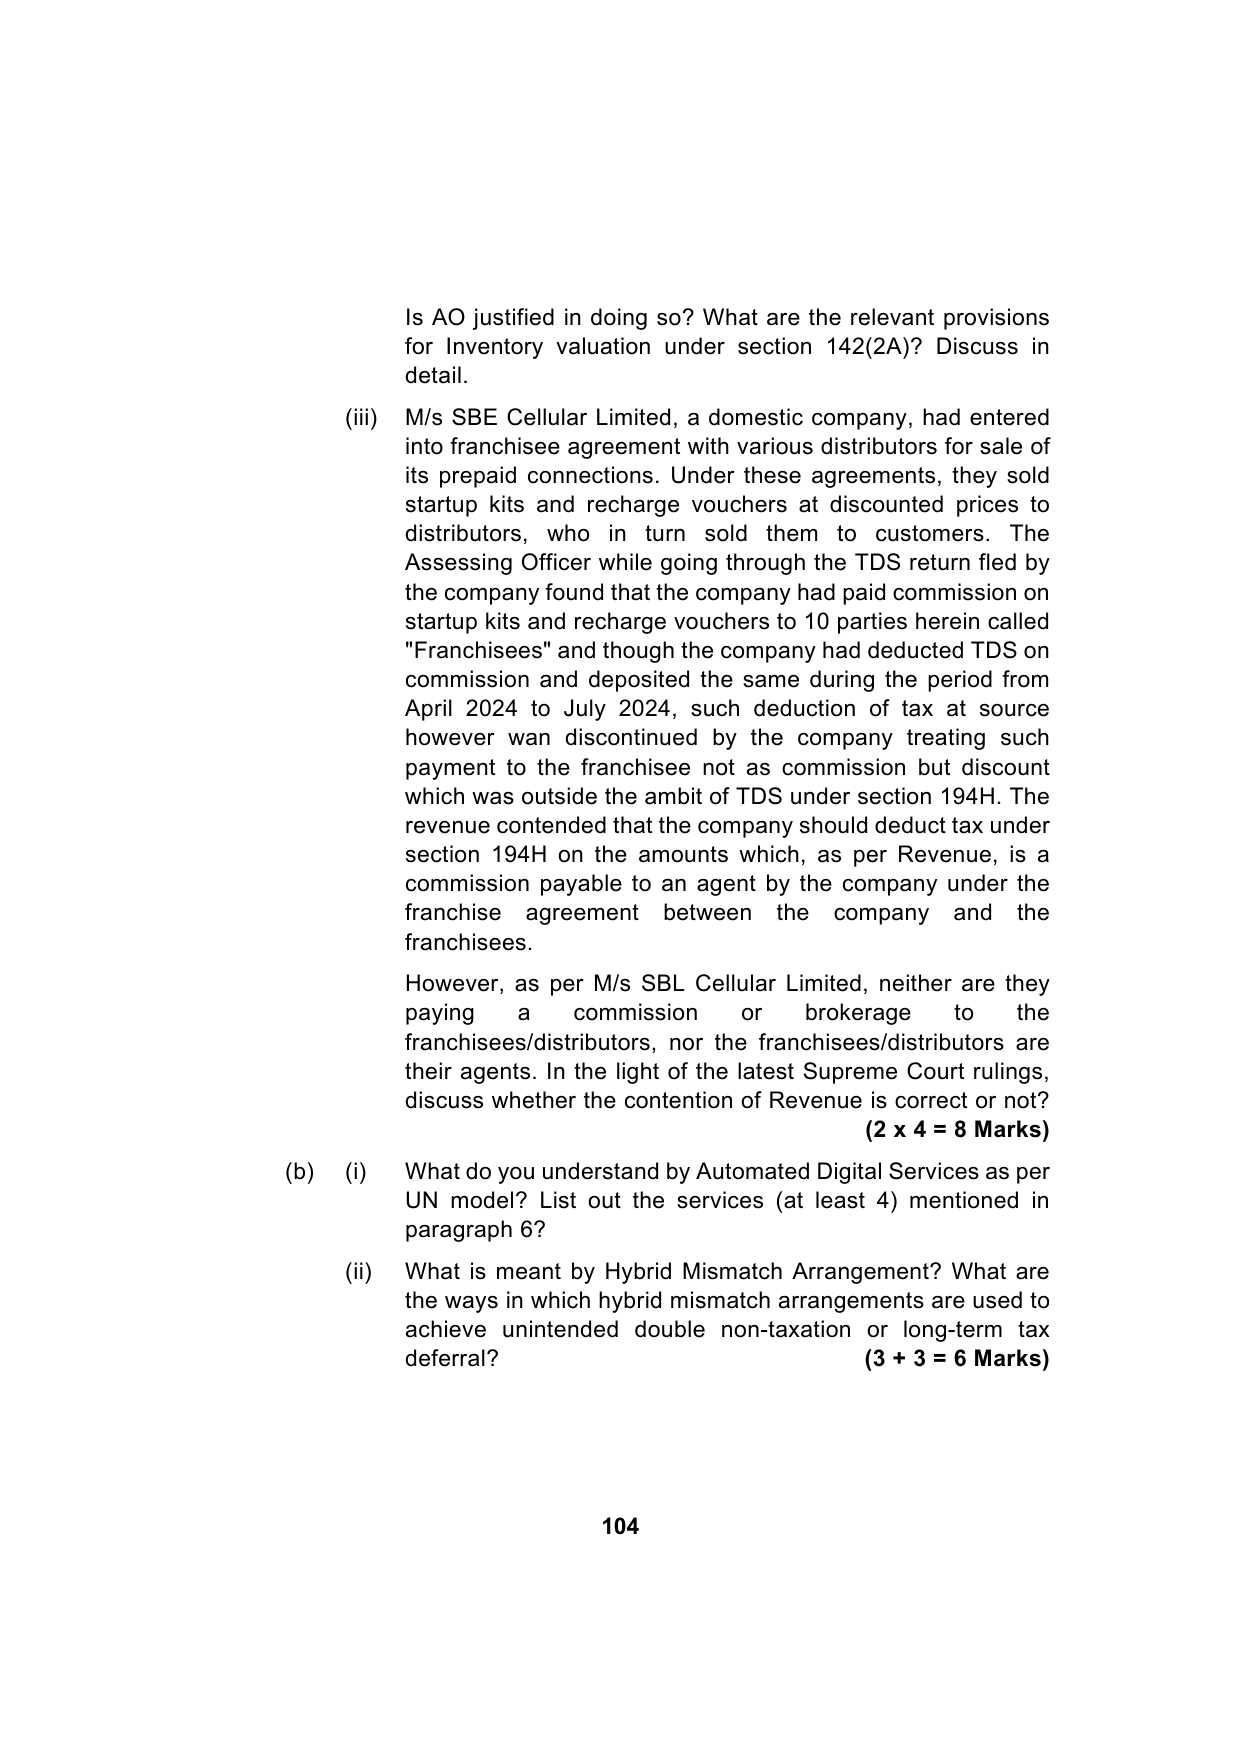
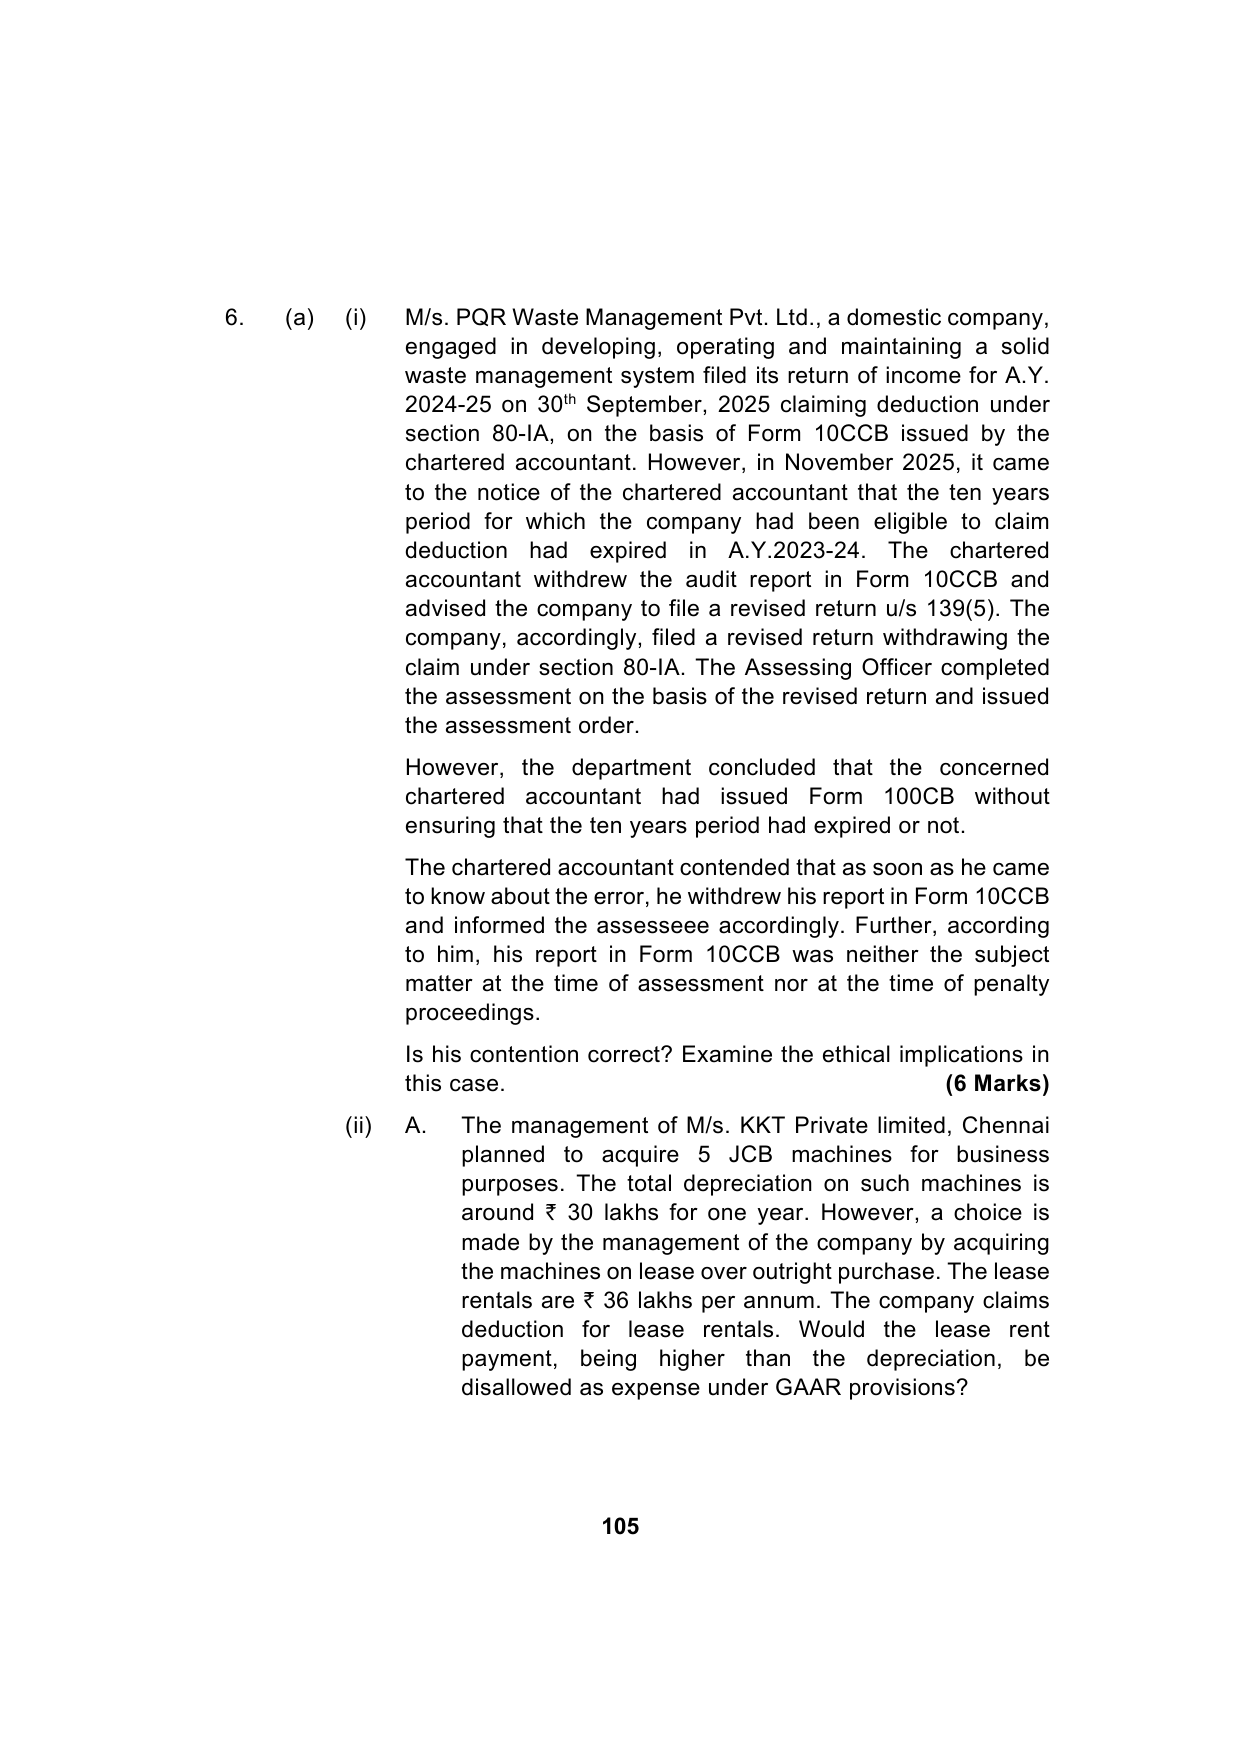
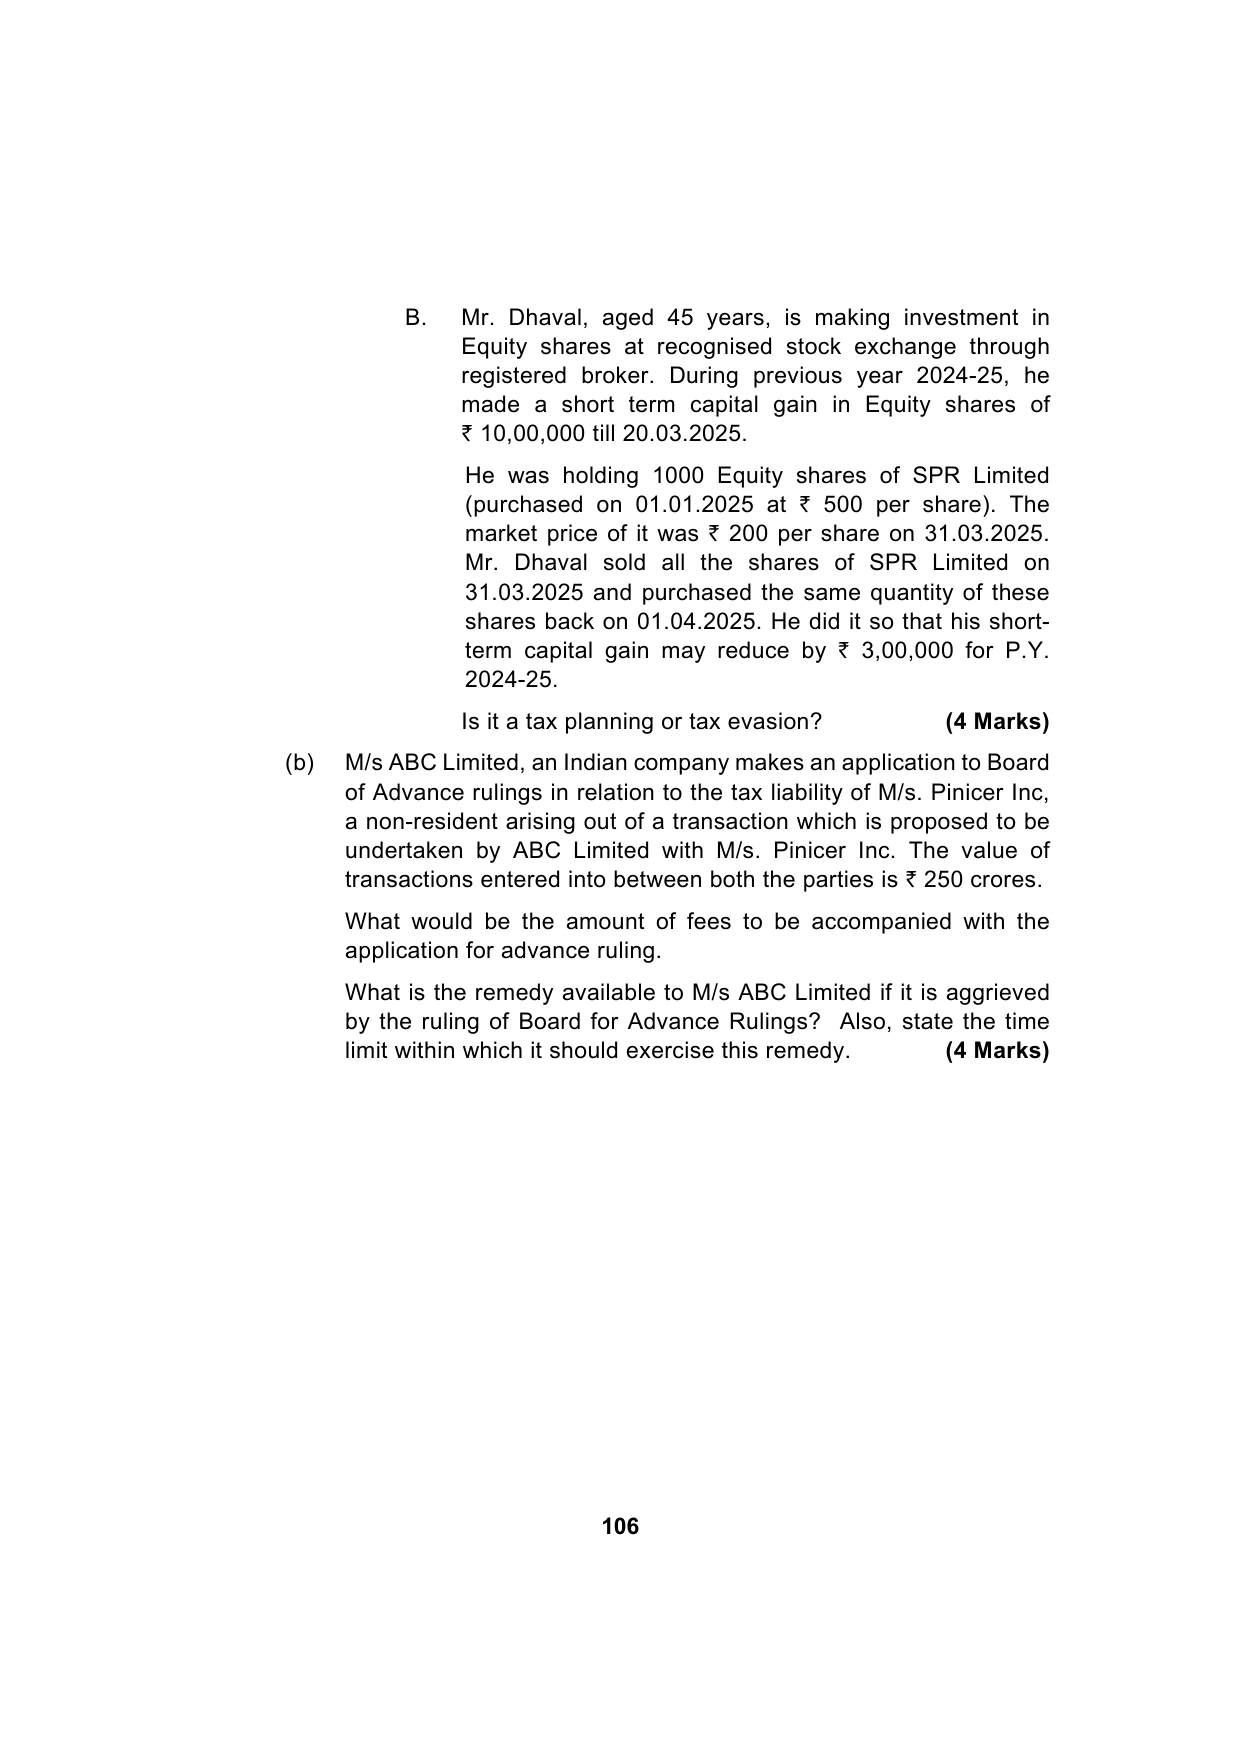
Paper 5: Indirect Tax Laws — Model Test Paper 1
Question
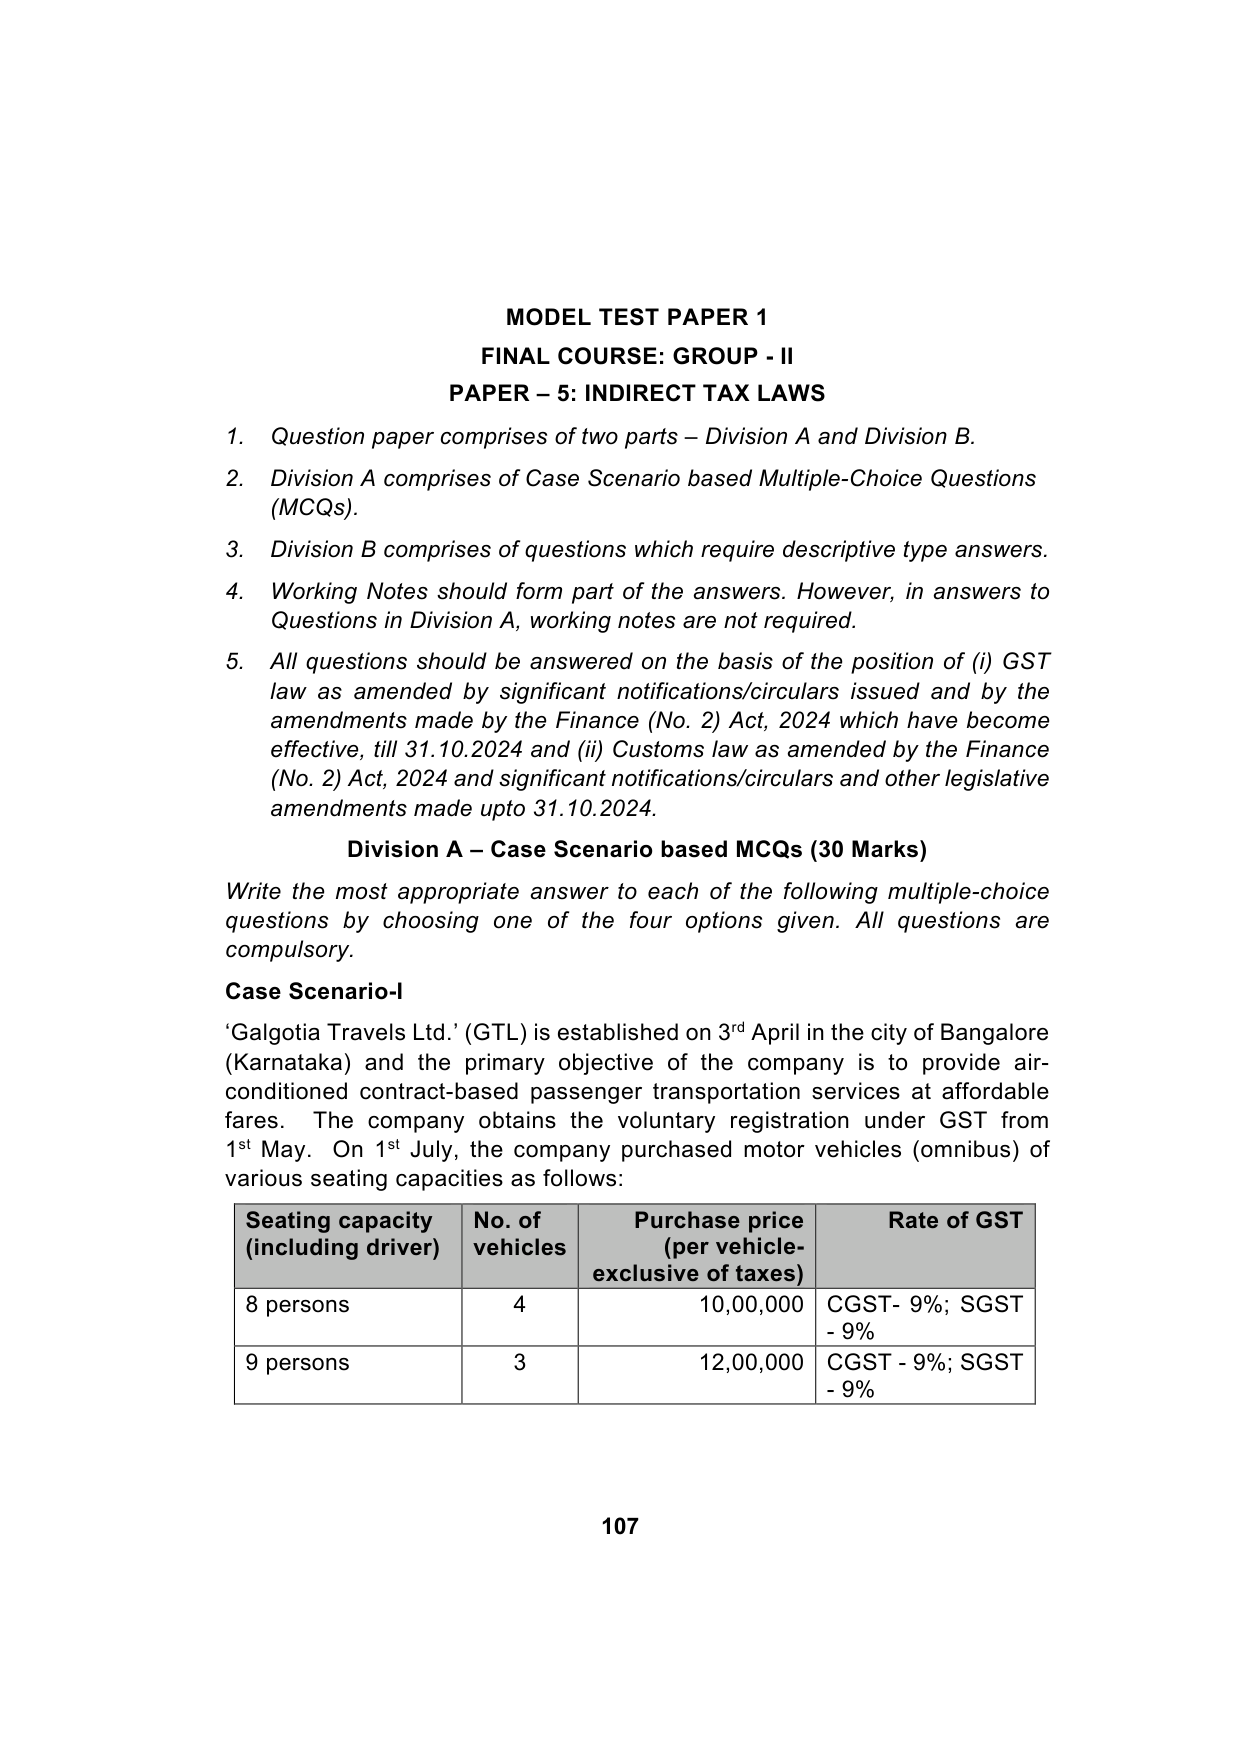
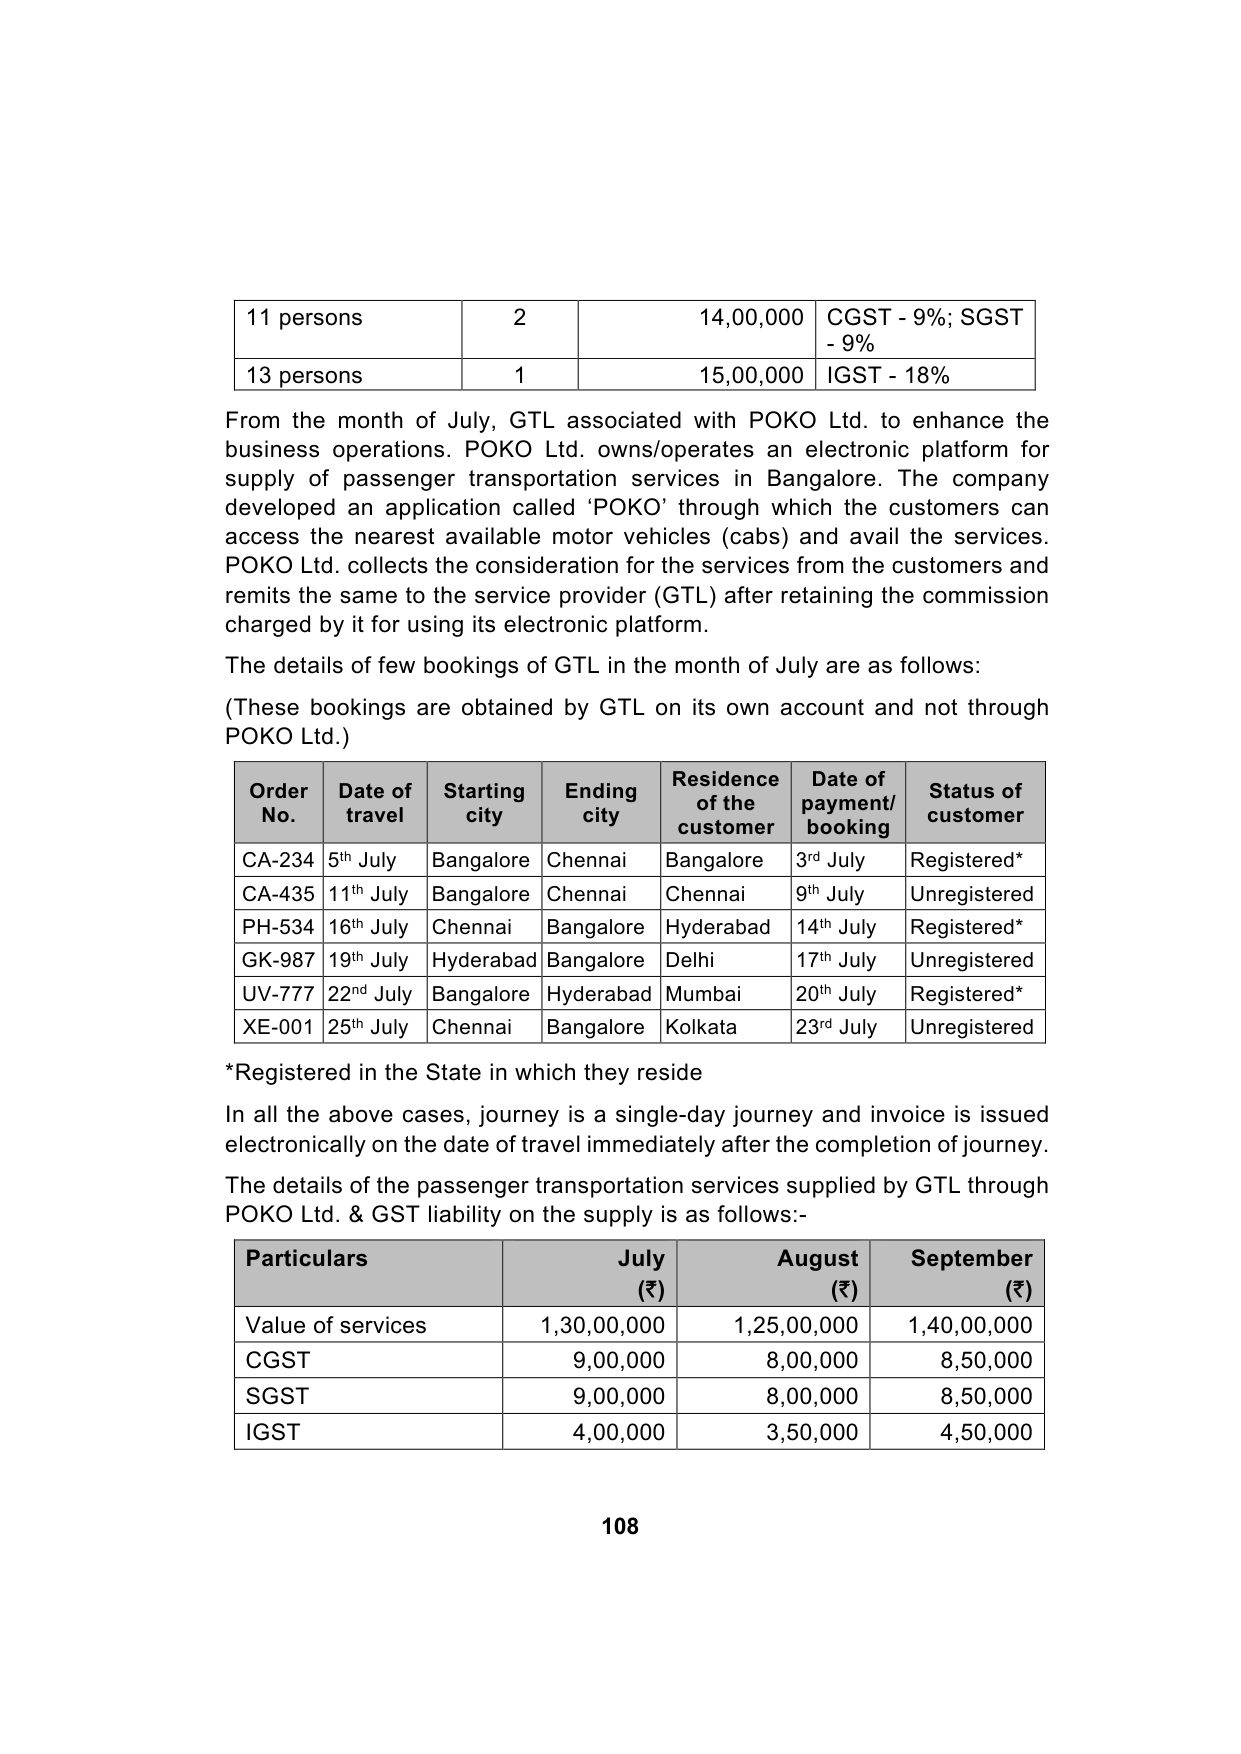
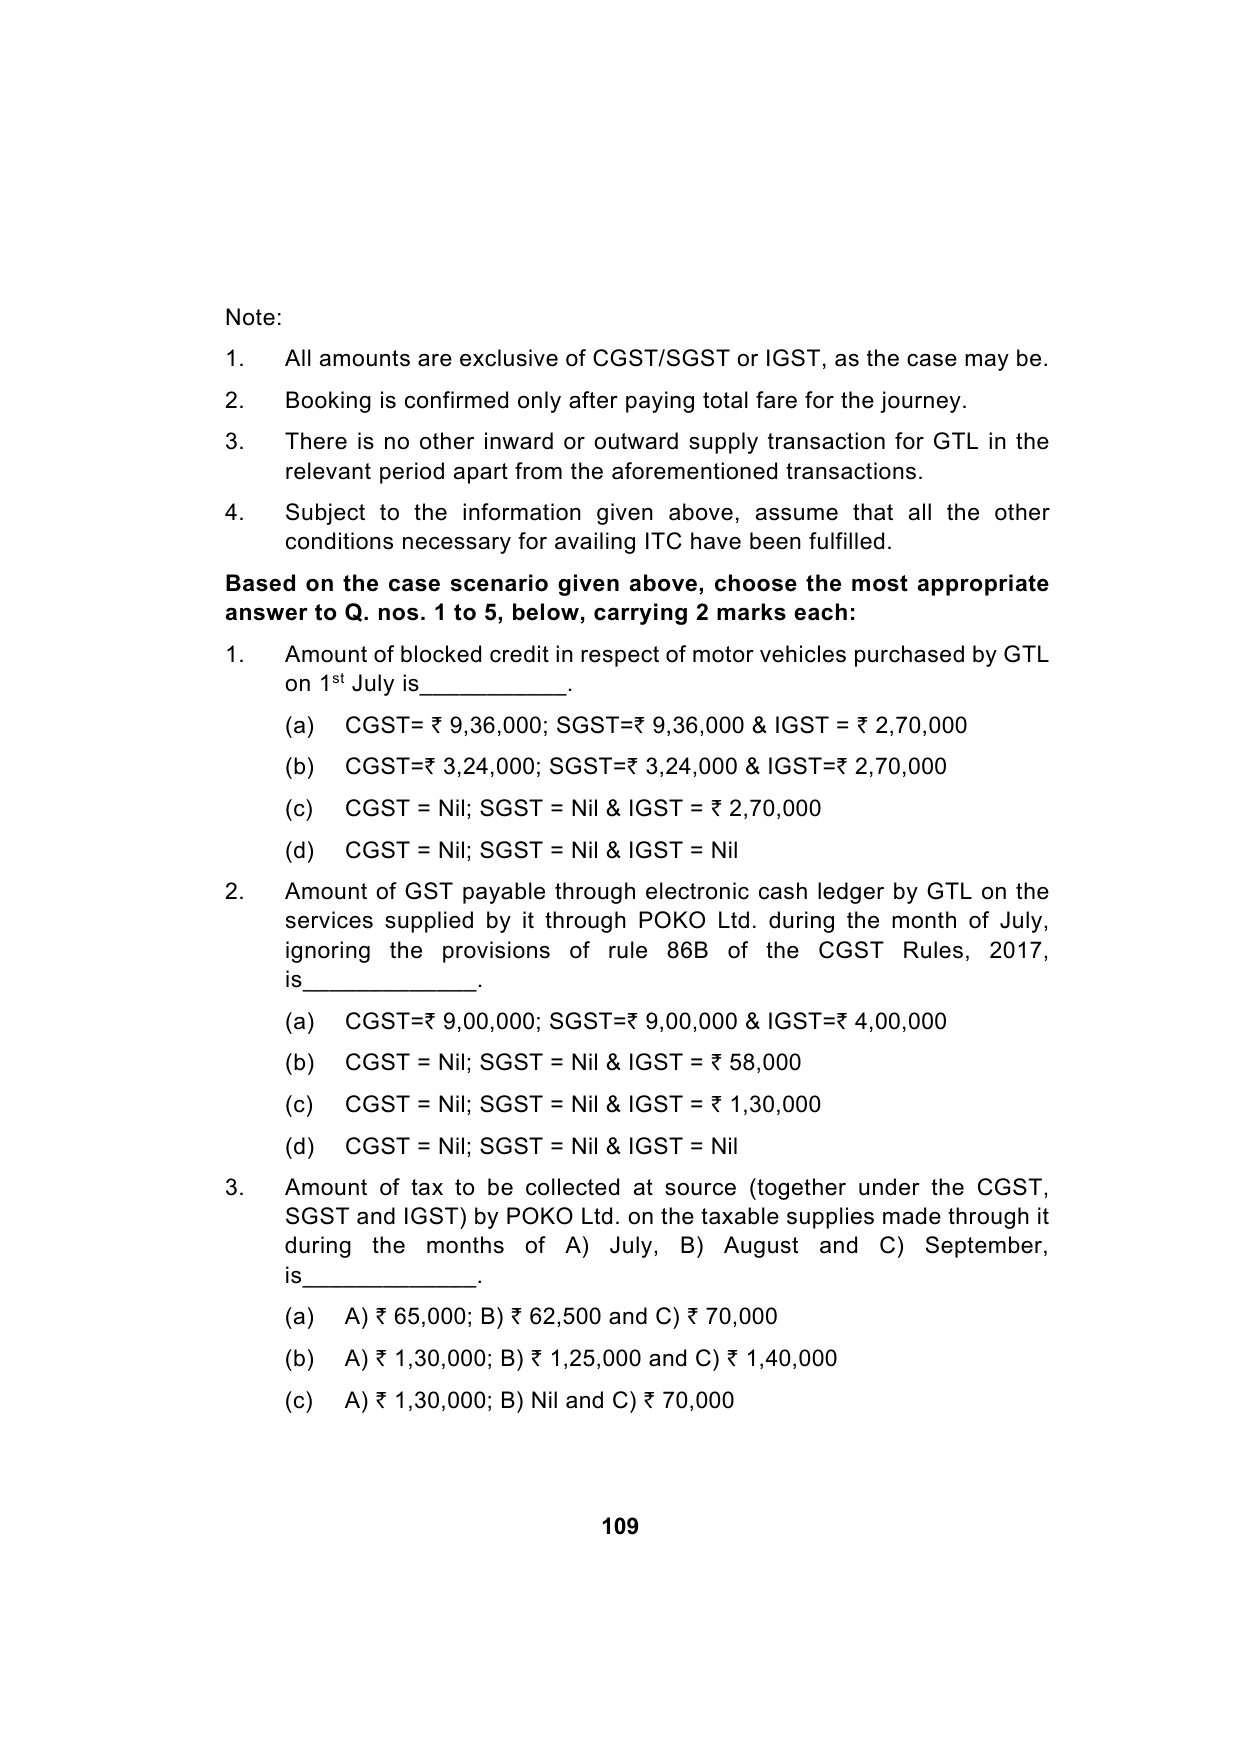
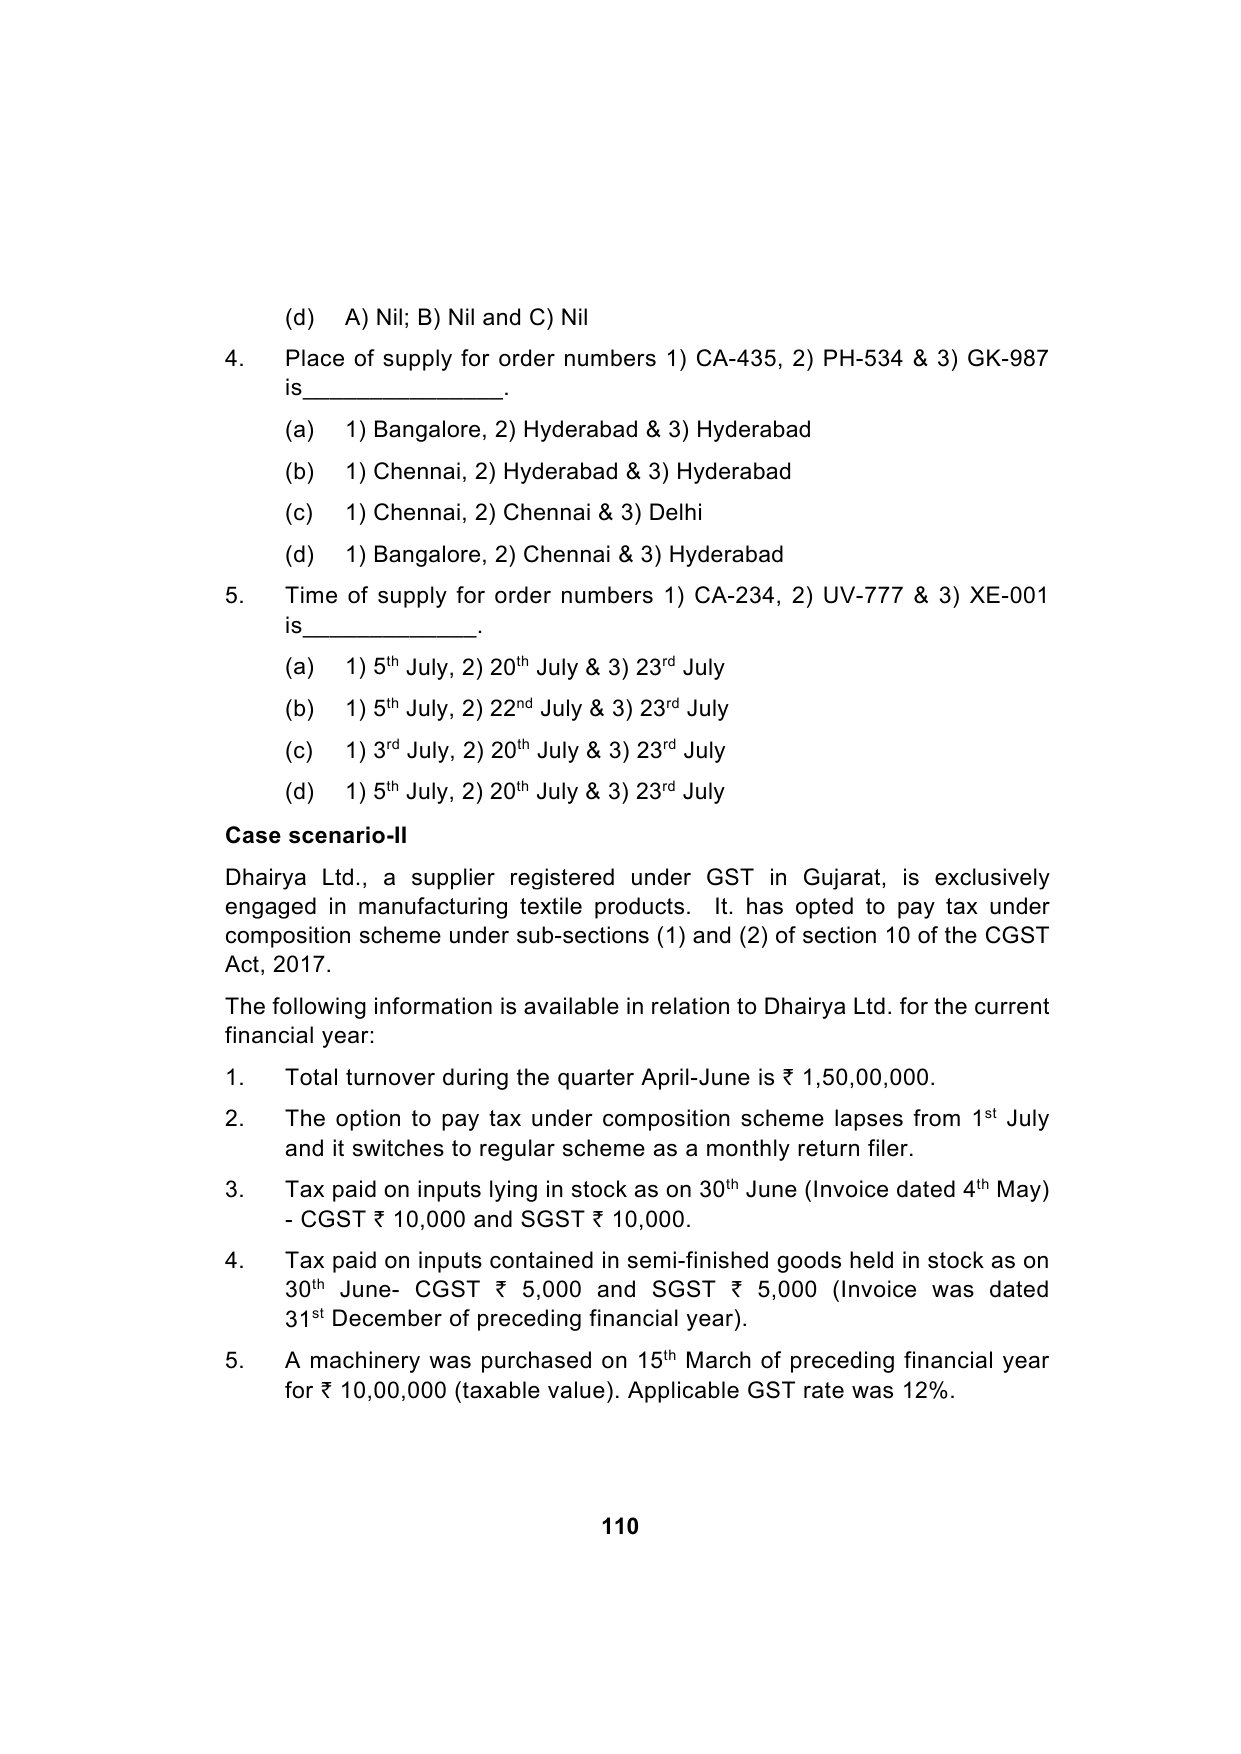
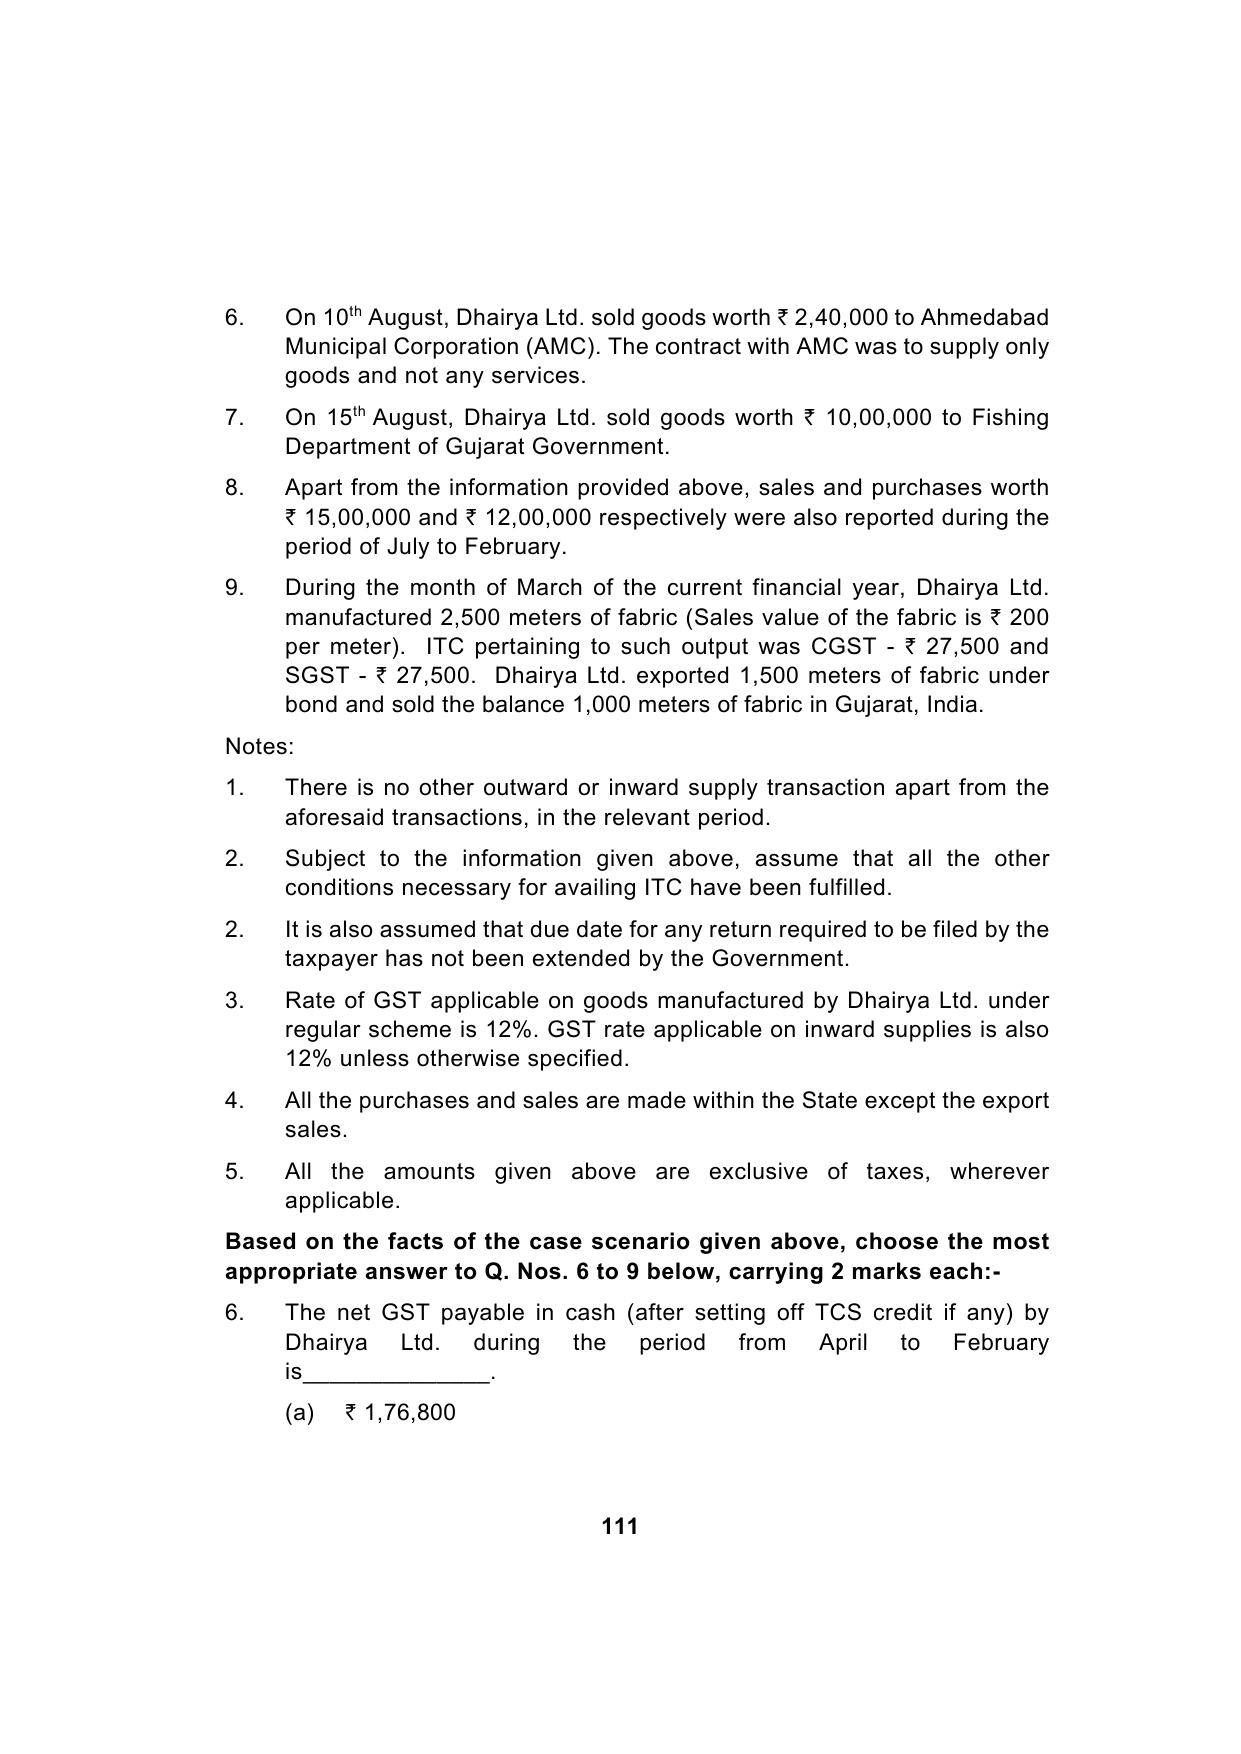
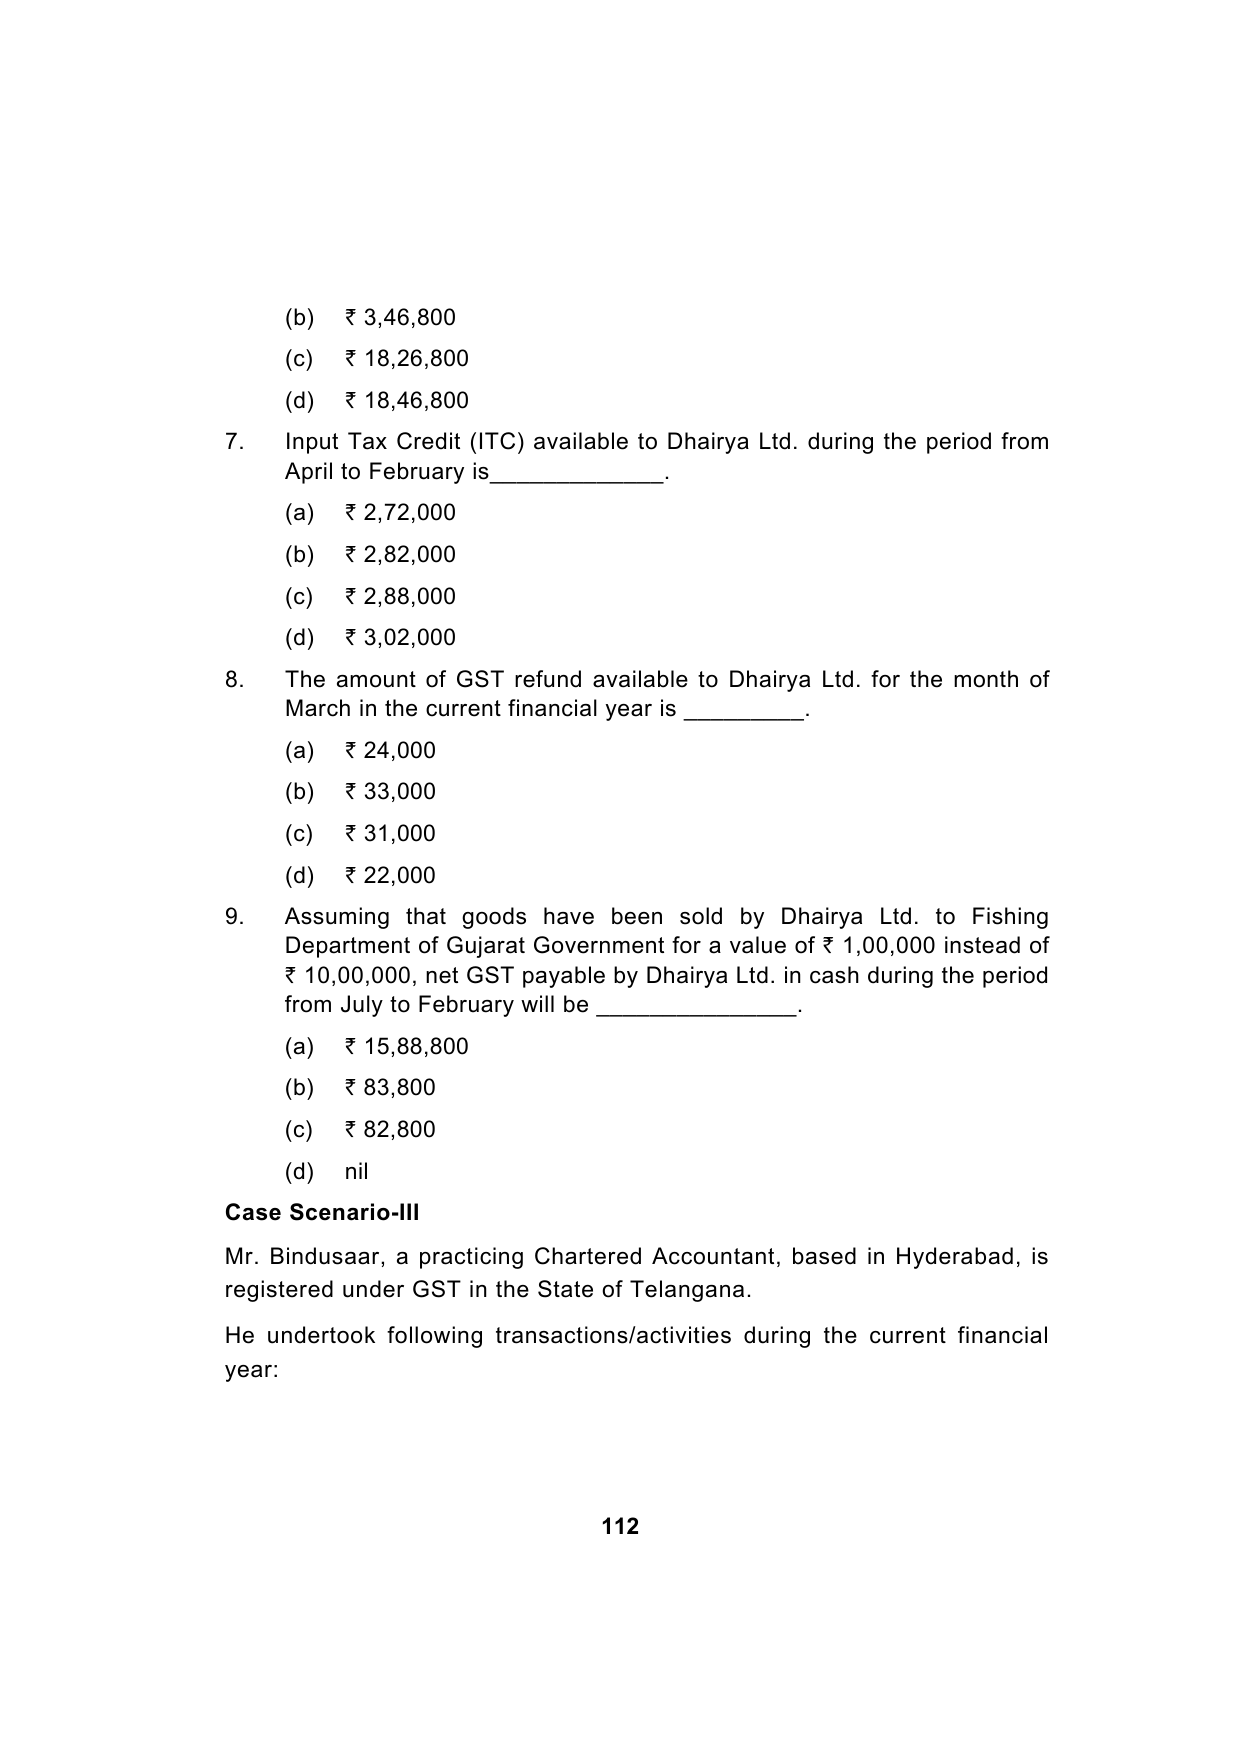
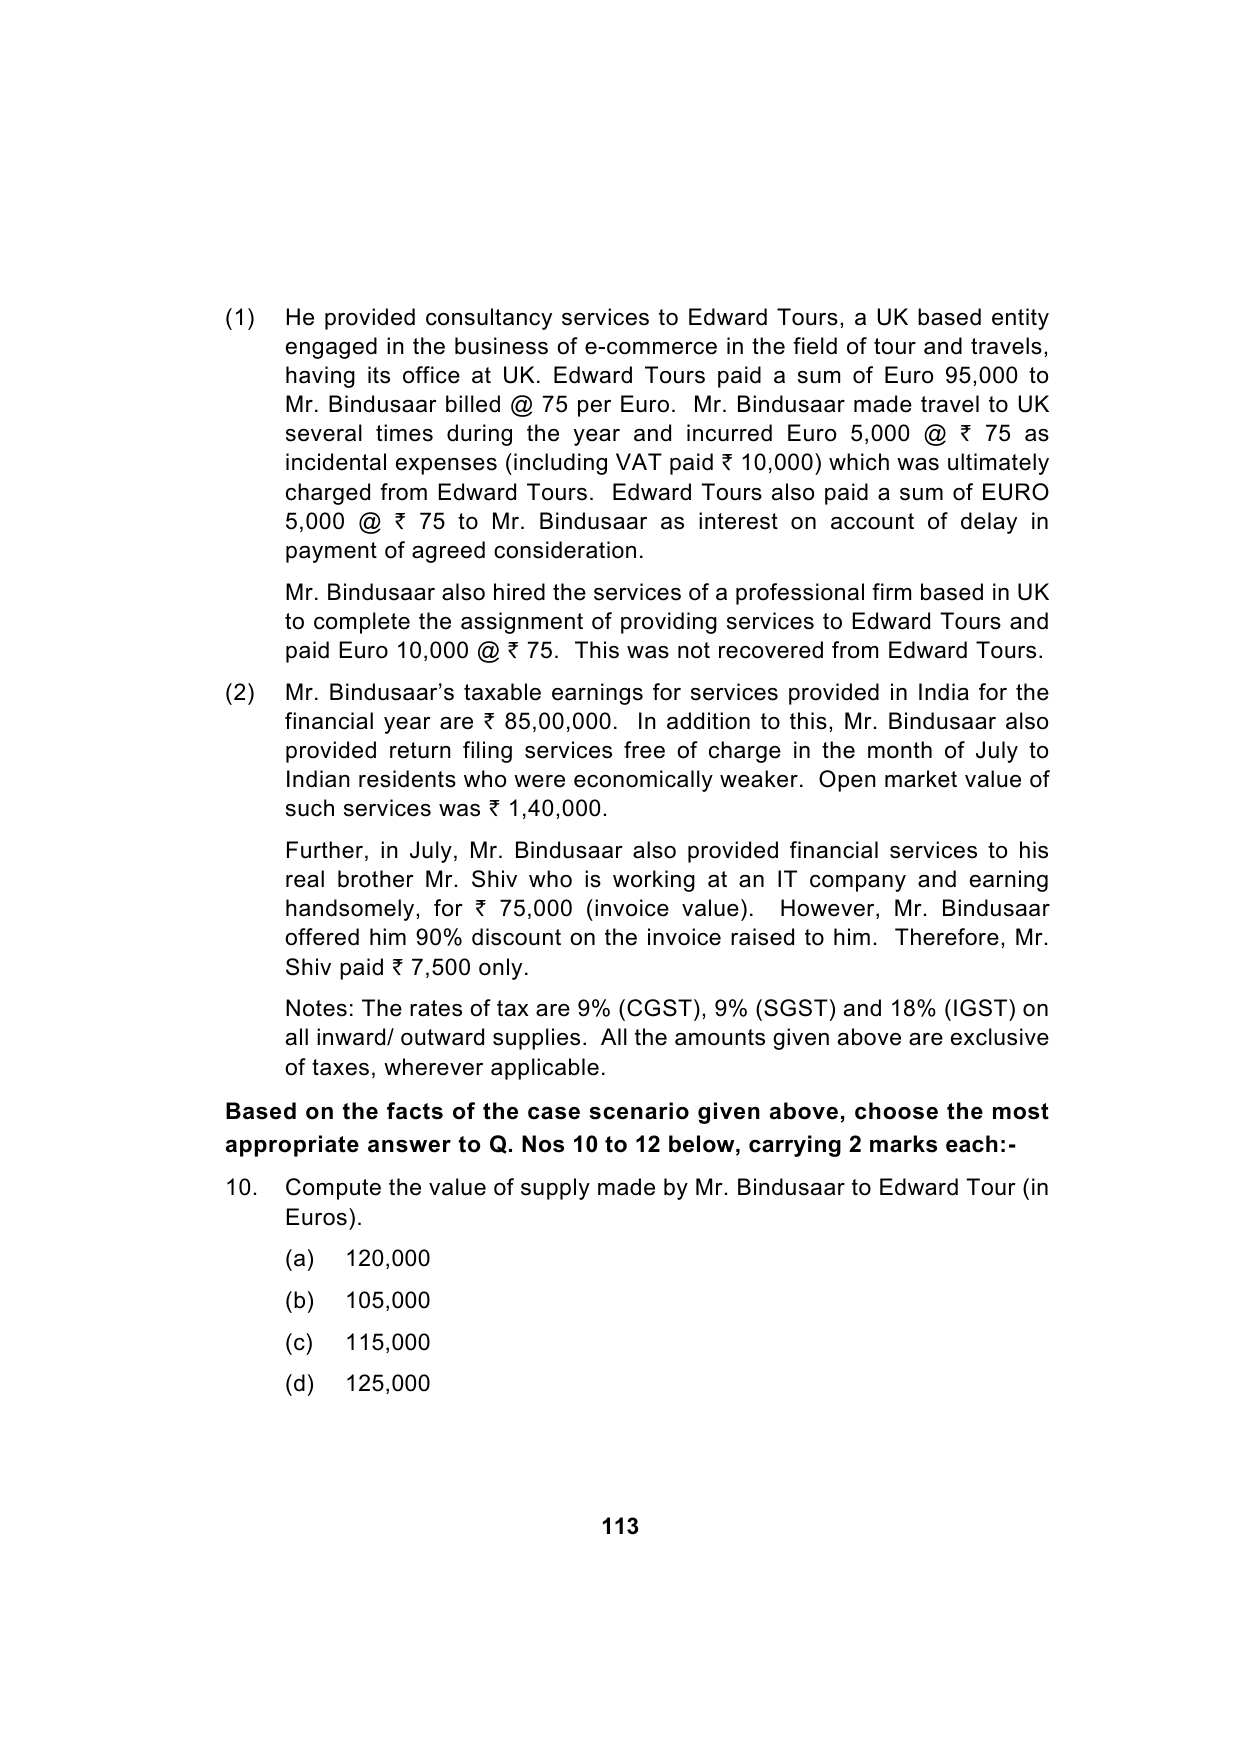
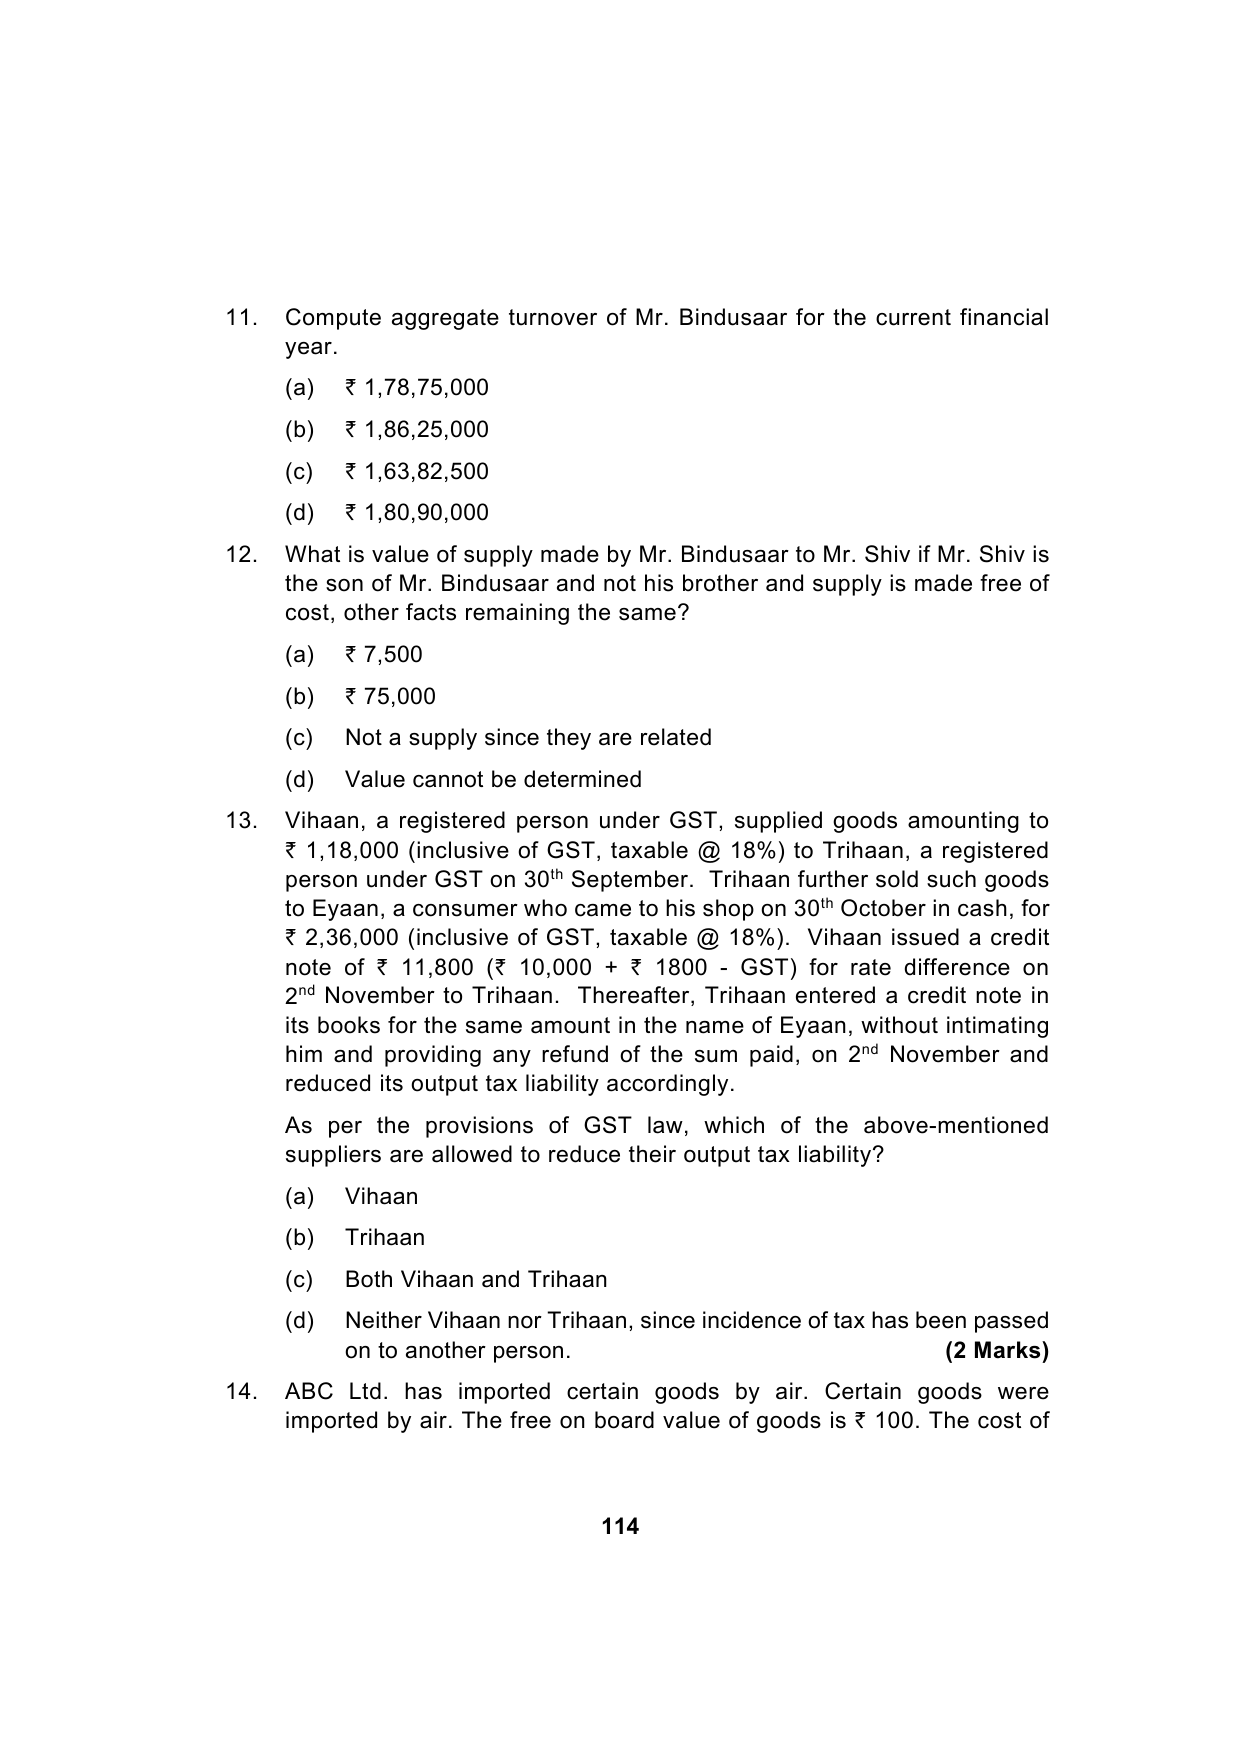
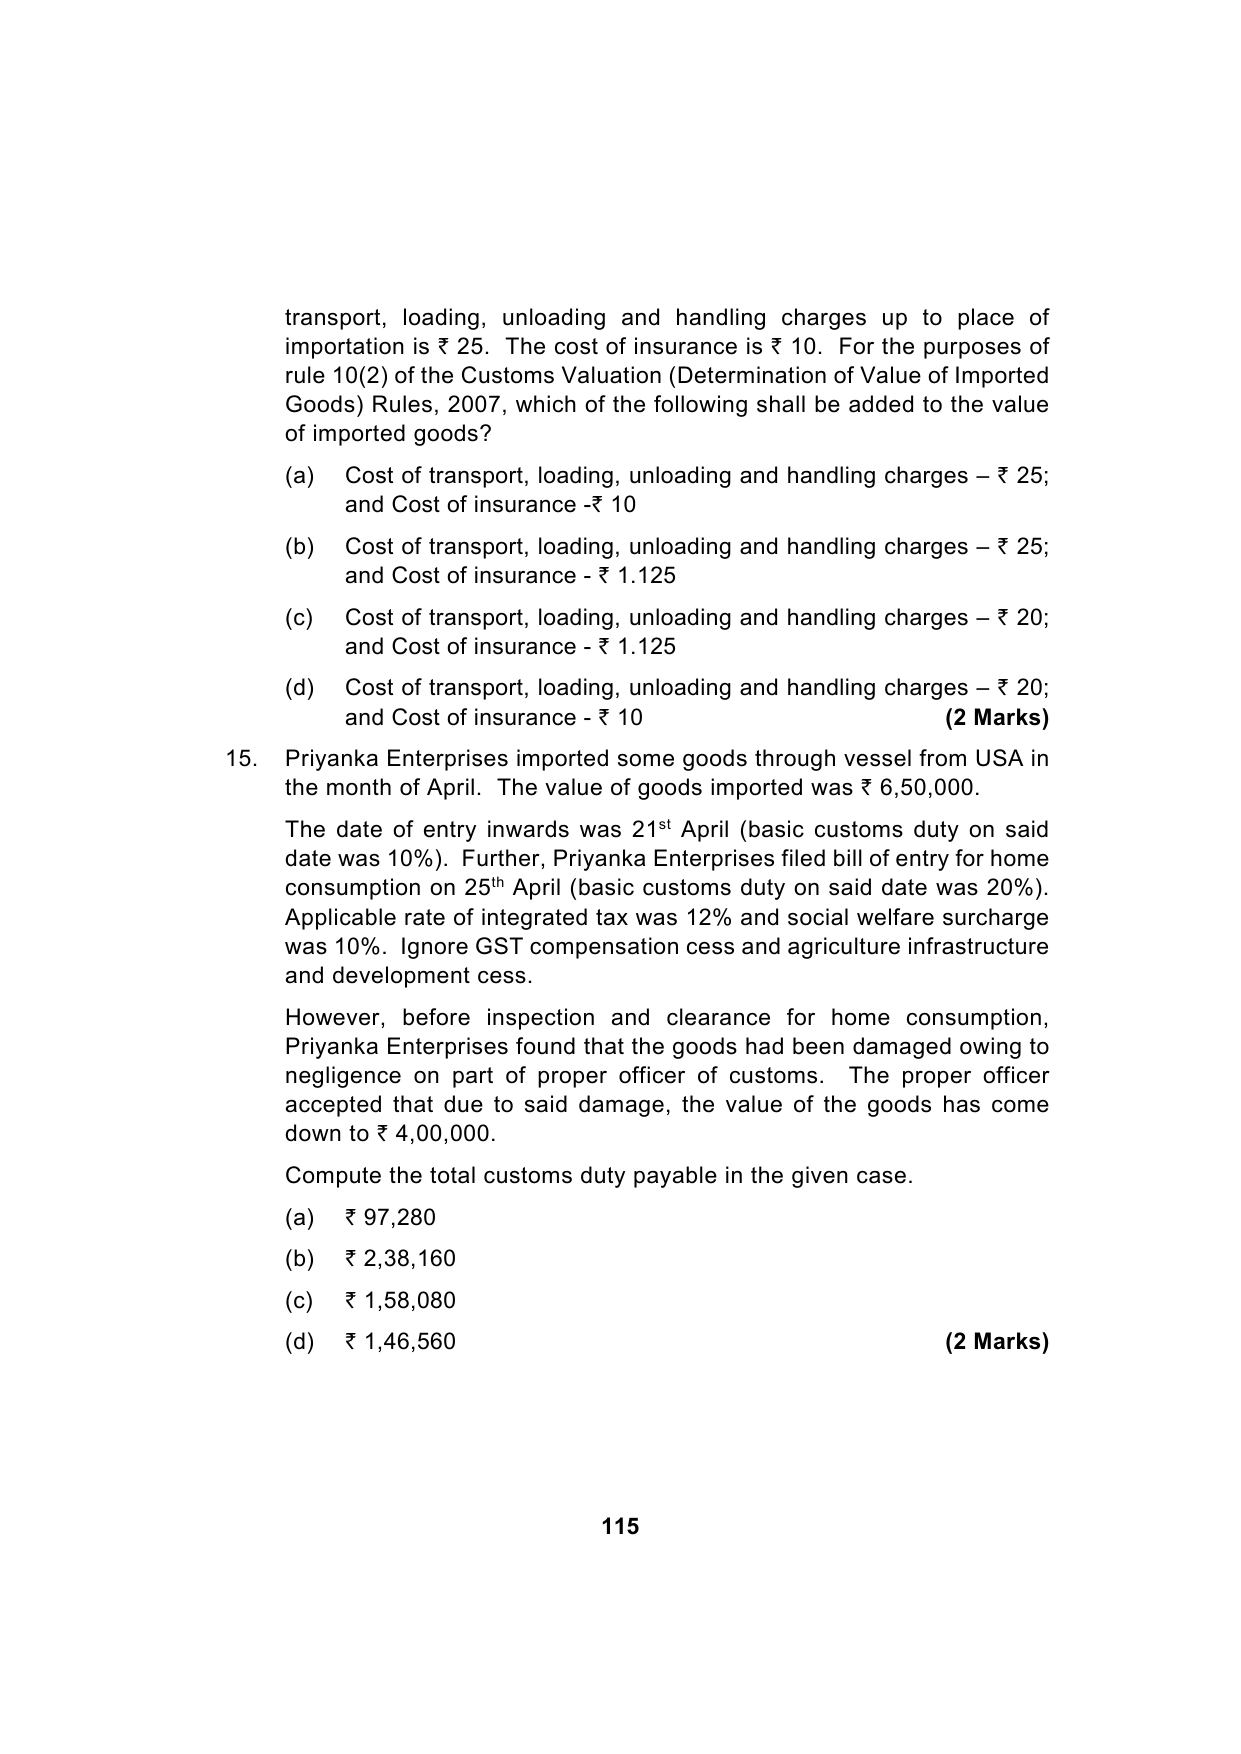
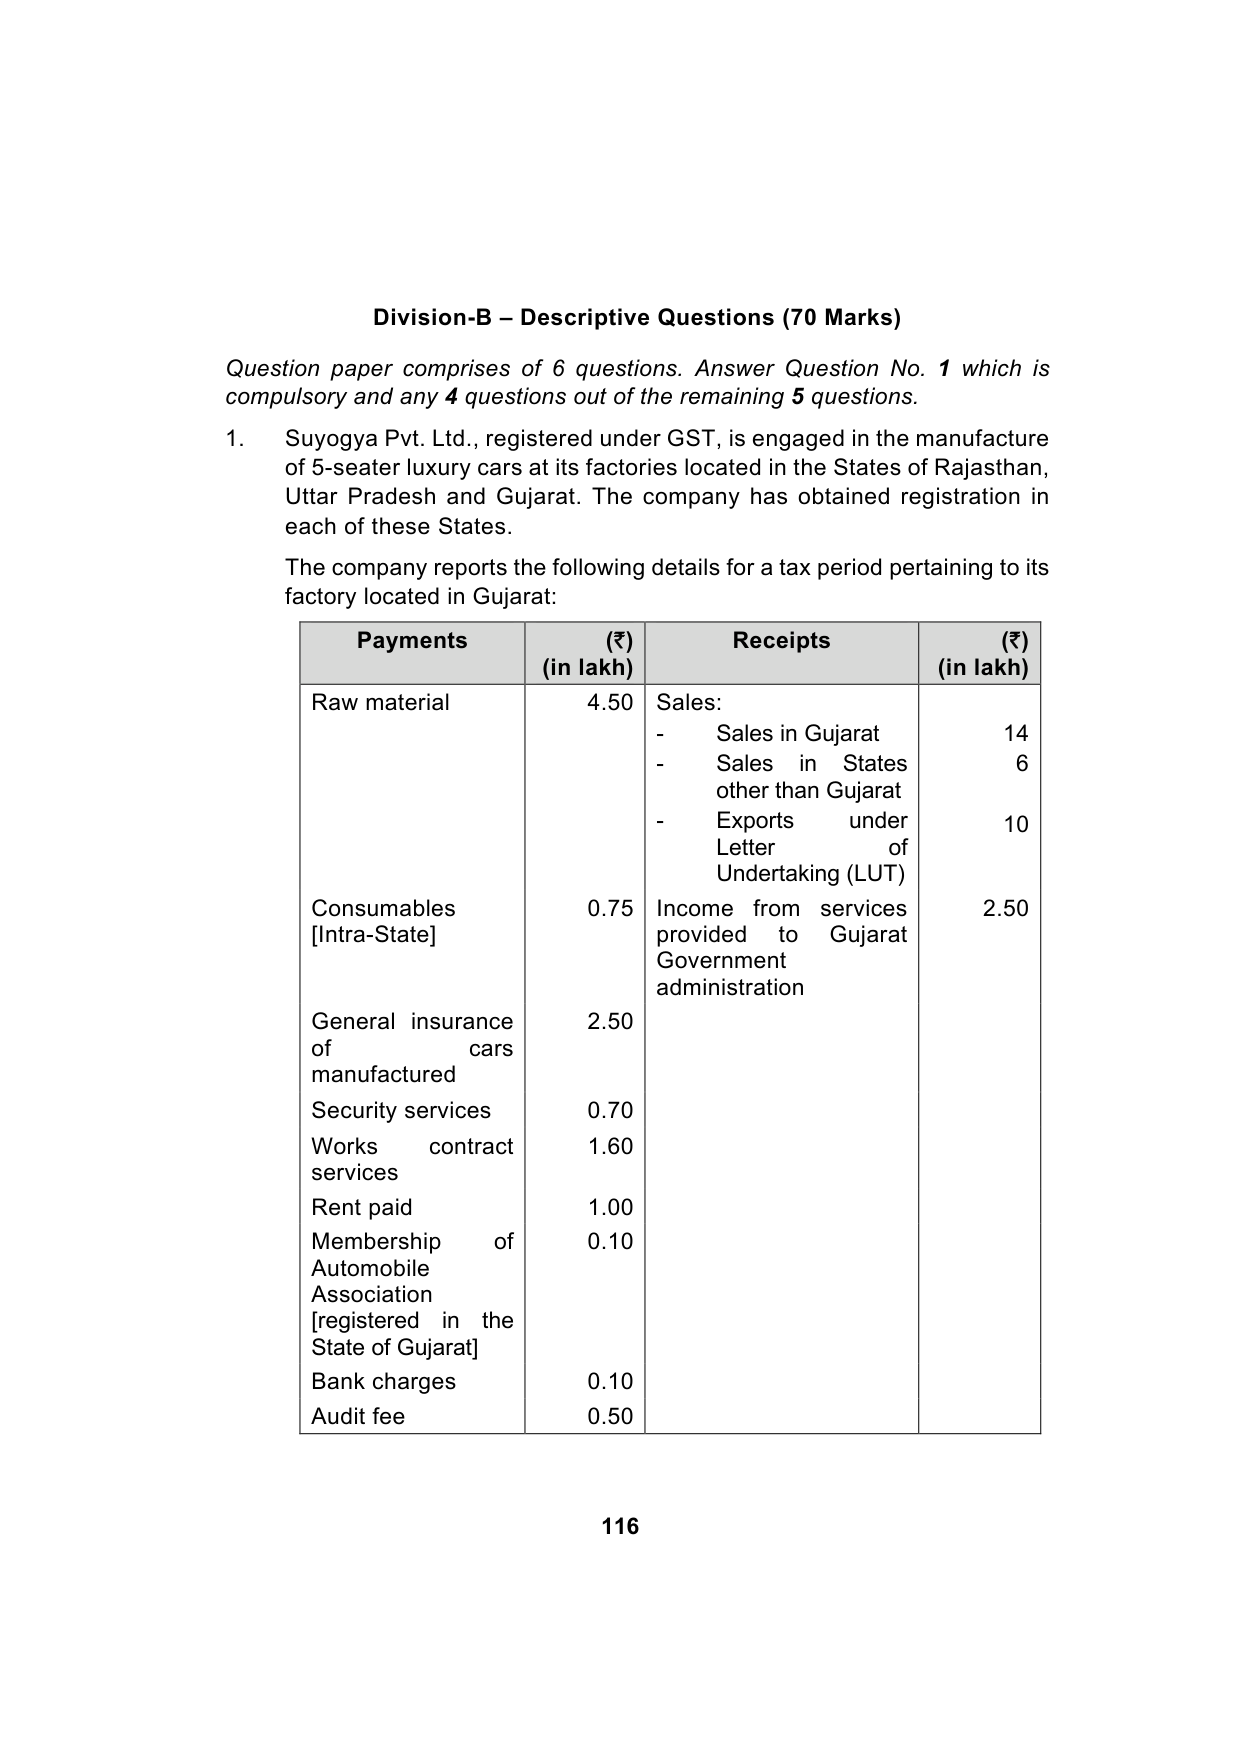
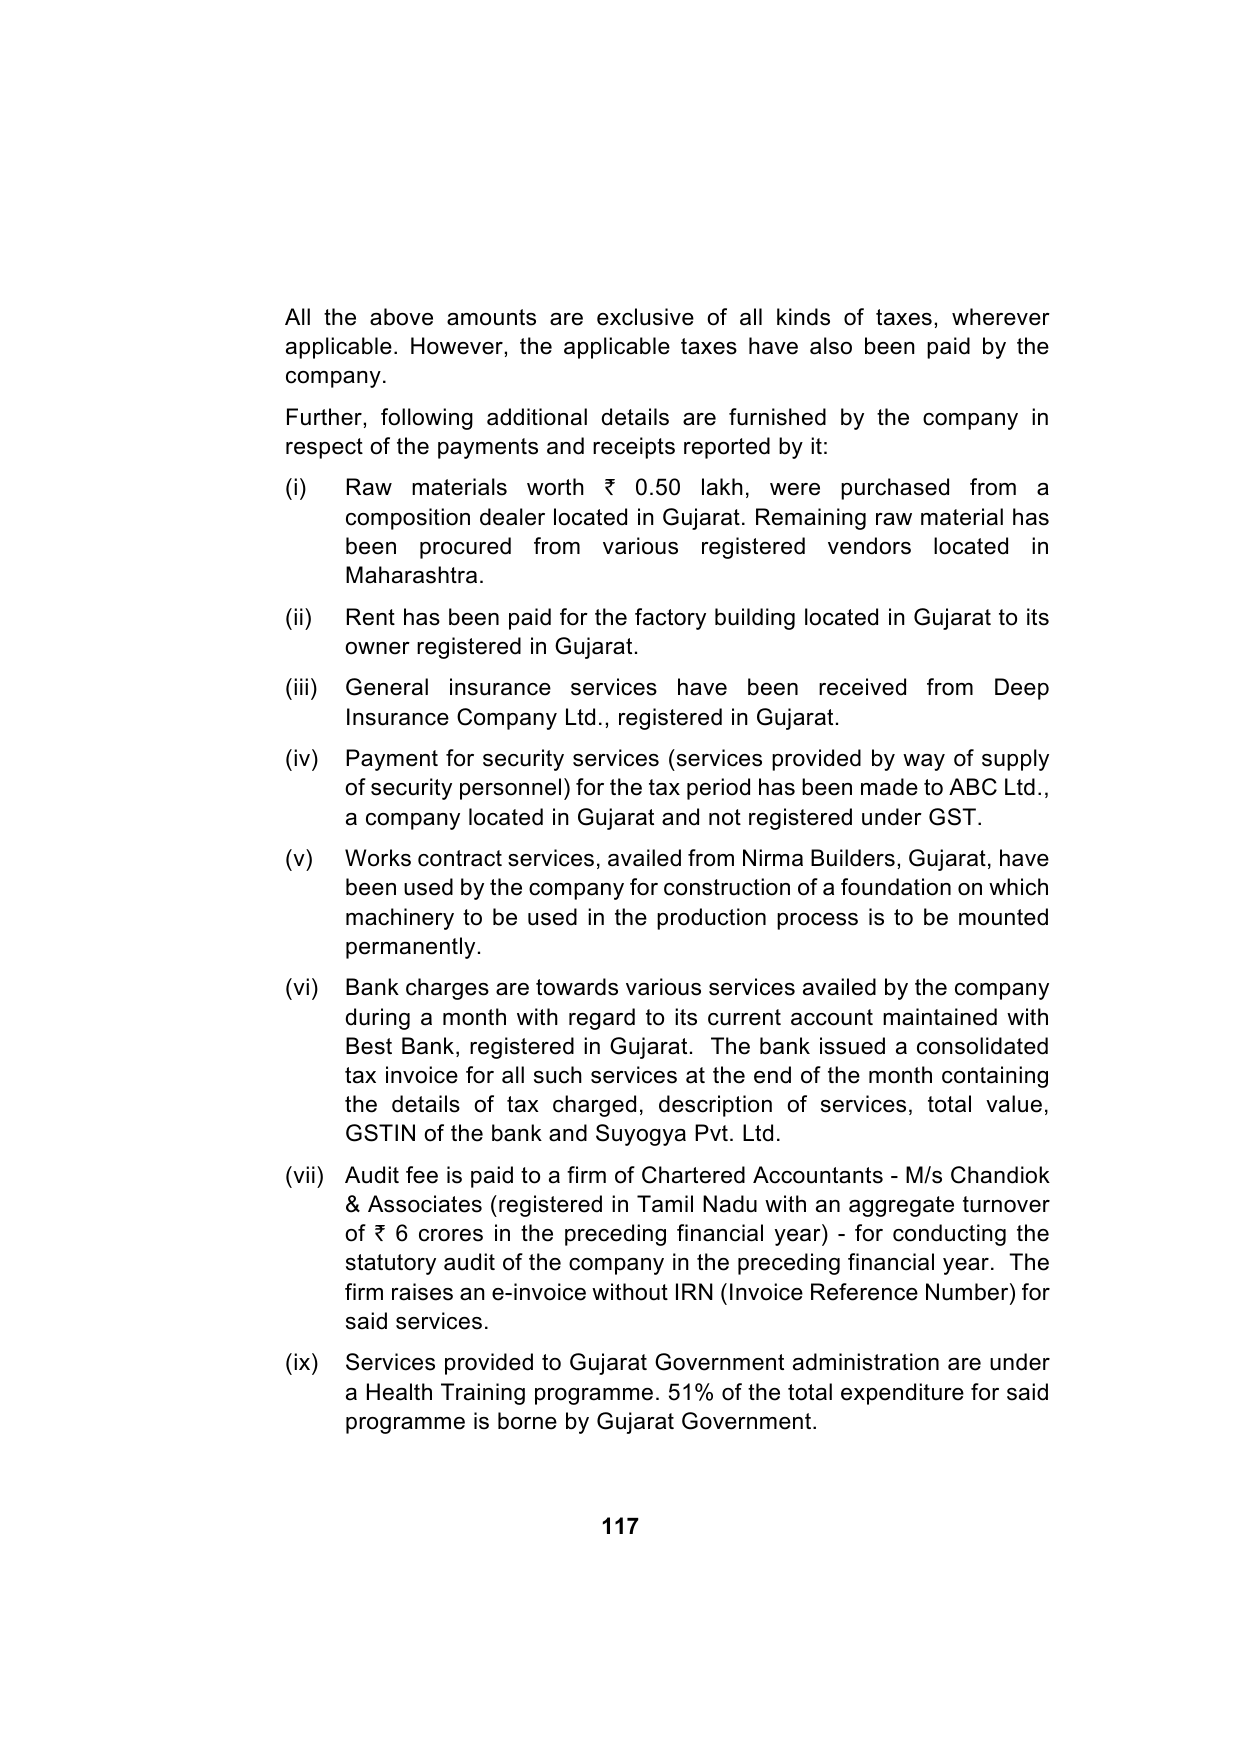
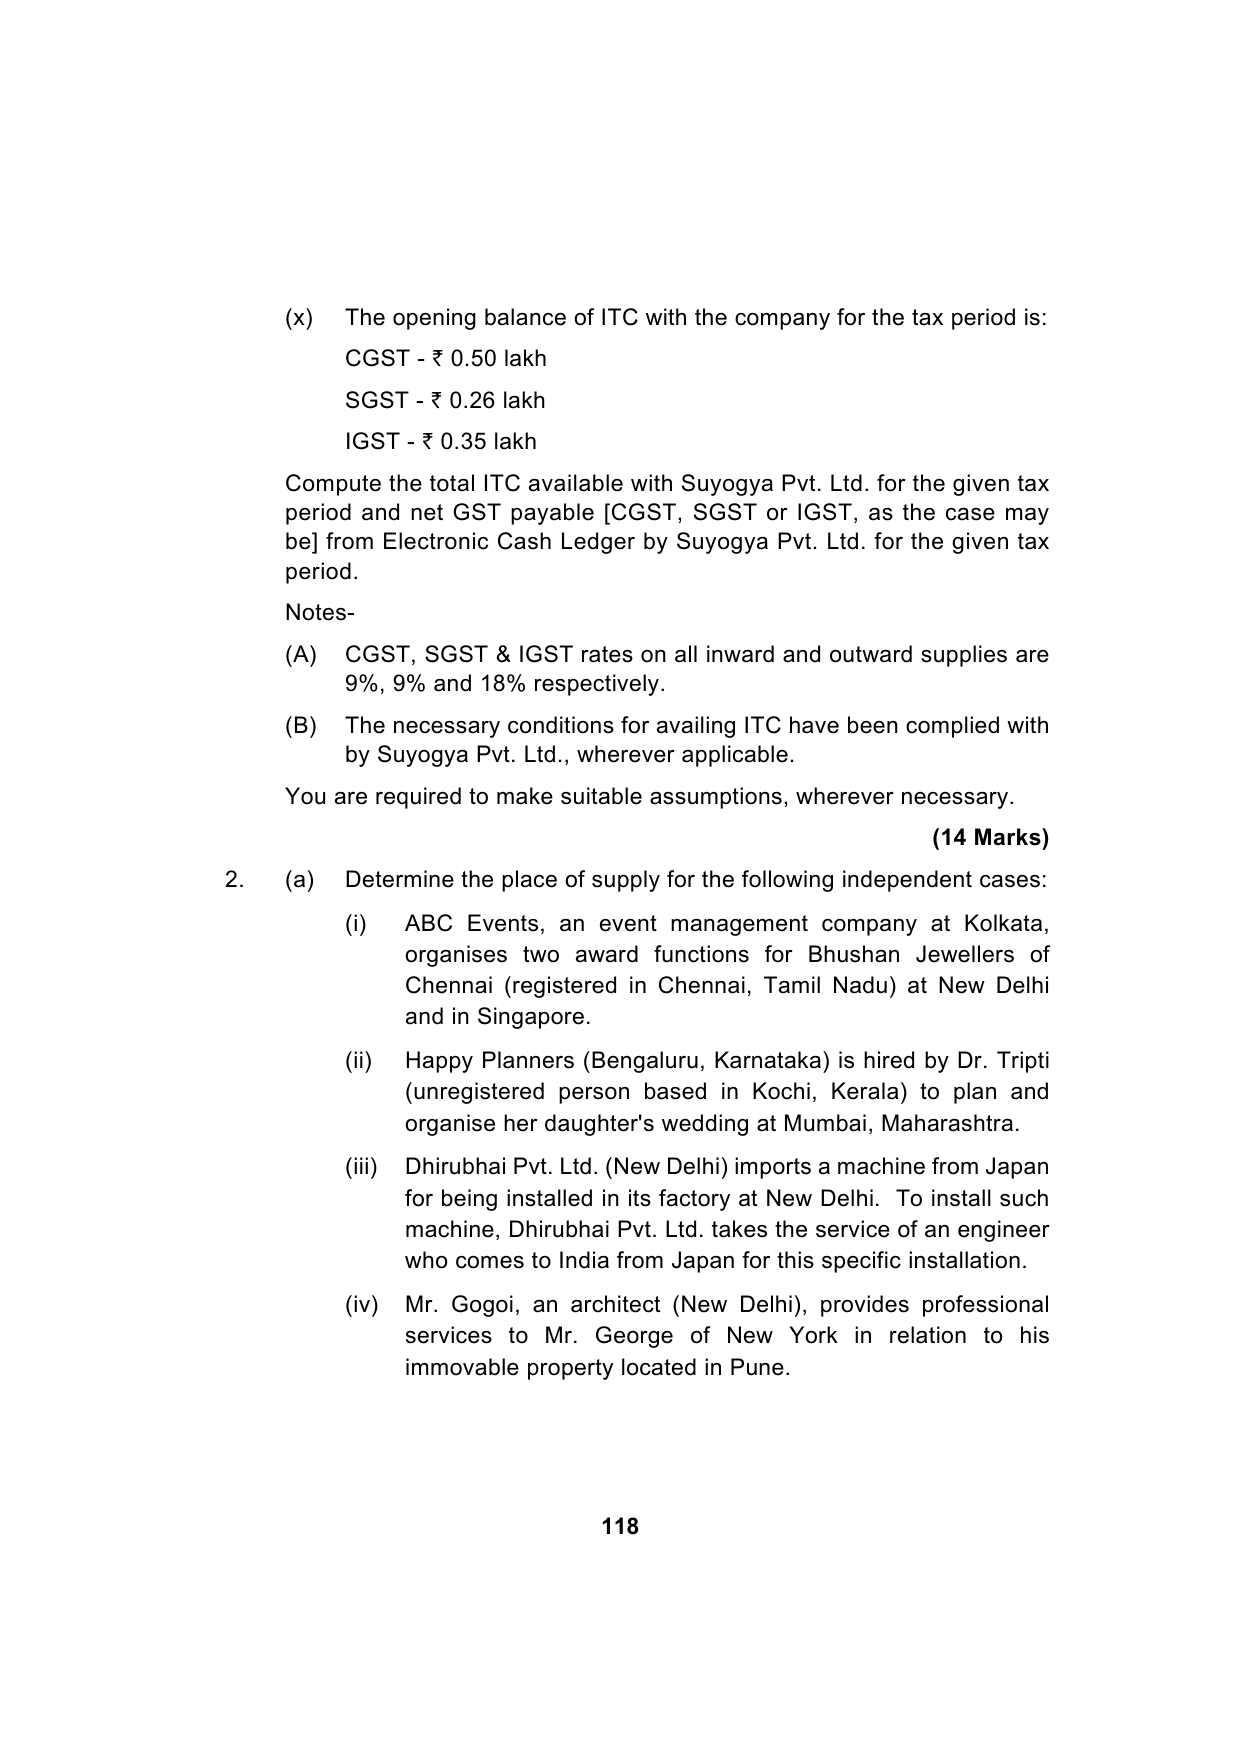
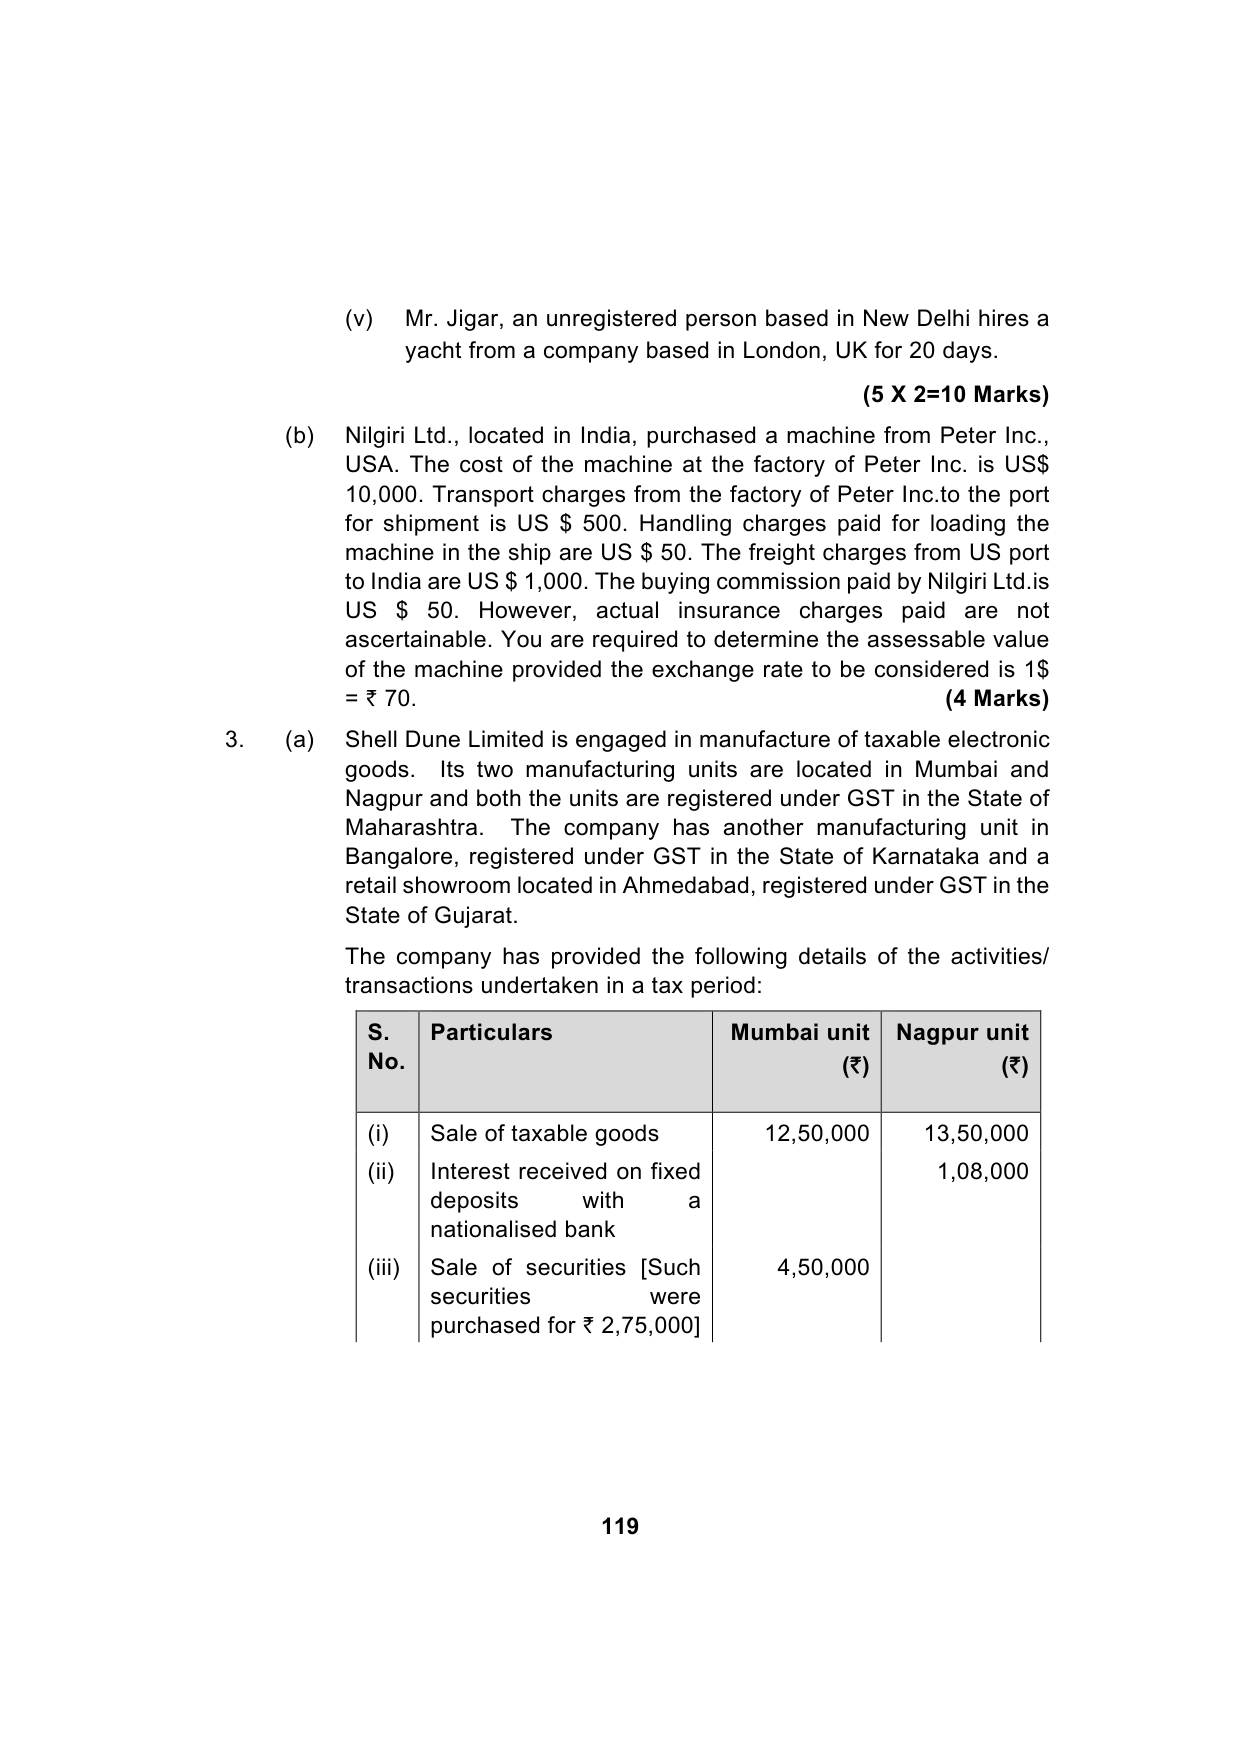
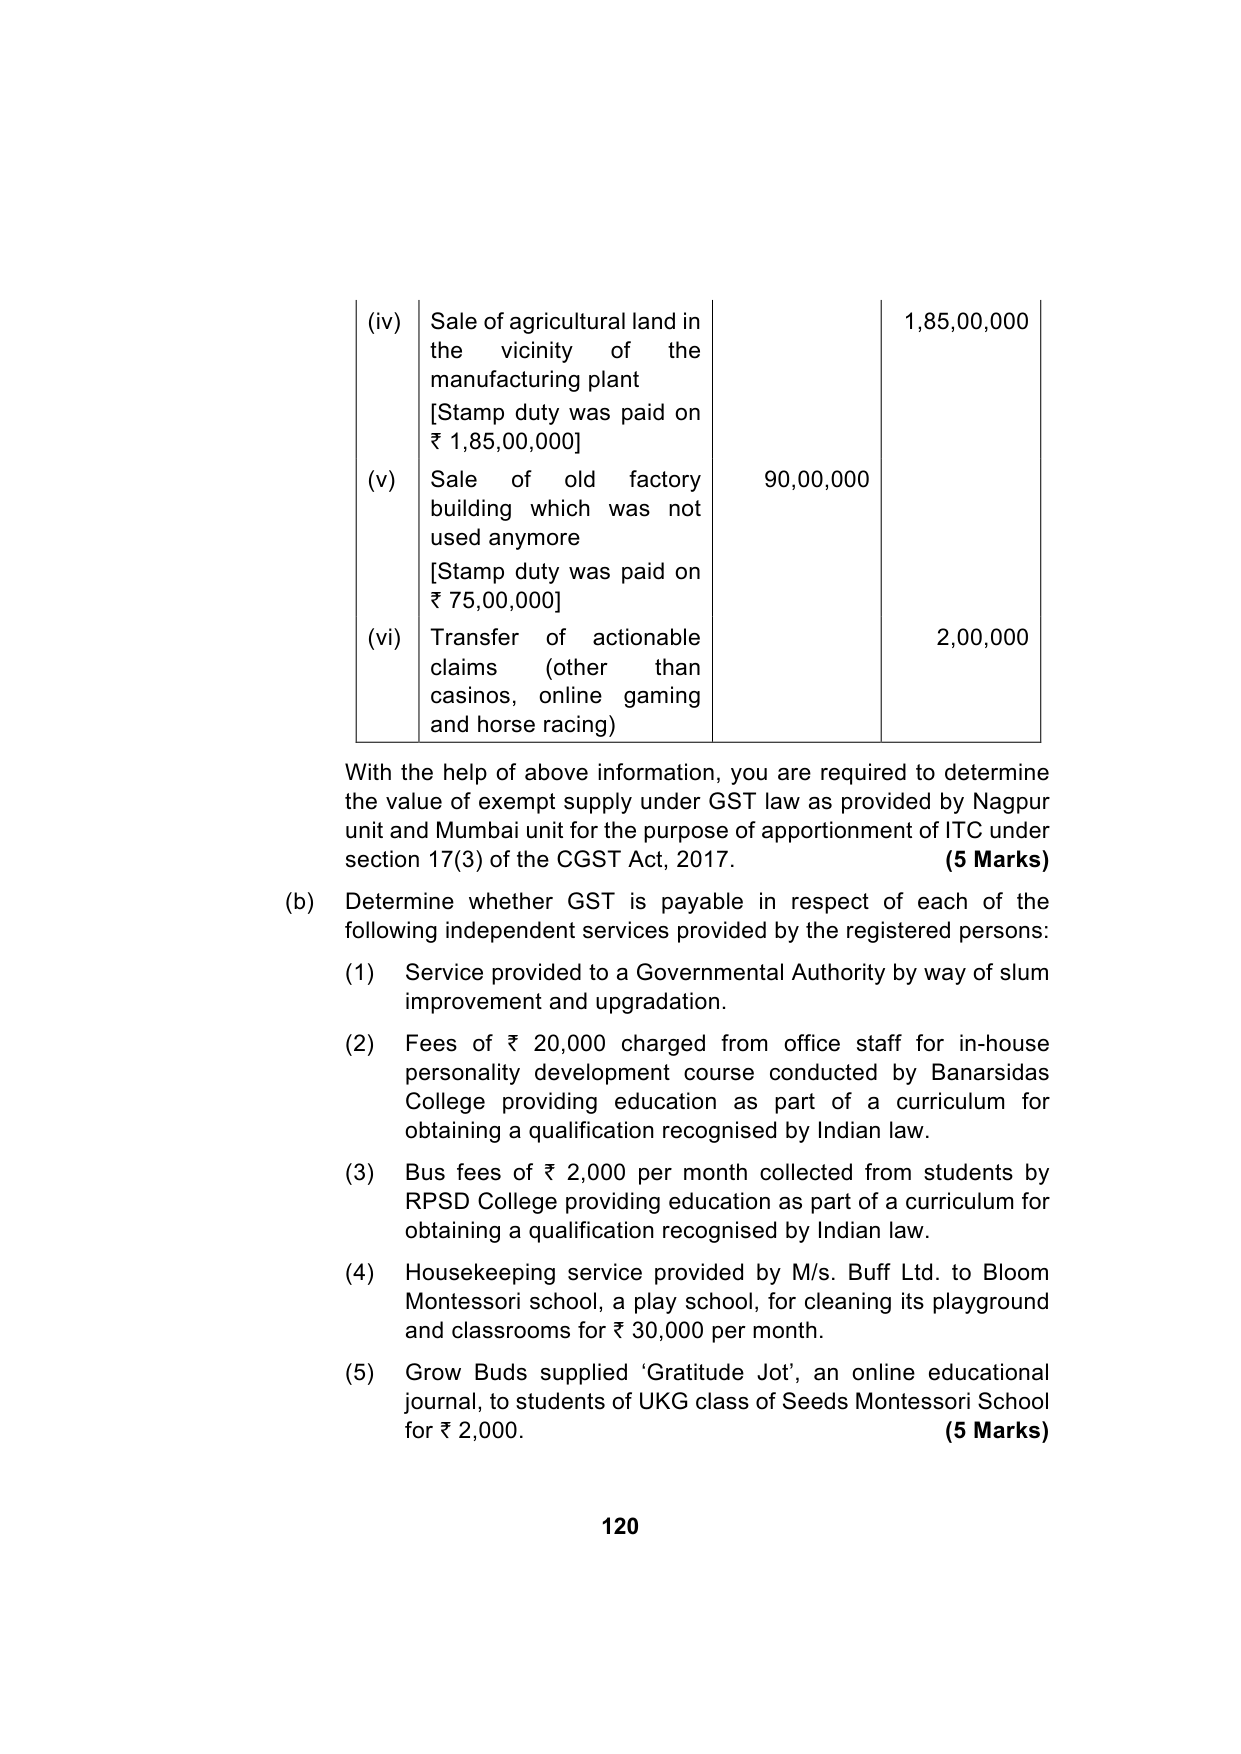
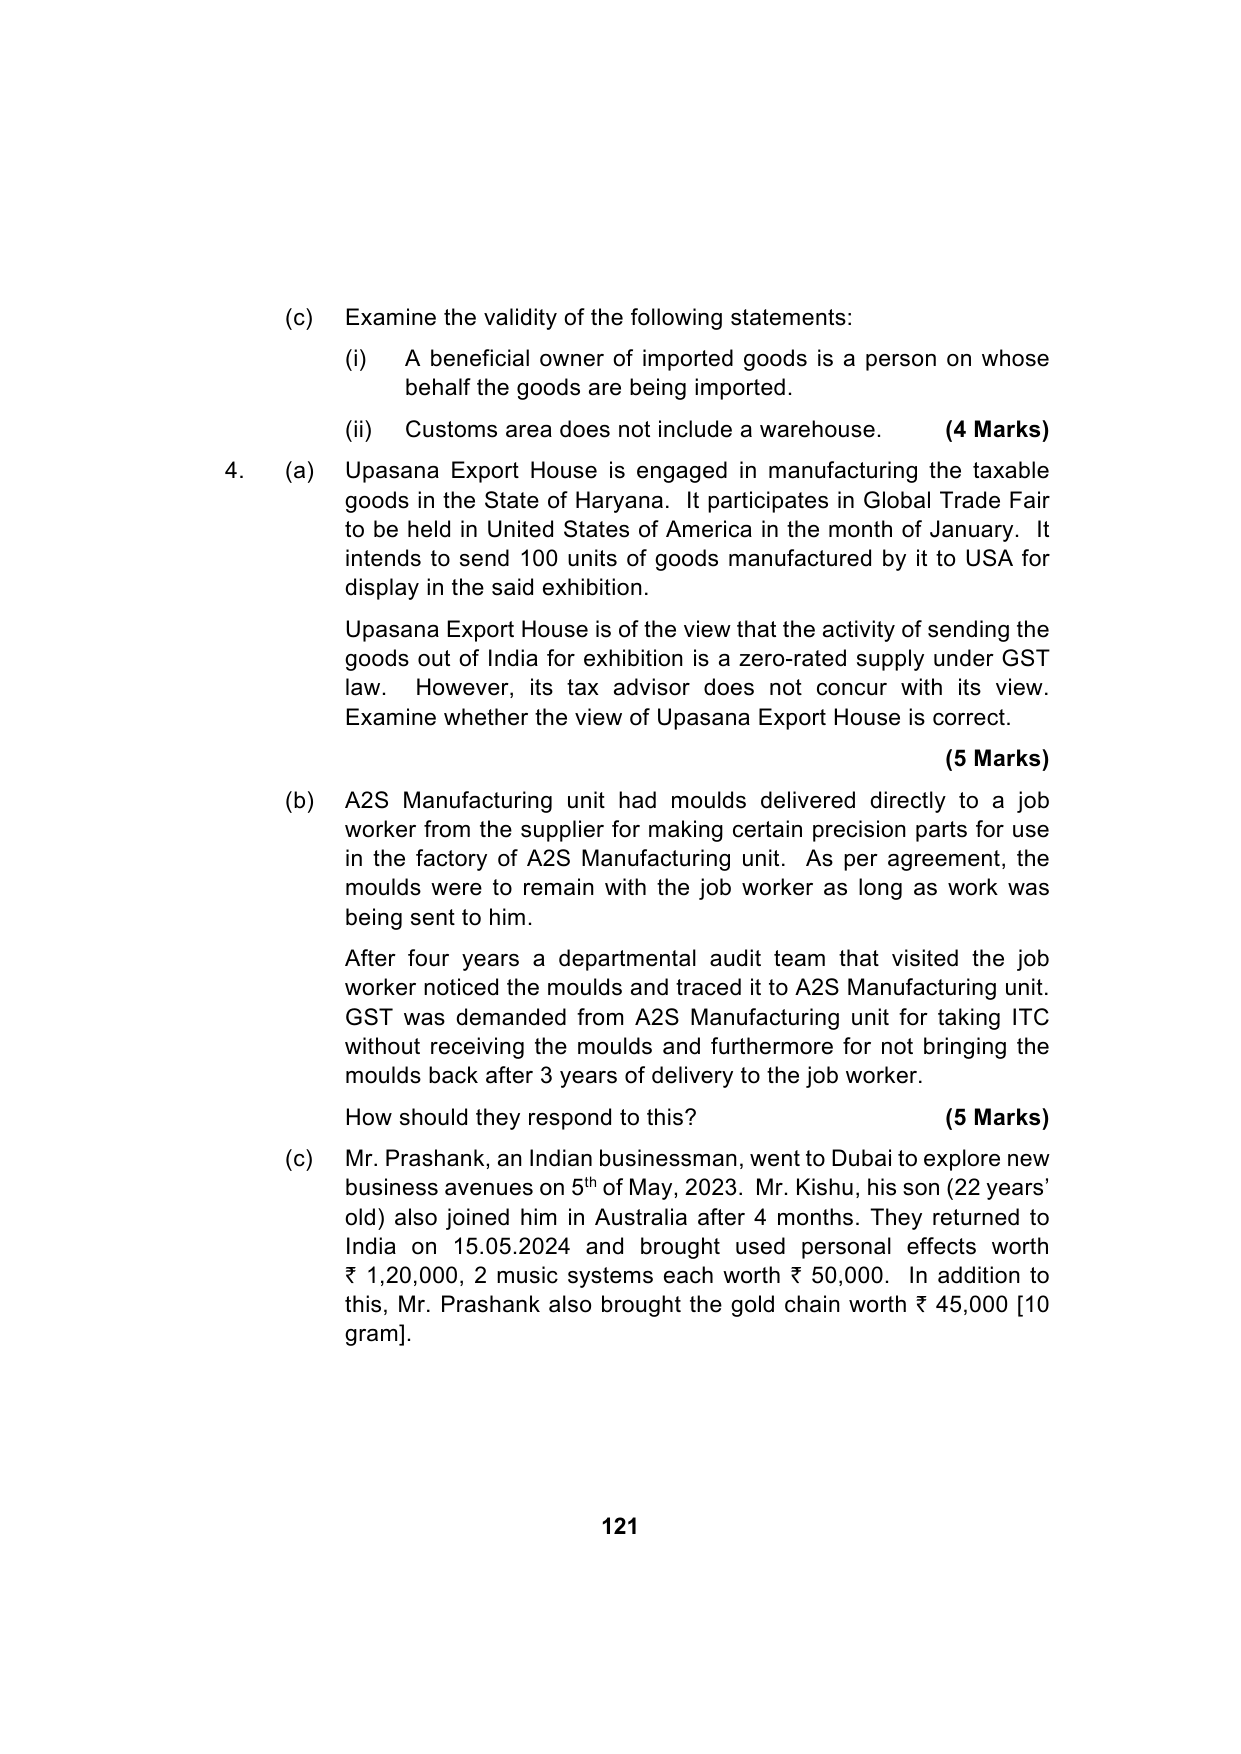
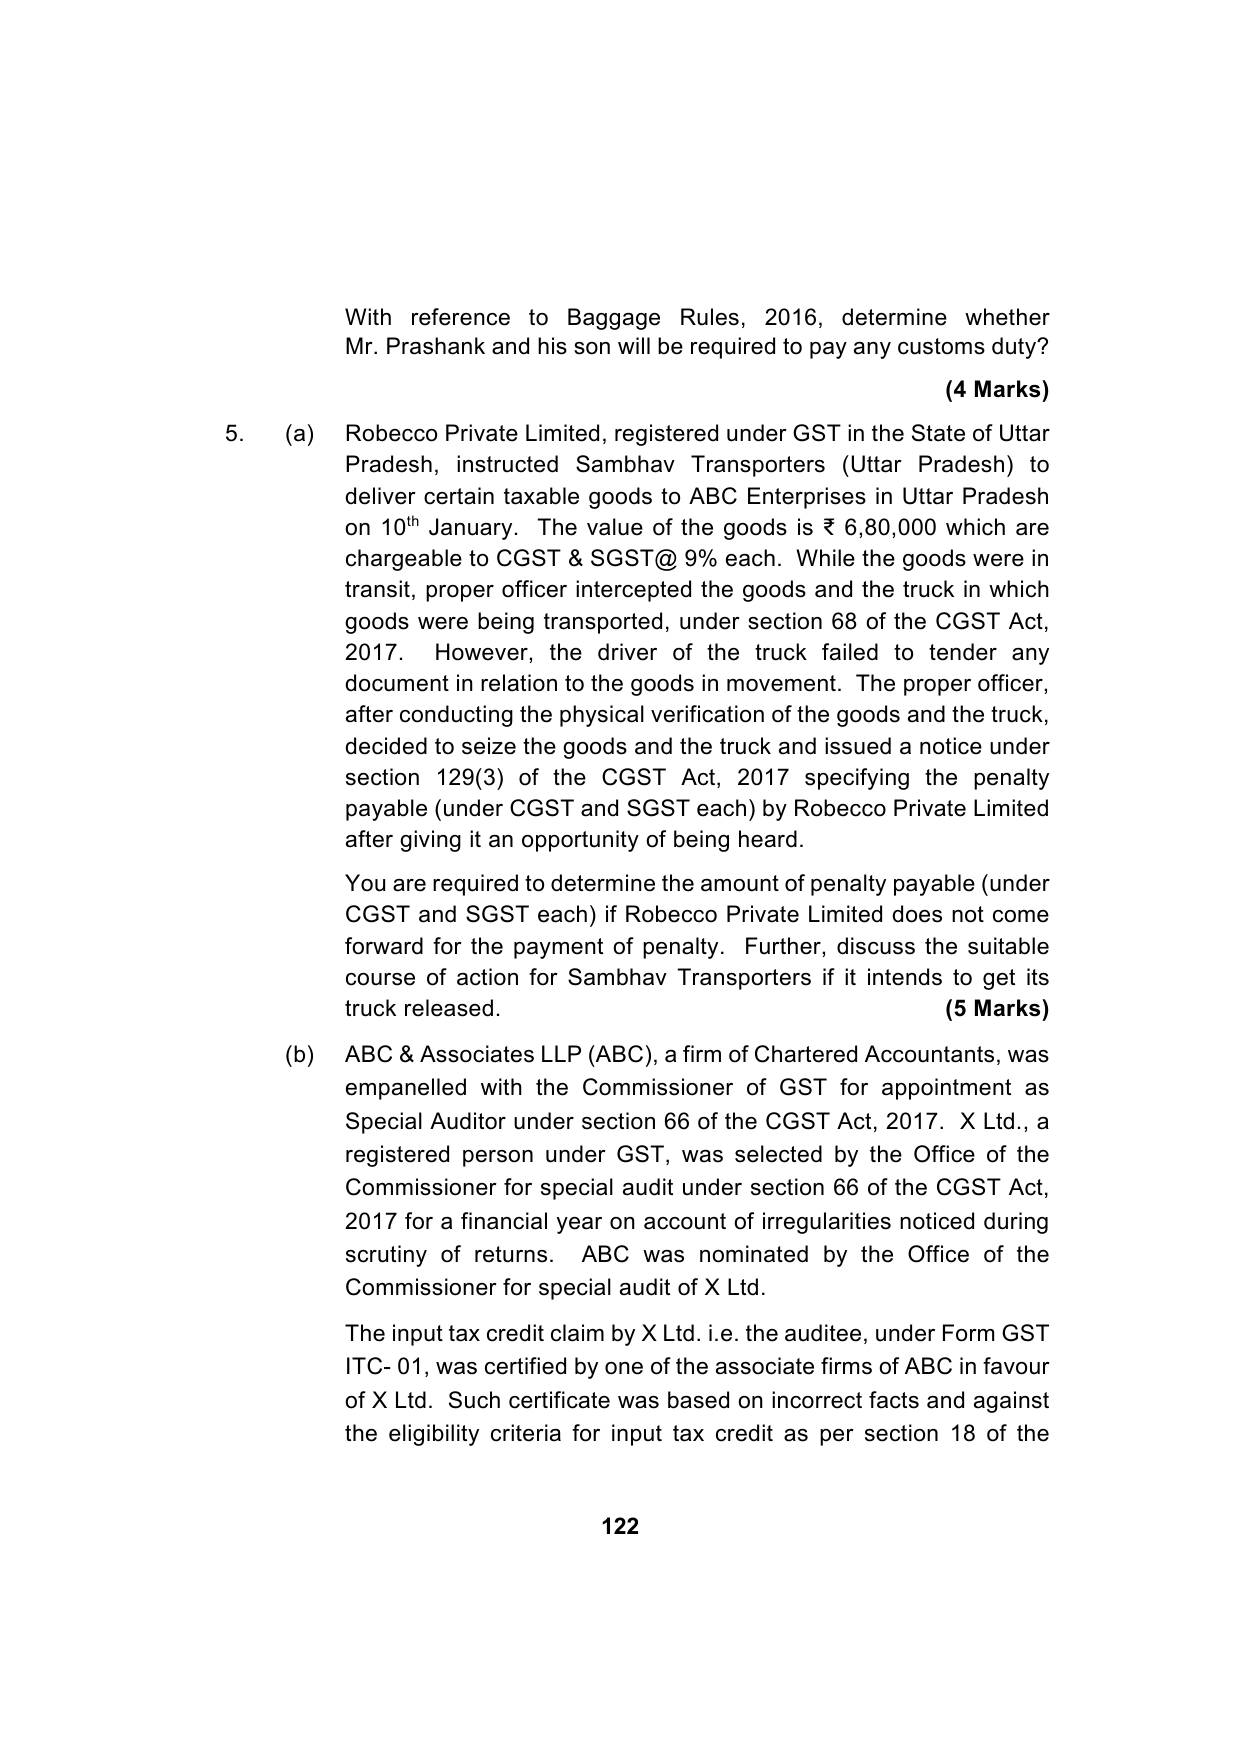
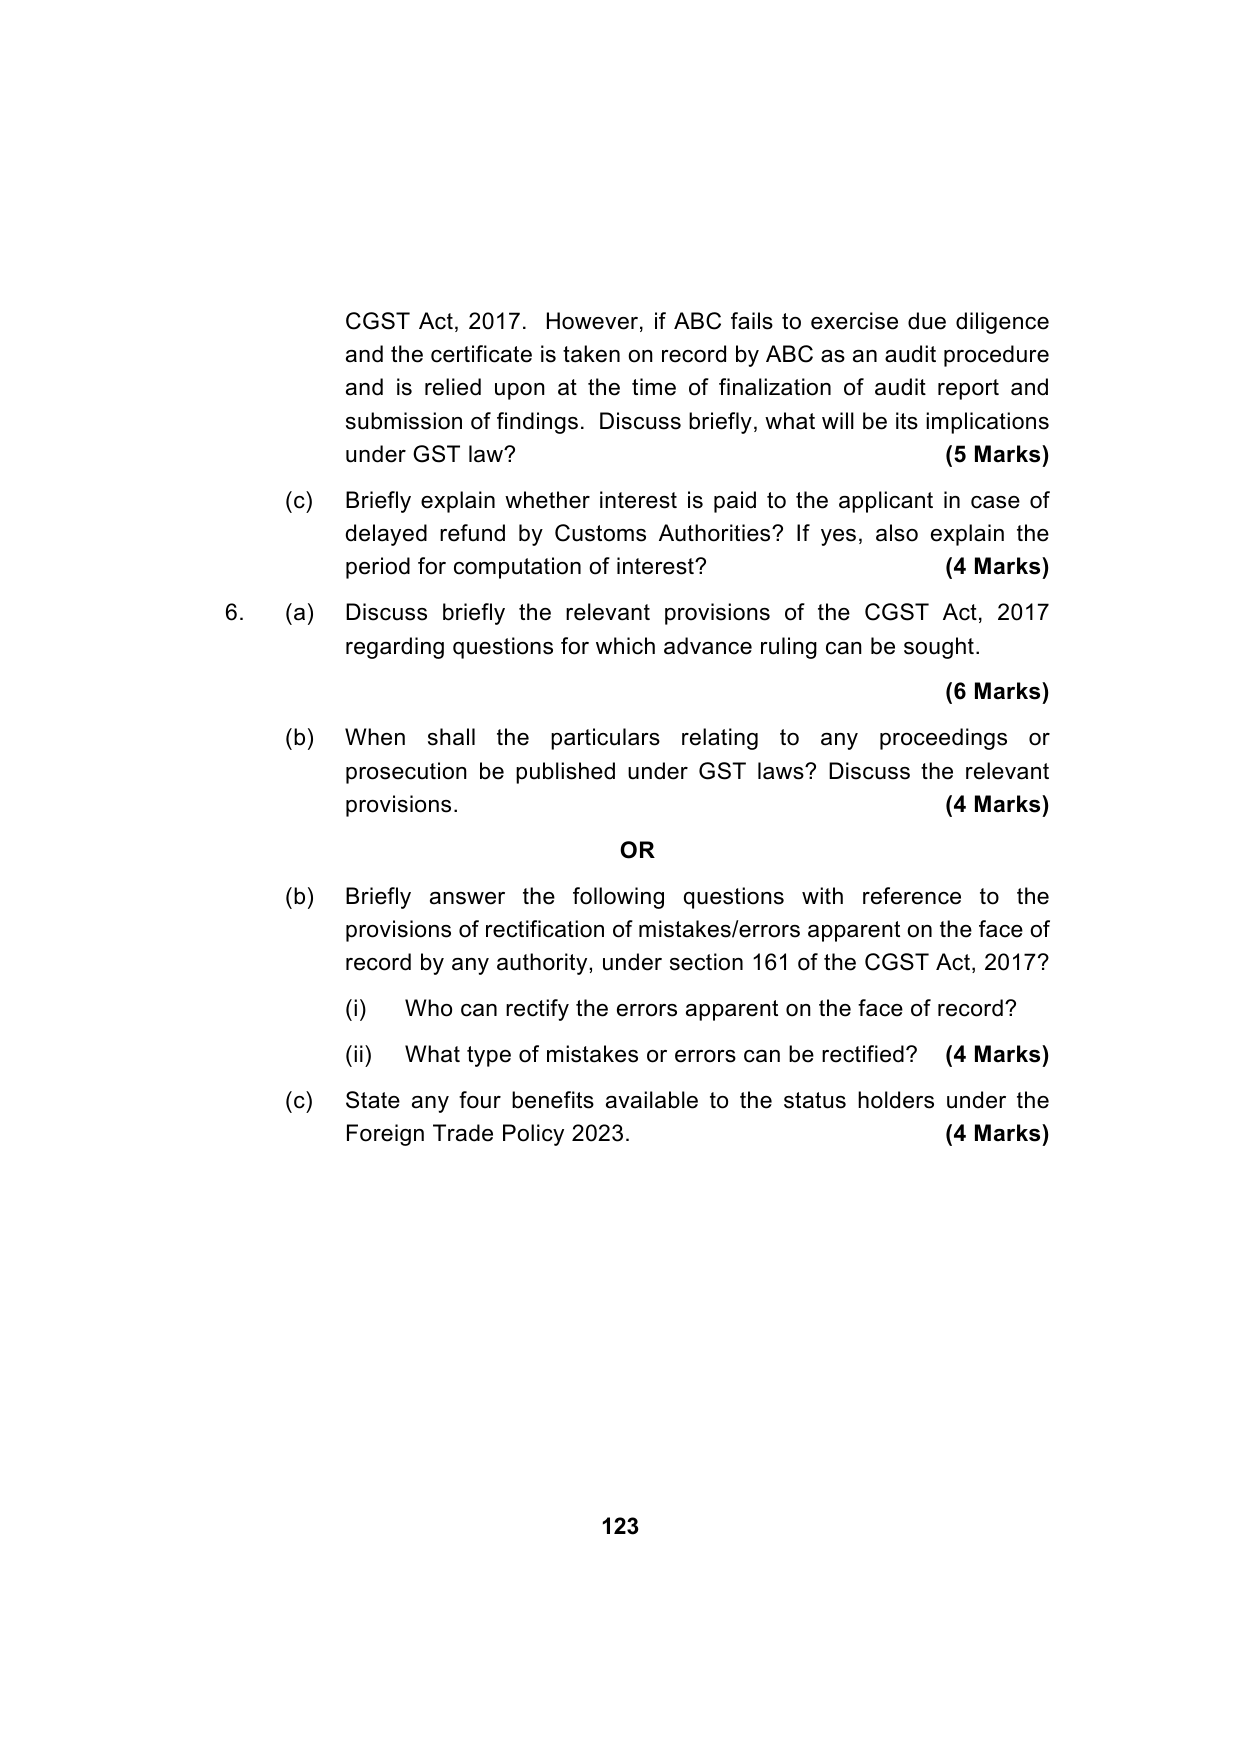
Paper 5: Indirect Tax Laws — Model Test Paper 2 (100 marks)
Question
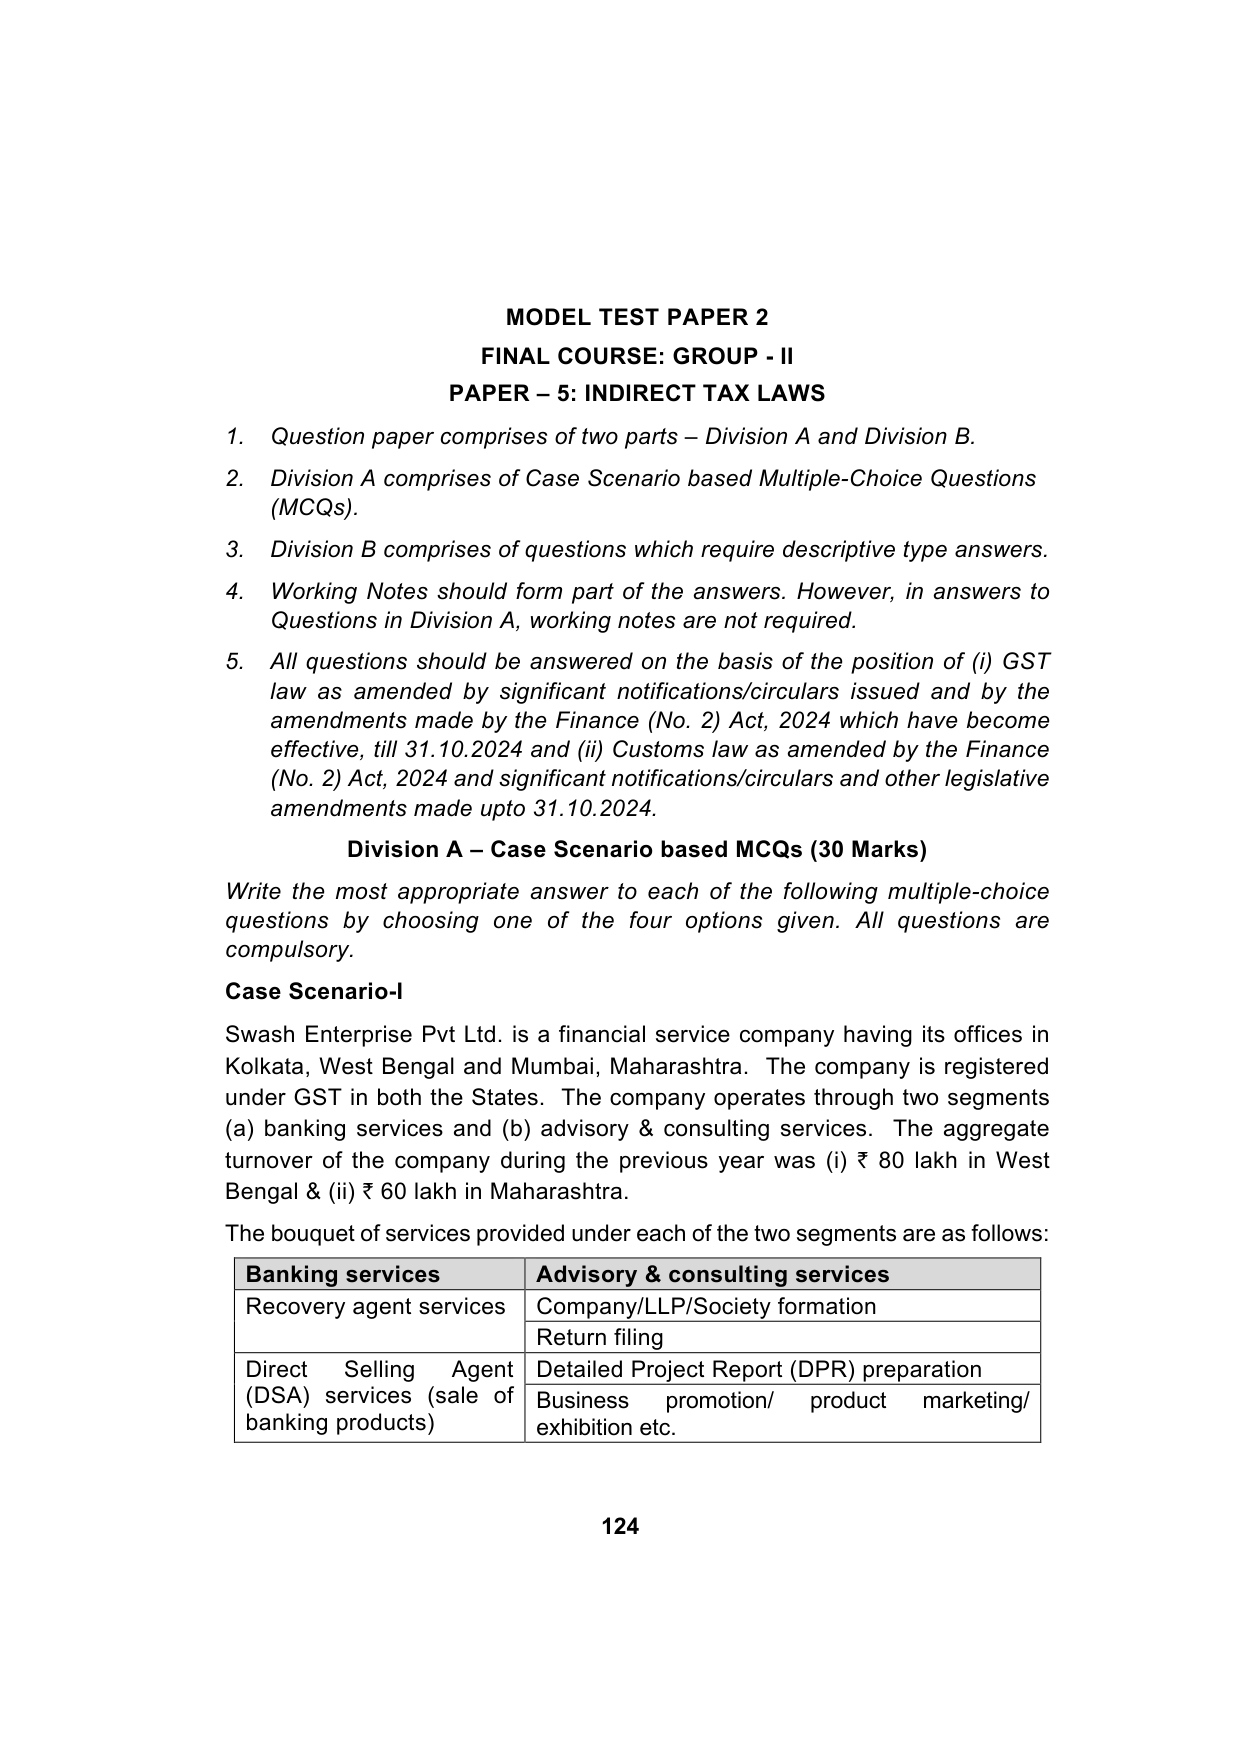
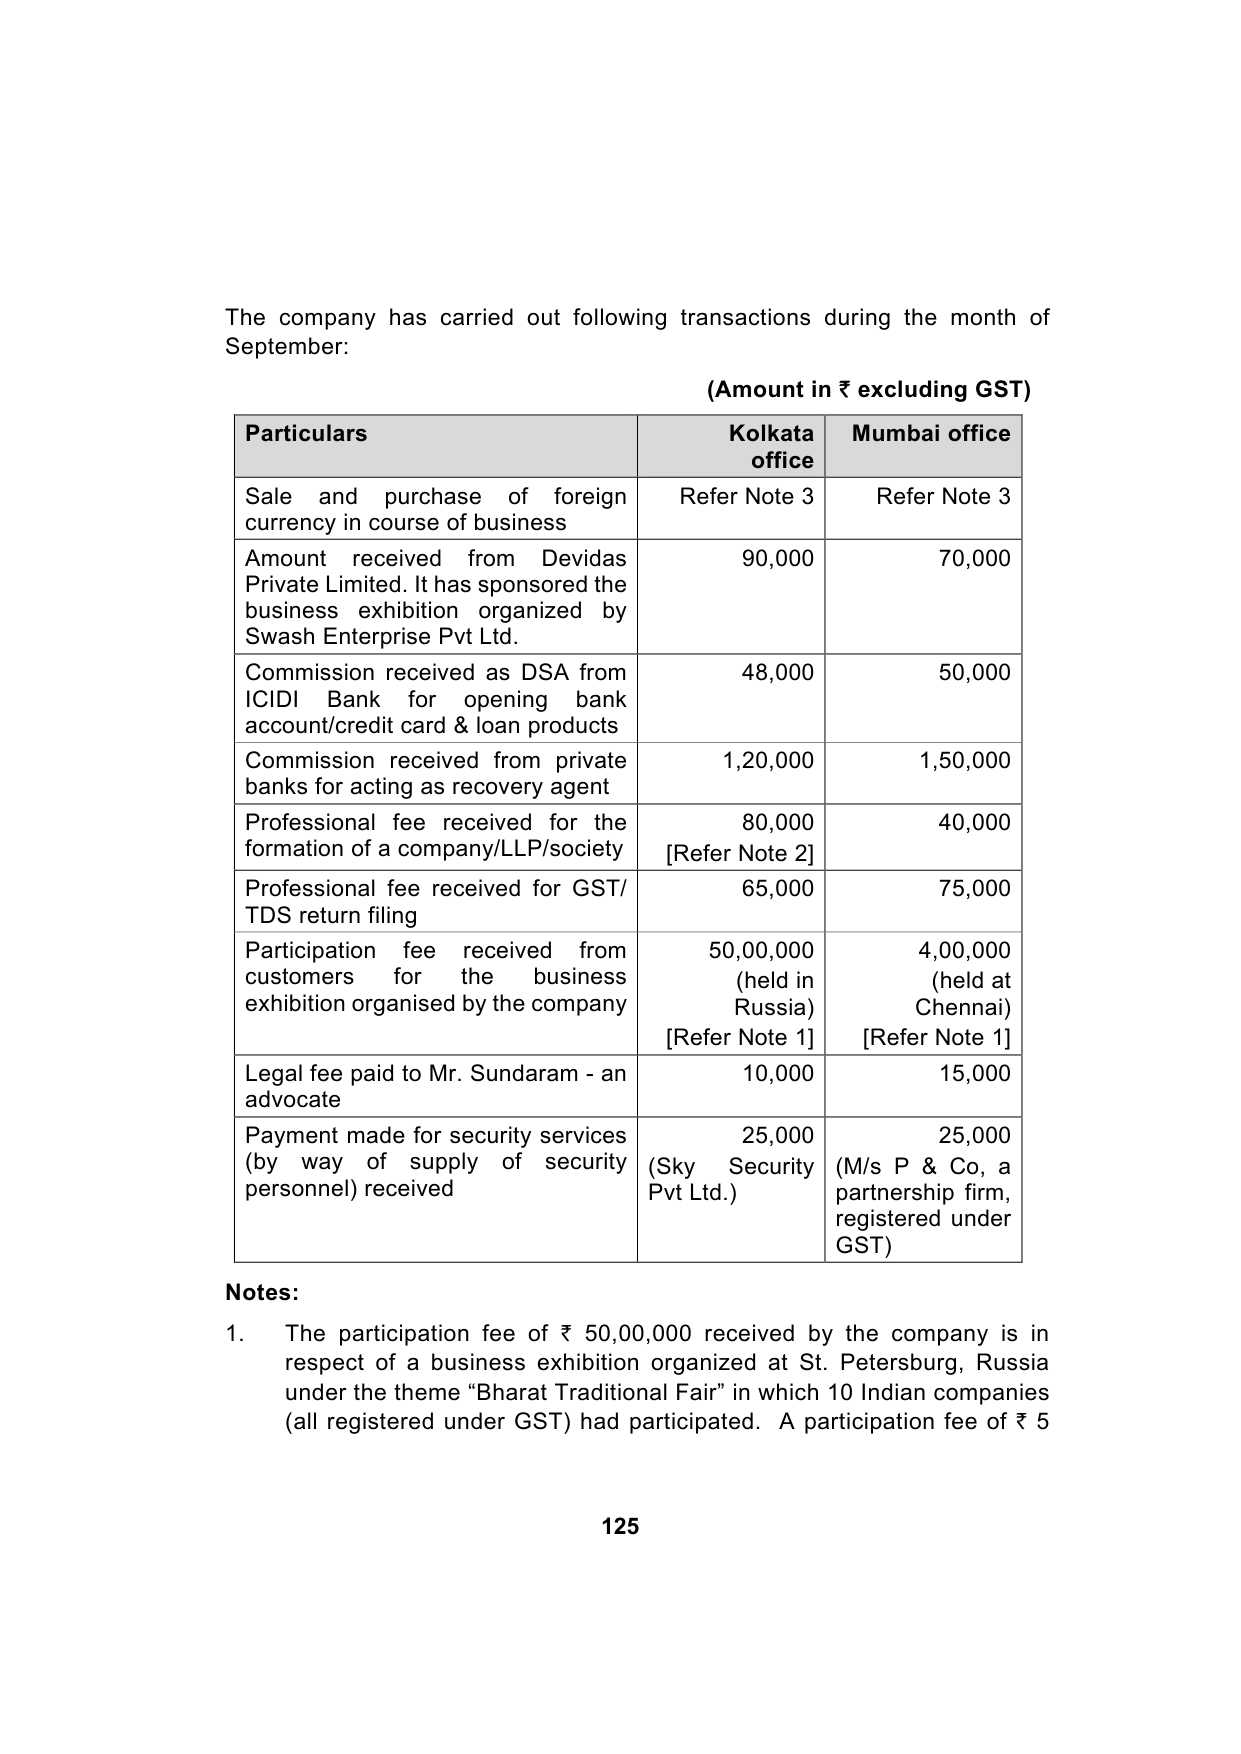
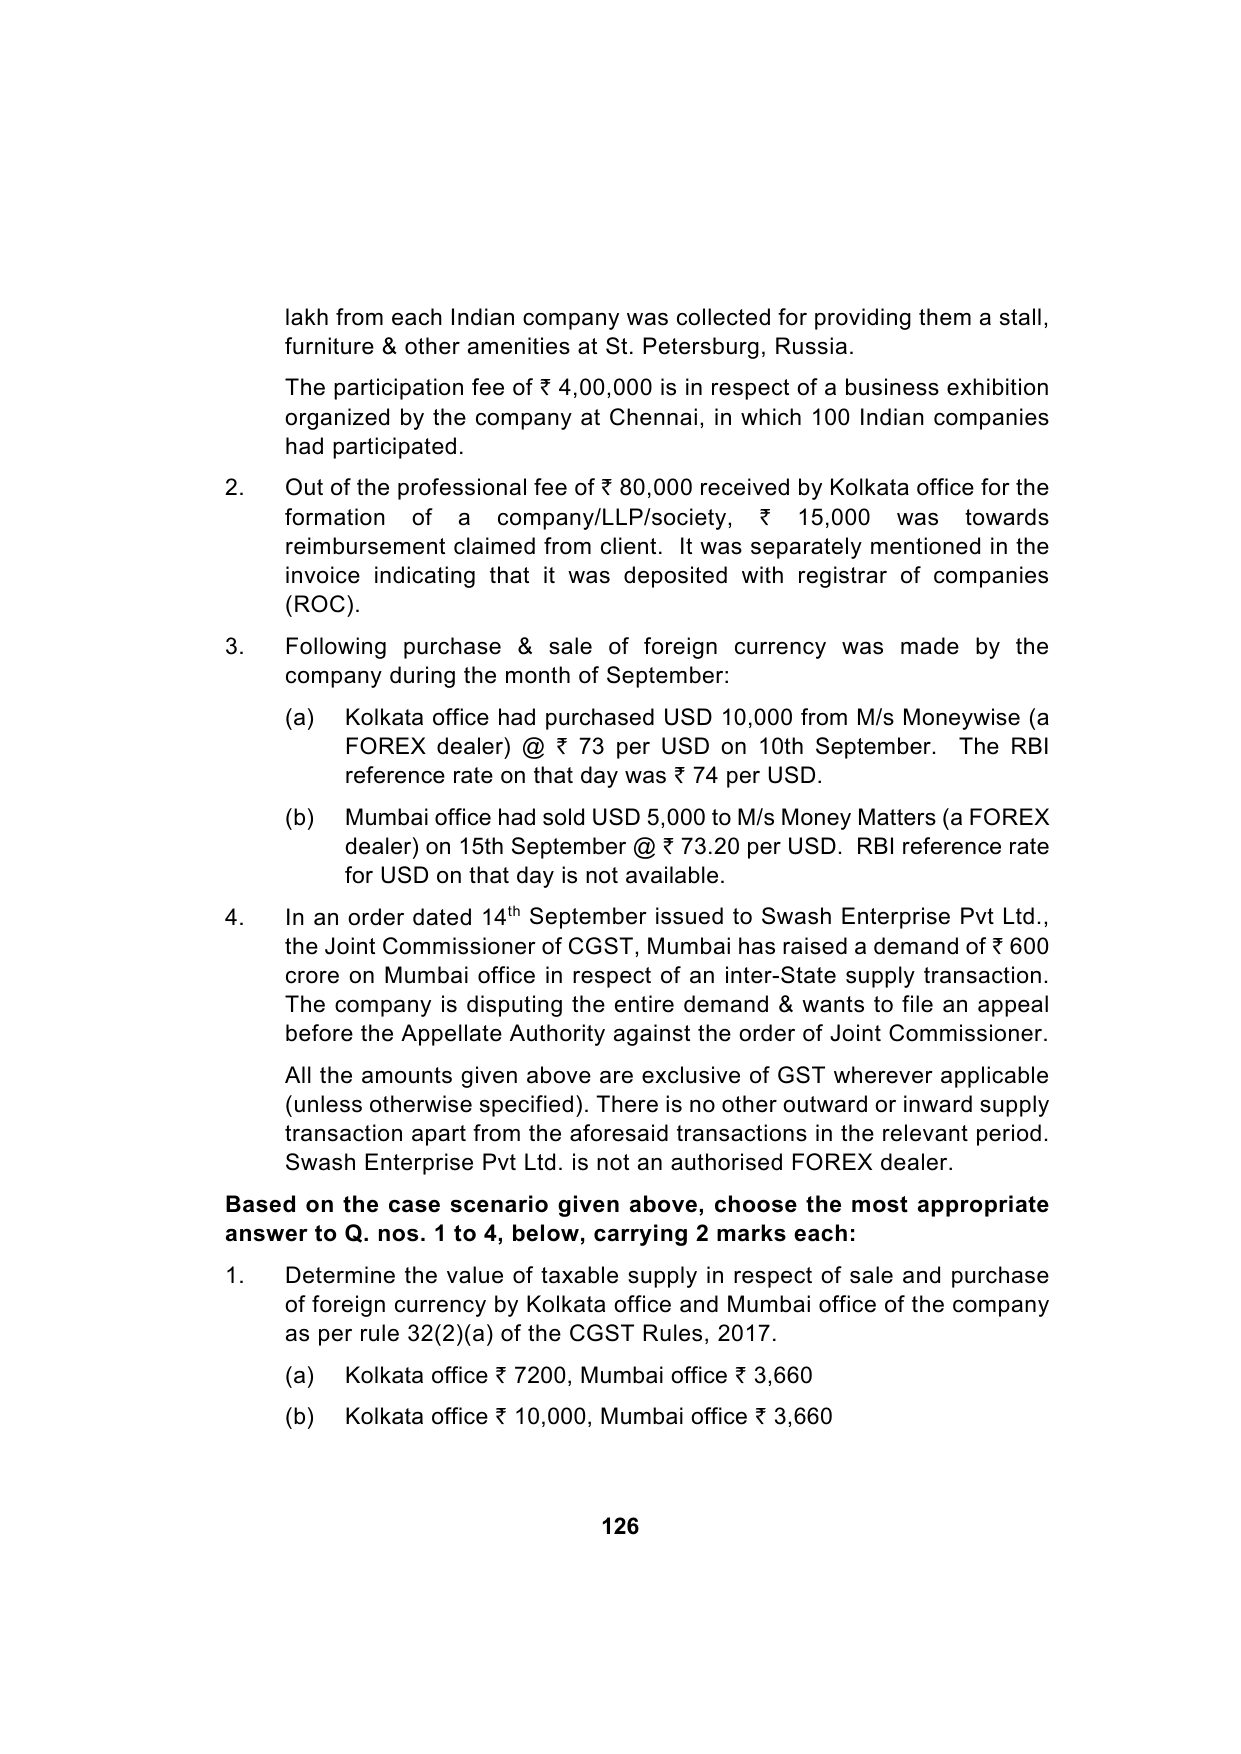
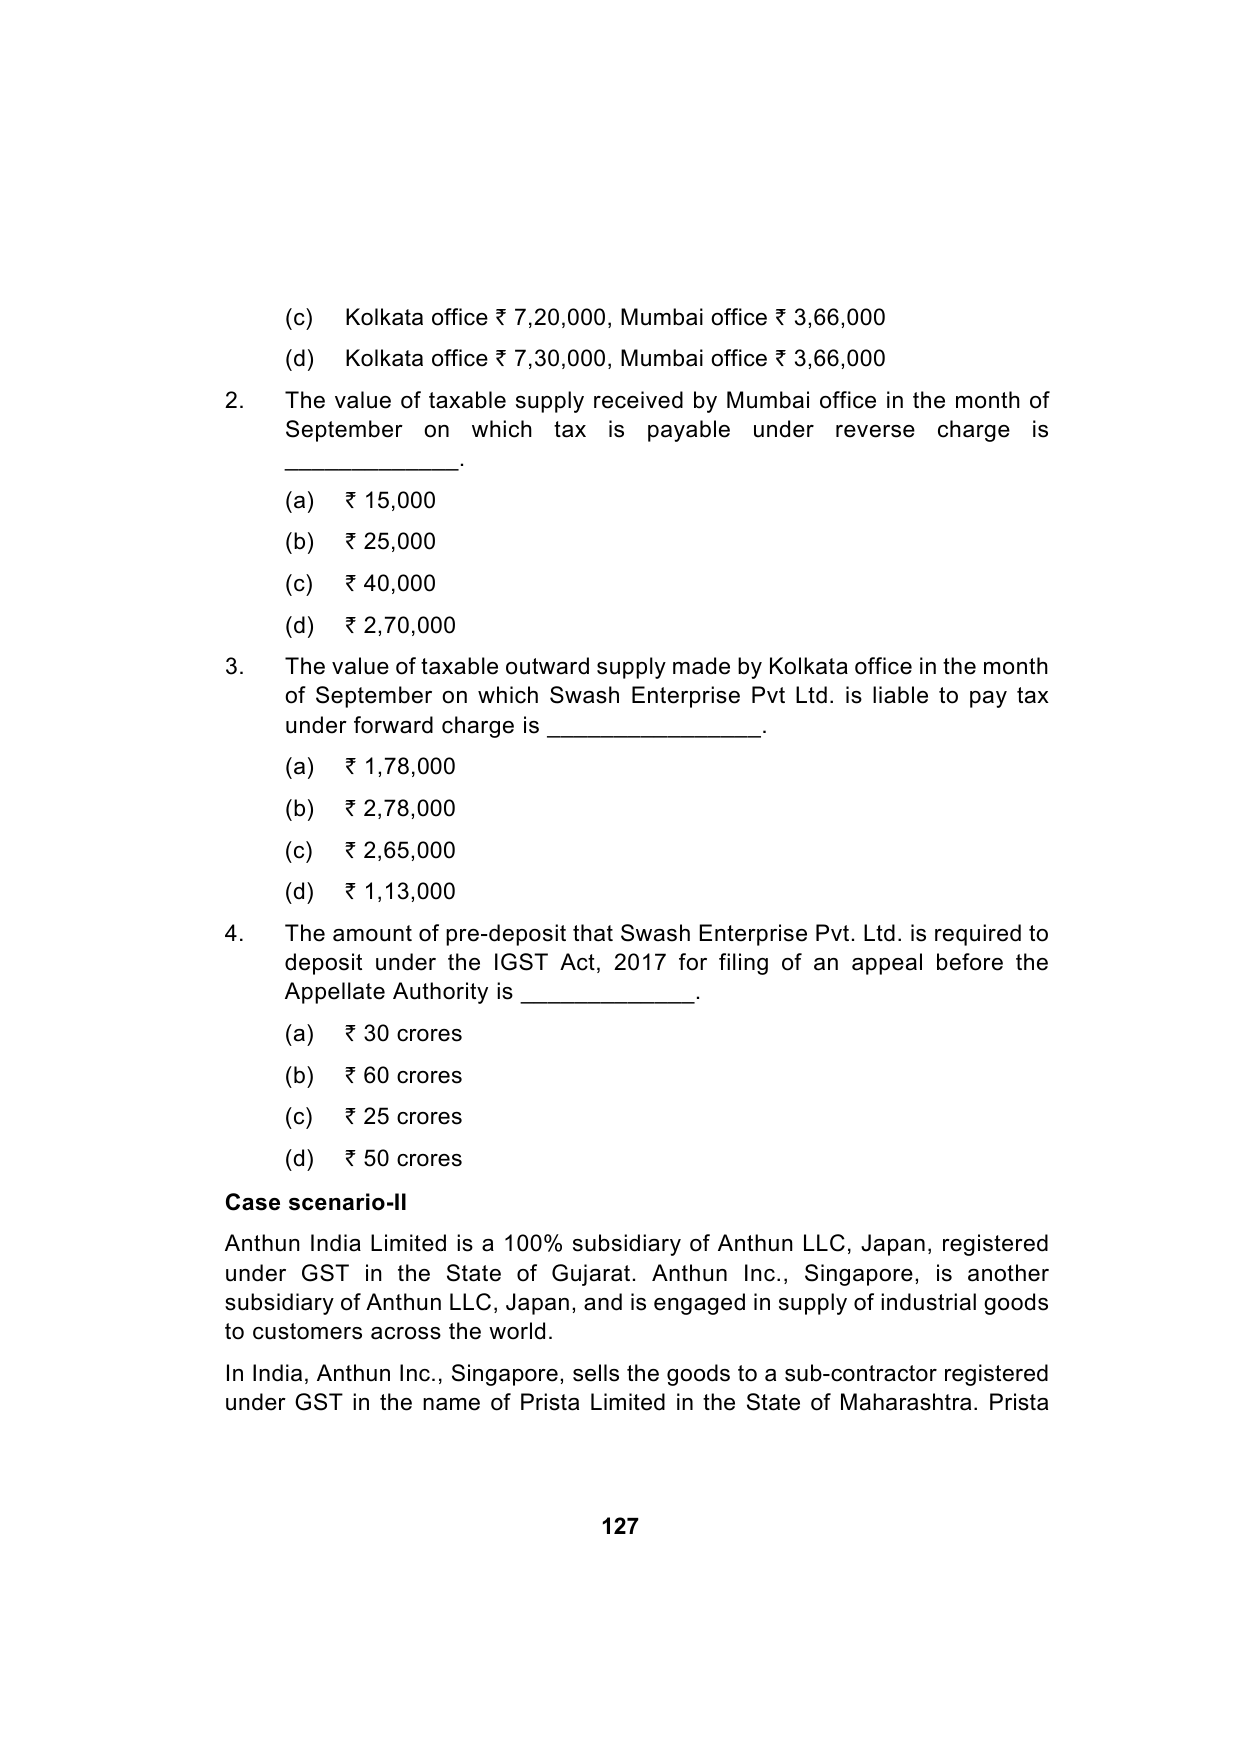
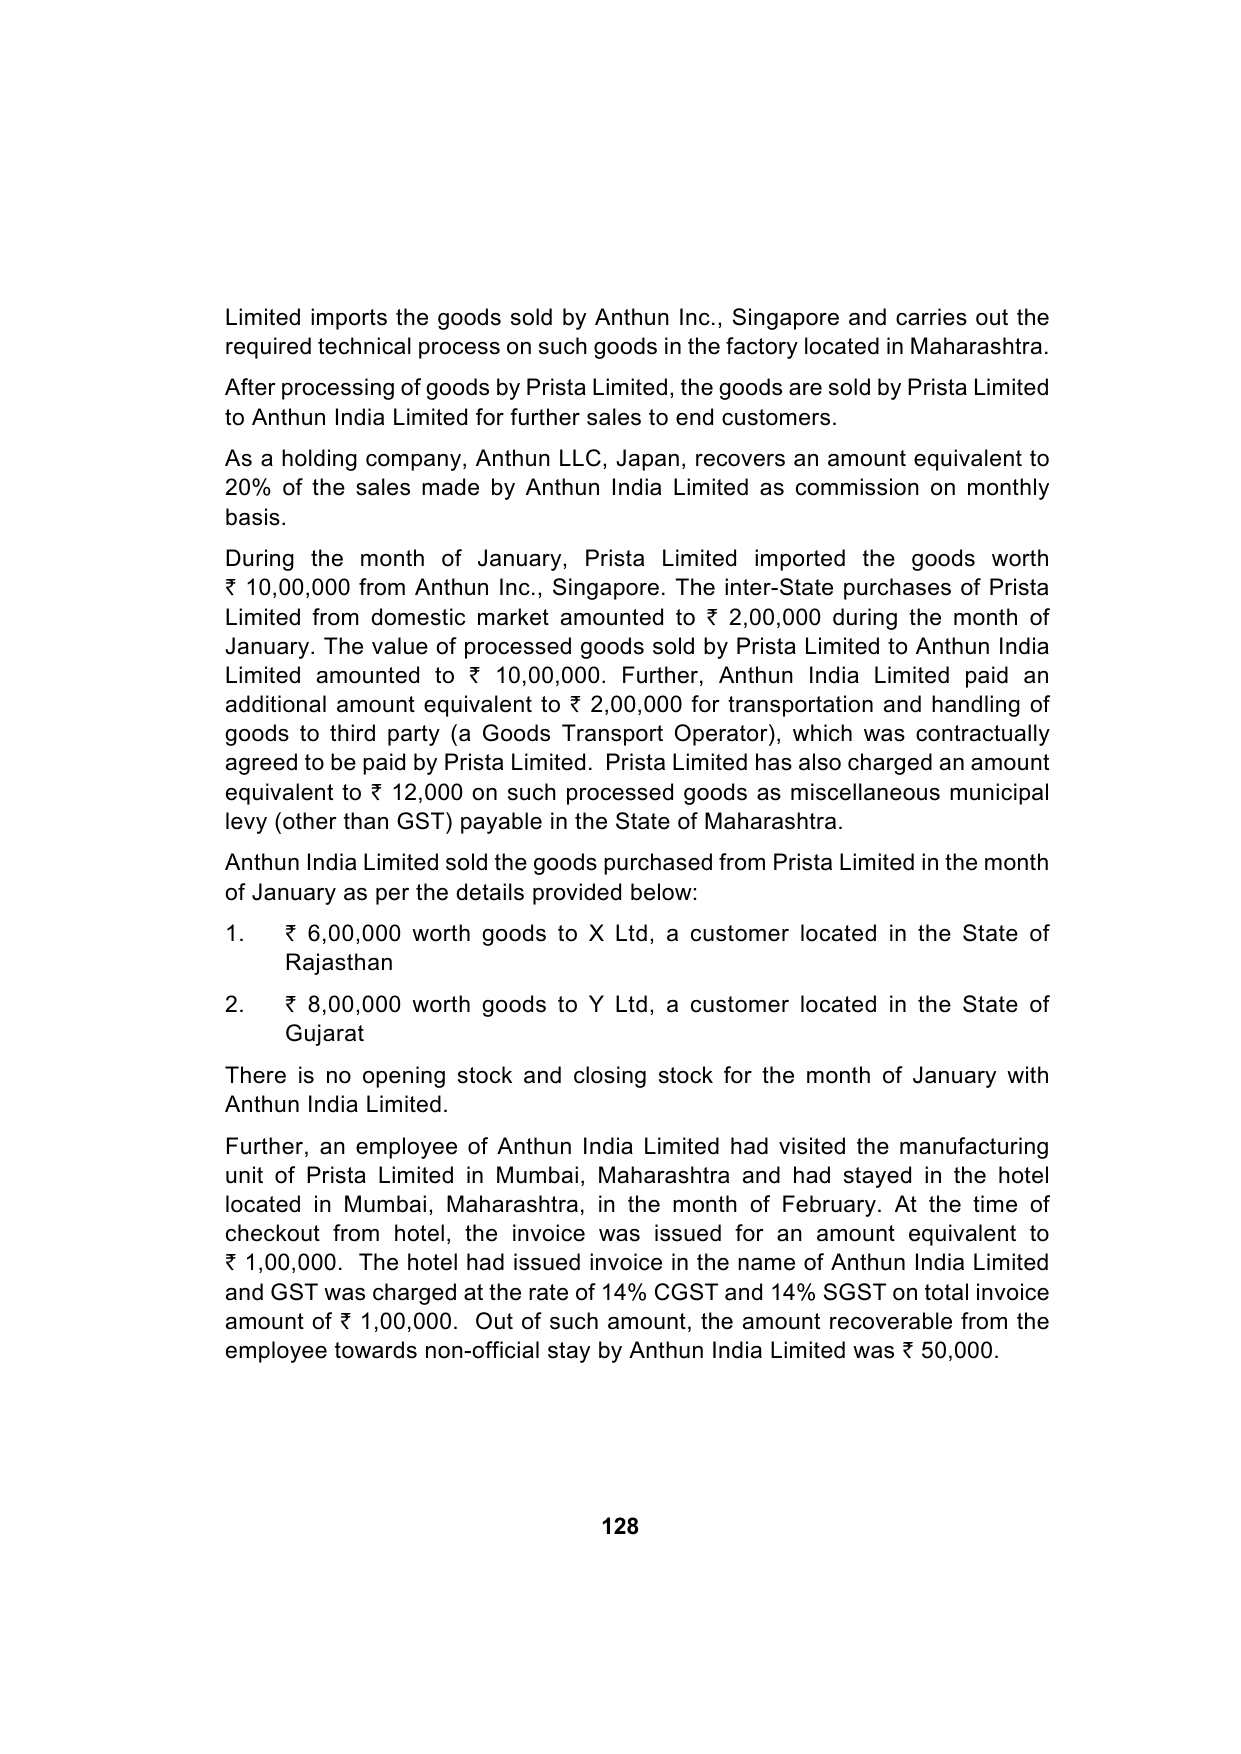
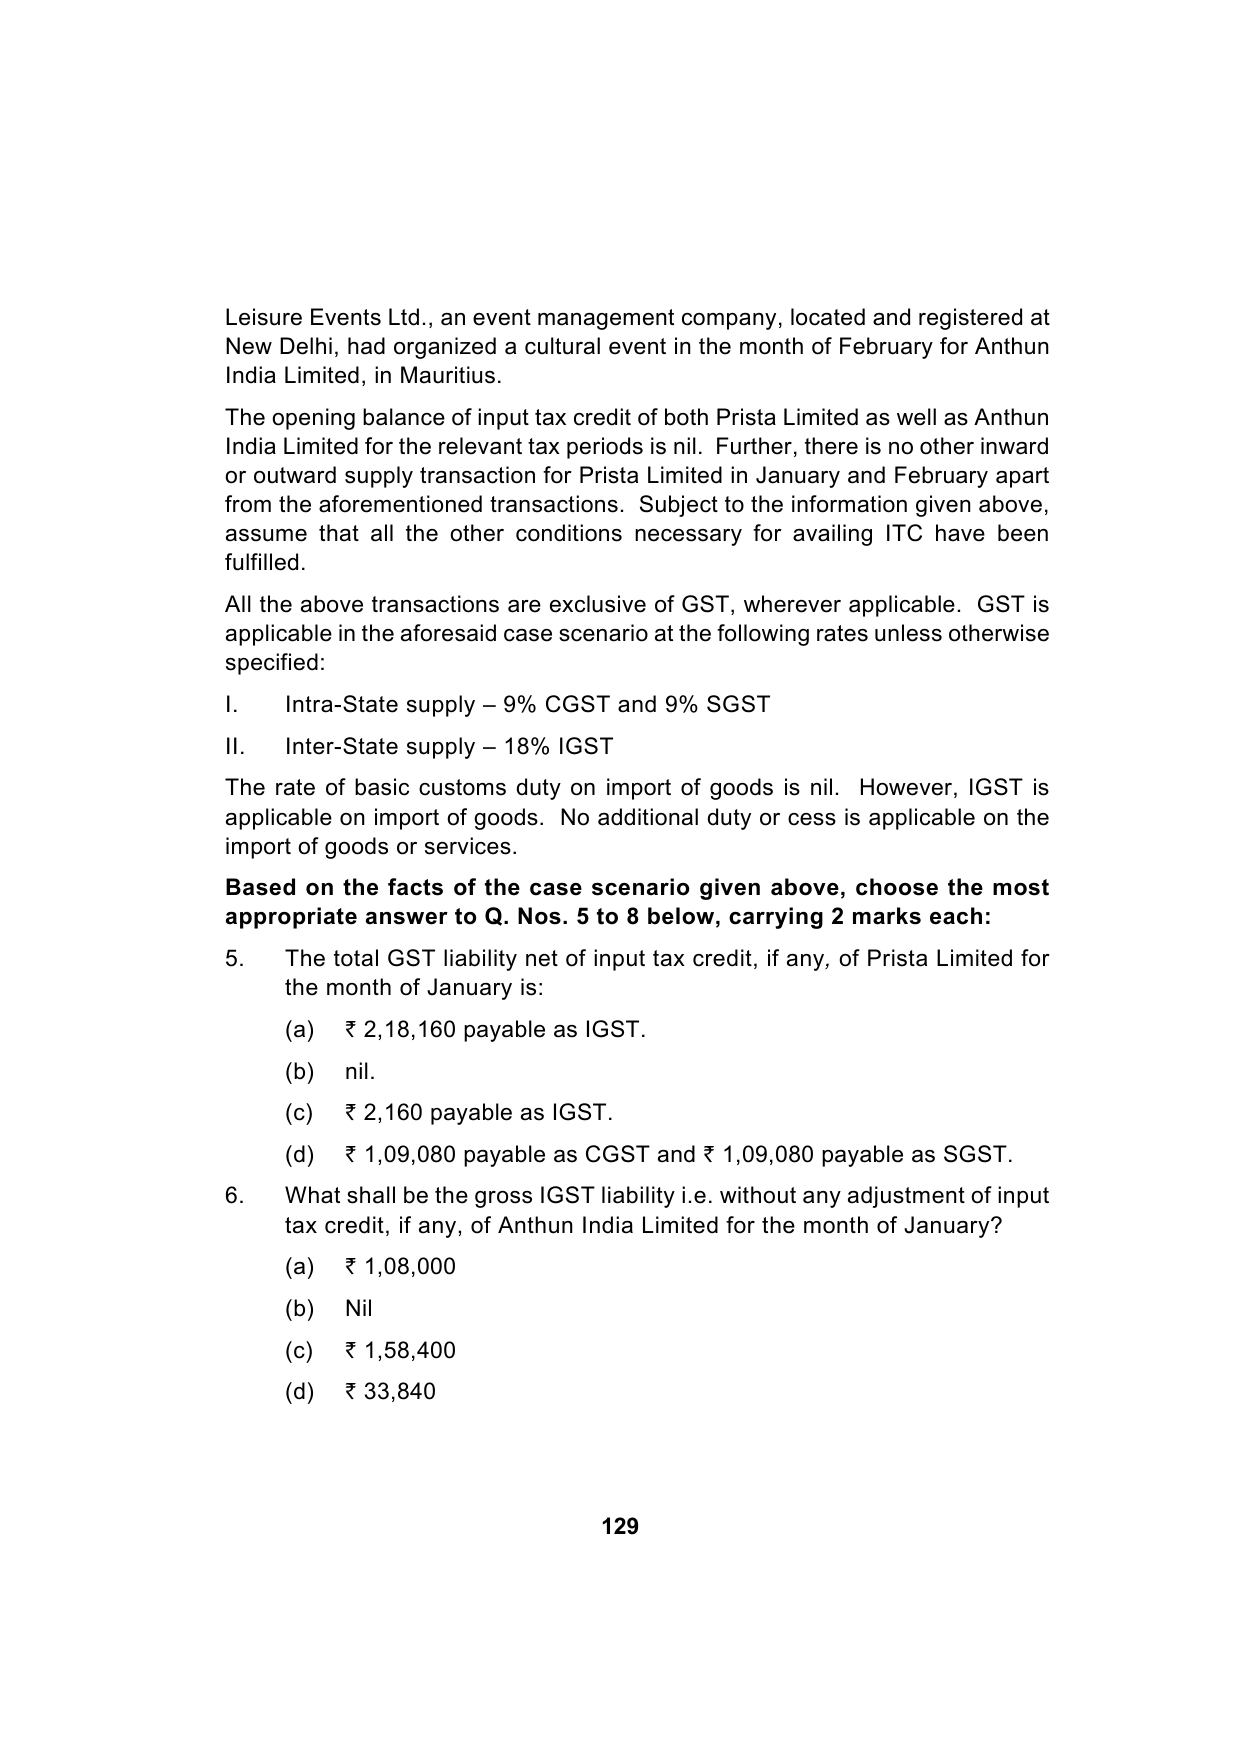
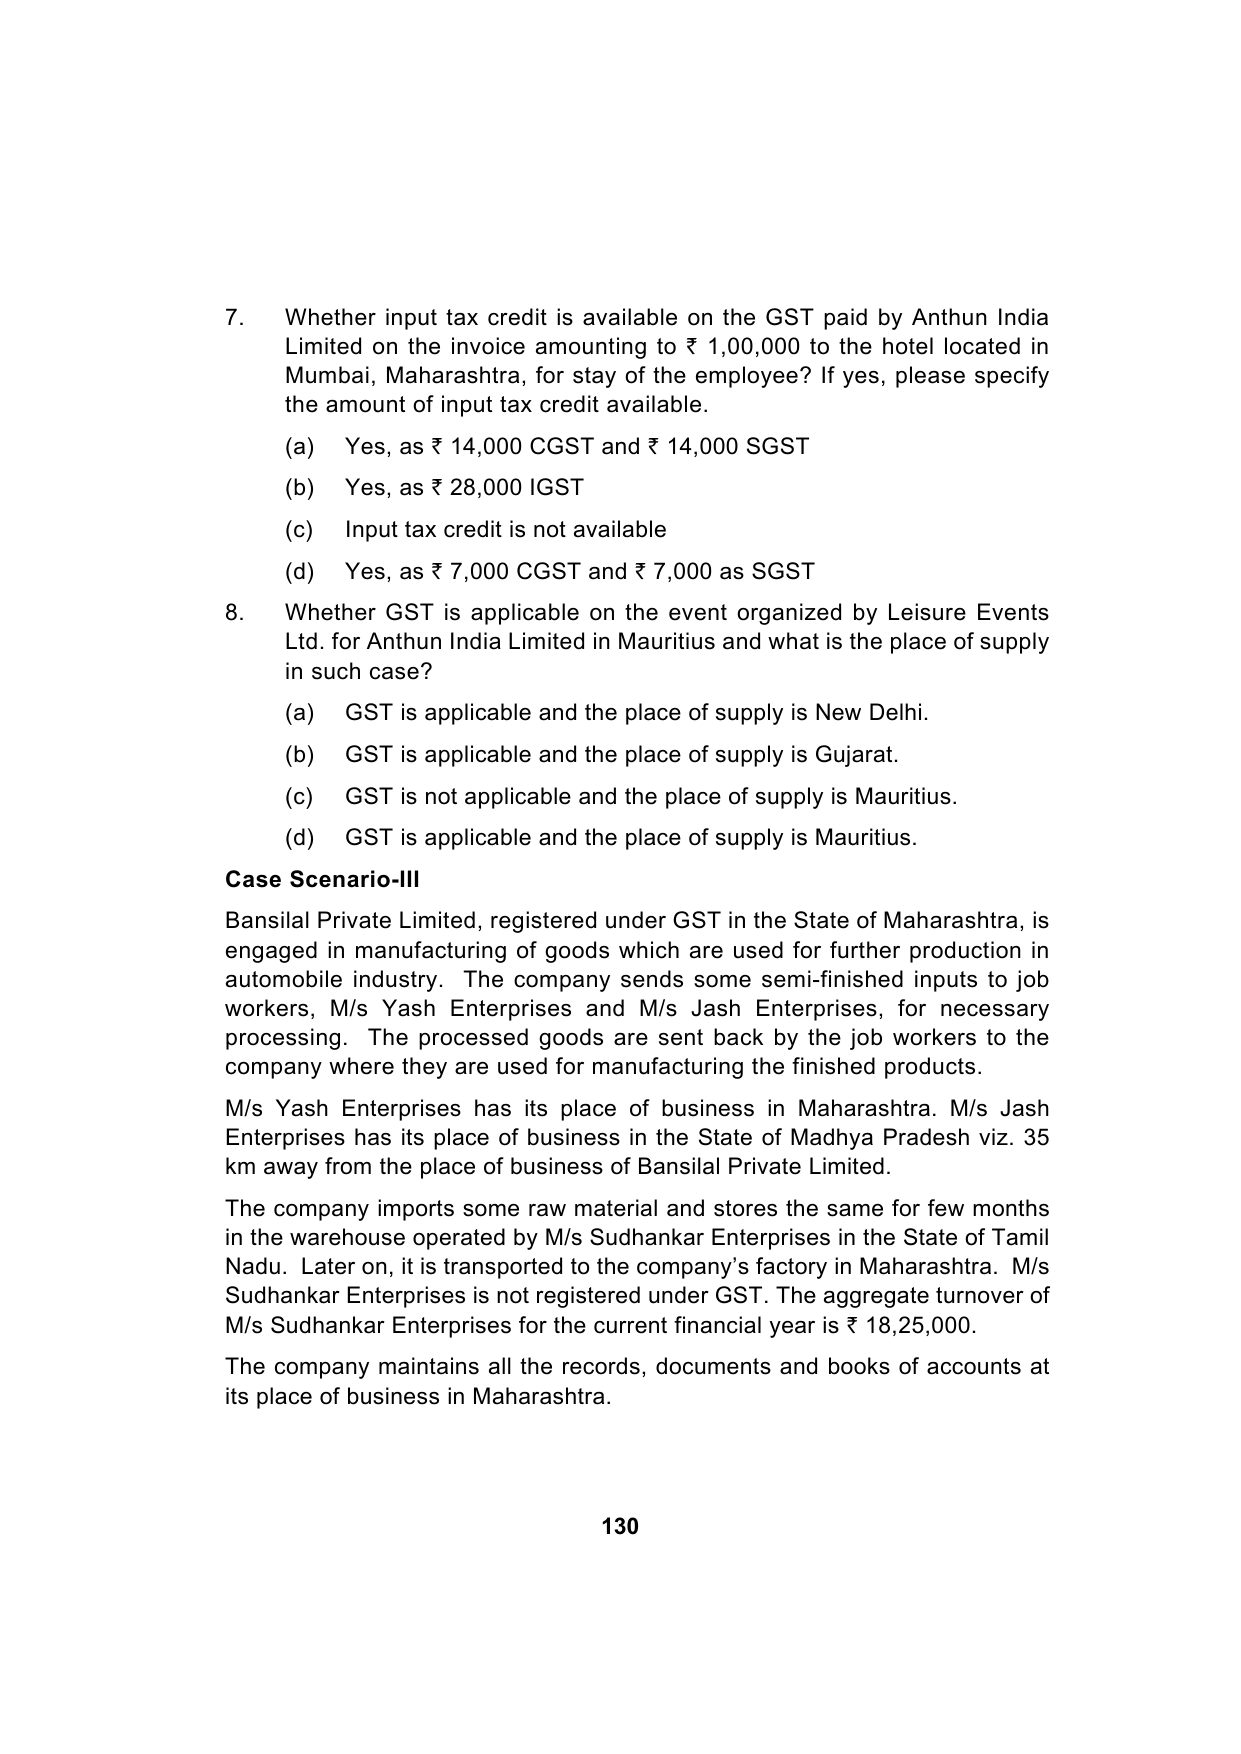
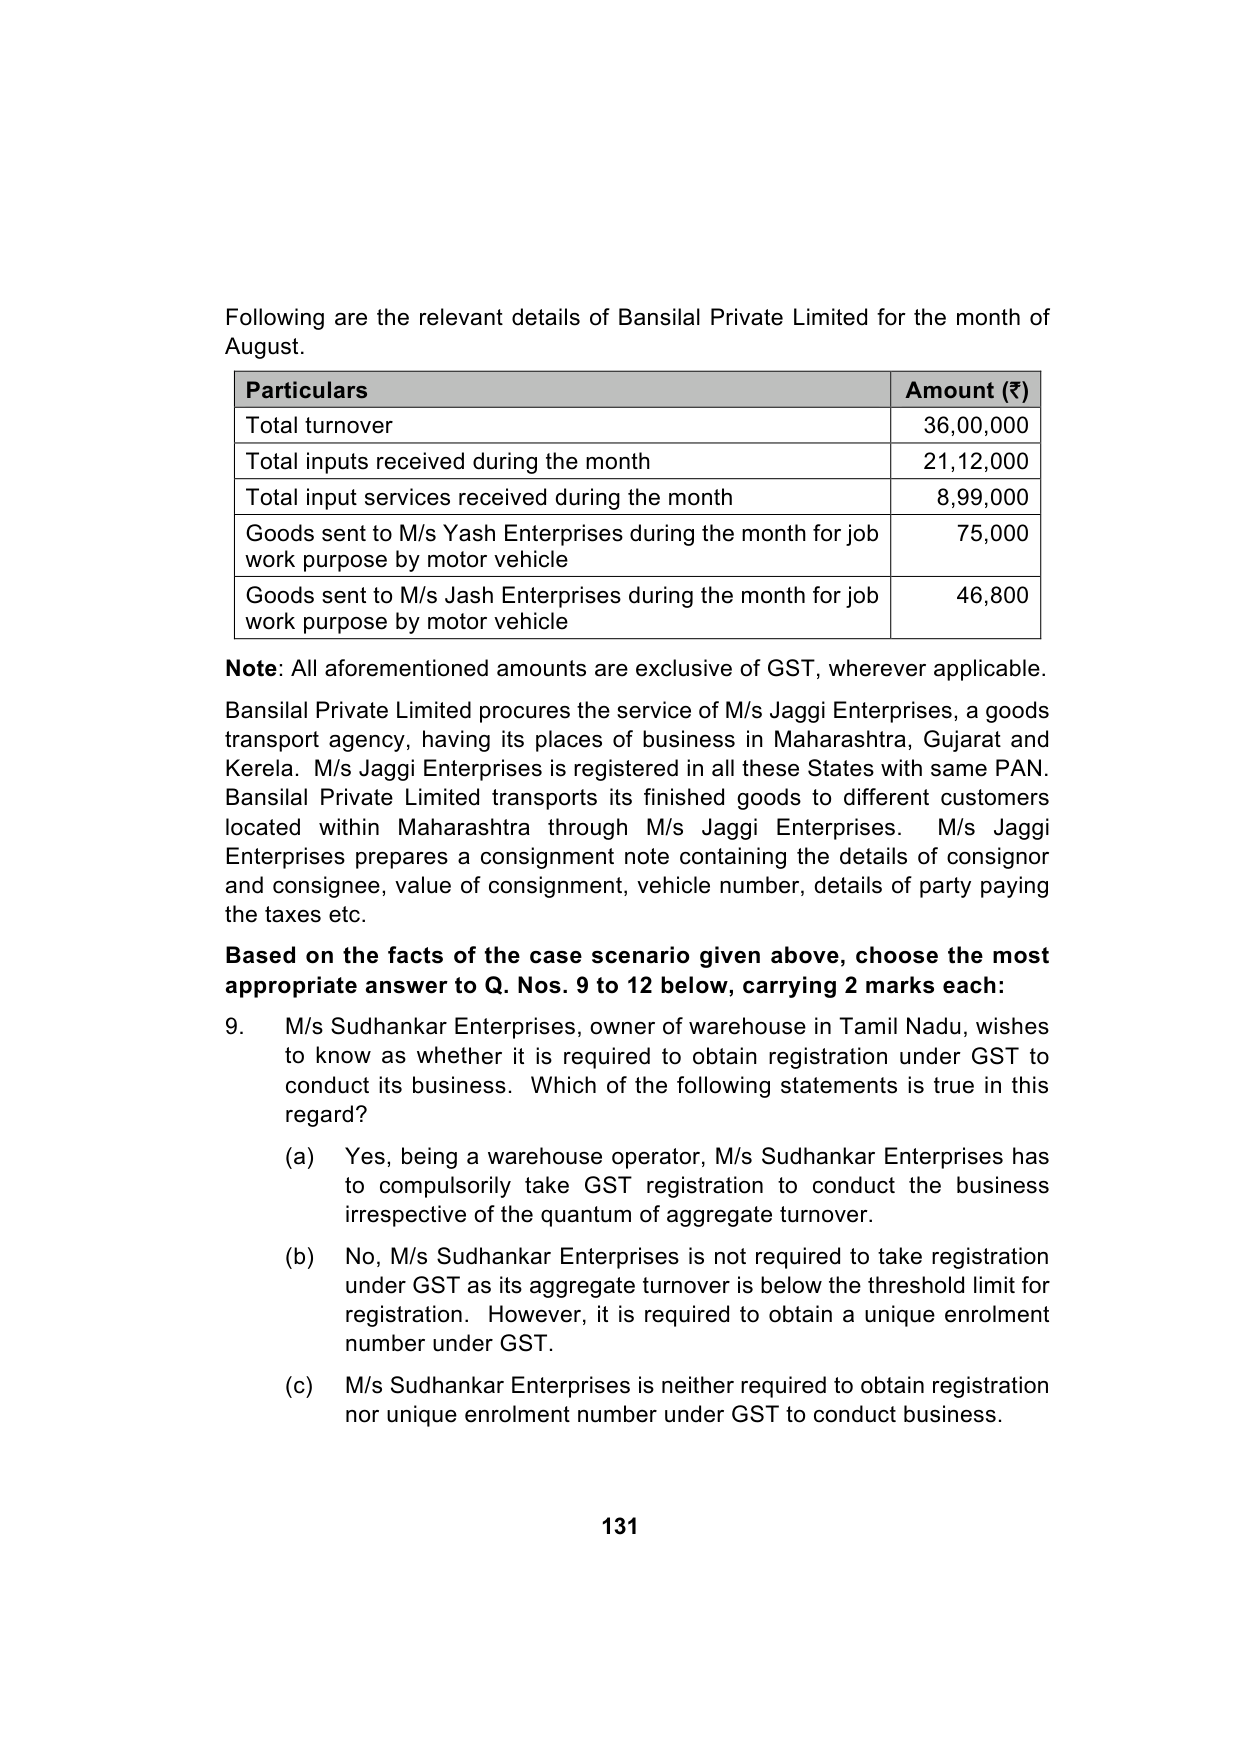
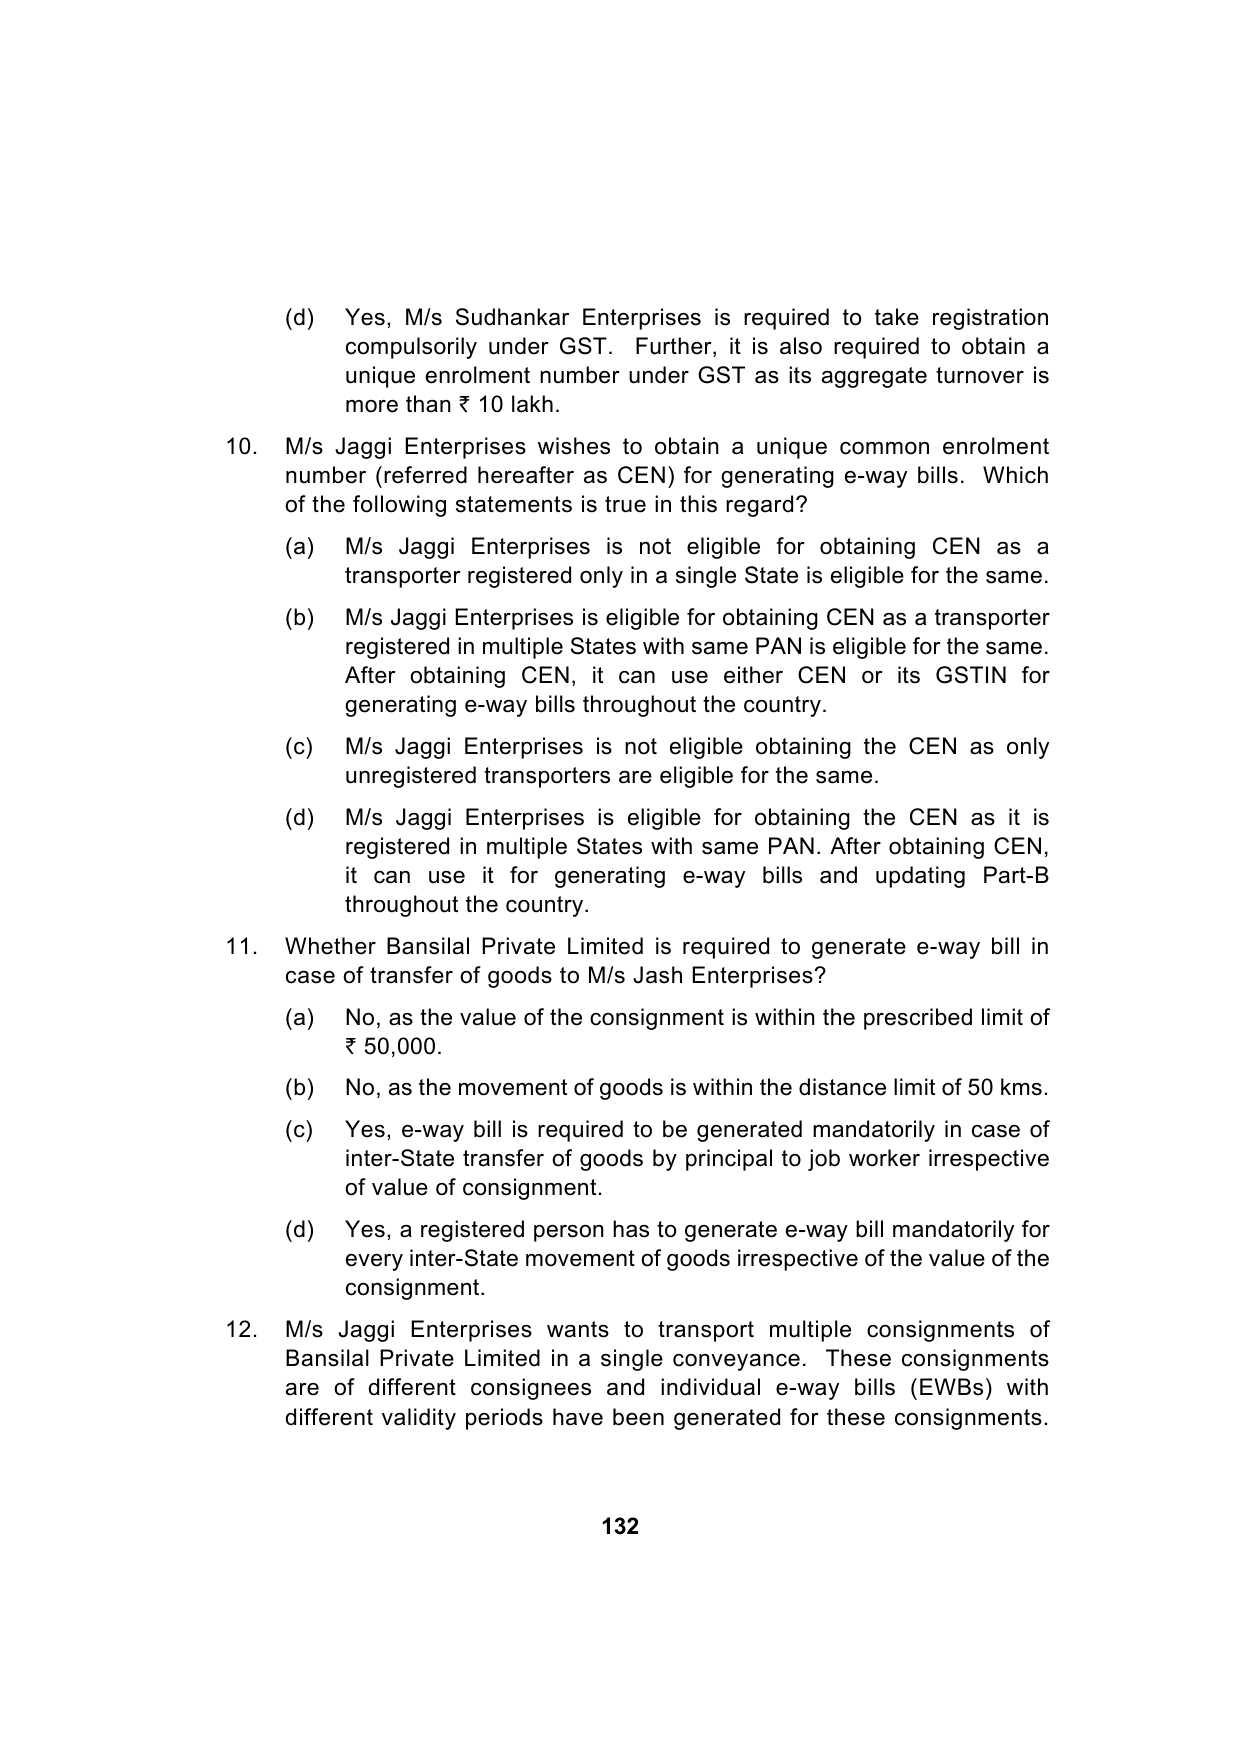
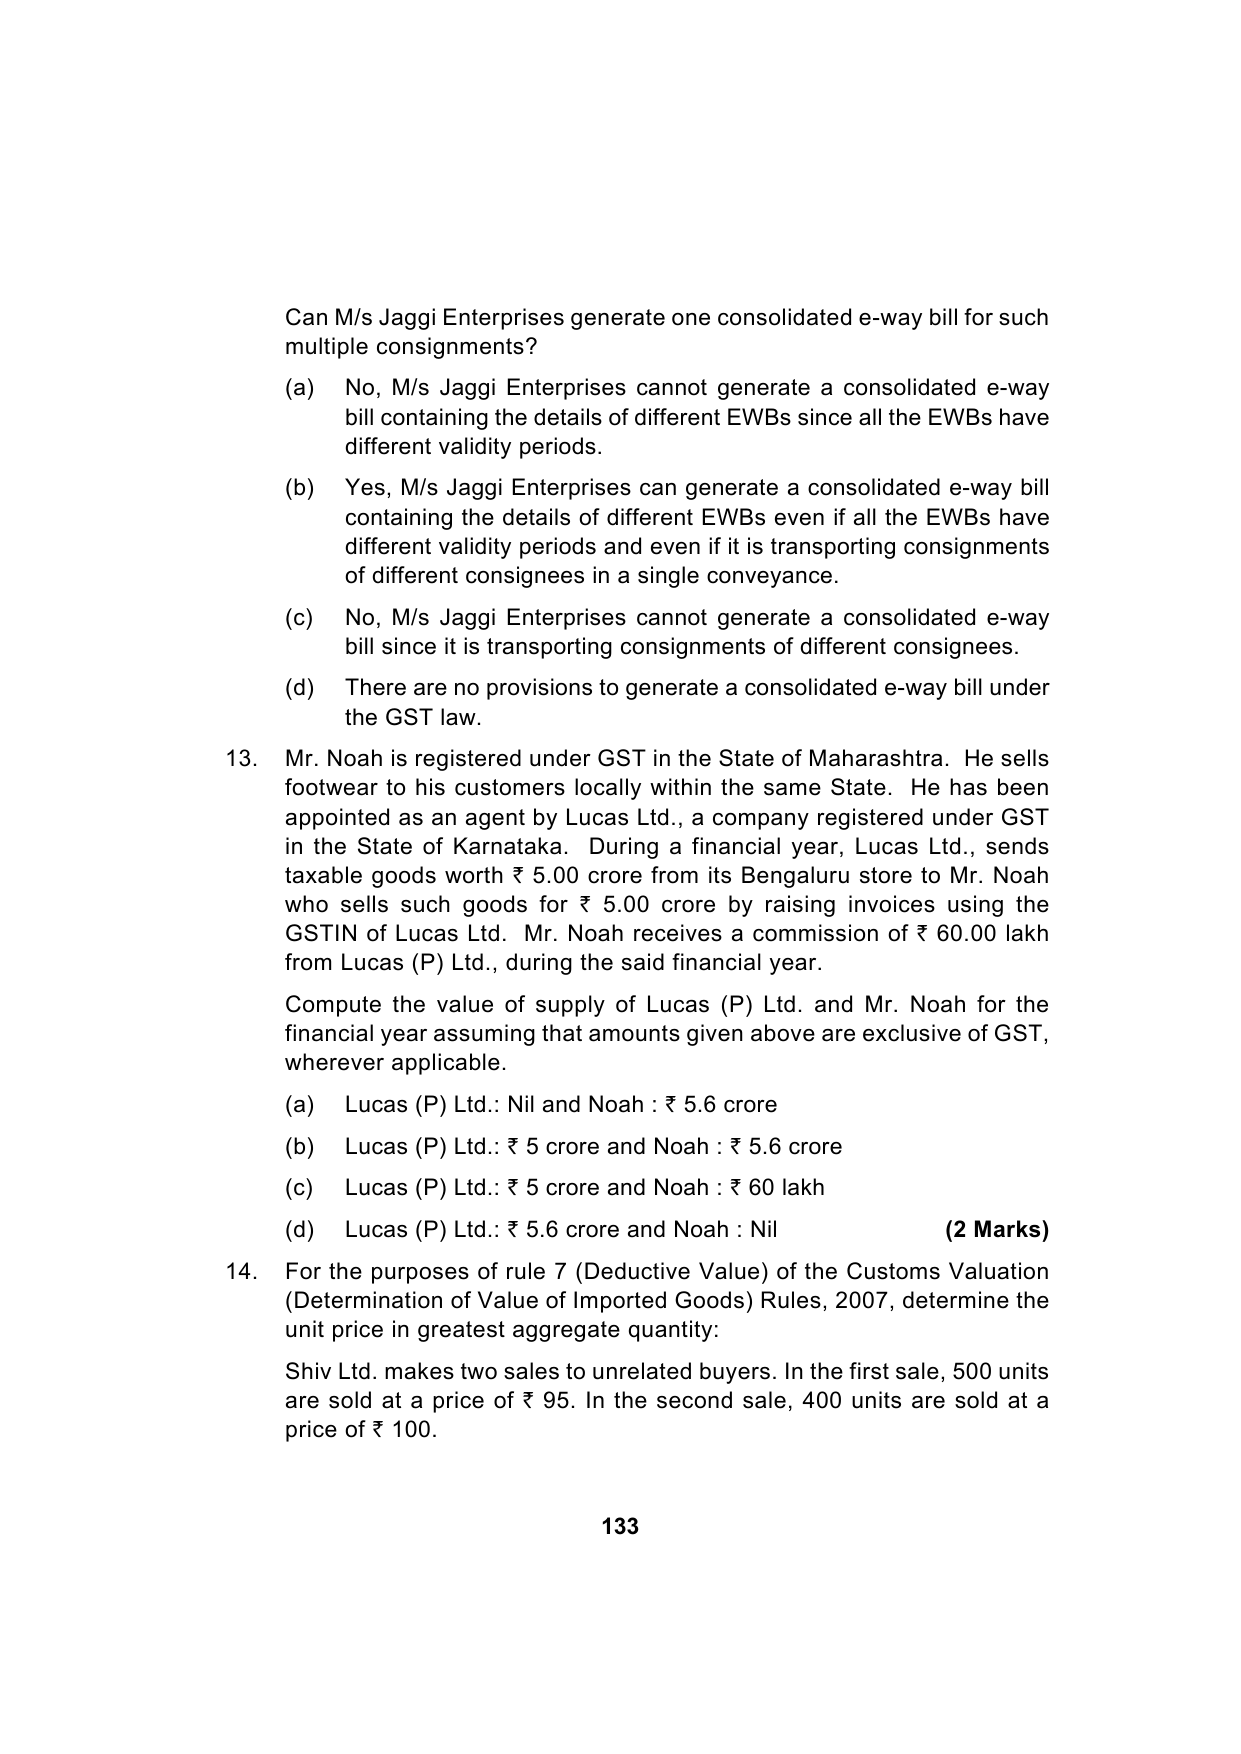
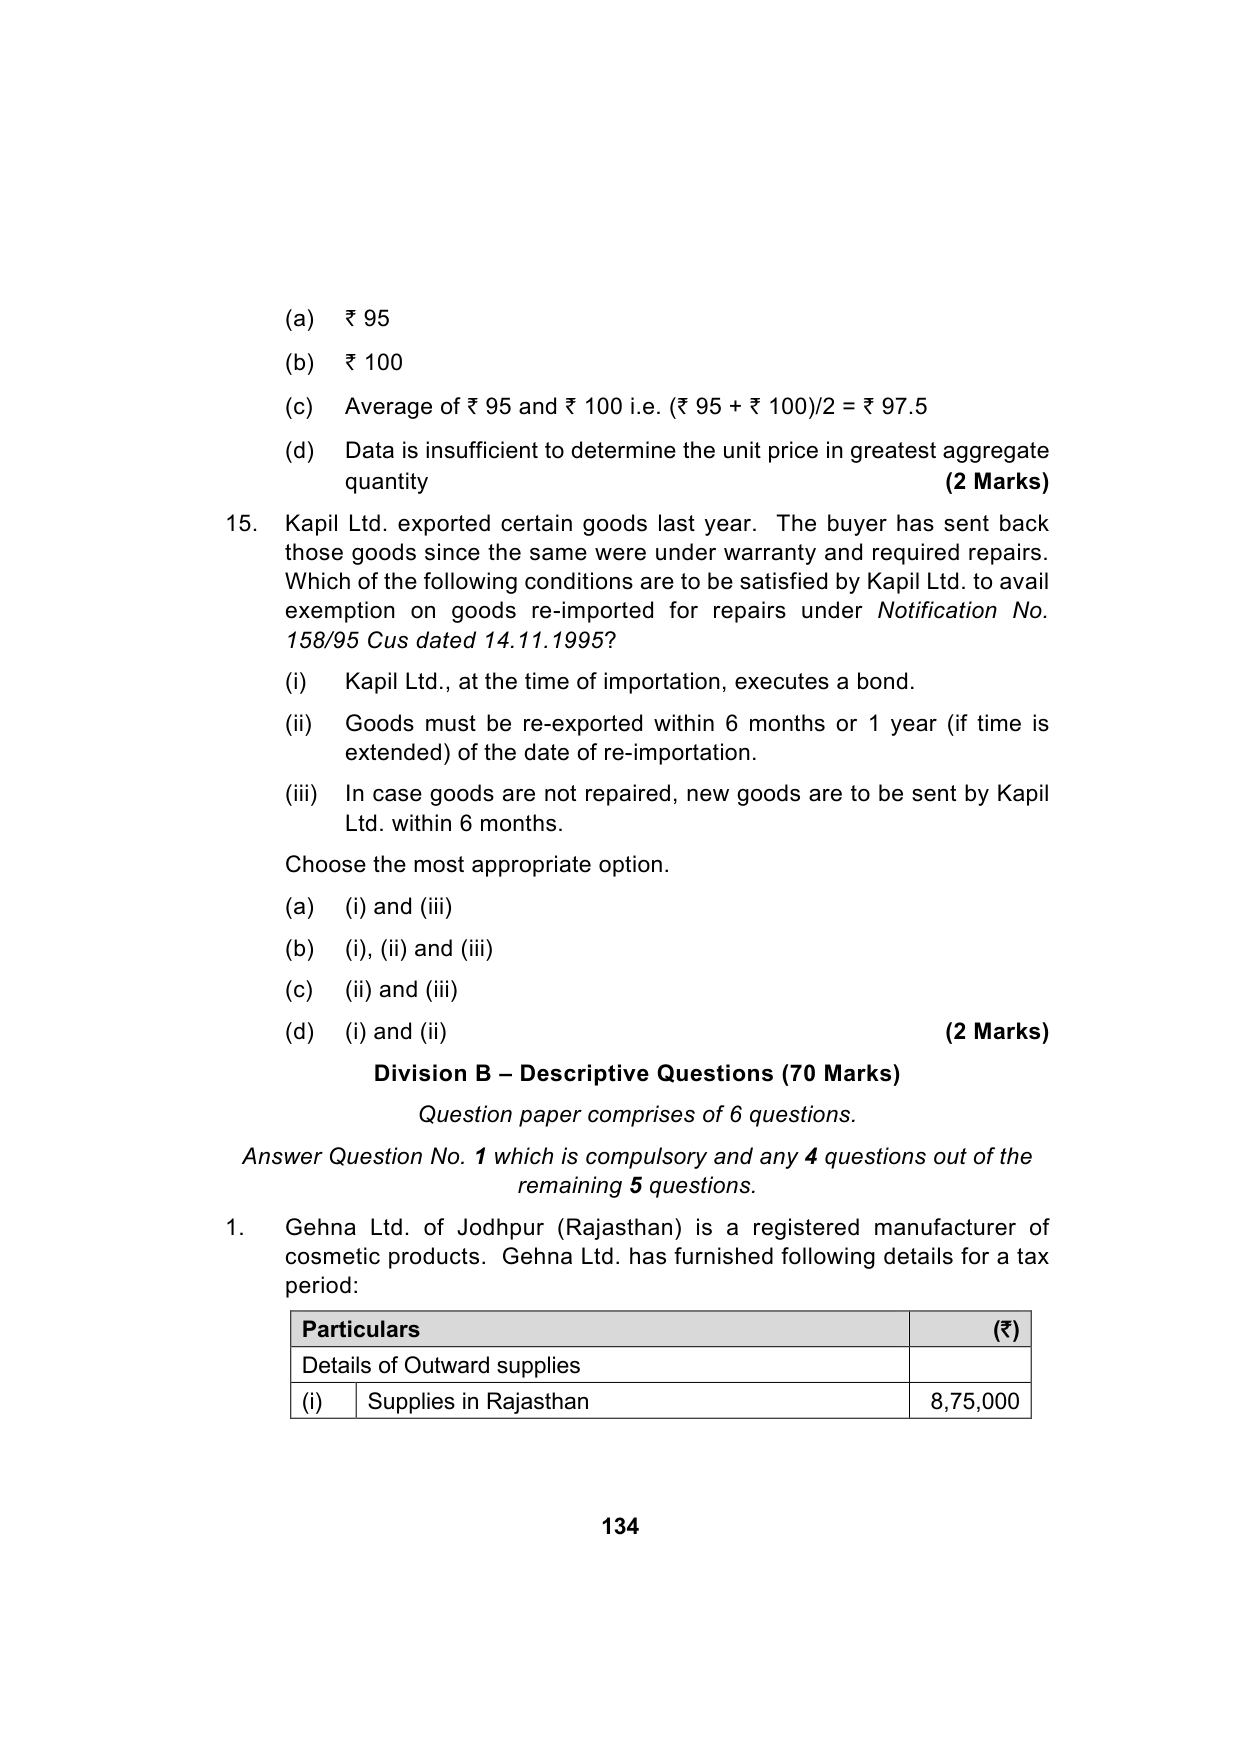
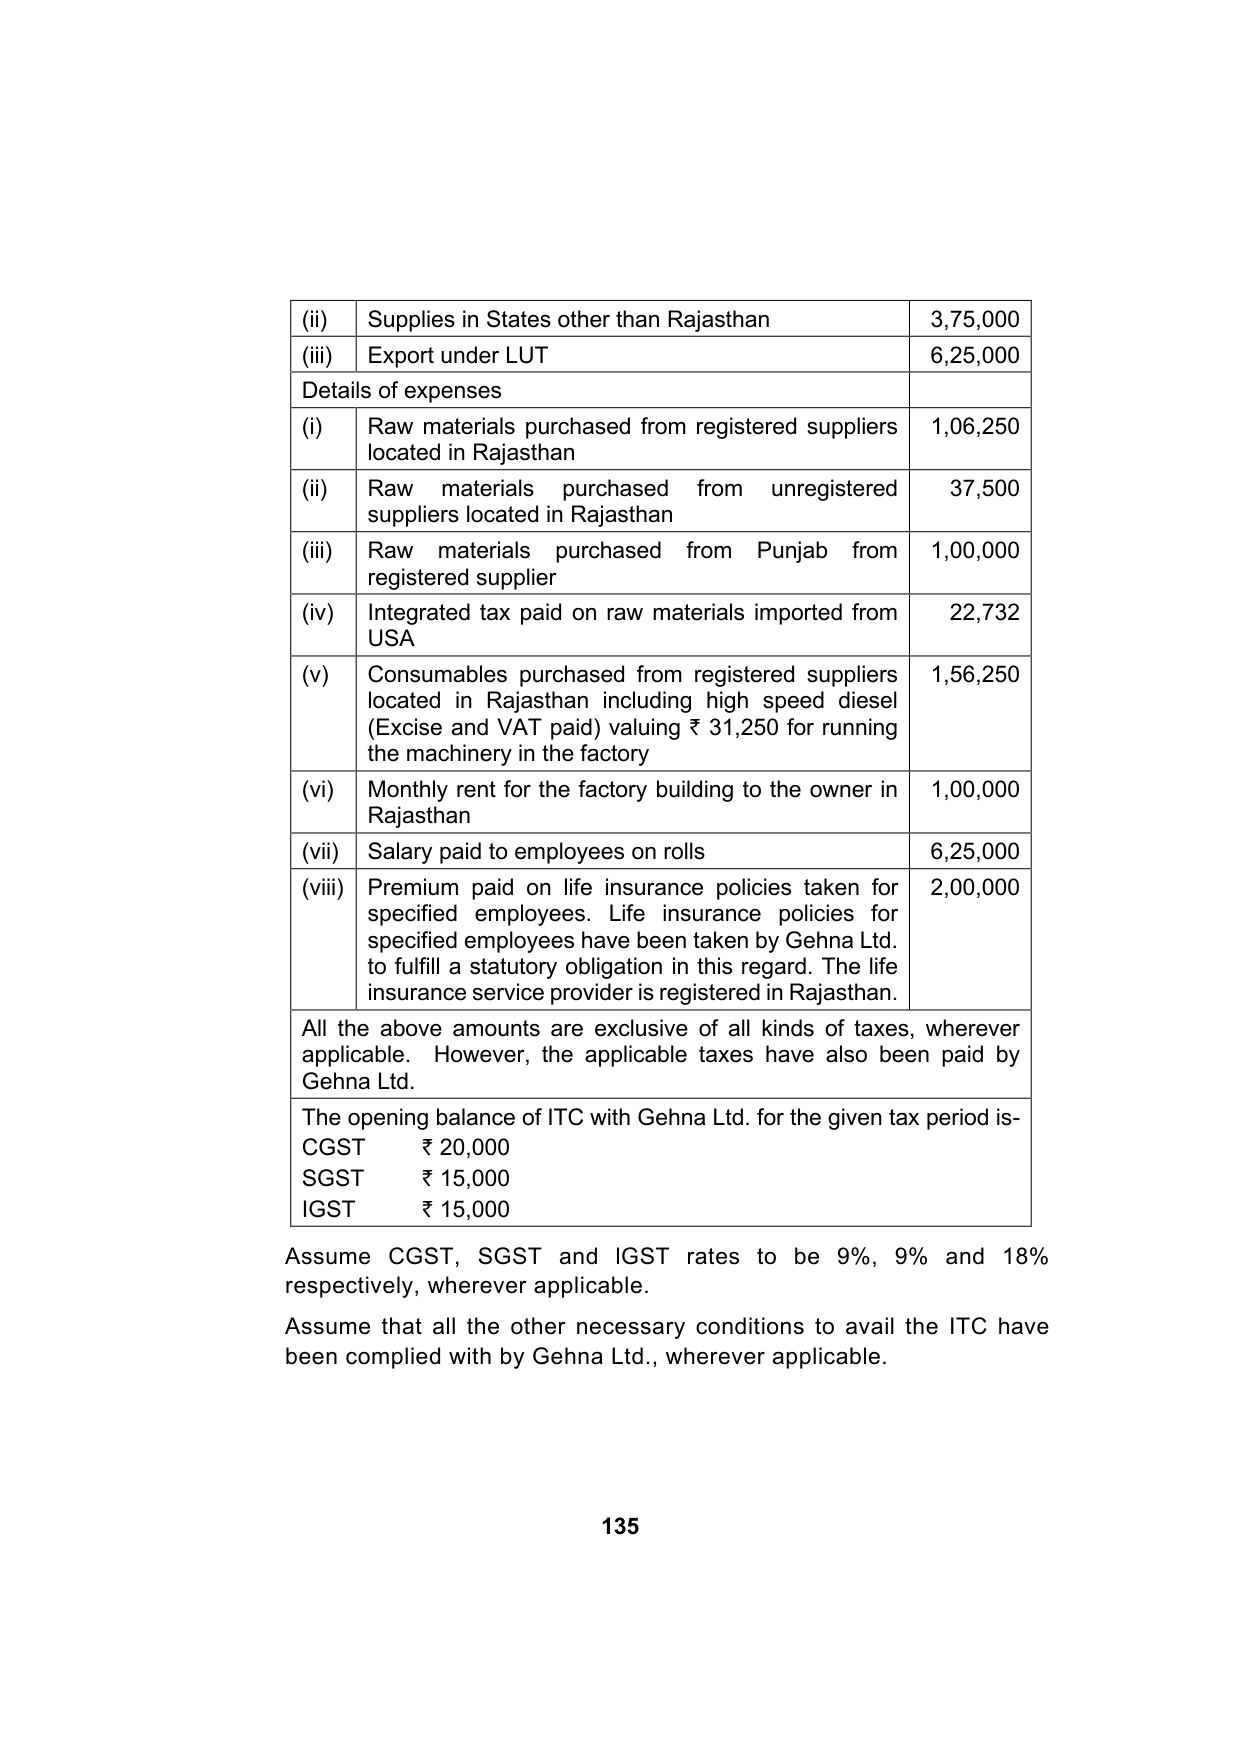
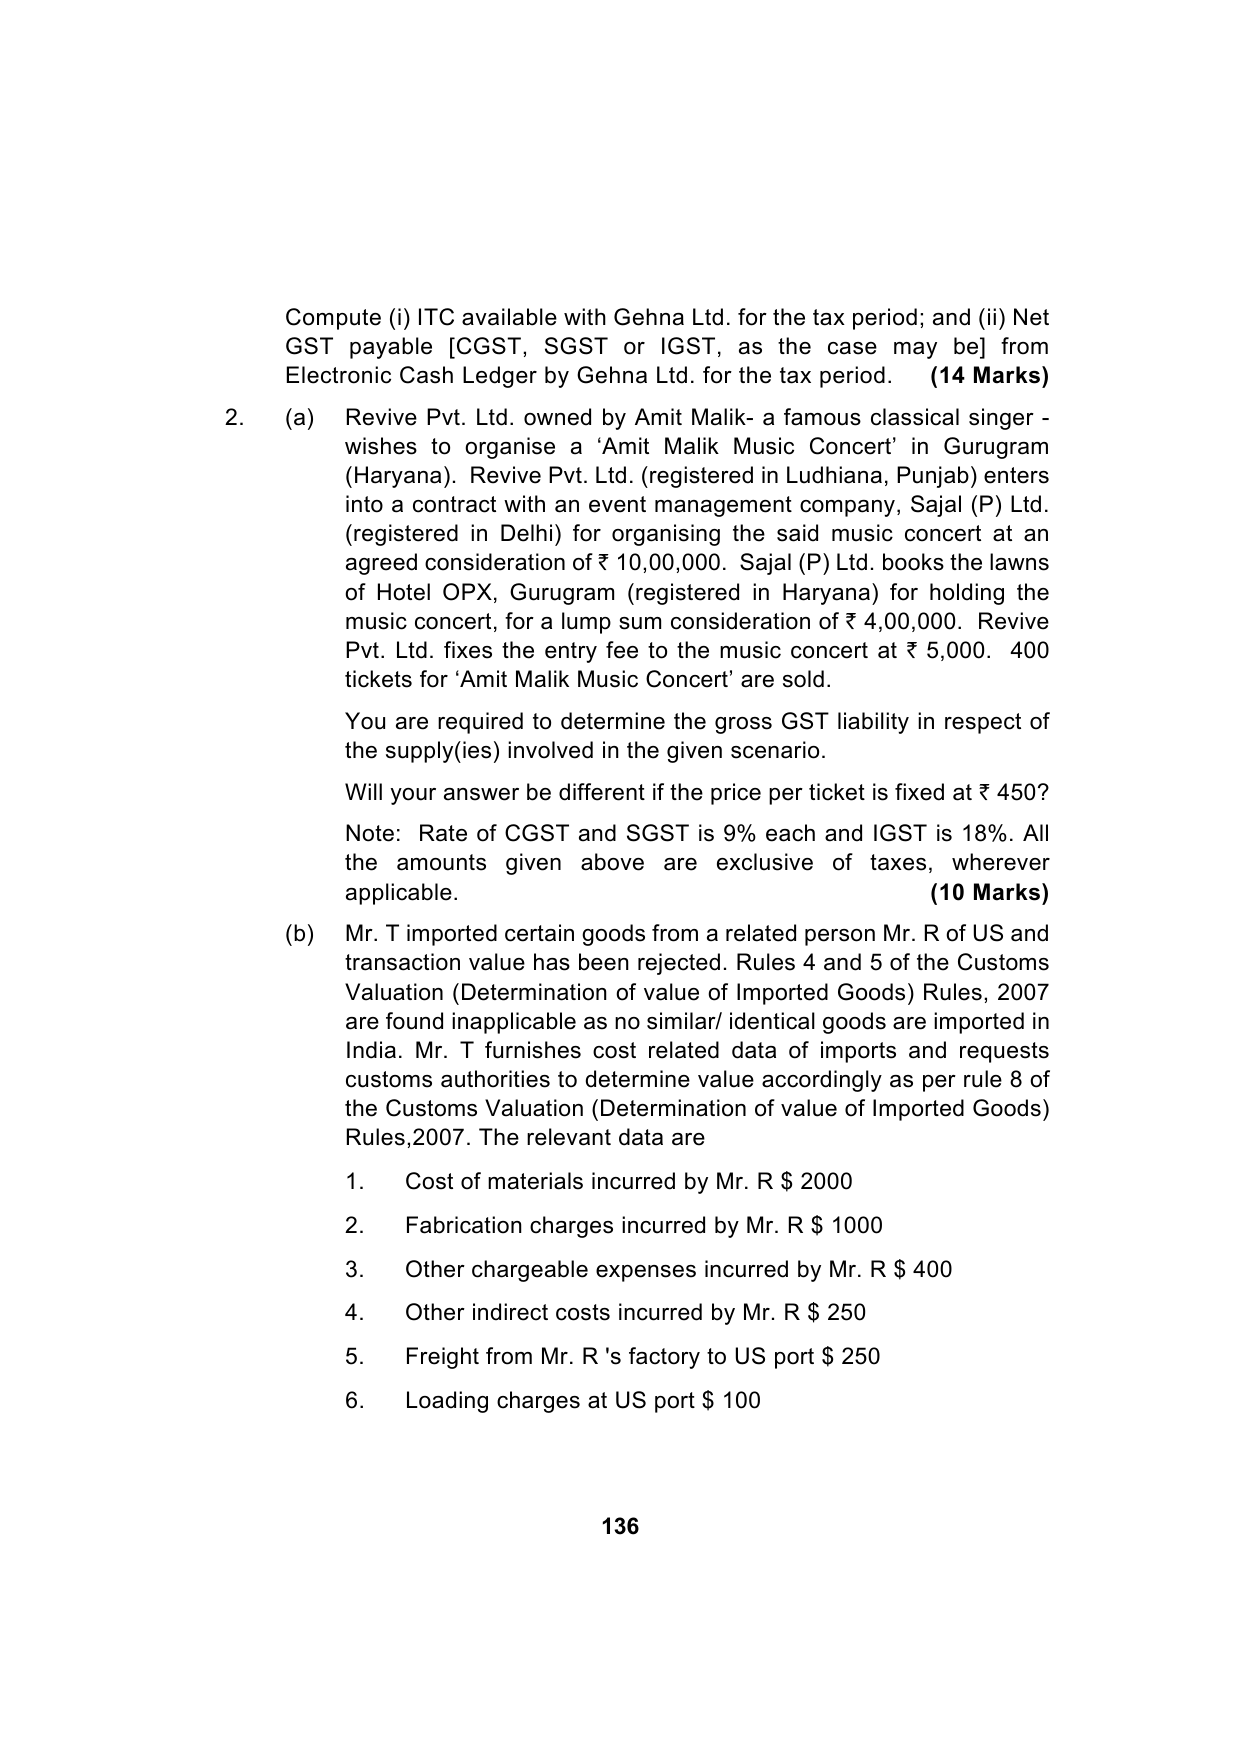
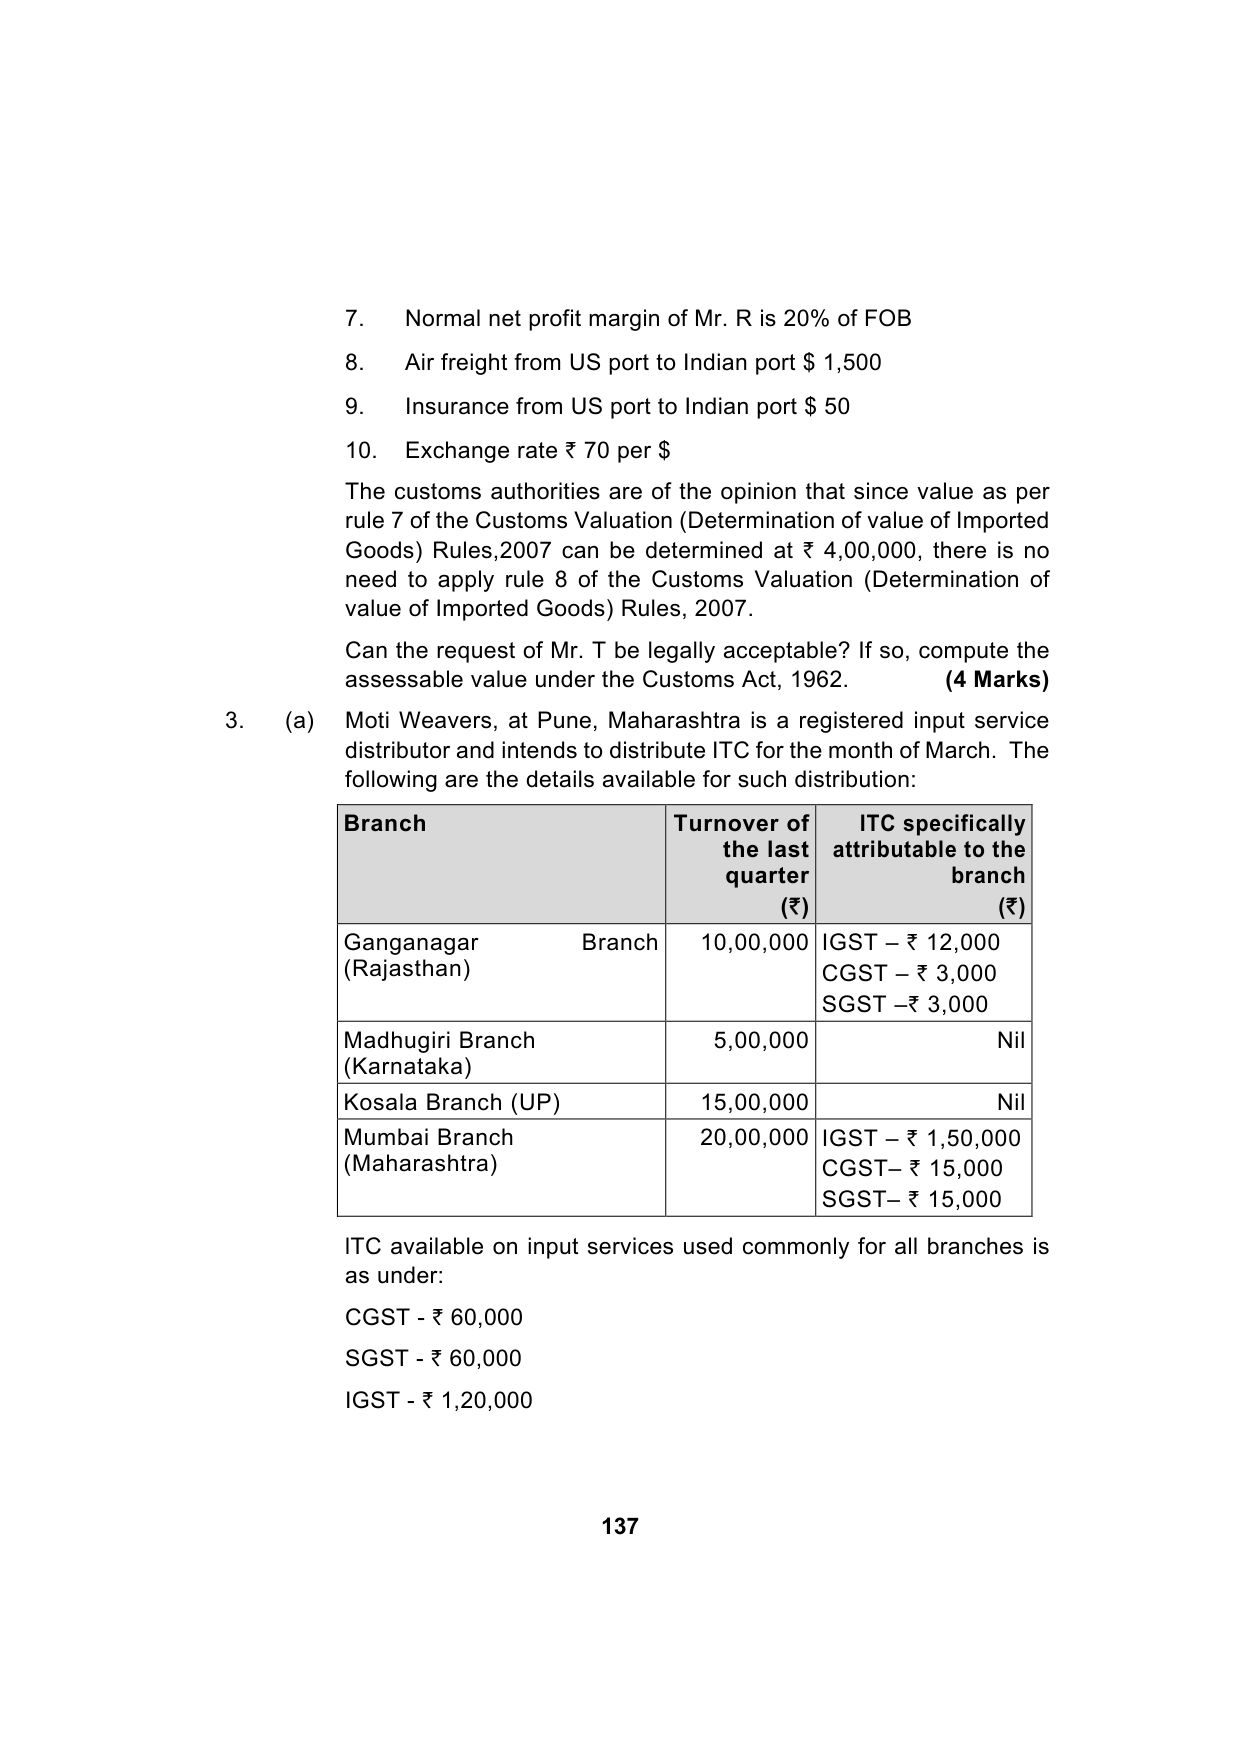
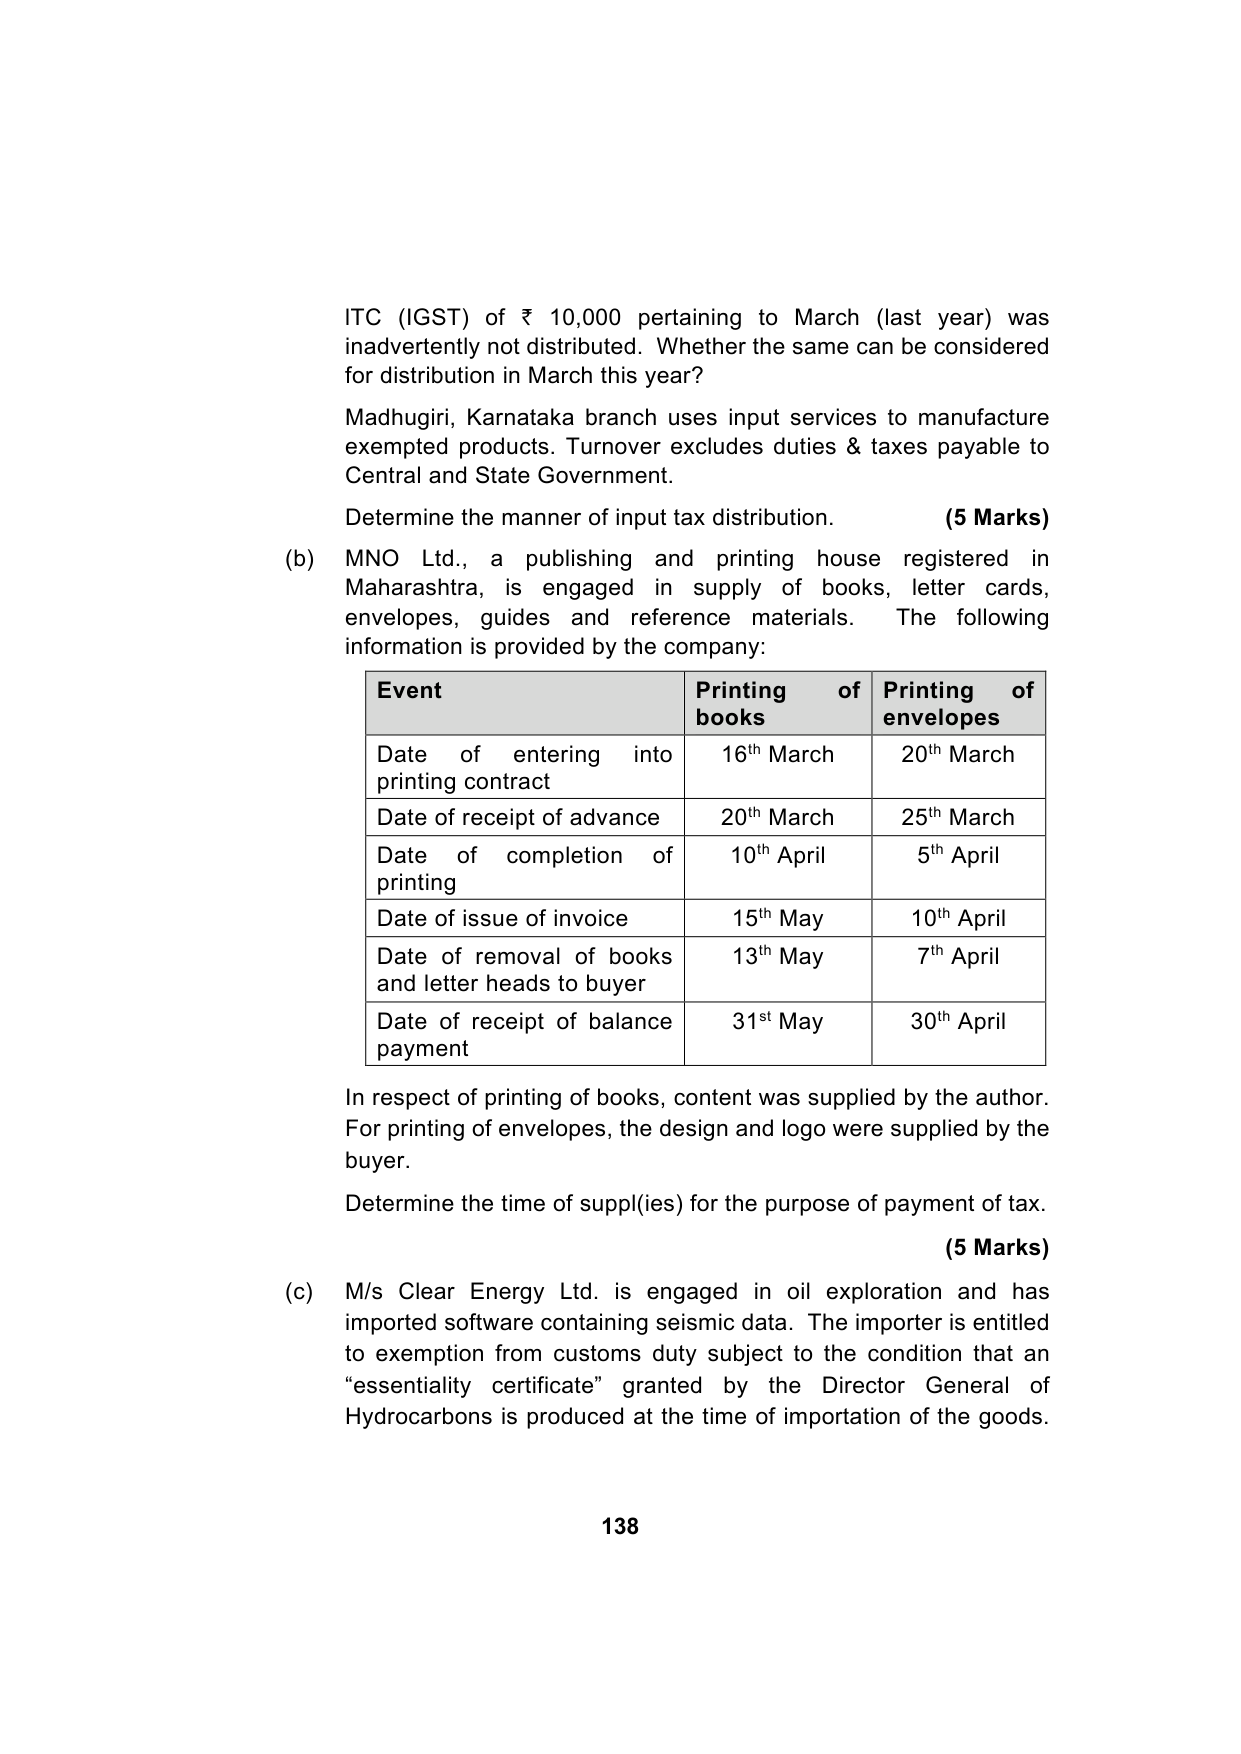
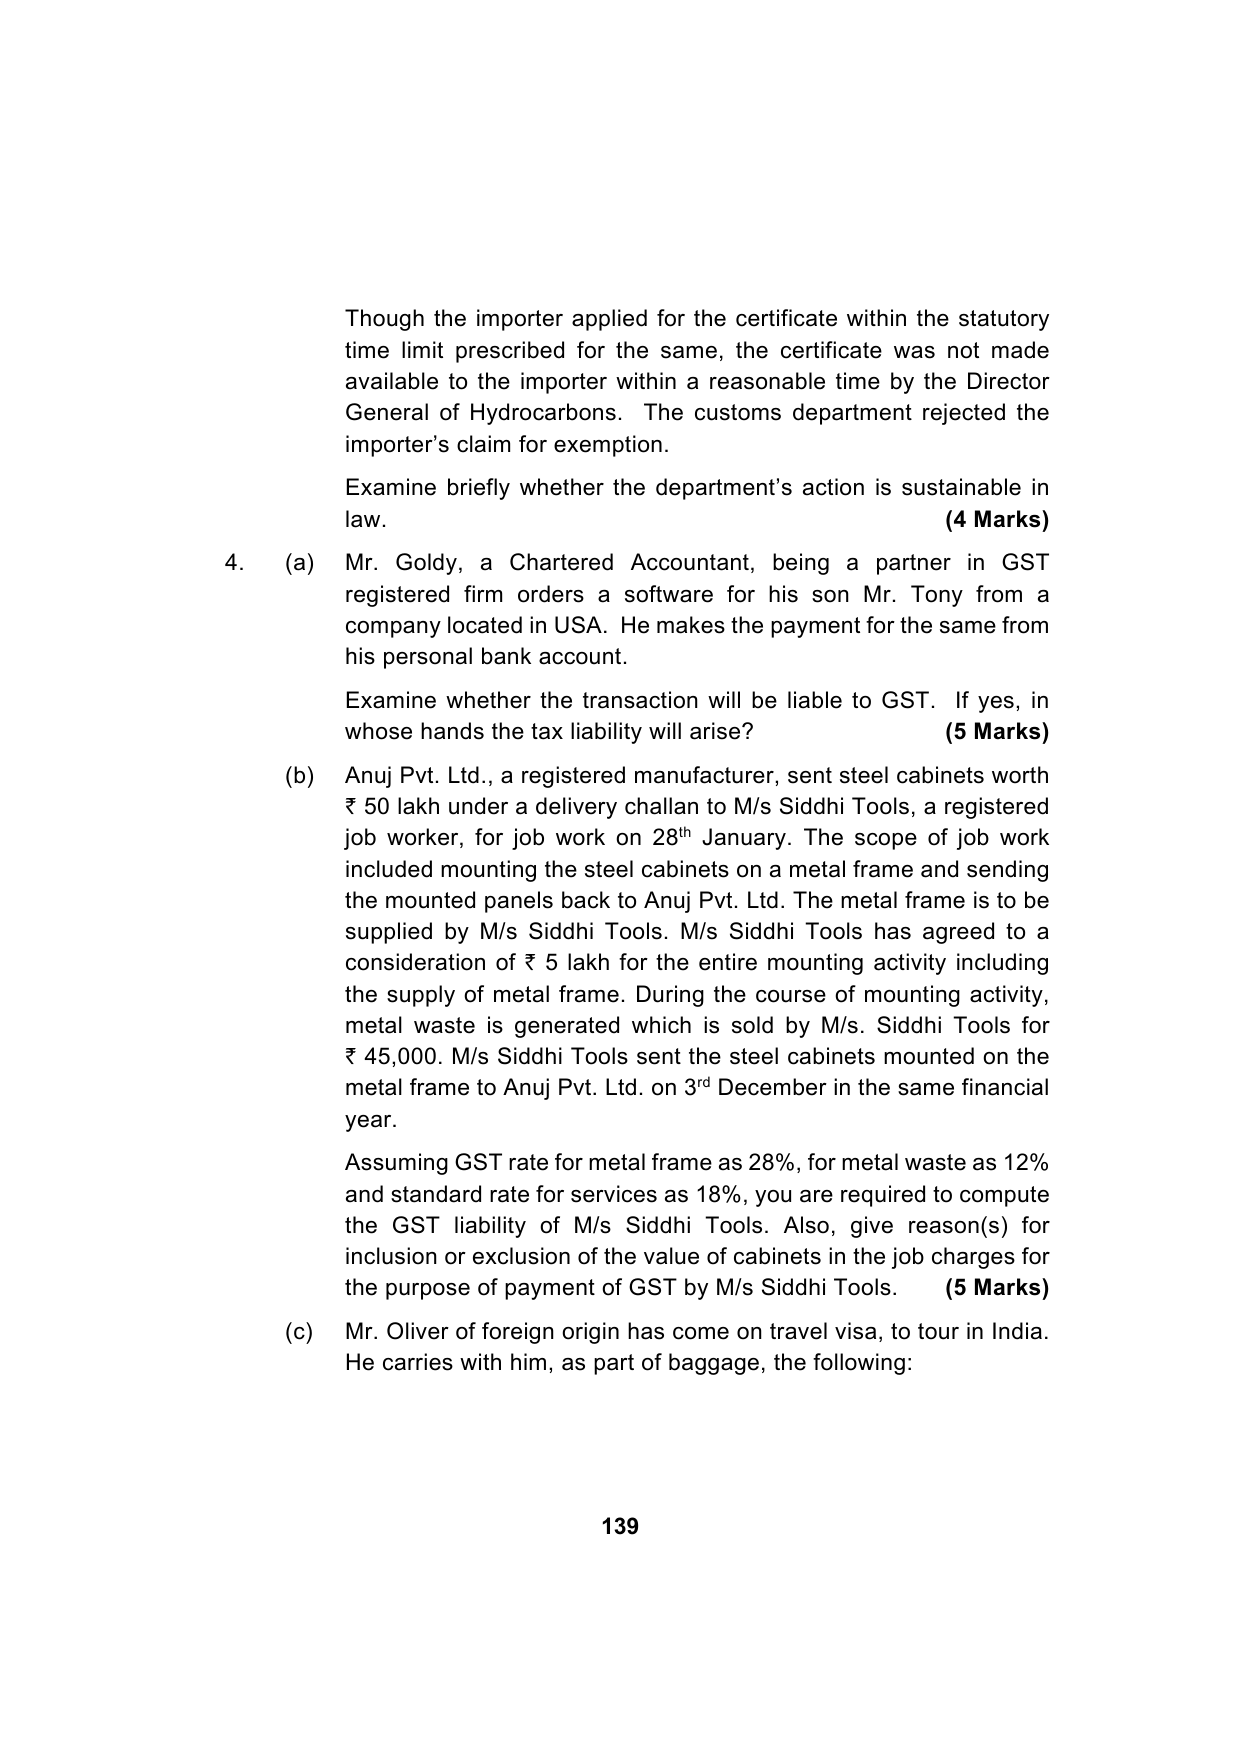
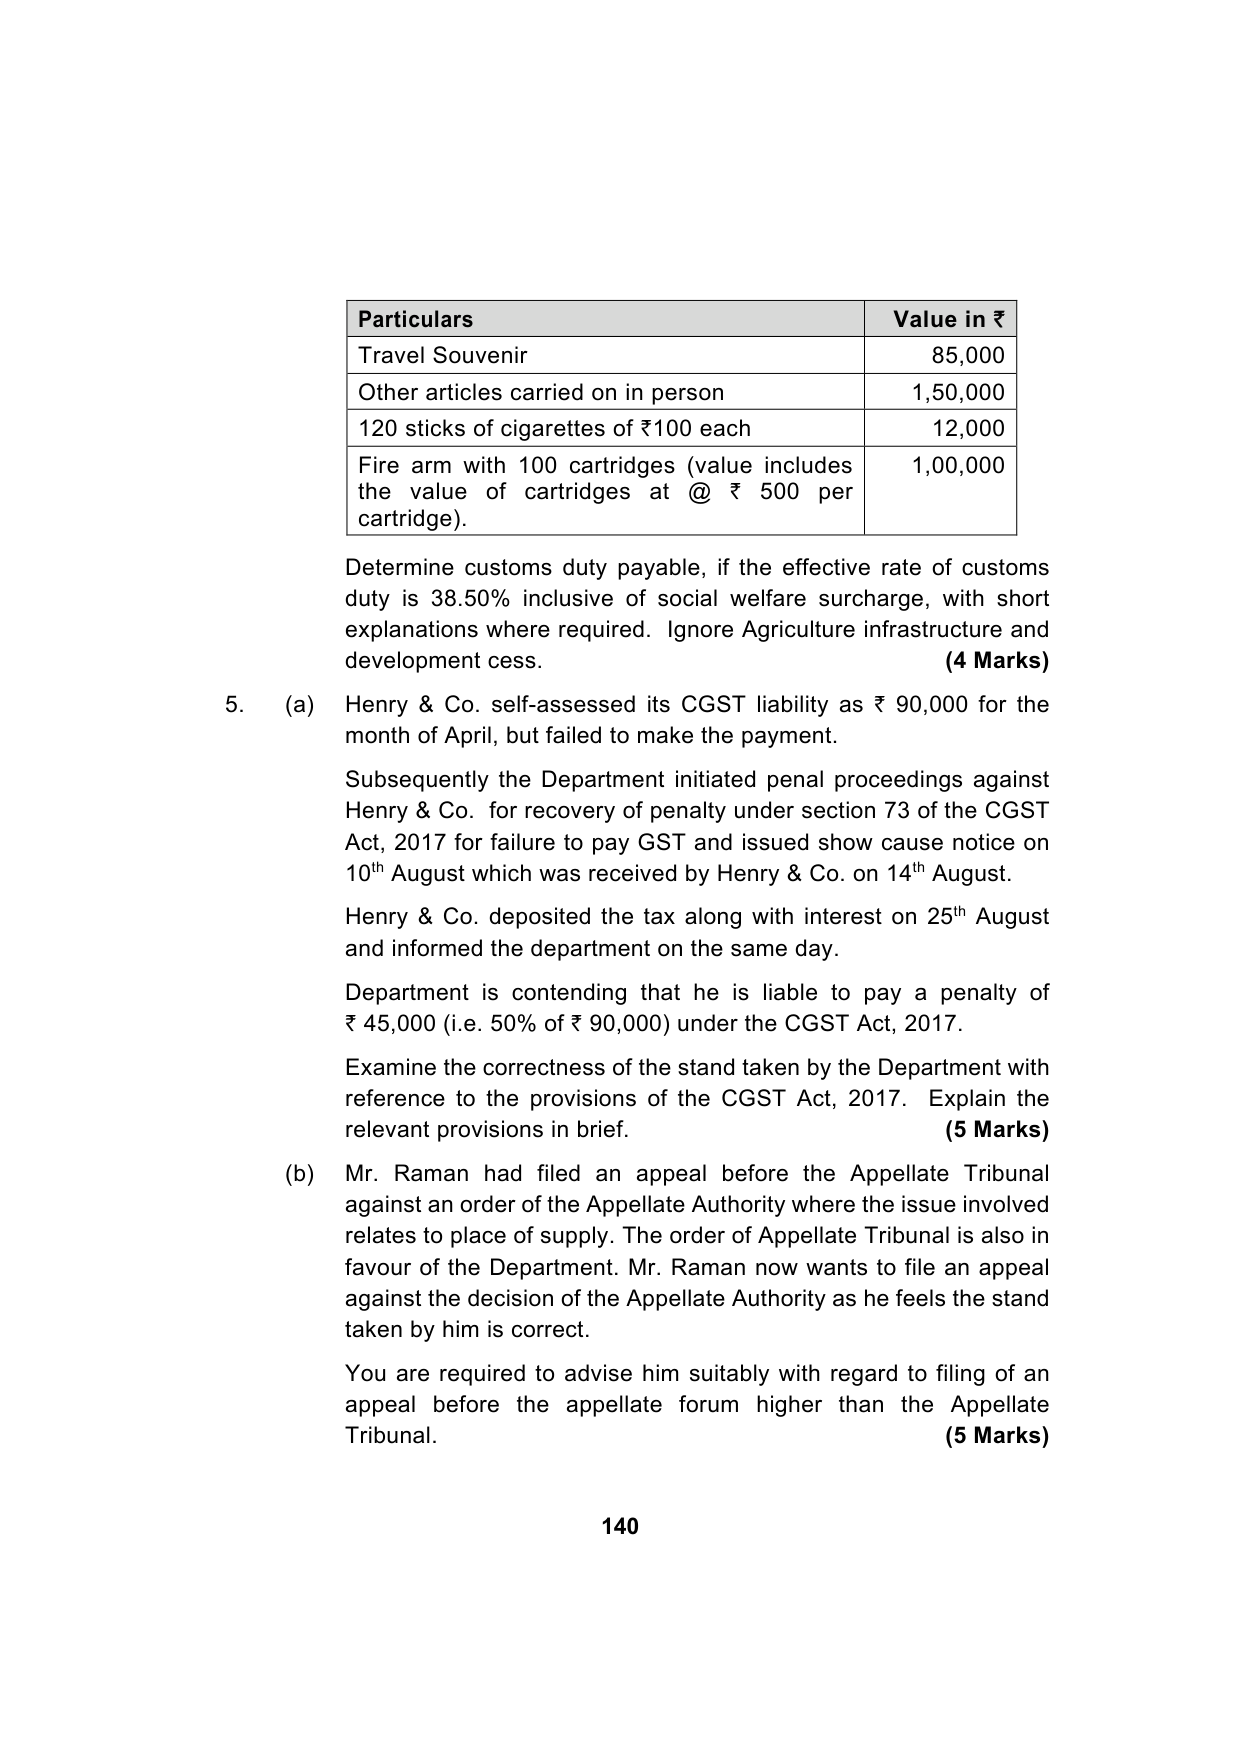
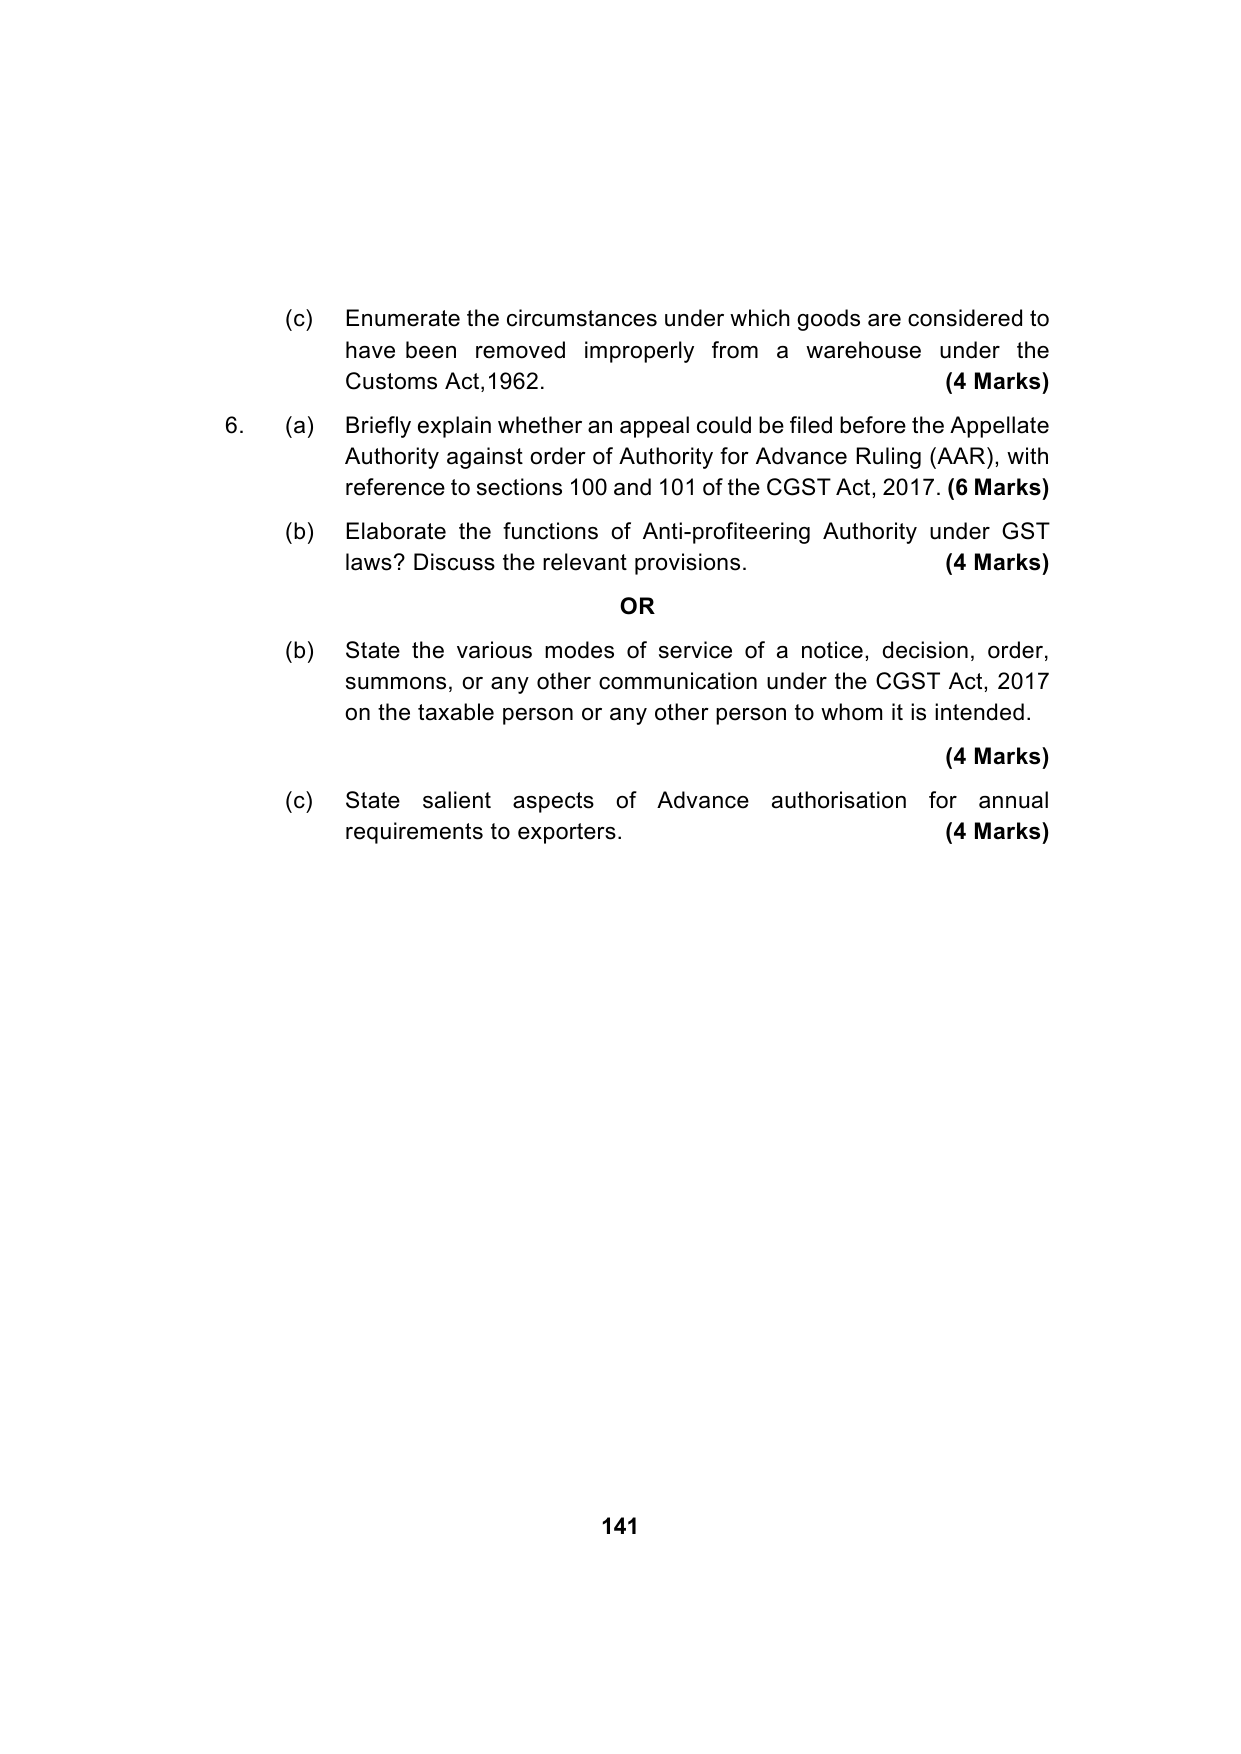
Paper 5: Indirect Tax Laws — Model Test Paper 3 (100 marks)
Question
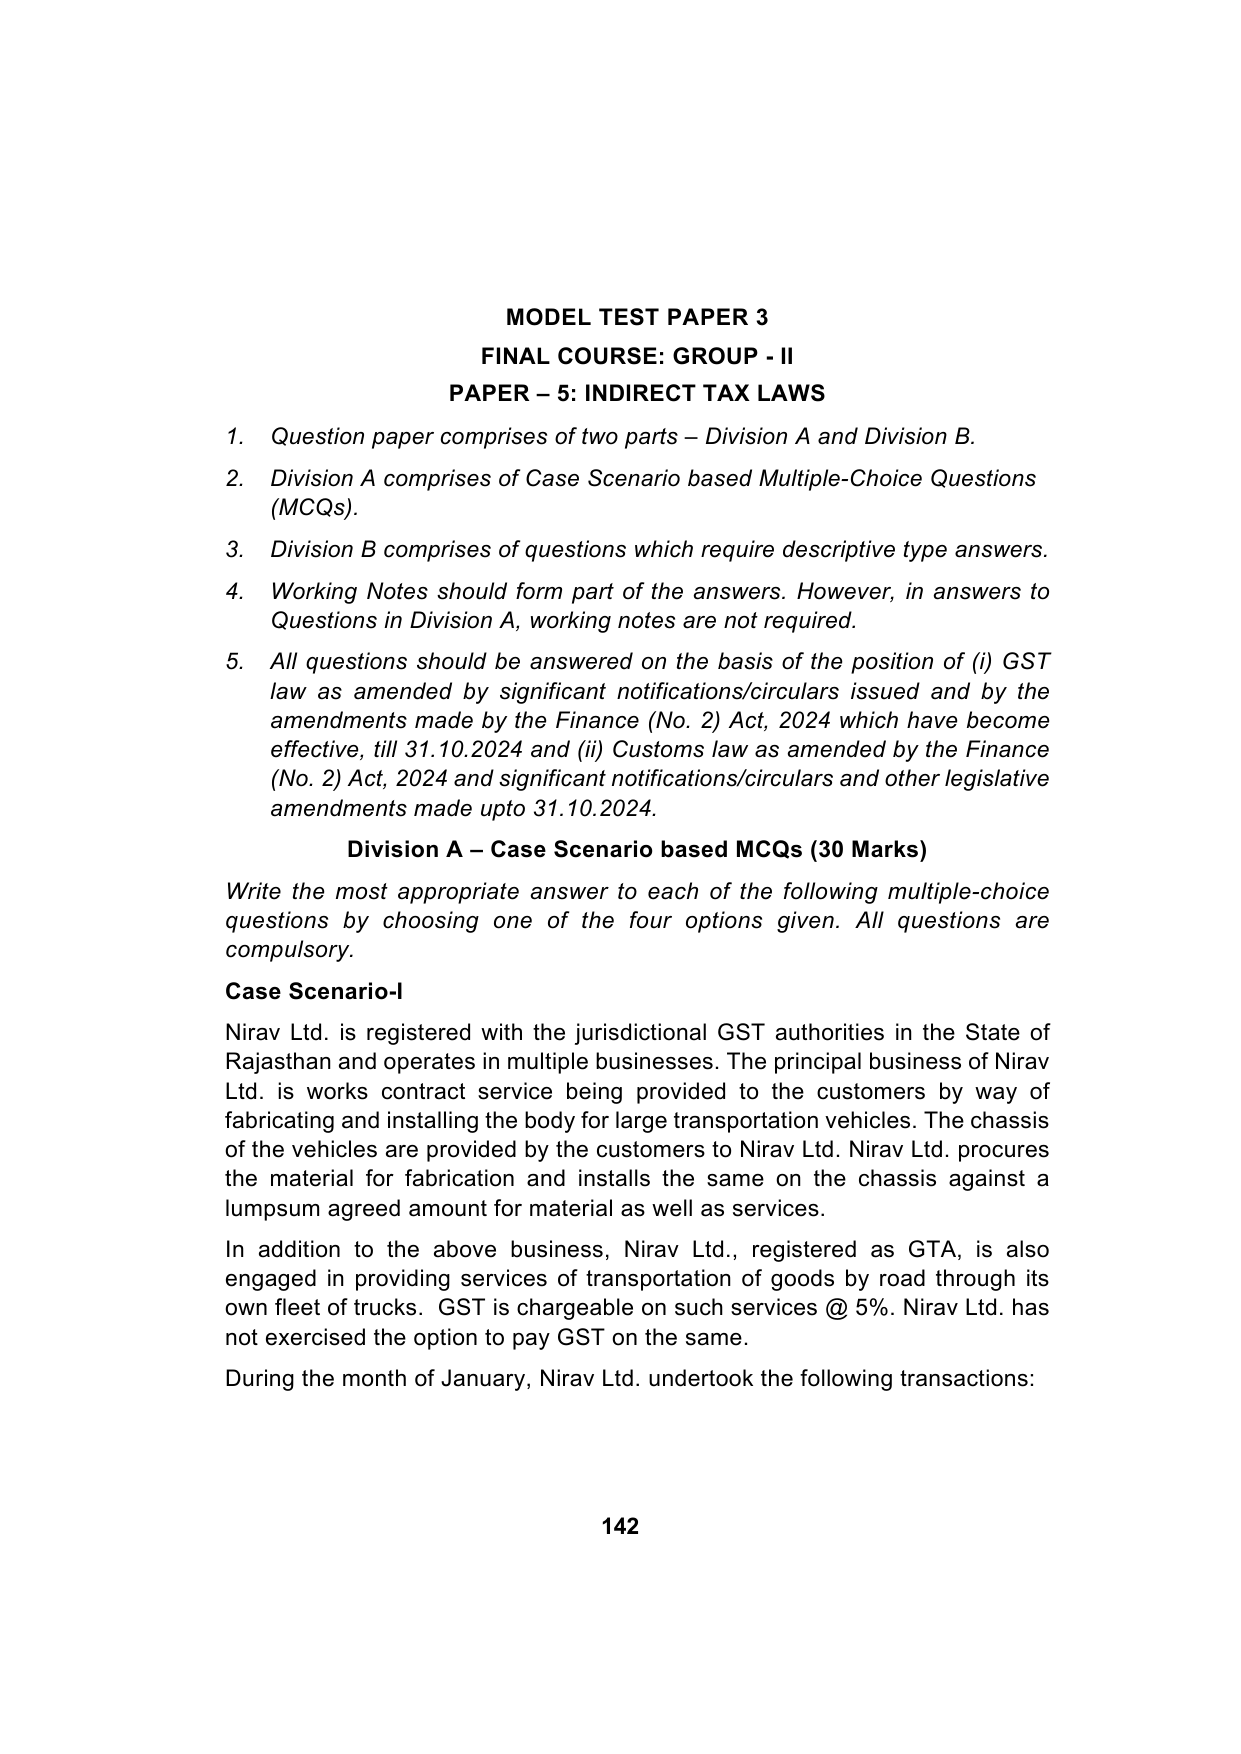
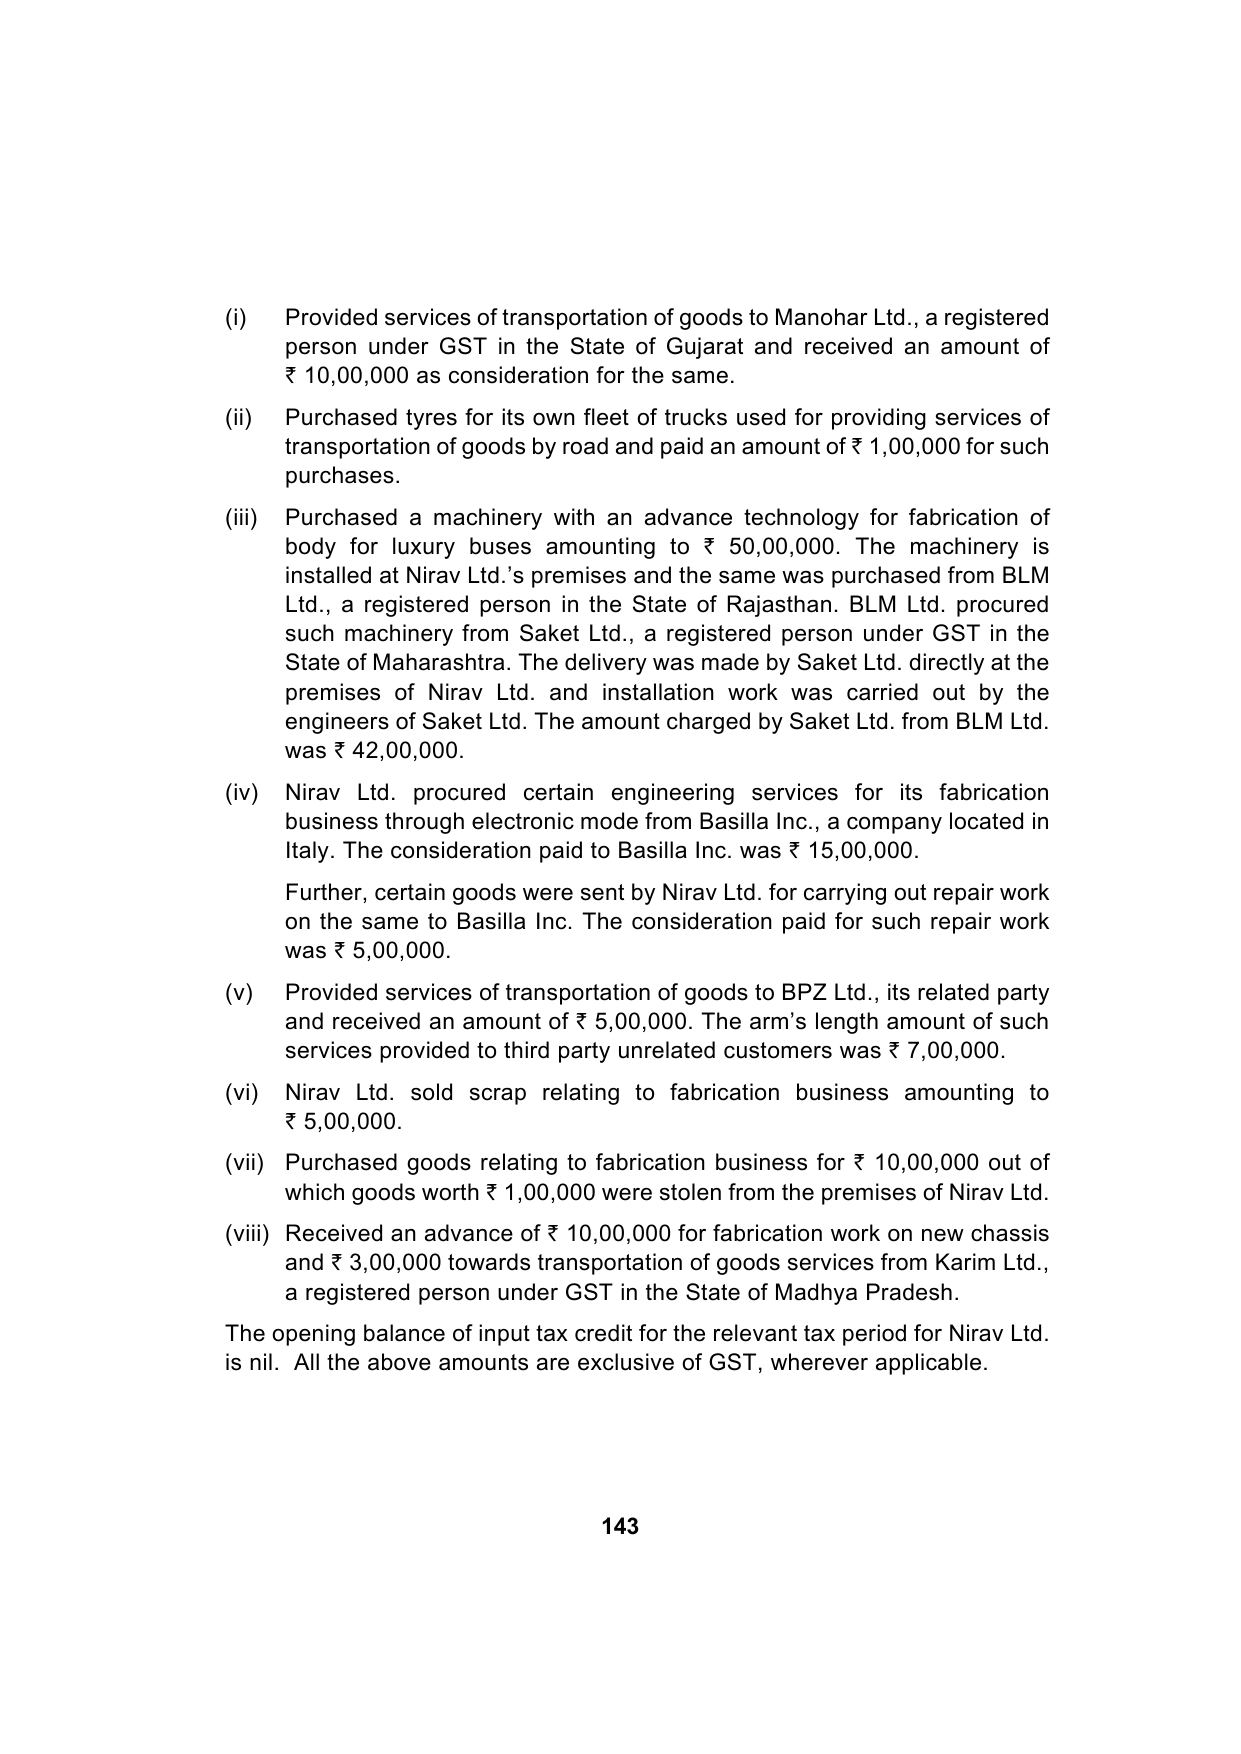
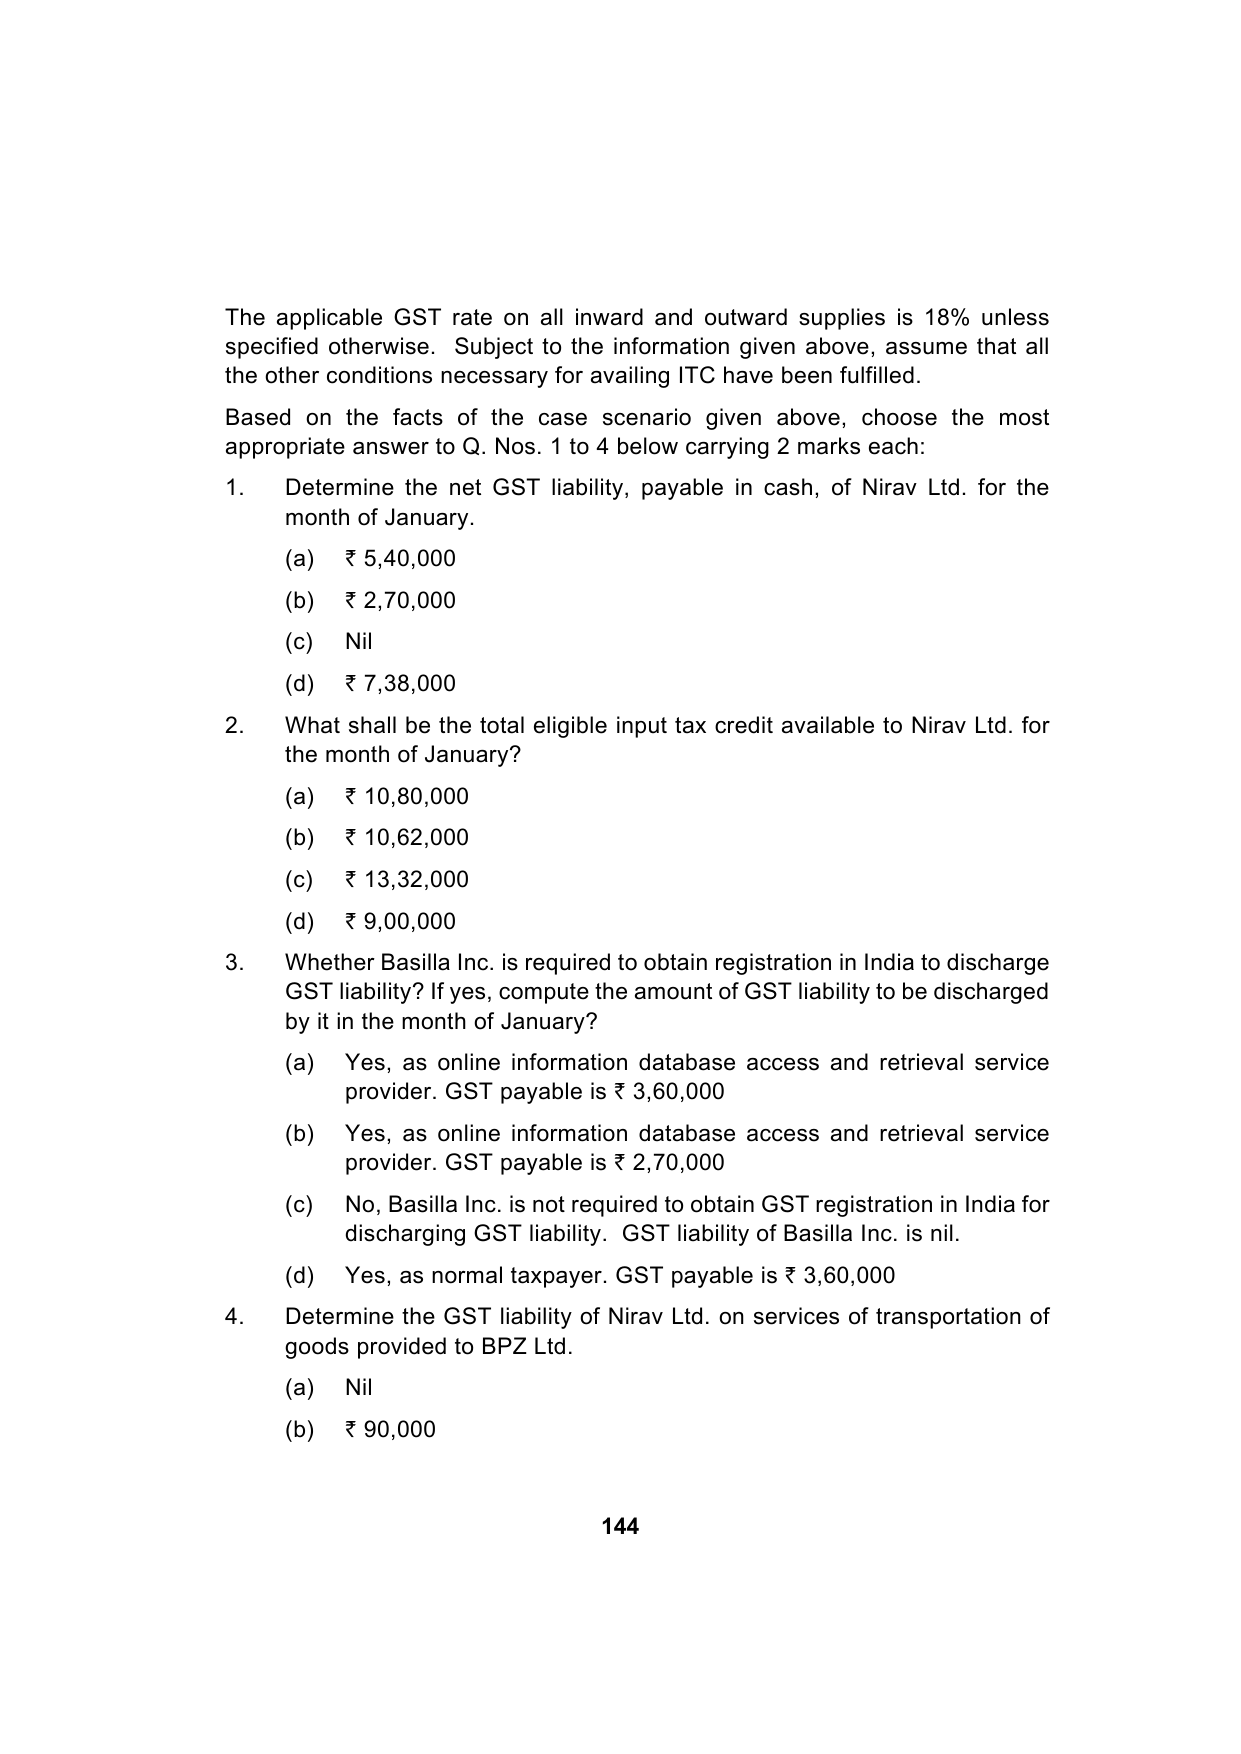
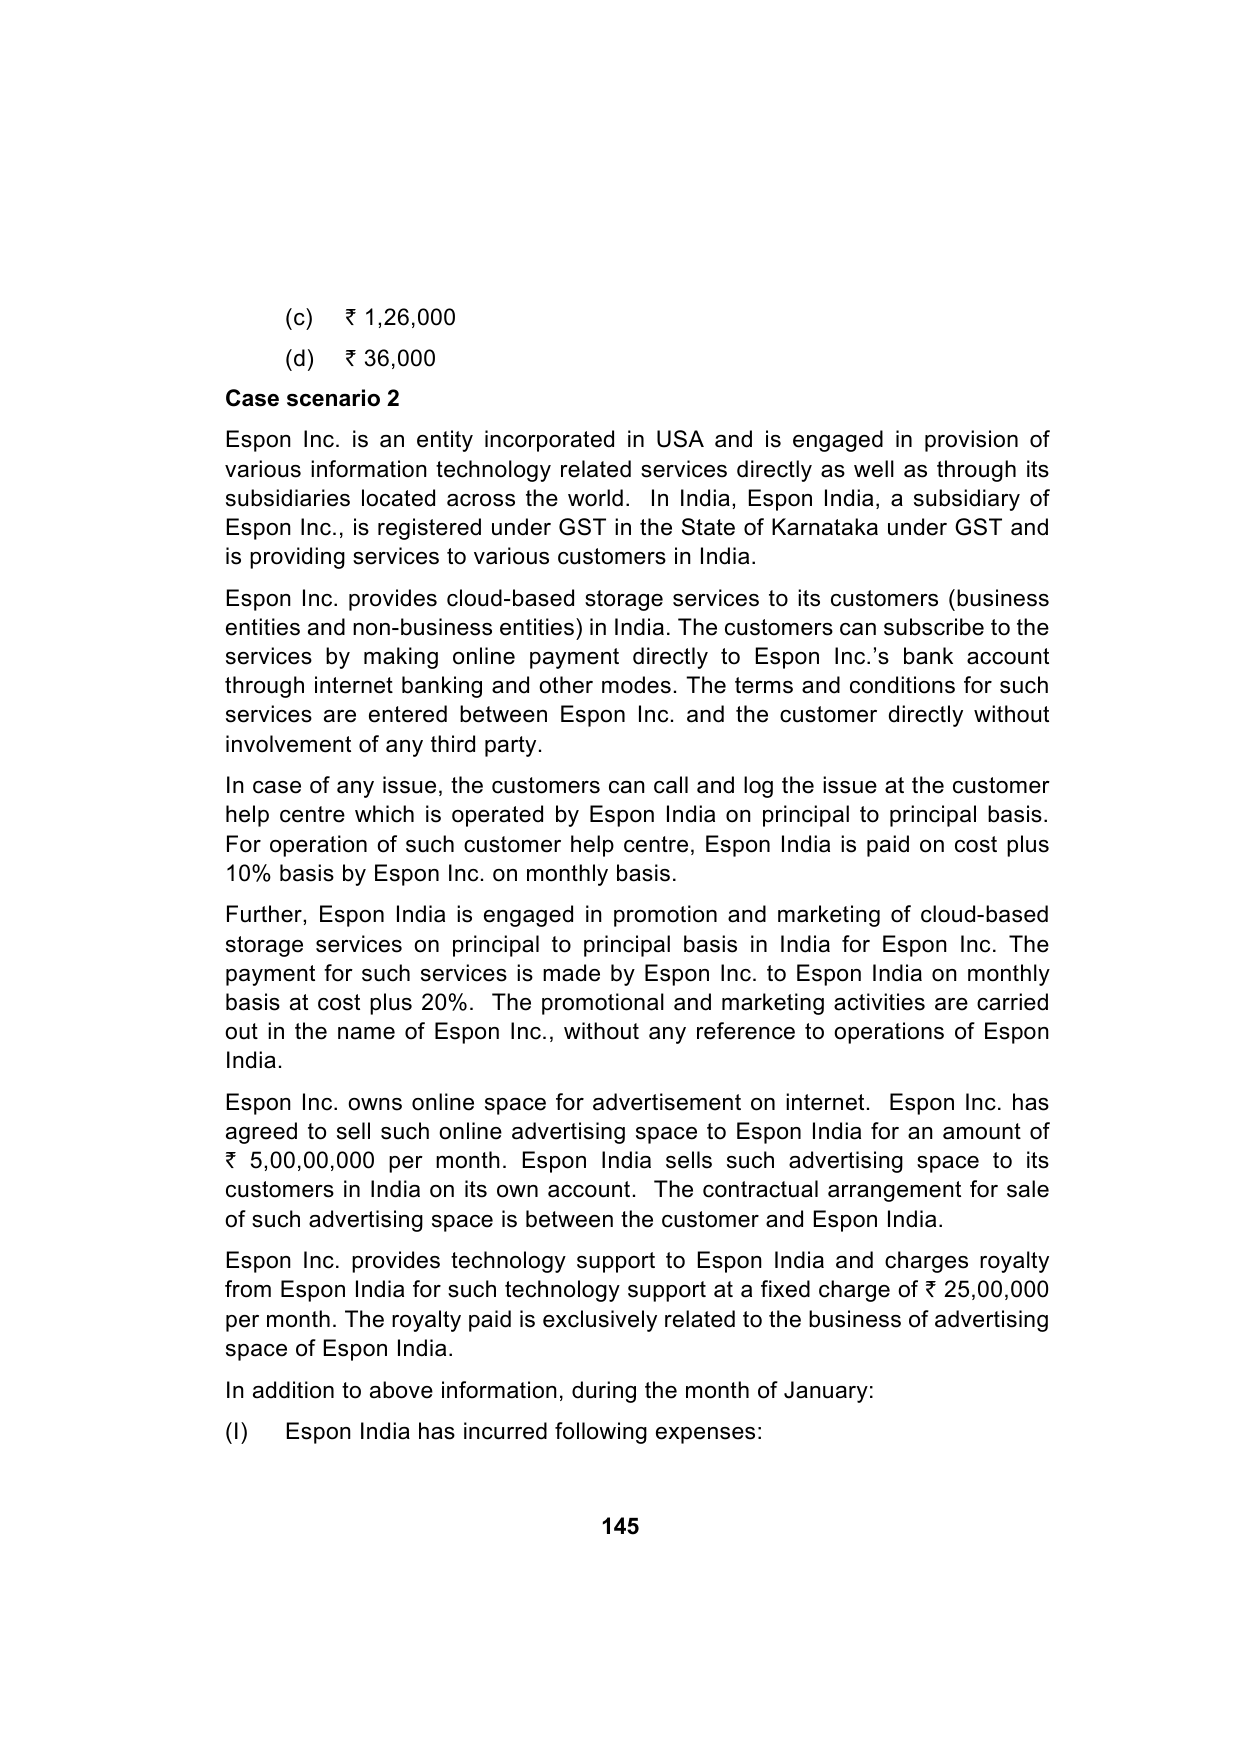
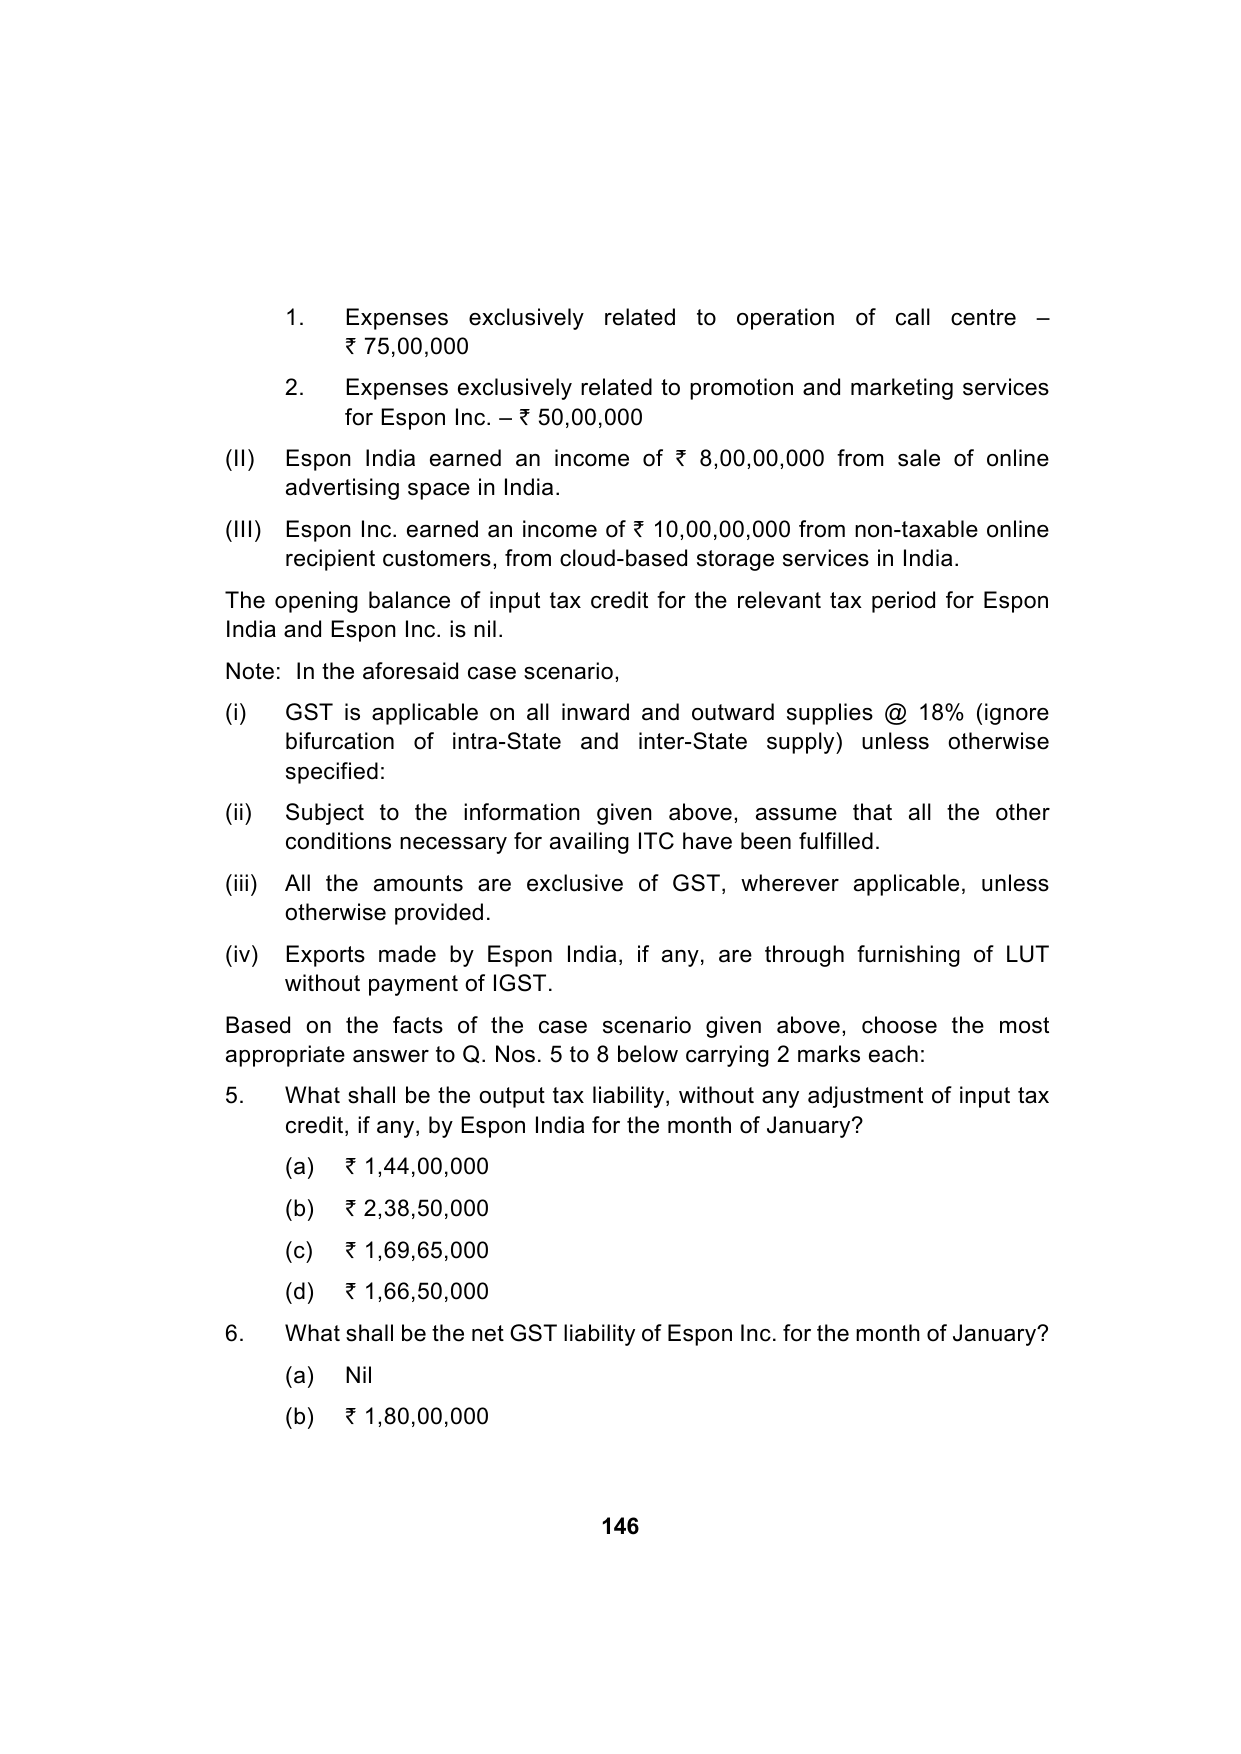
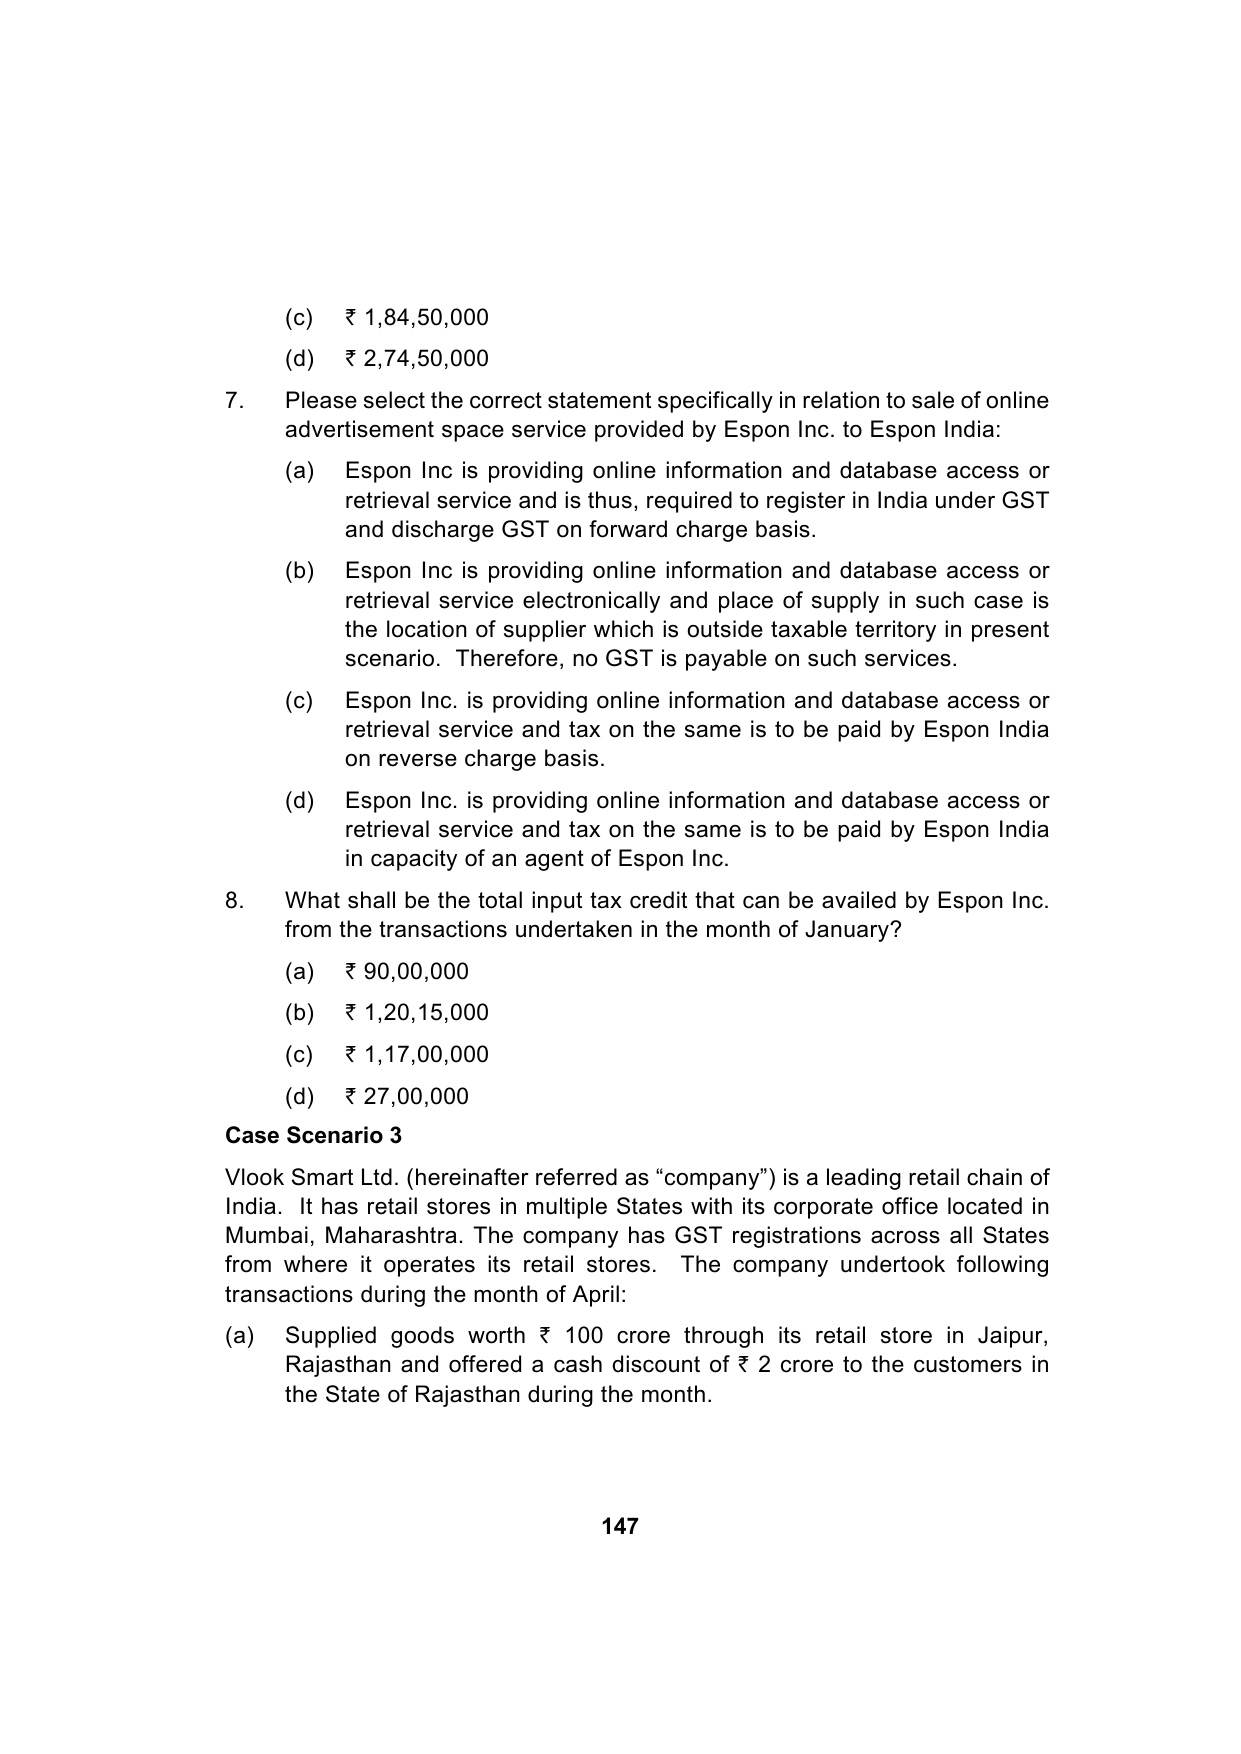
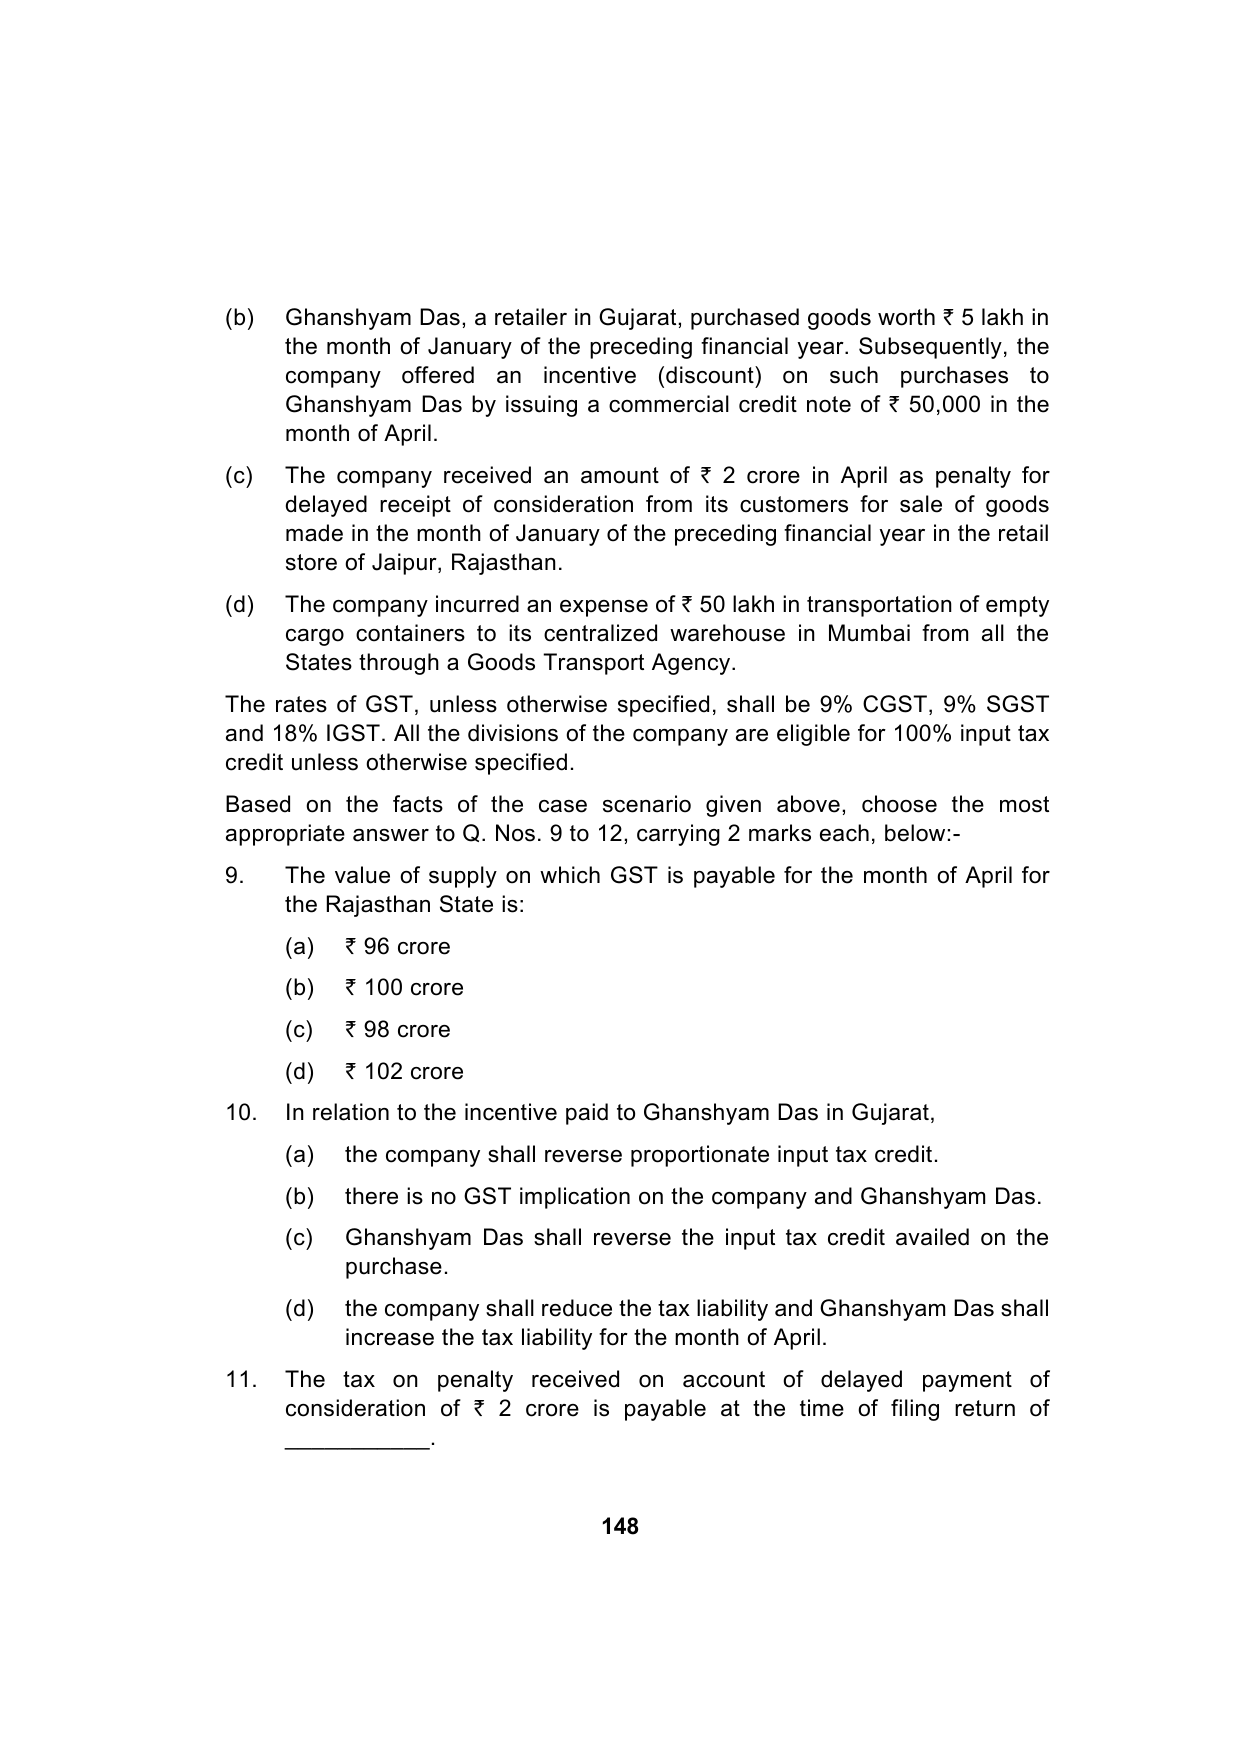
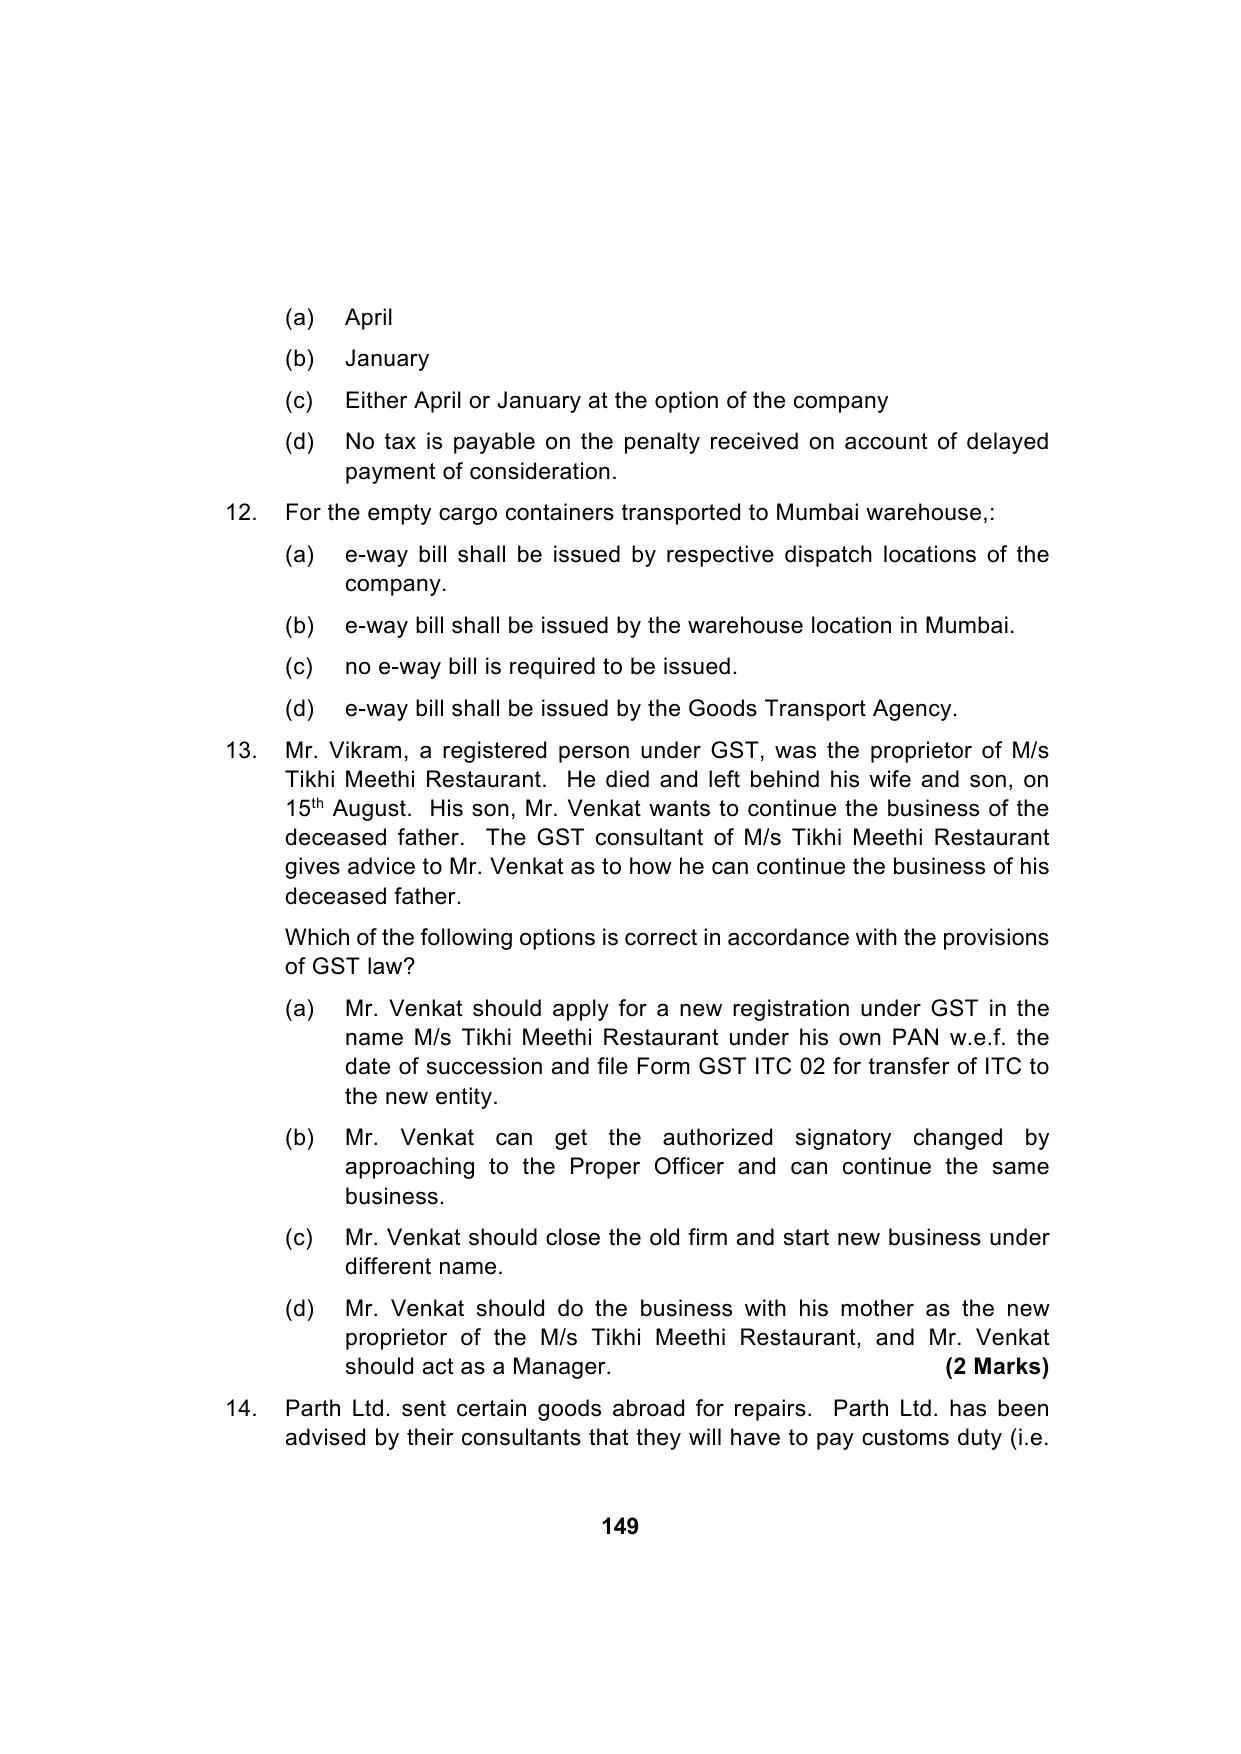
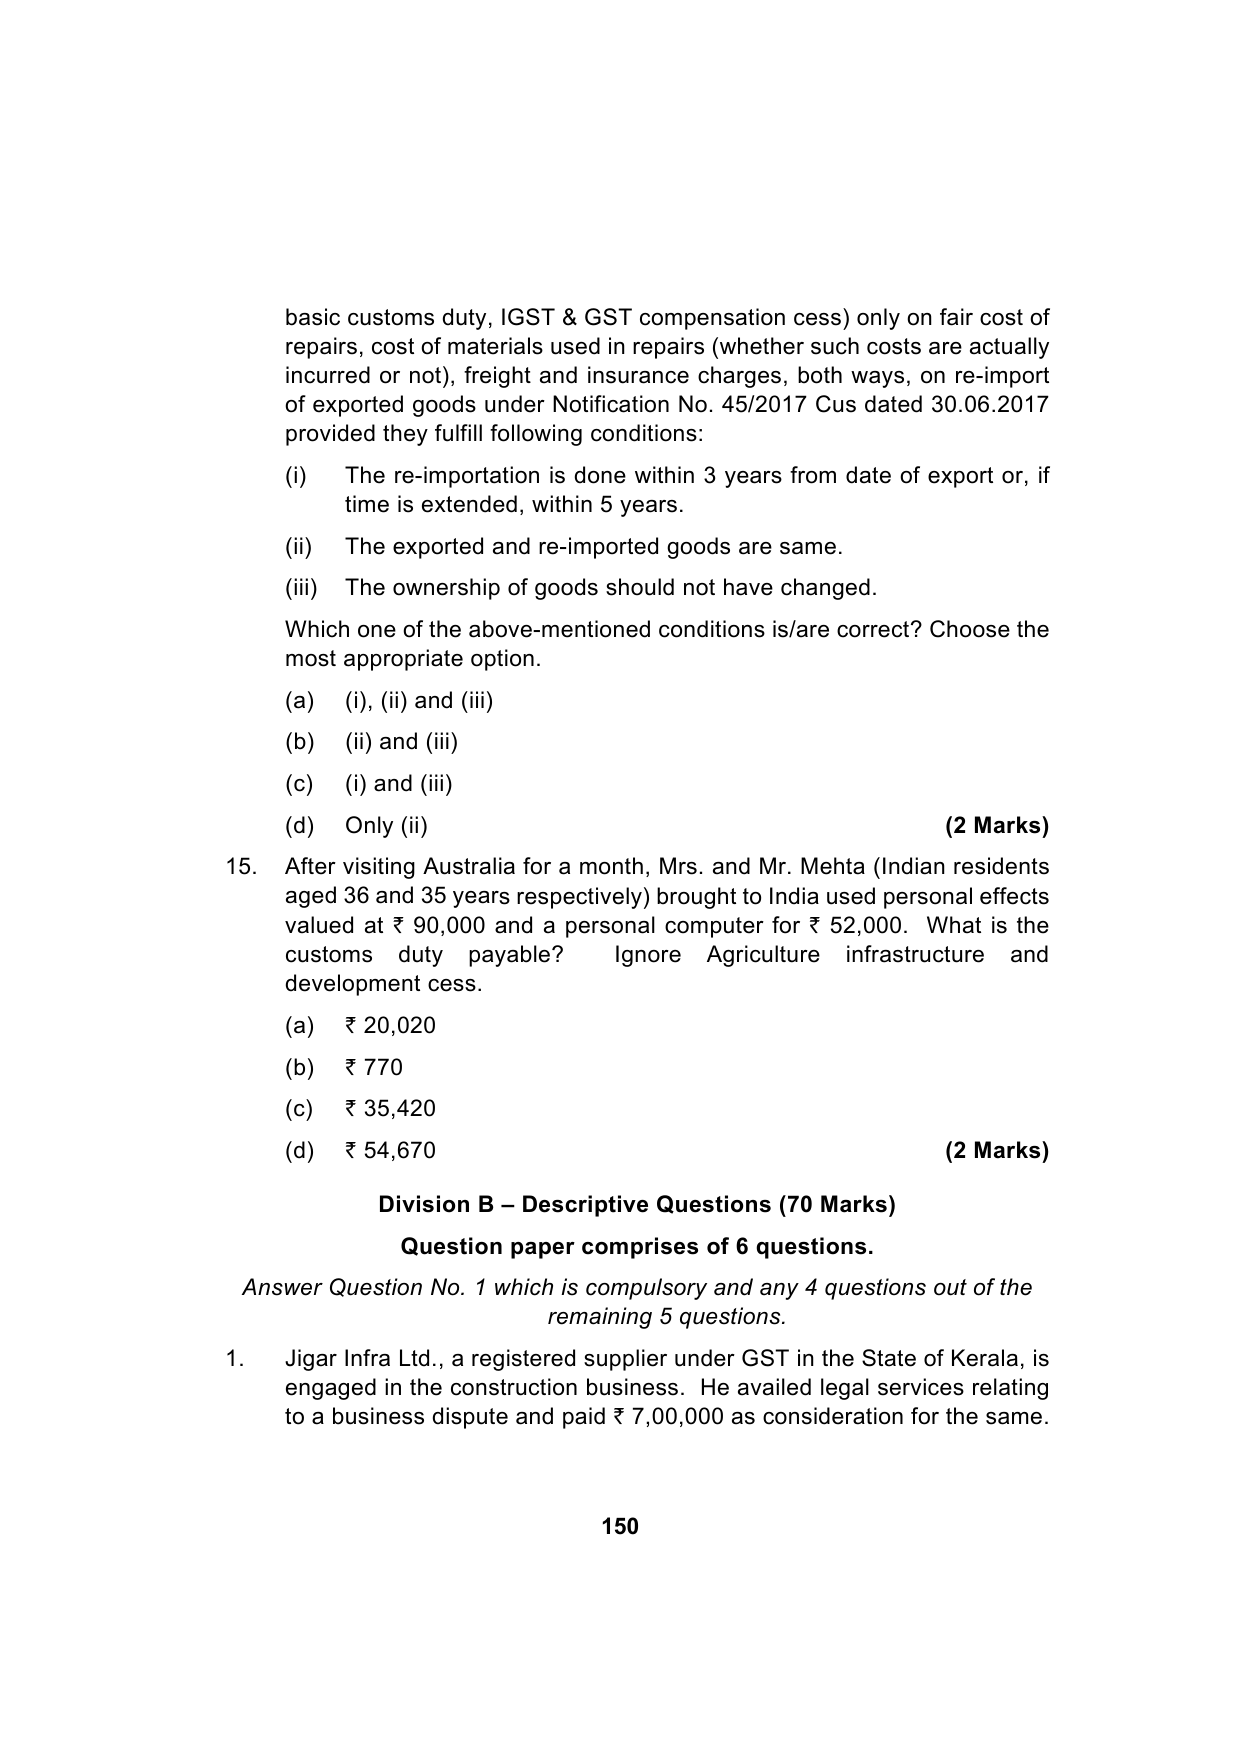
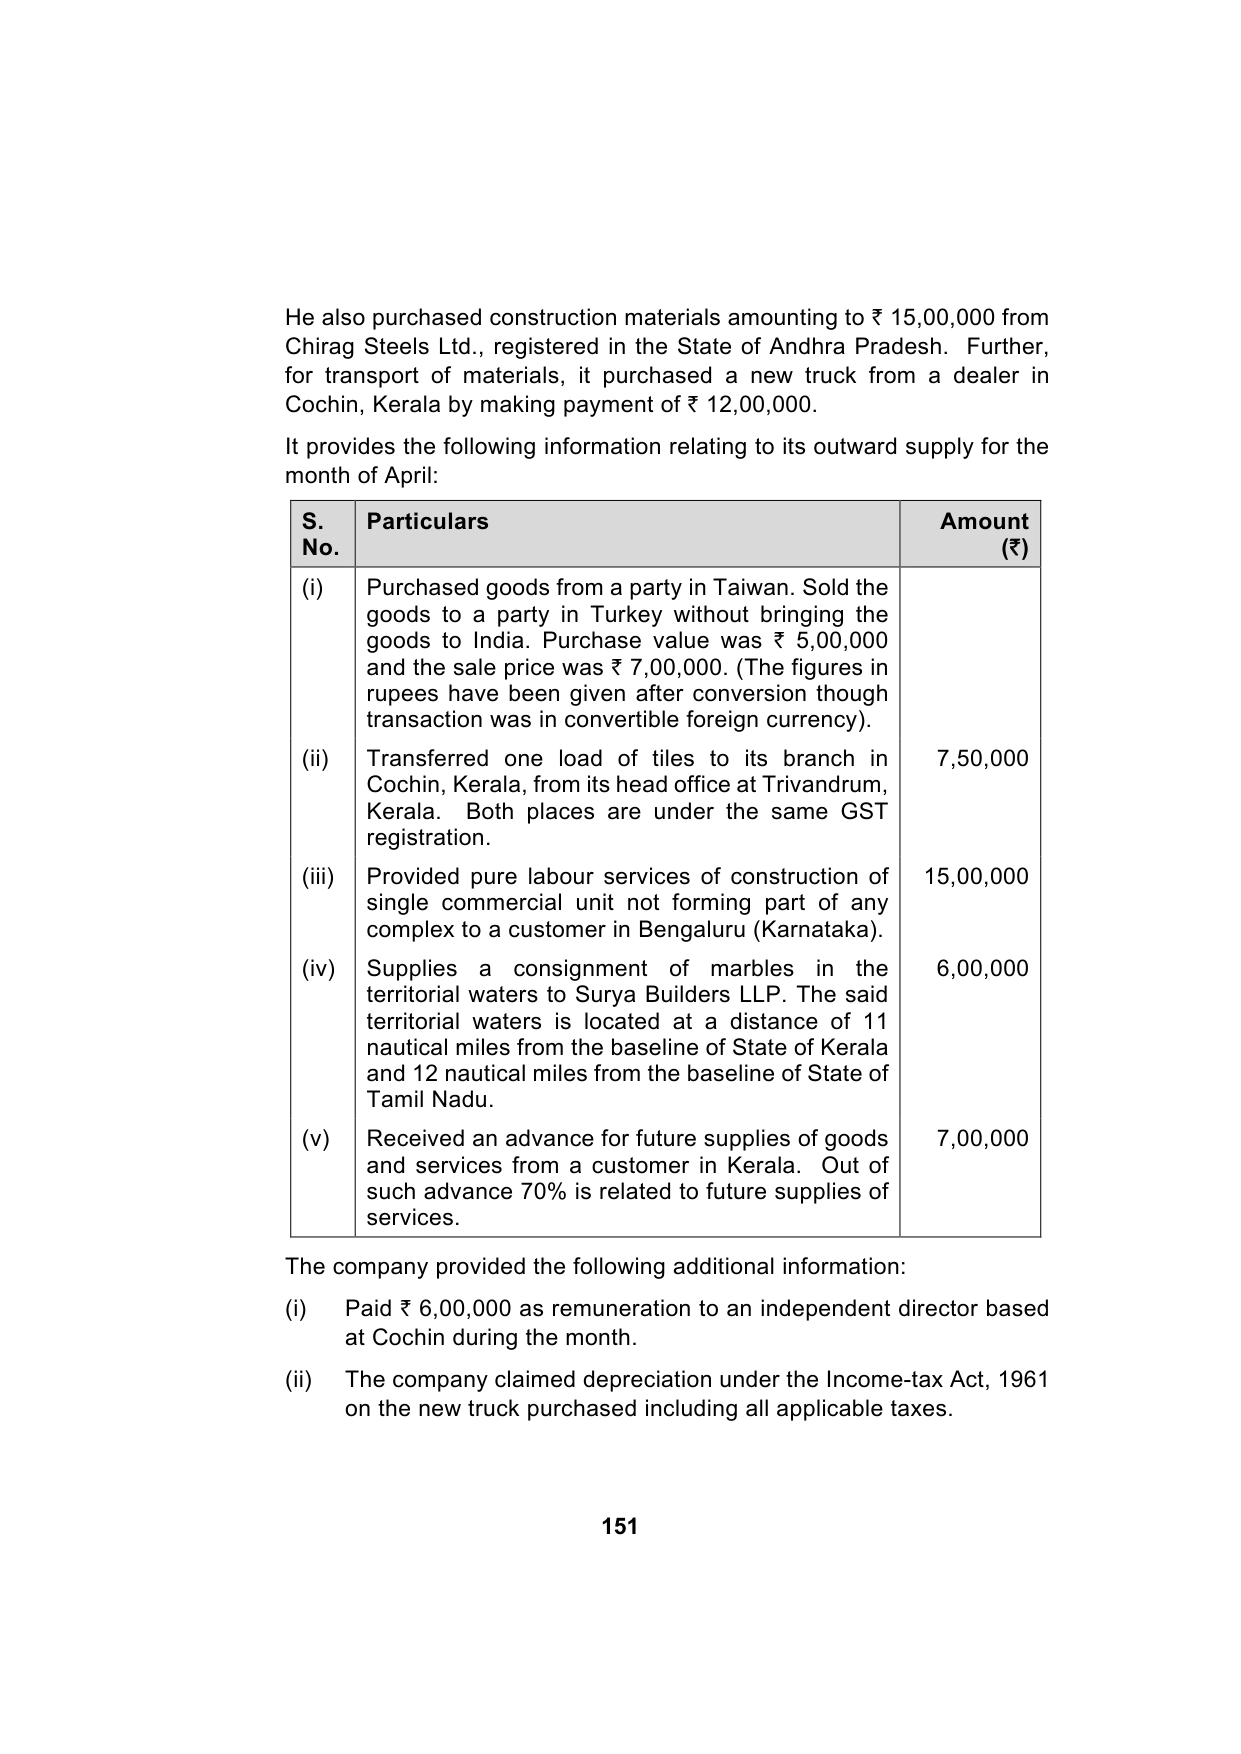
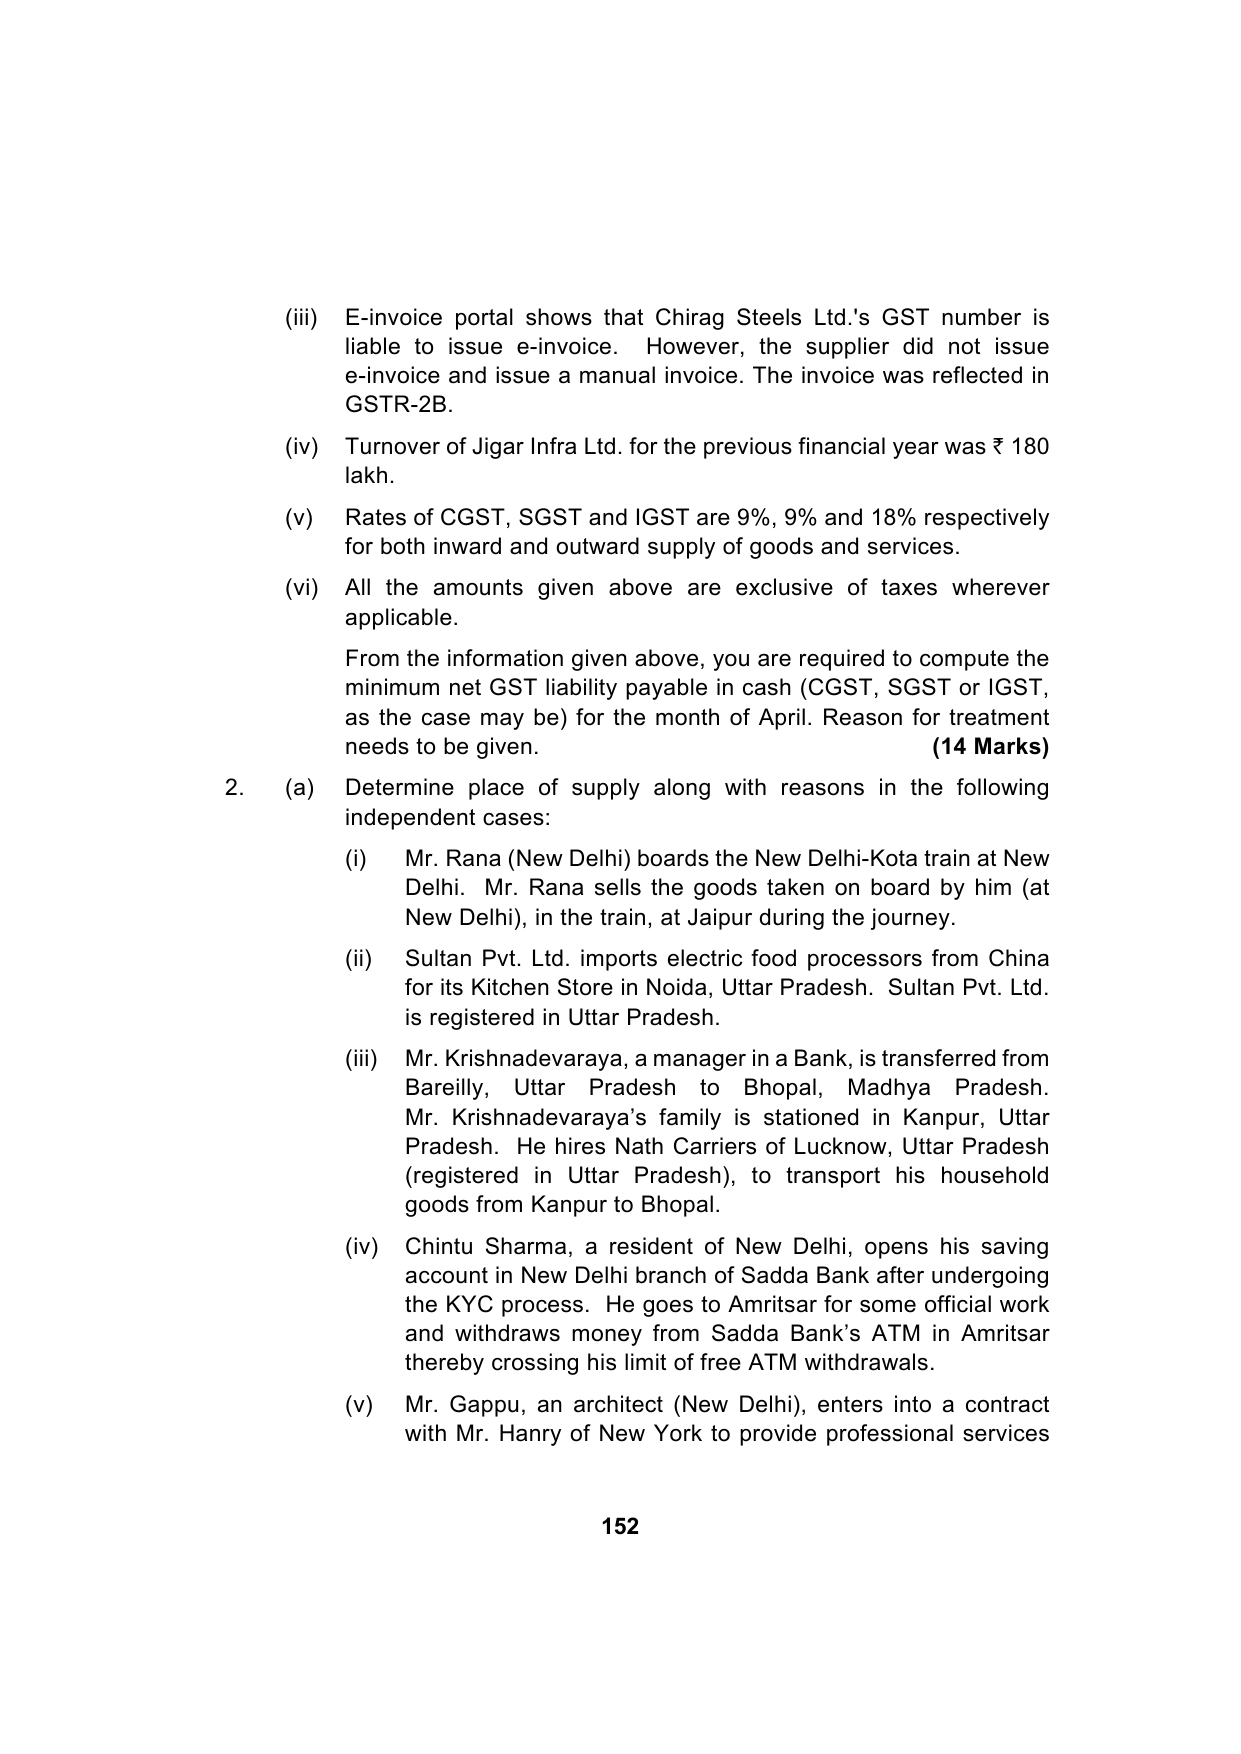
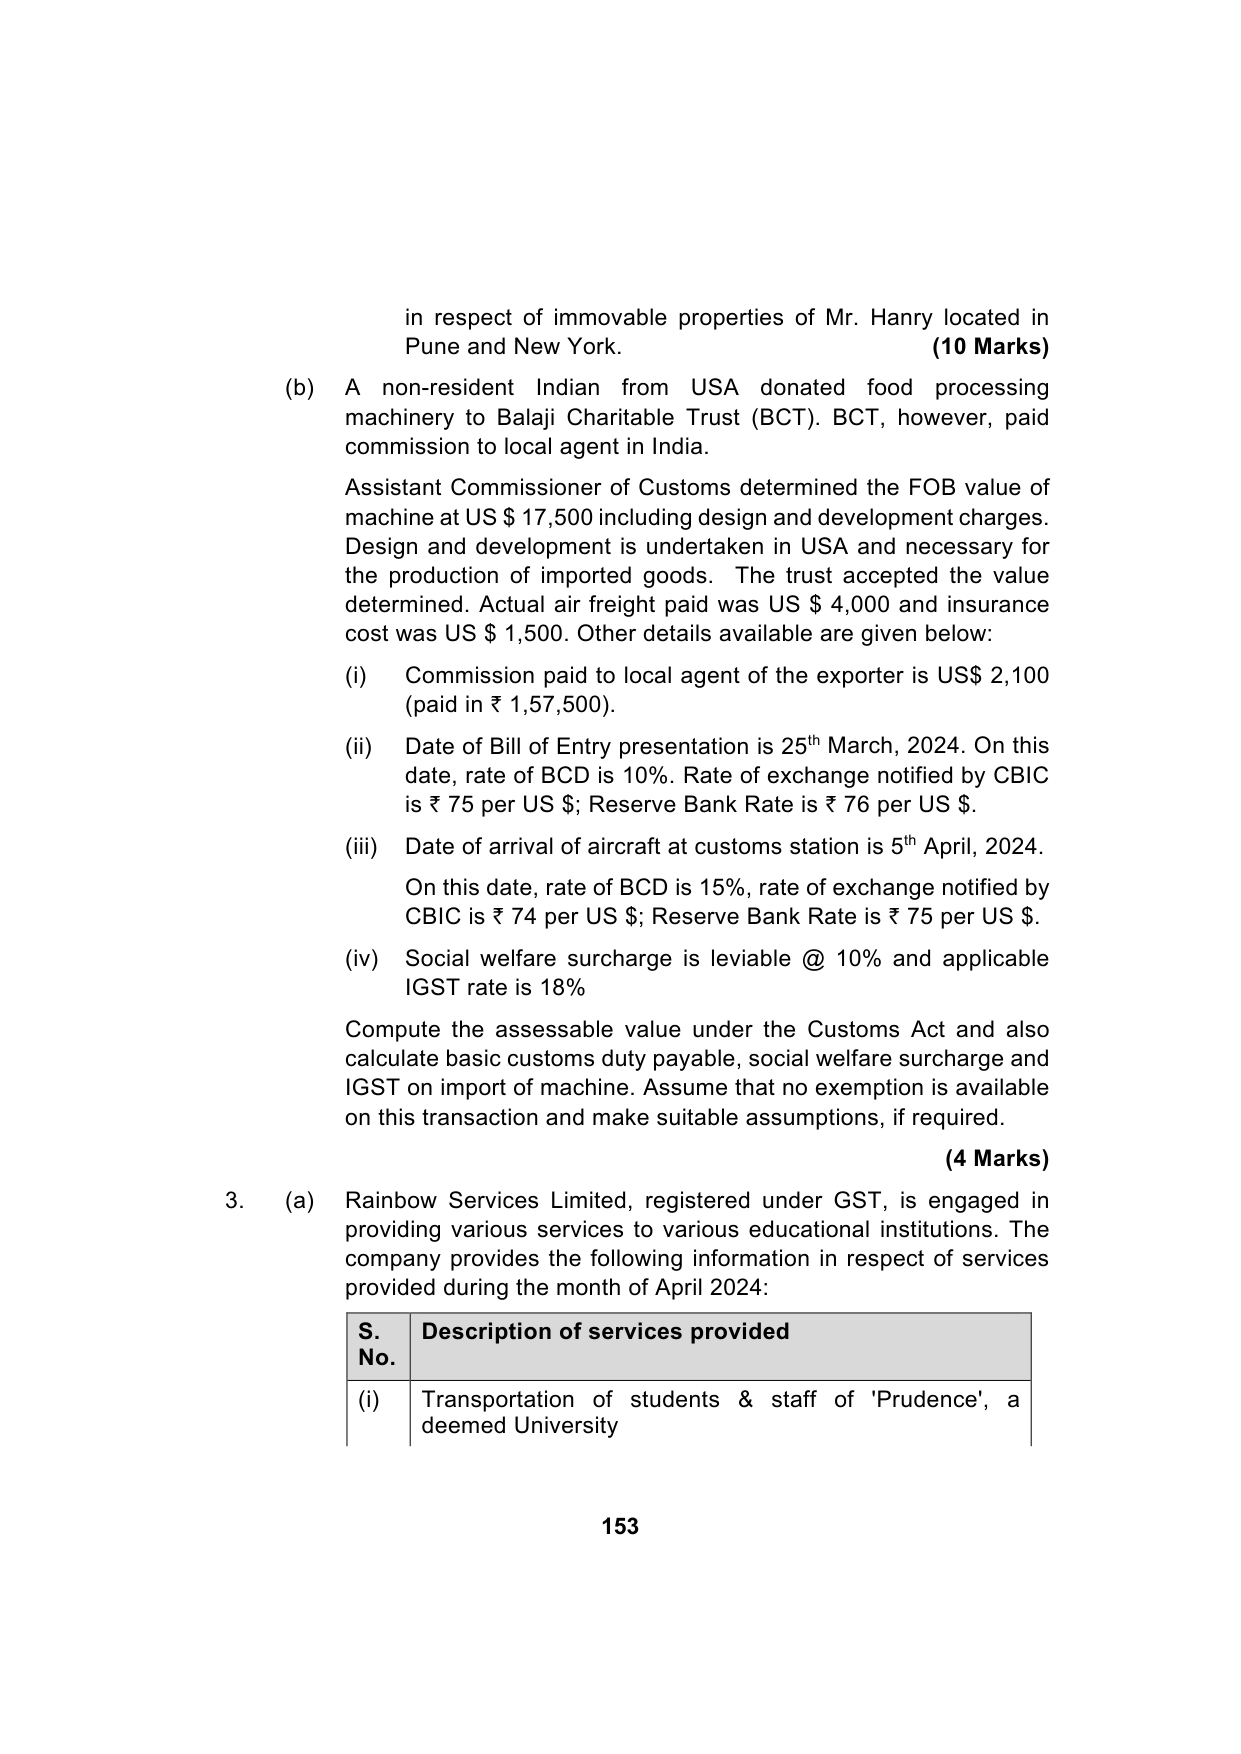
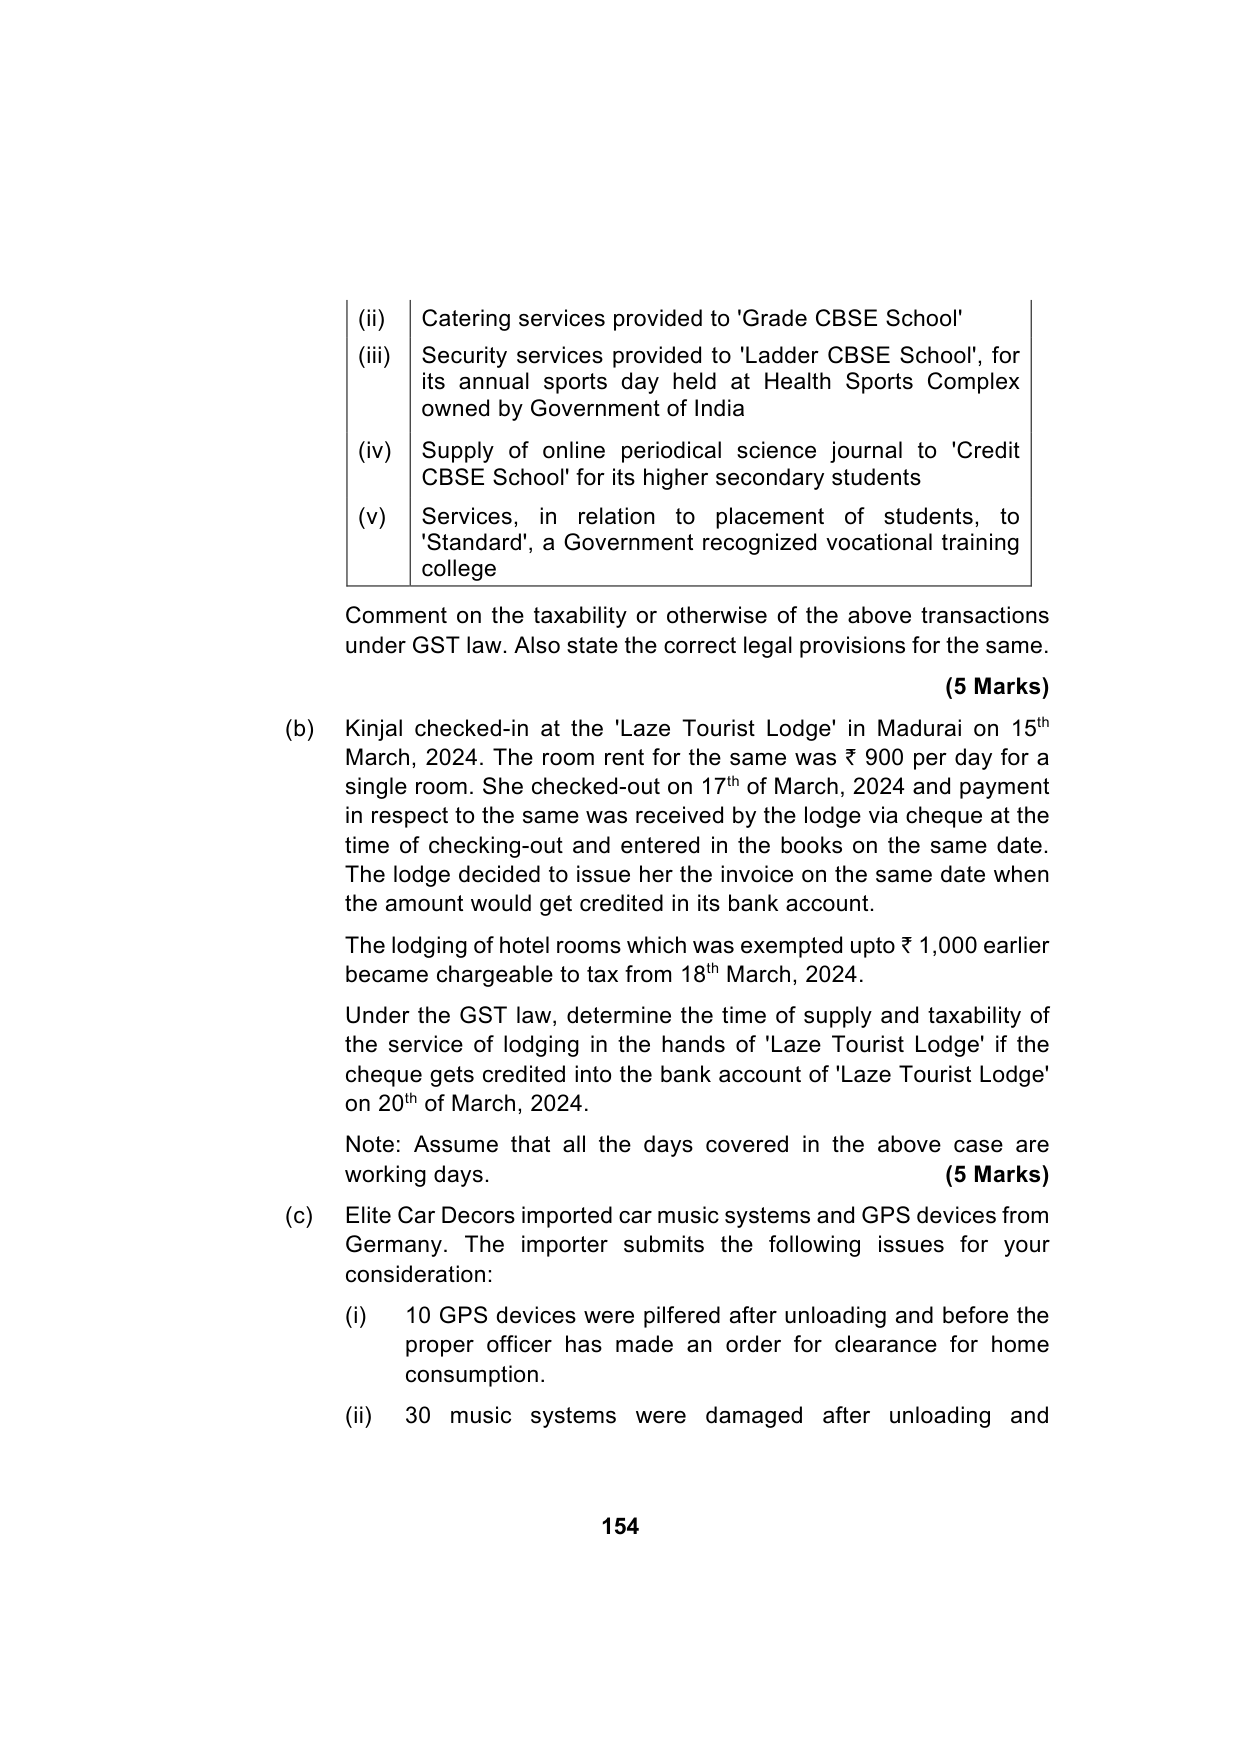
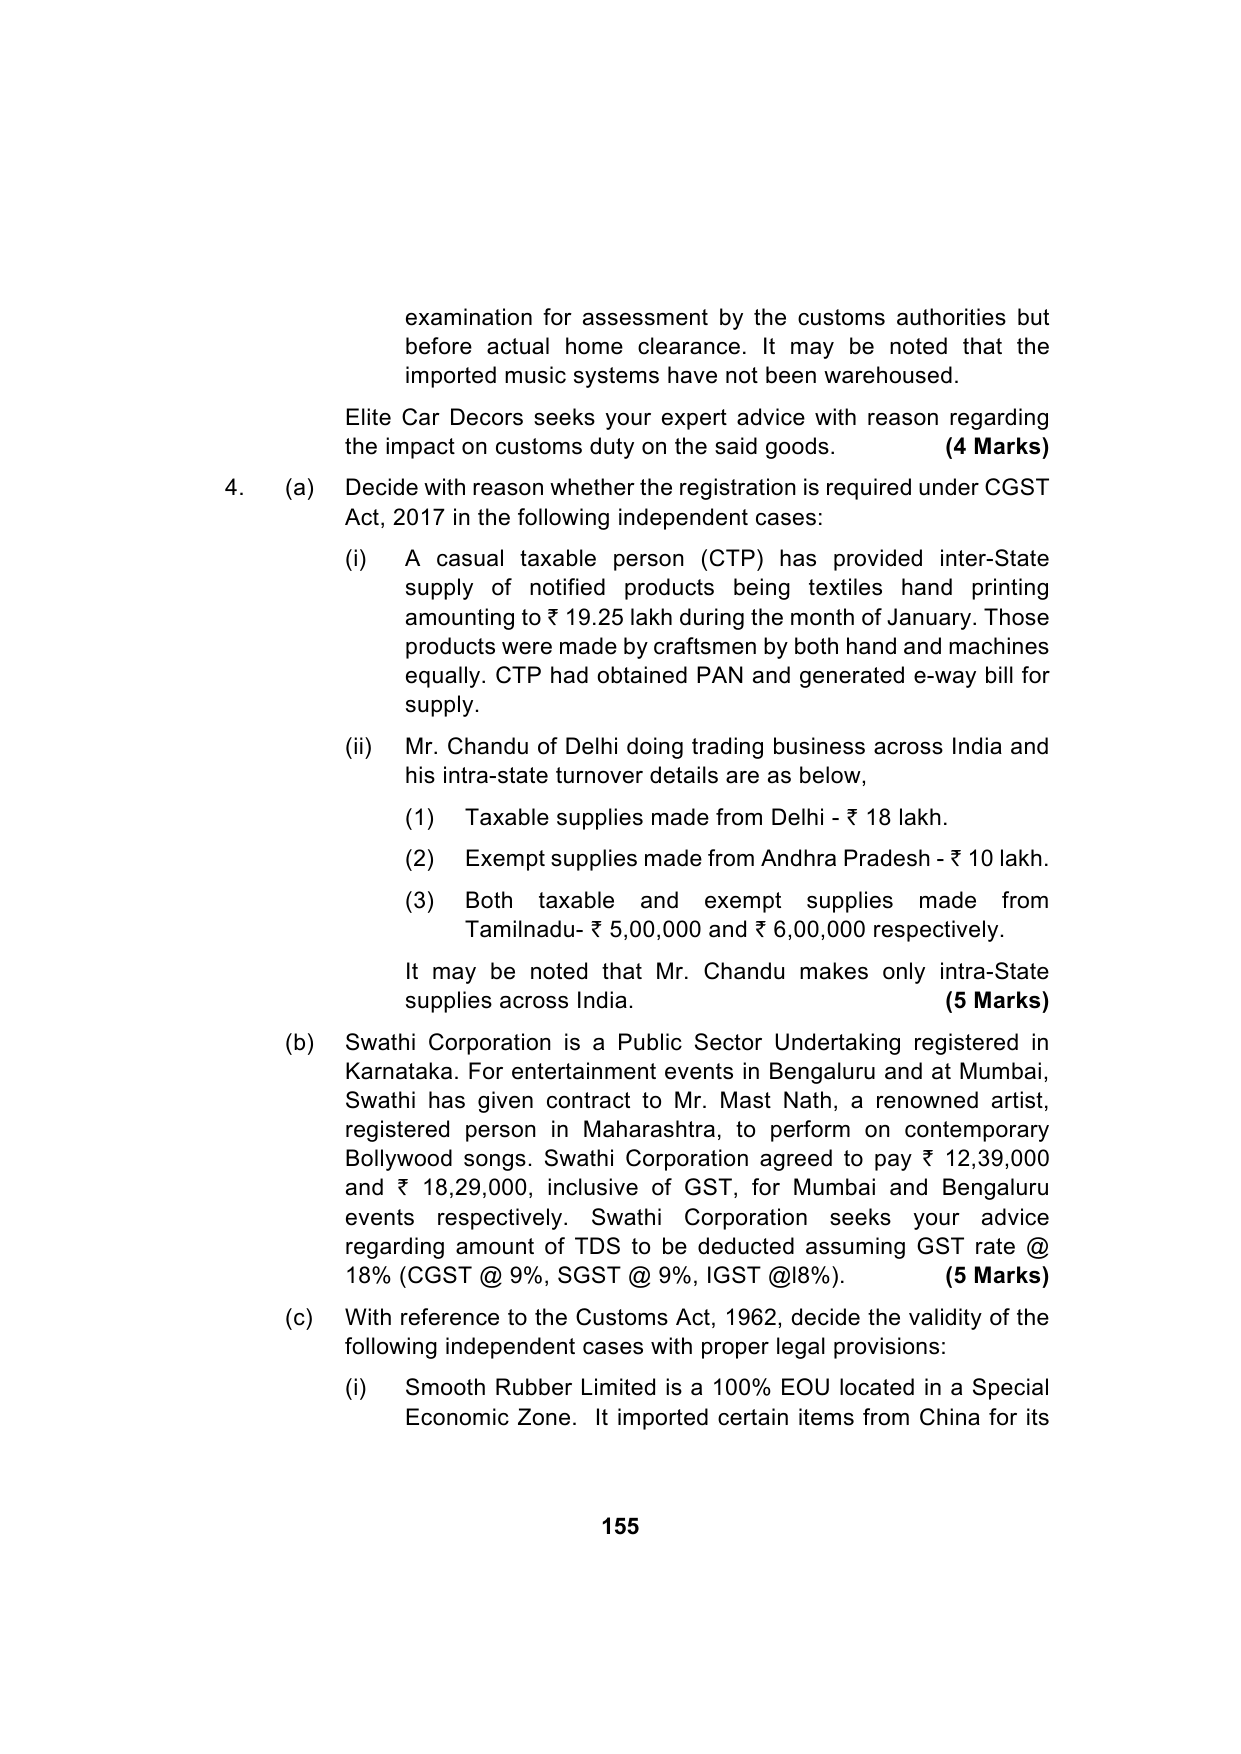
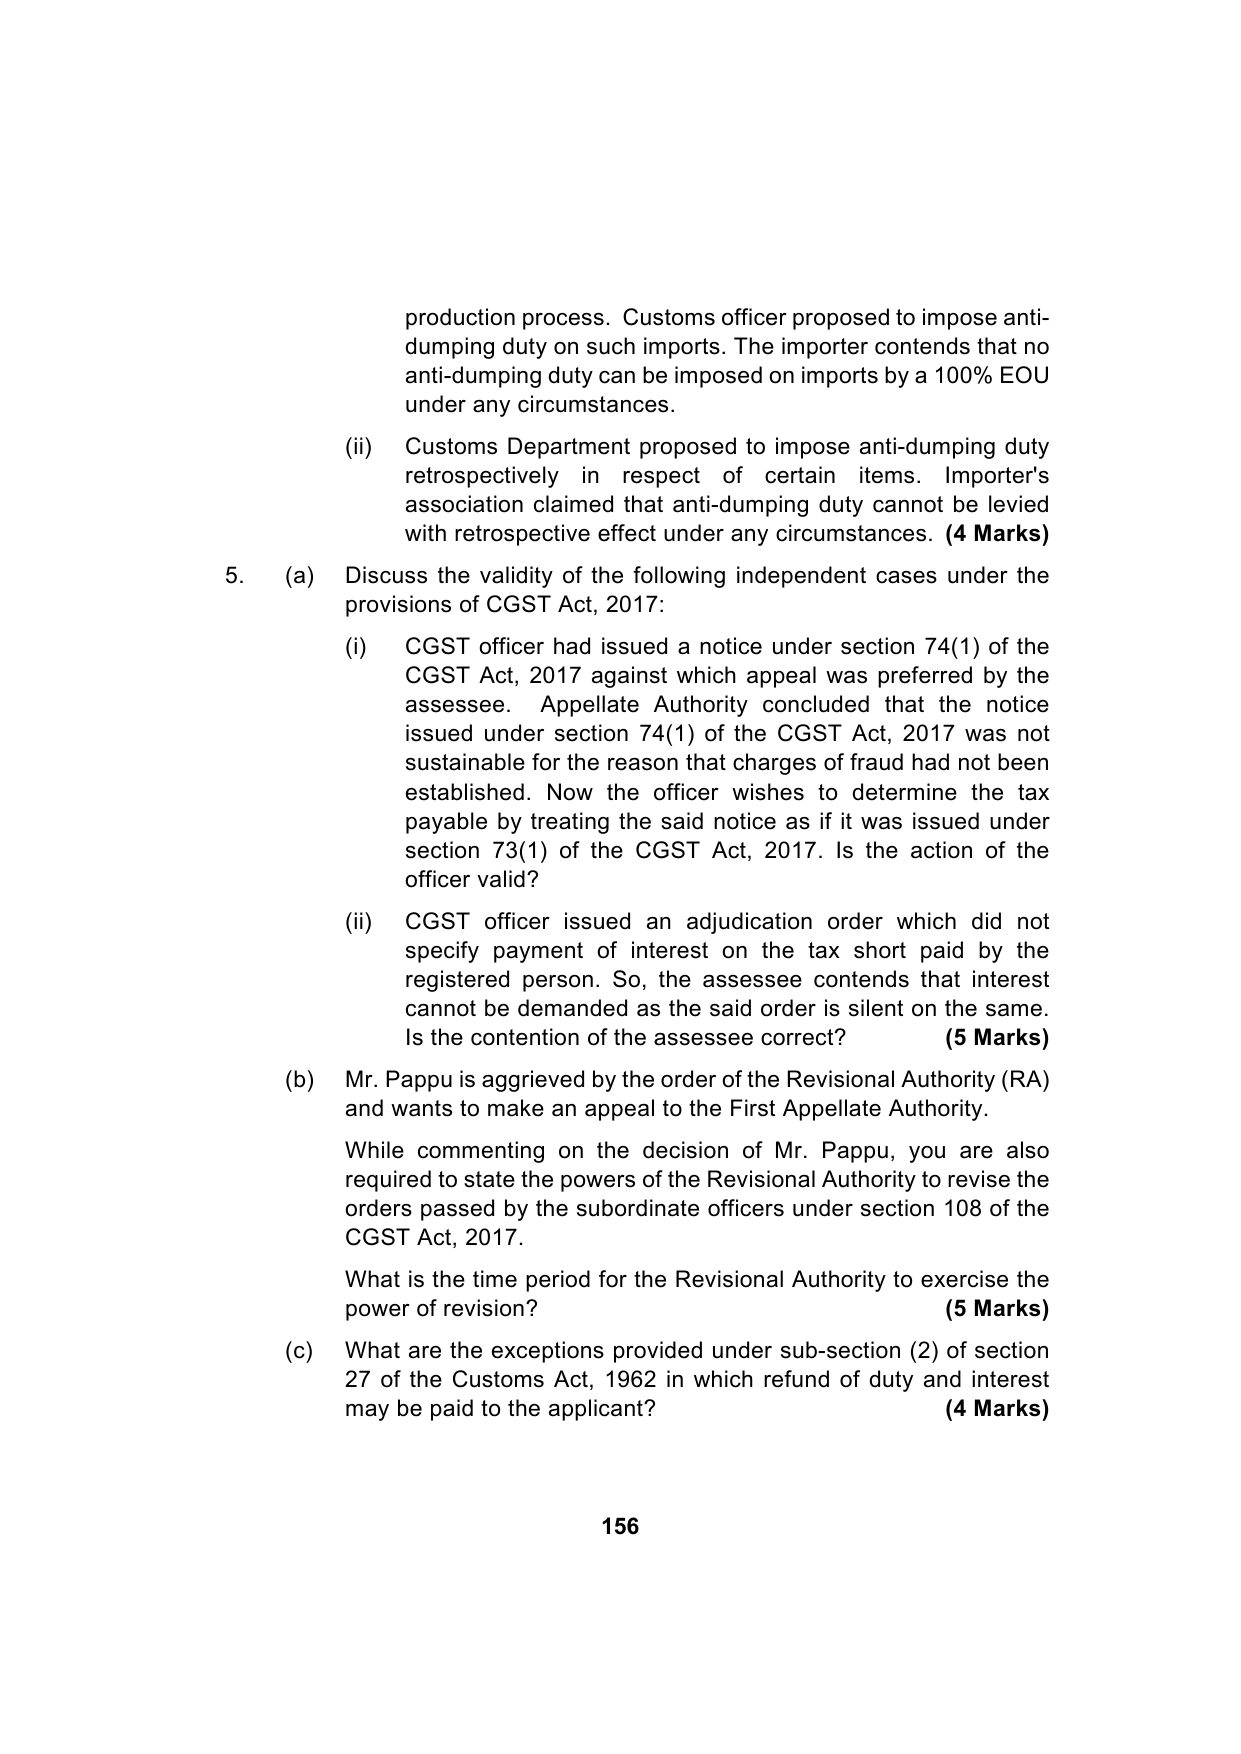
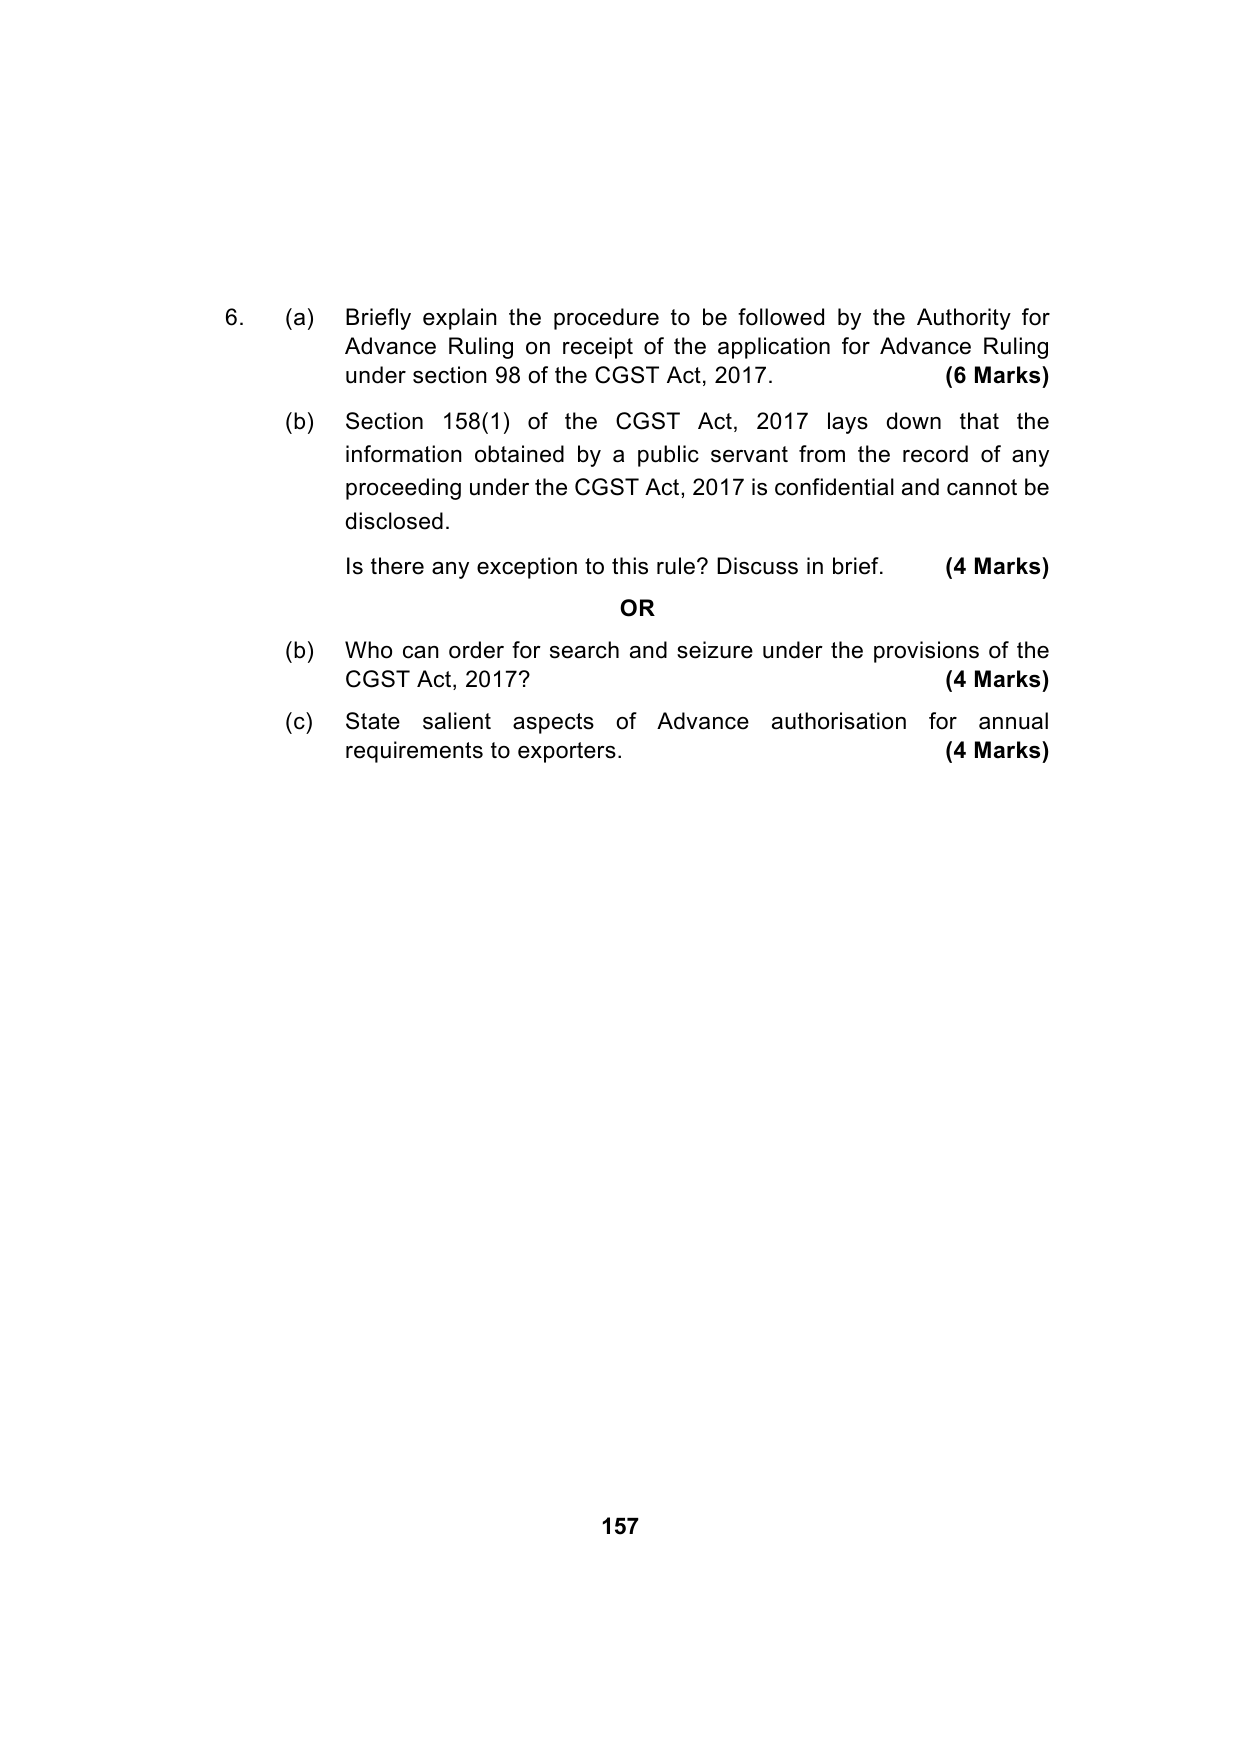
Paper 5: Indirect Tax Laws — Model Test Paper 4 (100 marks)
Question
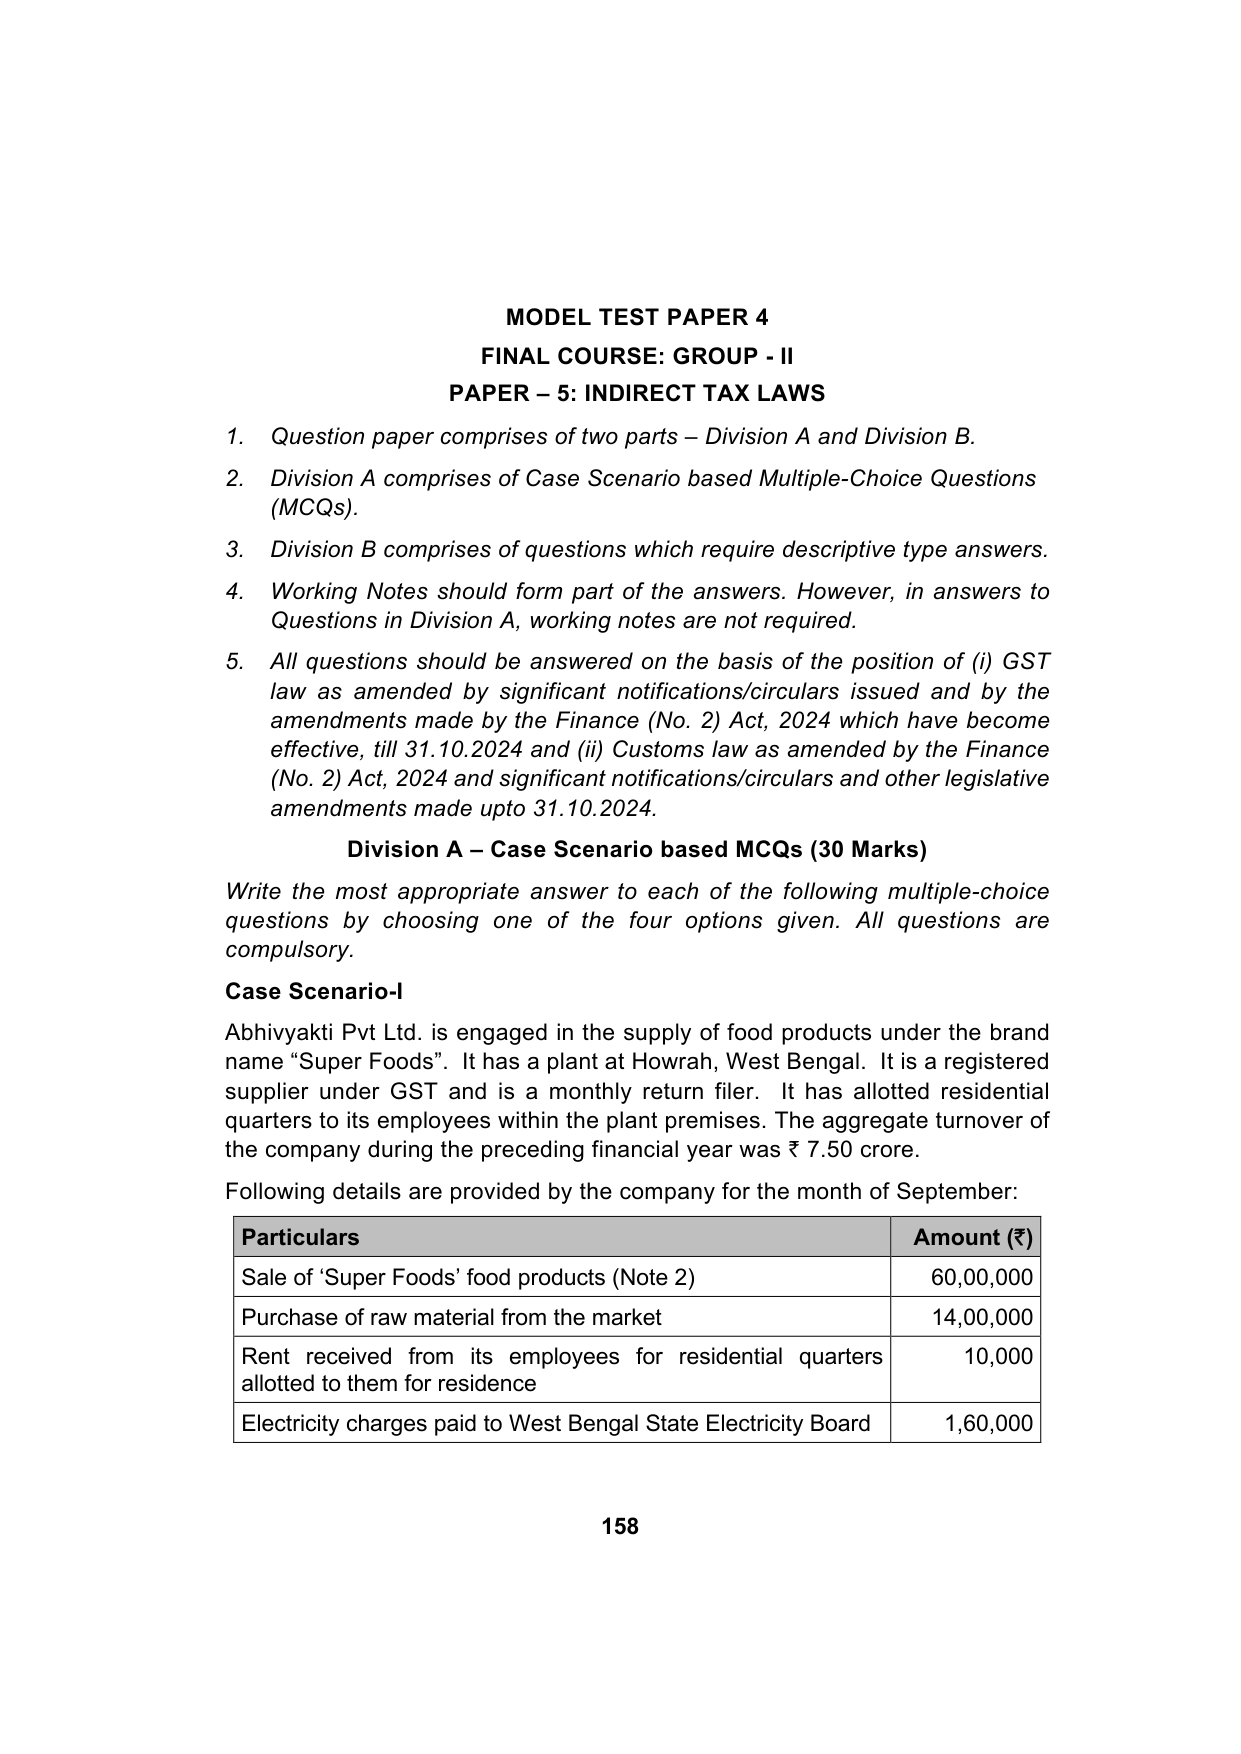
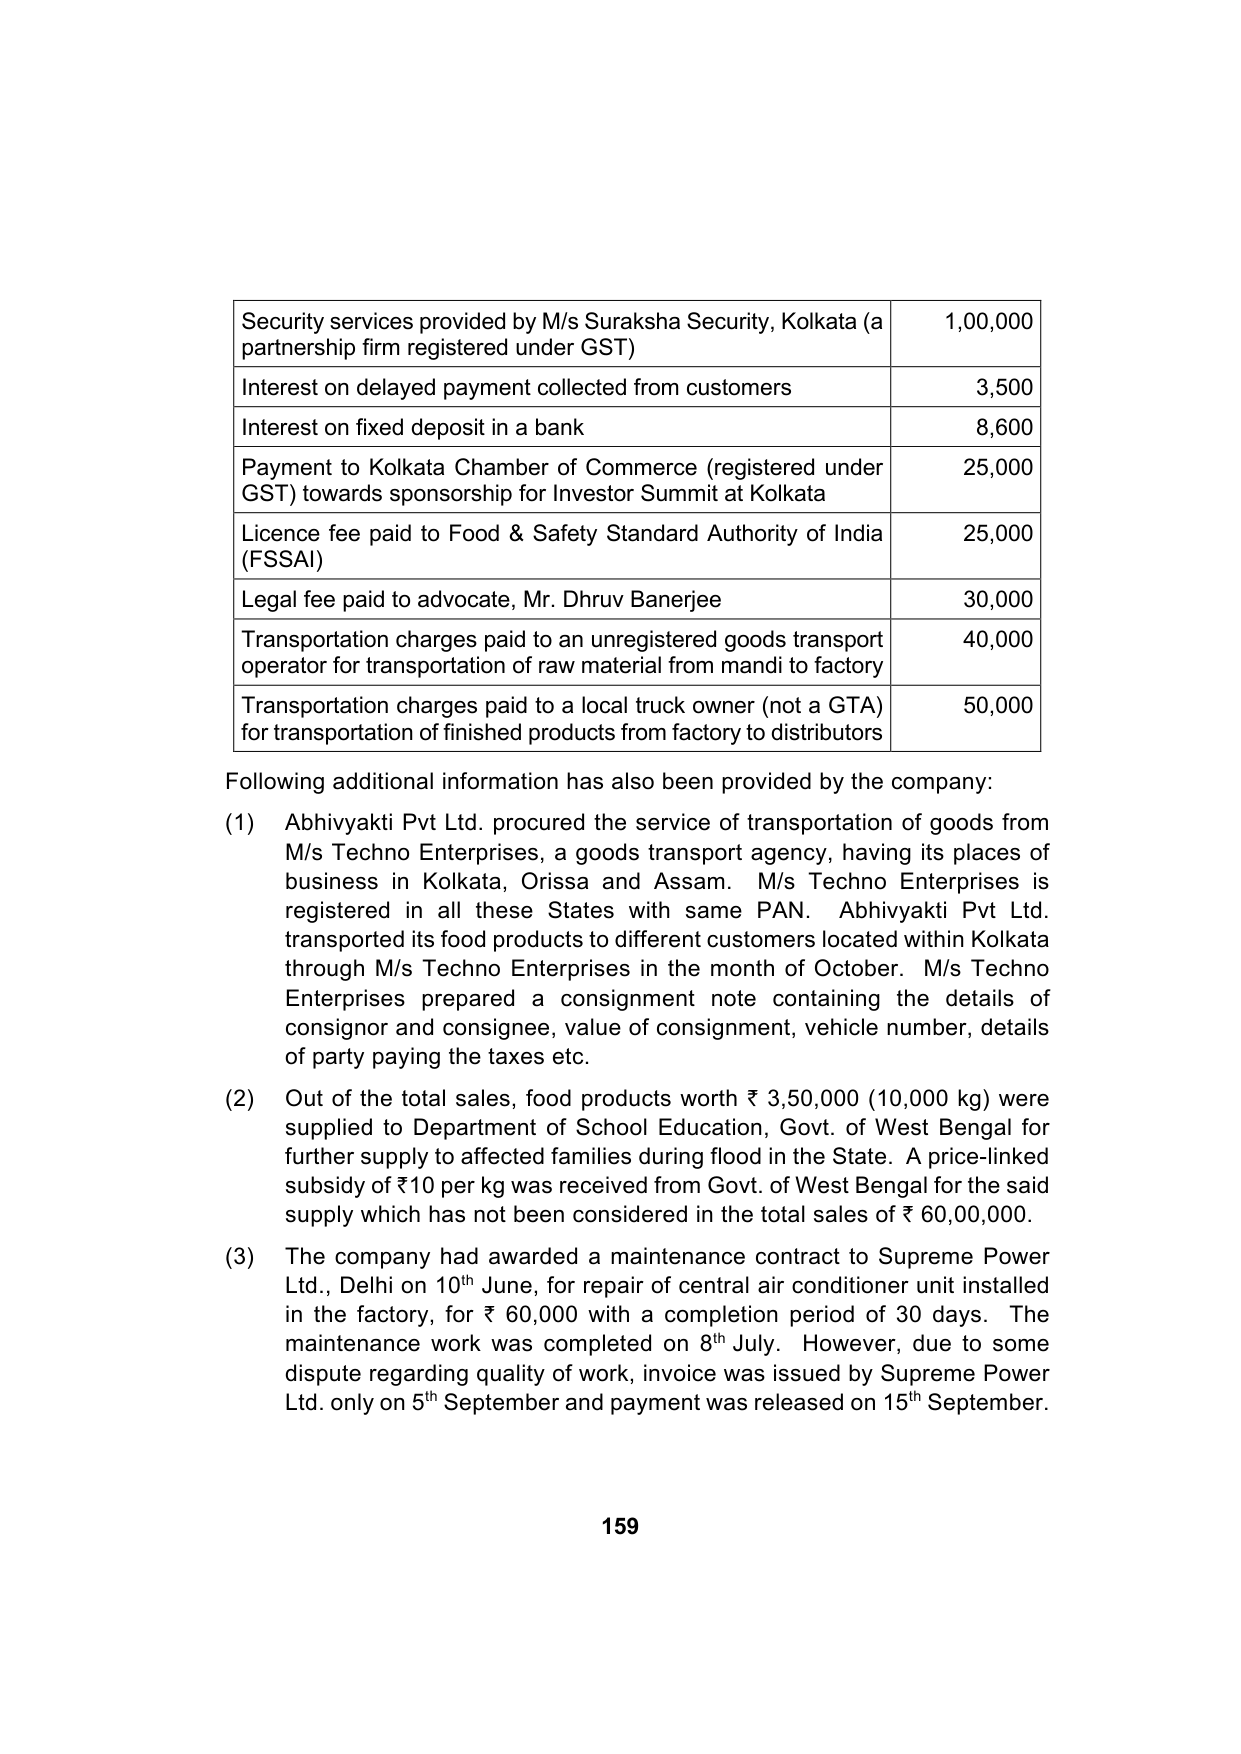
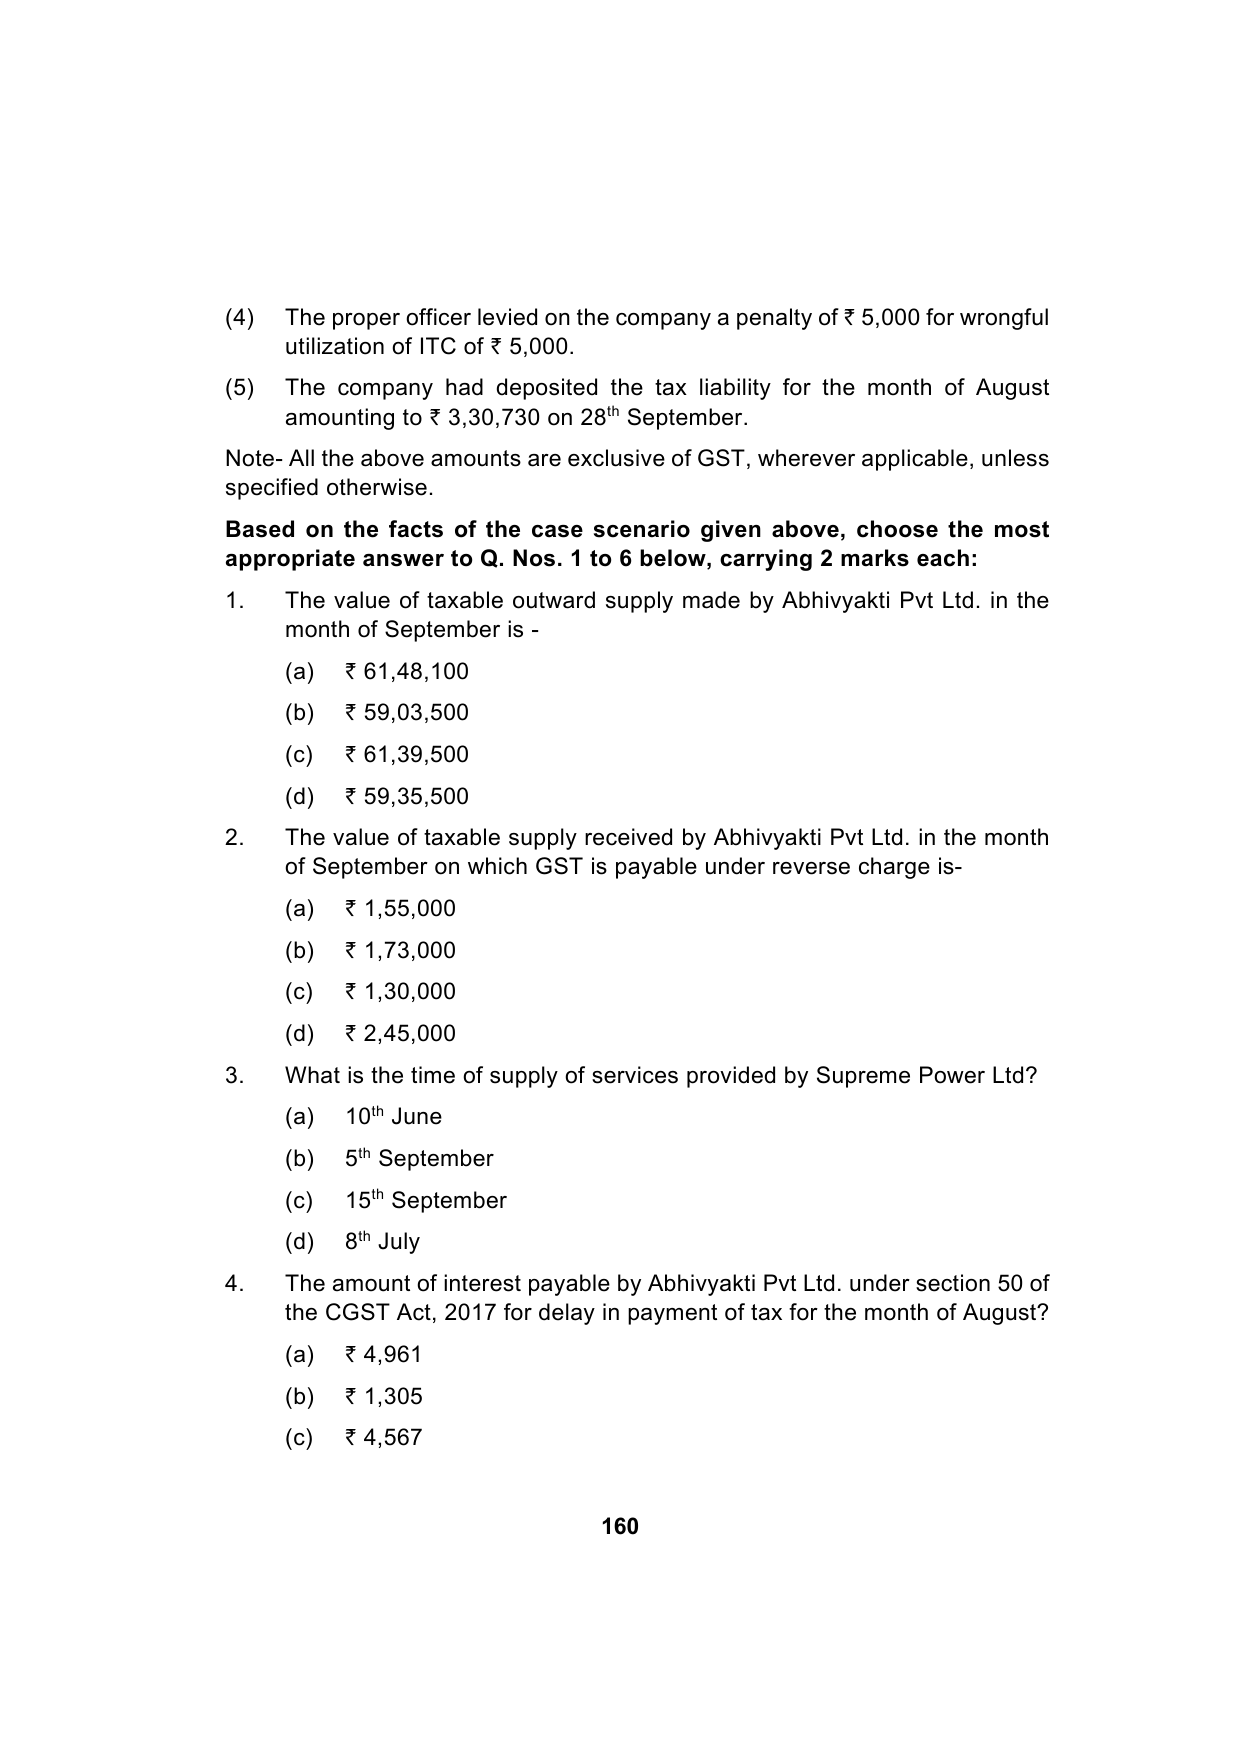
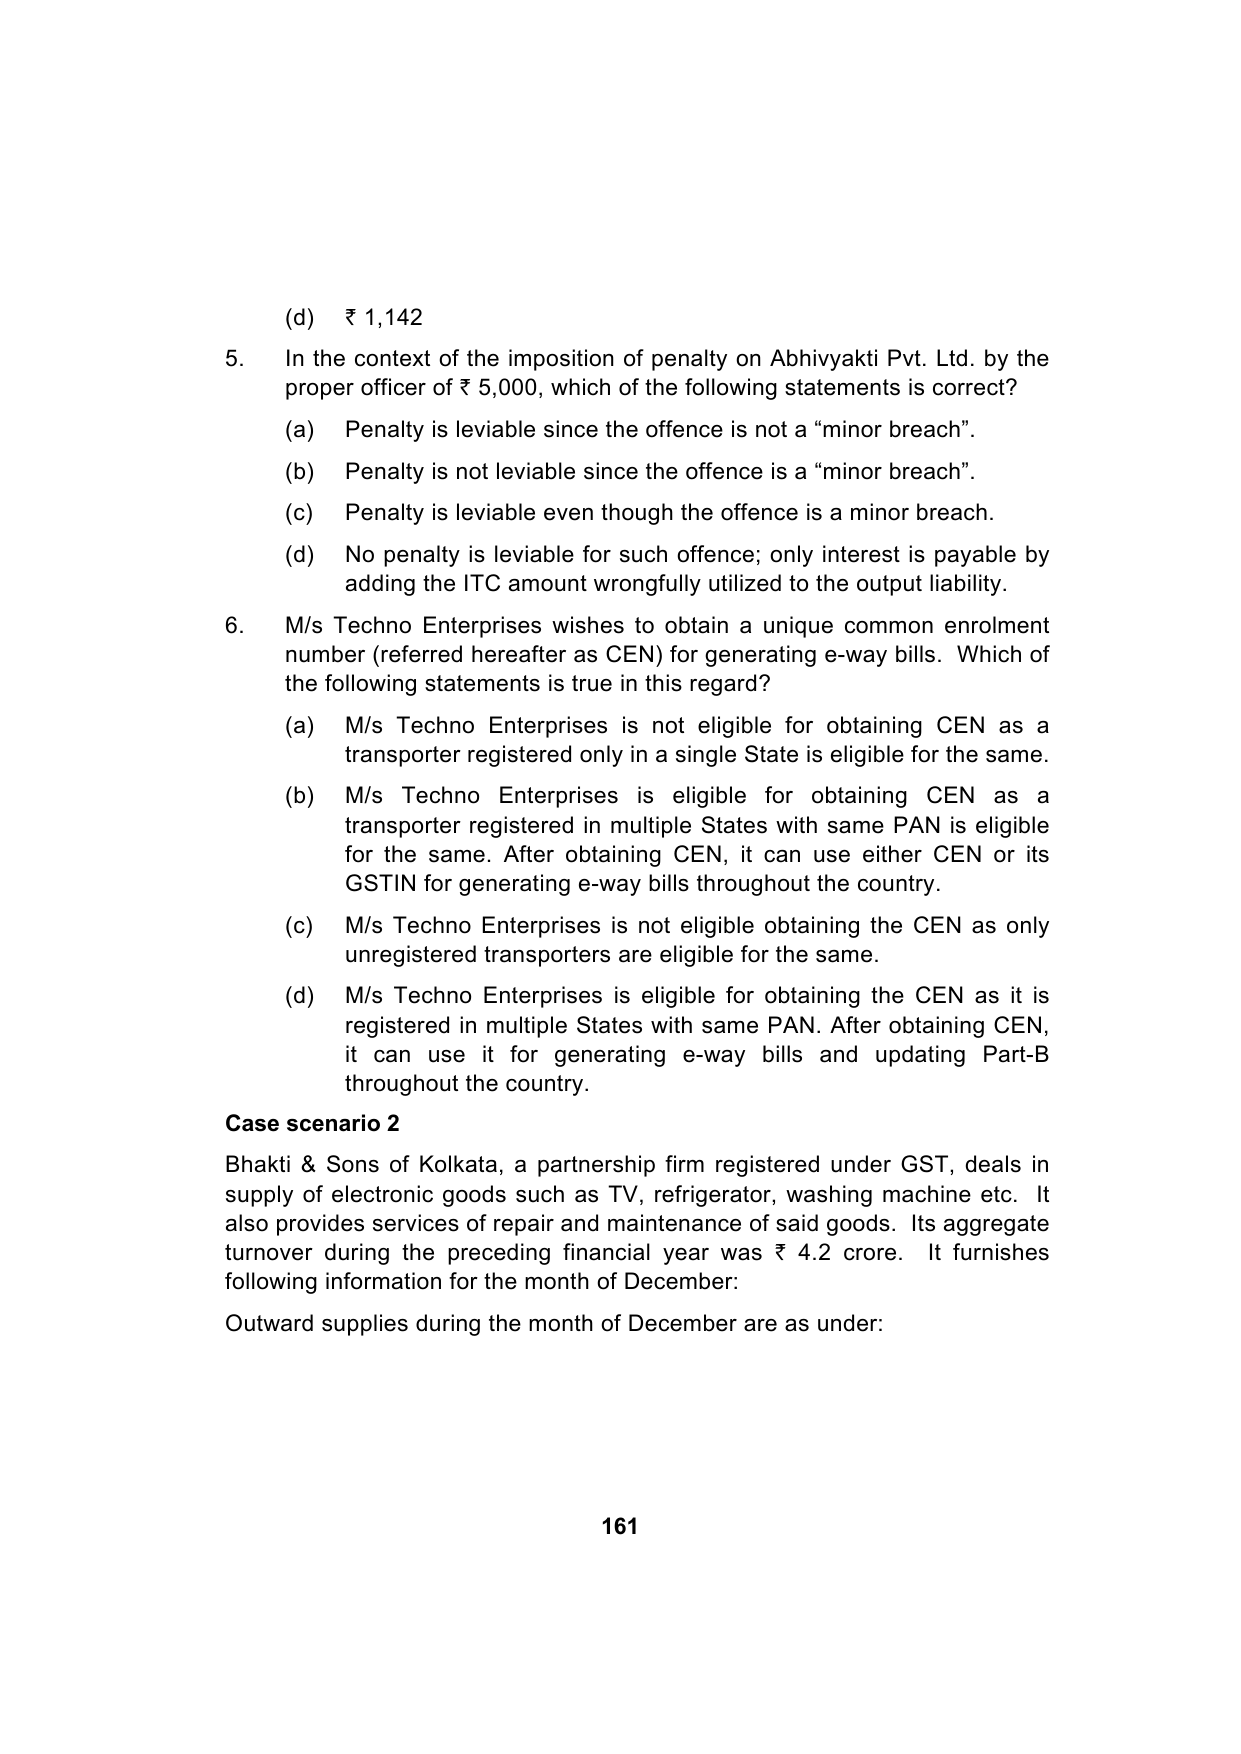
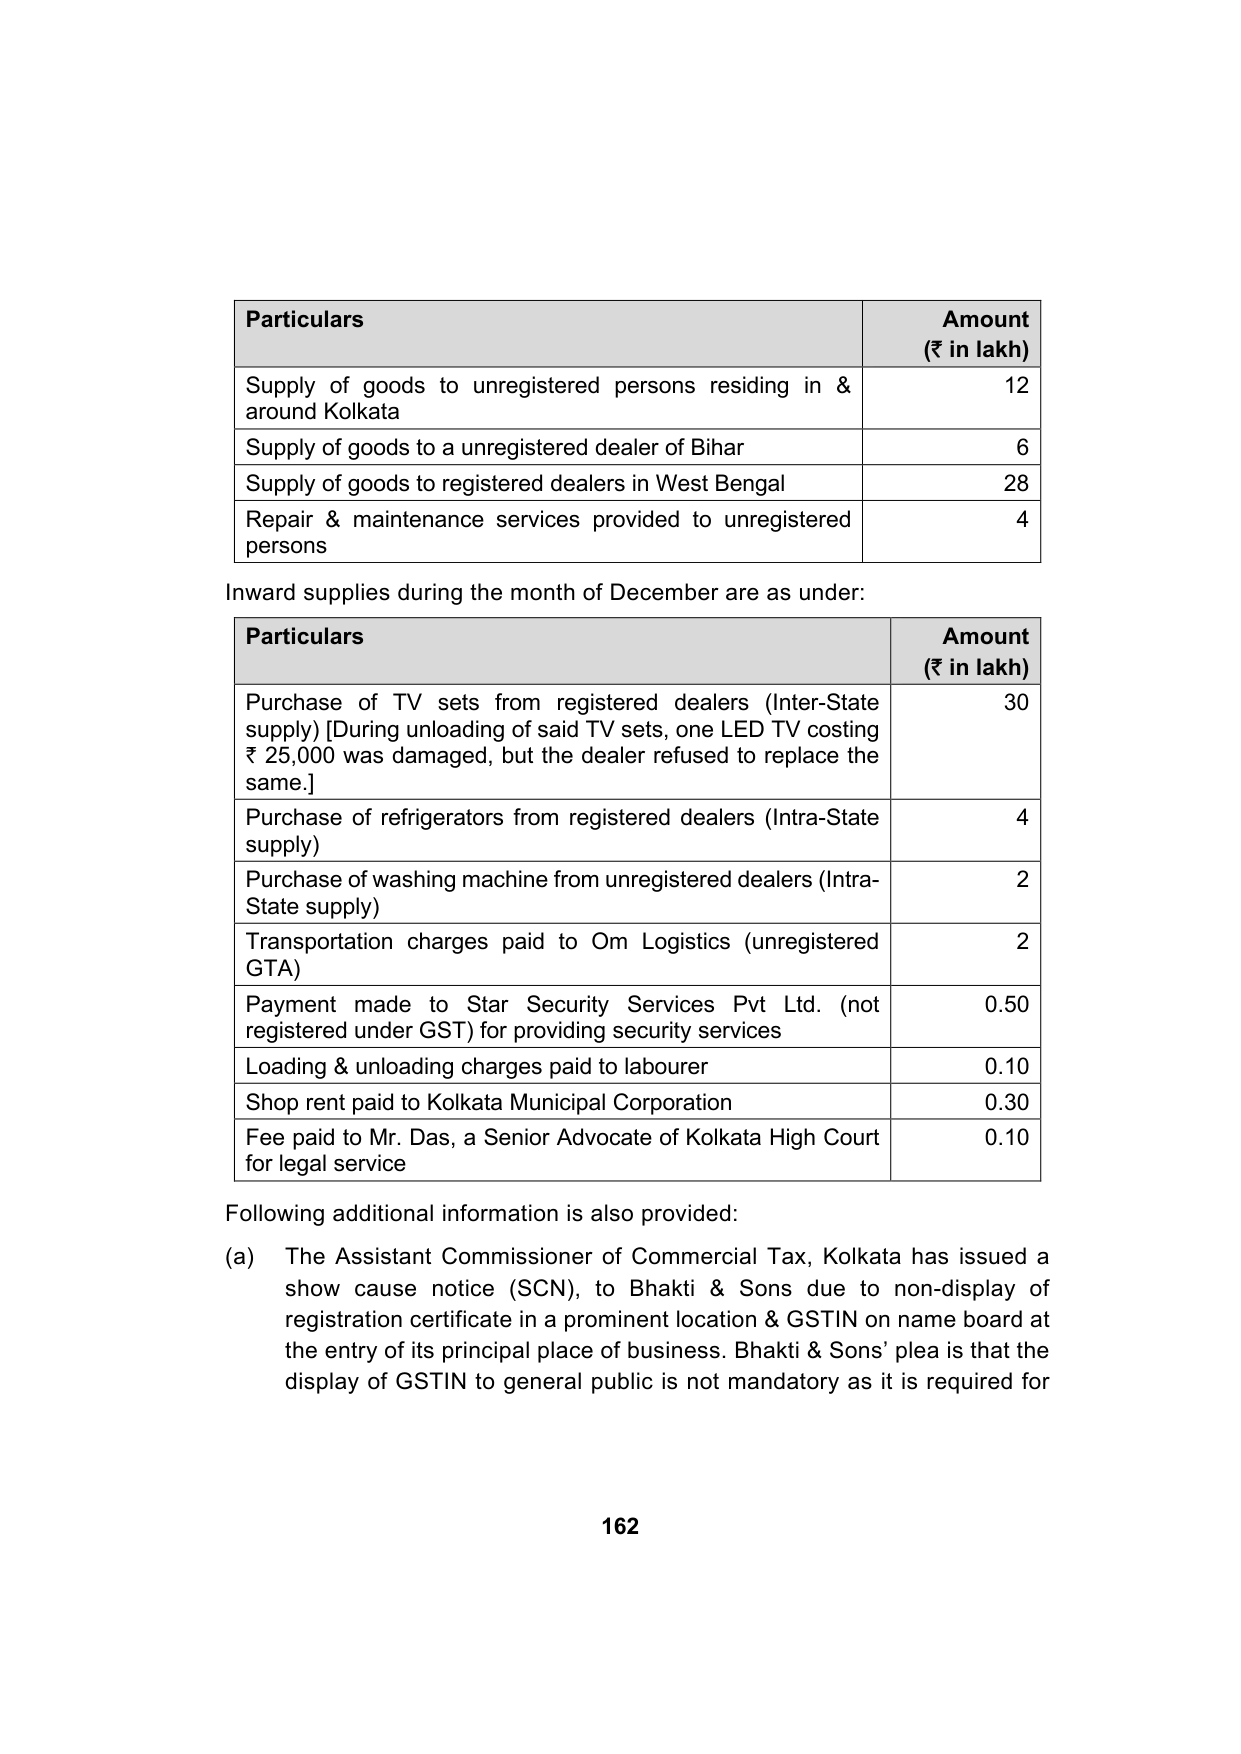
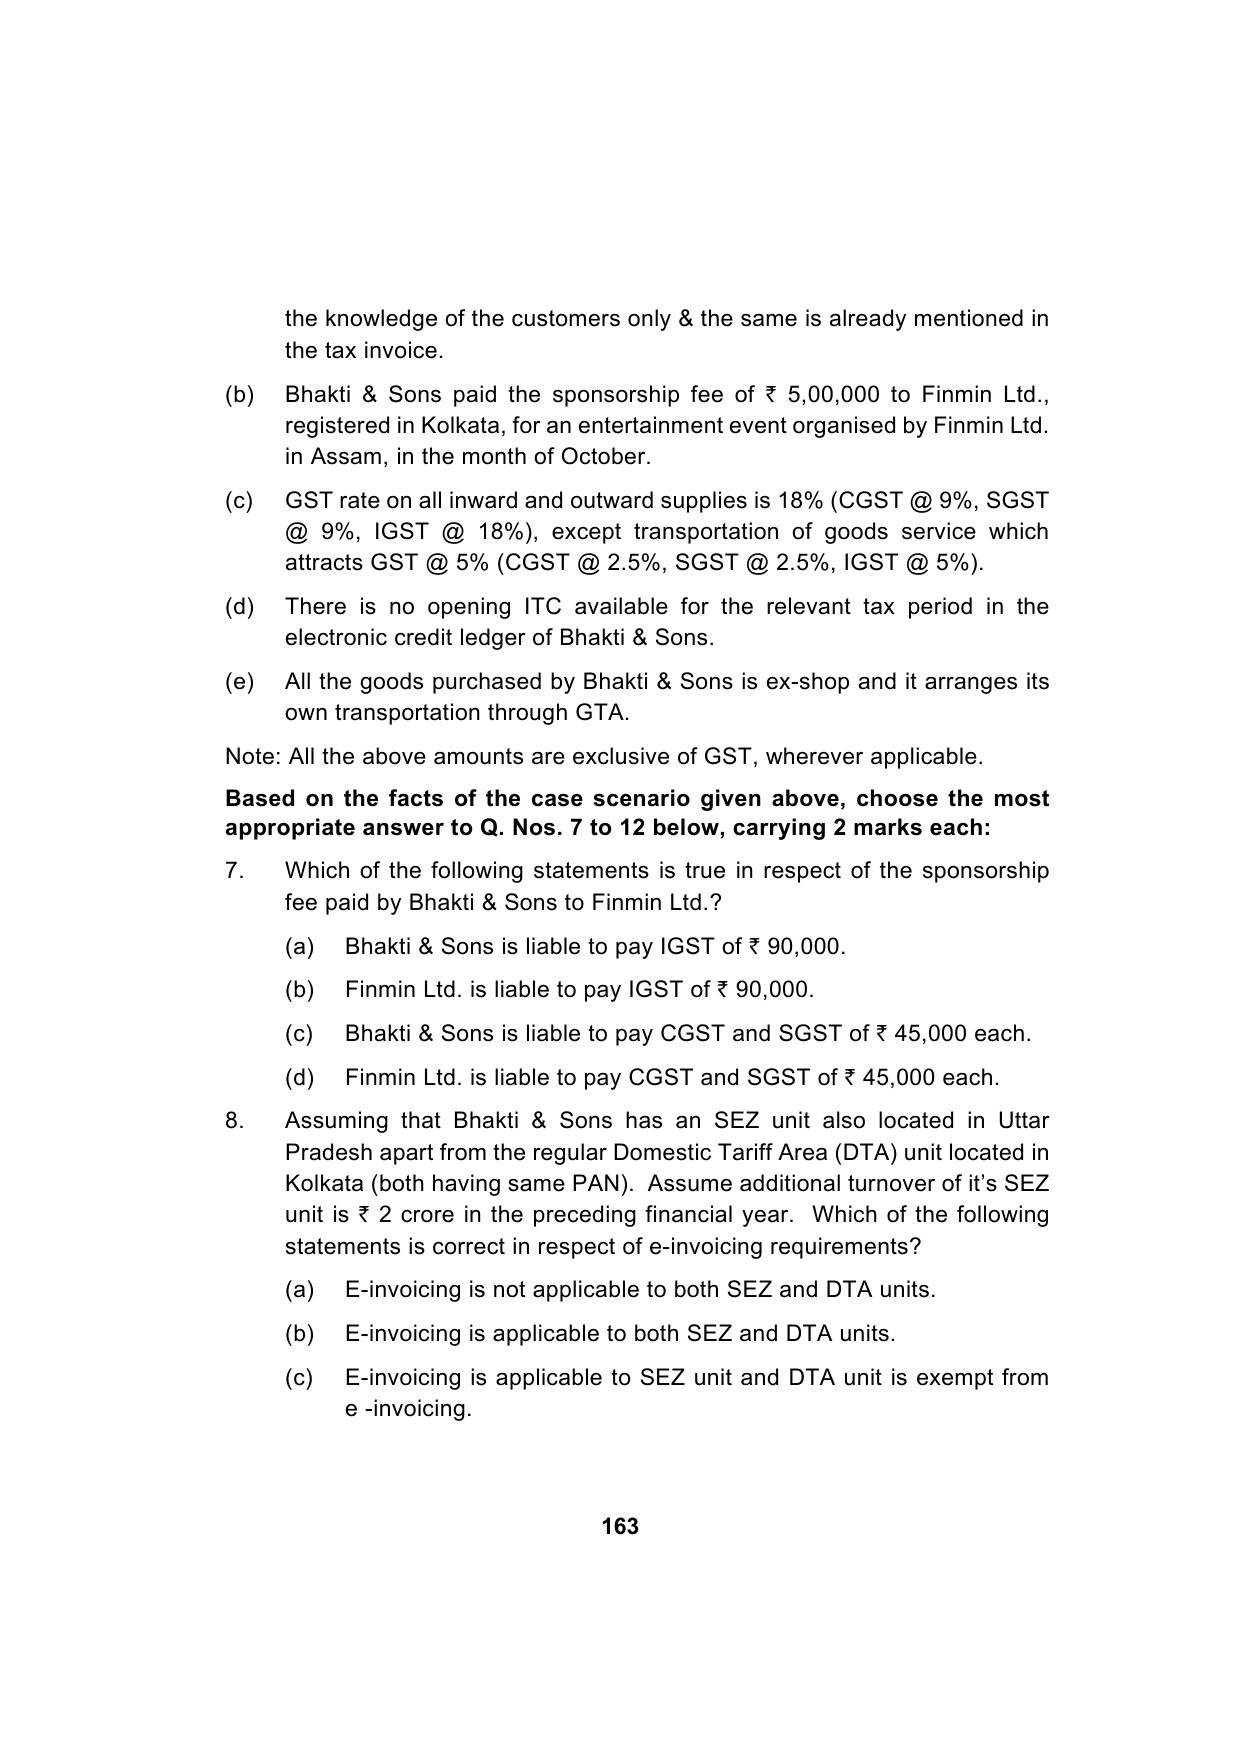
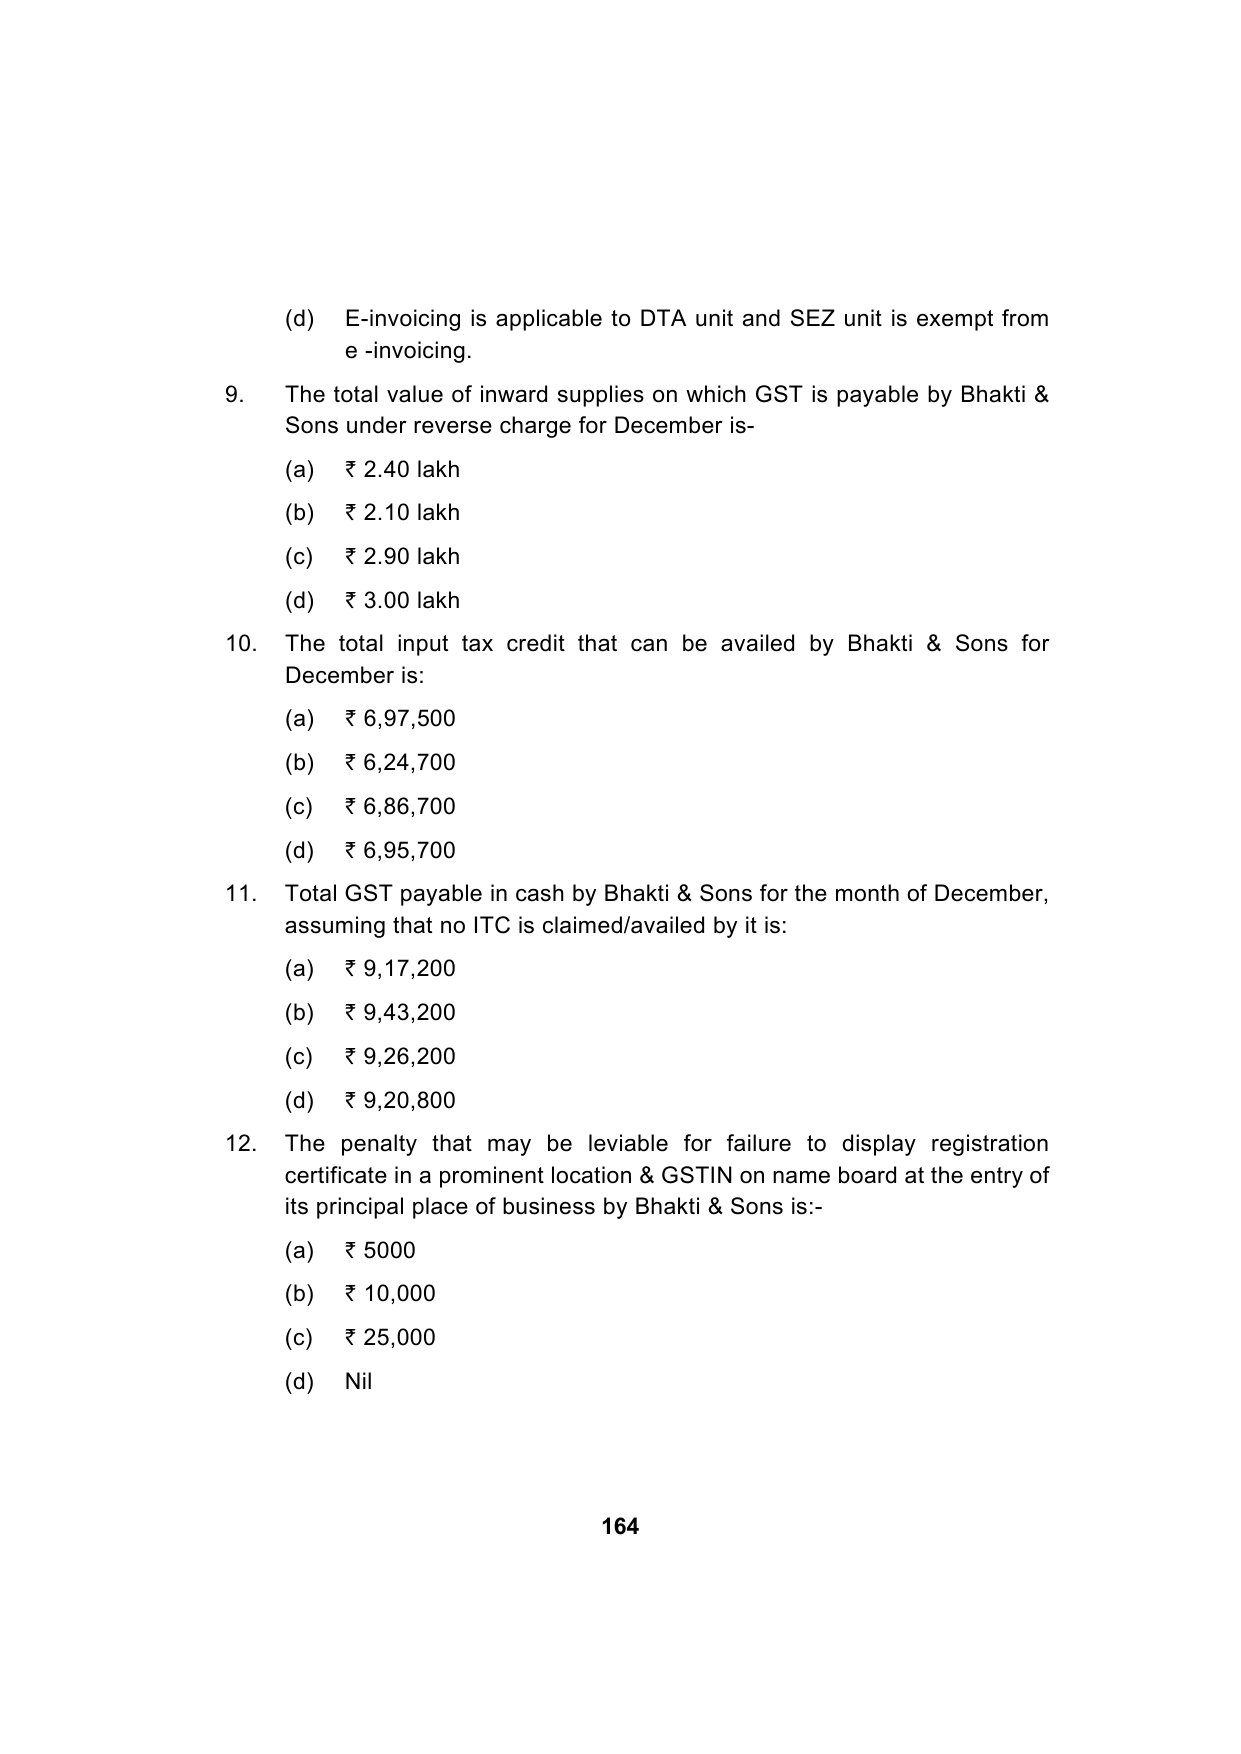
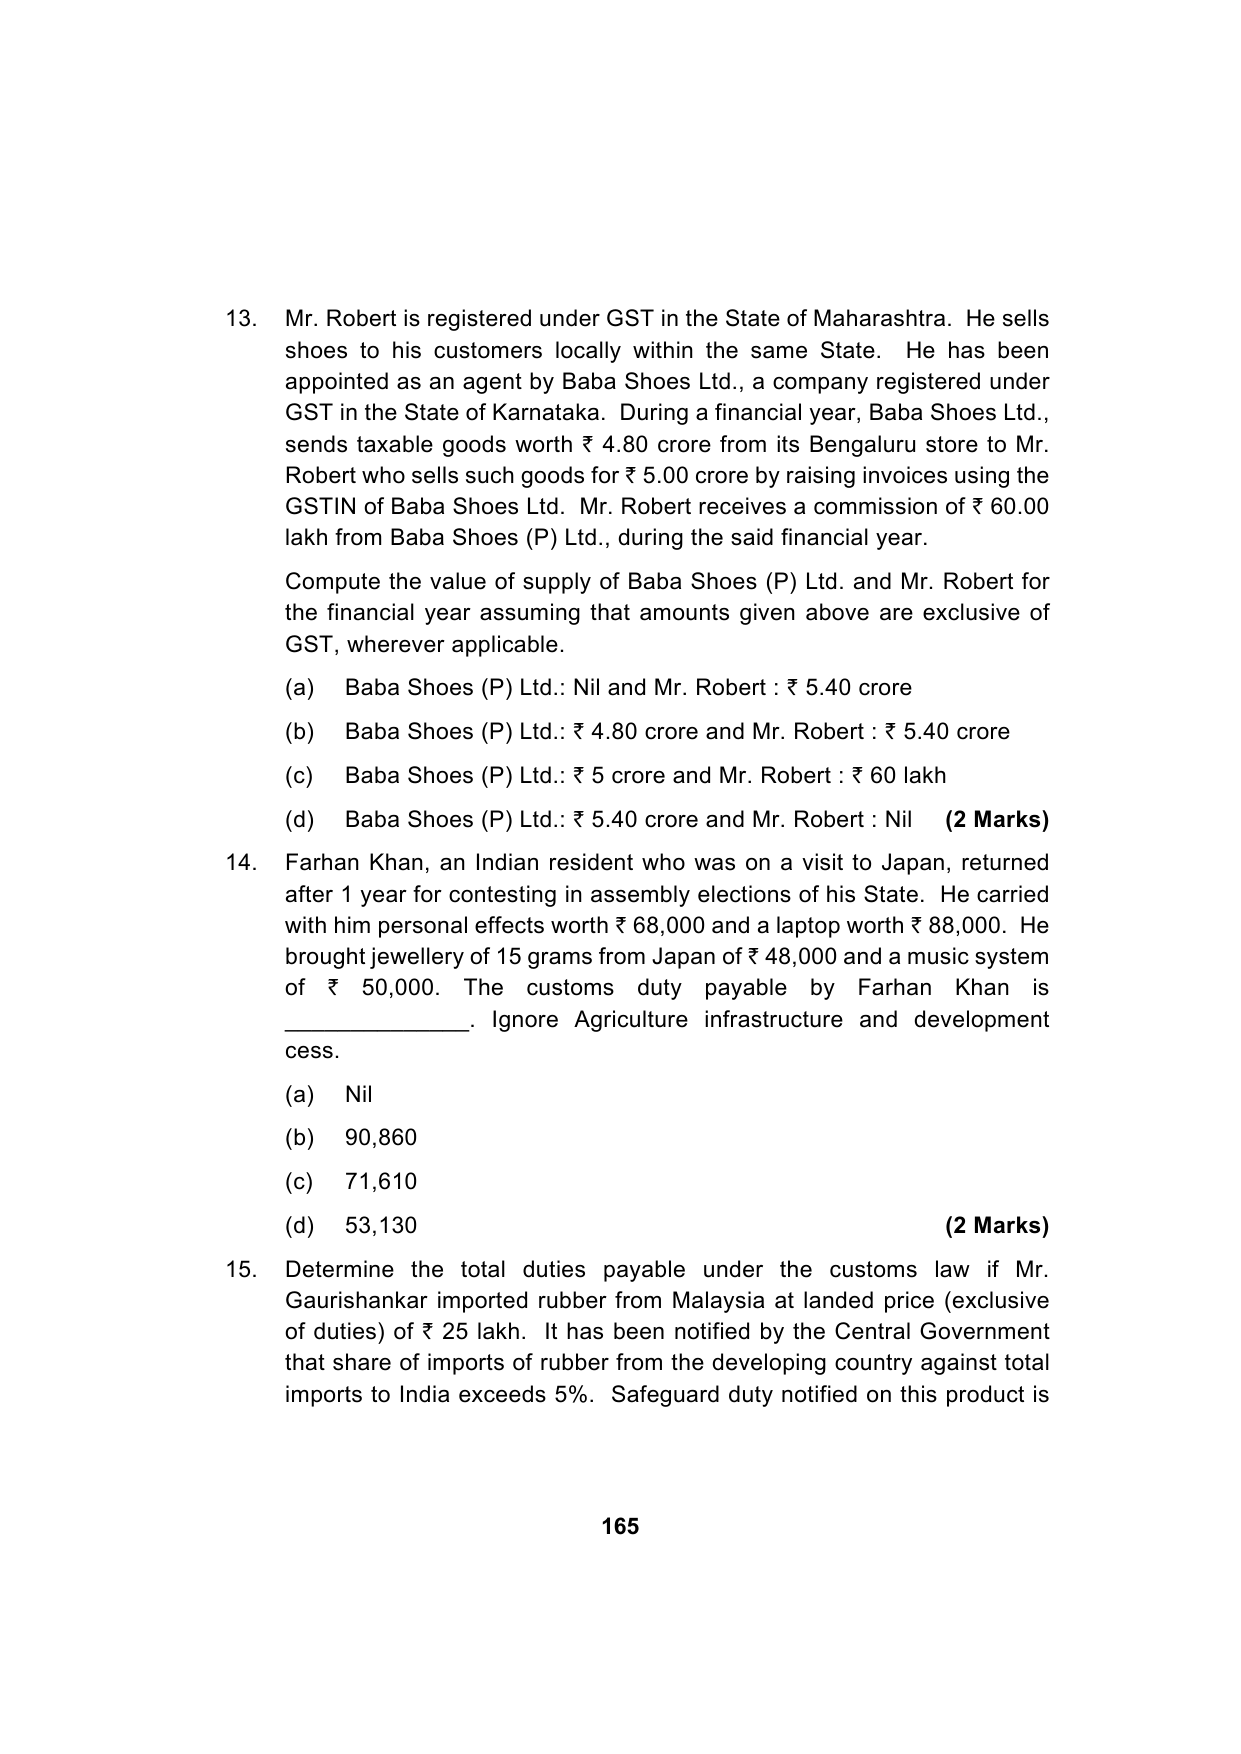
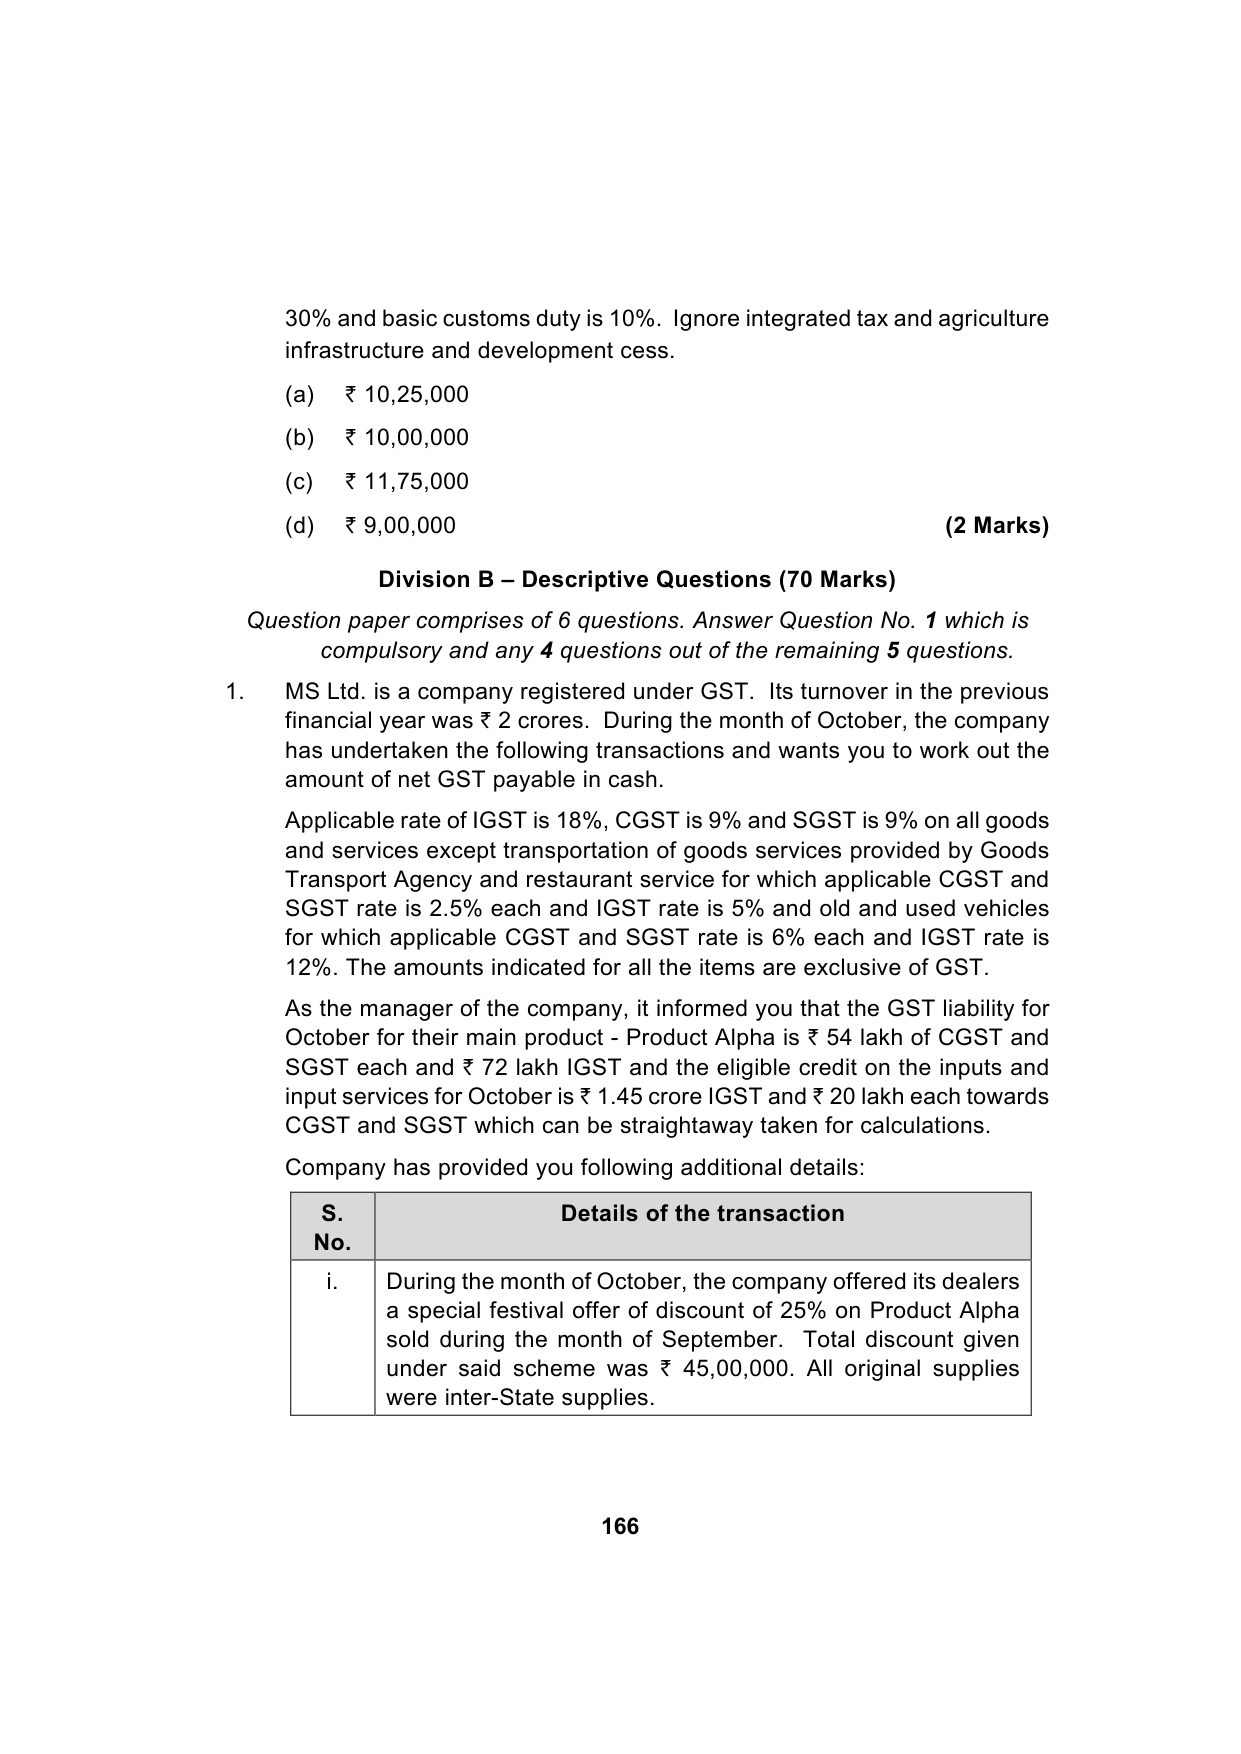
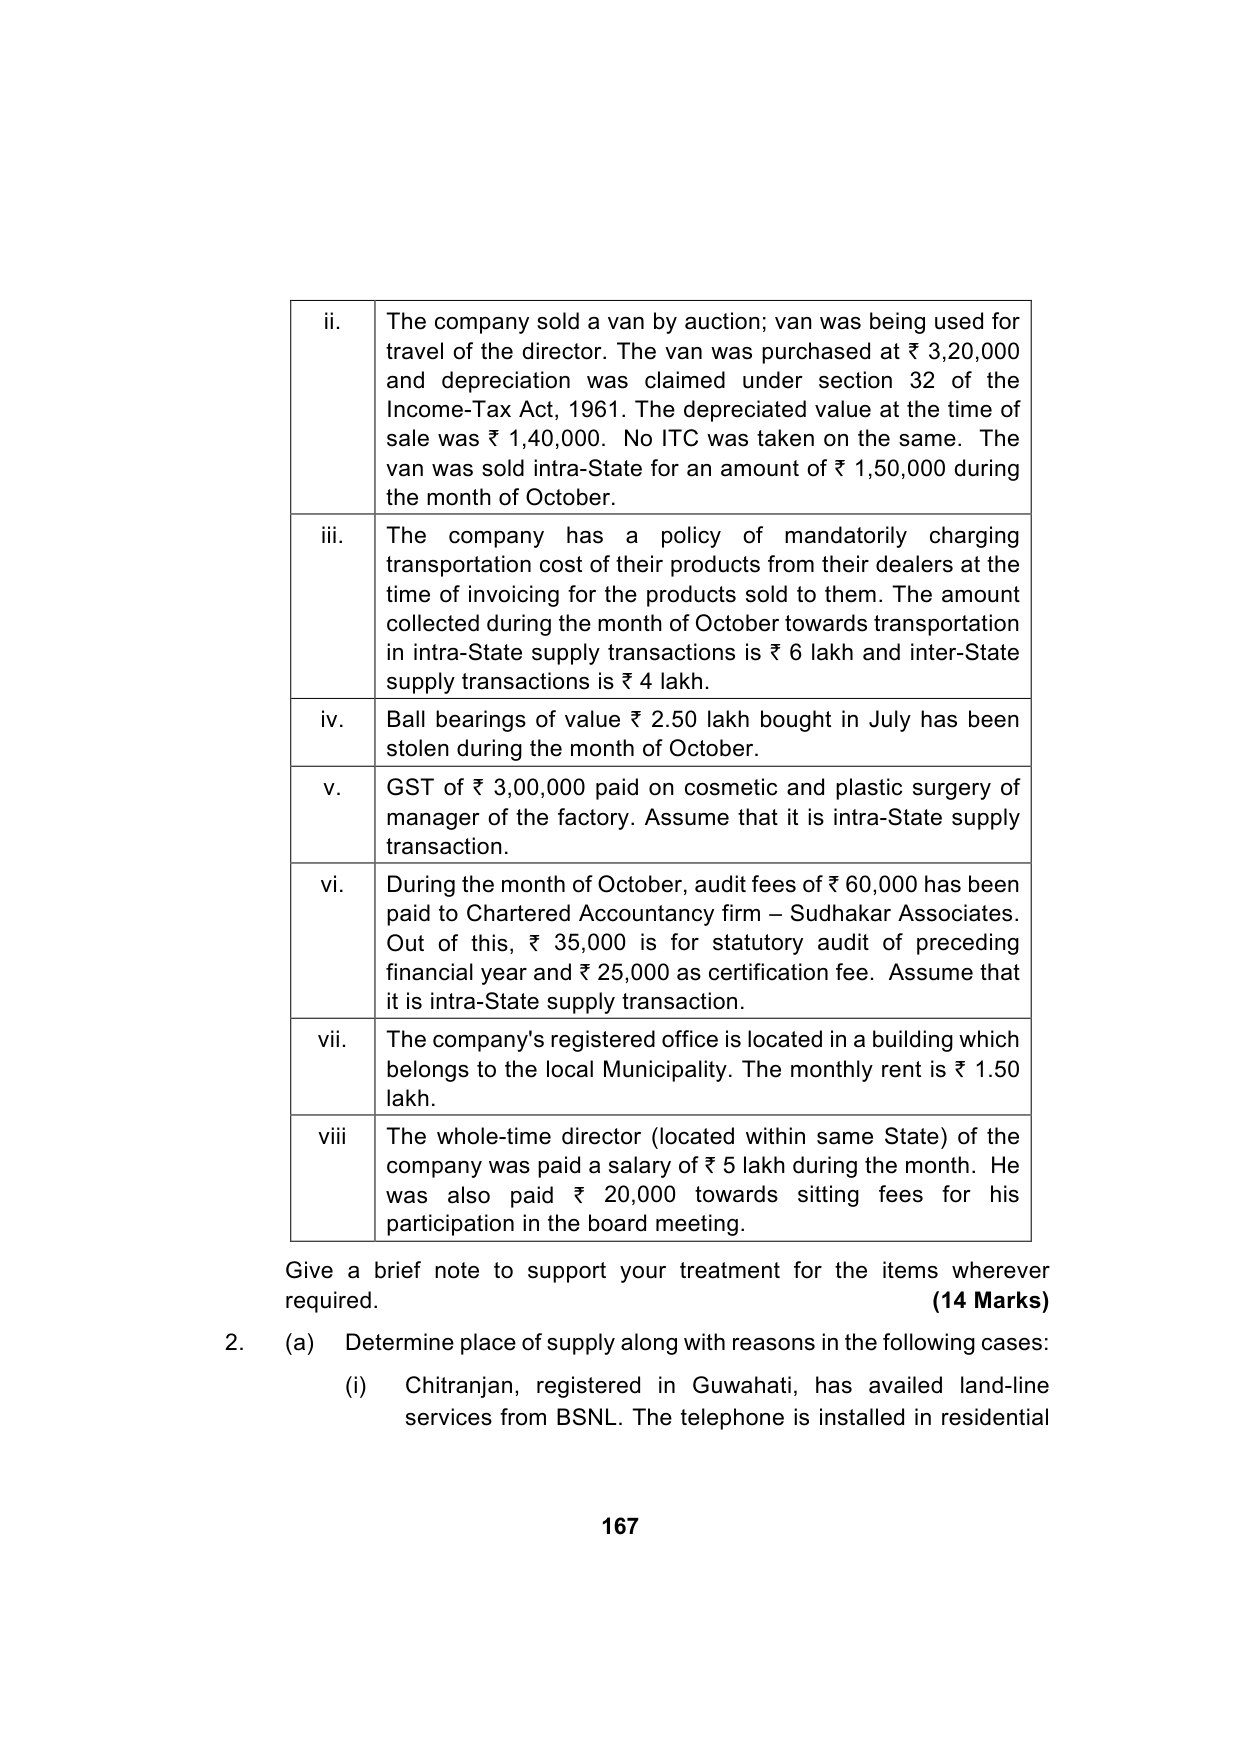
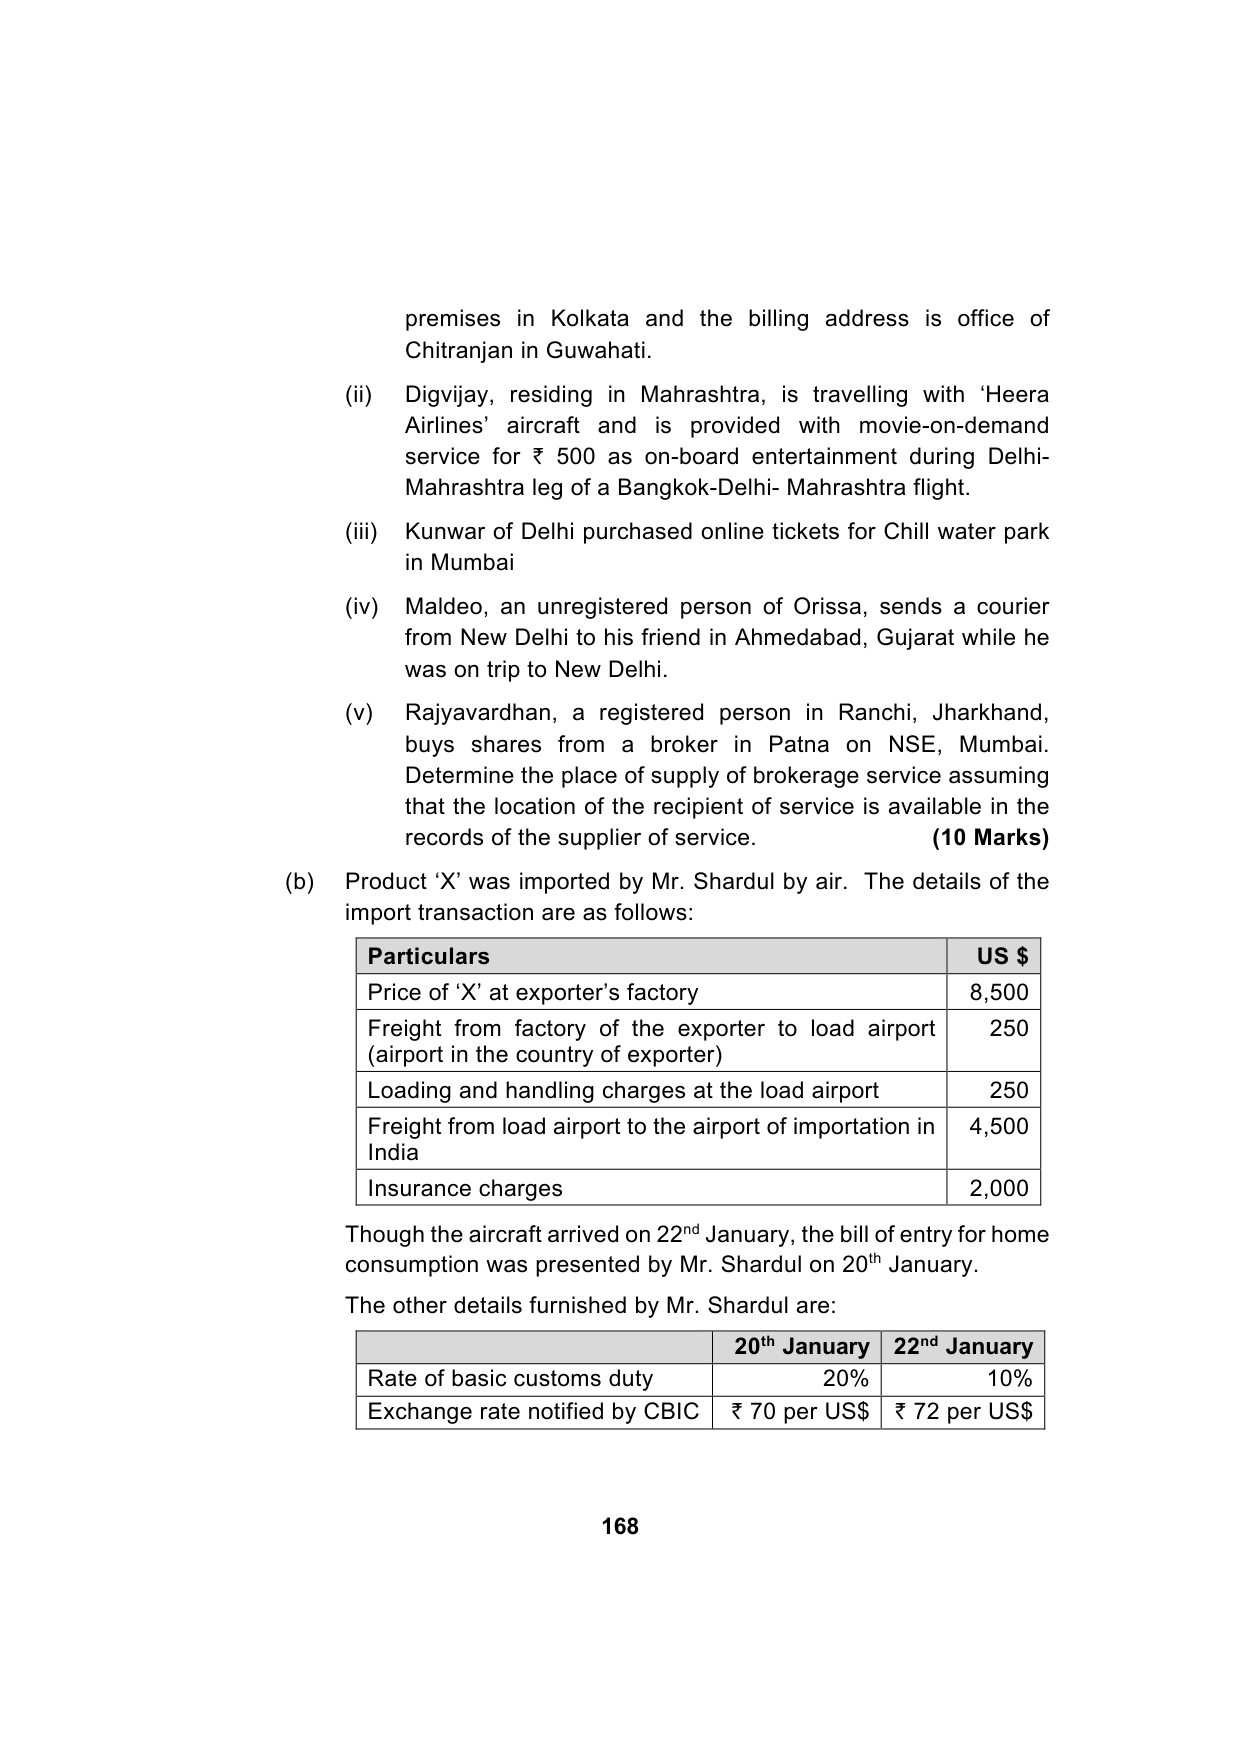
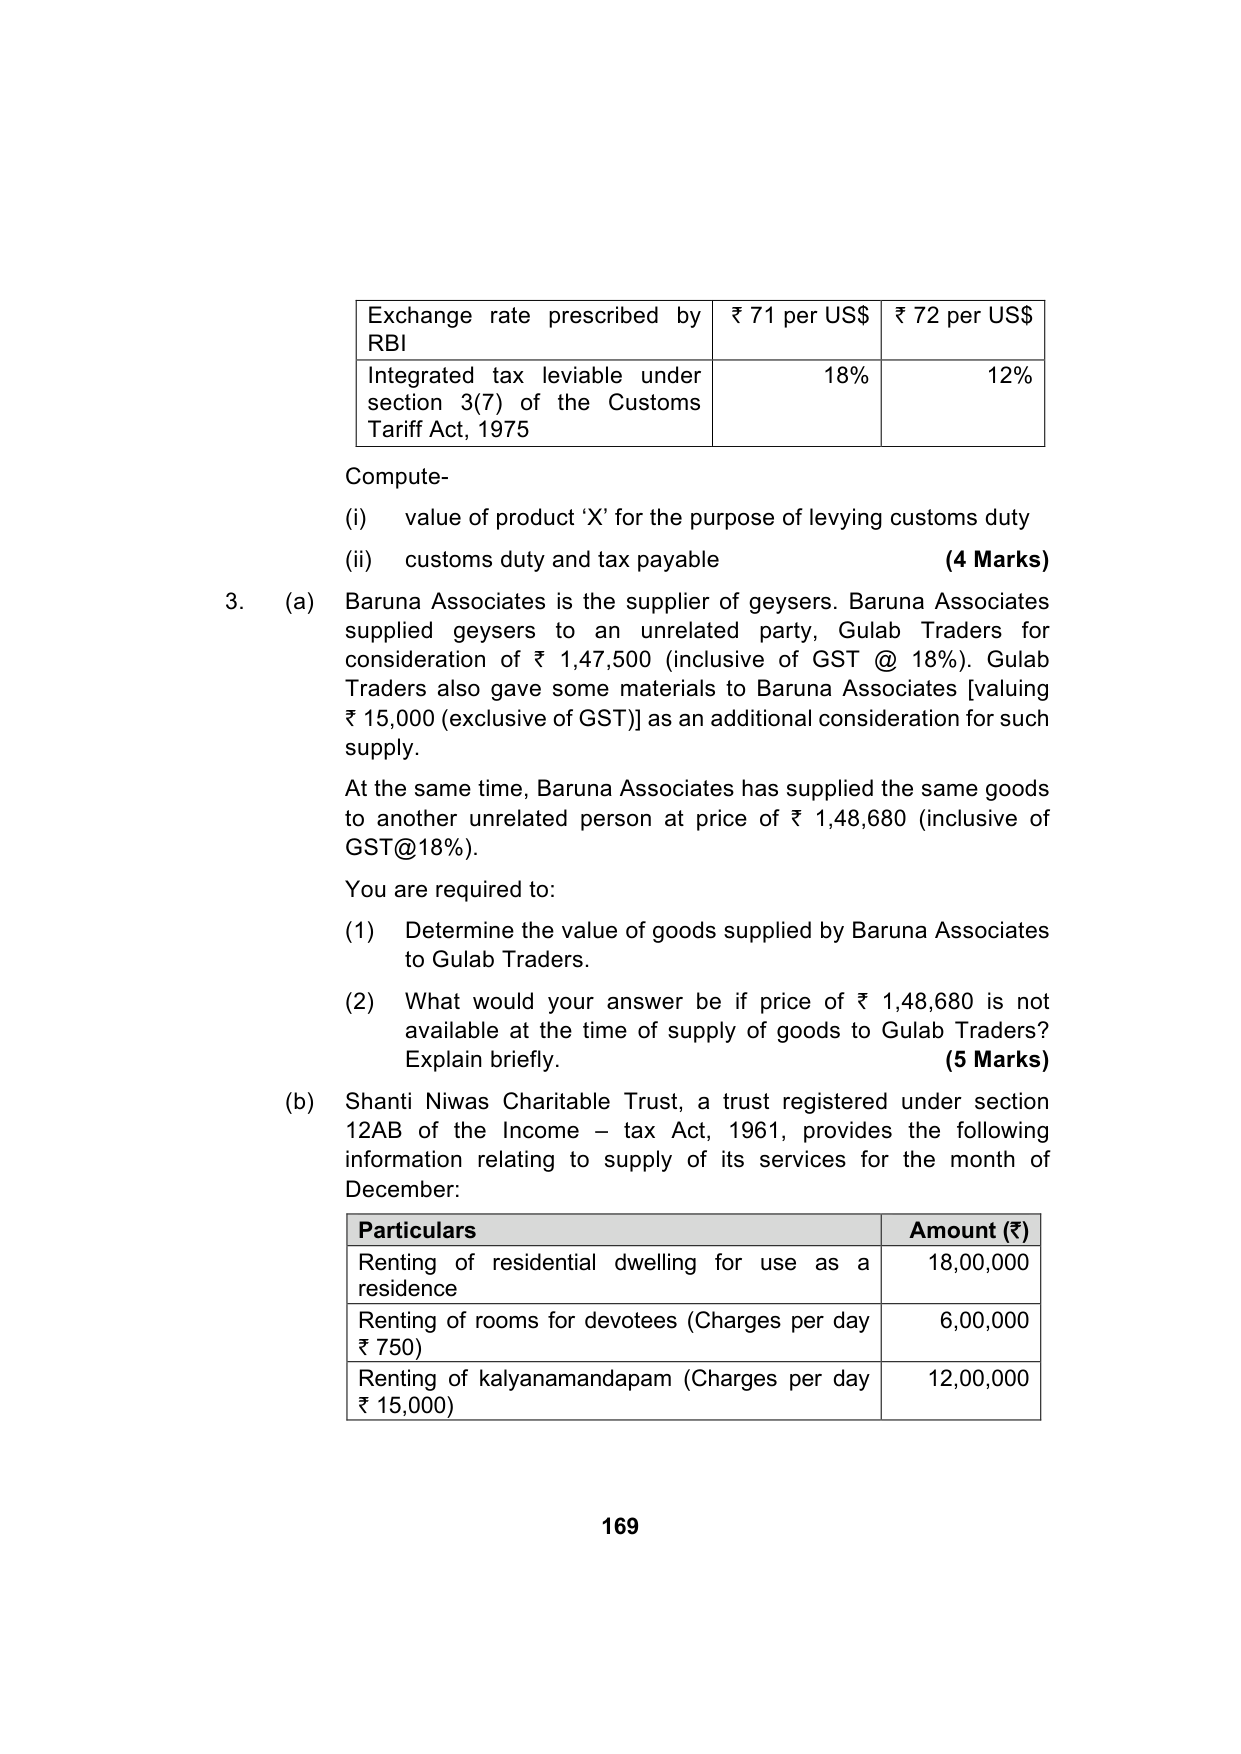
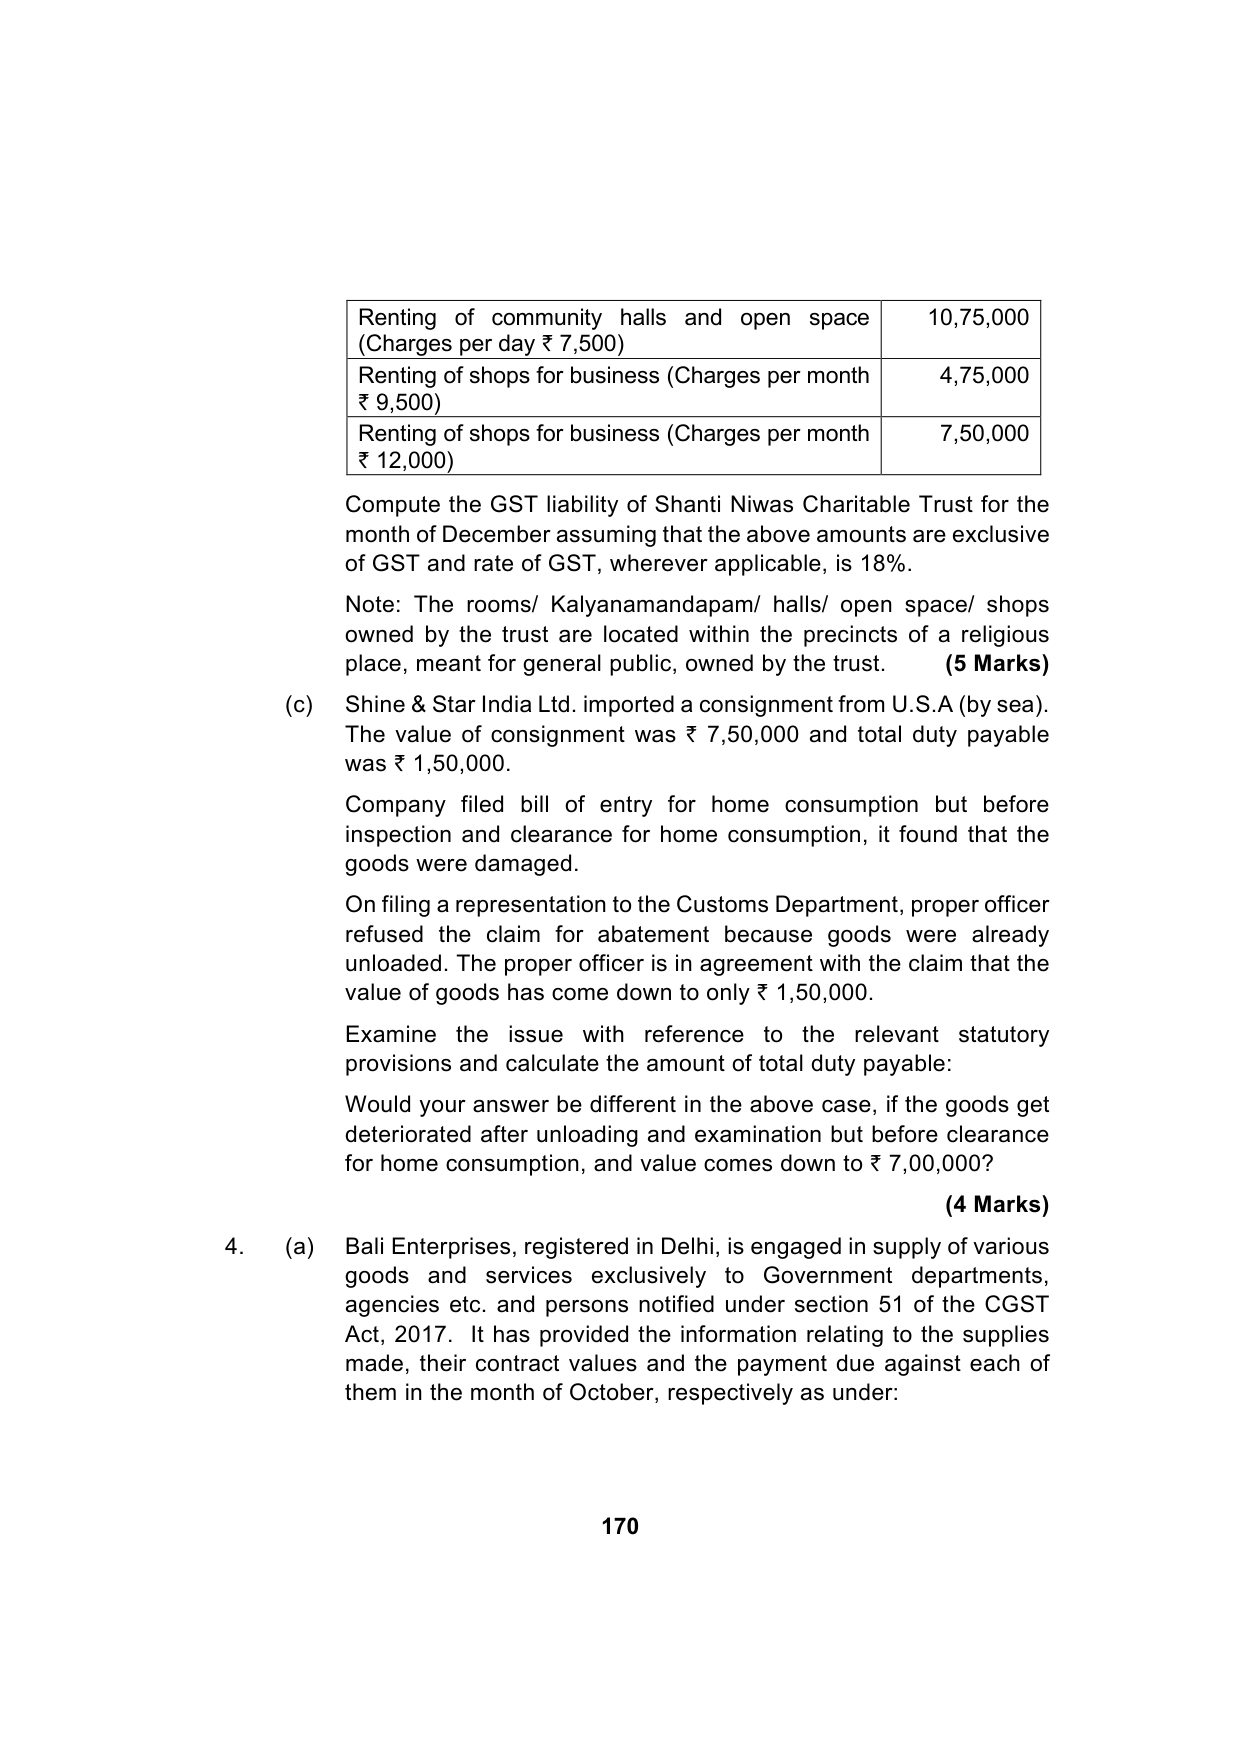
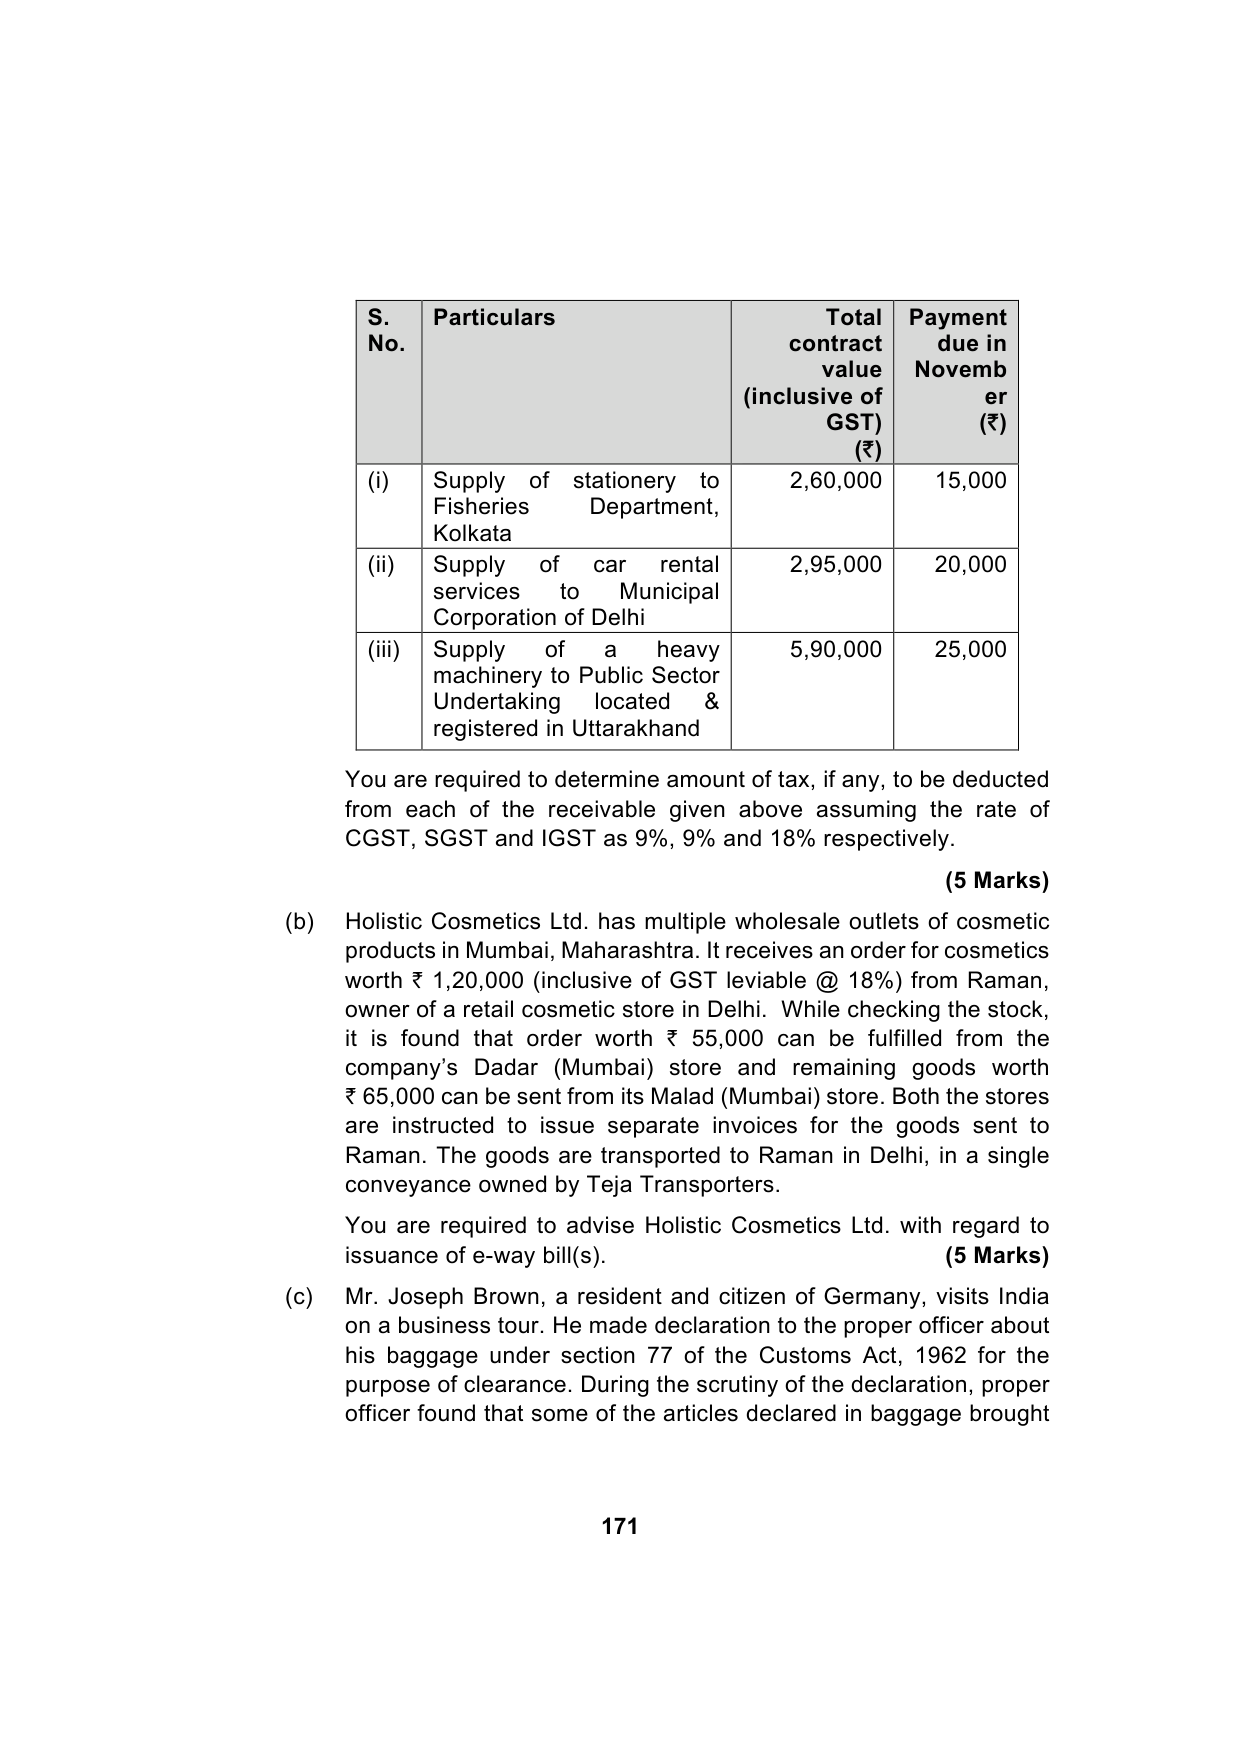
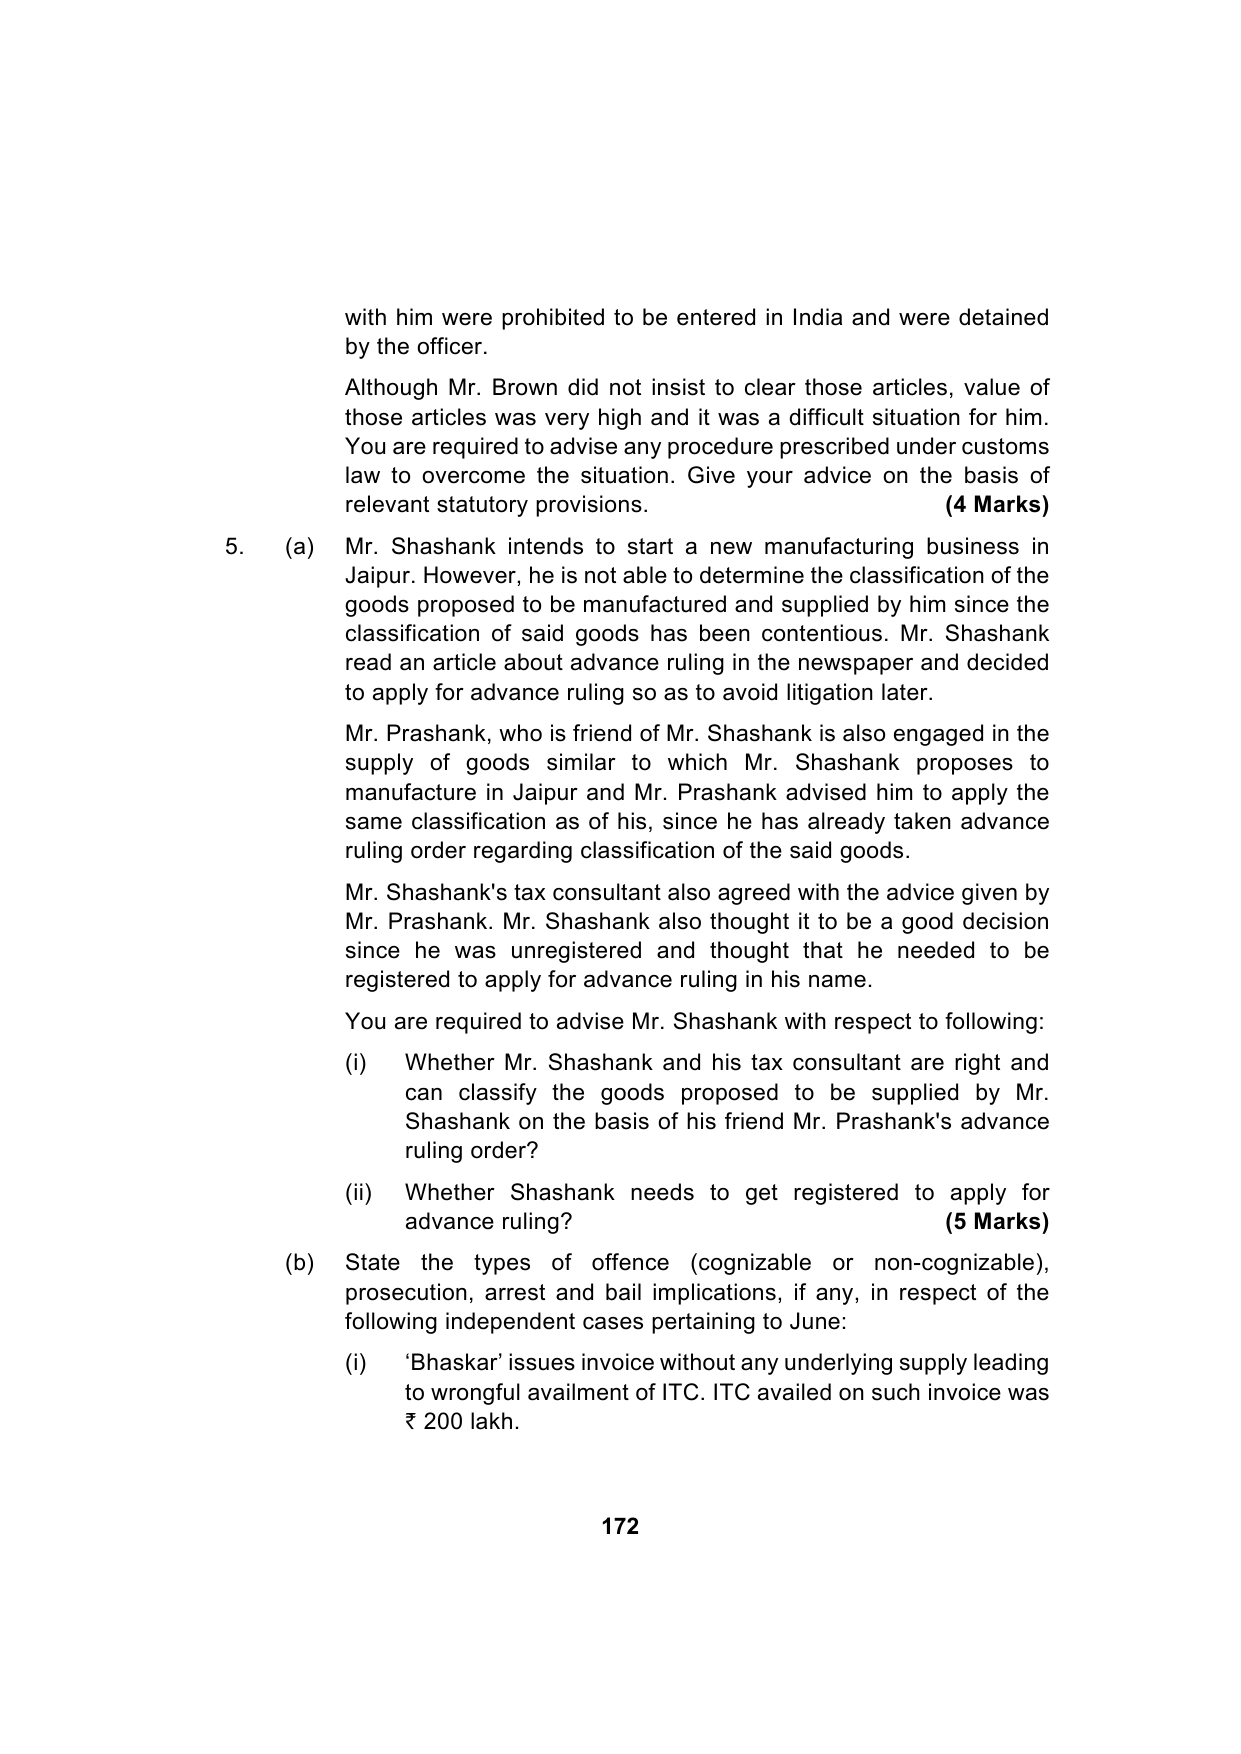
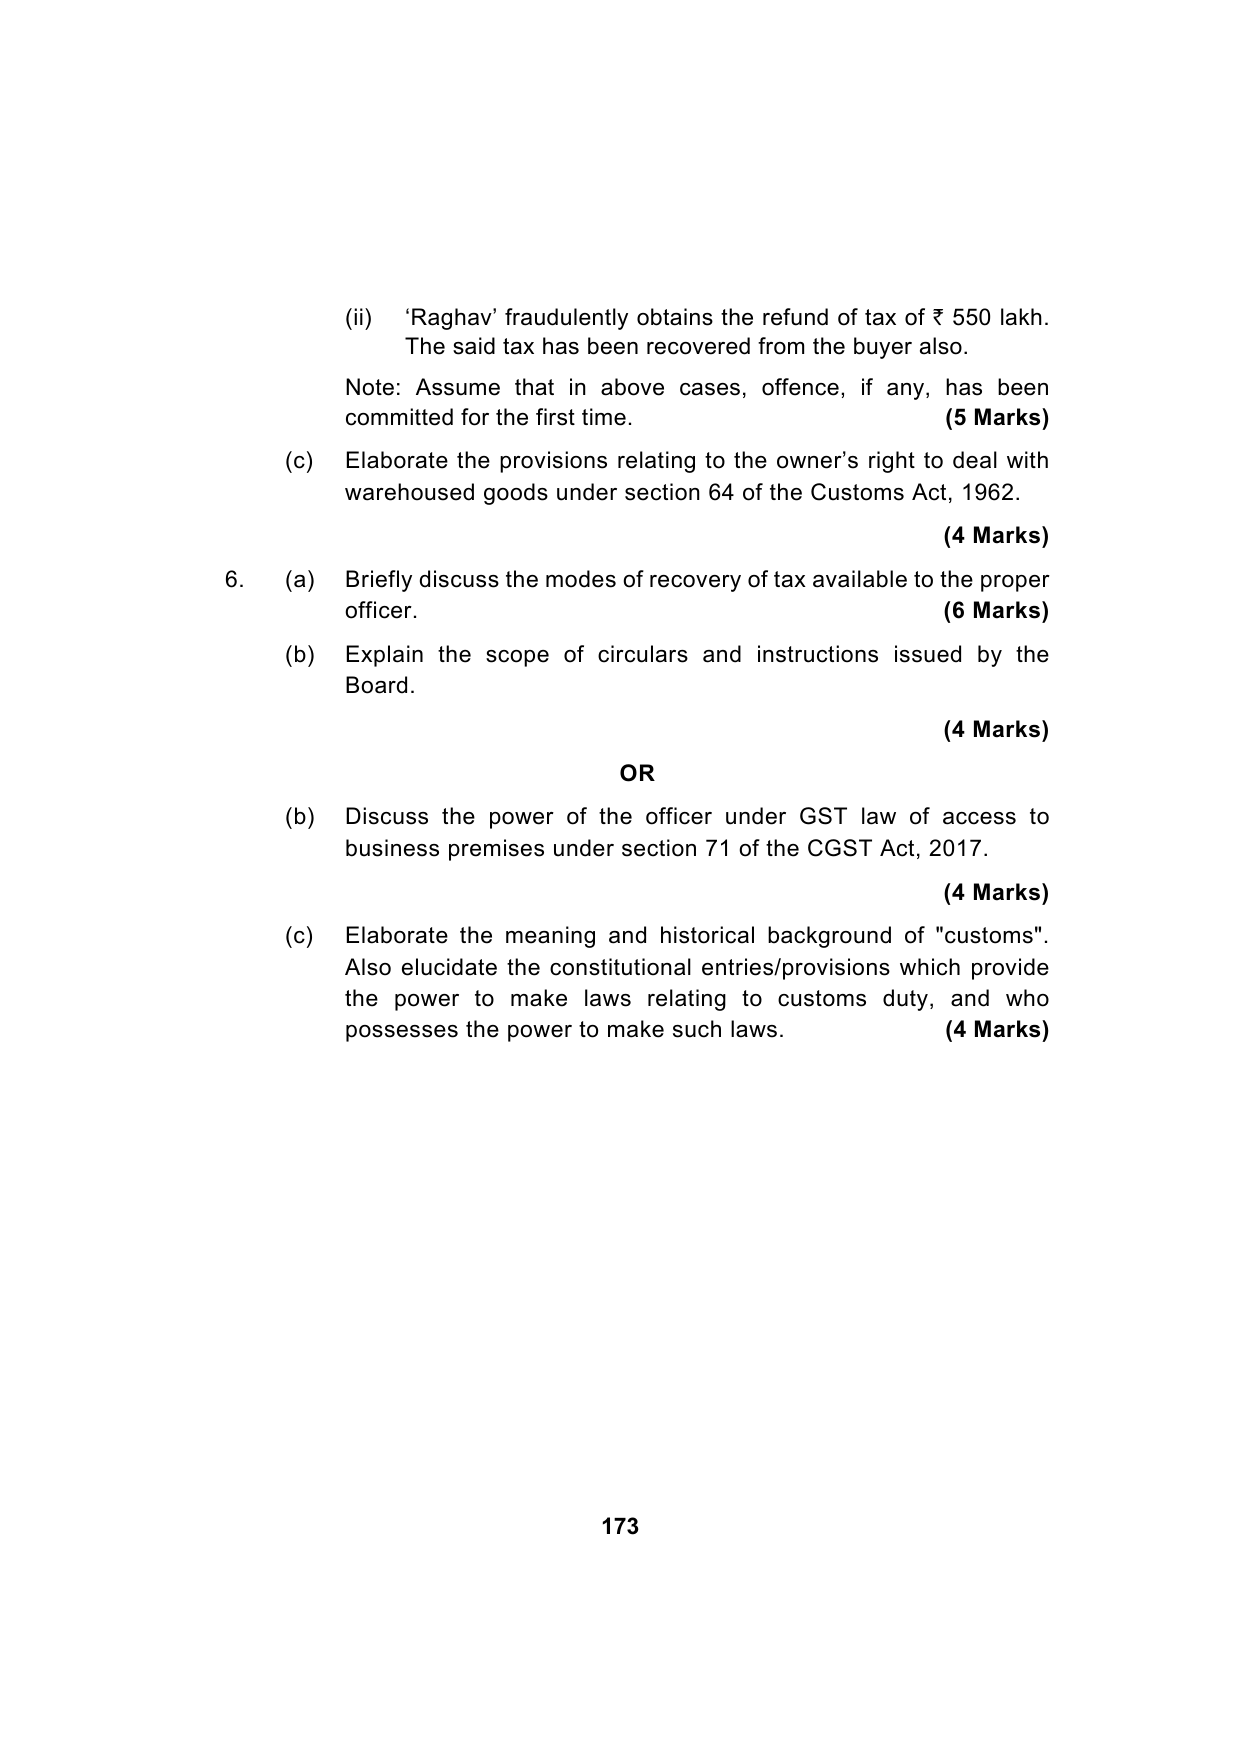
Paper 5: Indirect Tax Laws — Model Test Paper 5 (100 marks)
Question
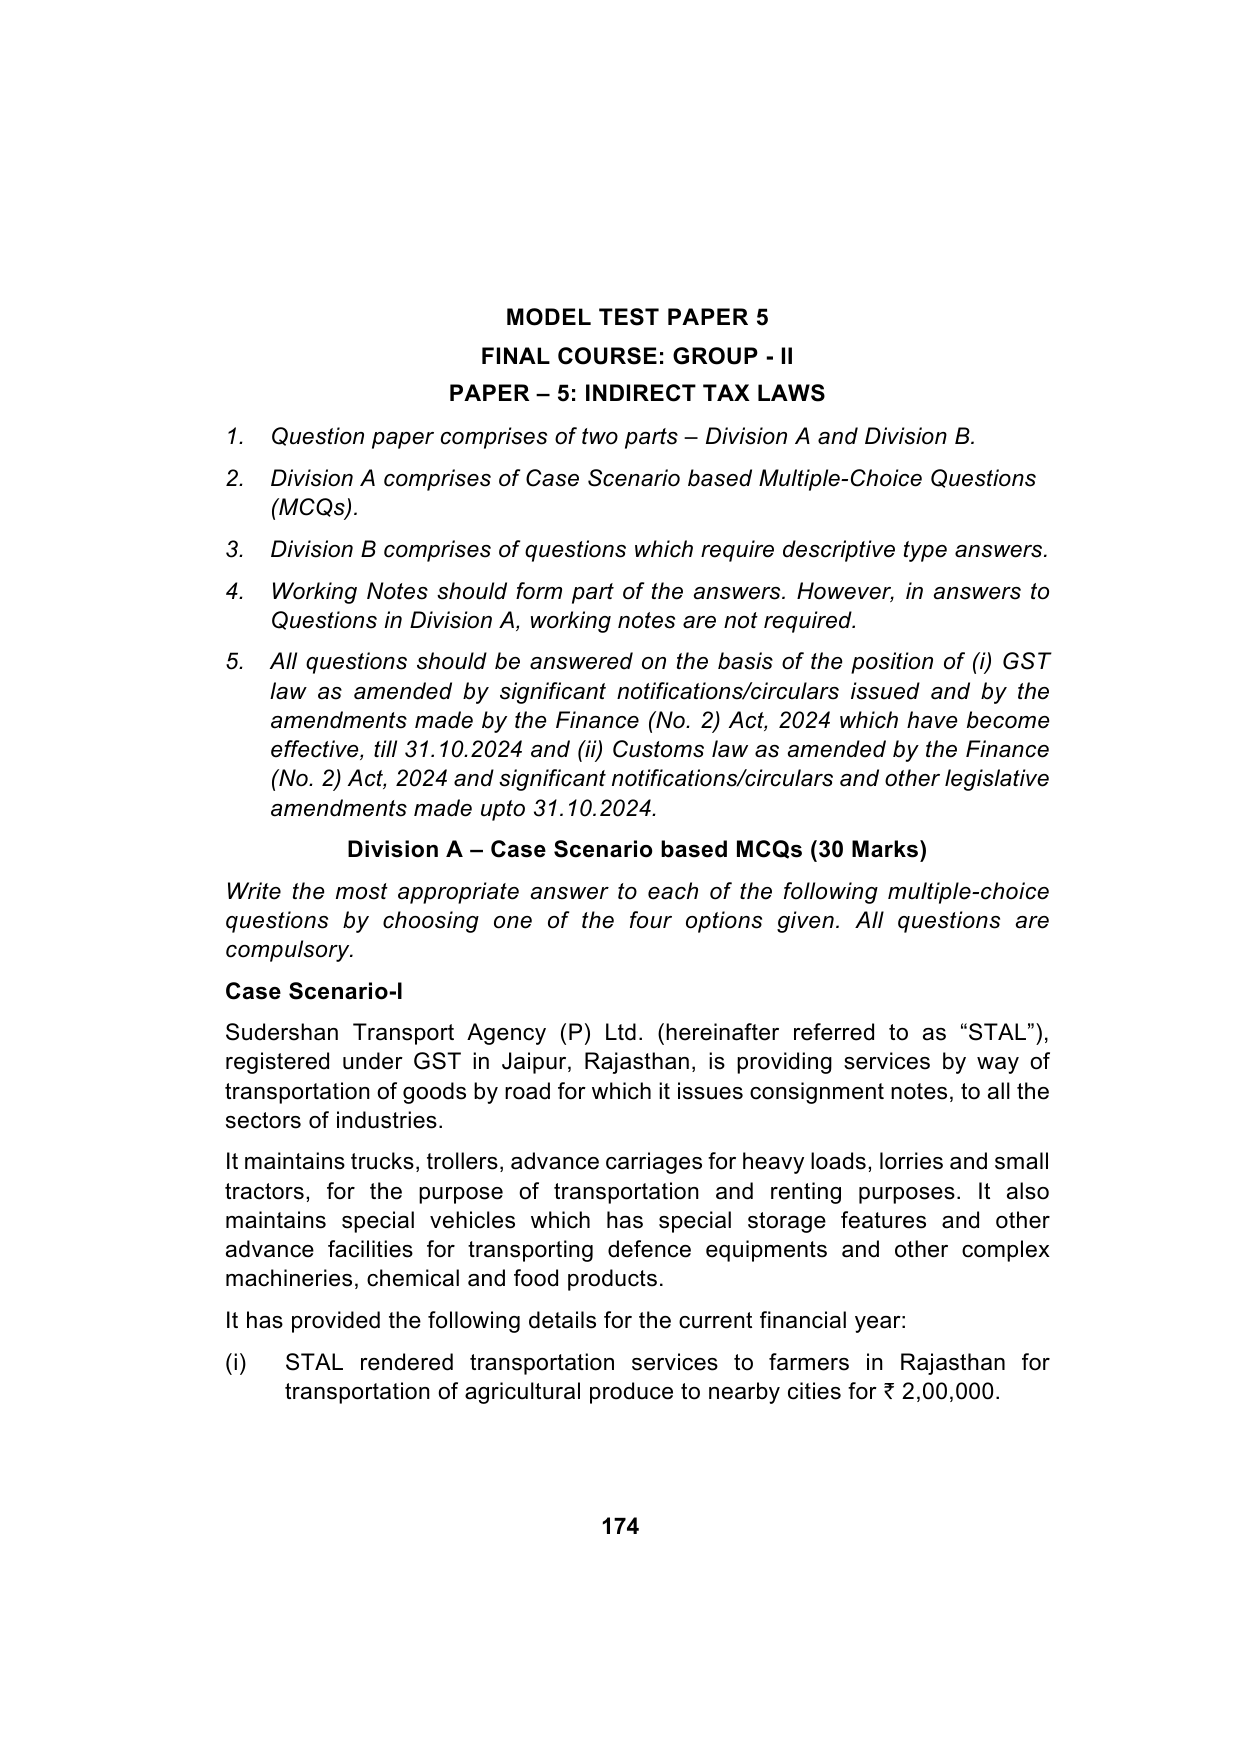
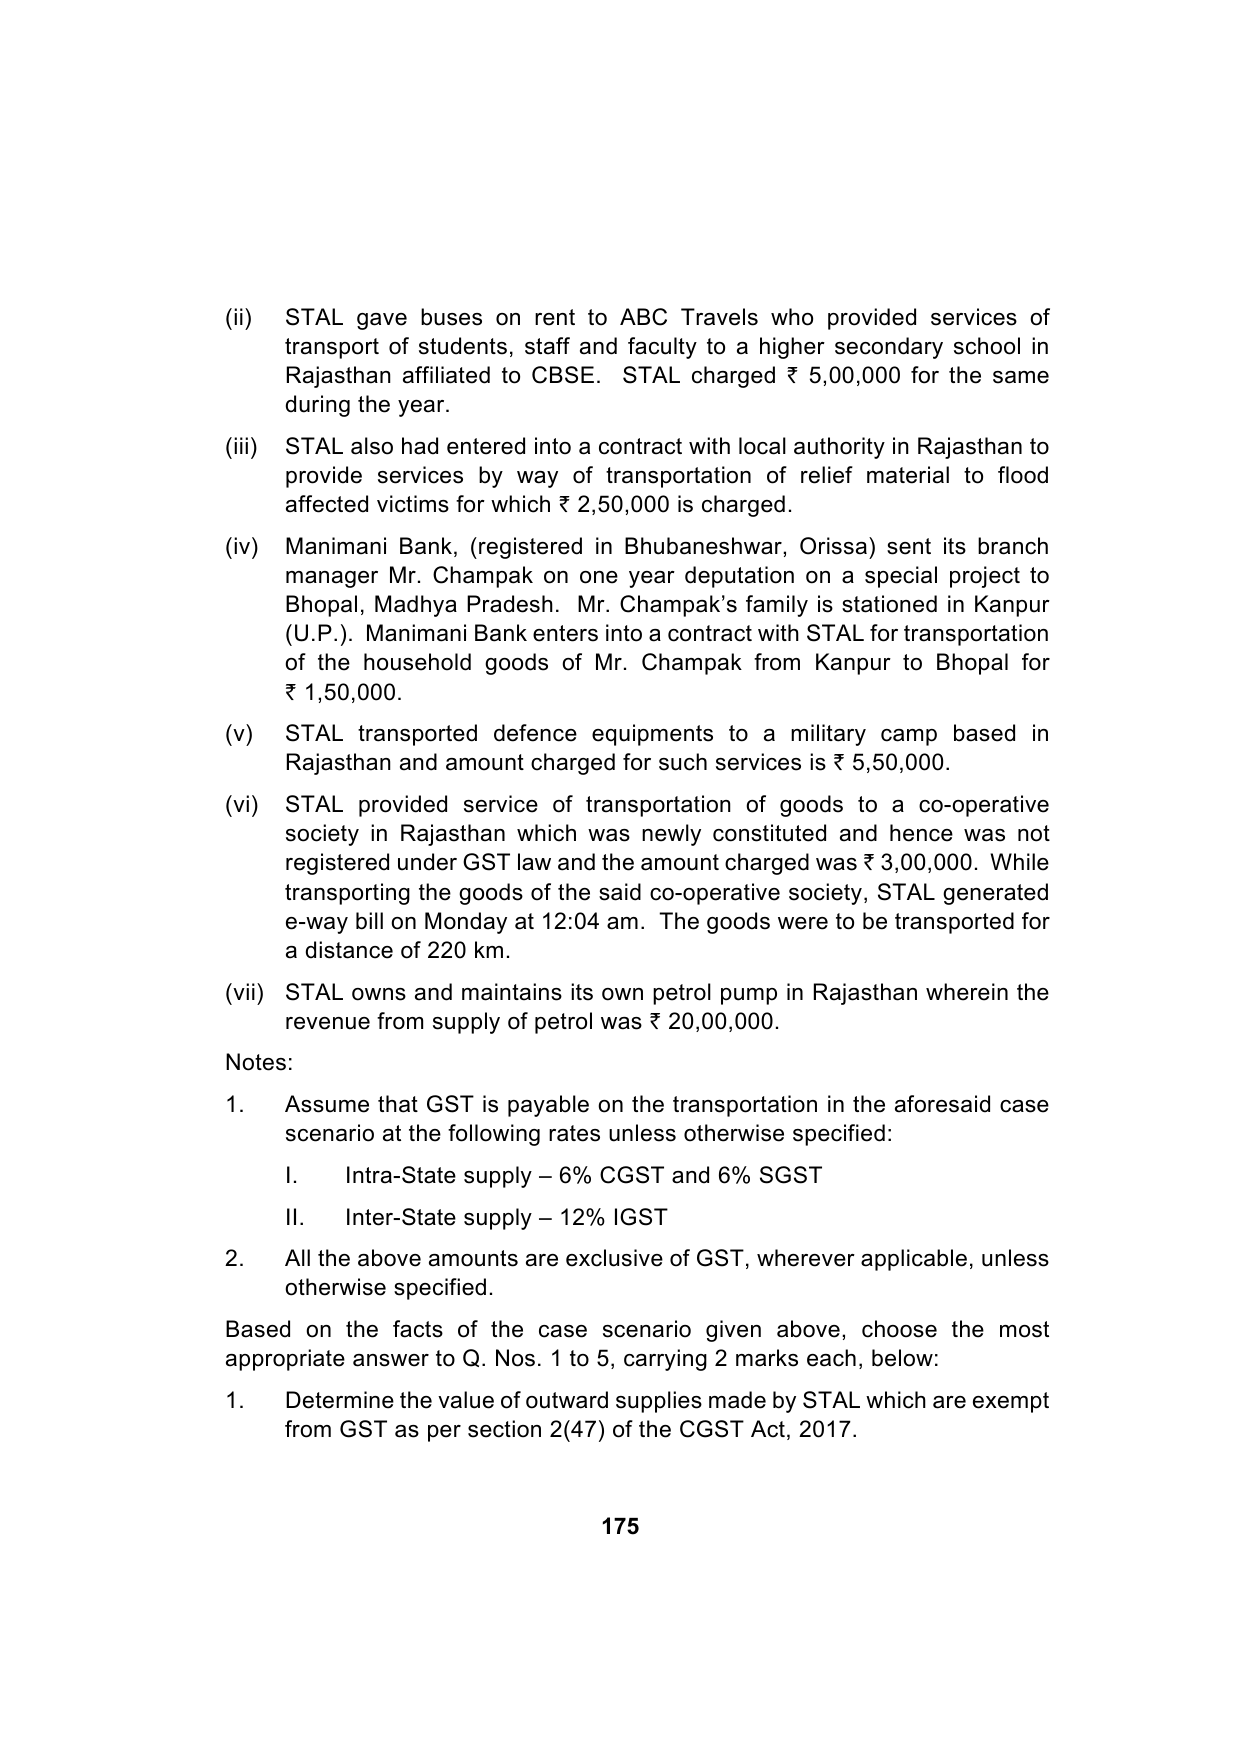
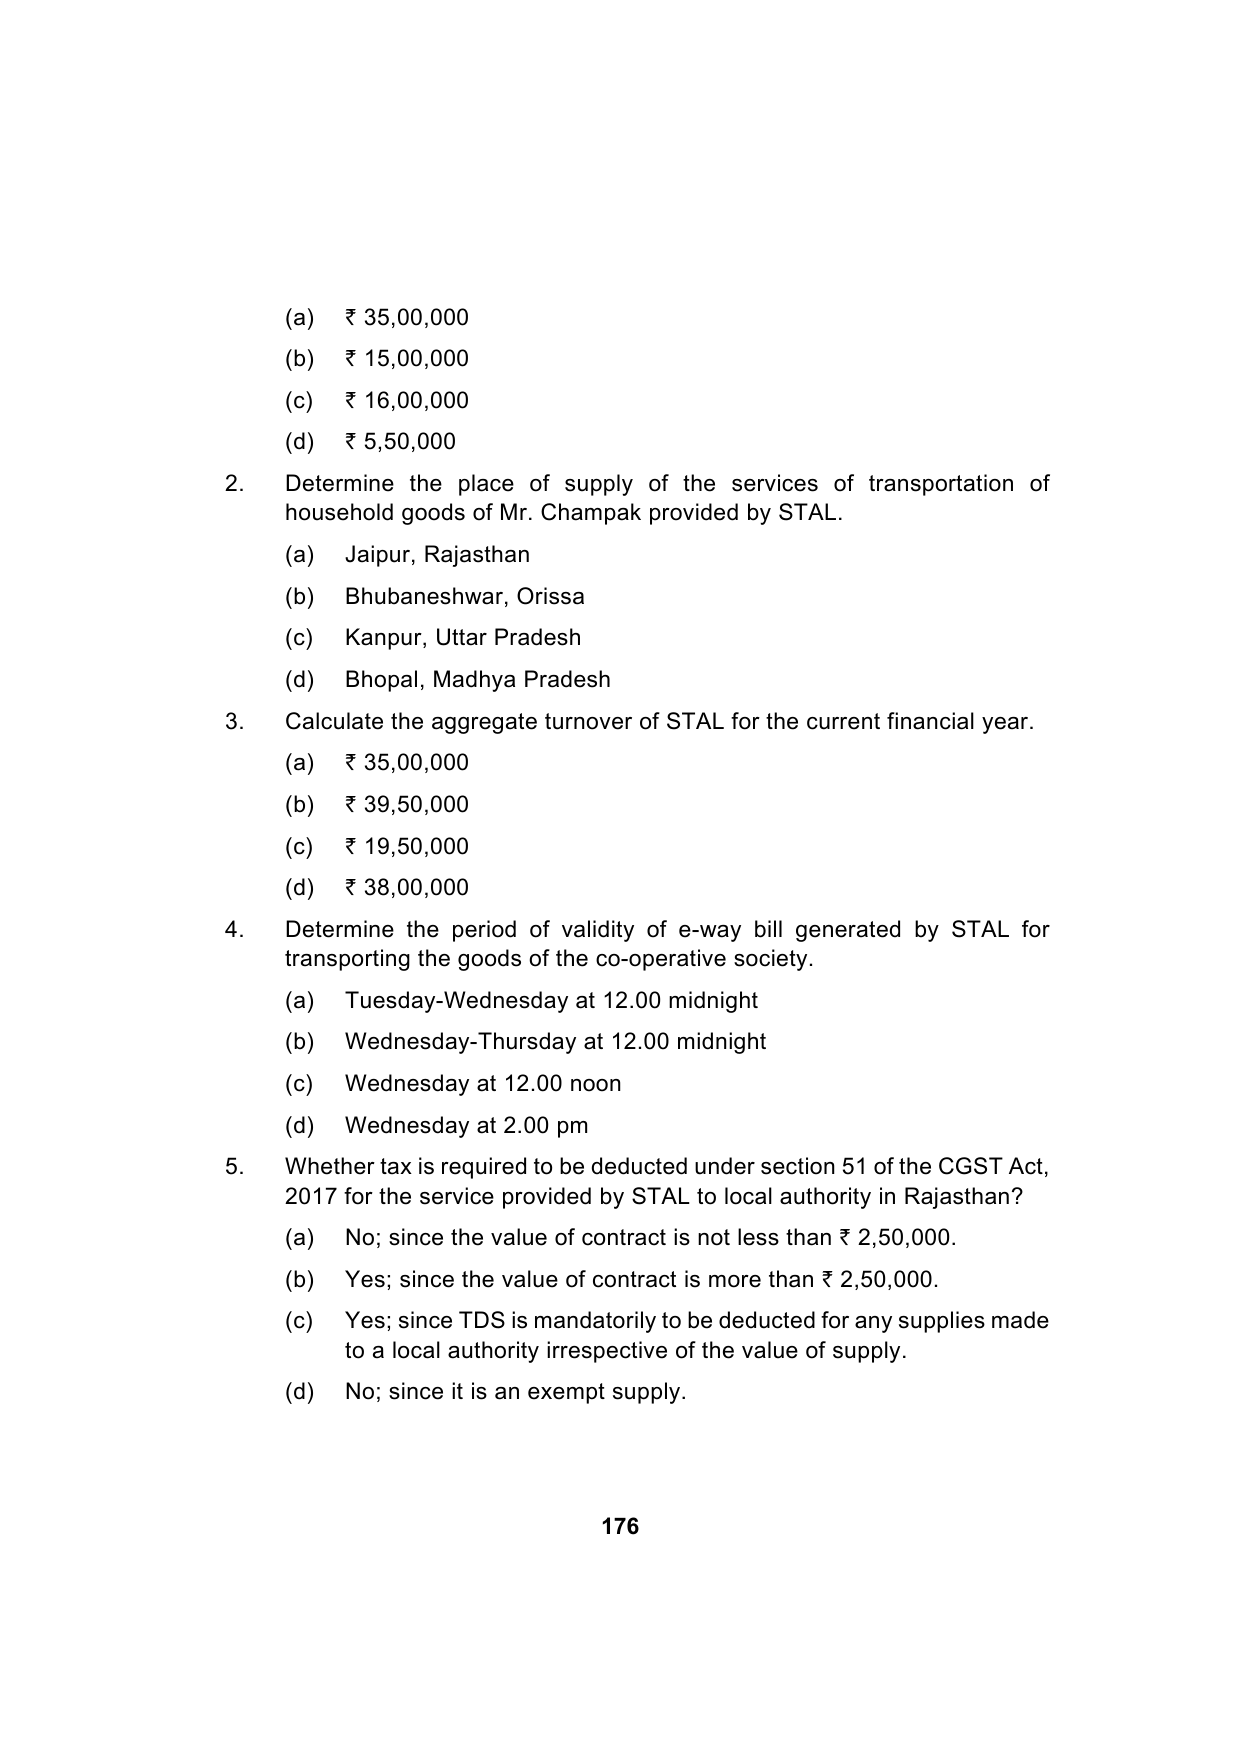
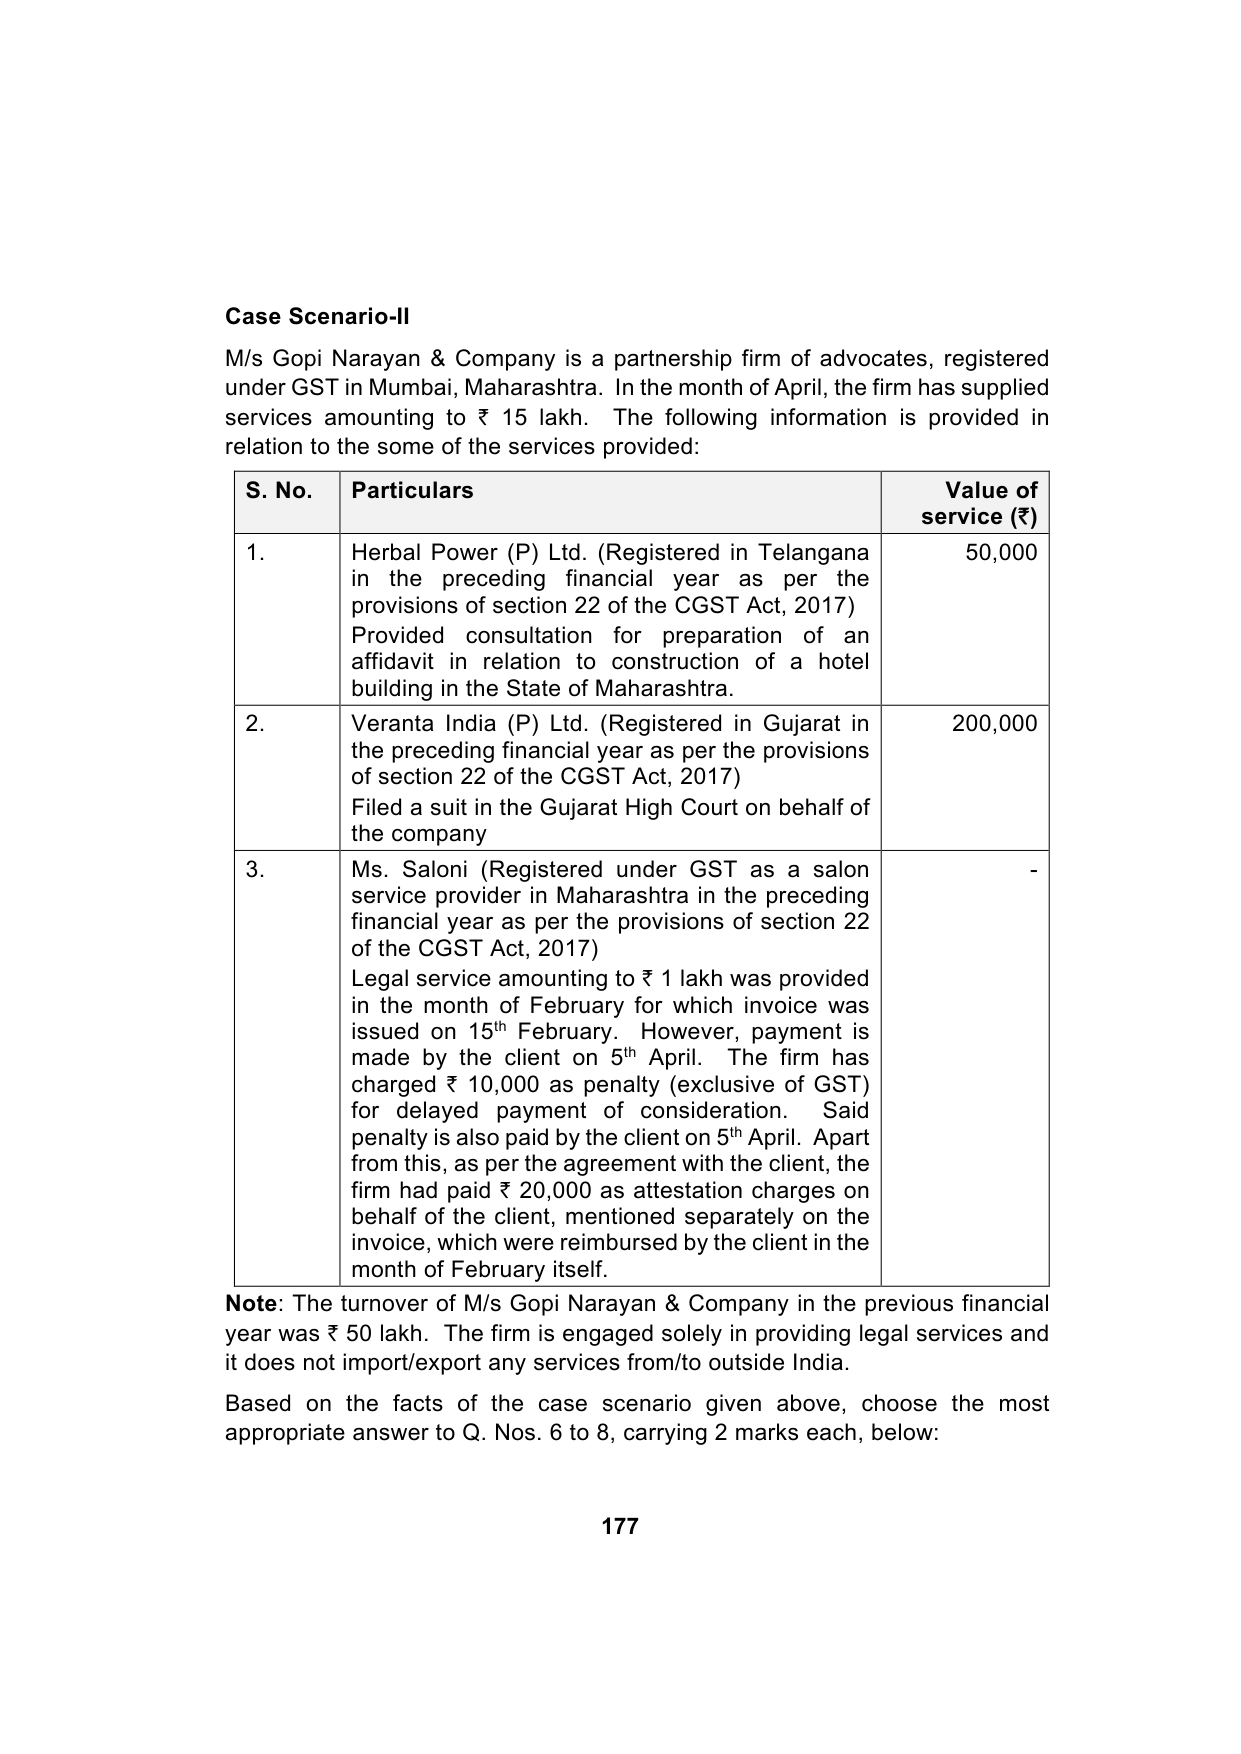
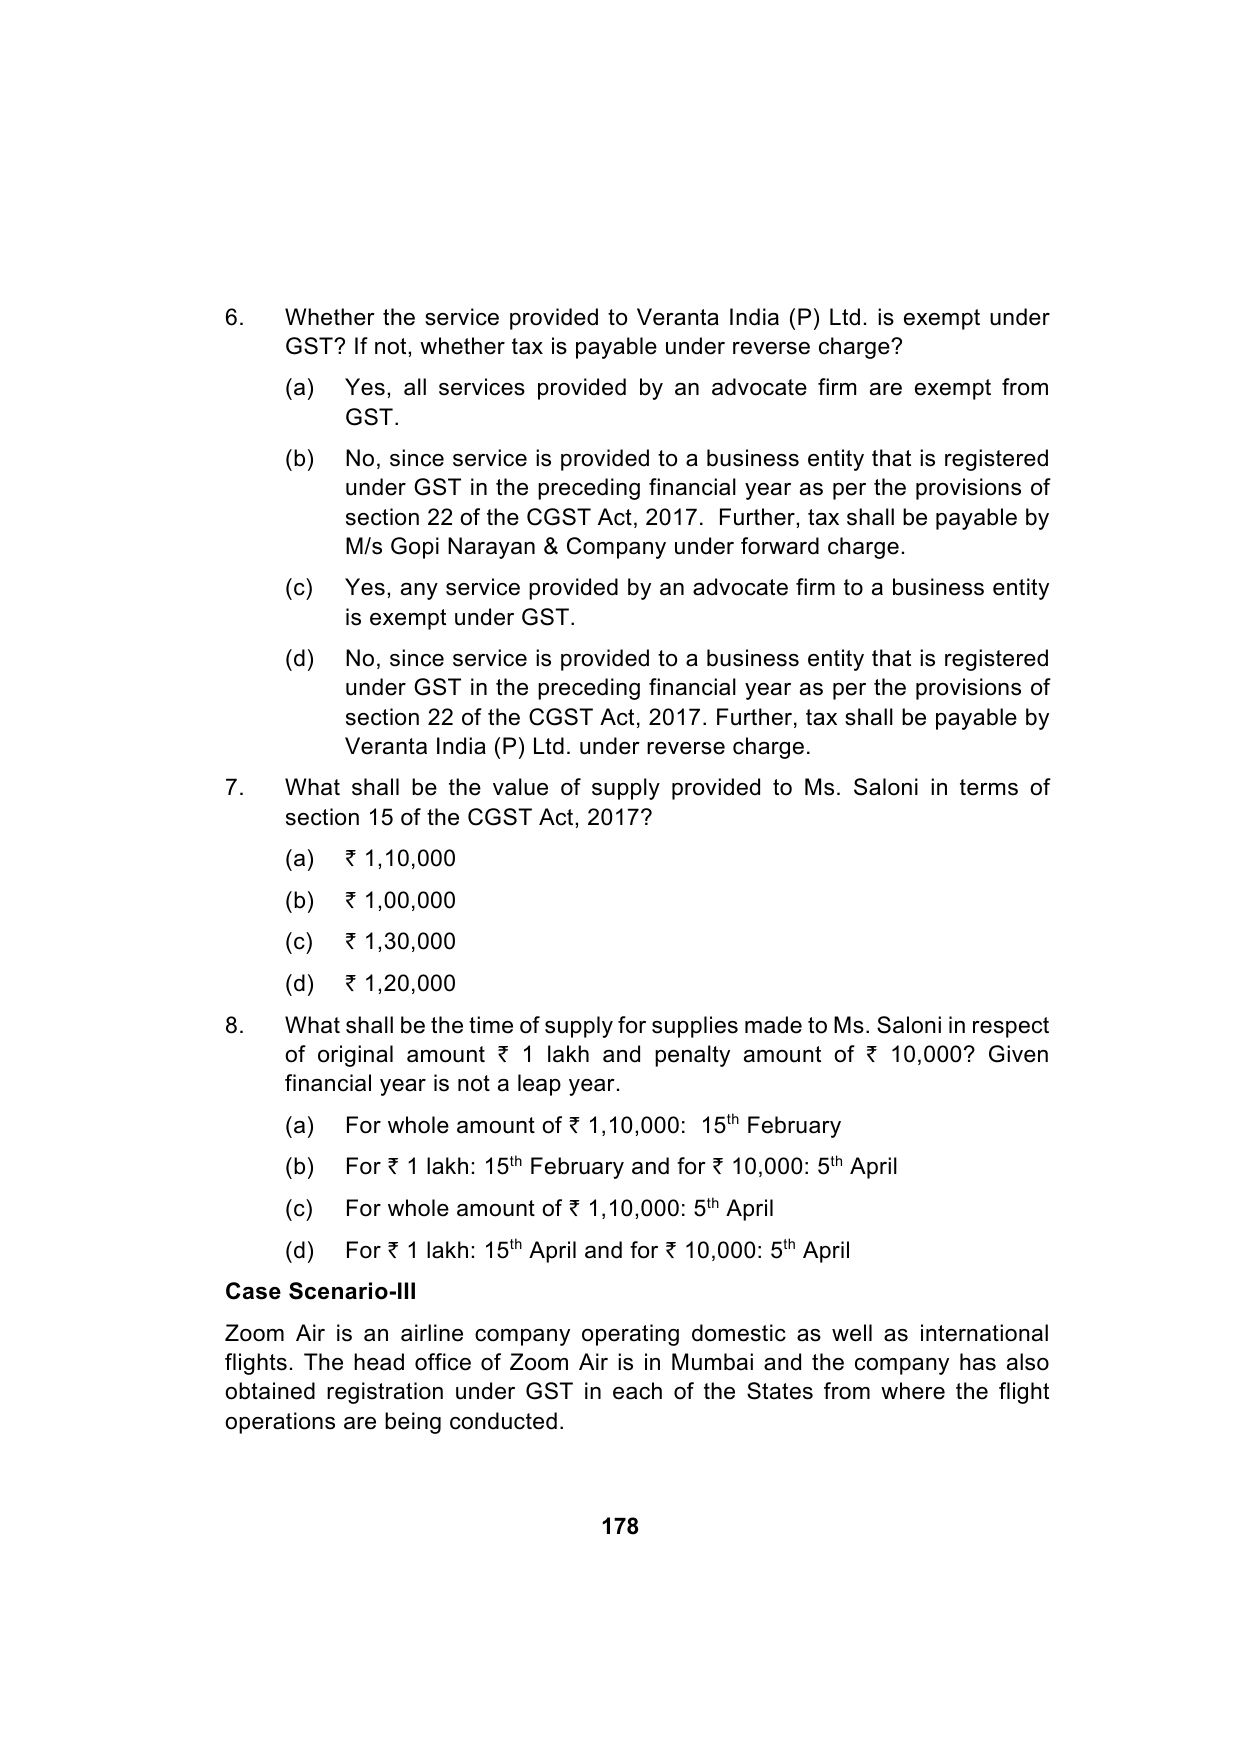
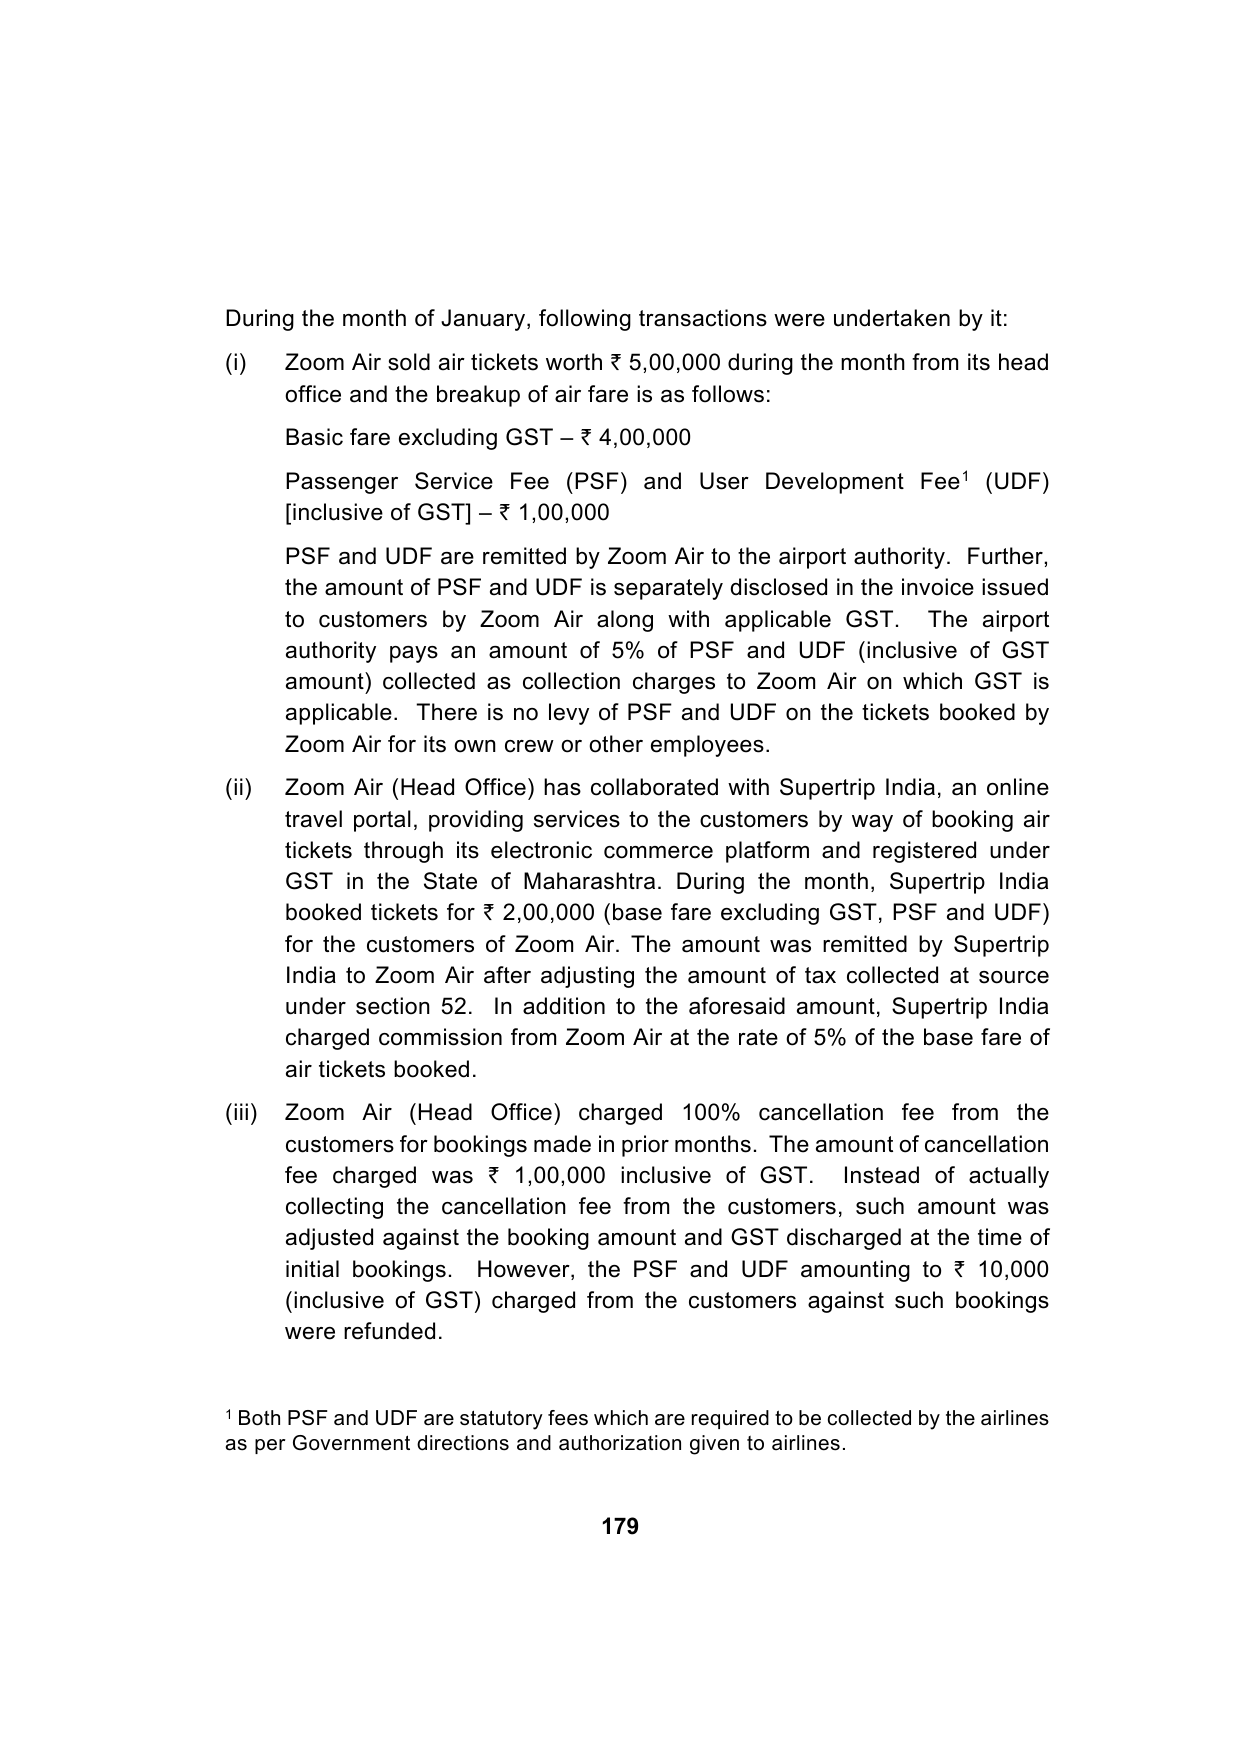
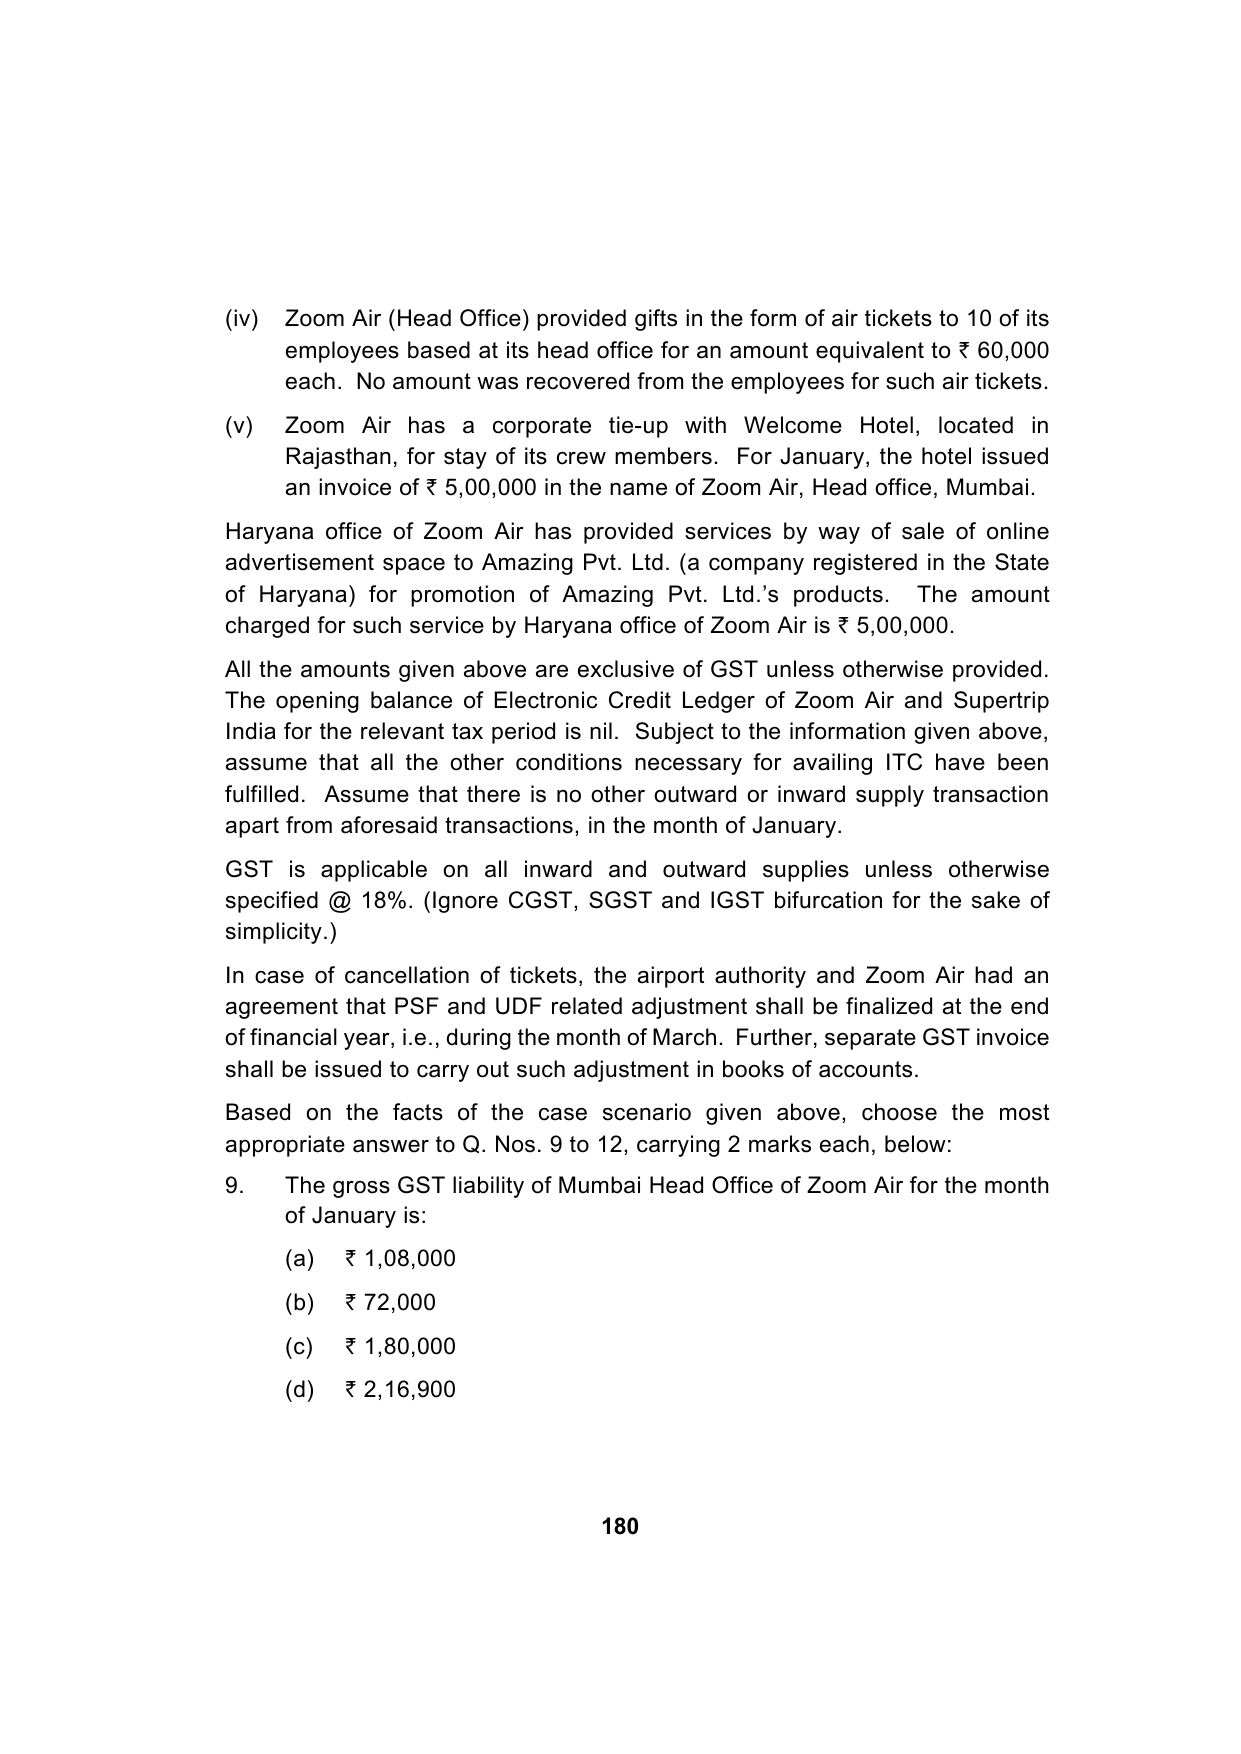
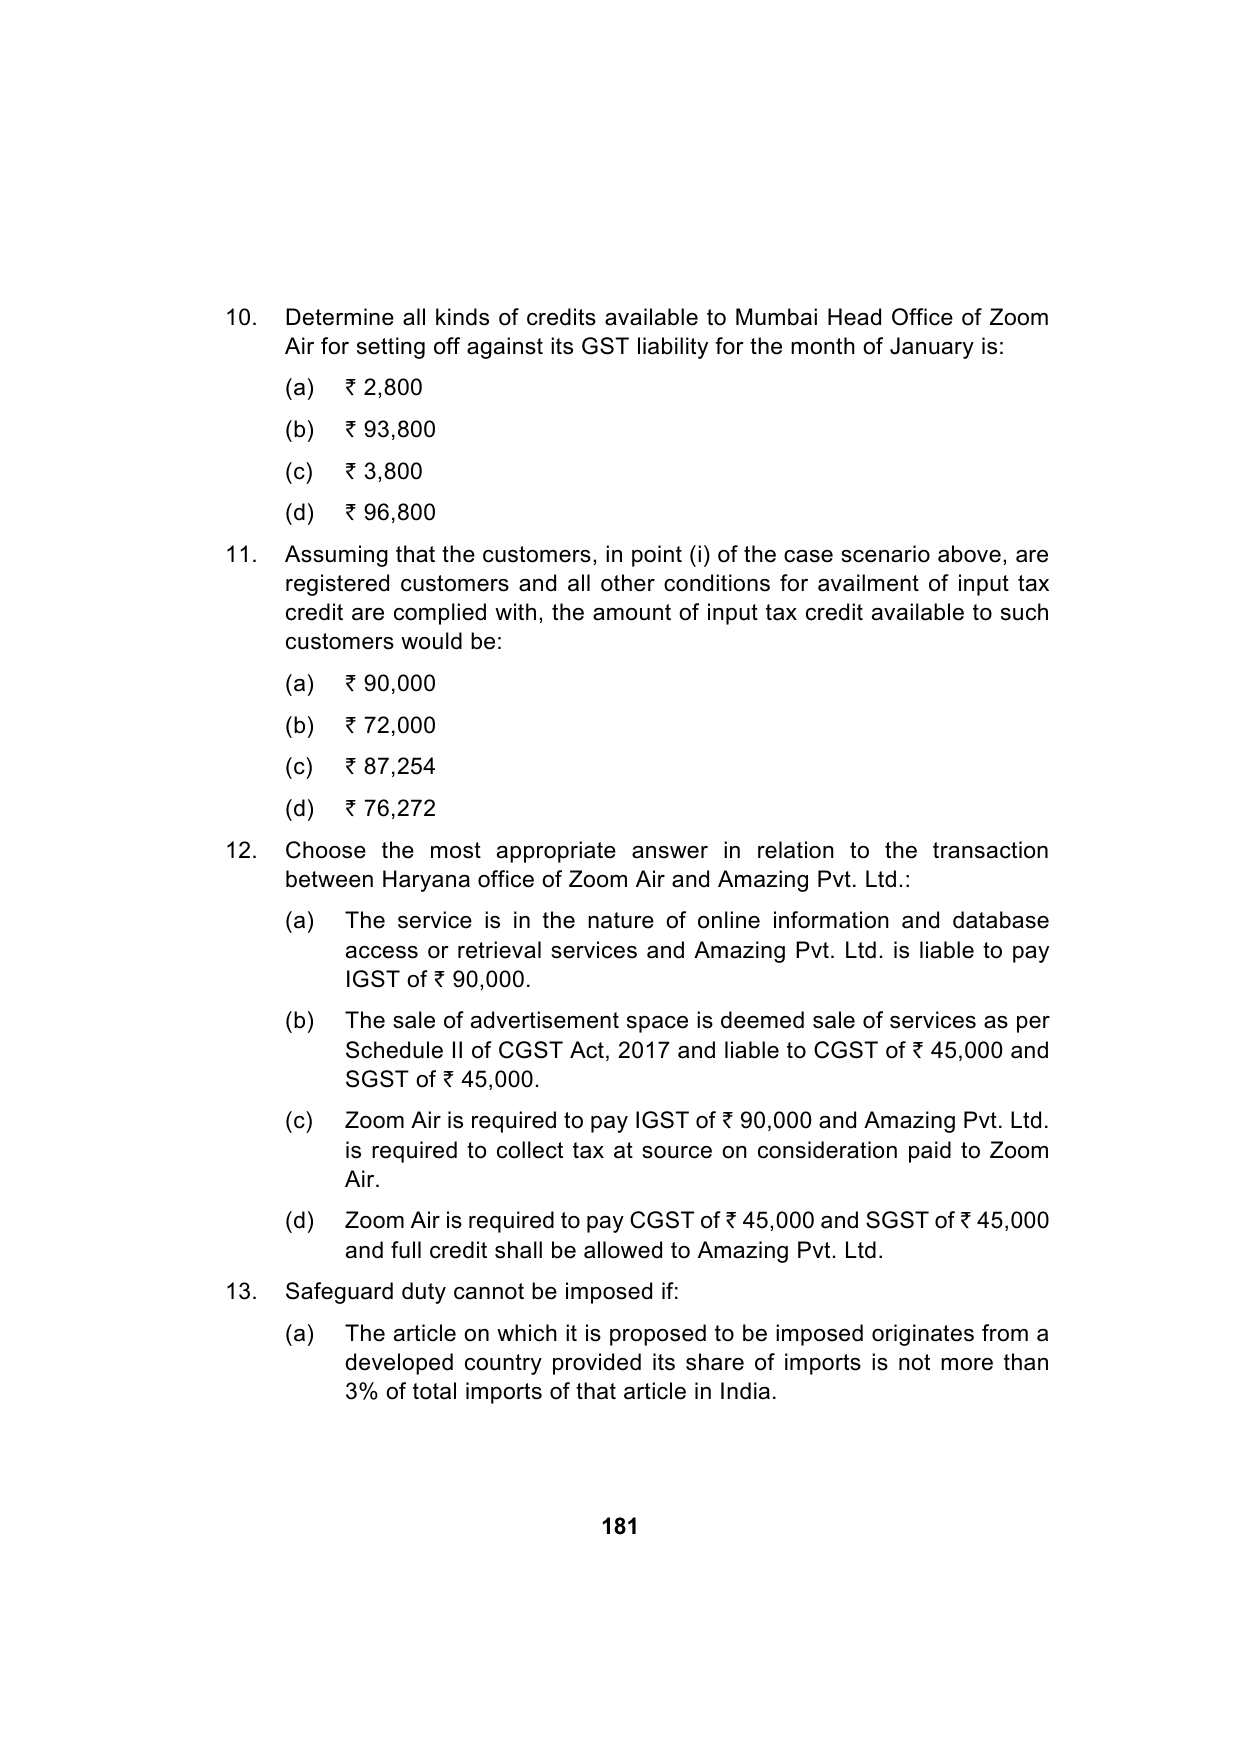
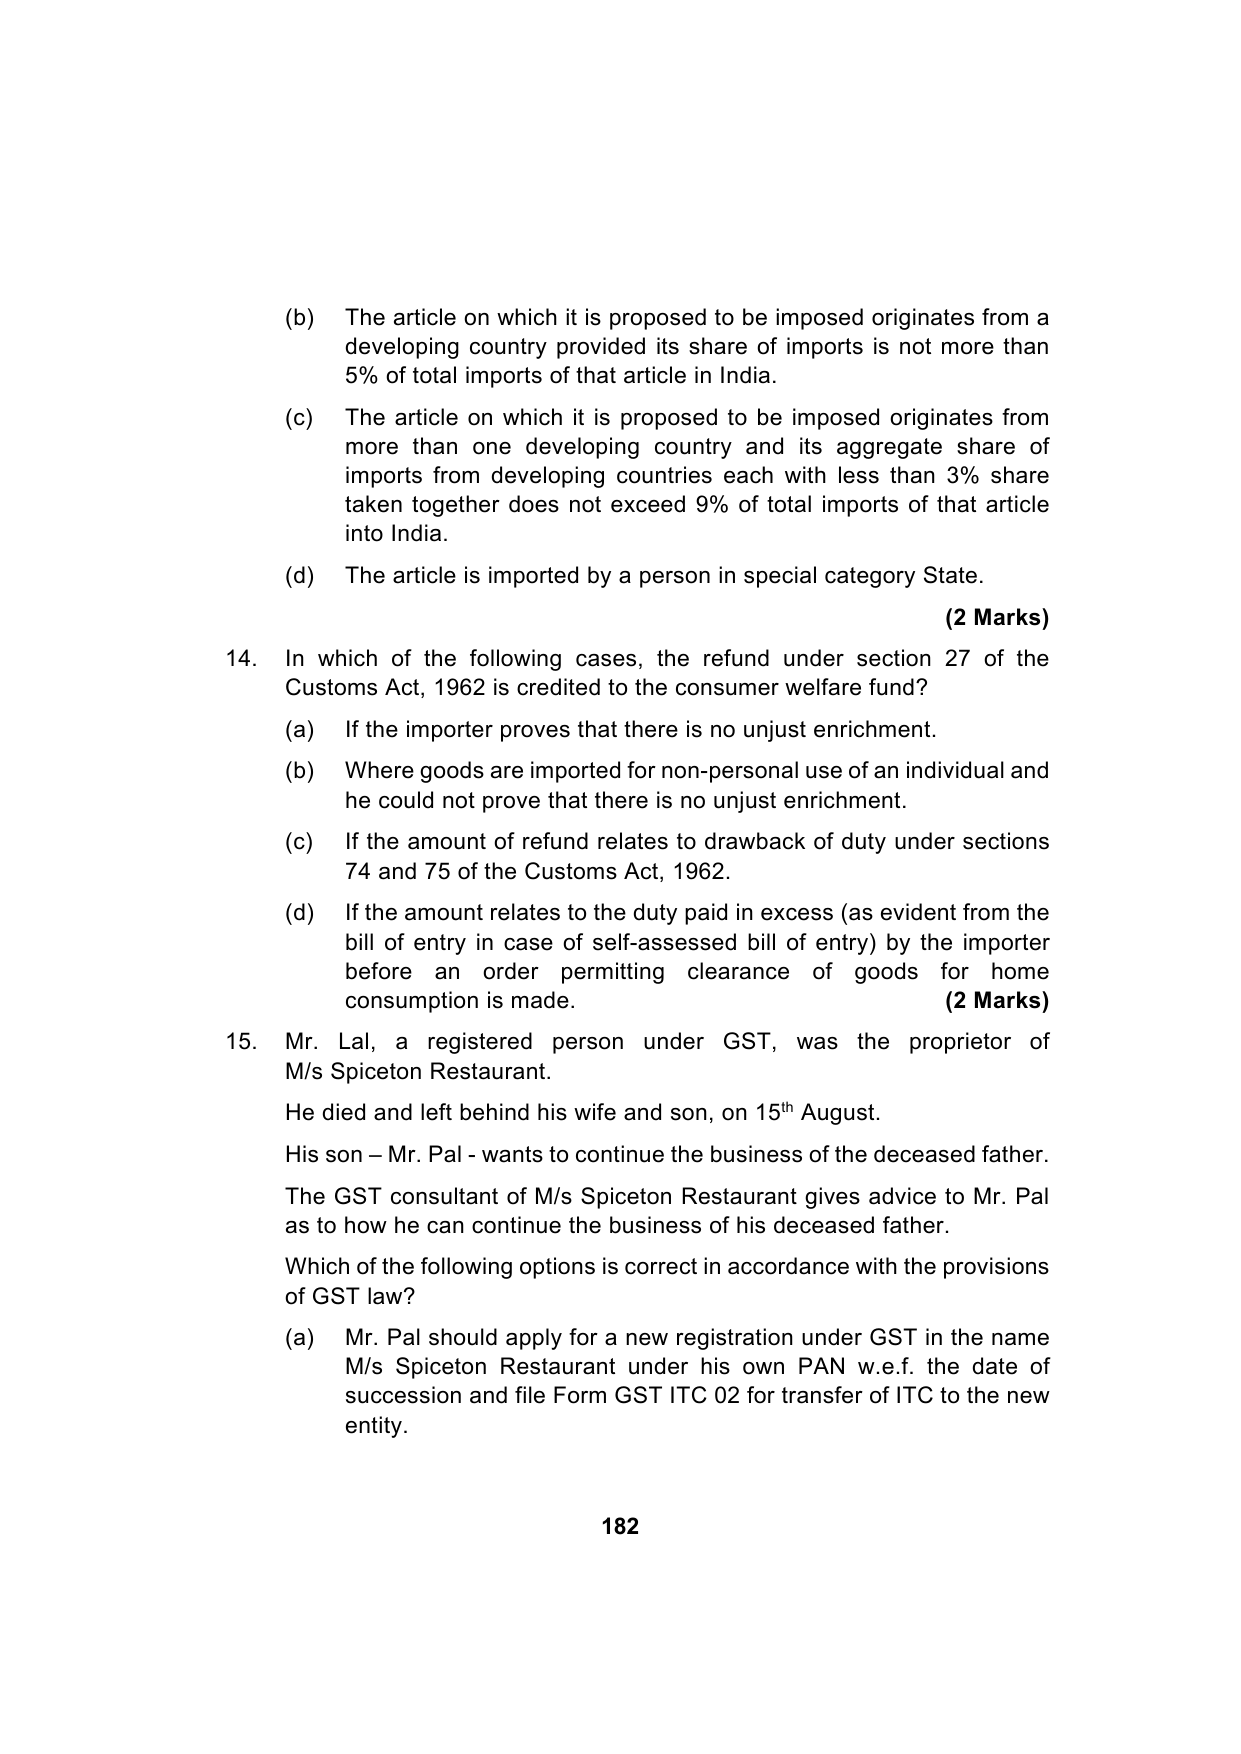
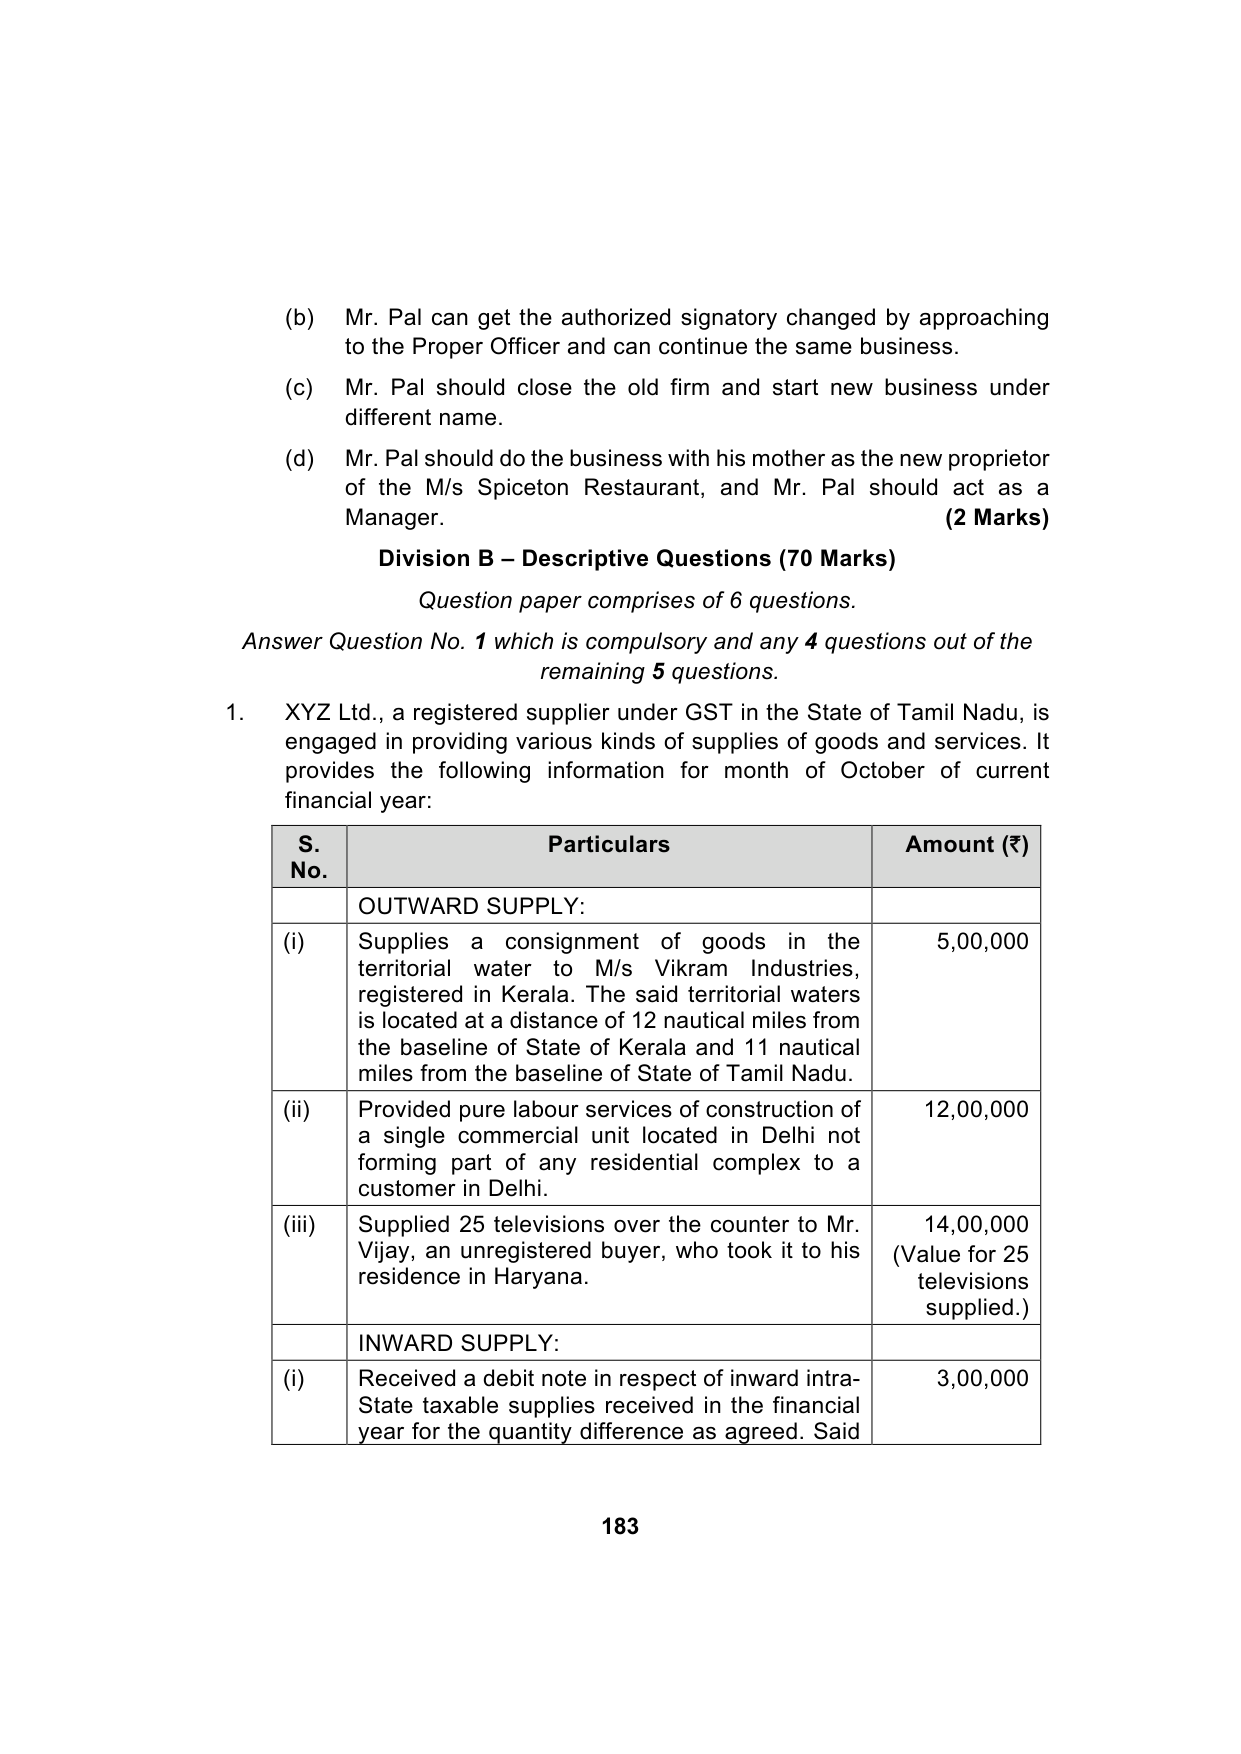
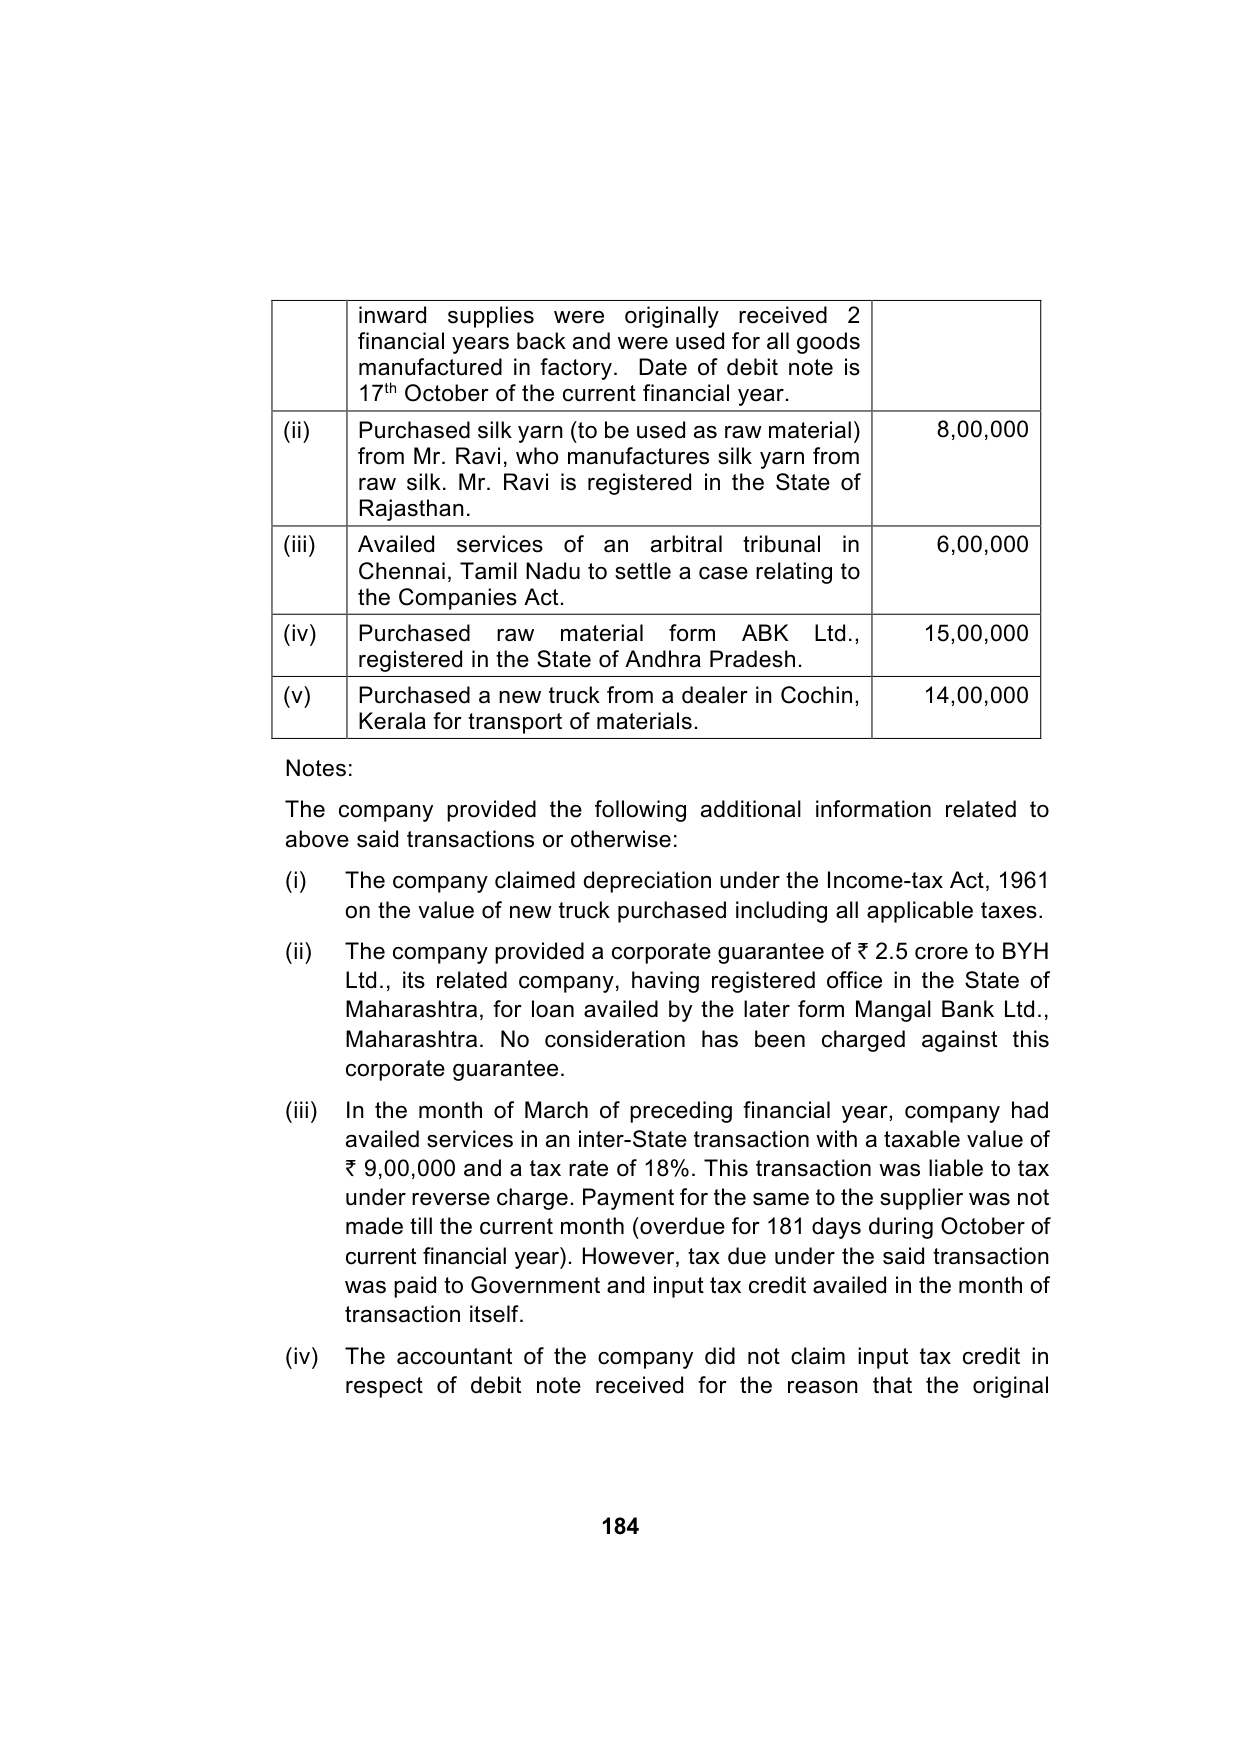
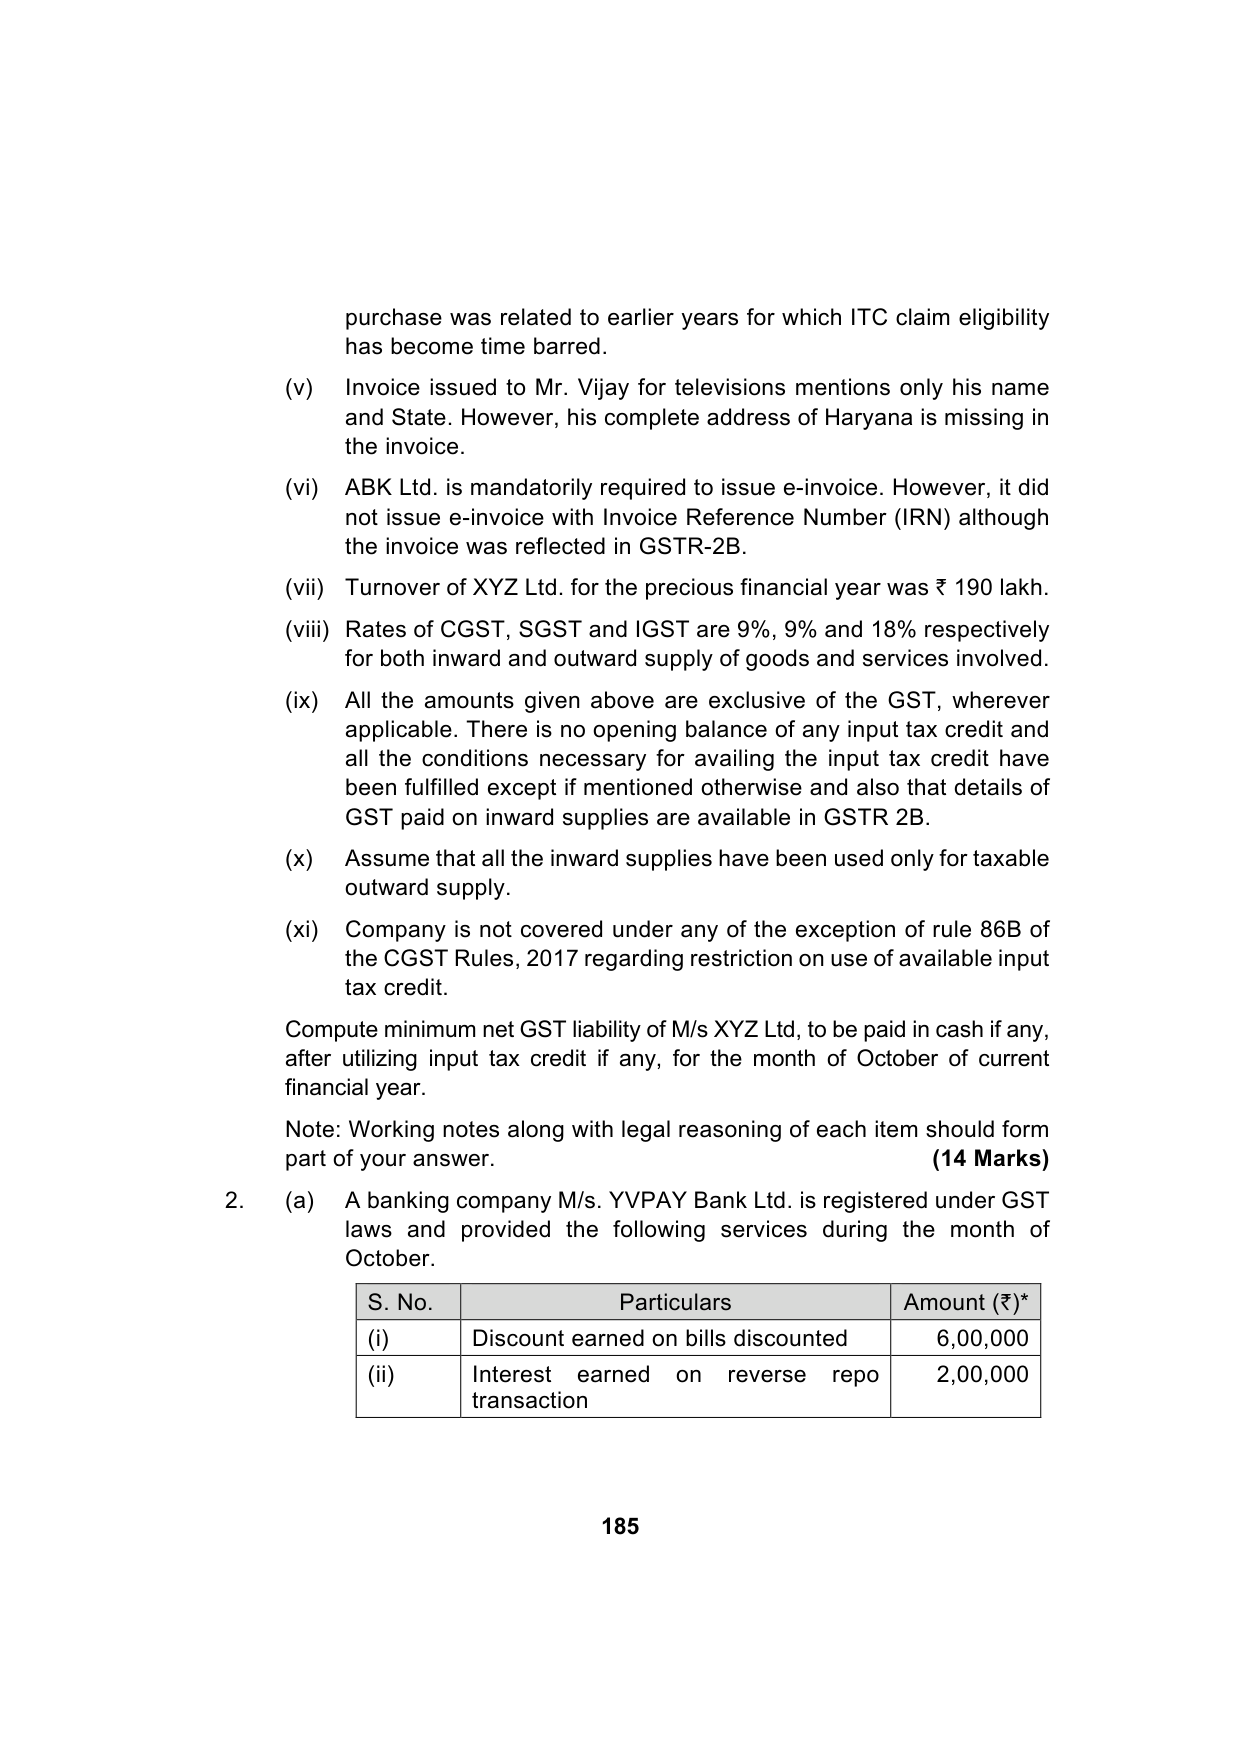
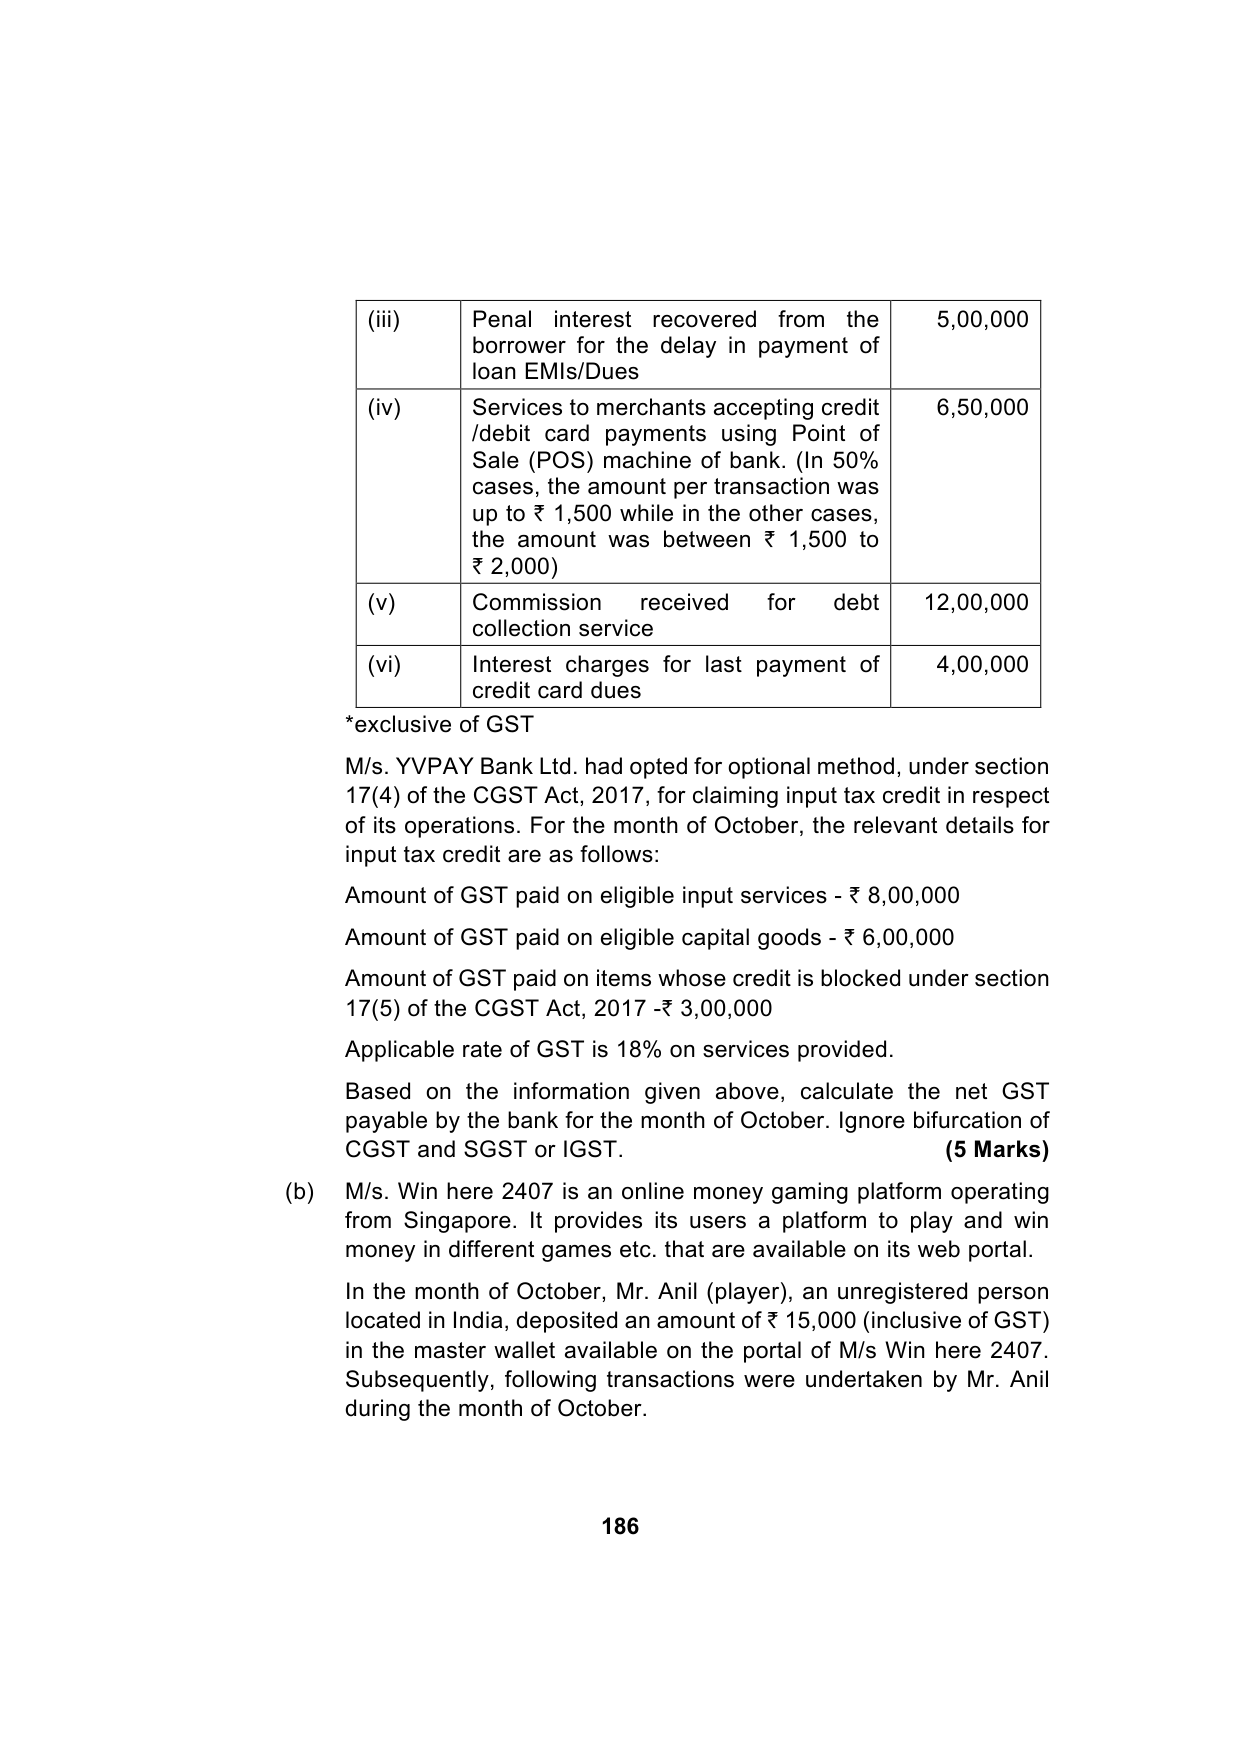
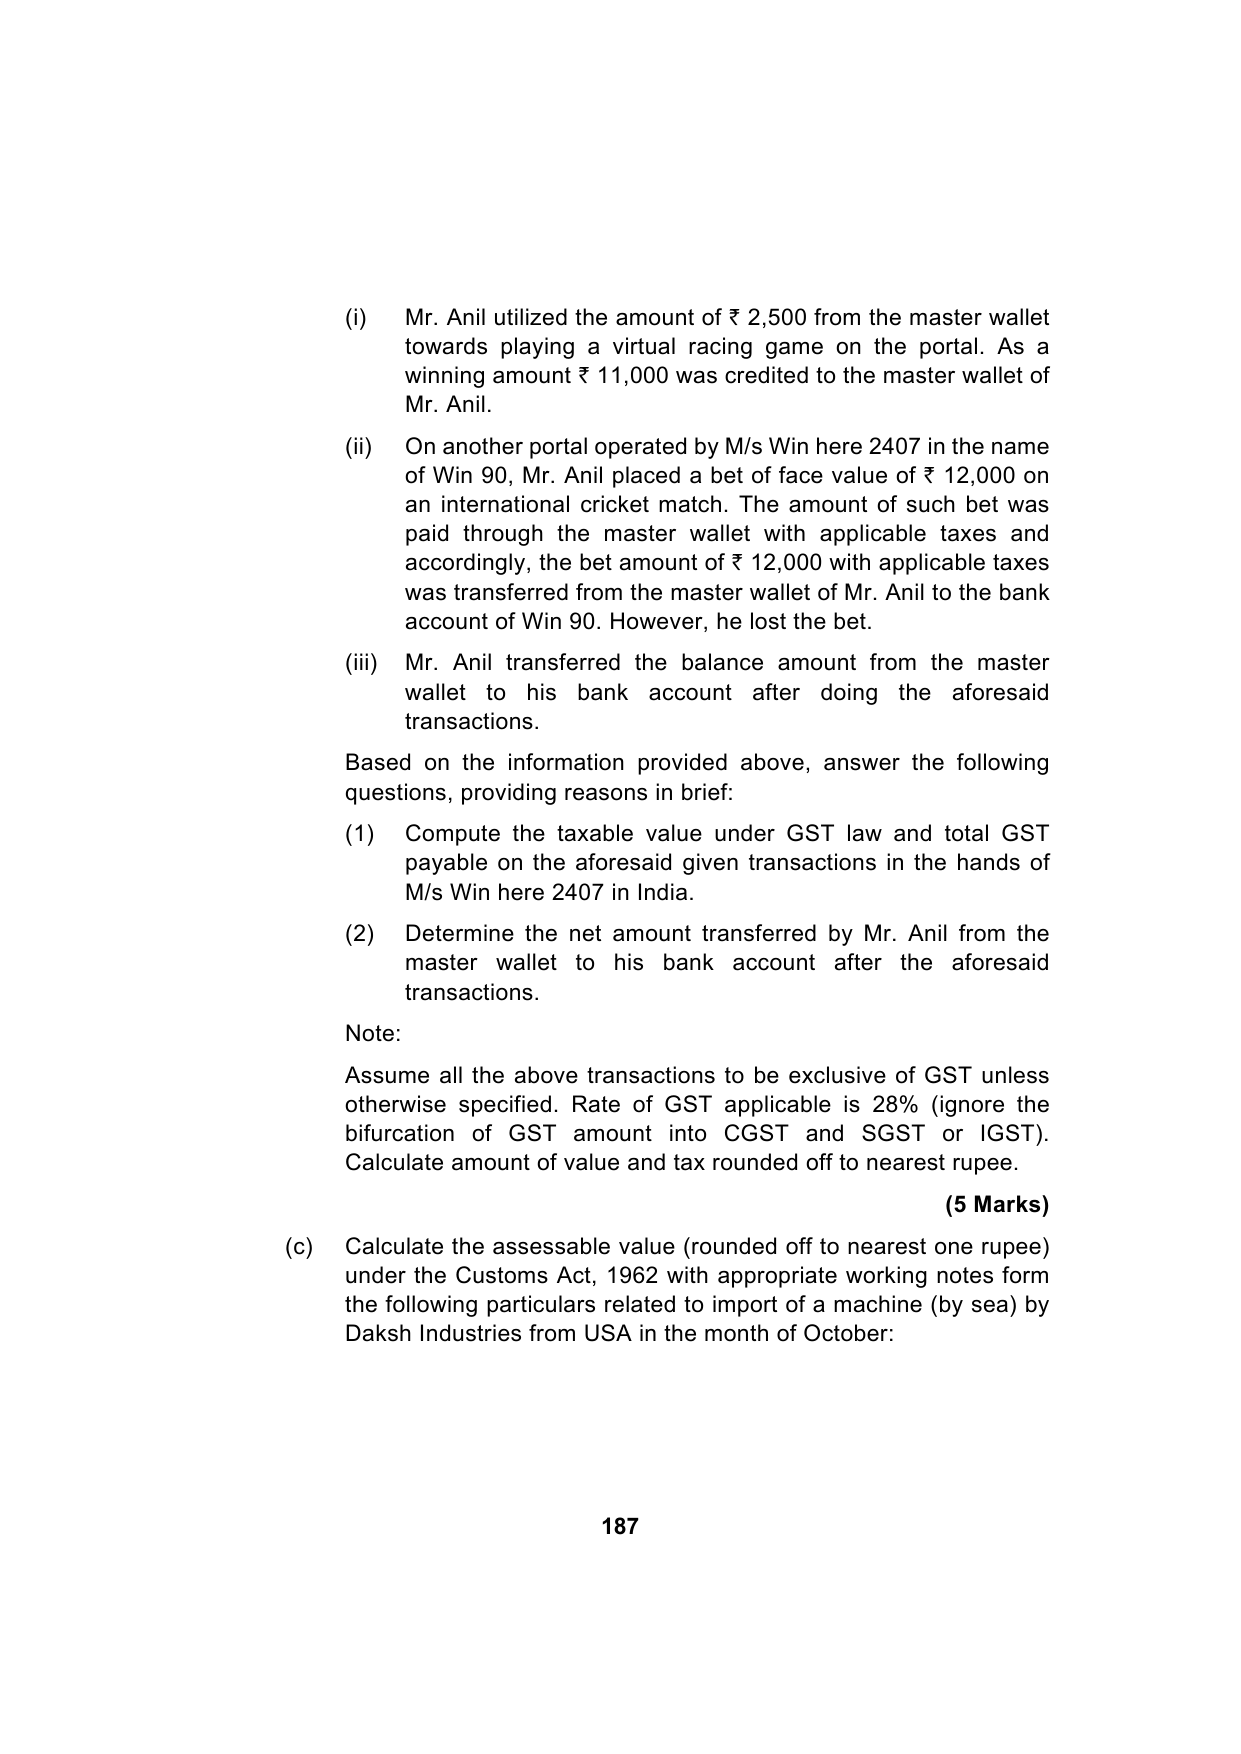
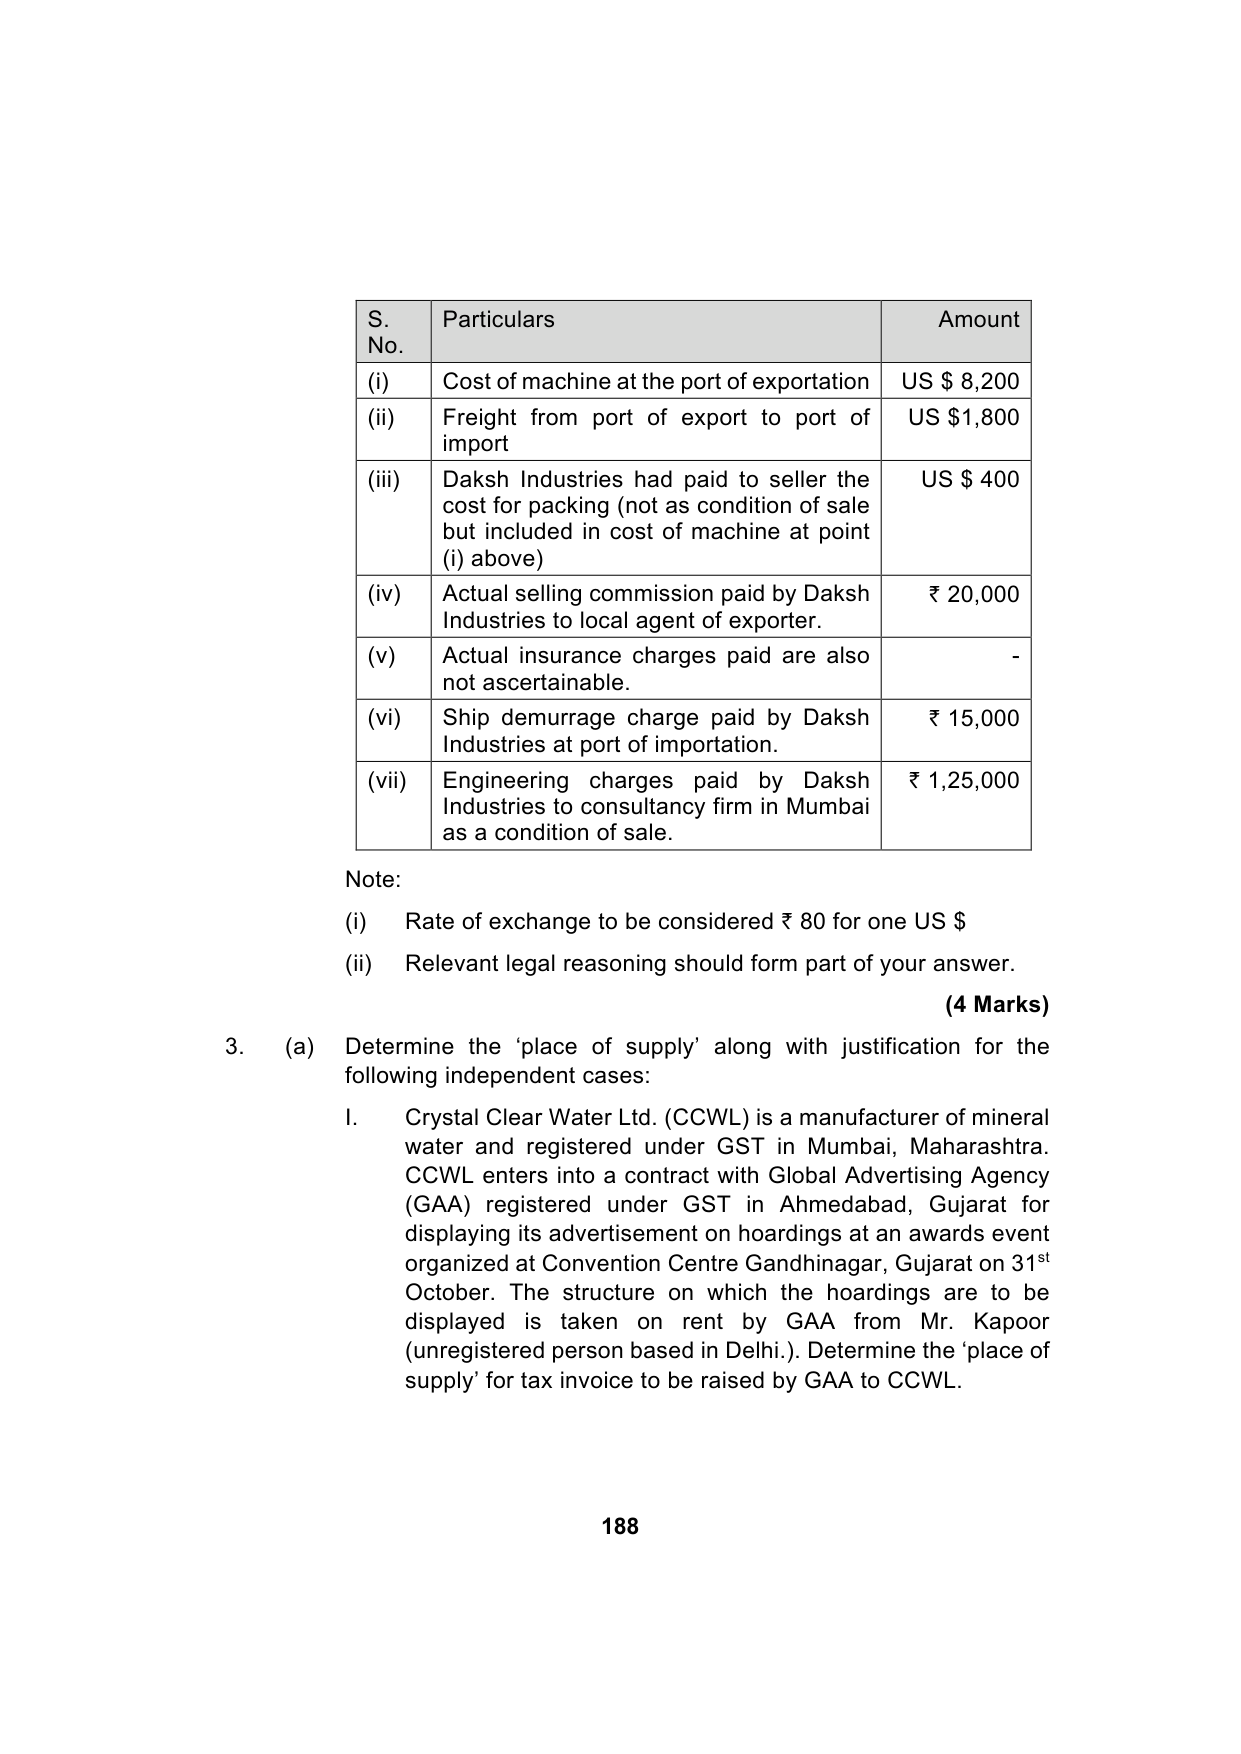
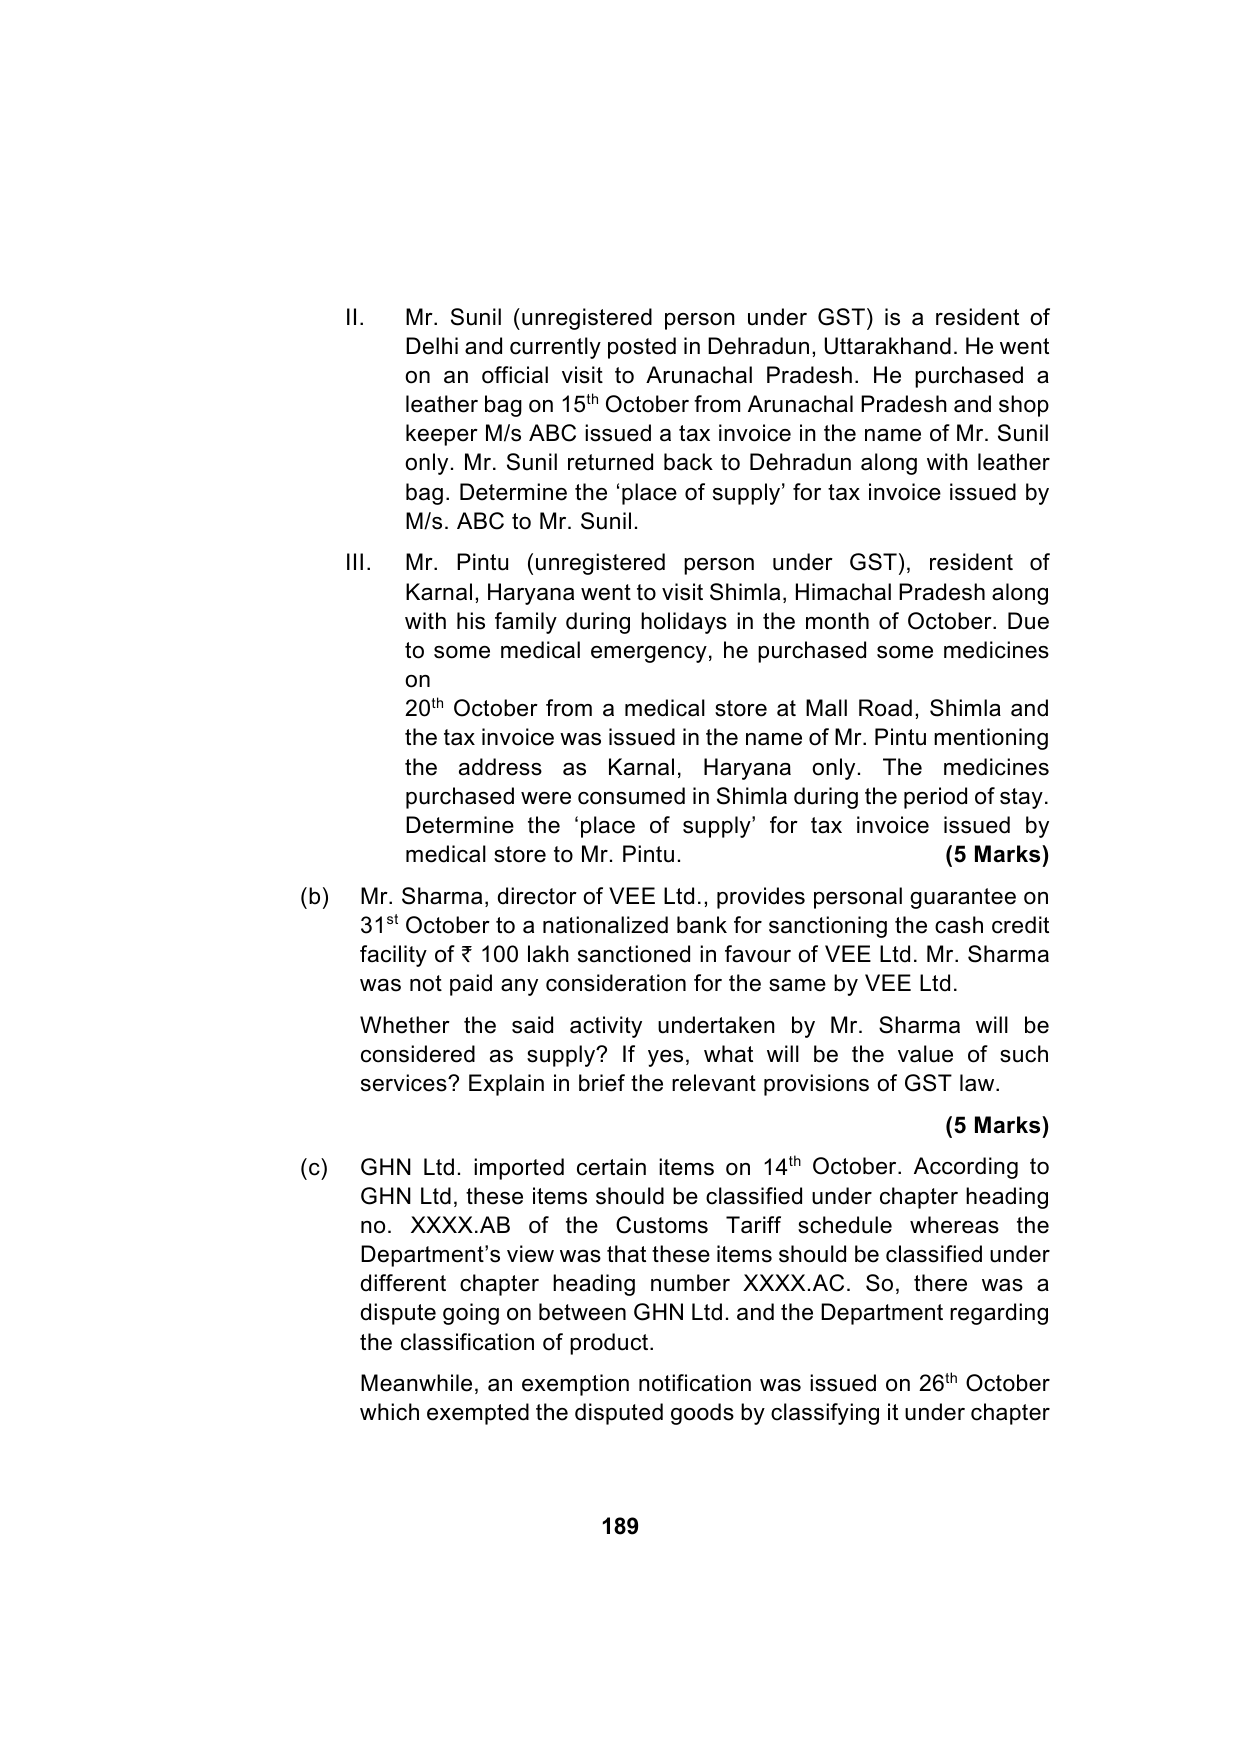
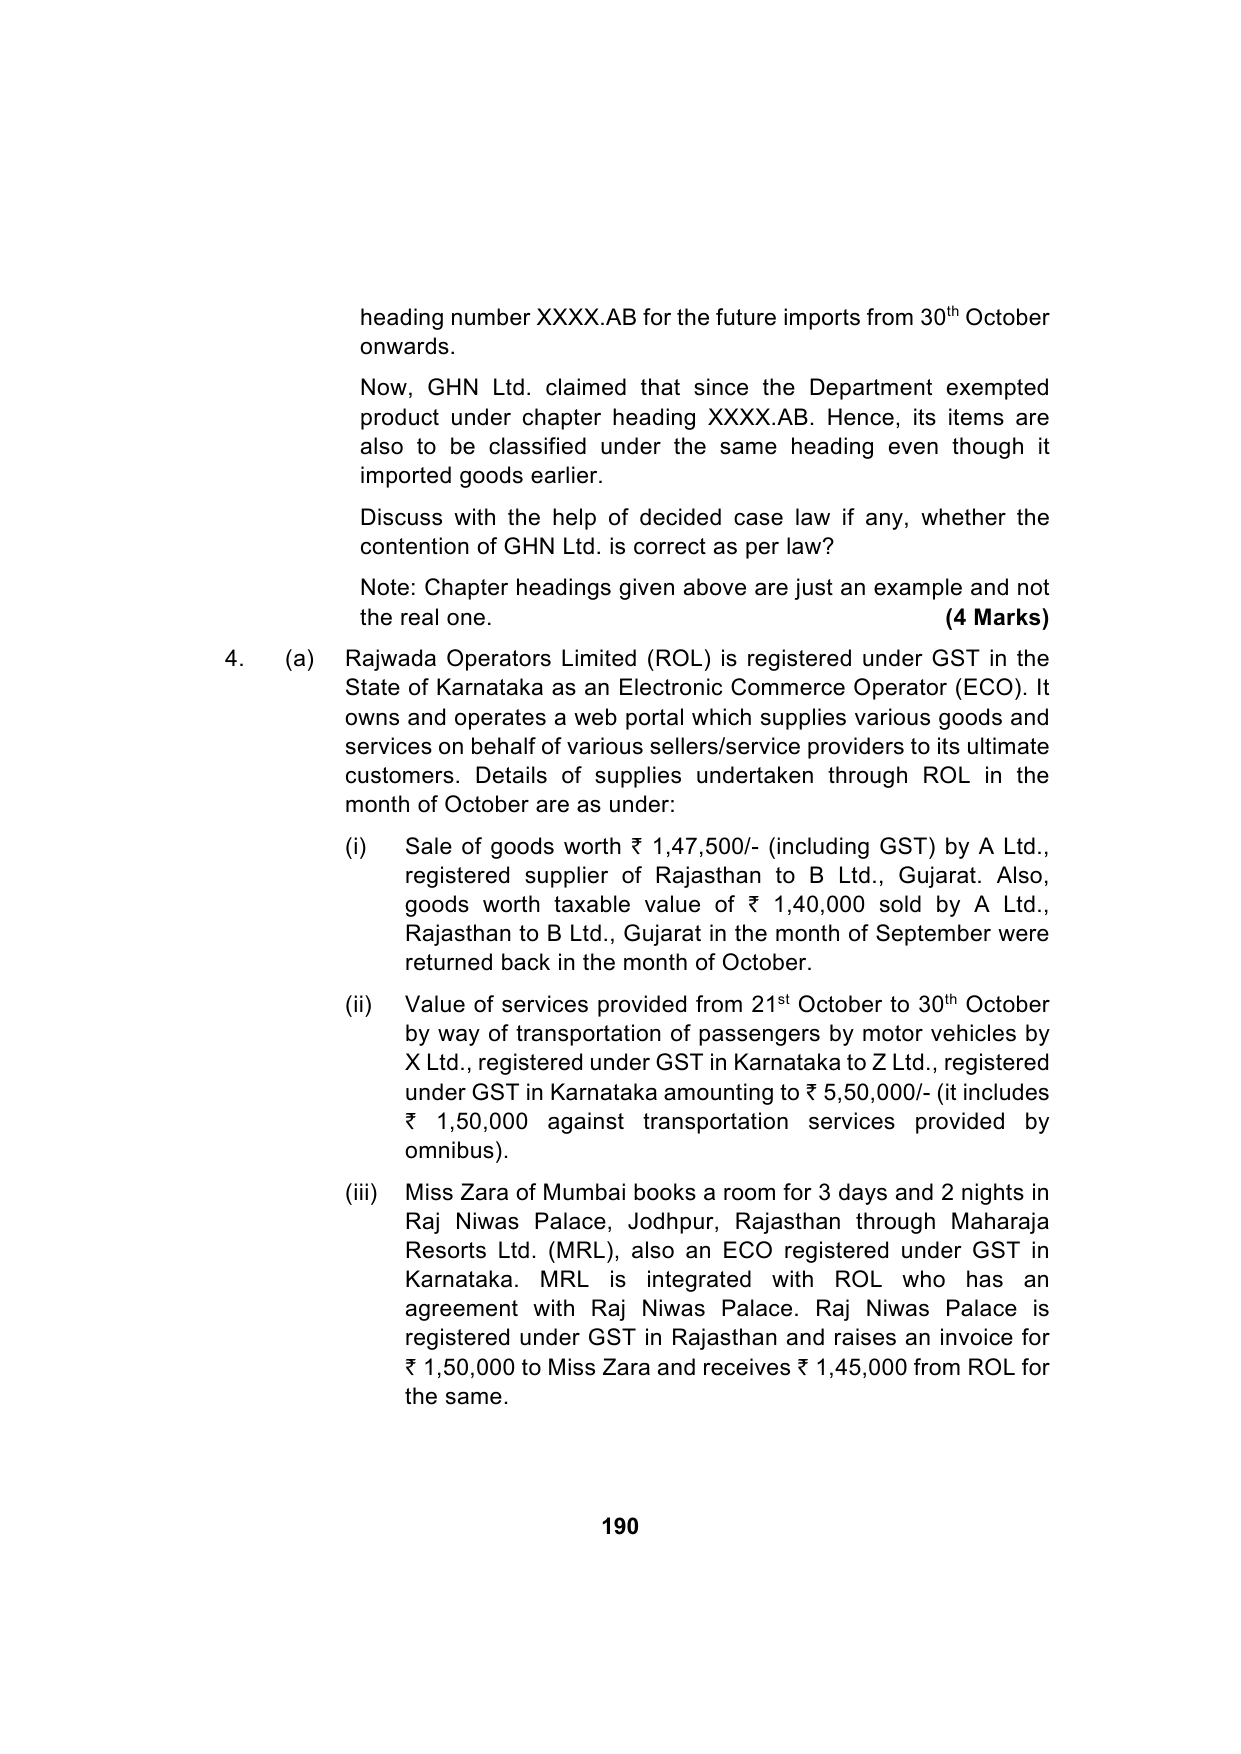
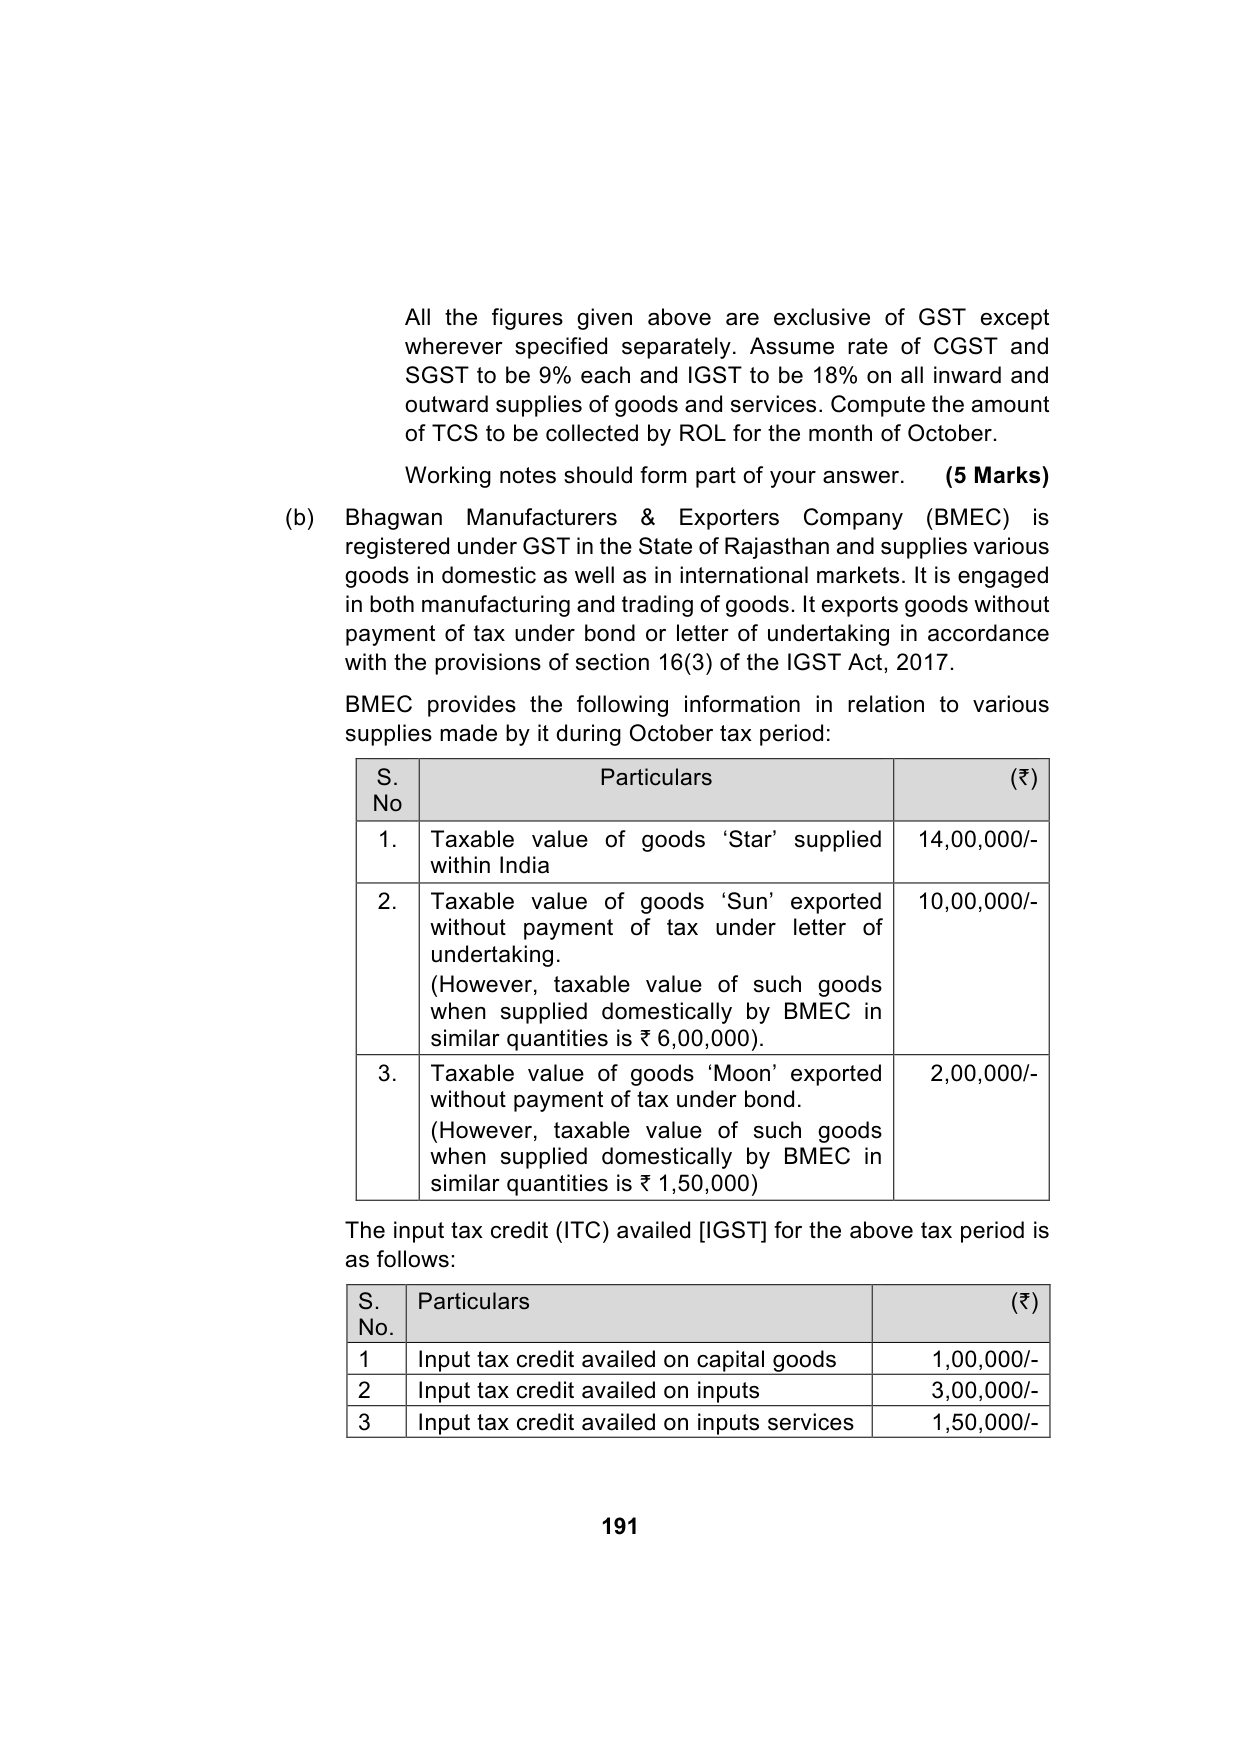
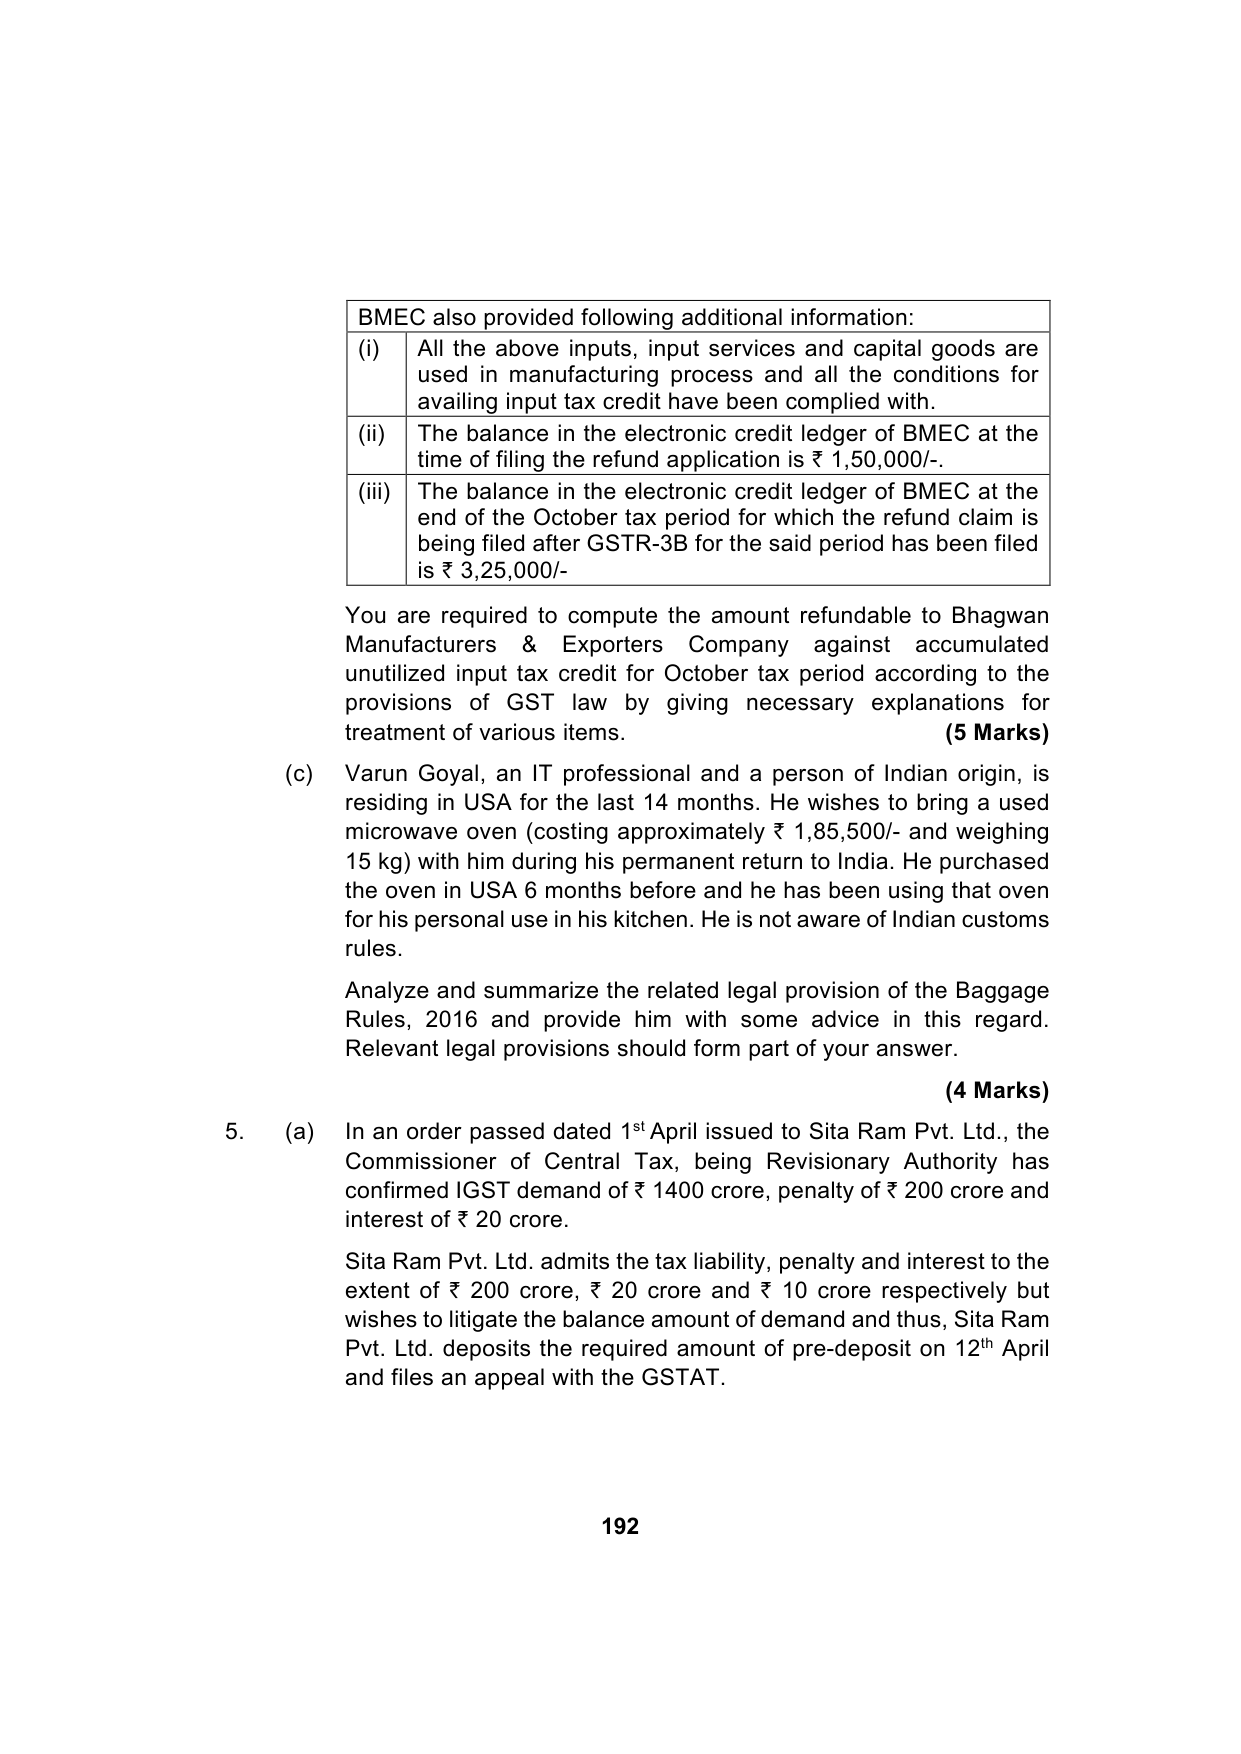
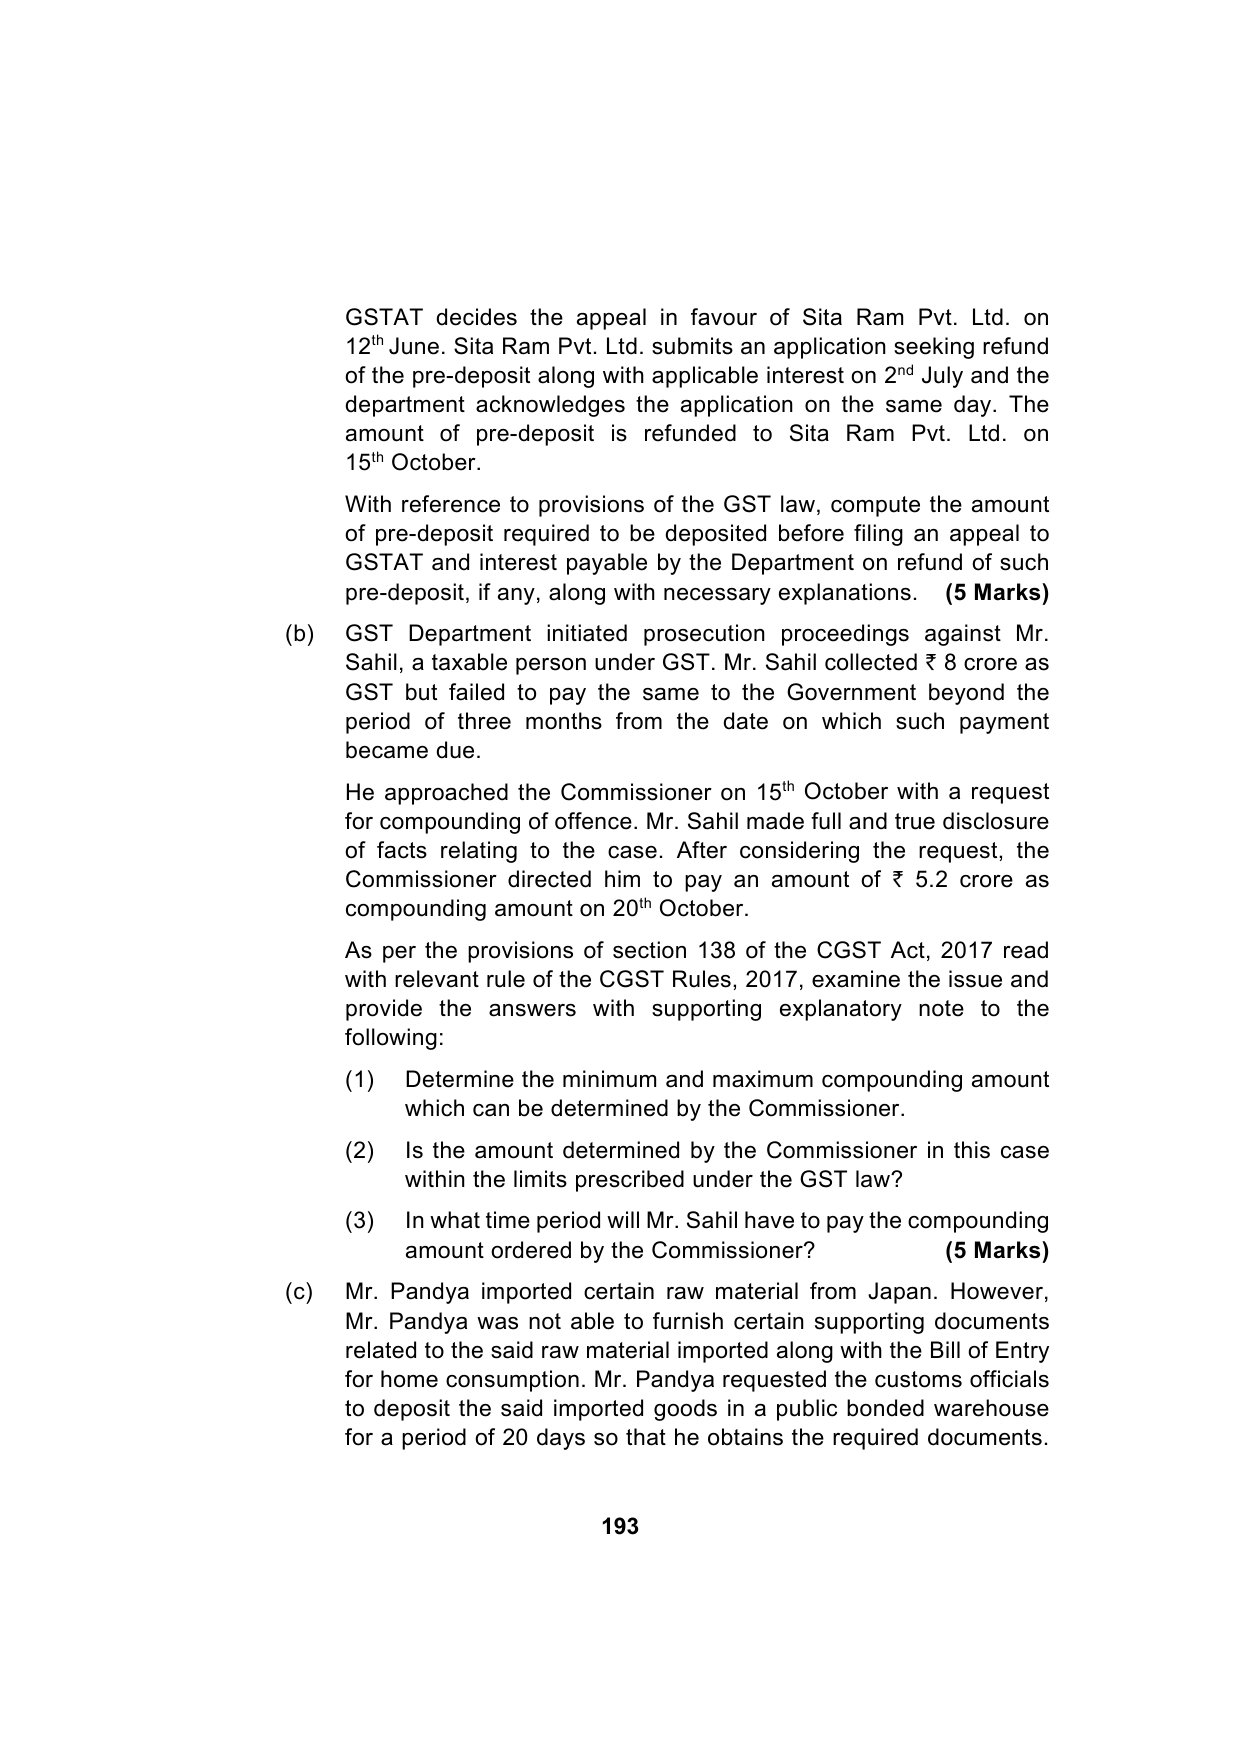
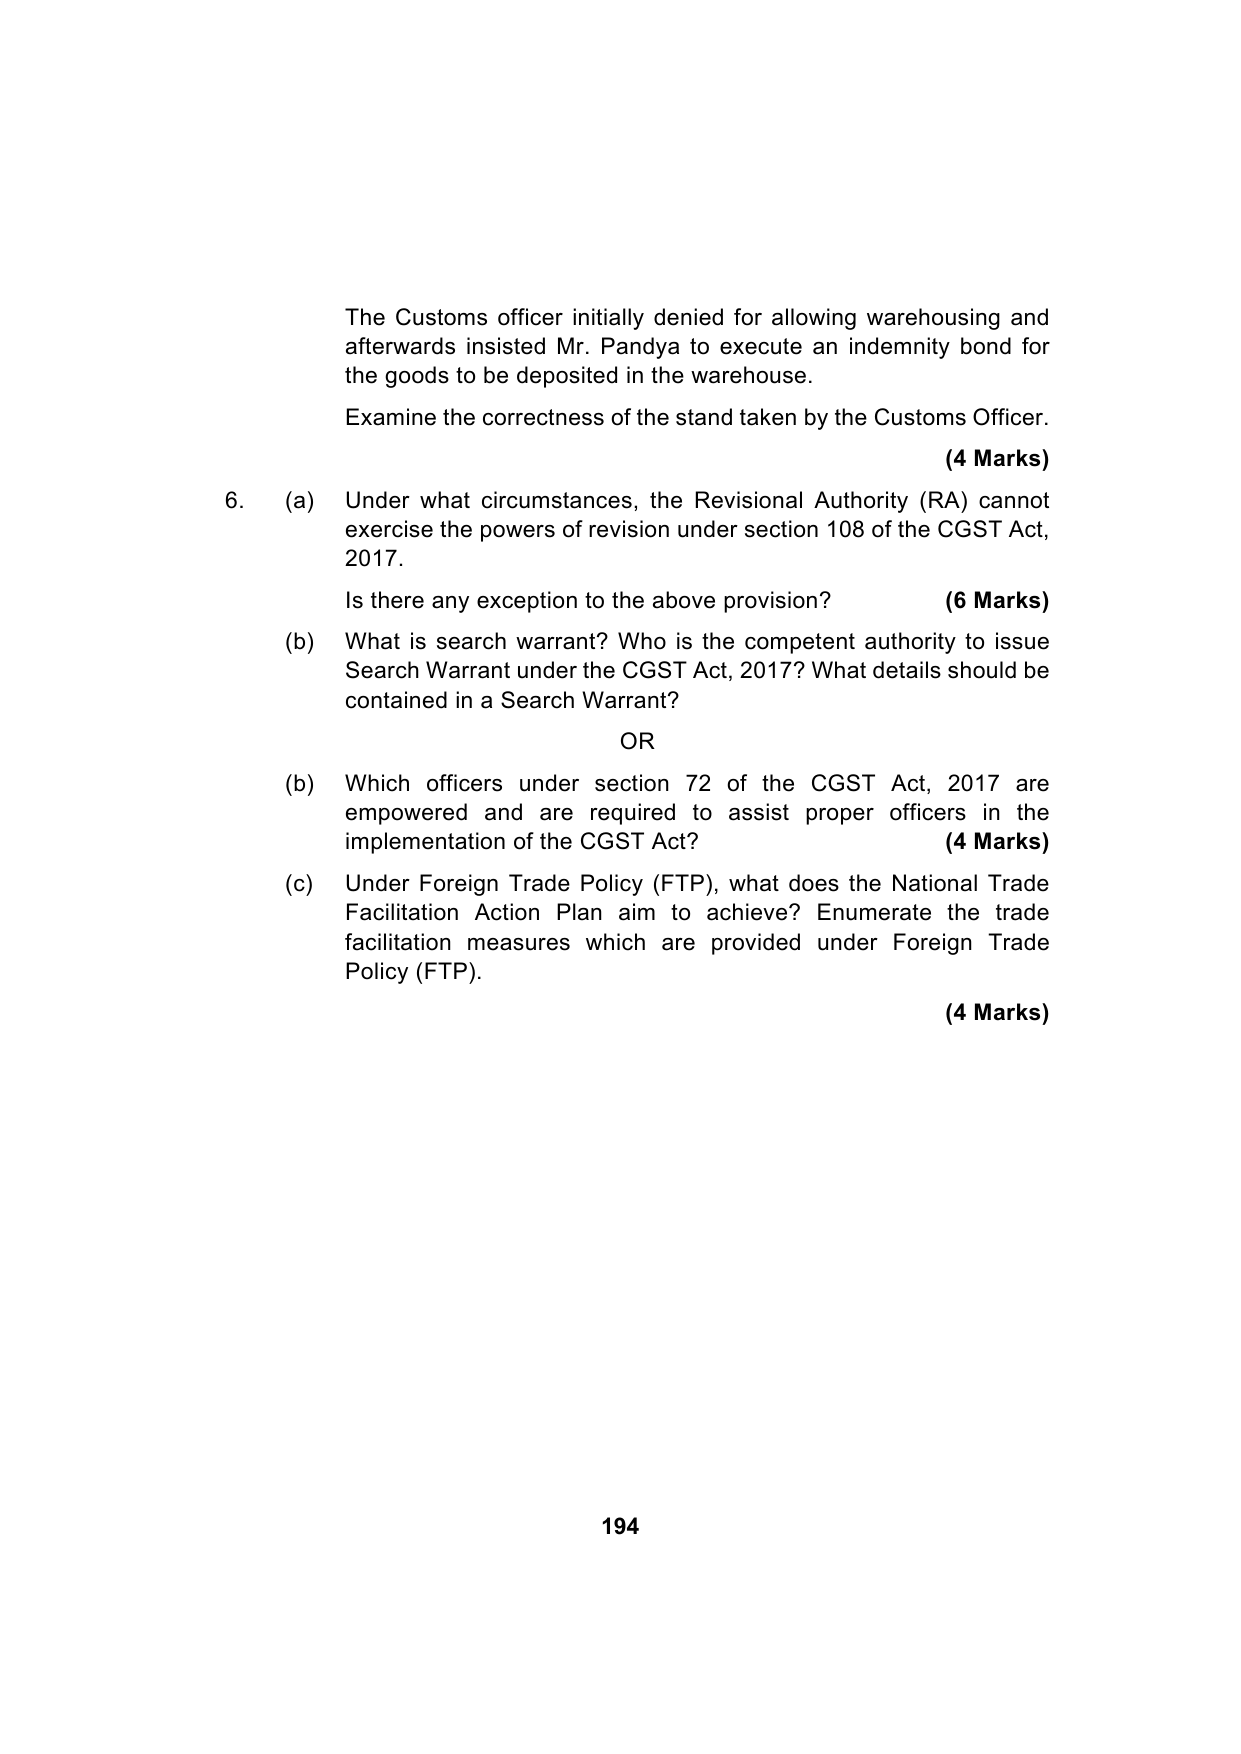
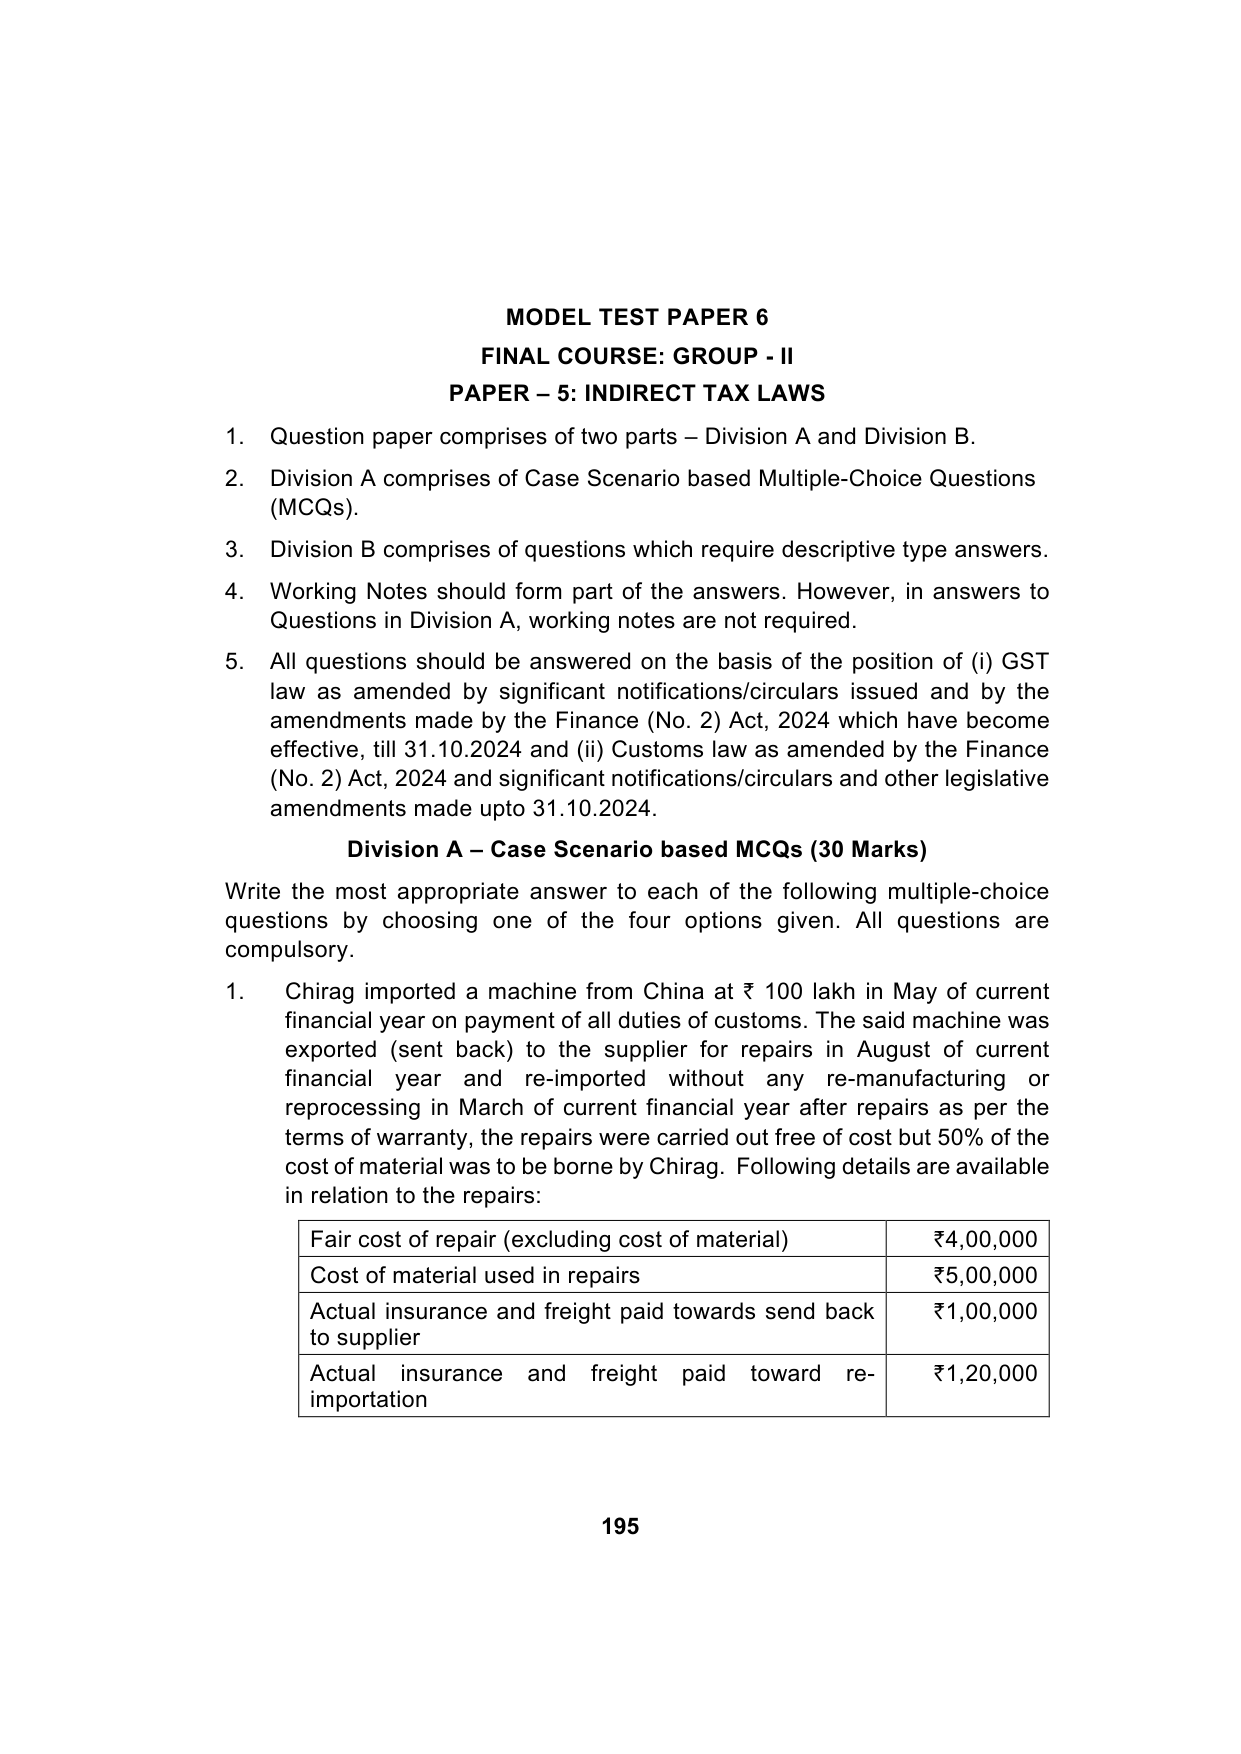
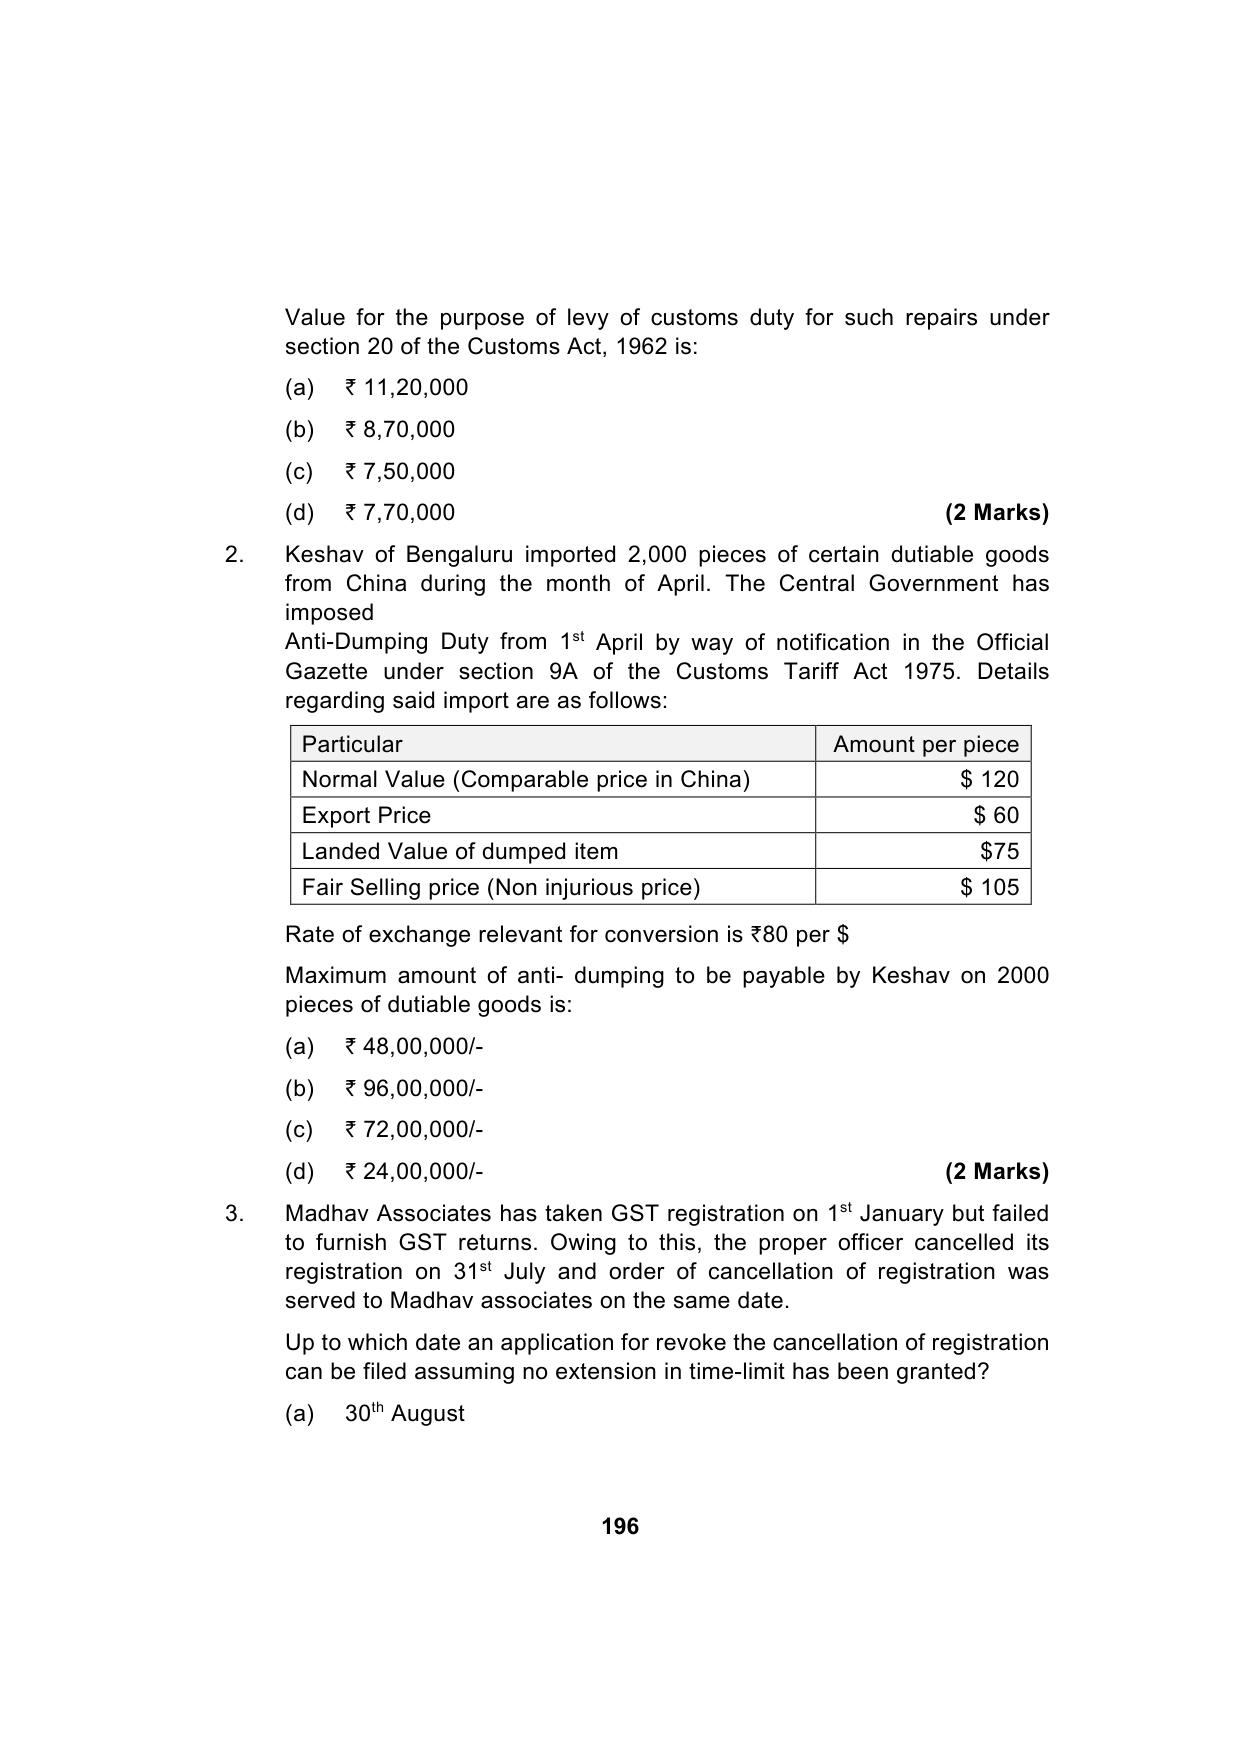
Paper 5: Indirect Tax Laws — Model Test Paper 6
Question
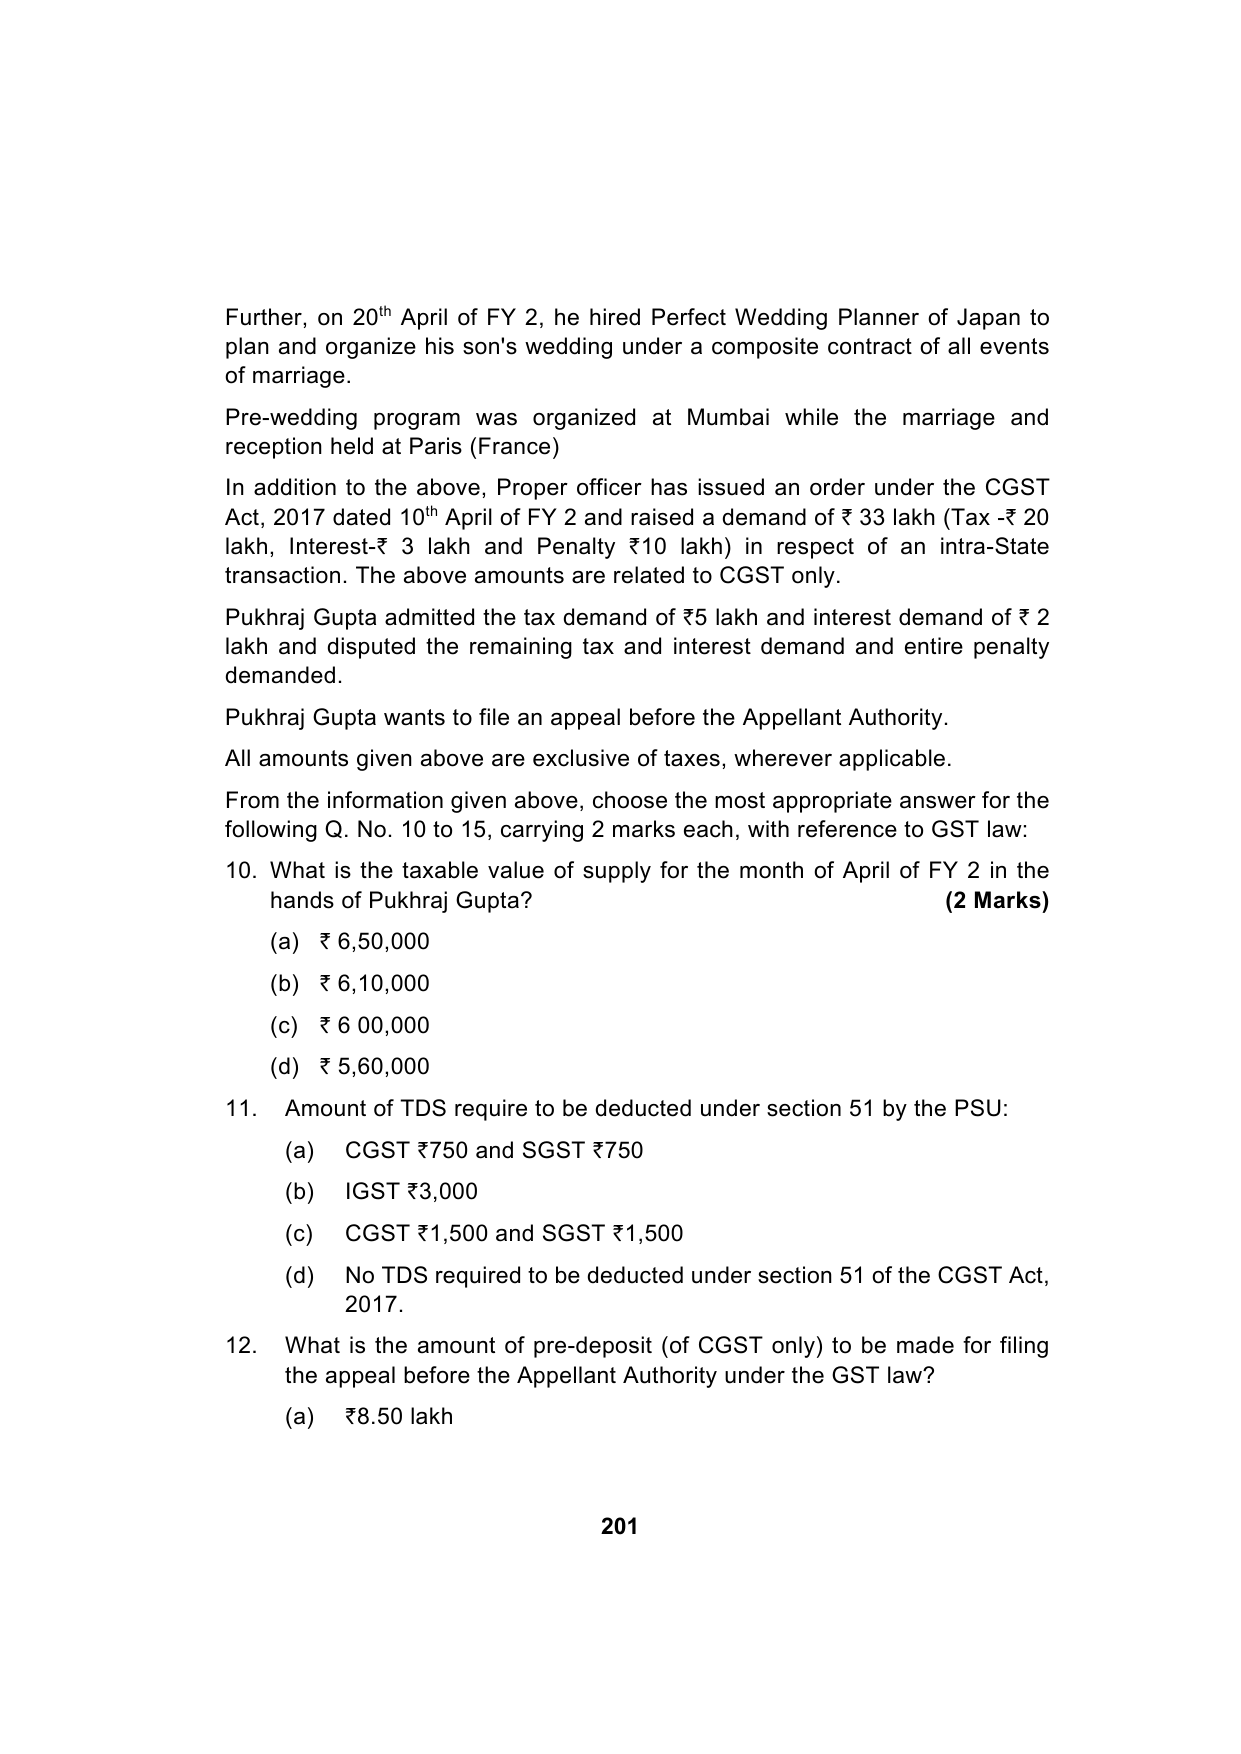
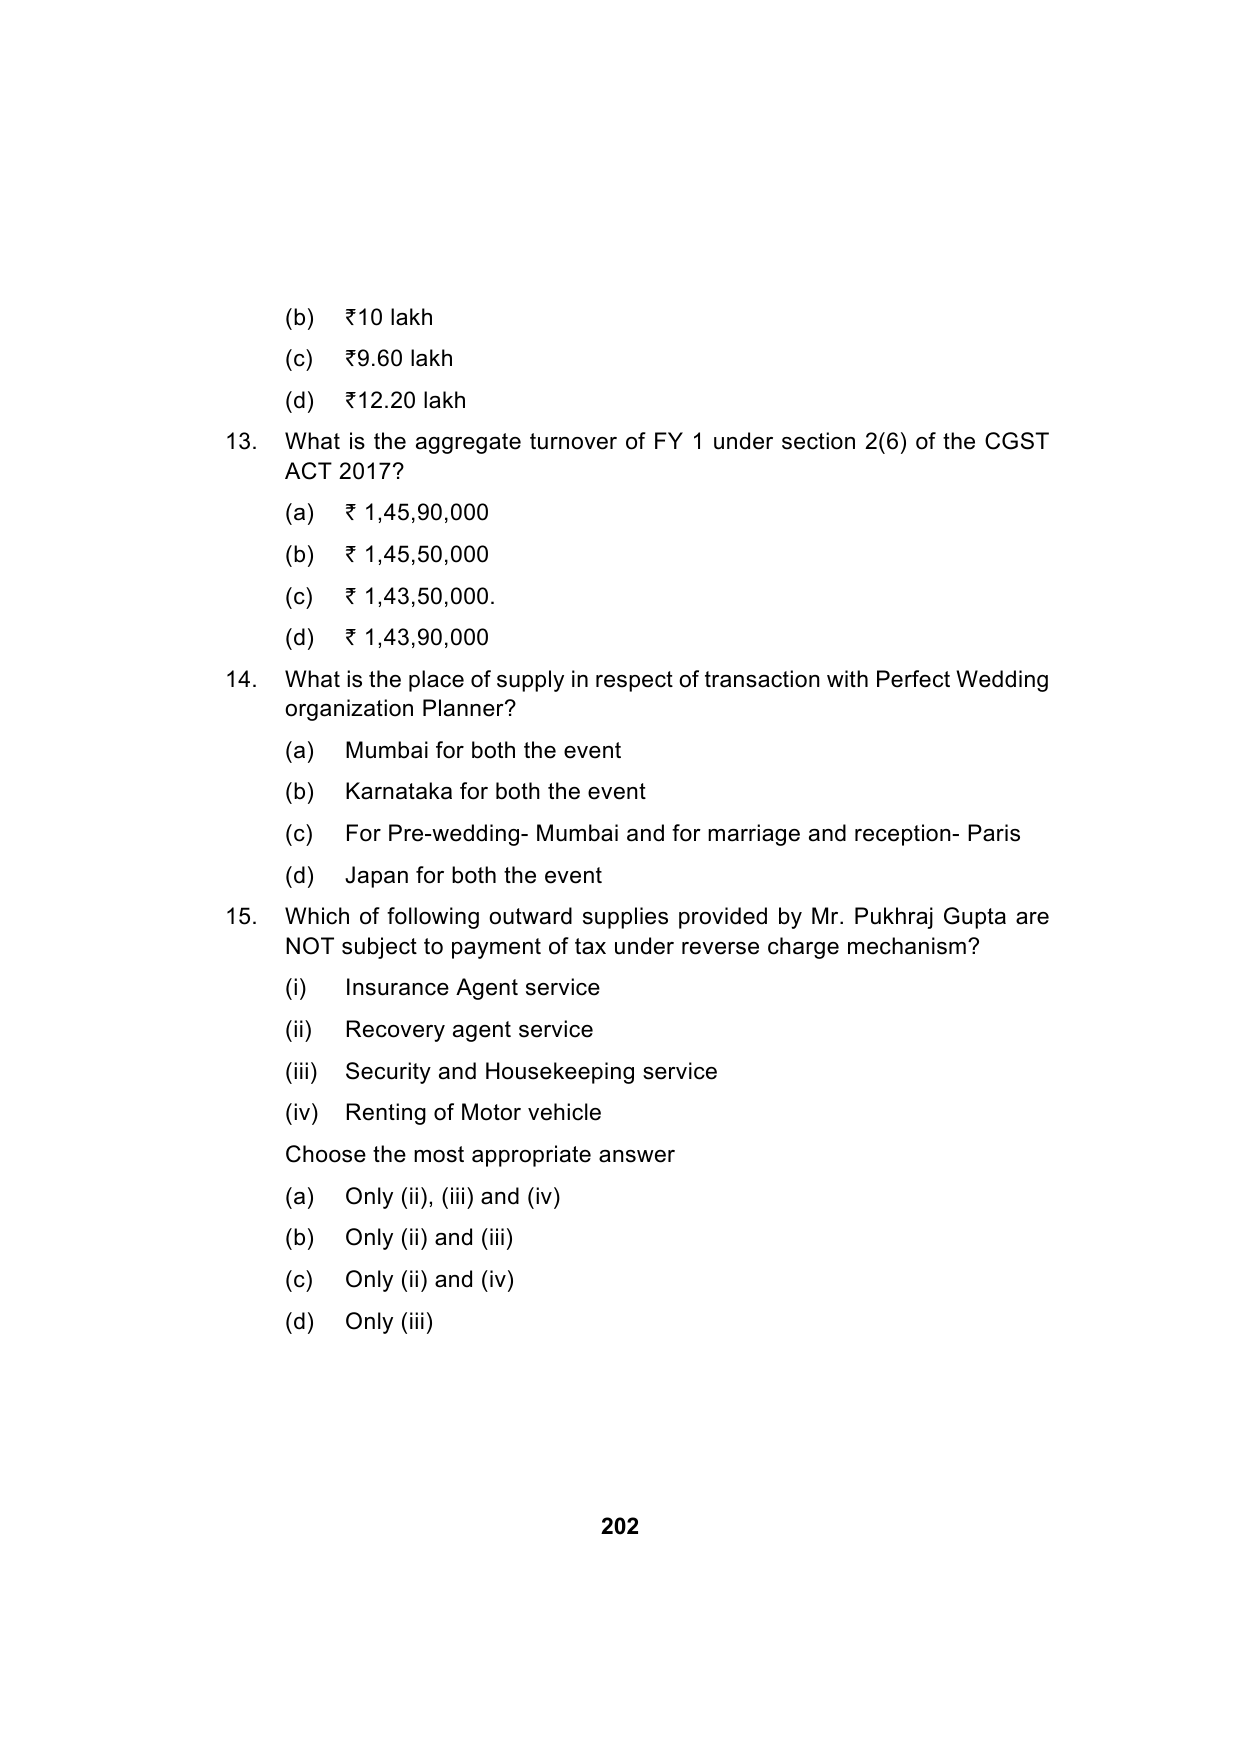
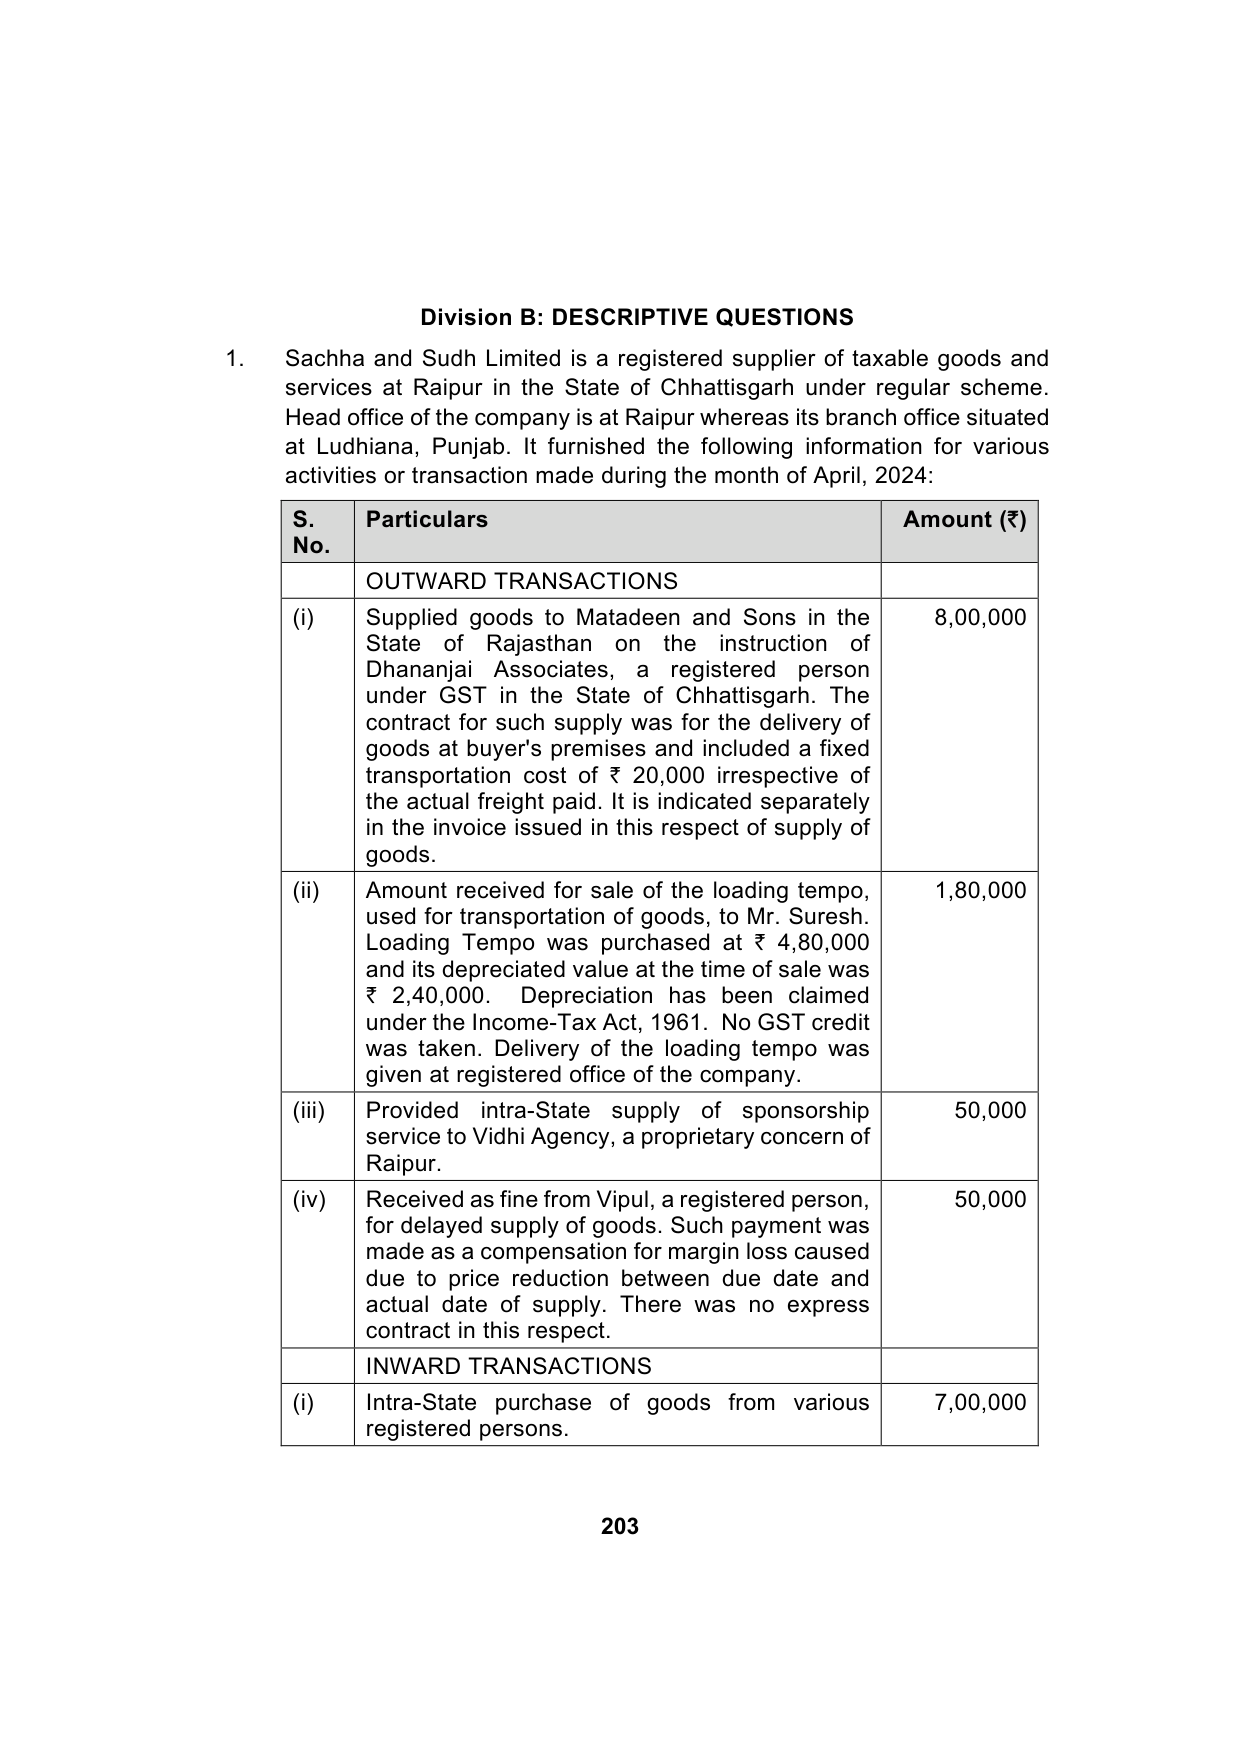
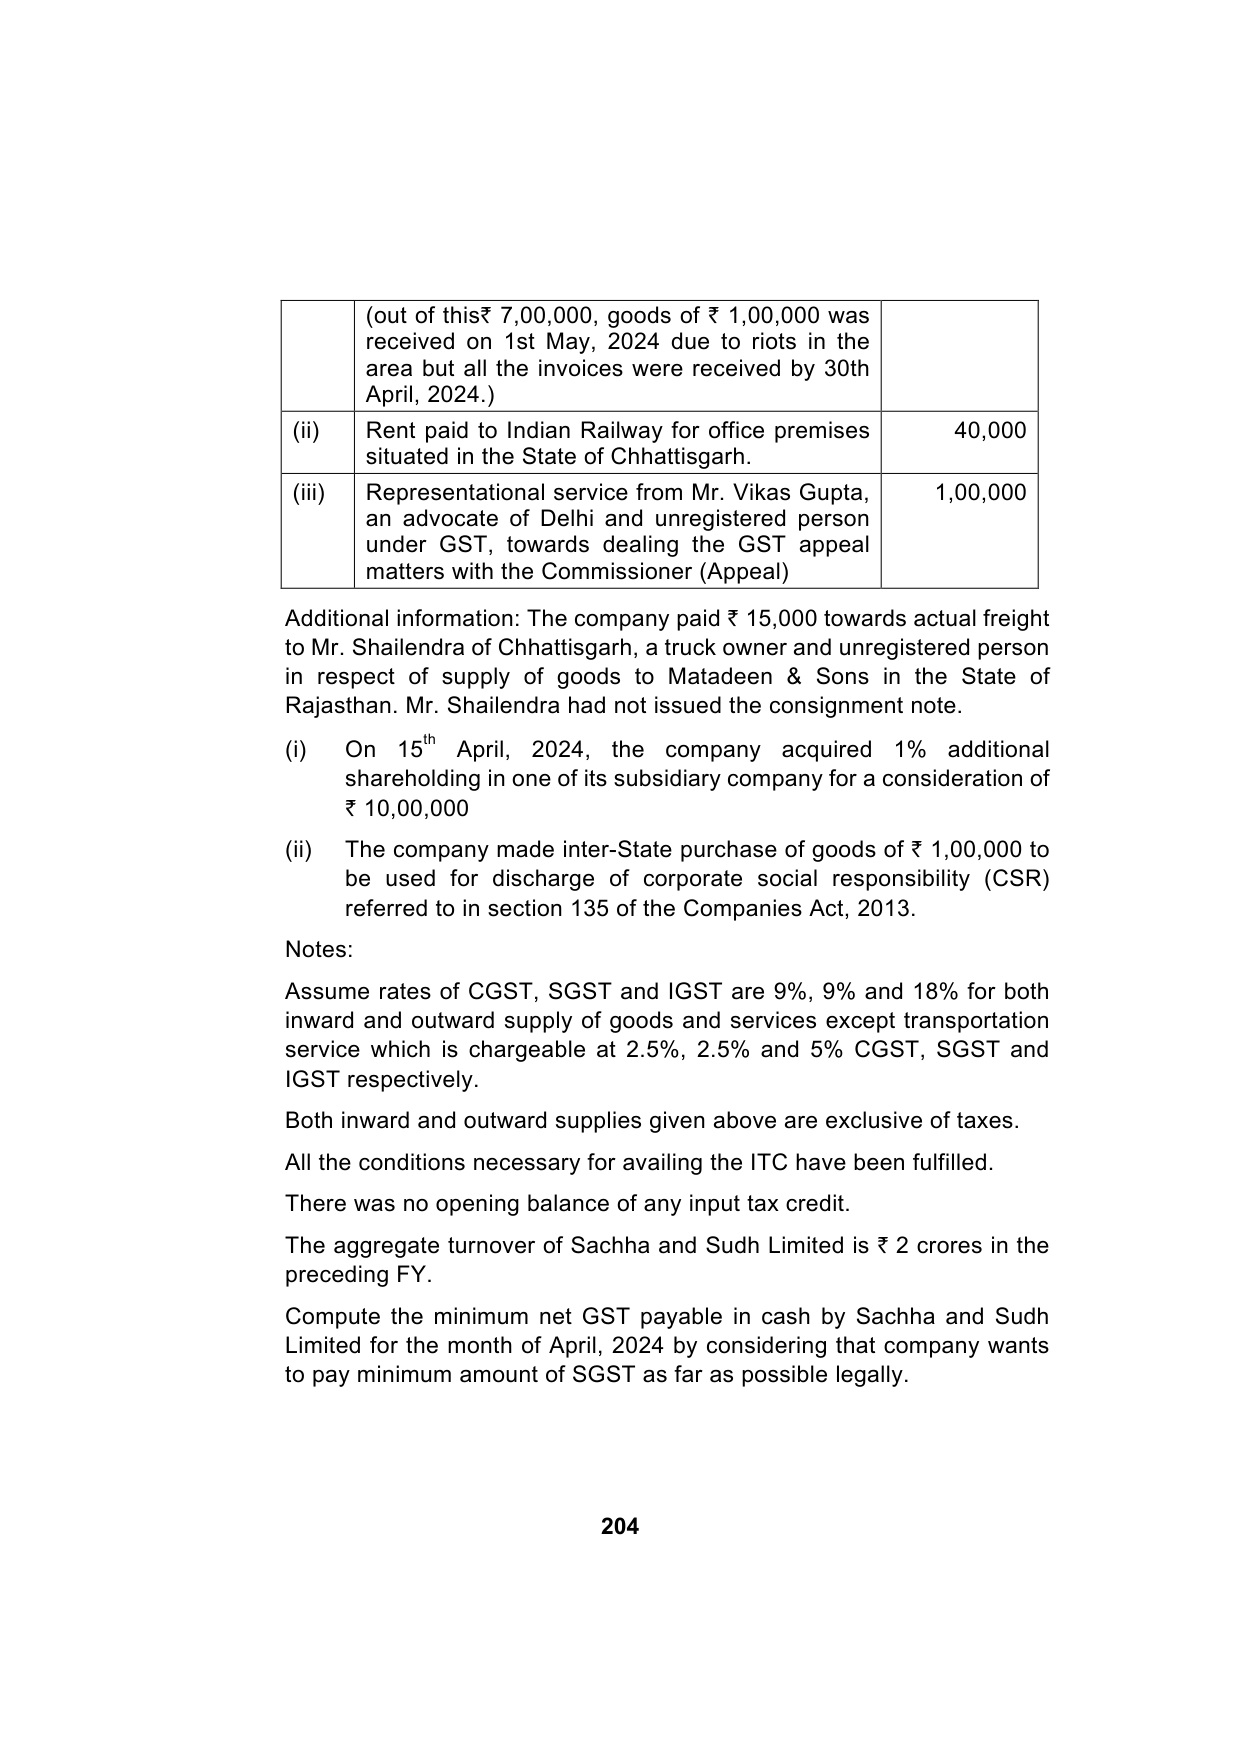
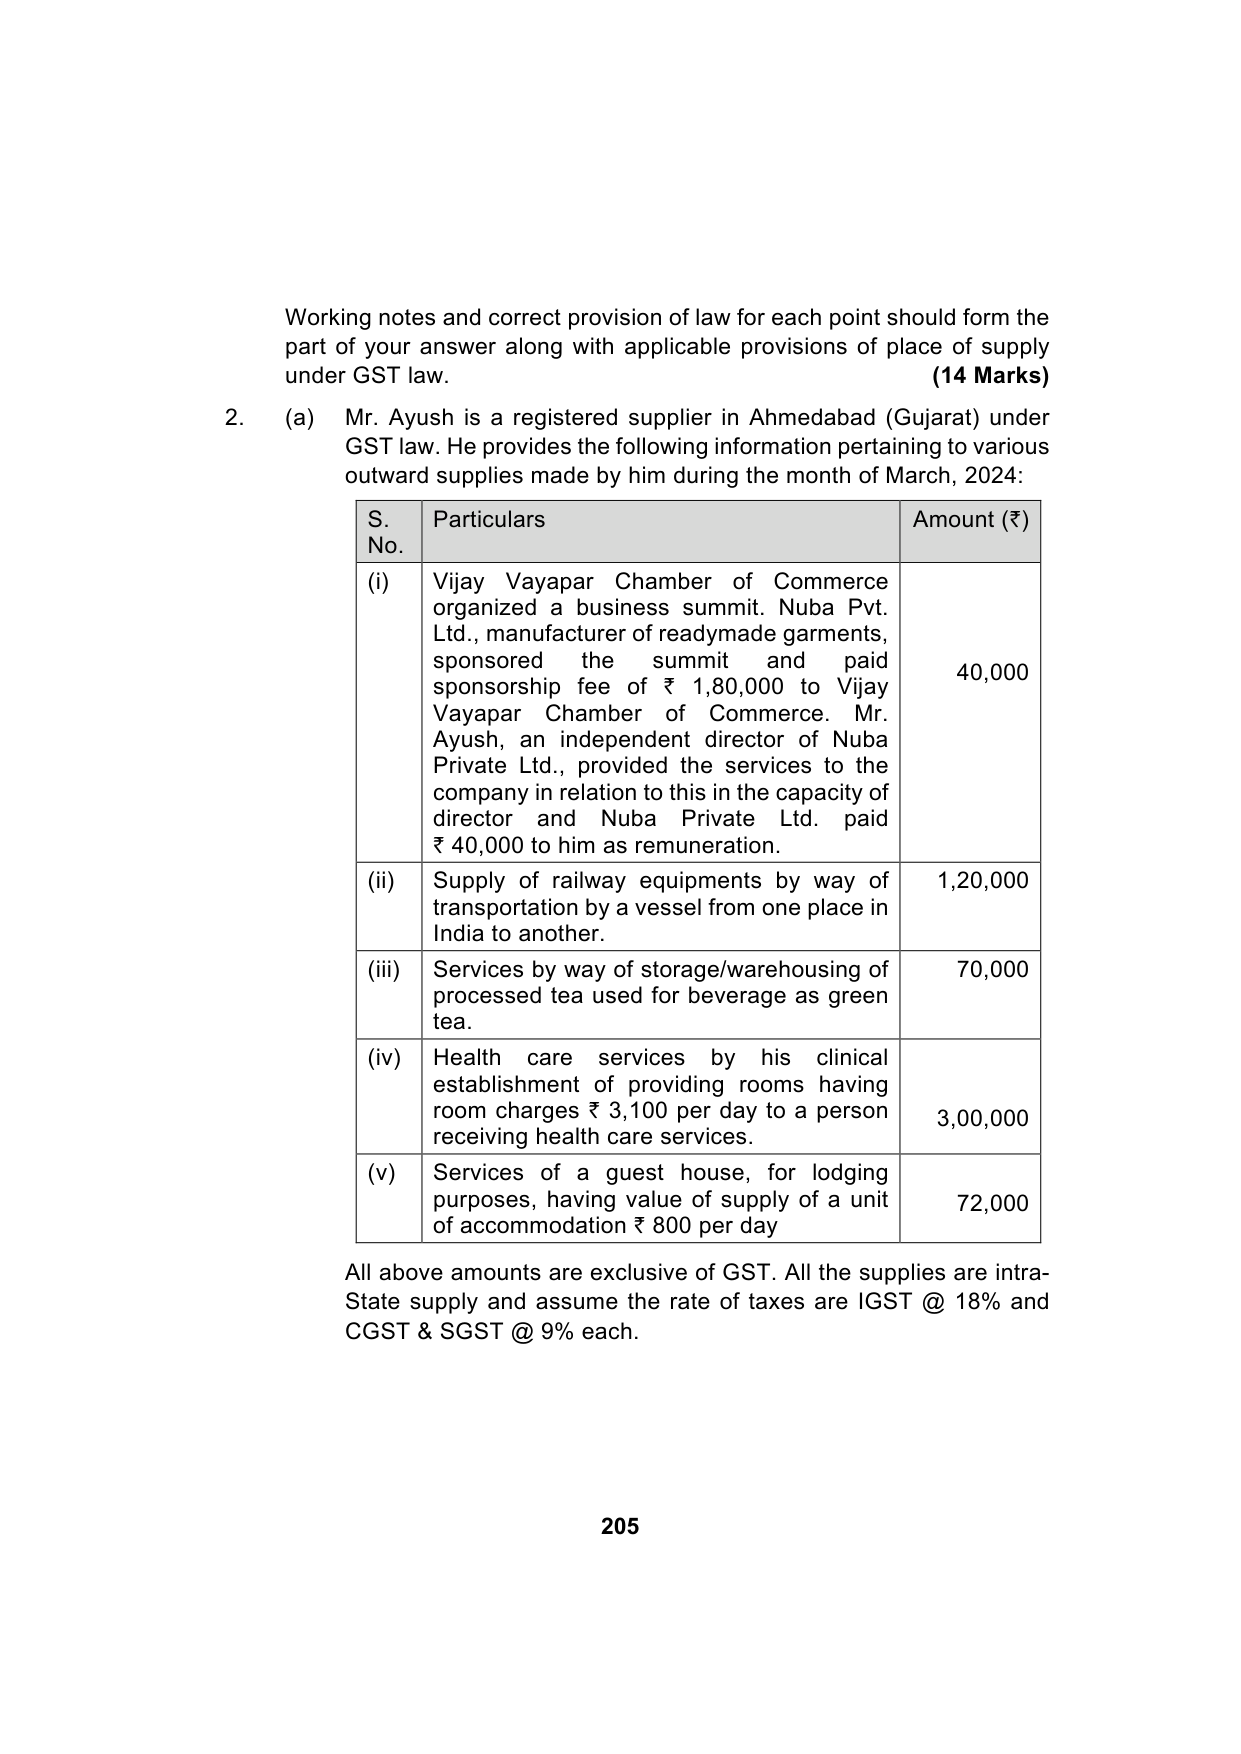
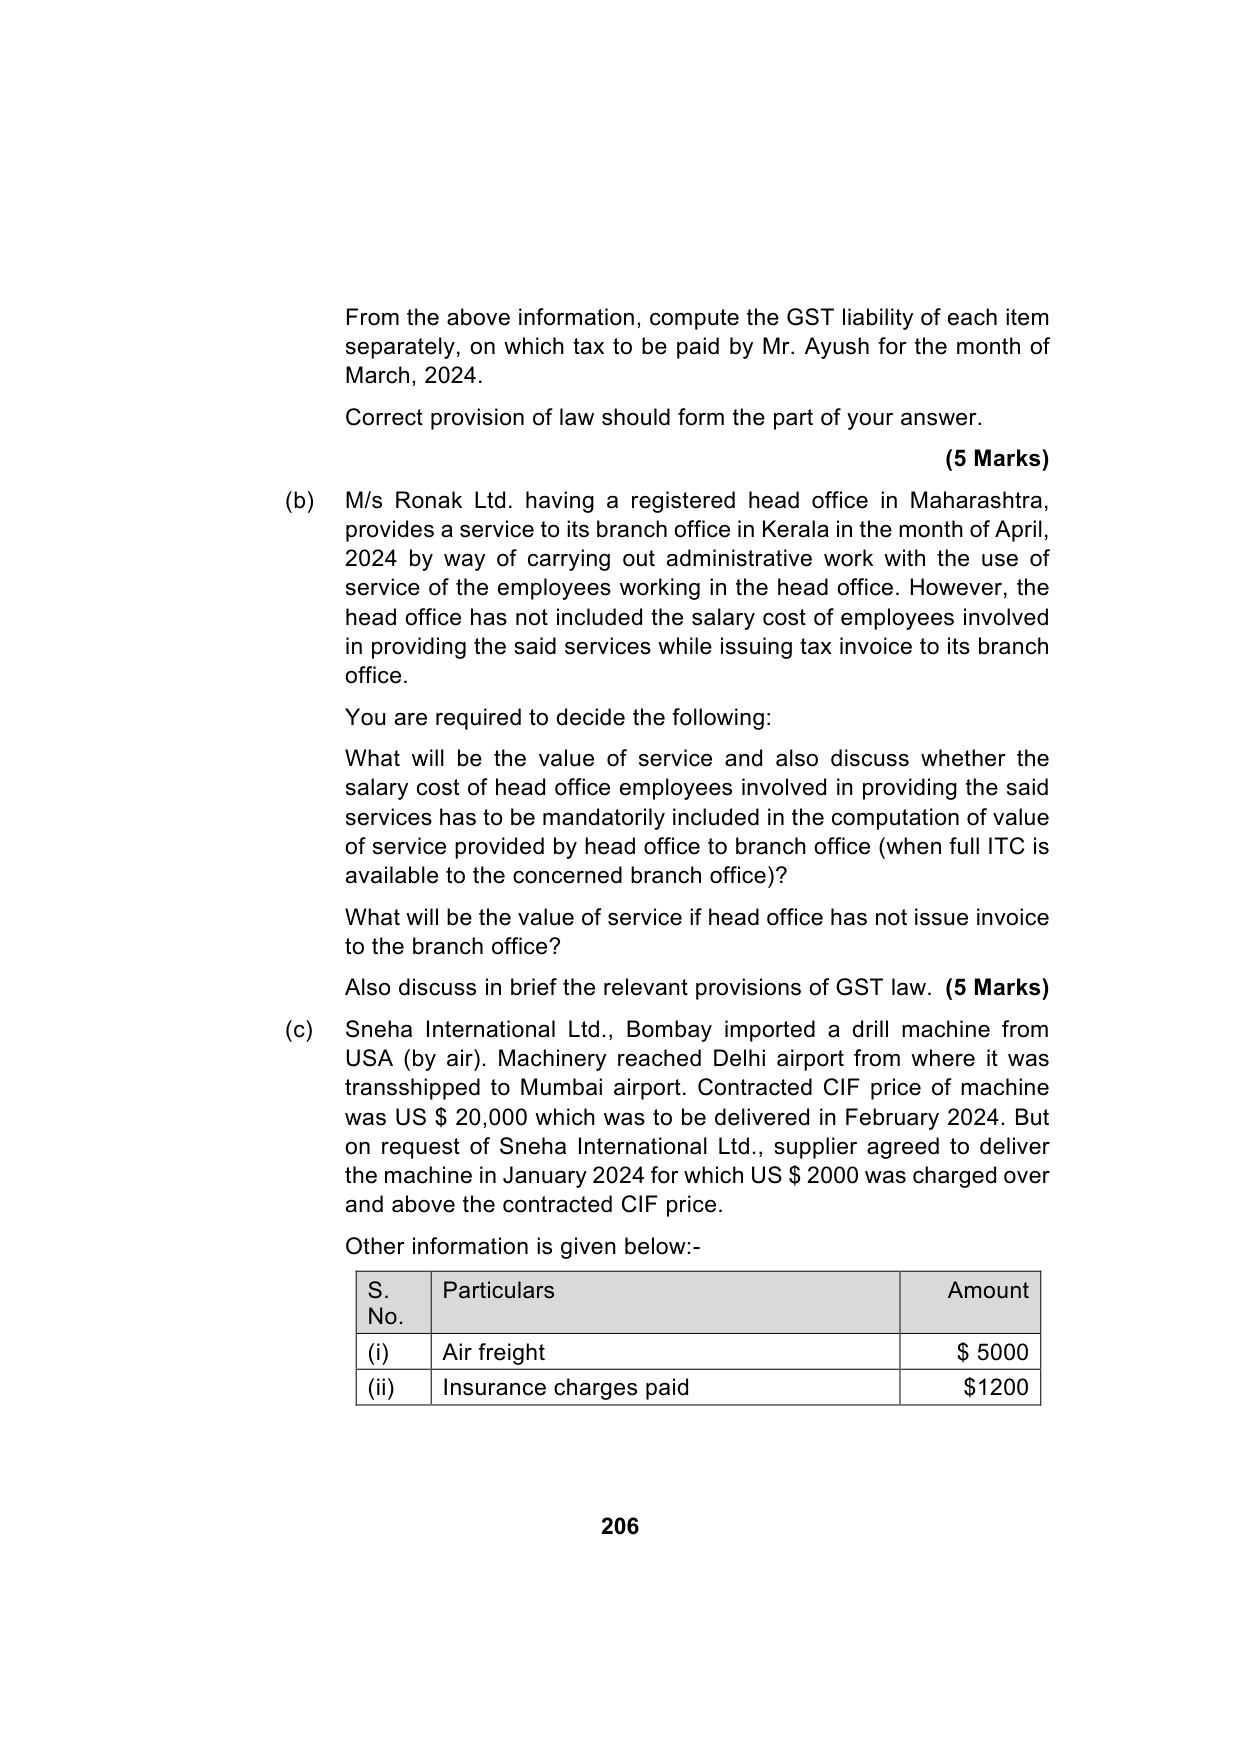
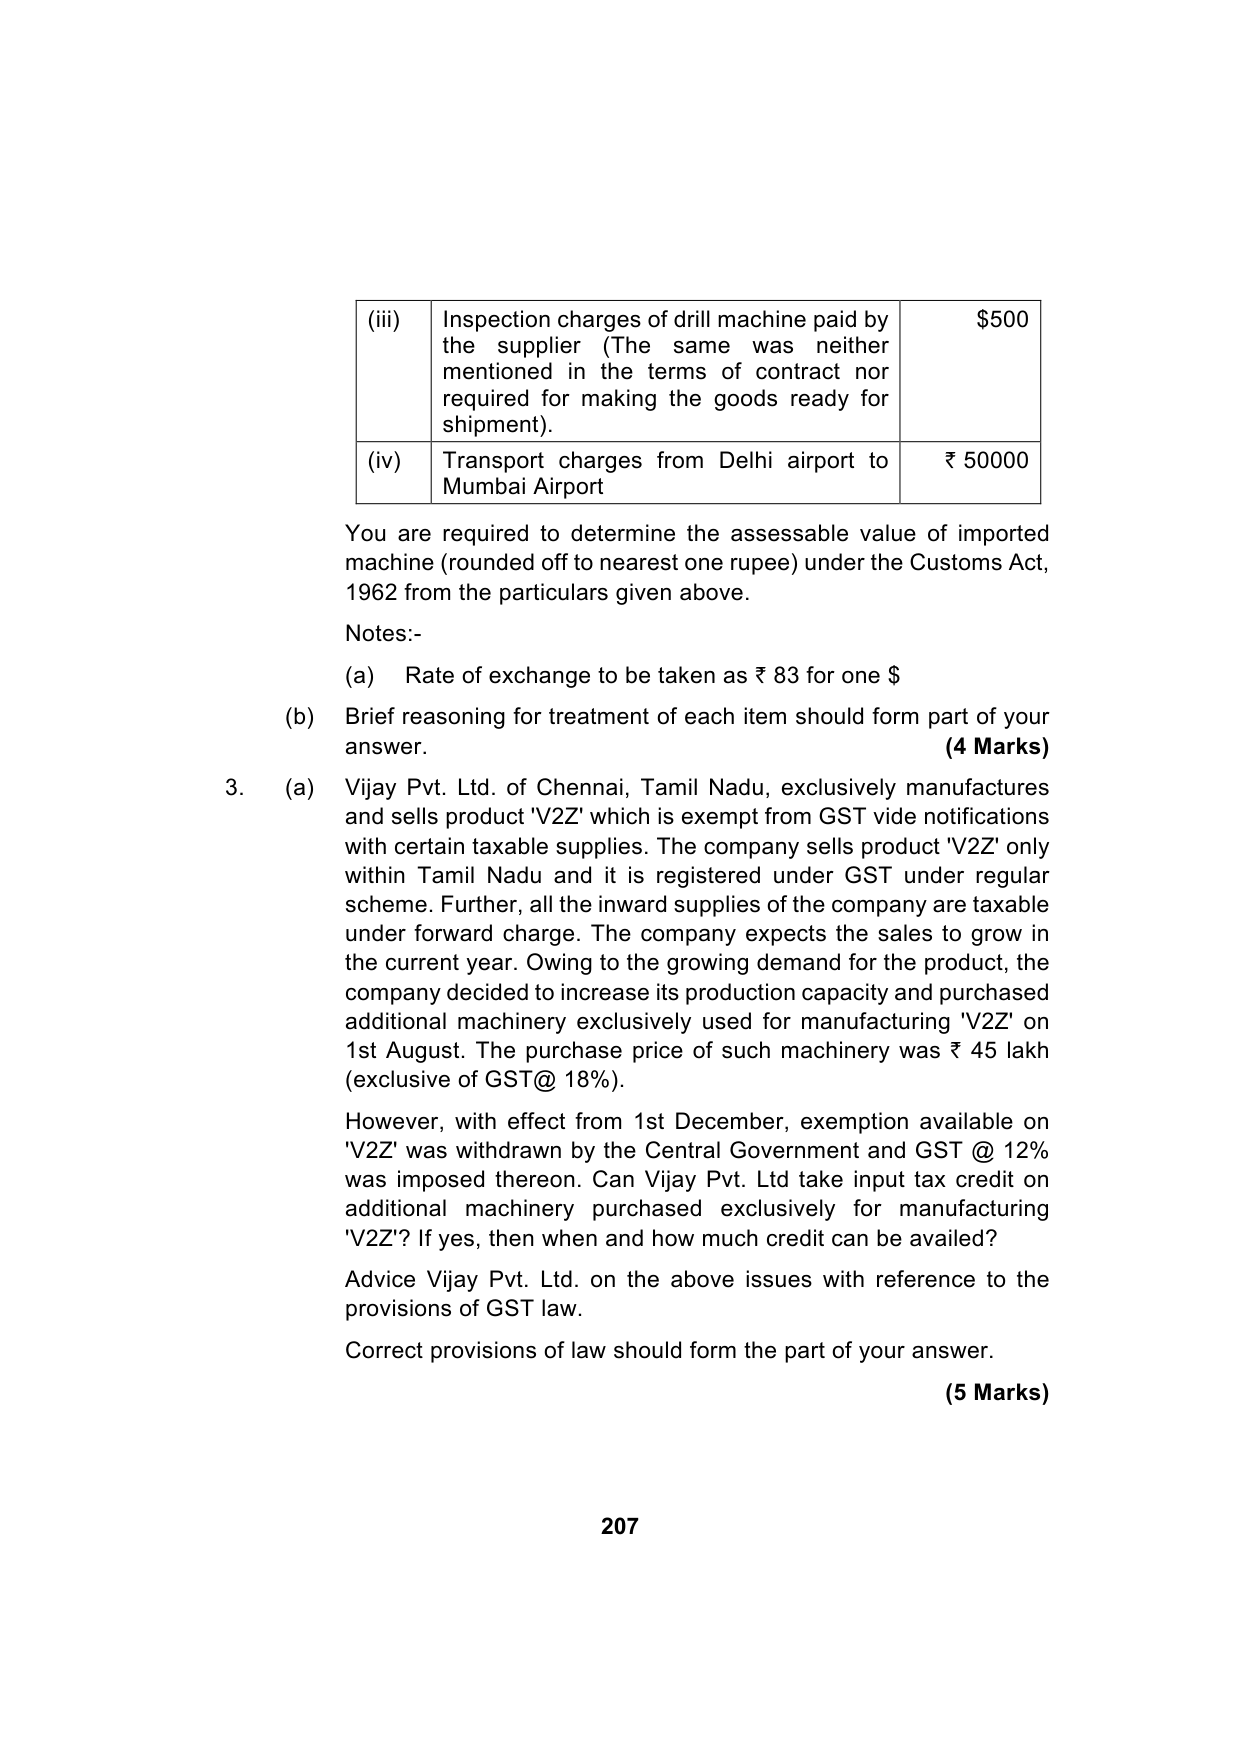
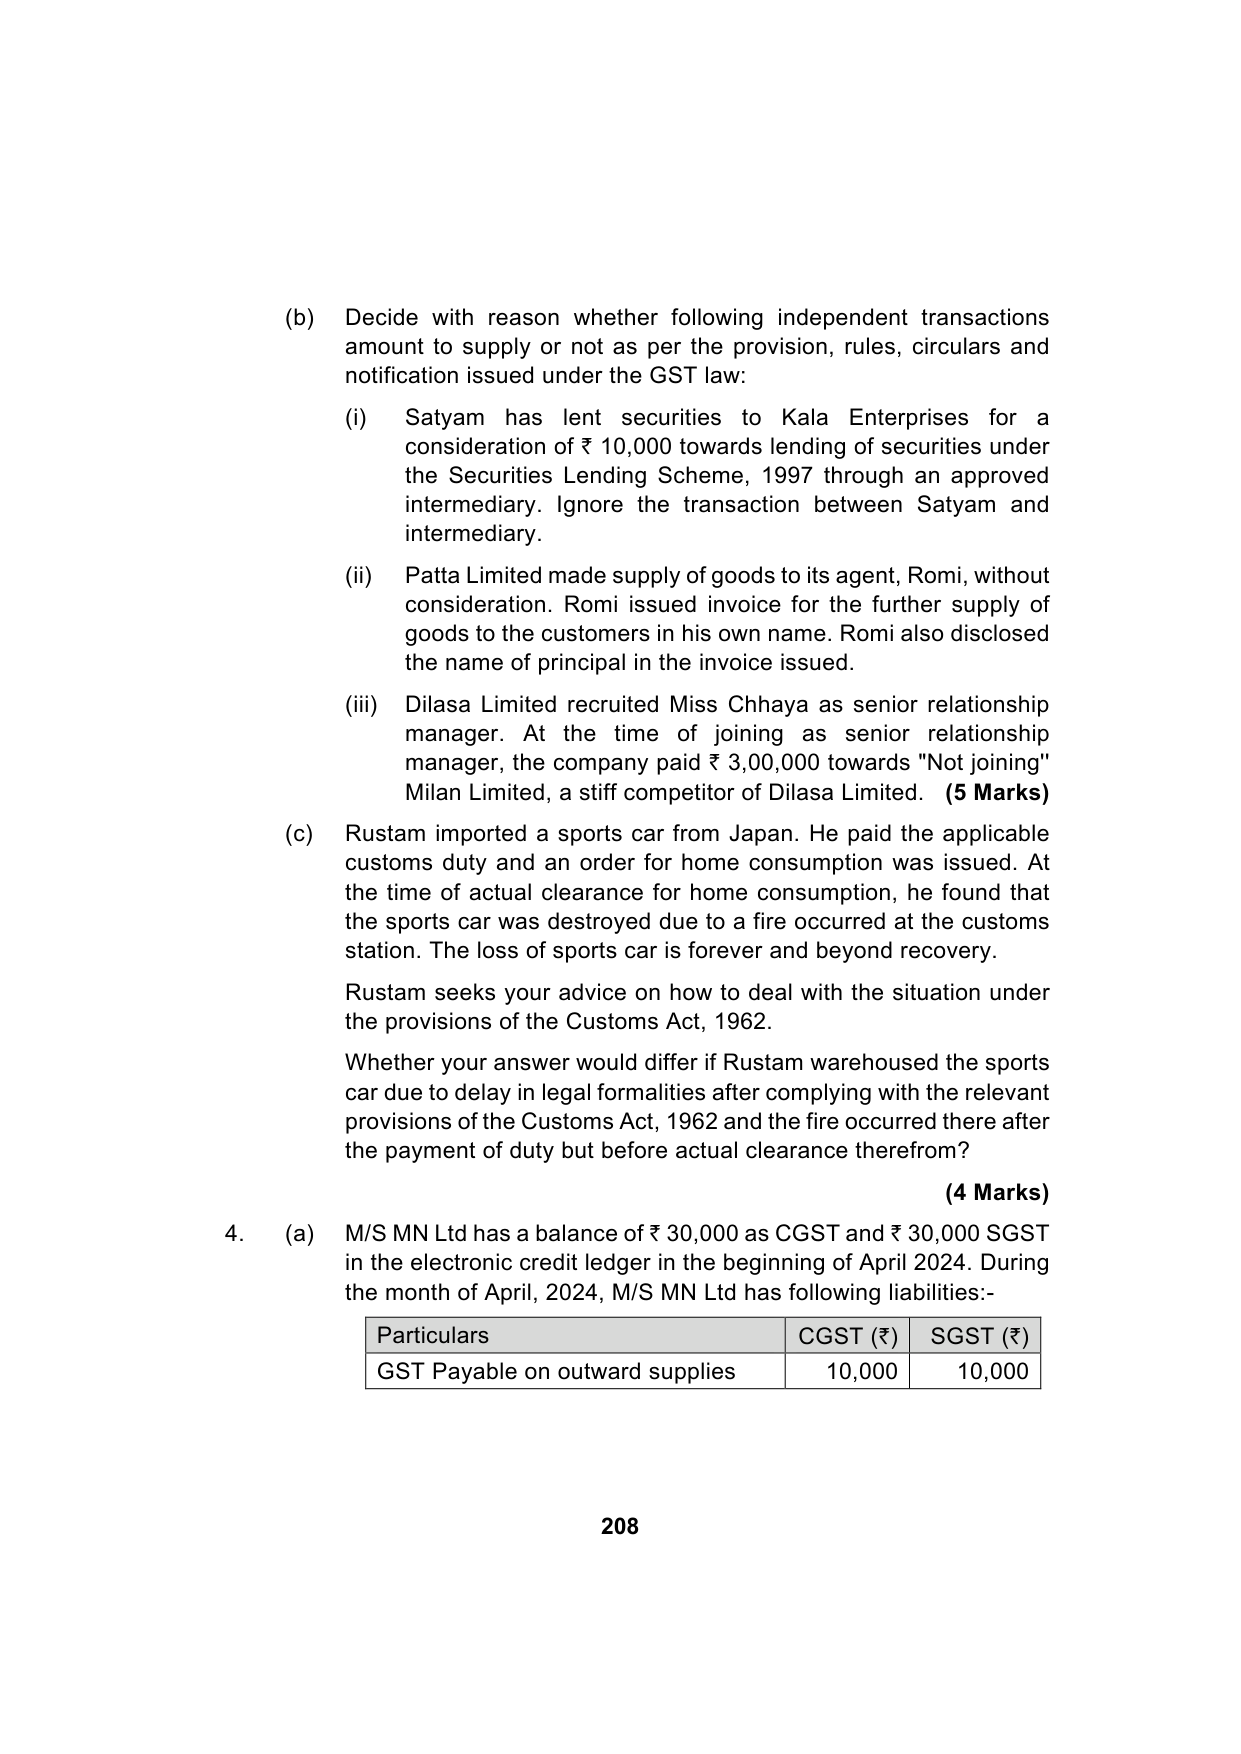
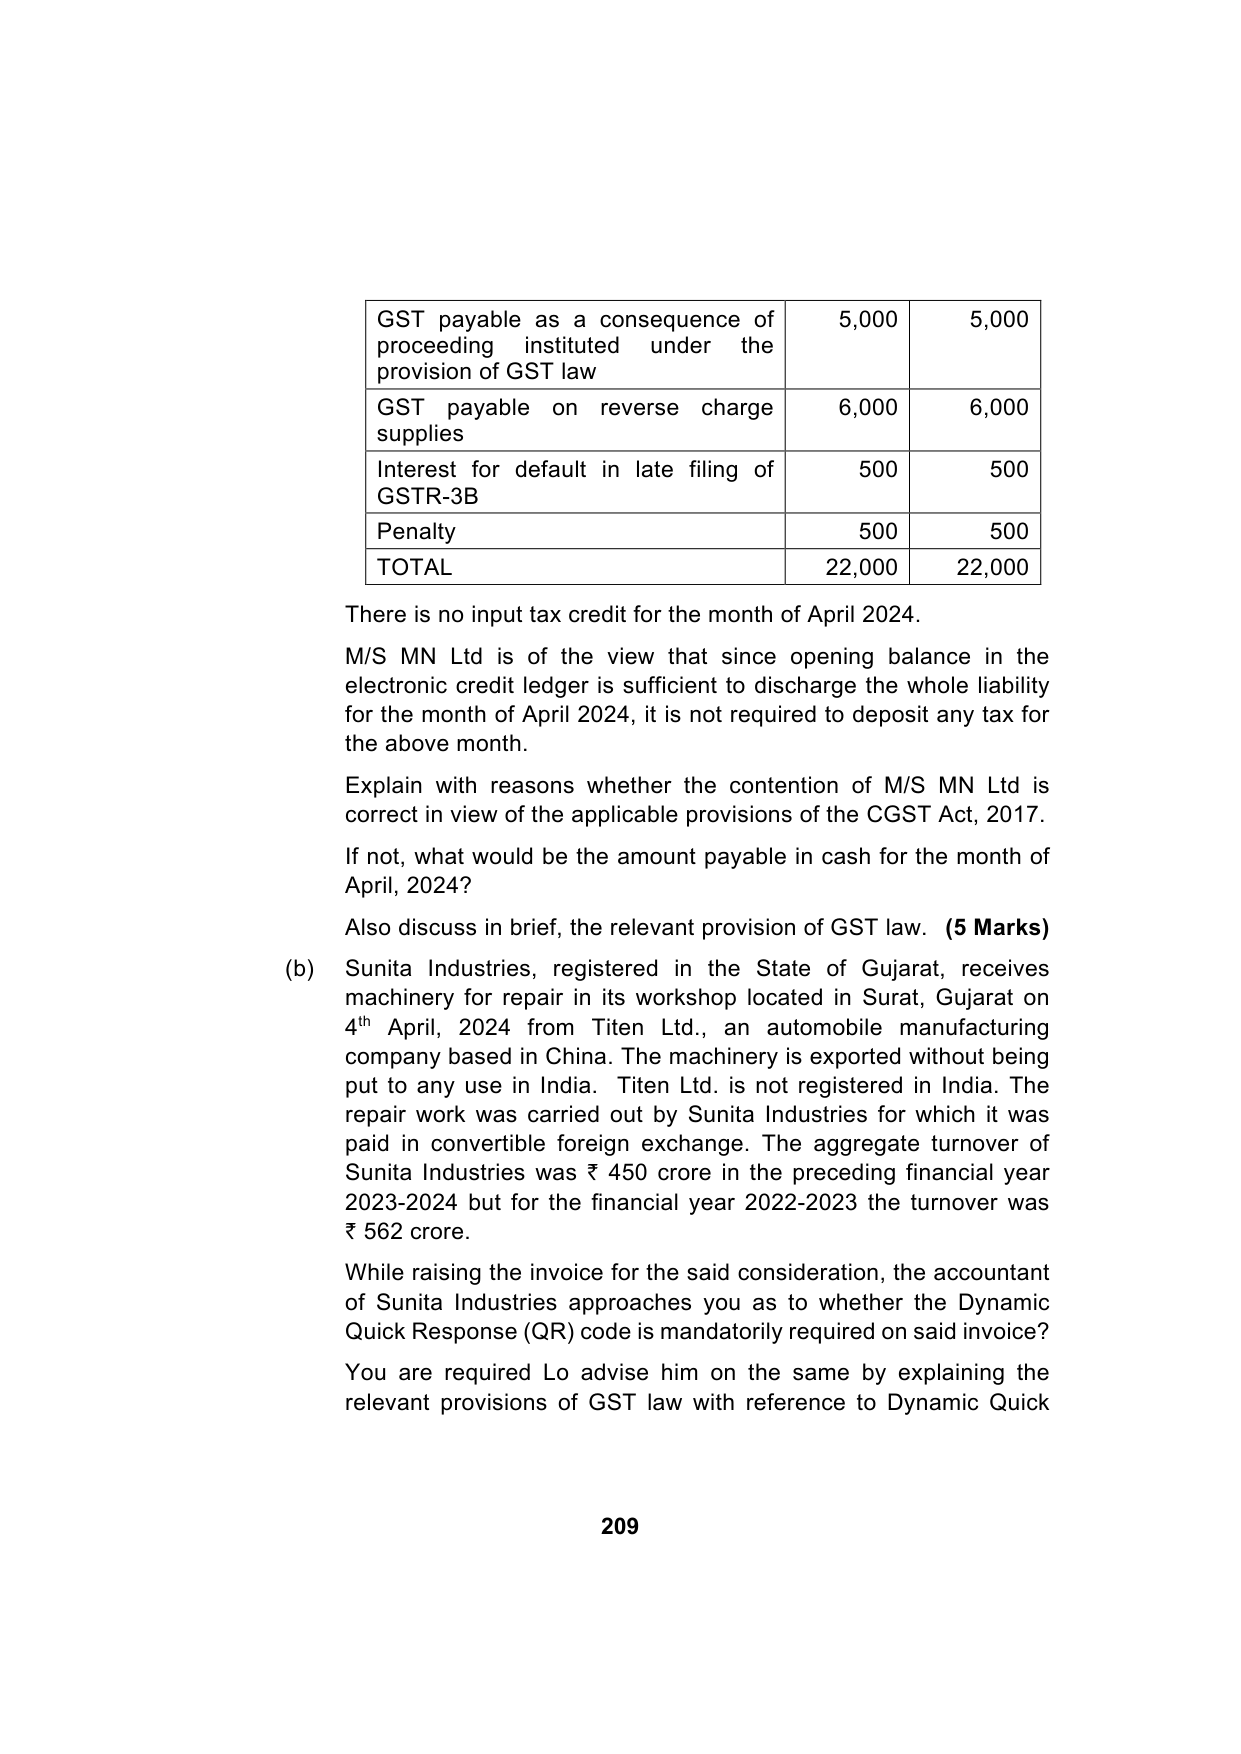
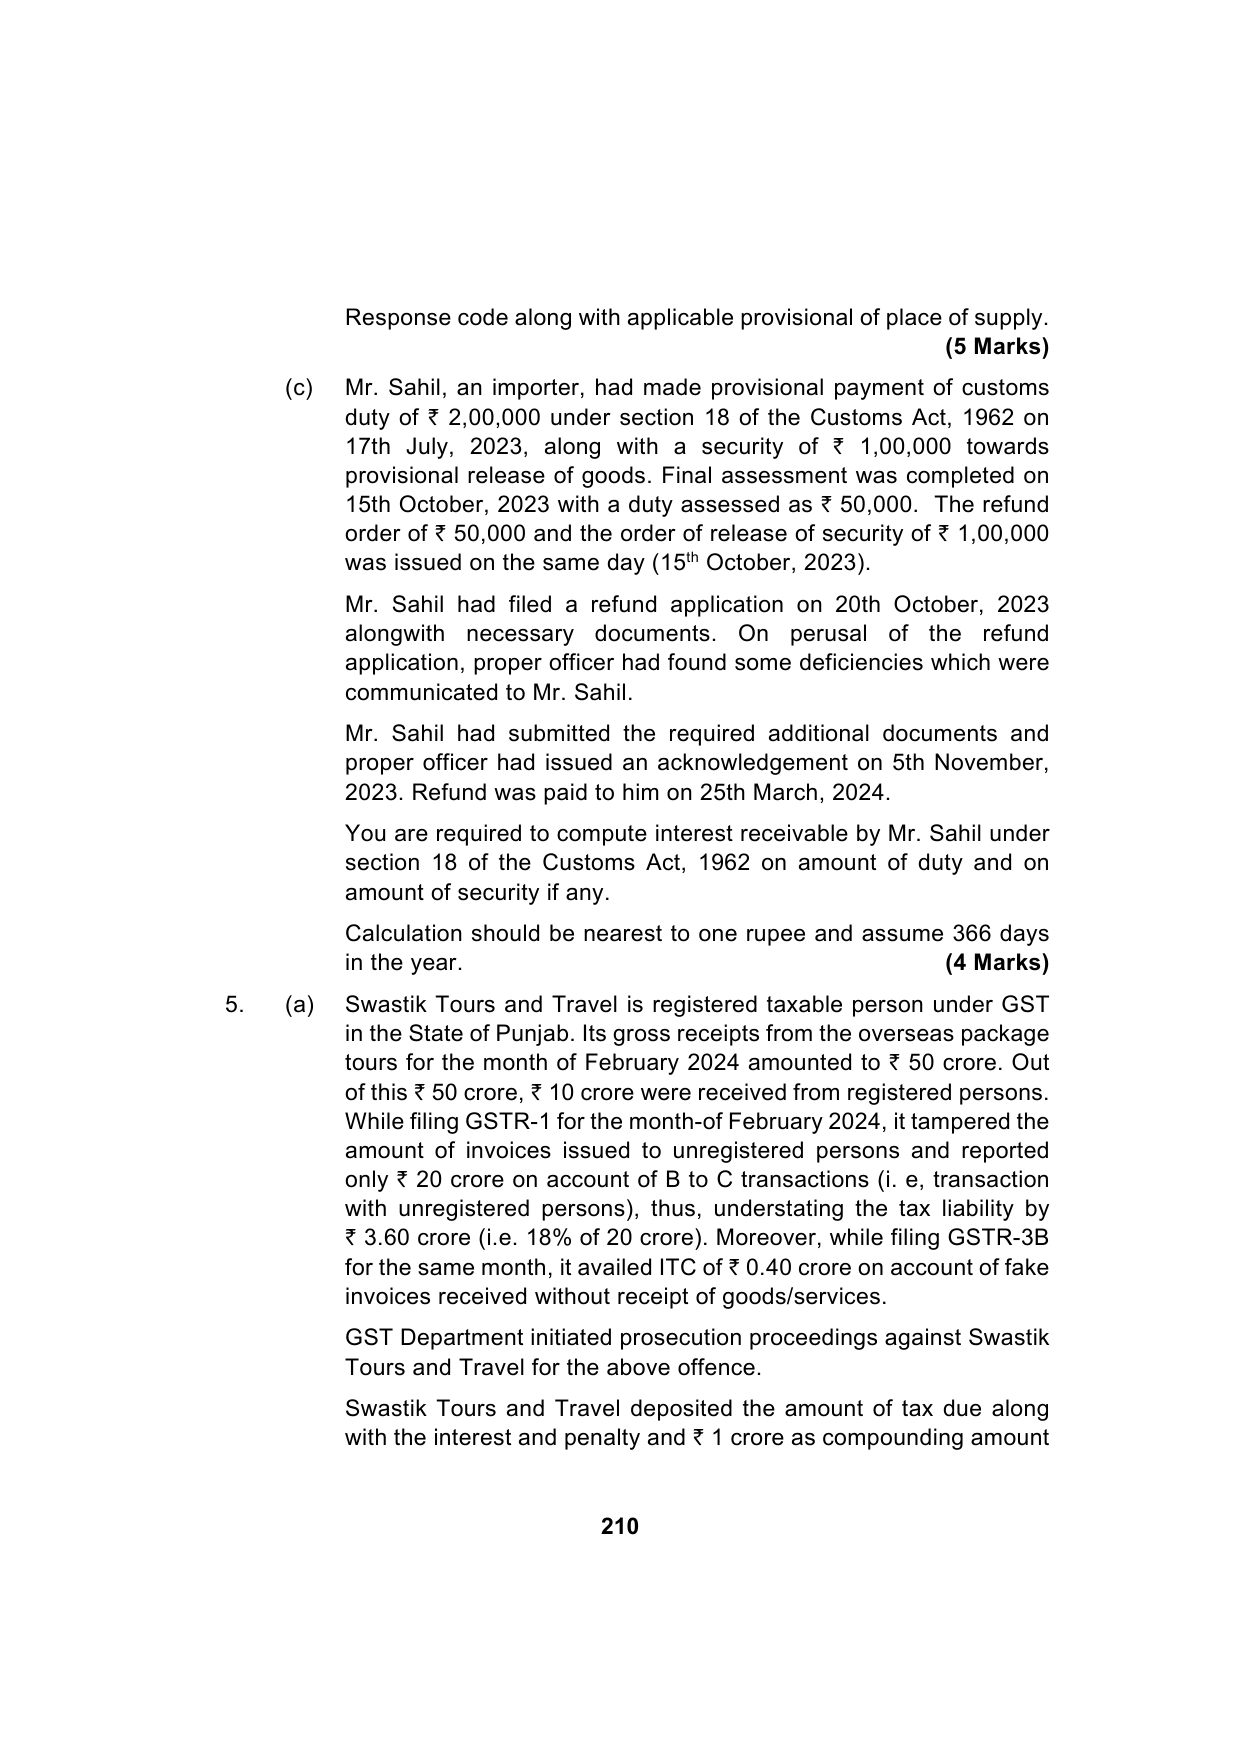
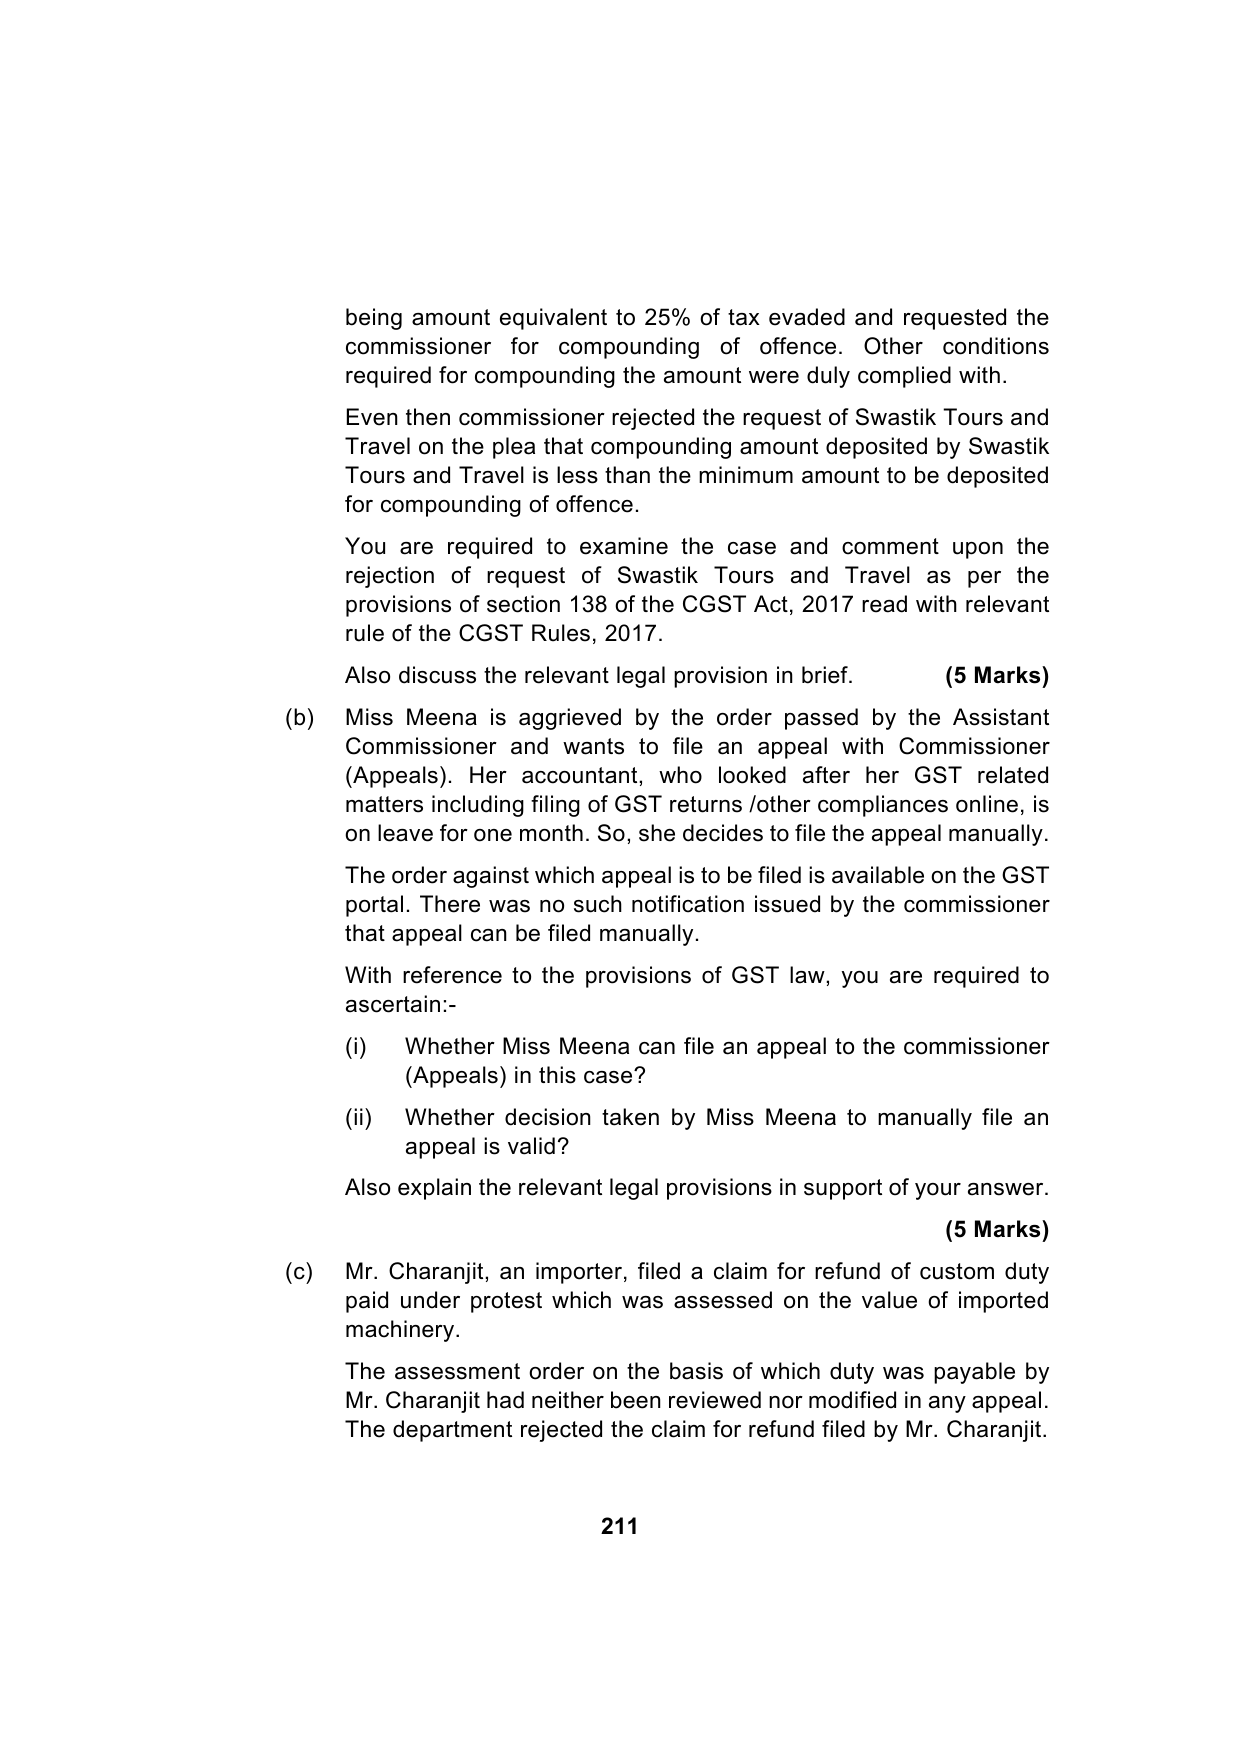
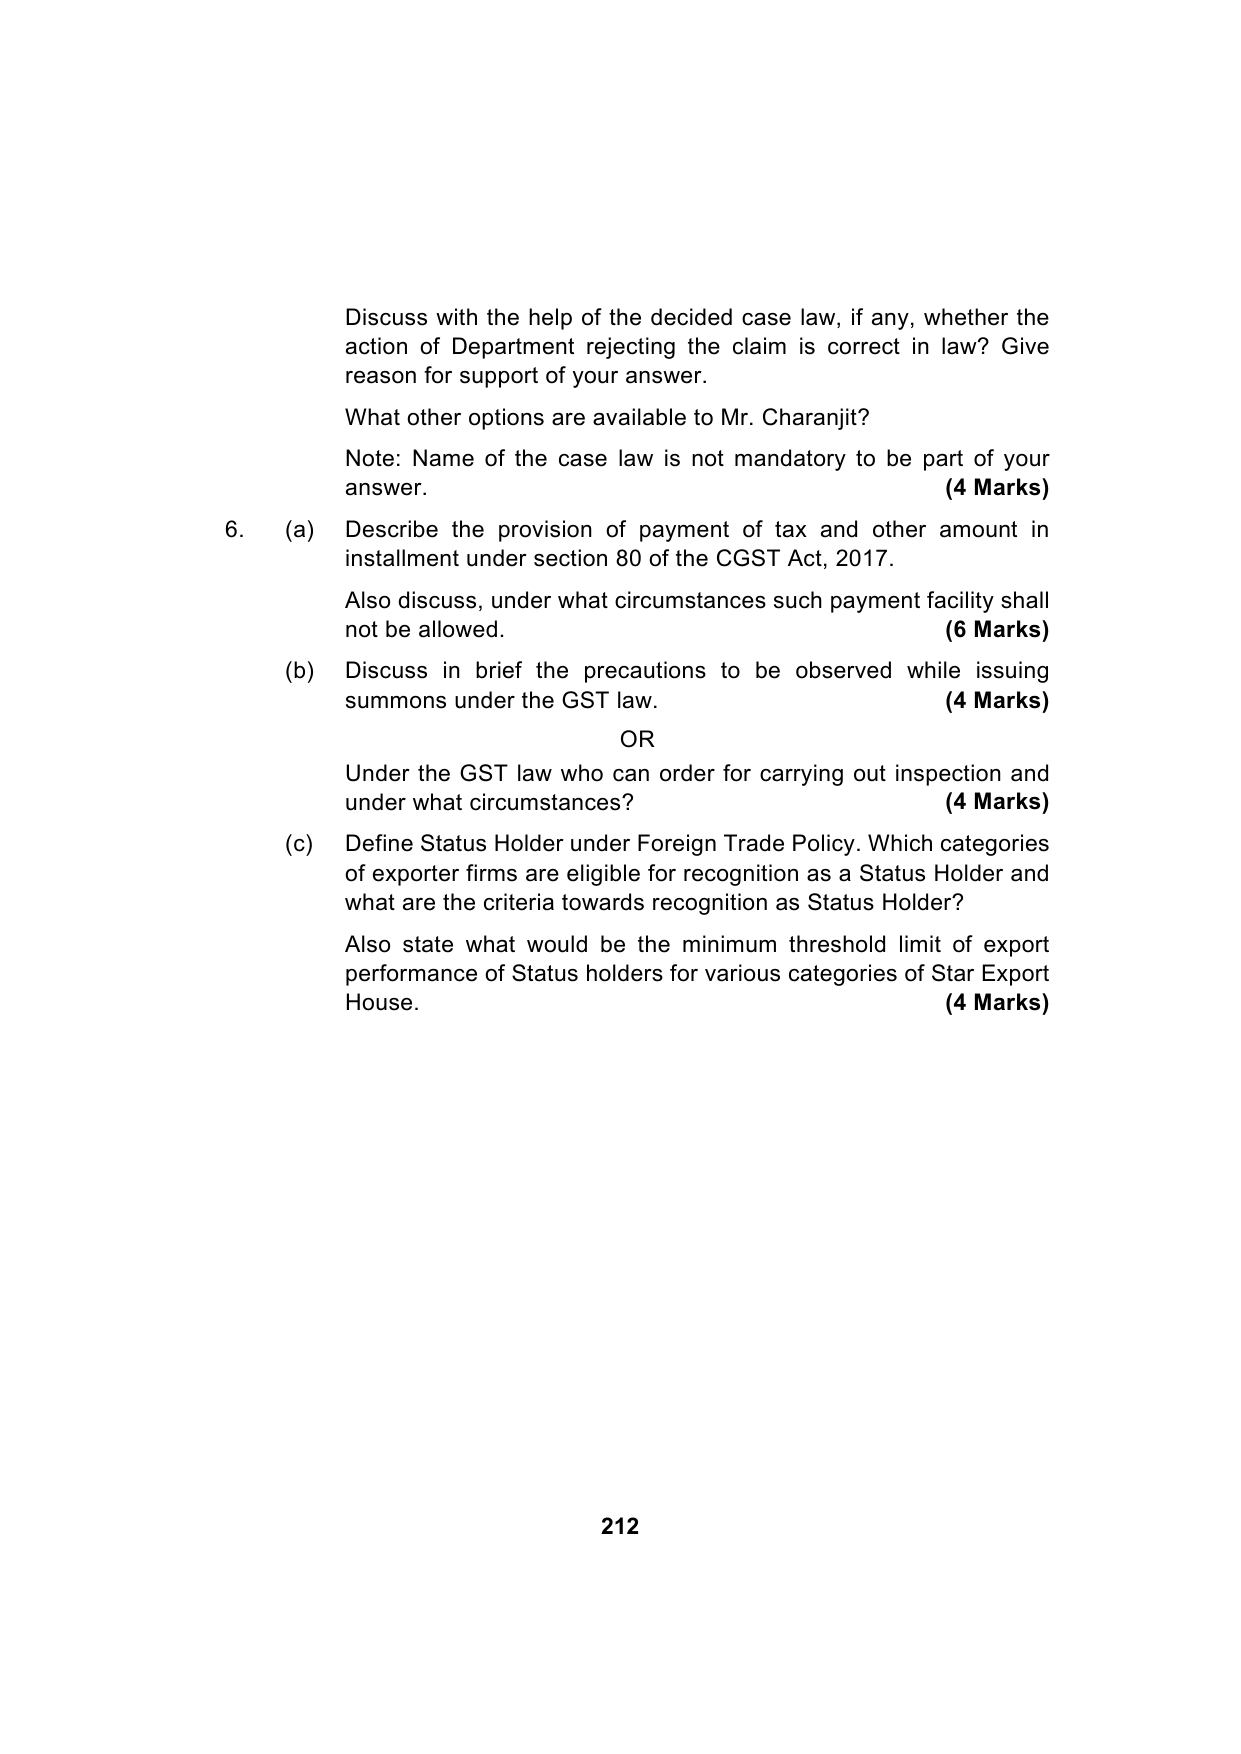
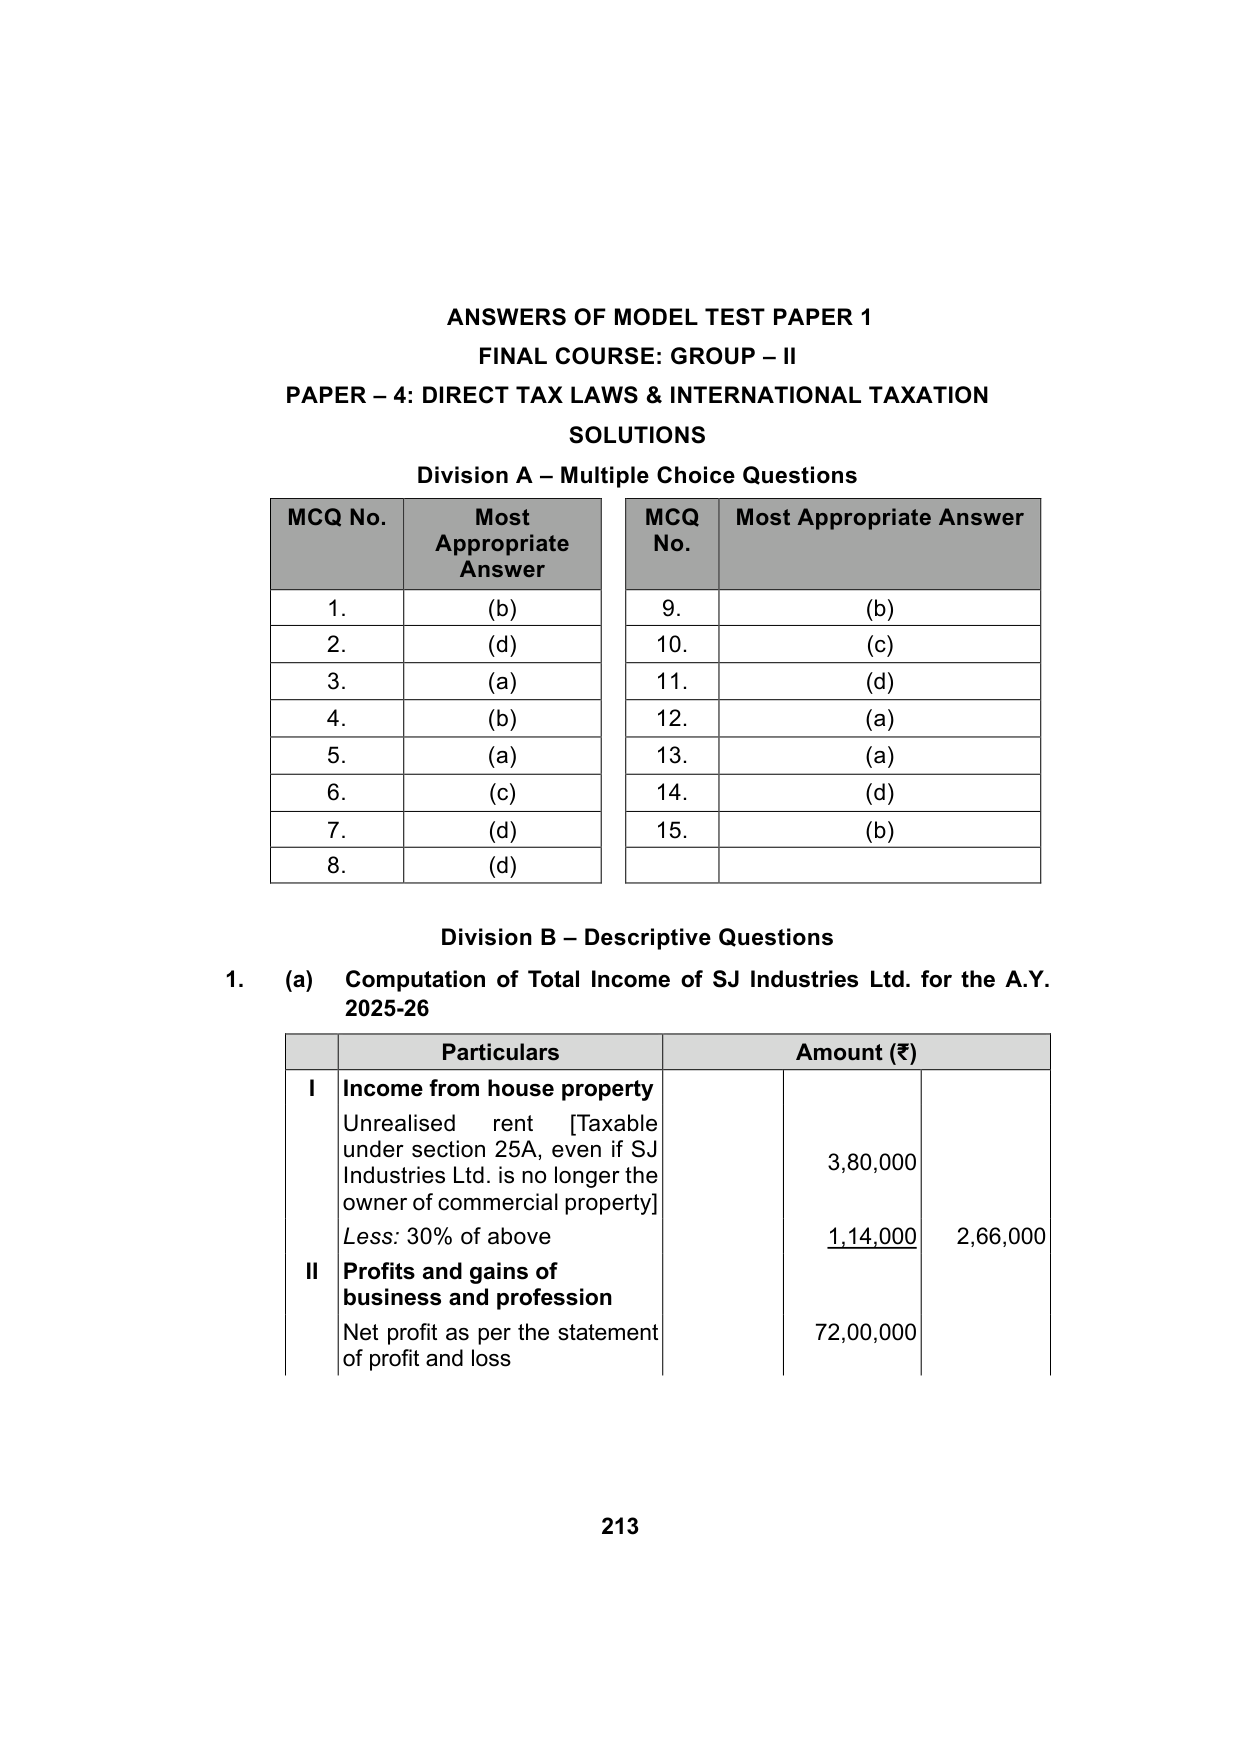
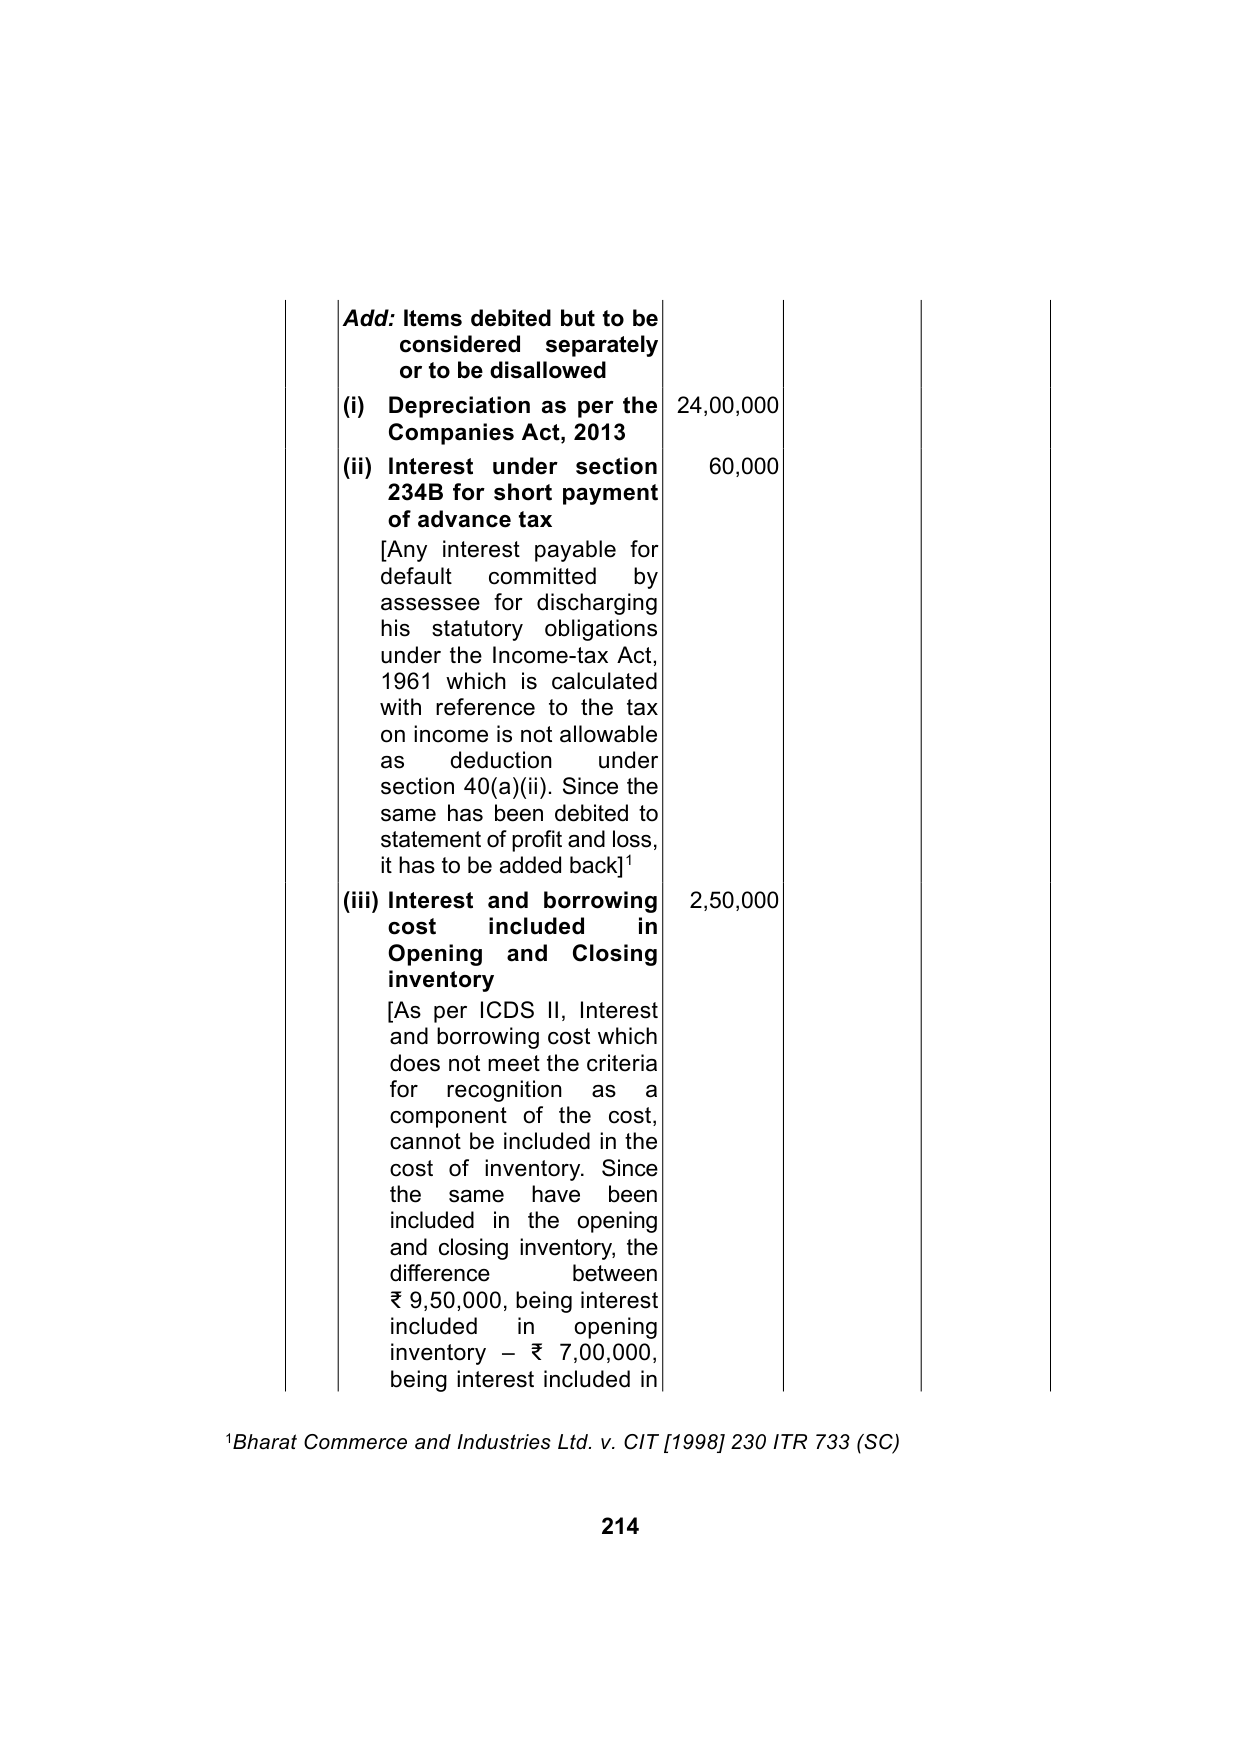
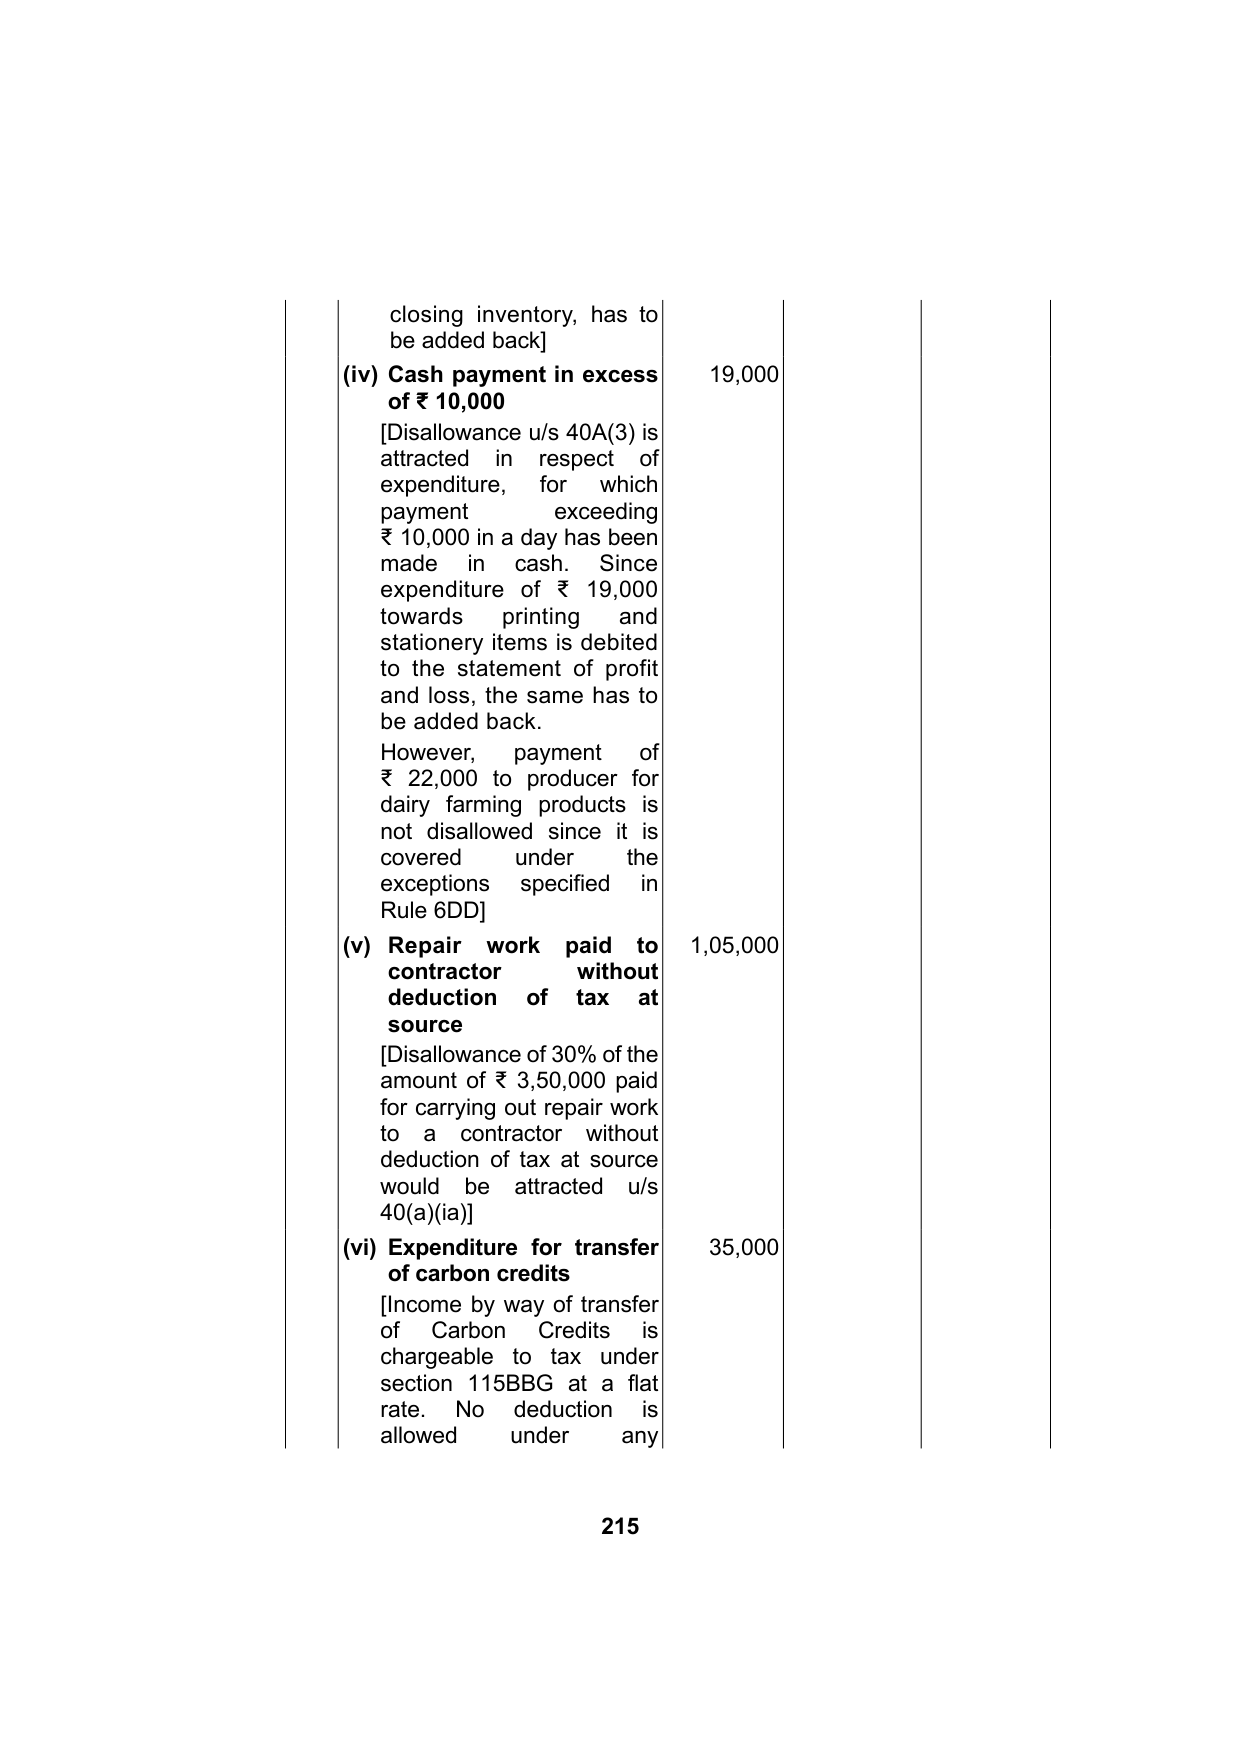
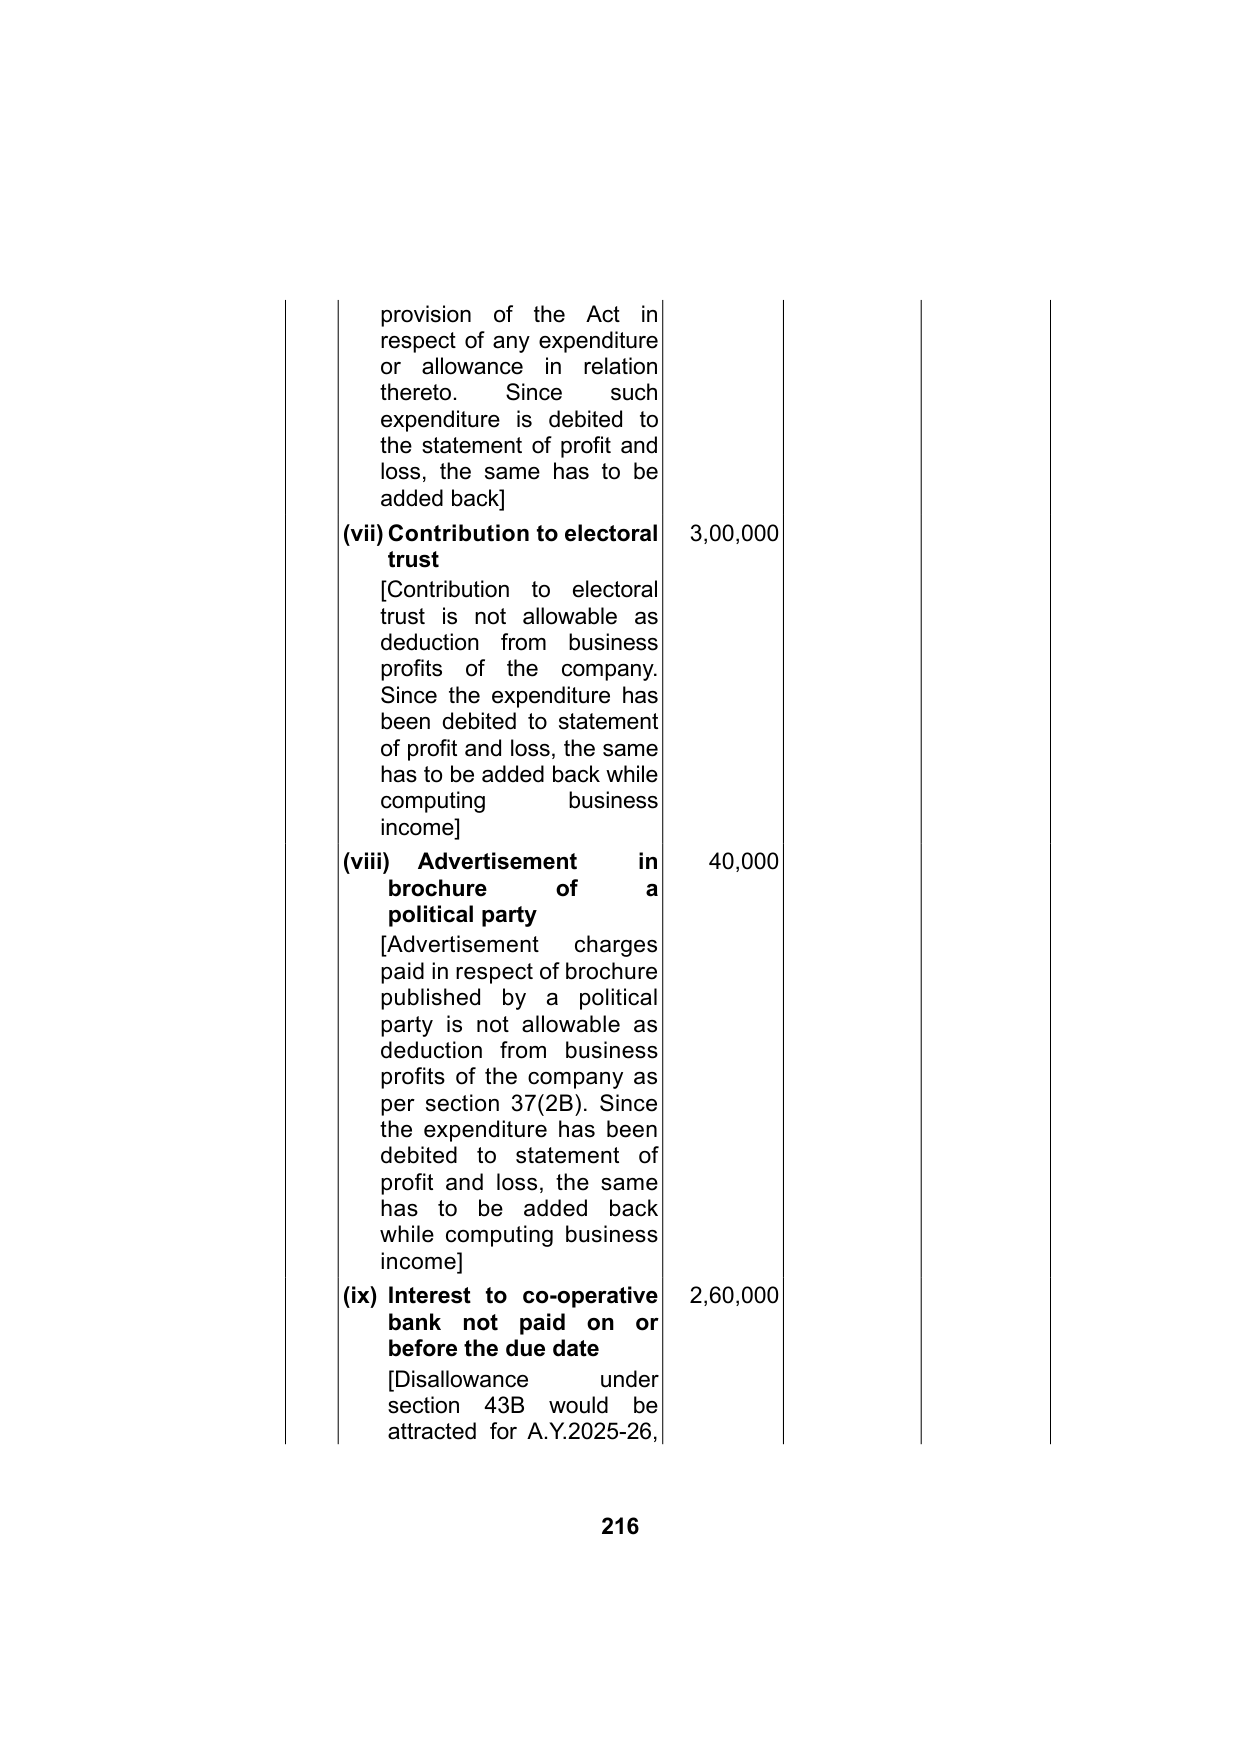
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 1 (100 marks)
Question
Answer
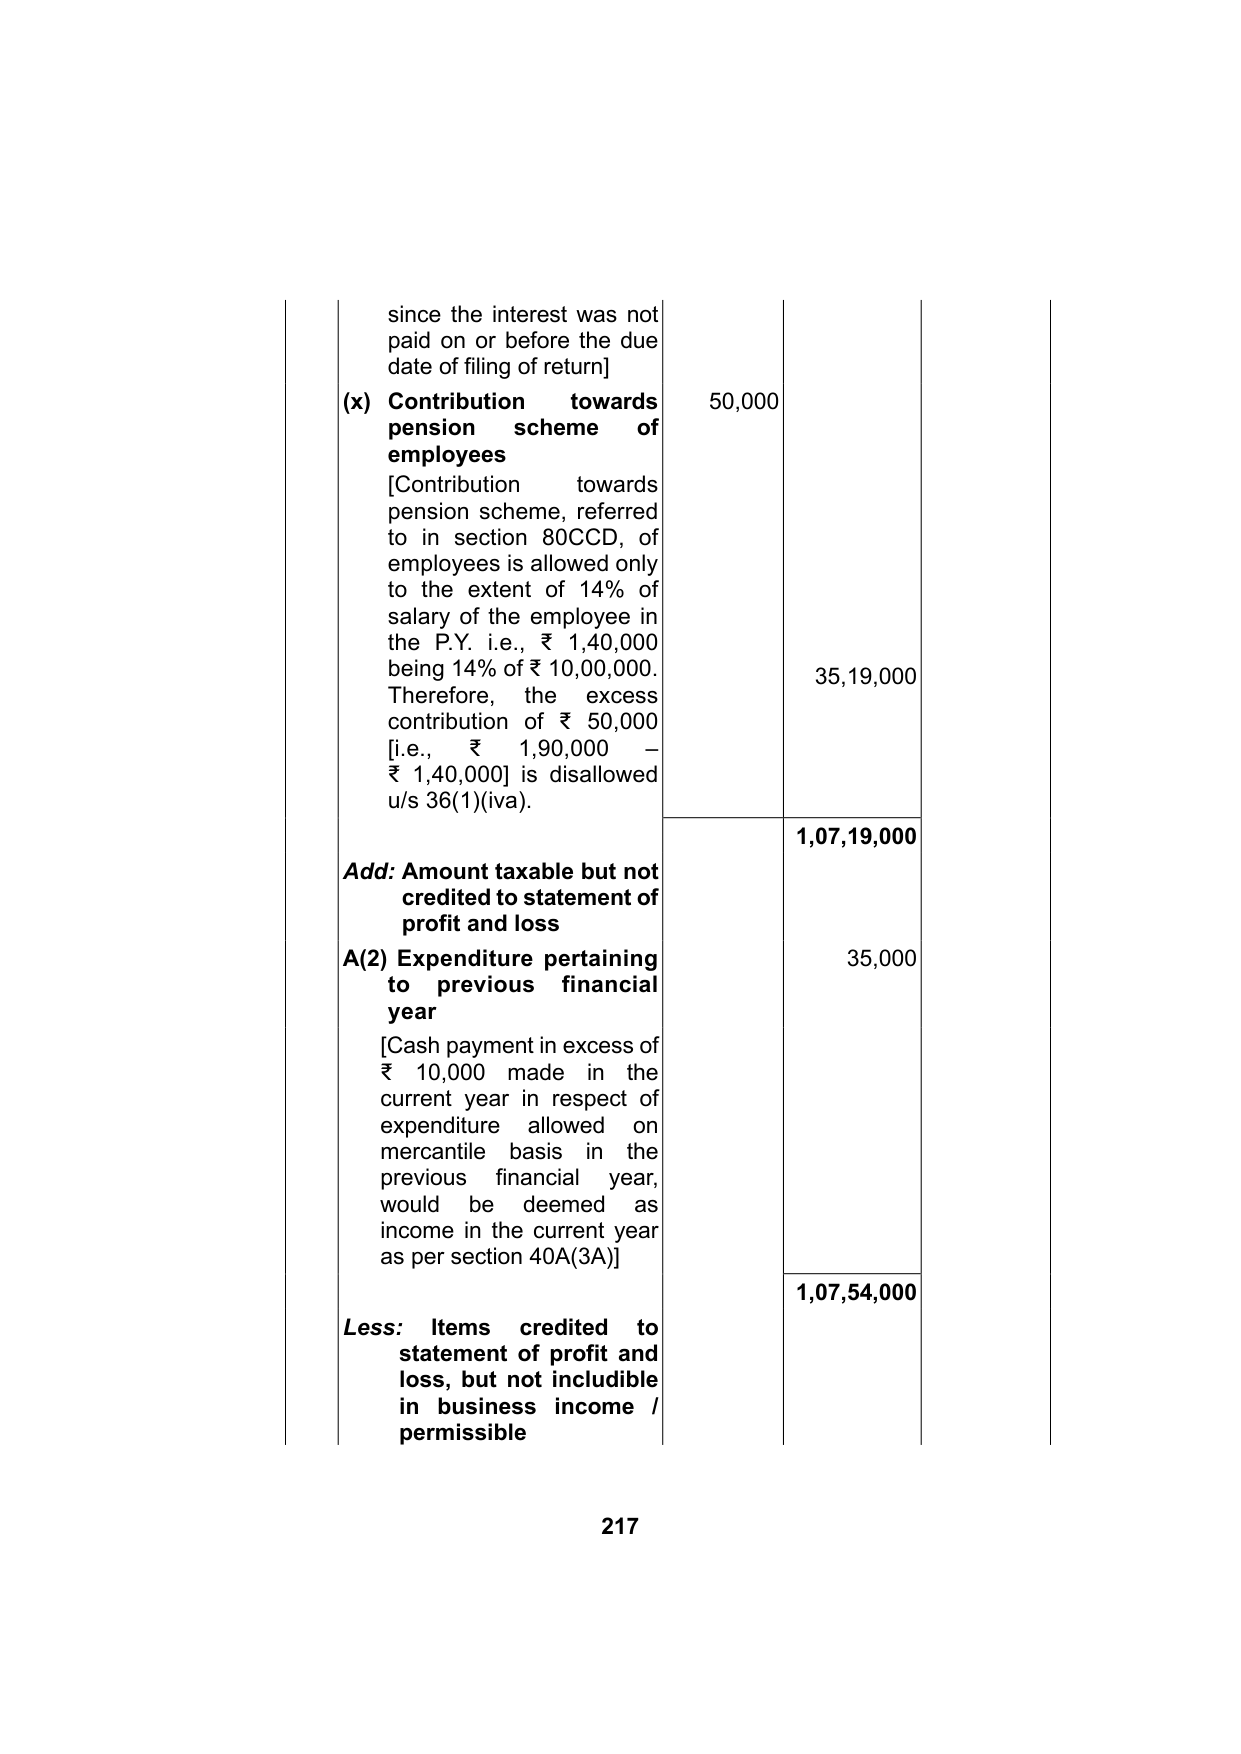
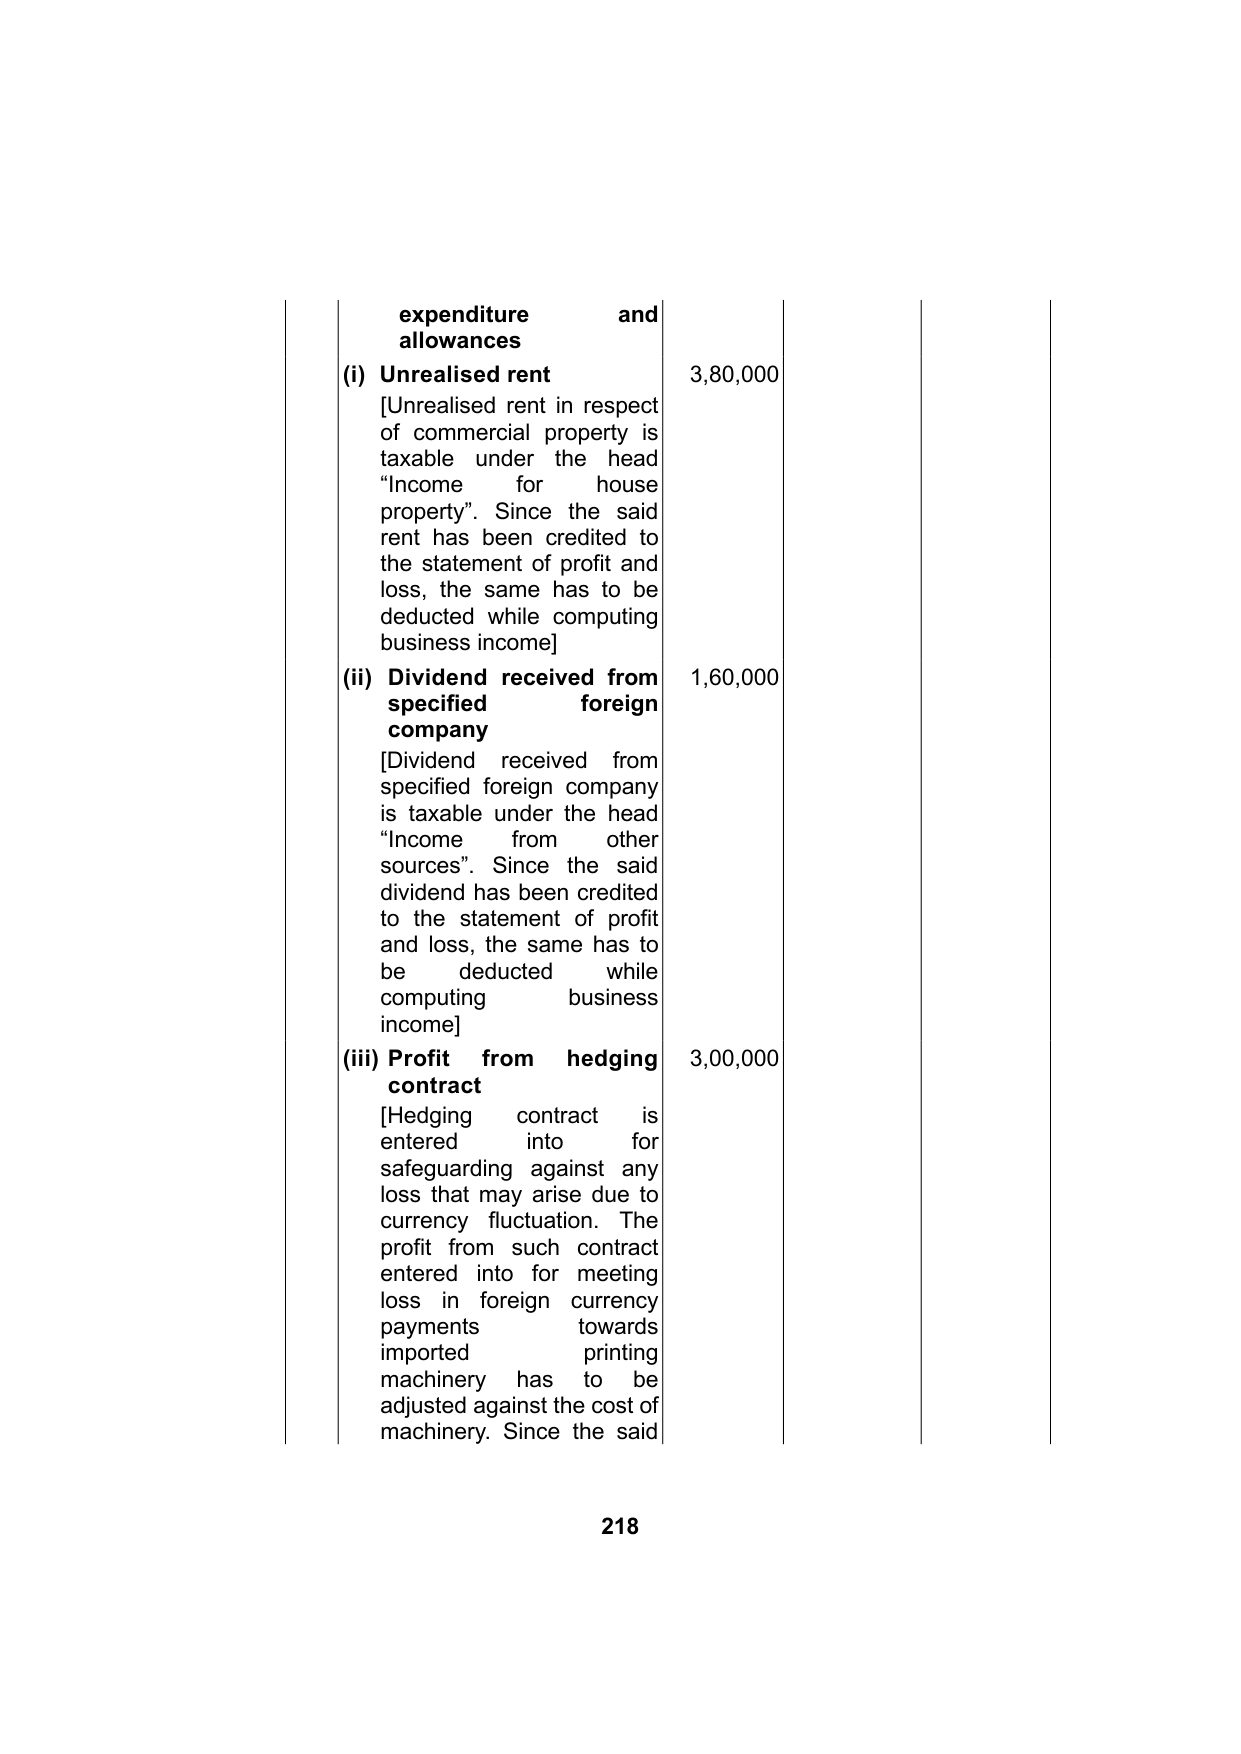
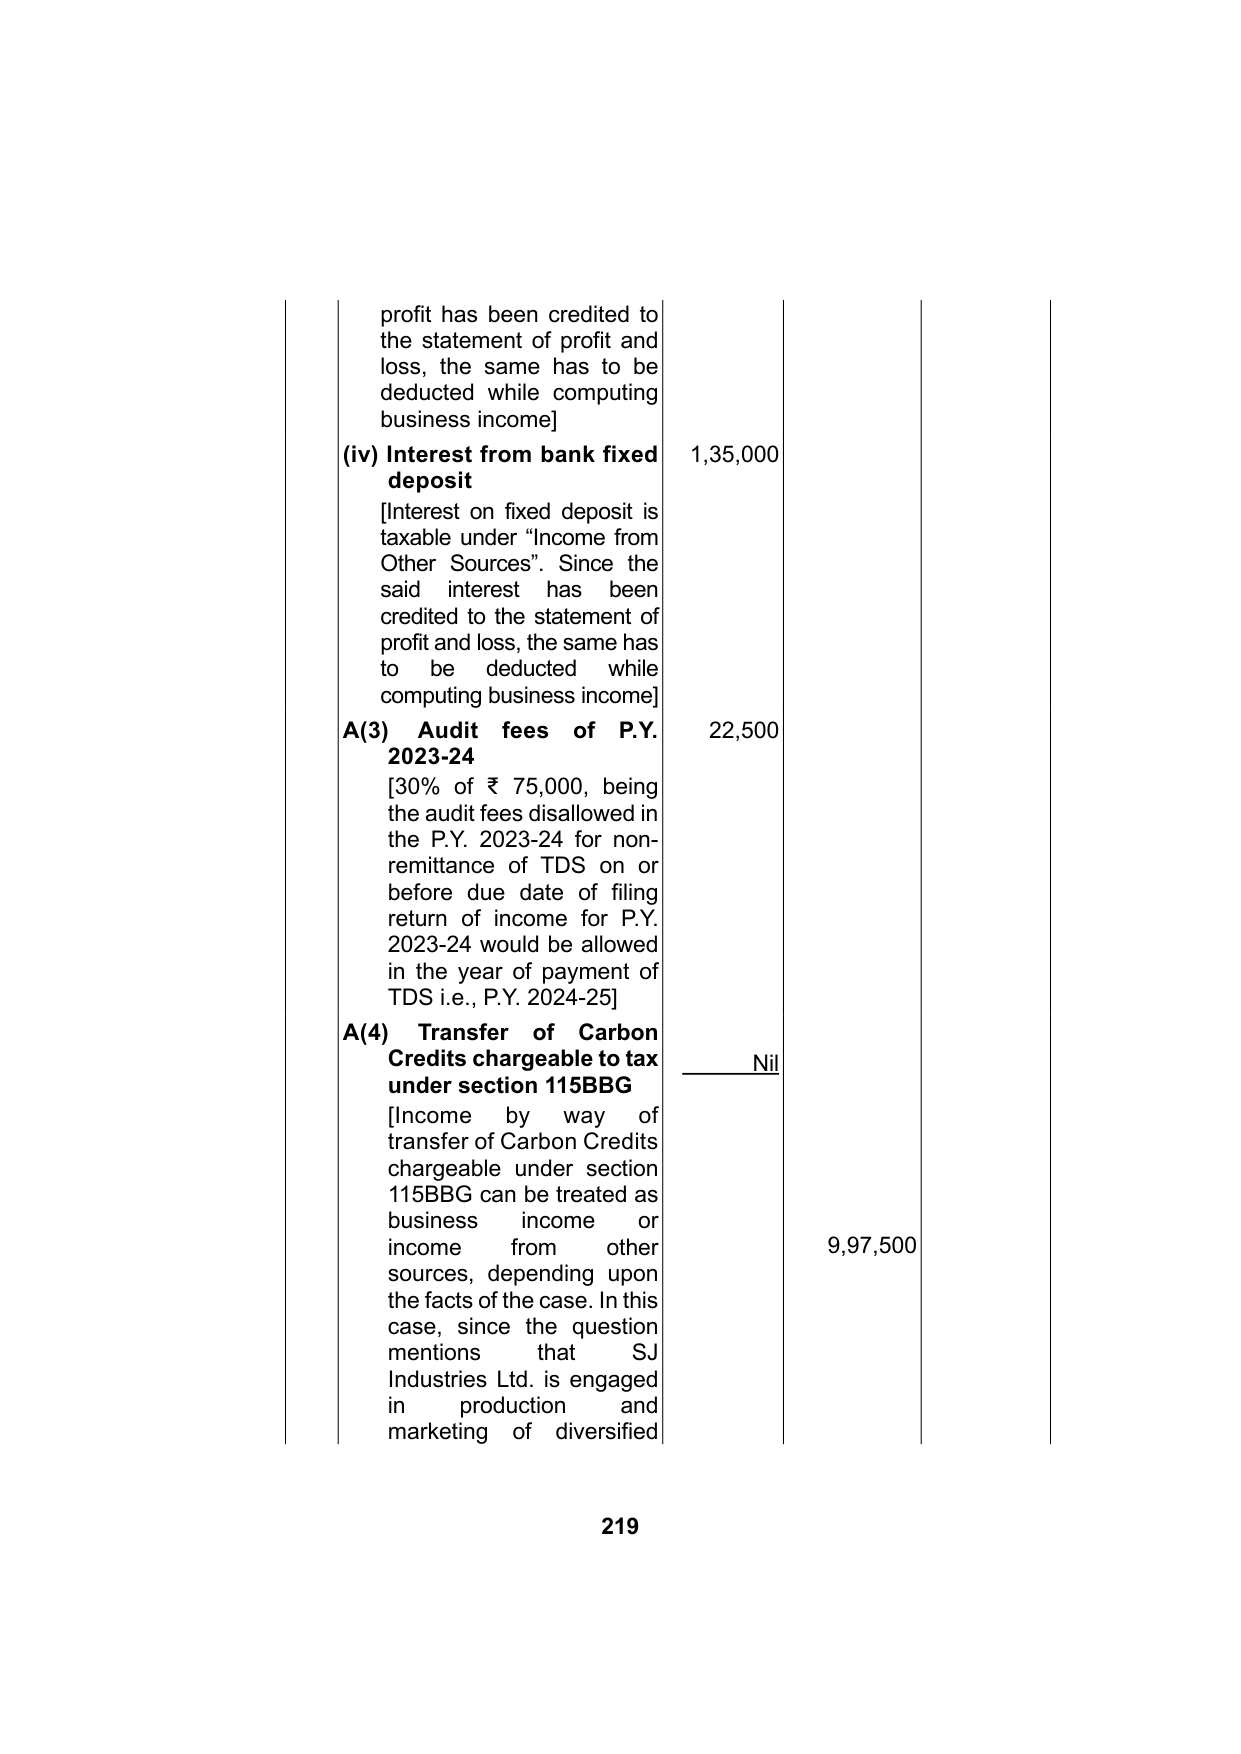
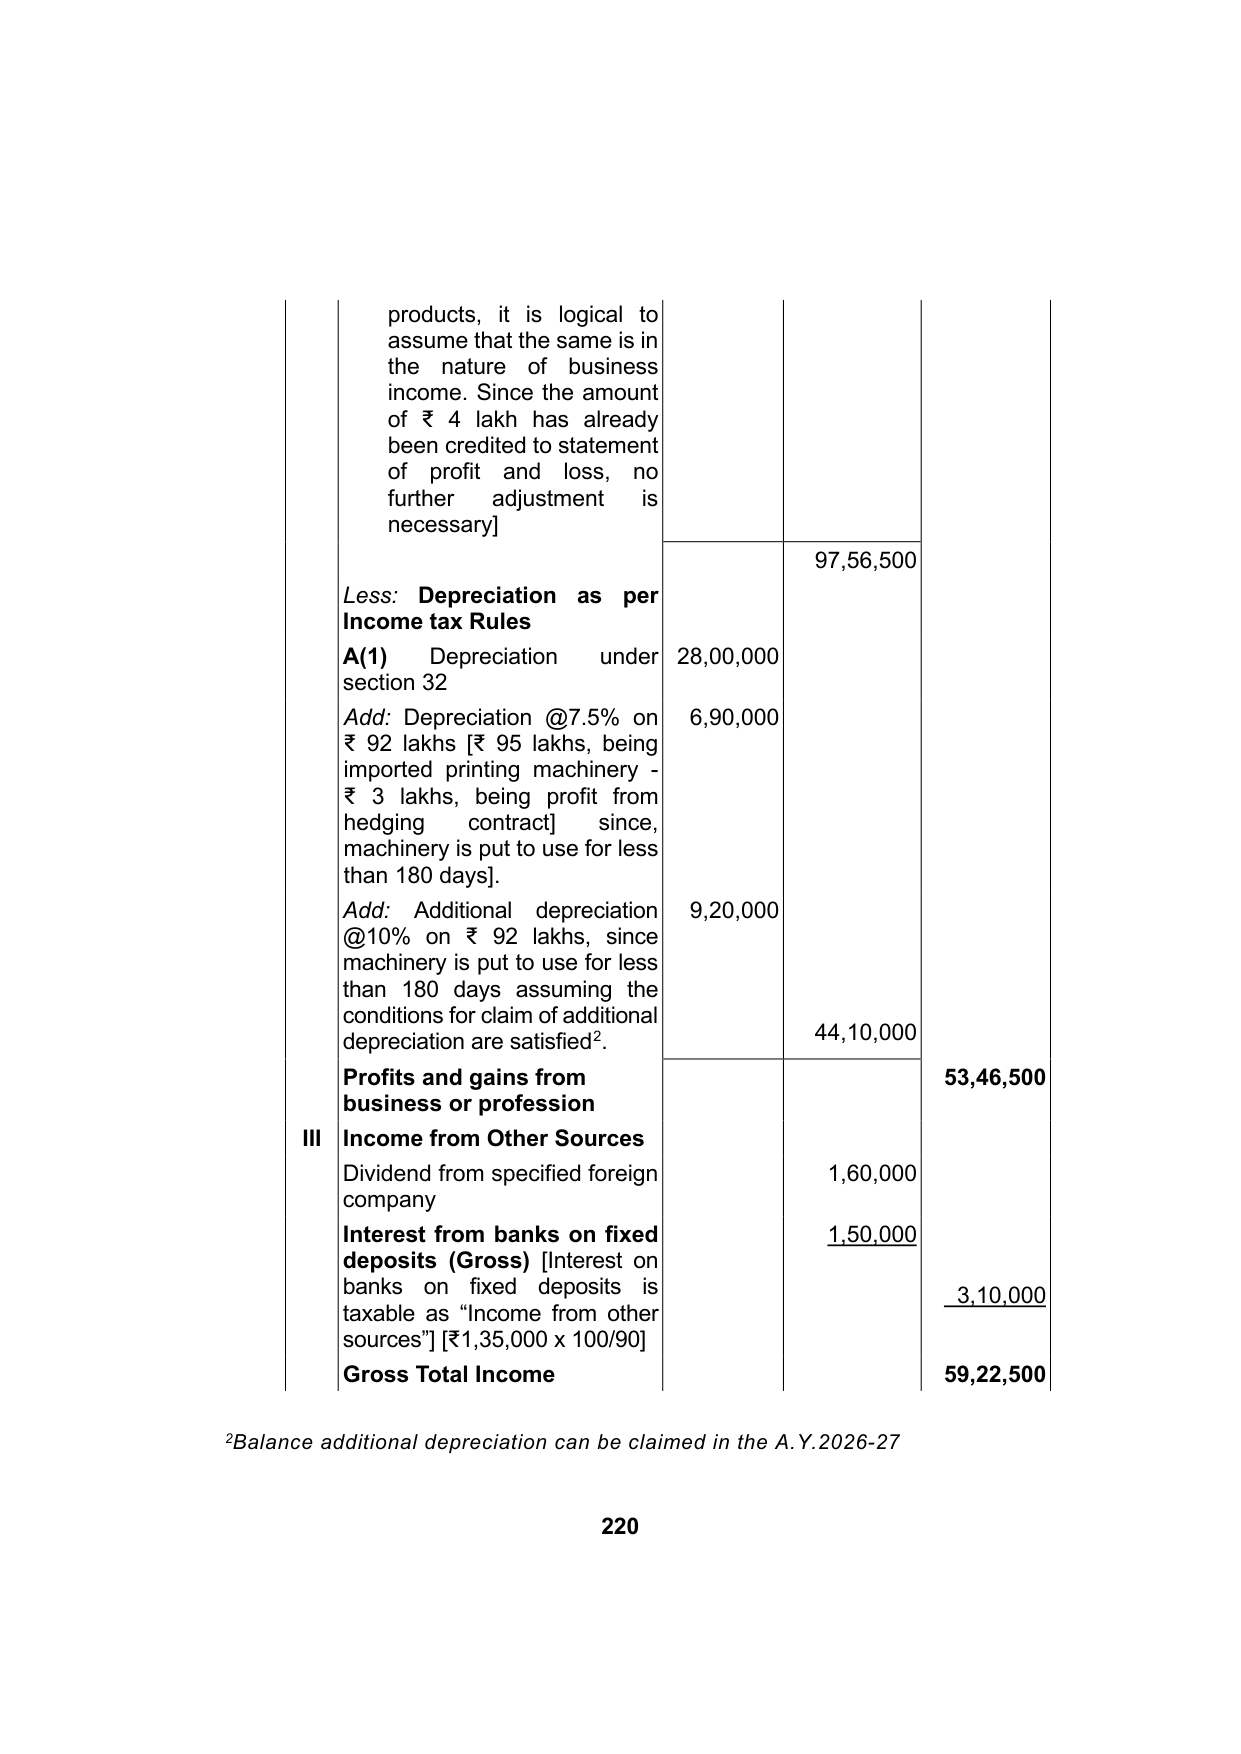
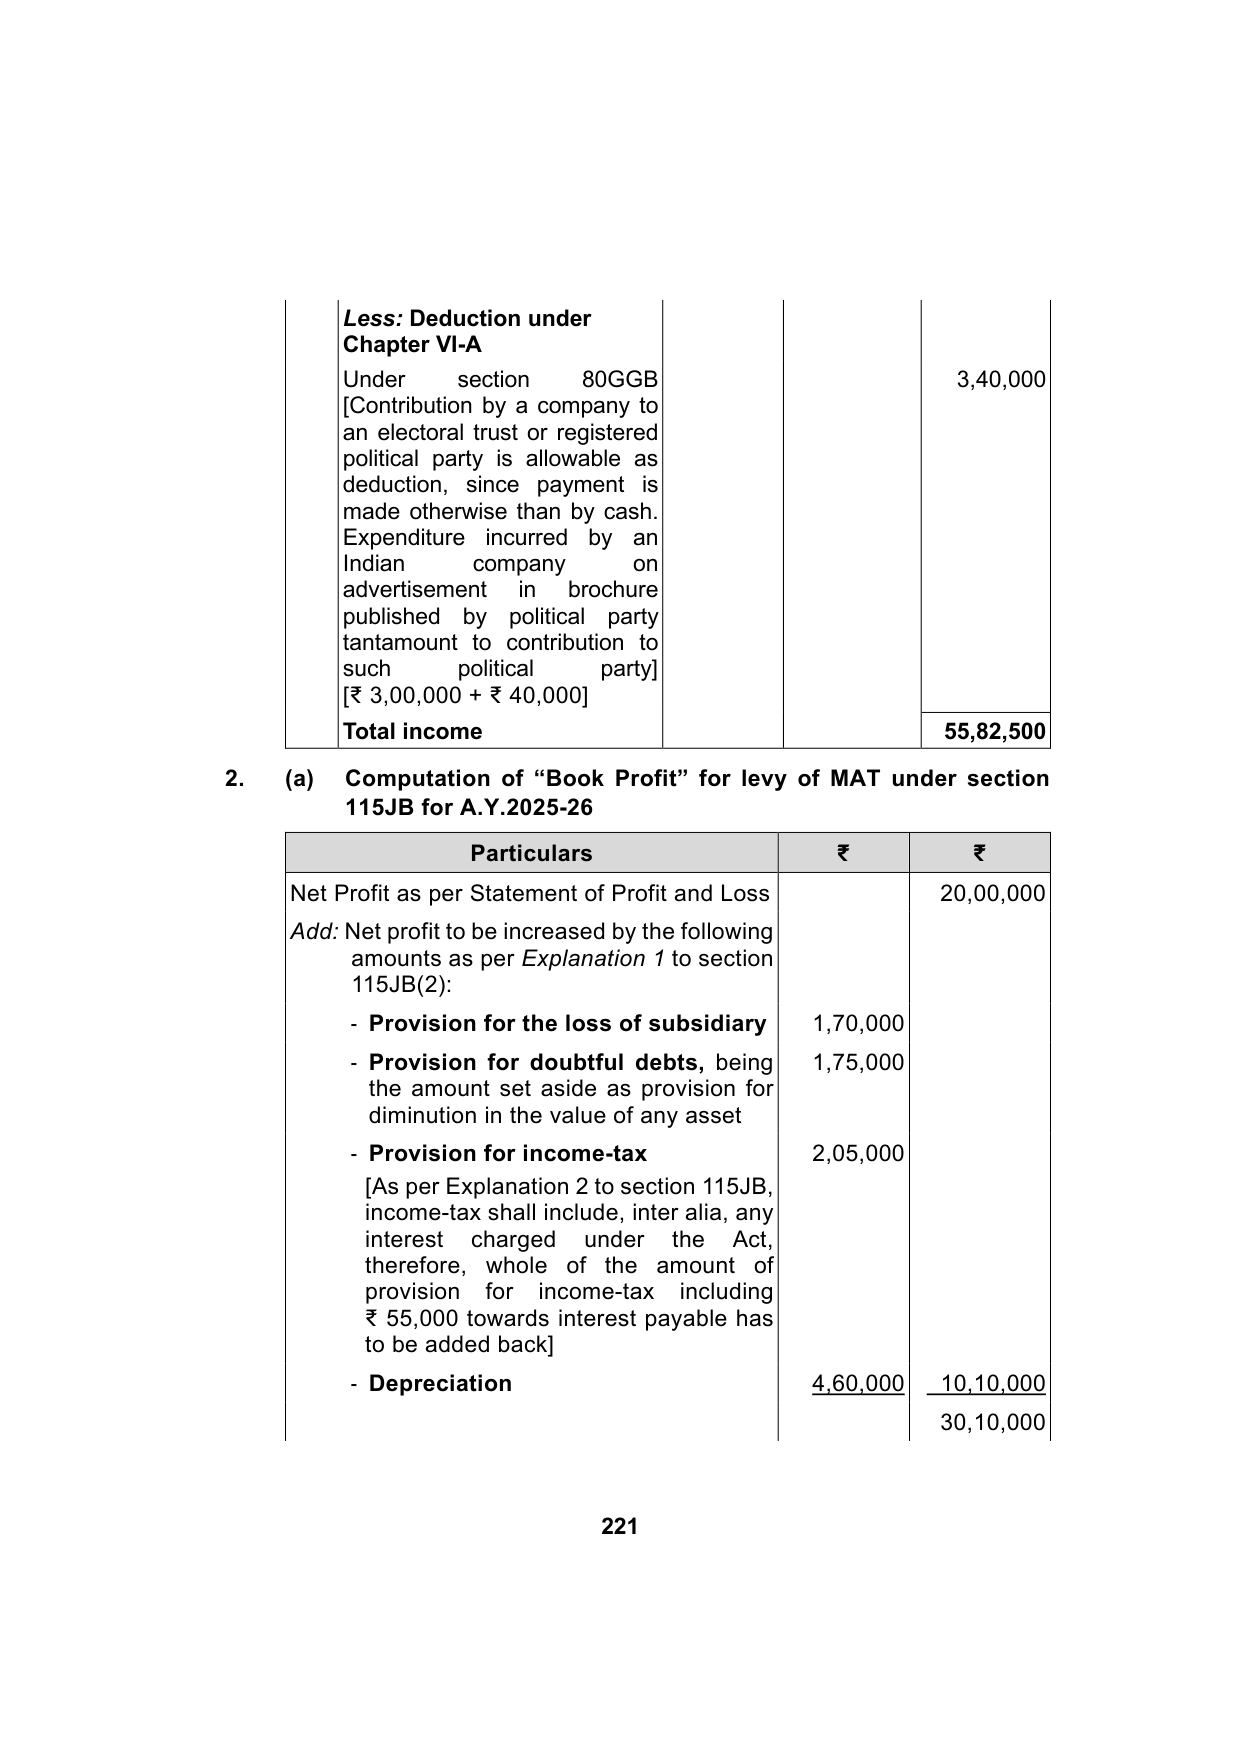
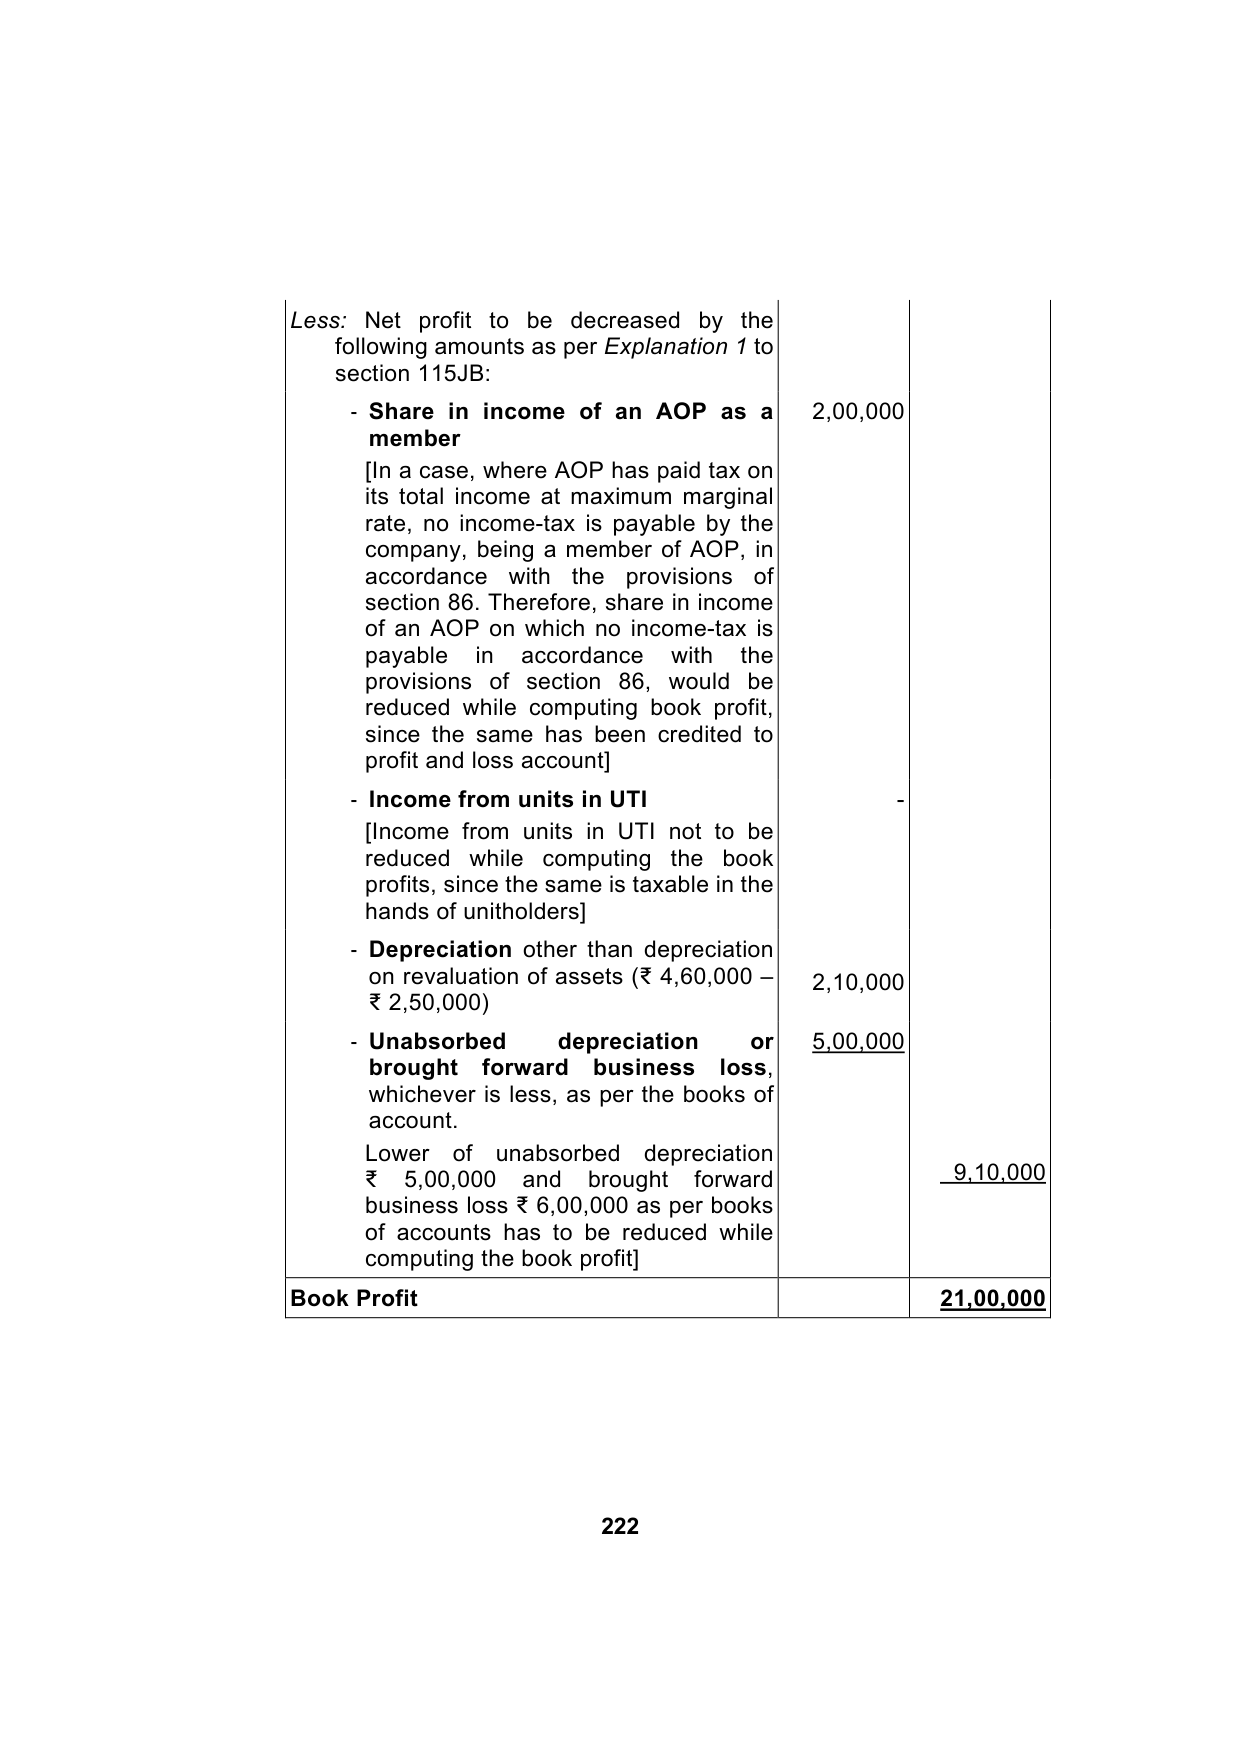
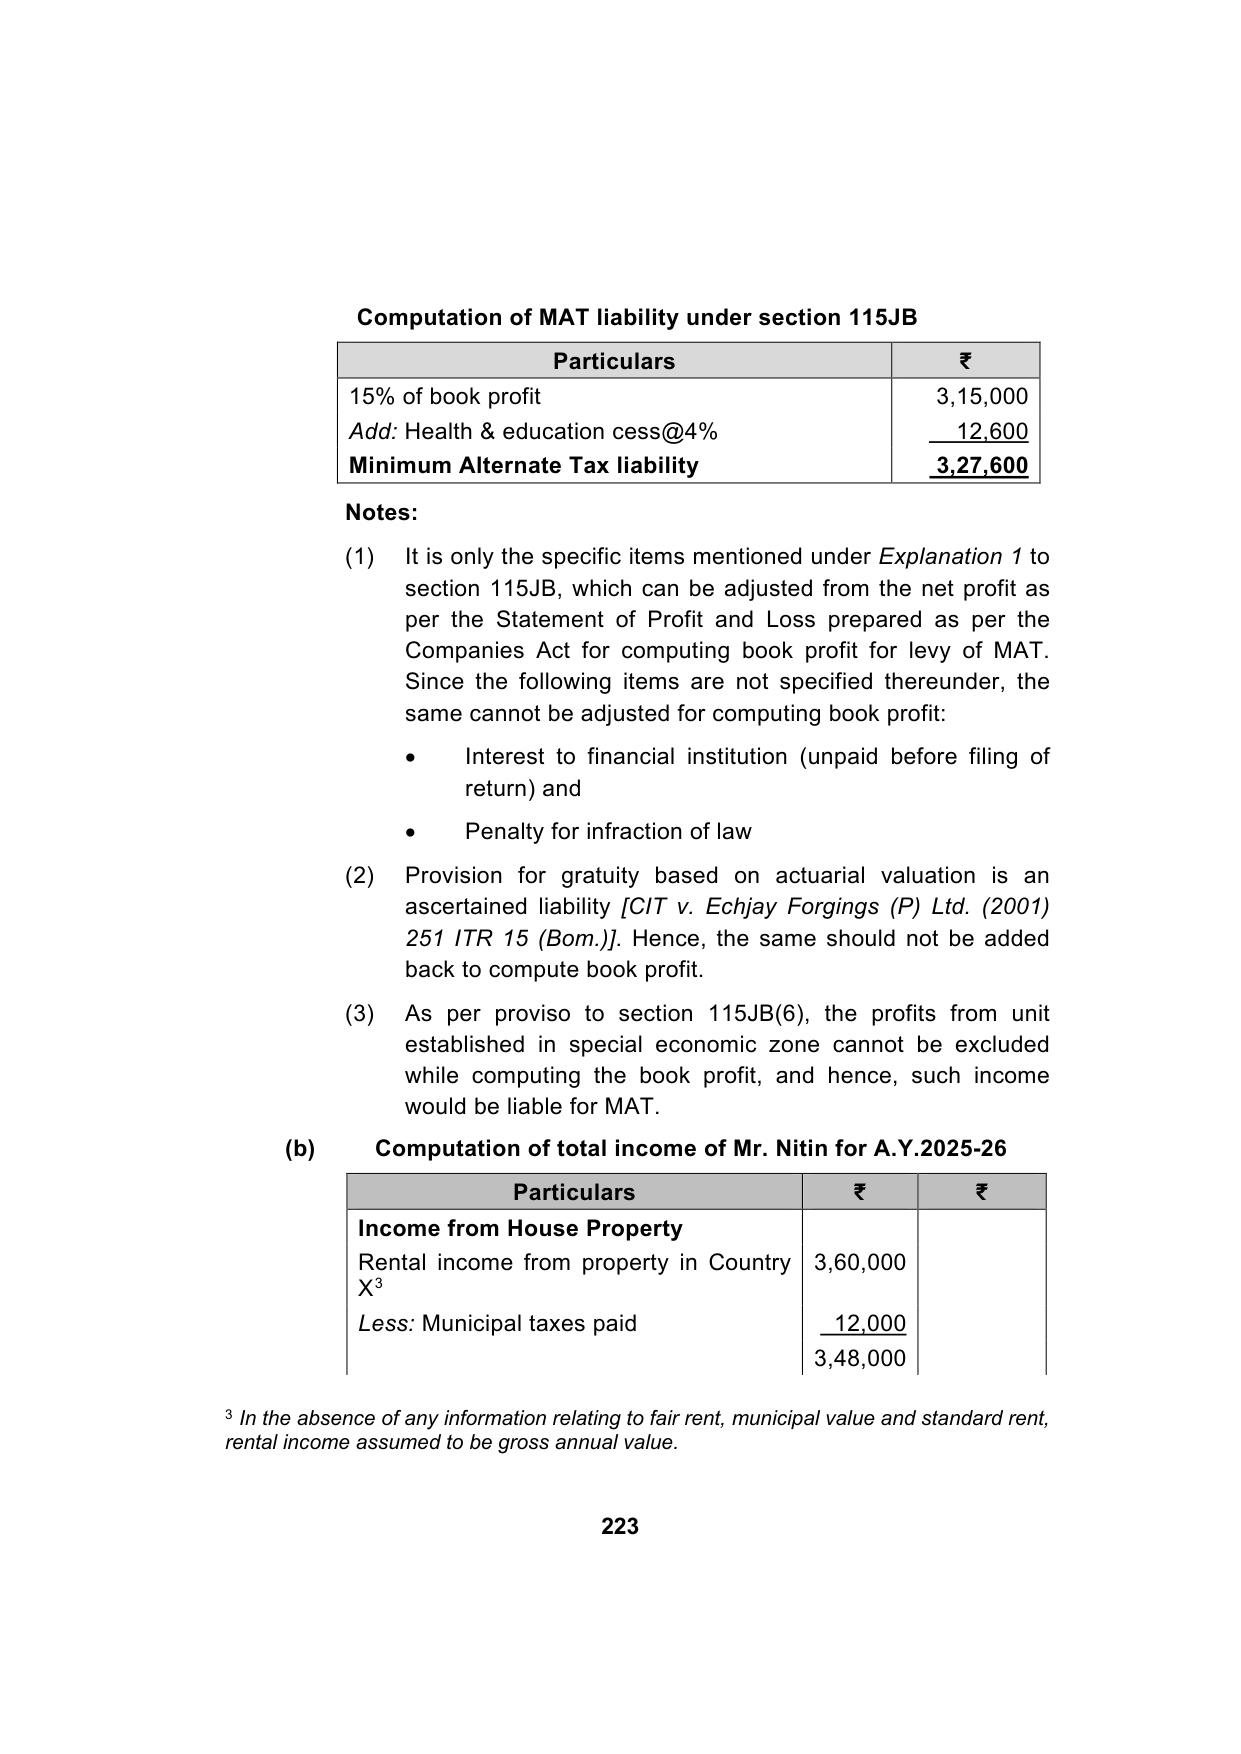
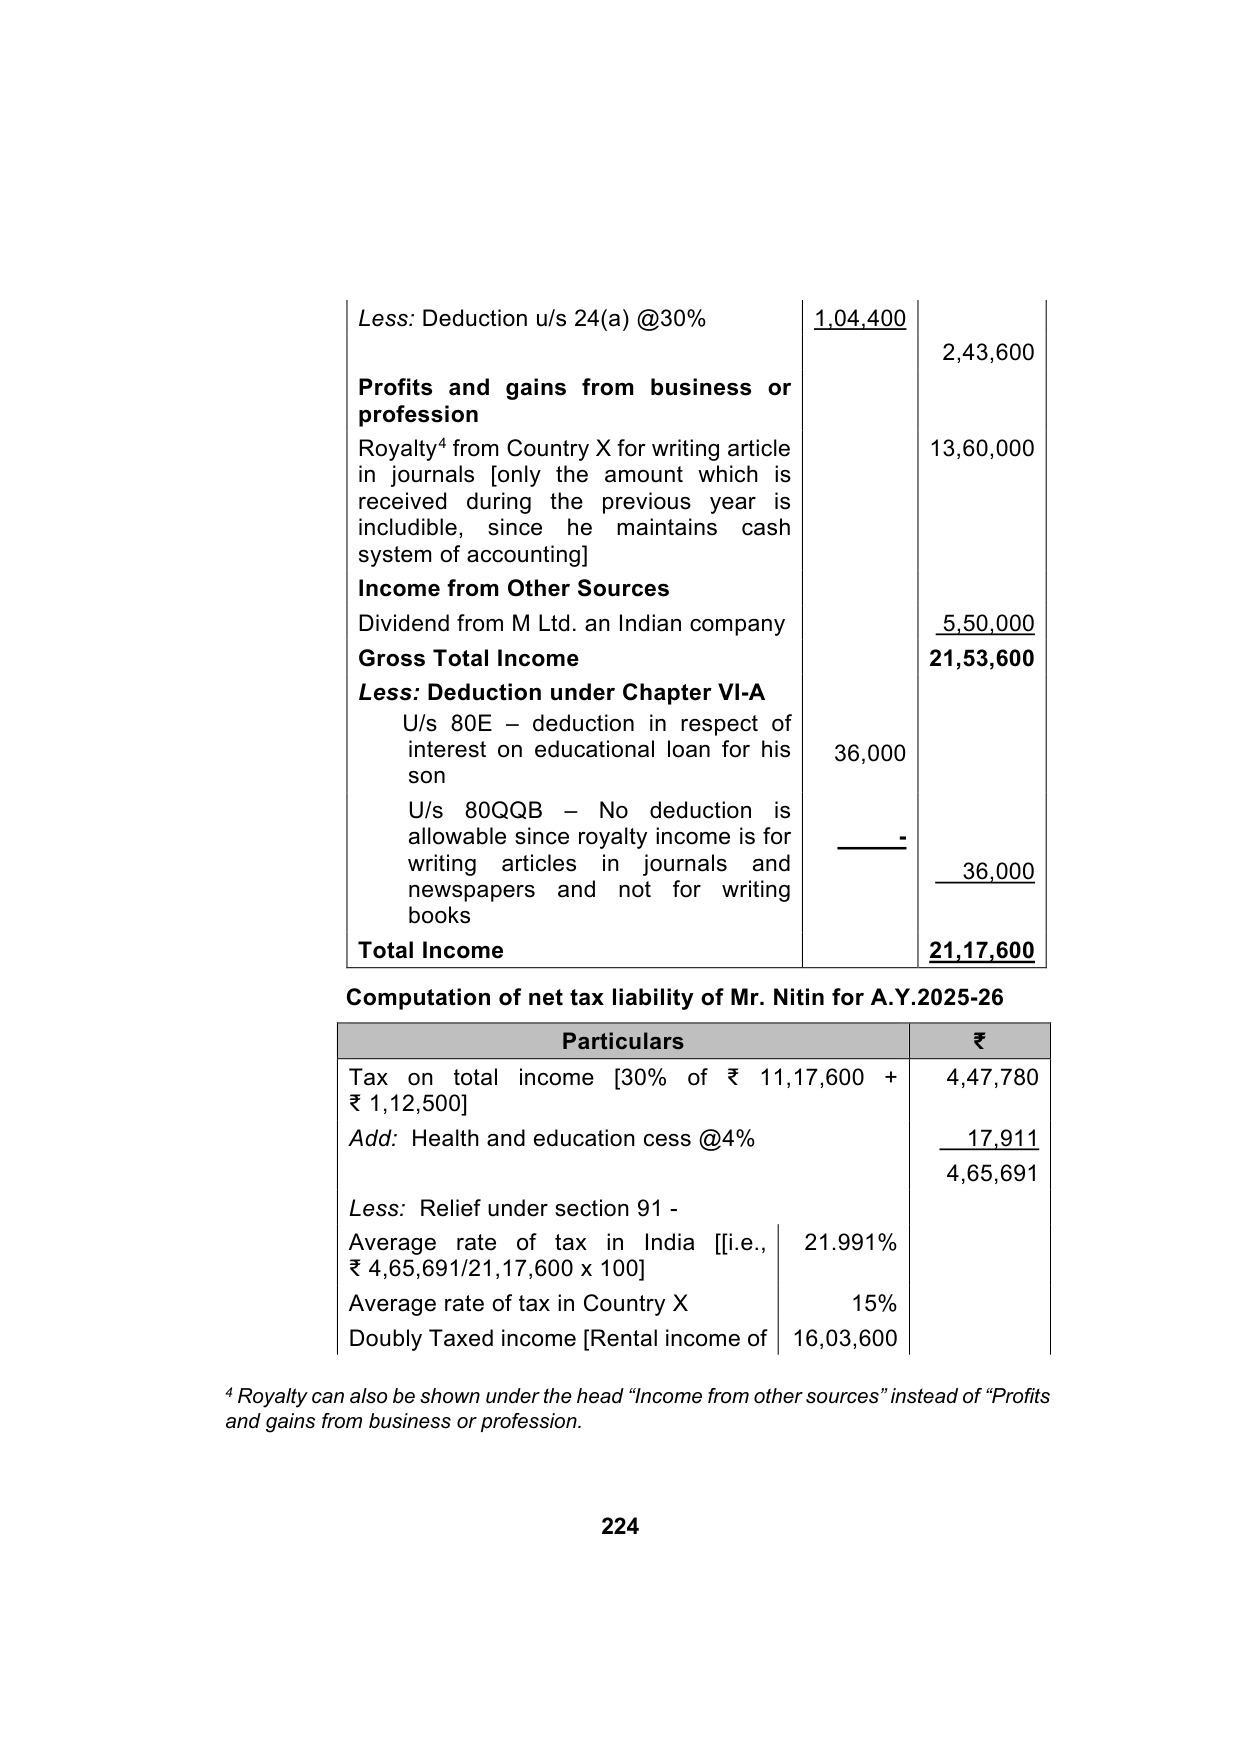
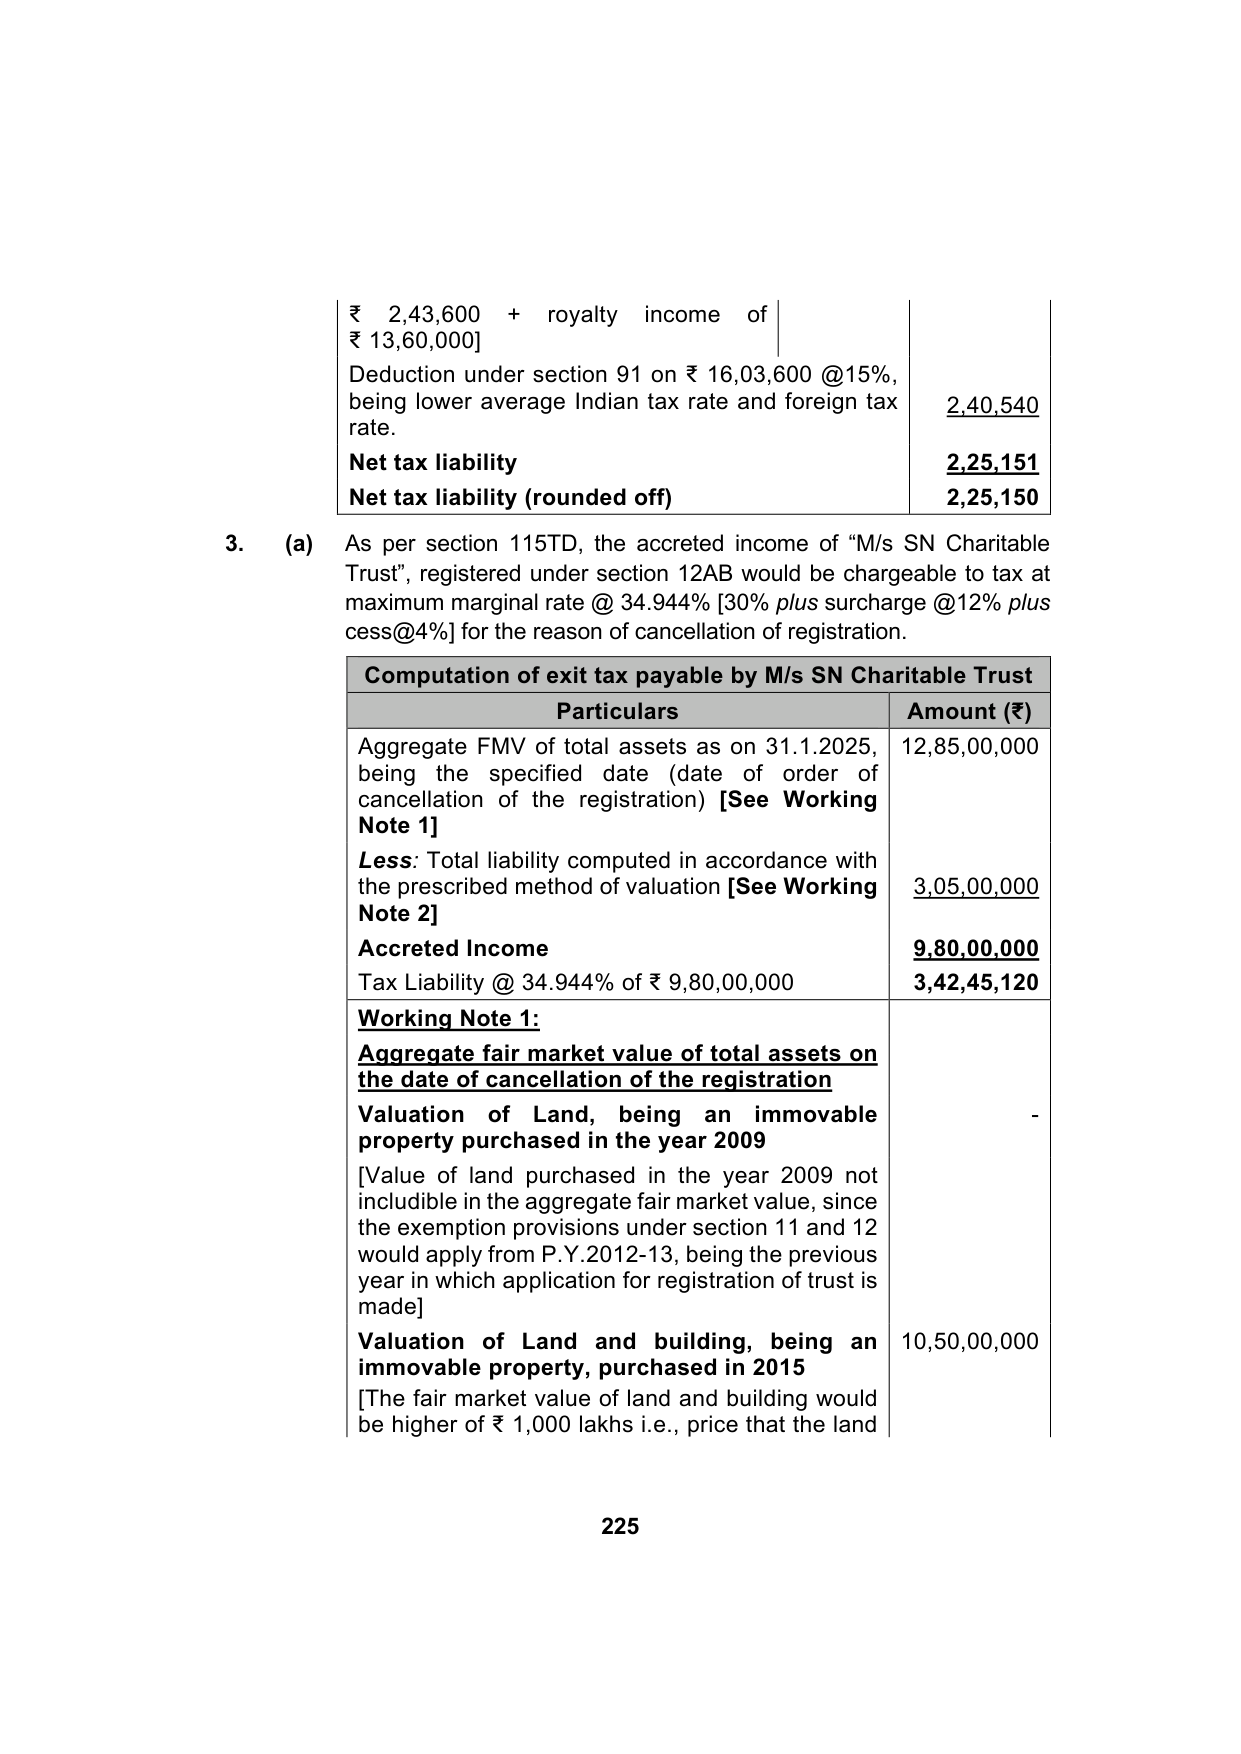
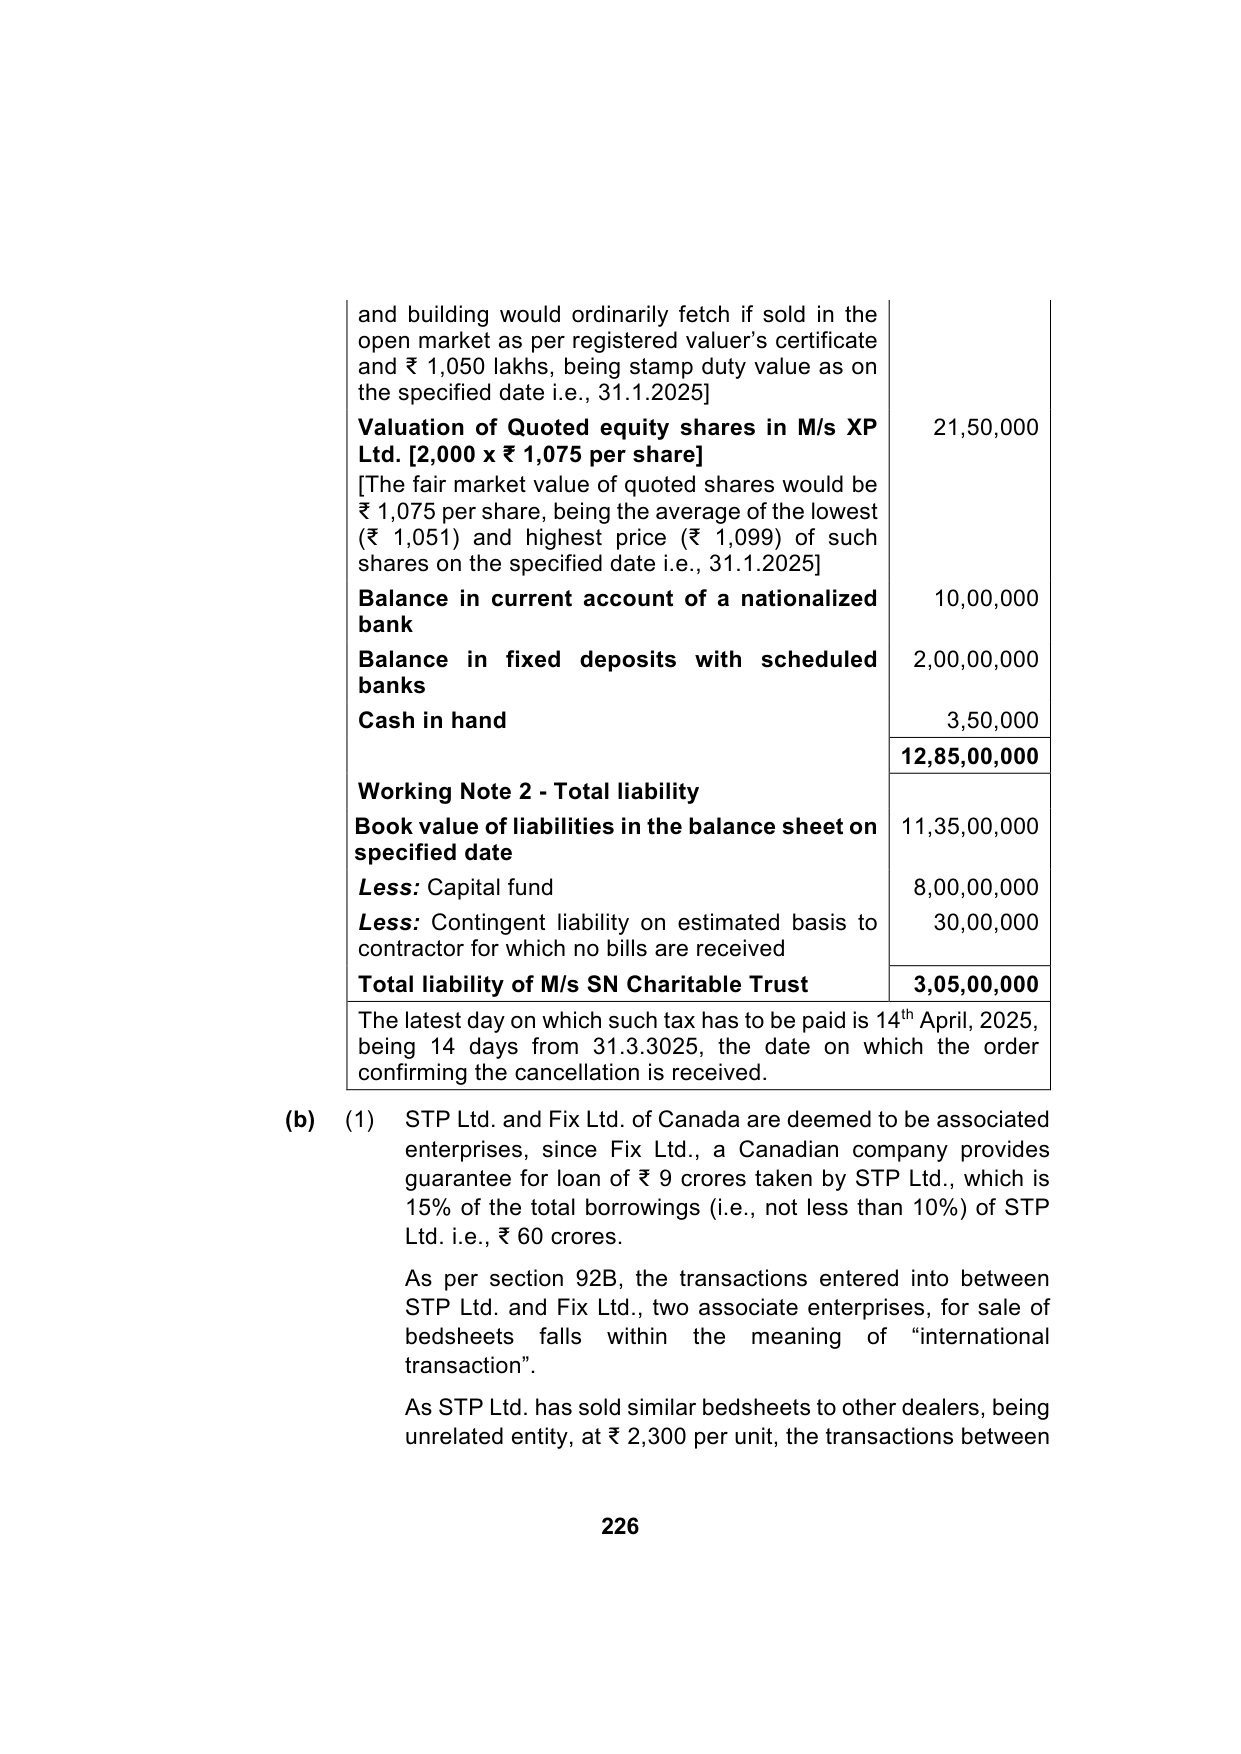
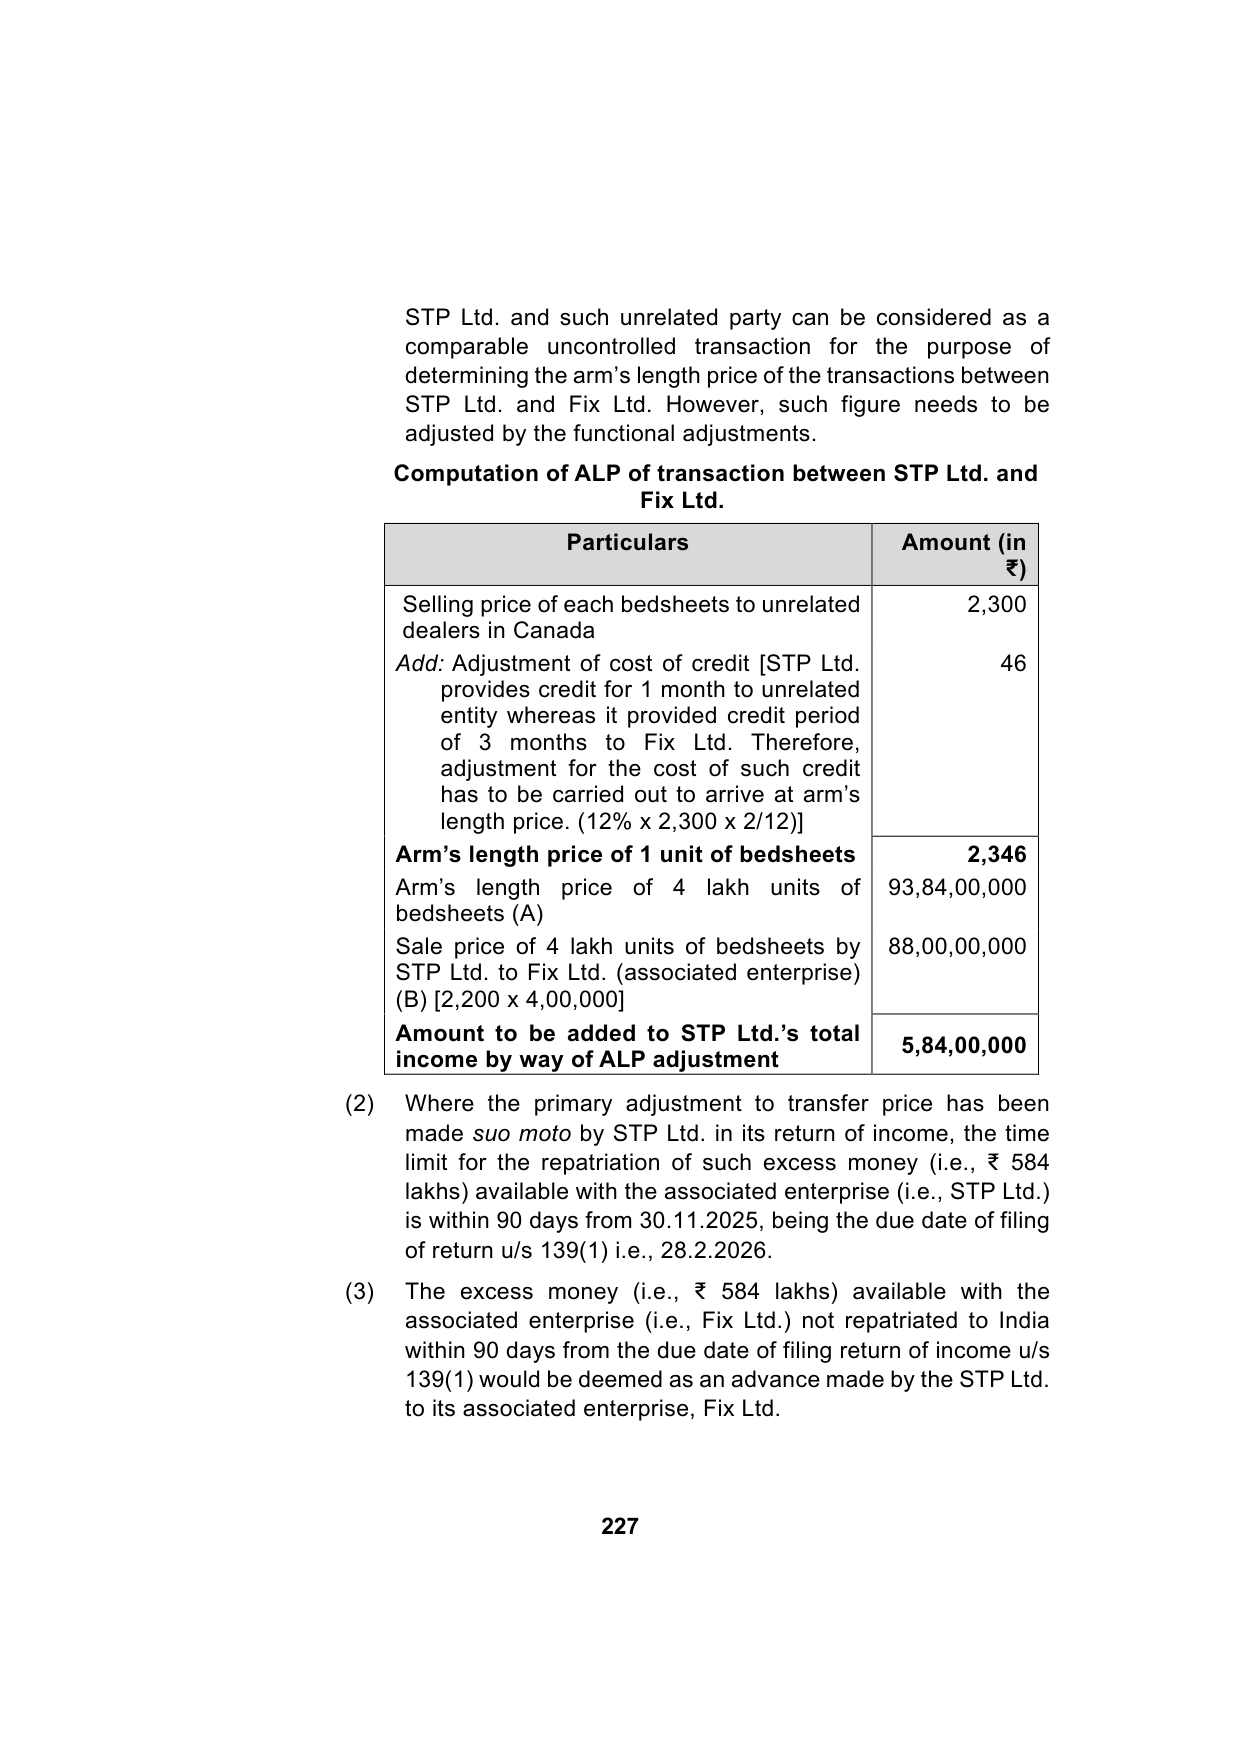
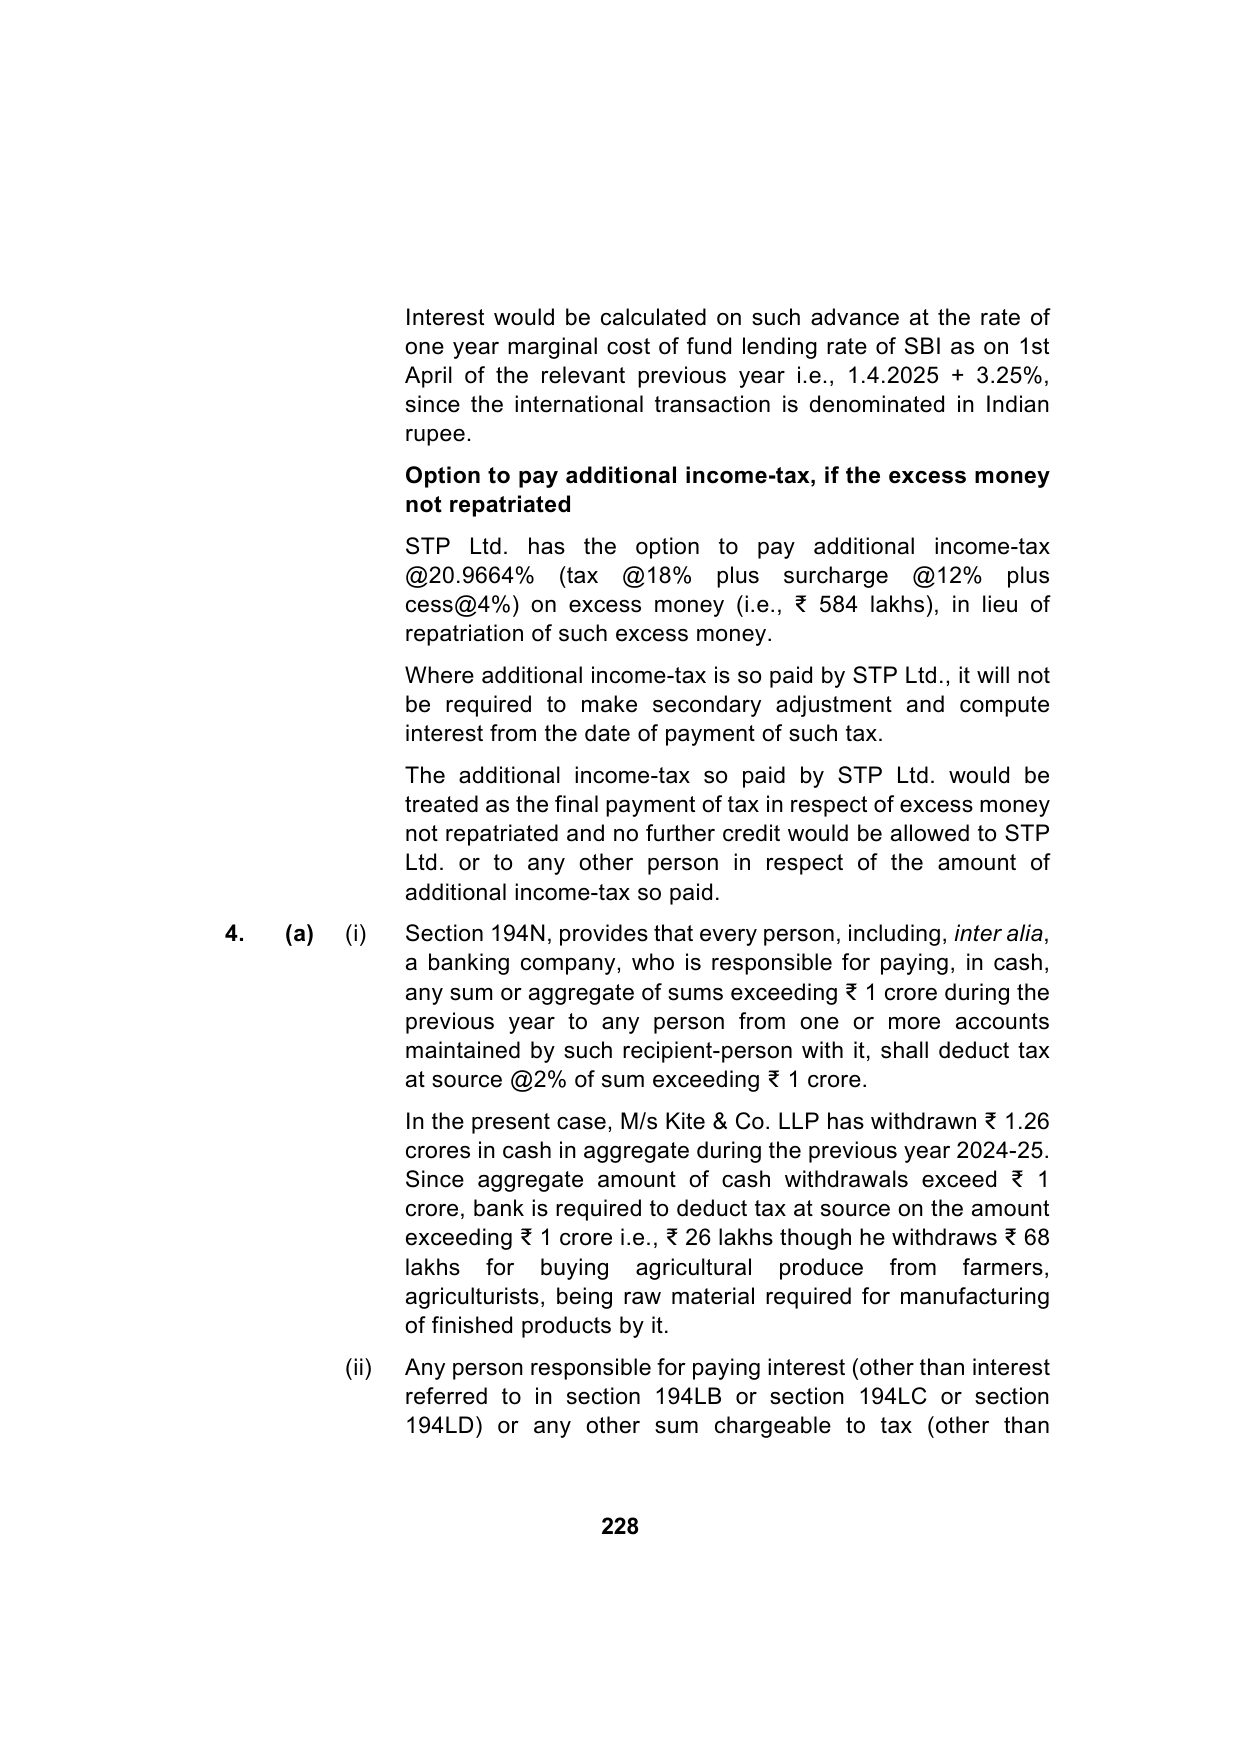
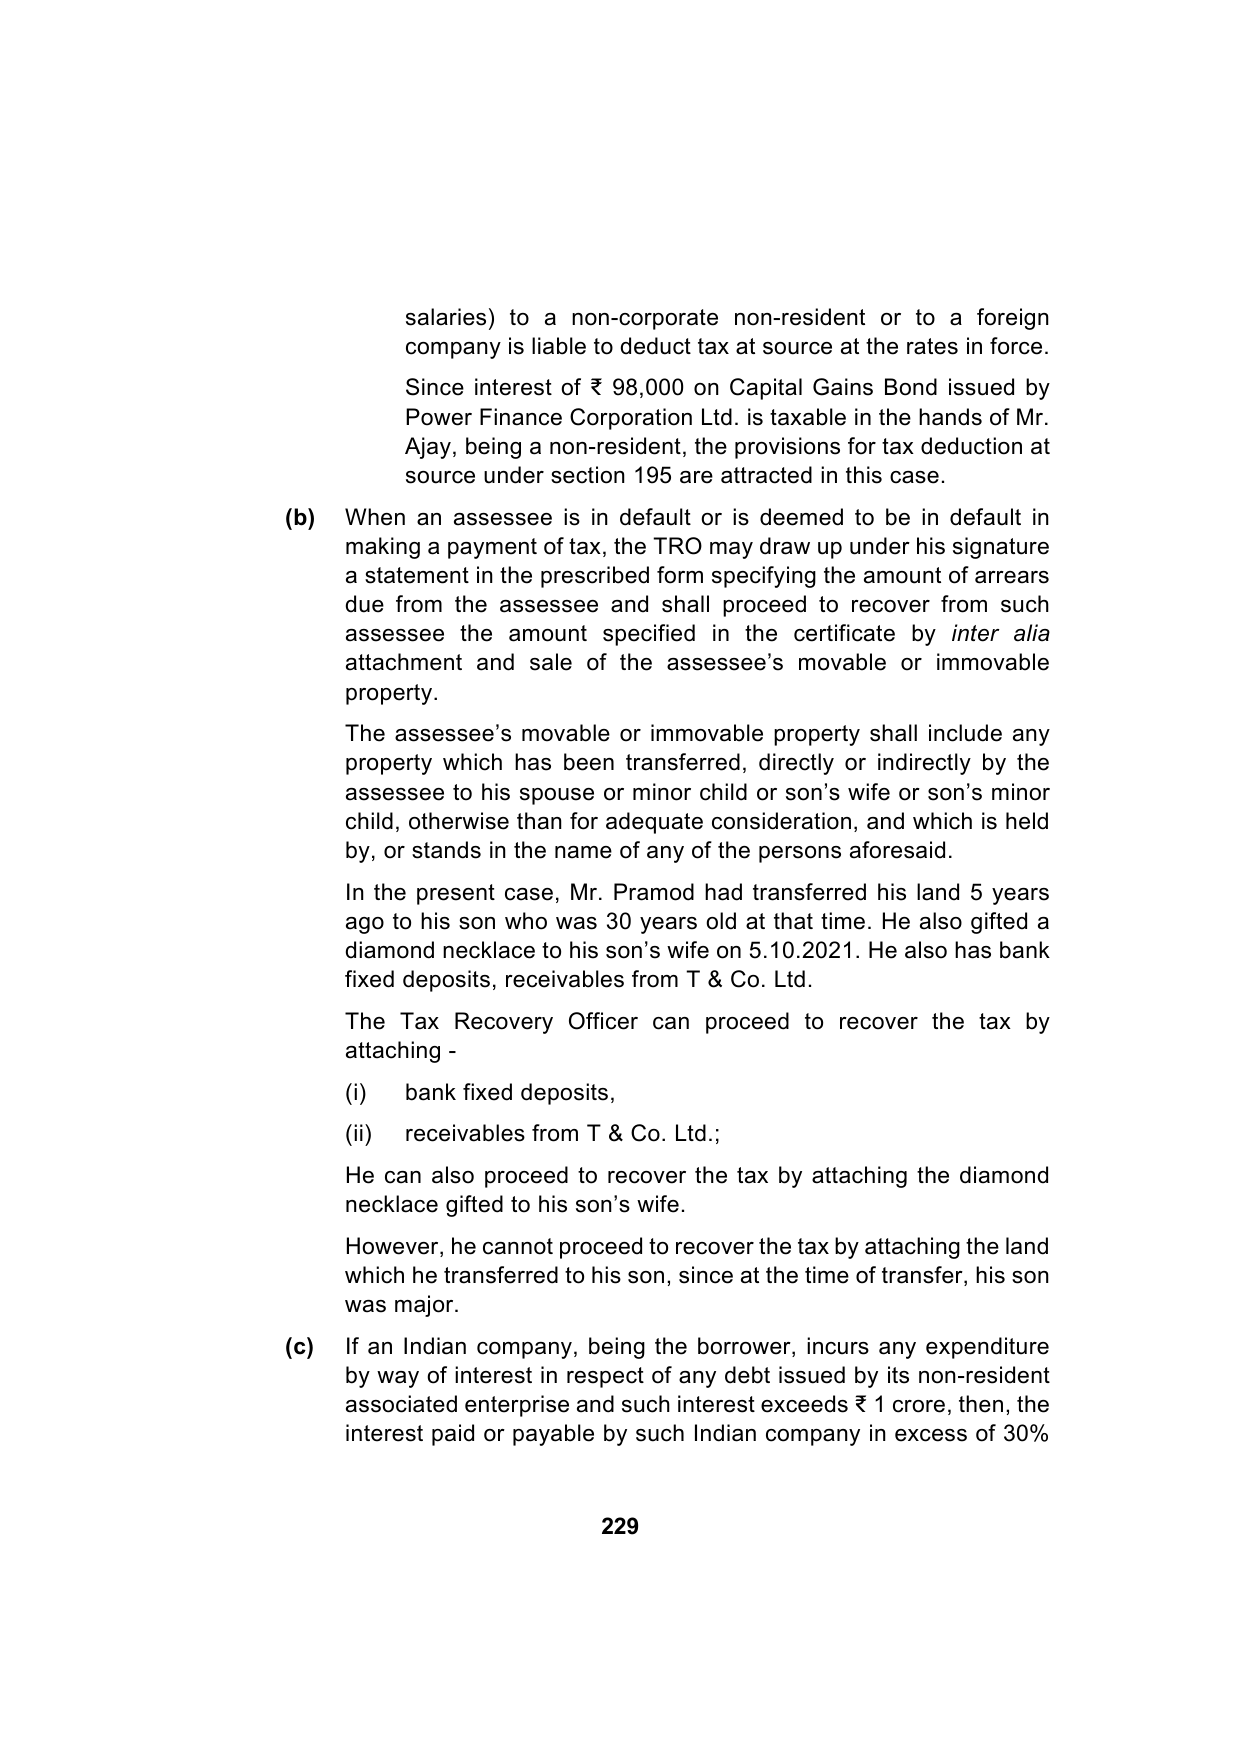
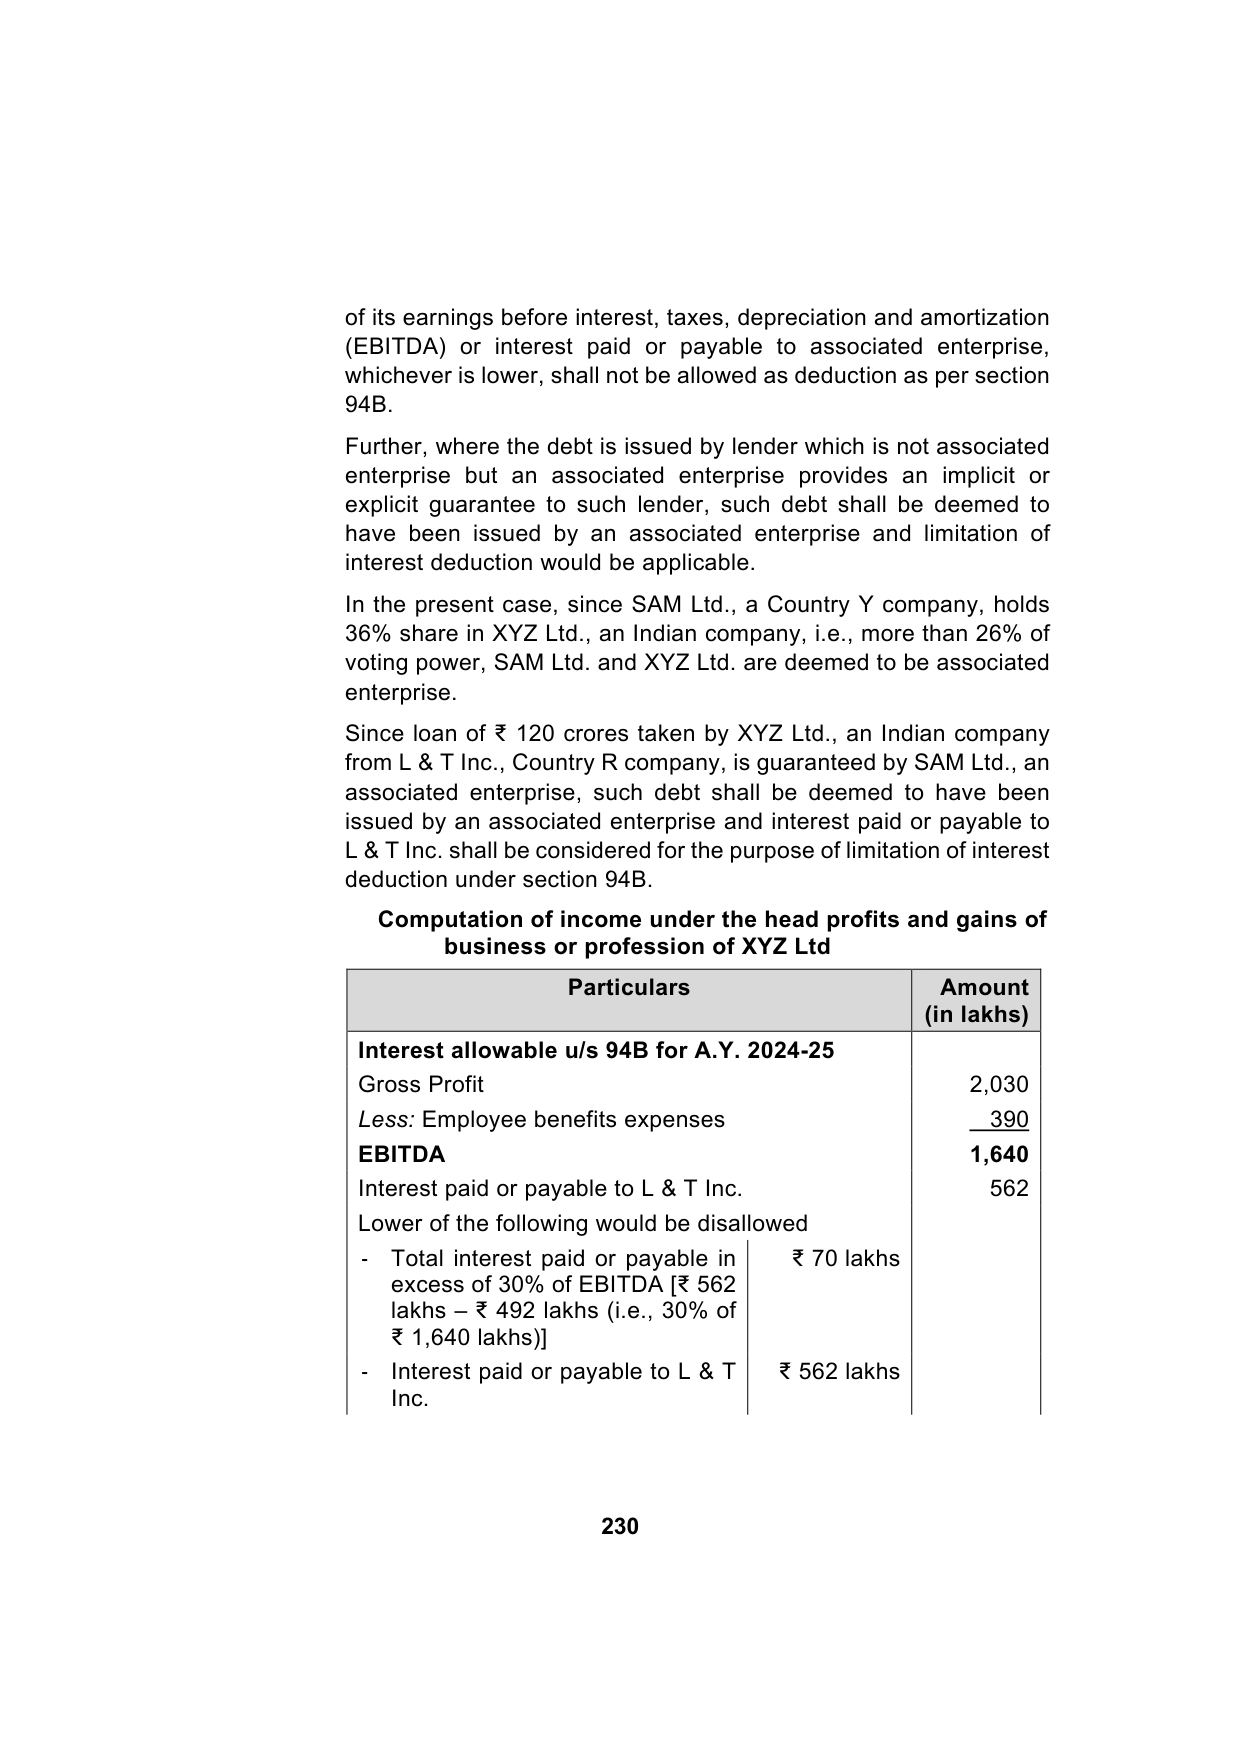
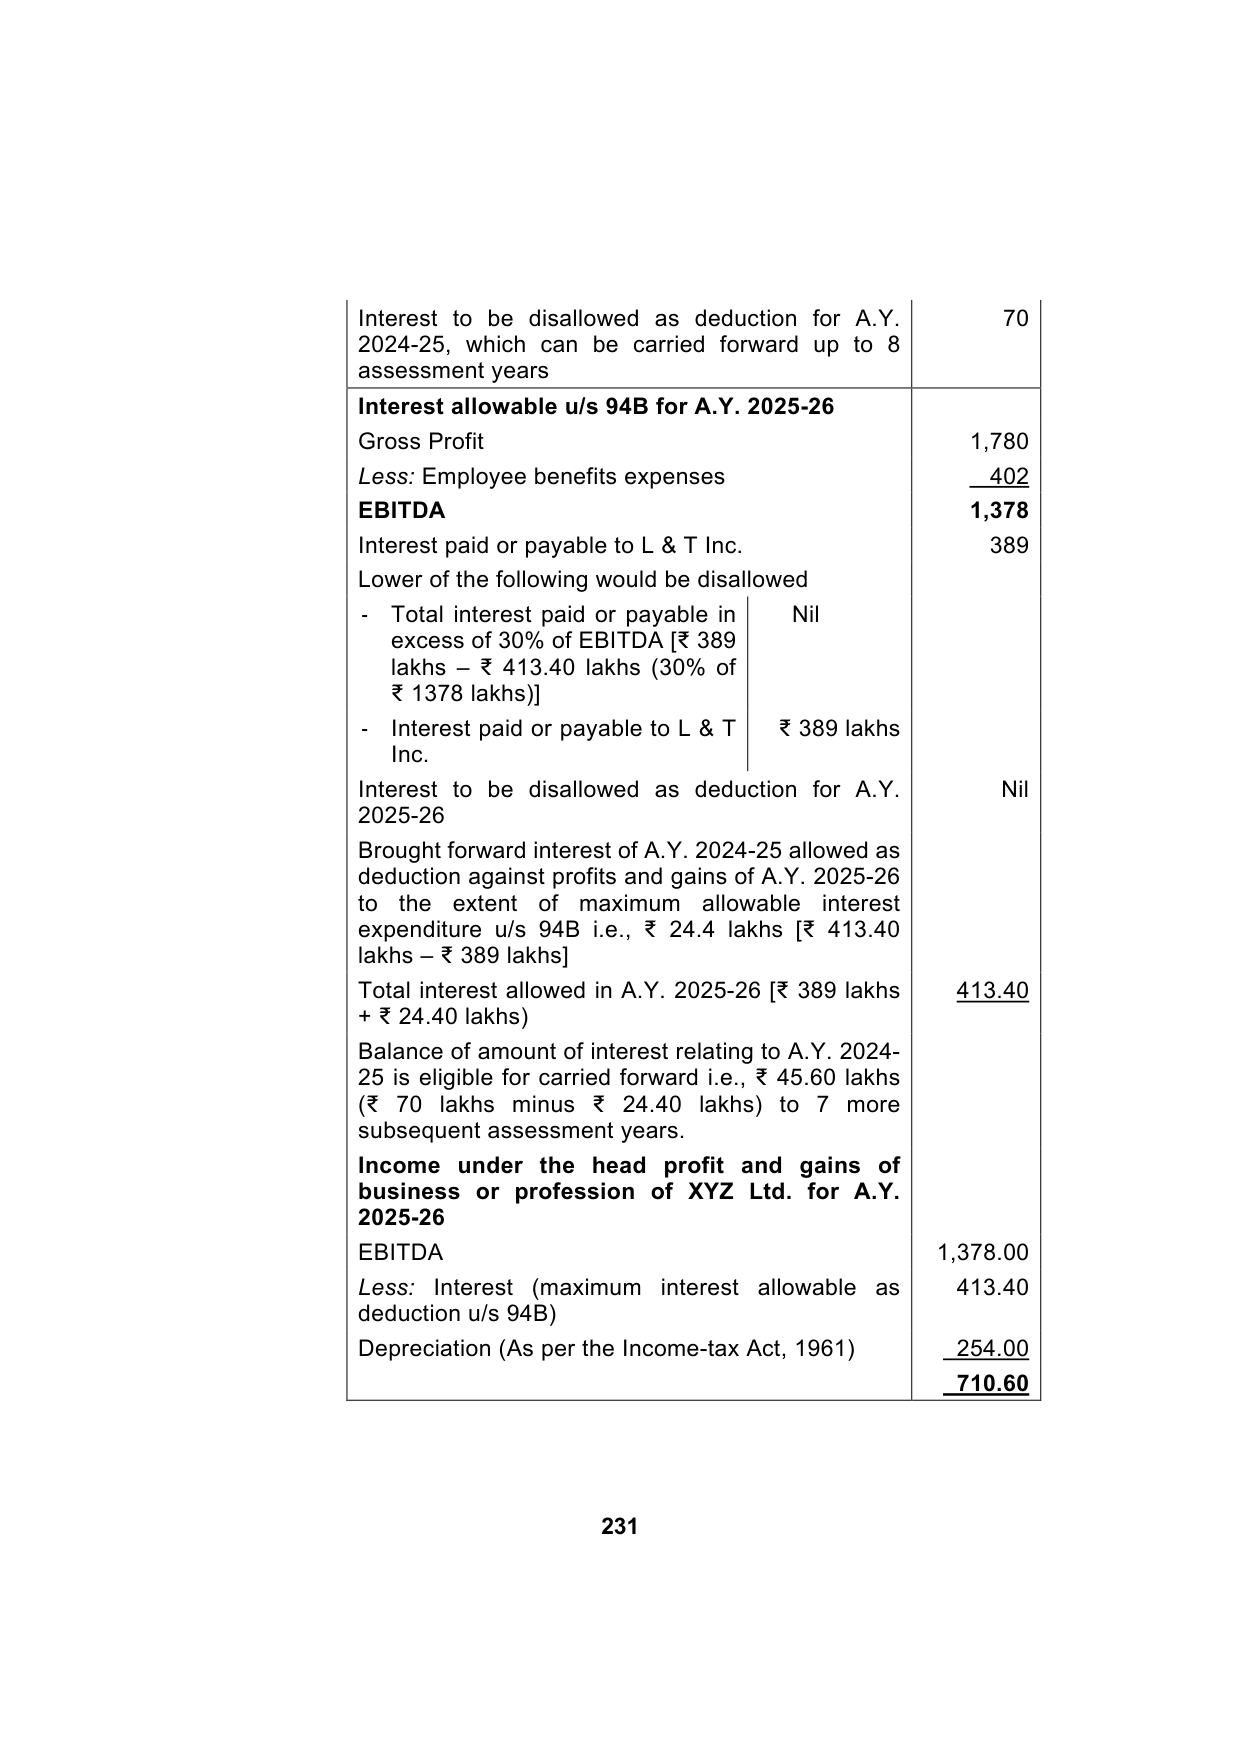
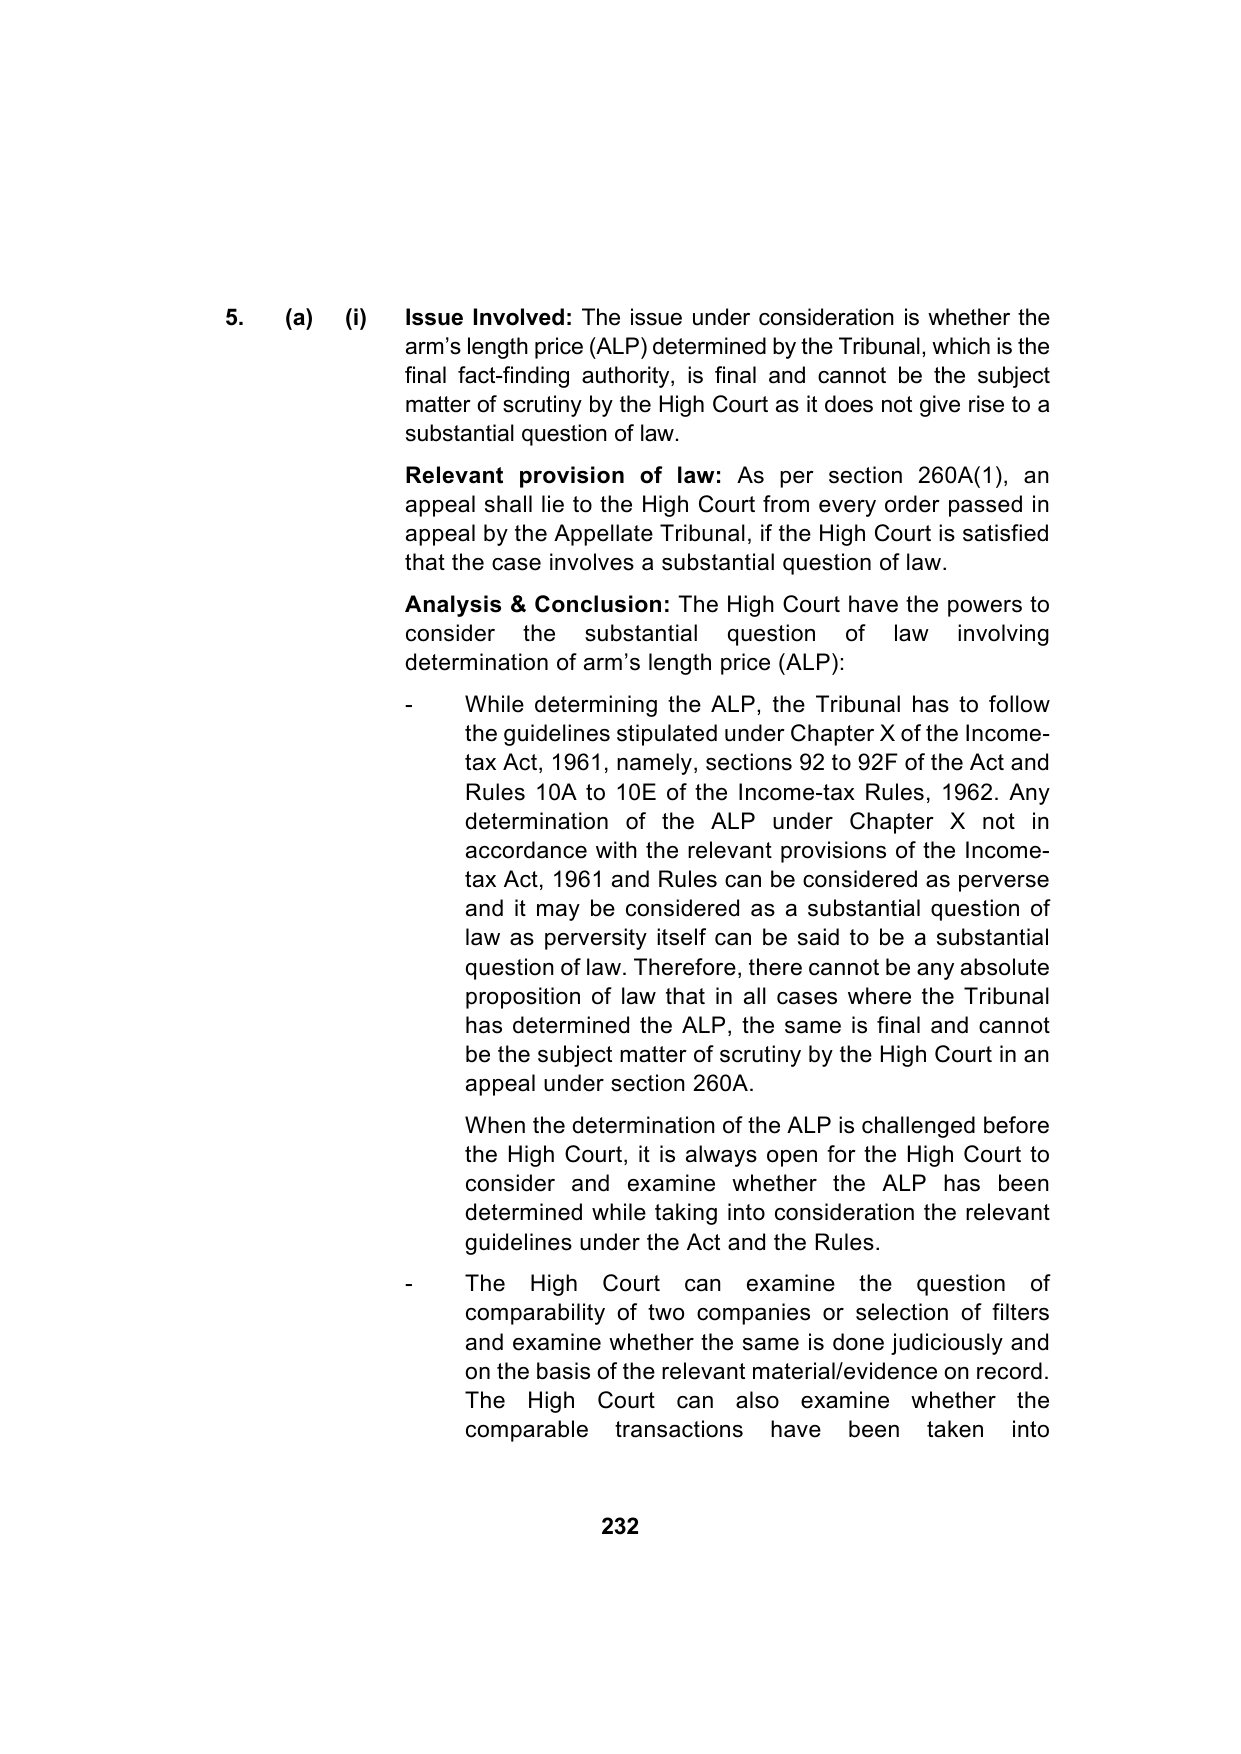
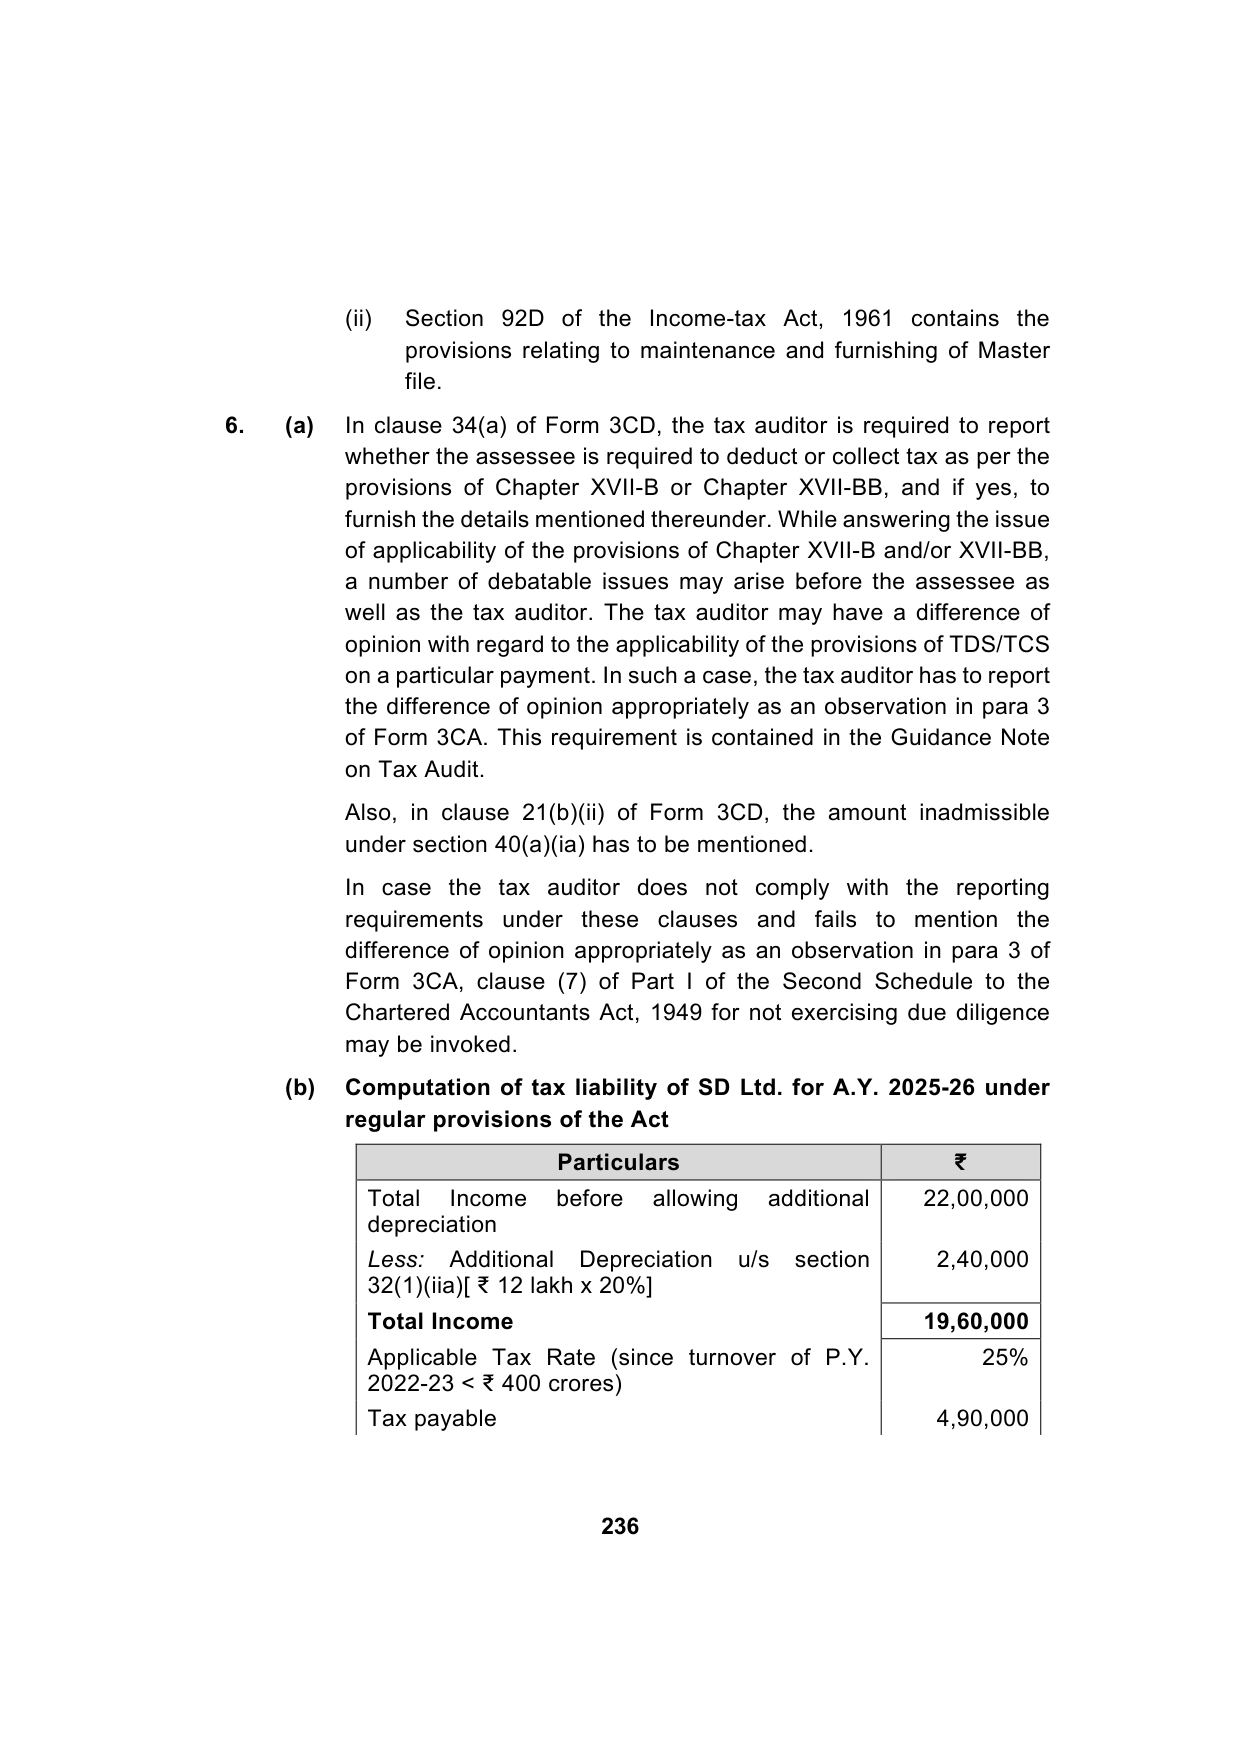
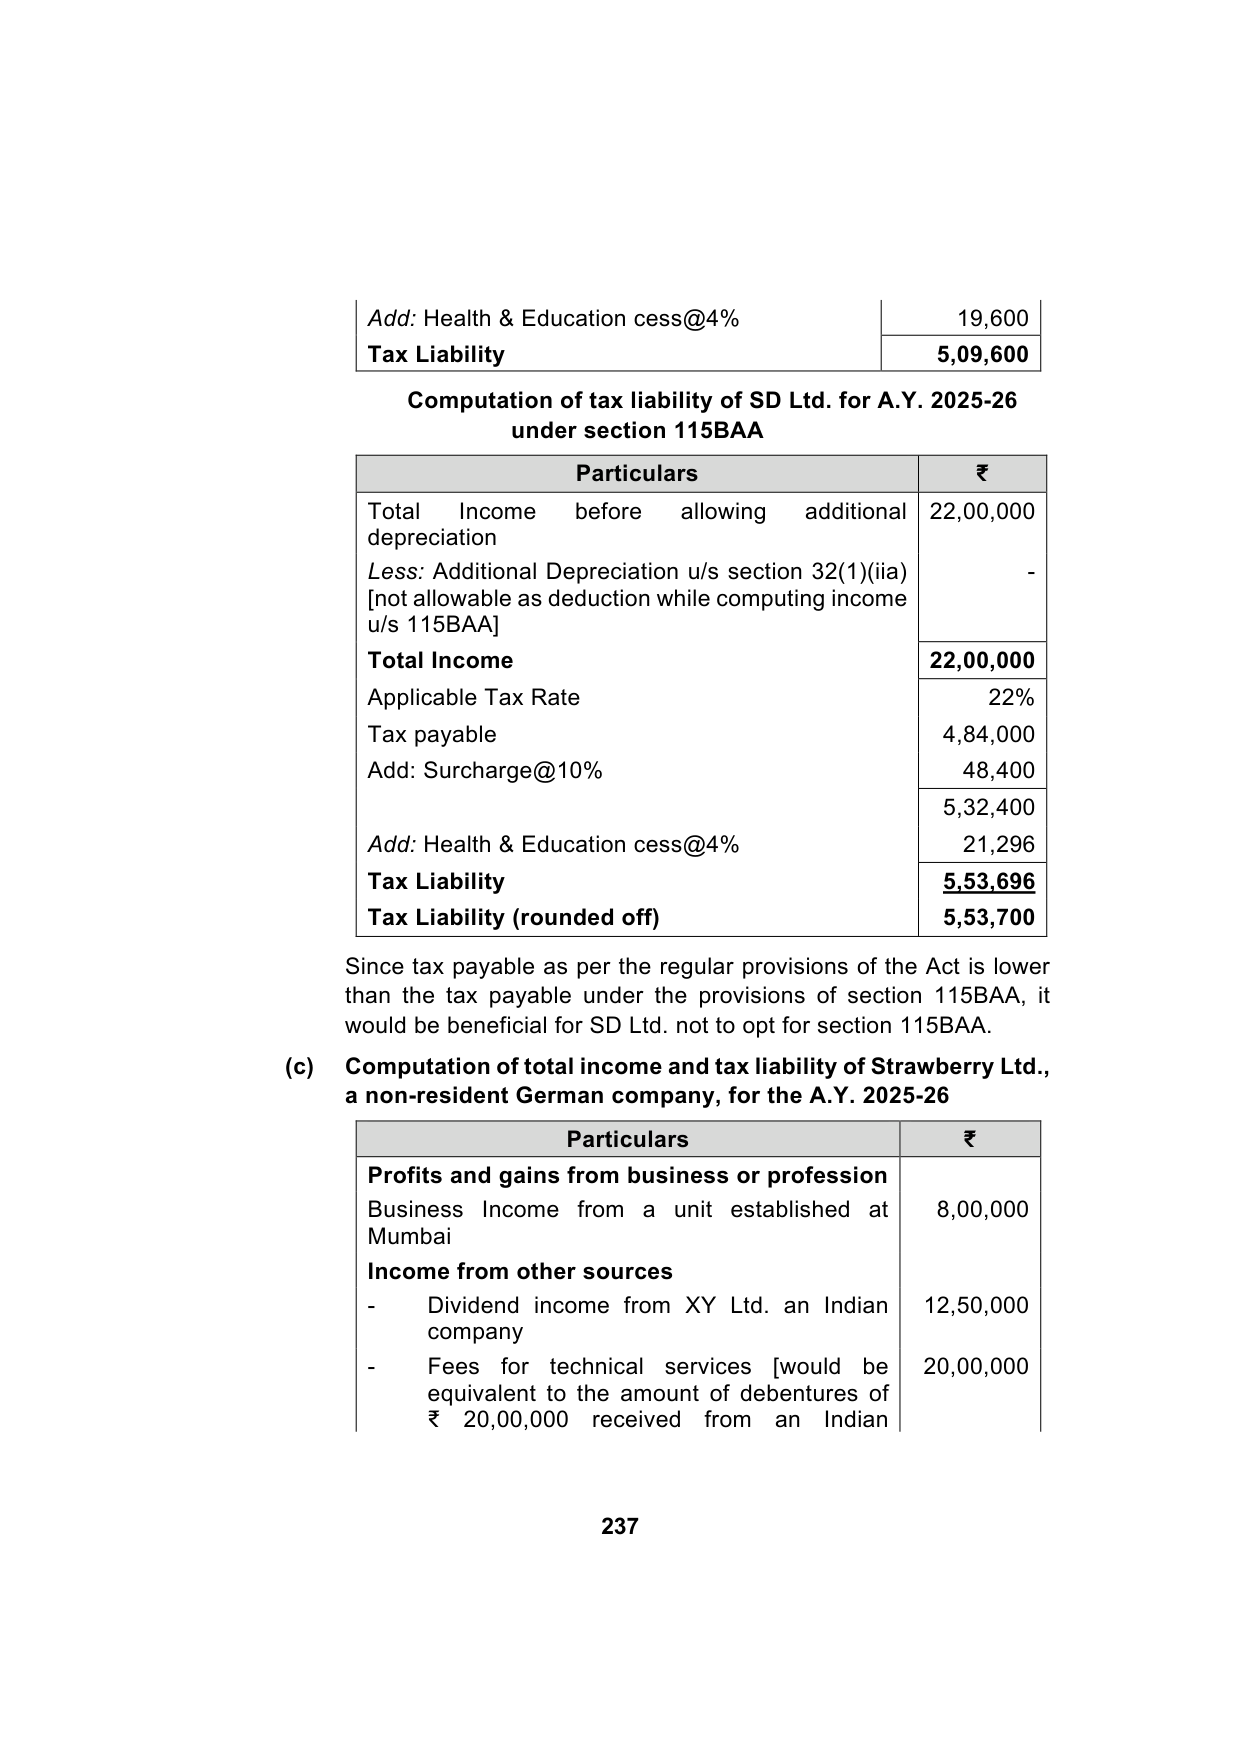
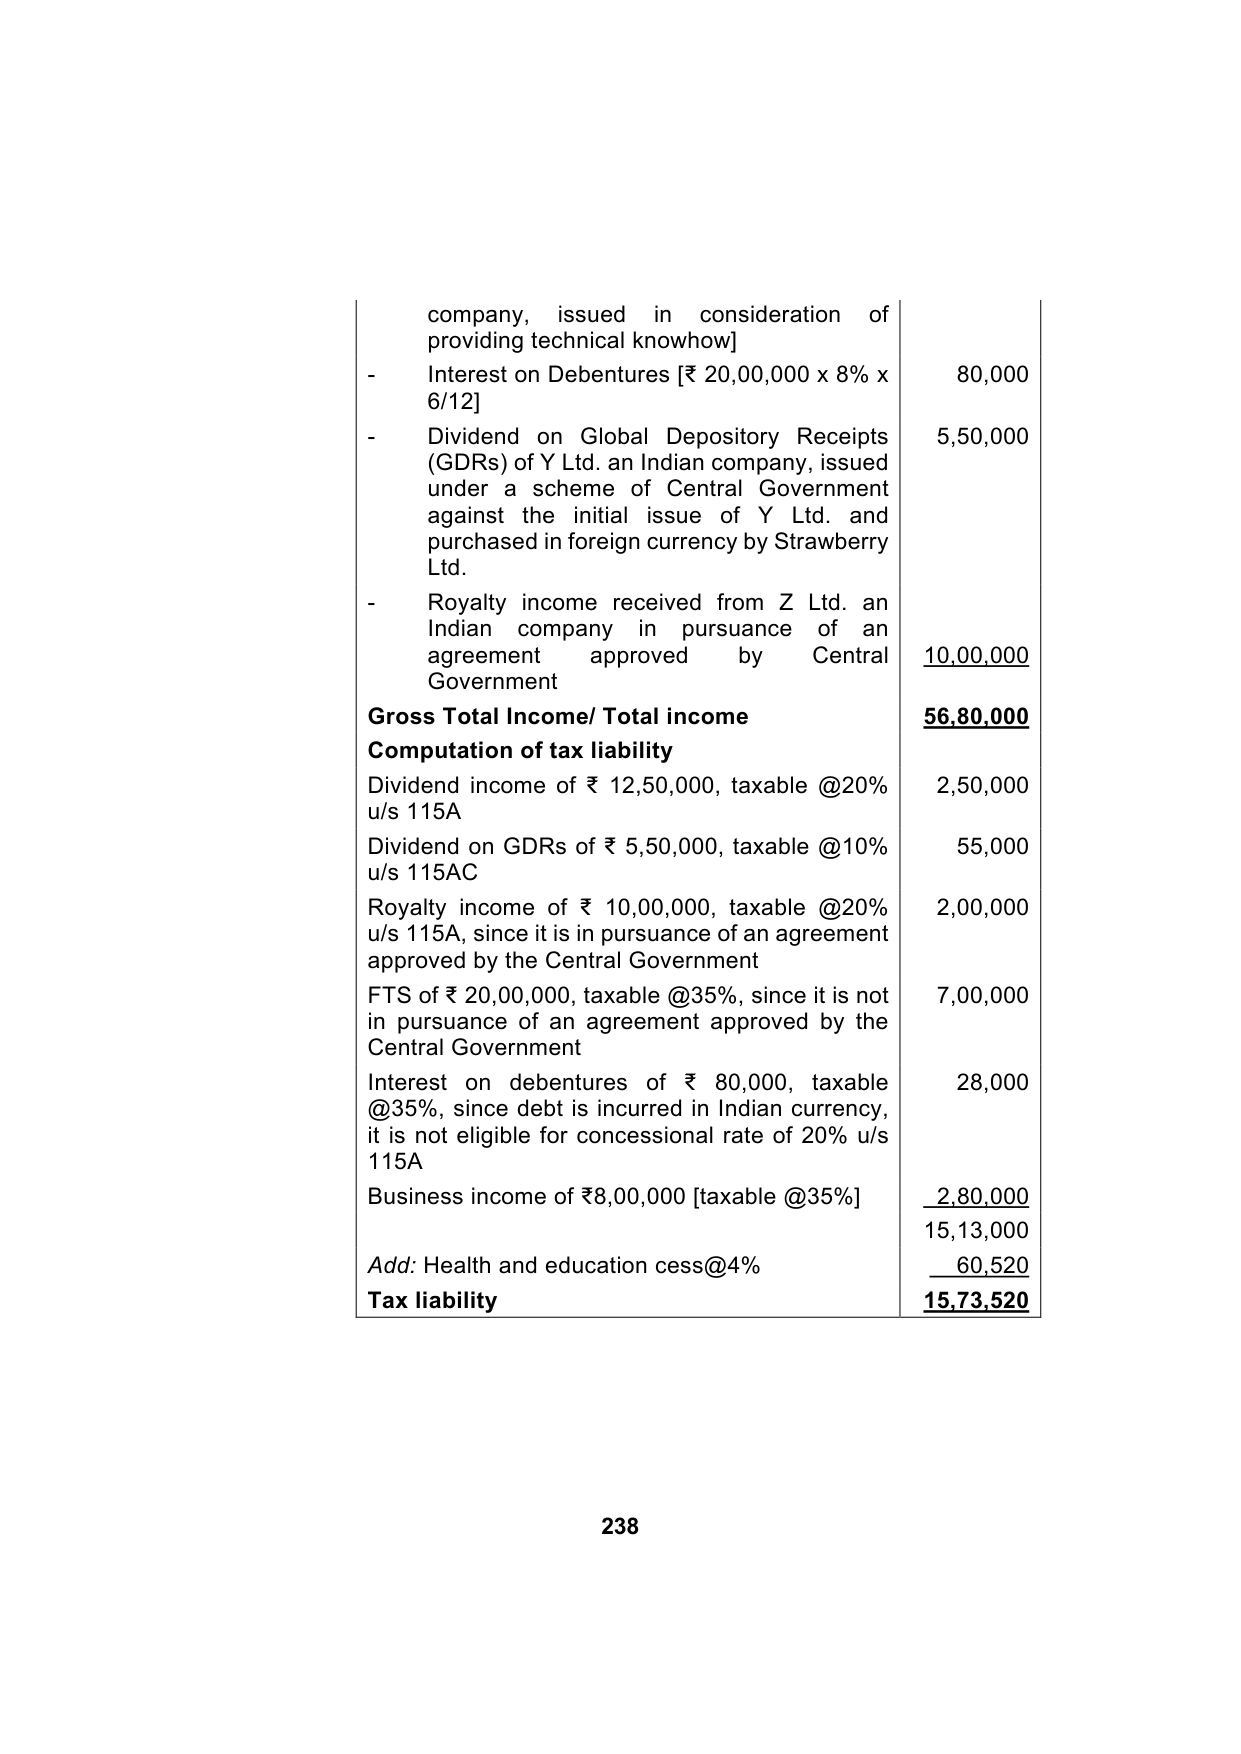
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 2
Question
Answer
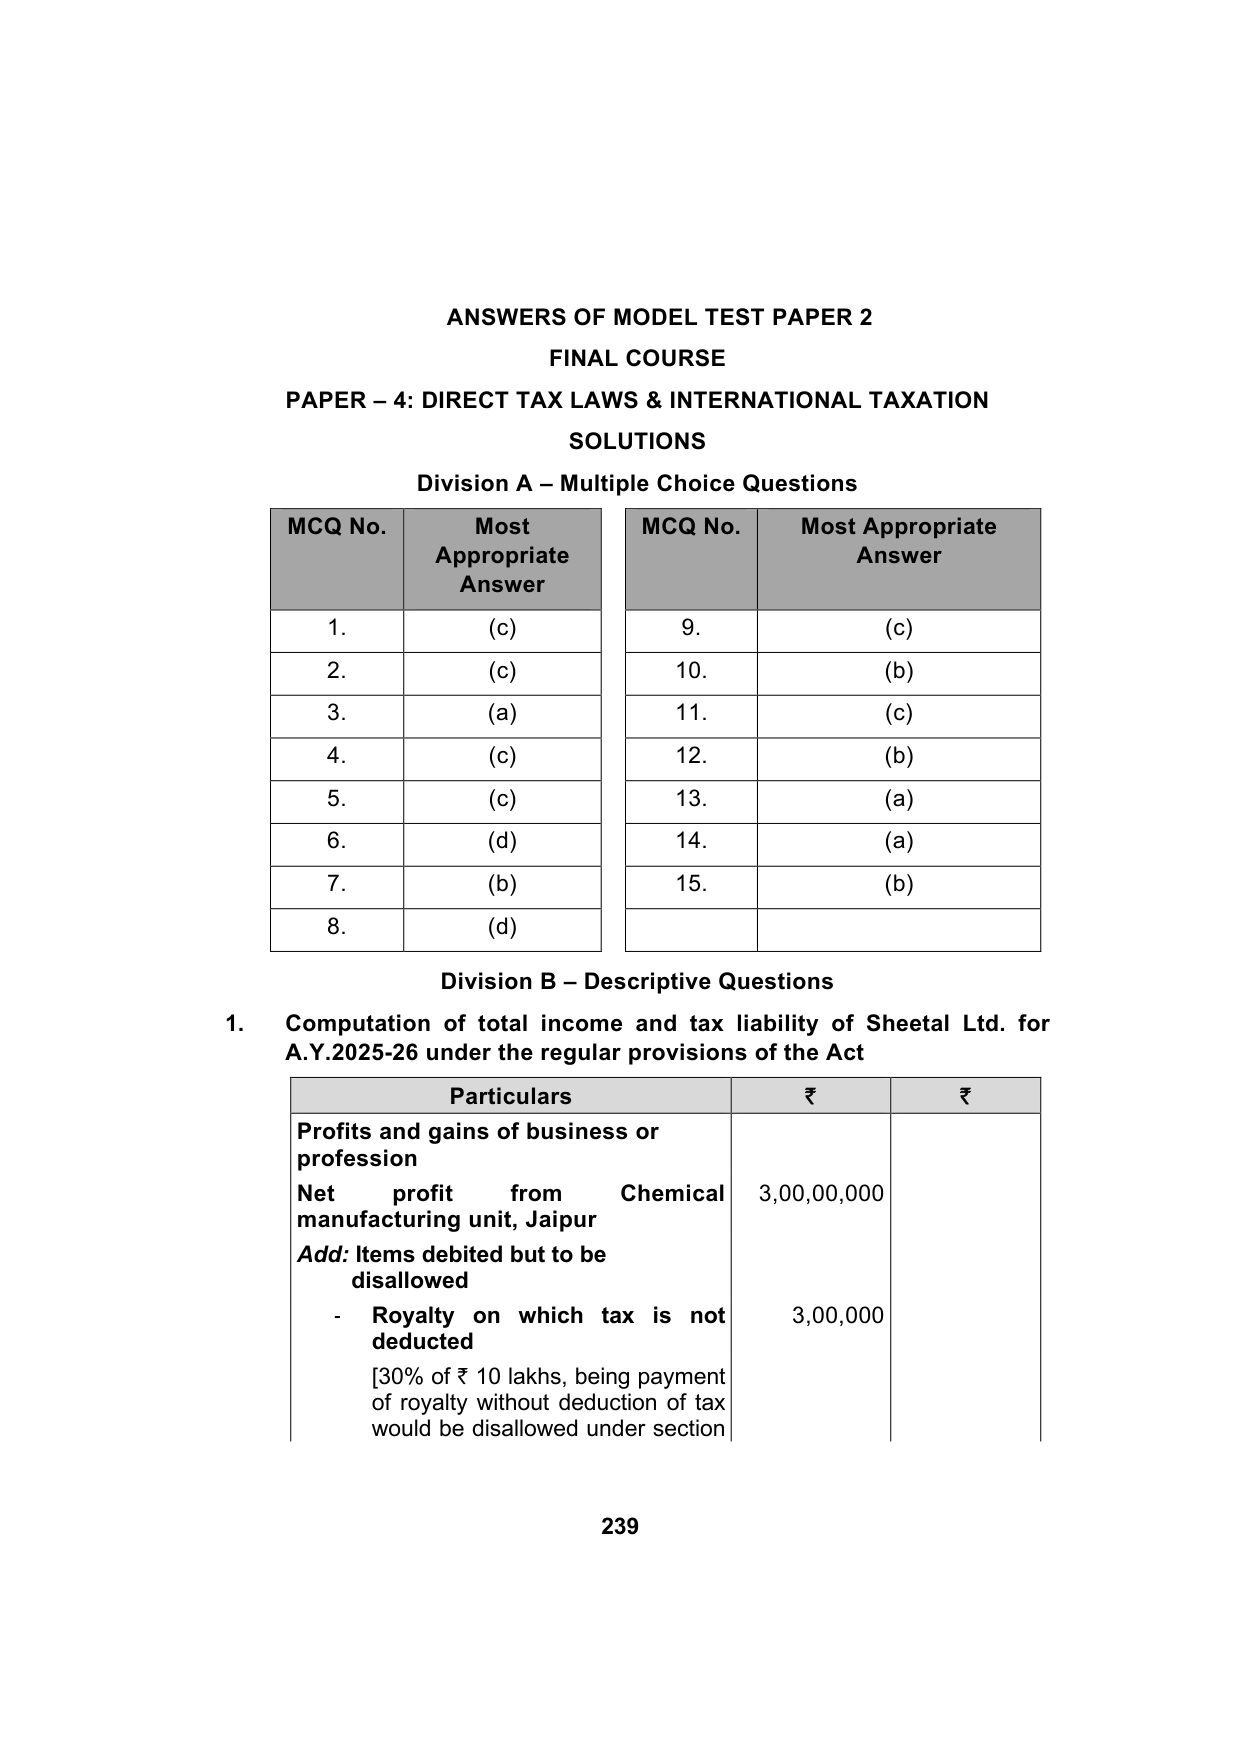
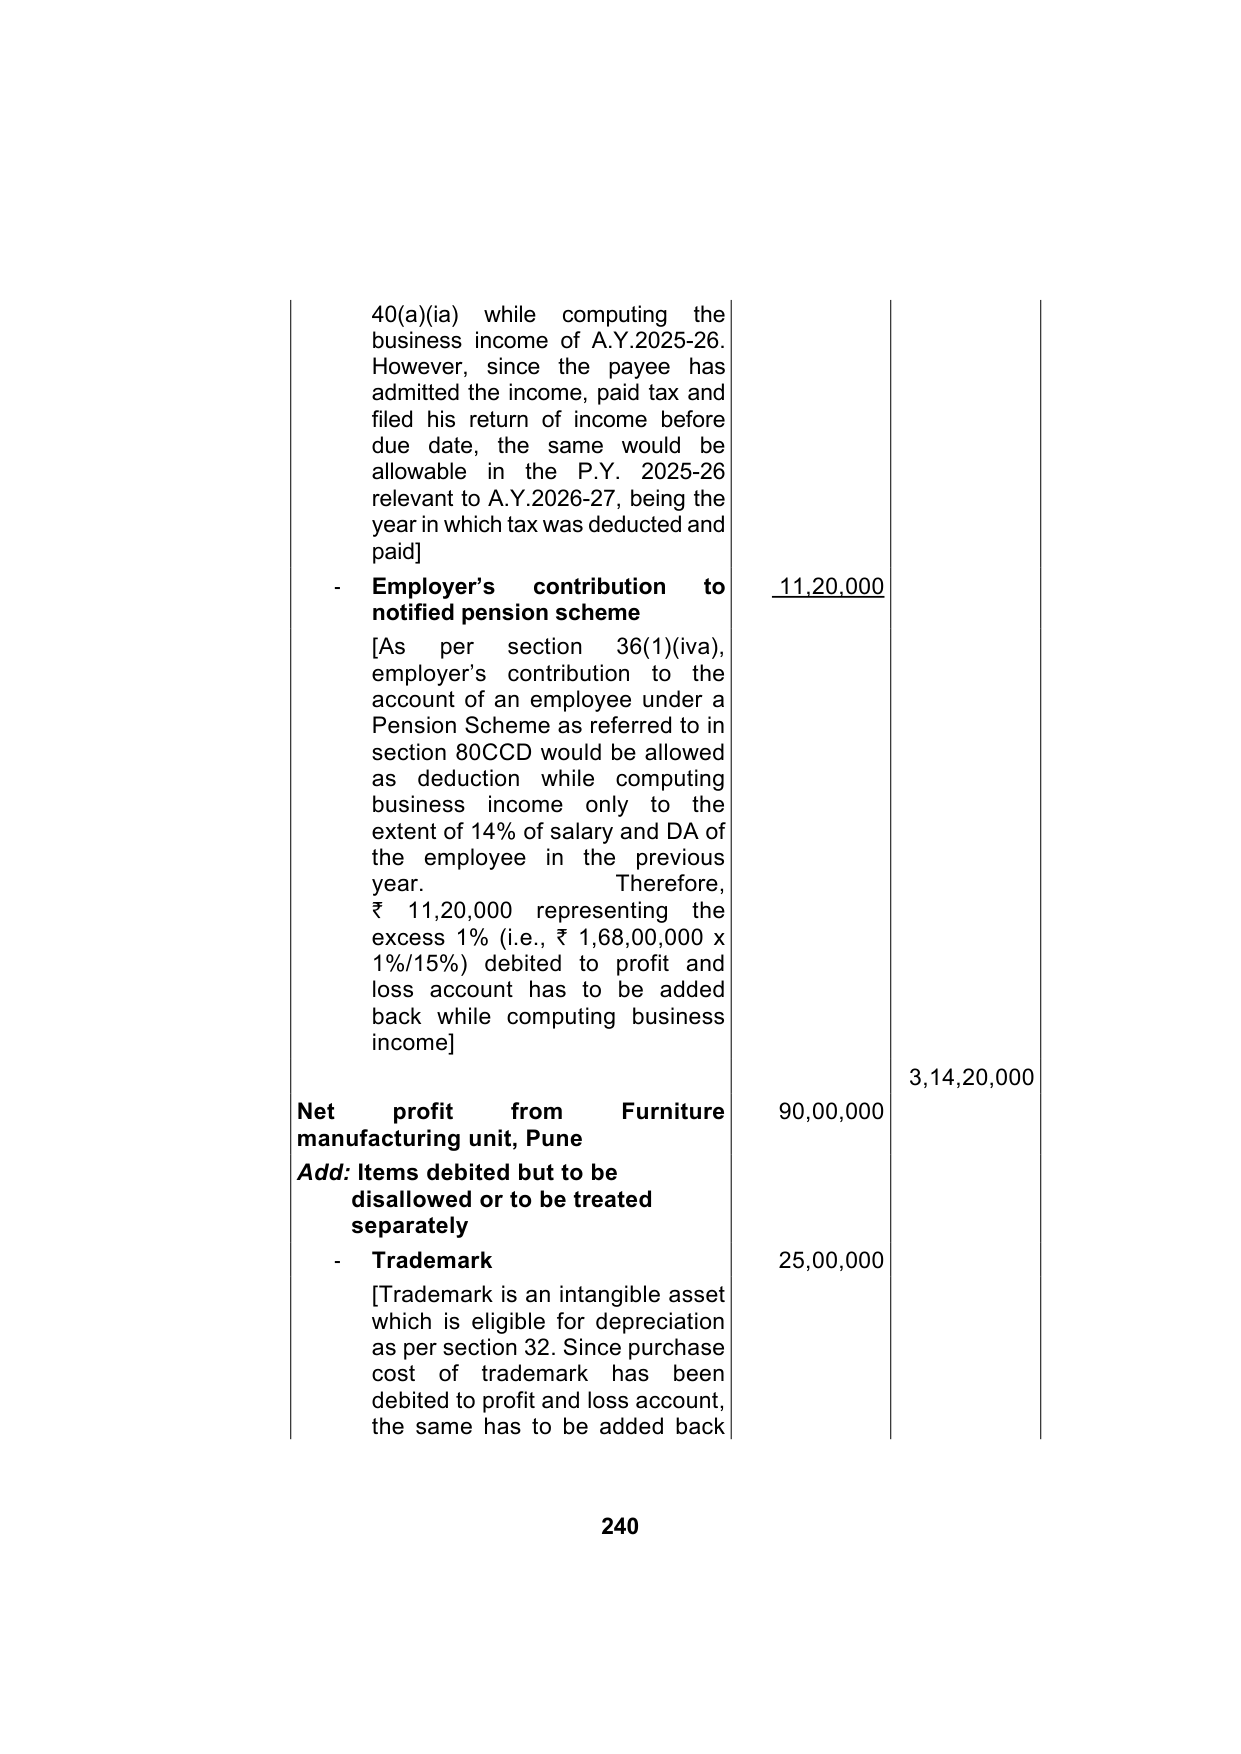
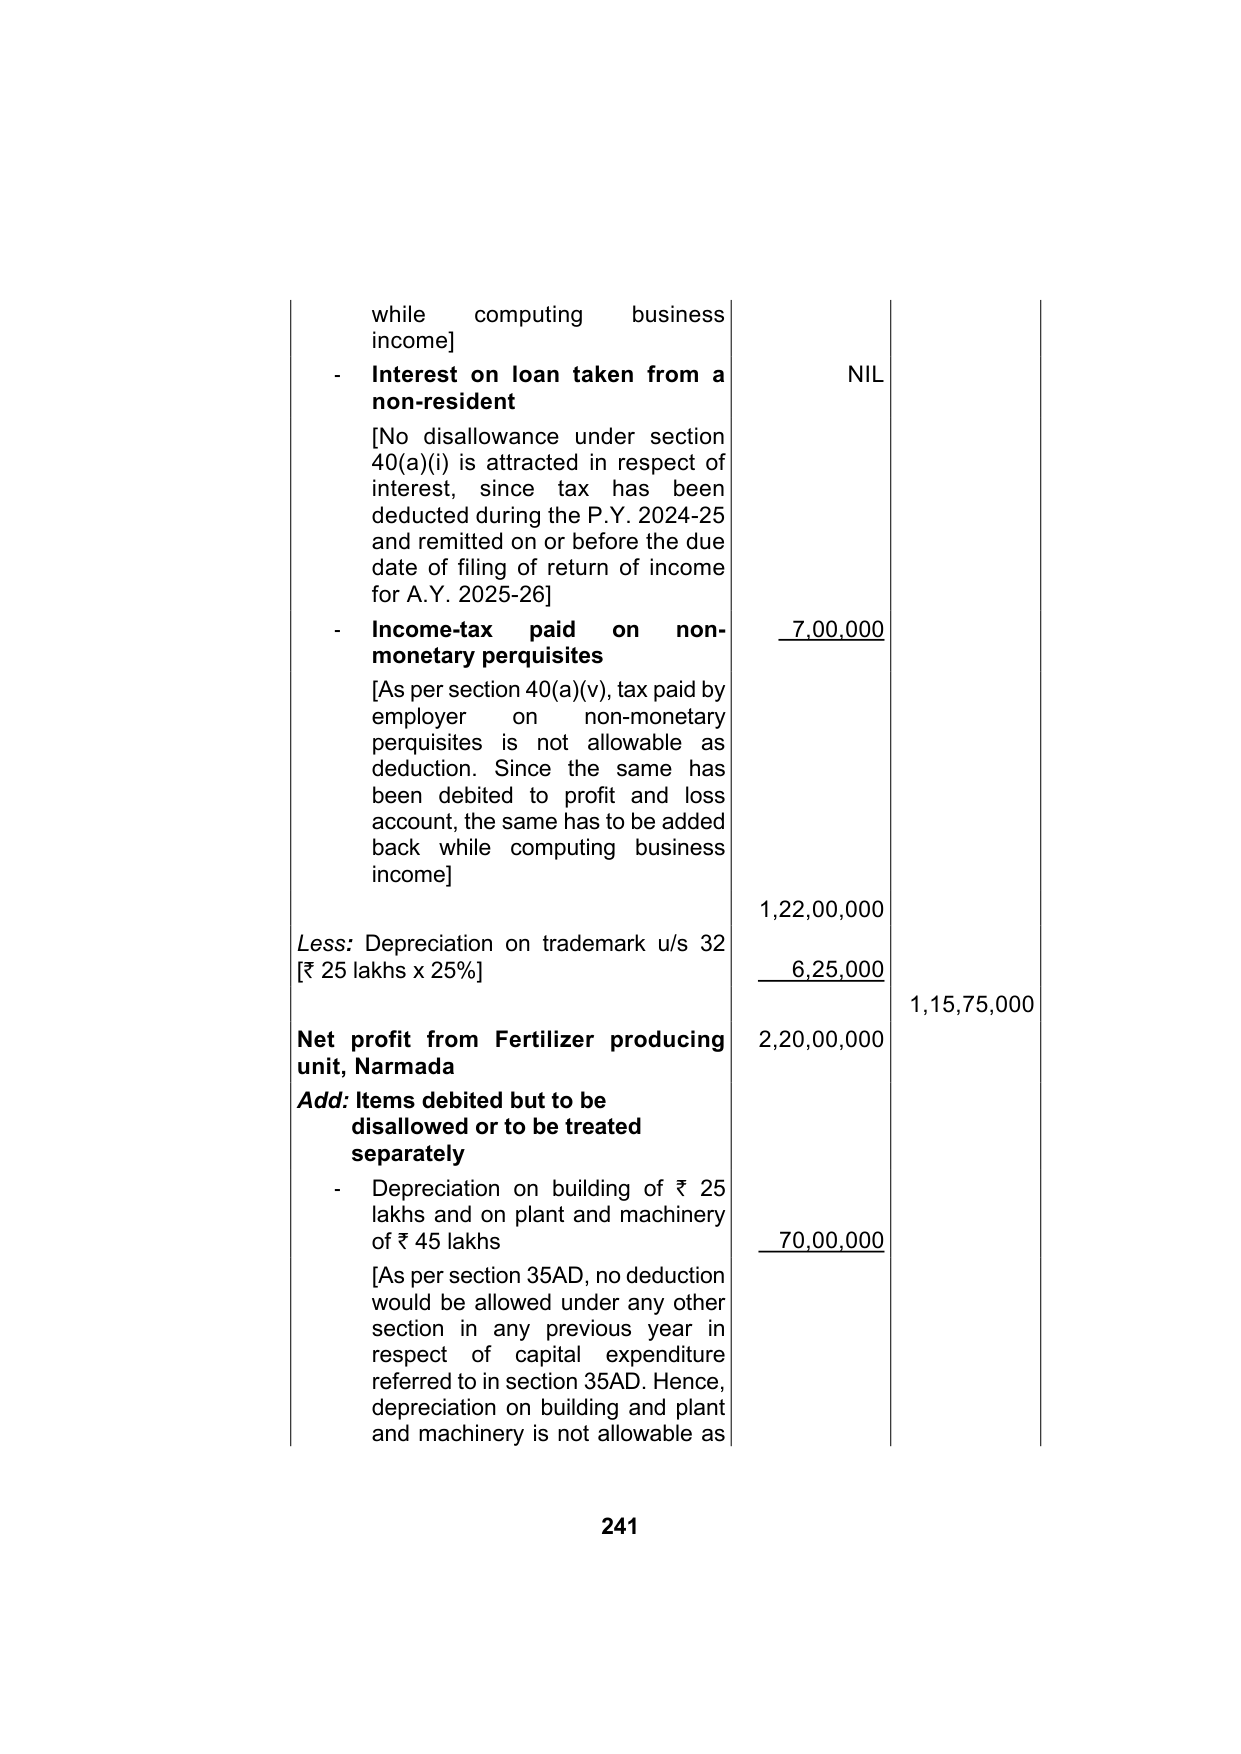
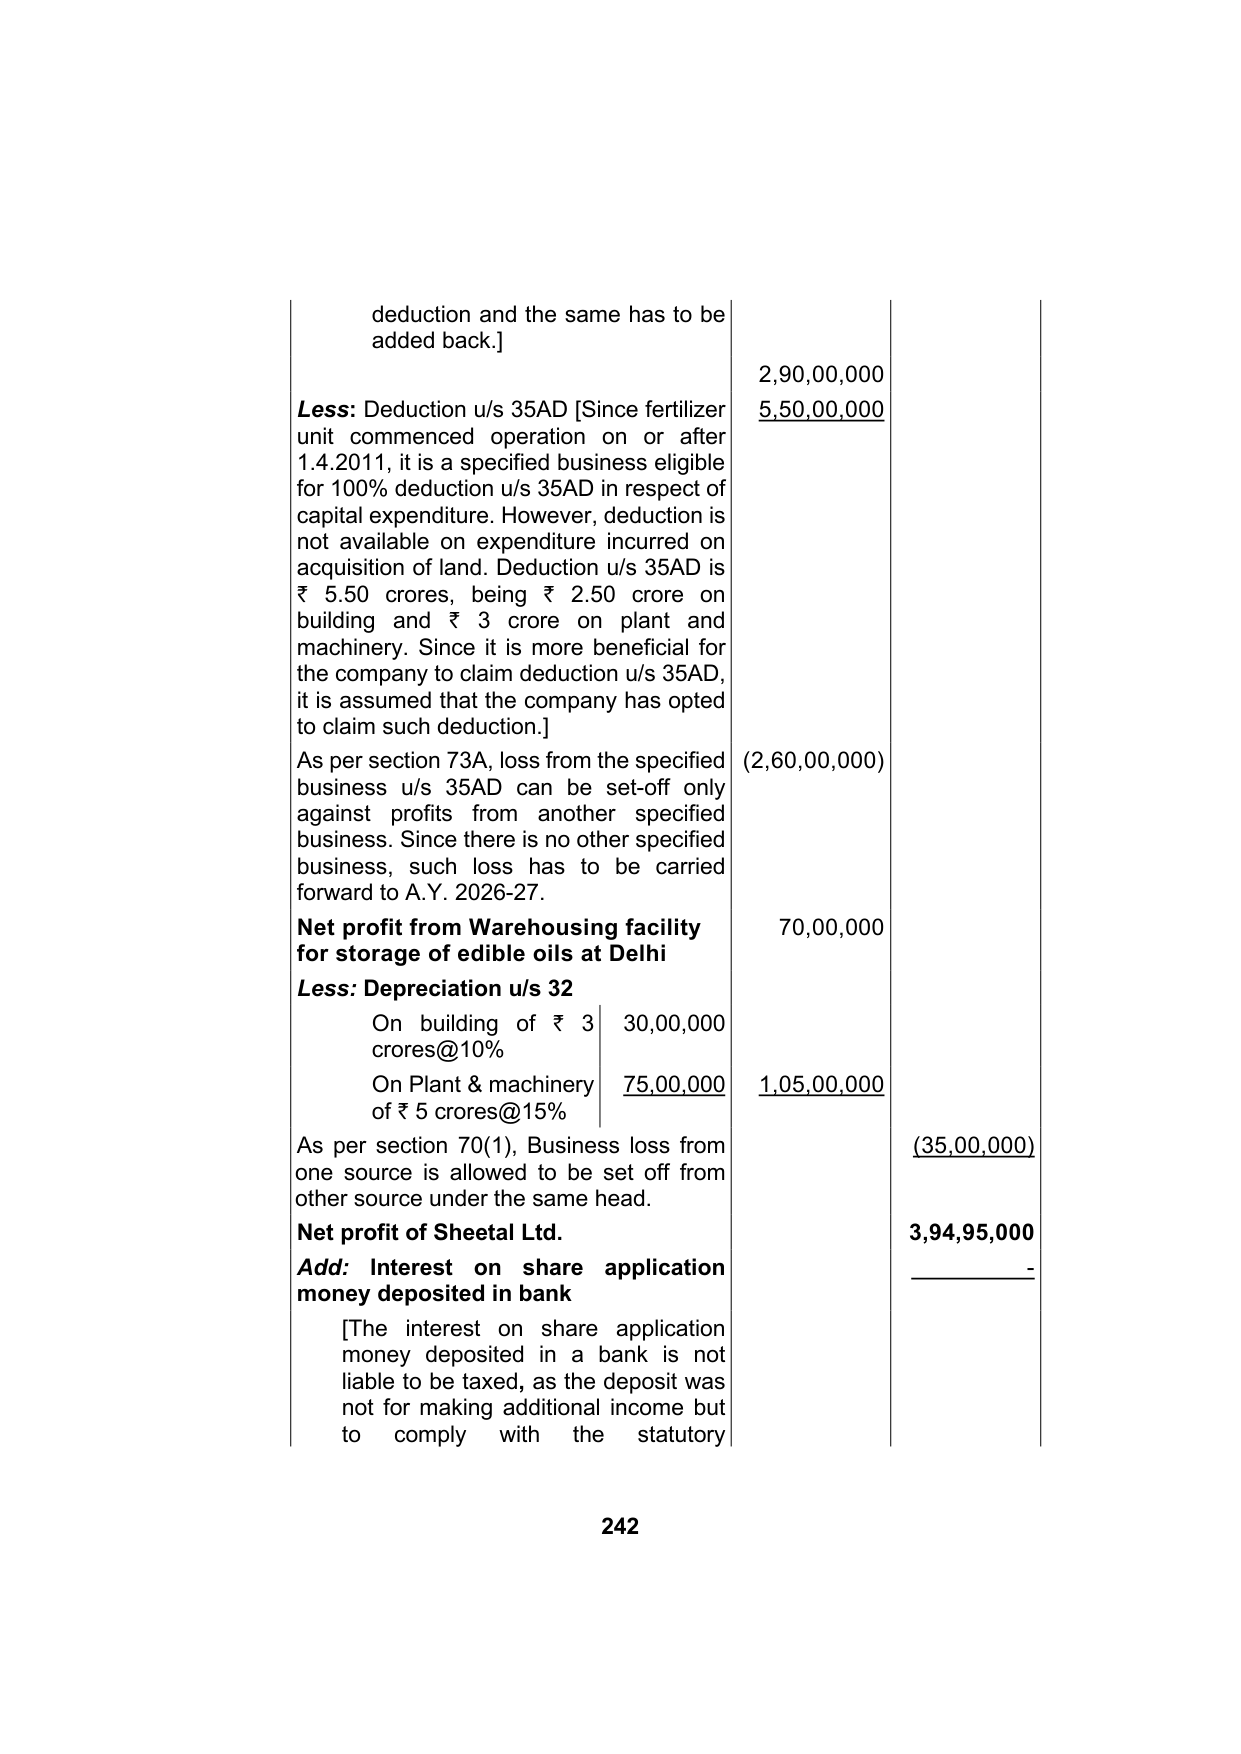
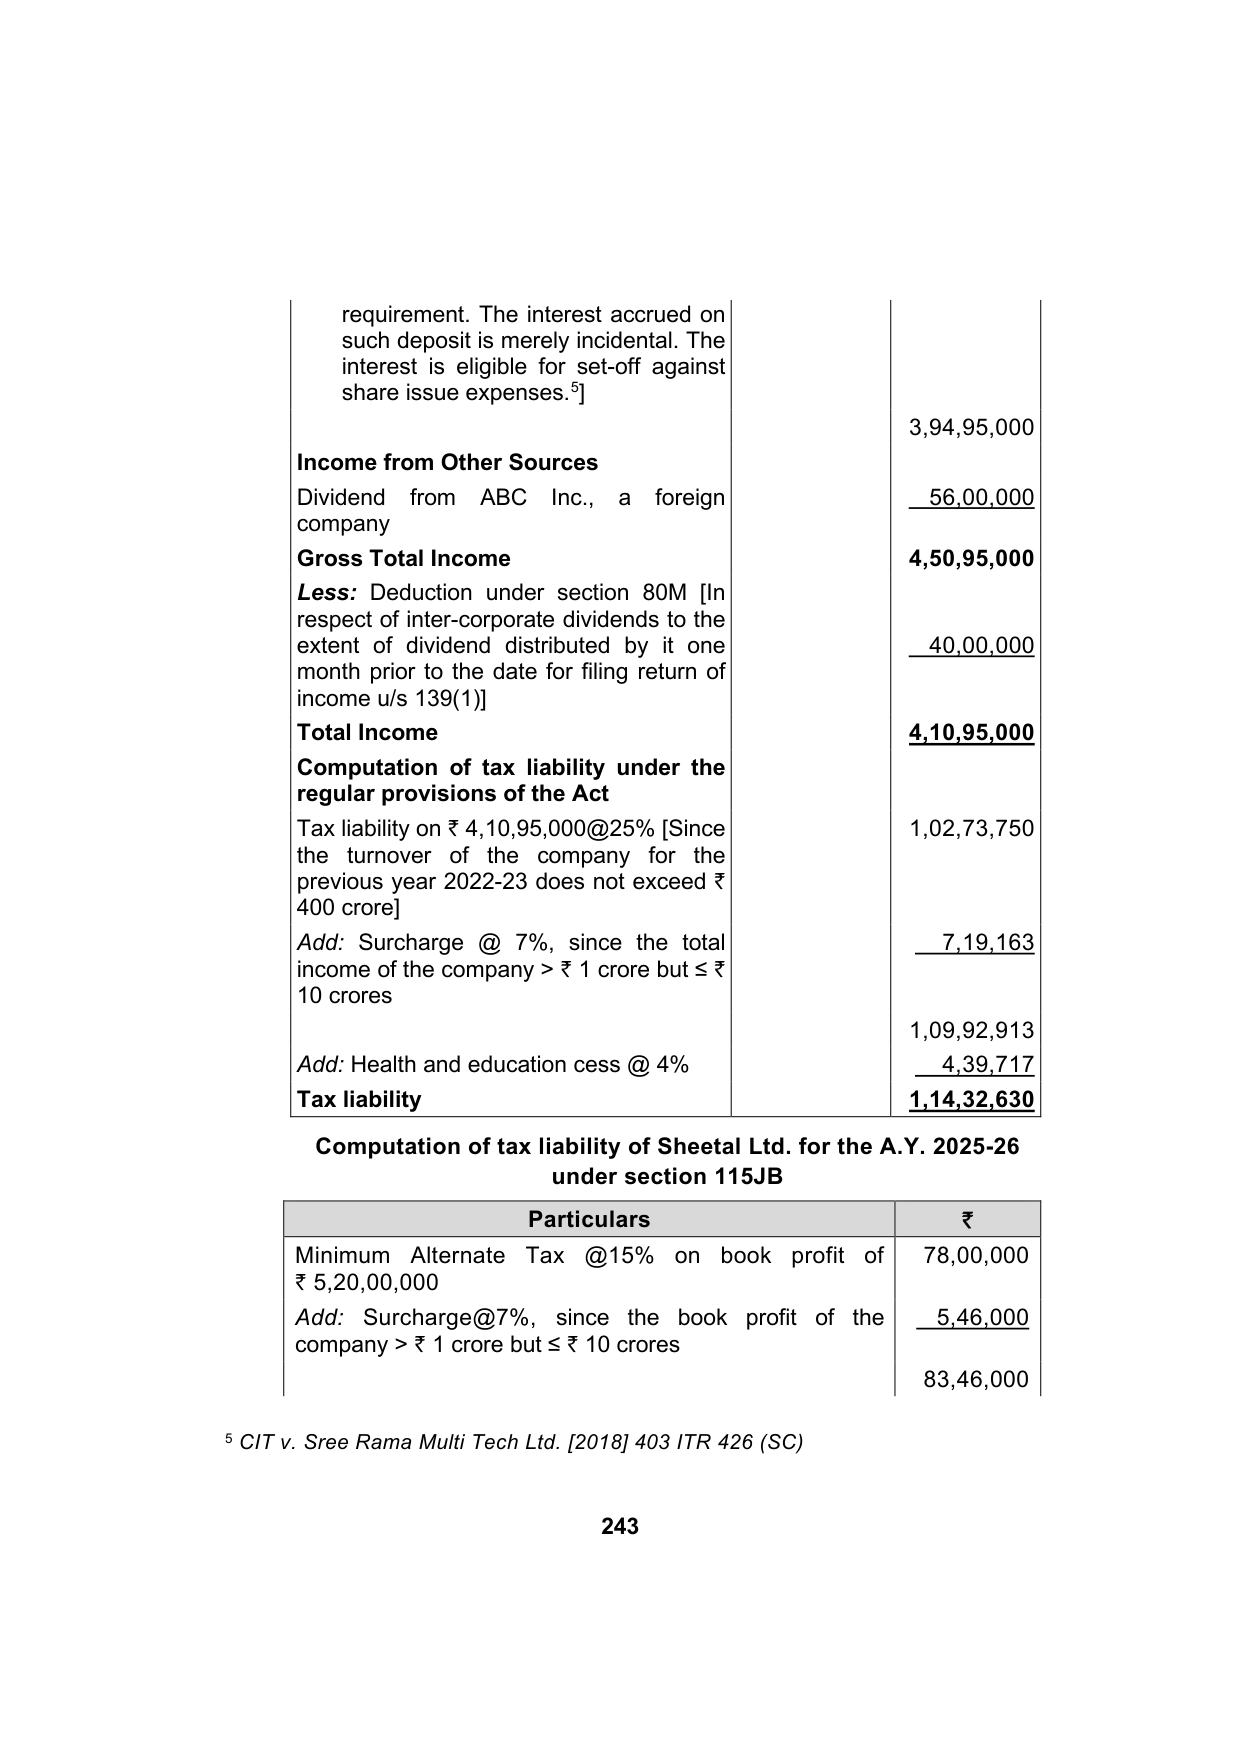
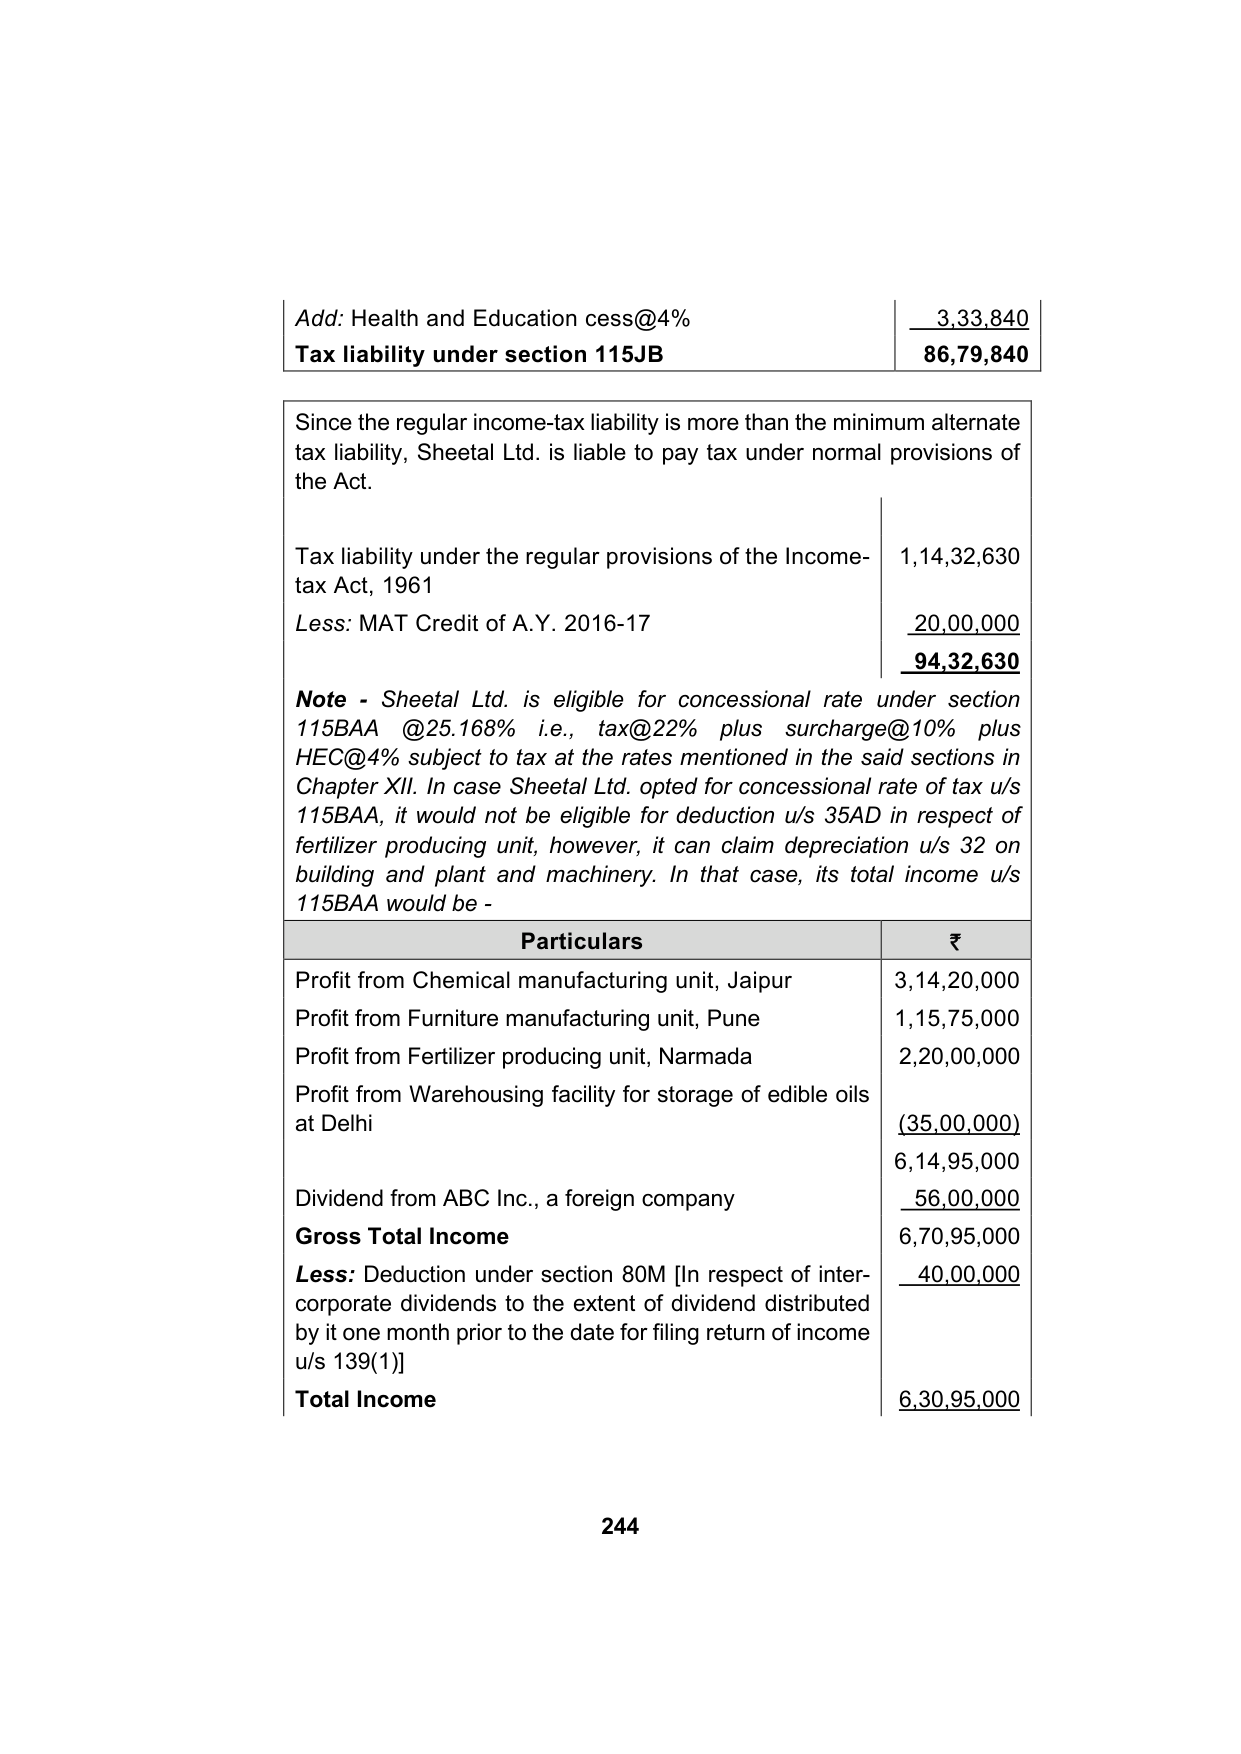
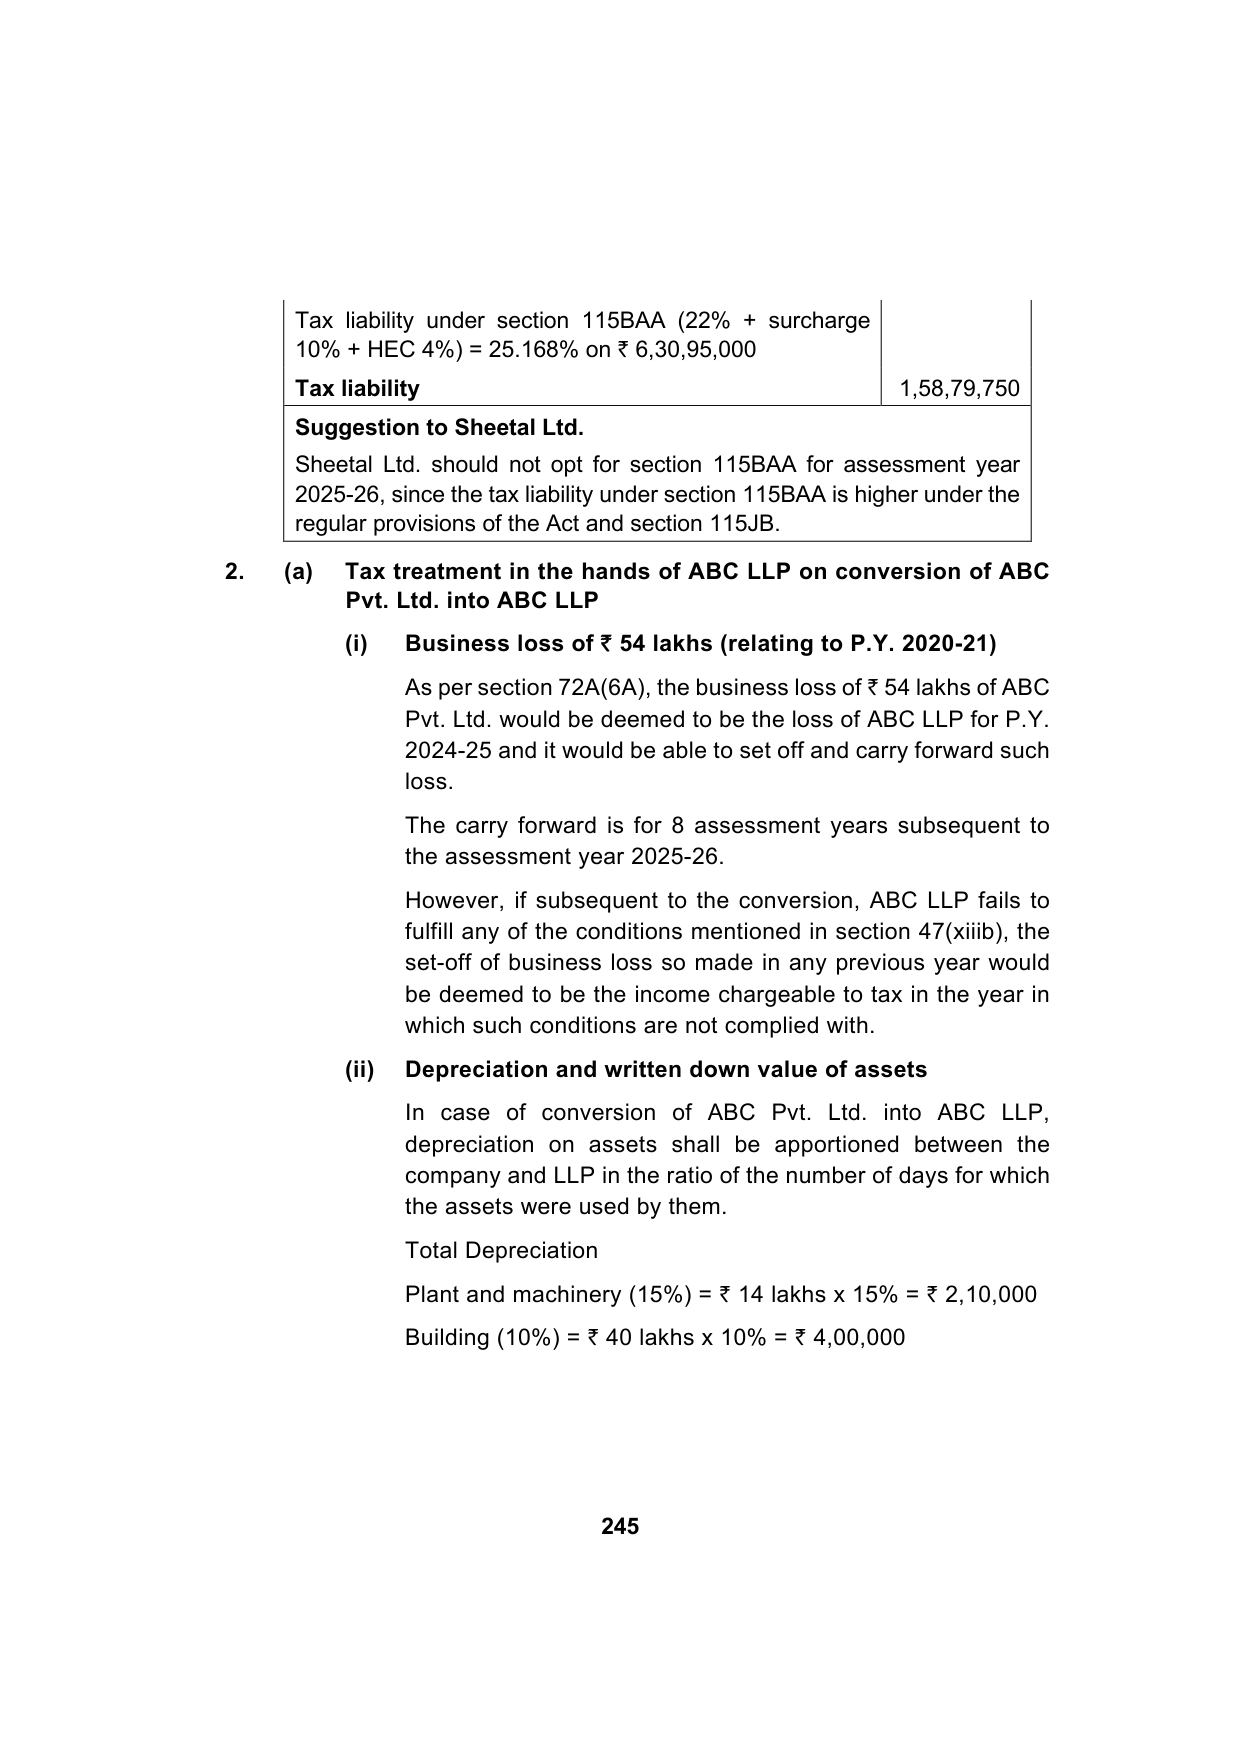
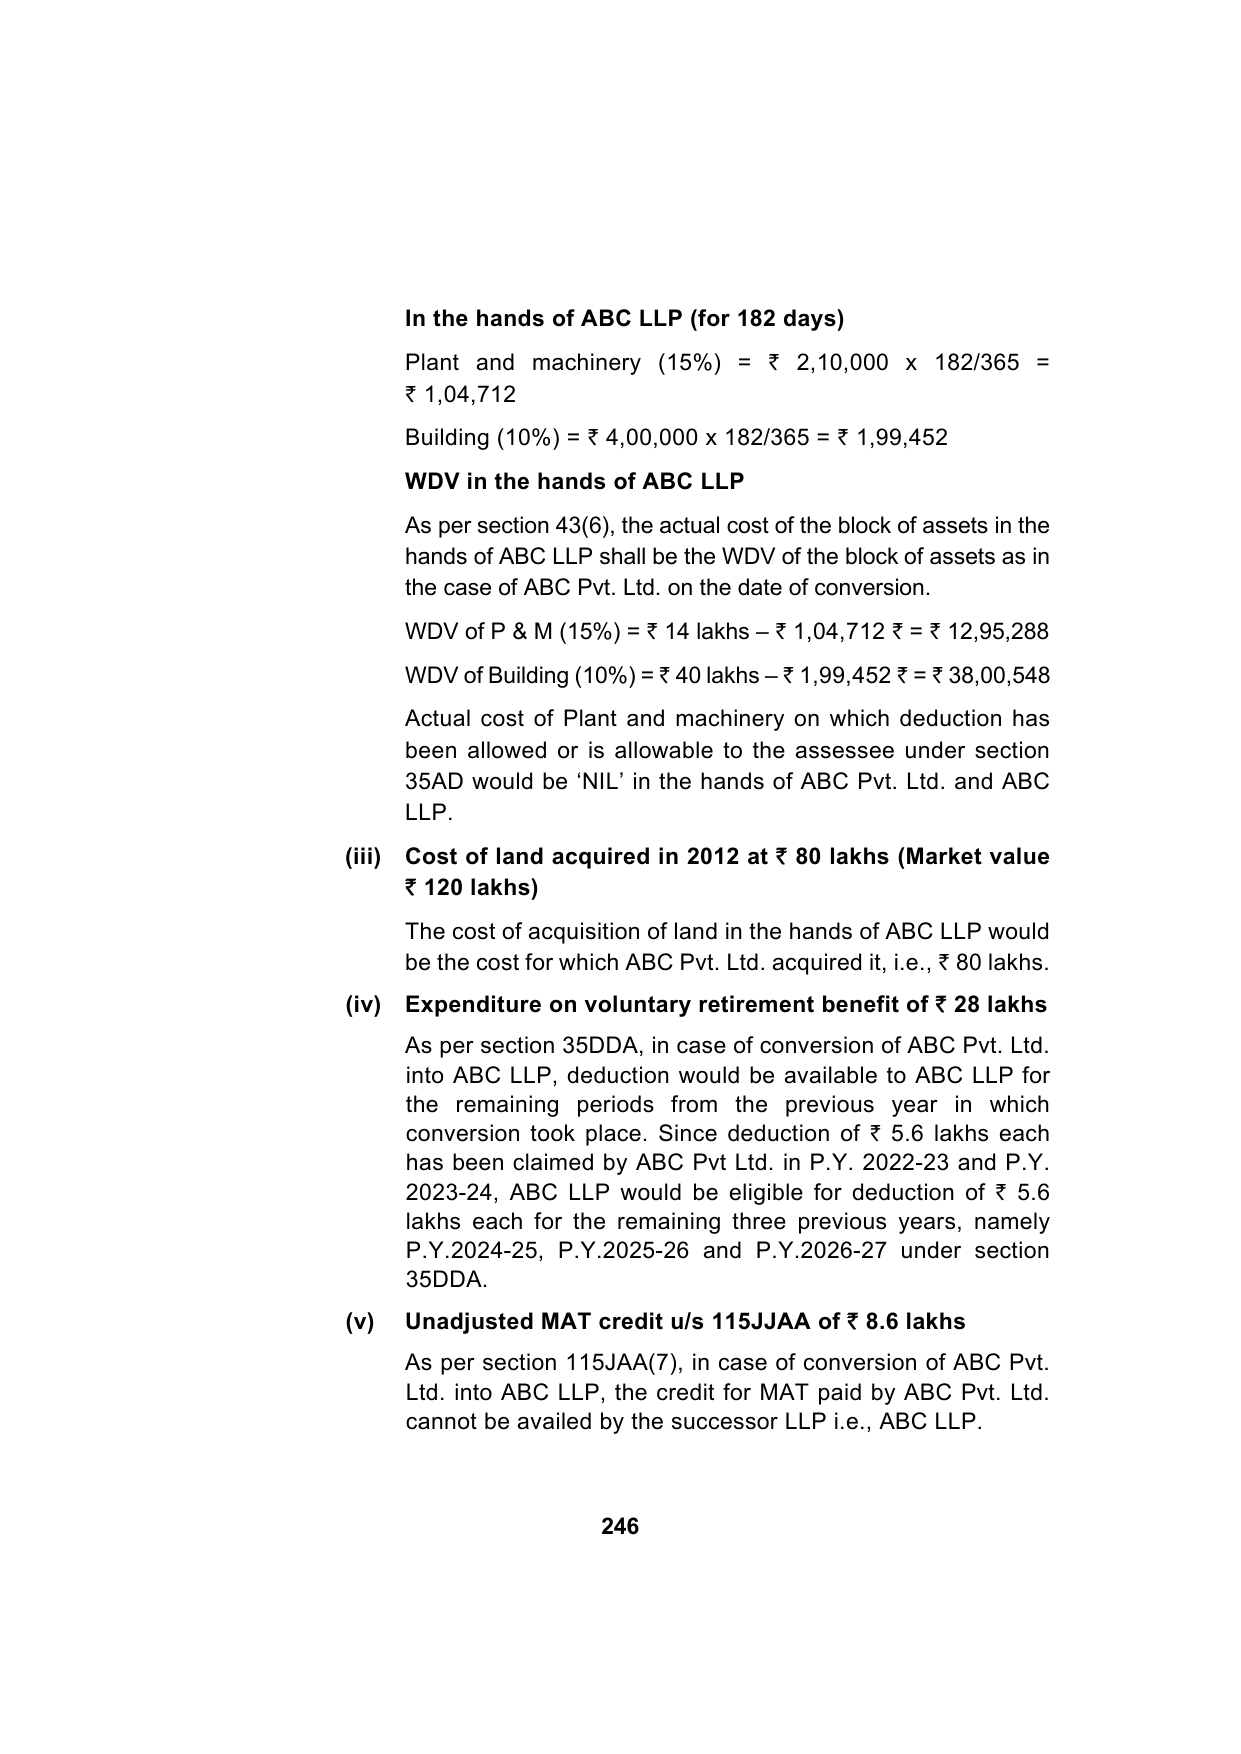
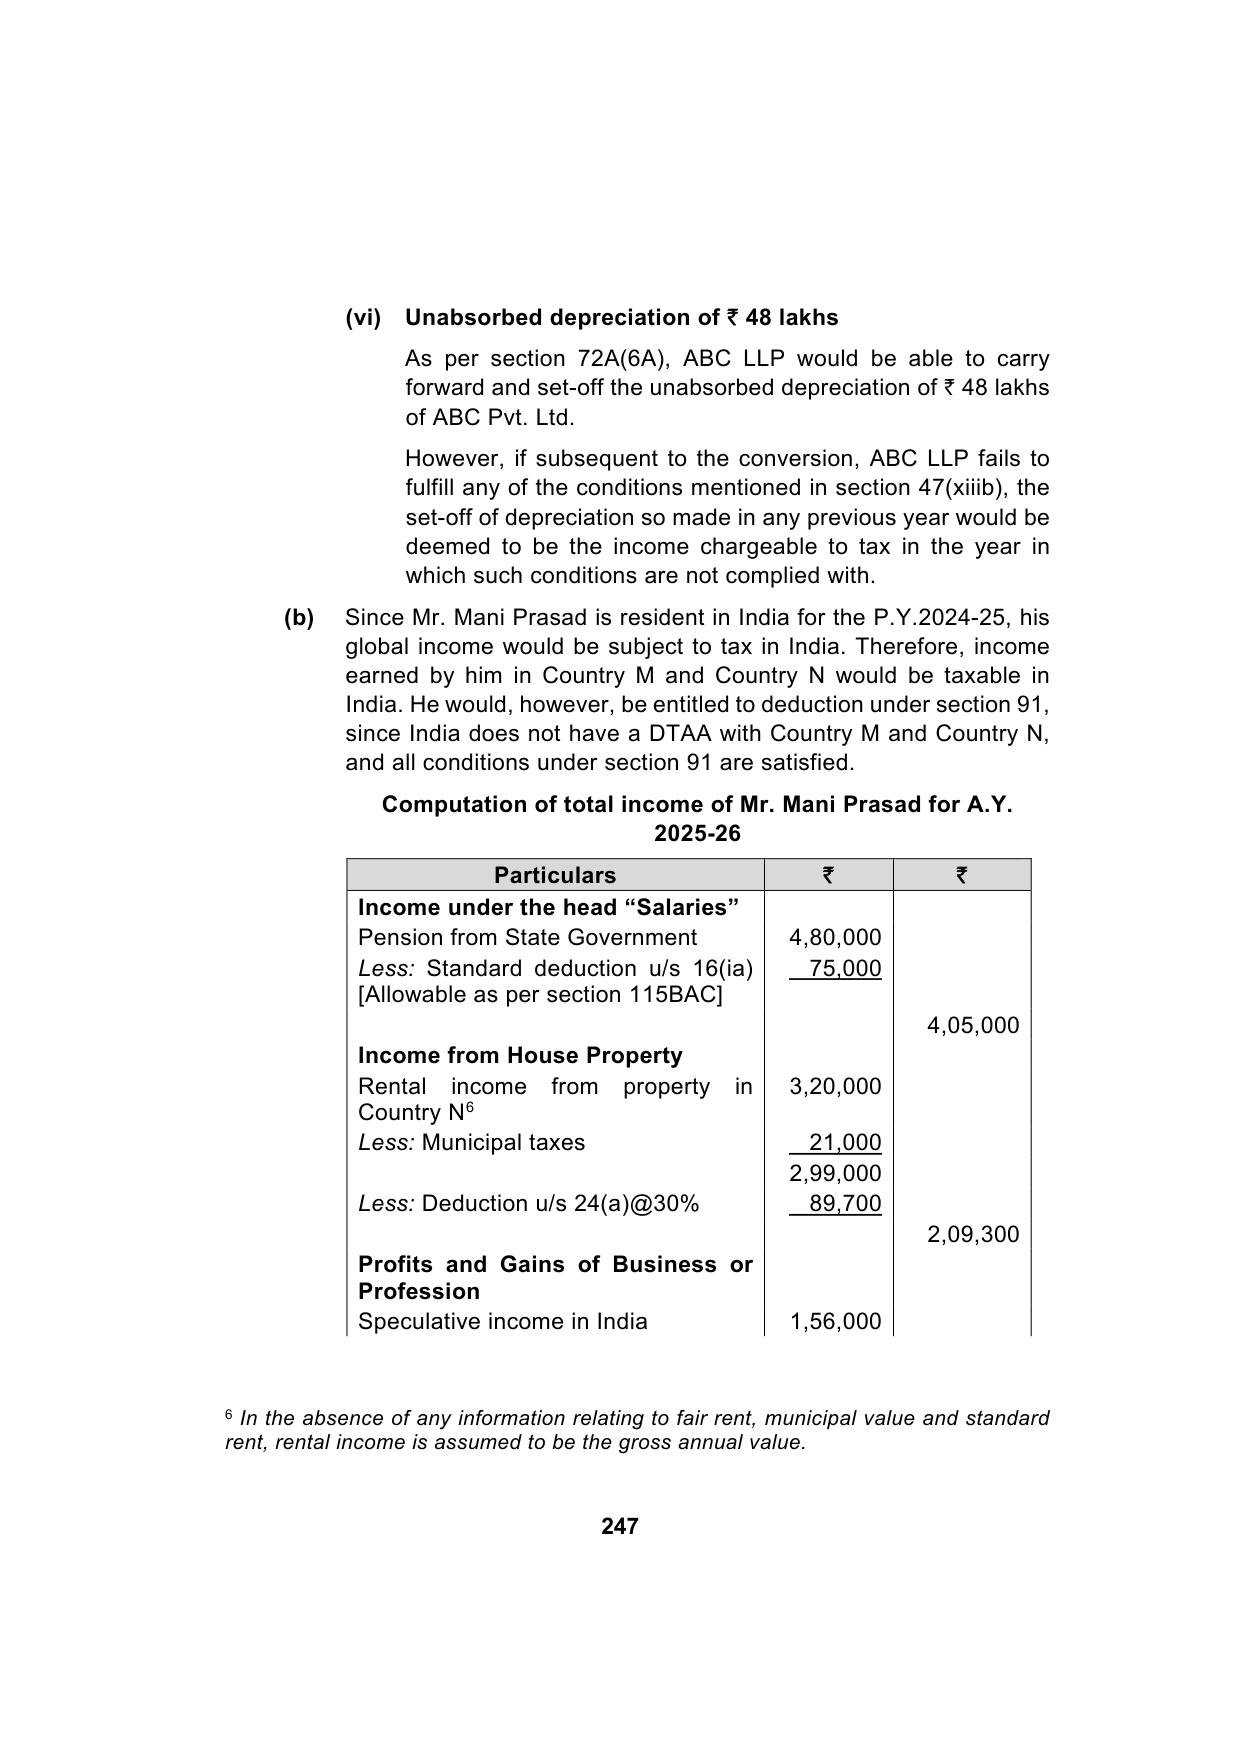
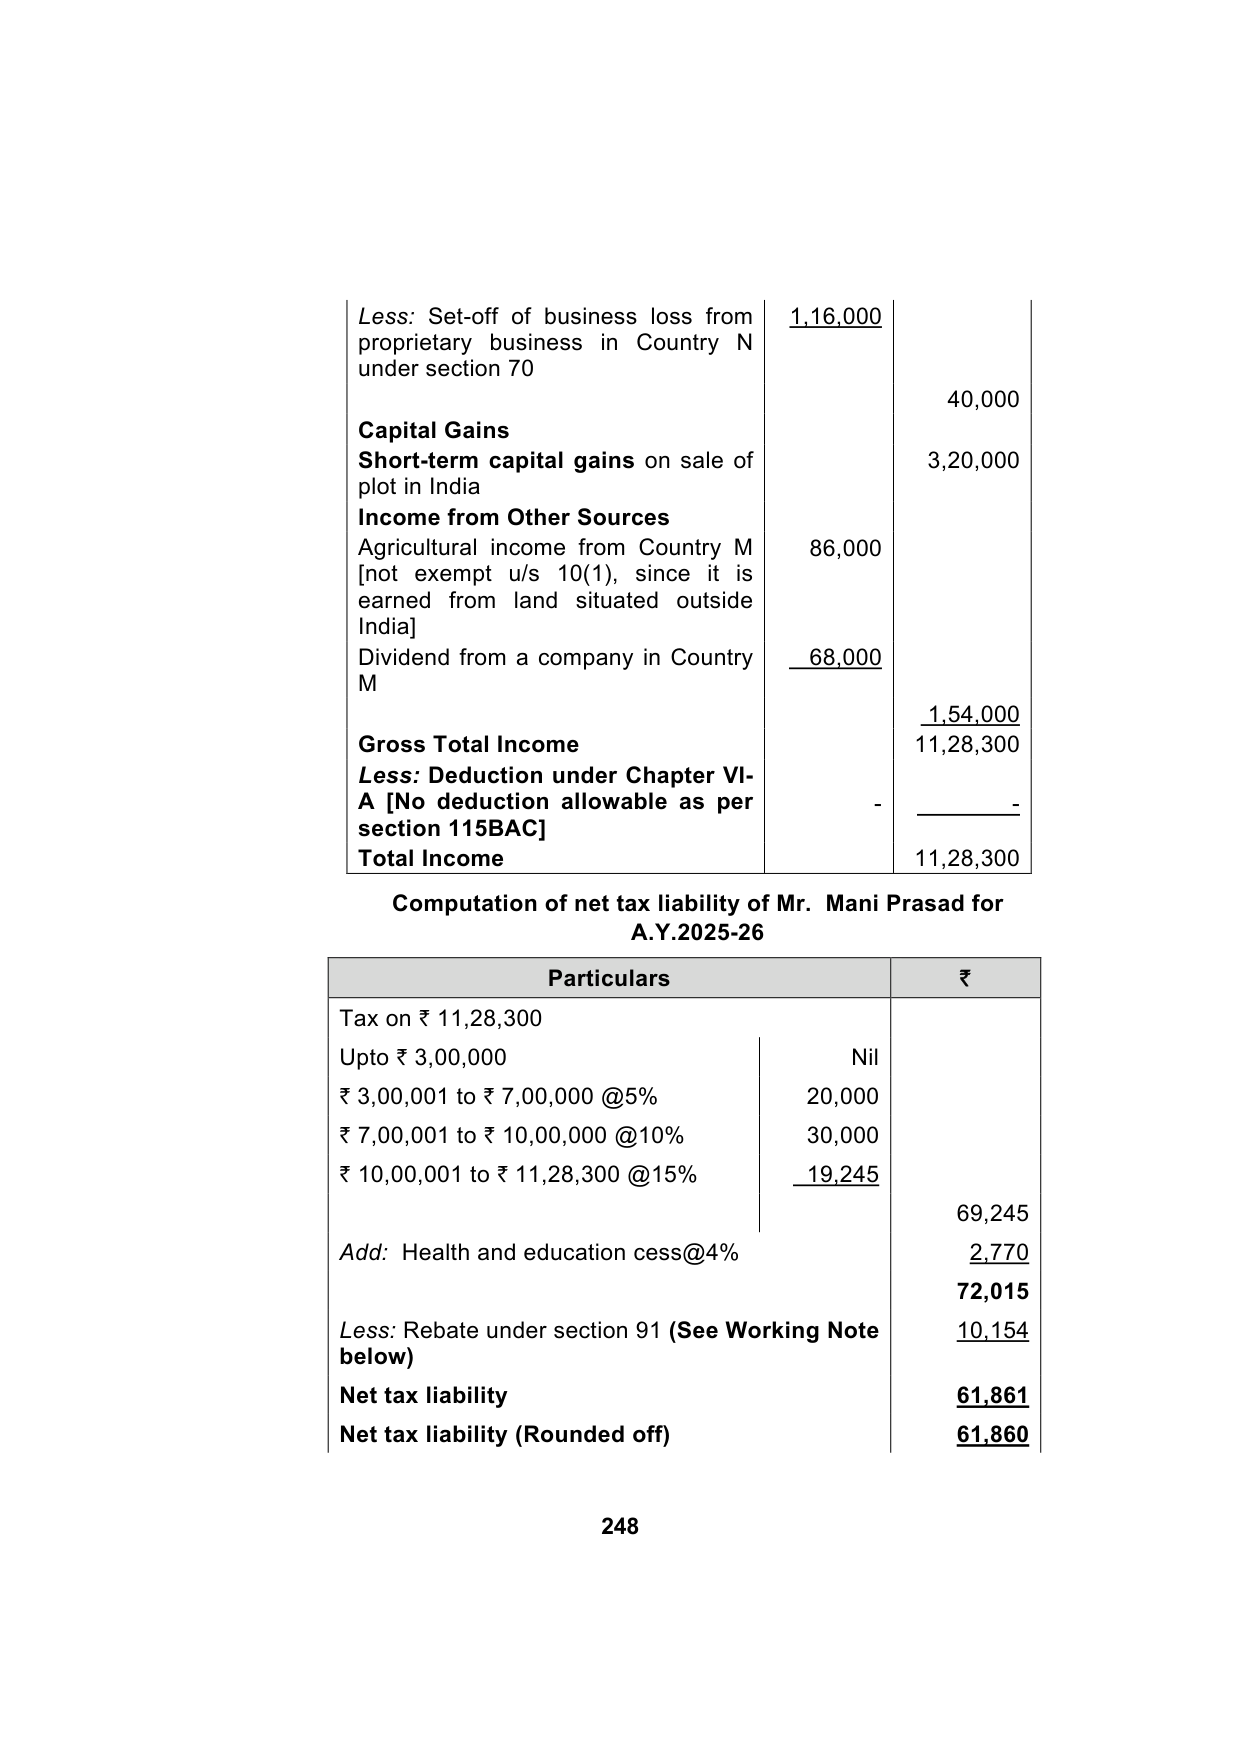
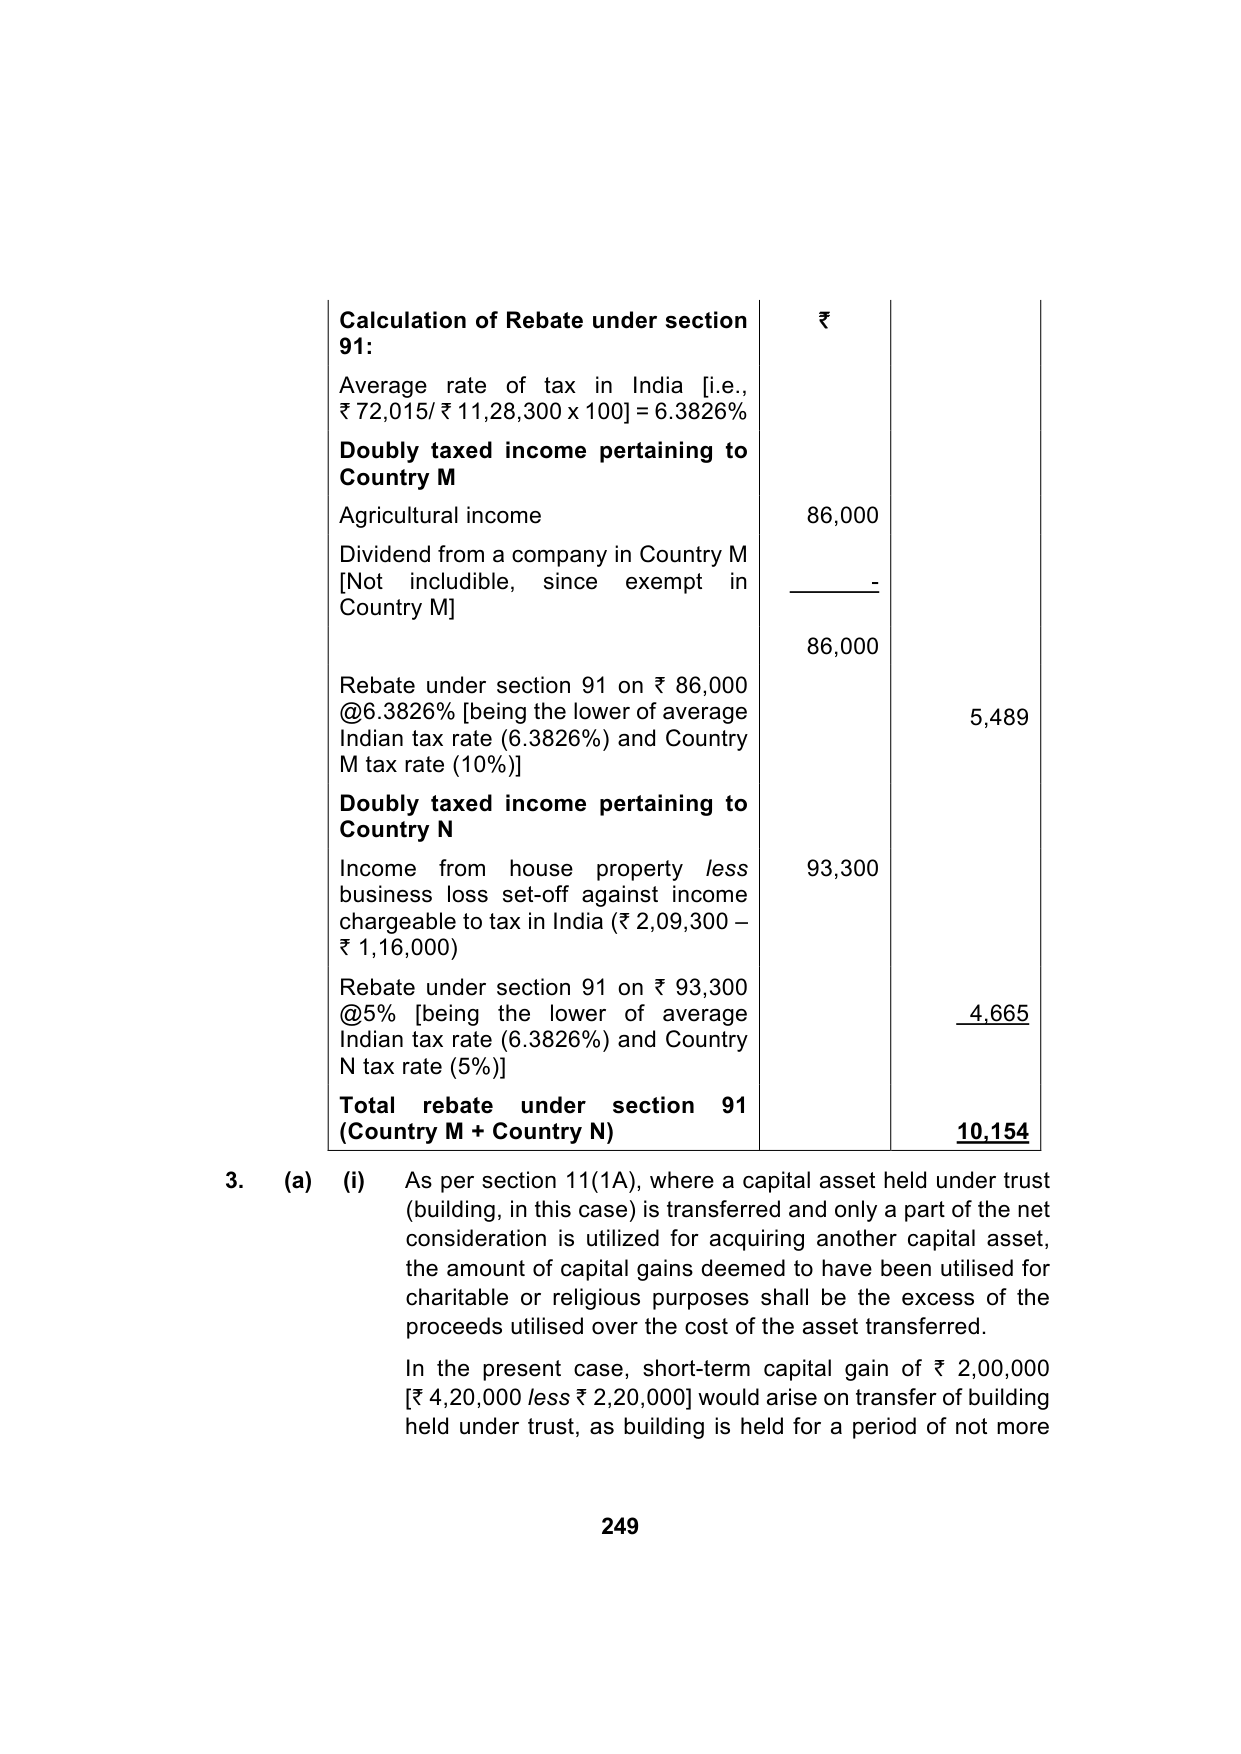
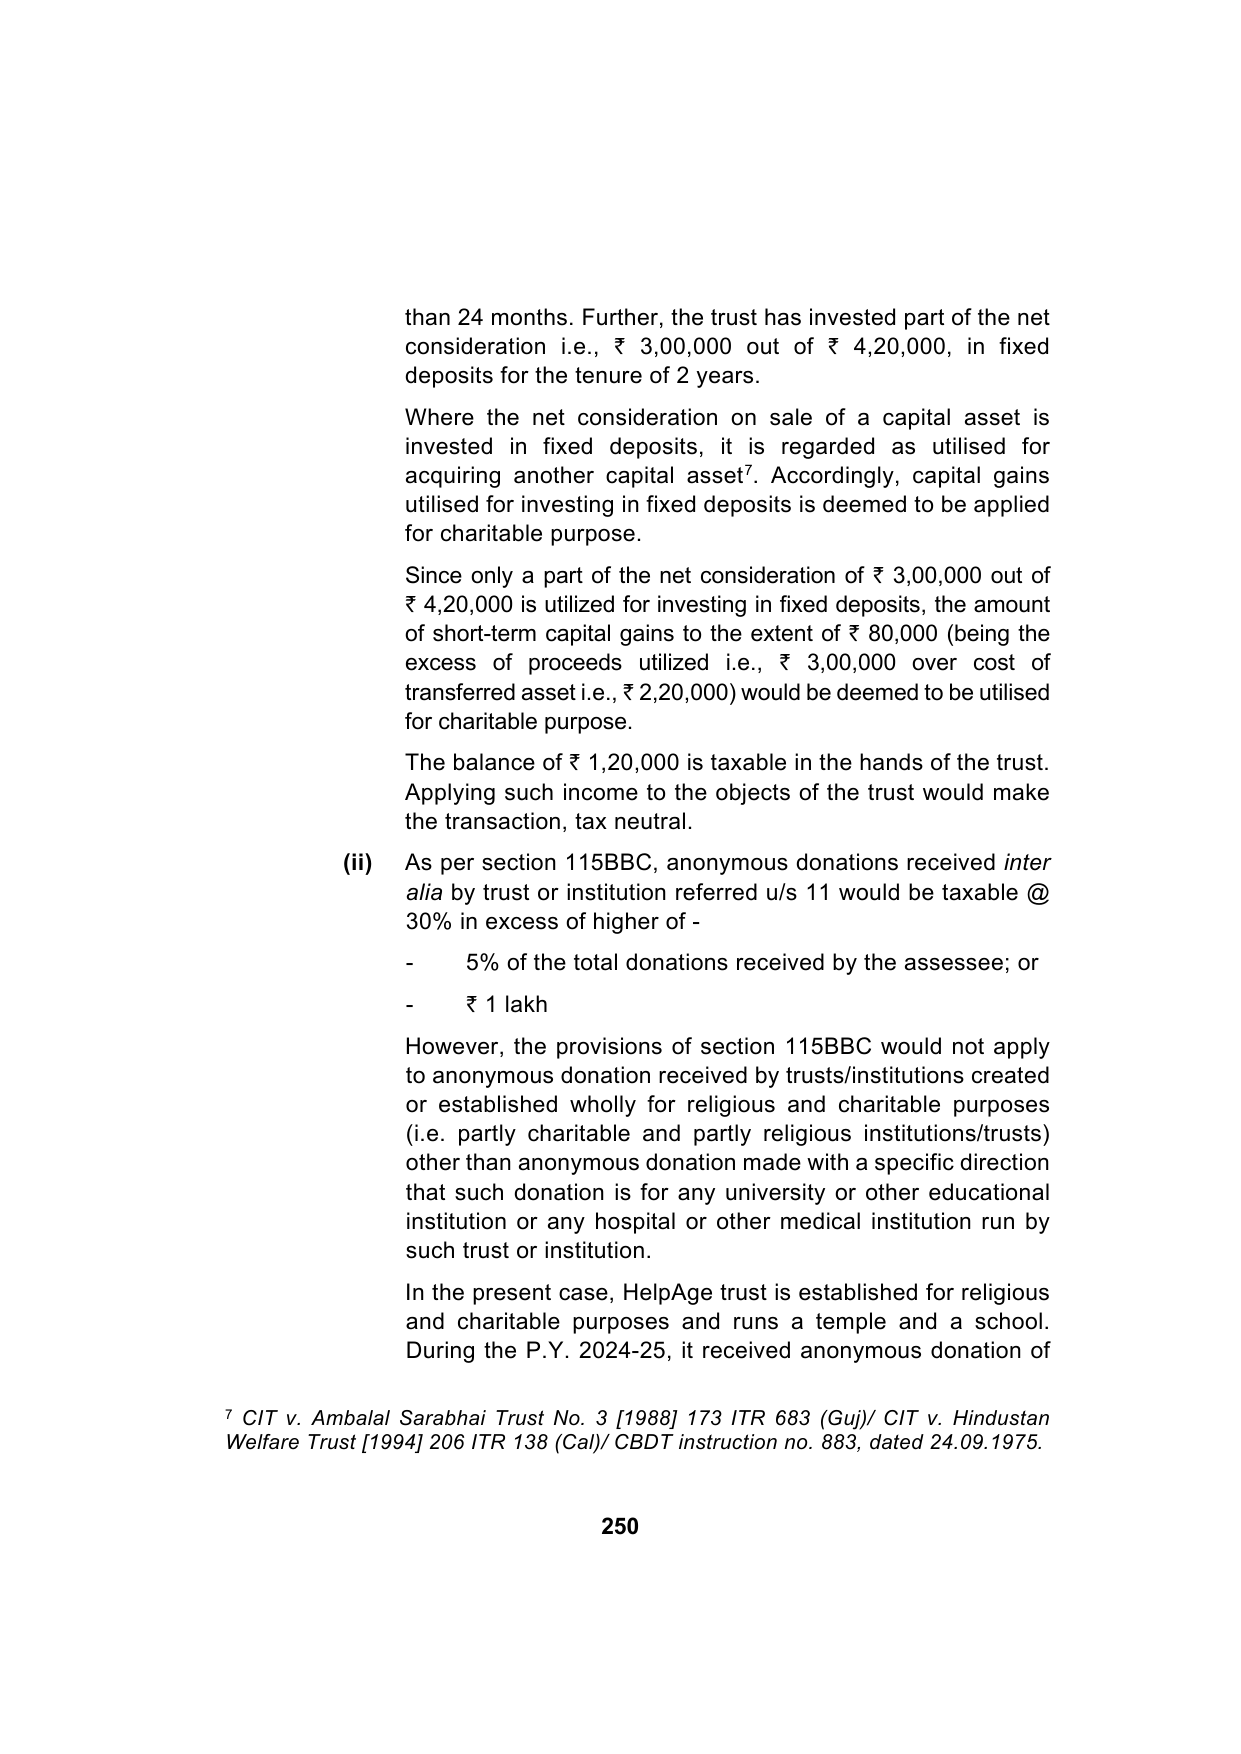
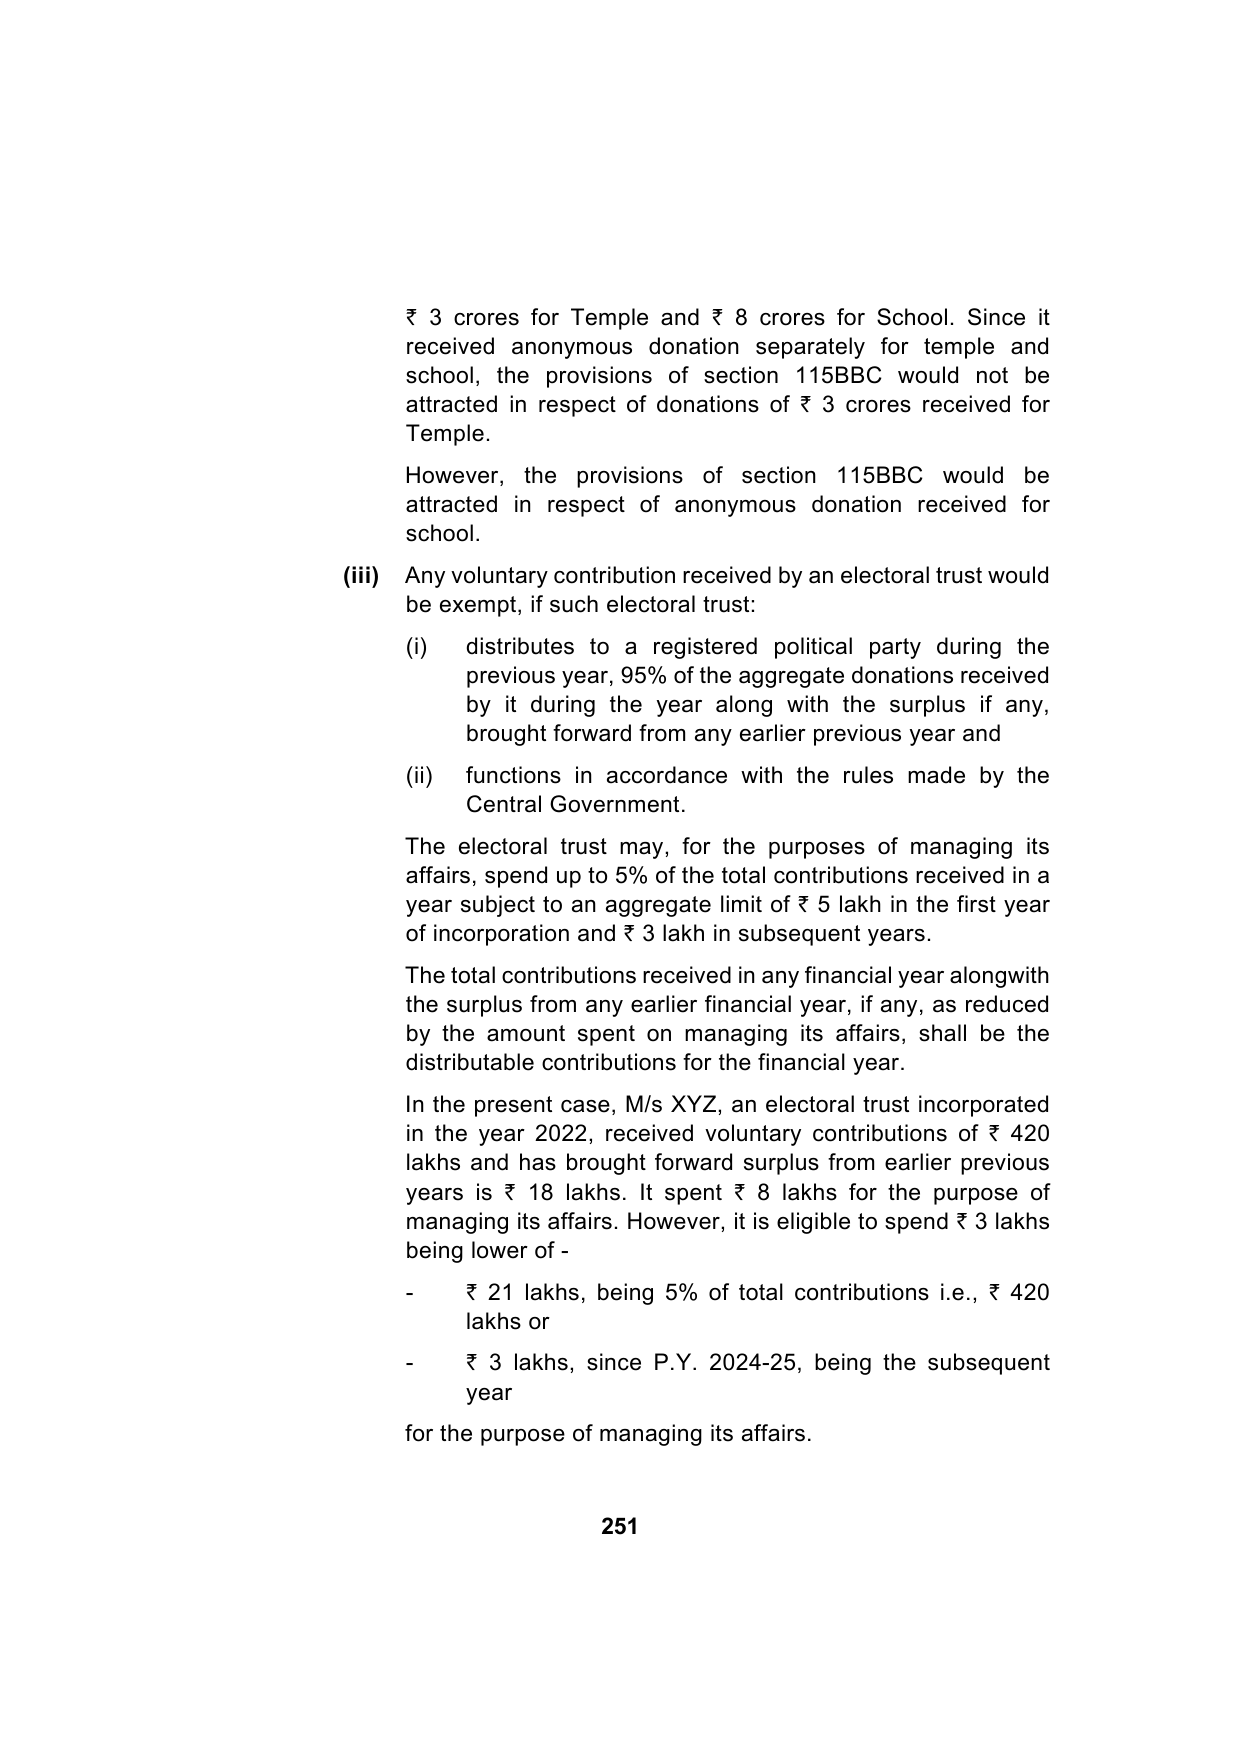
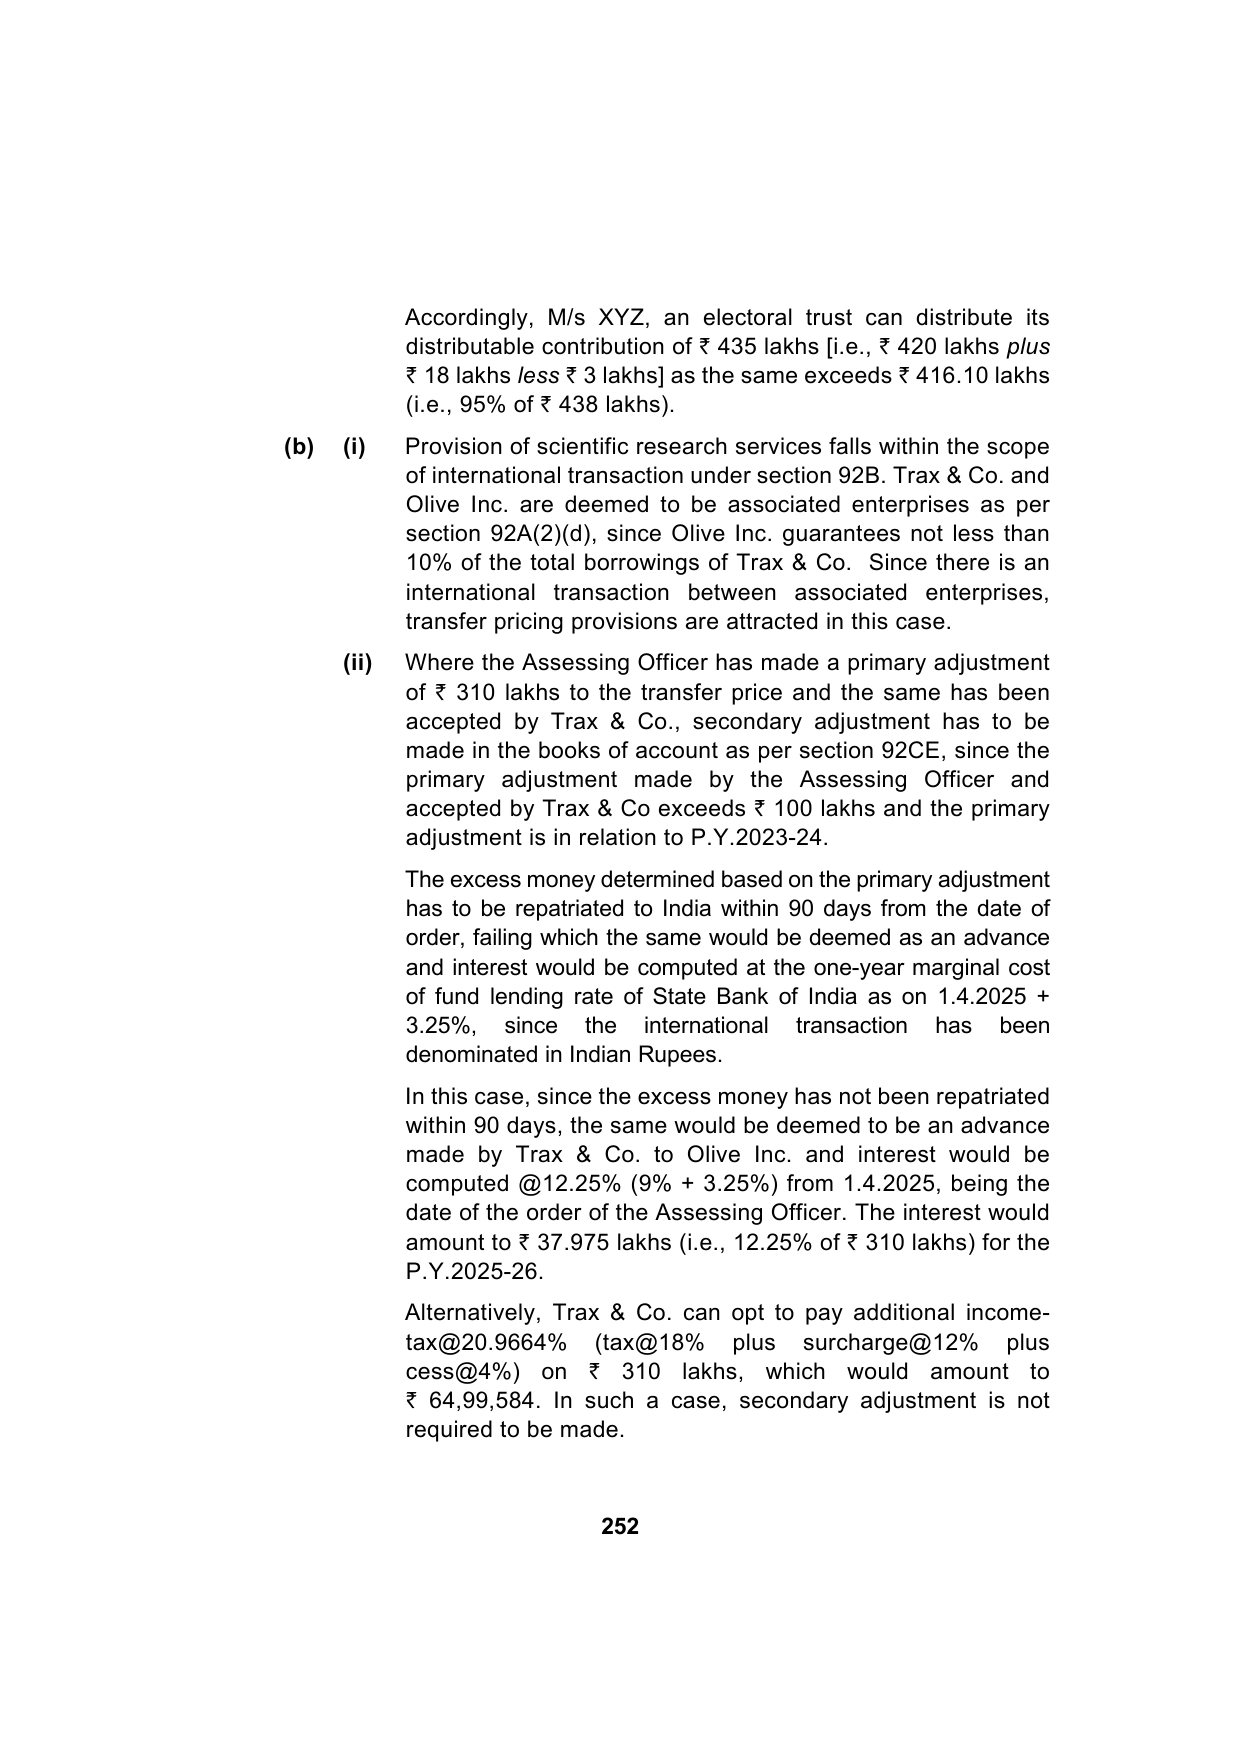
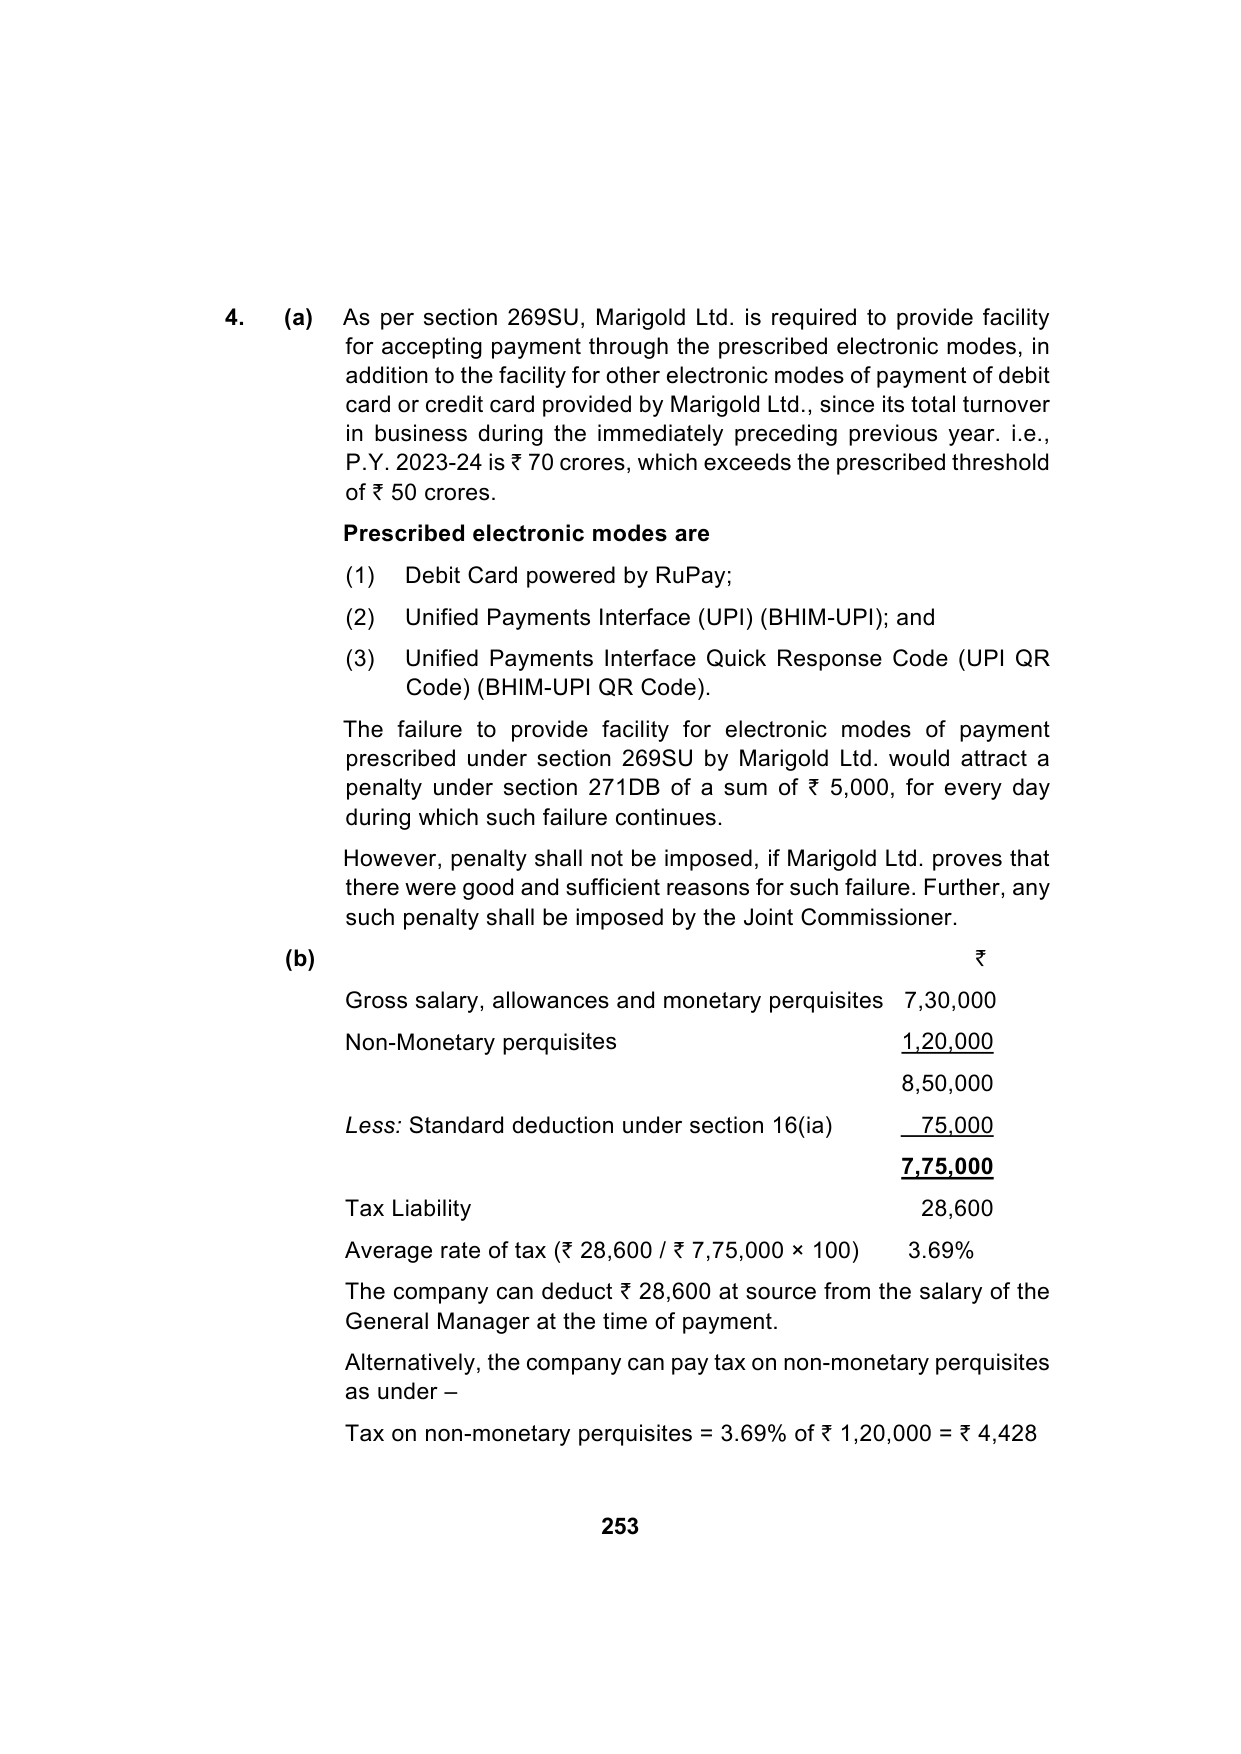
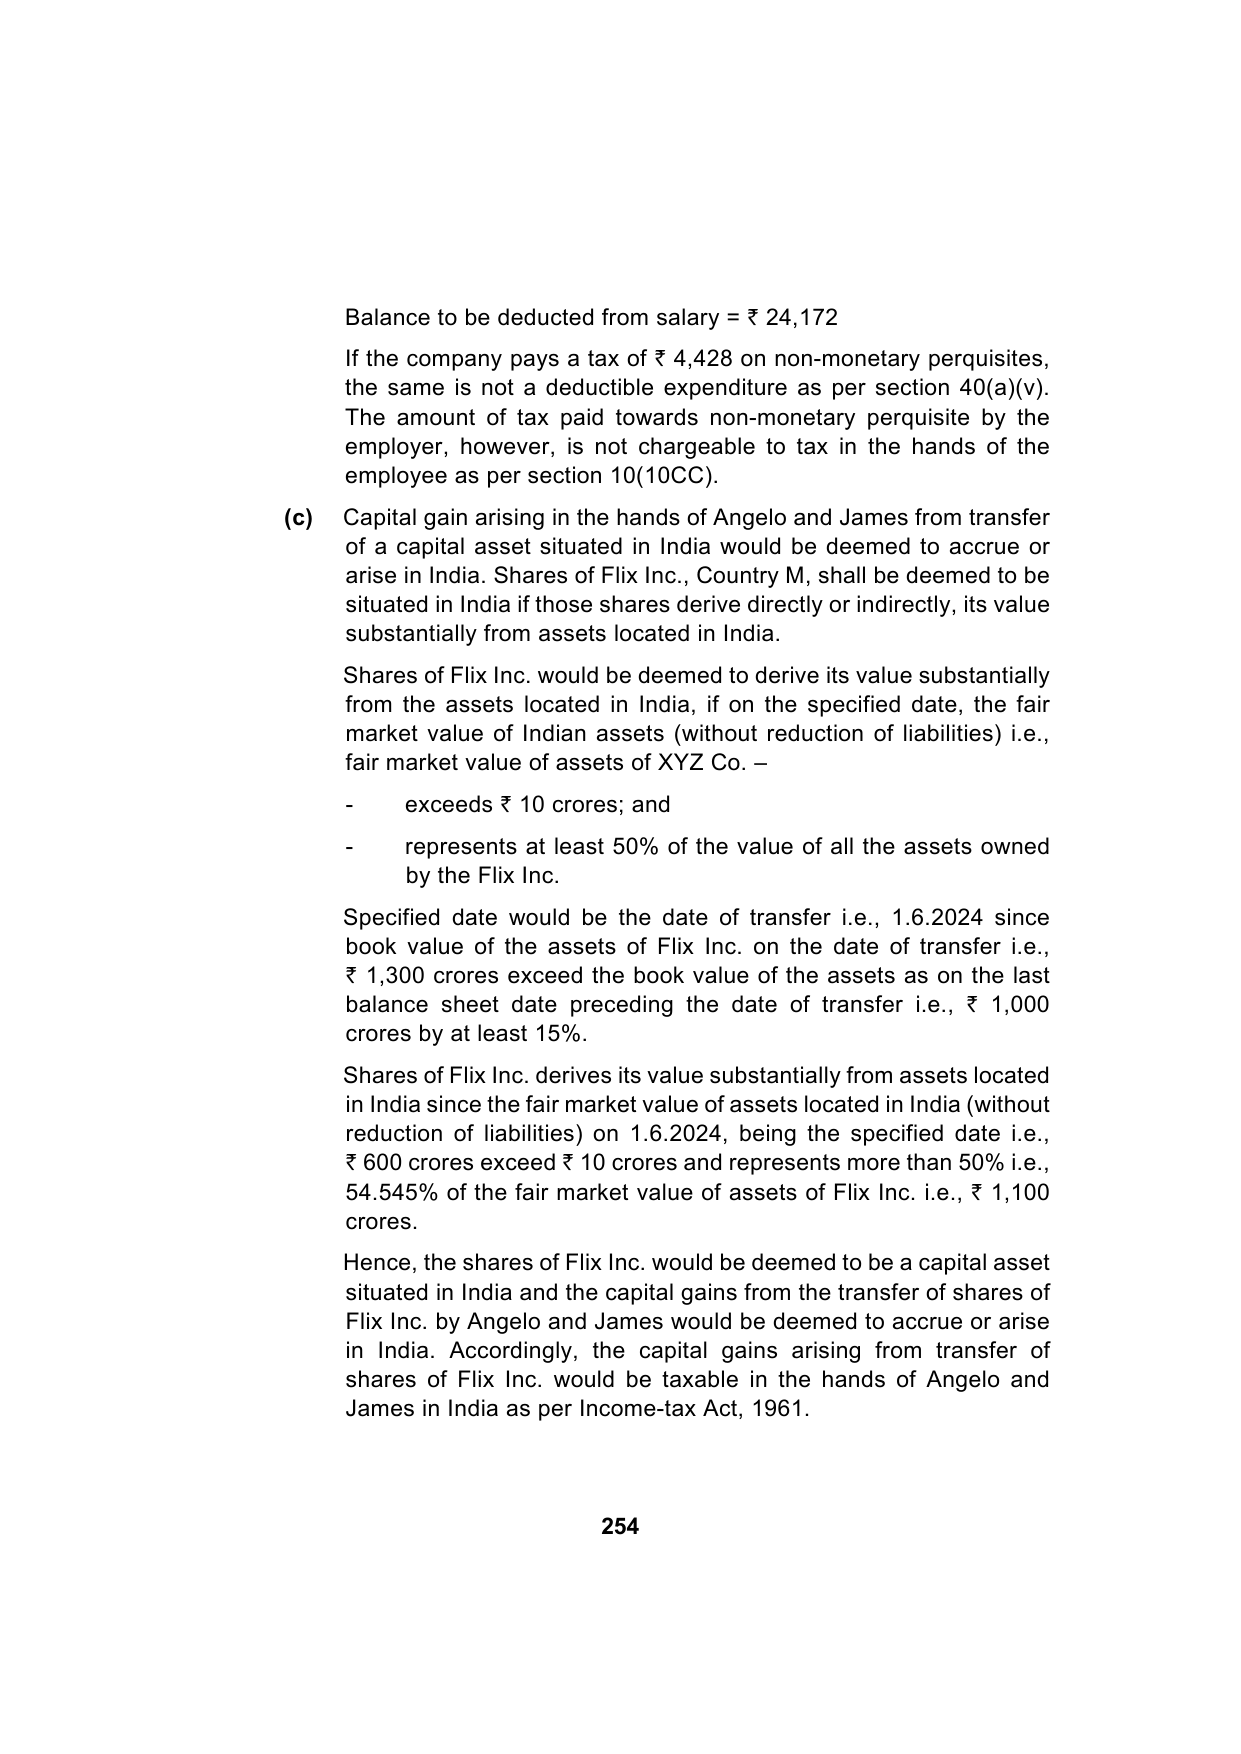
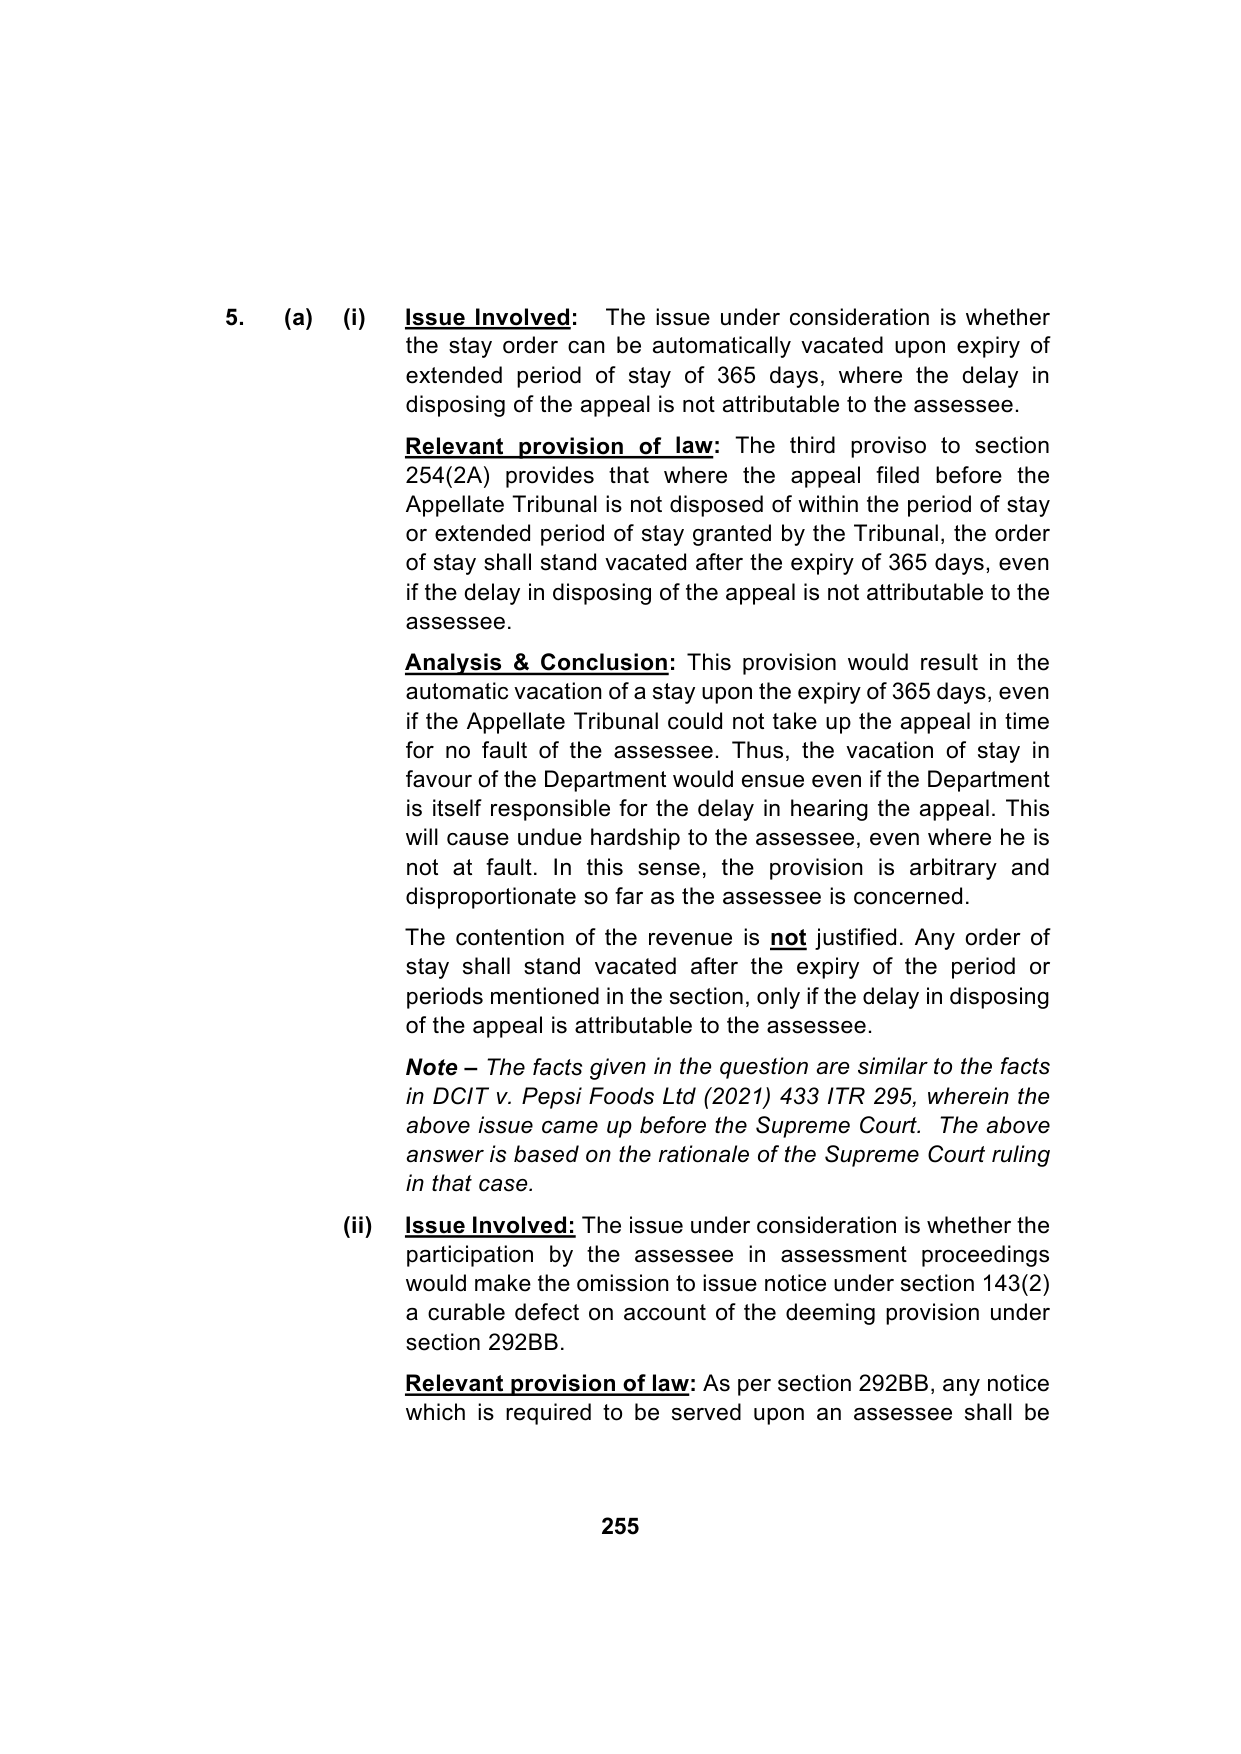
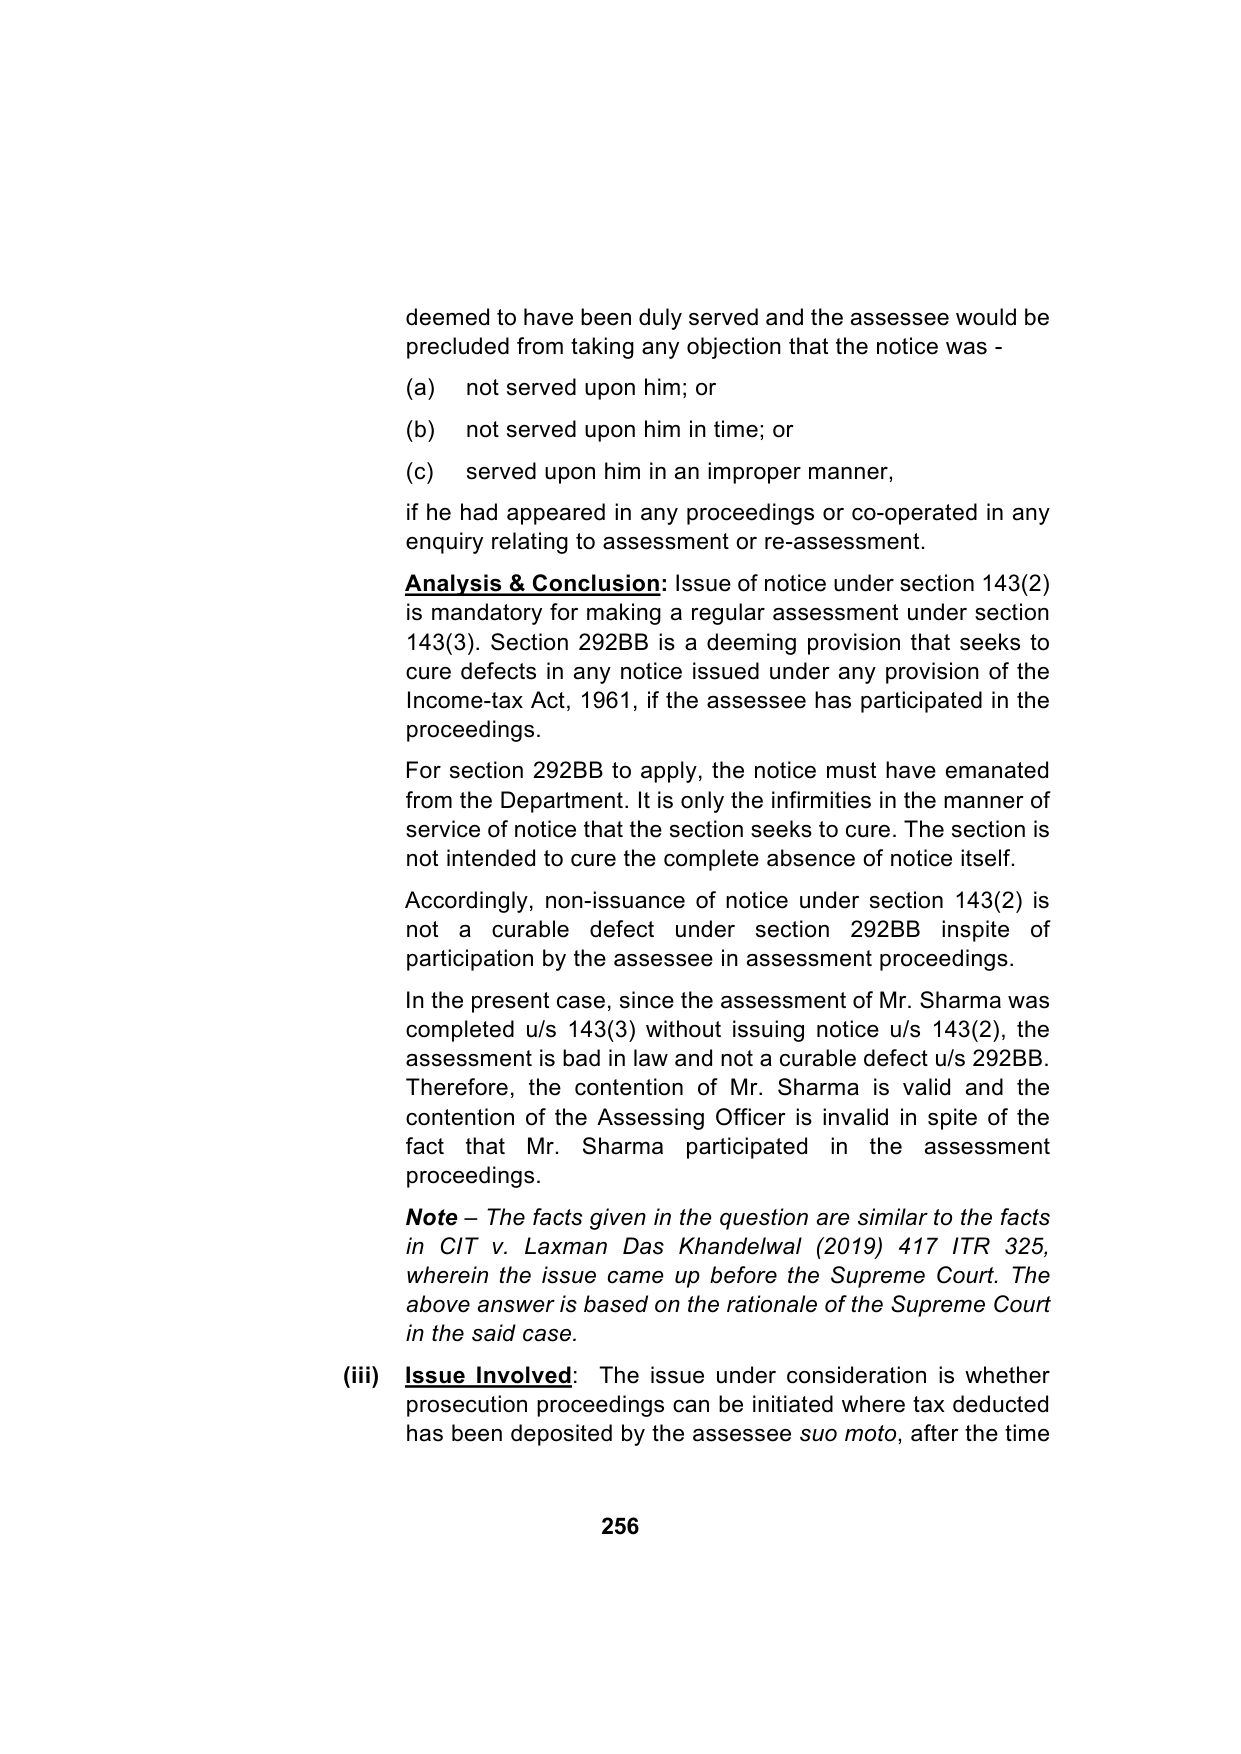
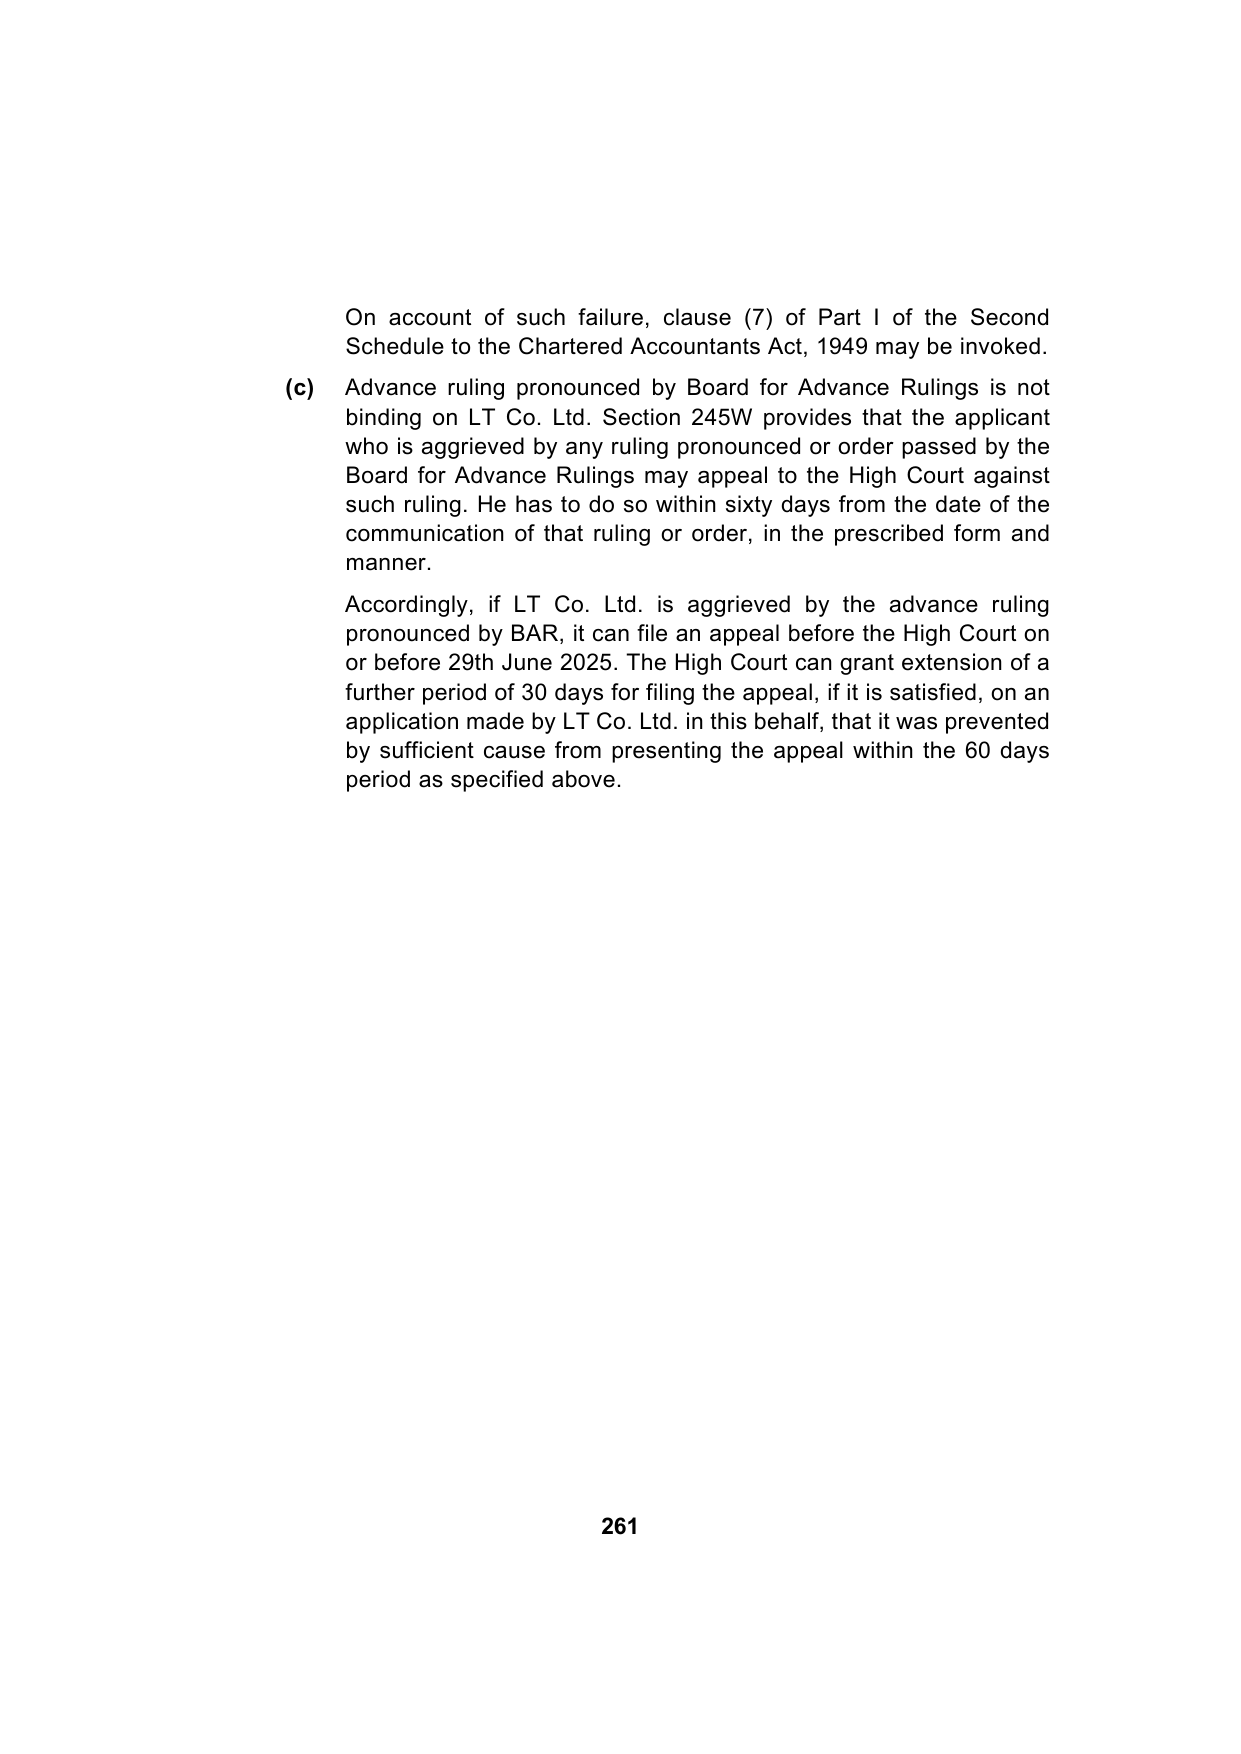
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 3
Question
Answer
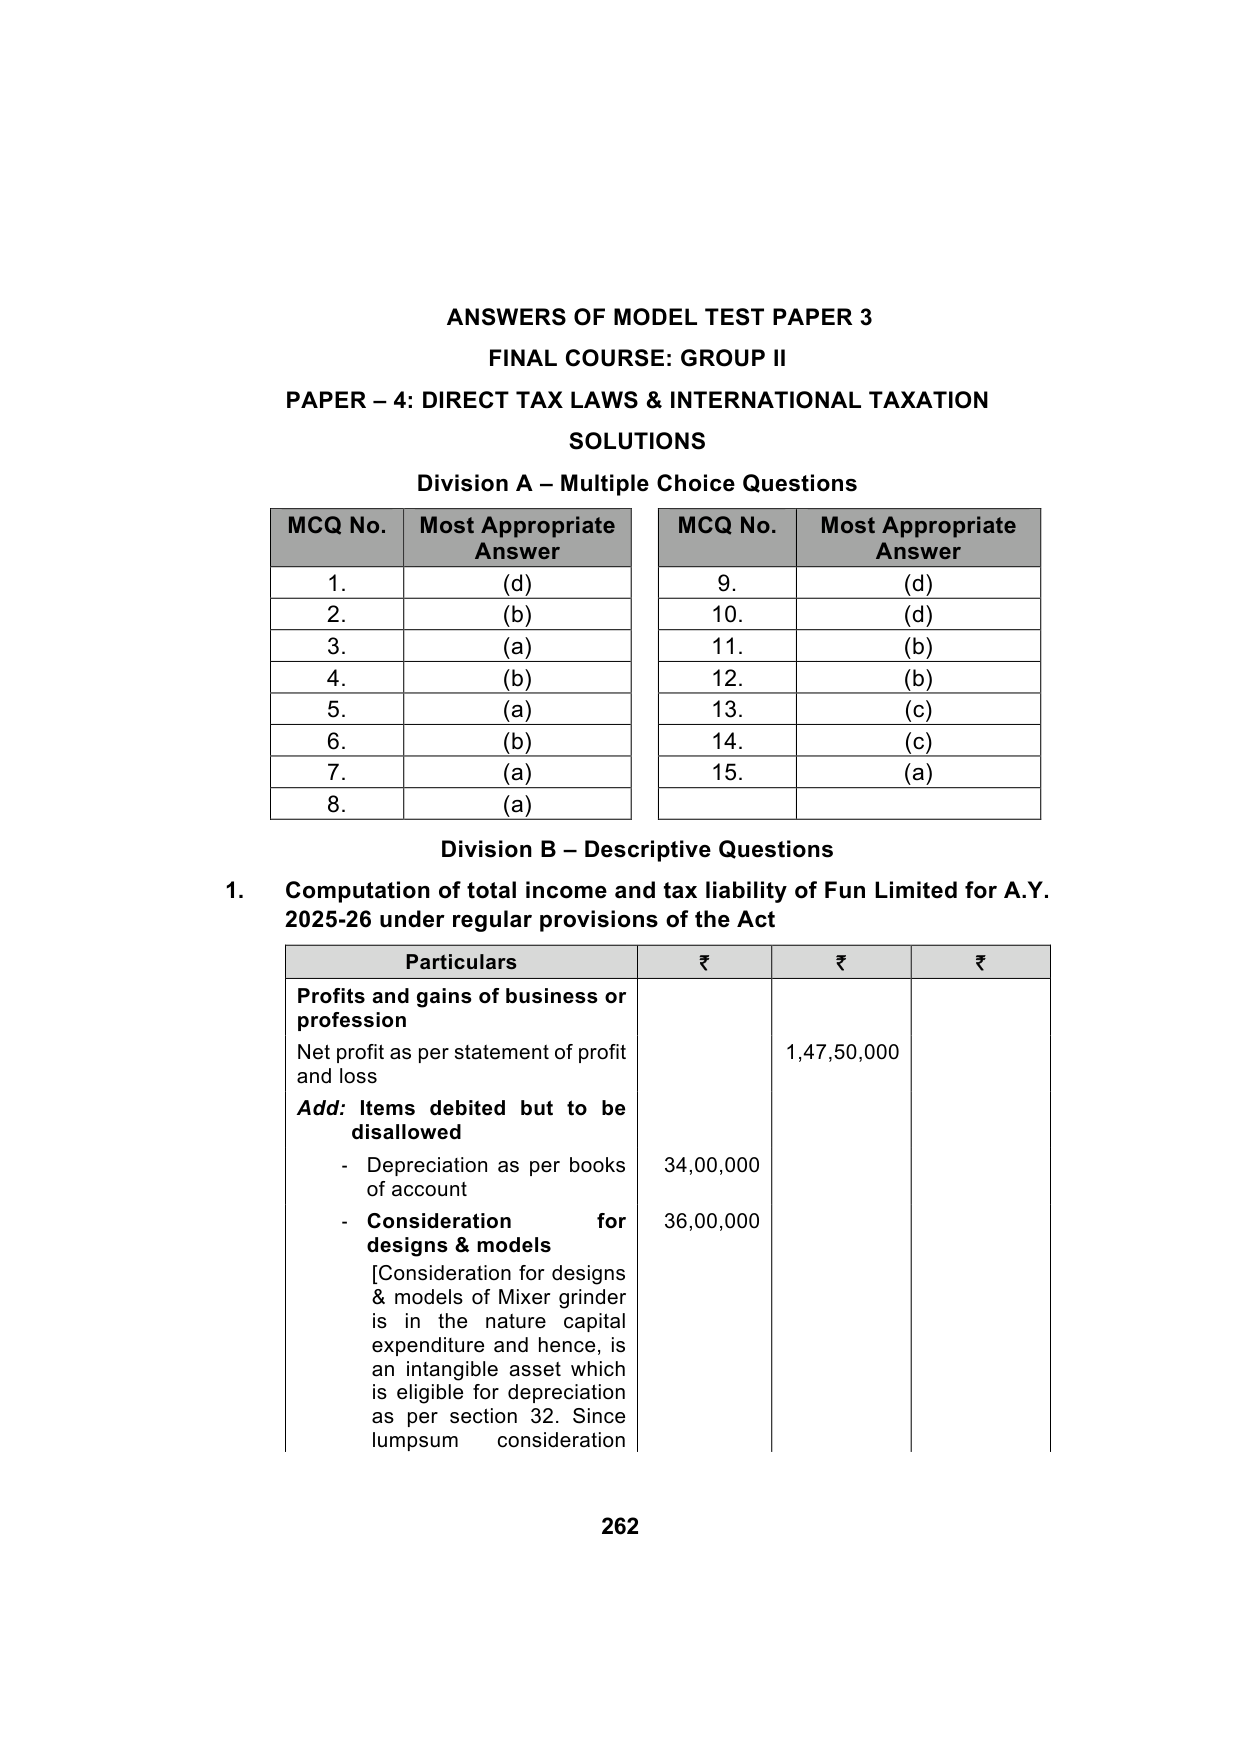
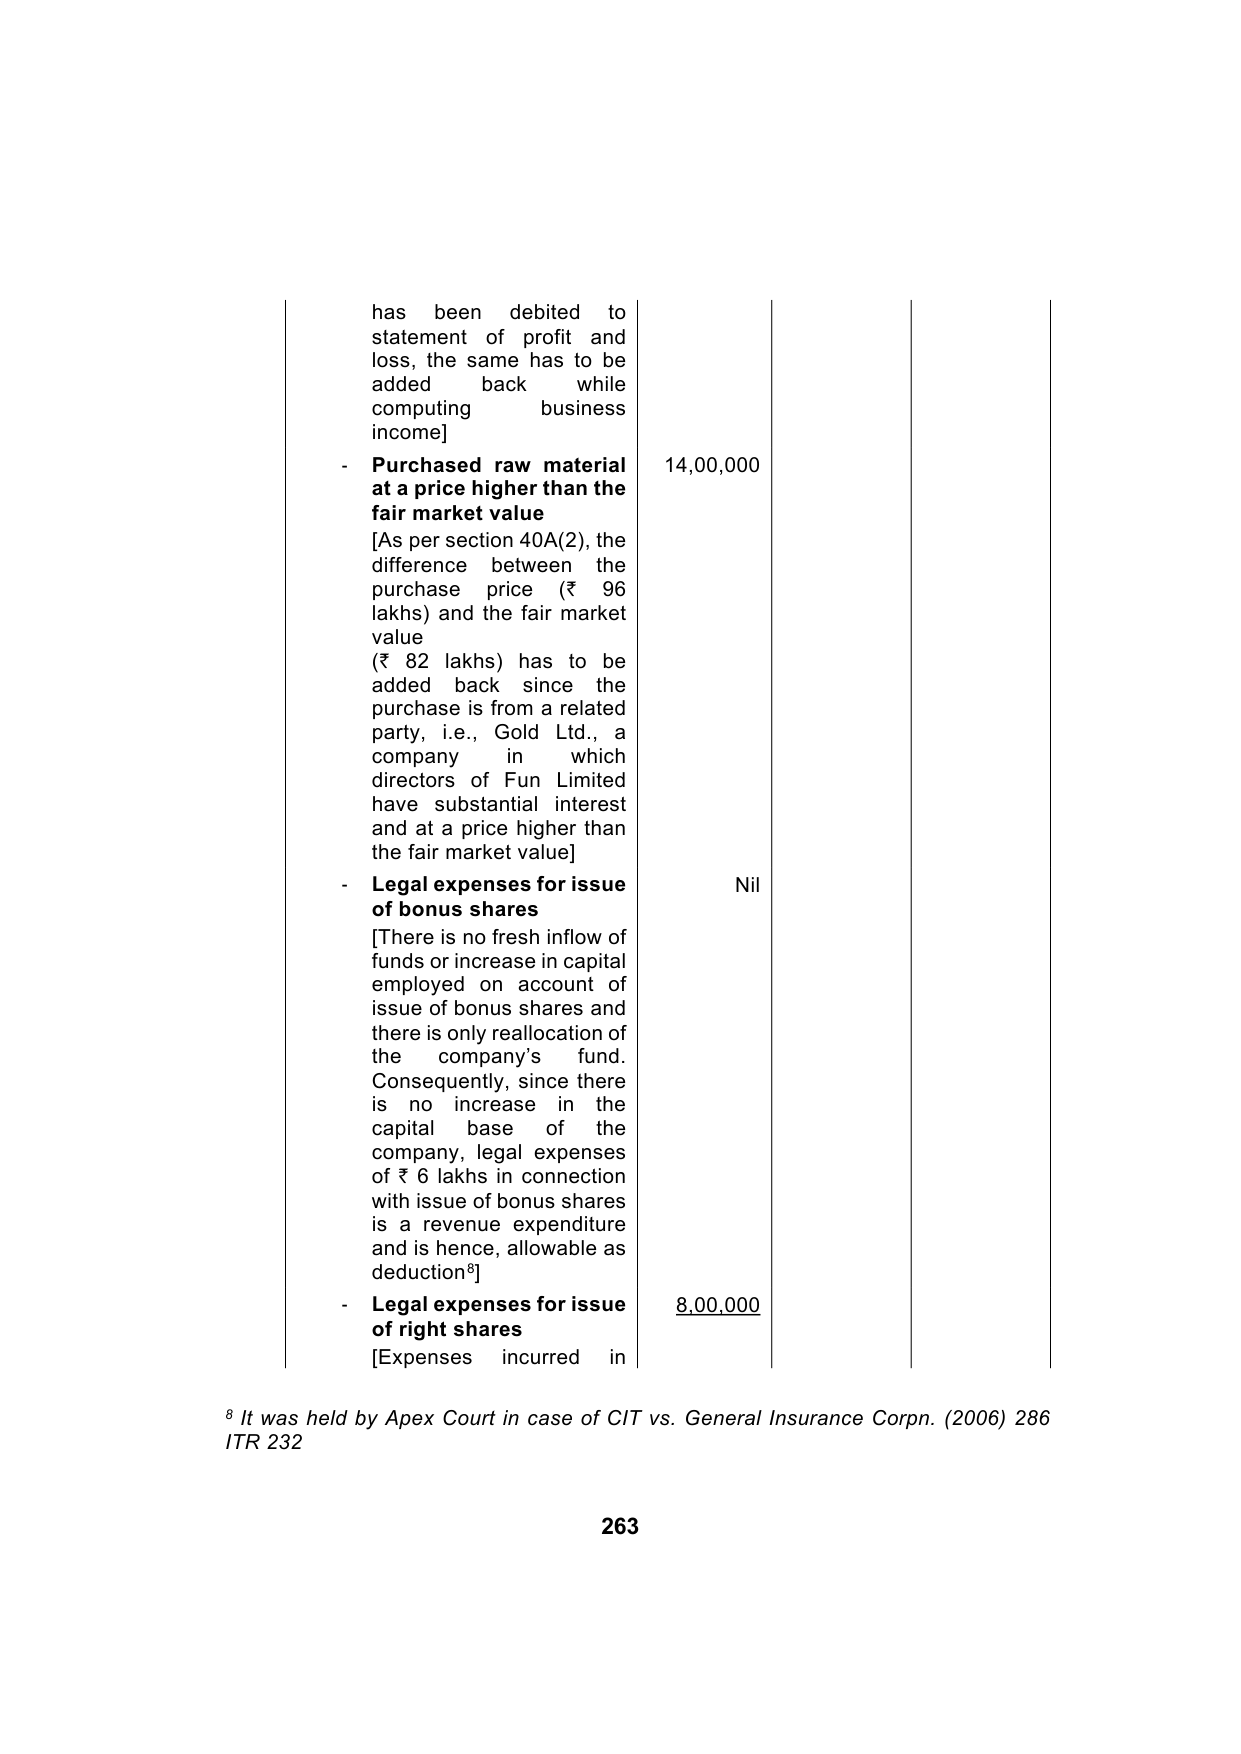
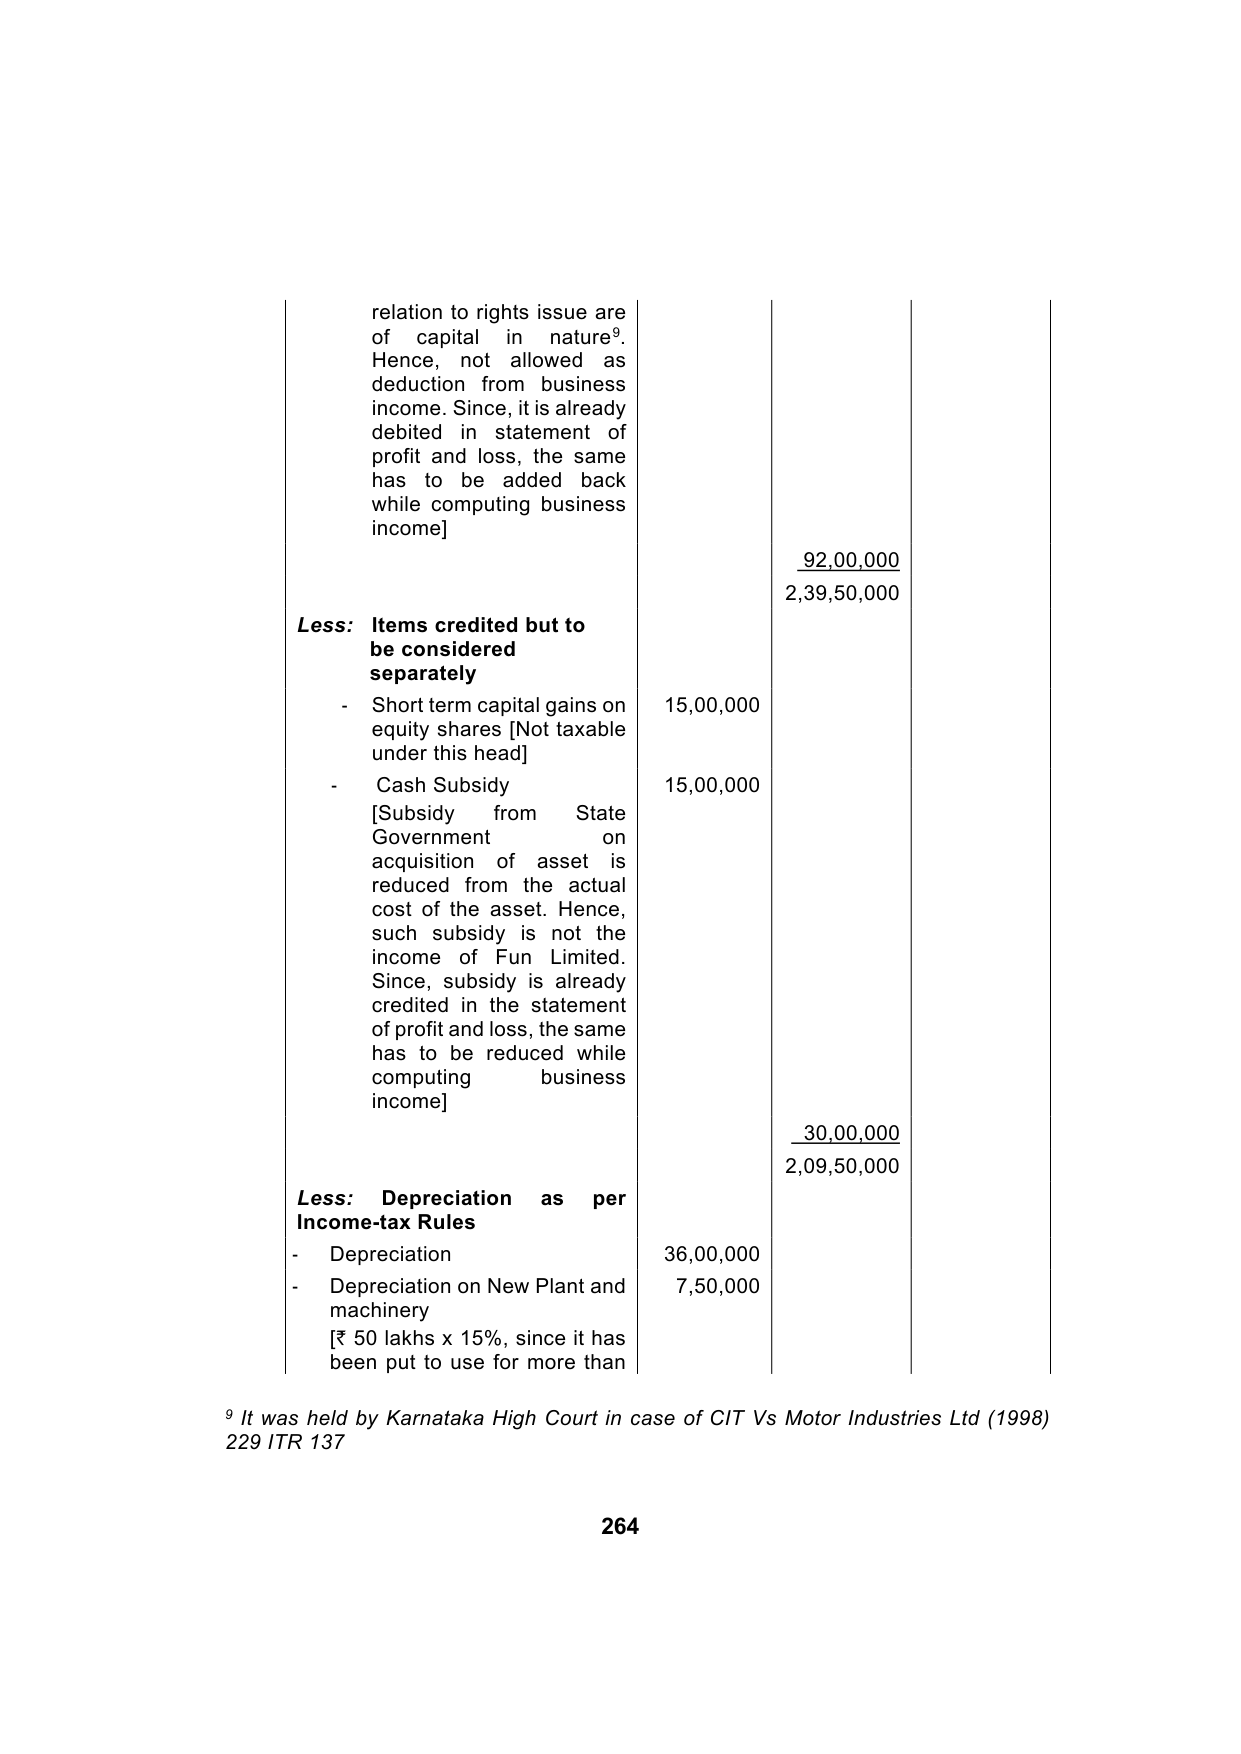
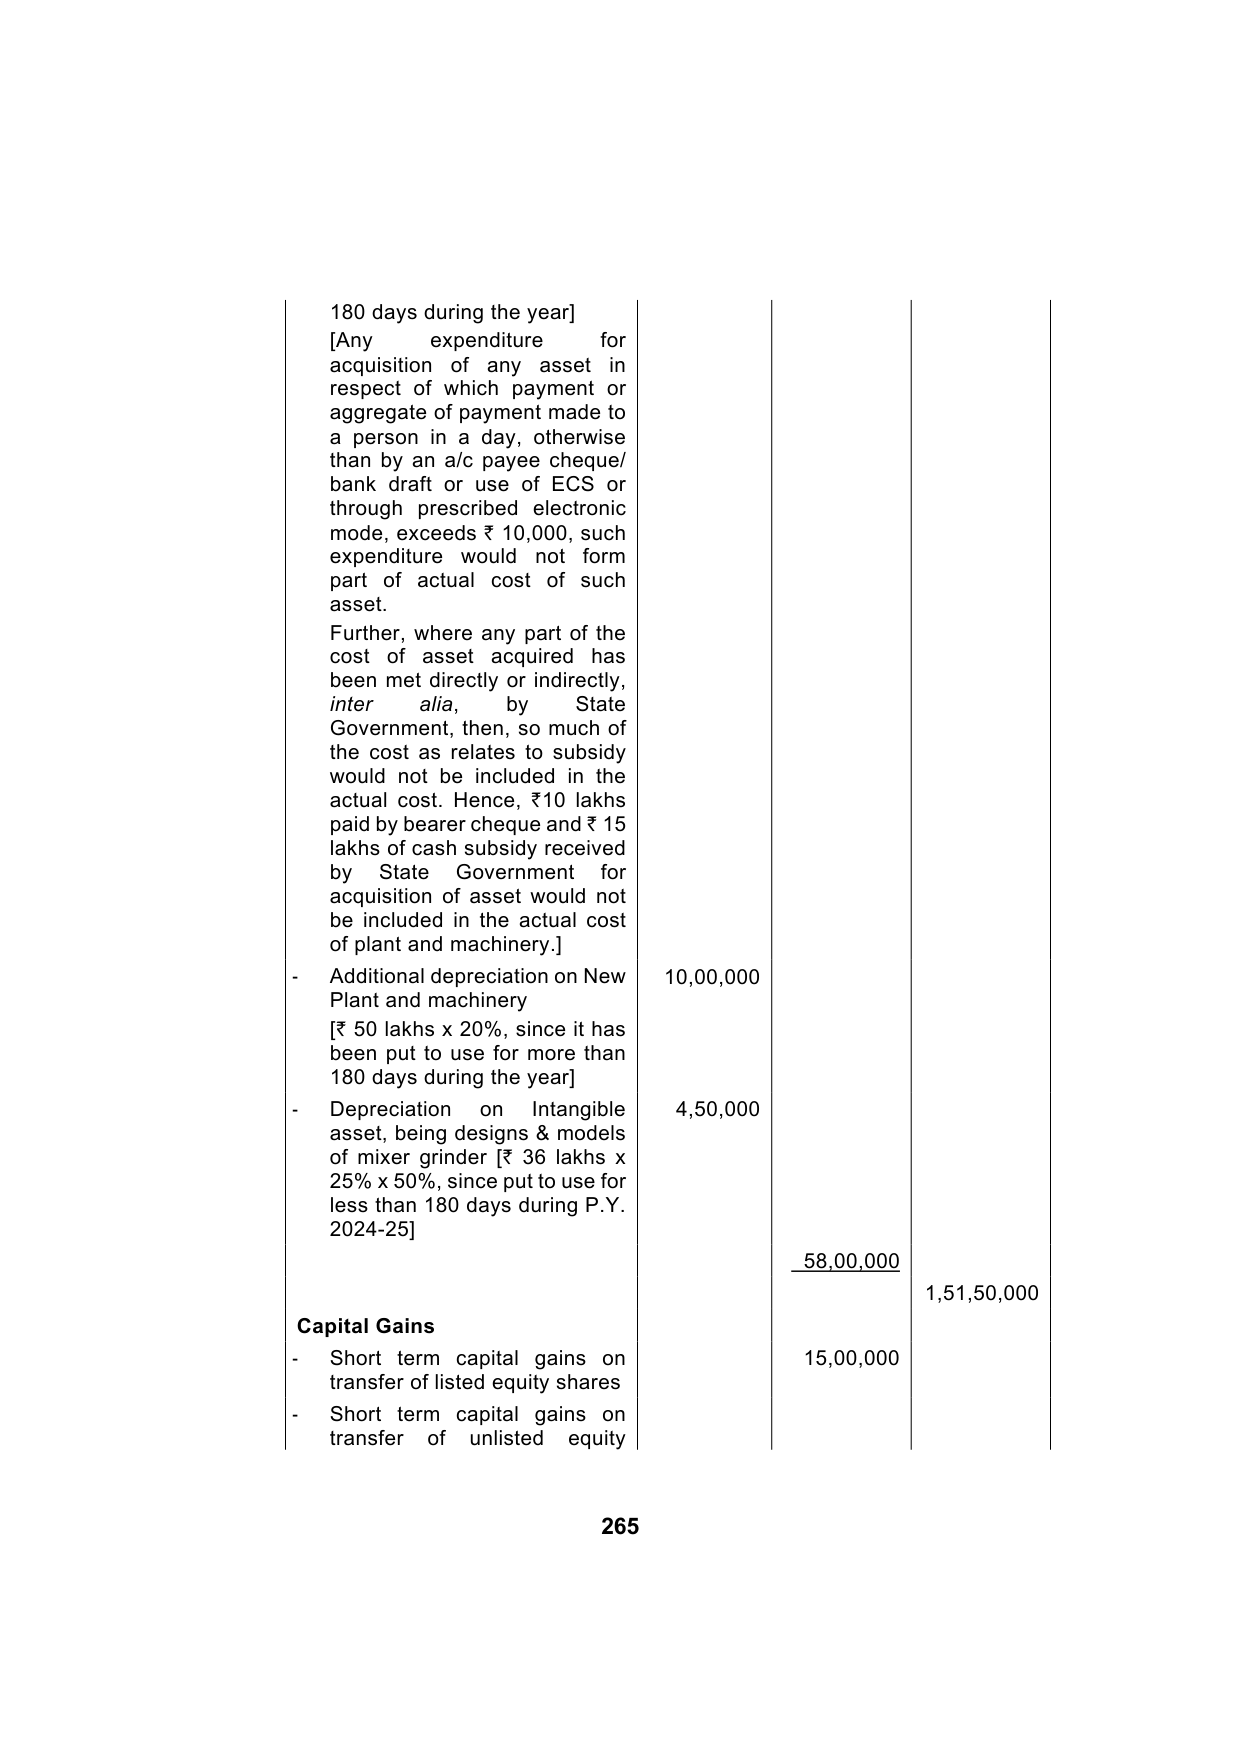
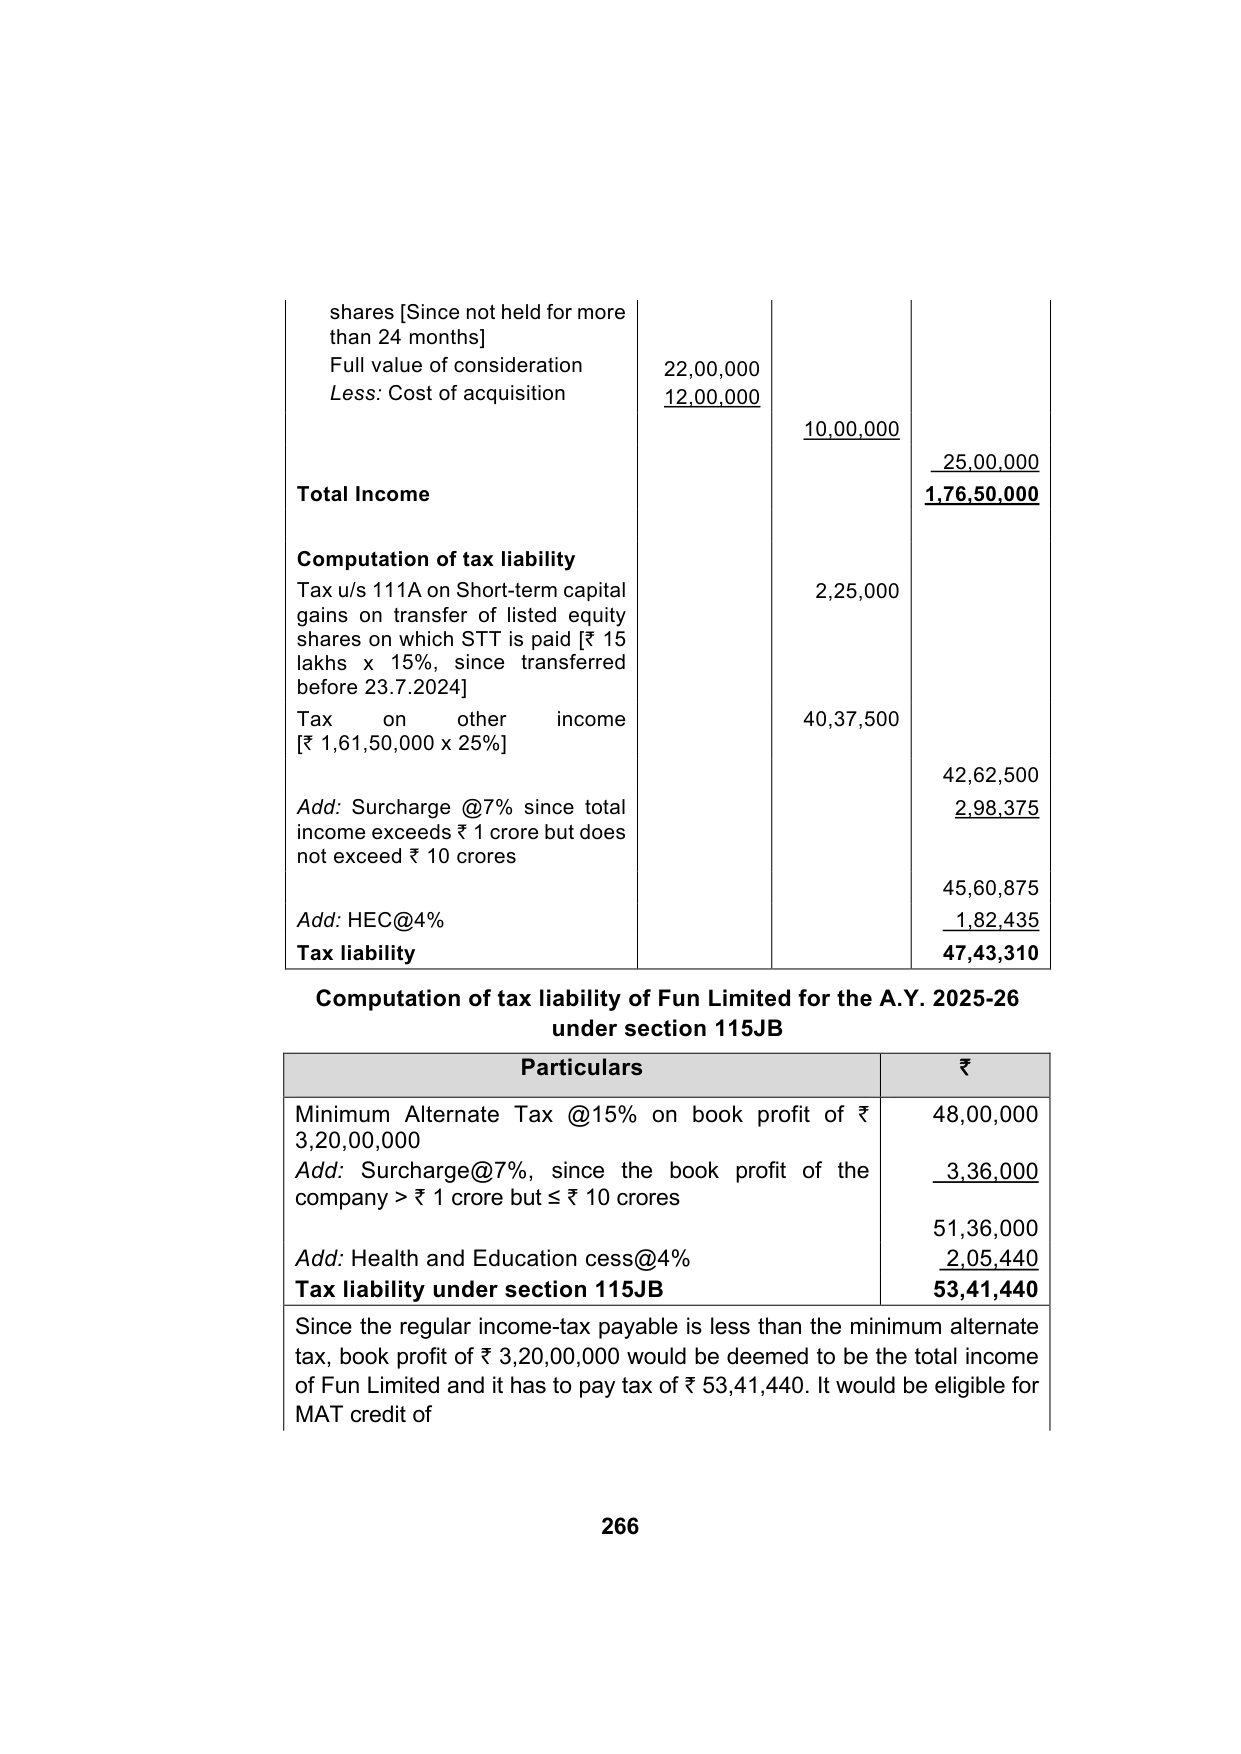
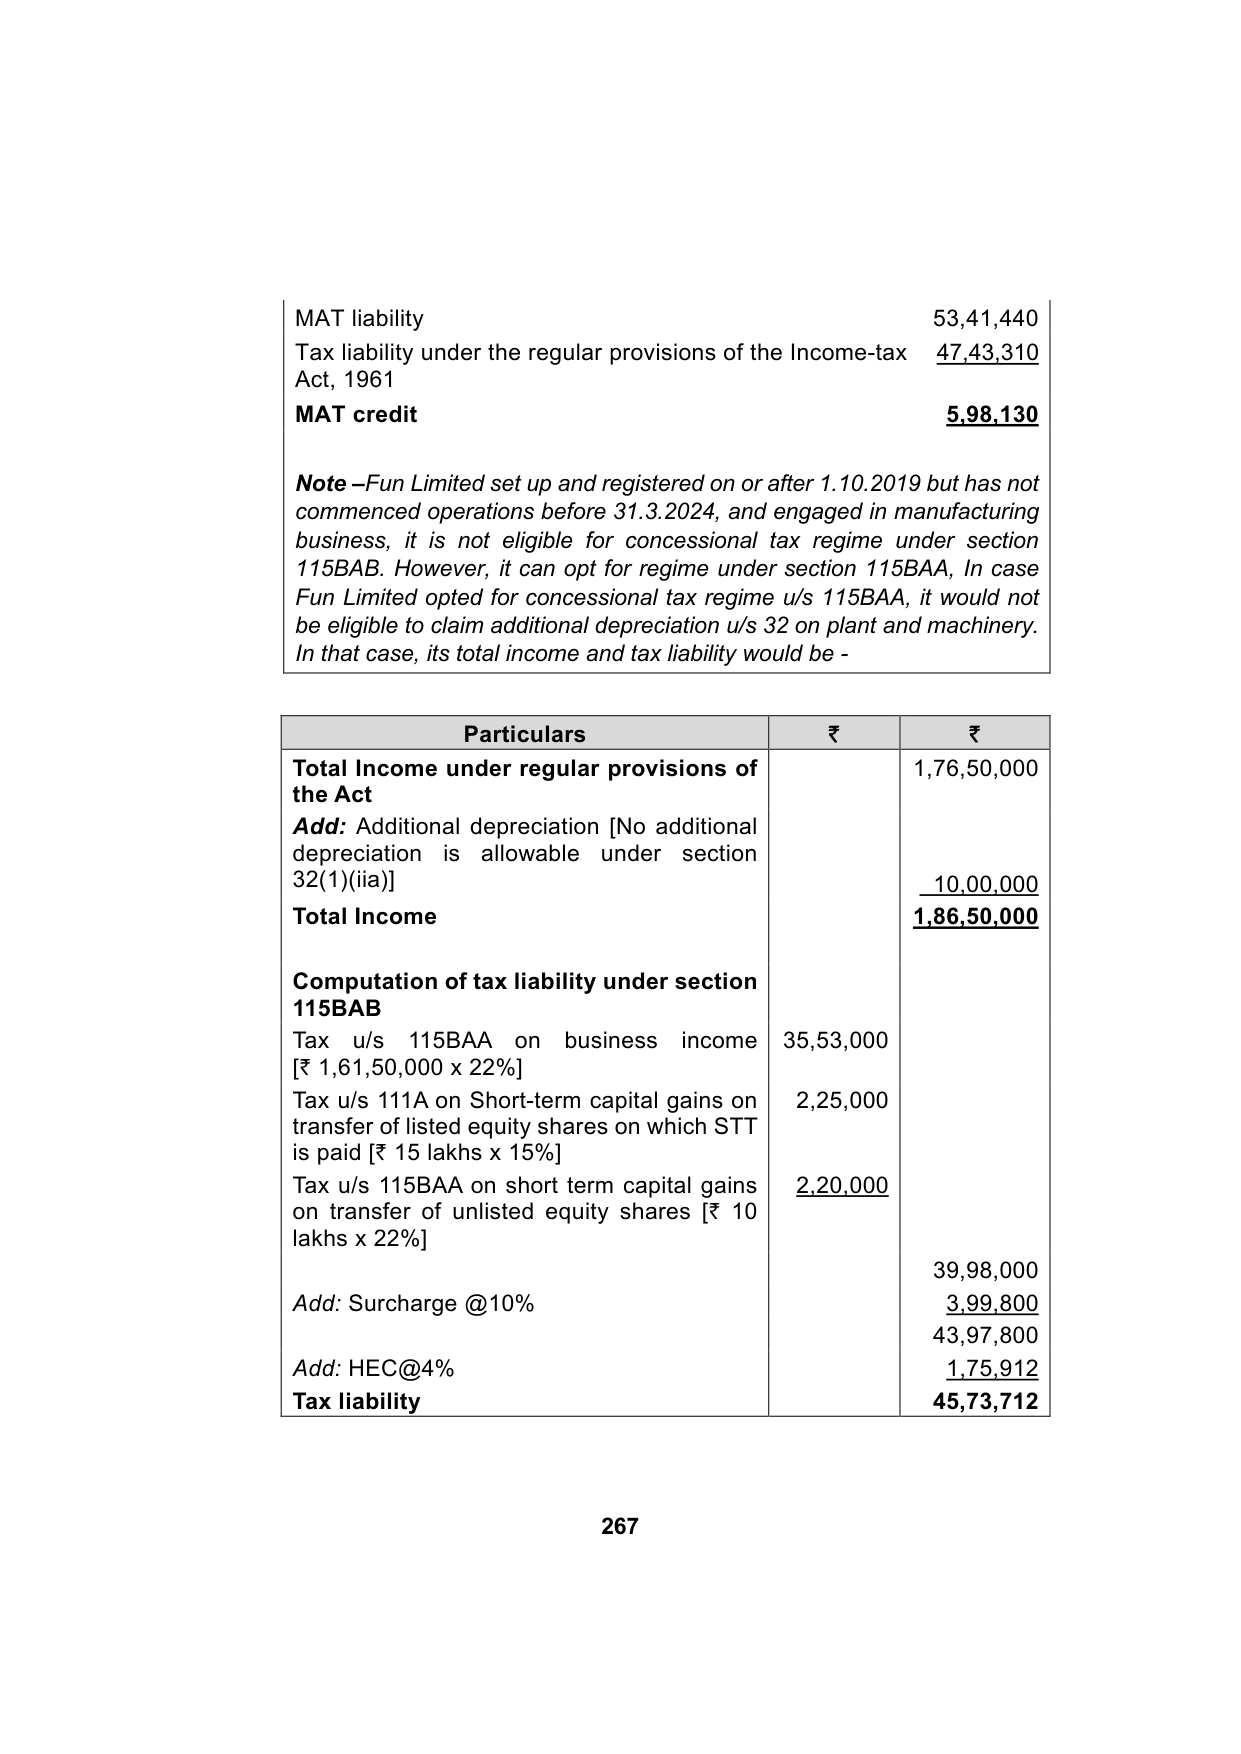
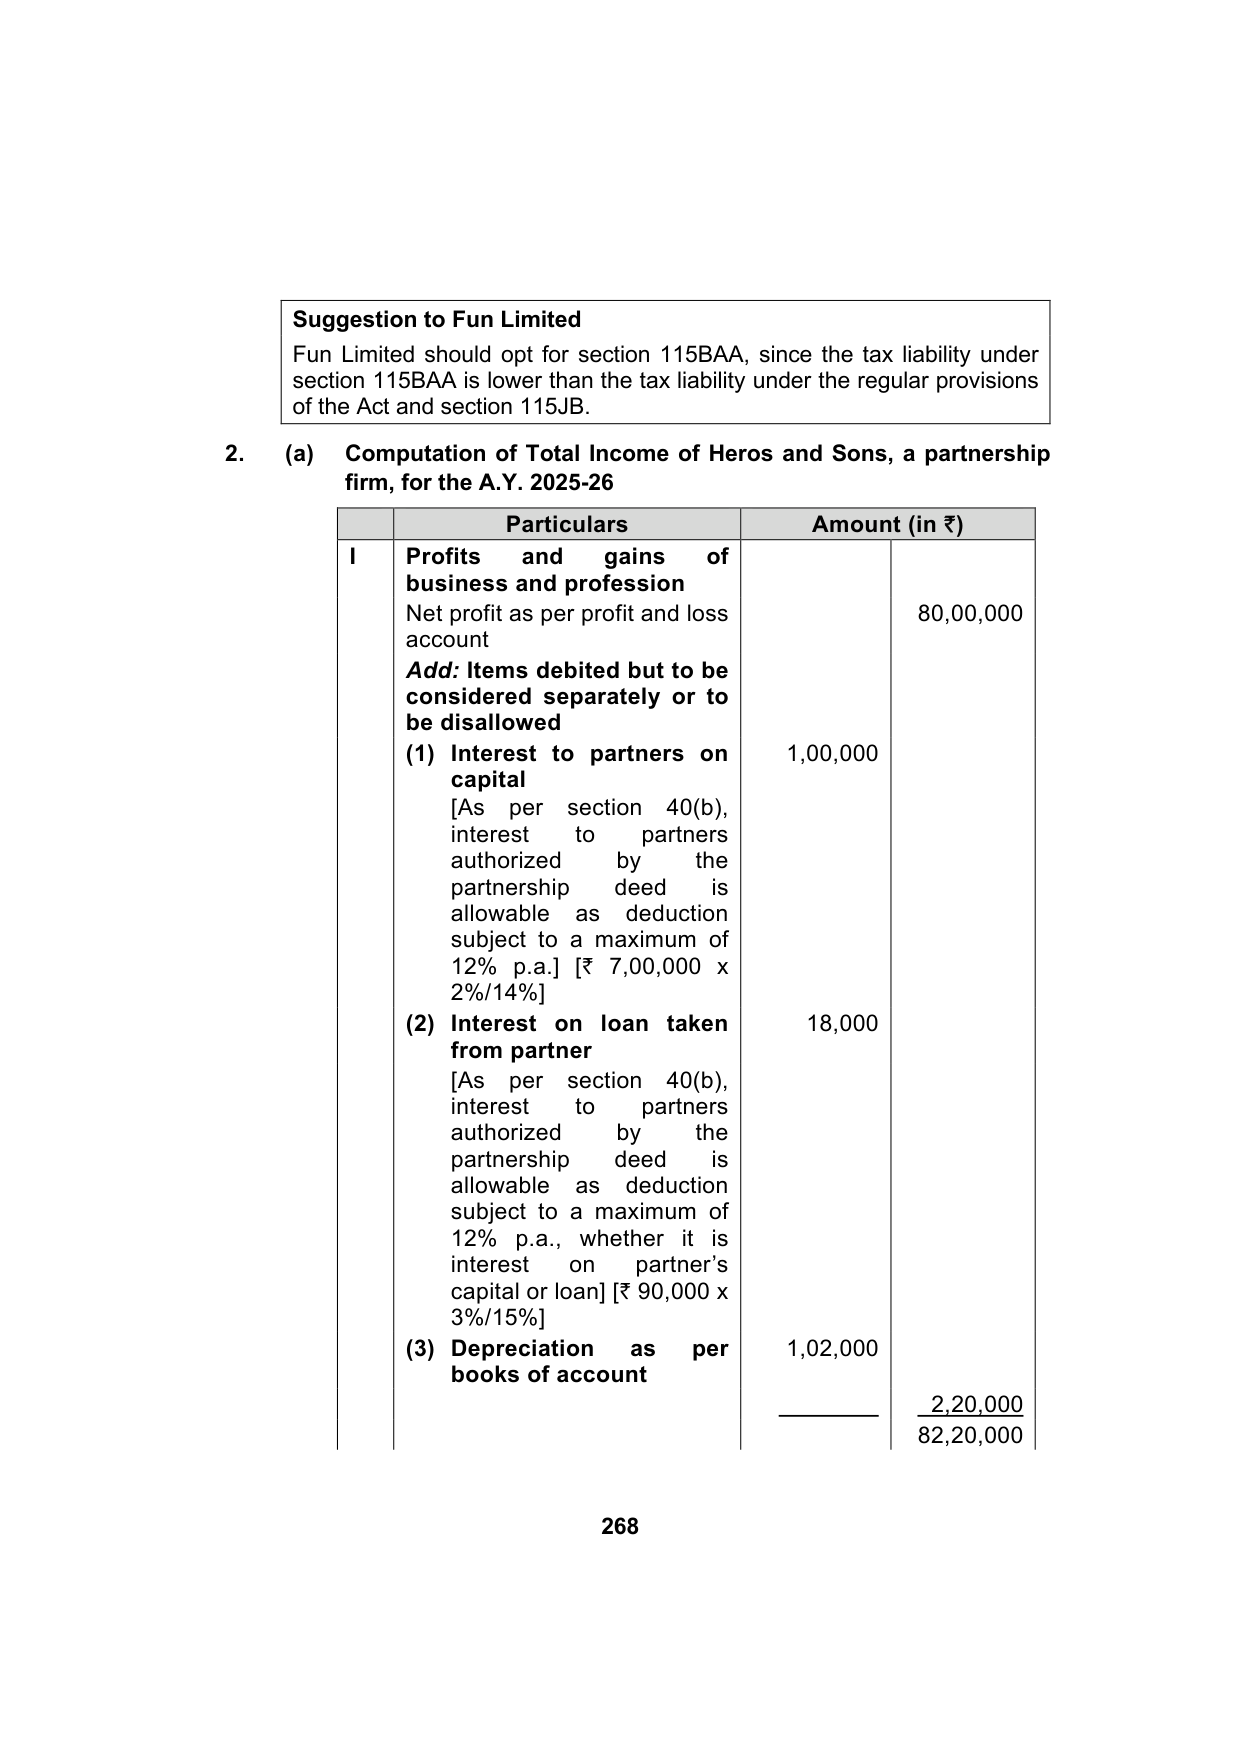
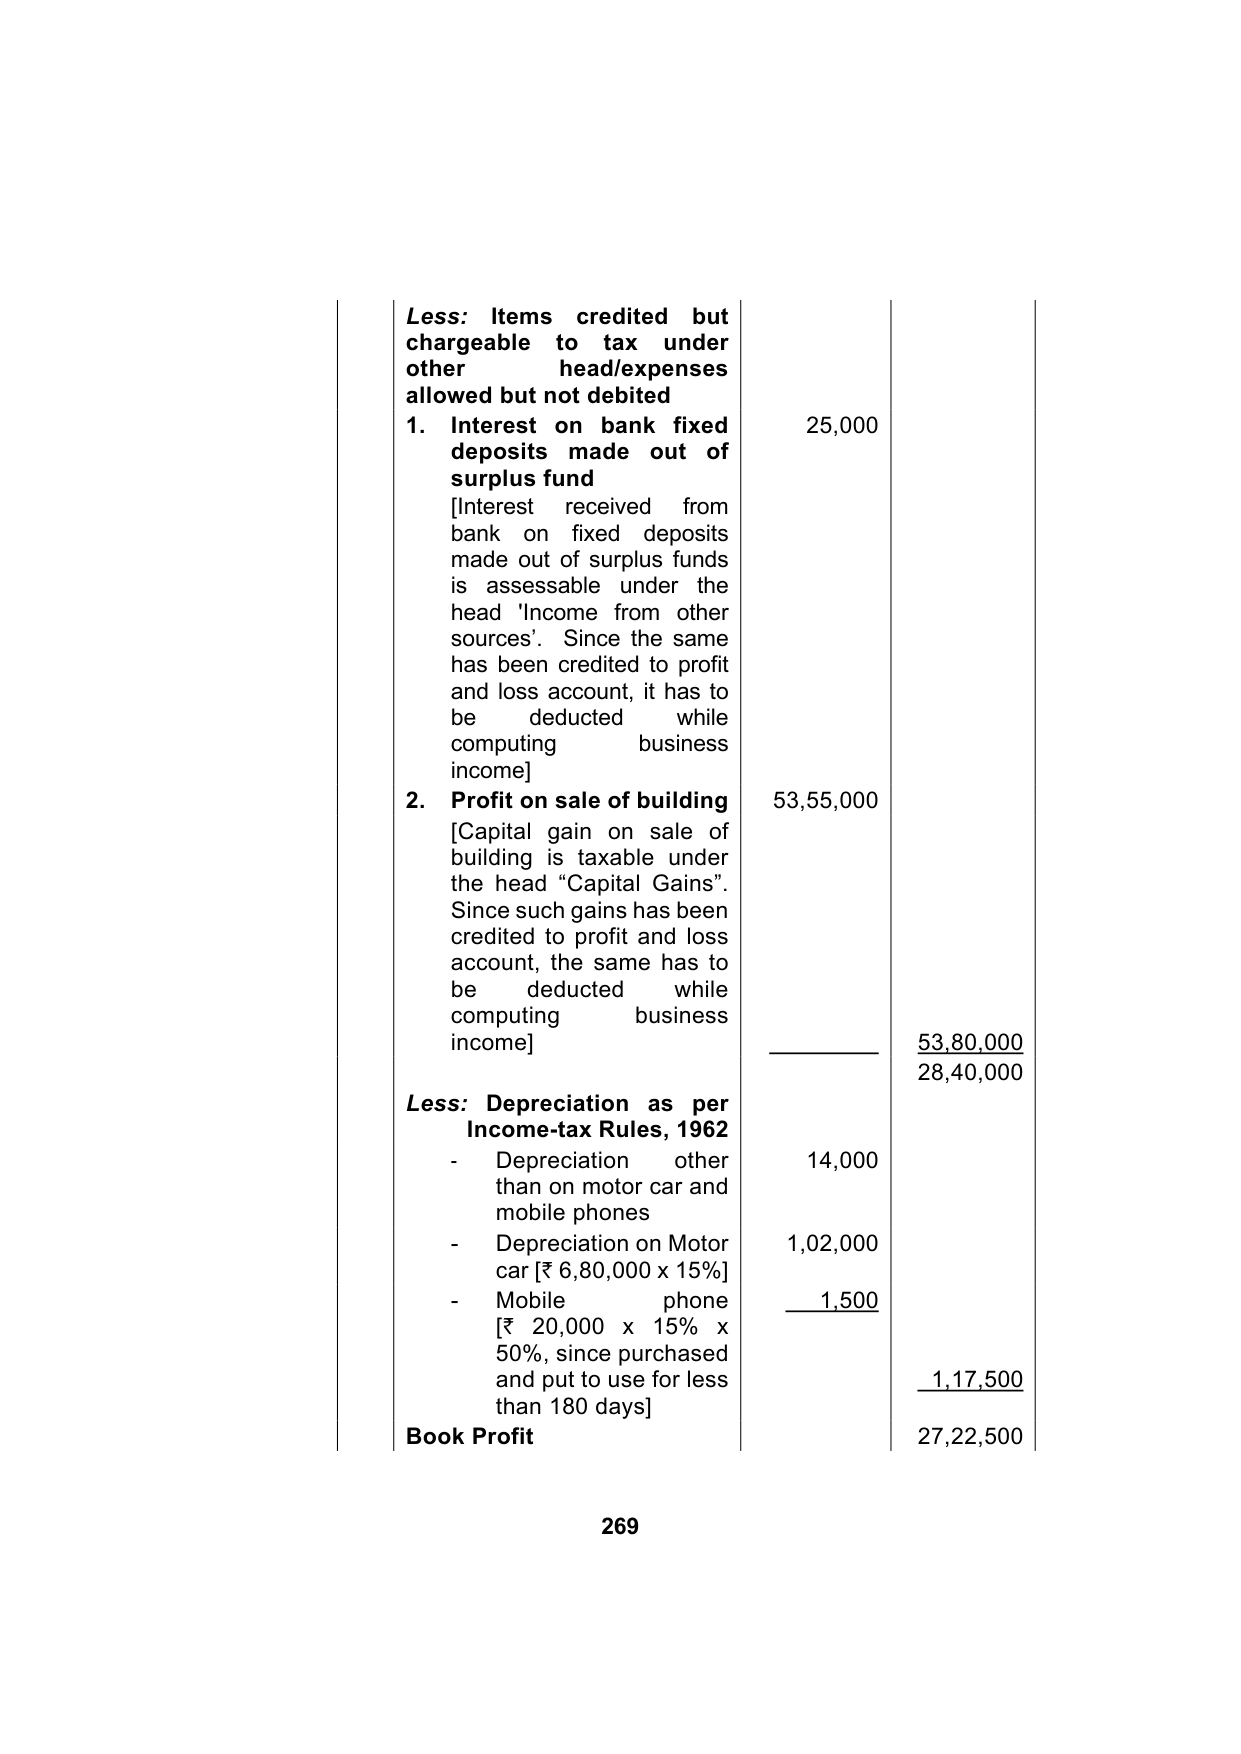
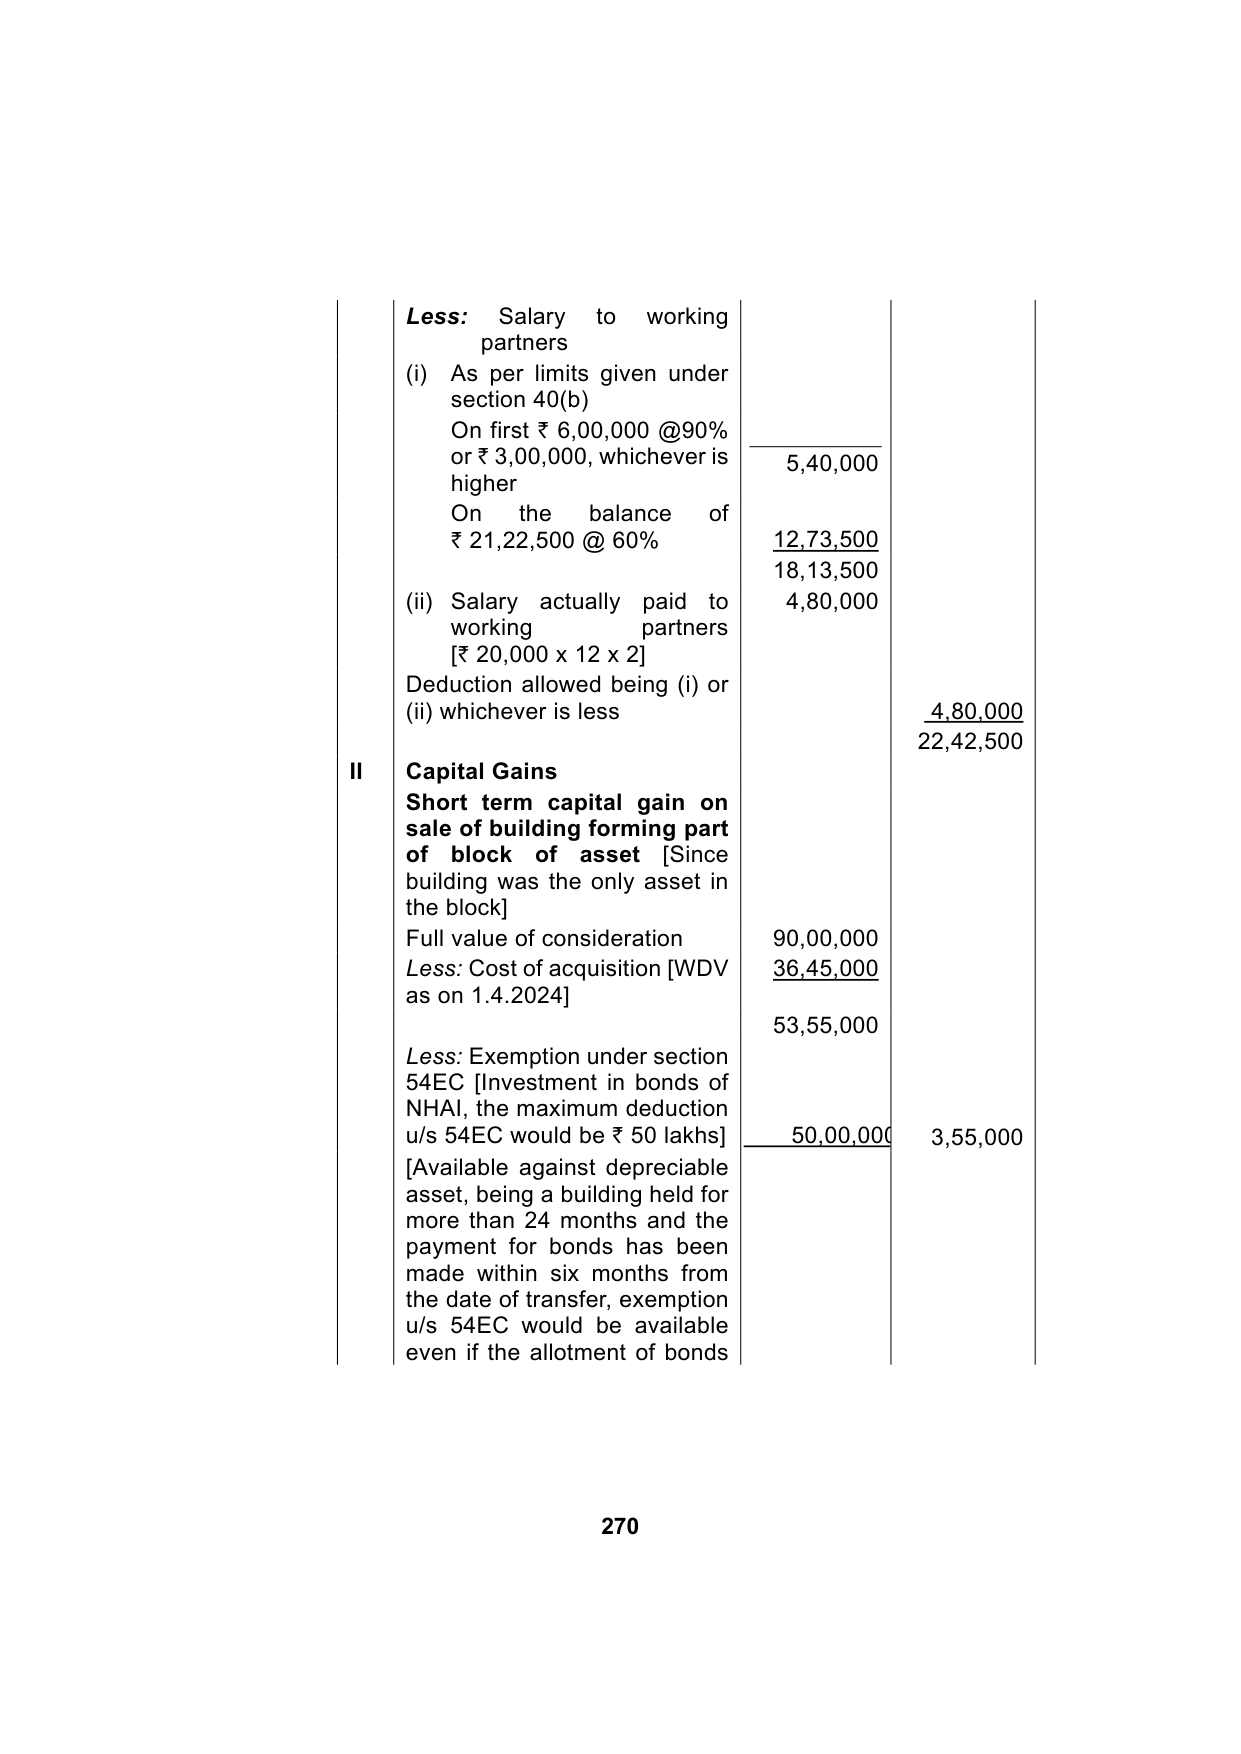
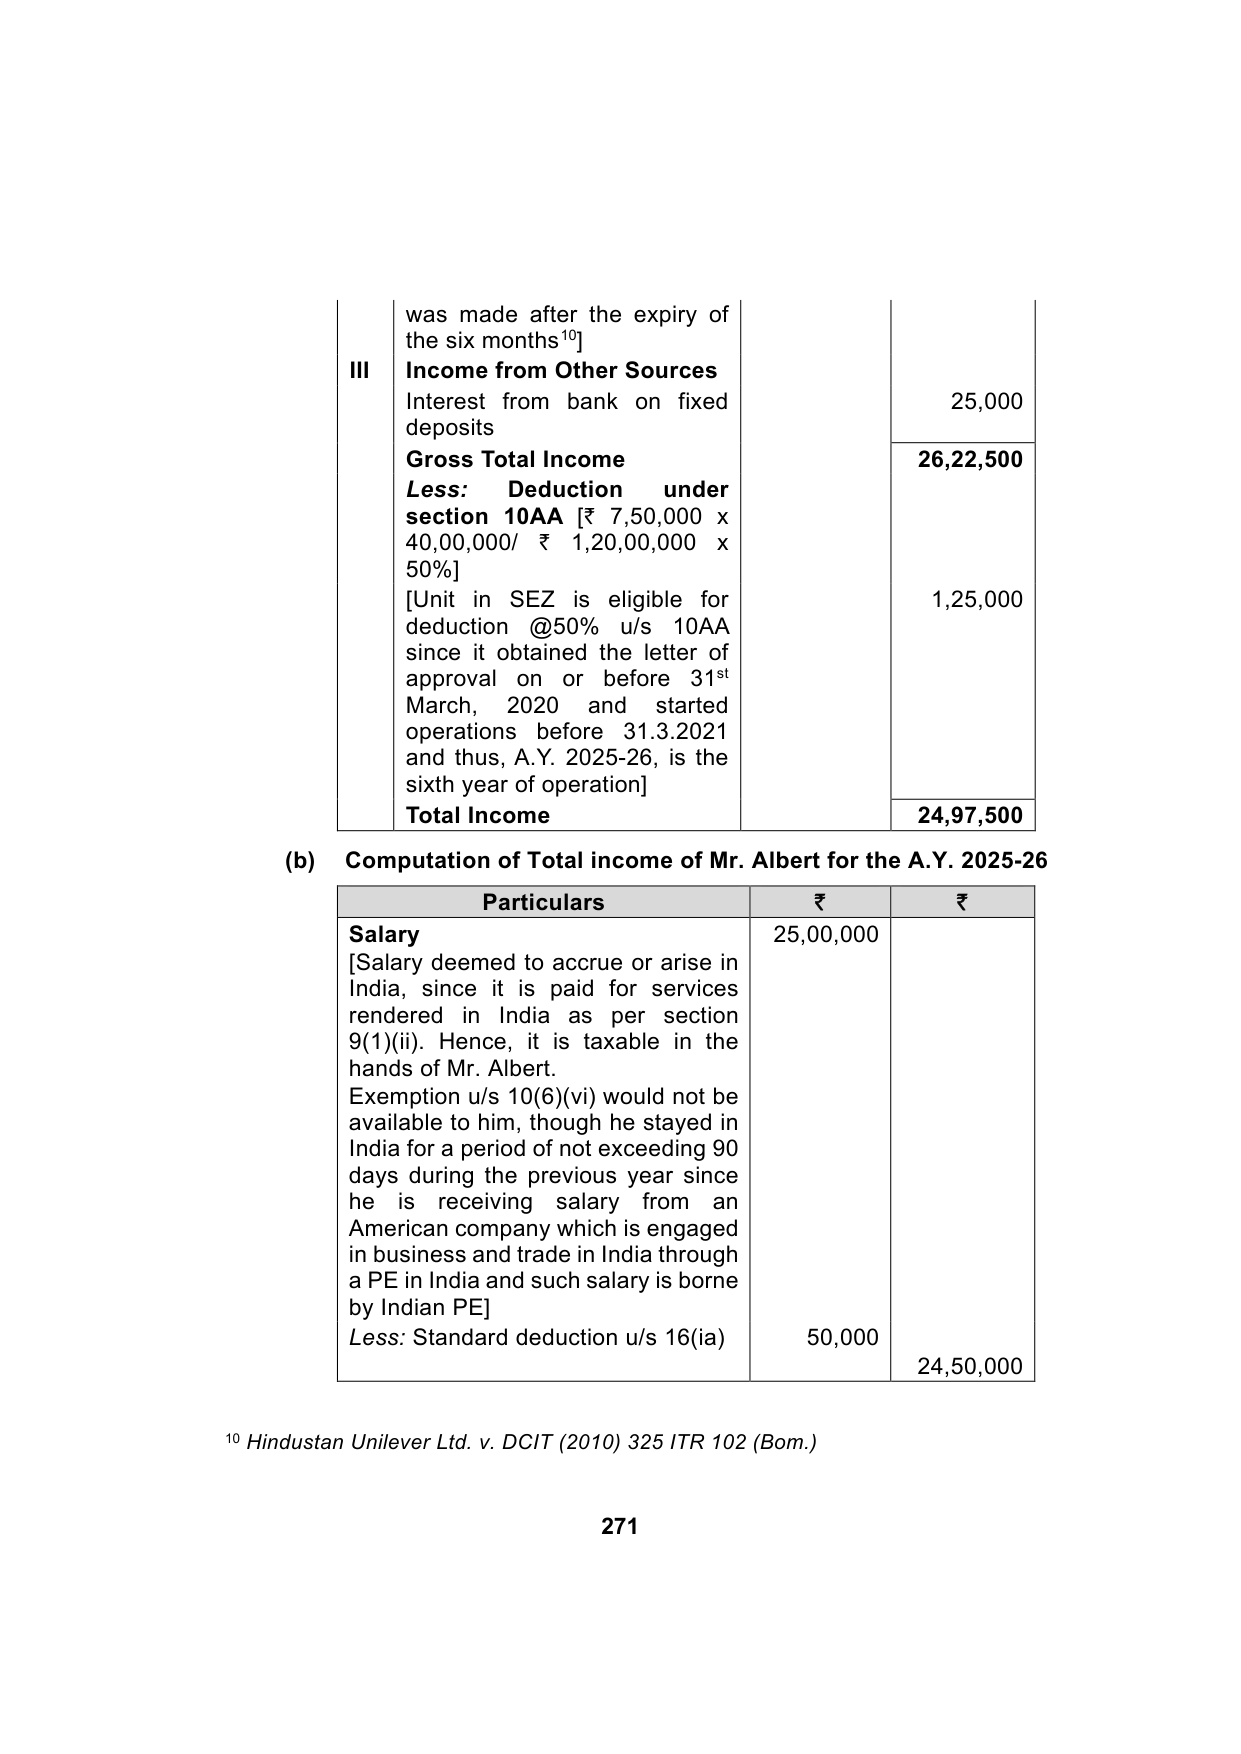
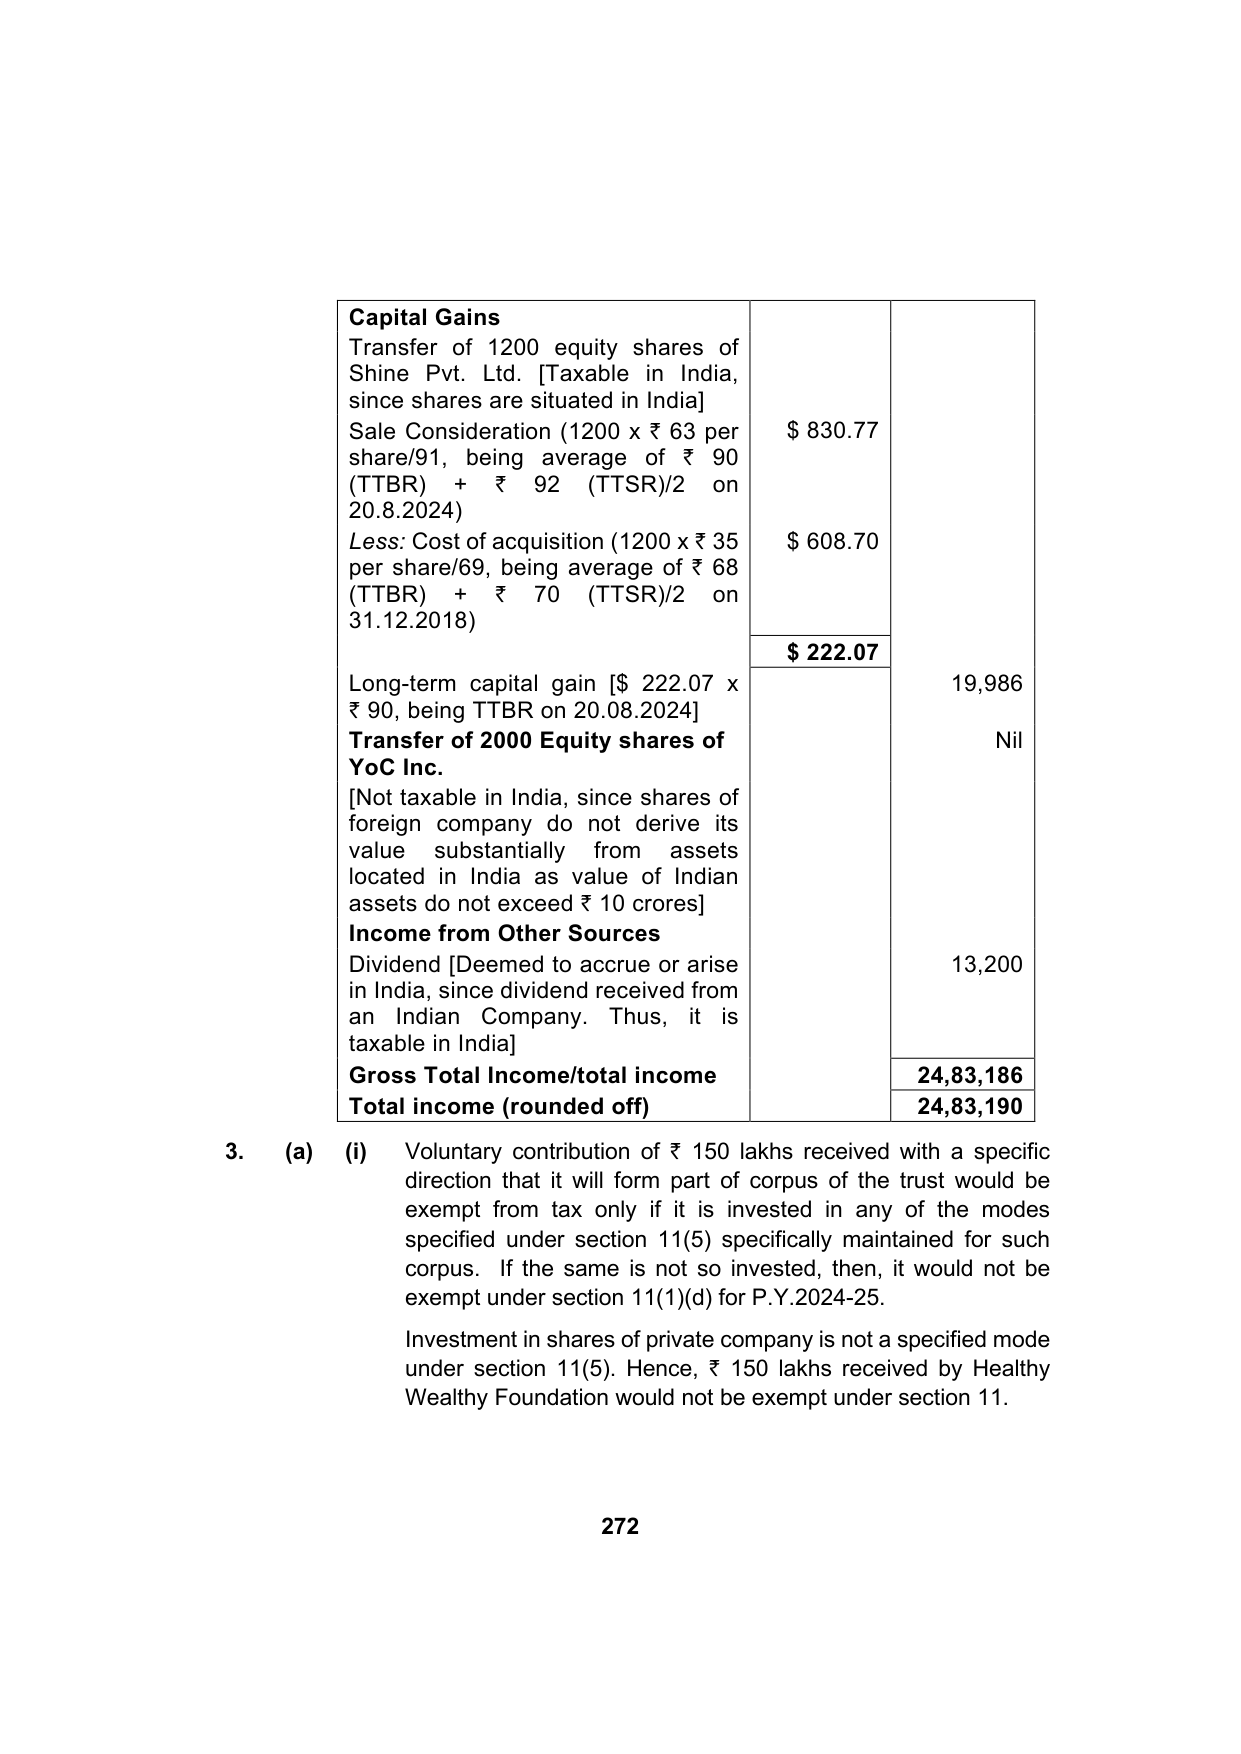
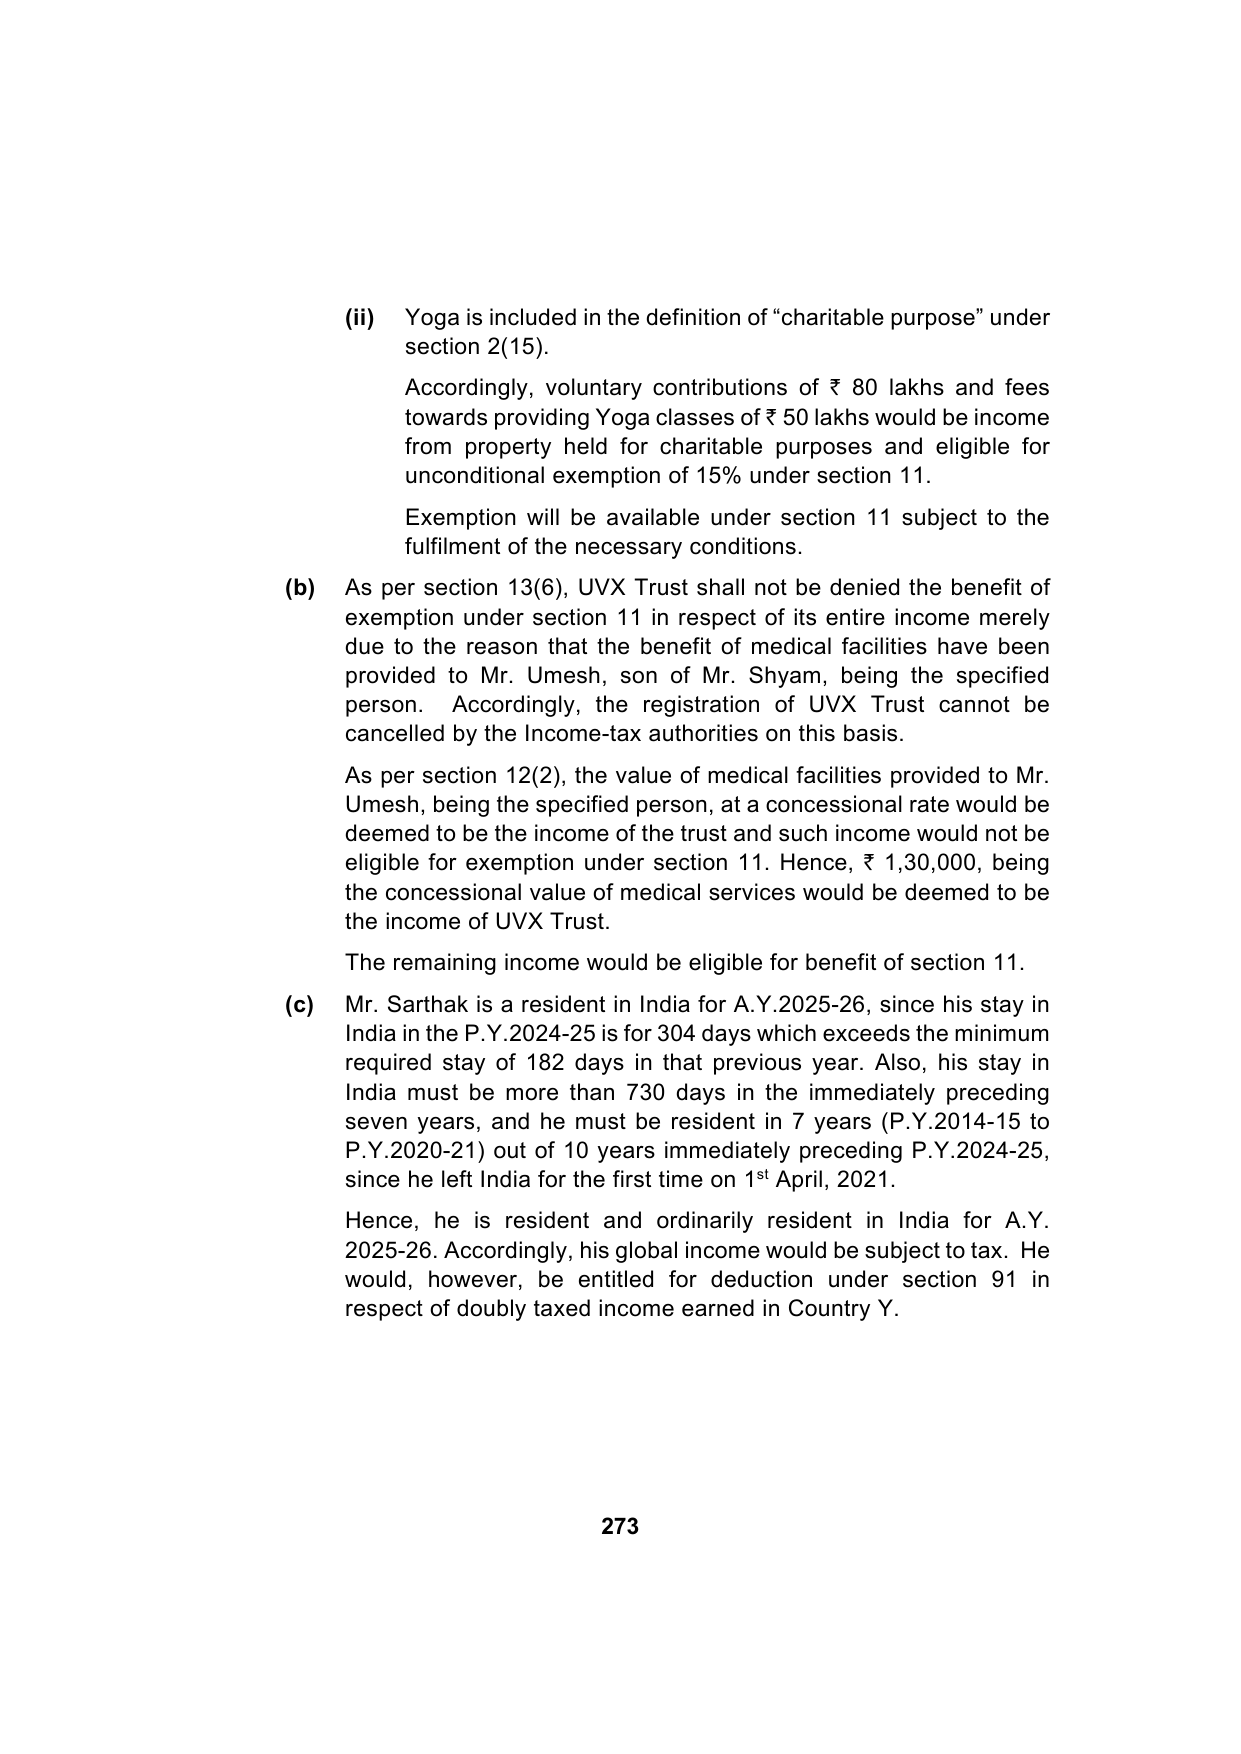
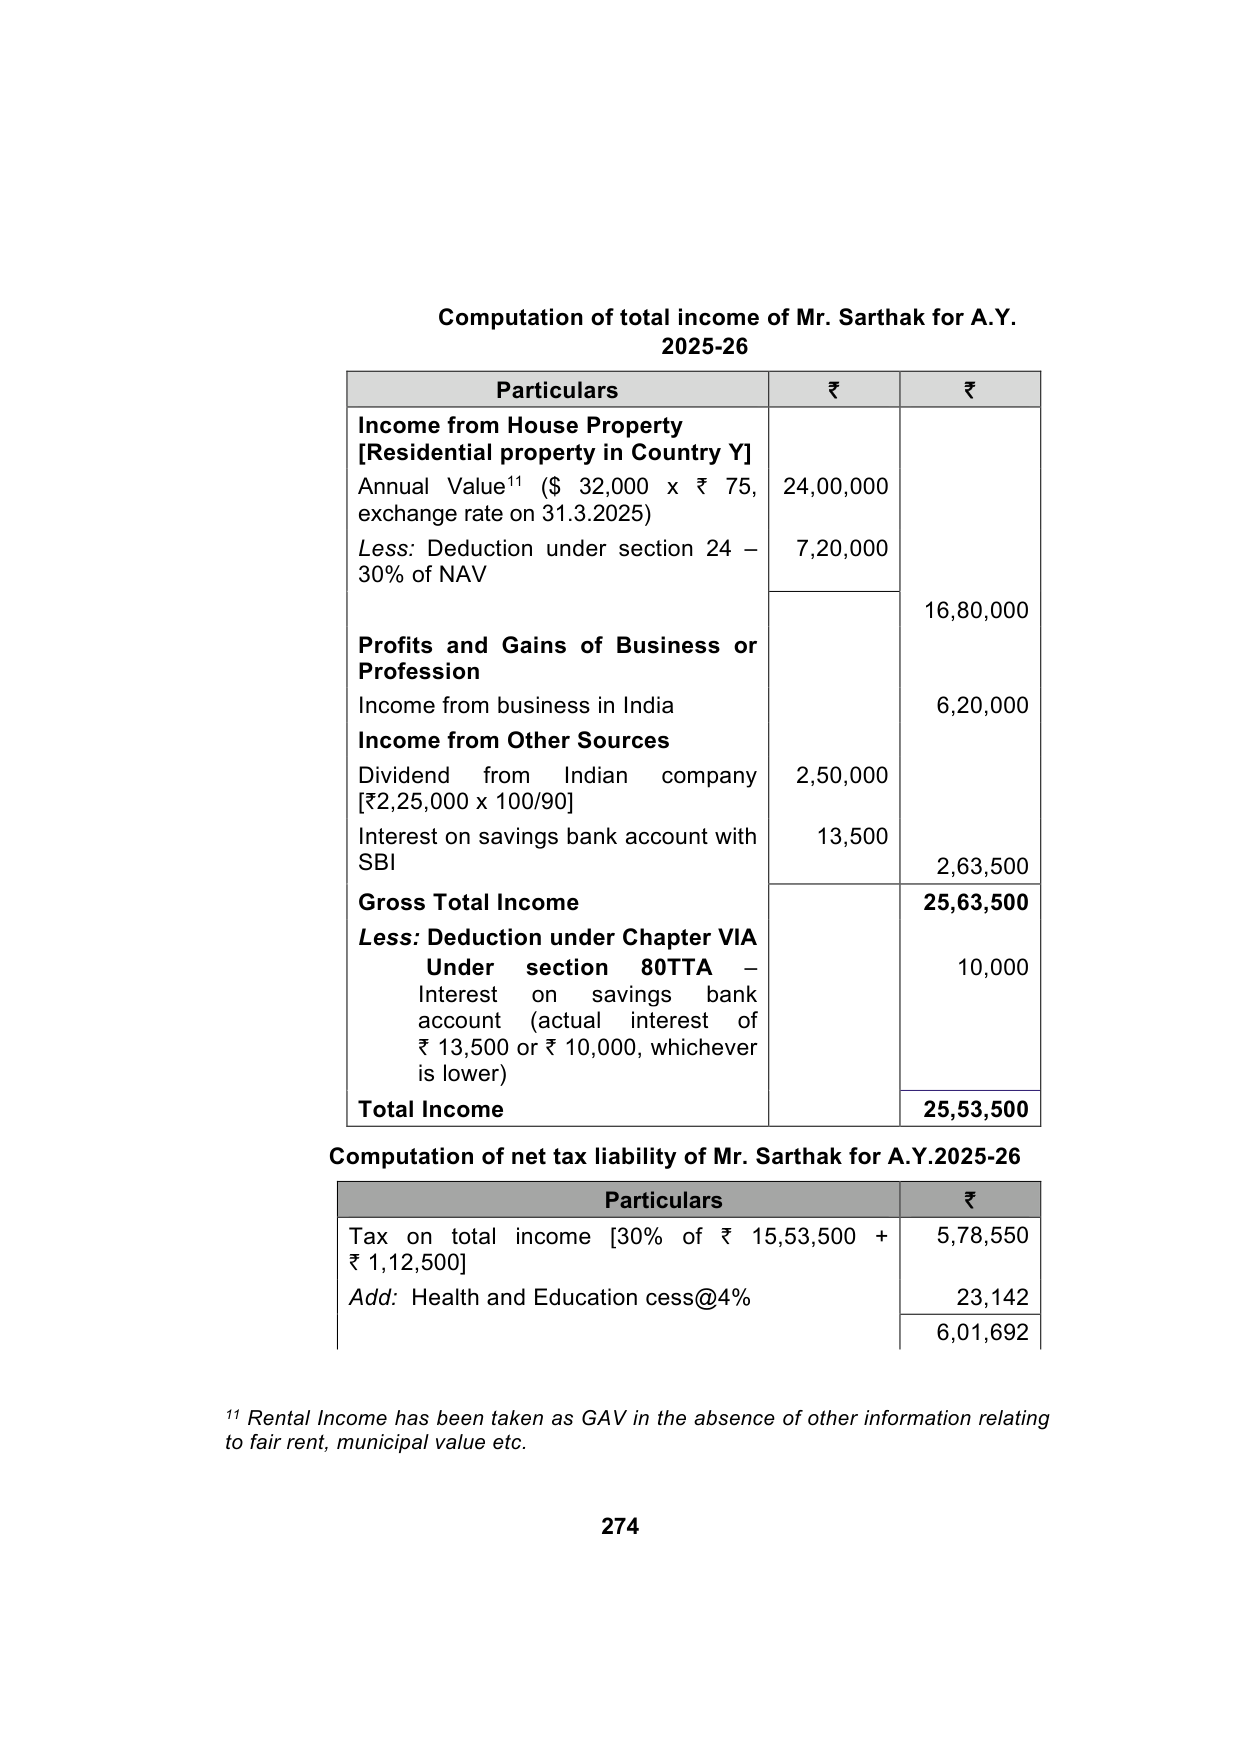
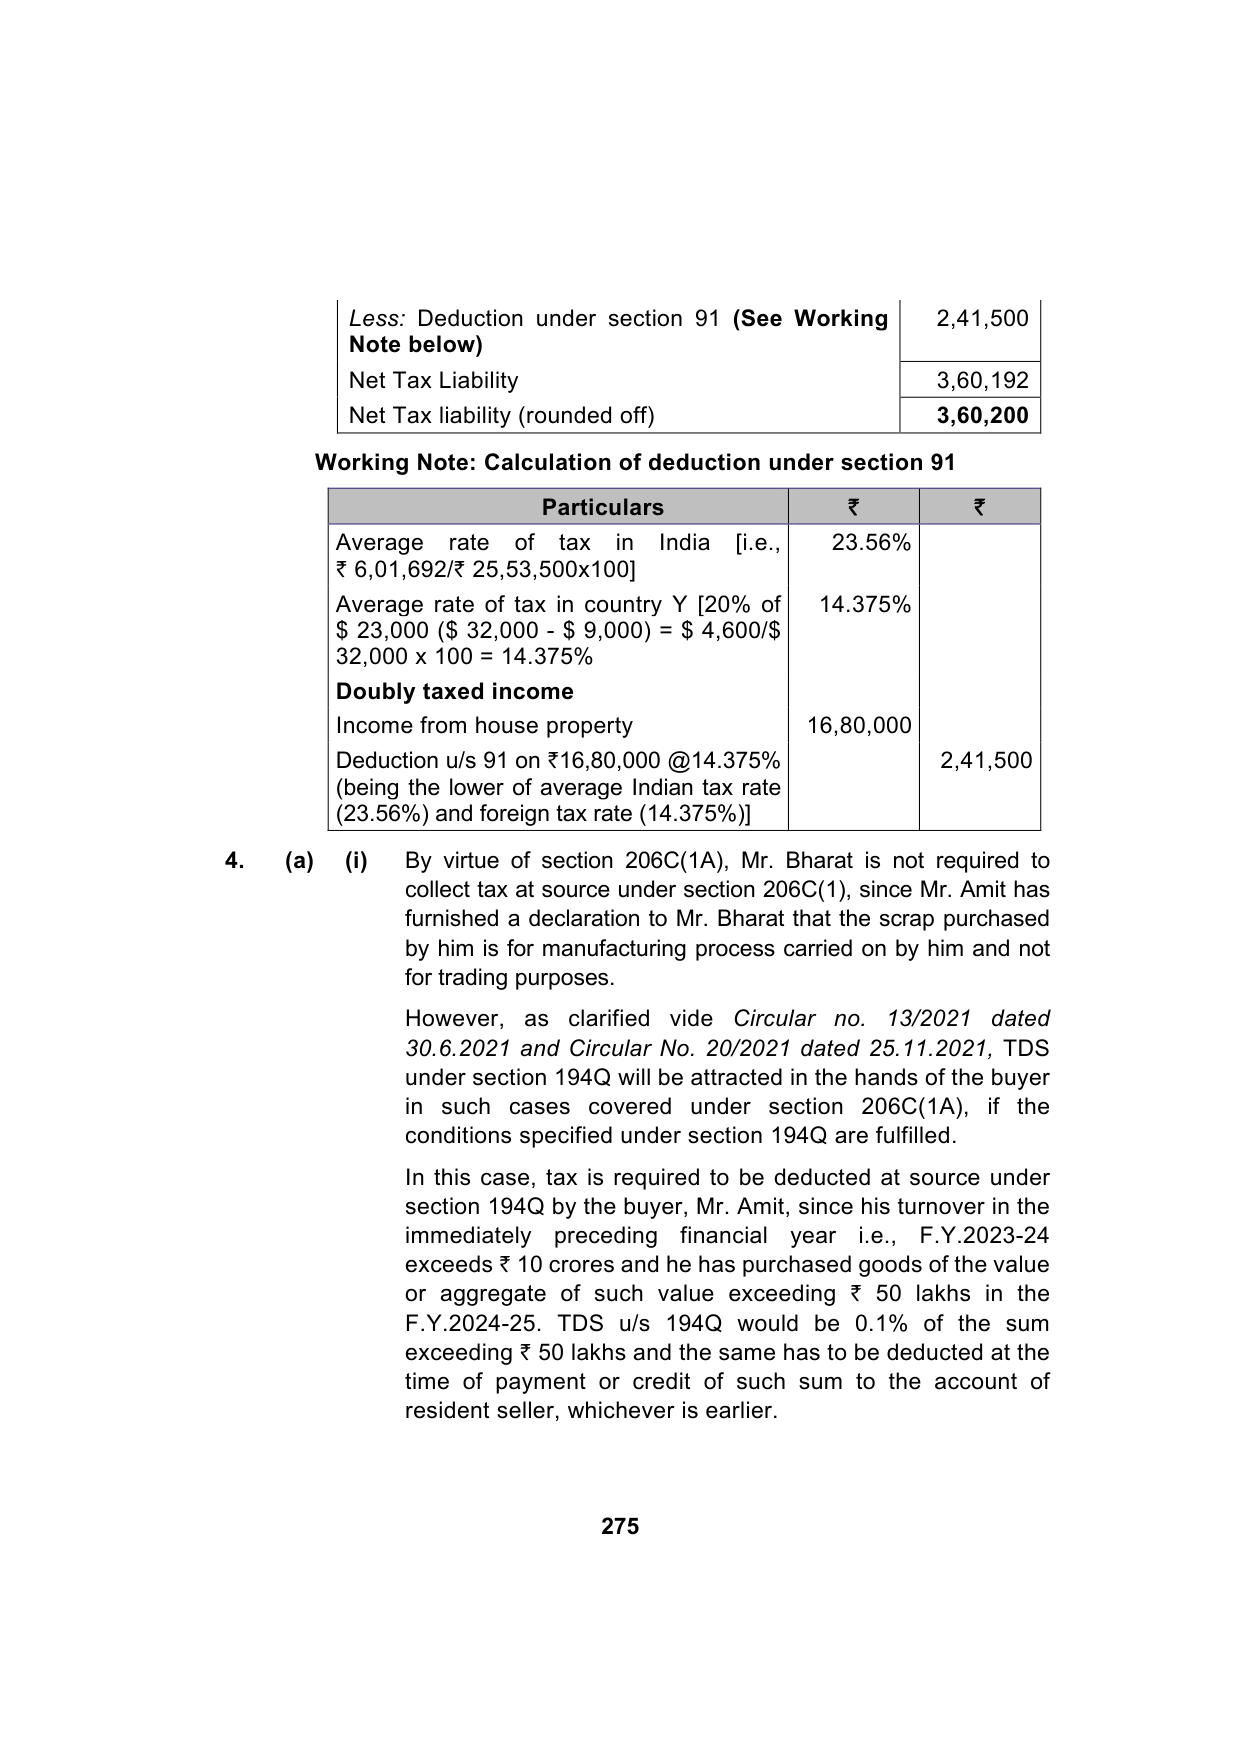
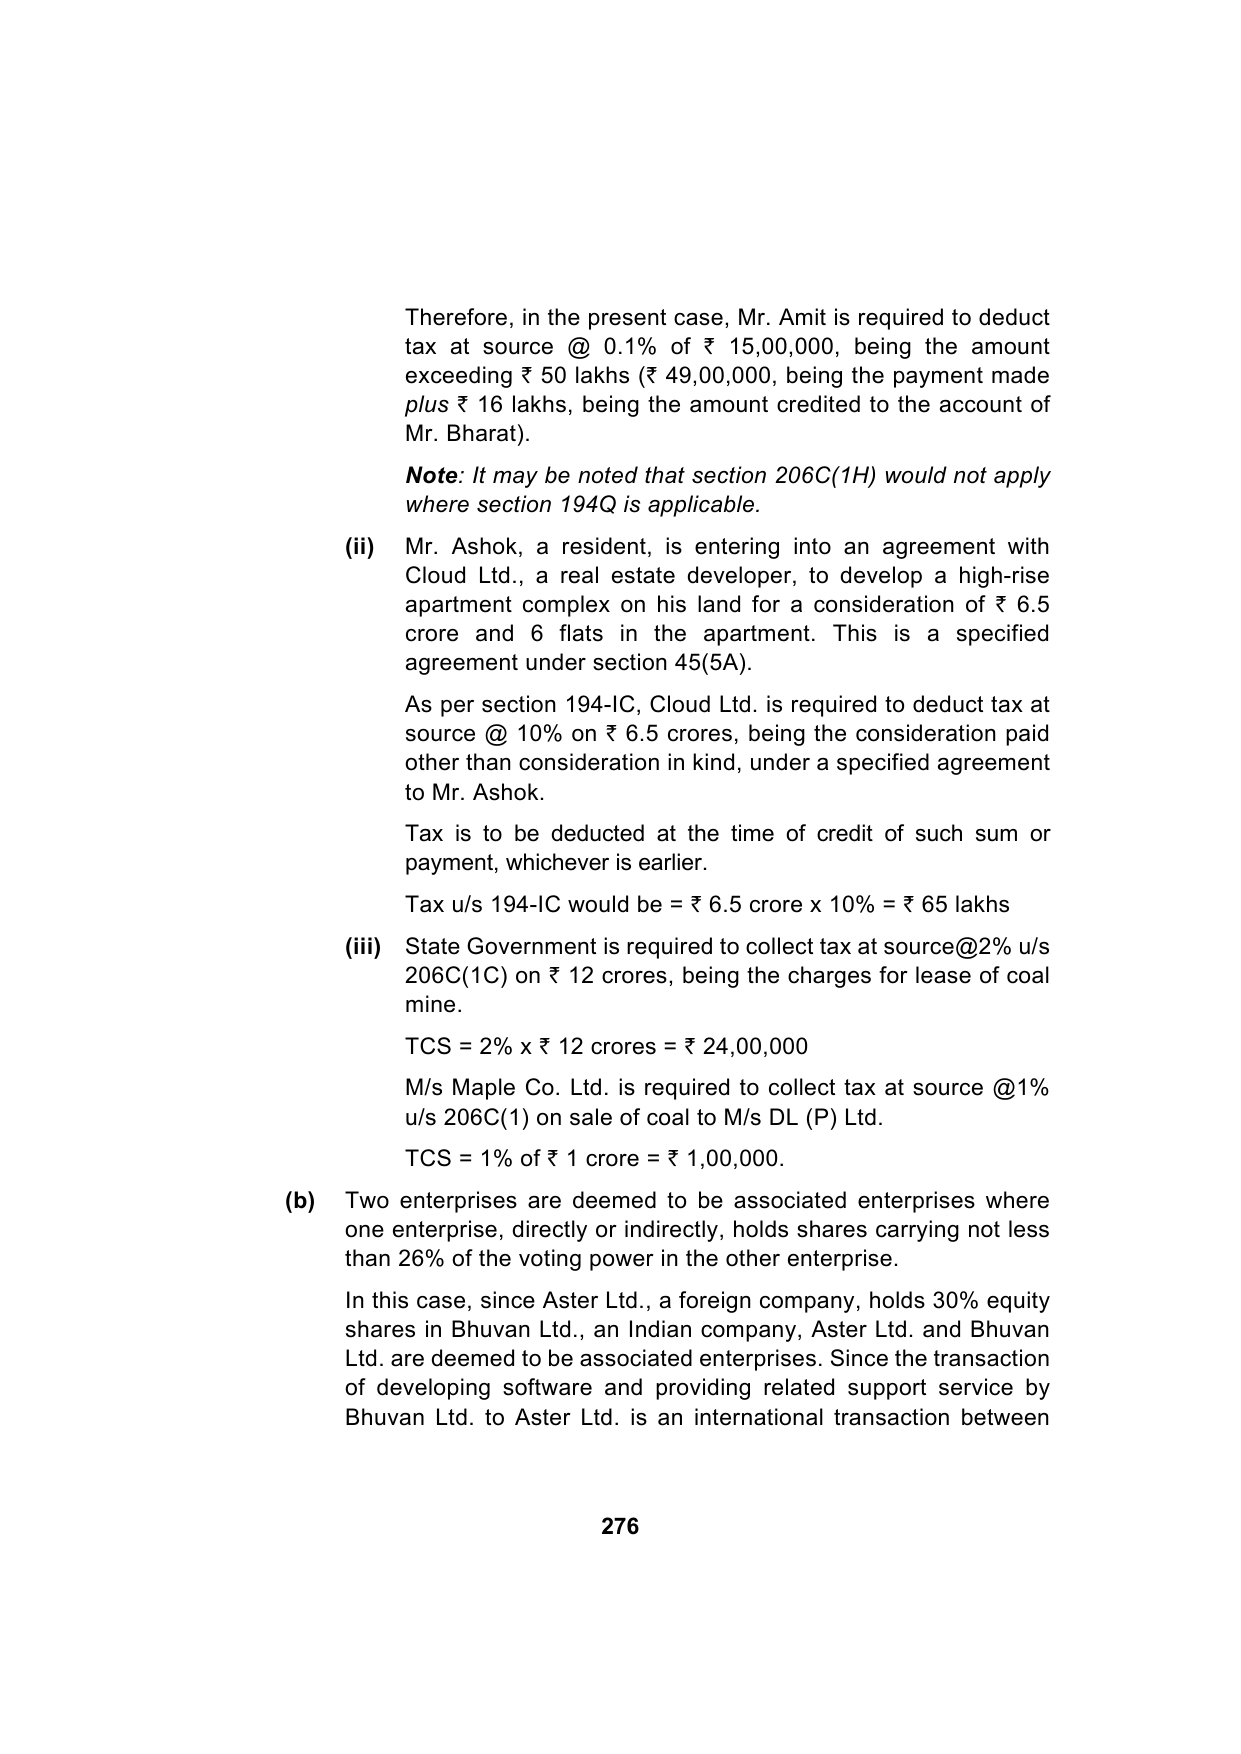
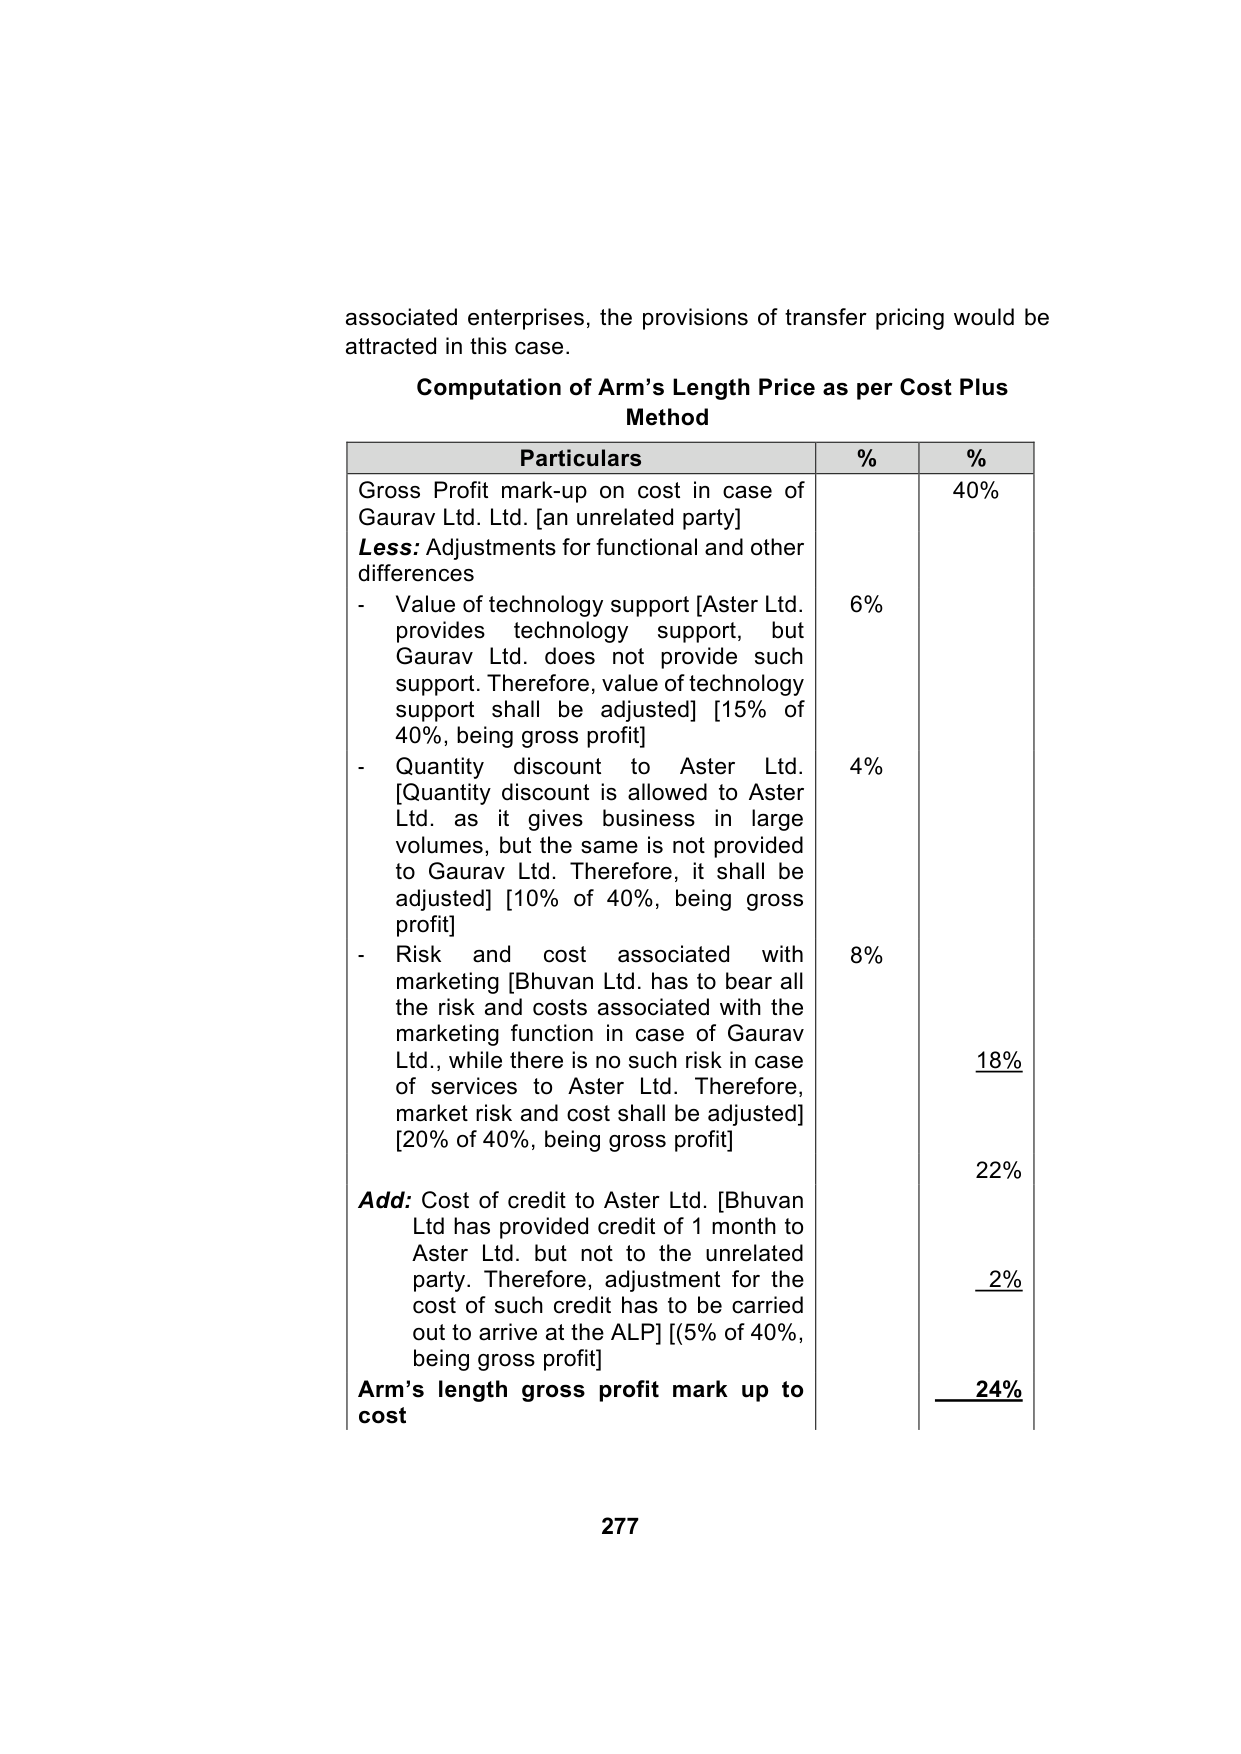
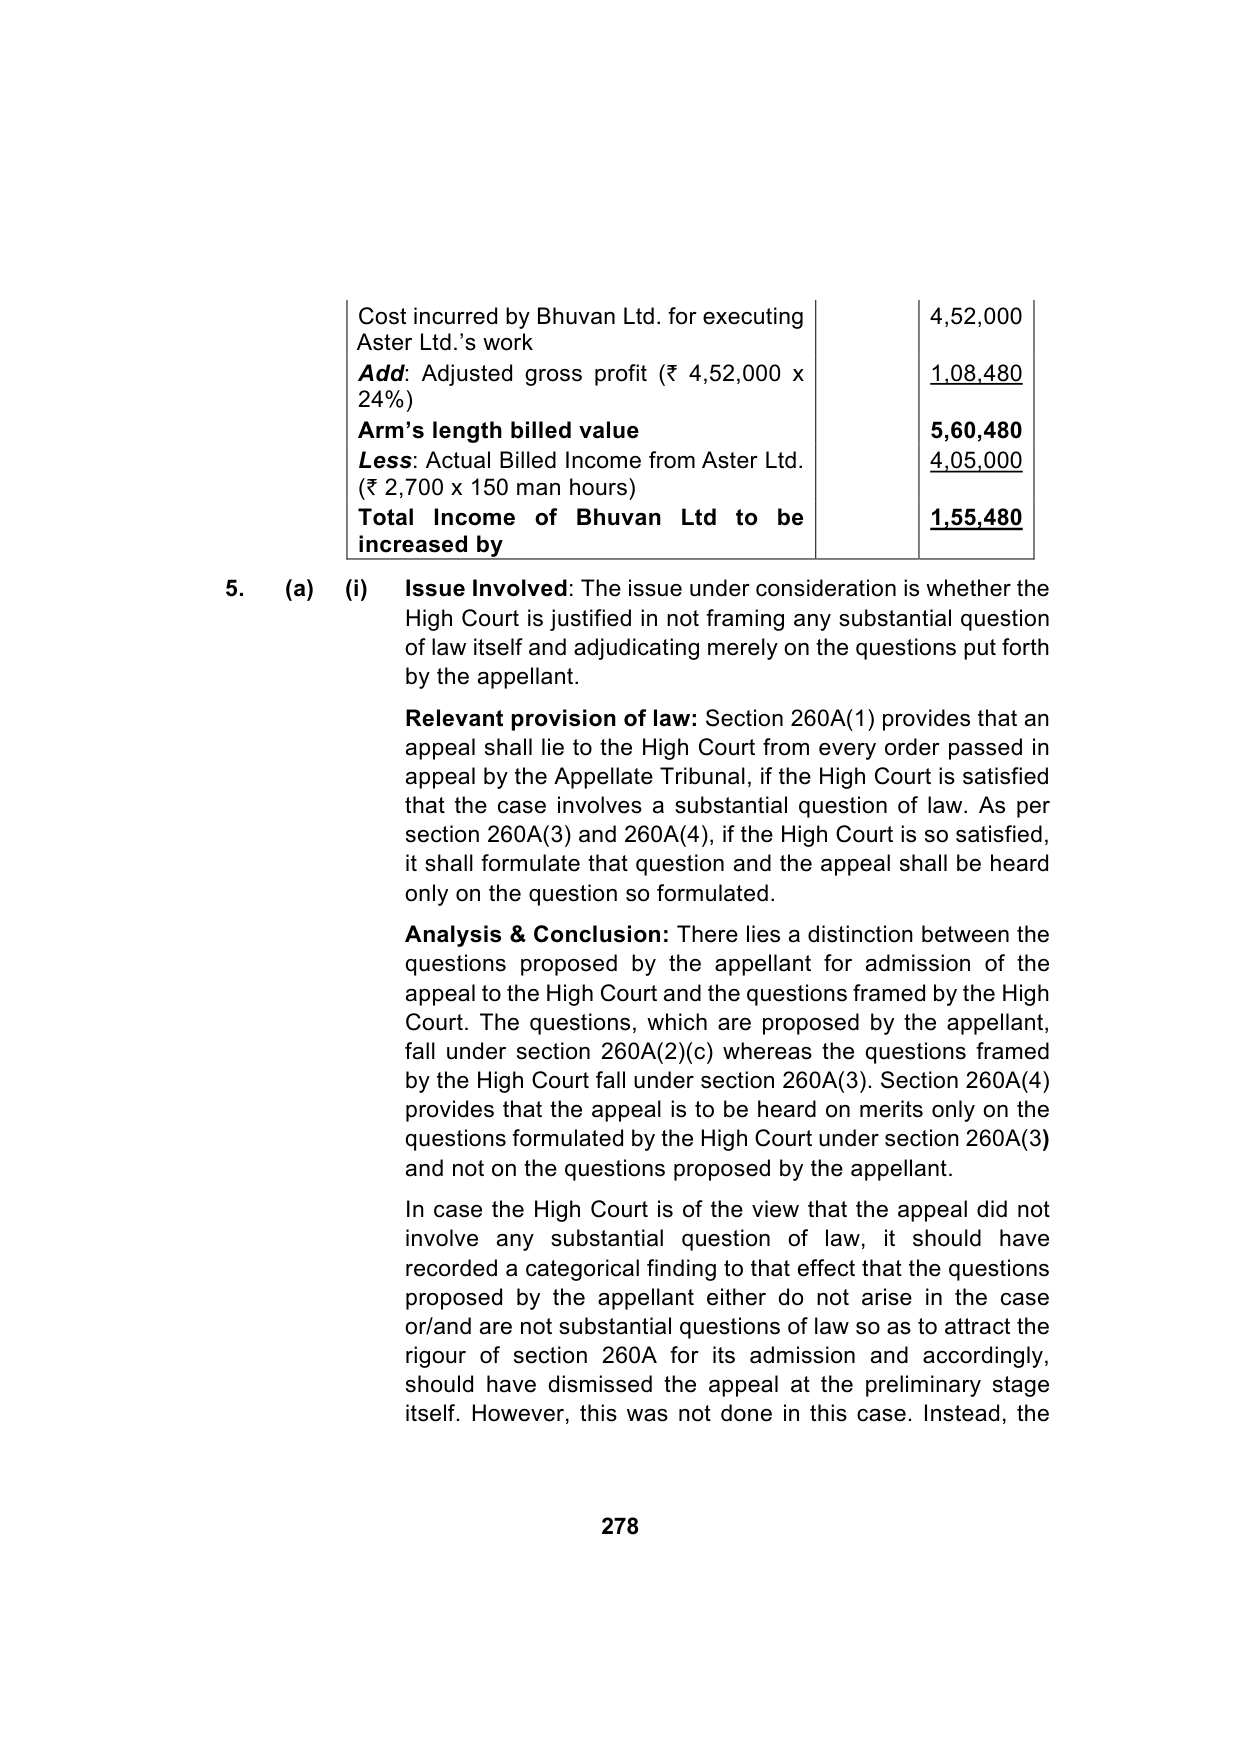
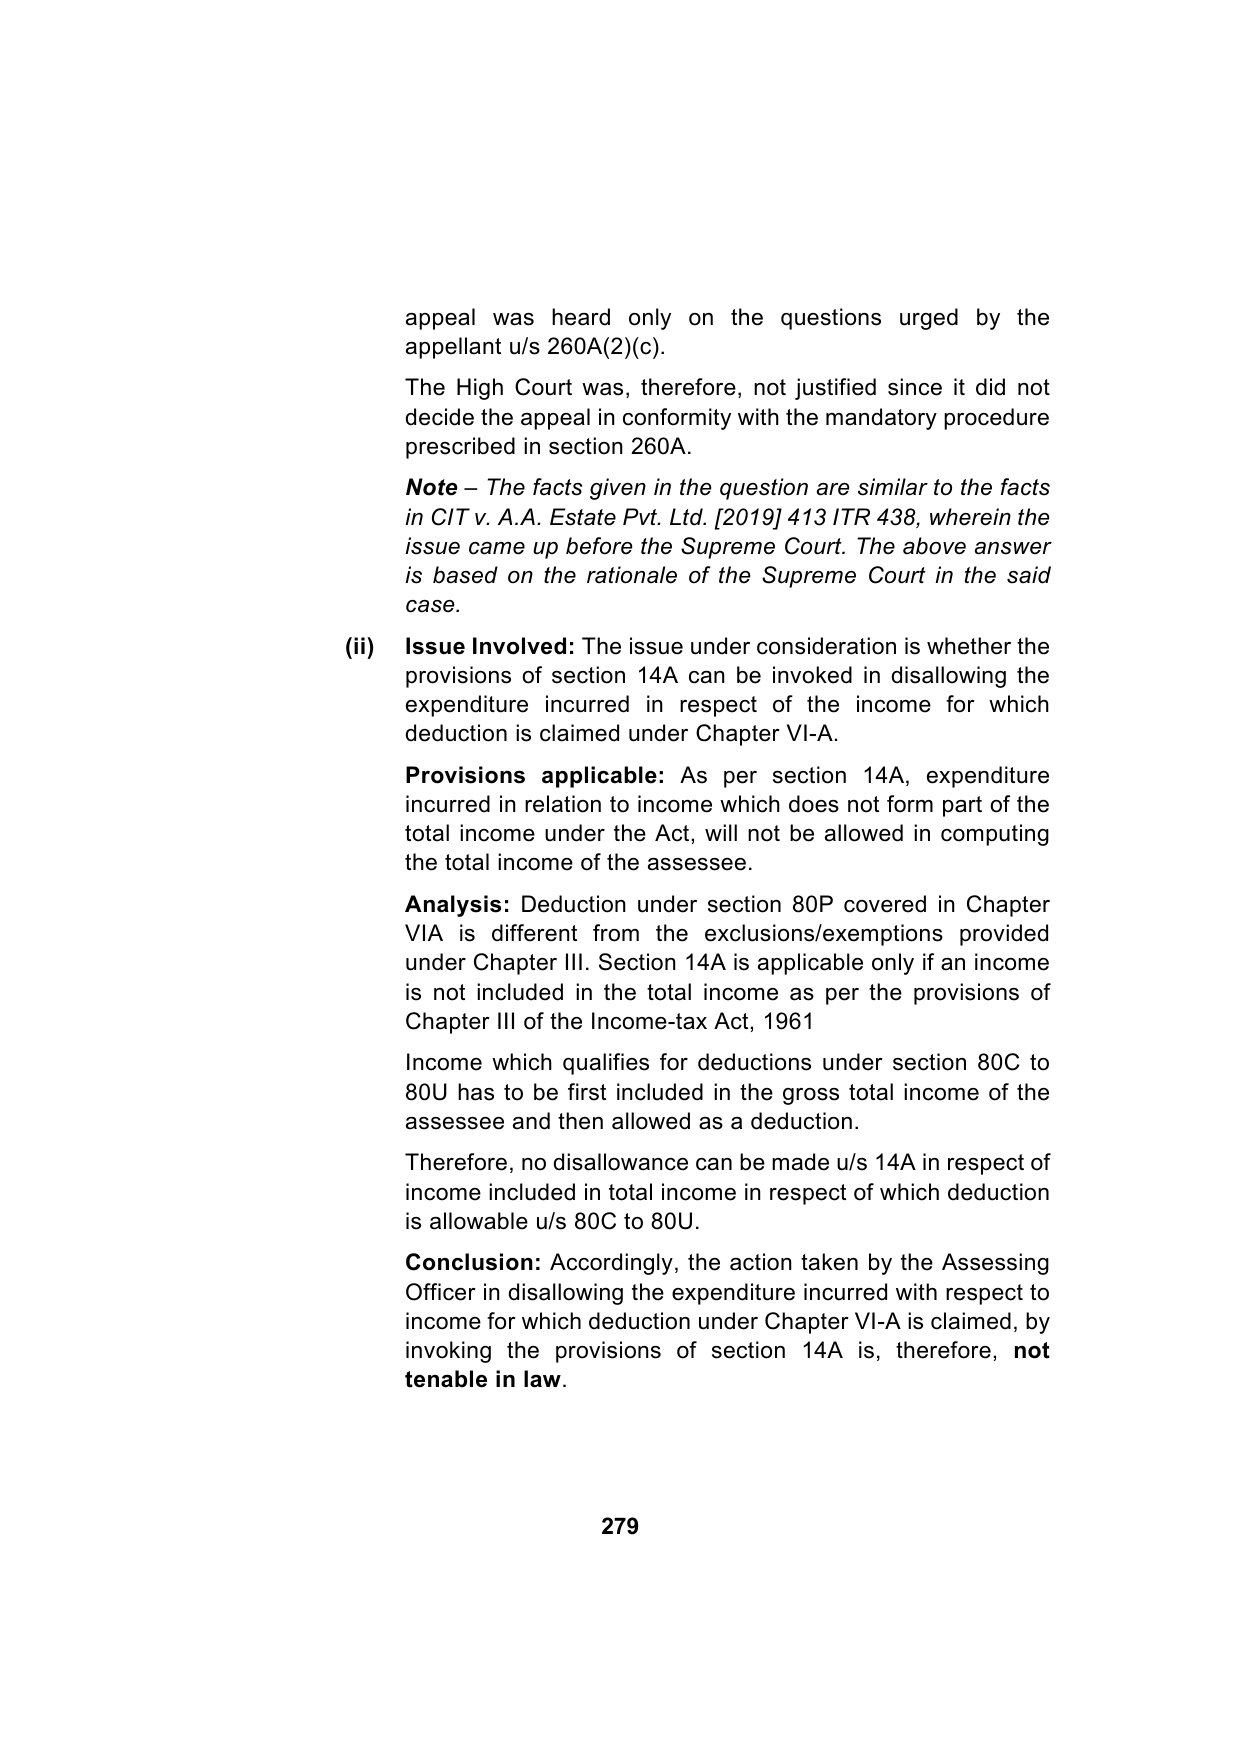
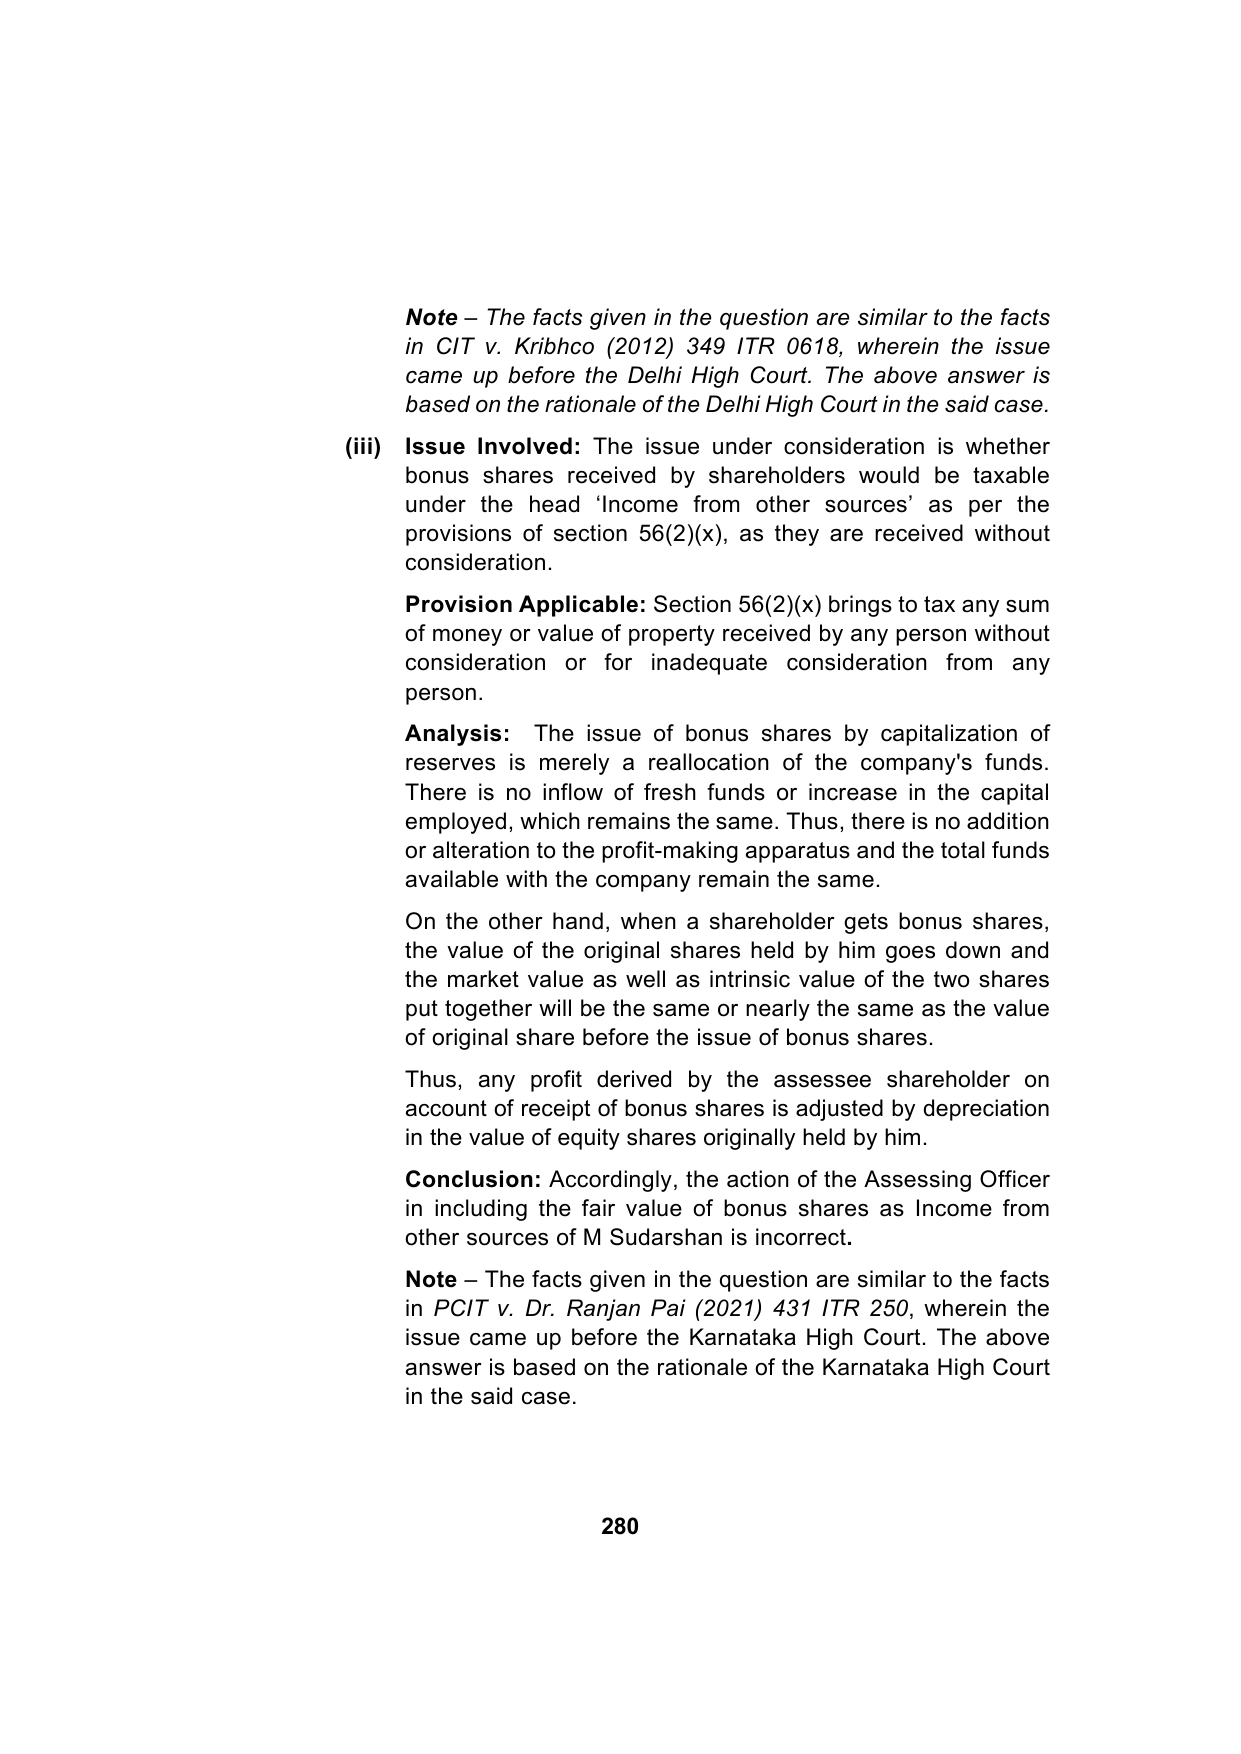
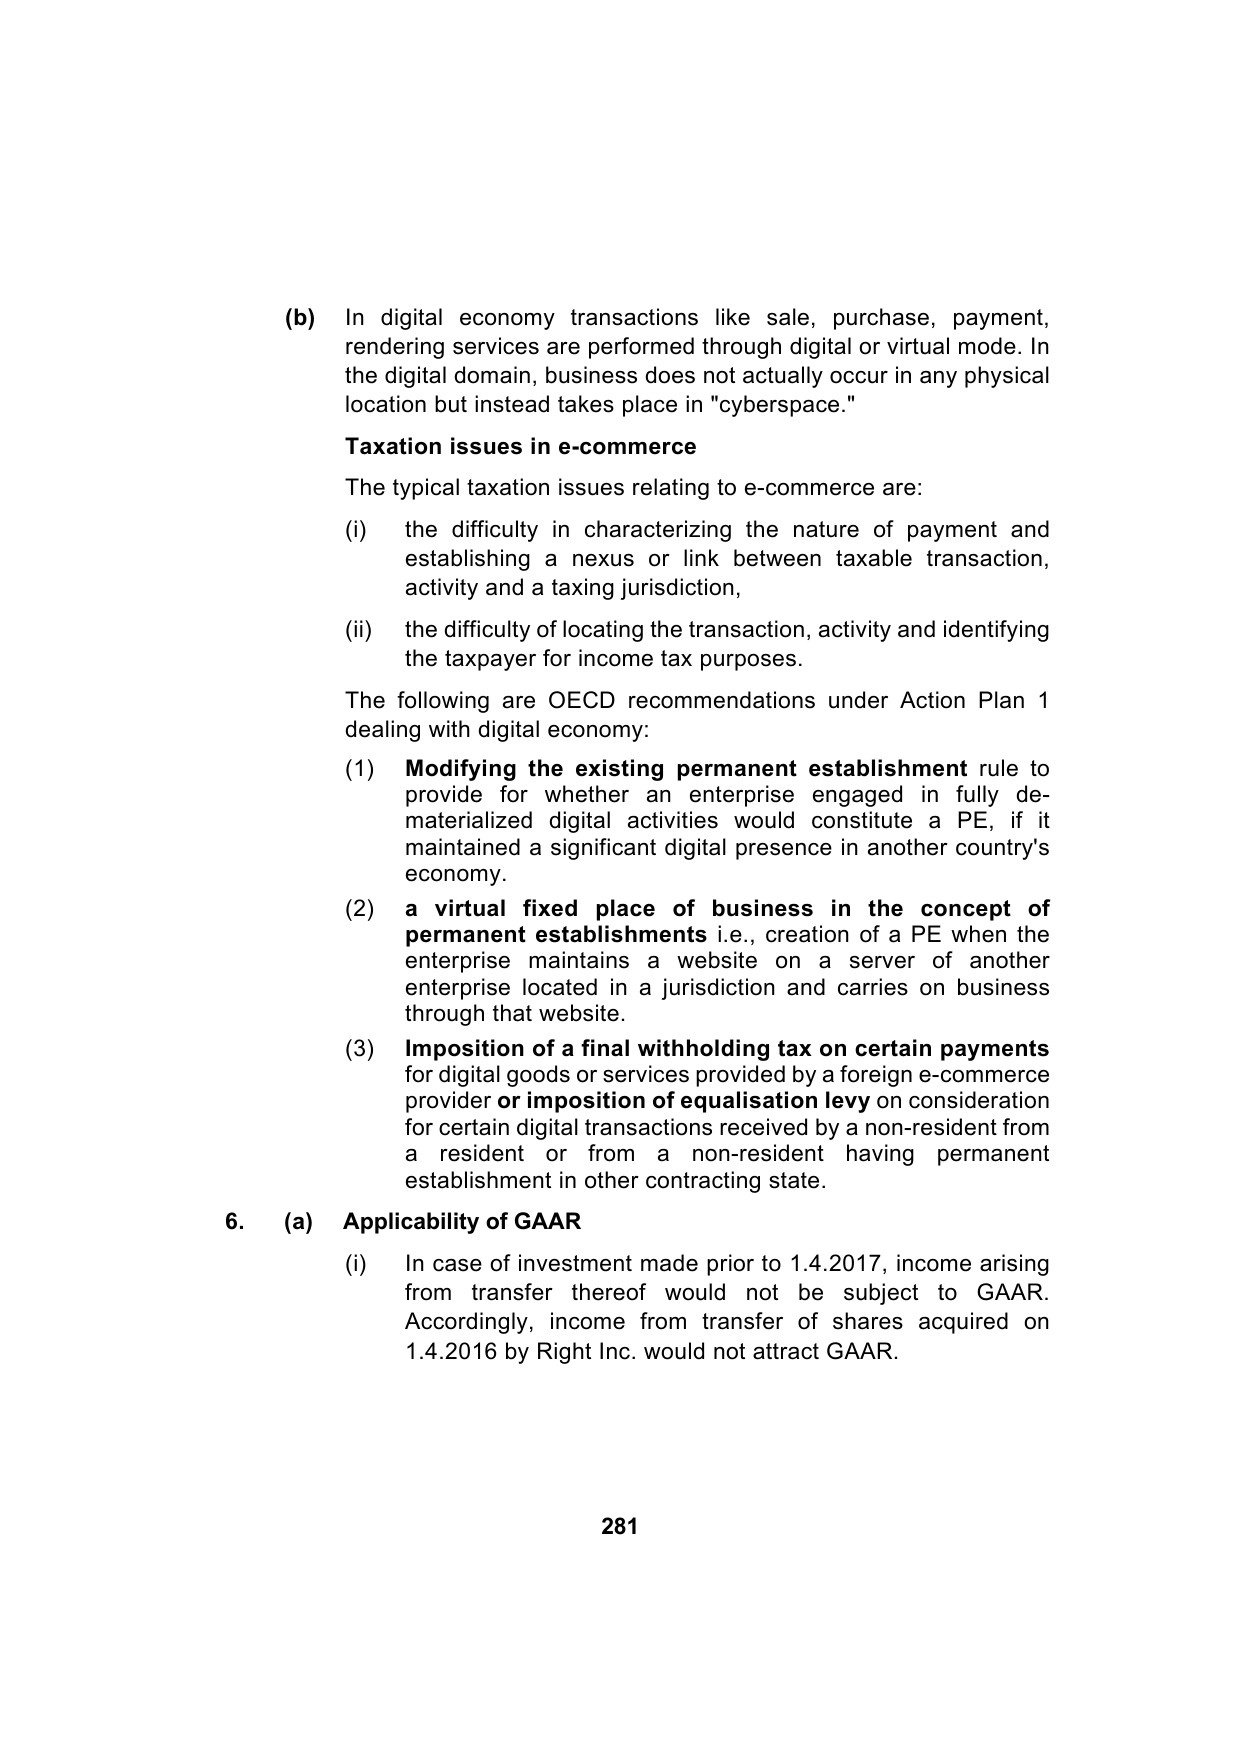
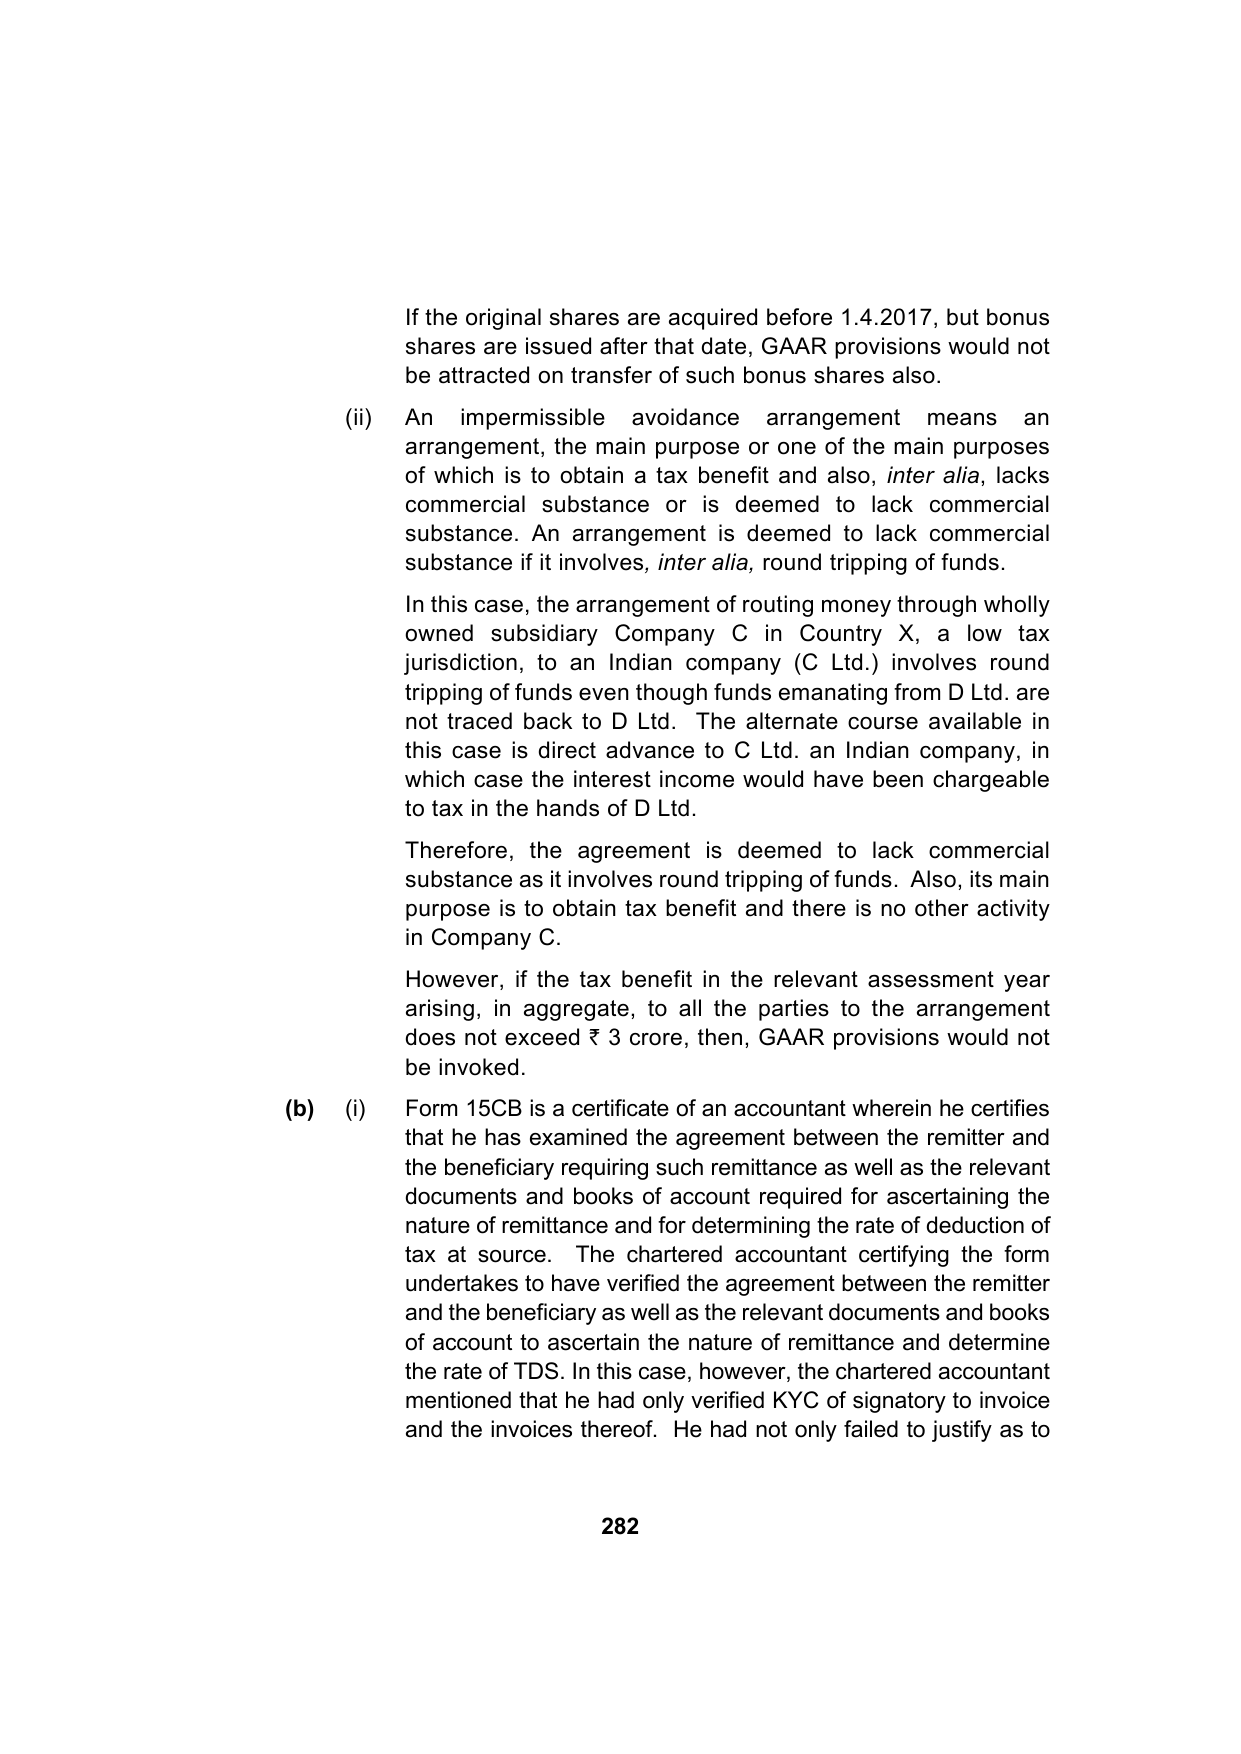
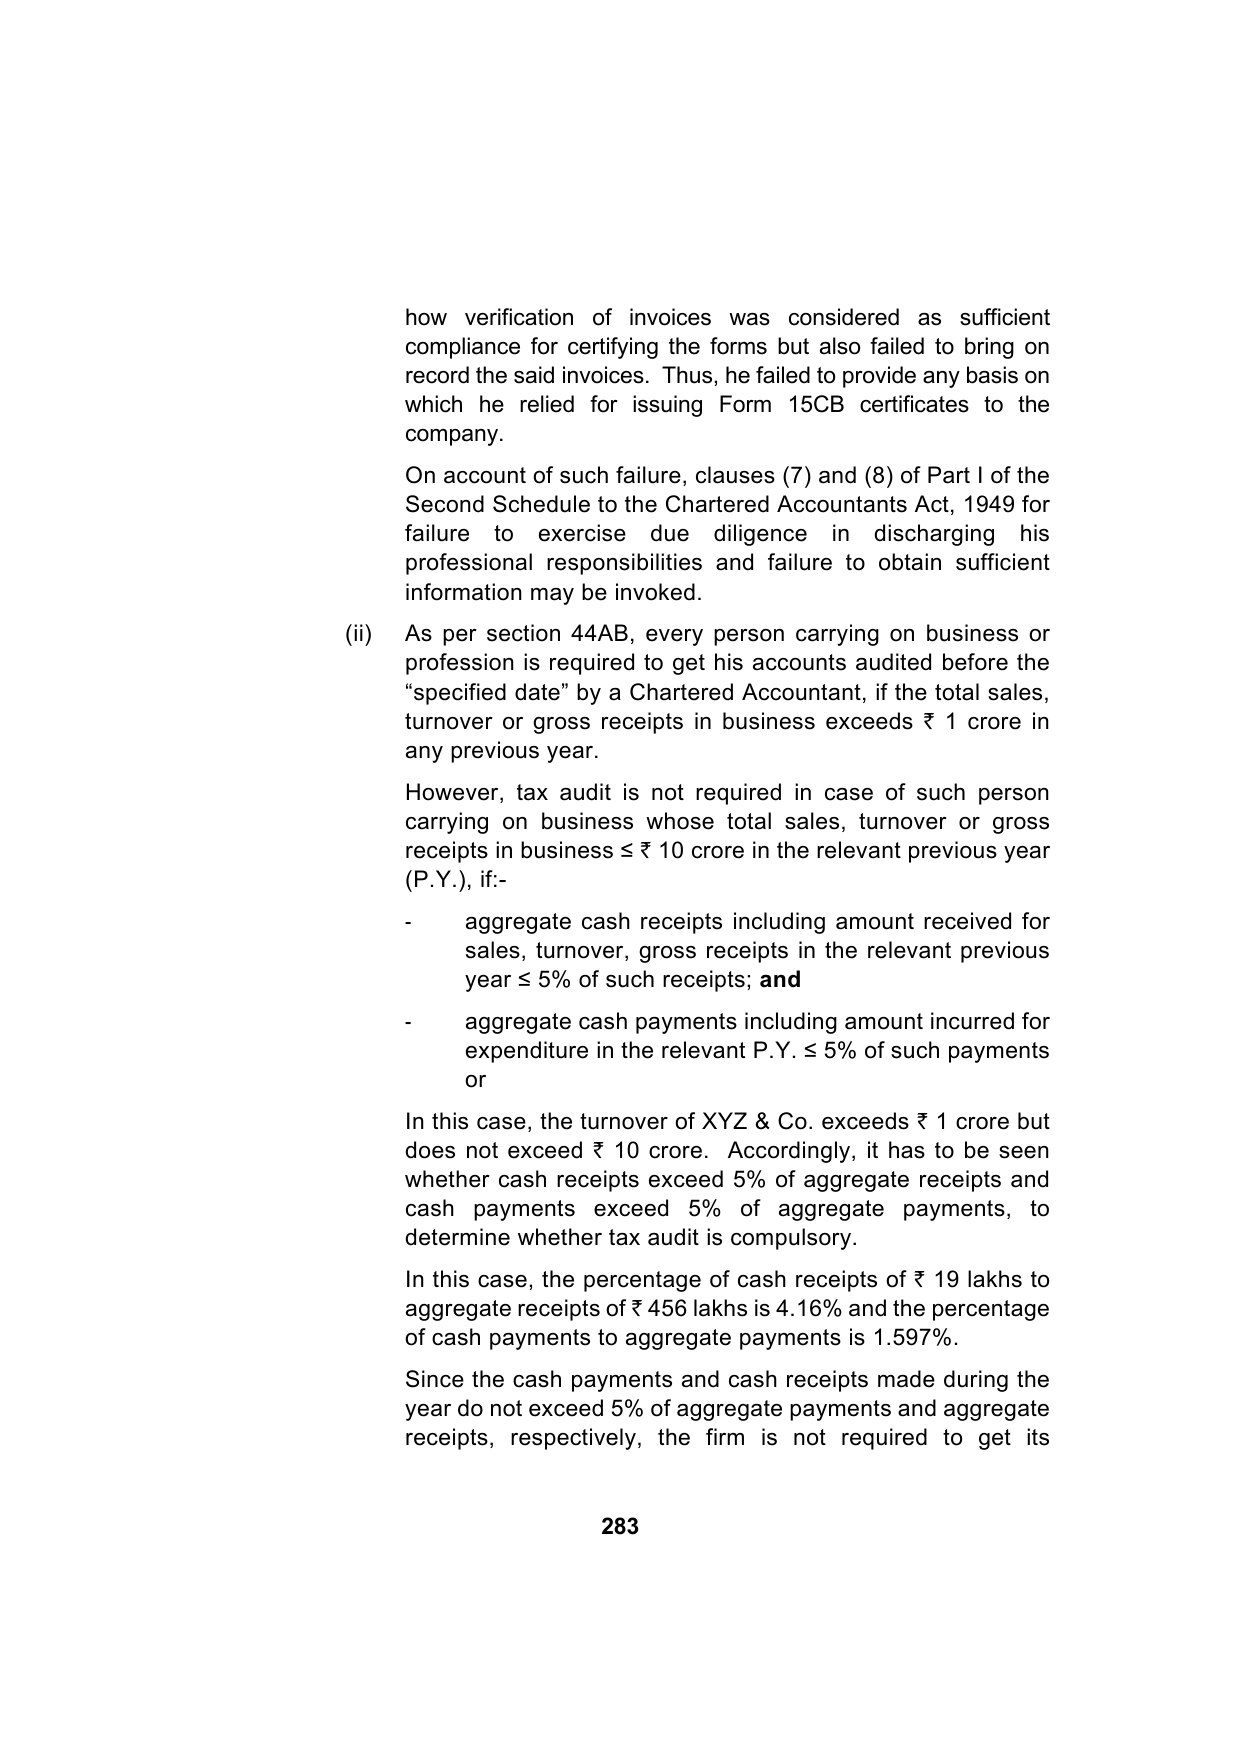
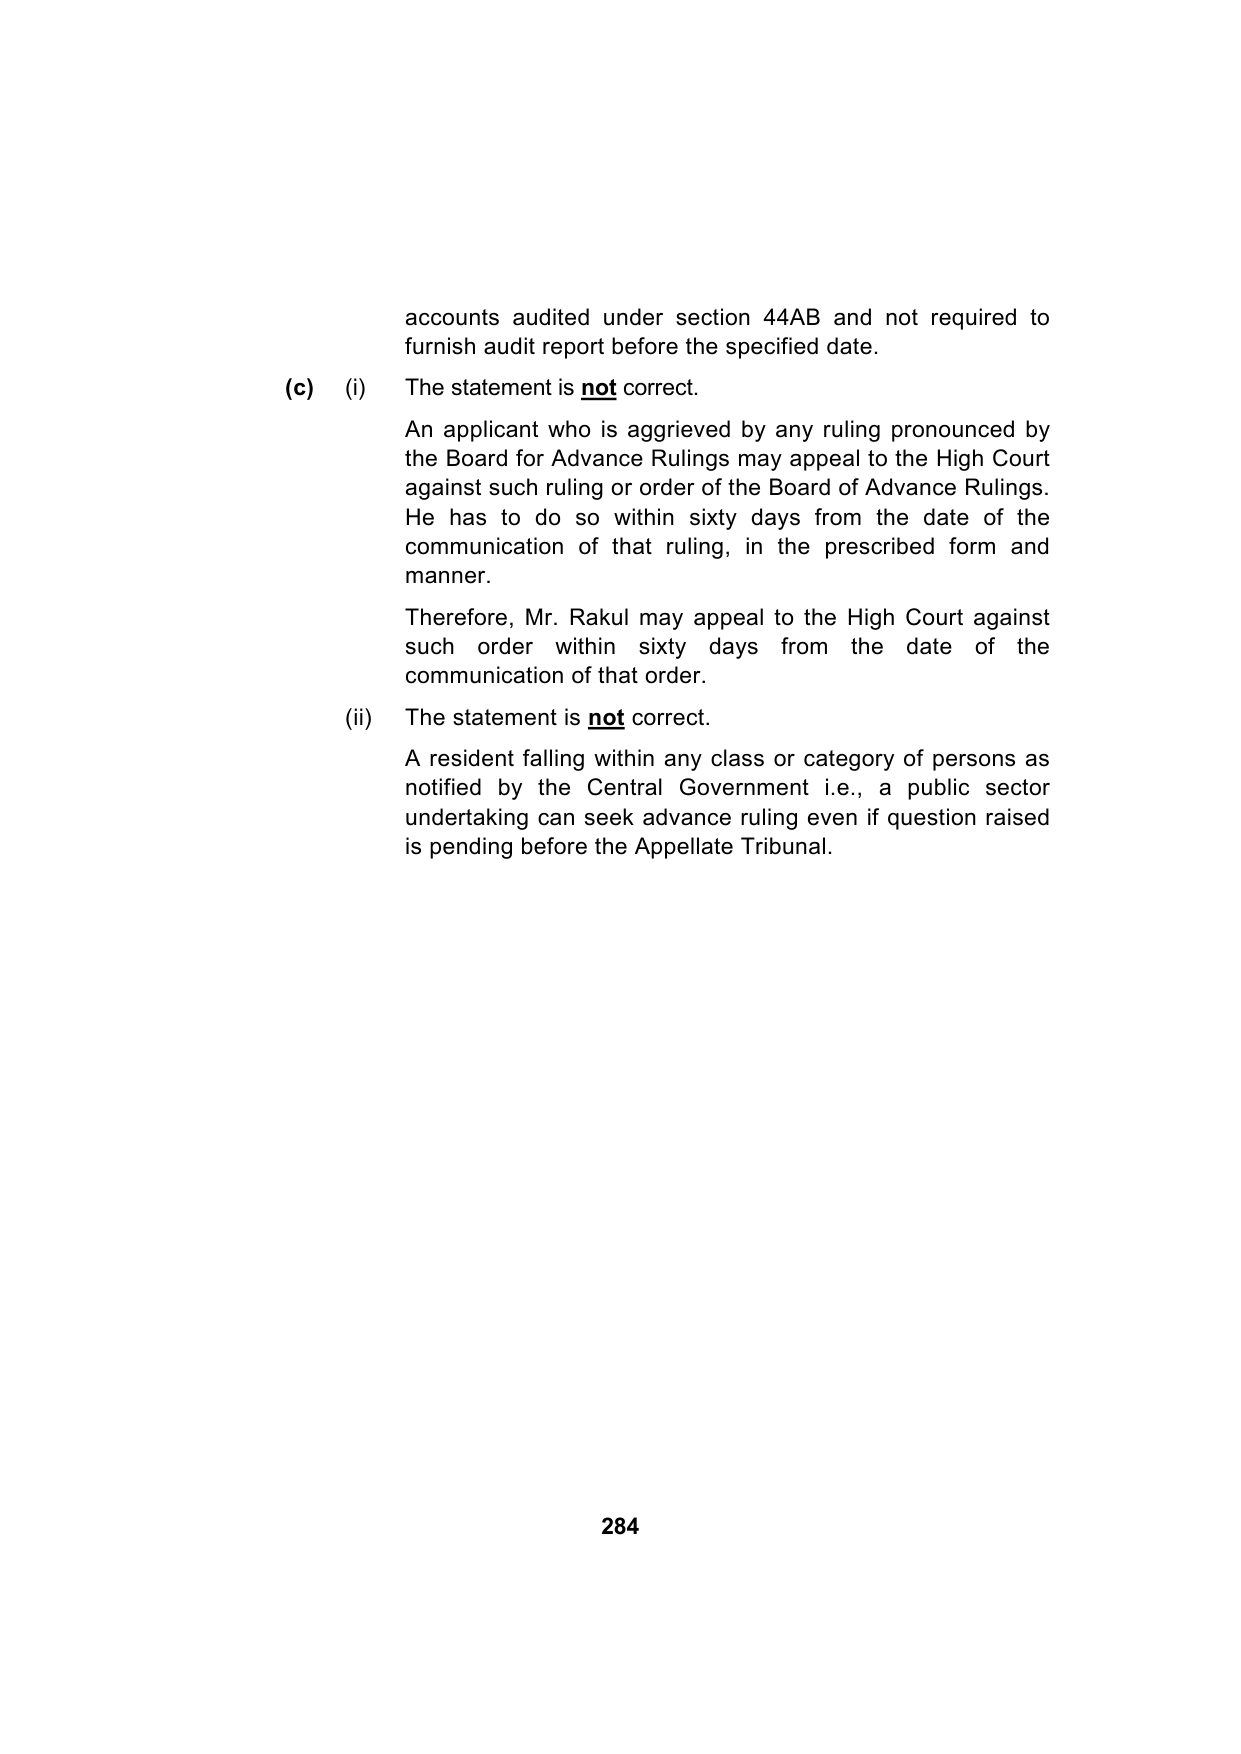
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 4 (100 marks)
Question
Answer
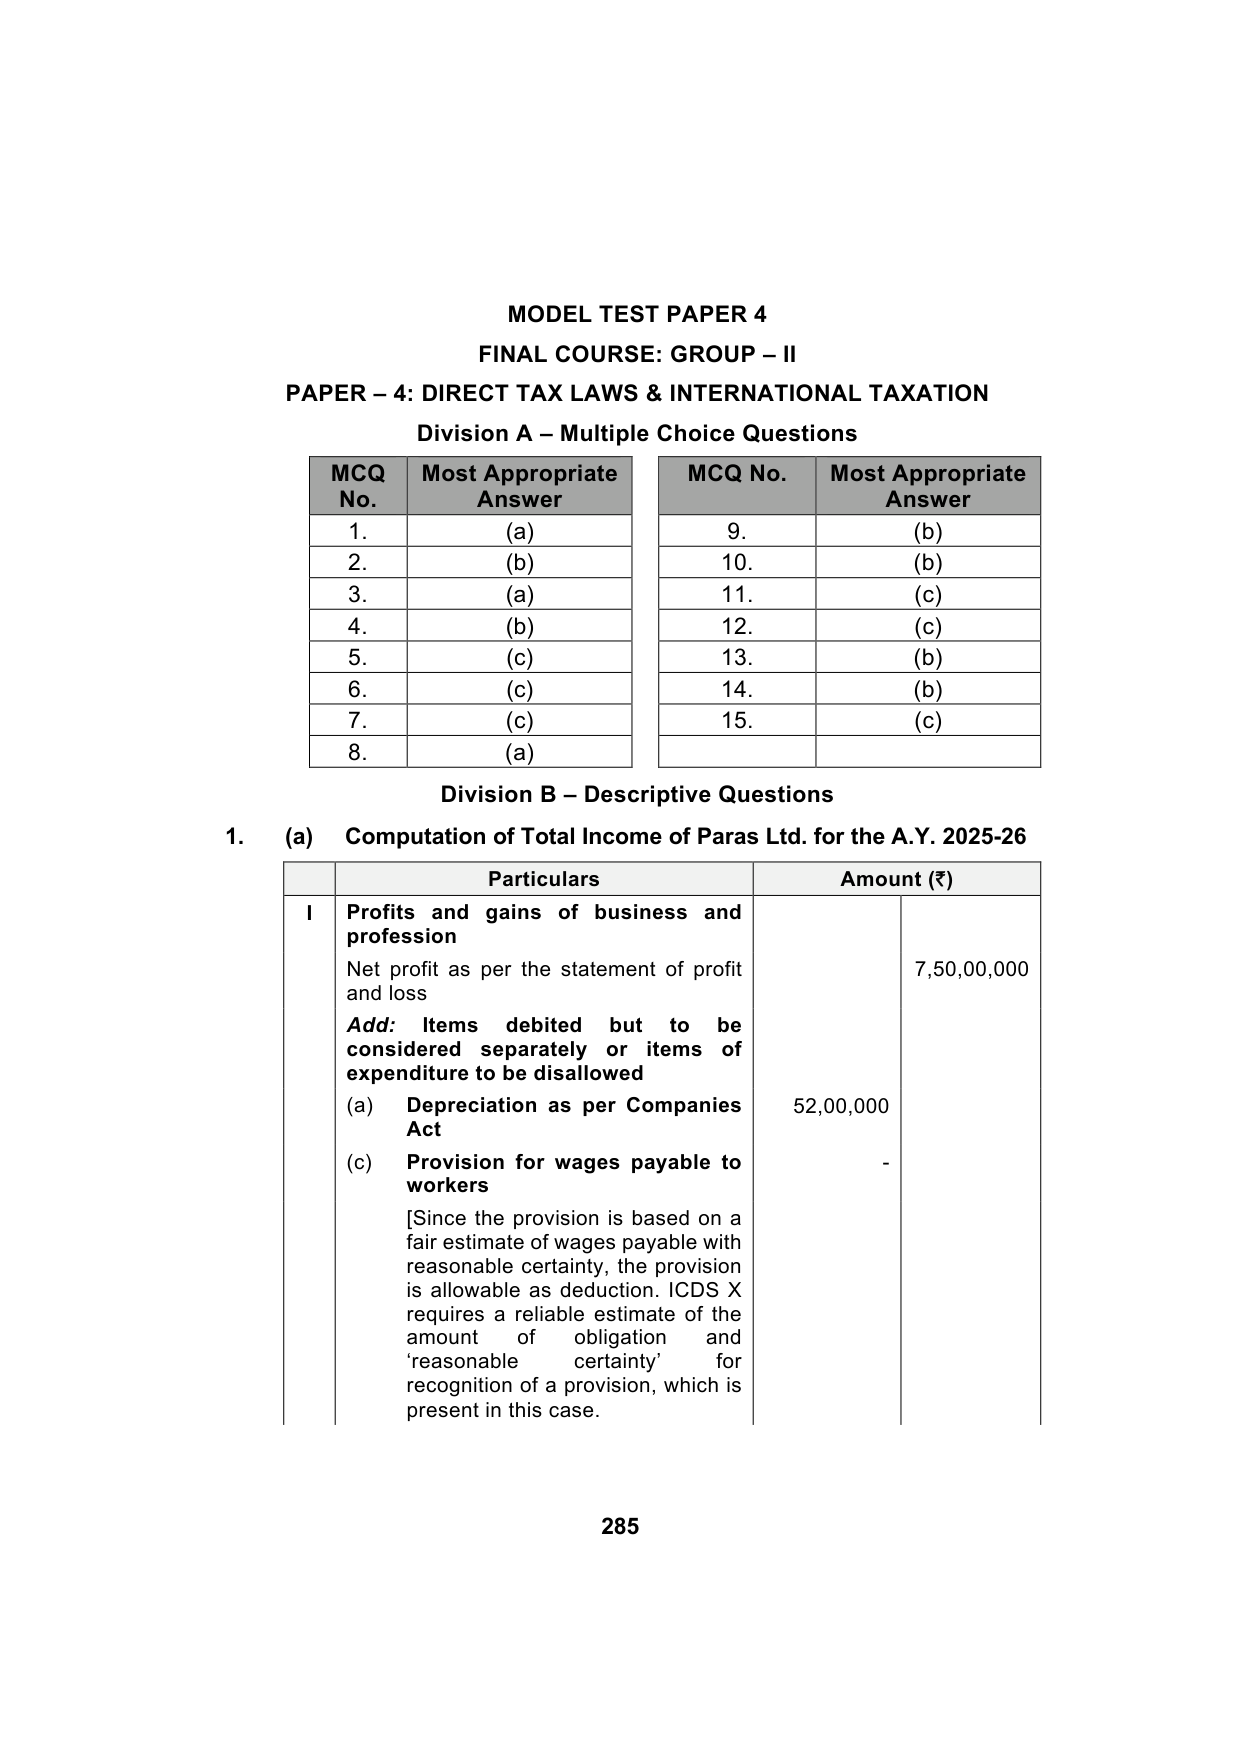
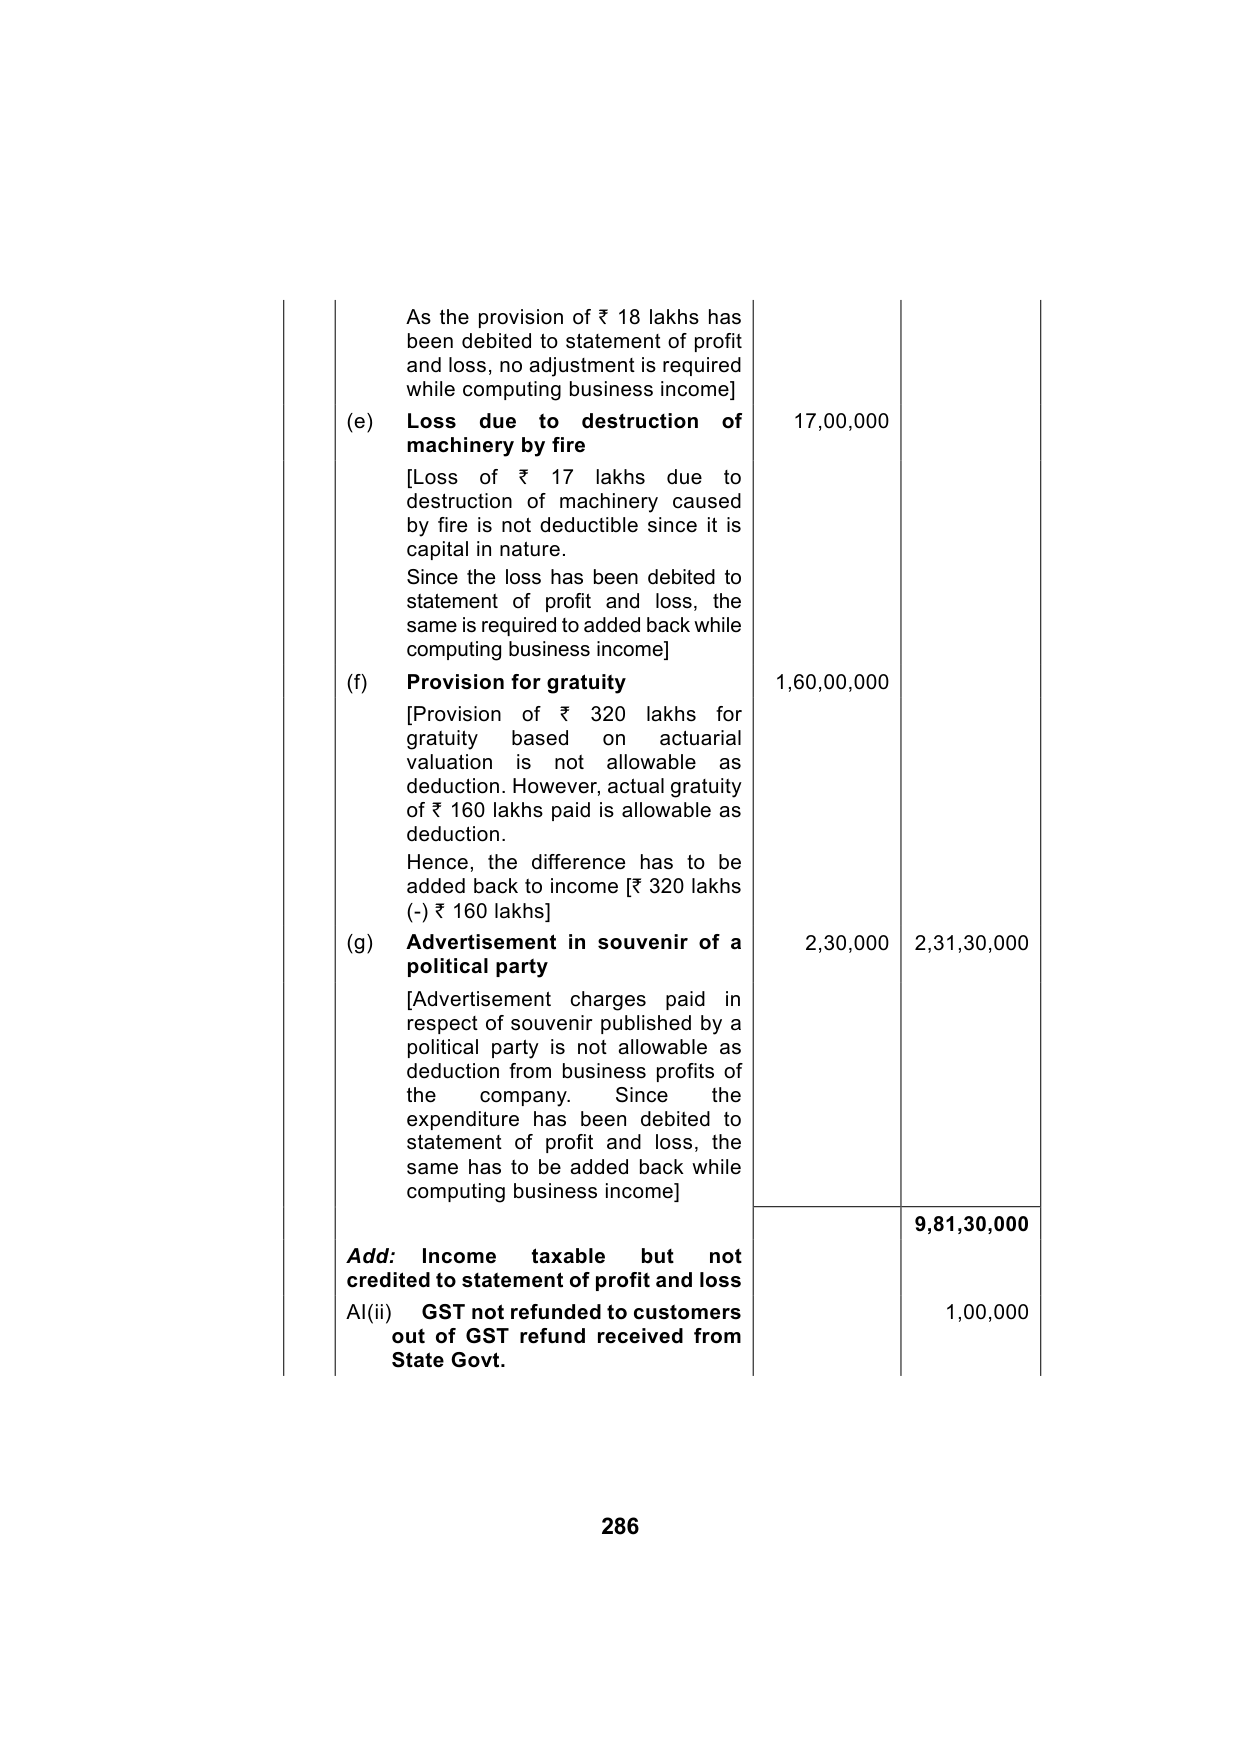
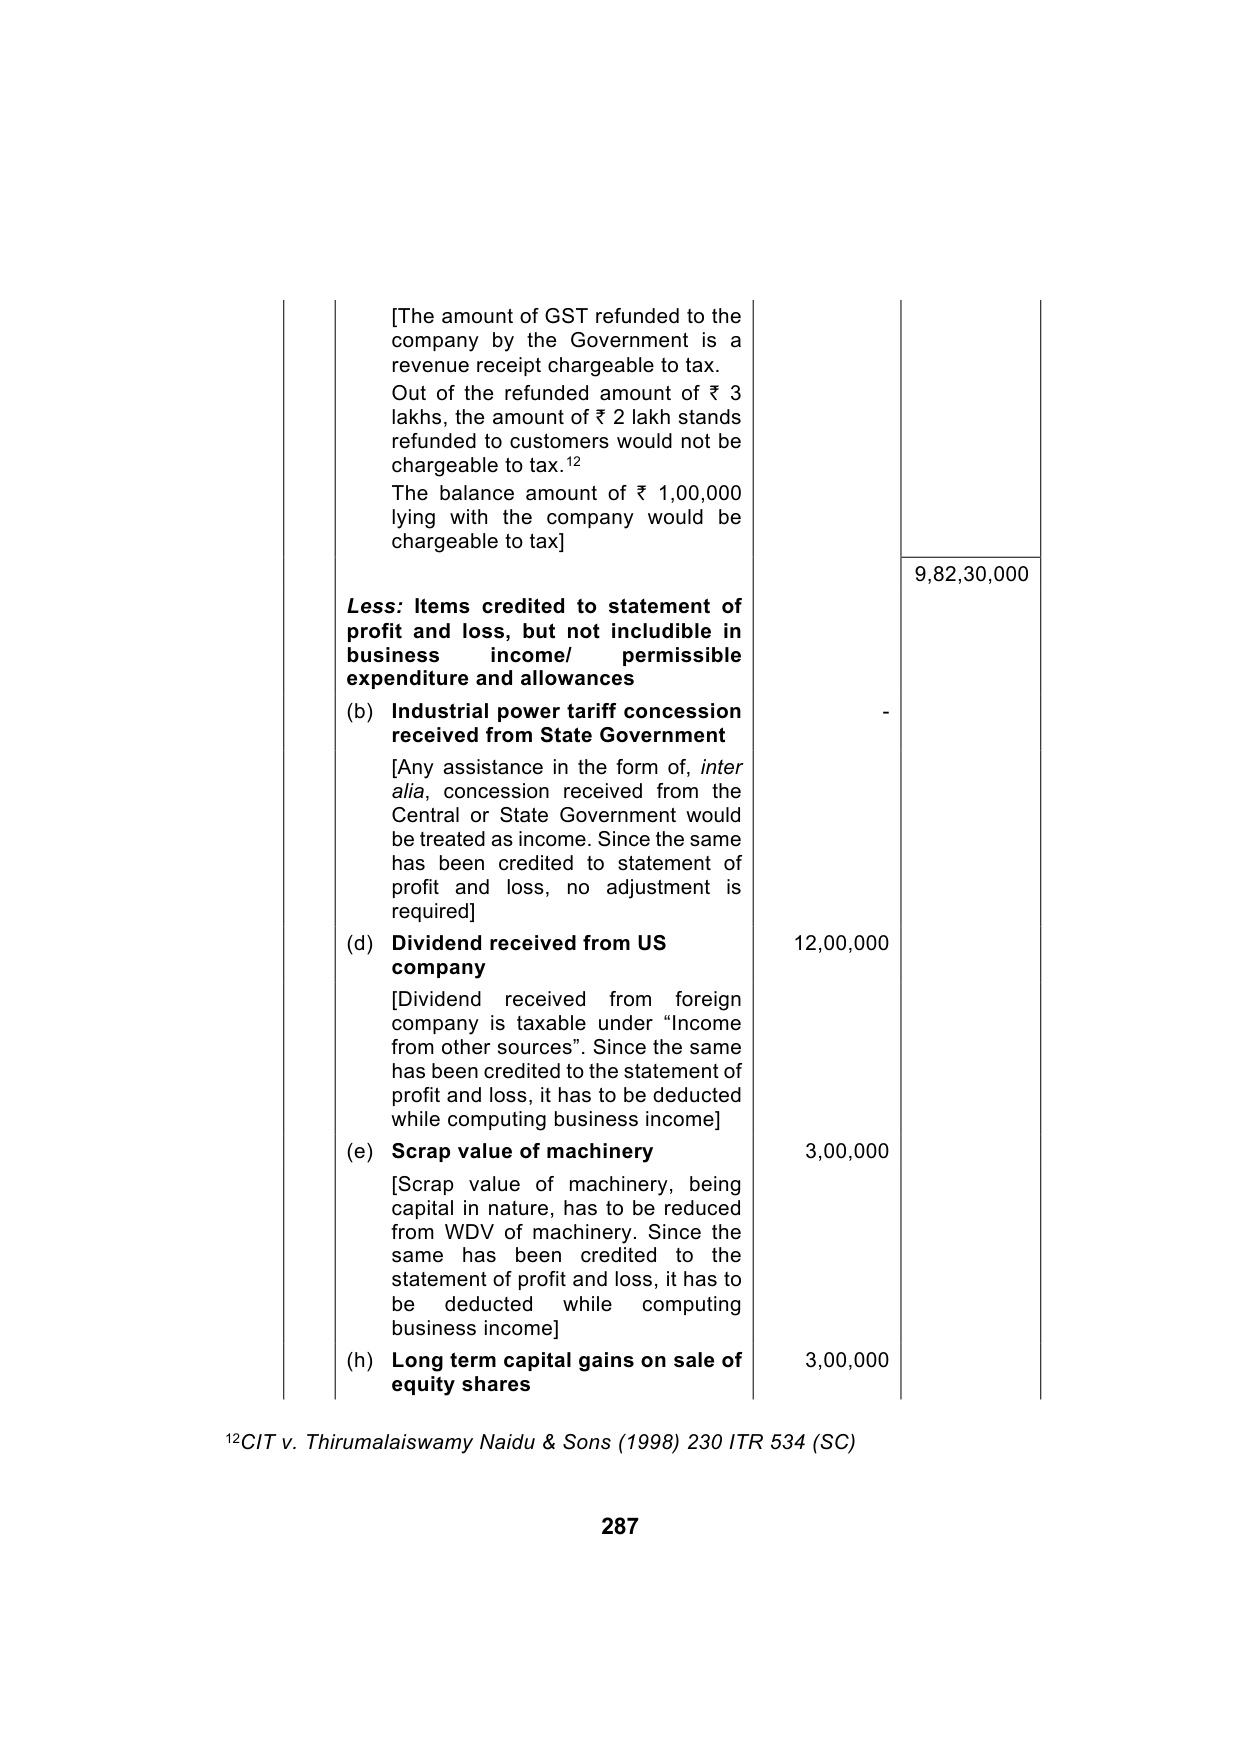
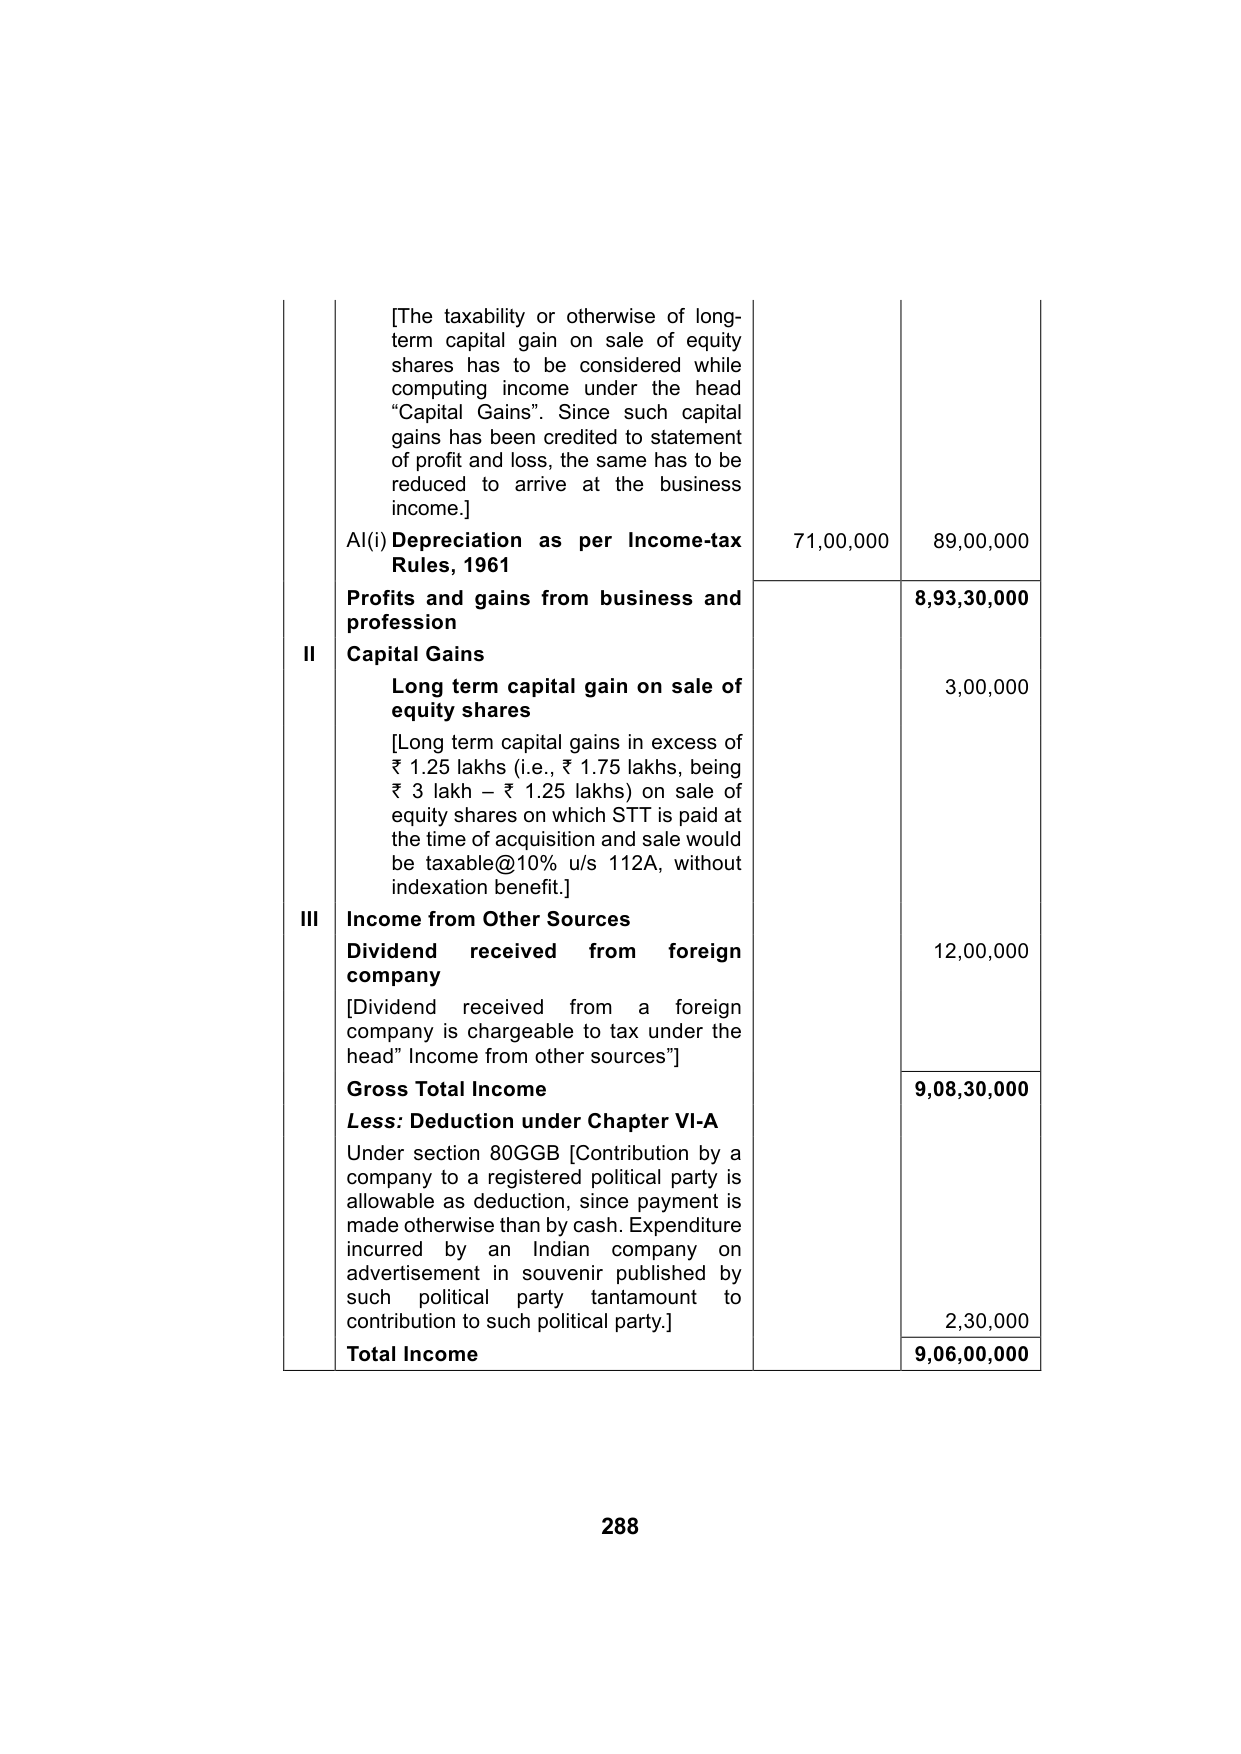
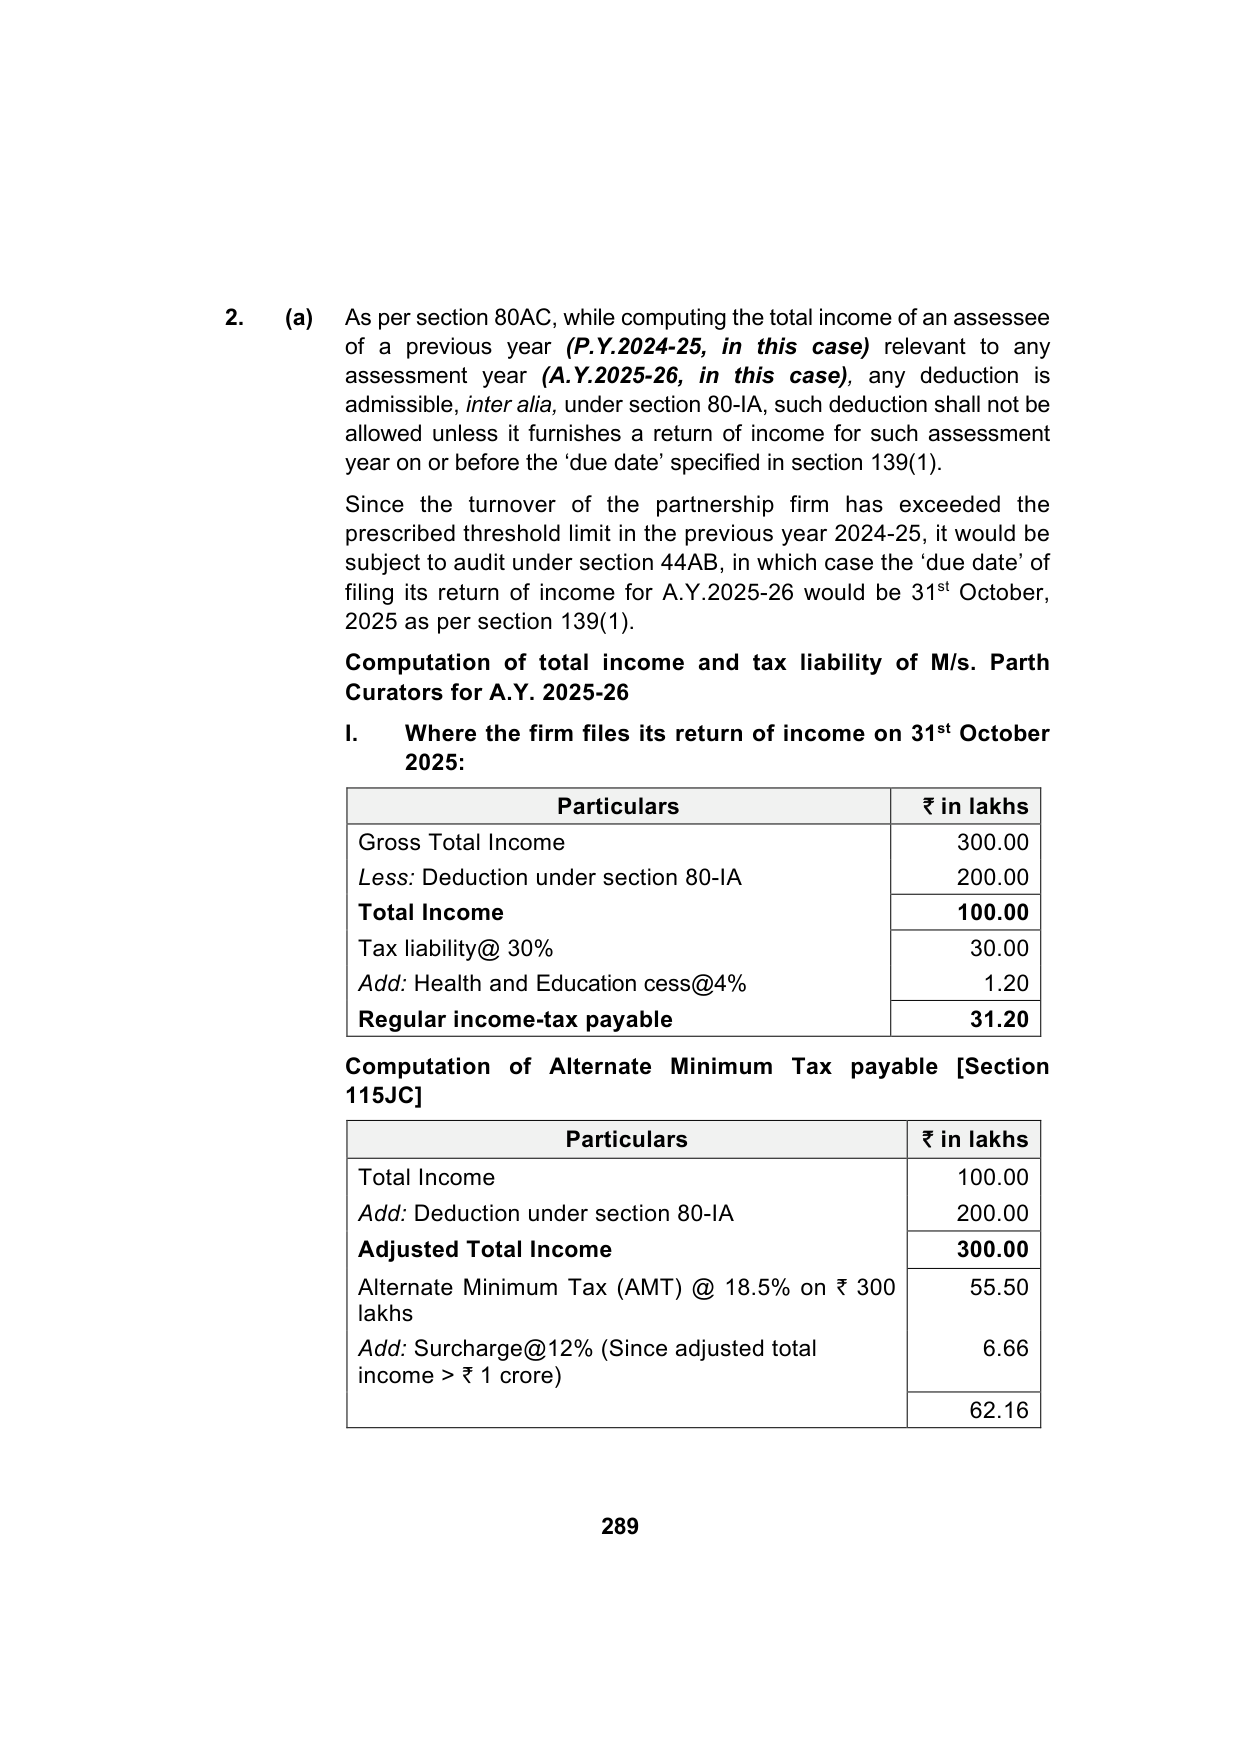
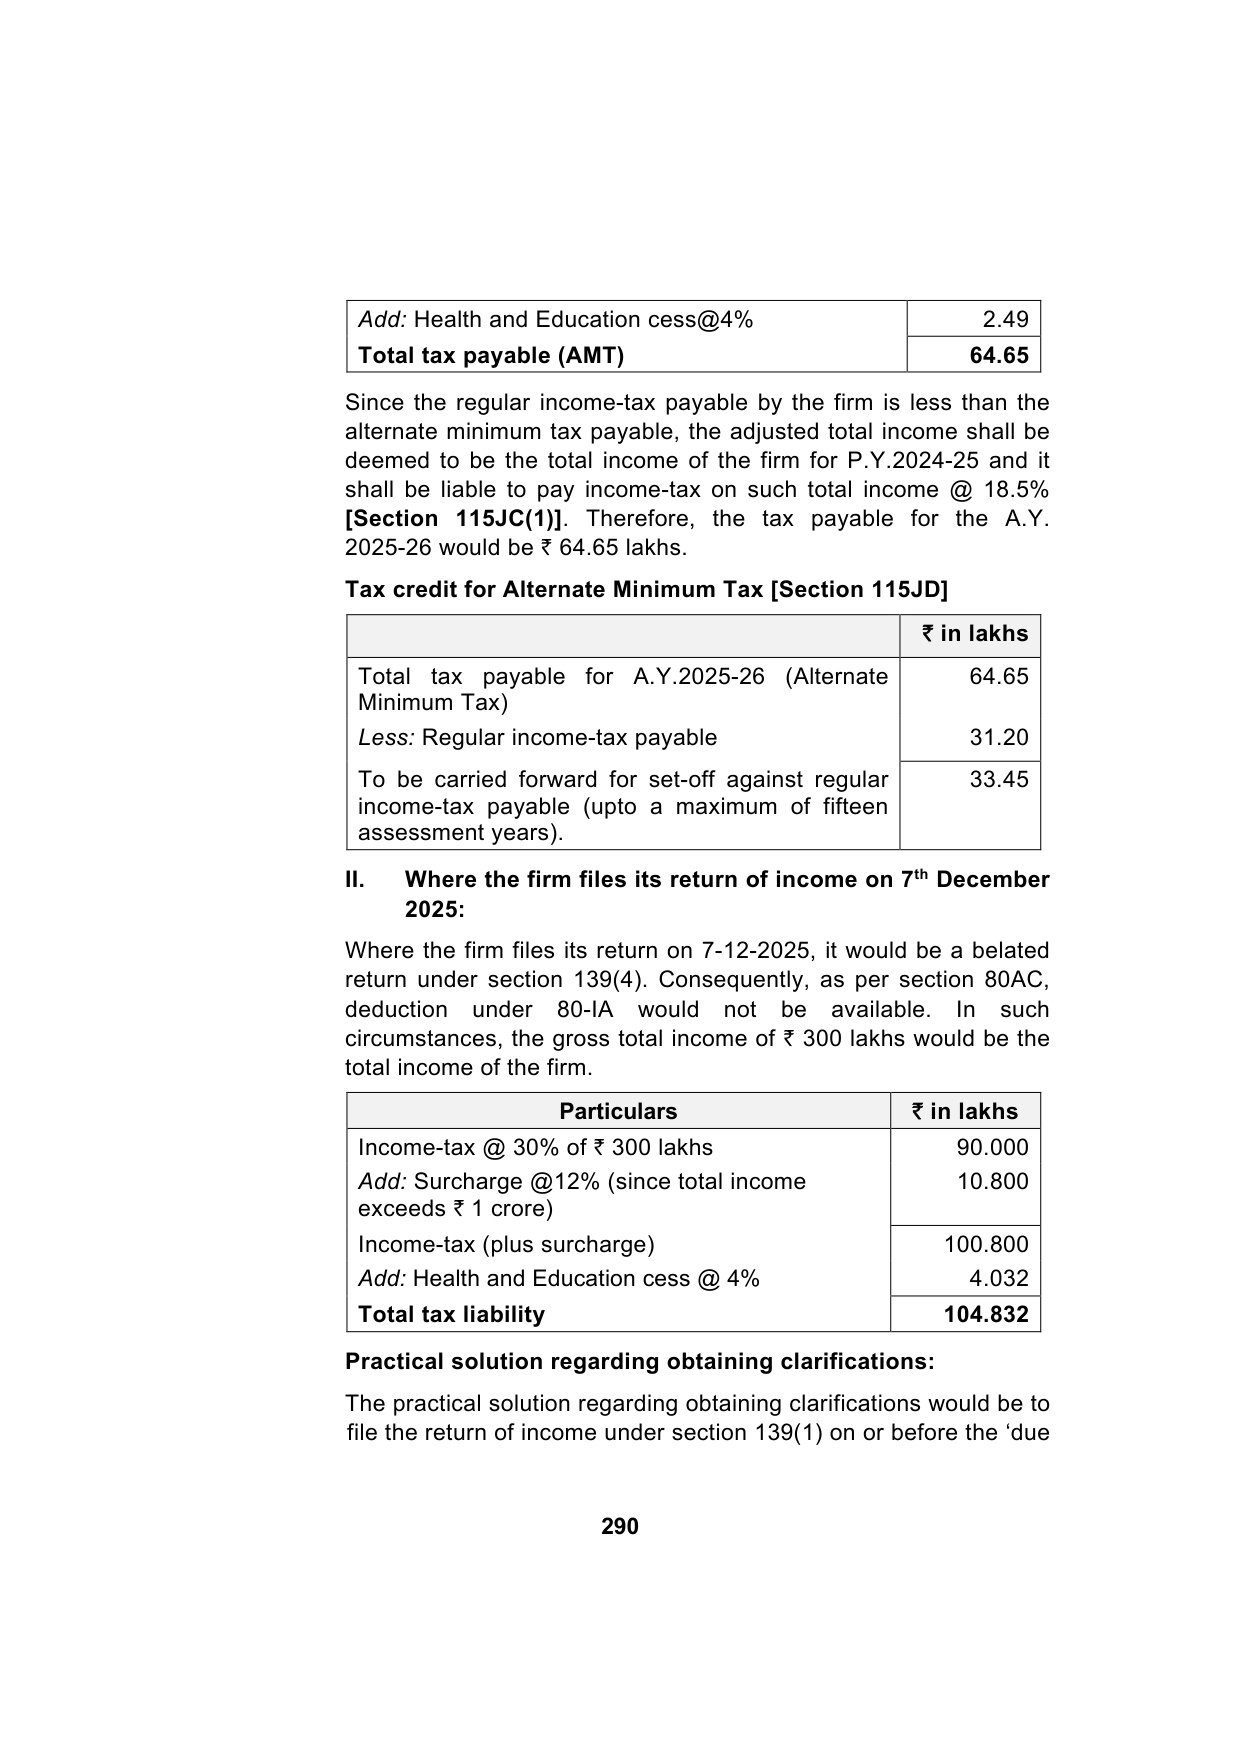
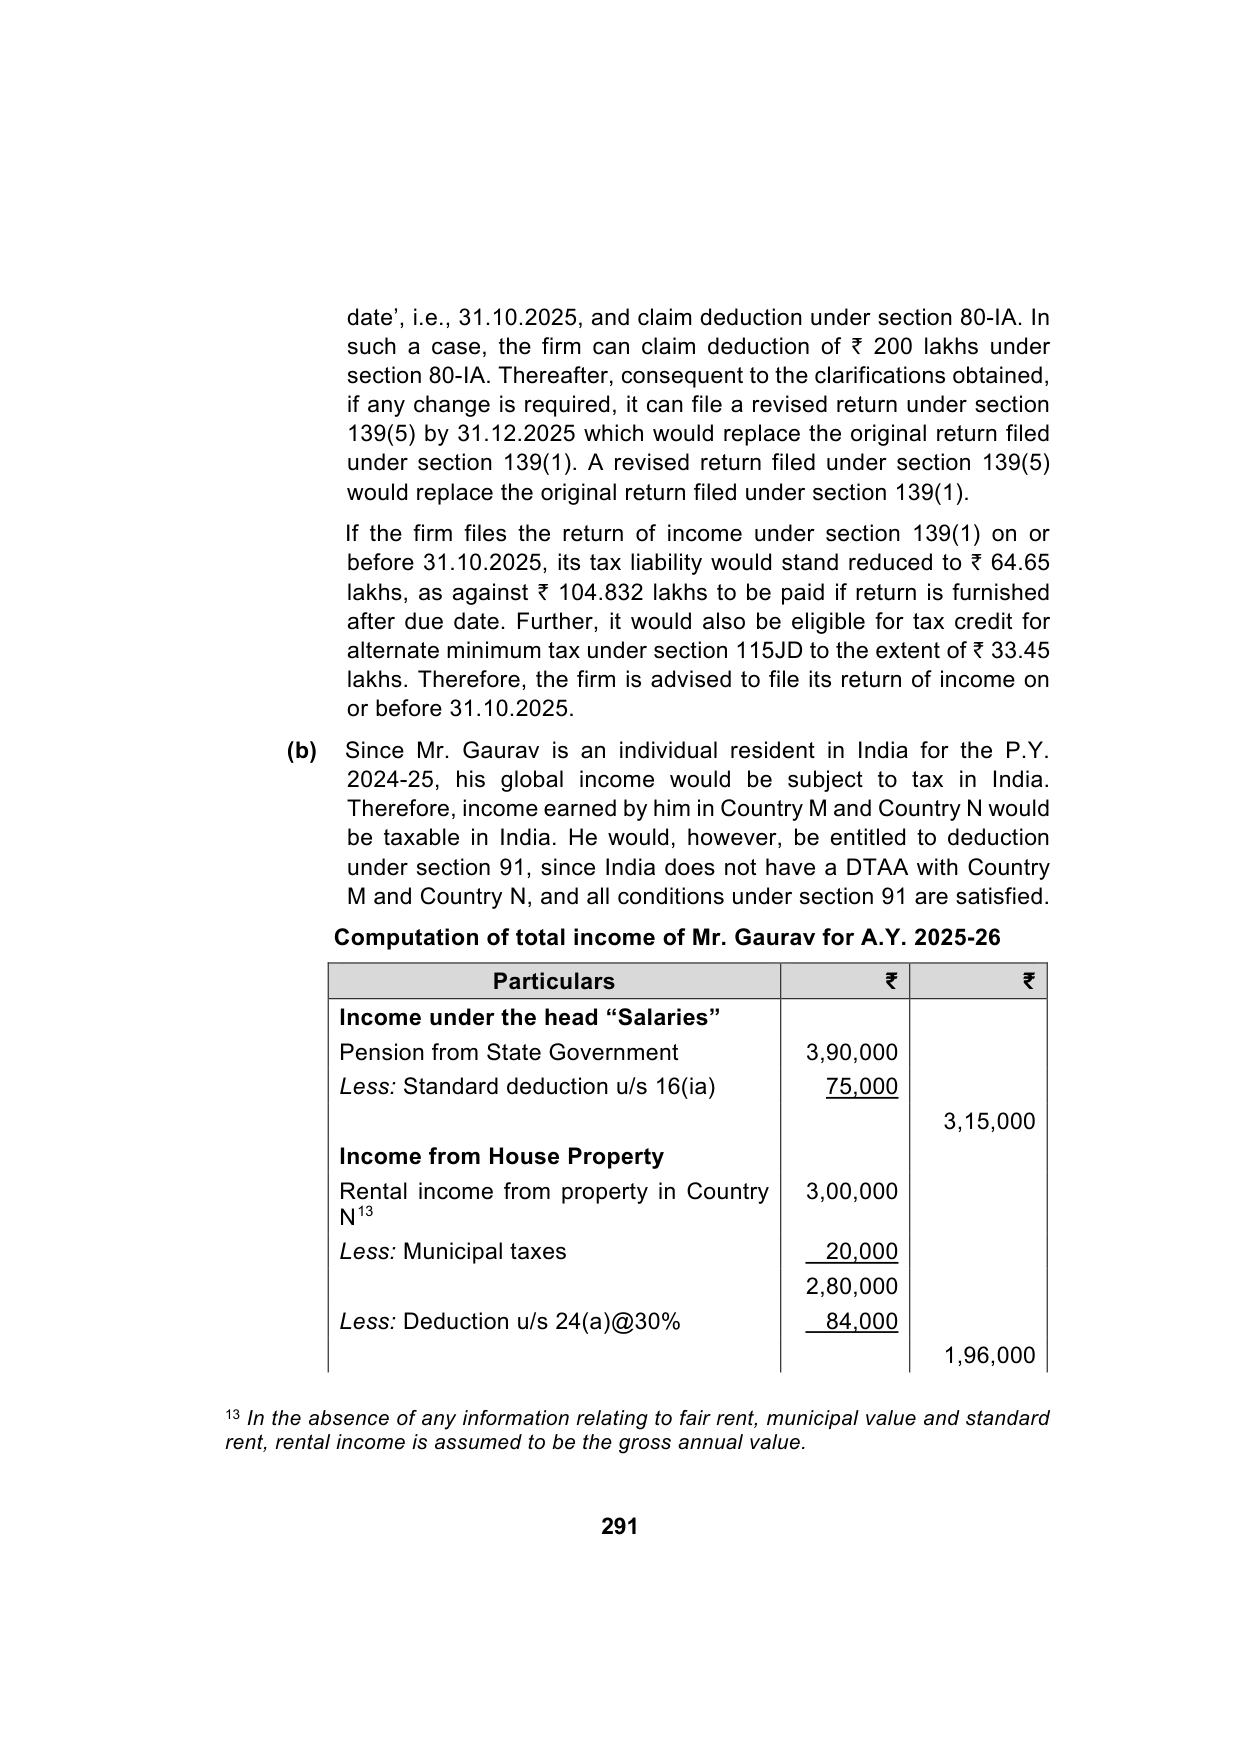
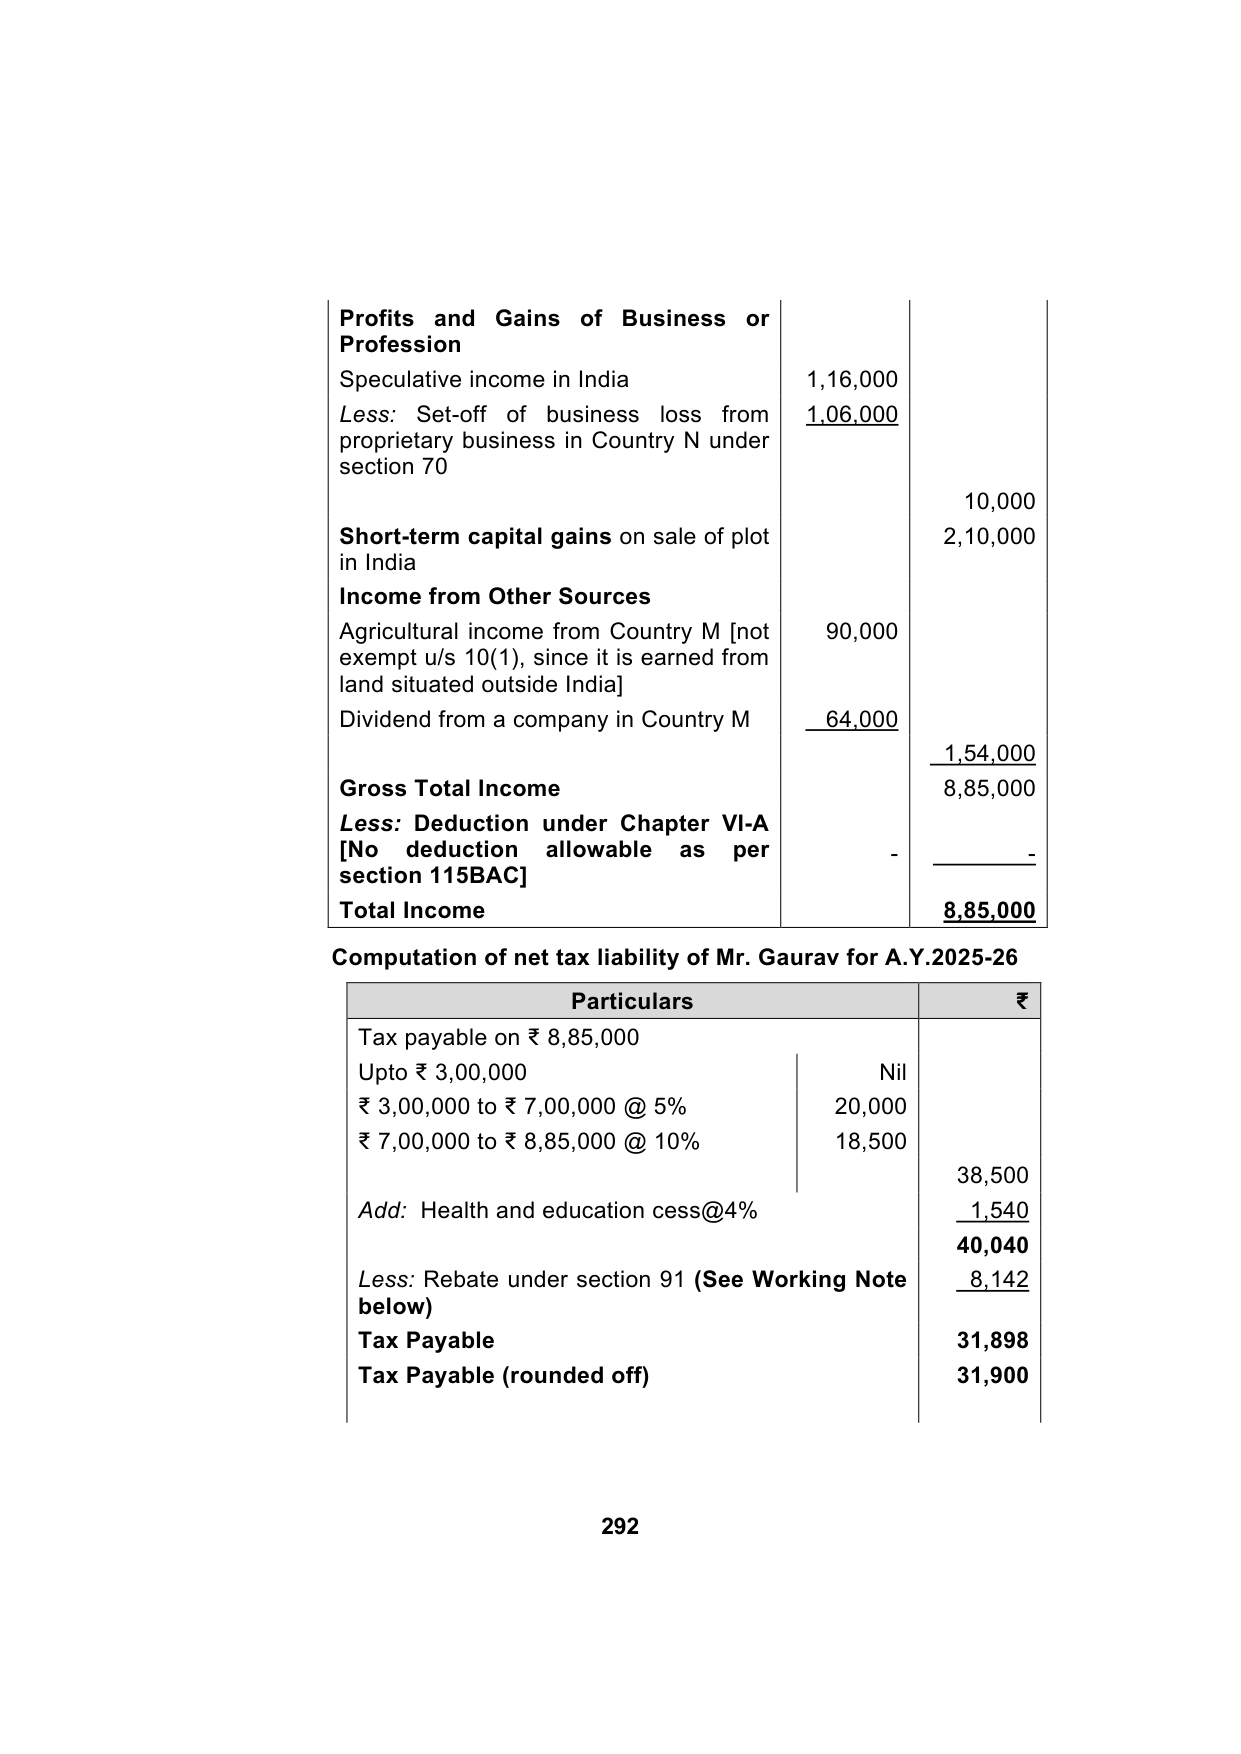
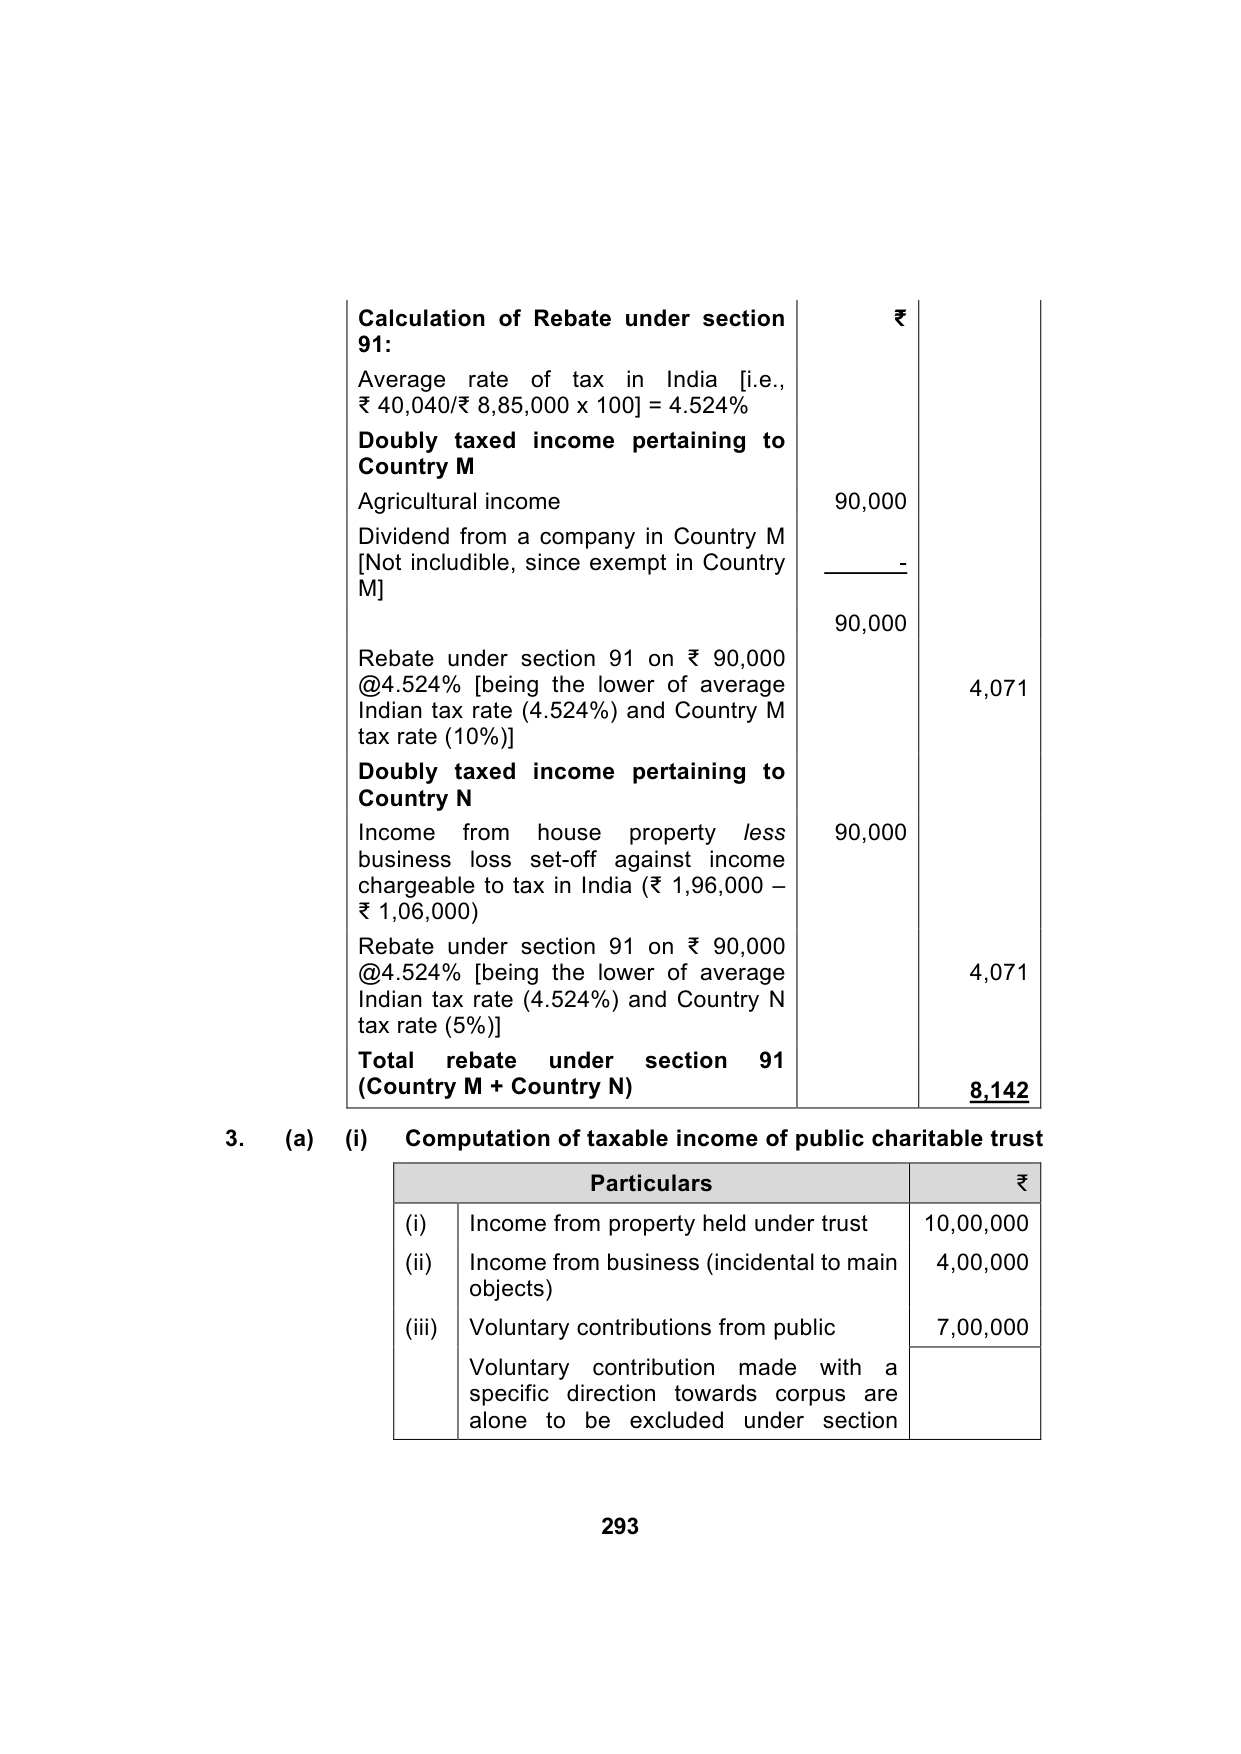
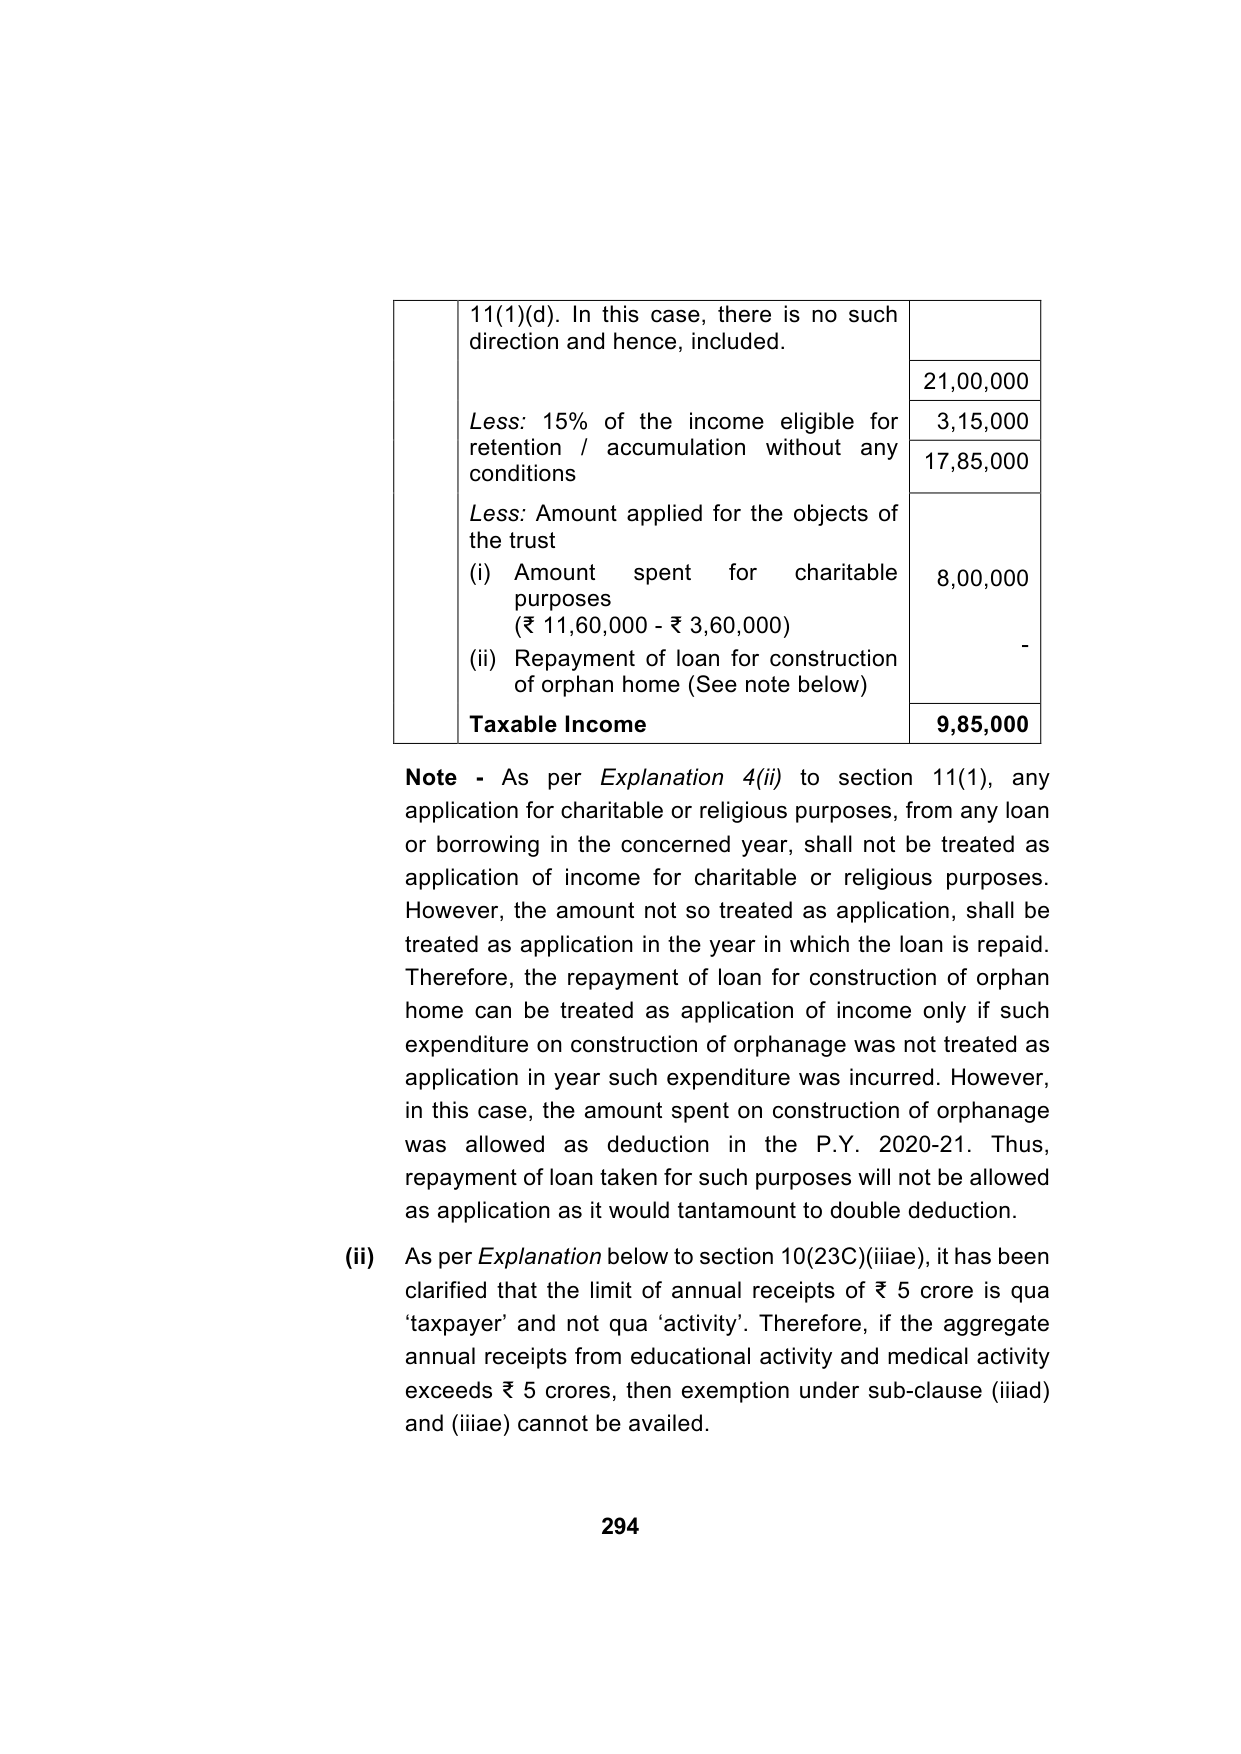
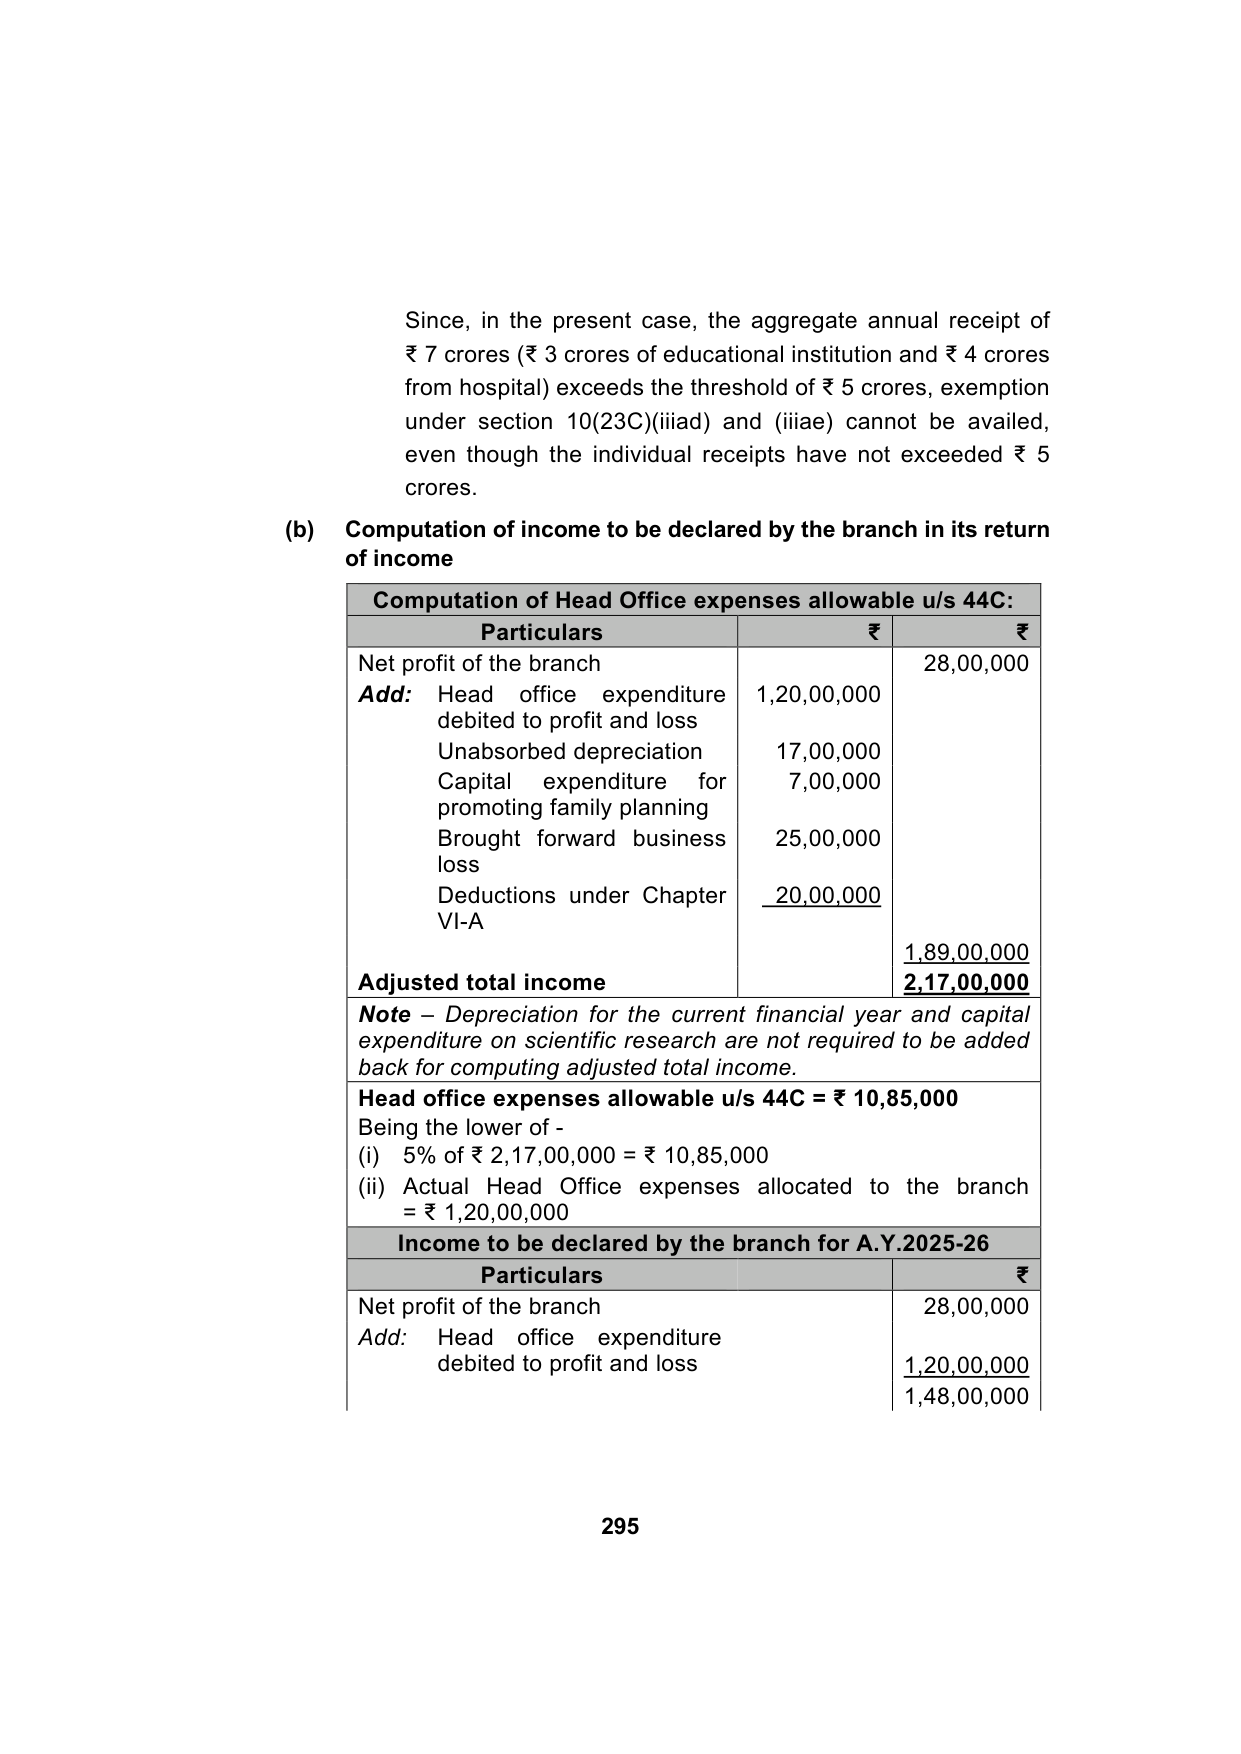
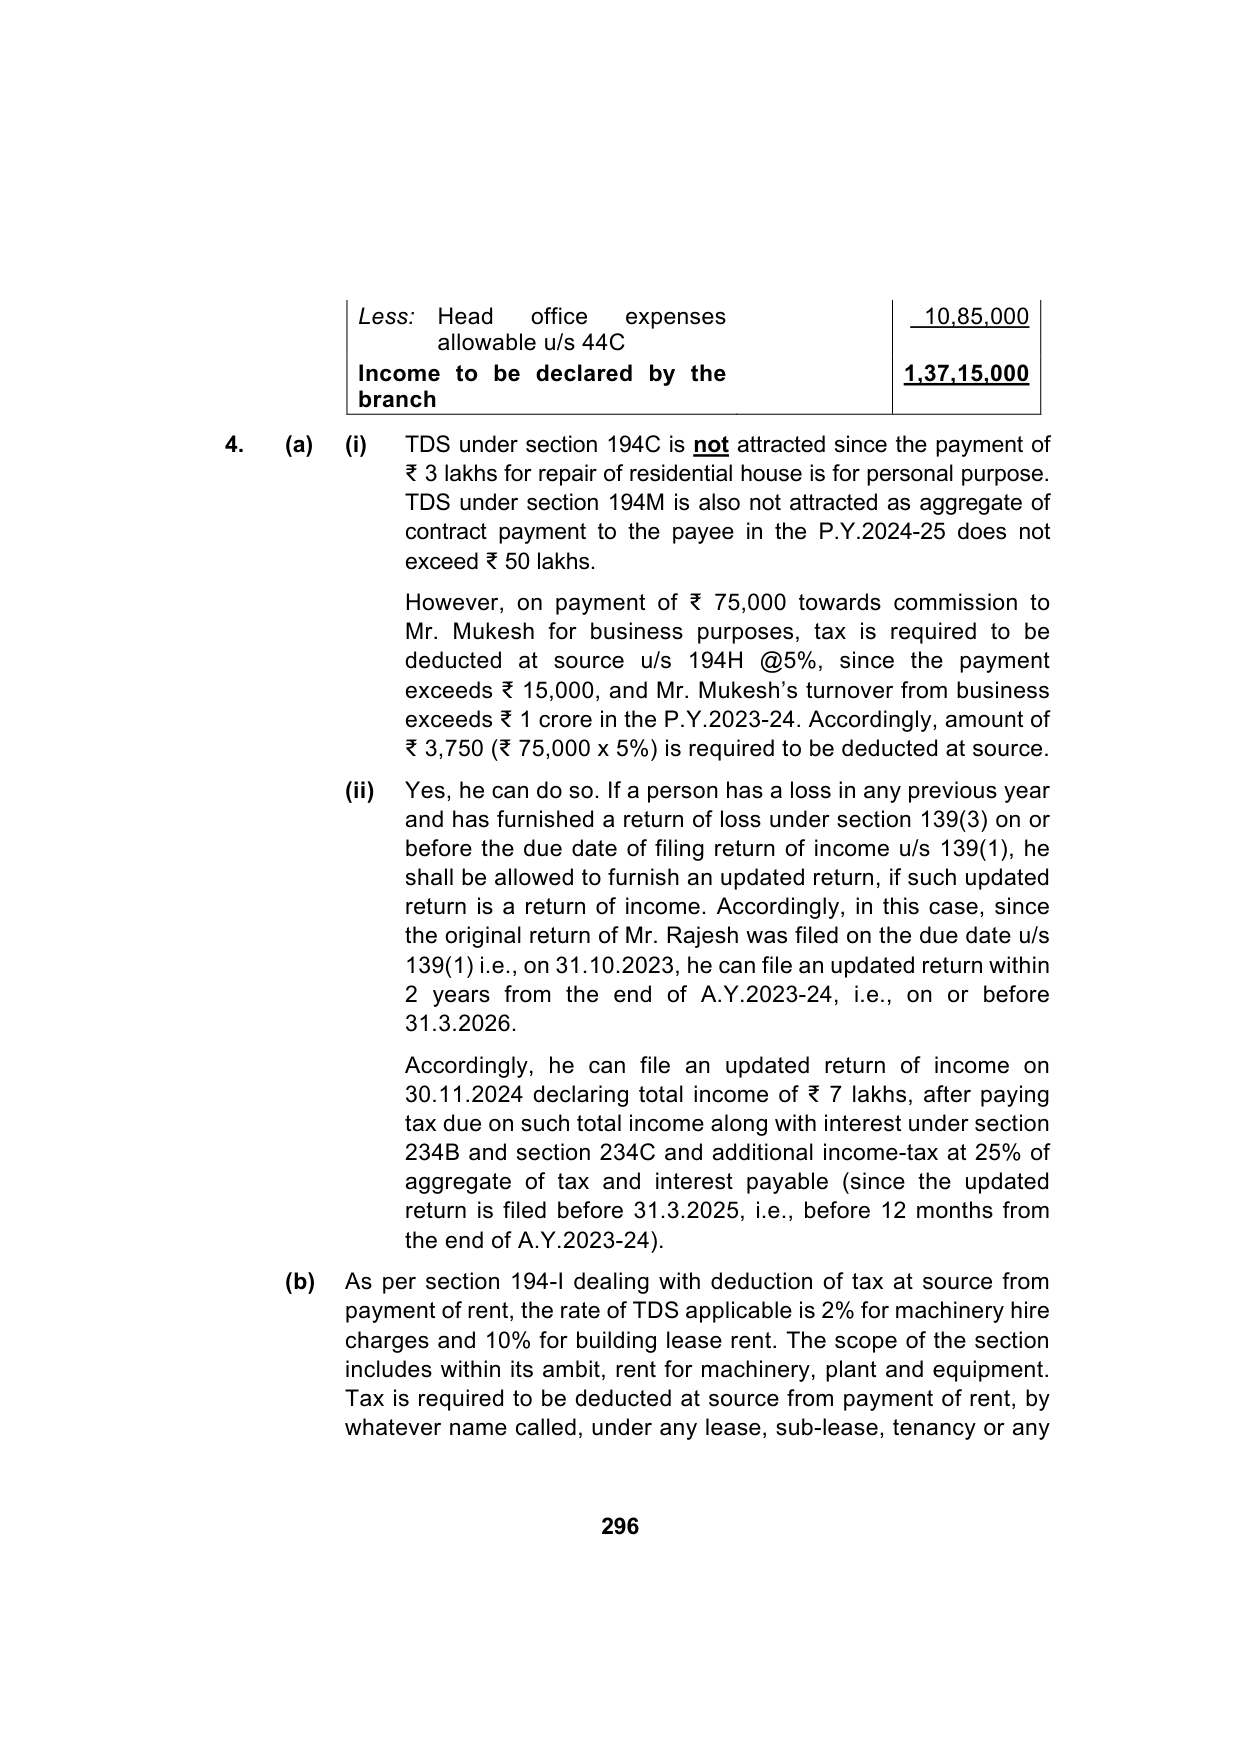
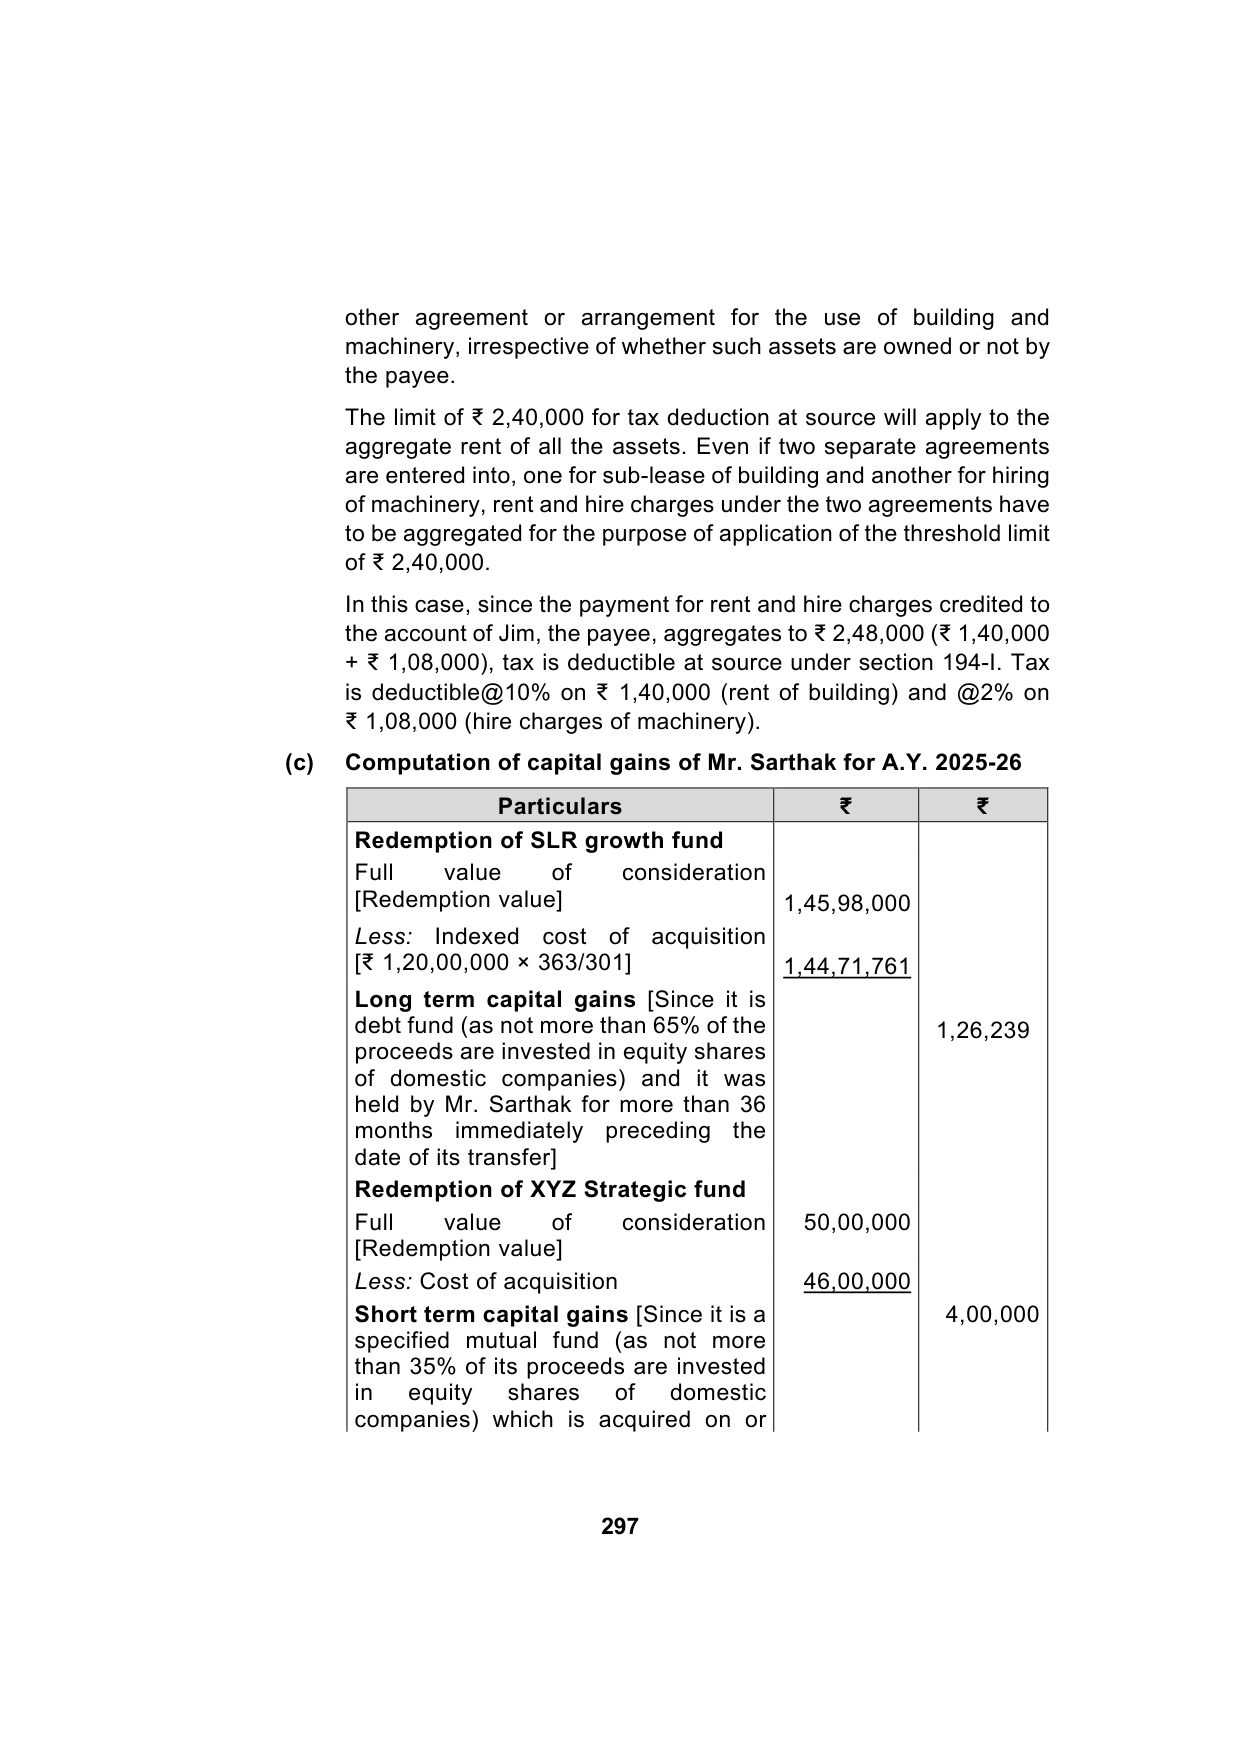
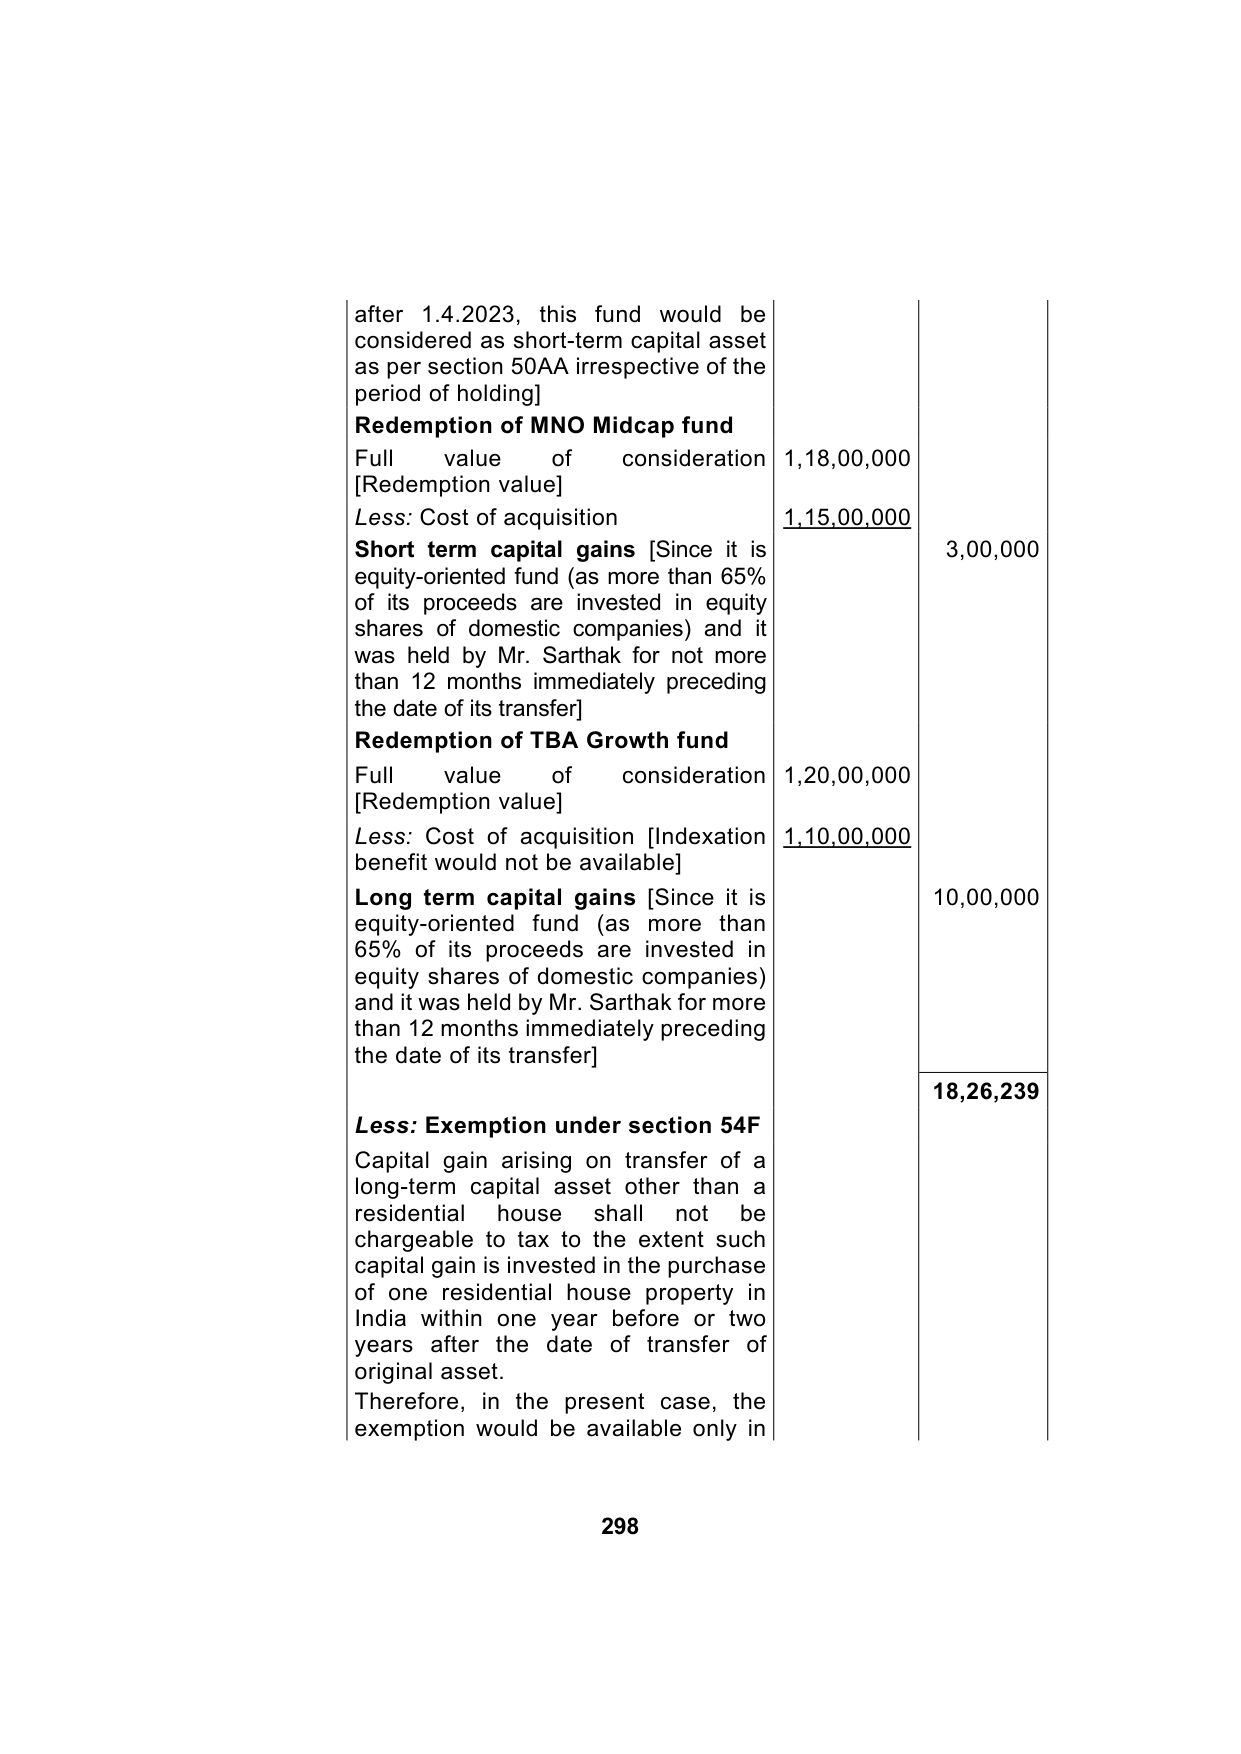
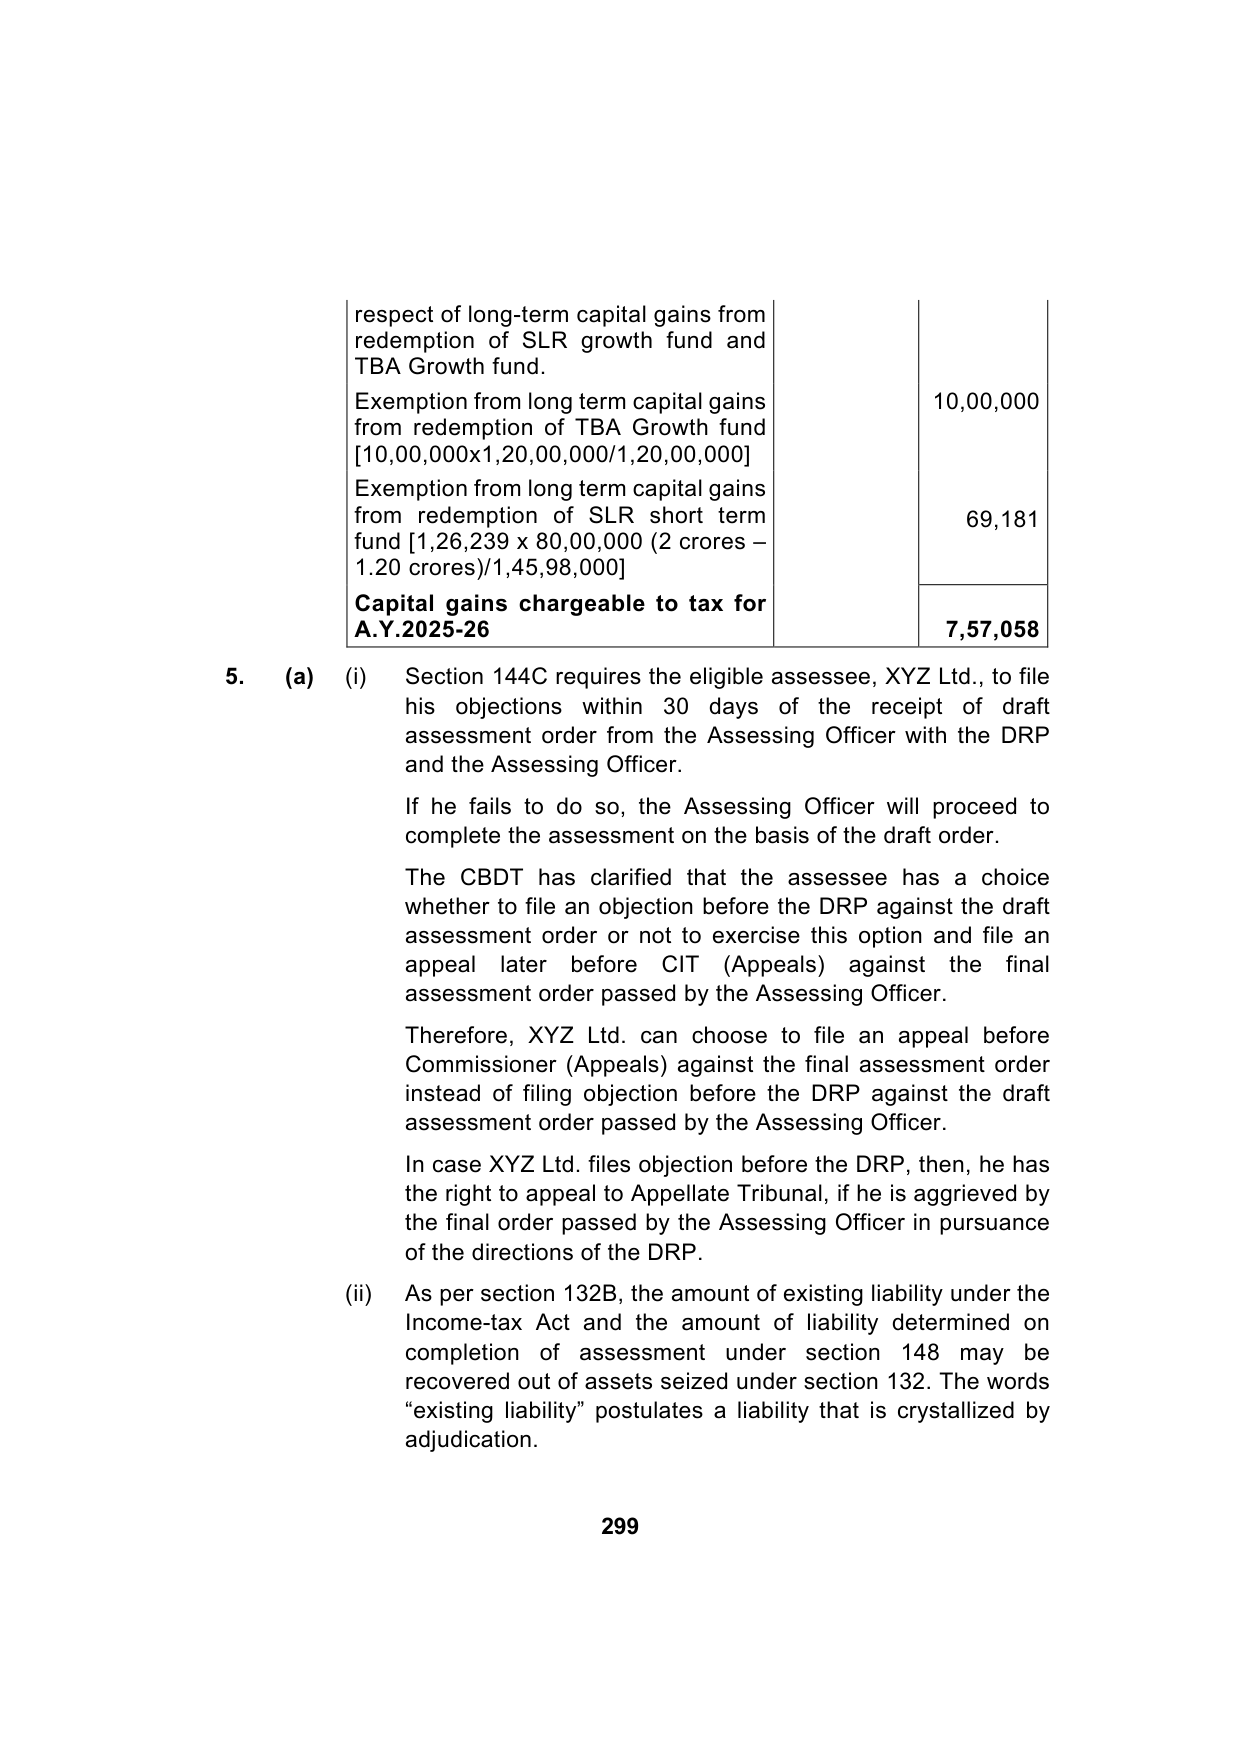
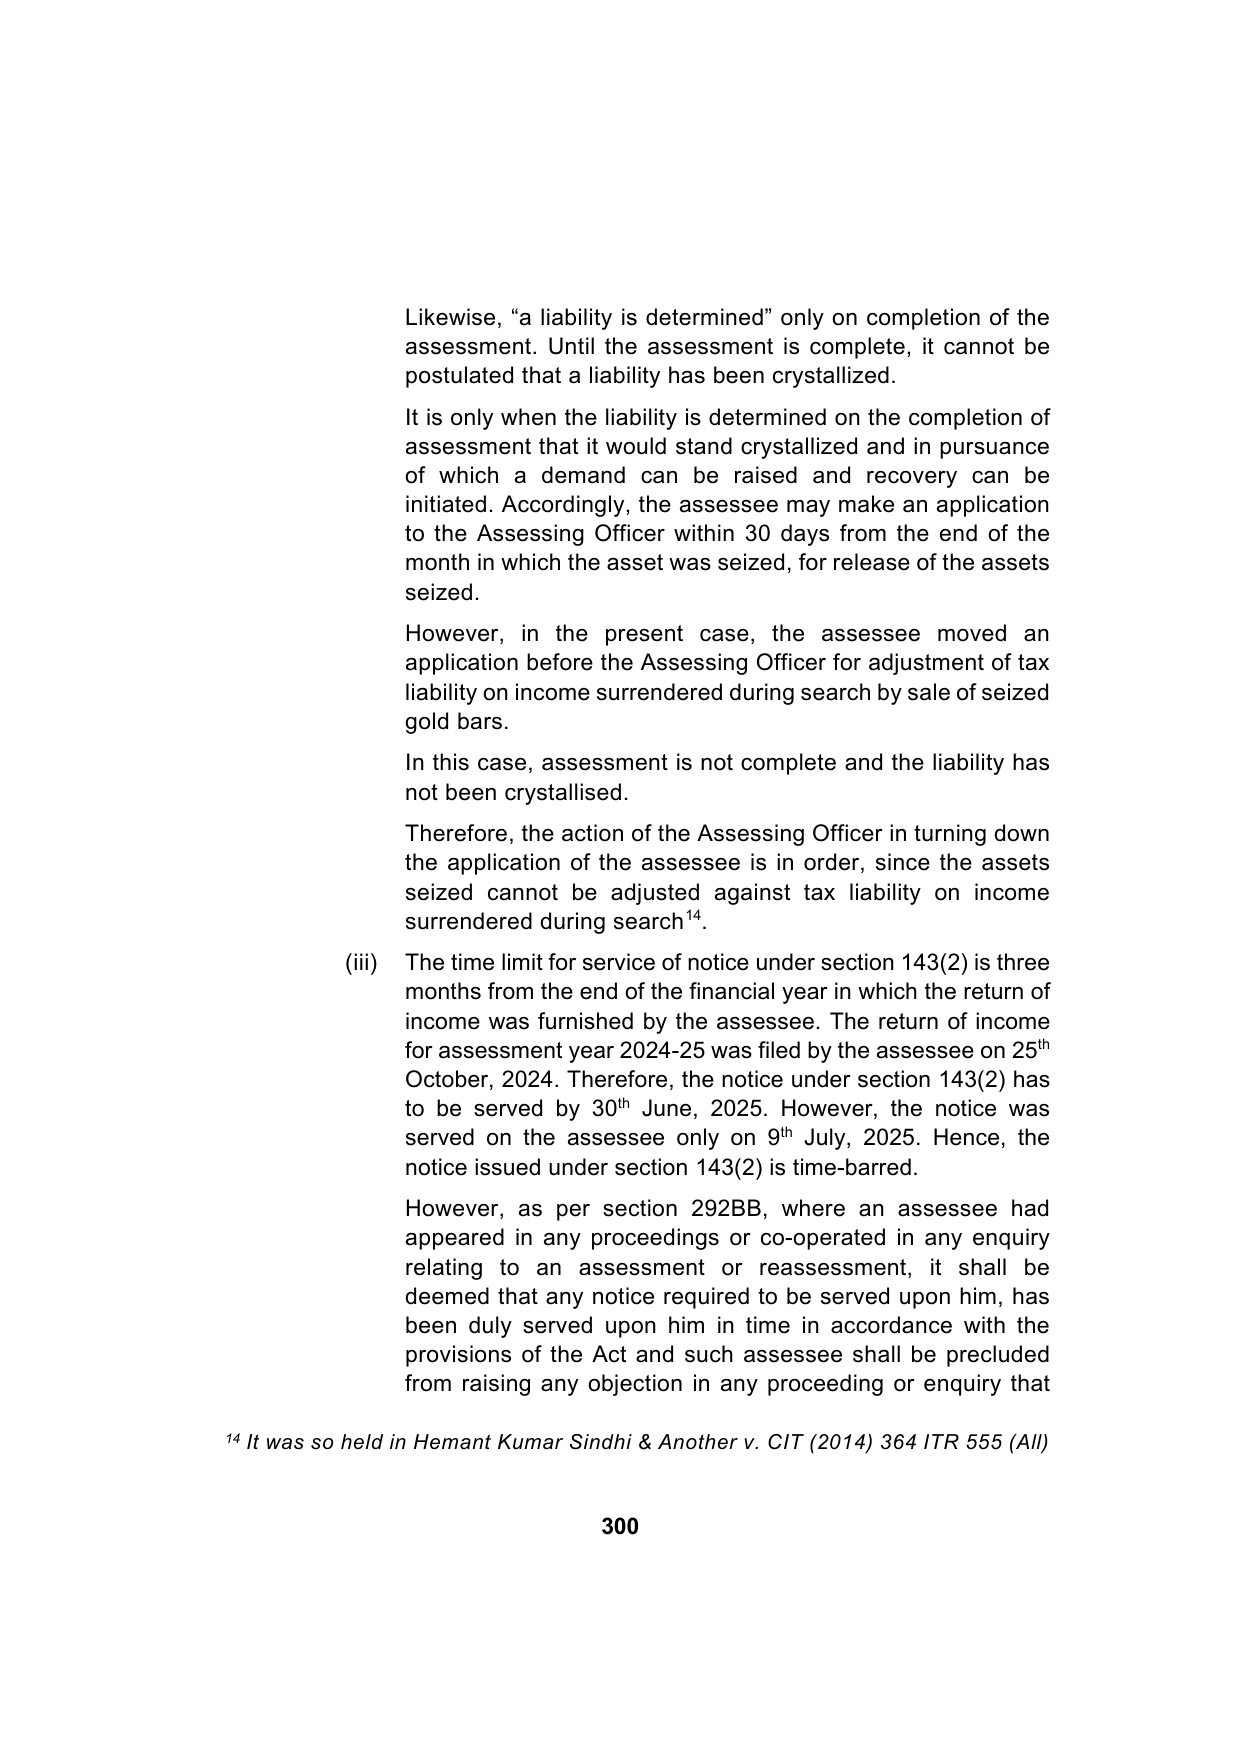
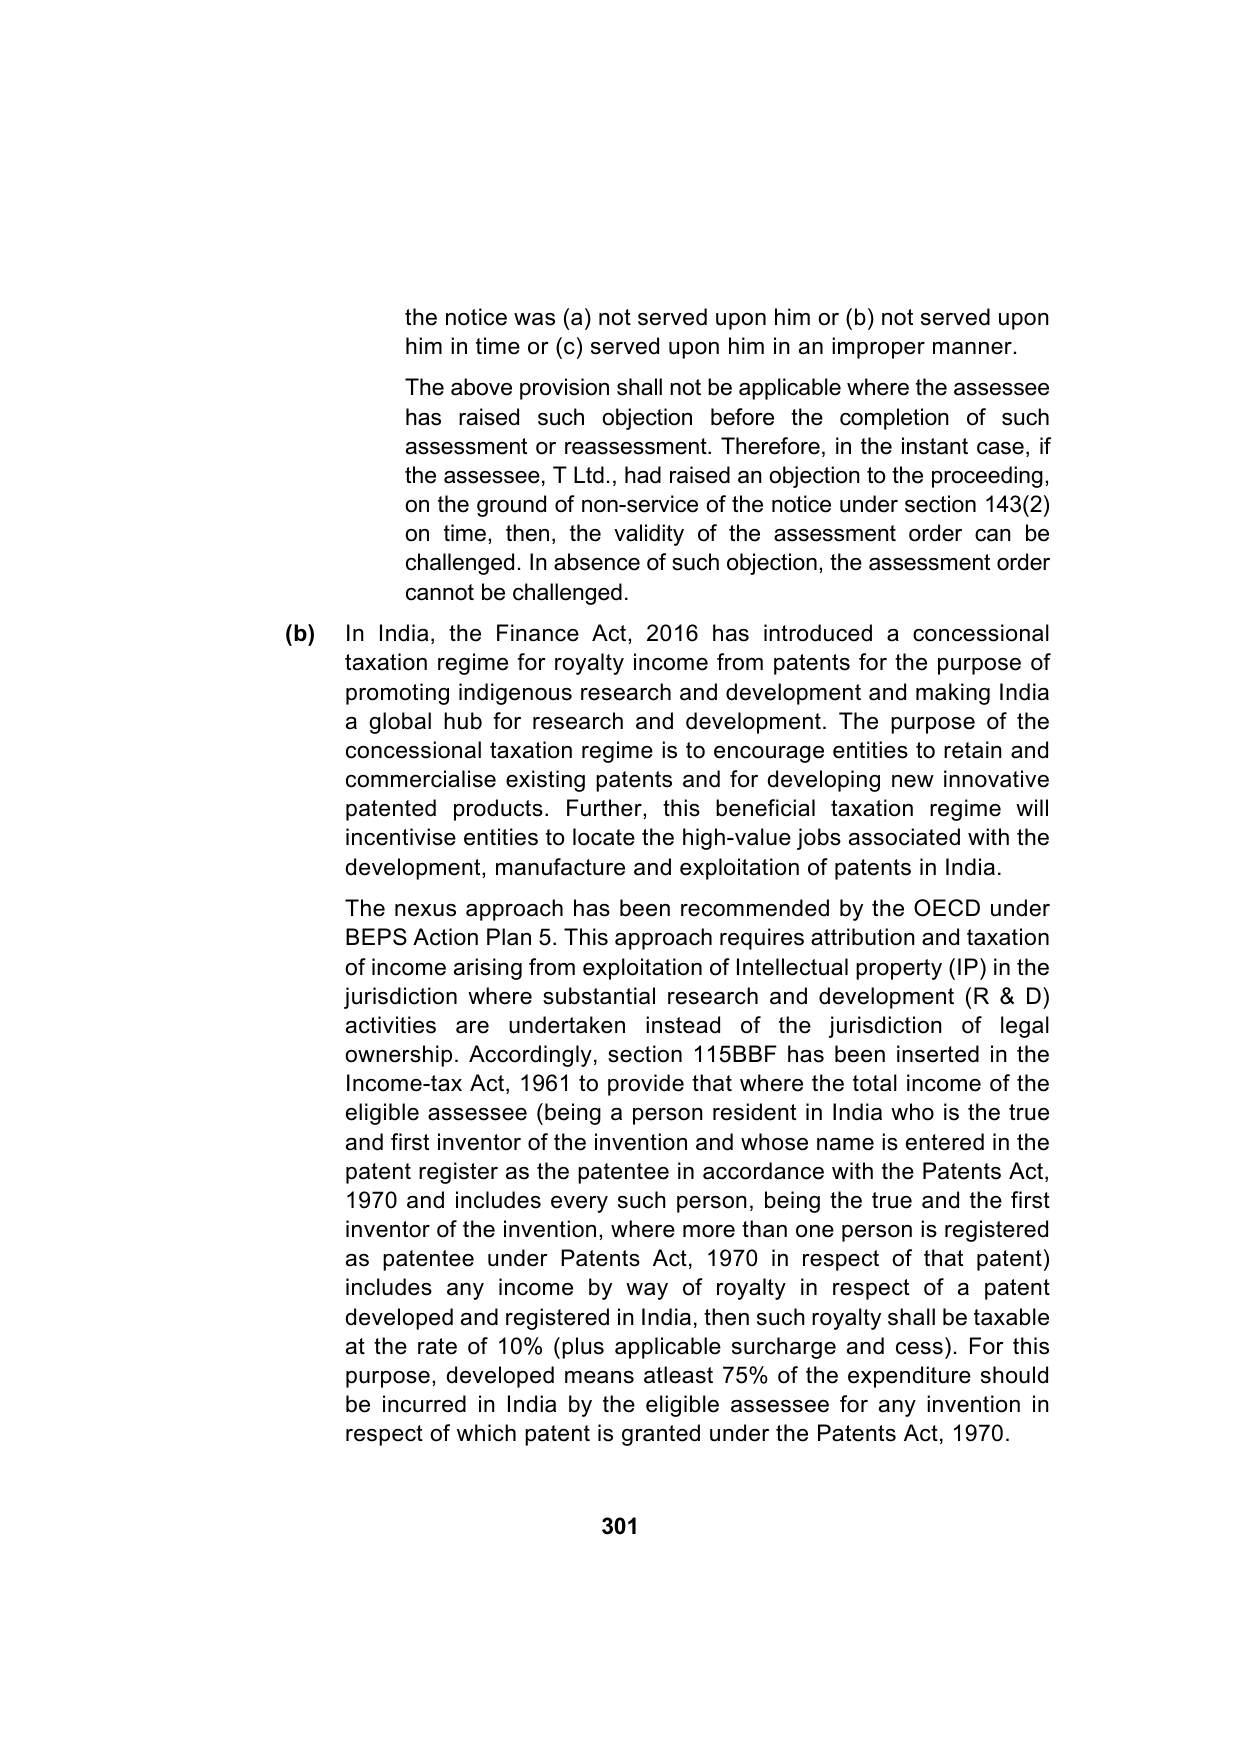
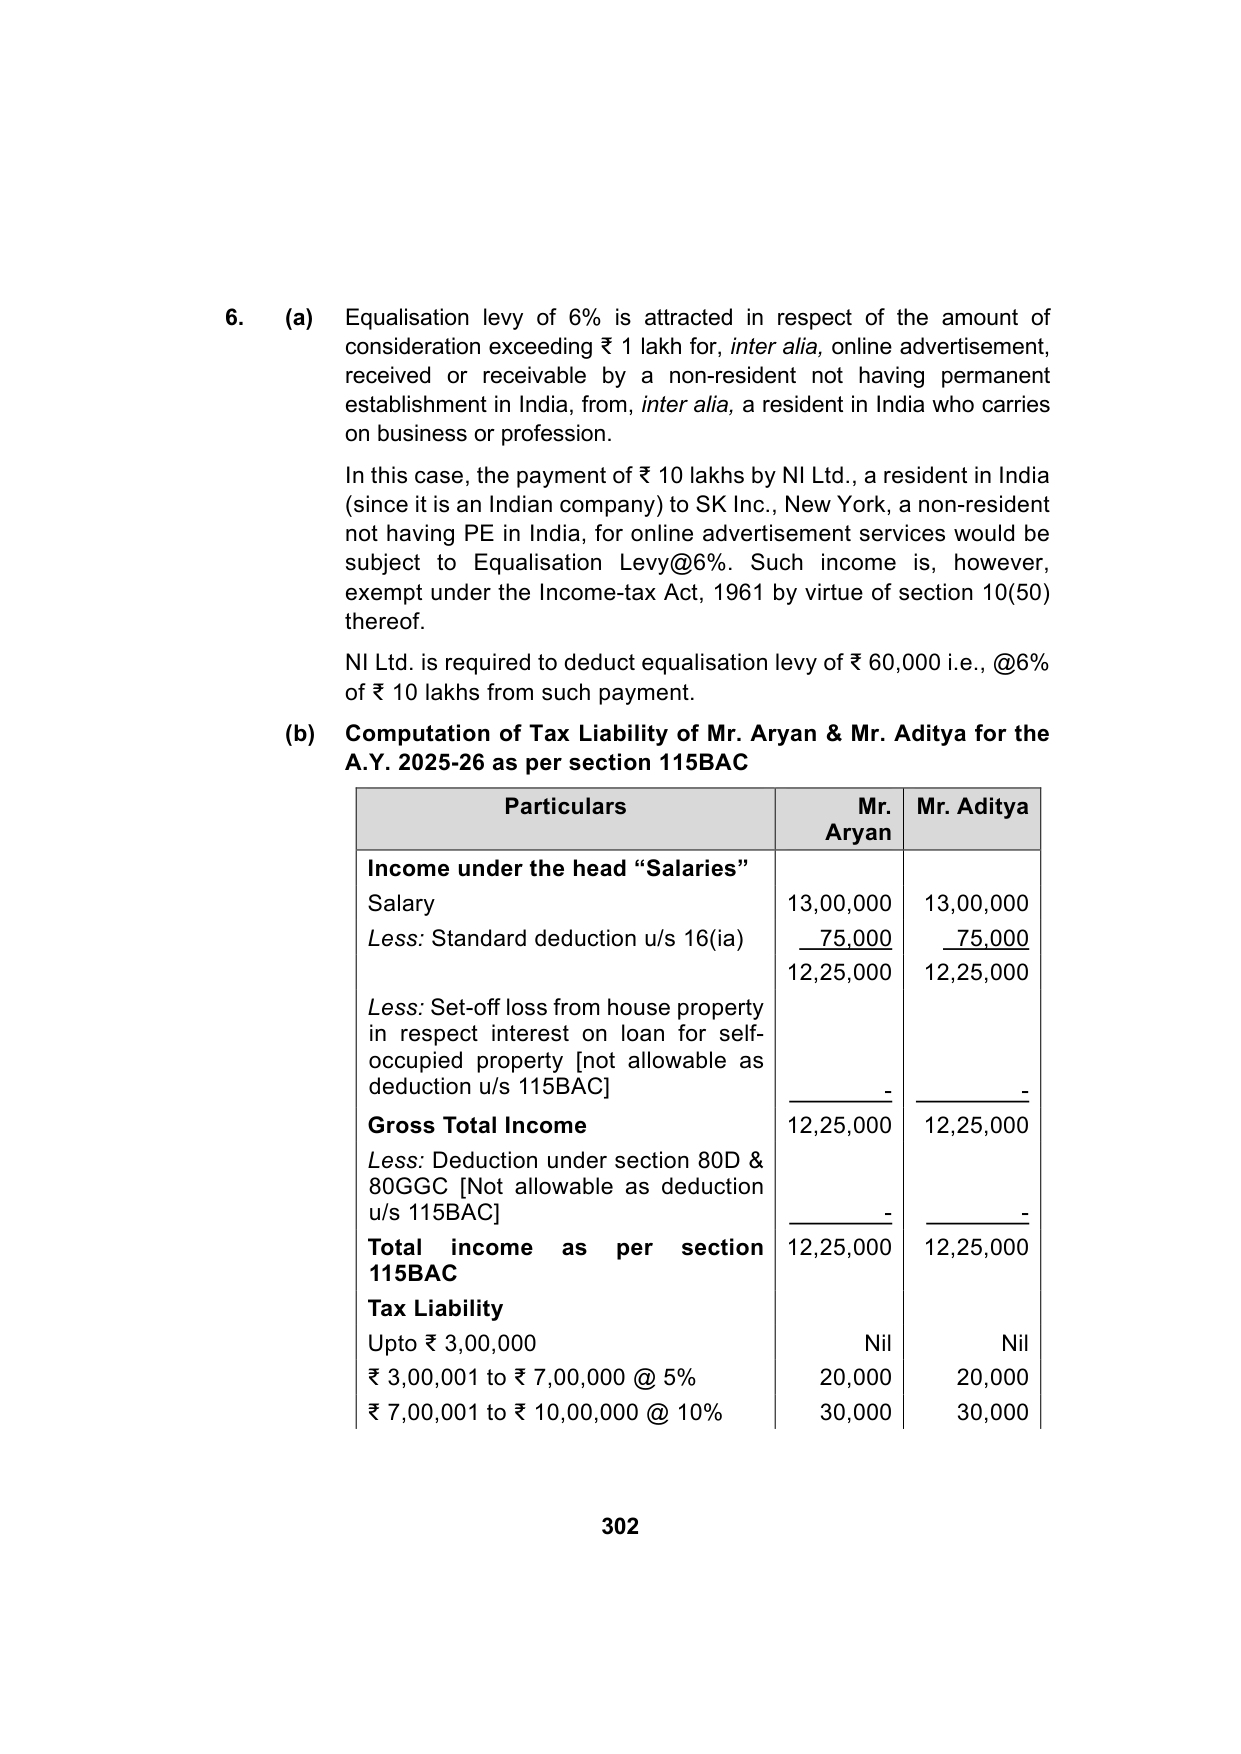
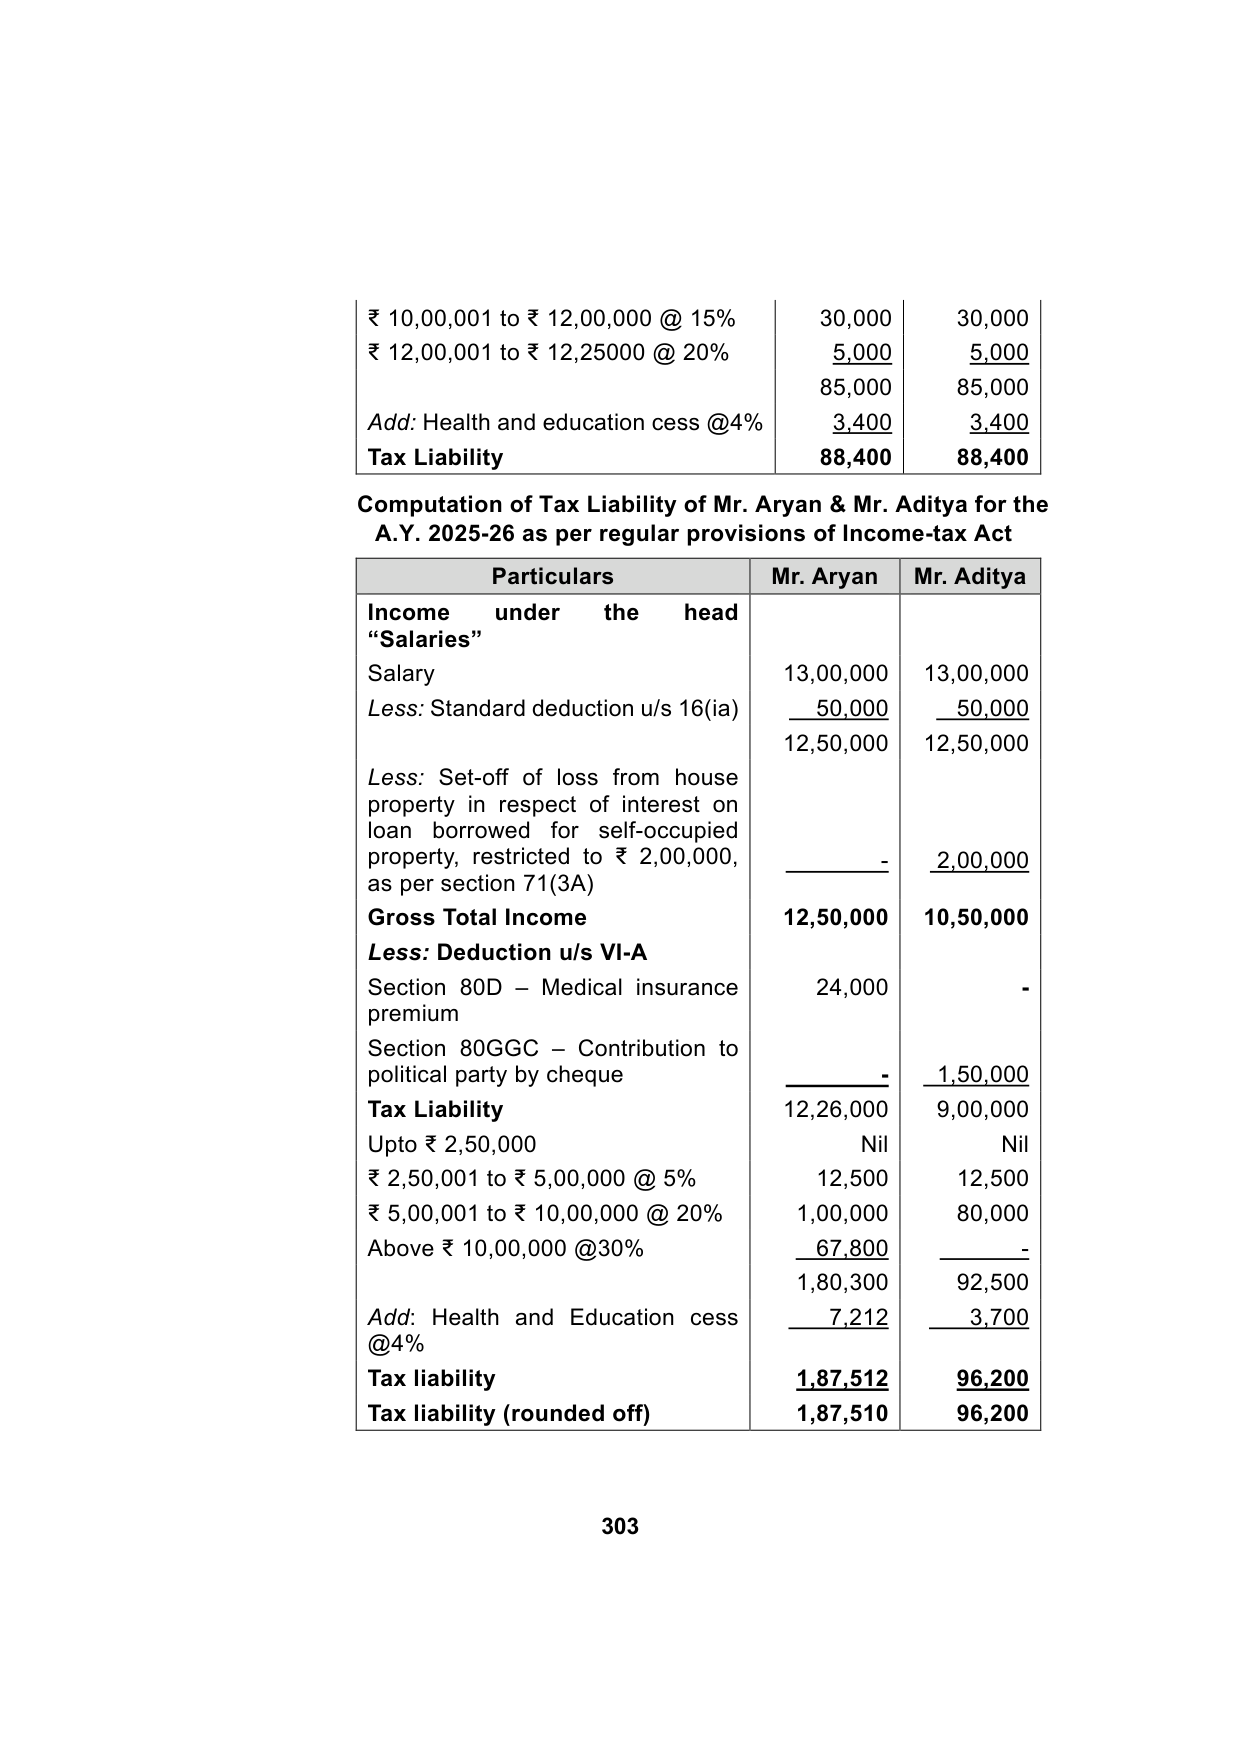
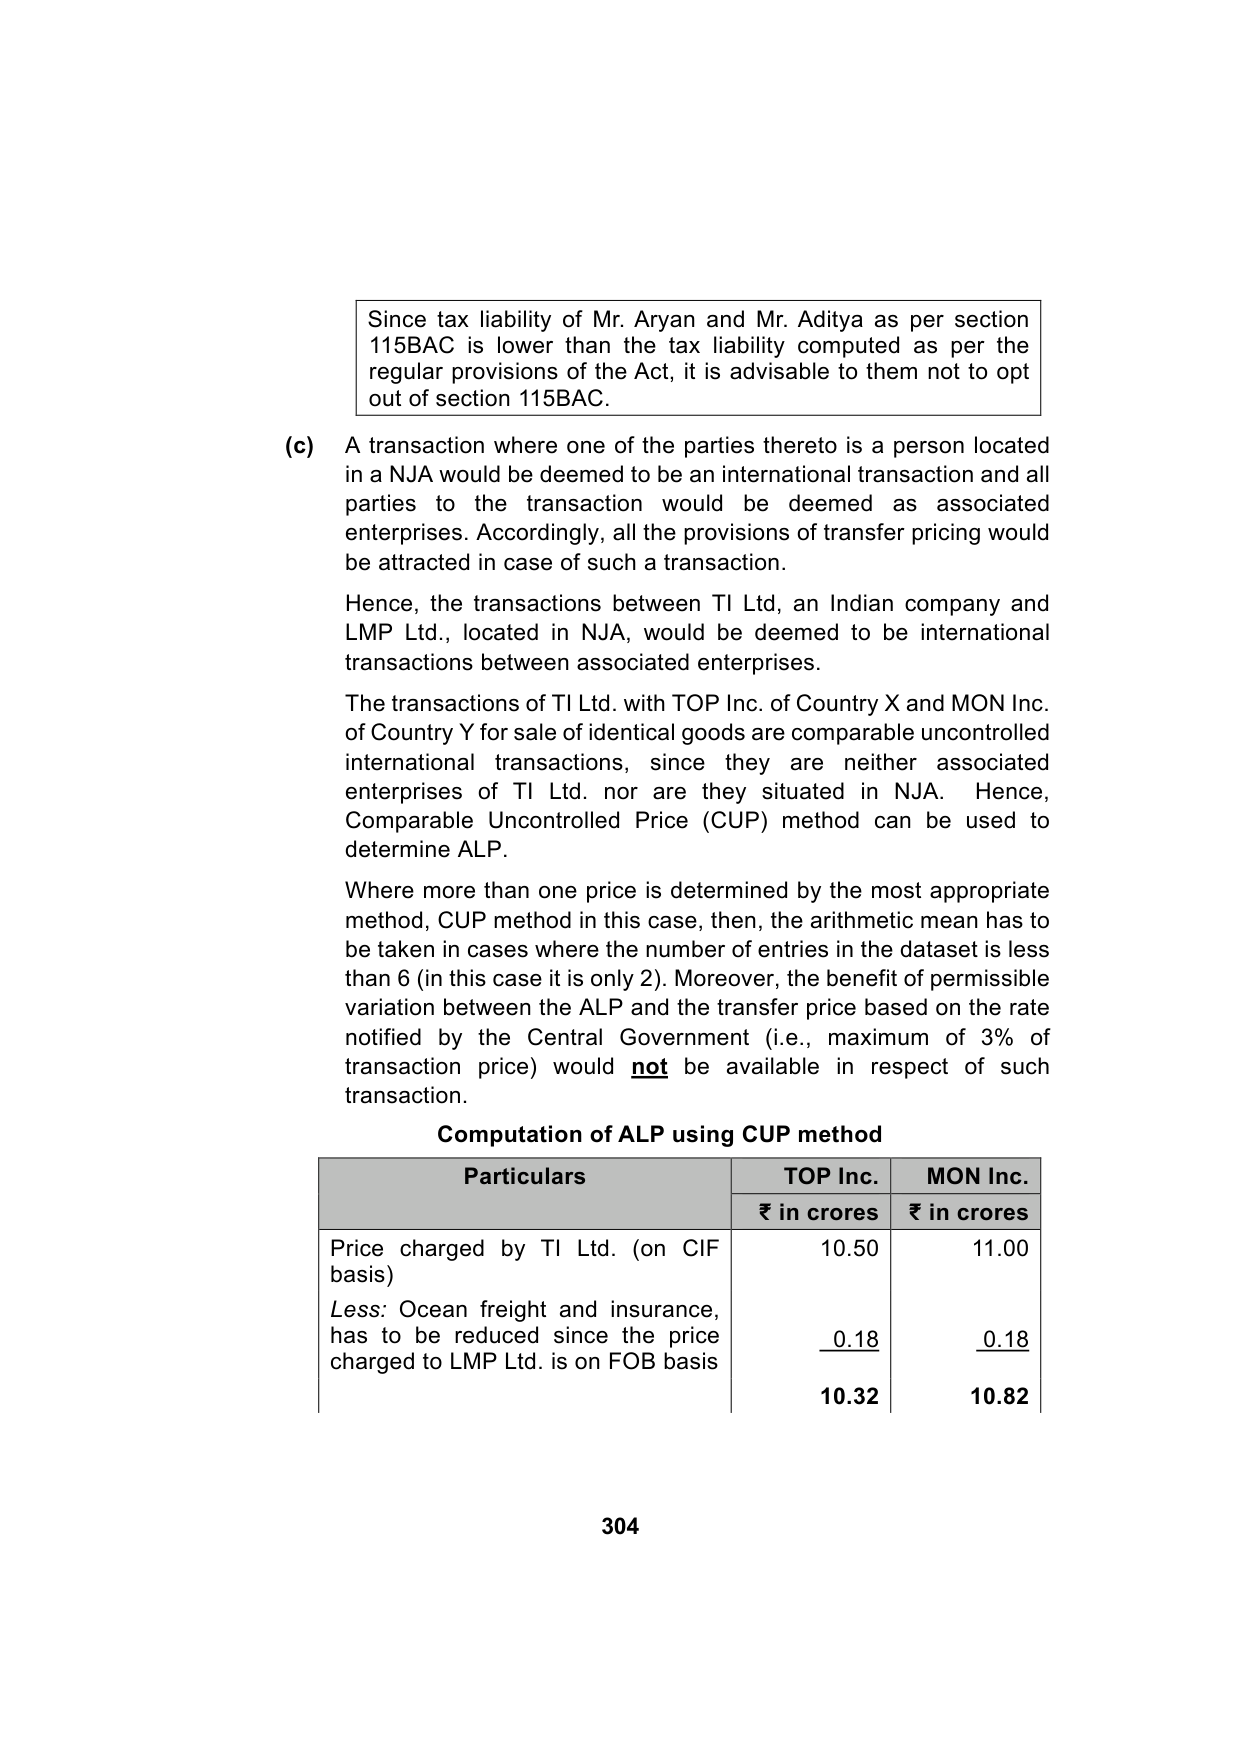
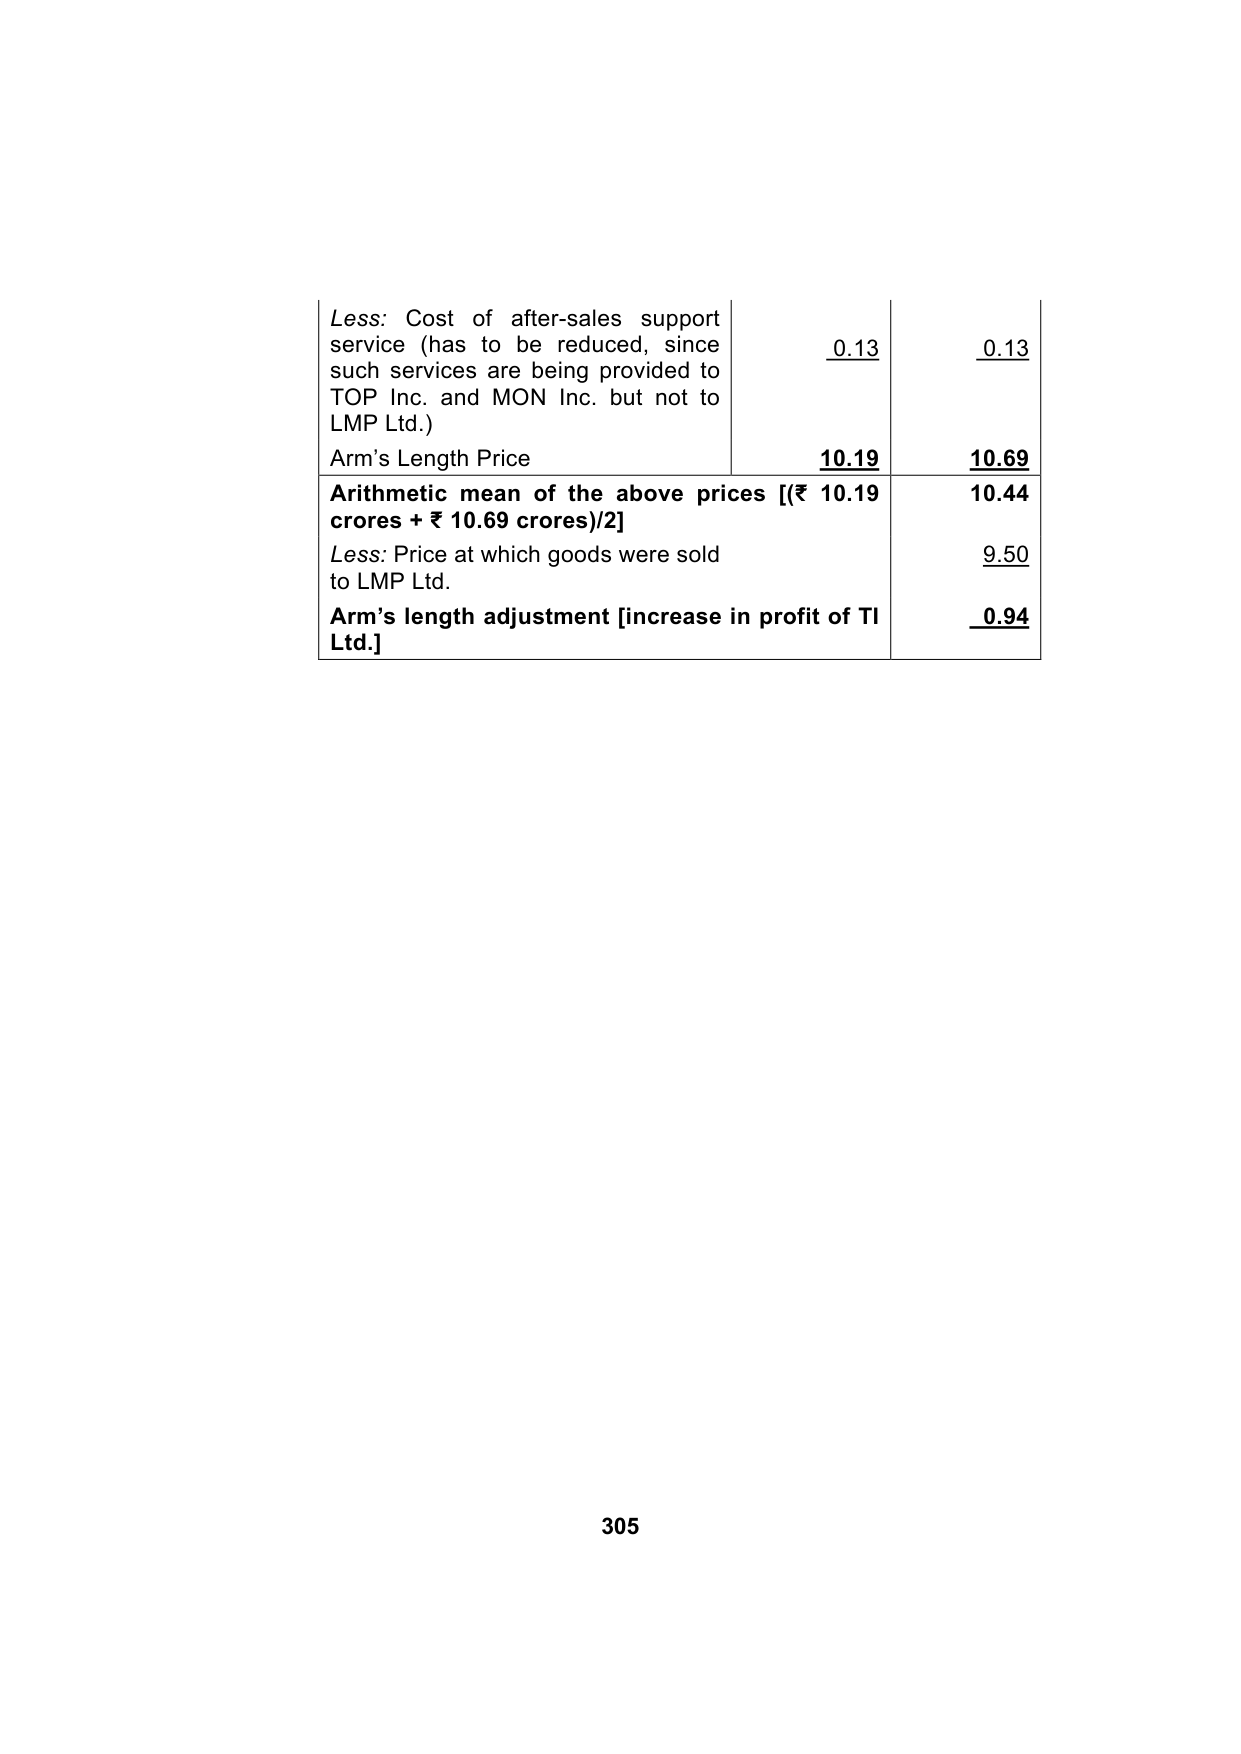
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 5 (100 marks)
Question
Answer
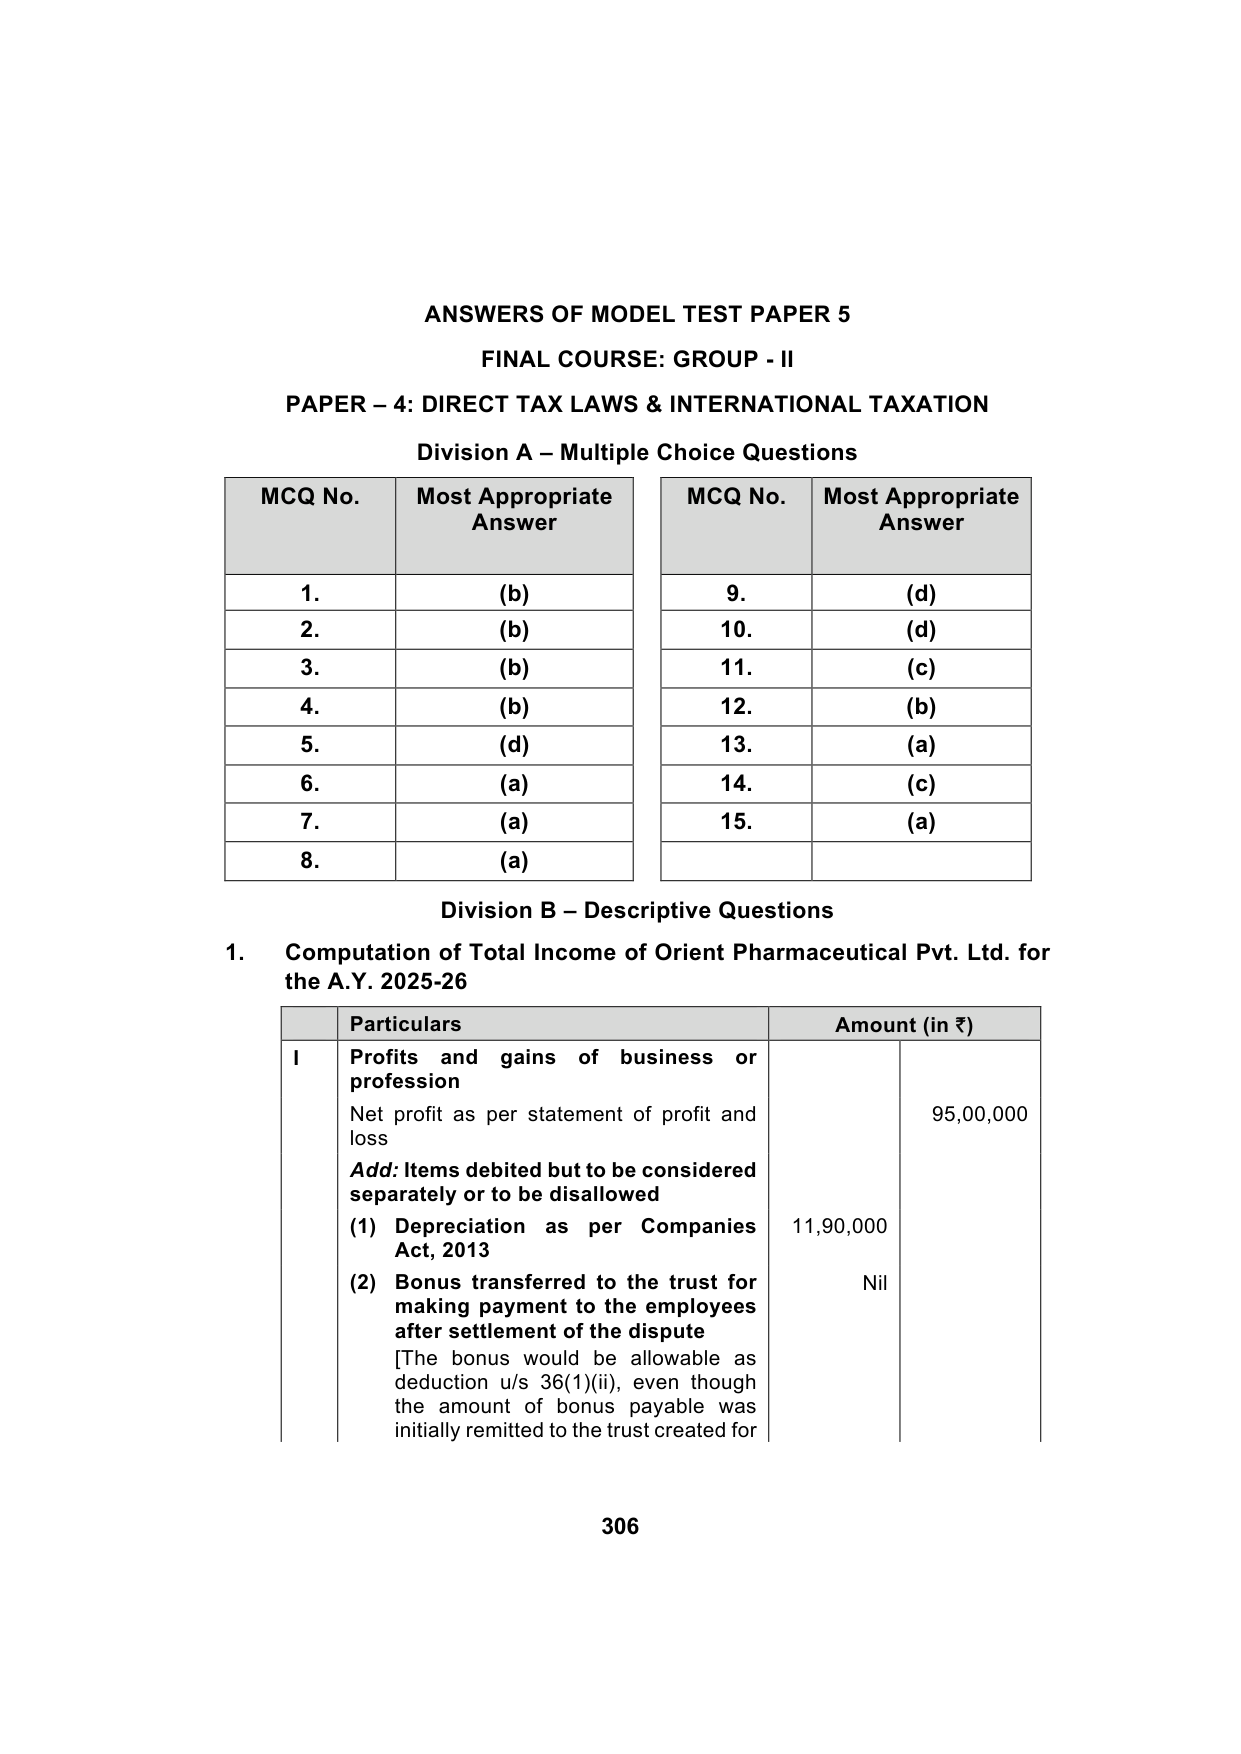
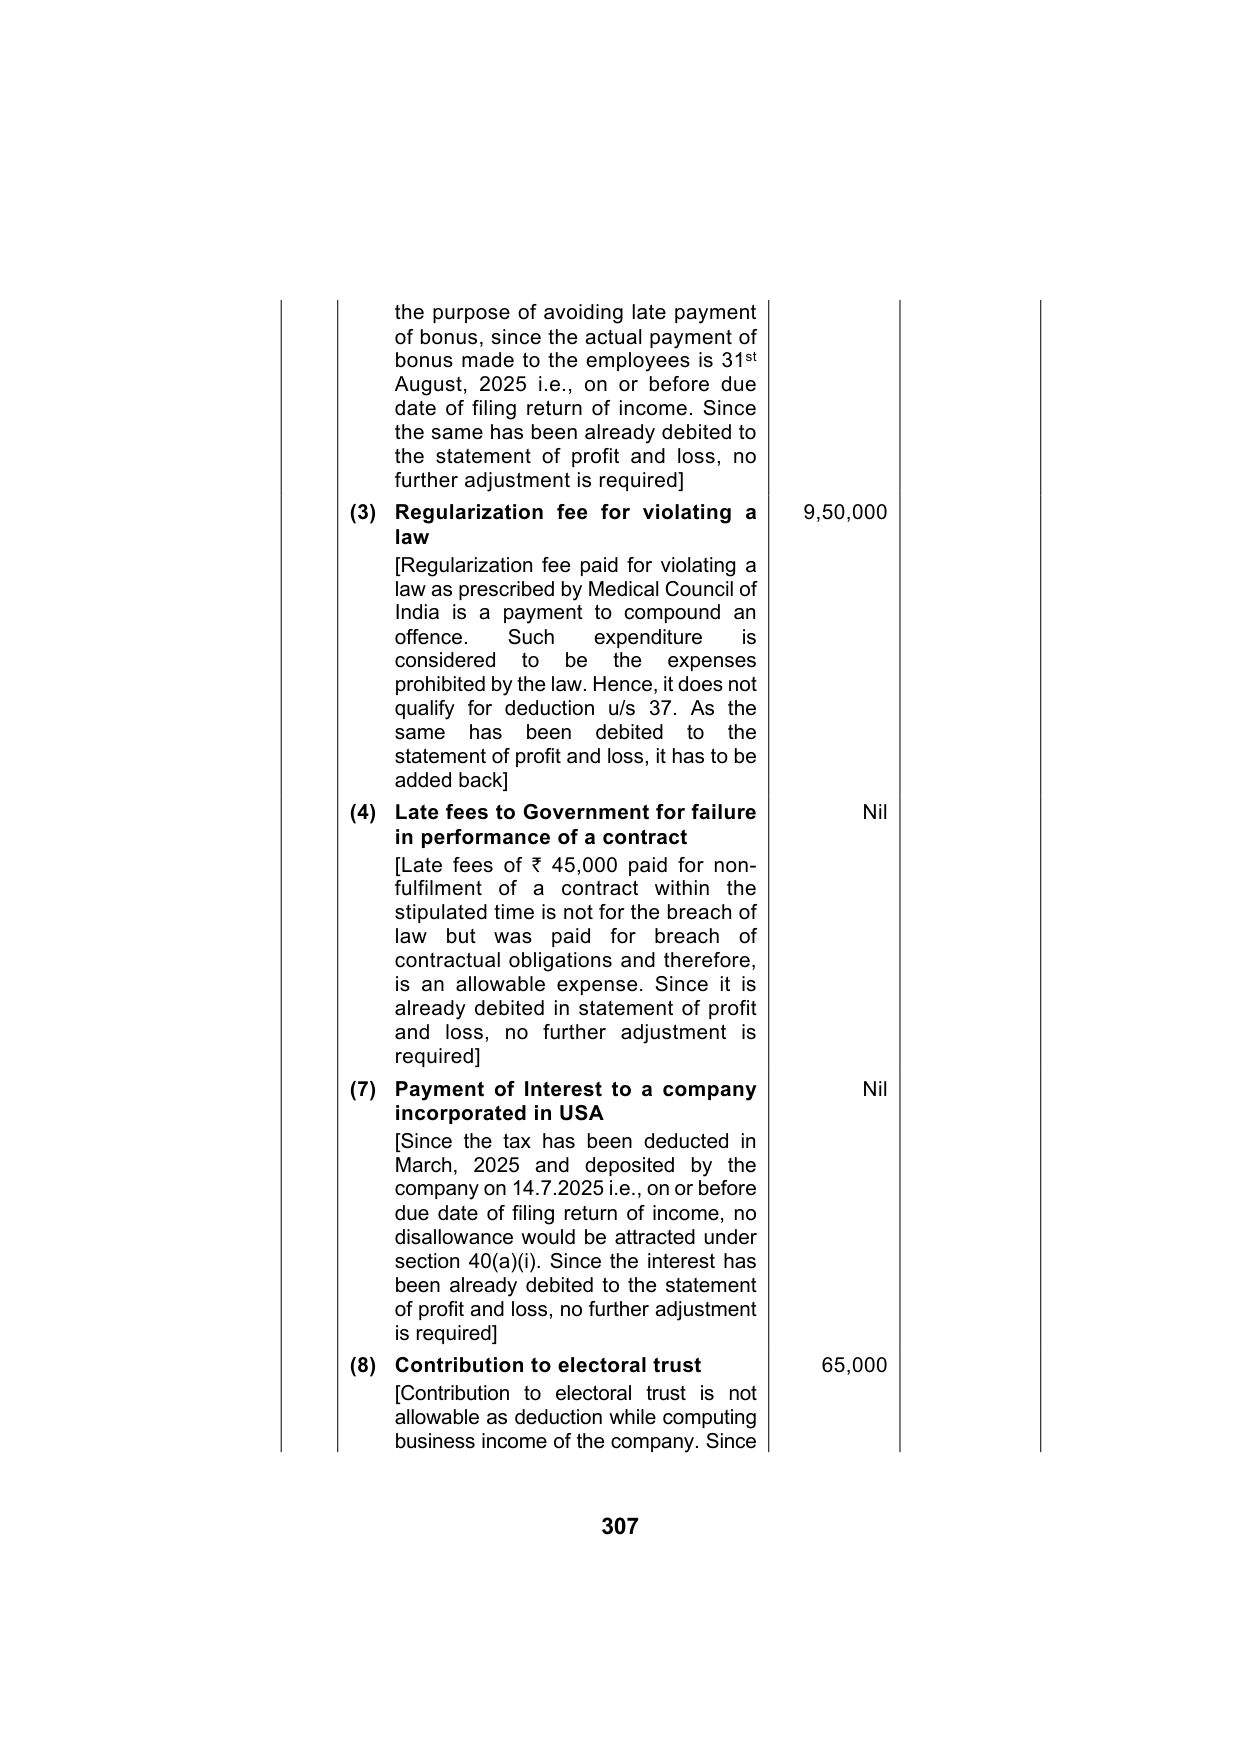
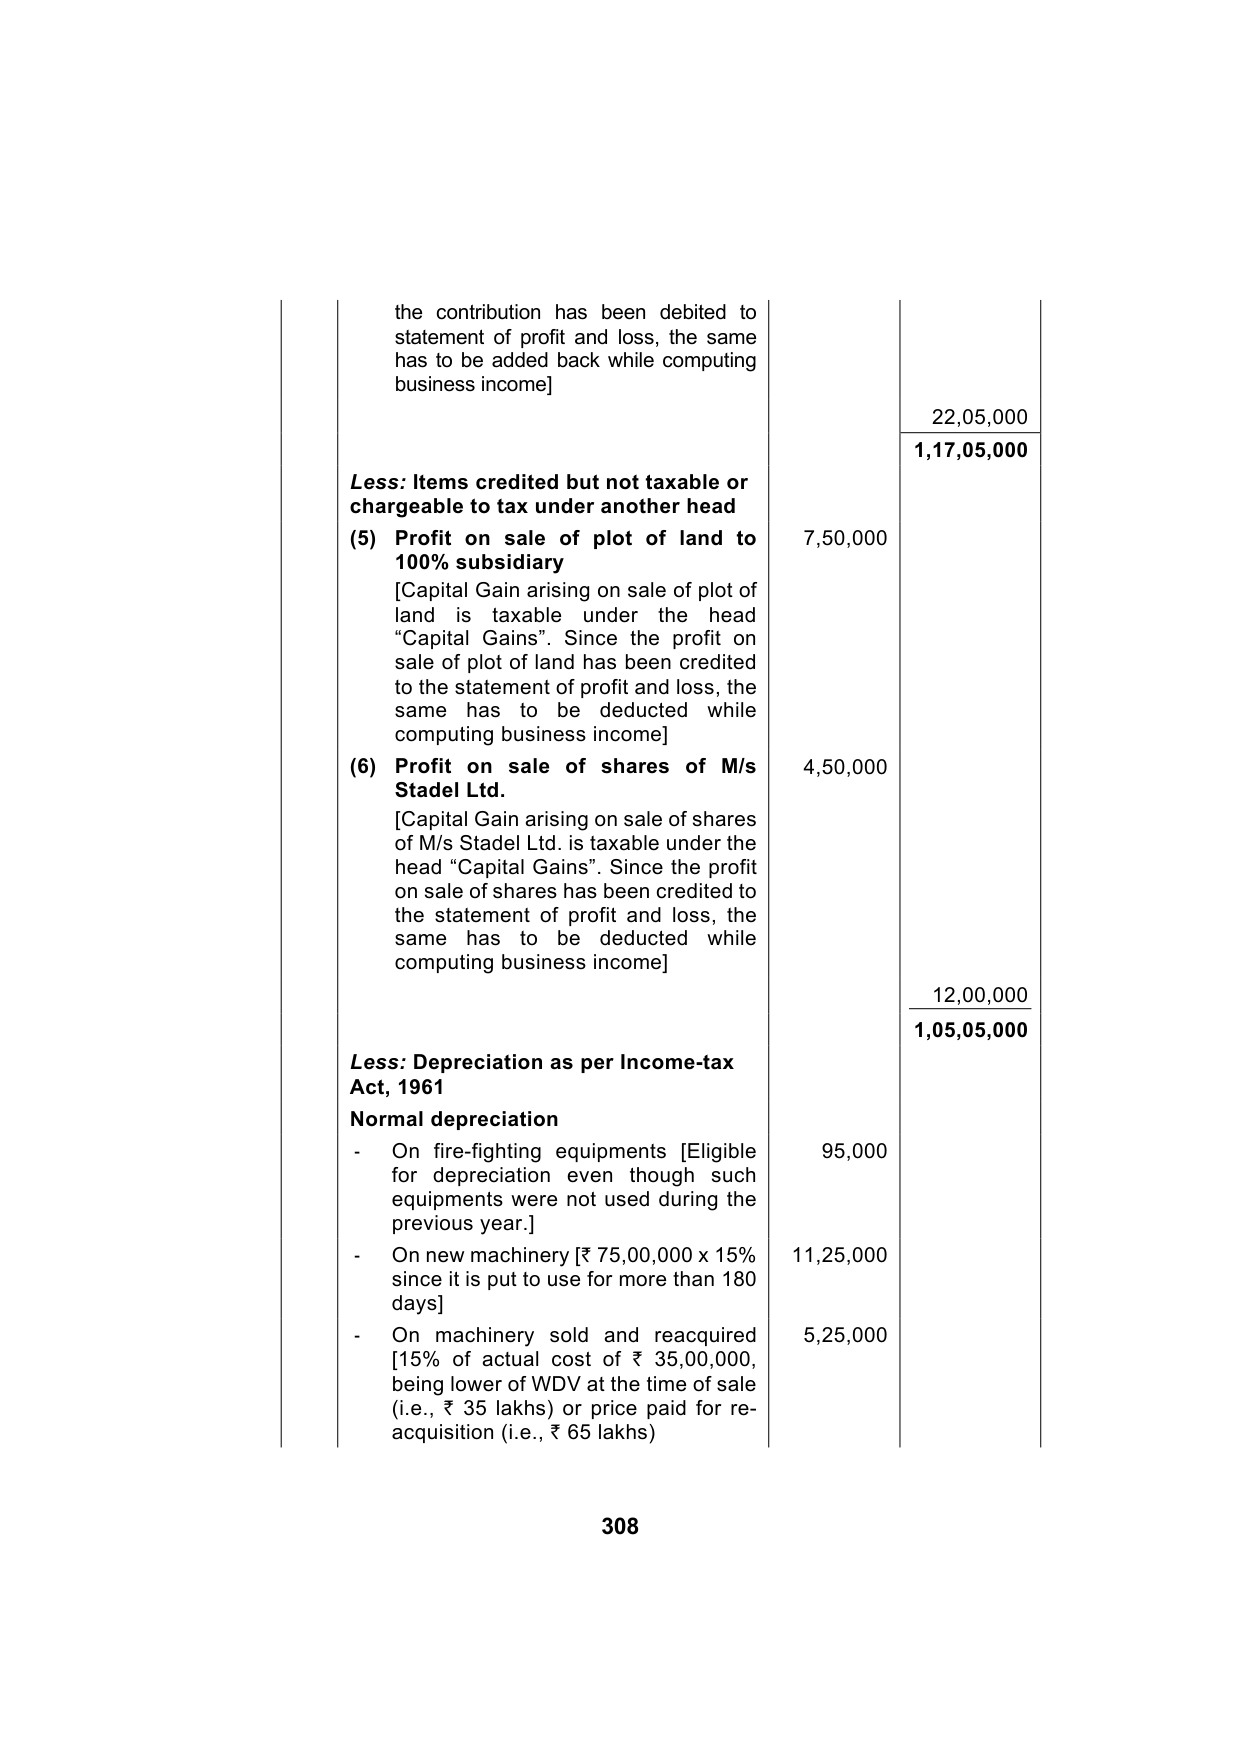
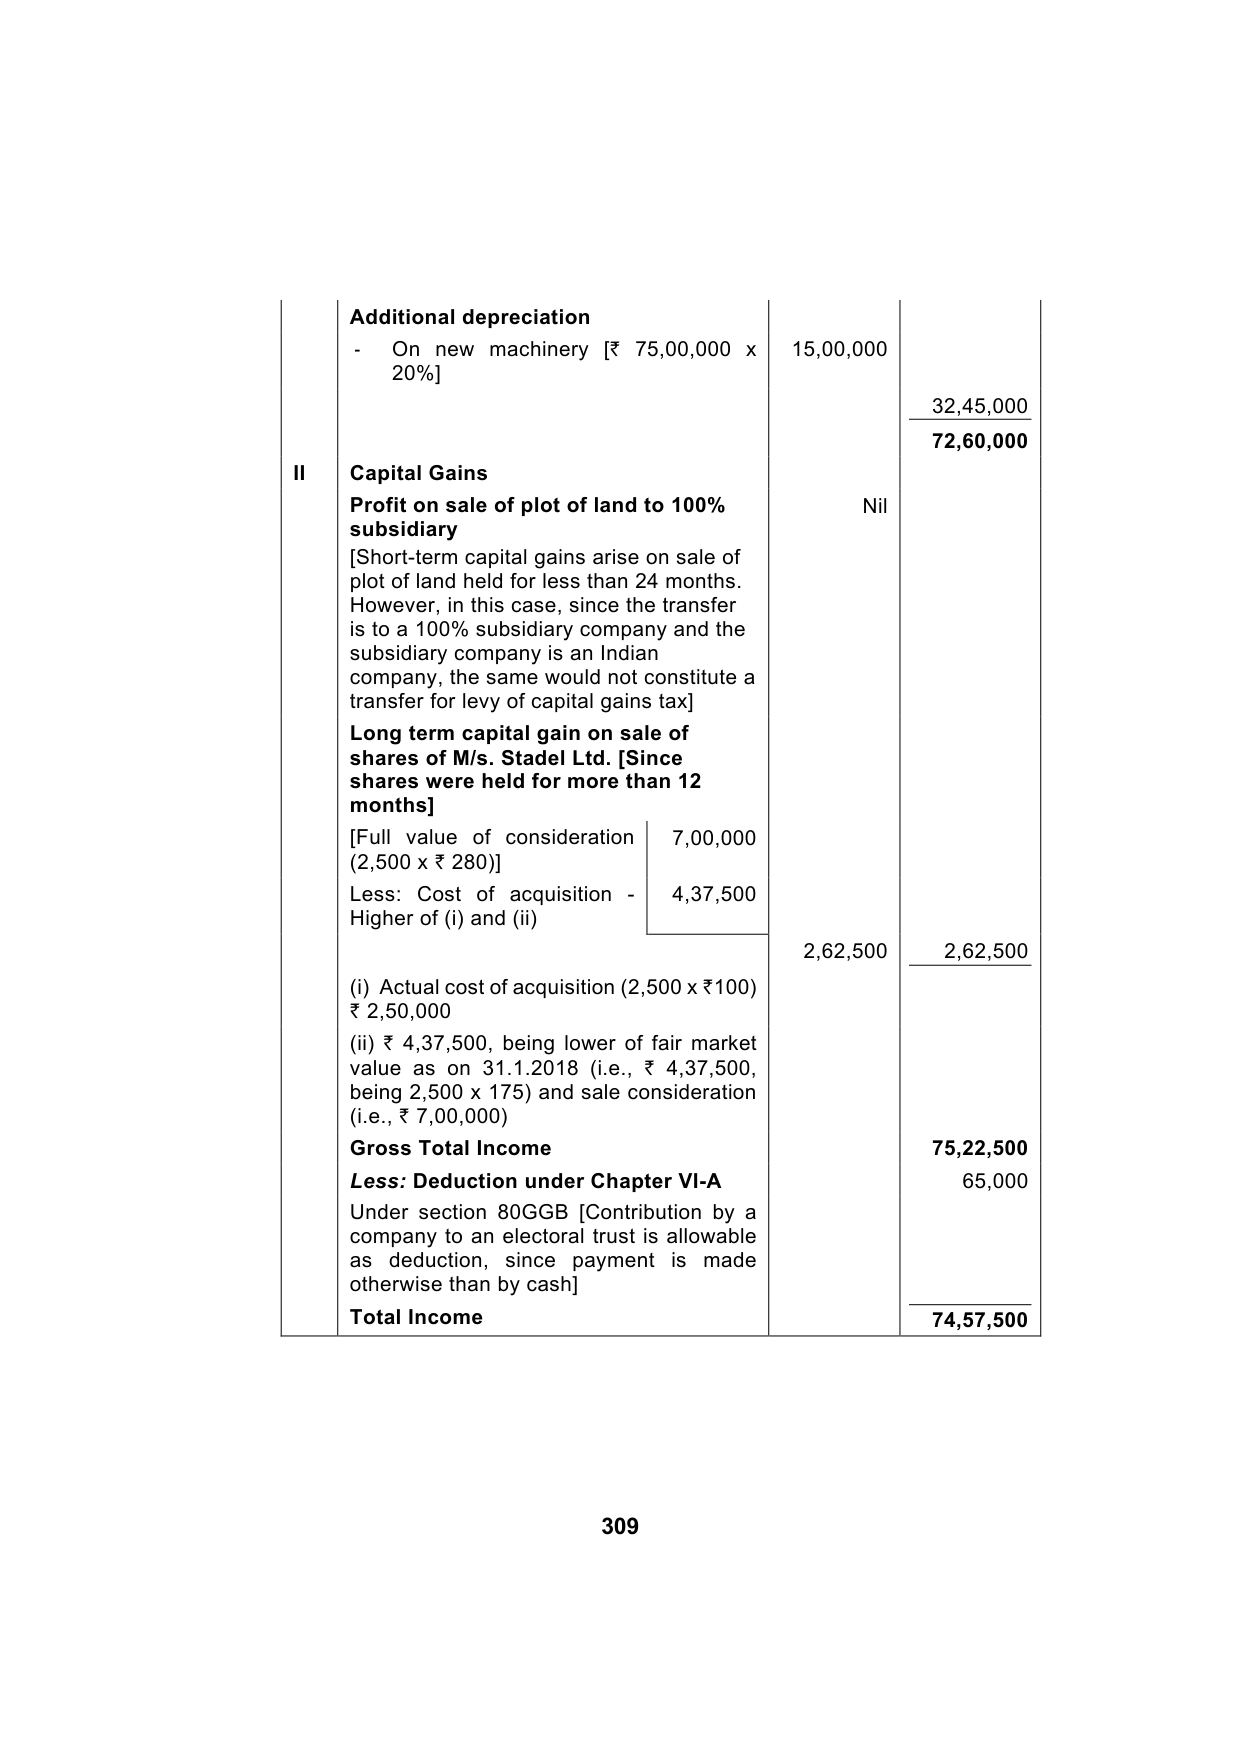
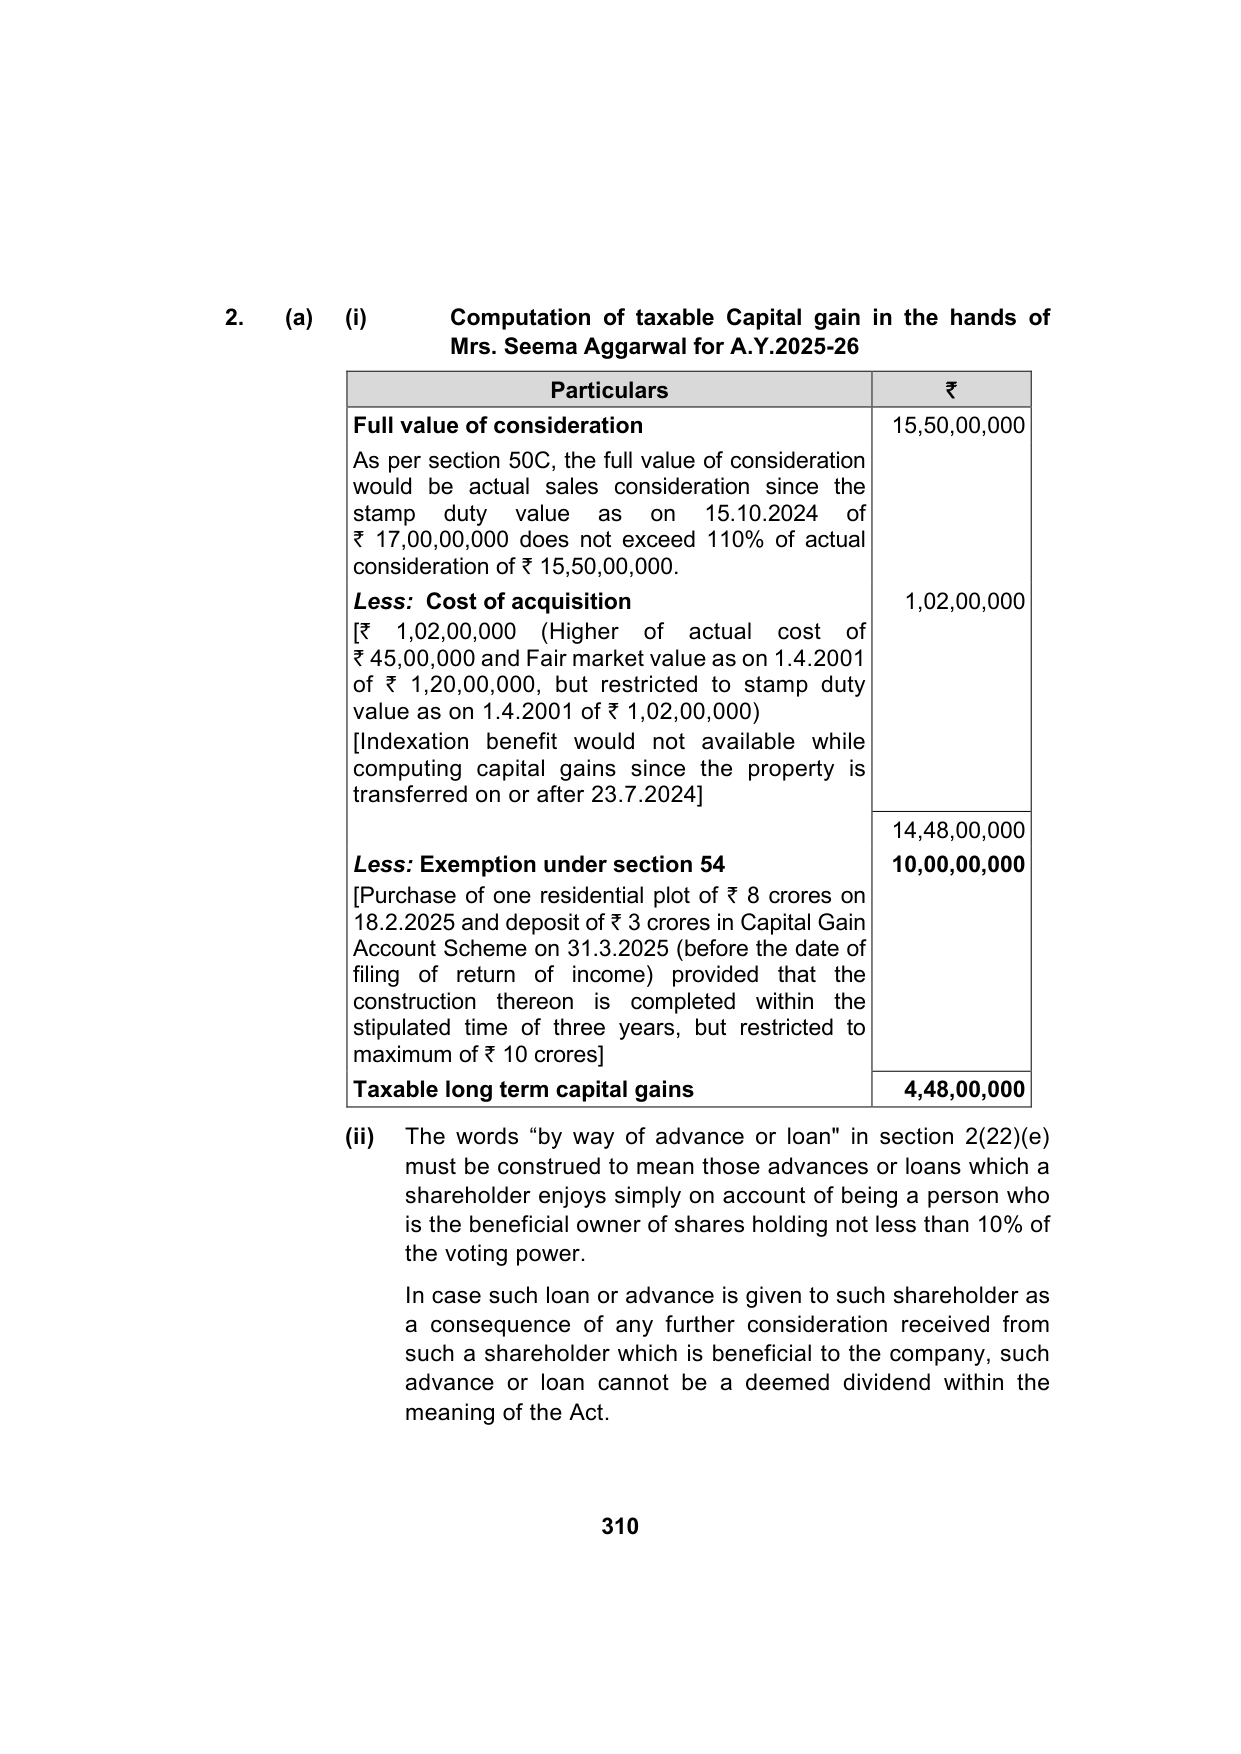
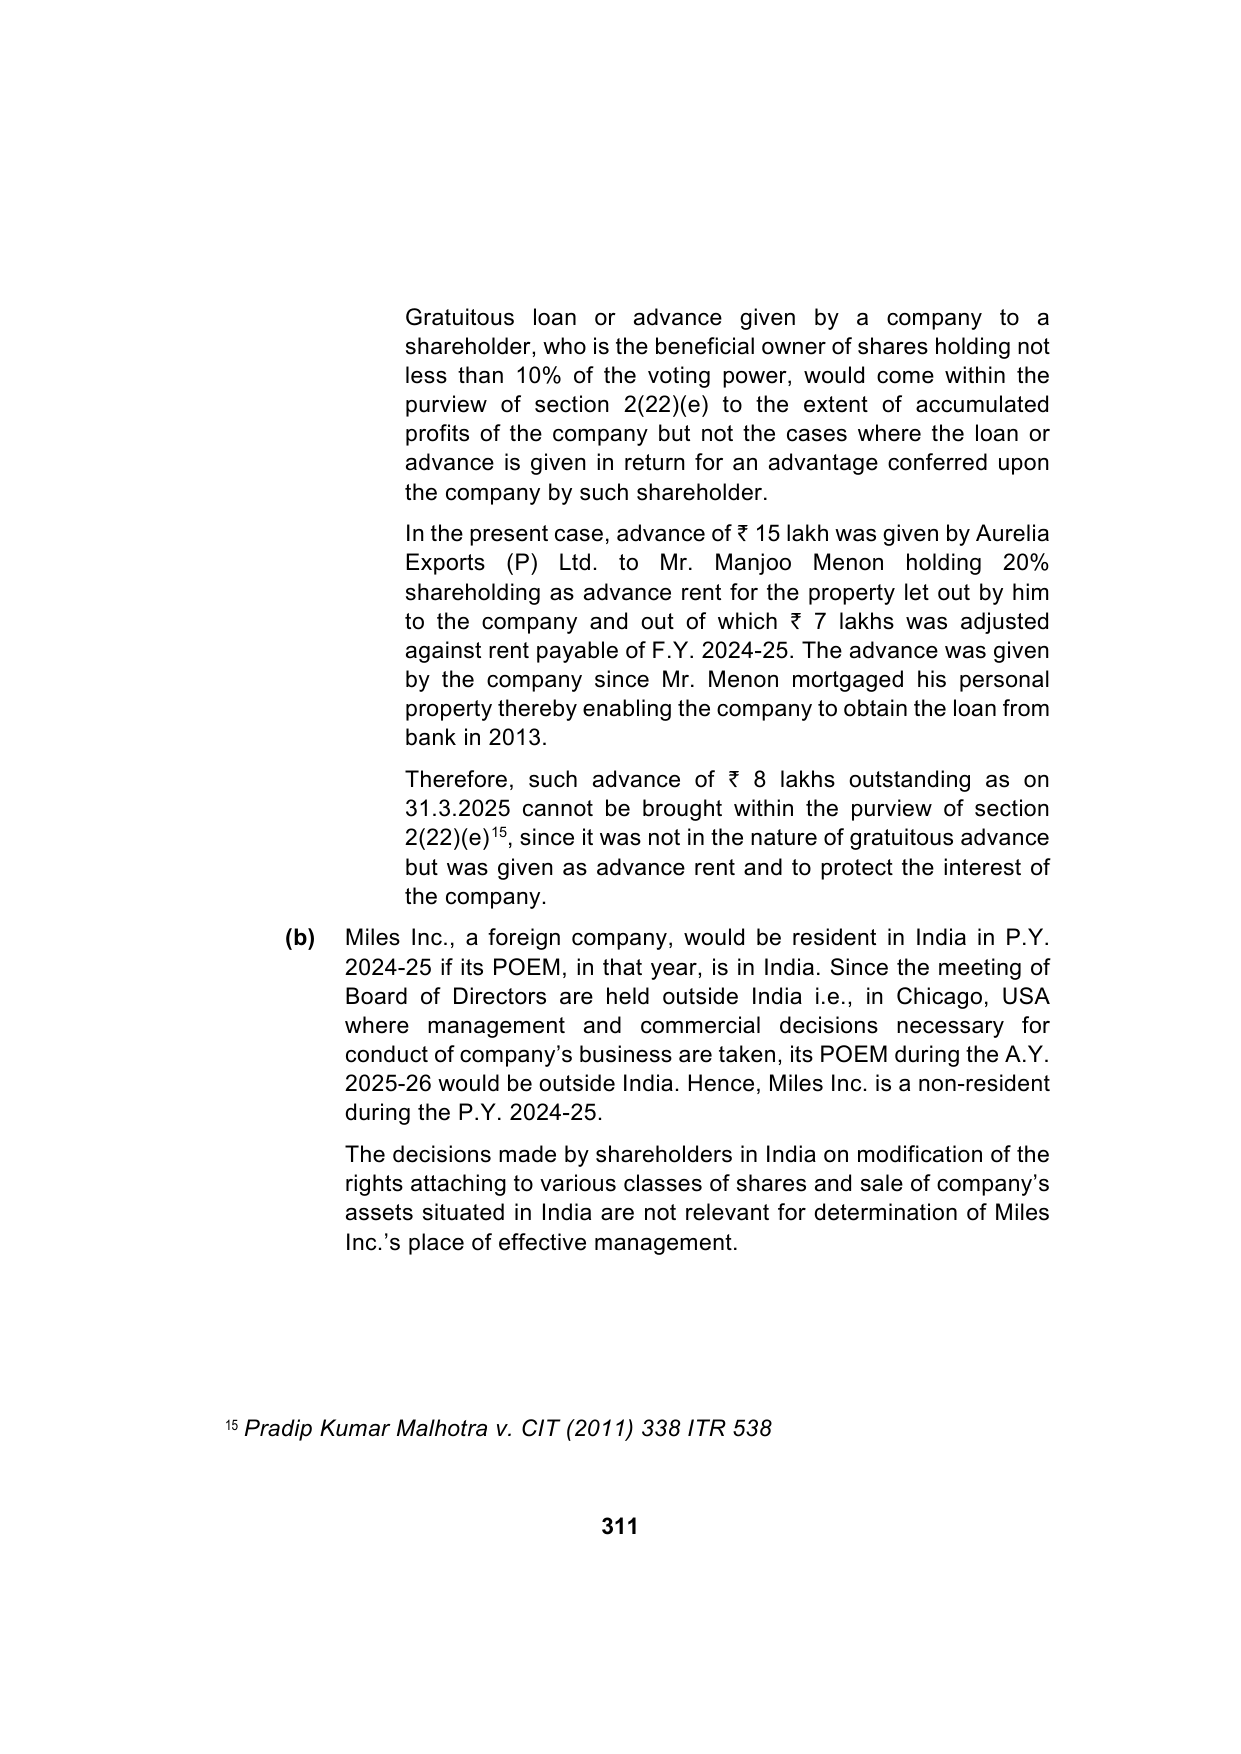
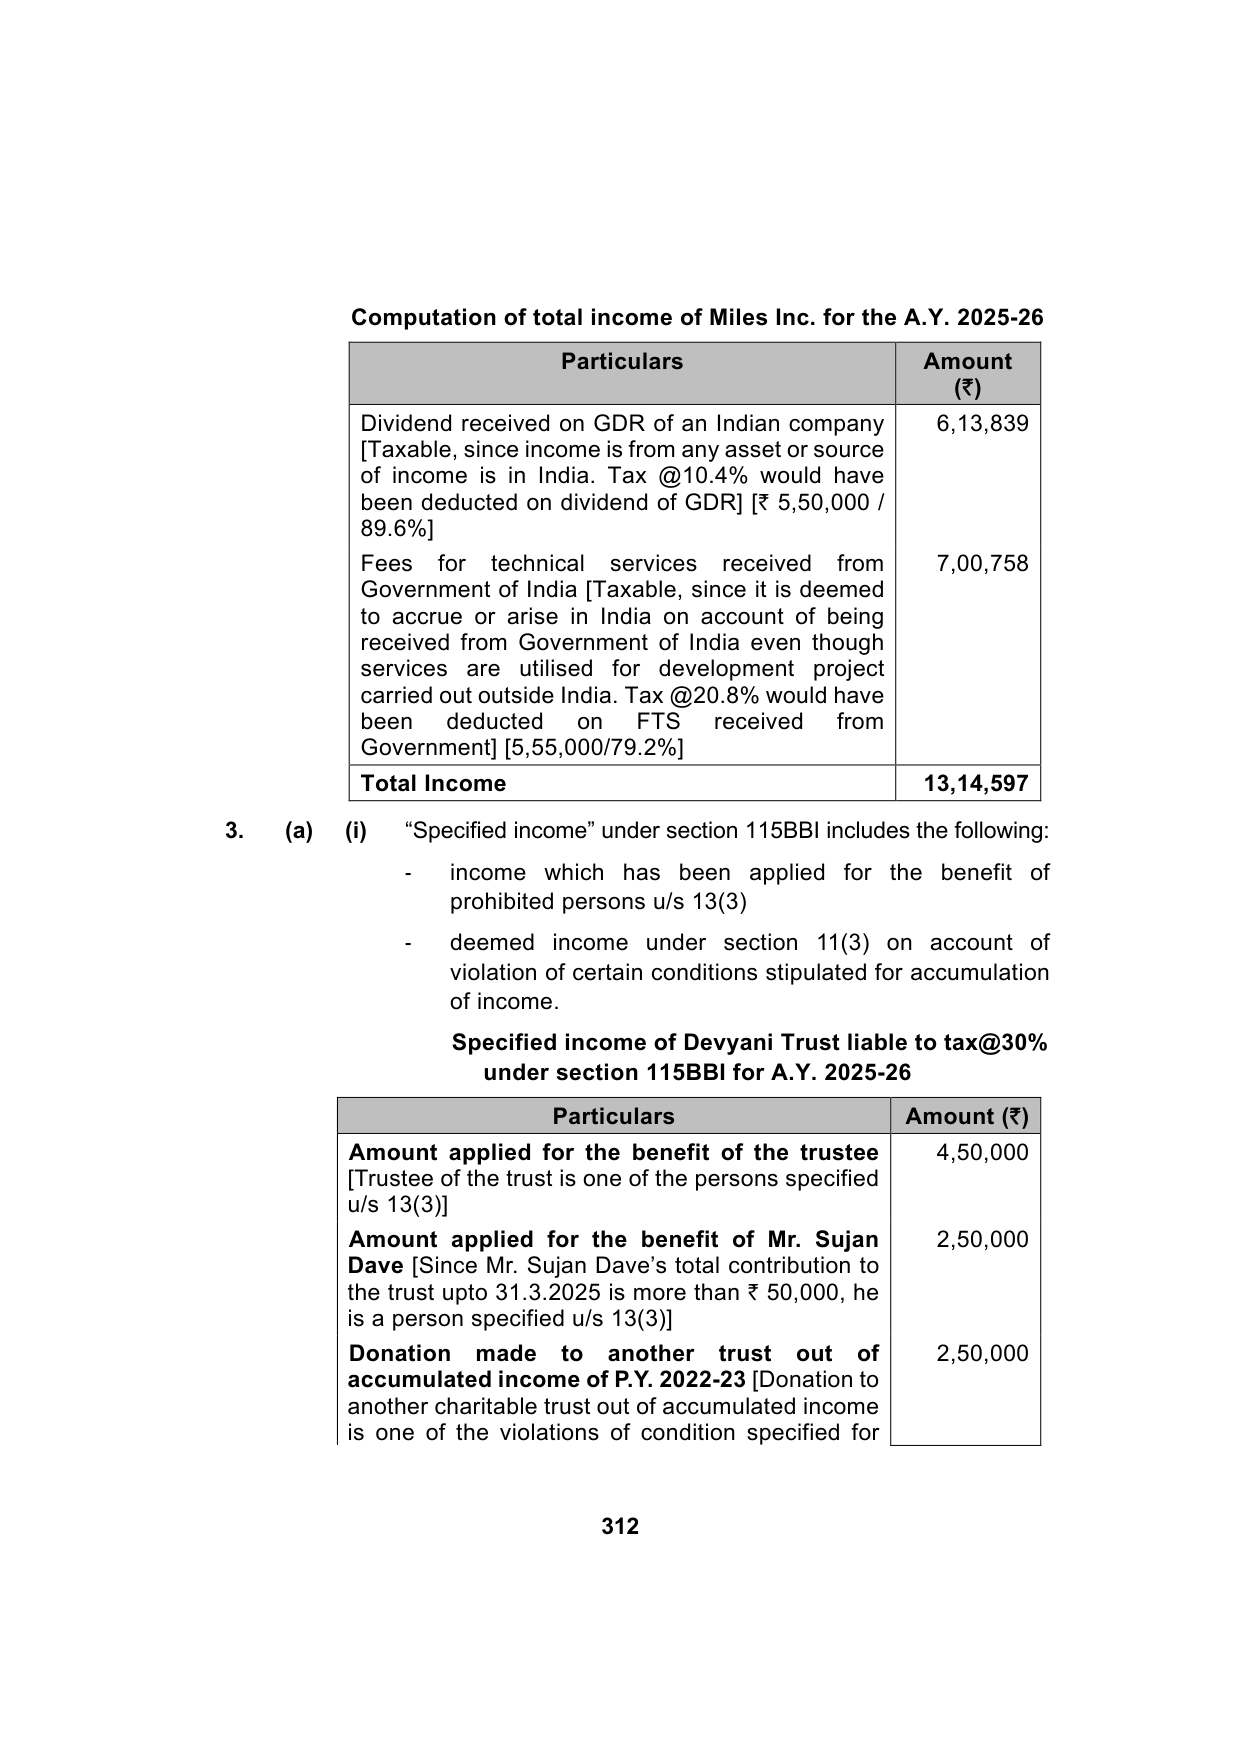
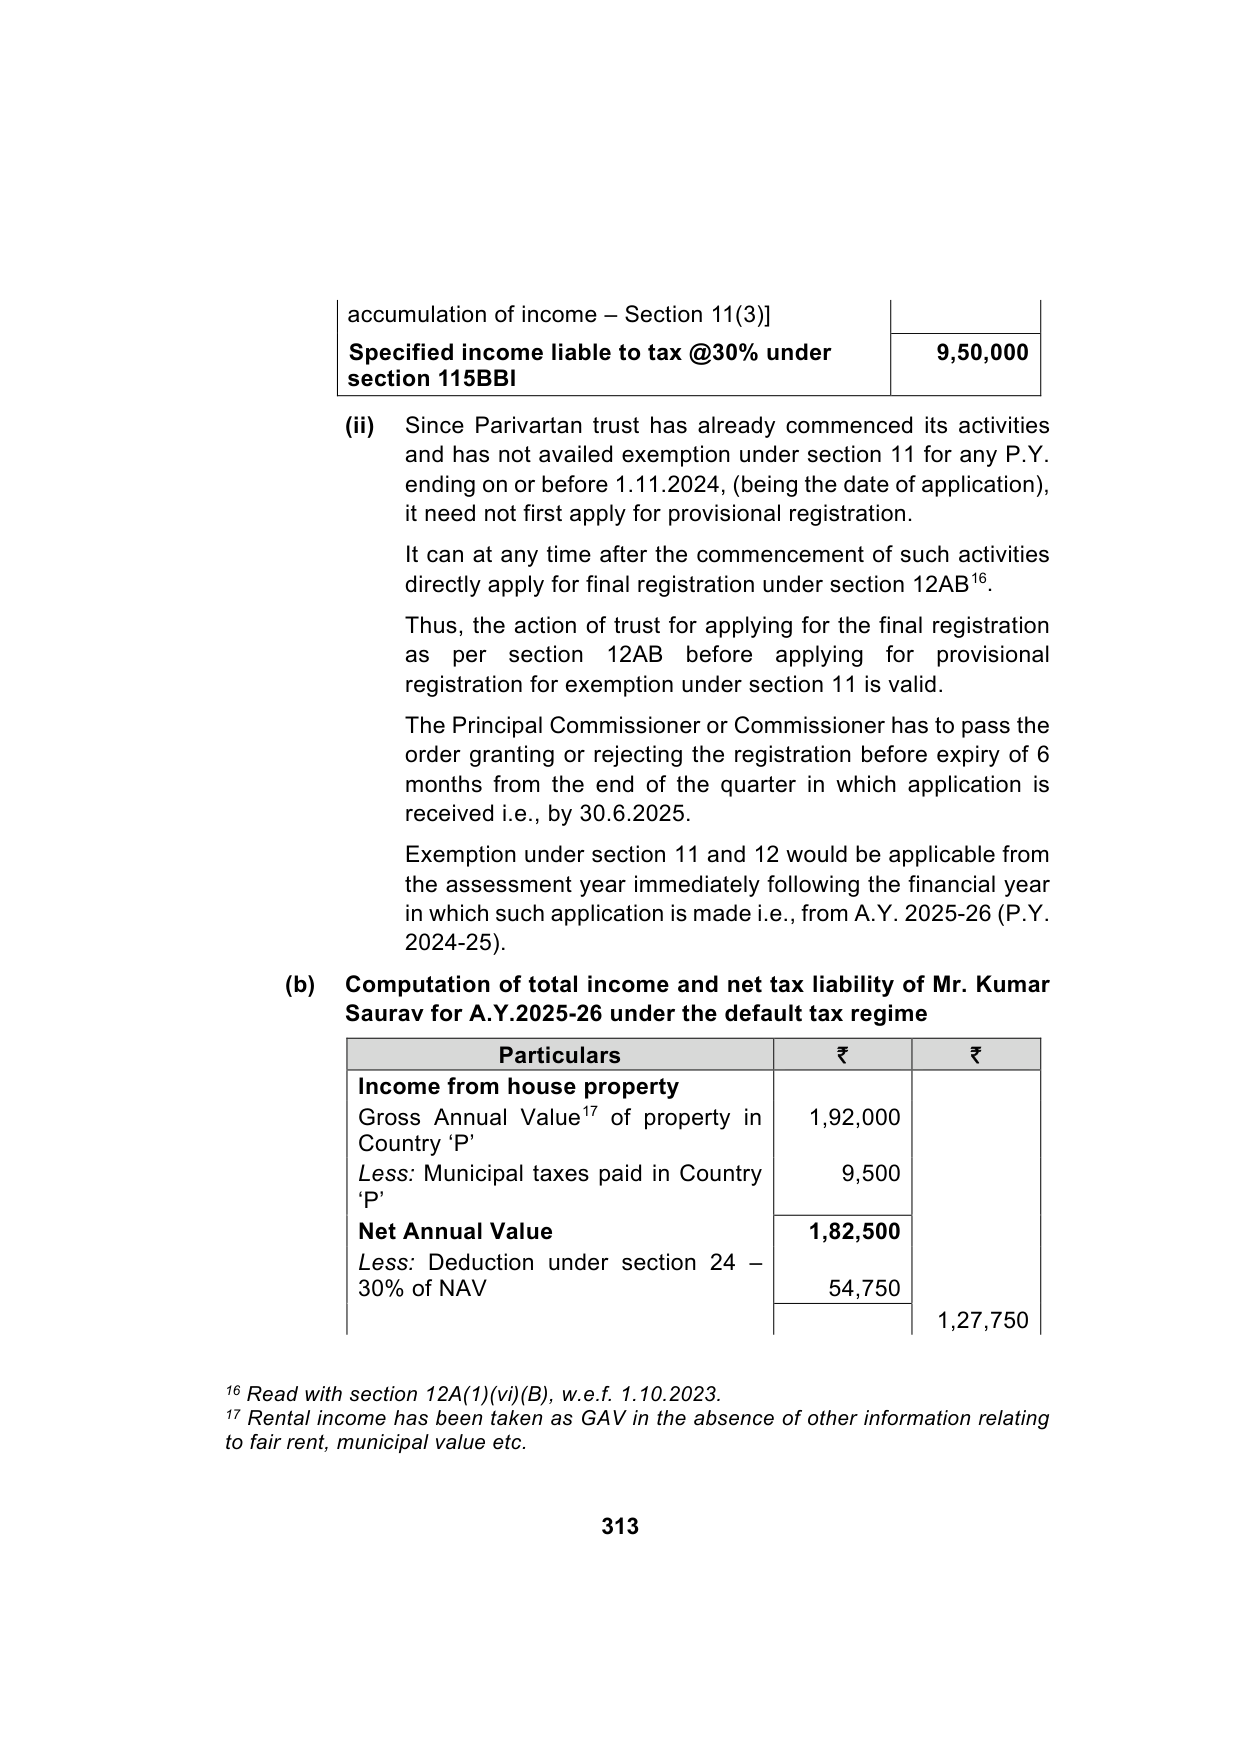
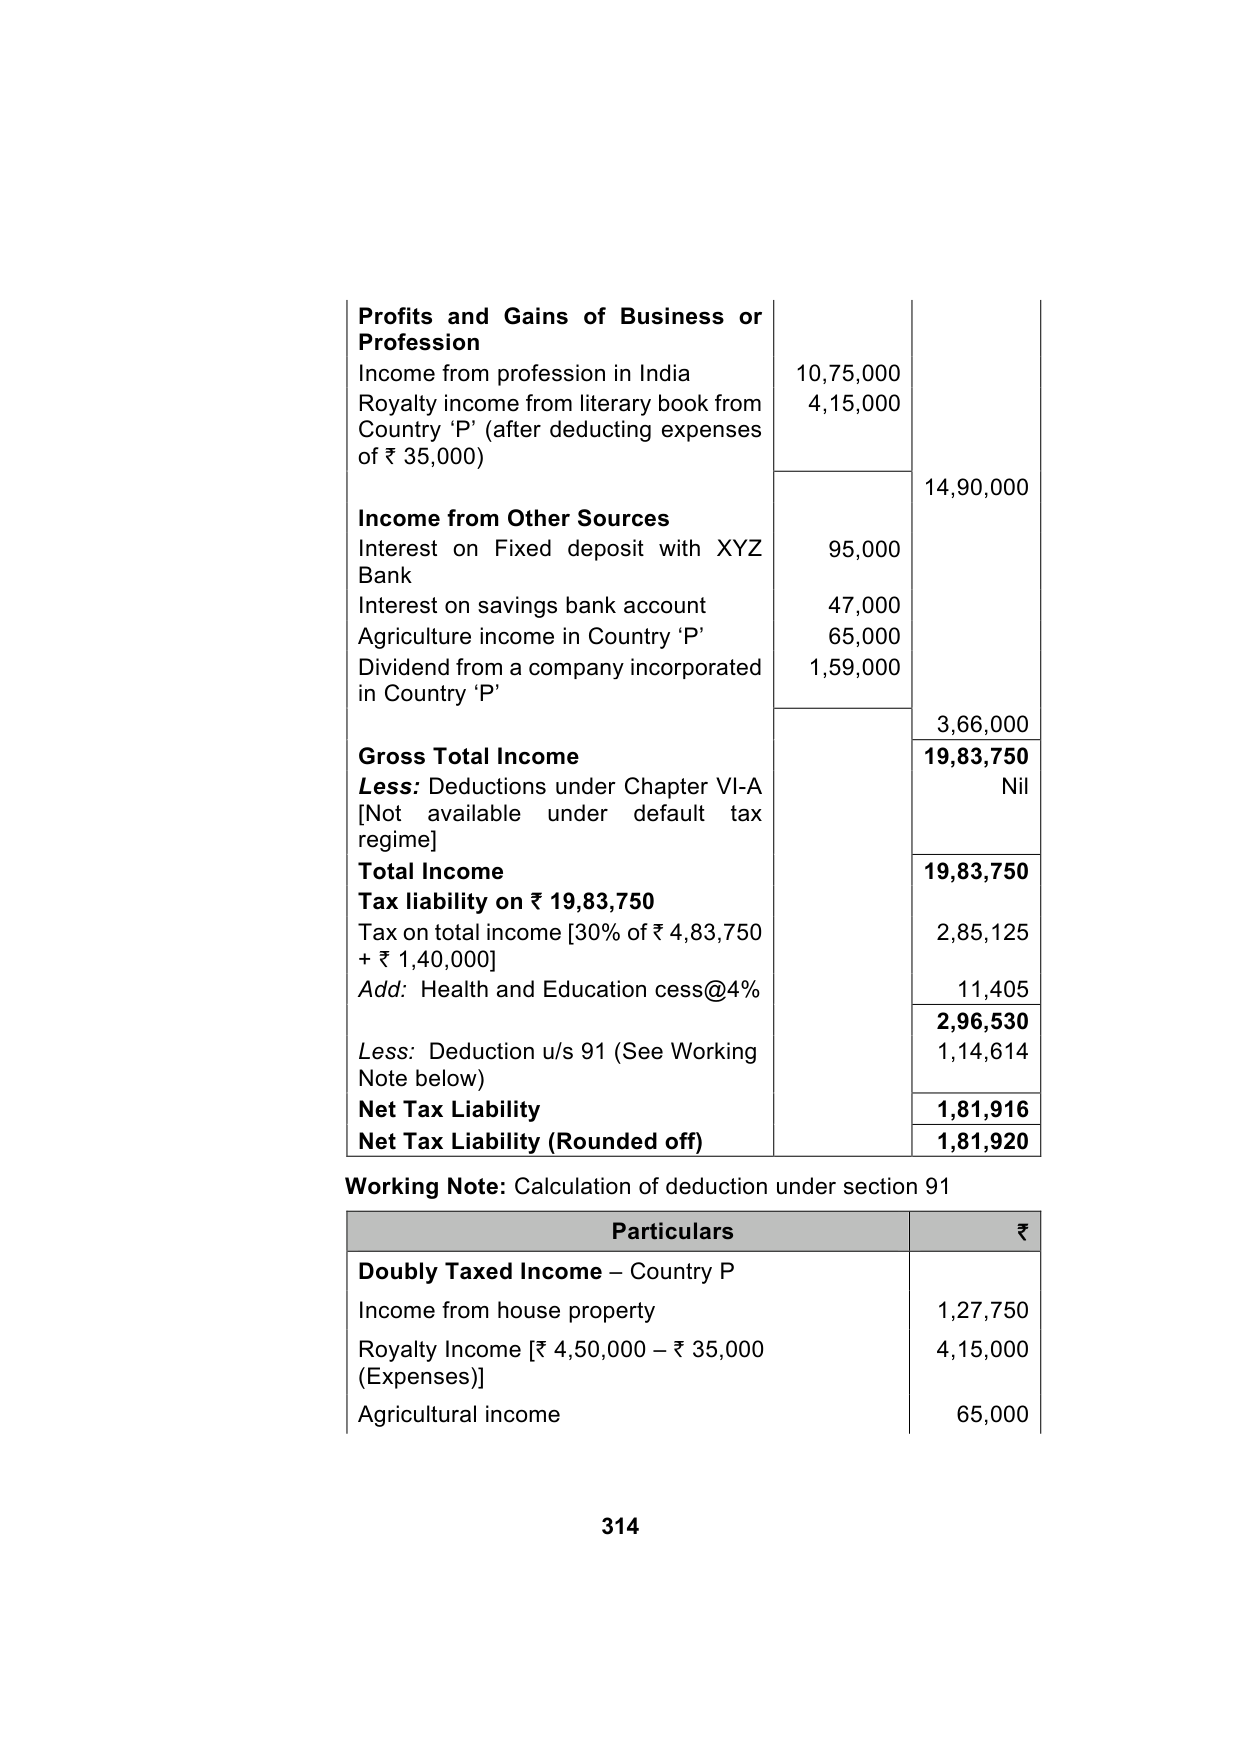
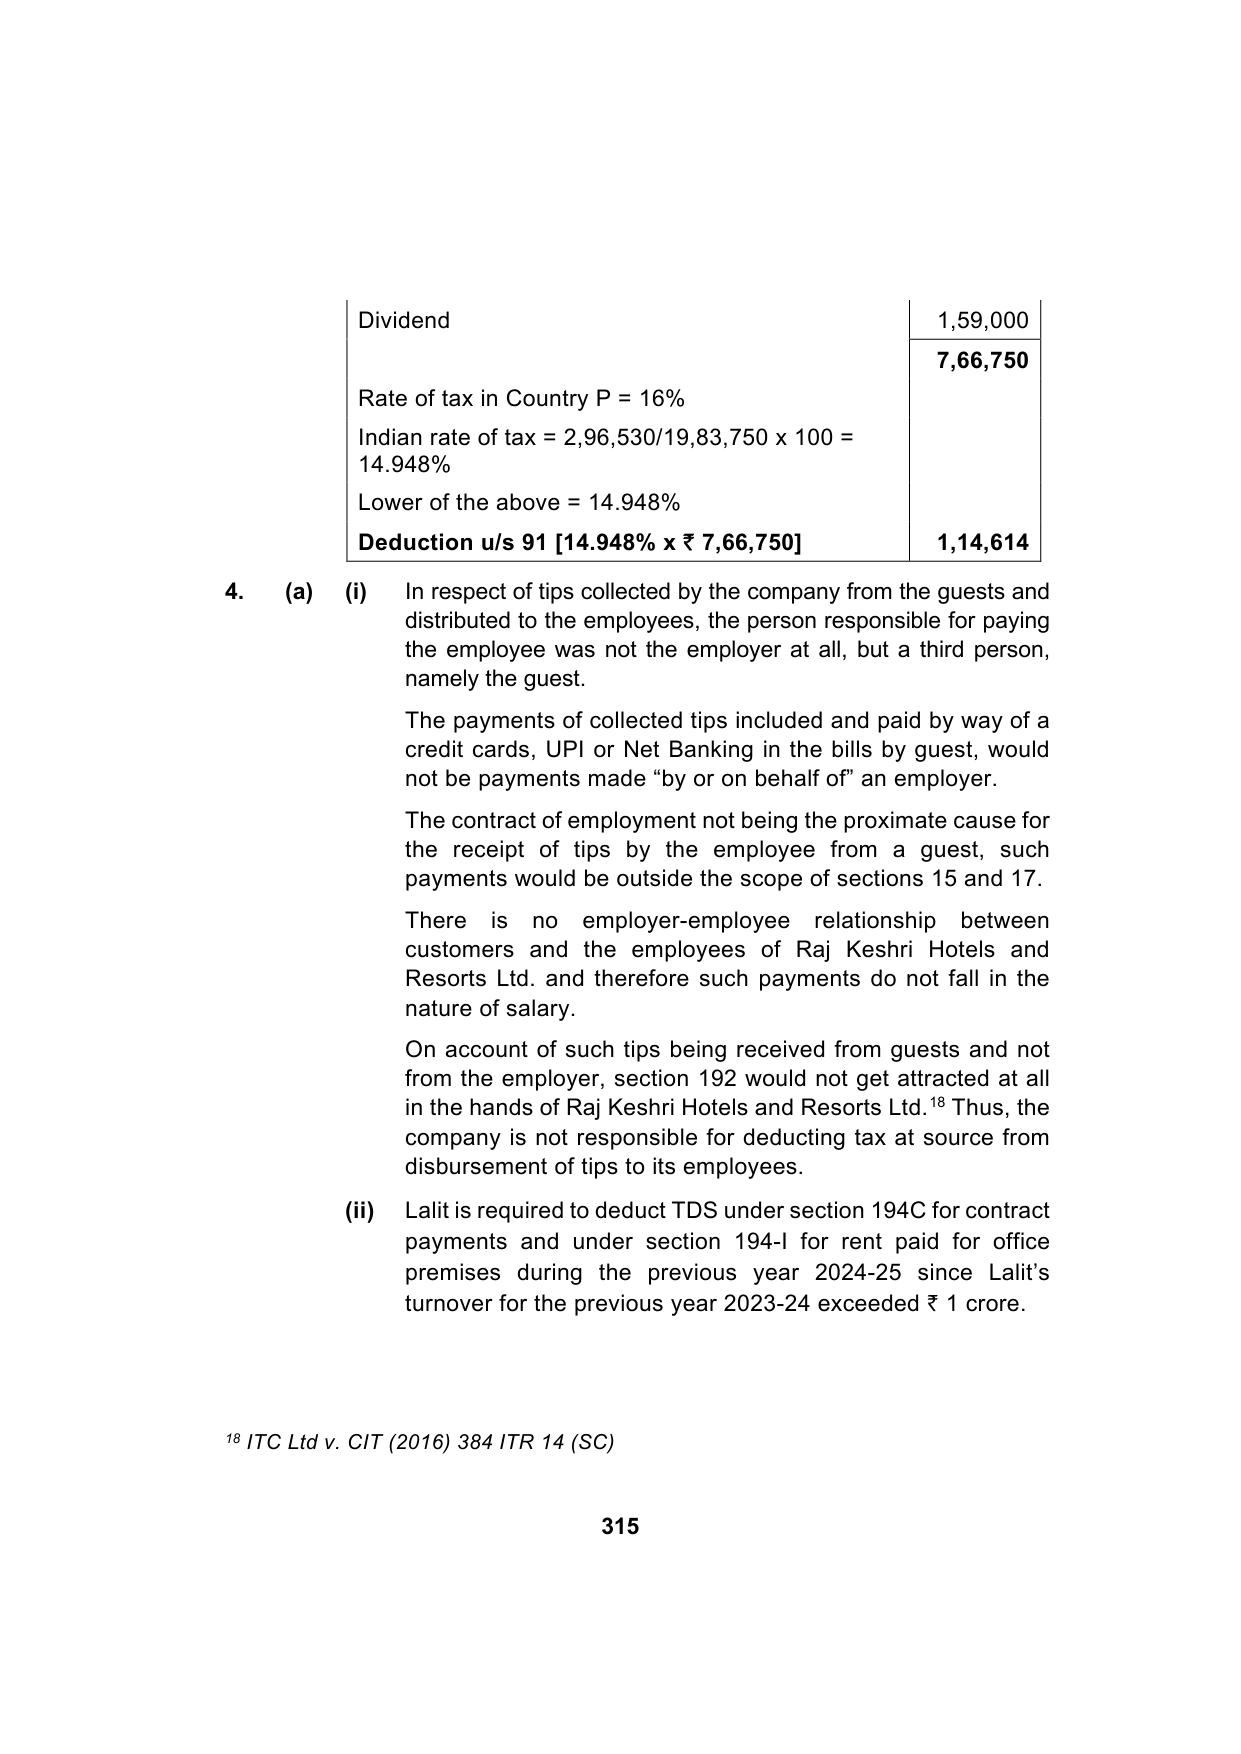
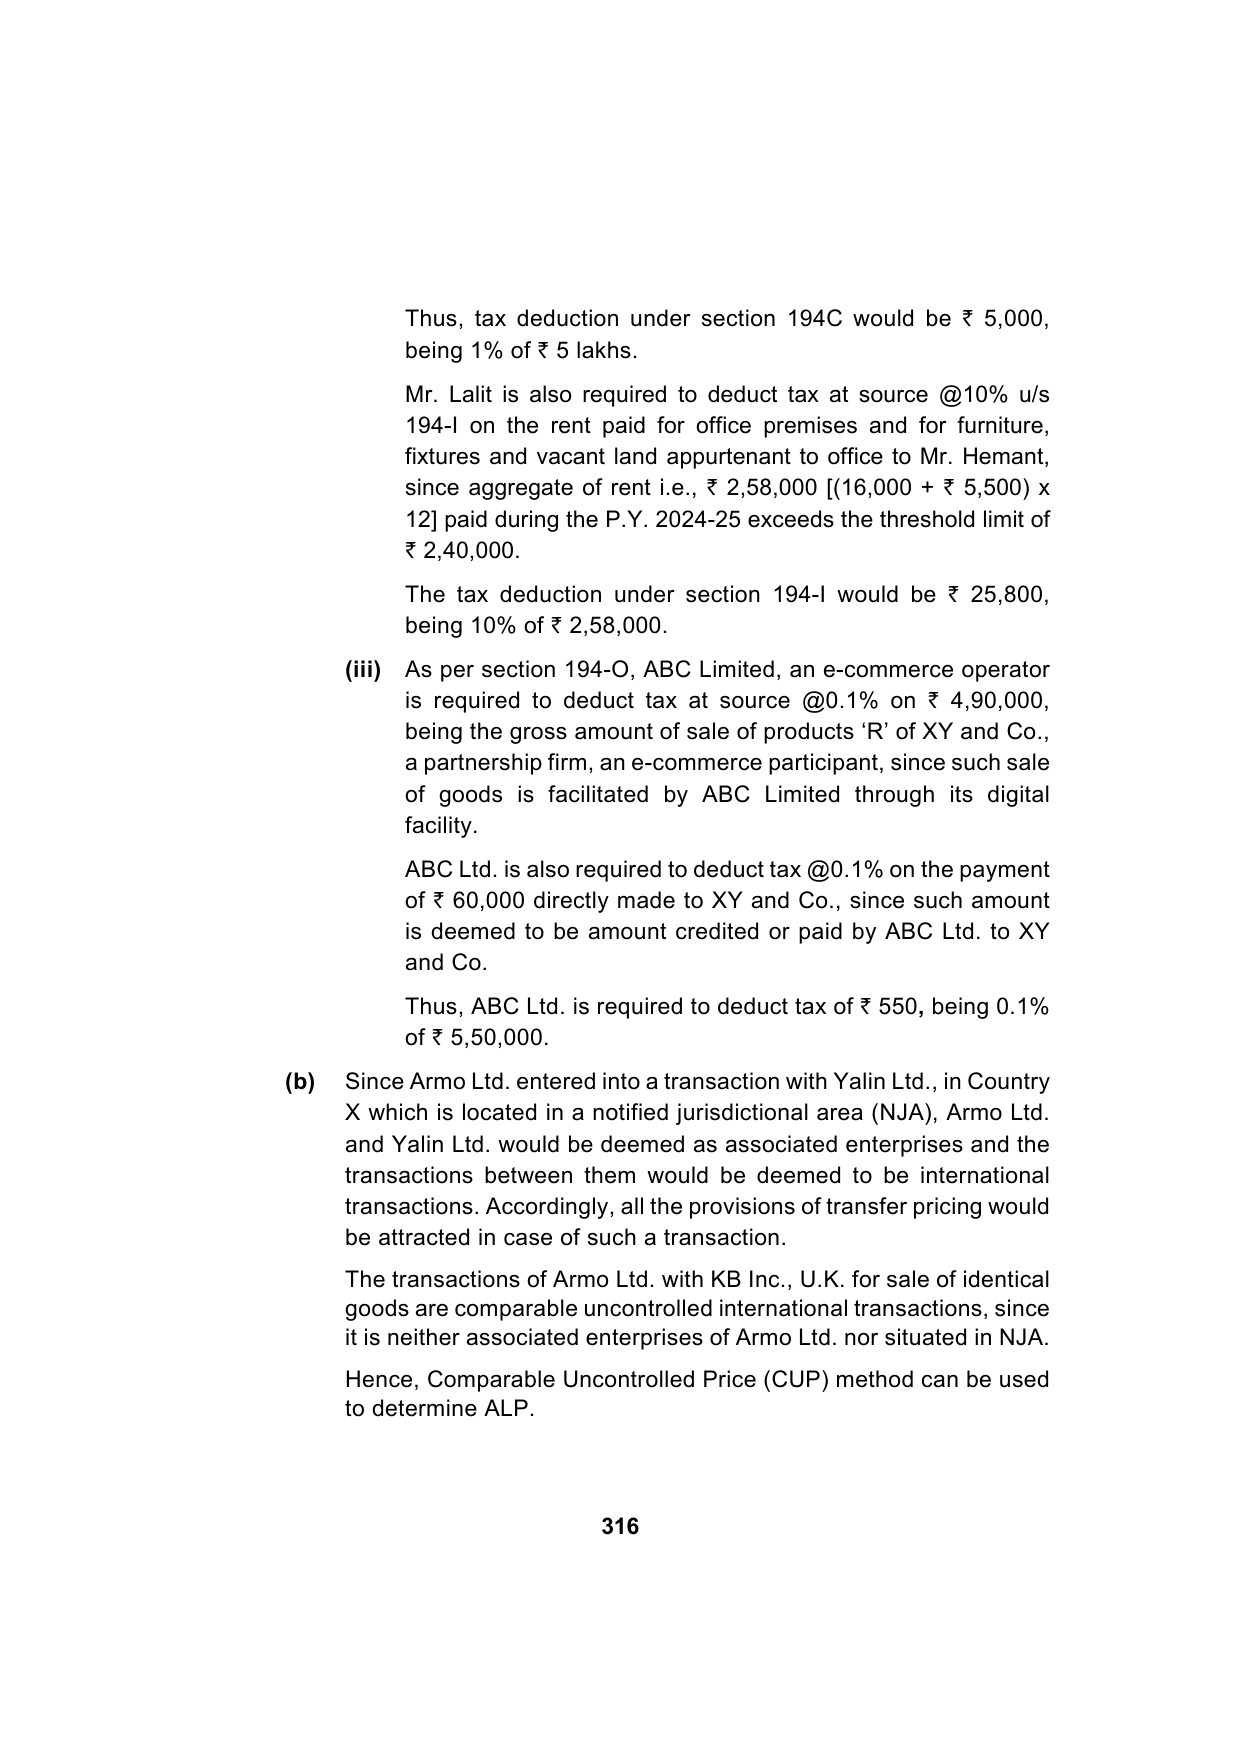
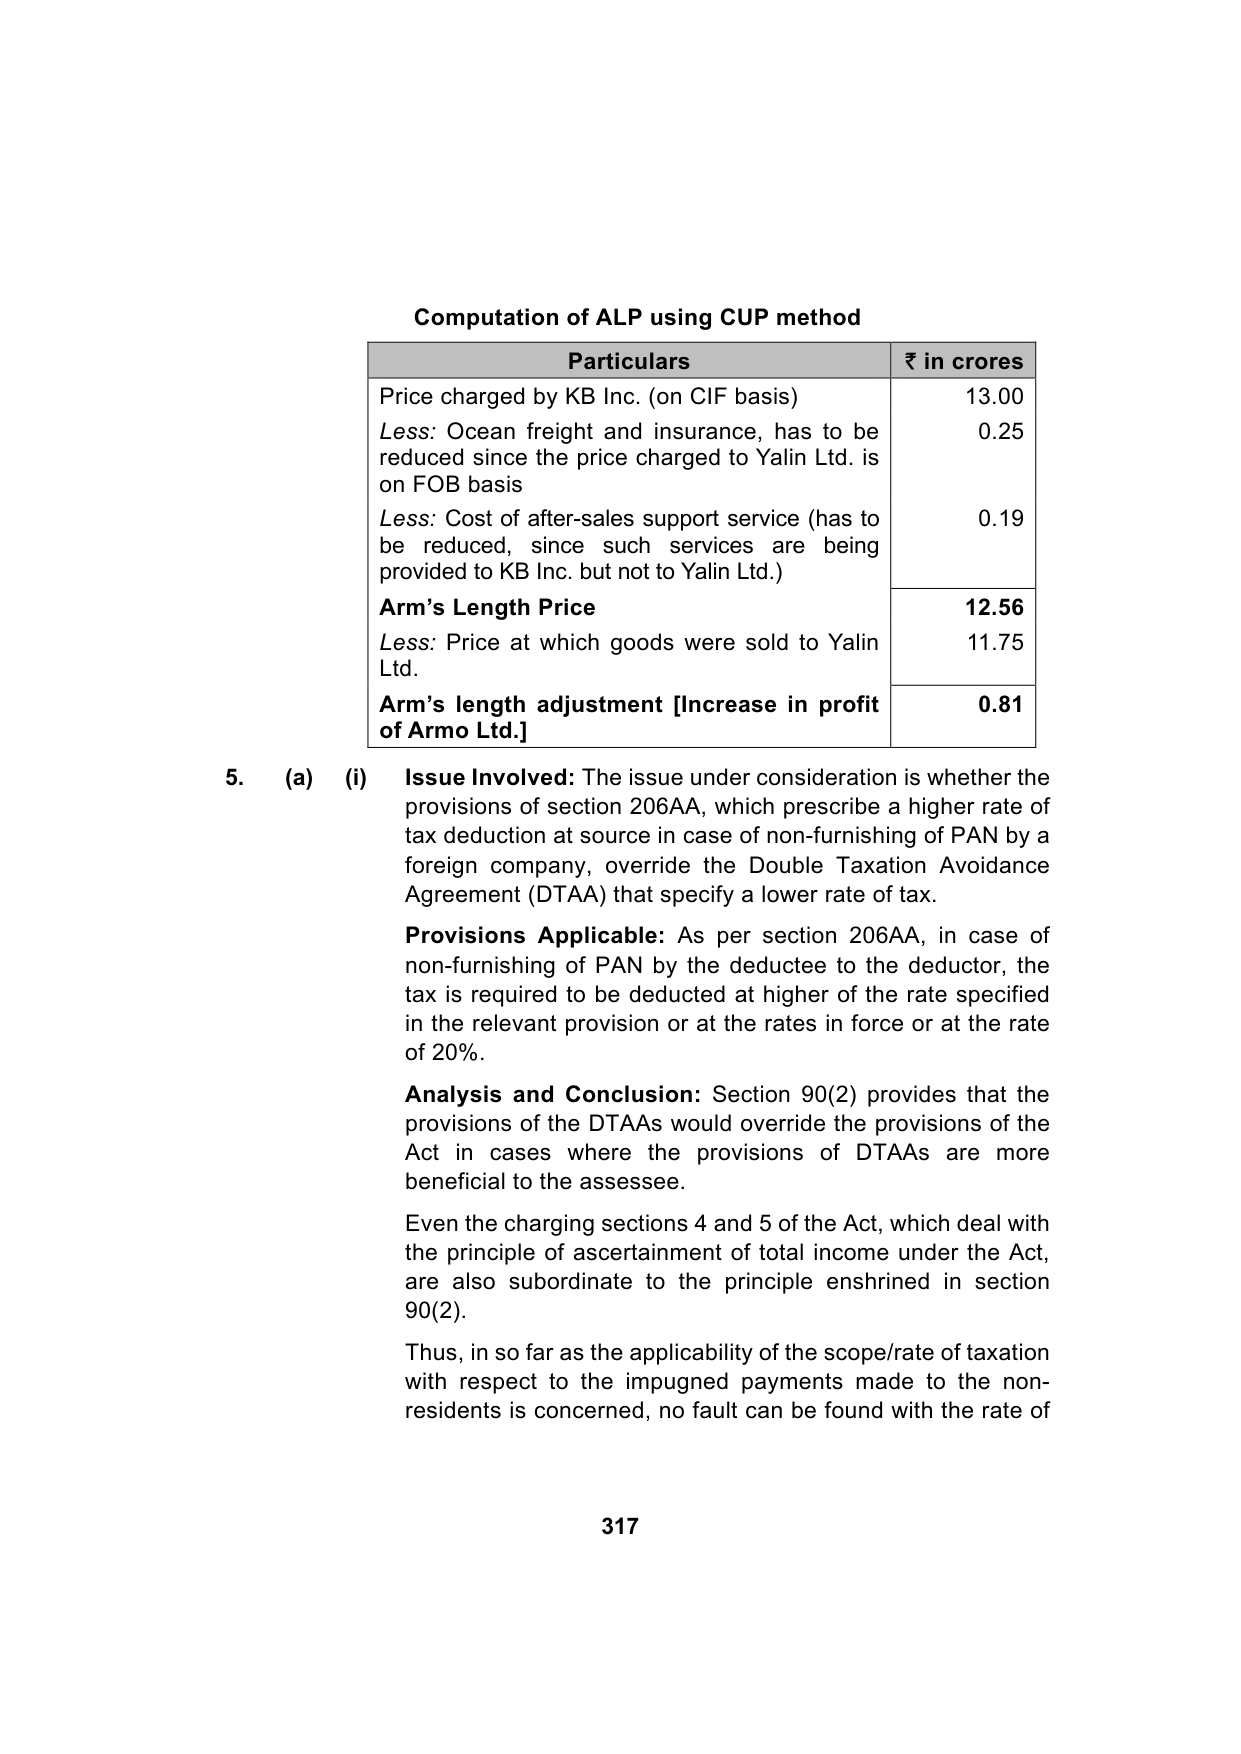
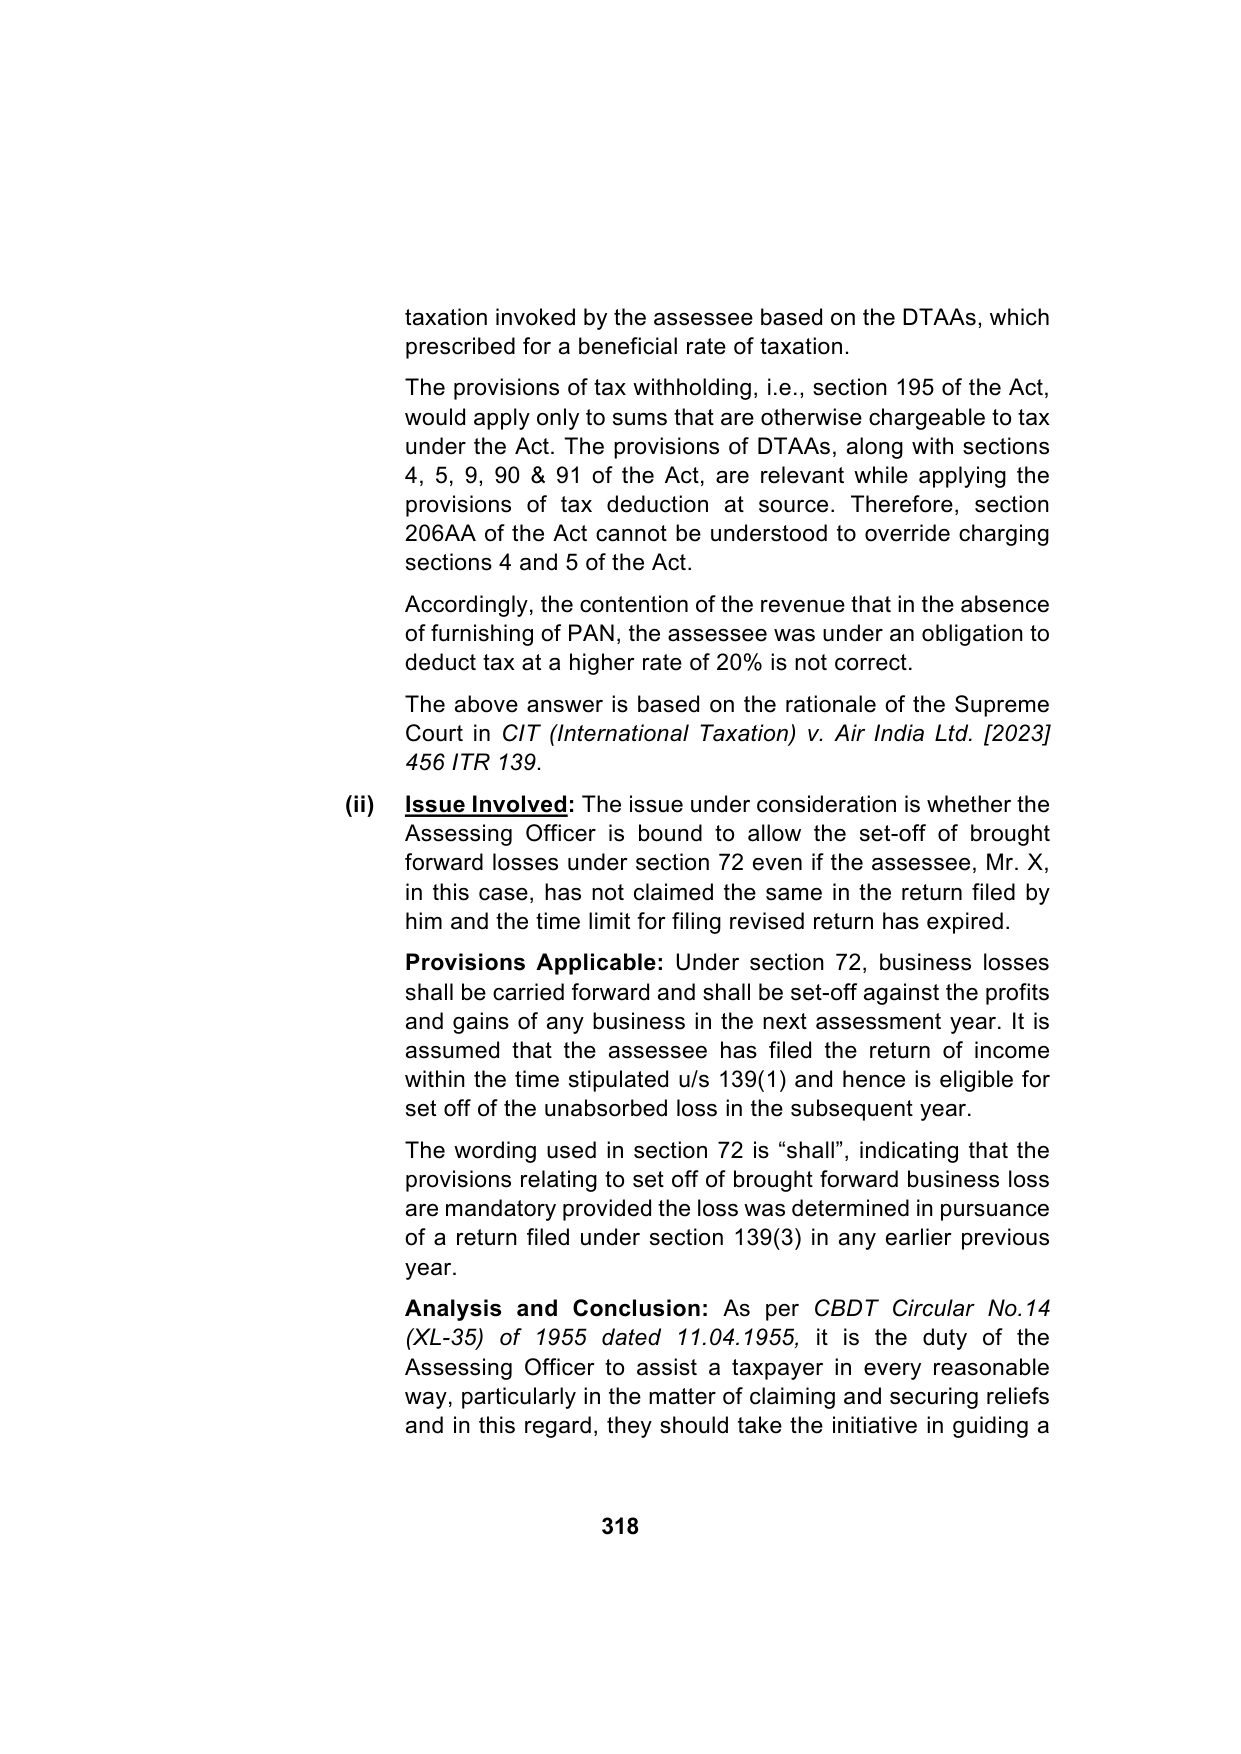
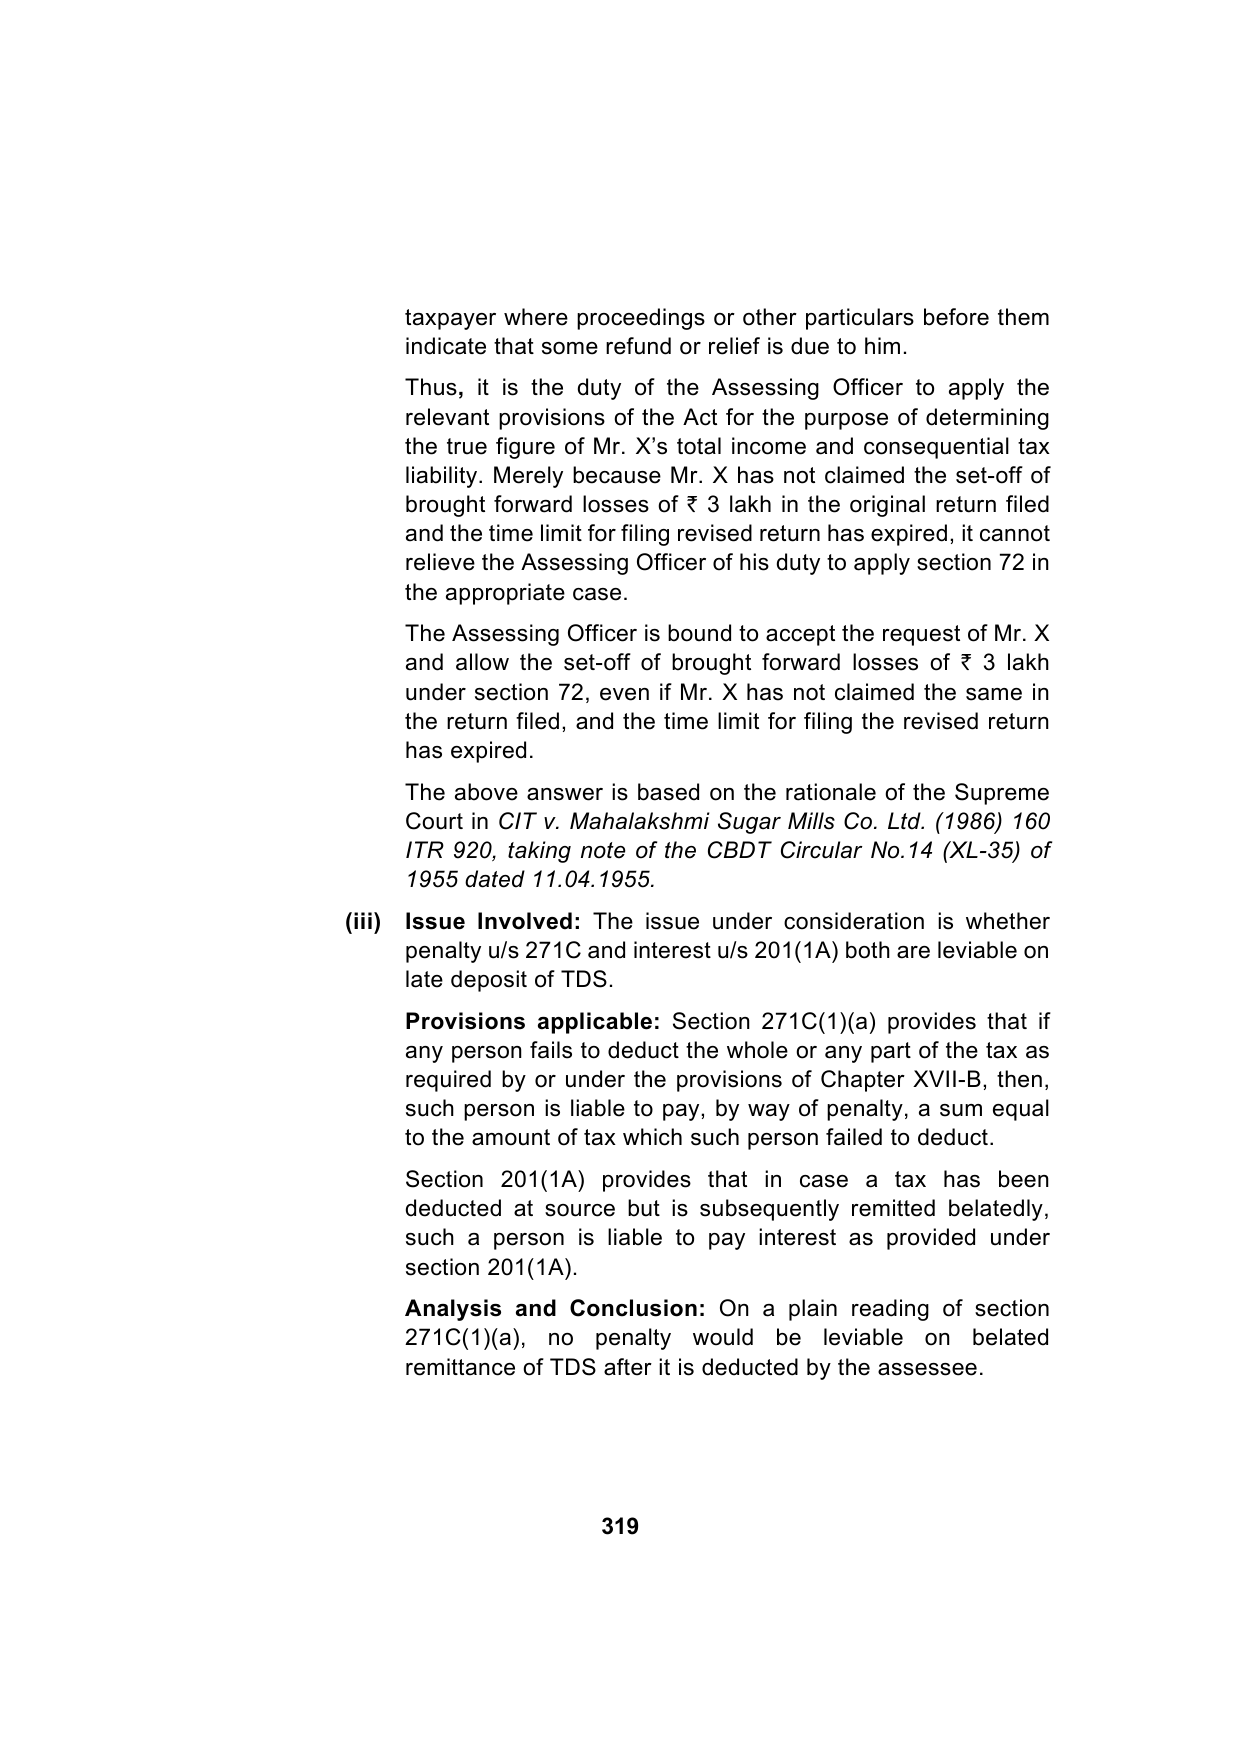
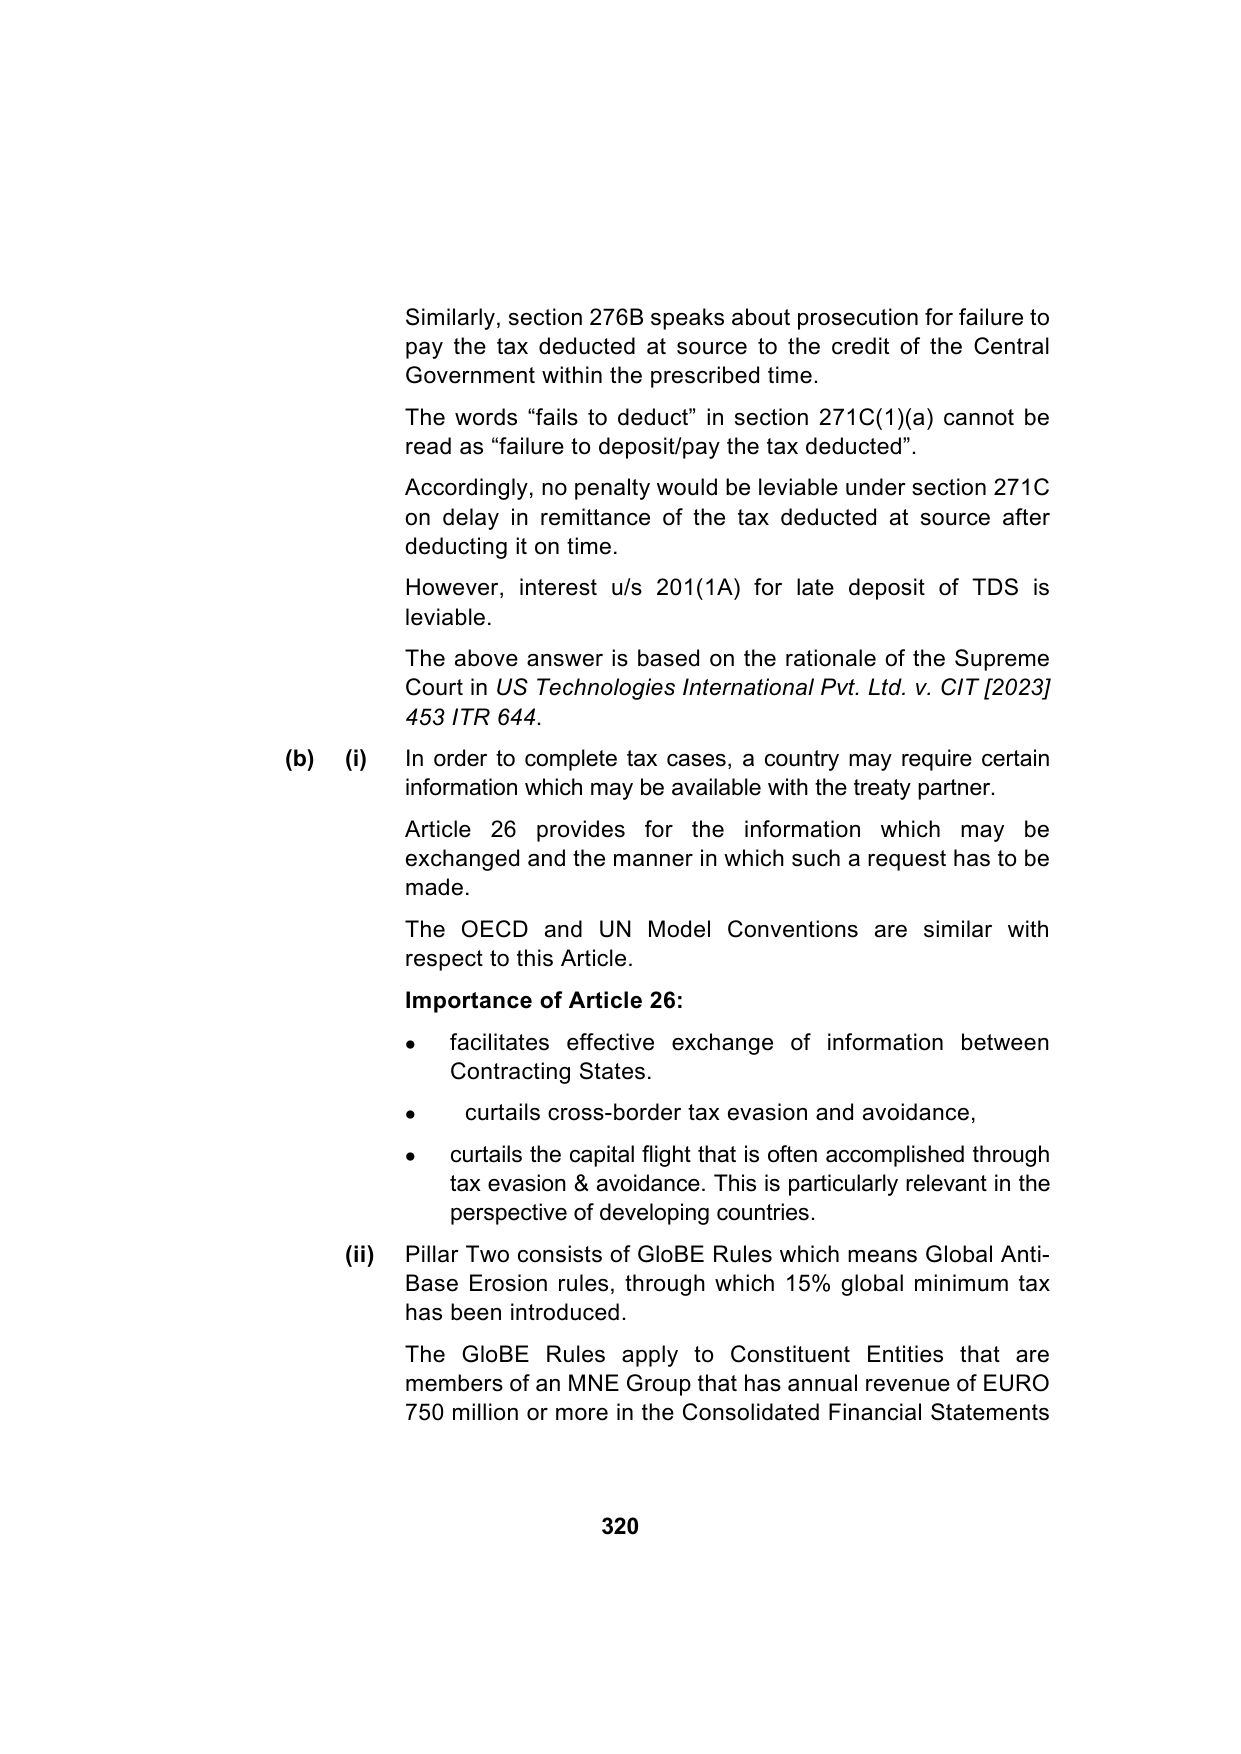
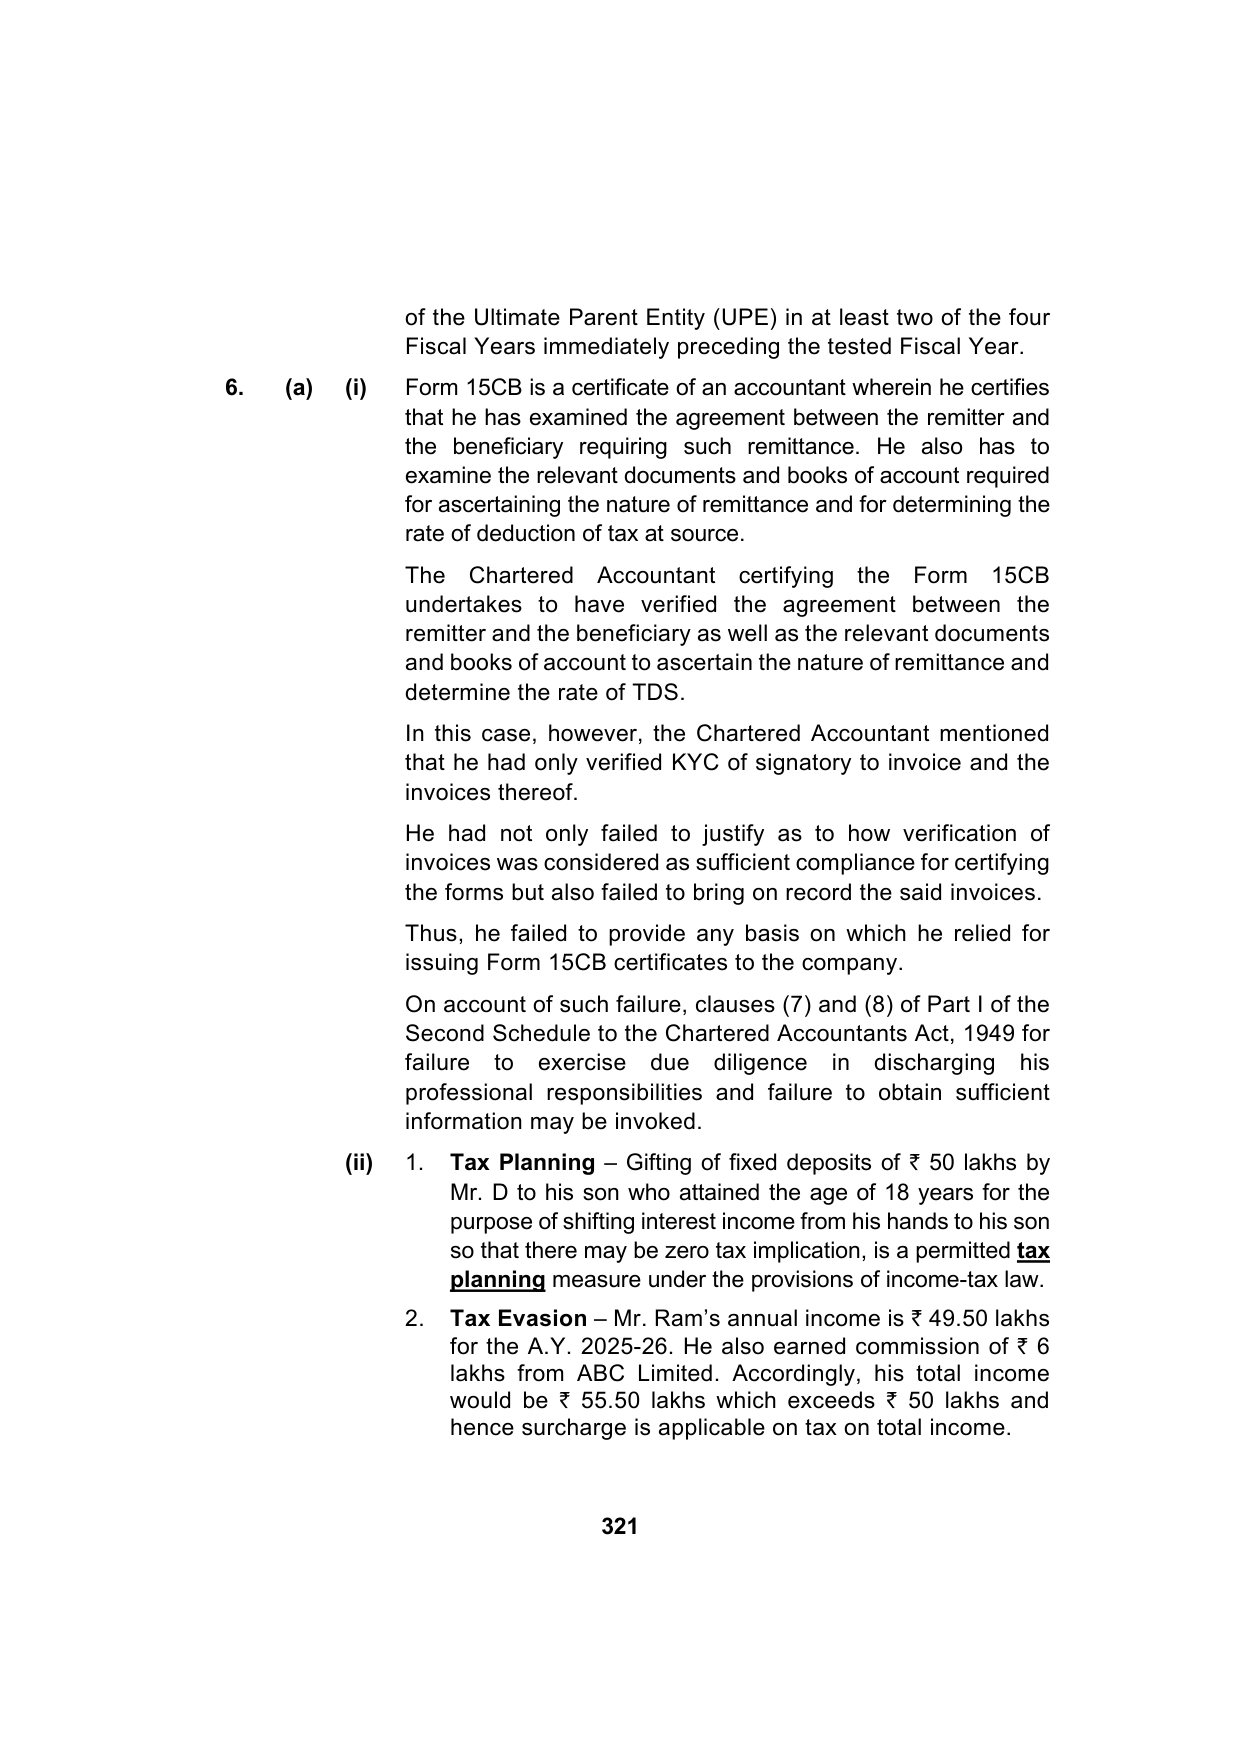
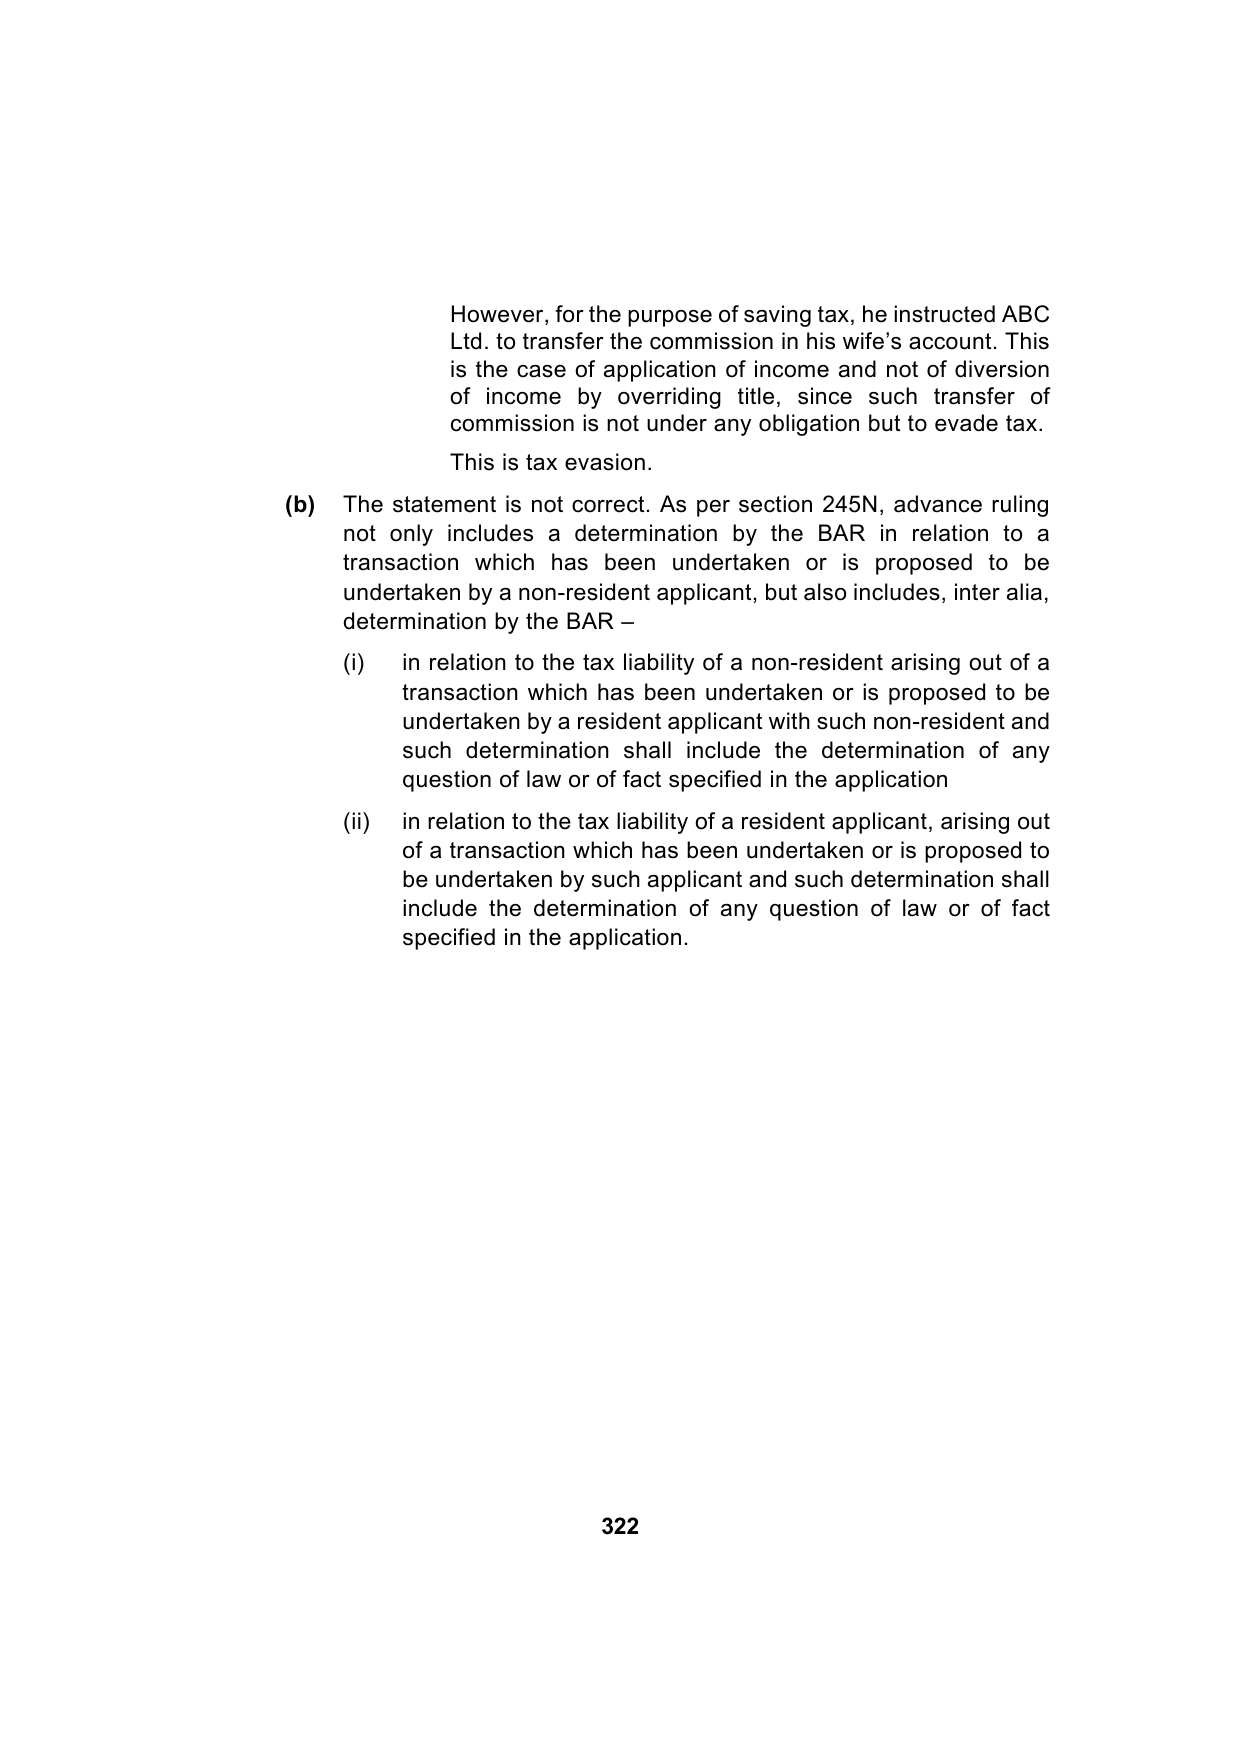
Paper 4: Direct Tax Laws & International Taxation — Model Test Paper 6 (100 marks)
Question
Answer
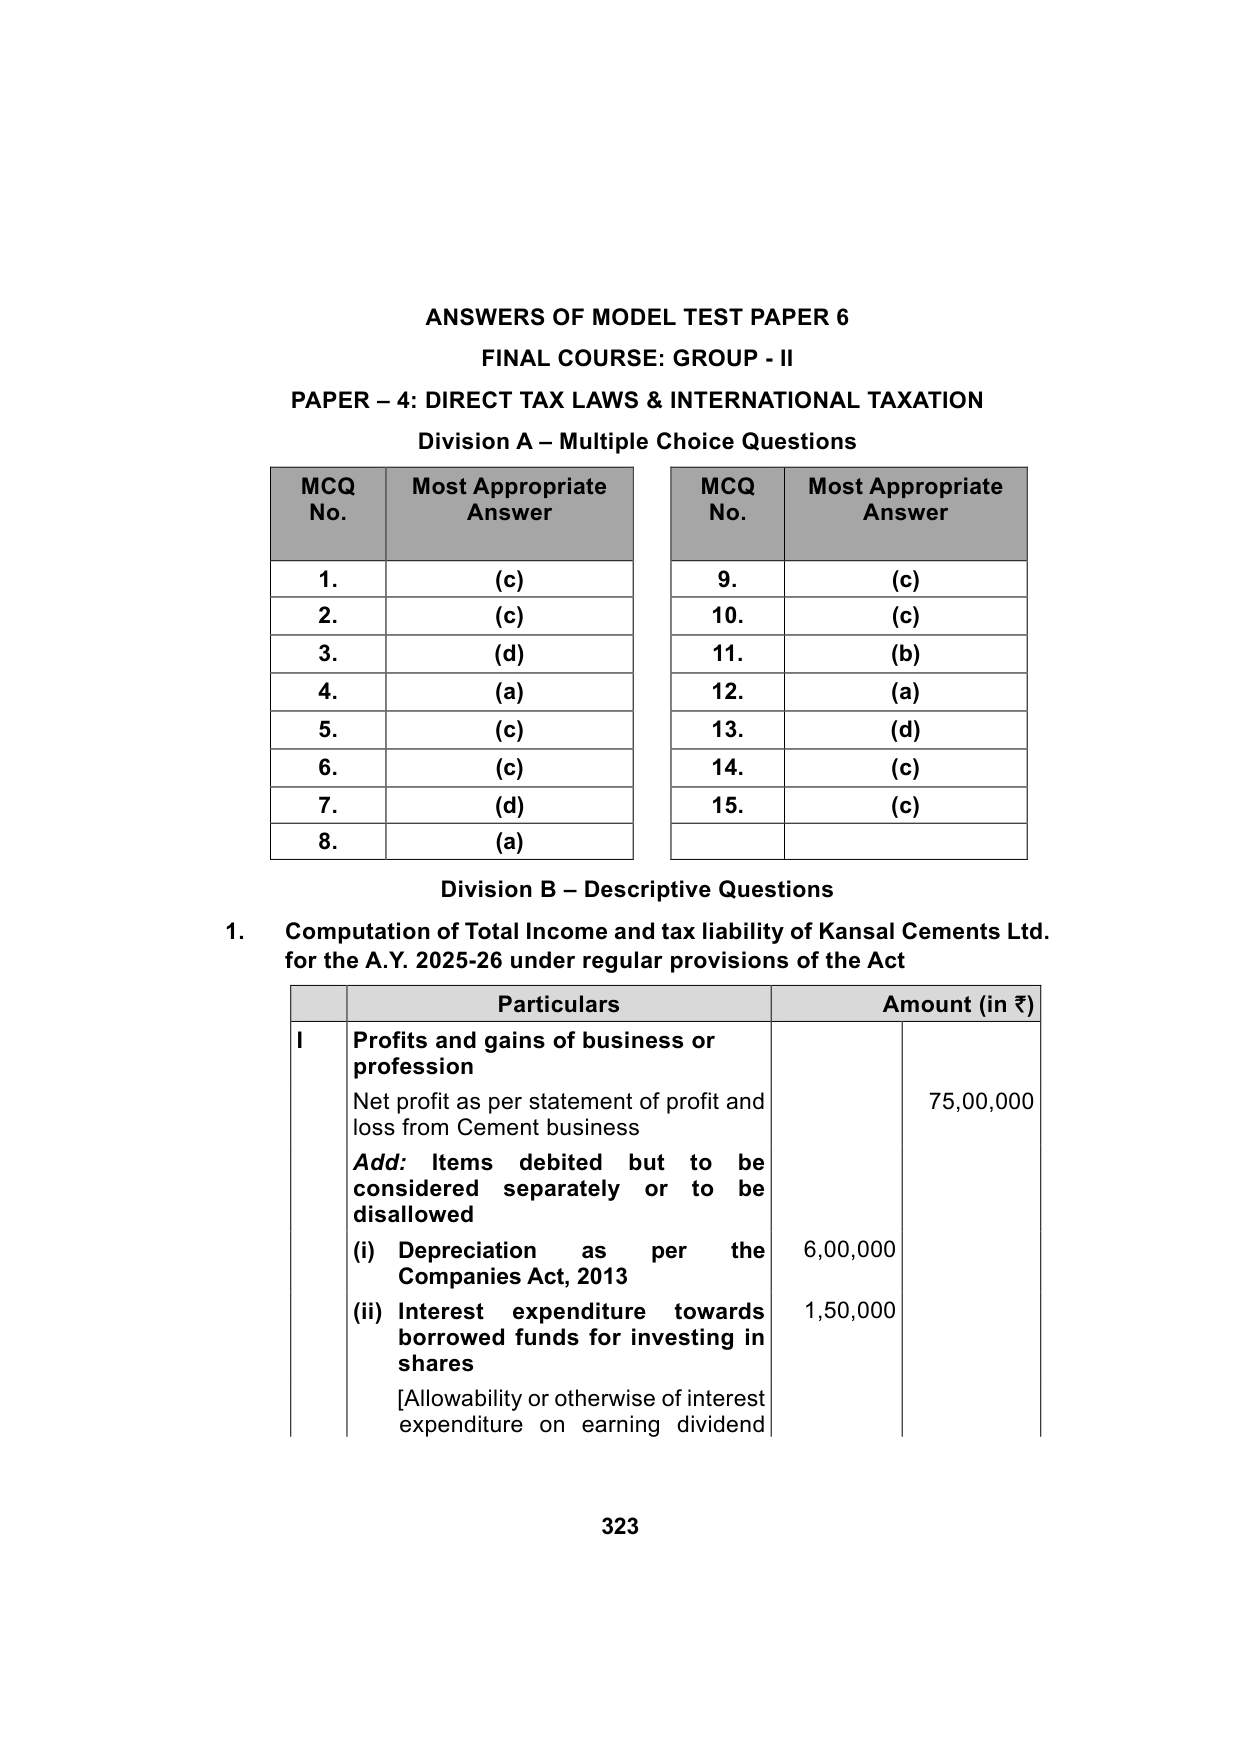
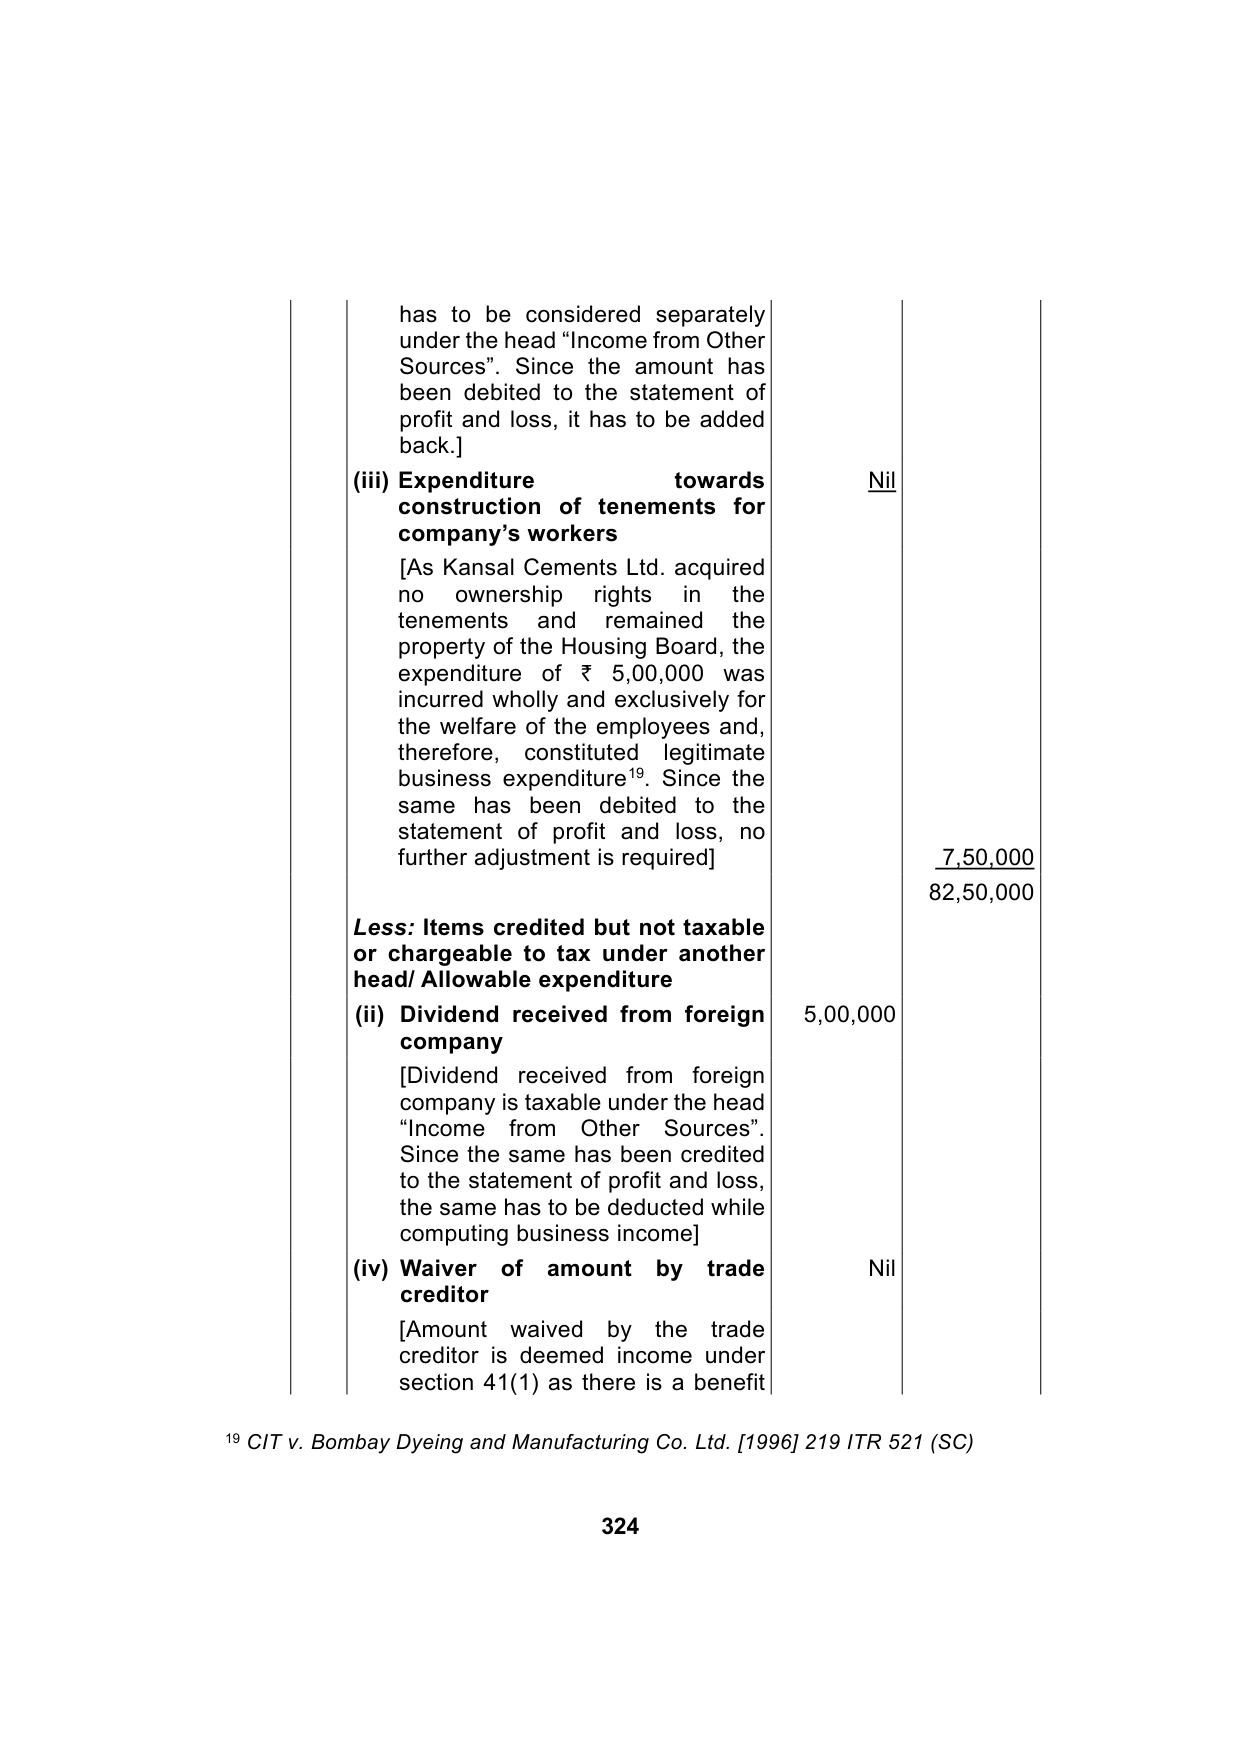
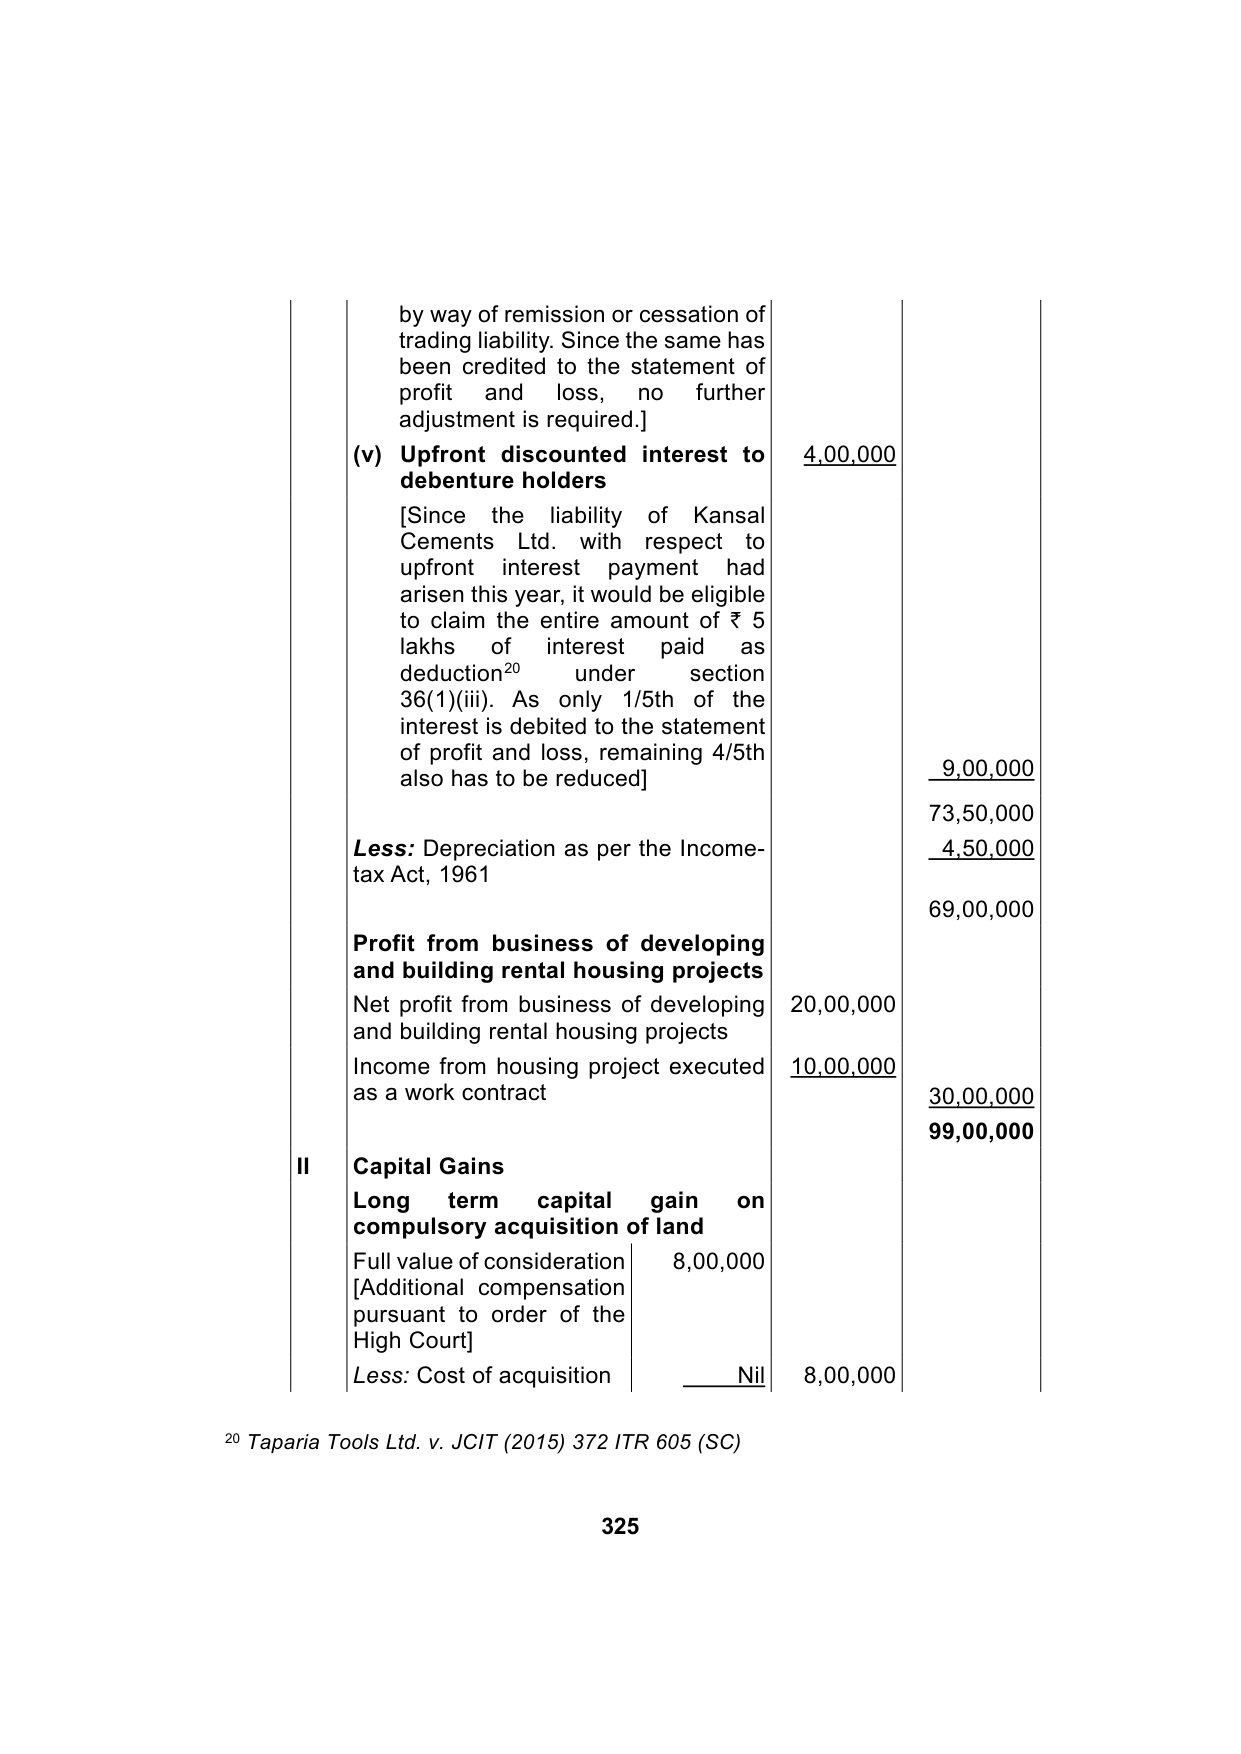
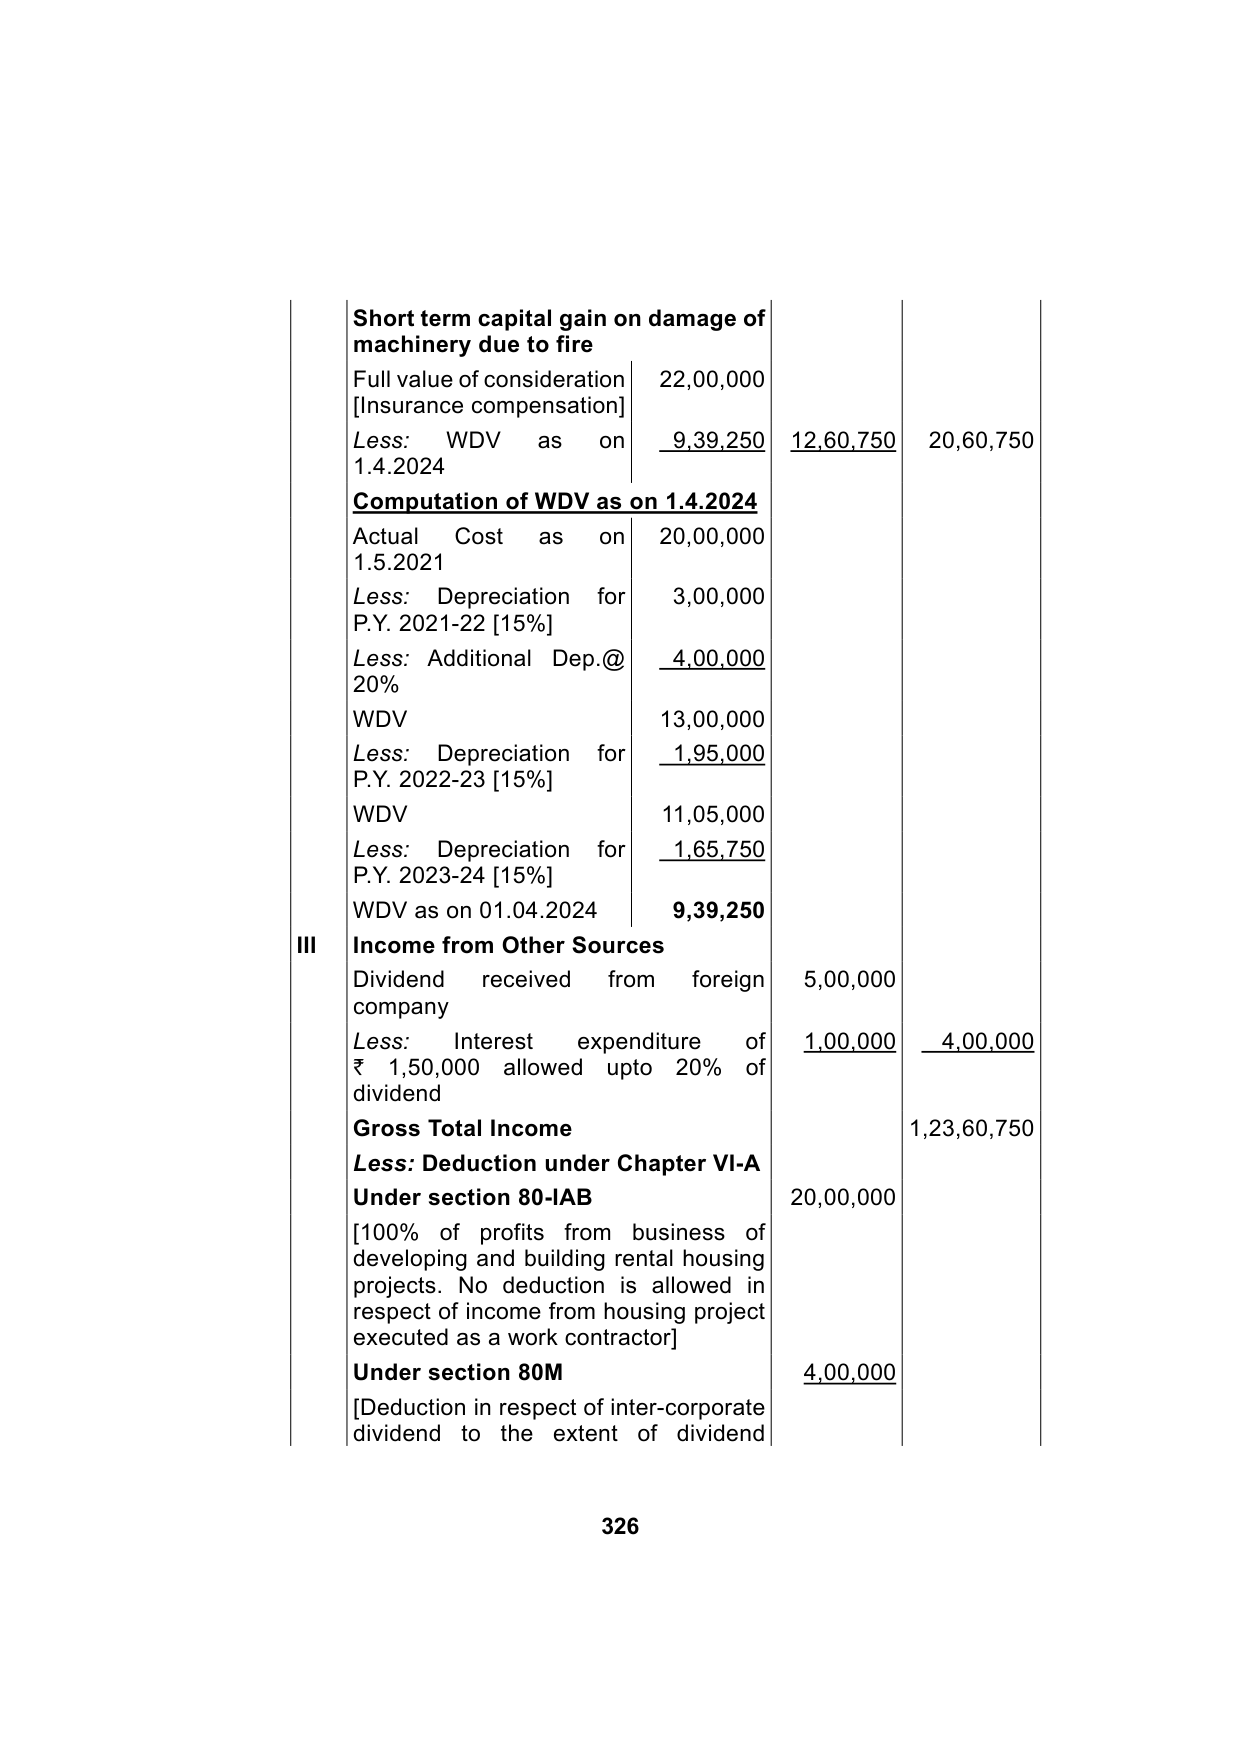
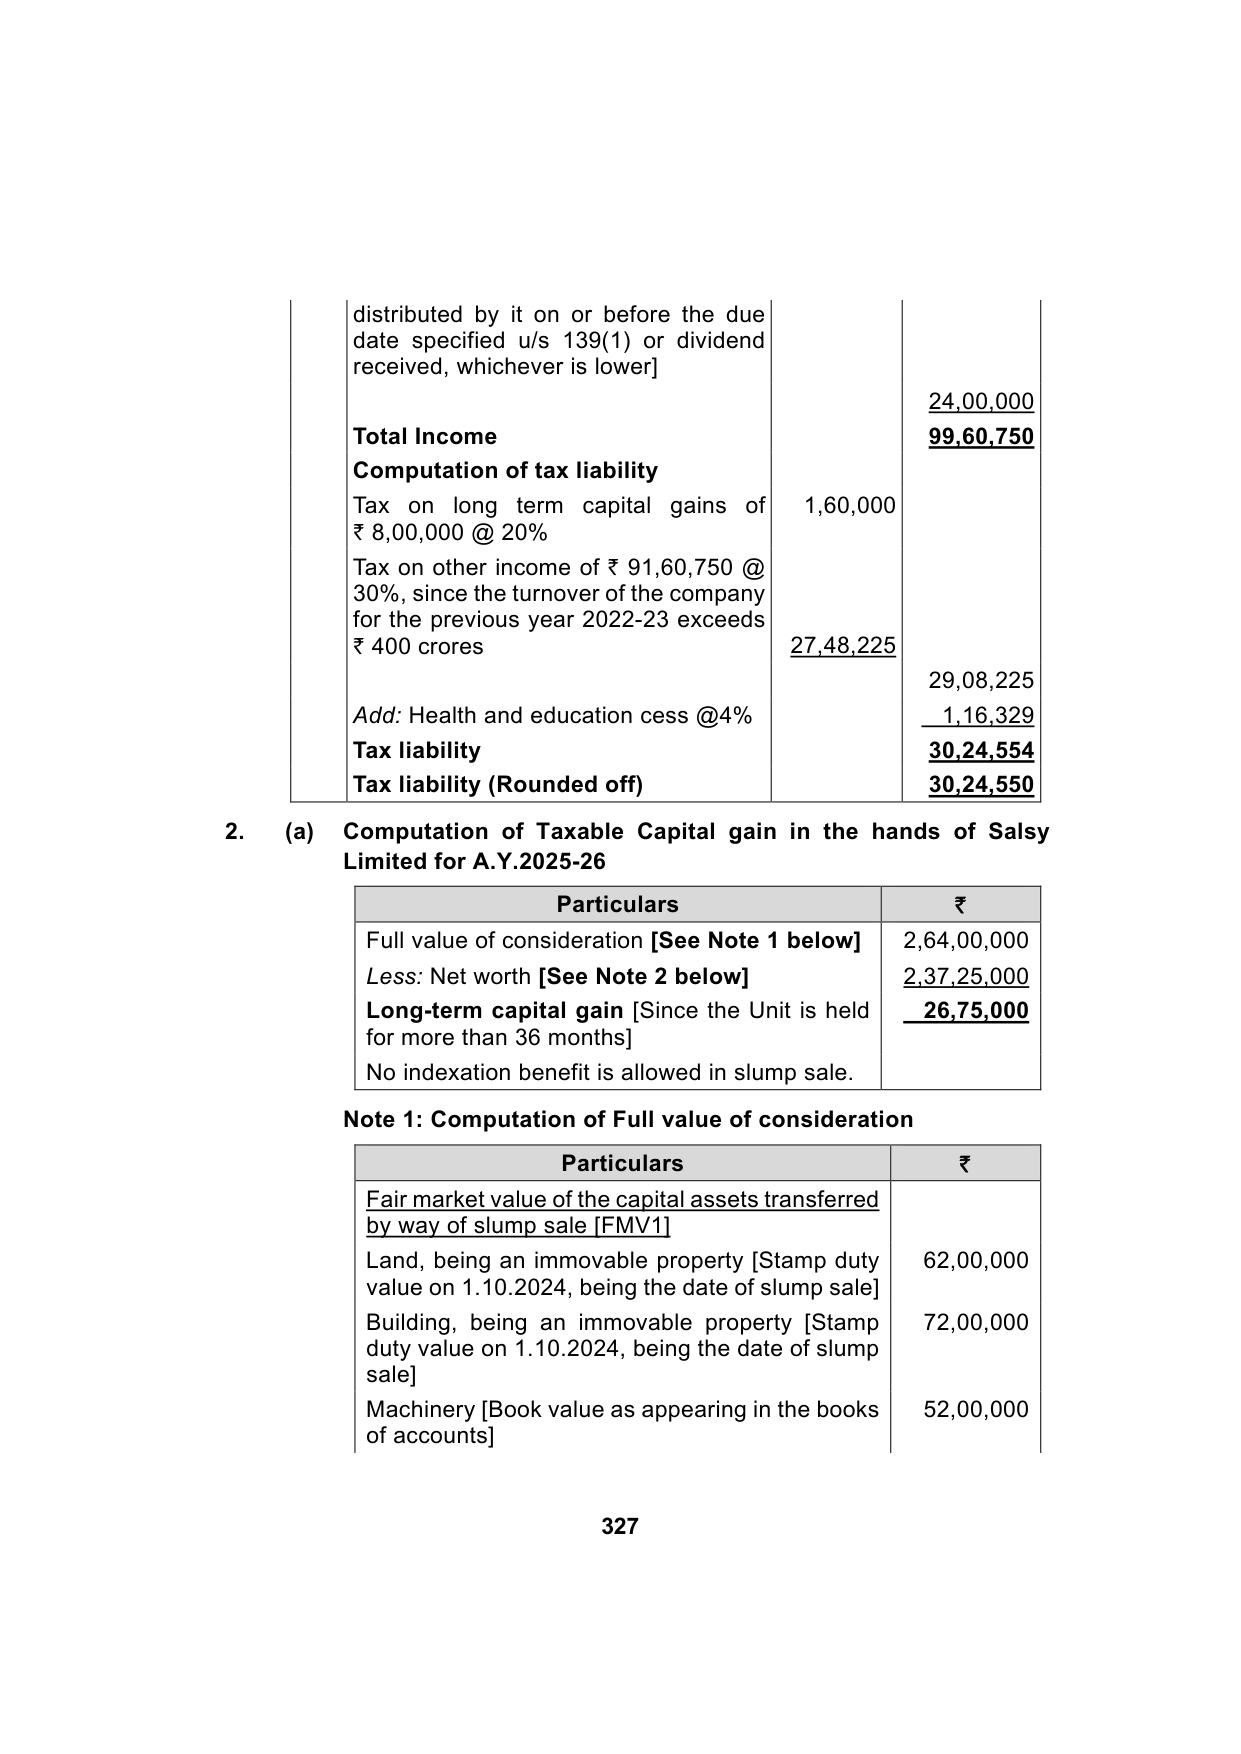
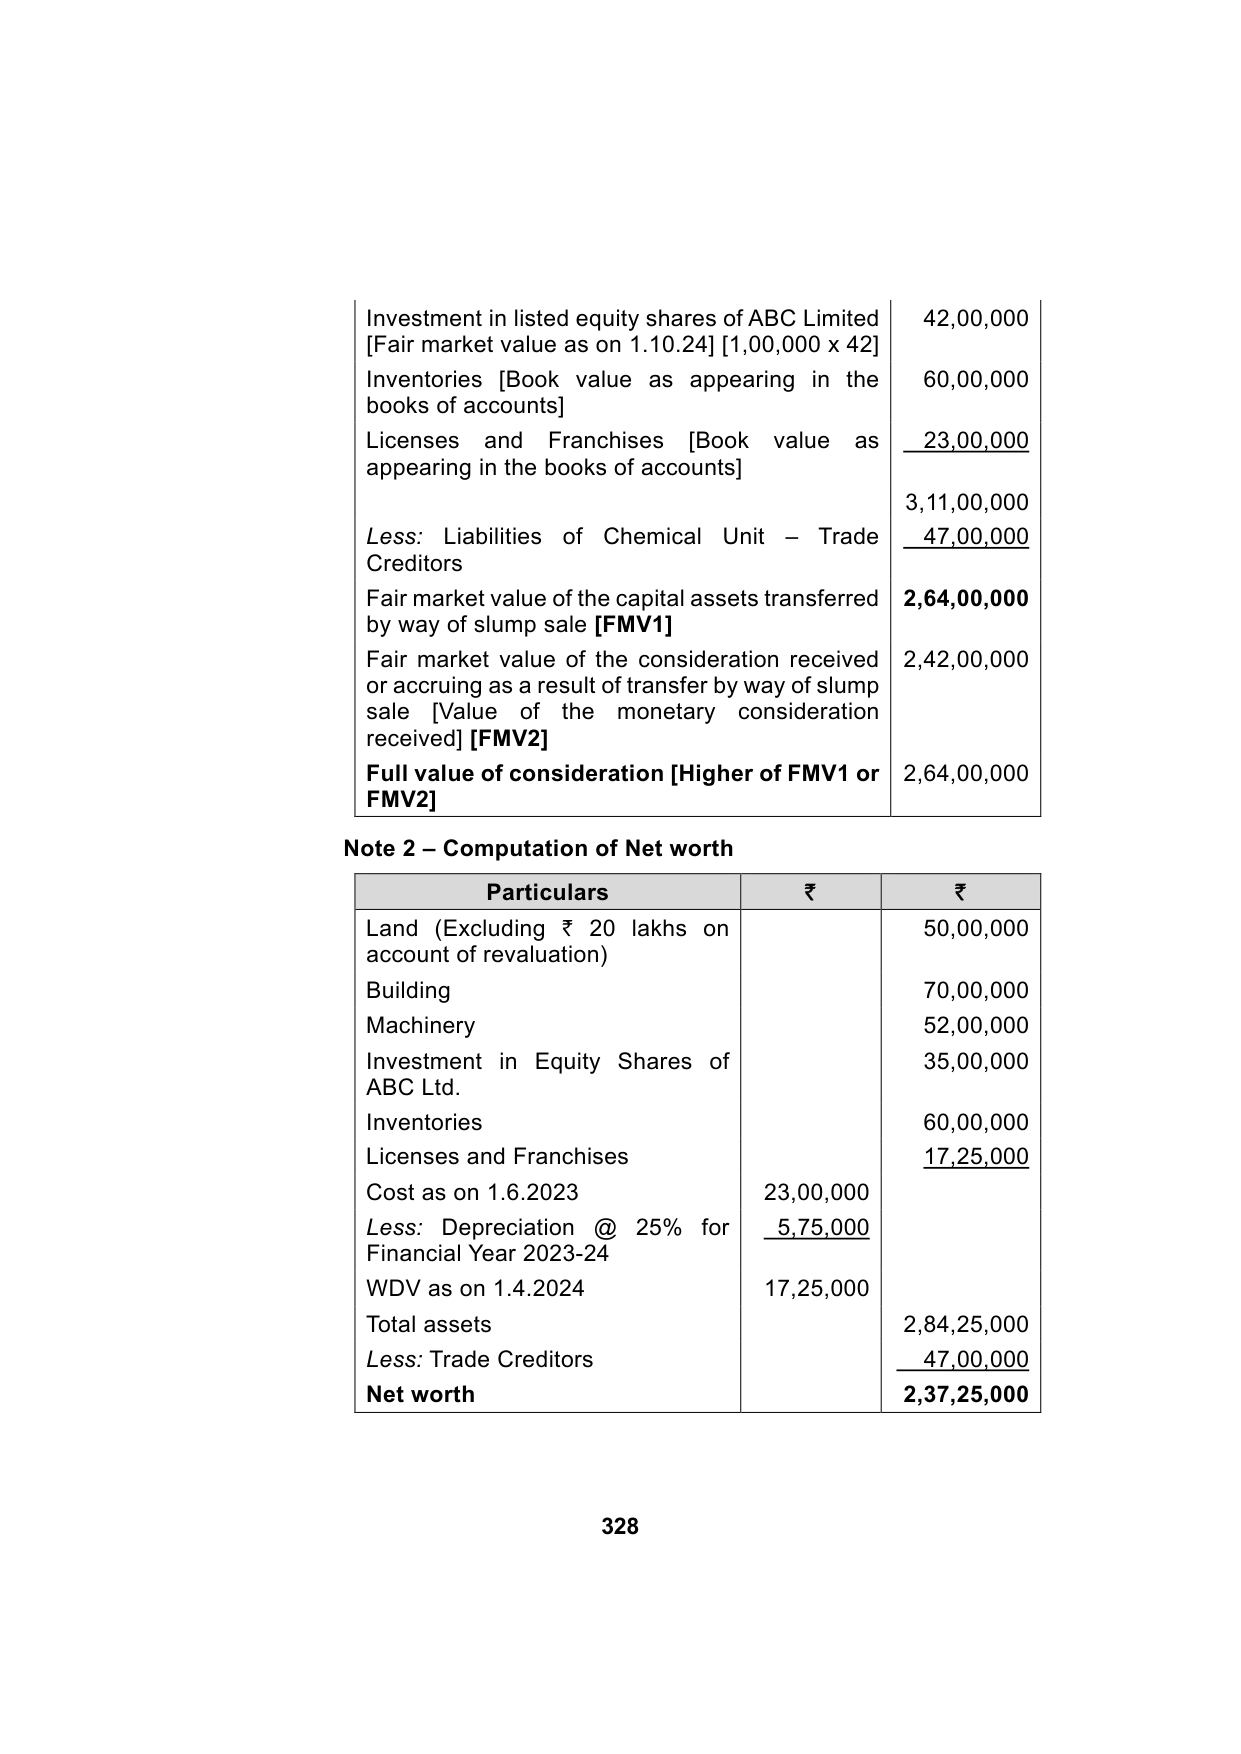
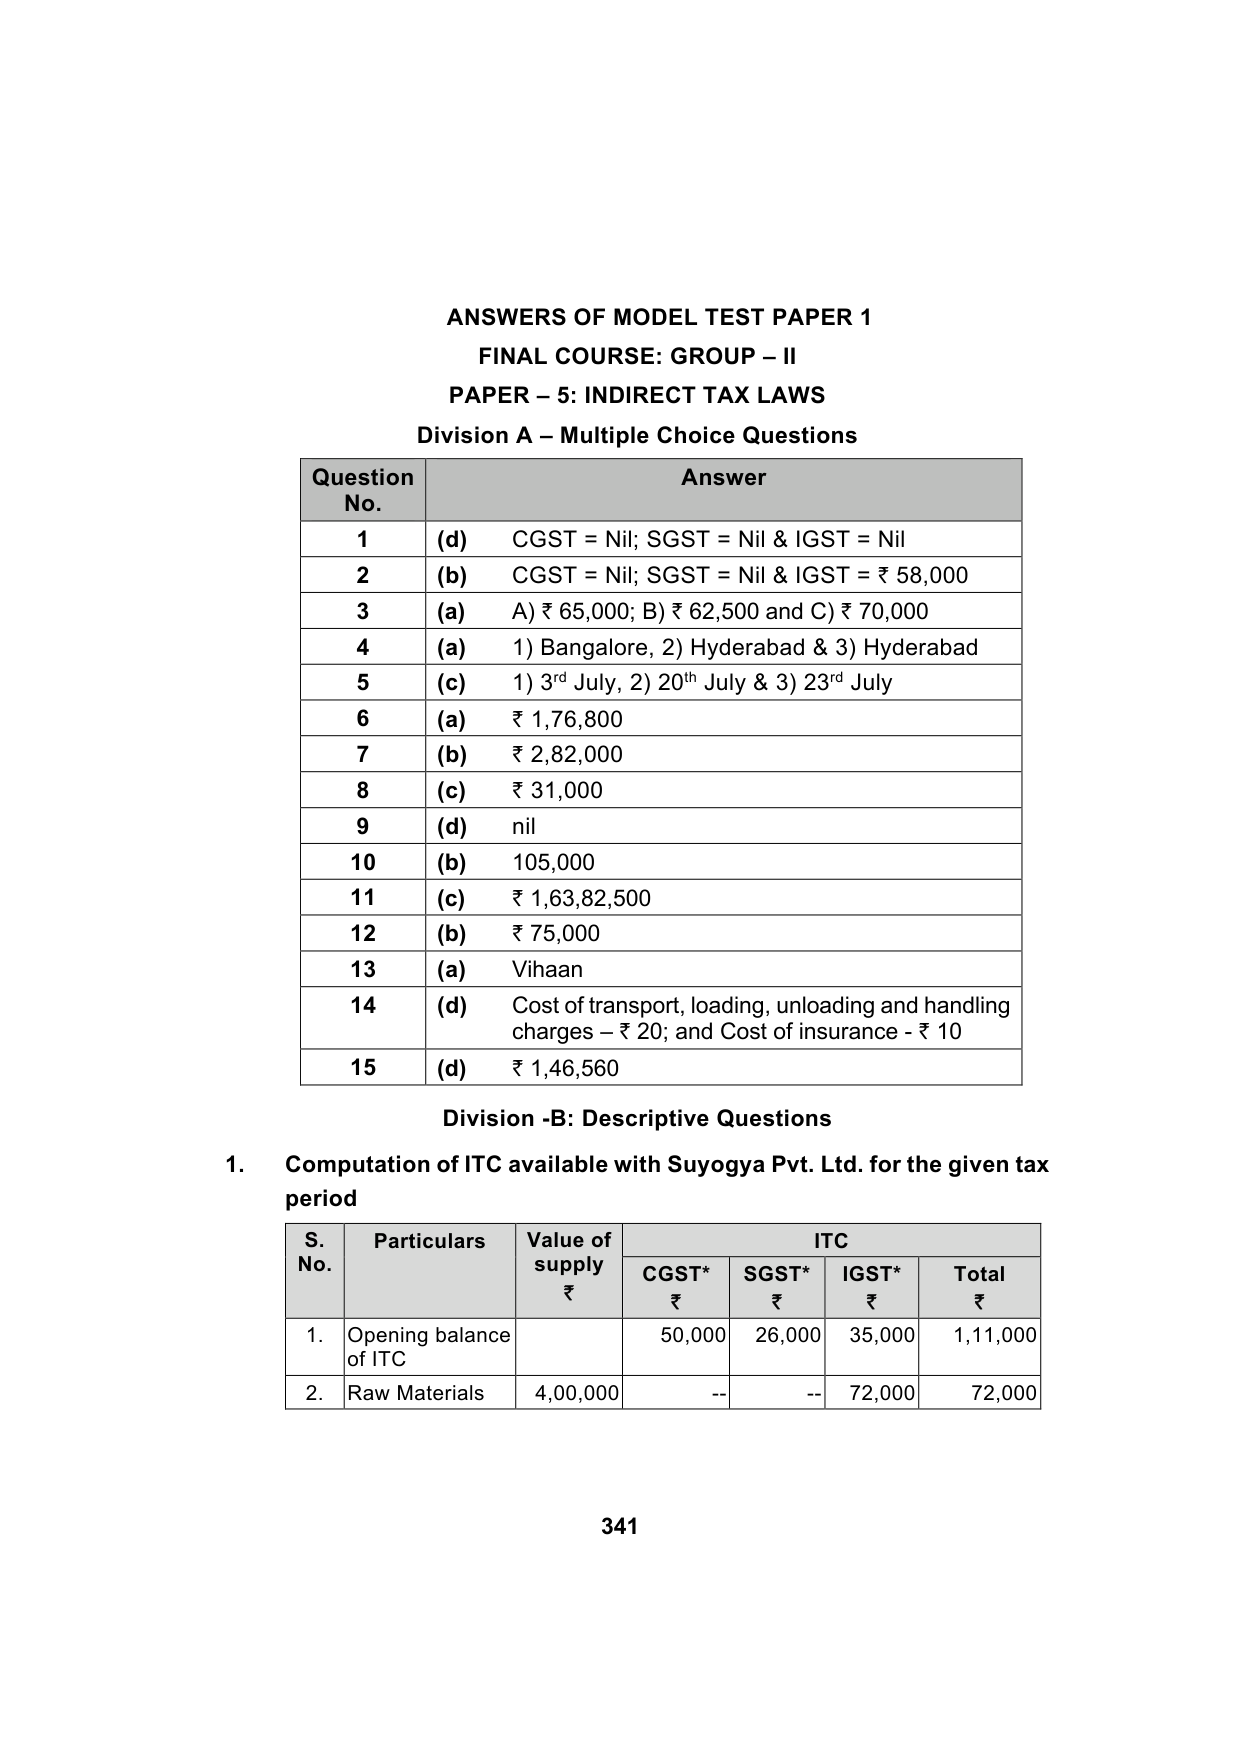
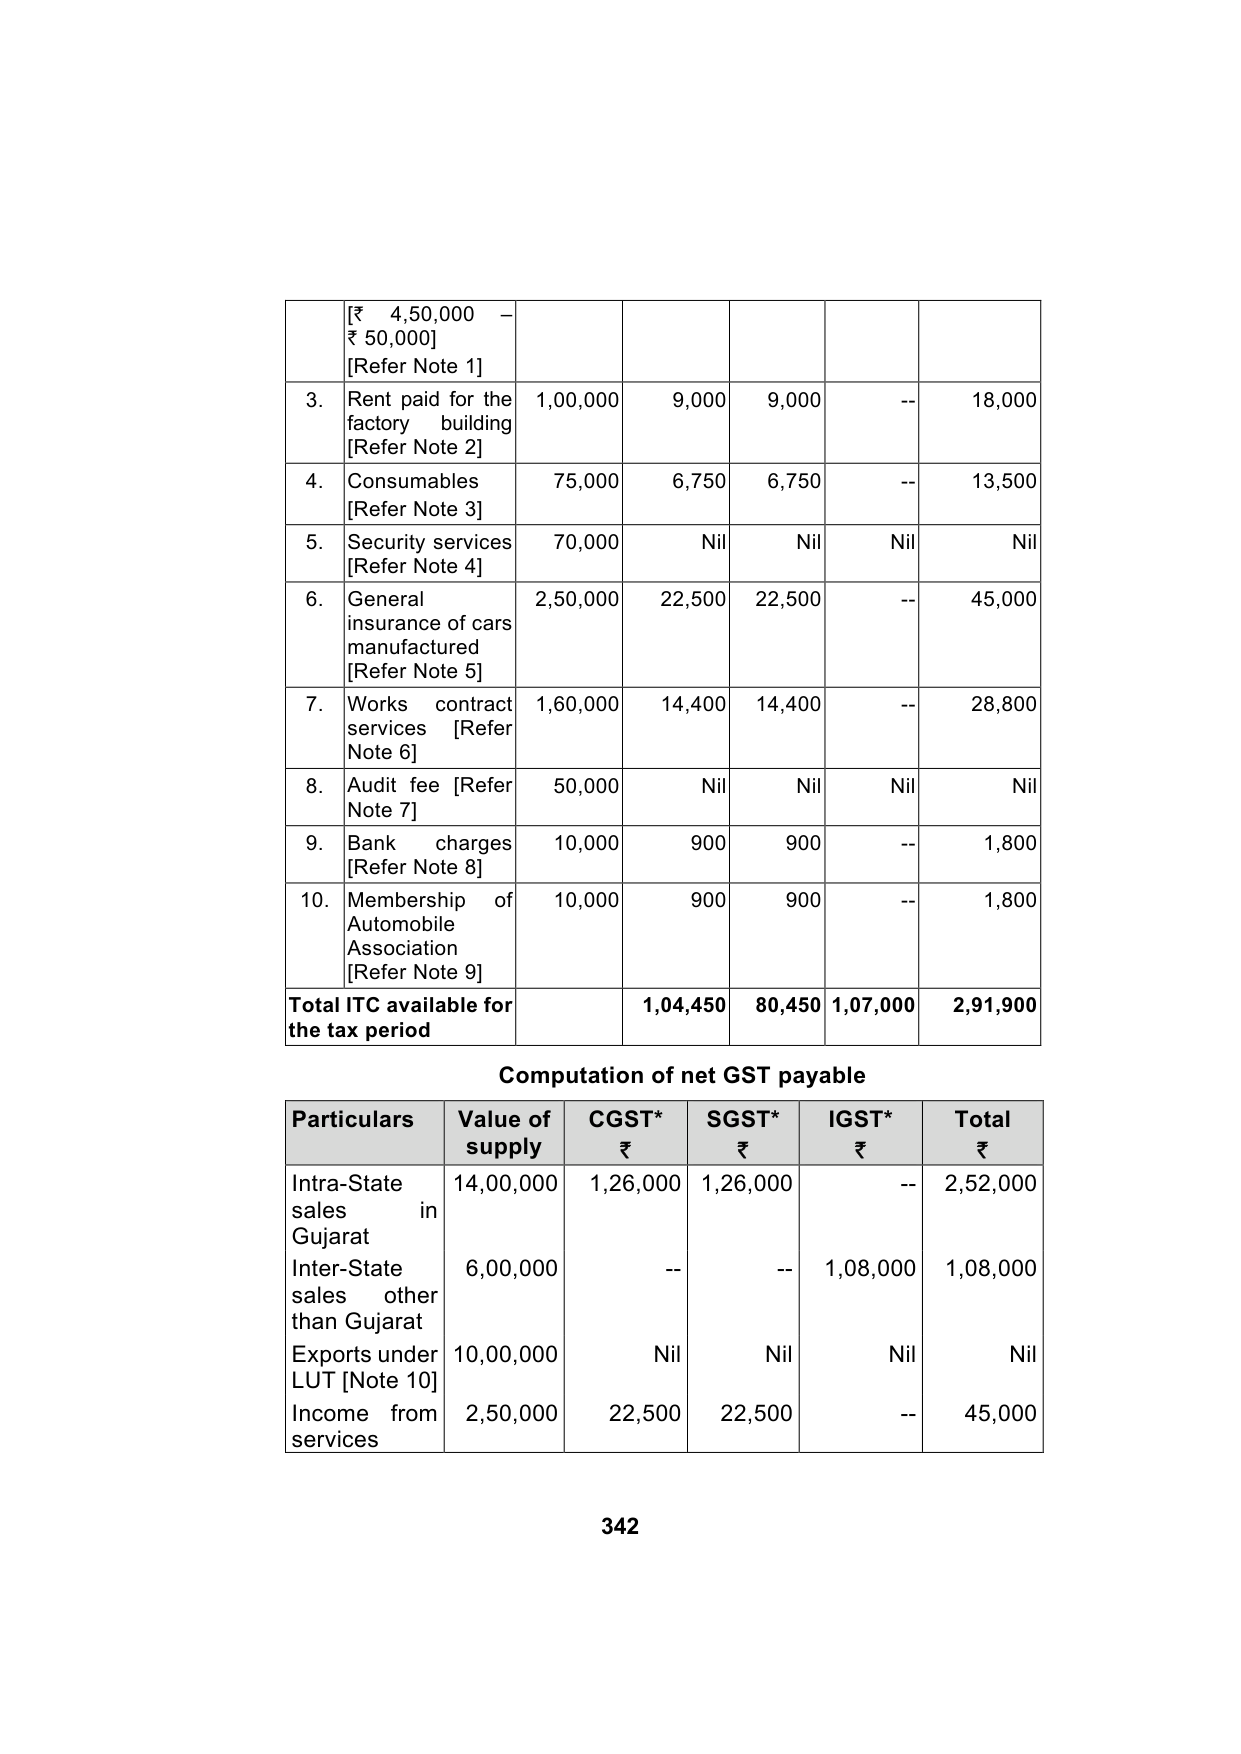
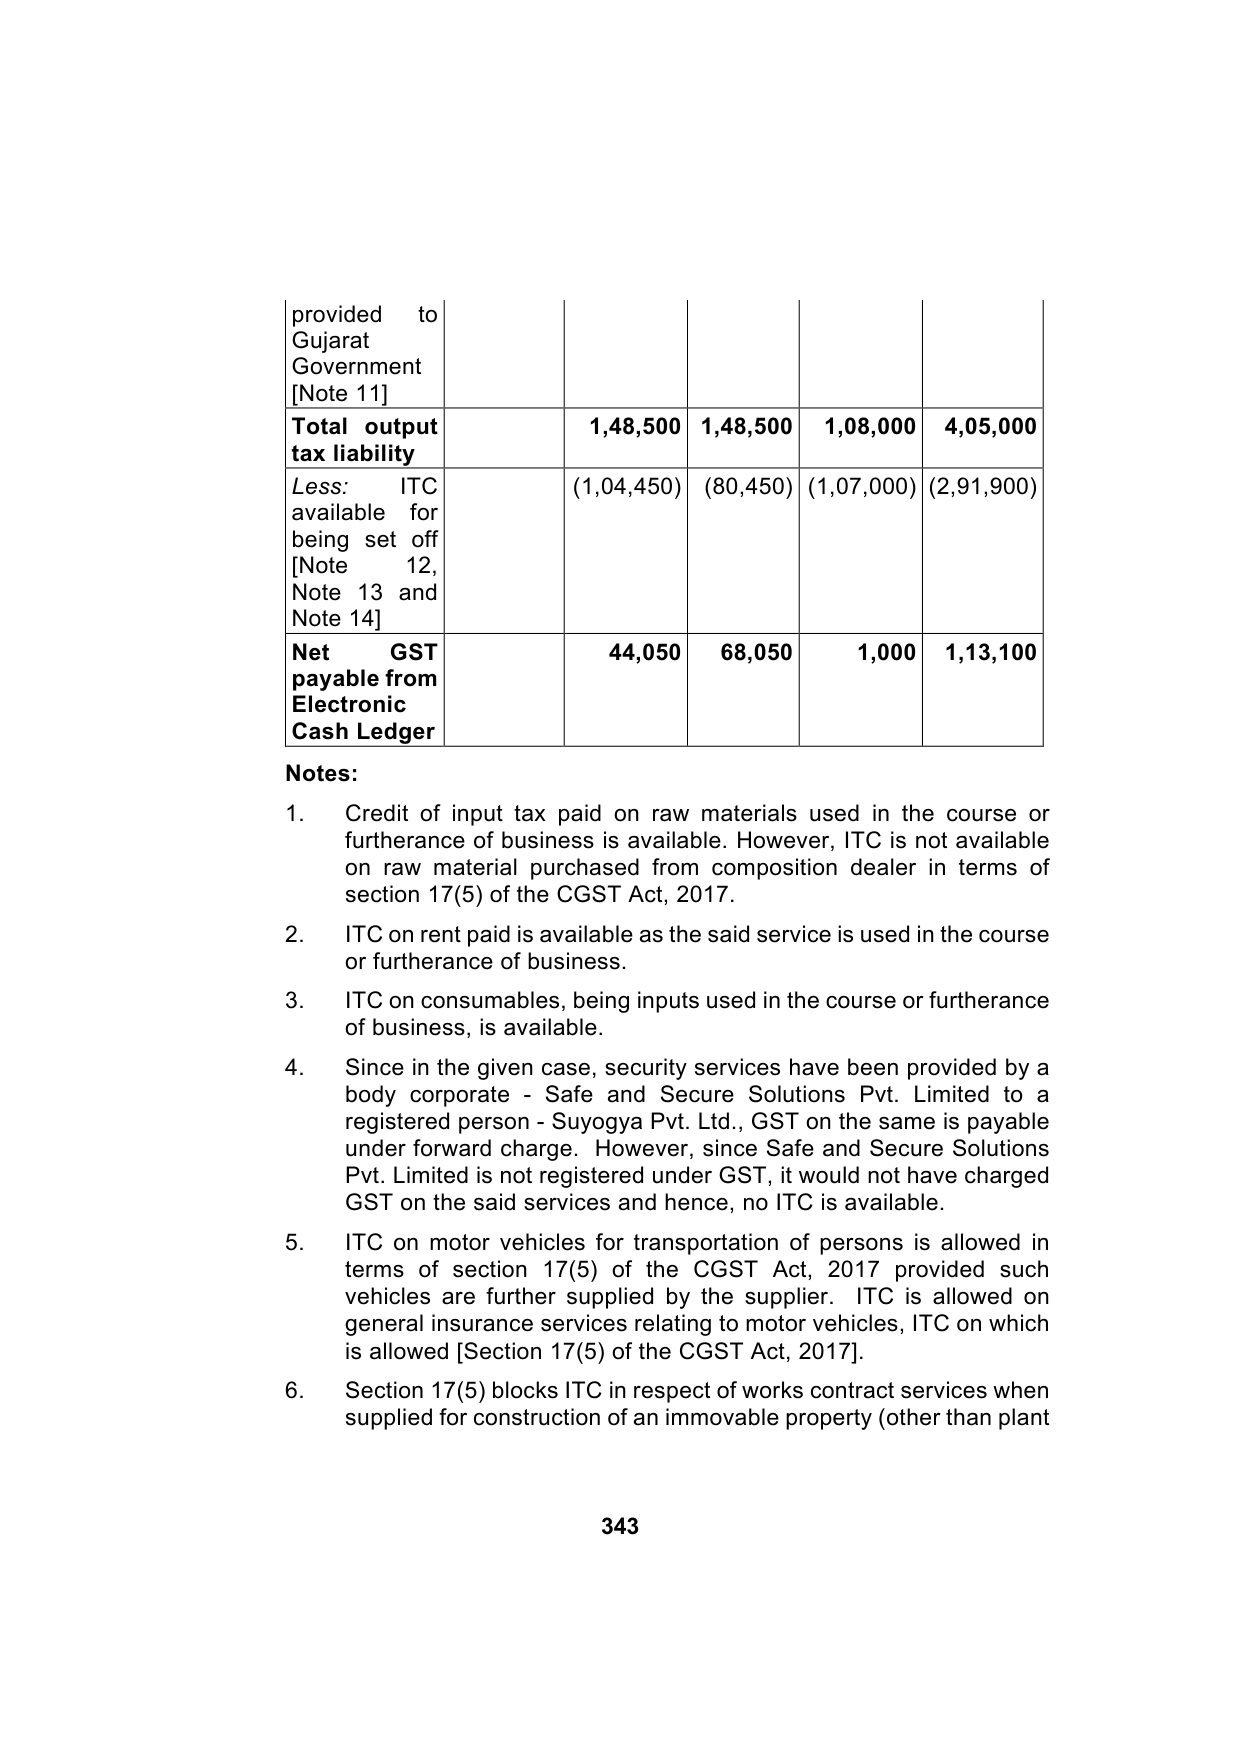
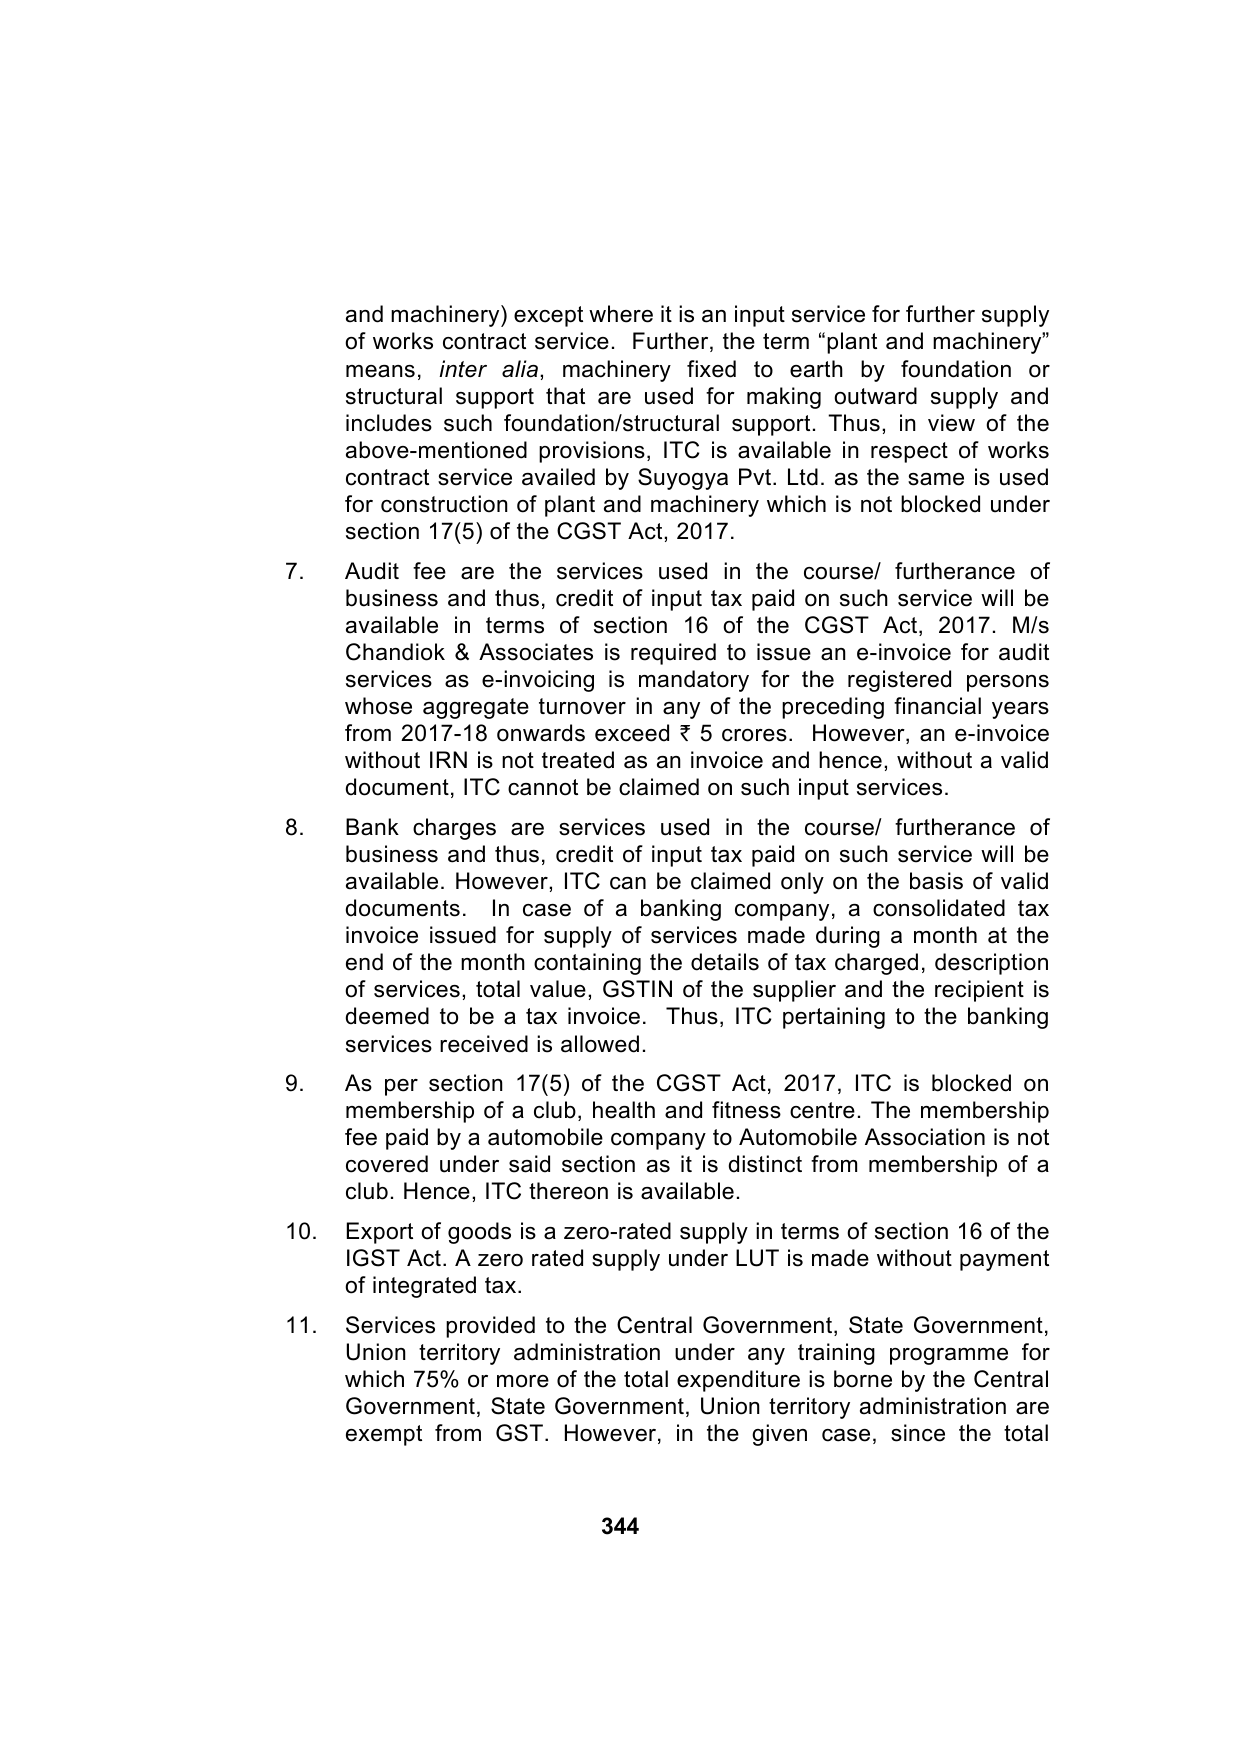
Paper 5: Indirect Tax Laws — Model Test Paper 1
Question
Answer
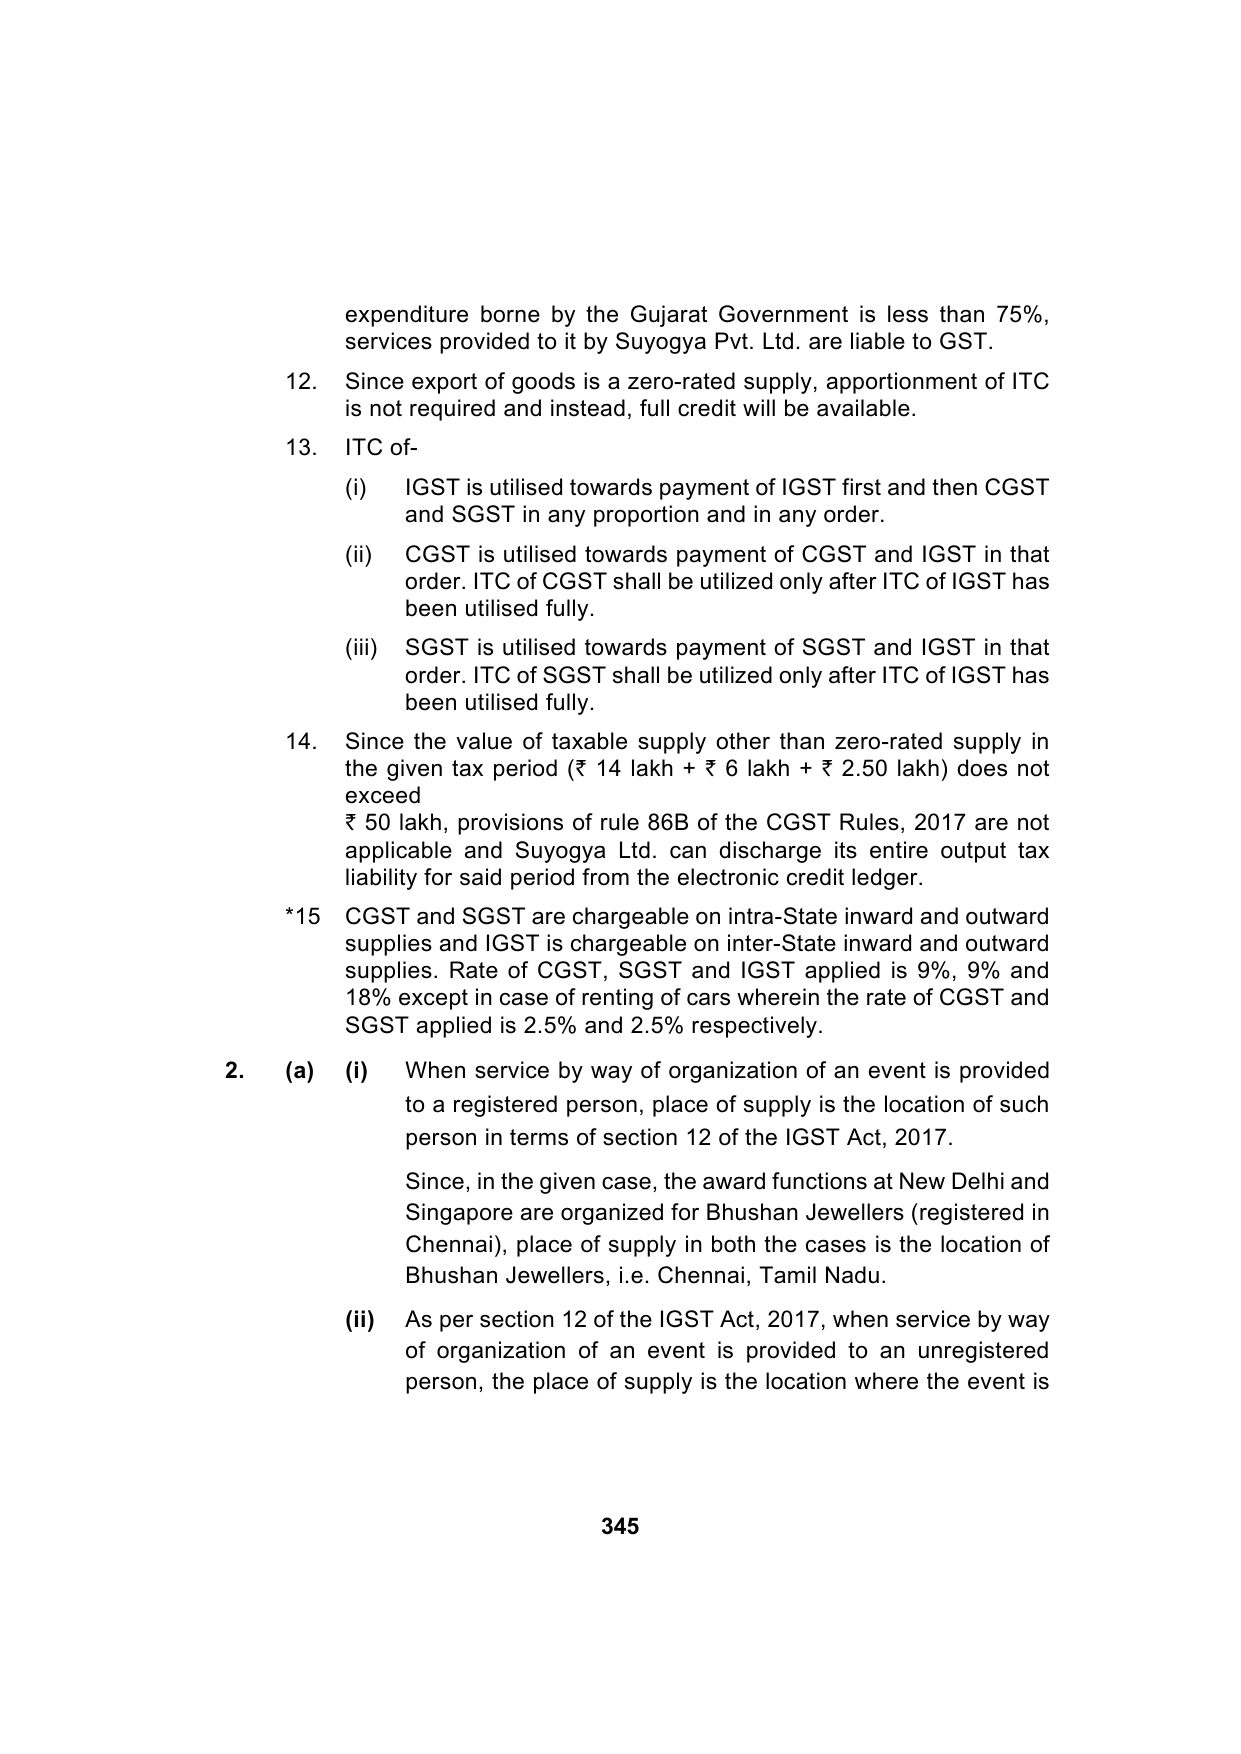
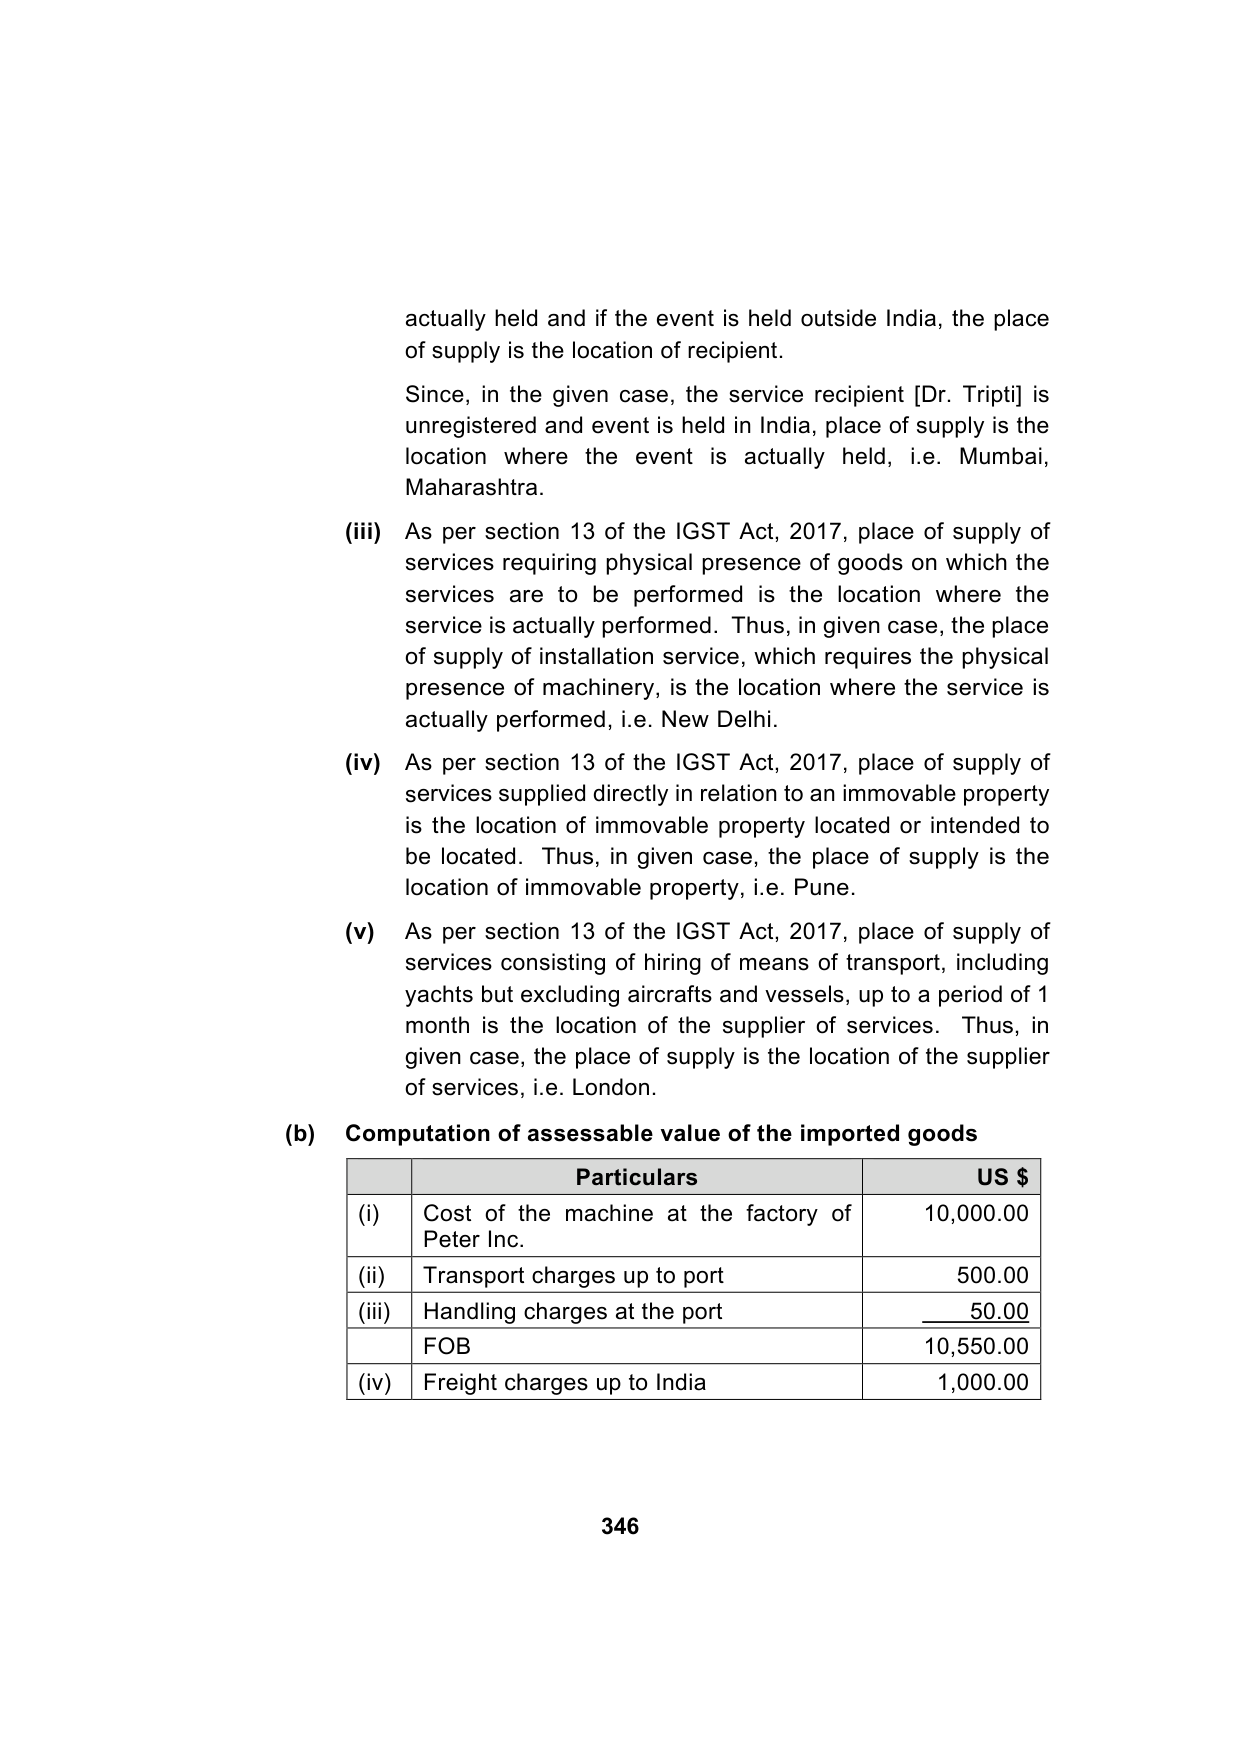
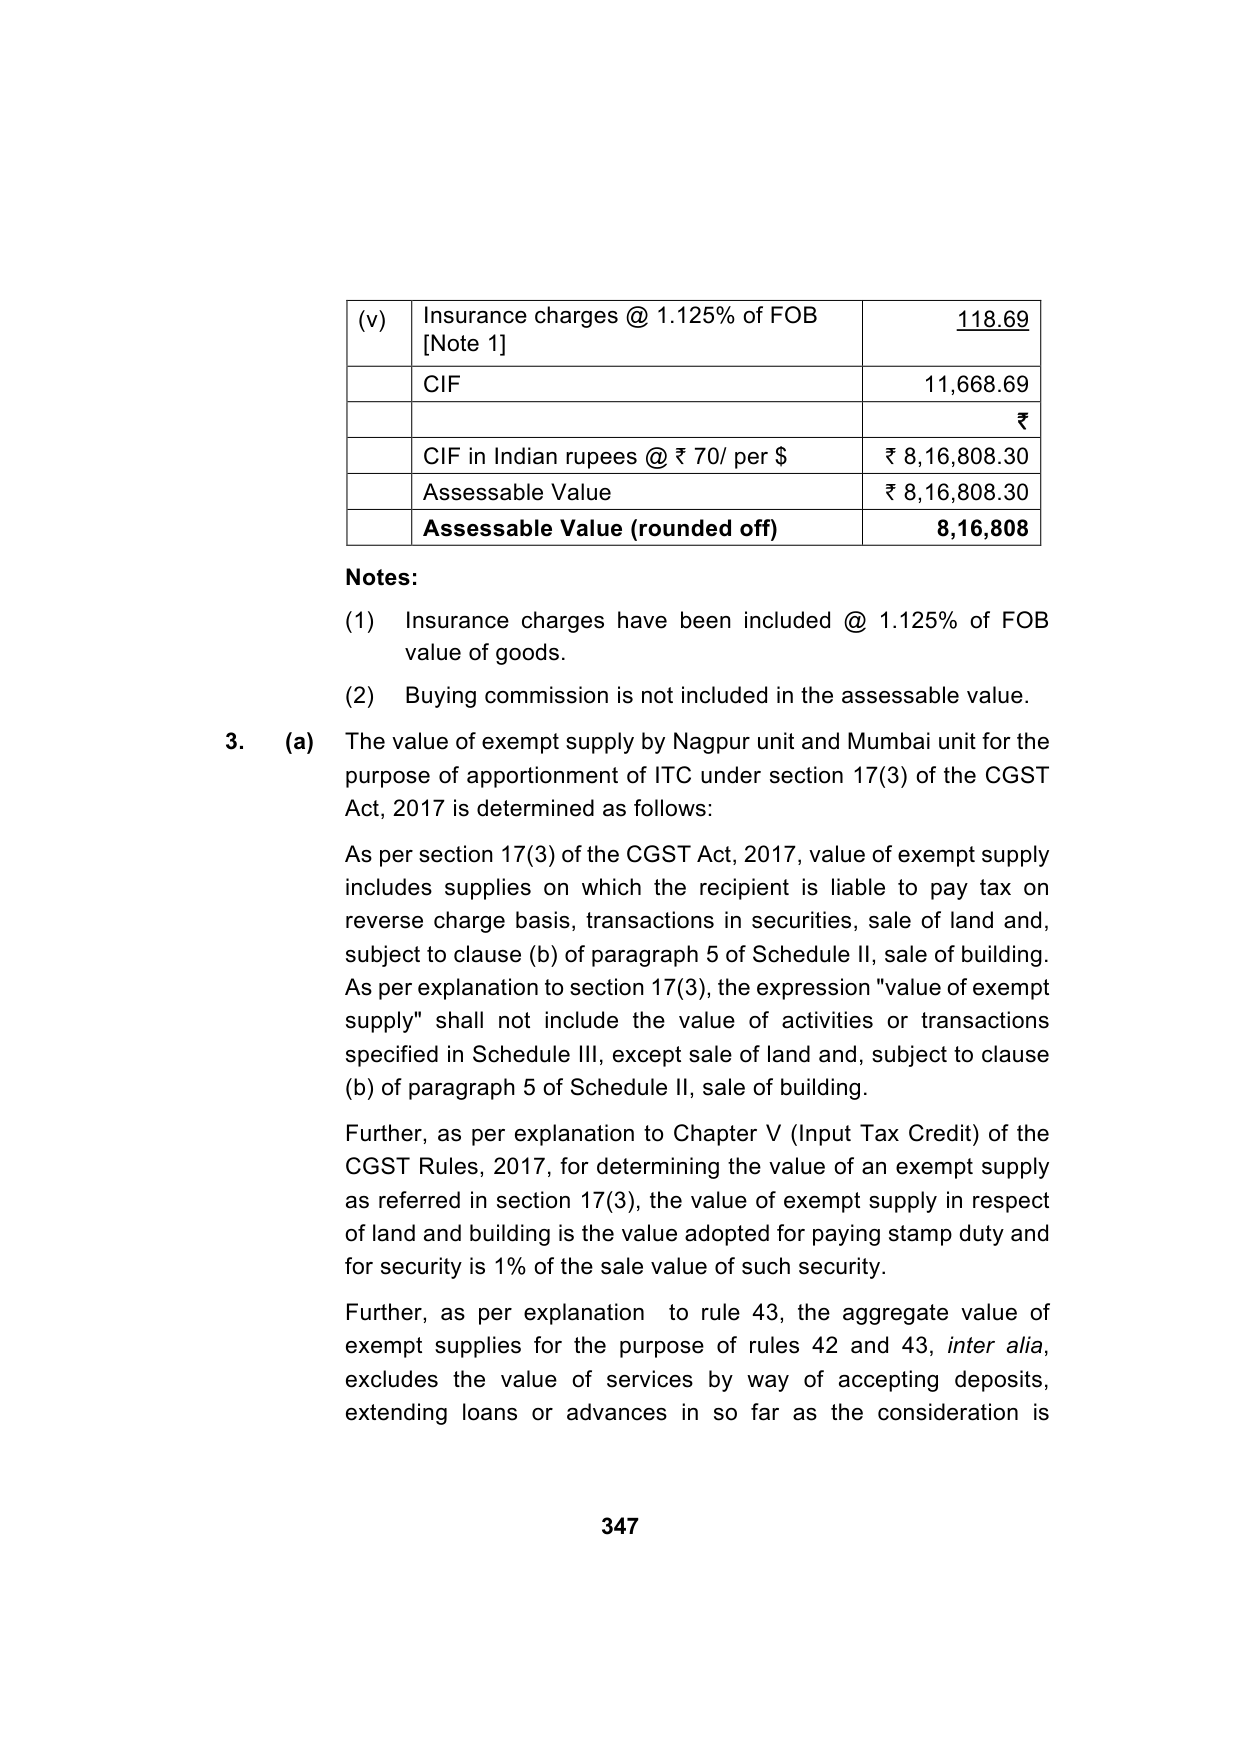
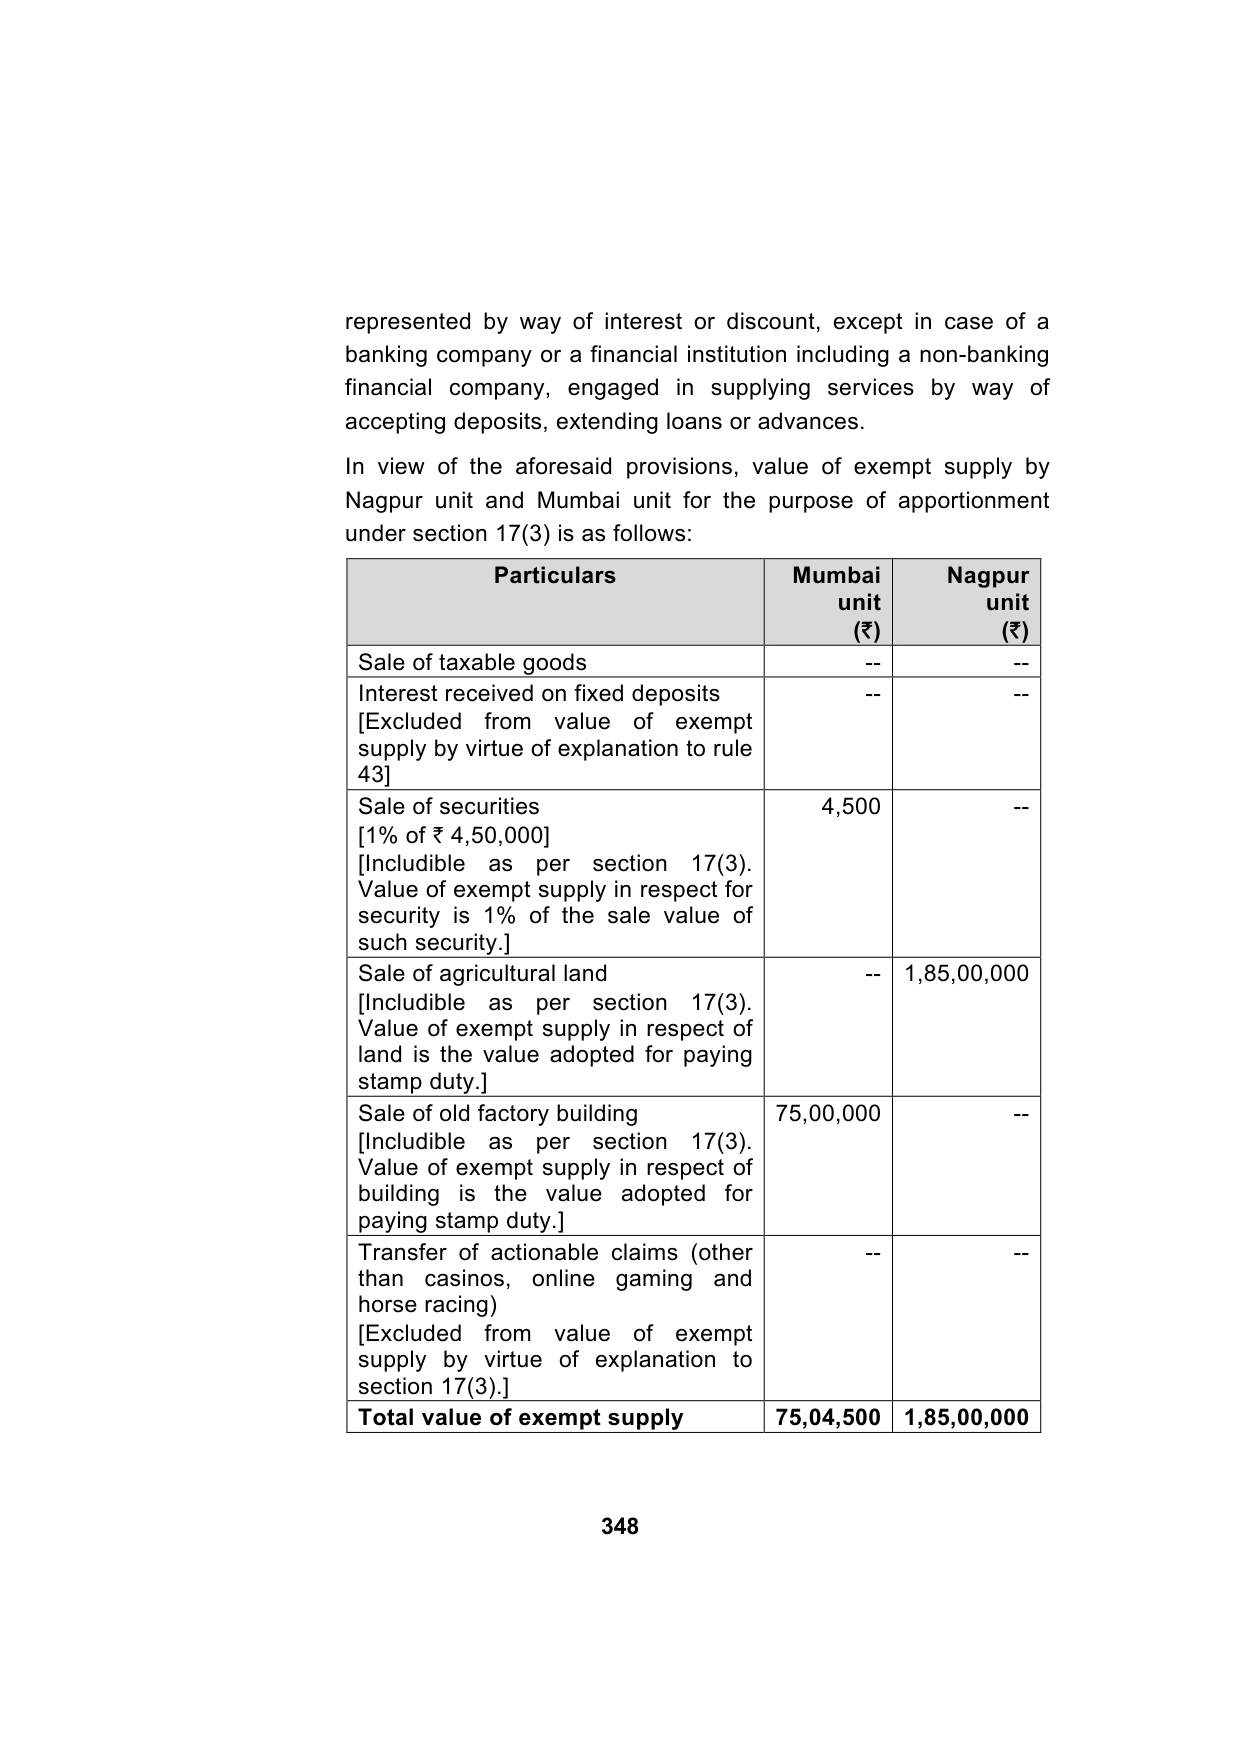
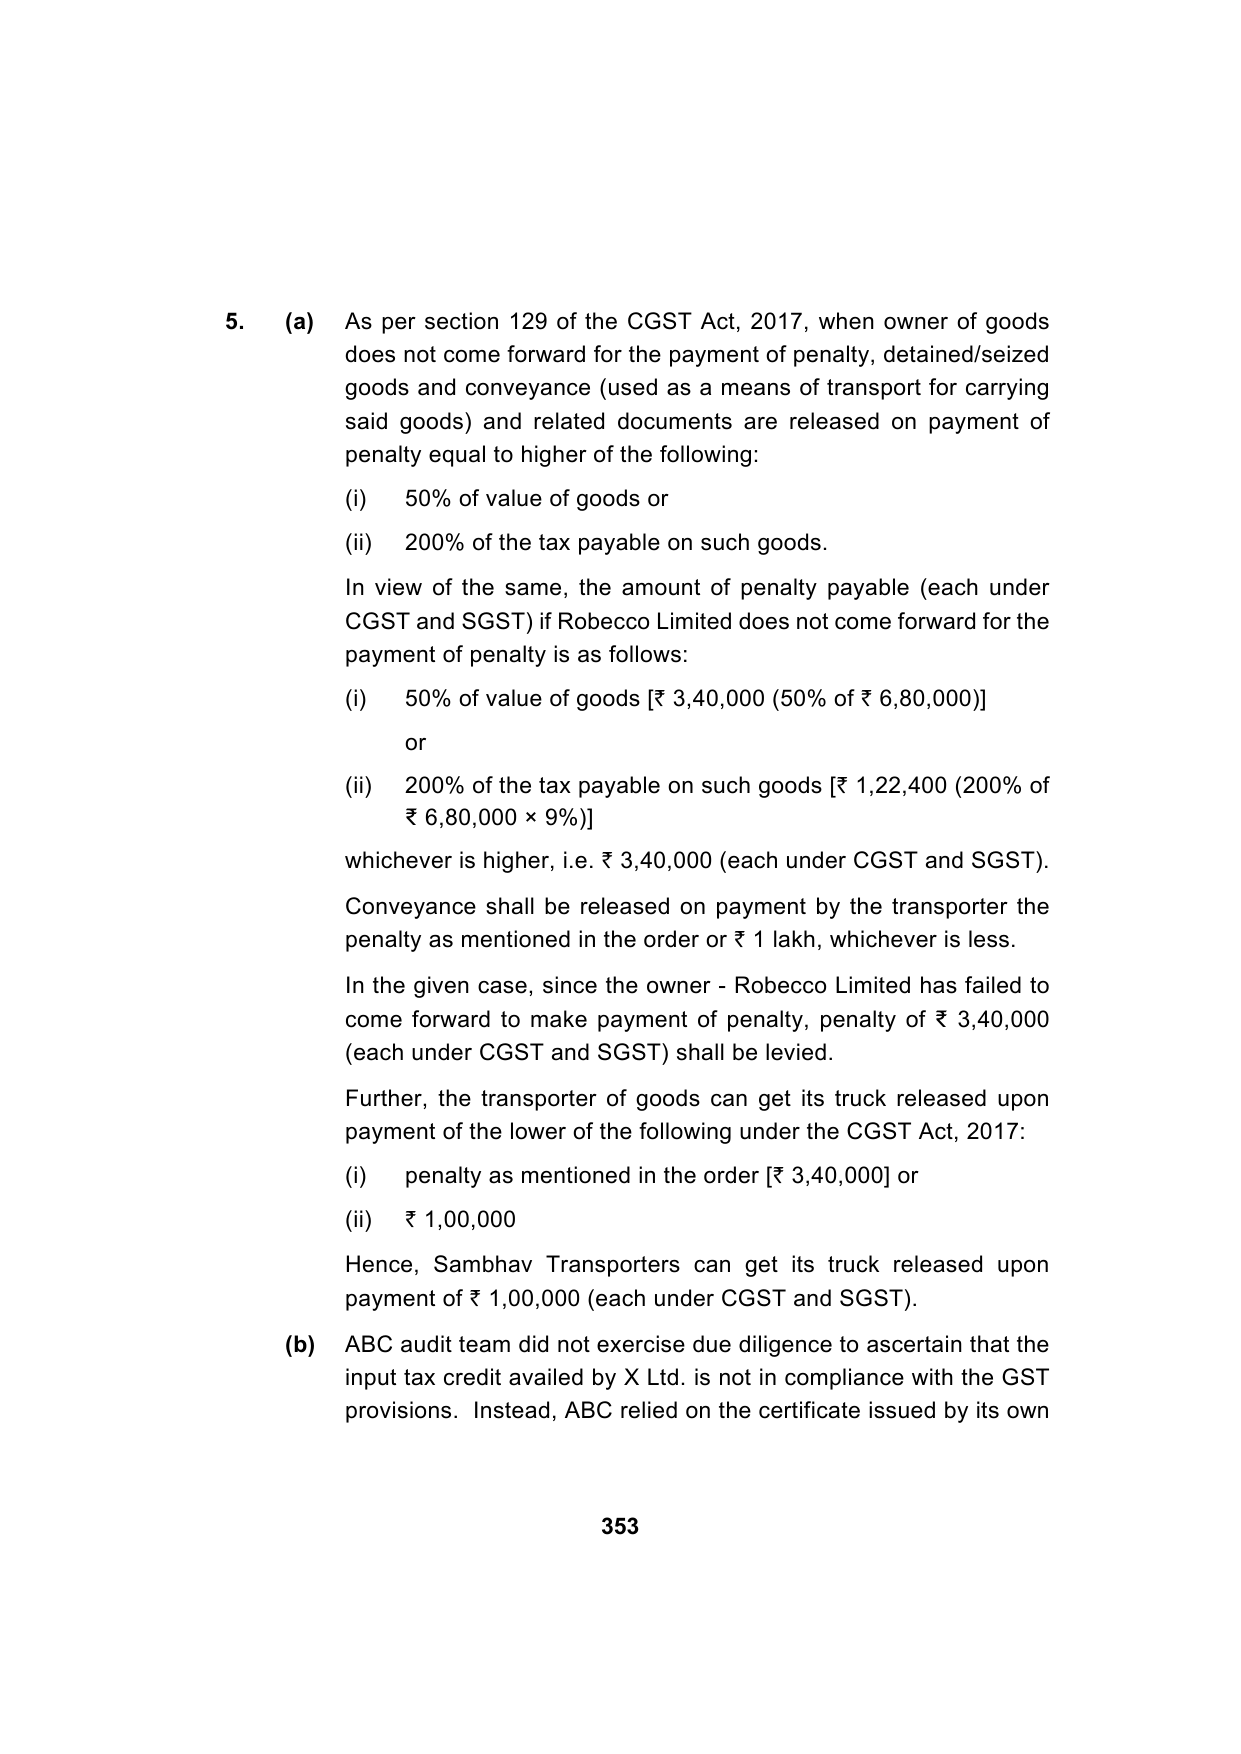
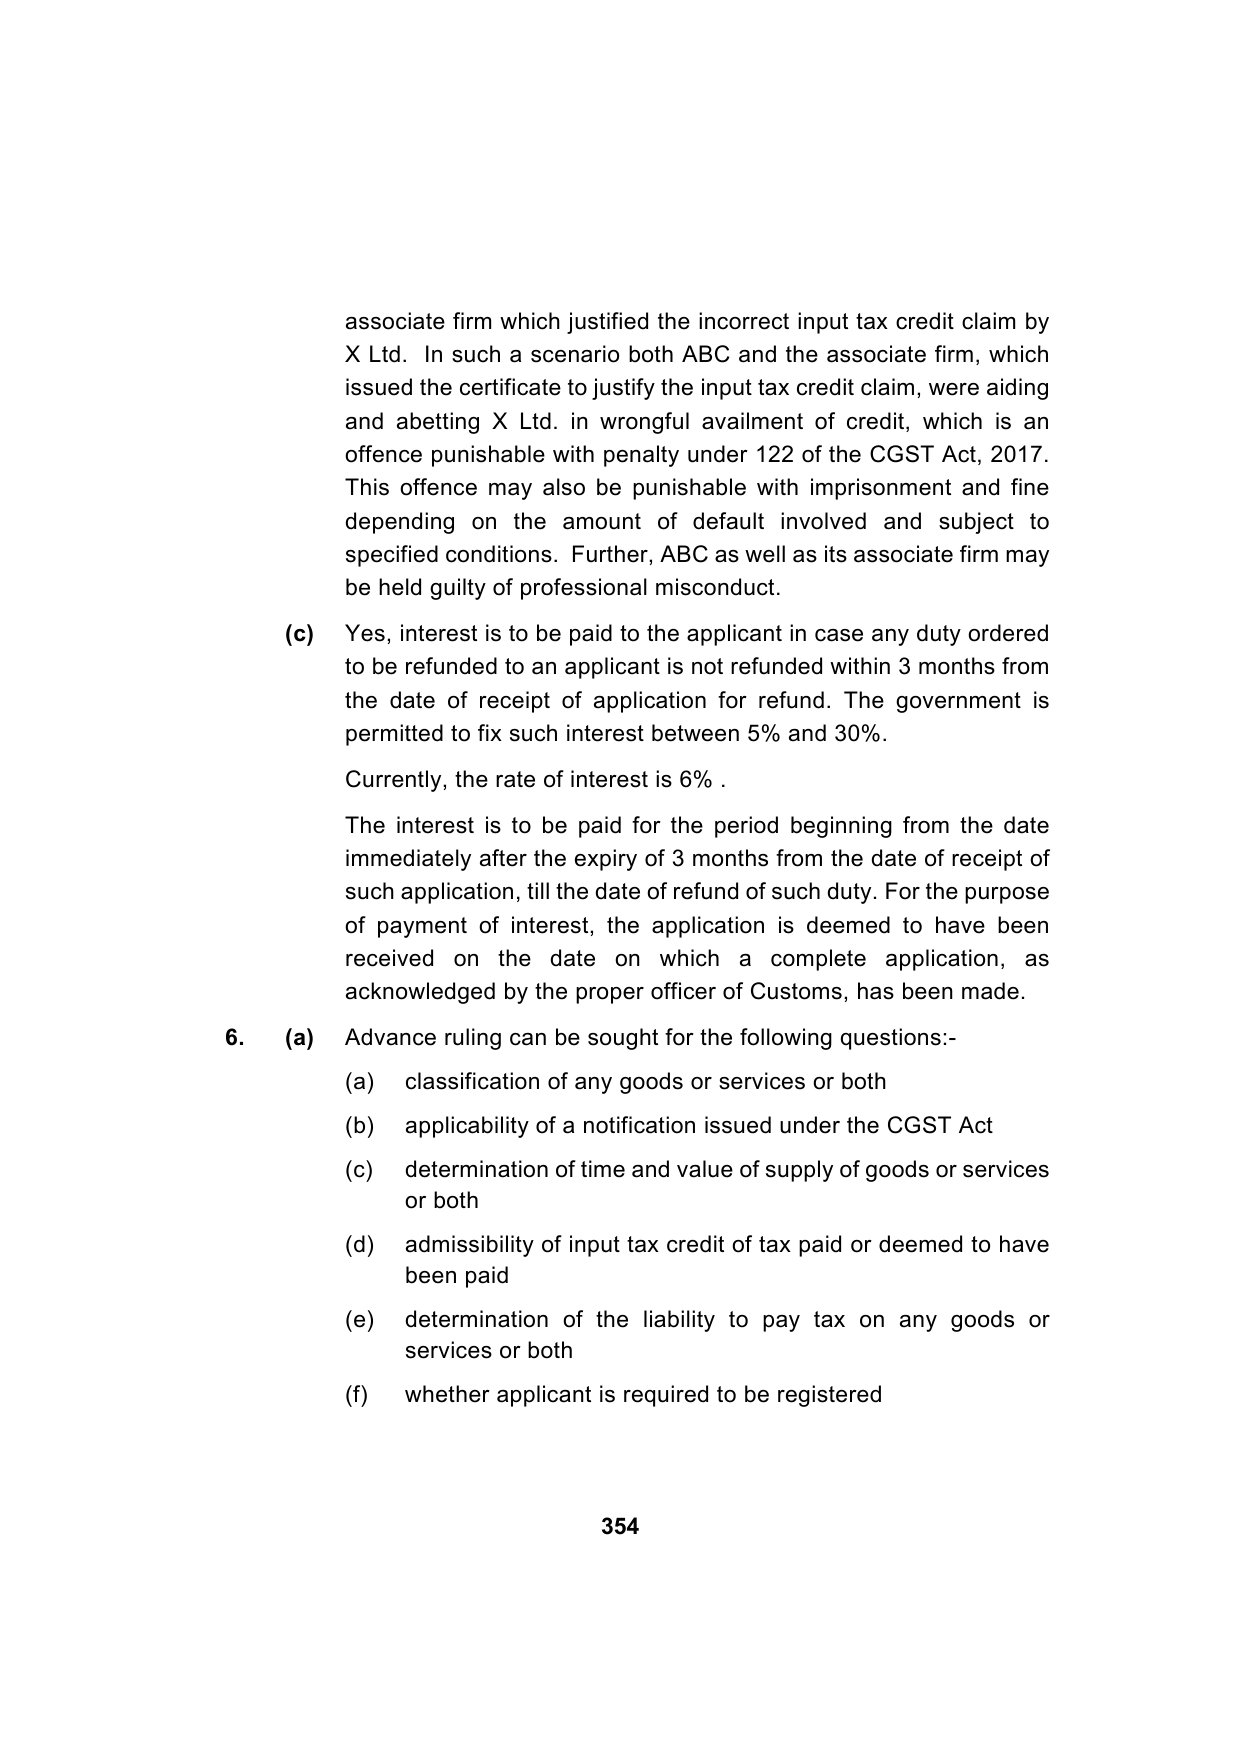
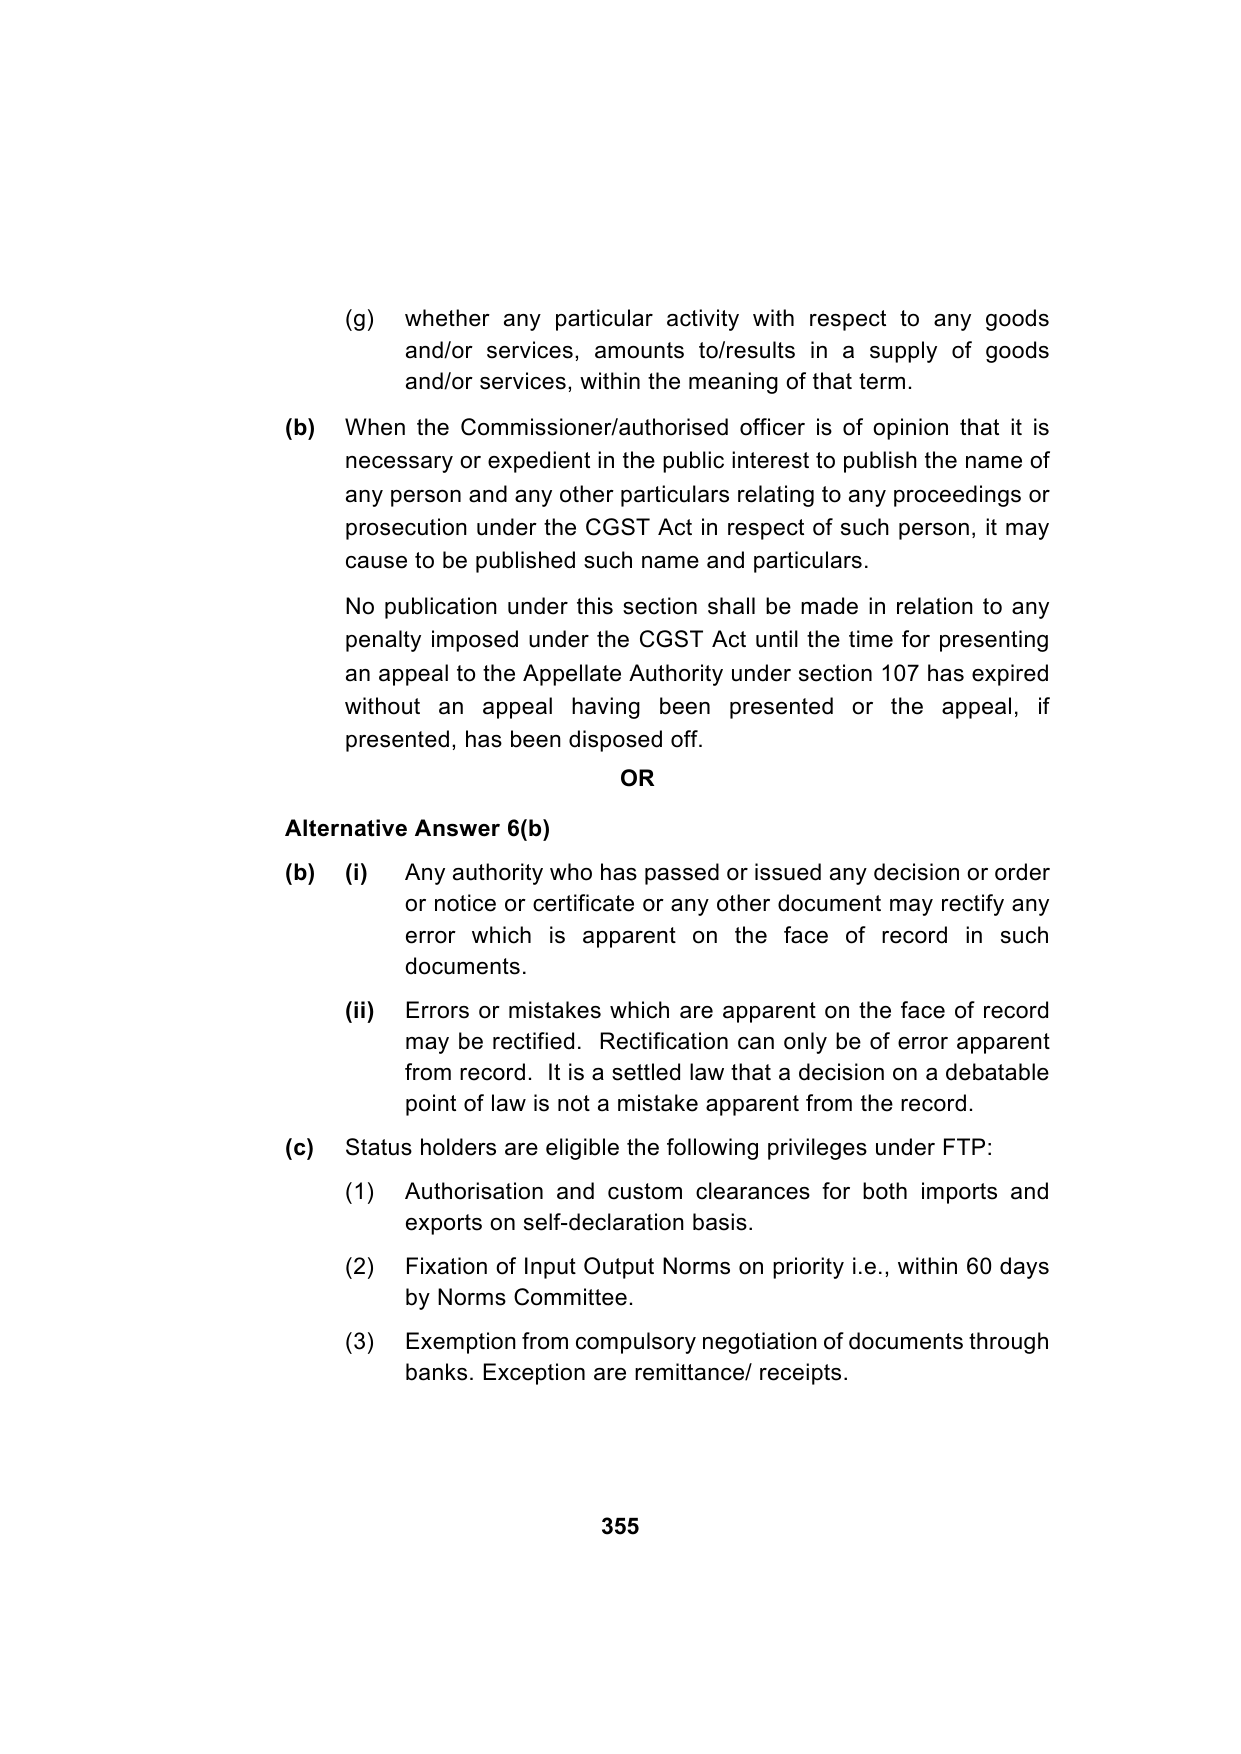
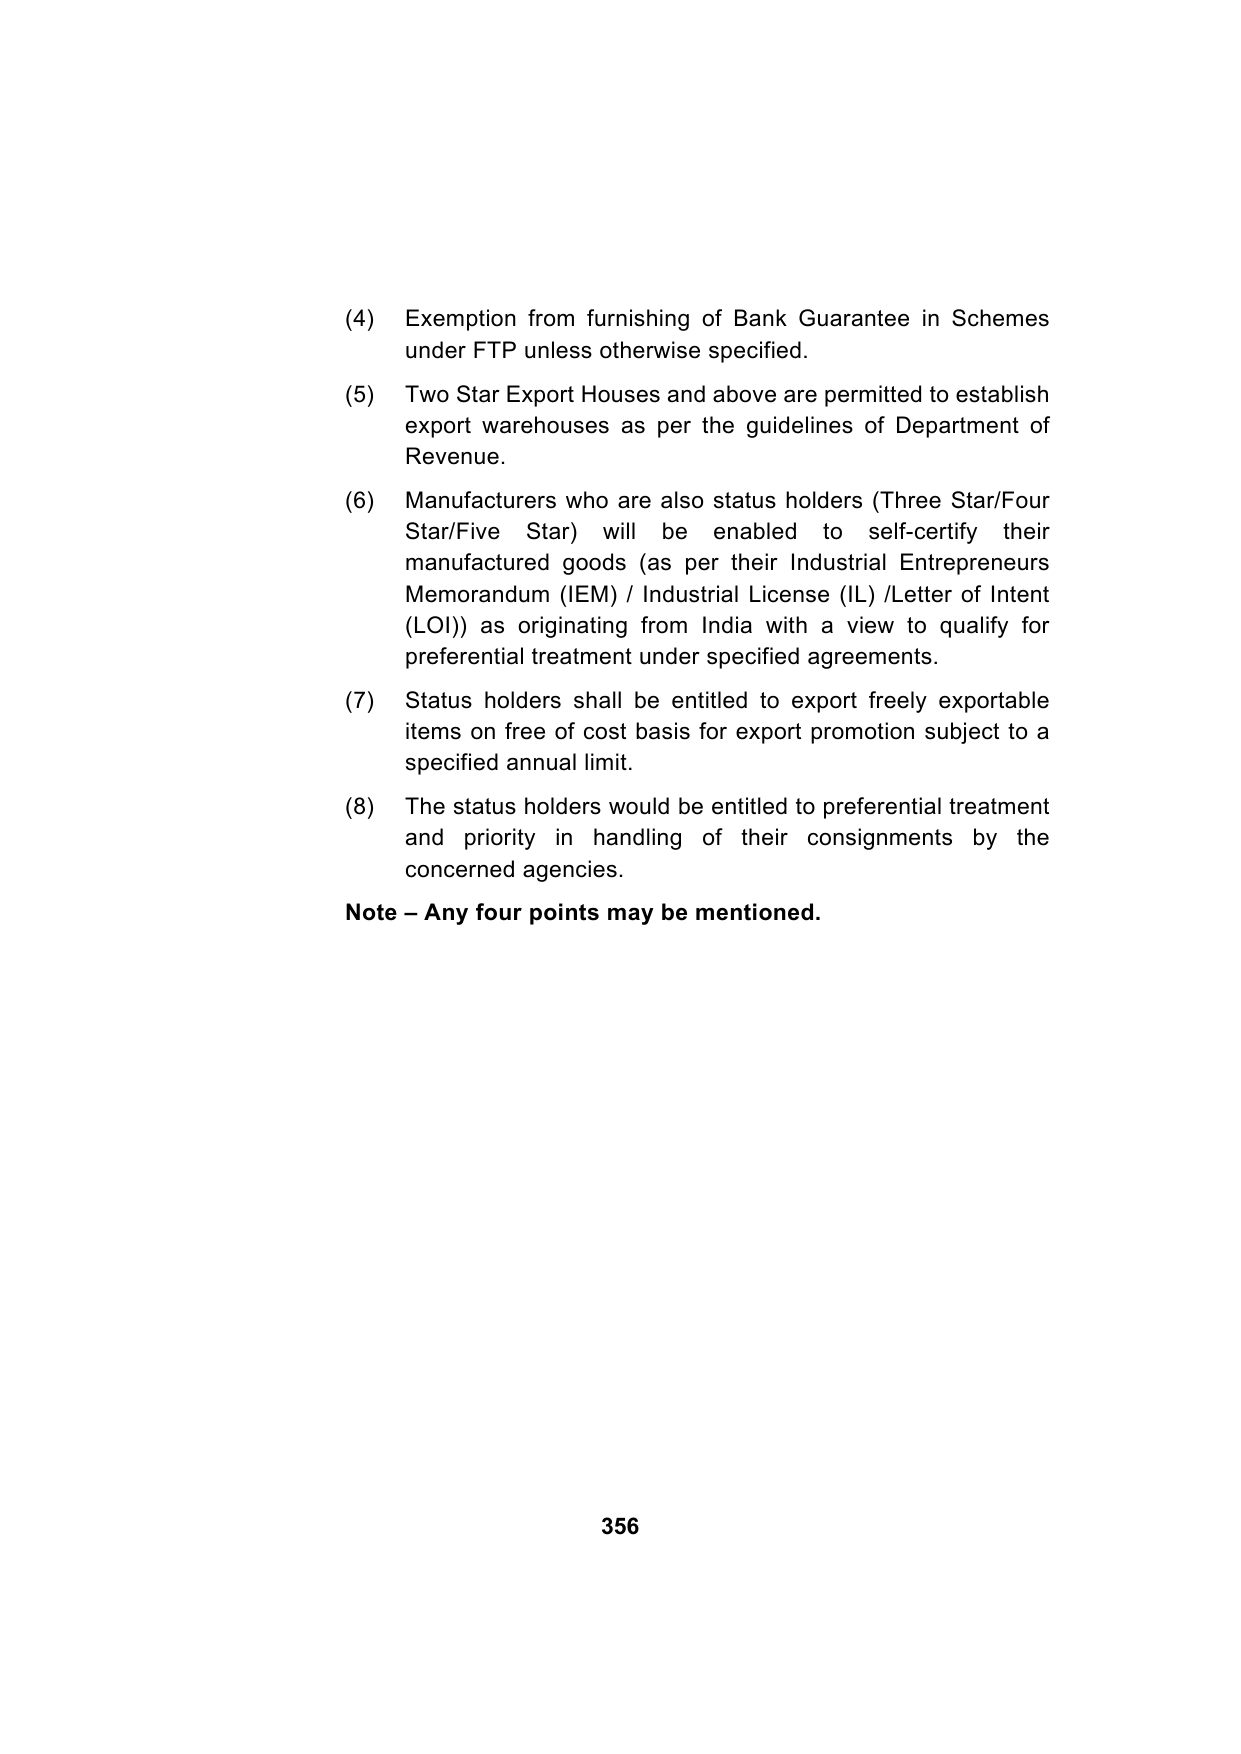
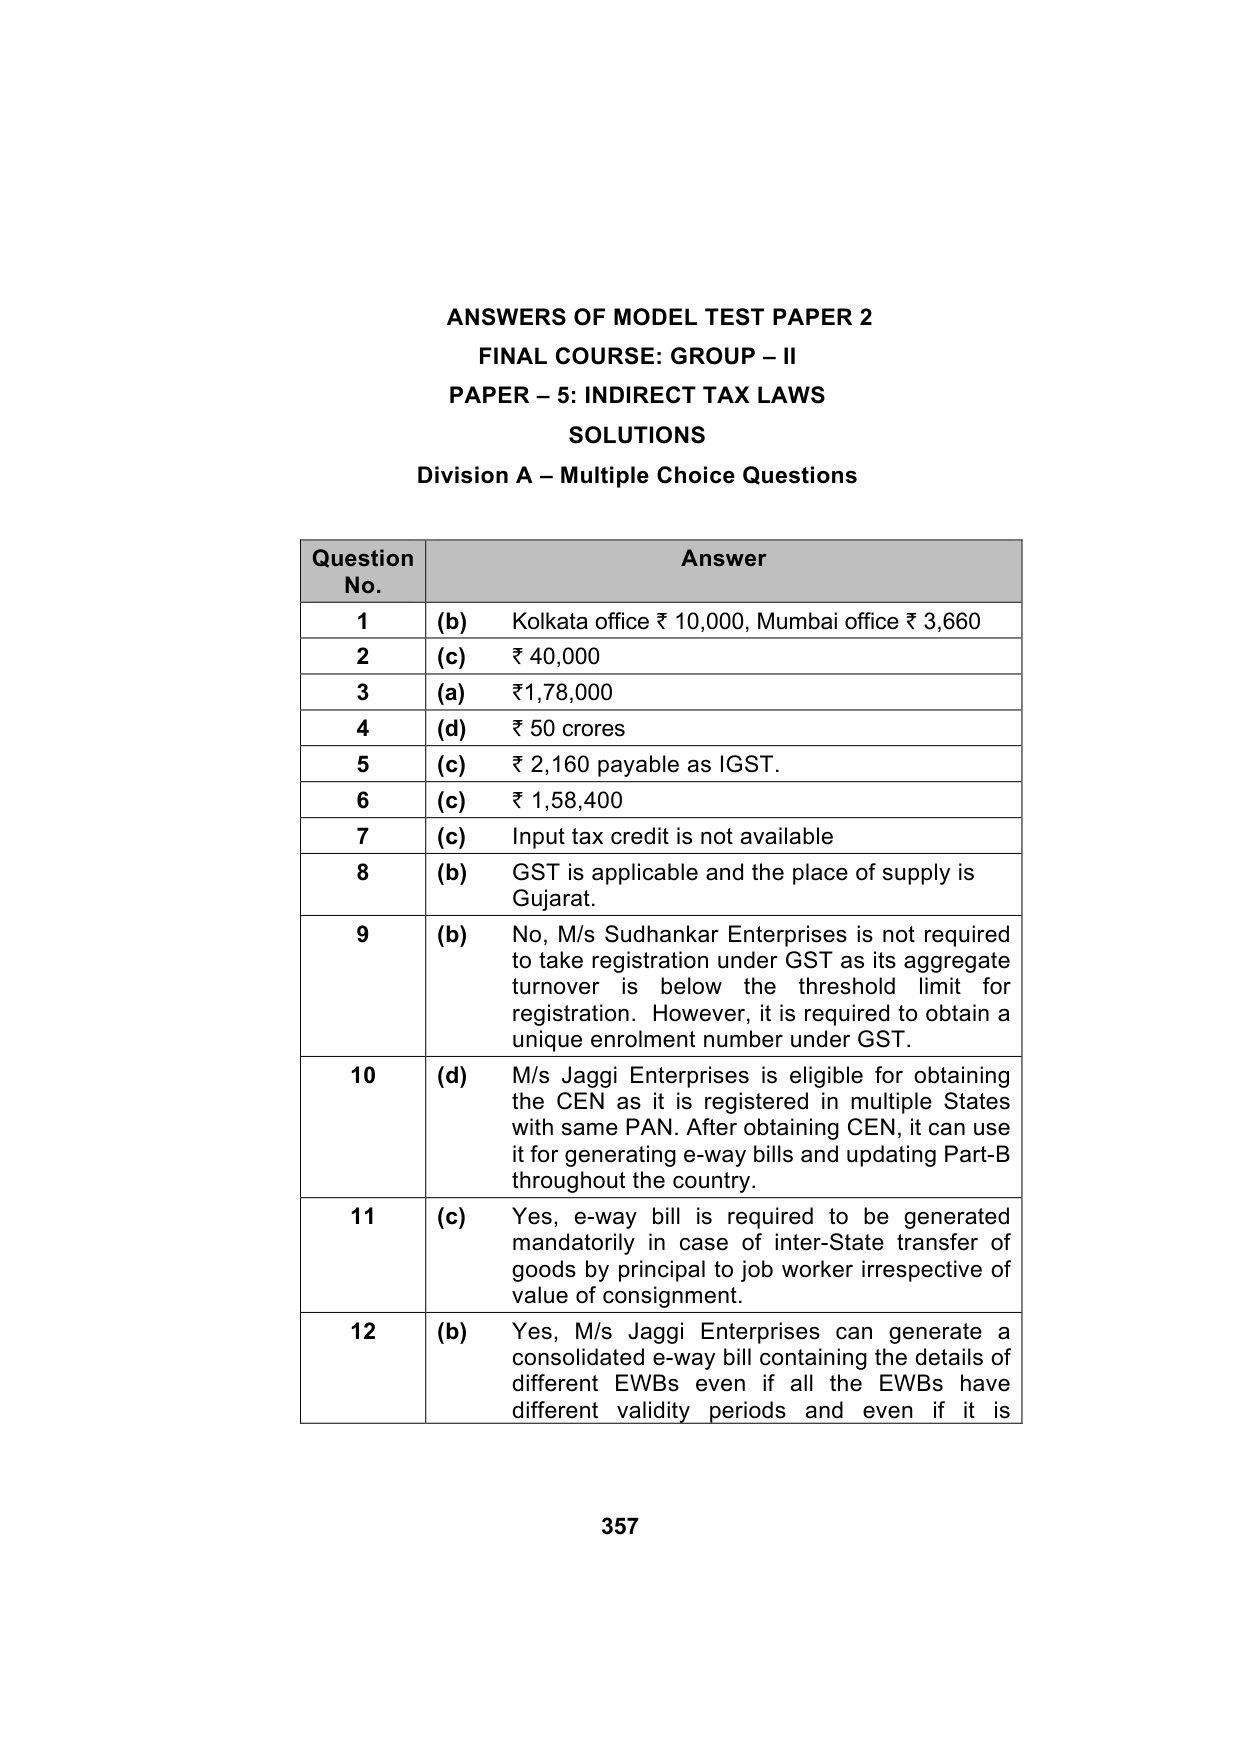
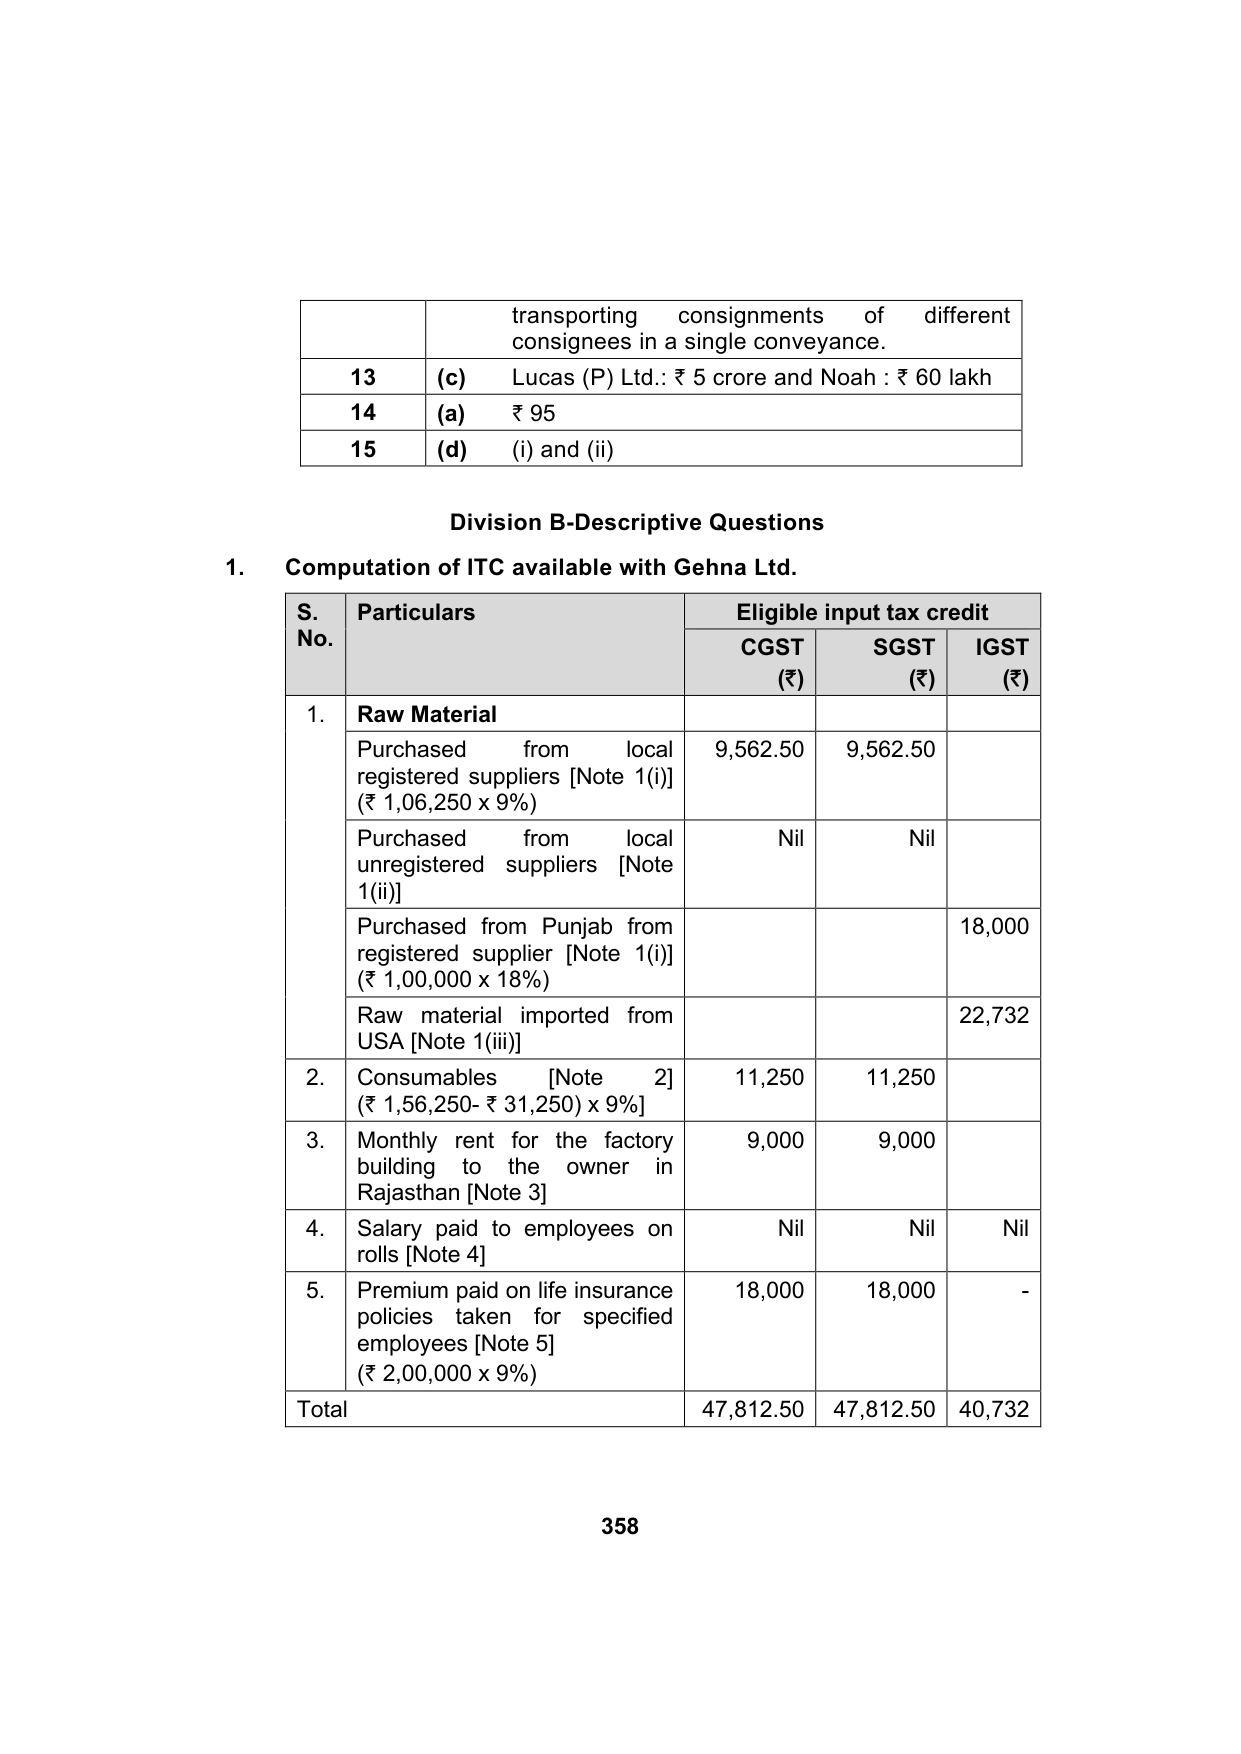
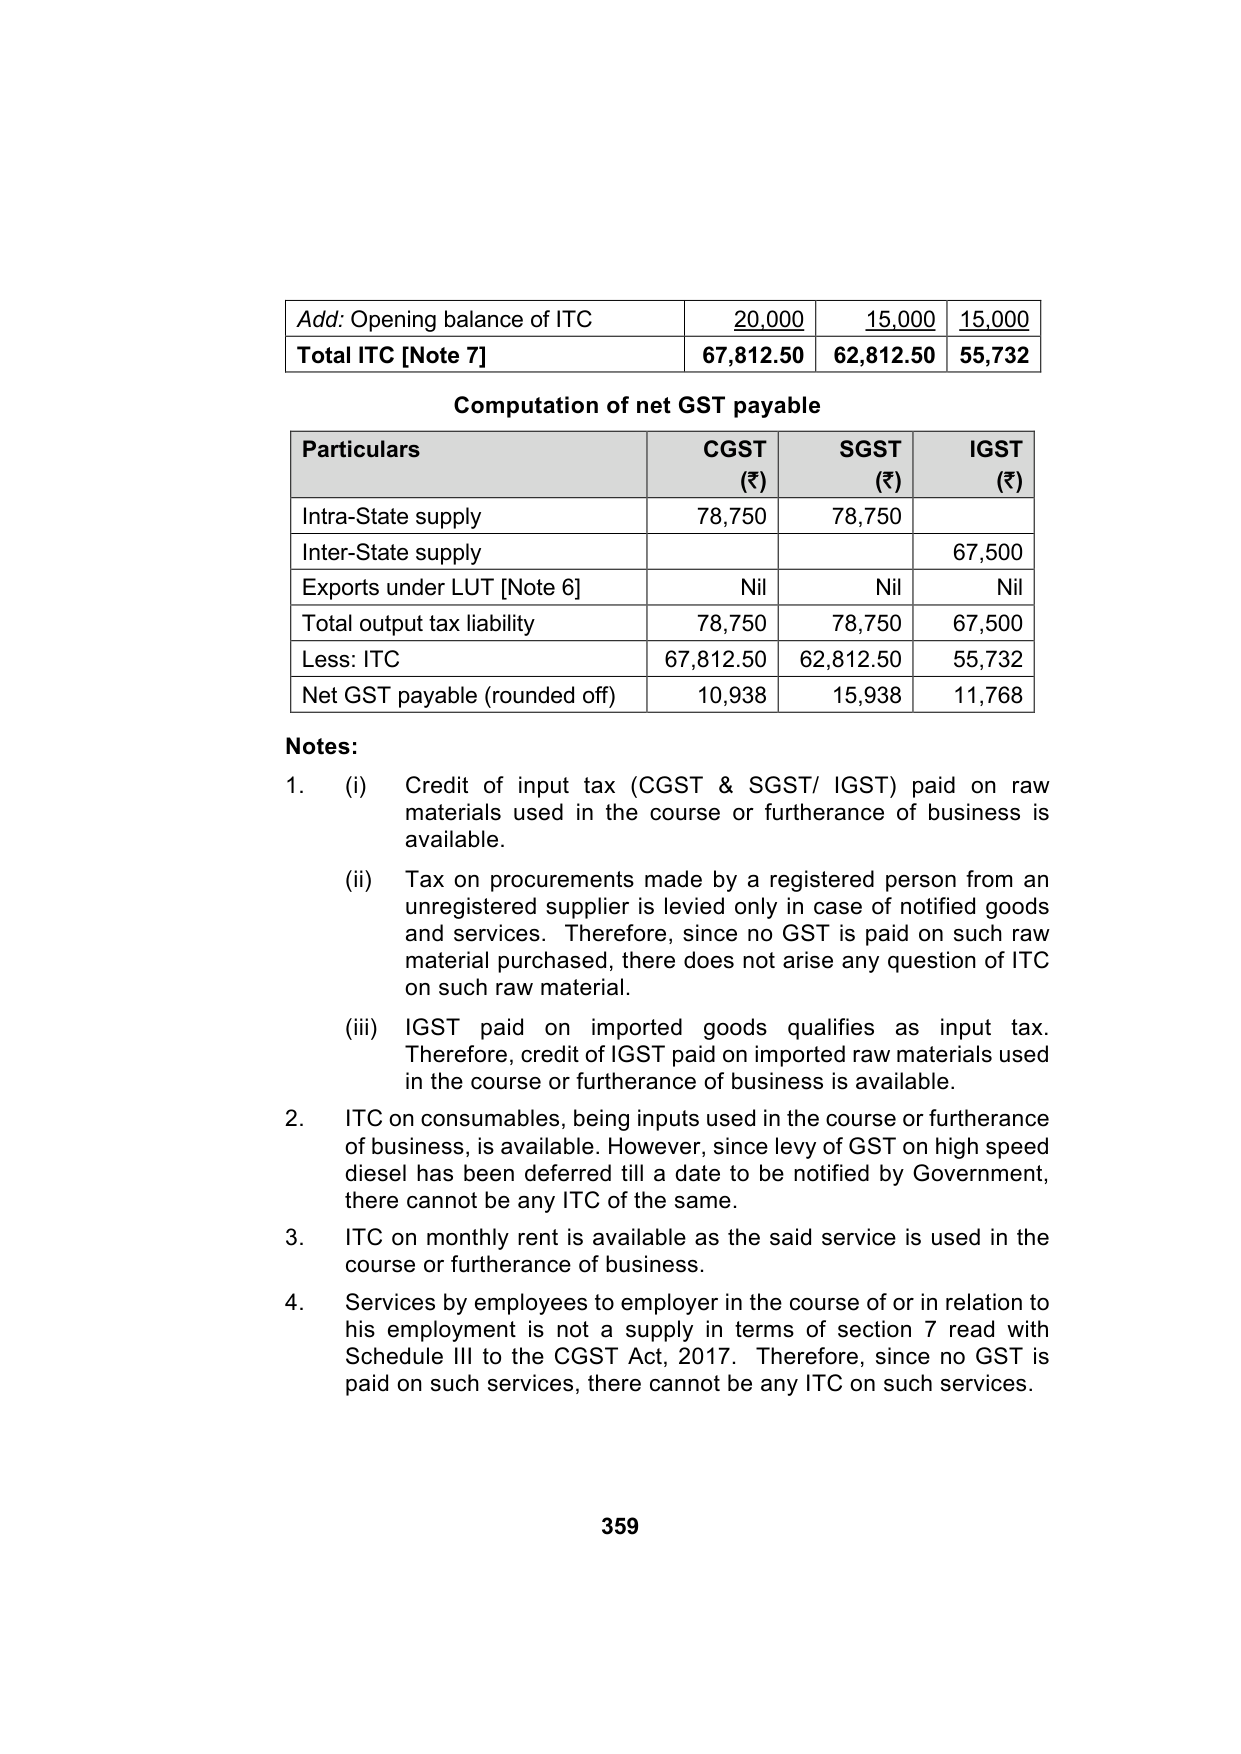
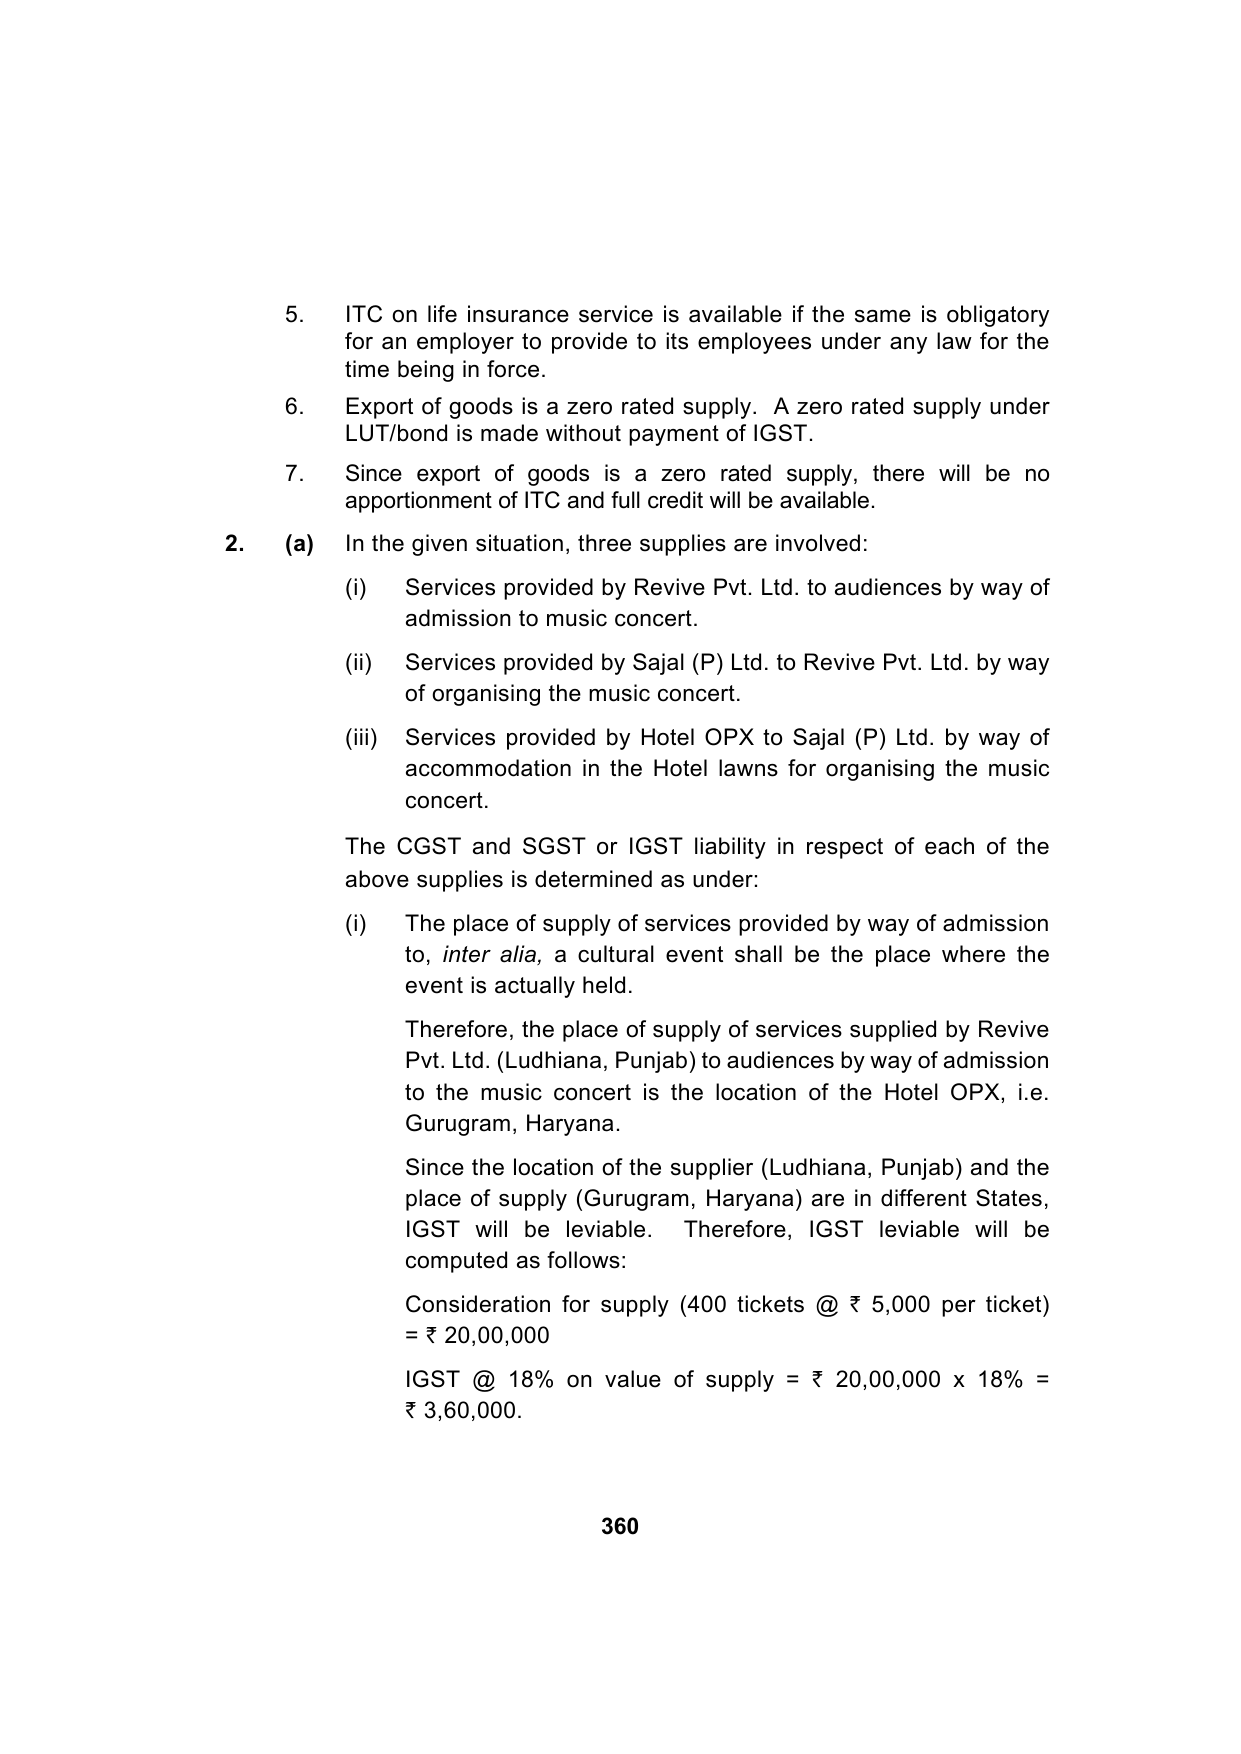
Paper 5: Indirect Tax Laws — Model Test Paper 2 (100 marks)
Question
Answer
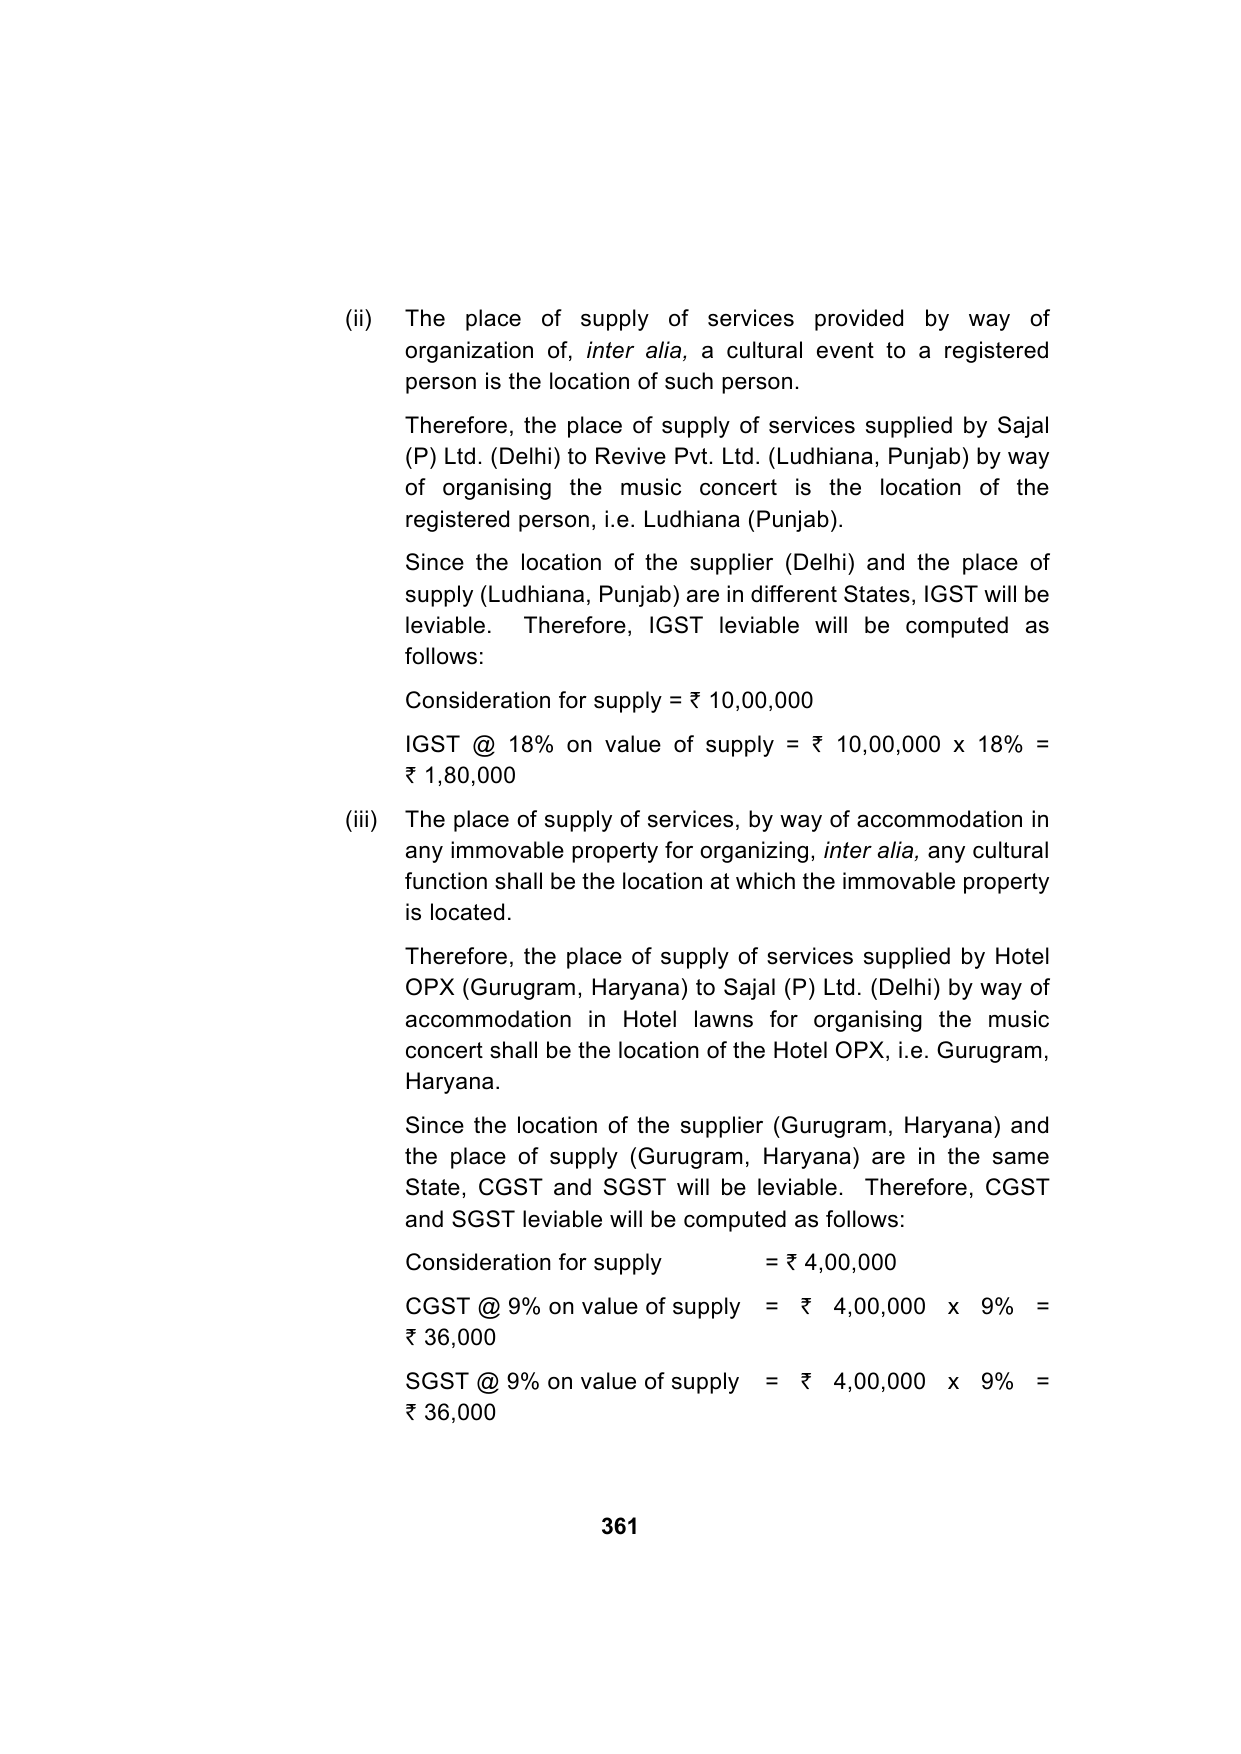
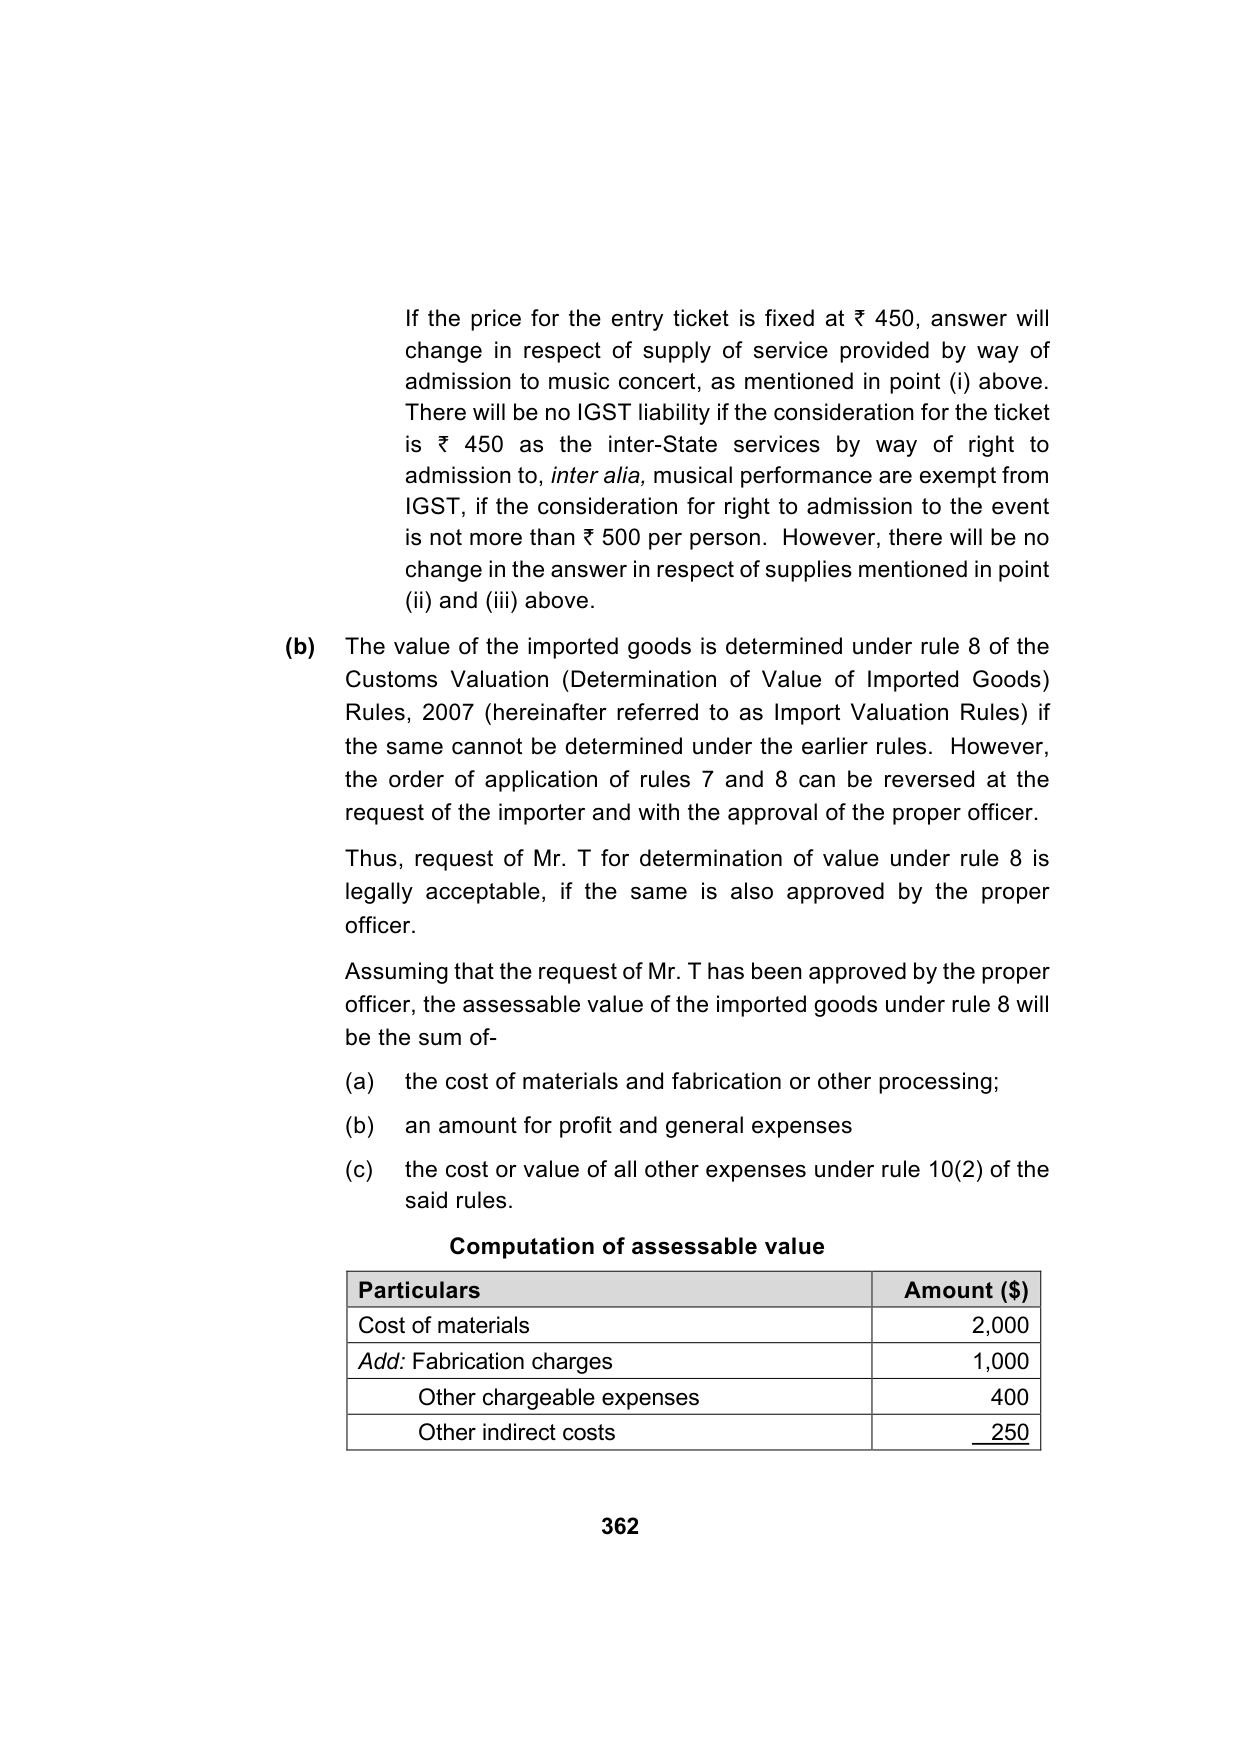
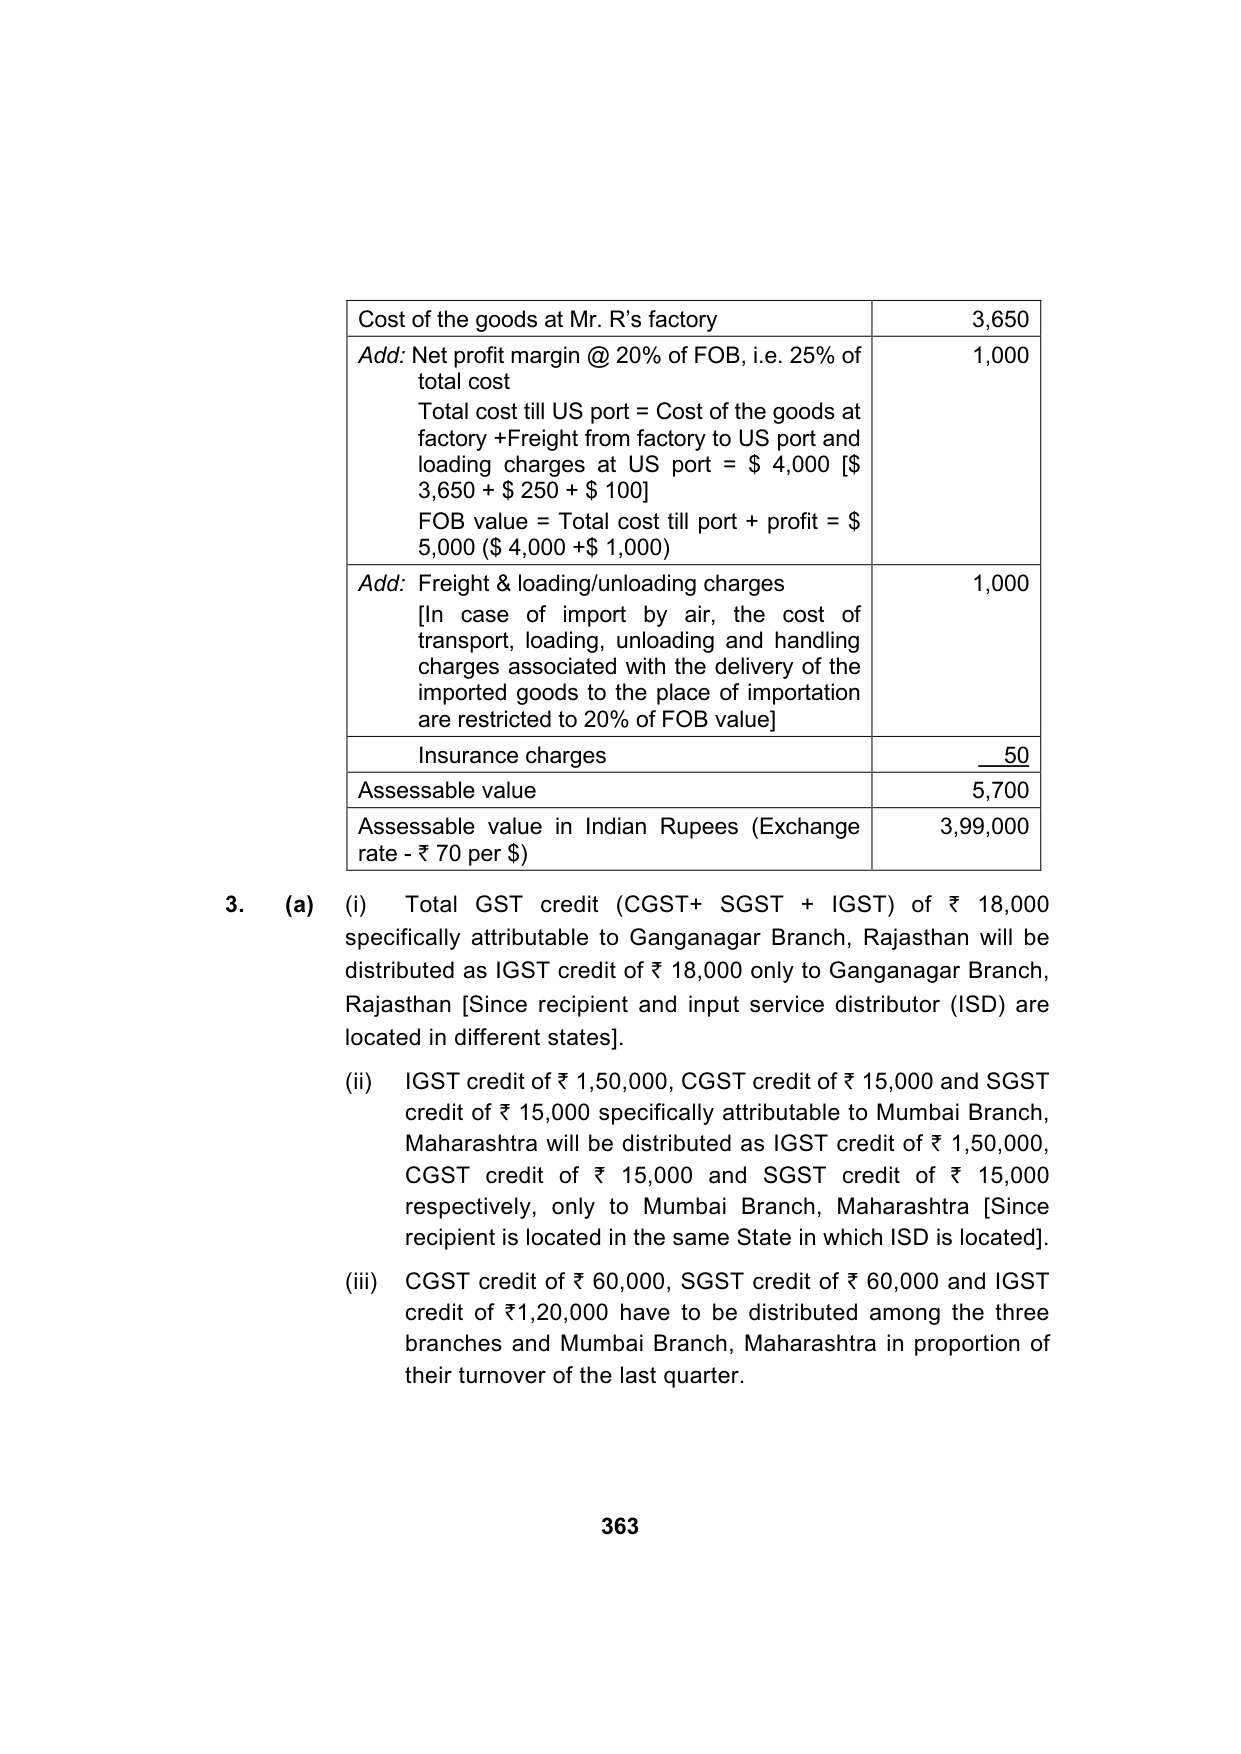
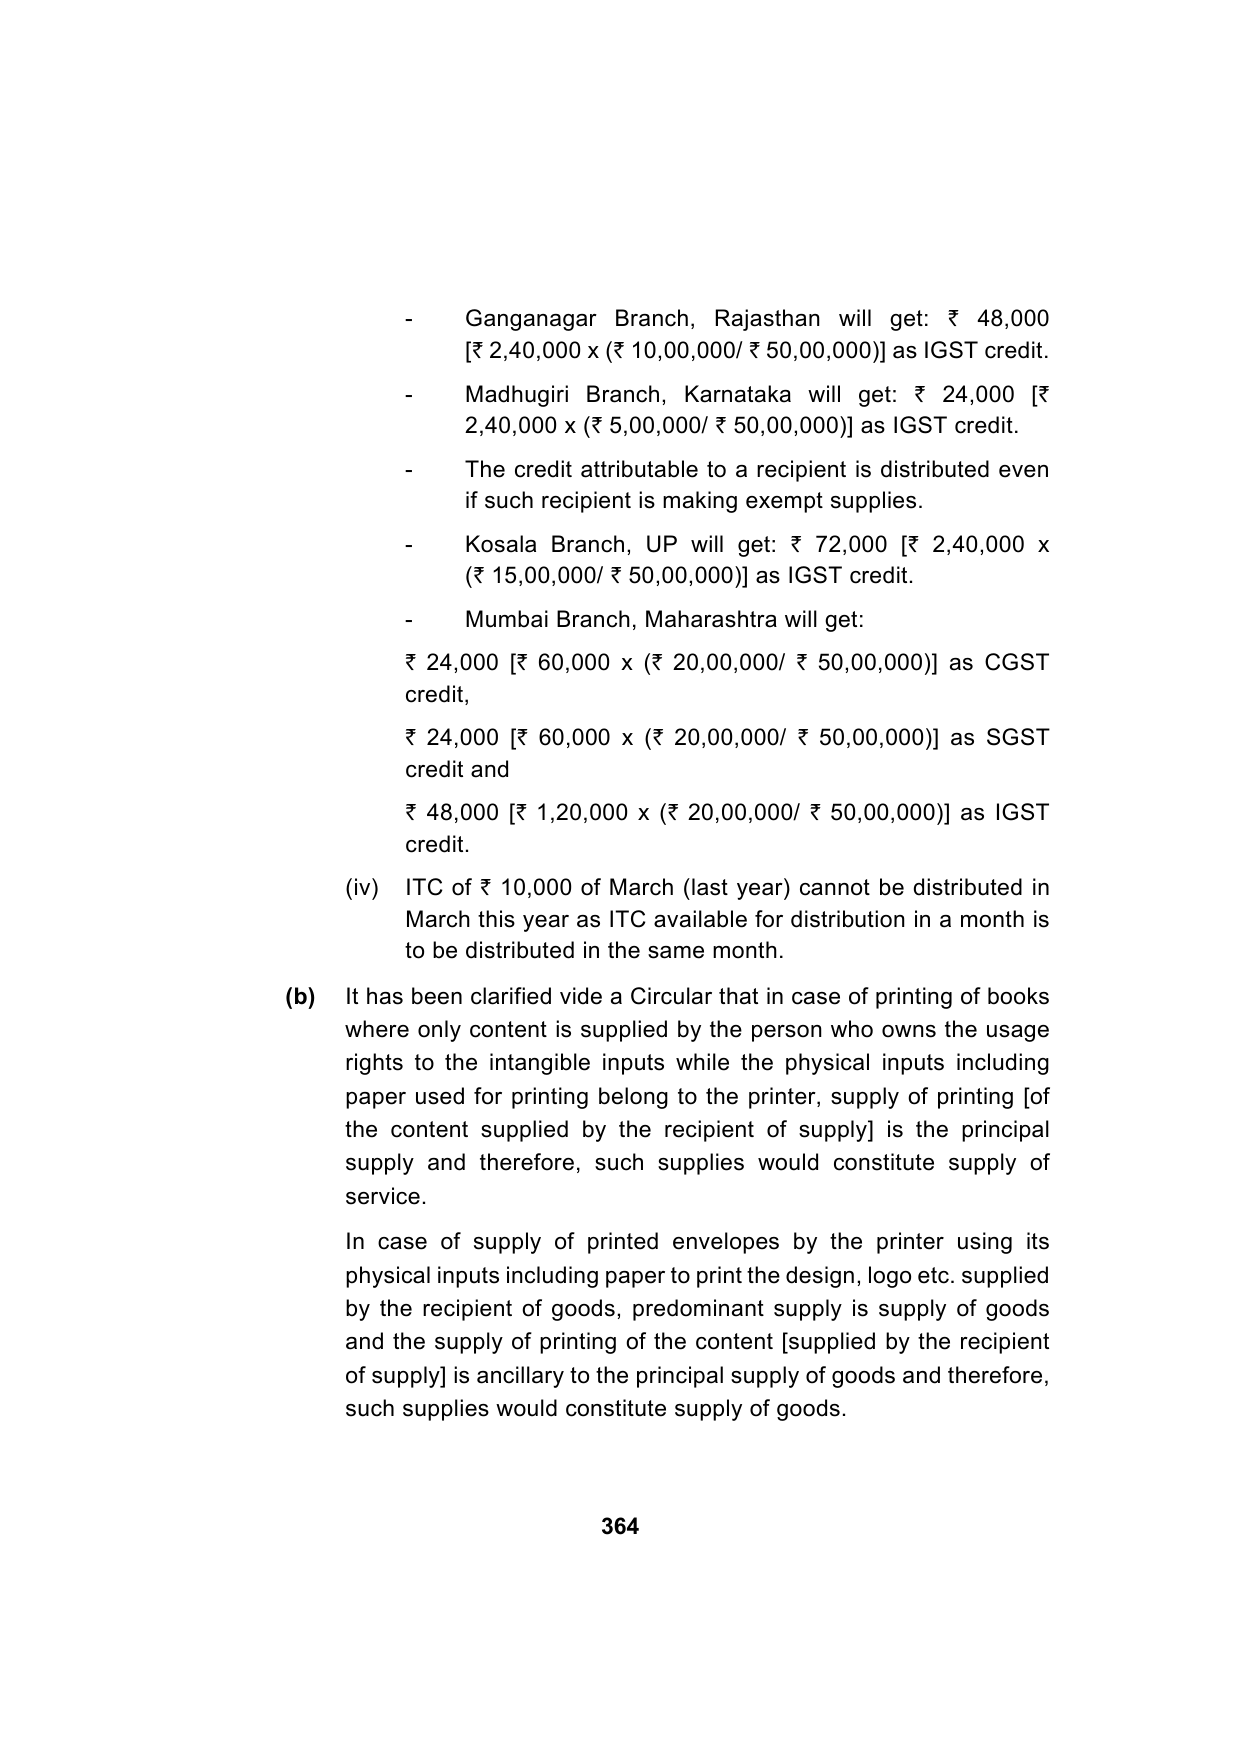
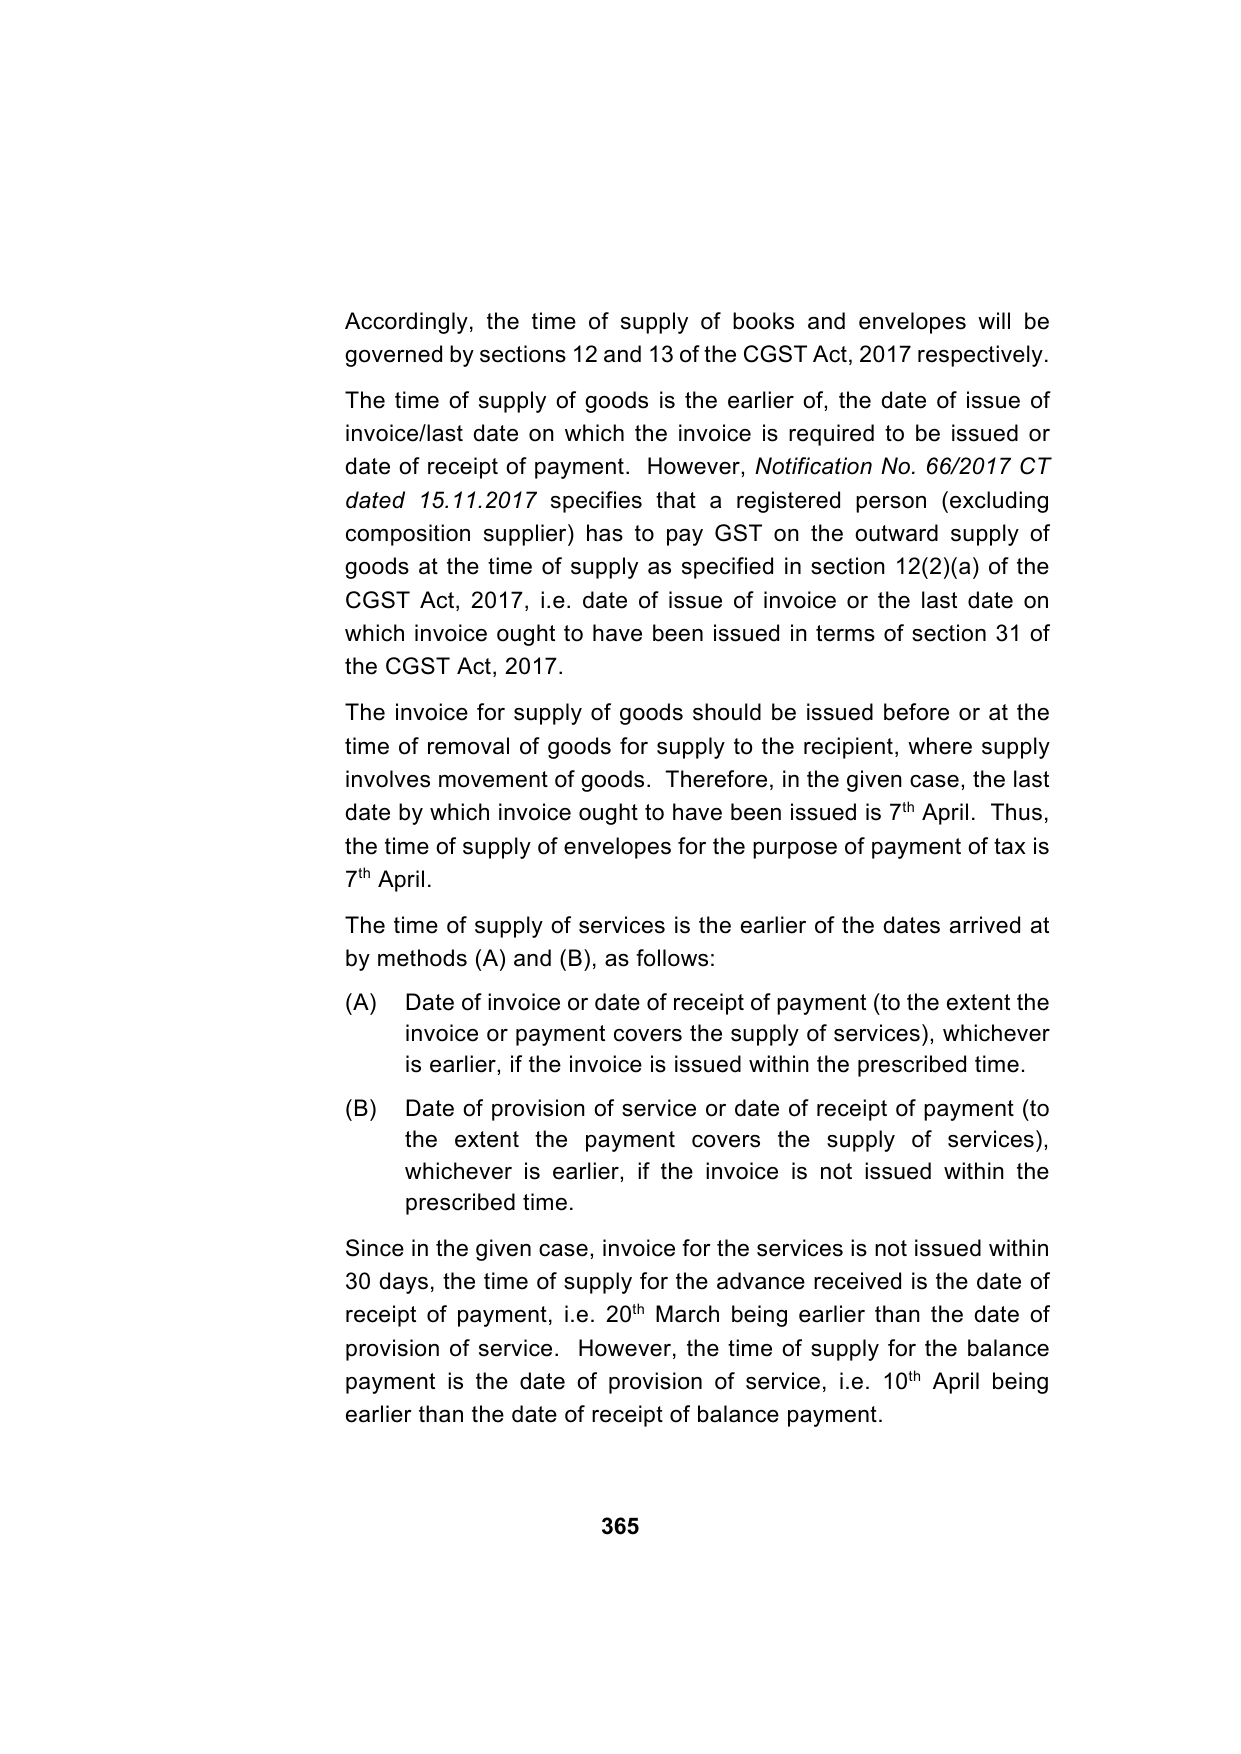
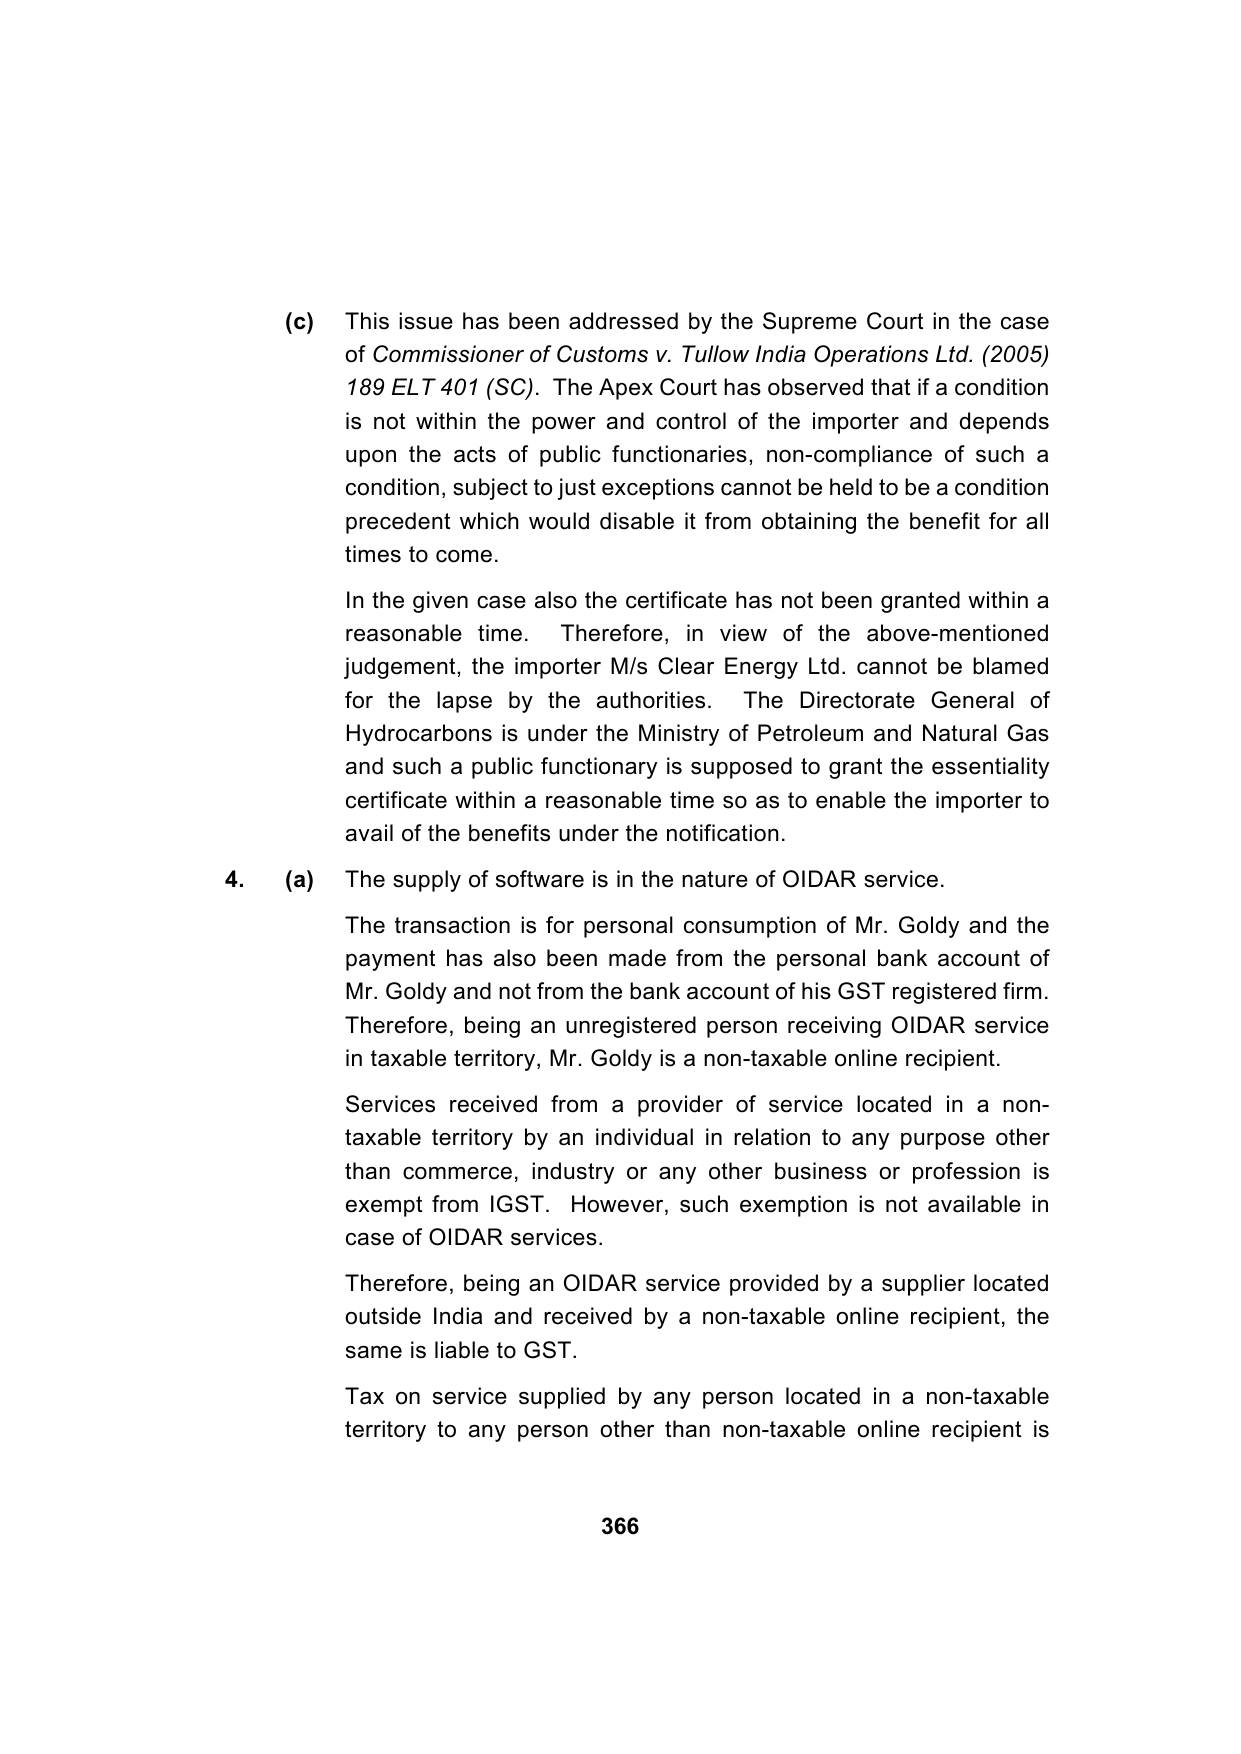
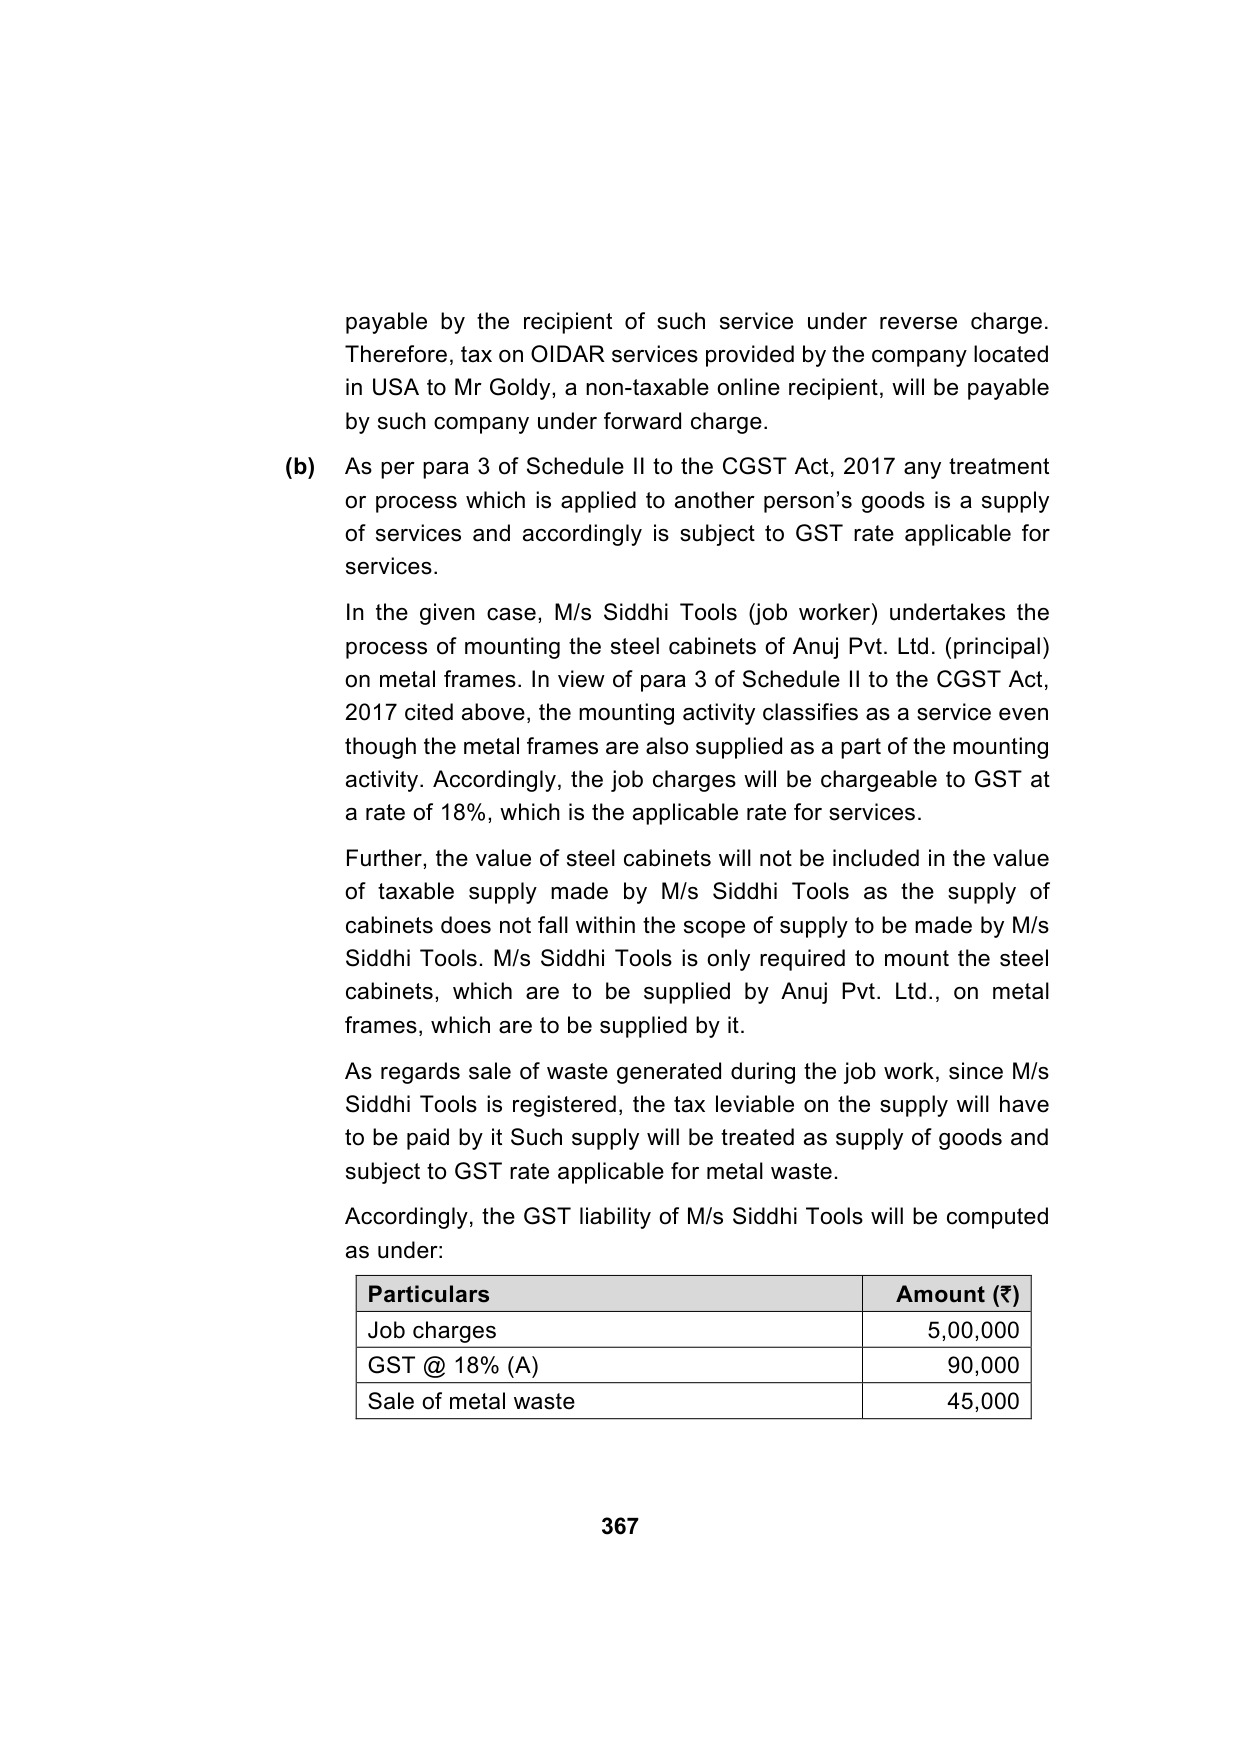
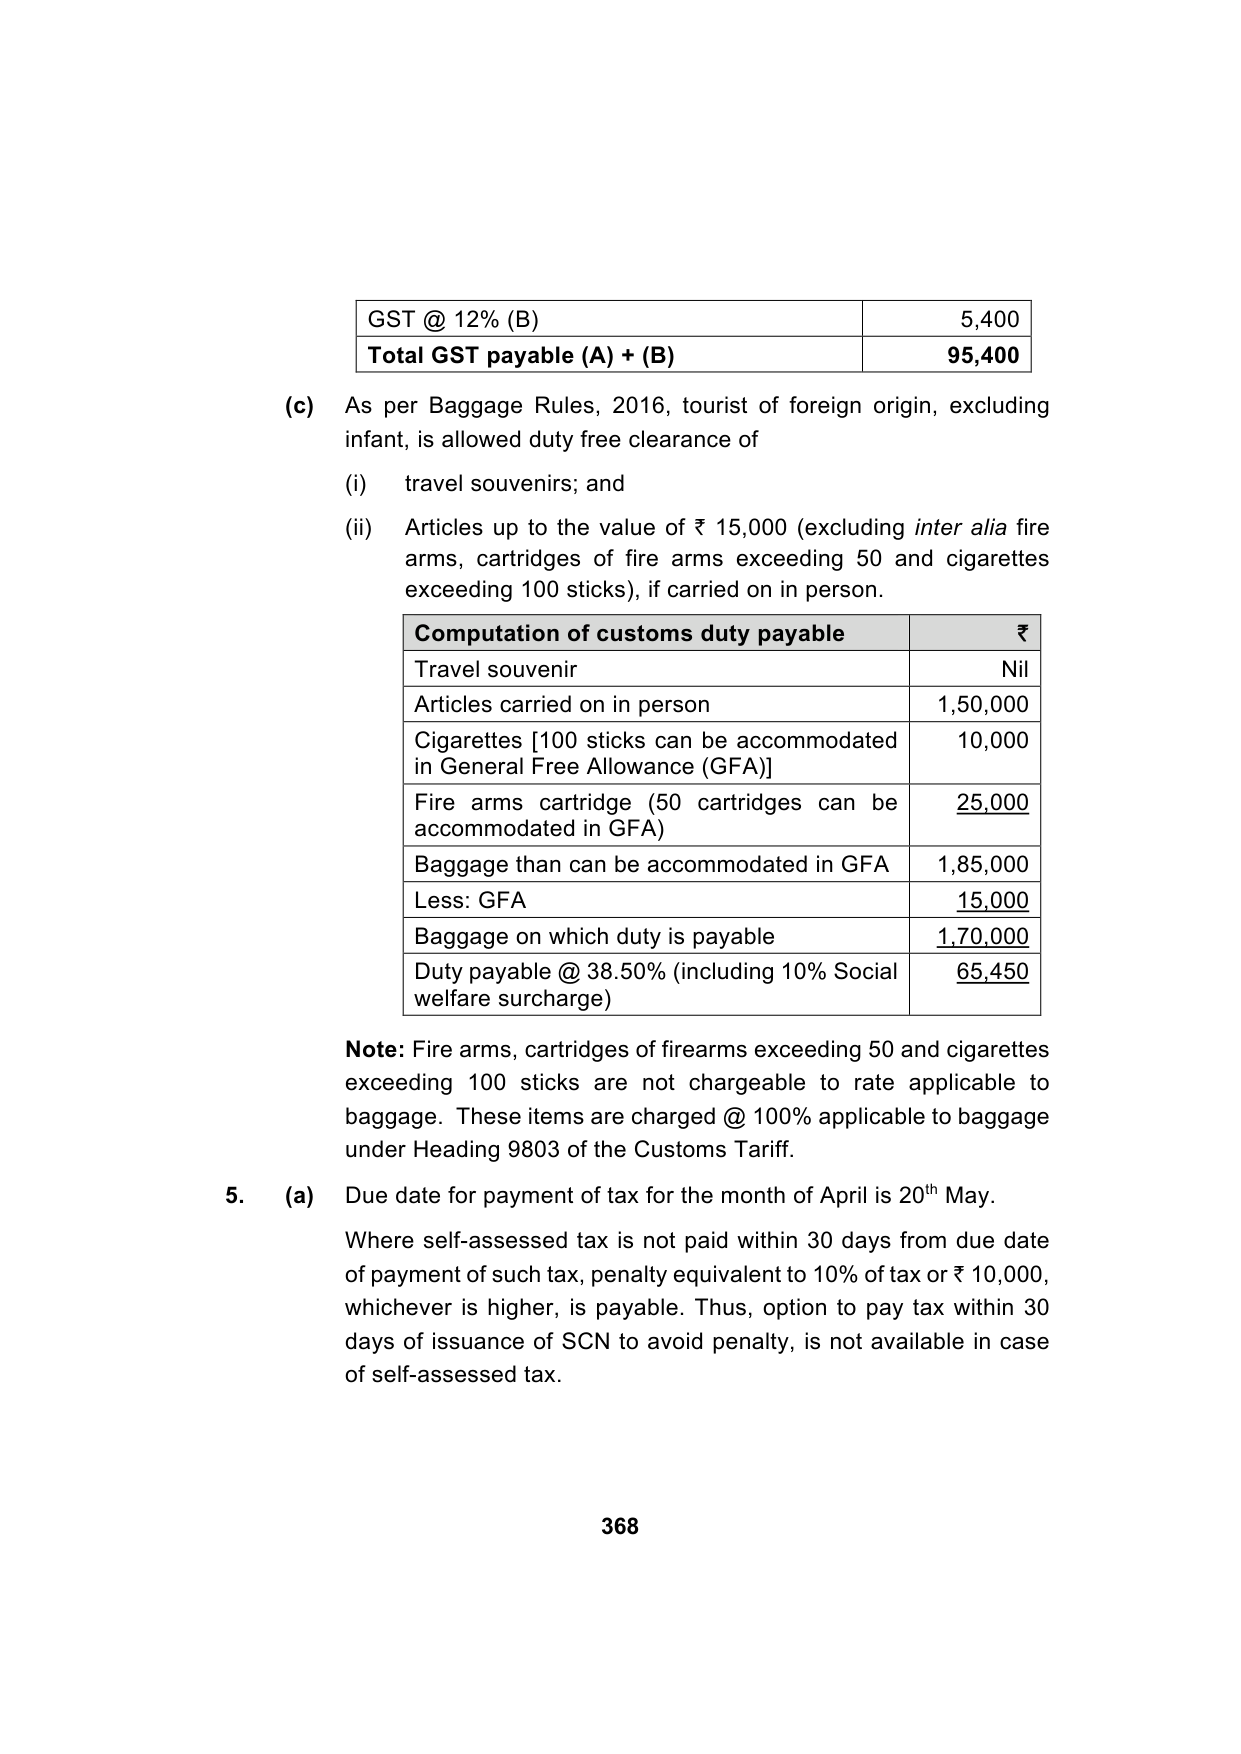
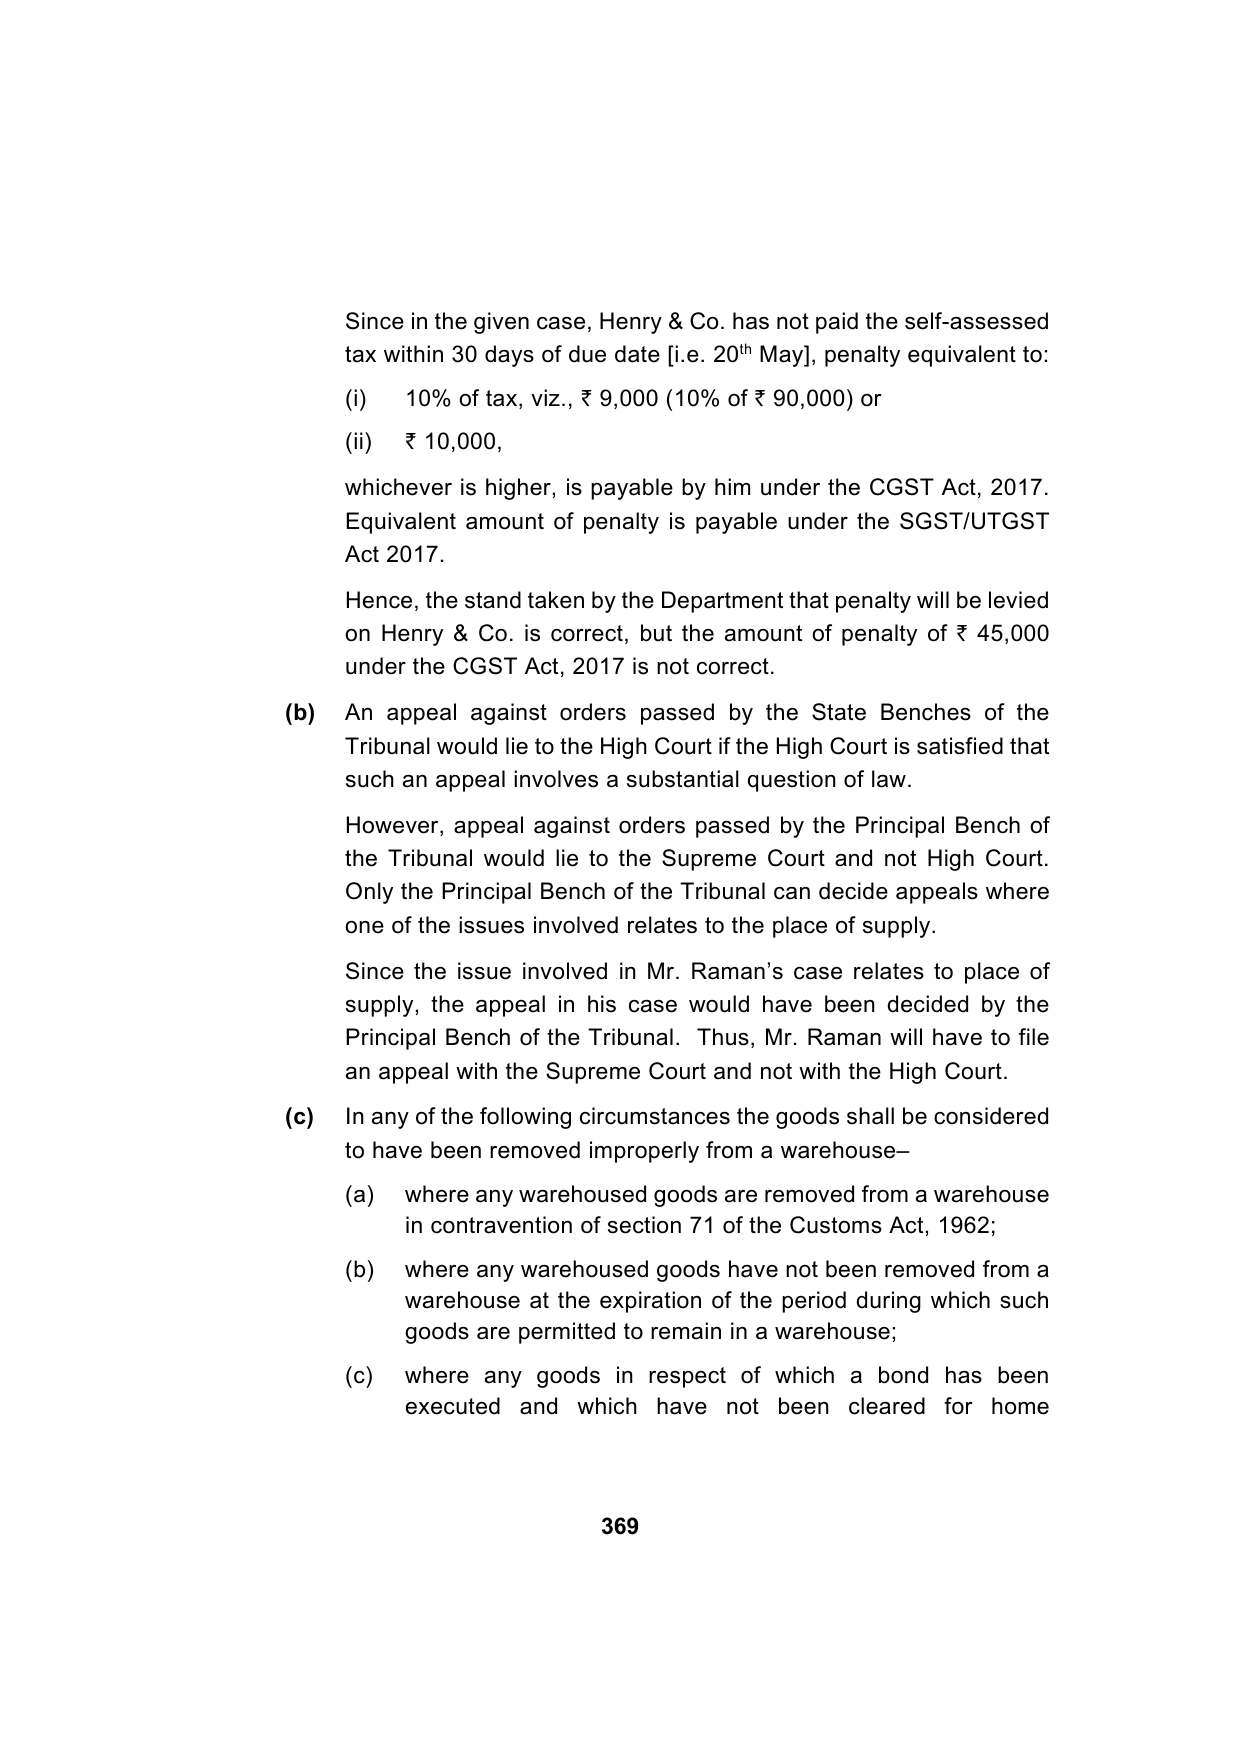
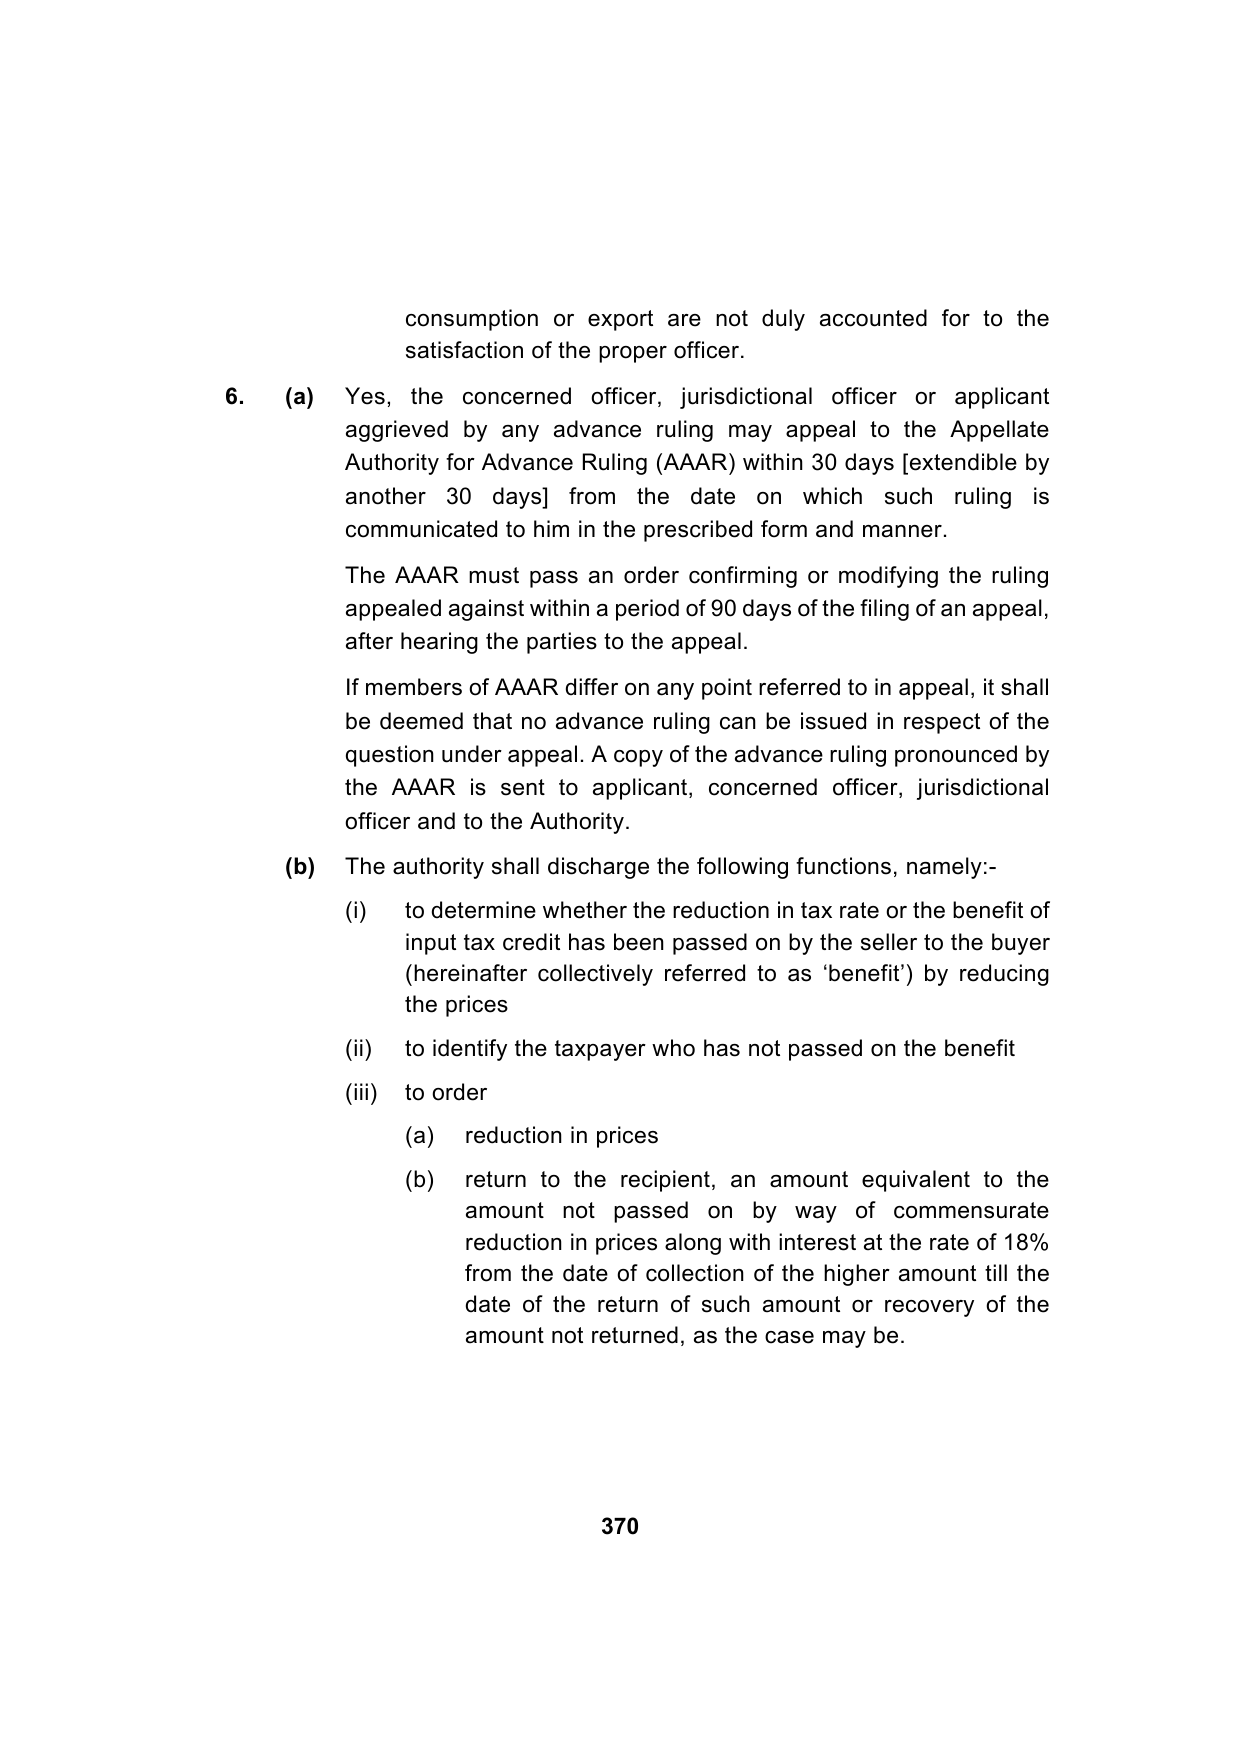
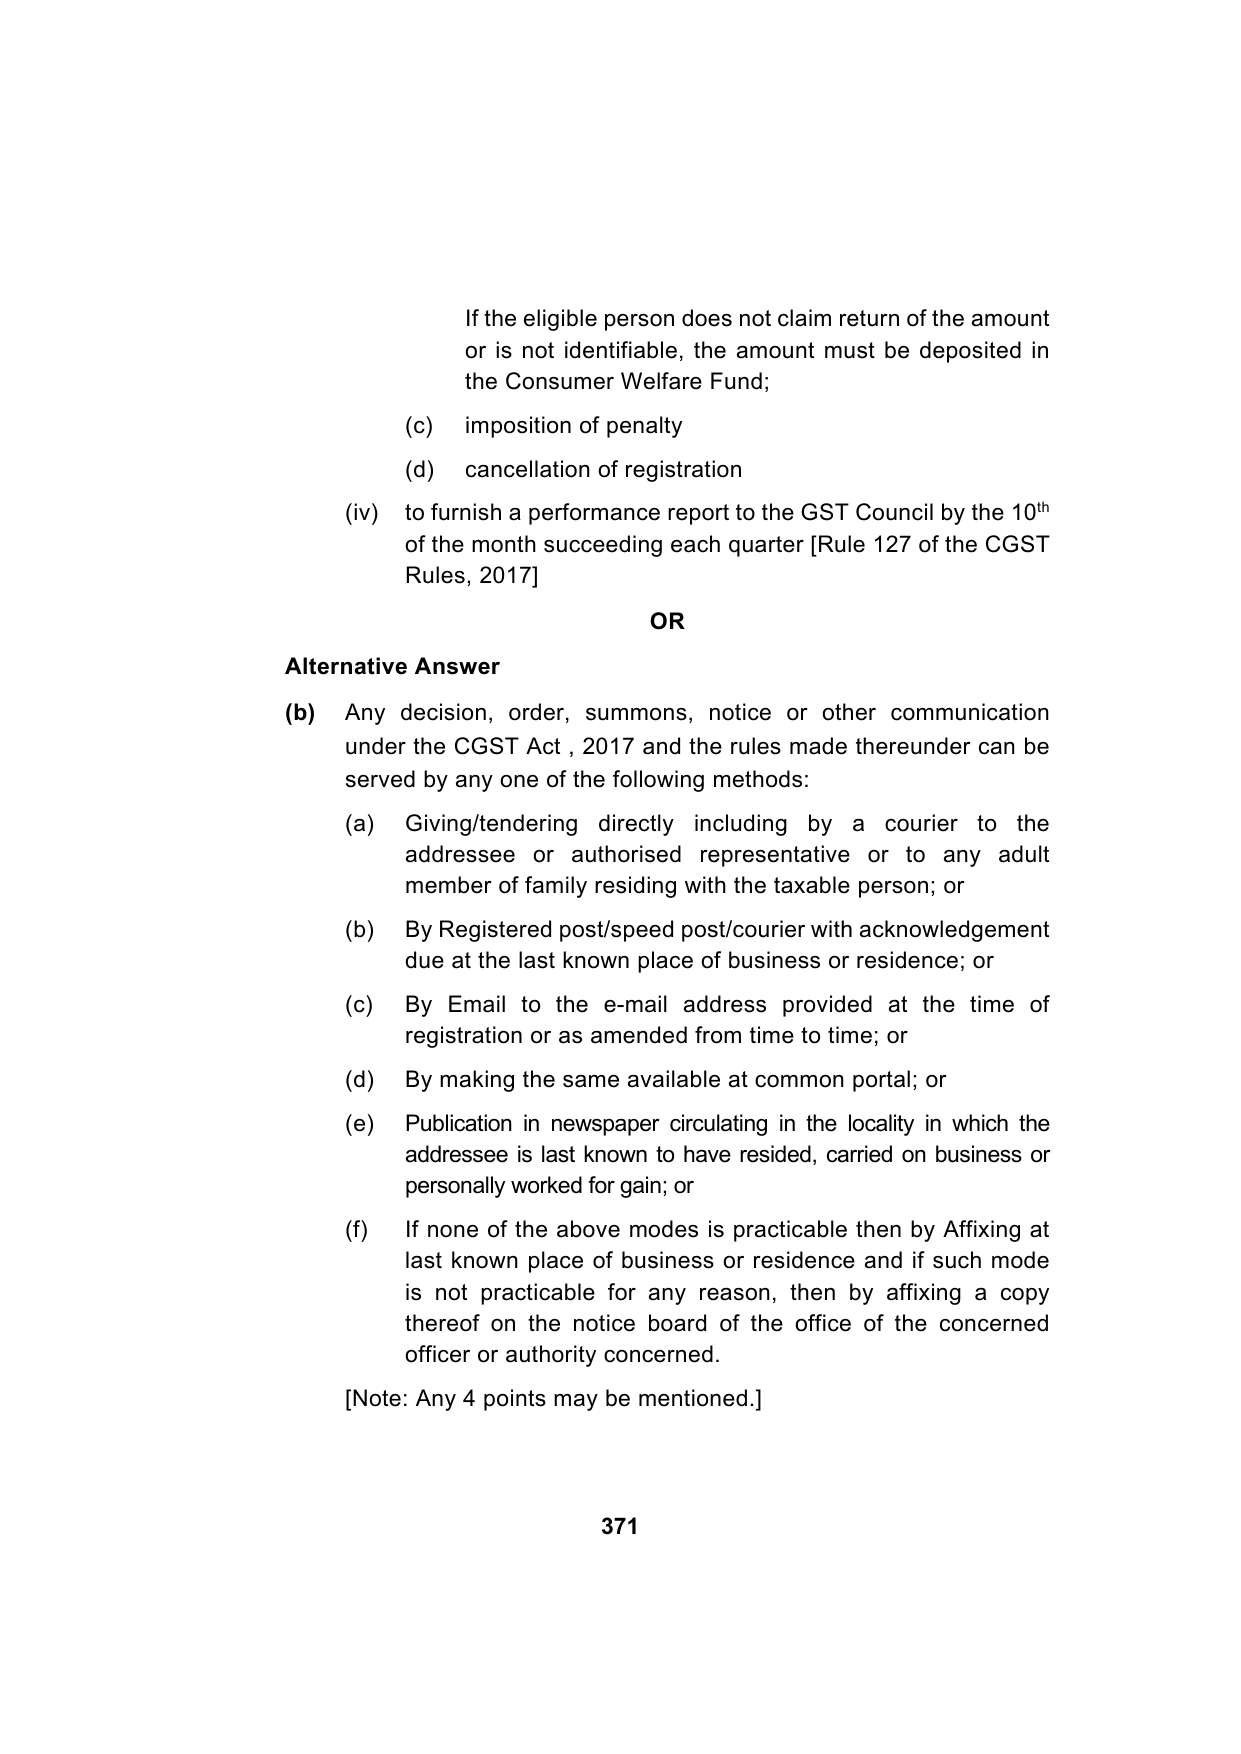
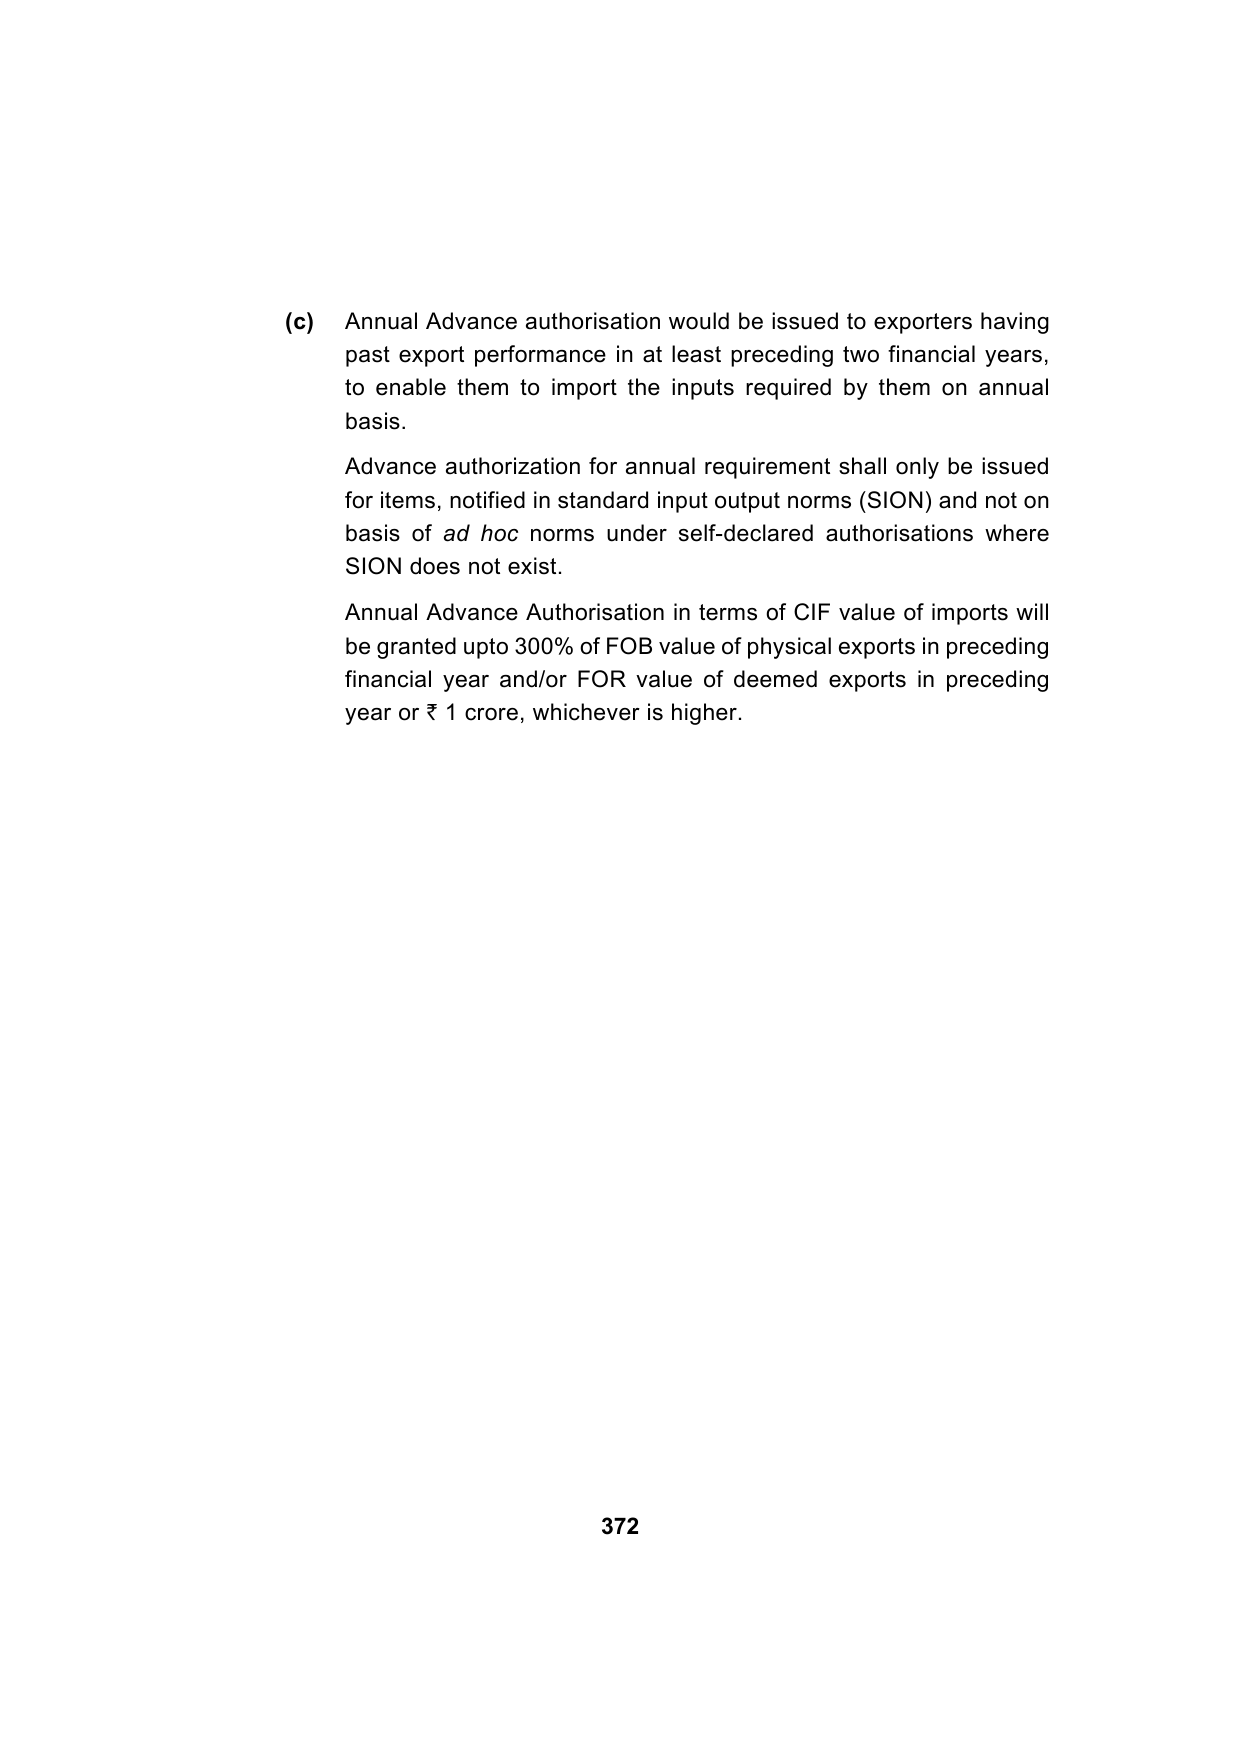
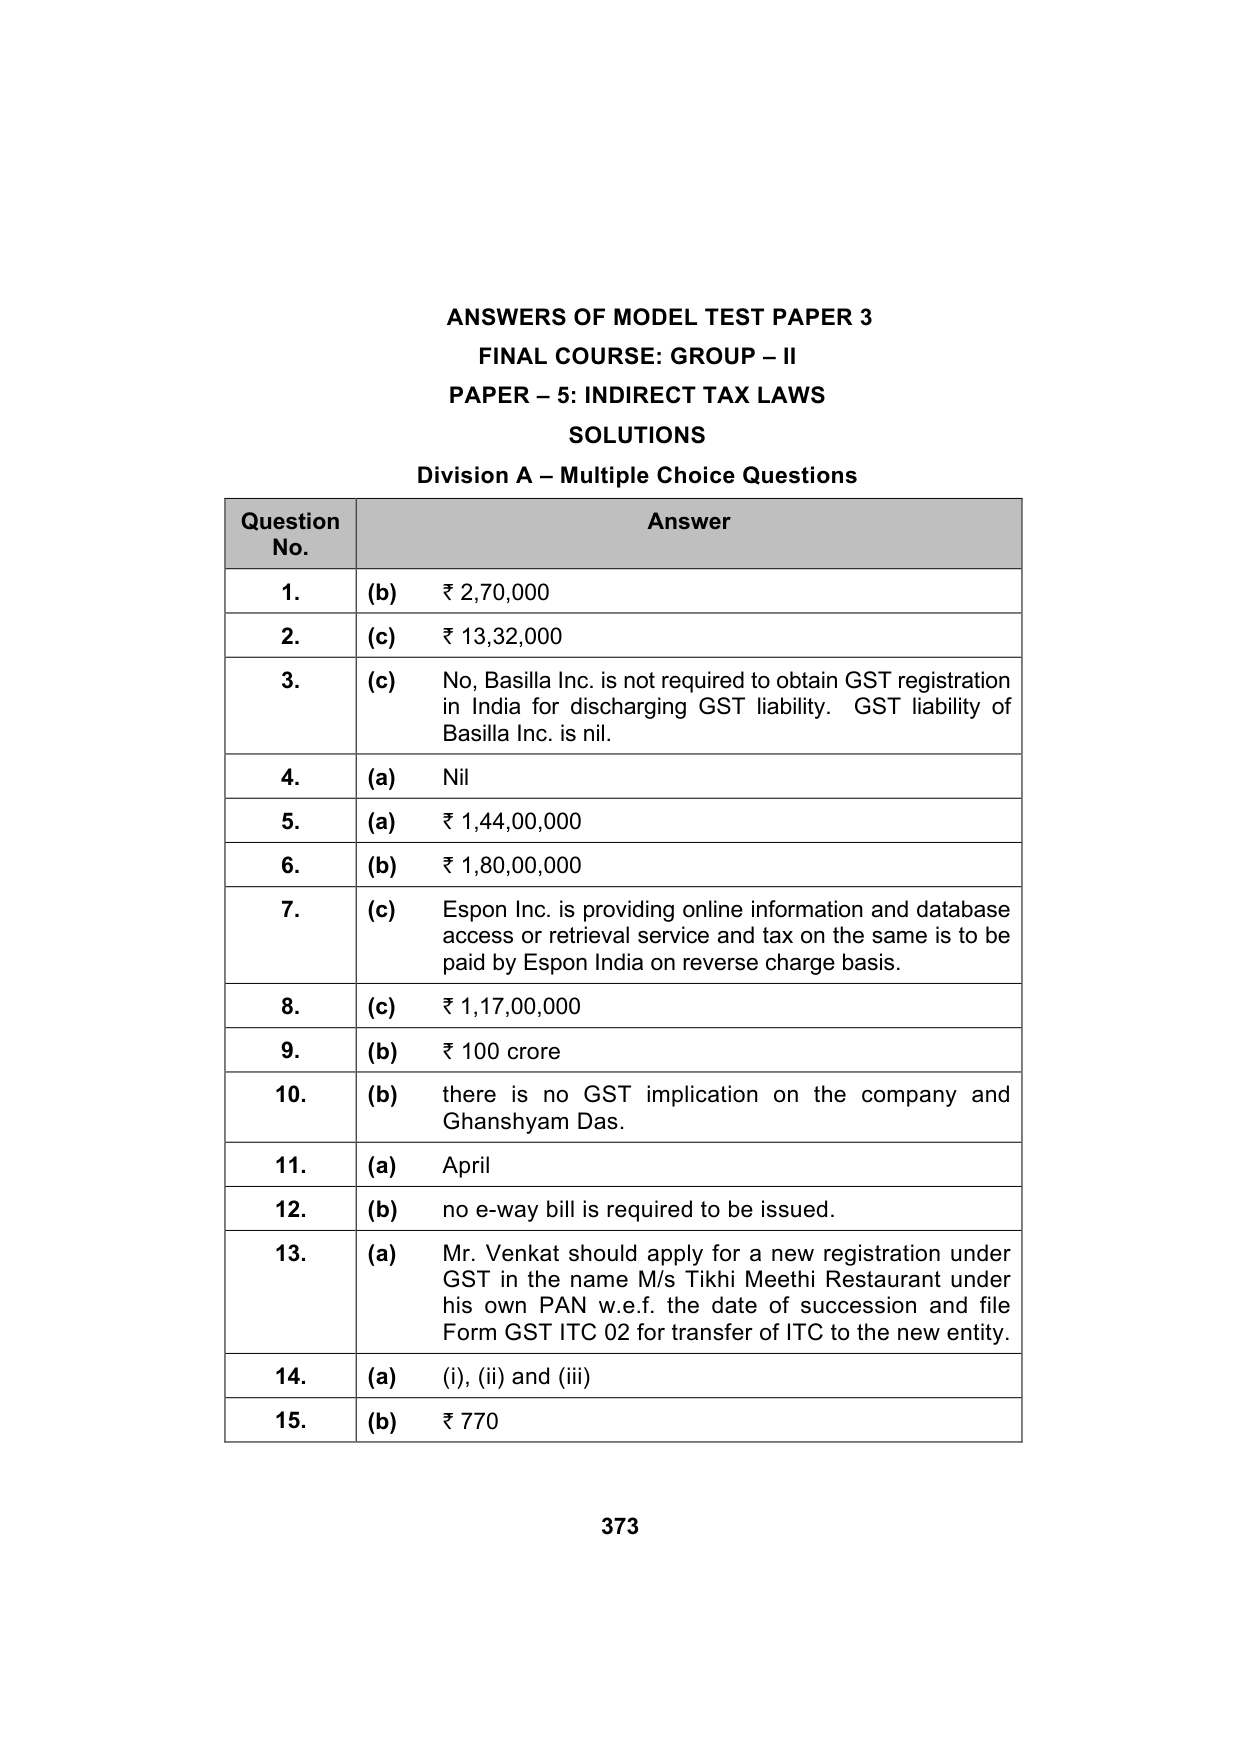
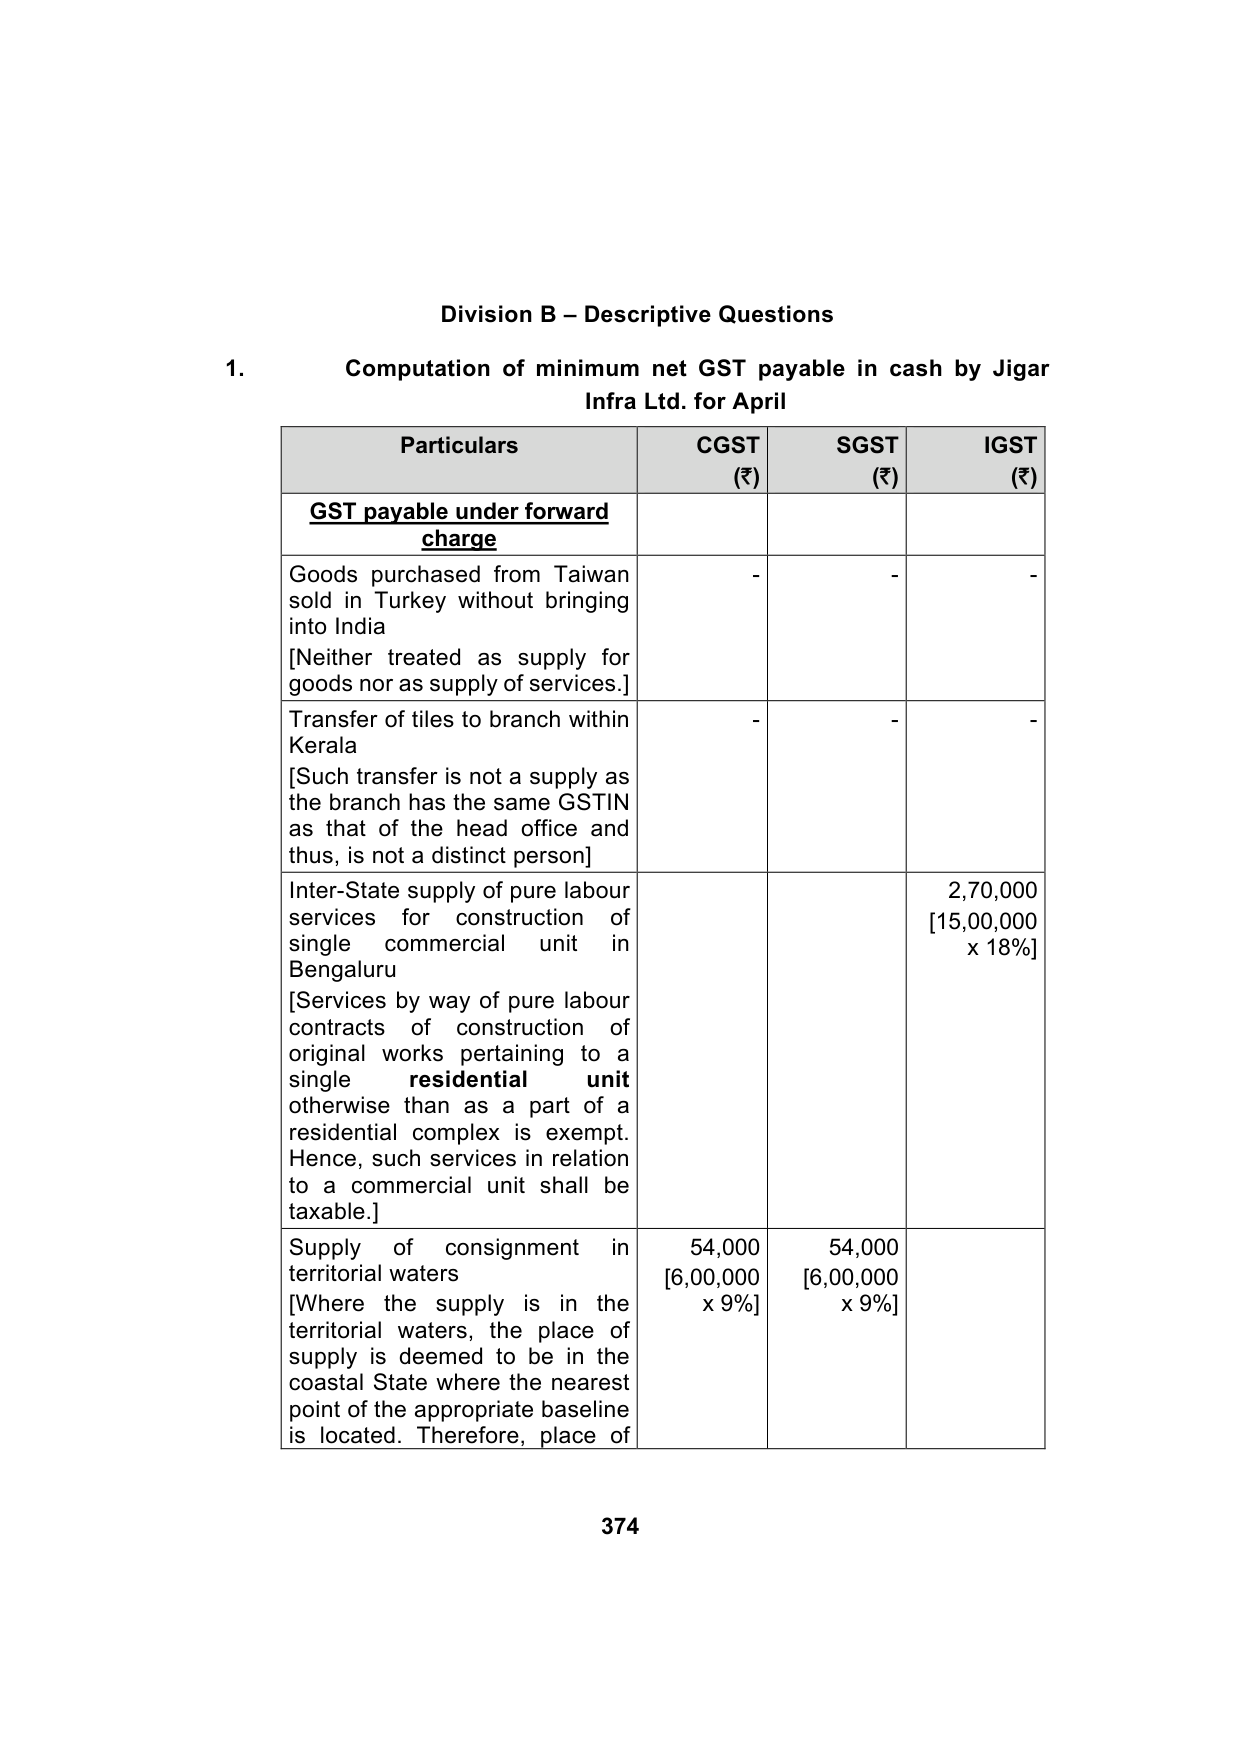
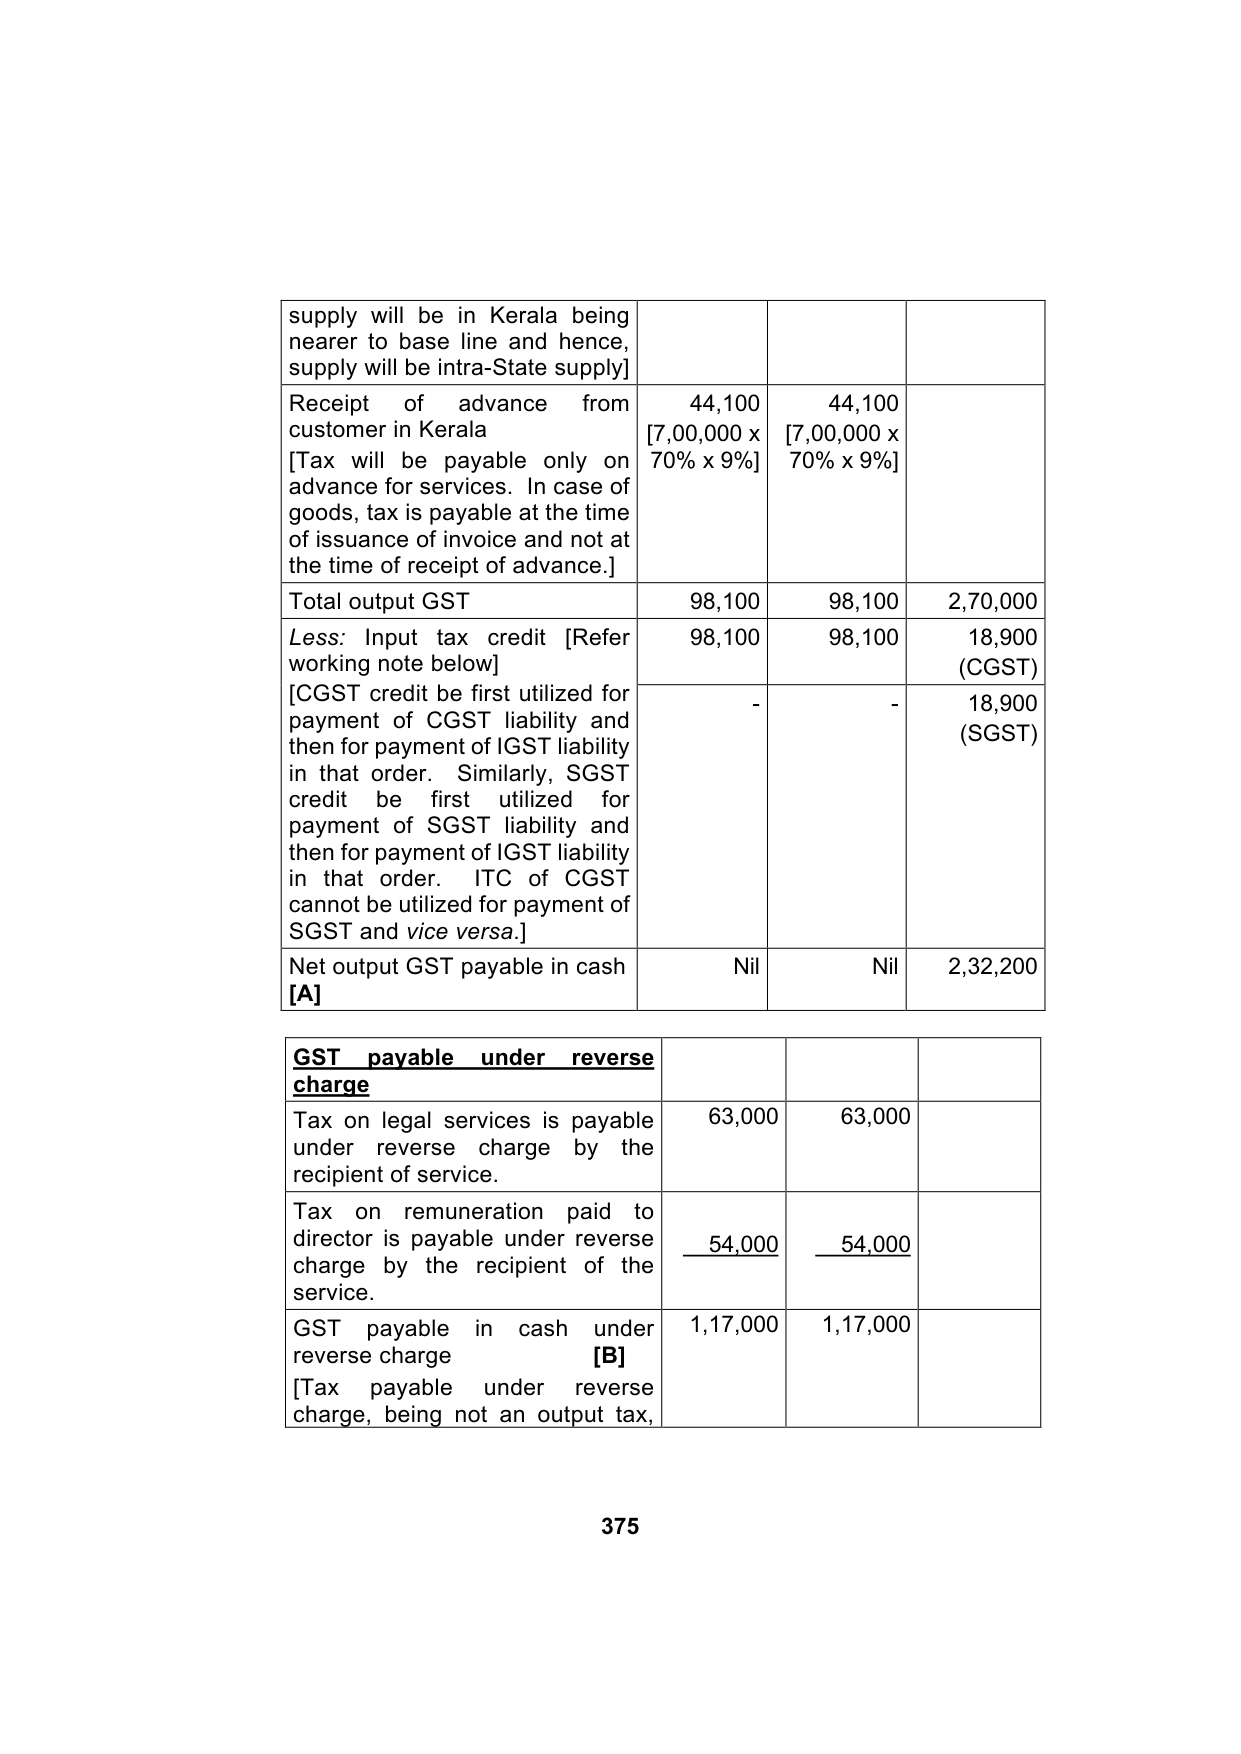
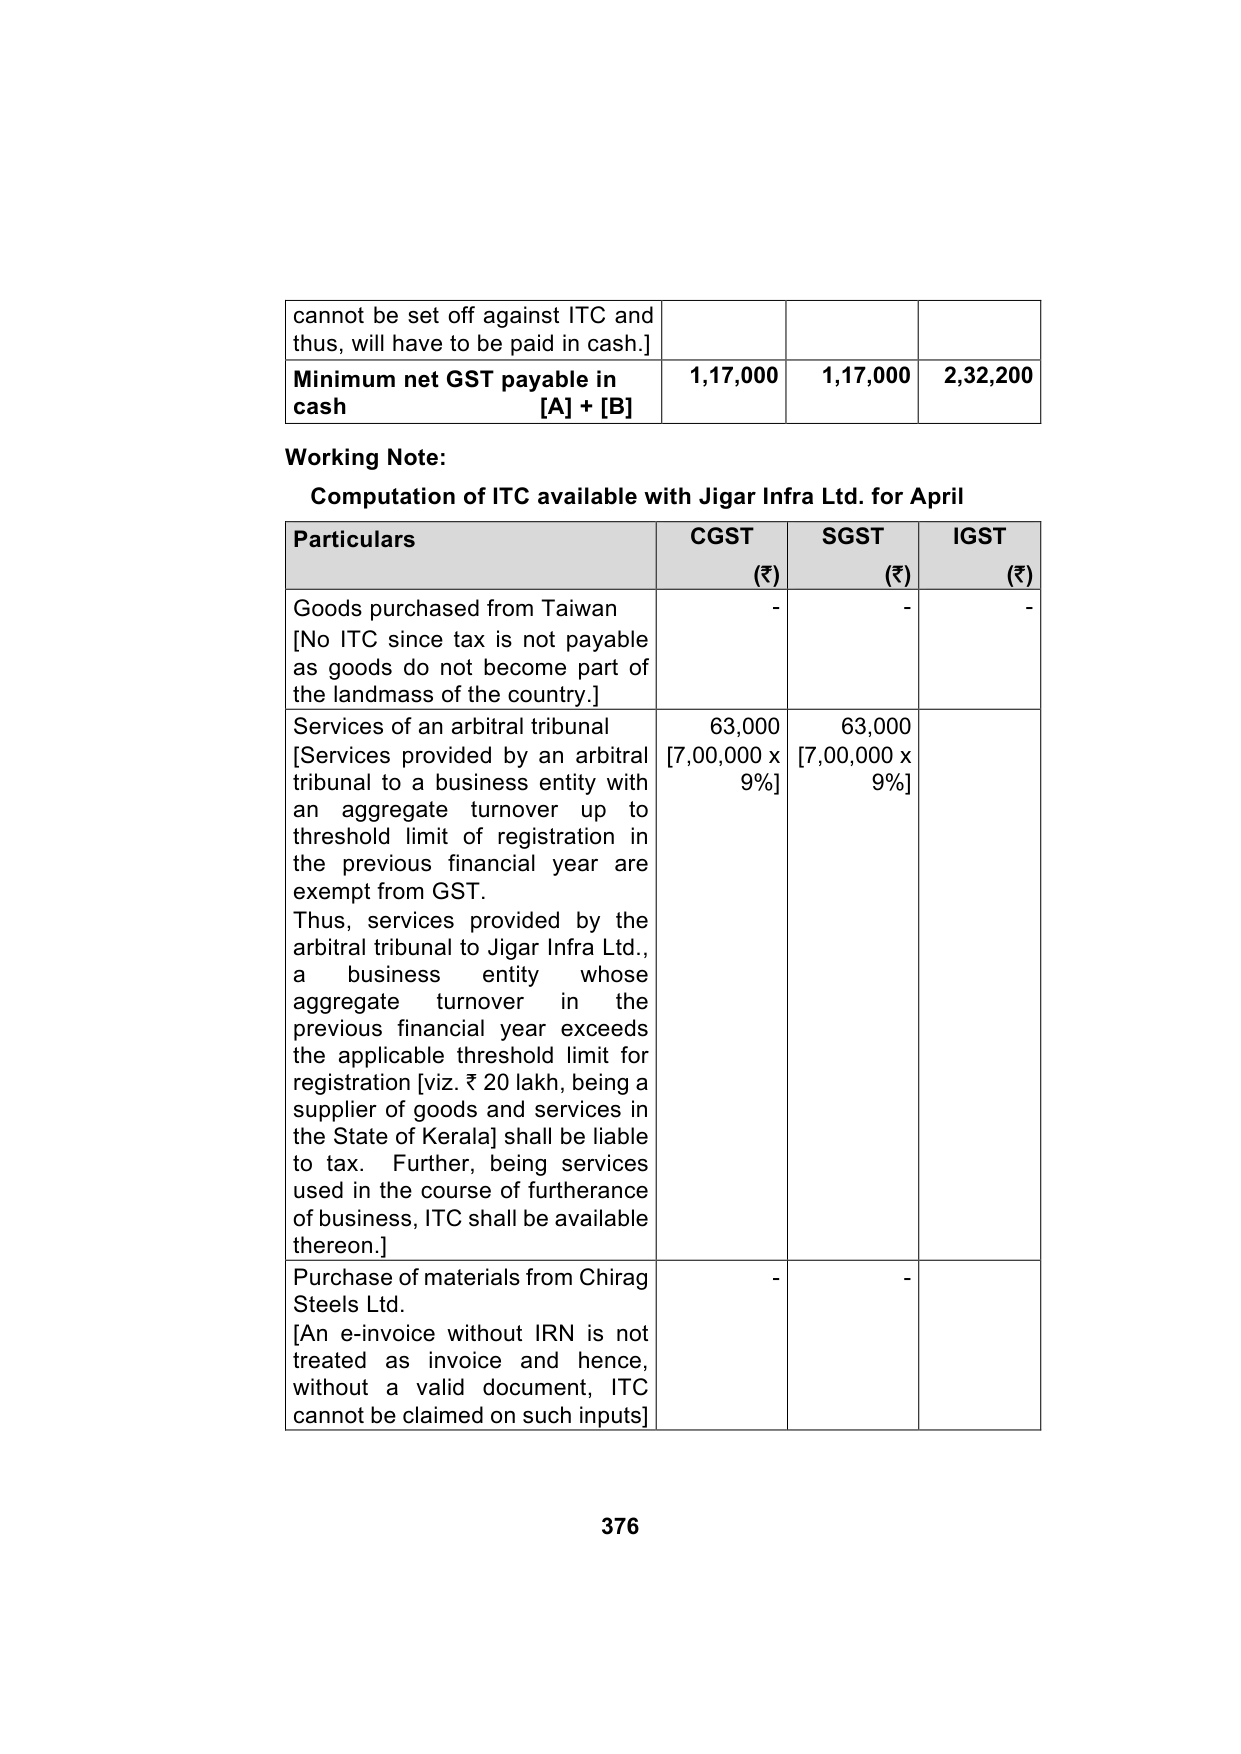
Paper 5: Indirect Tax Laws — Model Test Paper 3 (100 marks)
Question
Answer
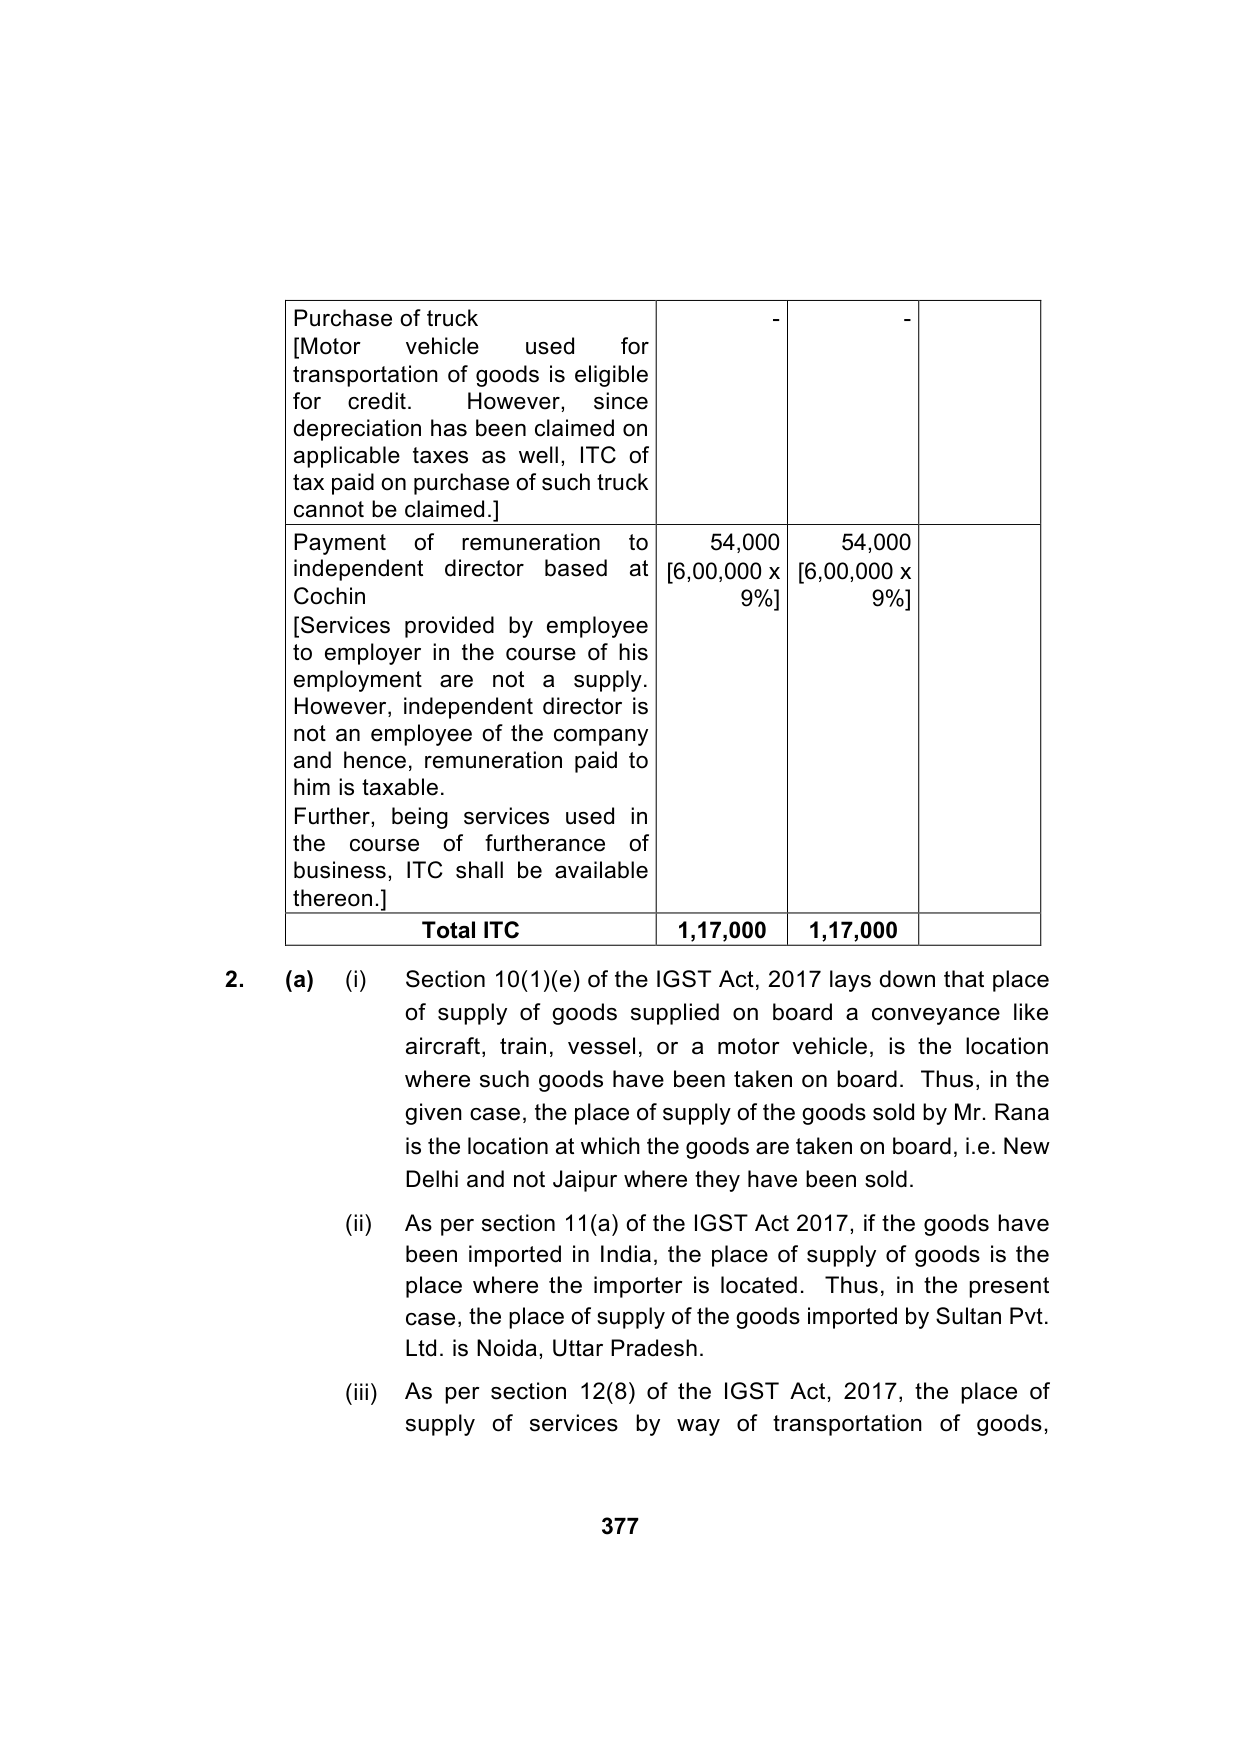
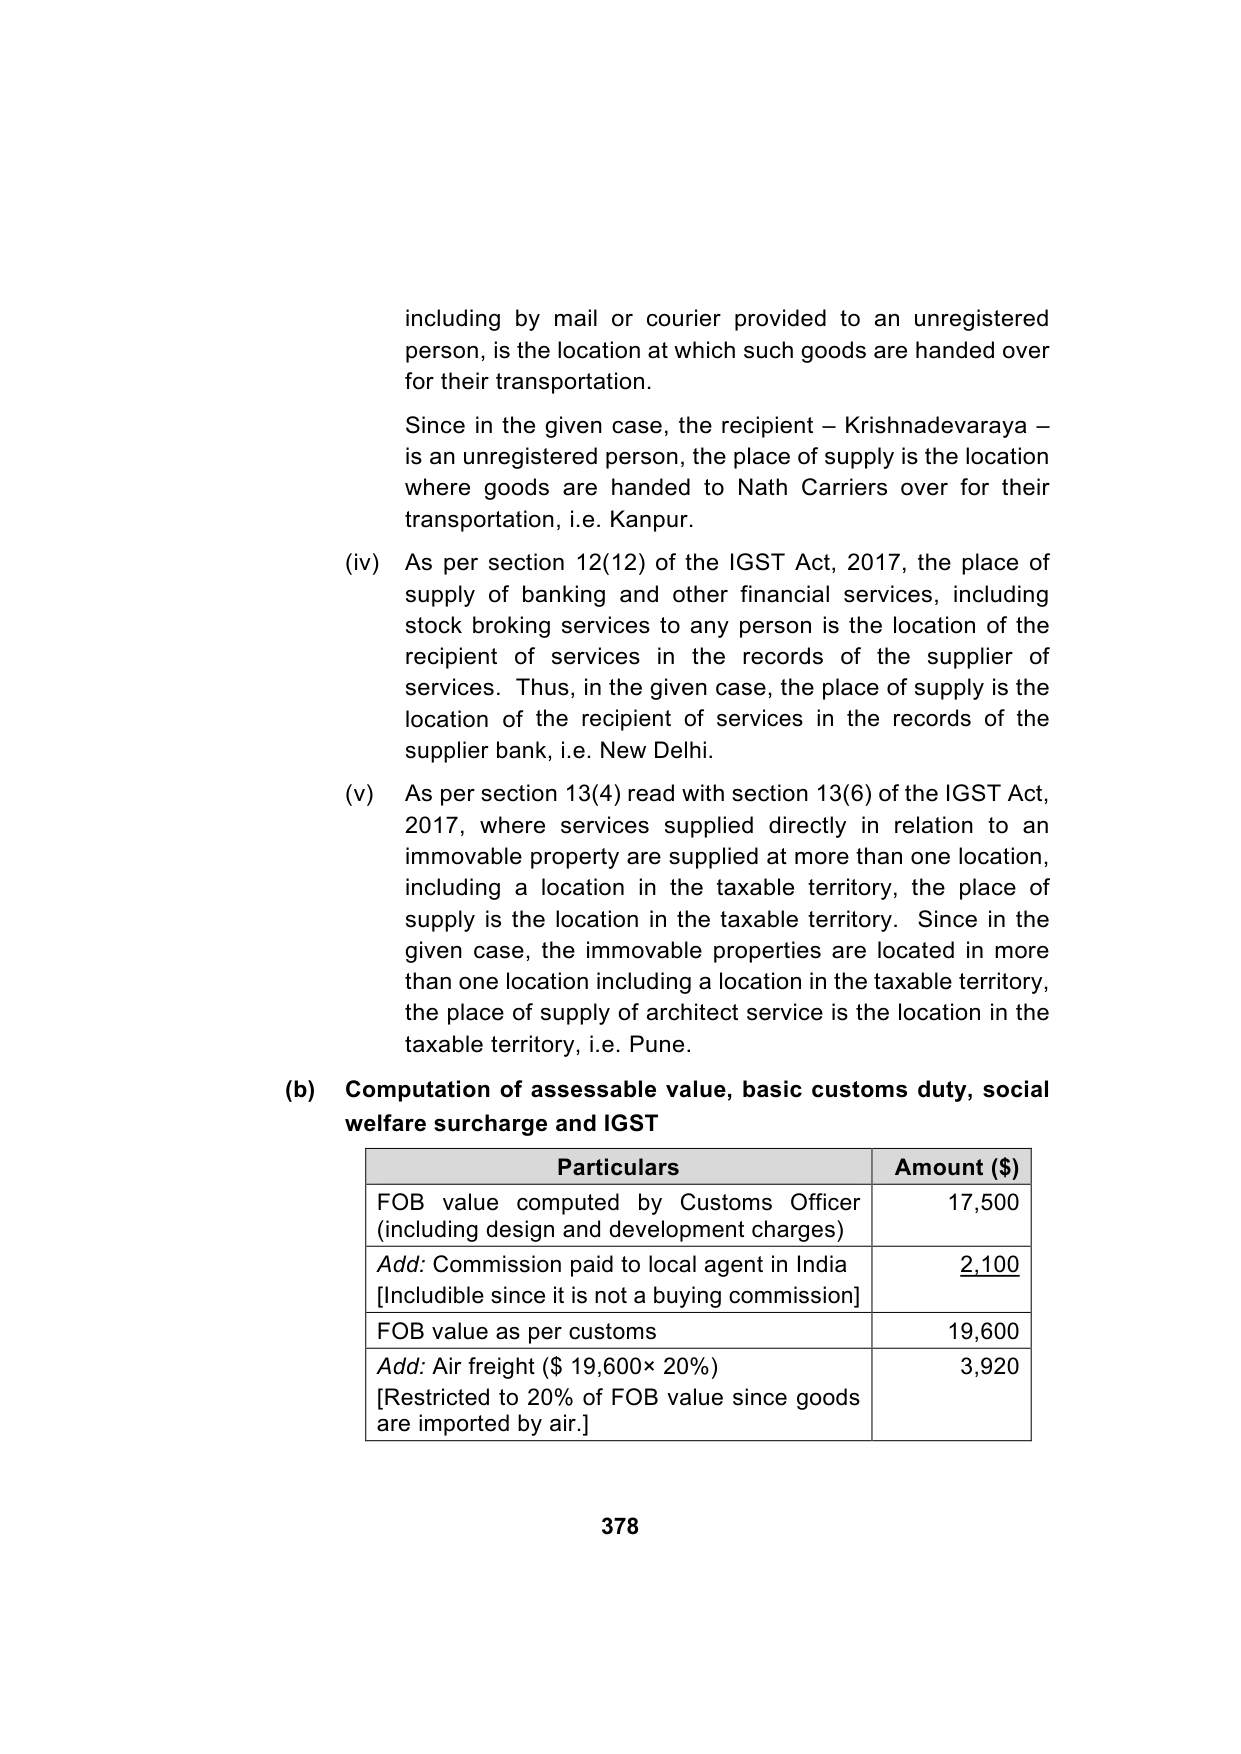
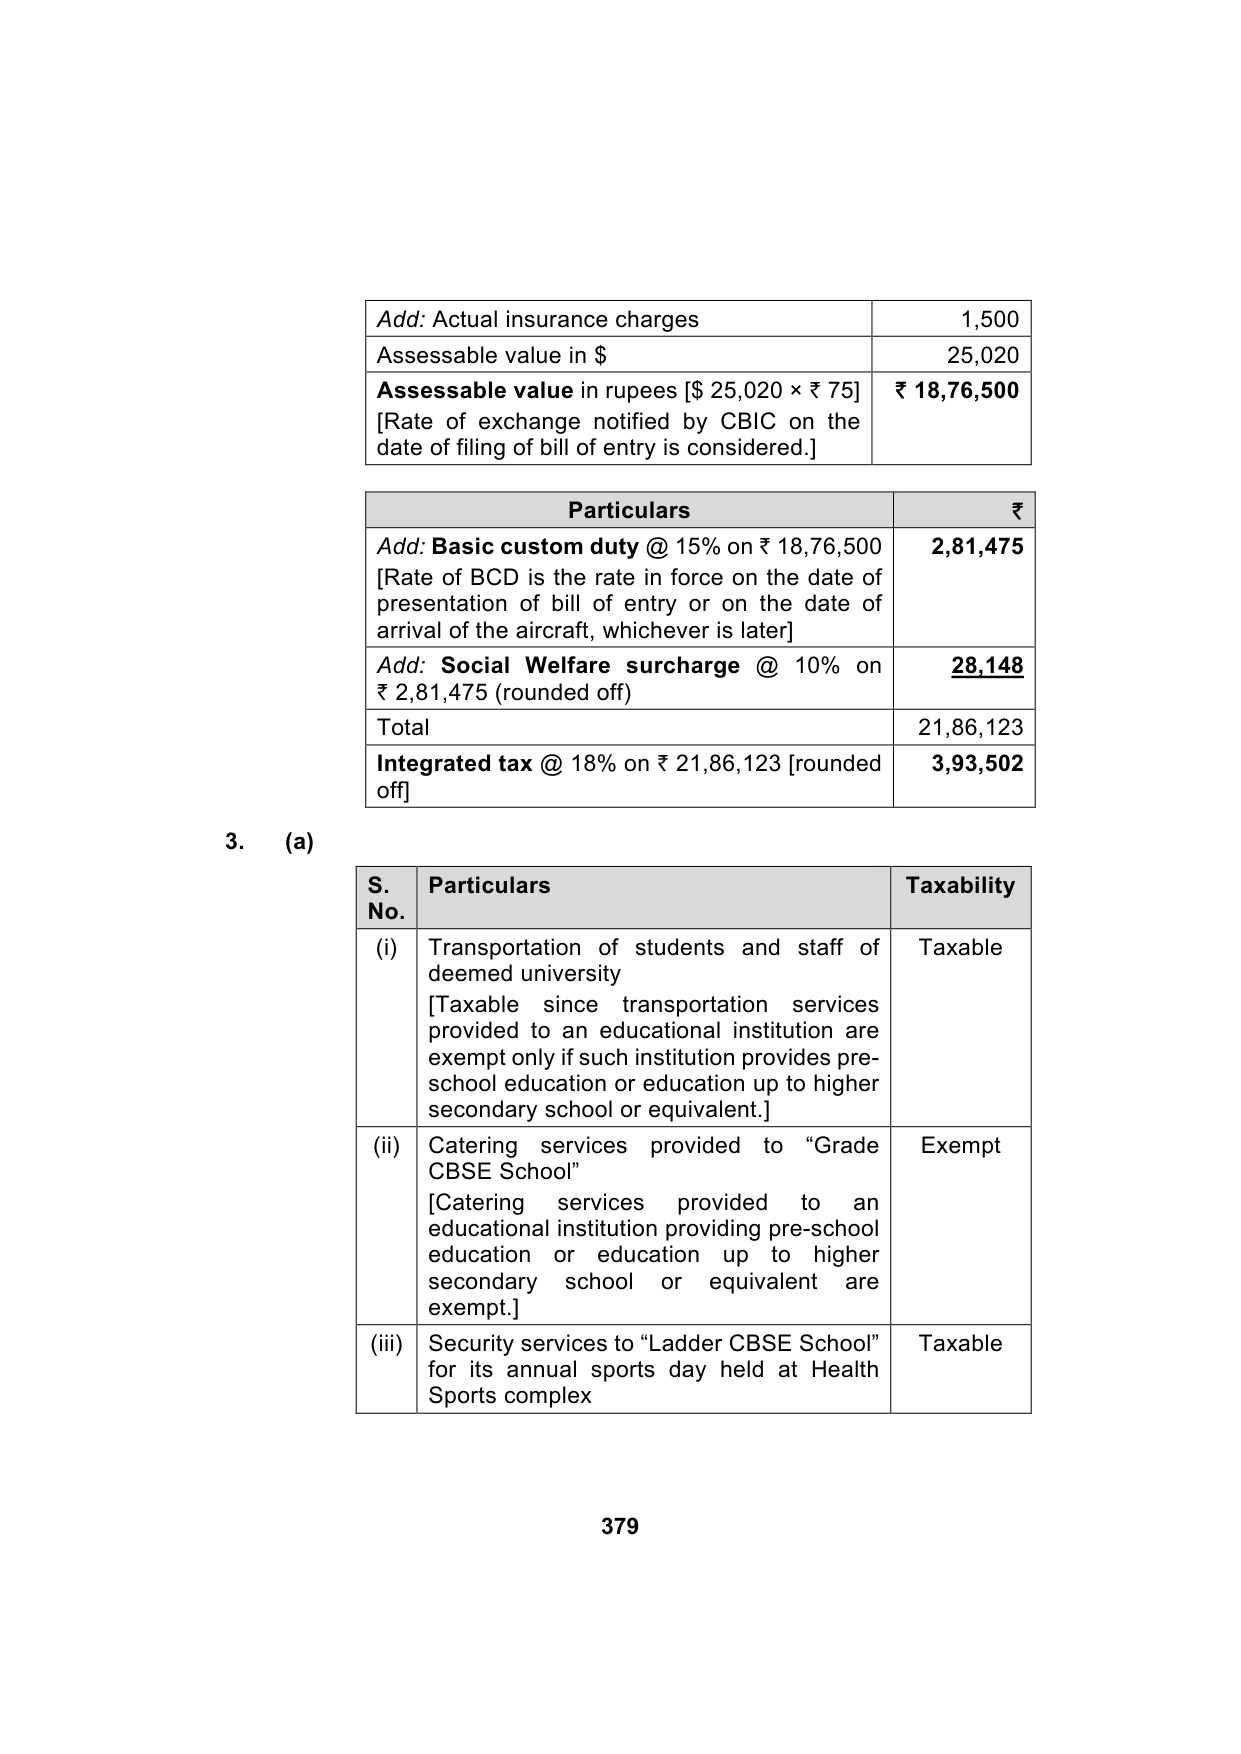
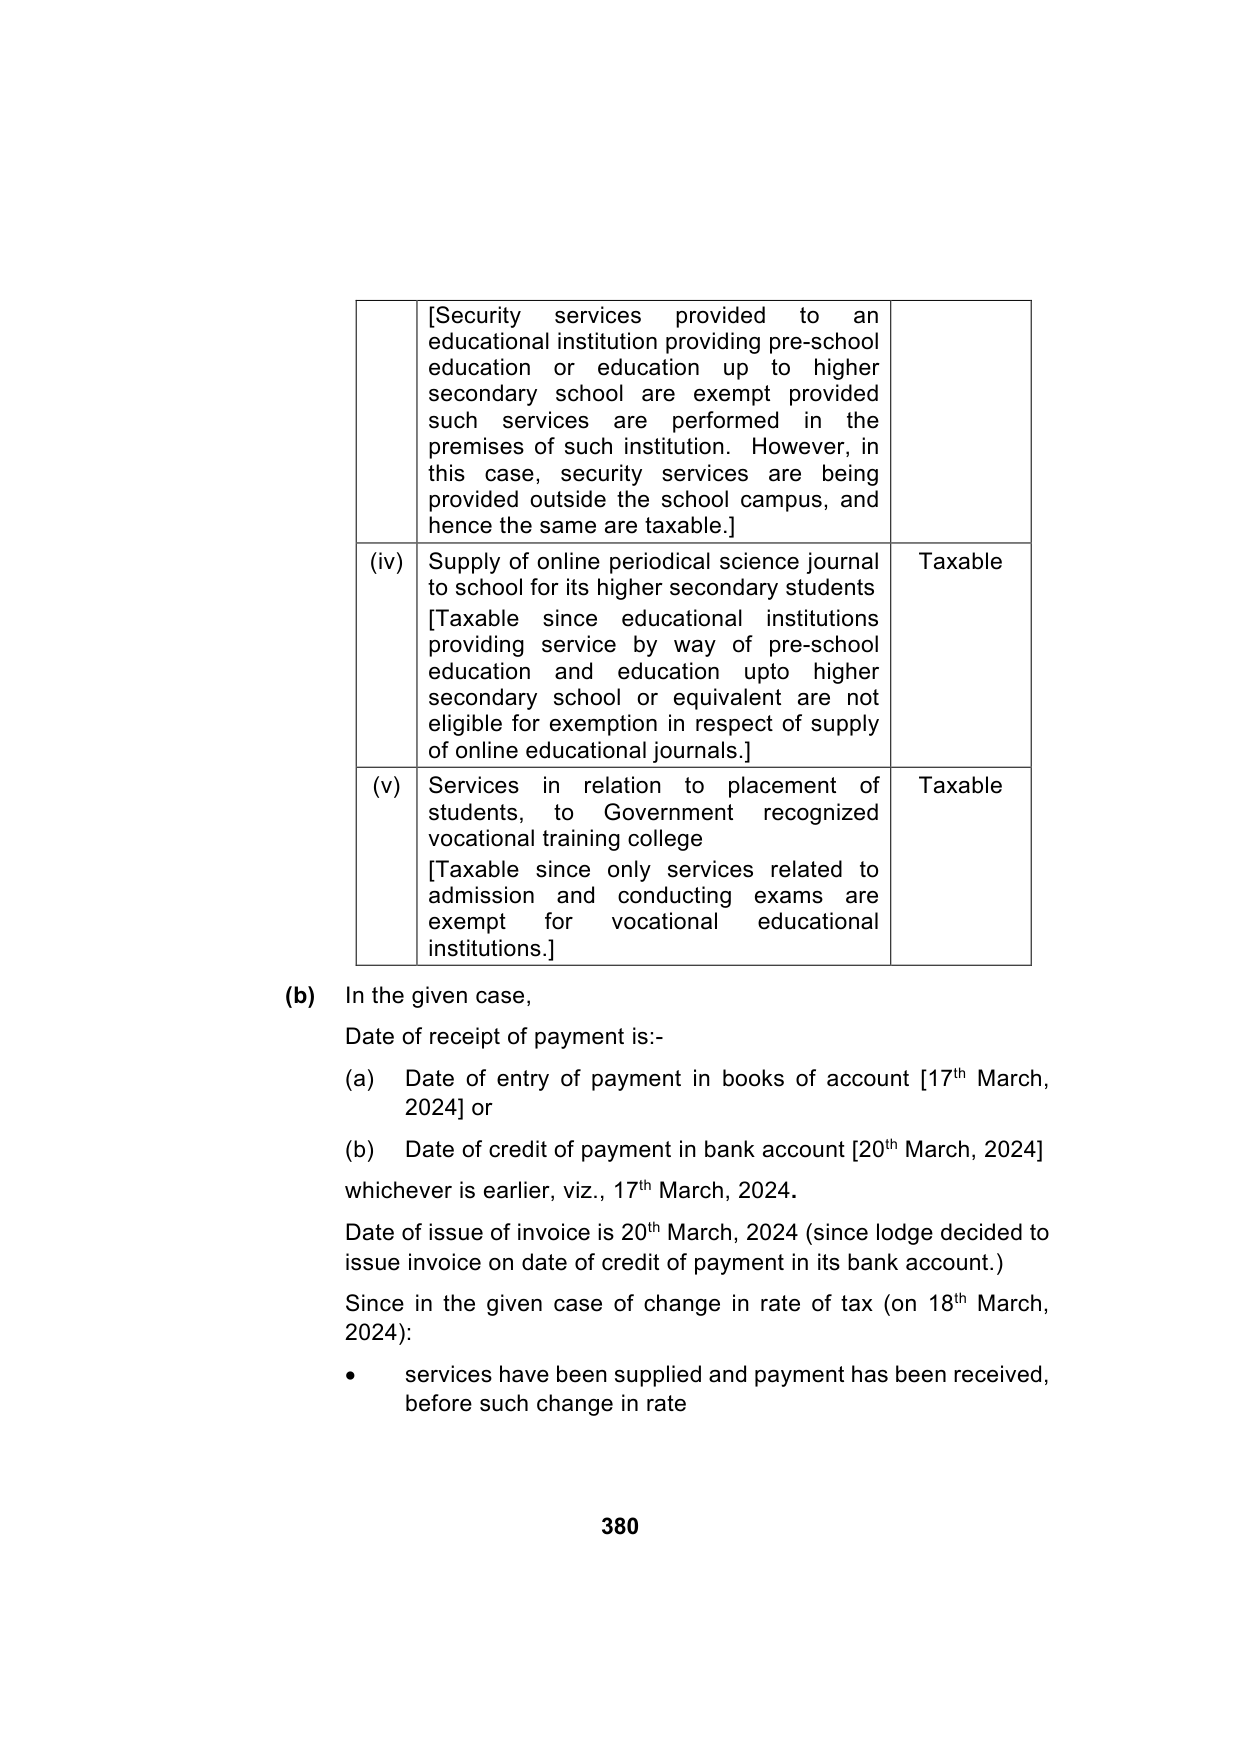
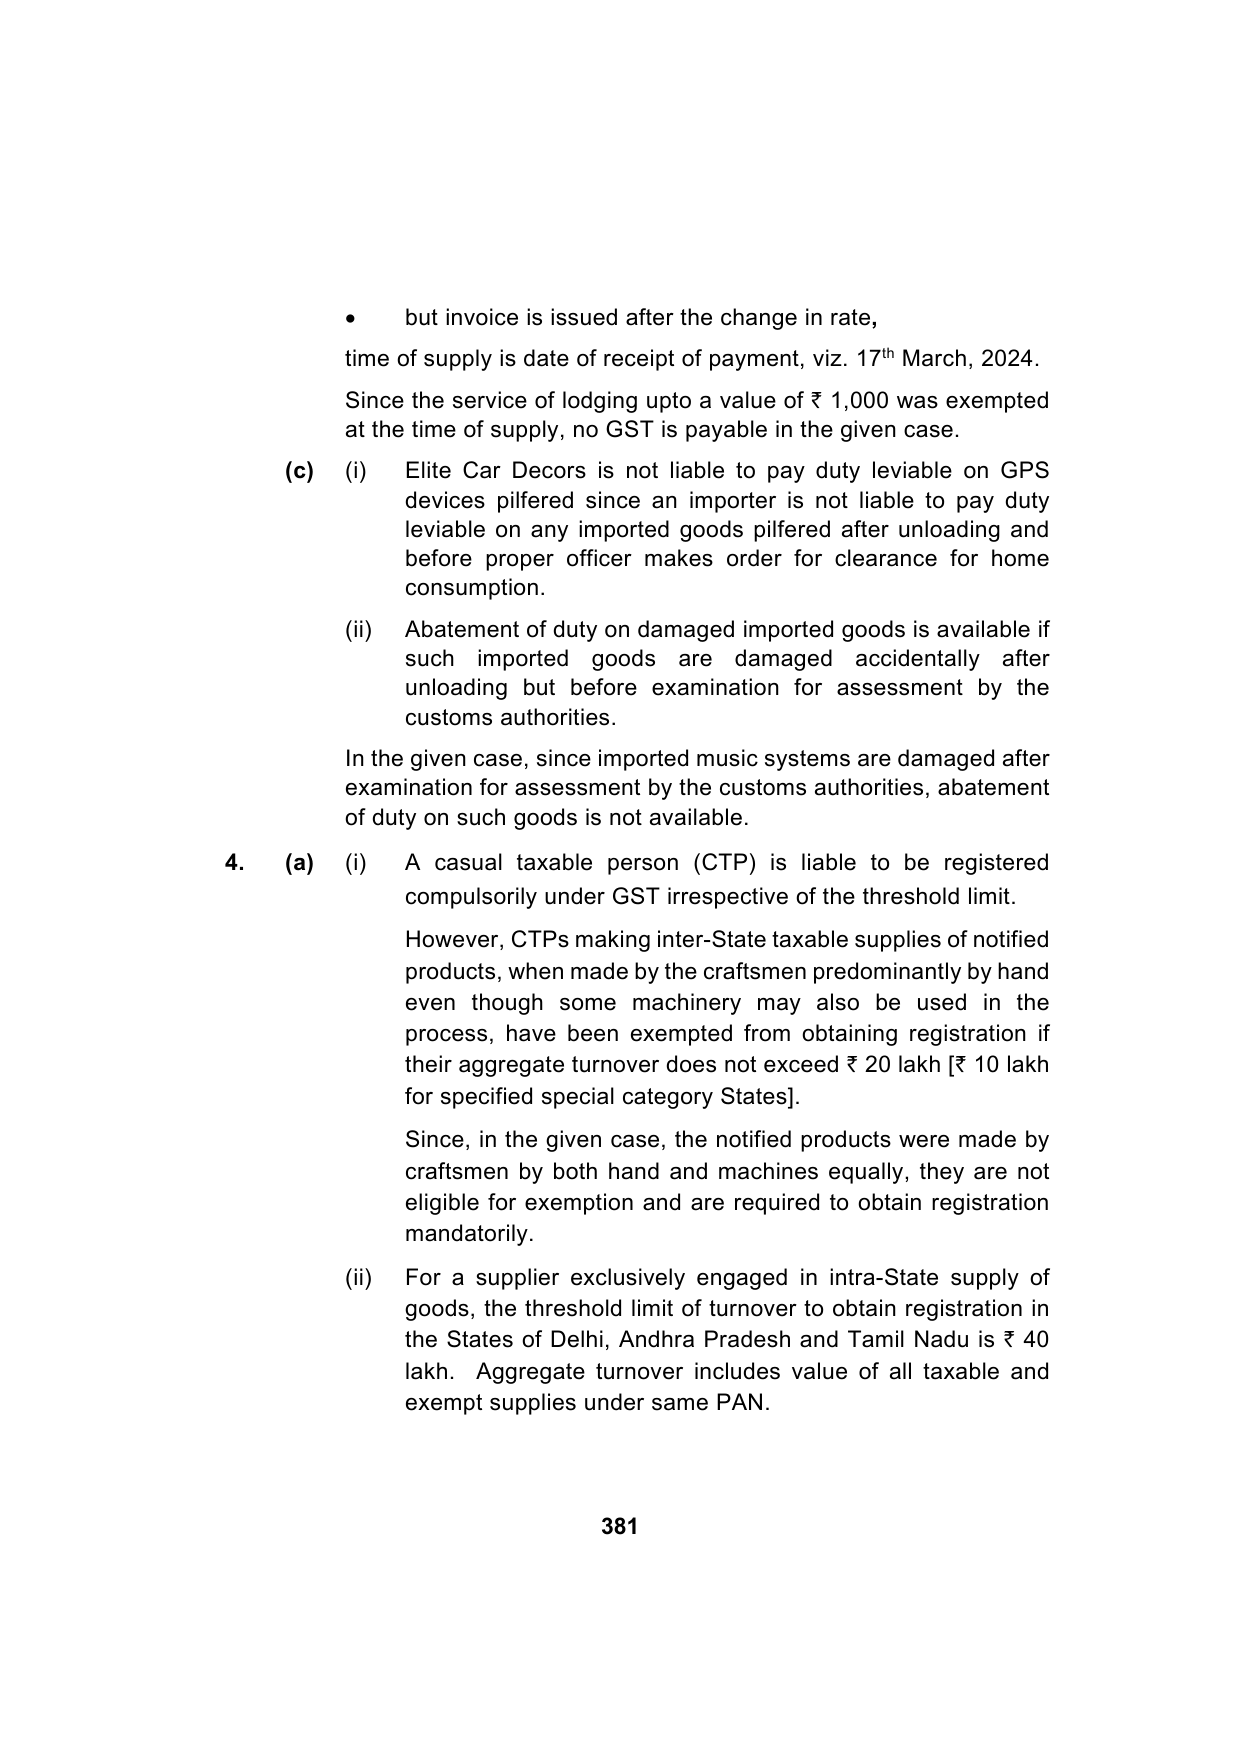
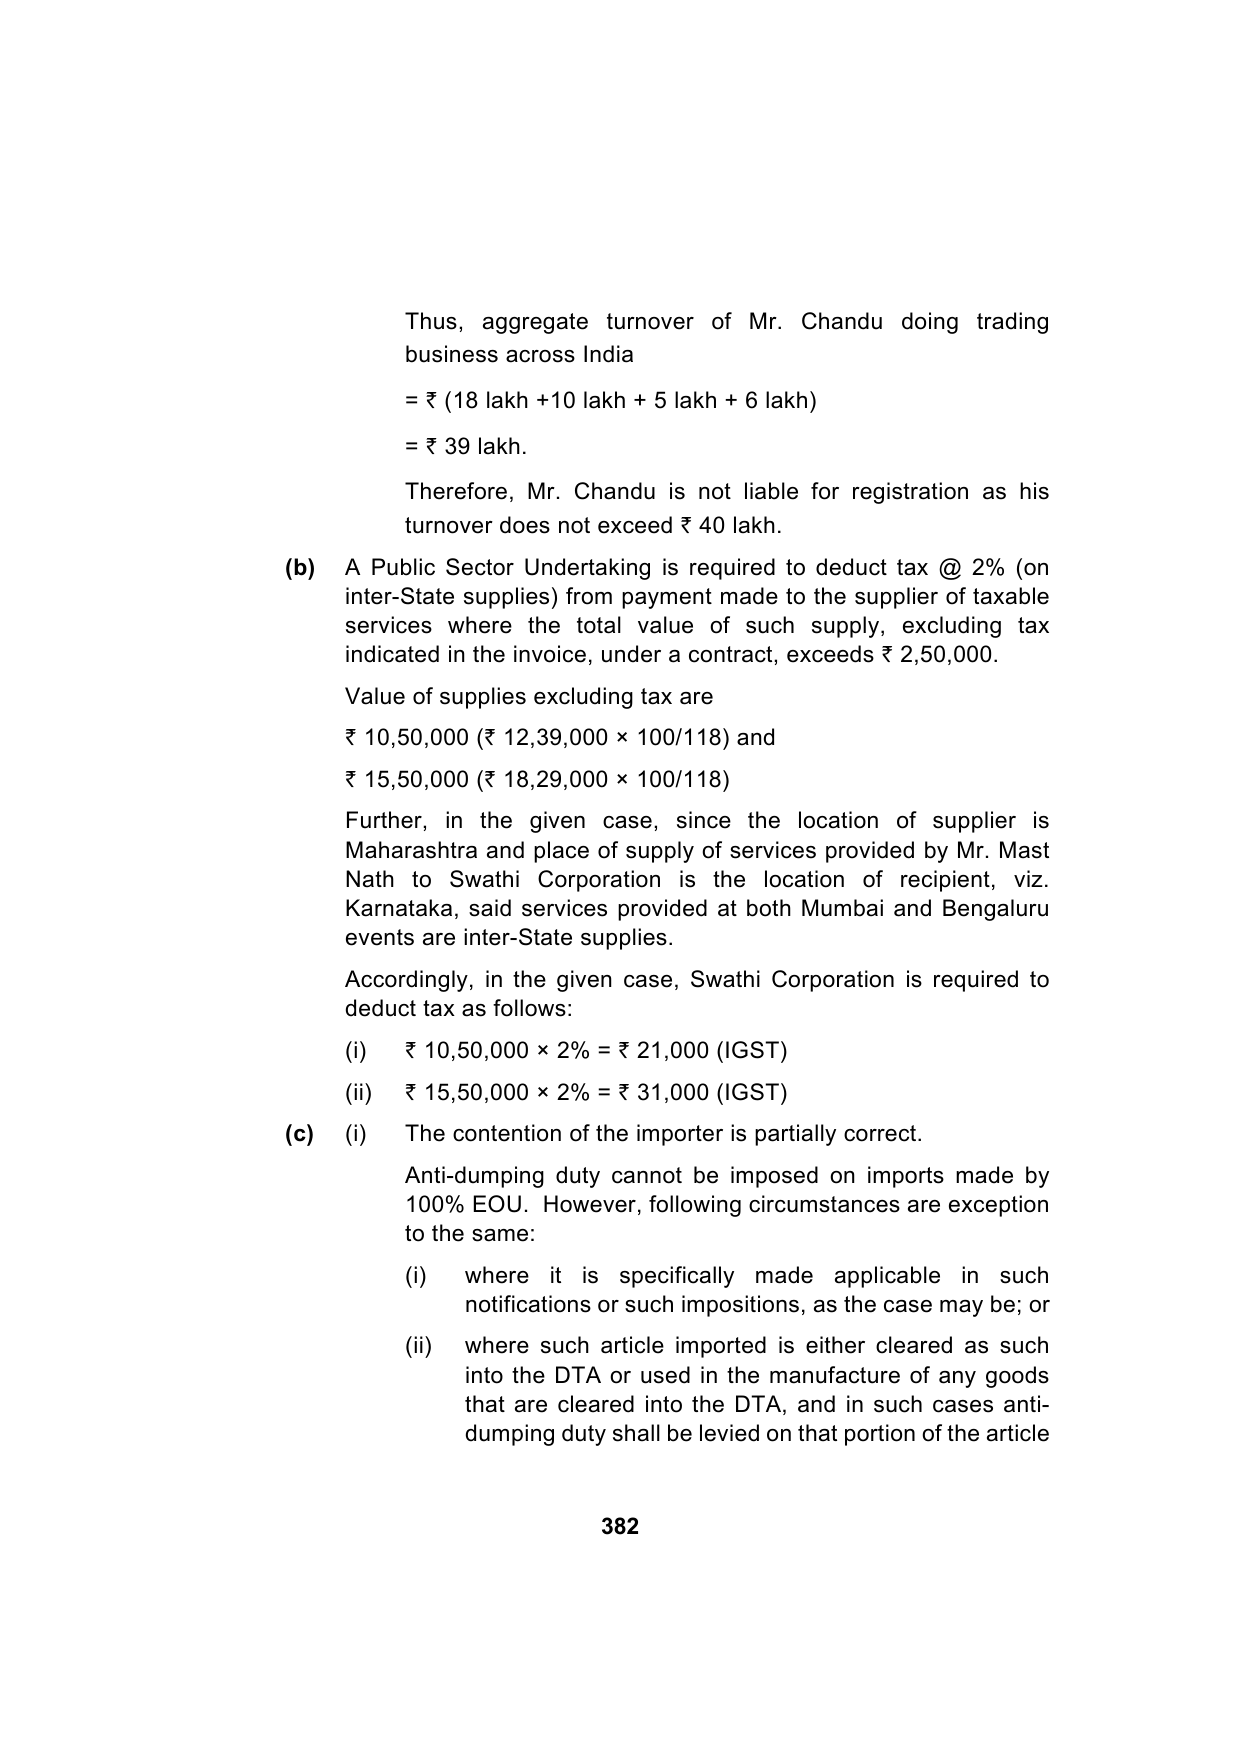
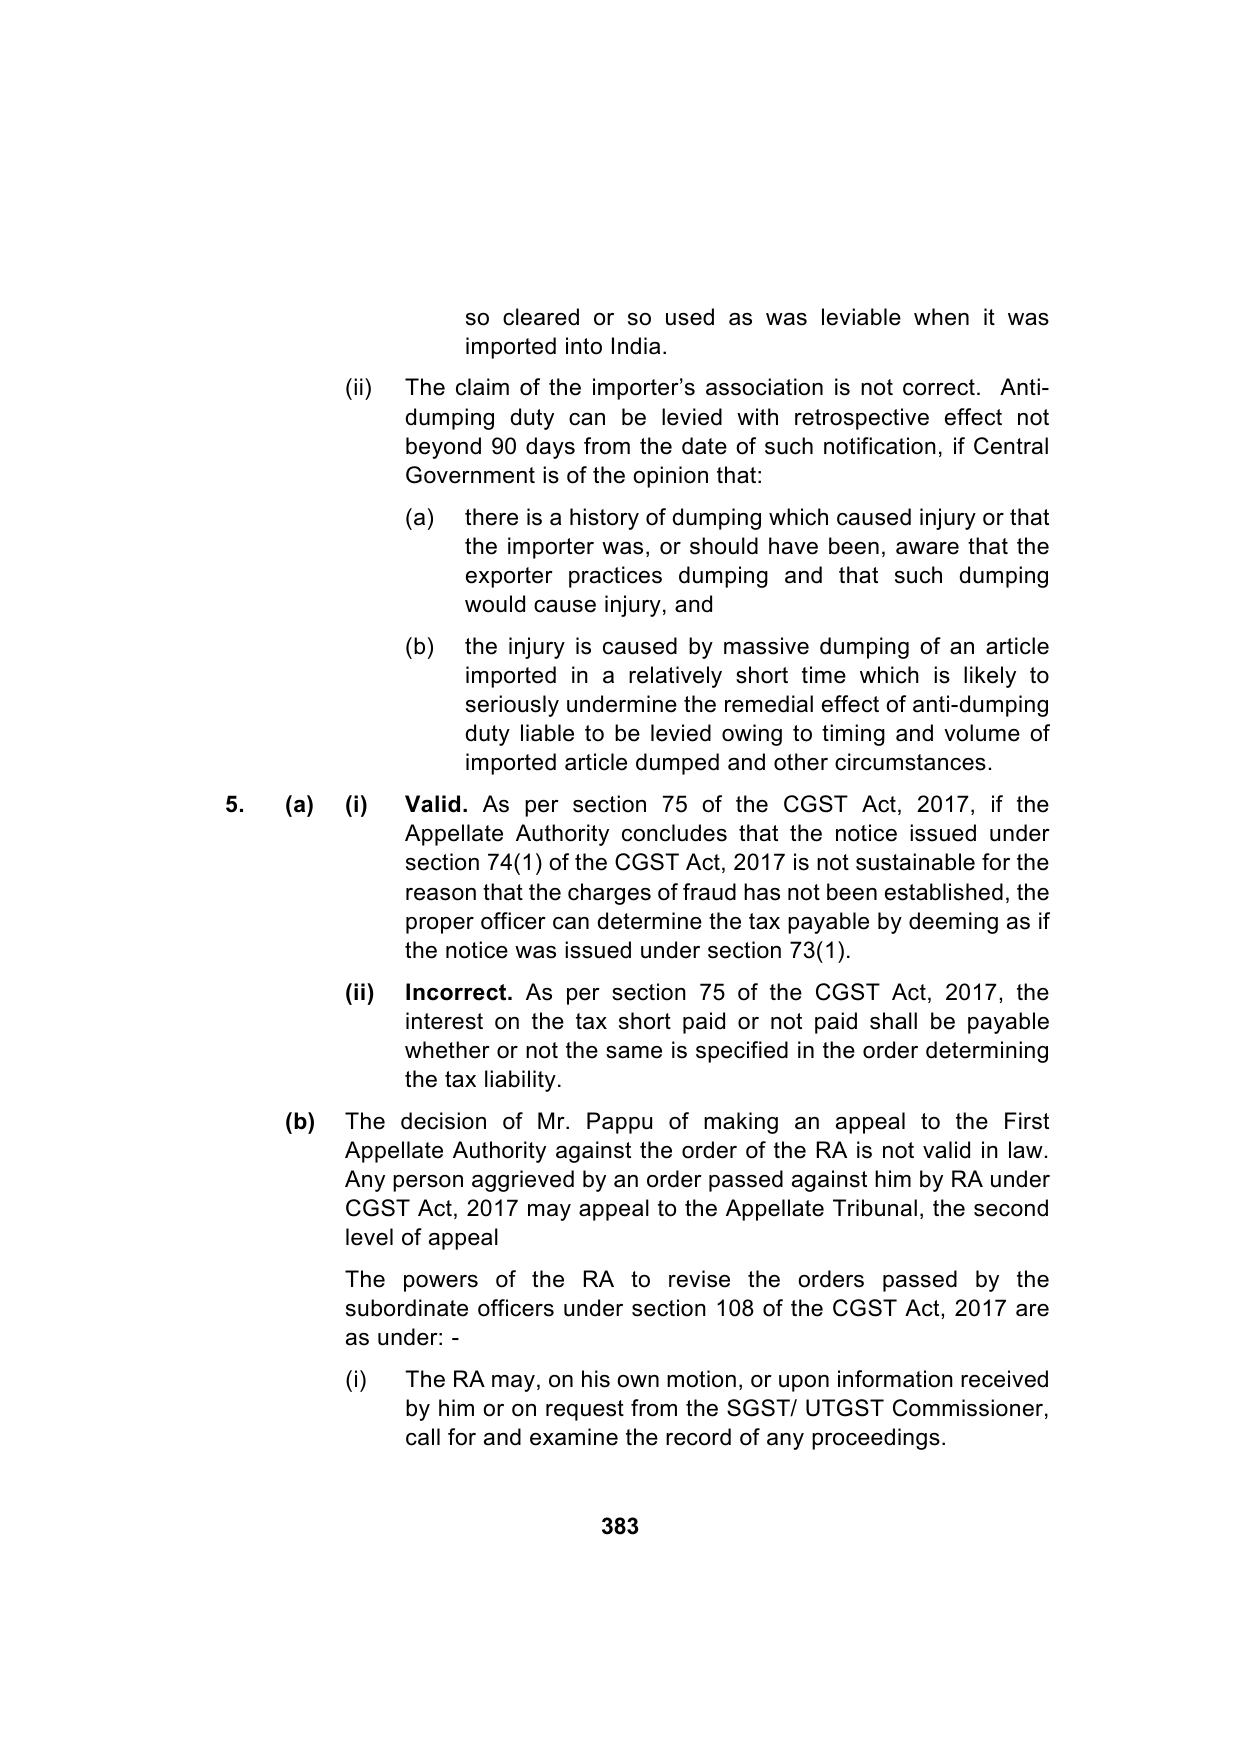
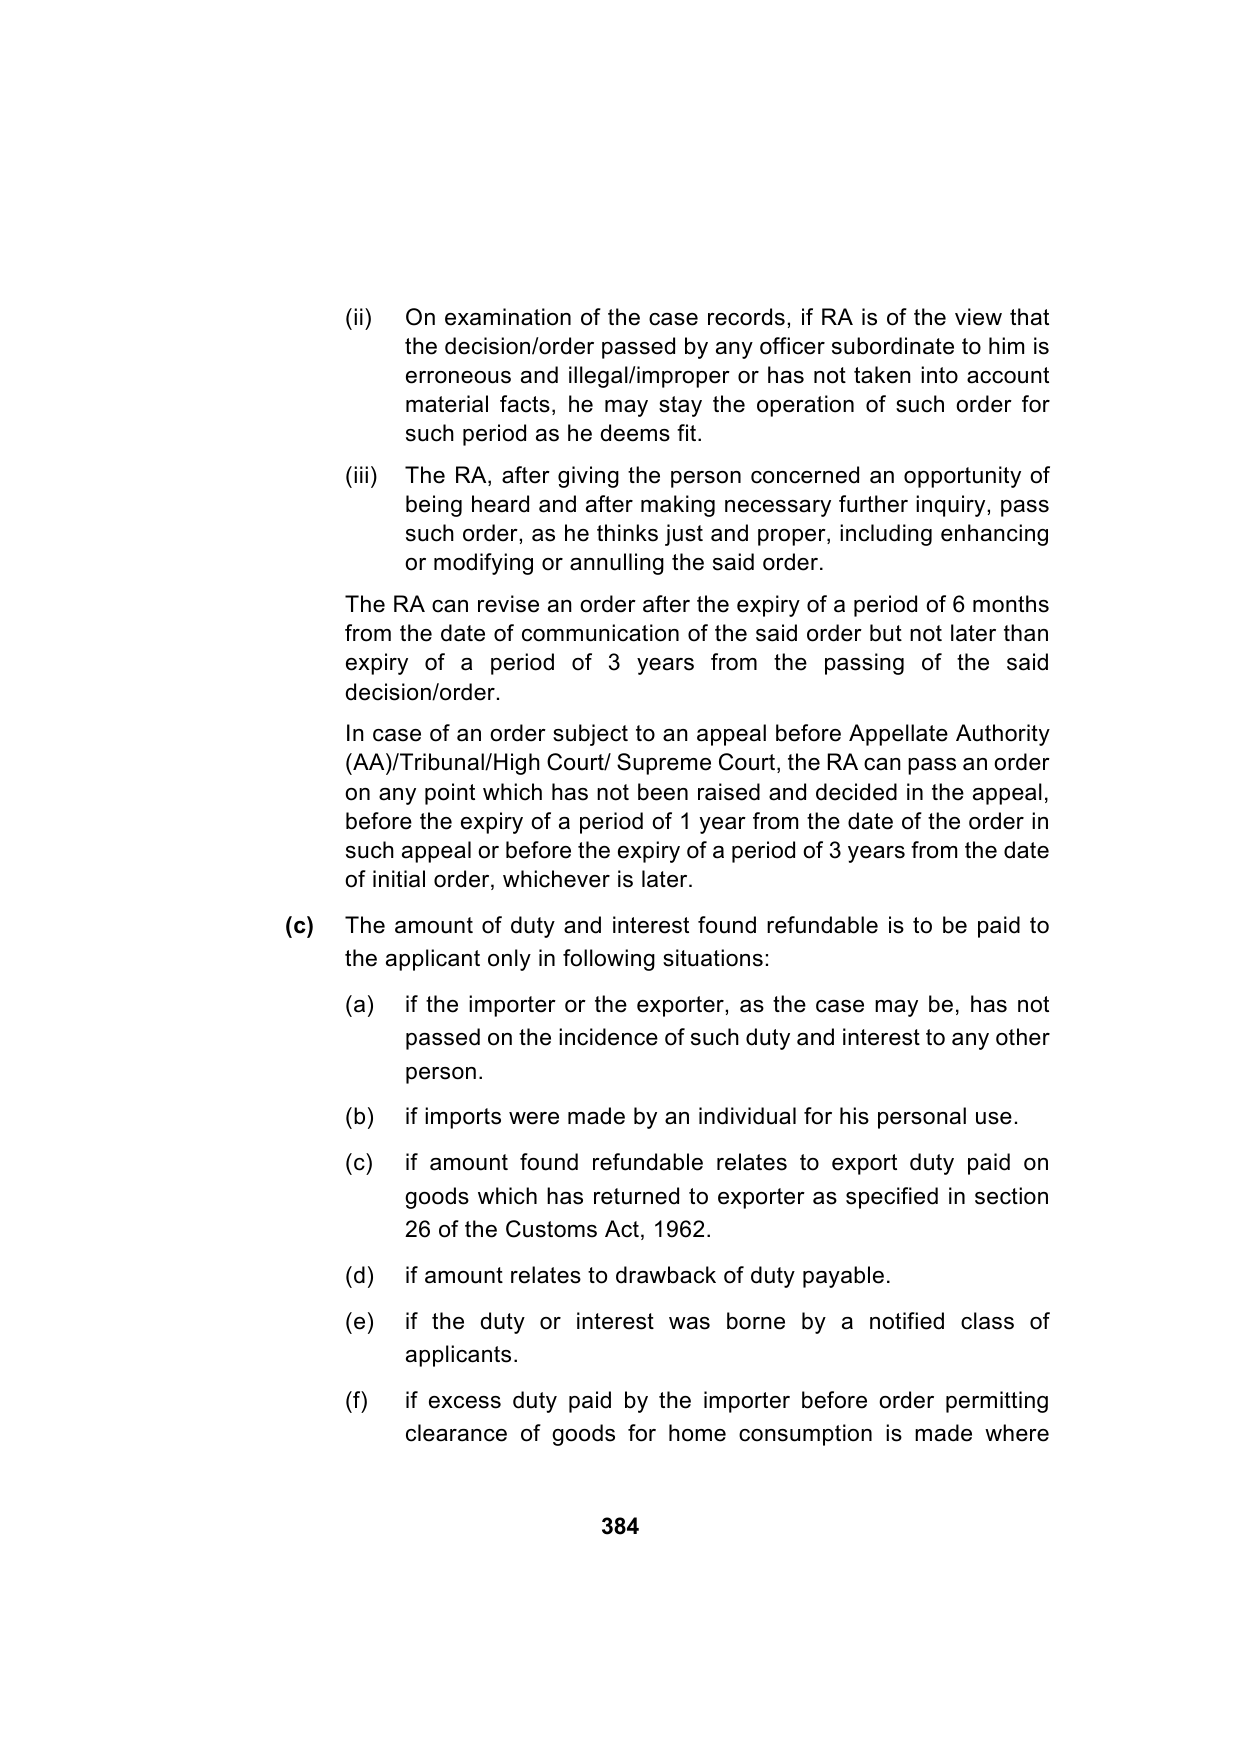
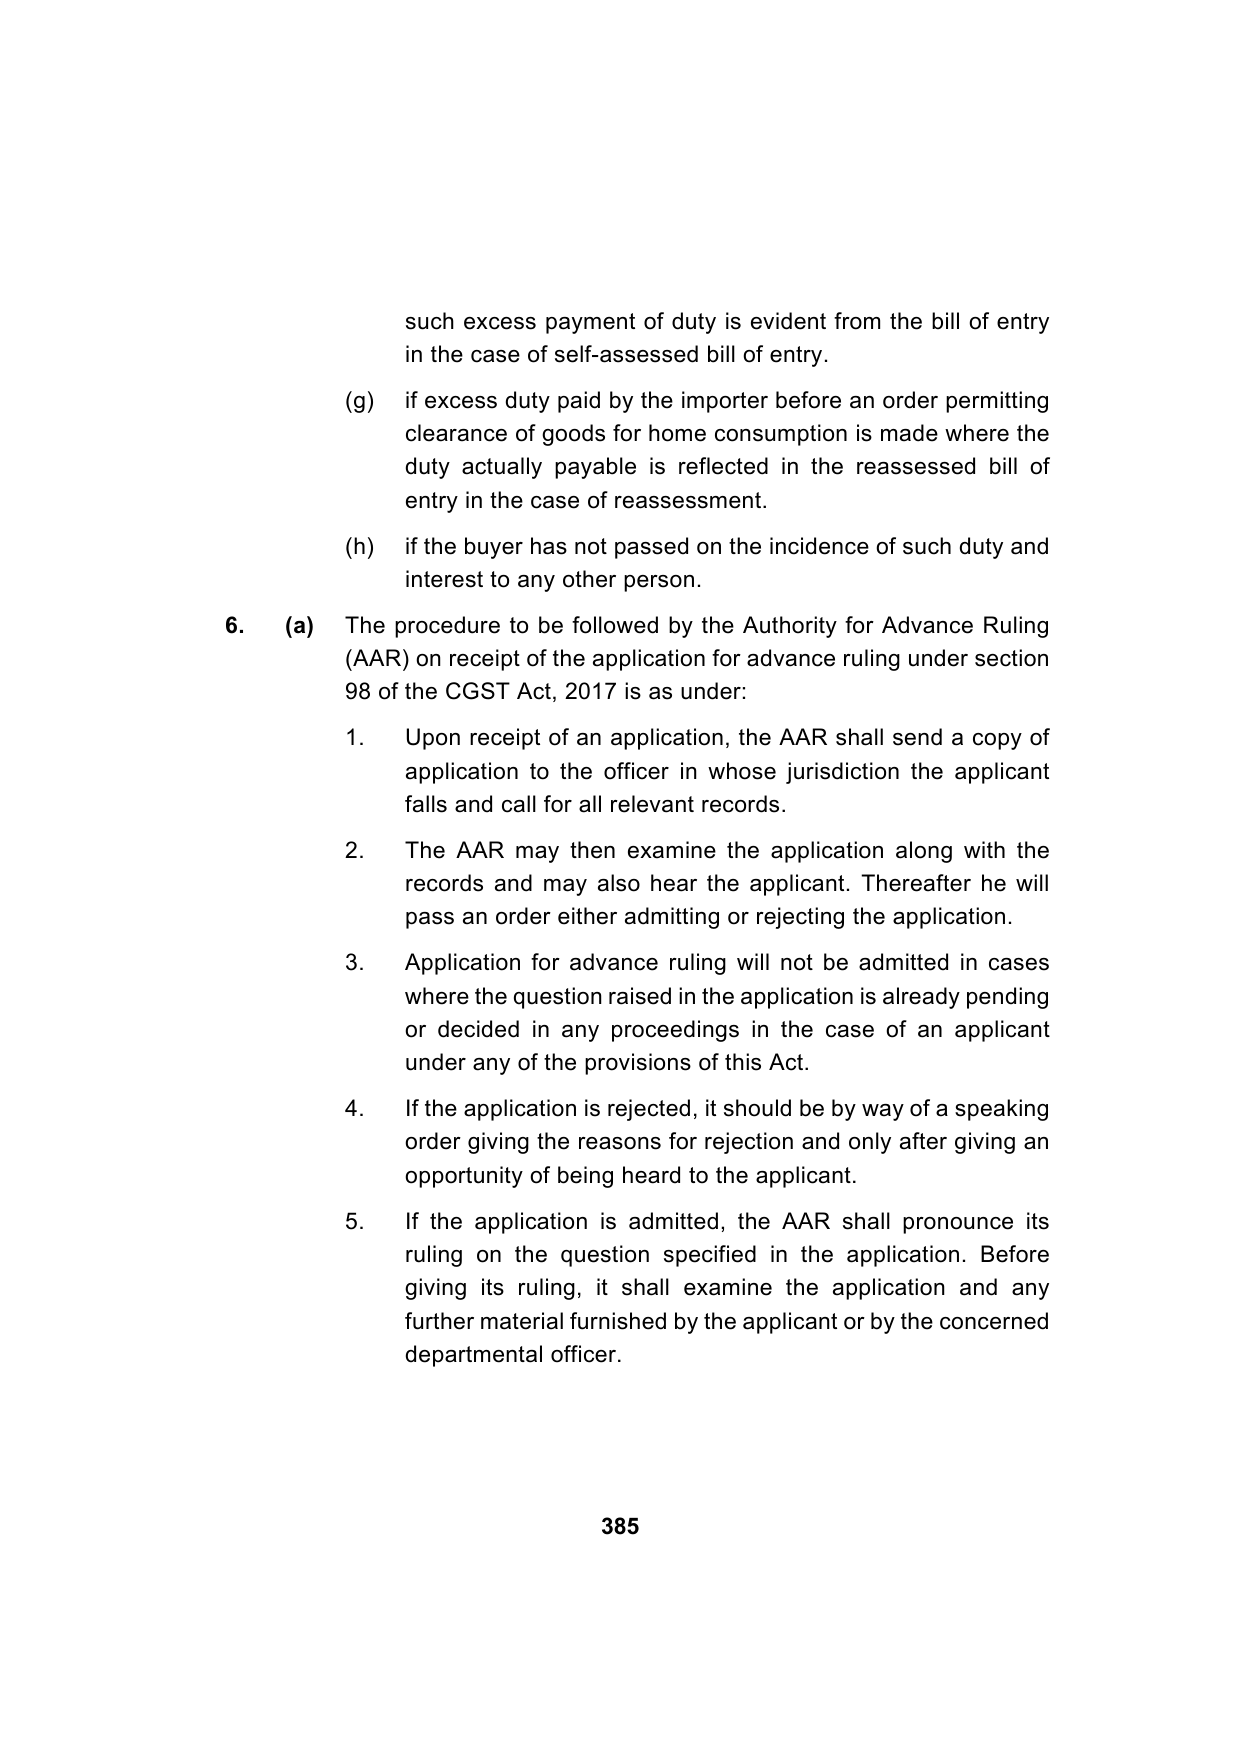
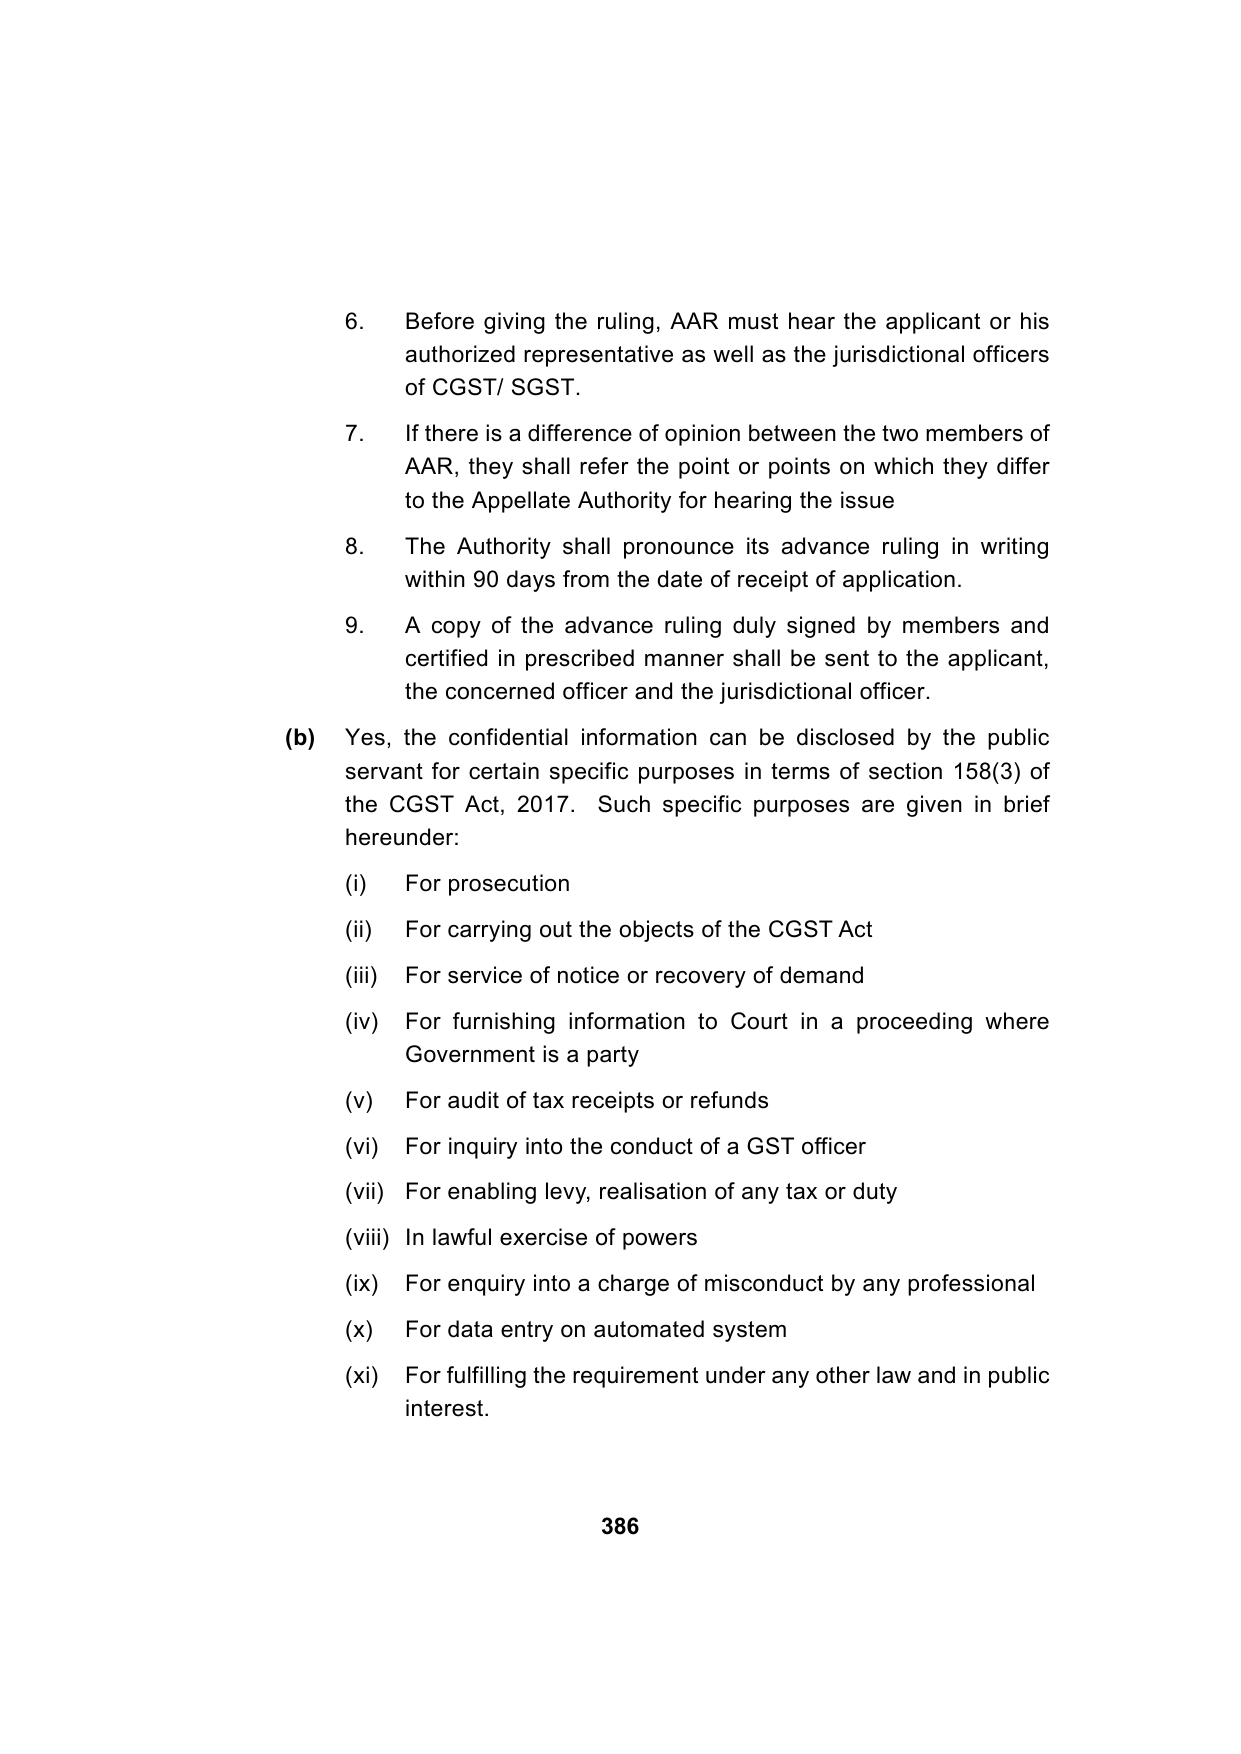
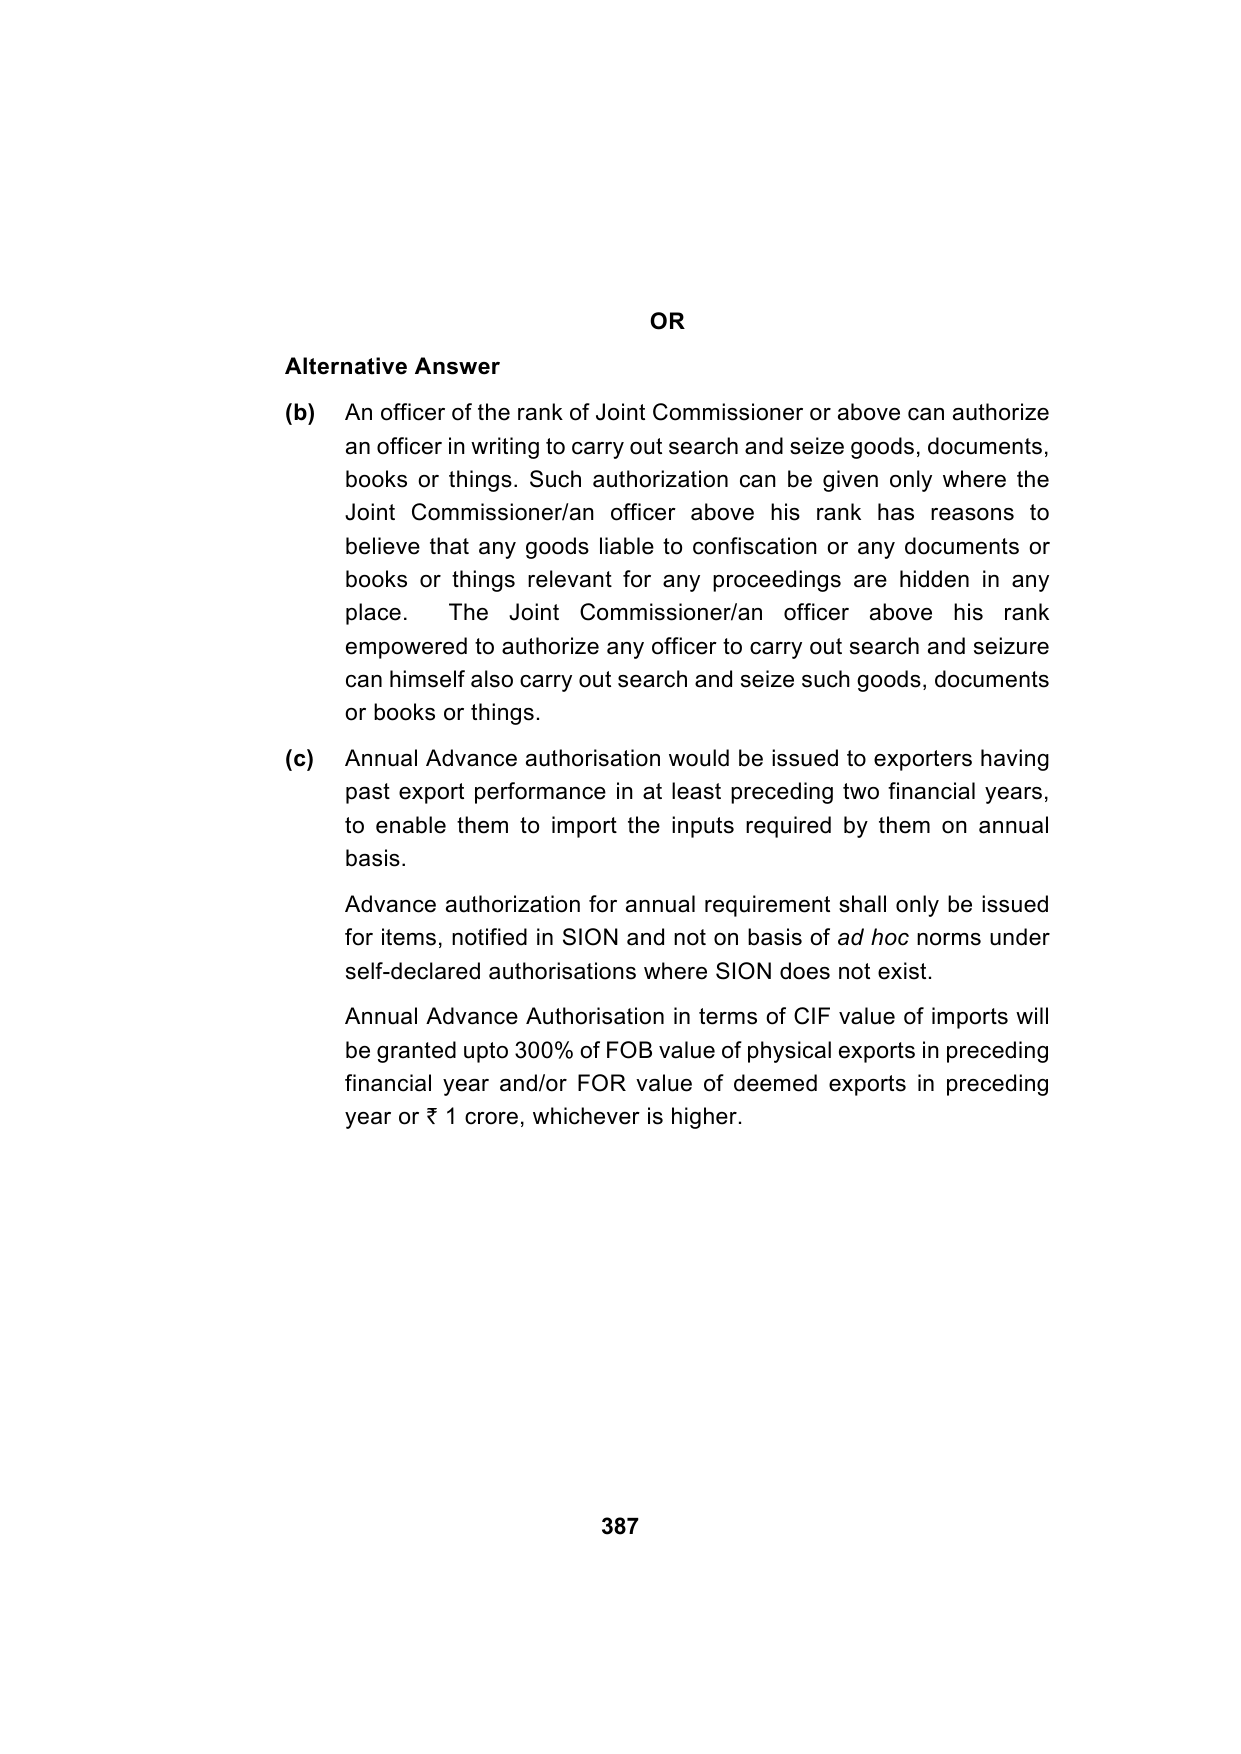
Paper 5: Indirect Tax Laws — Model Test Paper 4 (100 marks)
Question
Answer
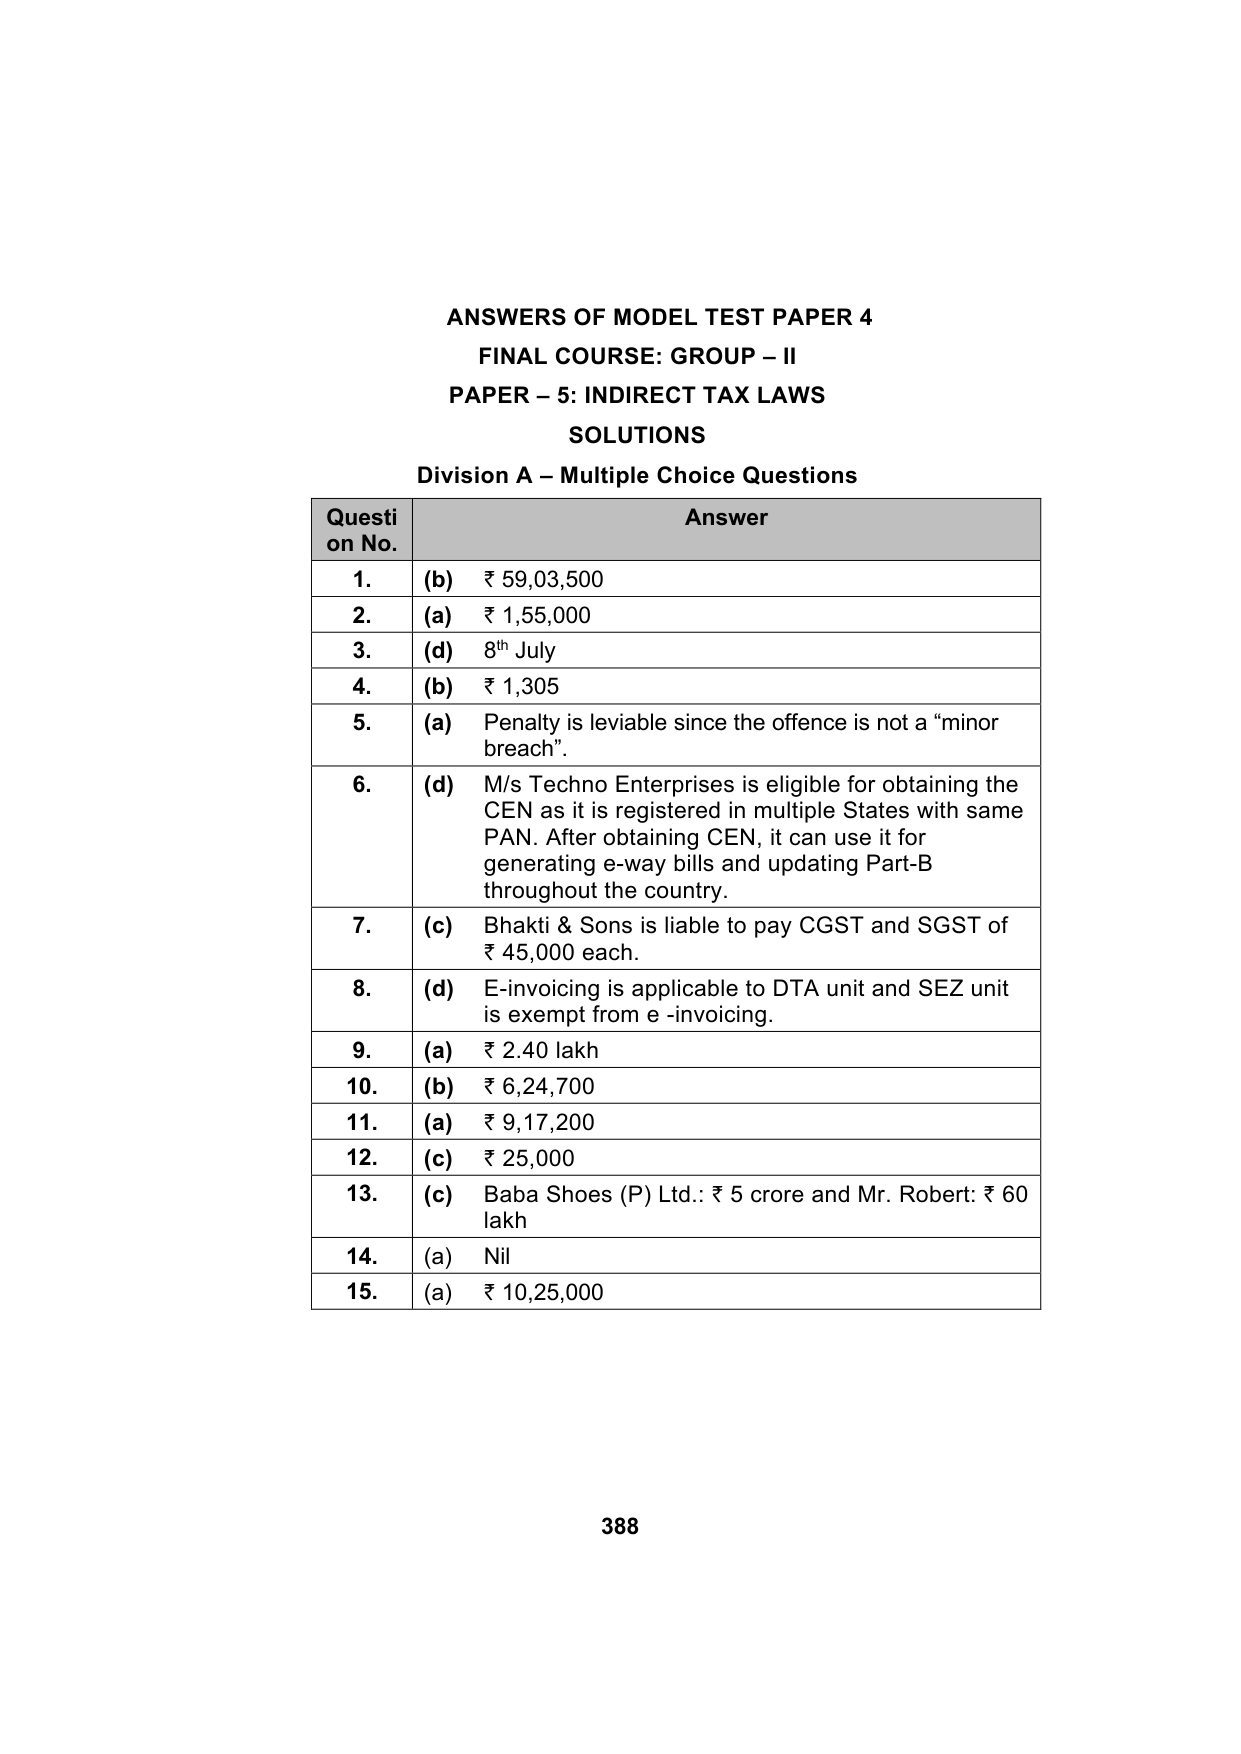
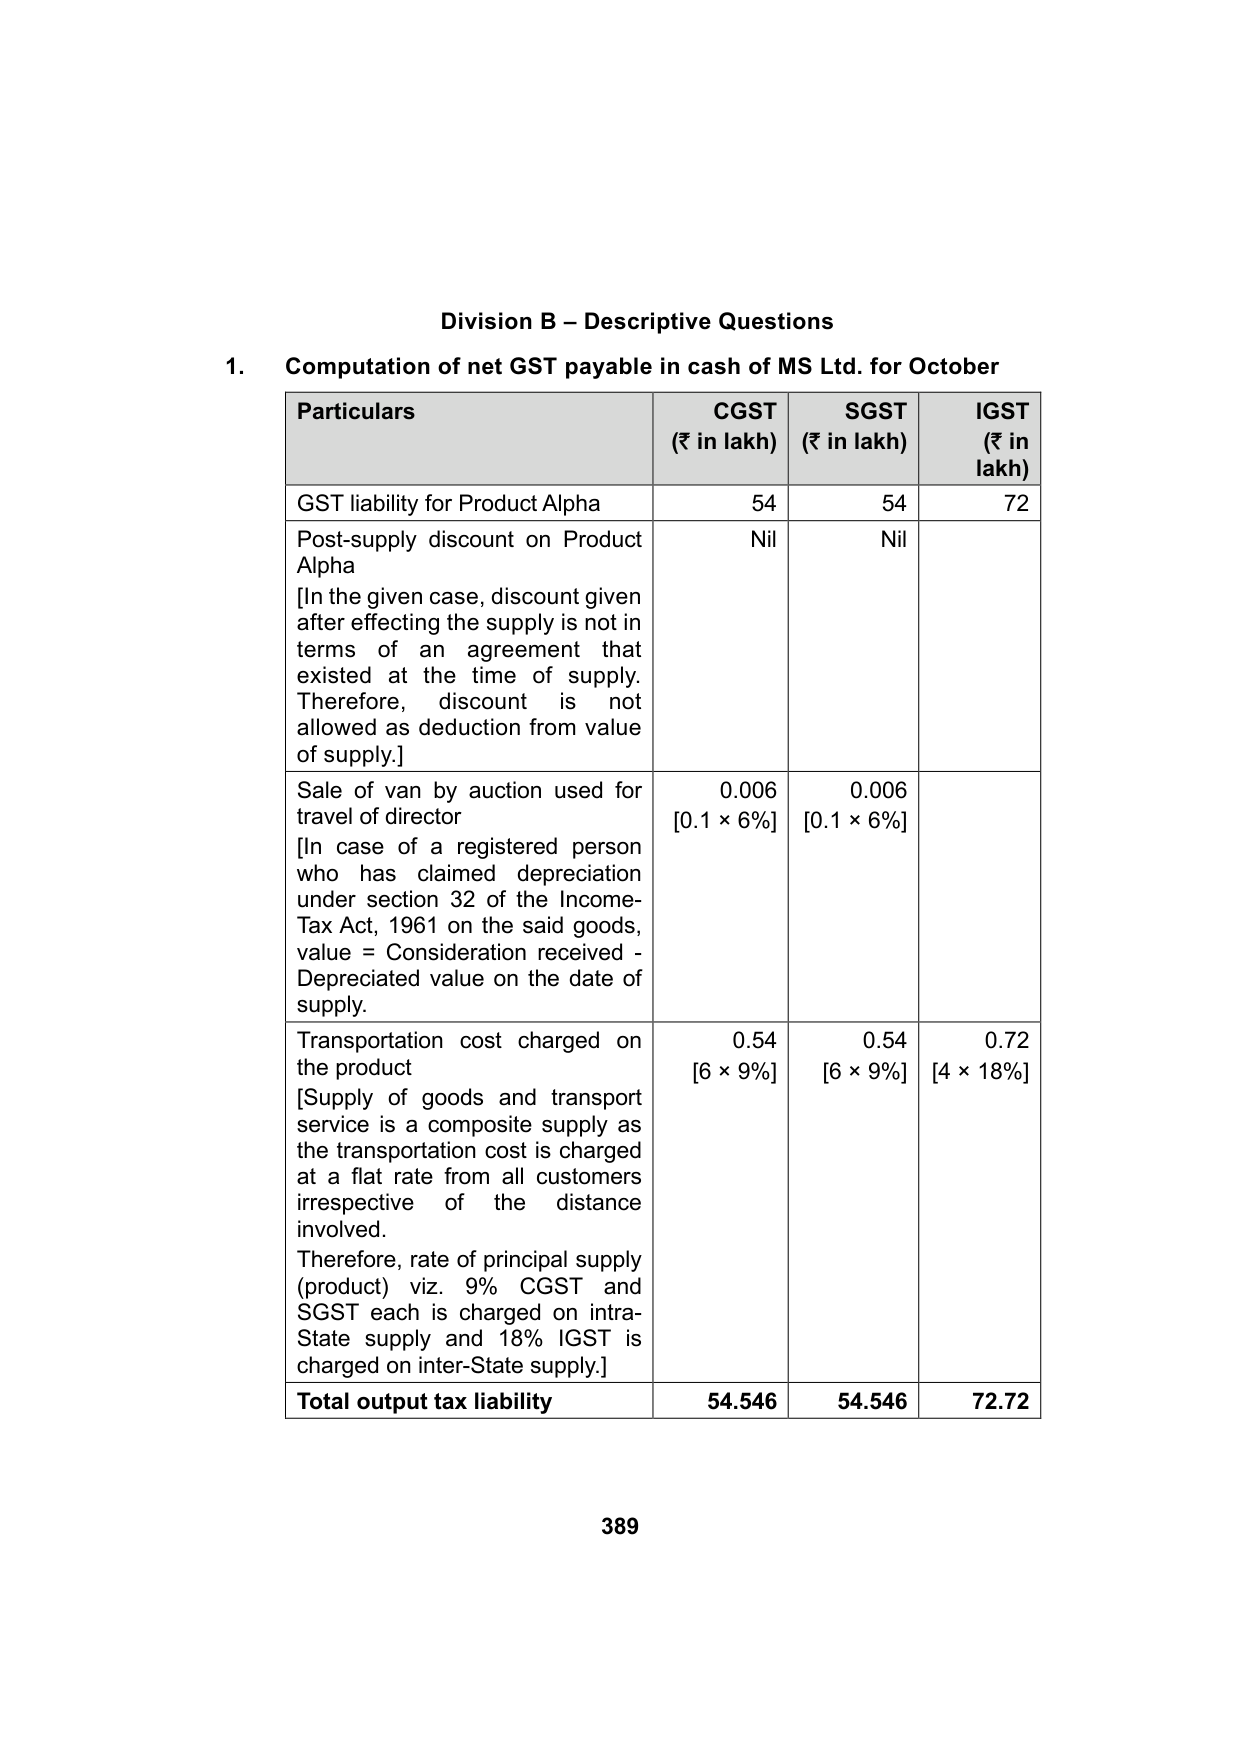
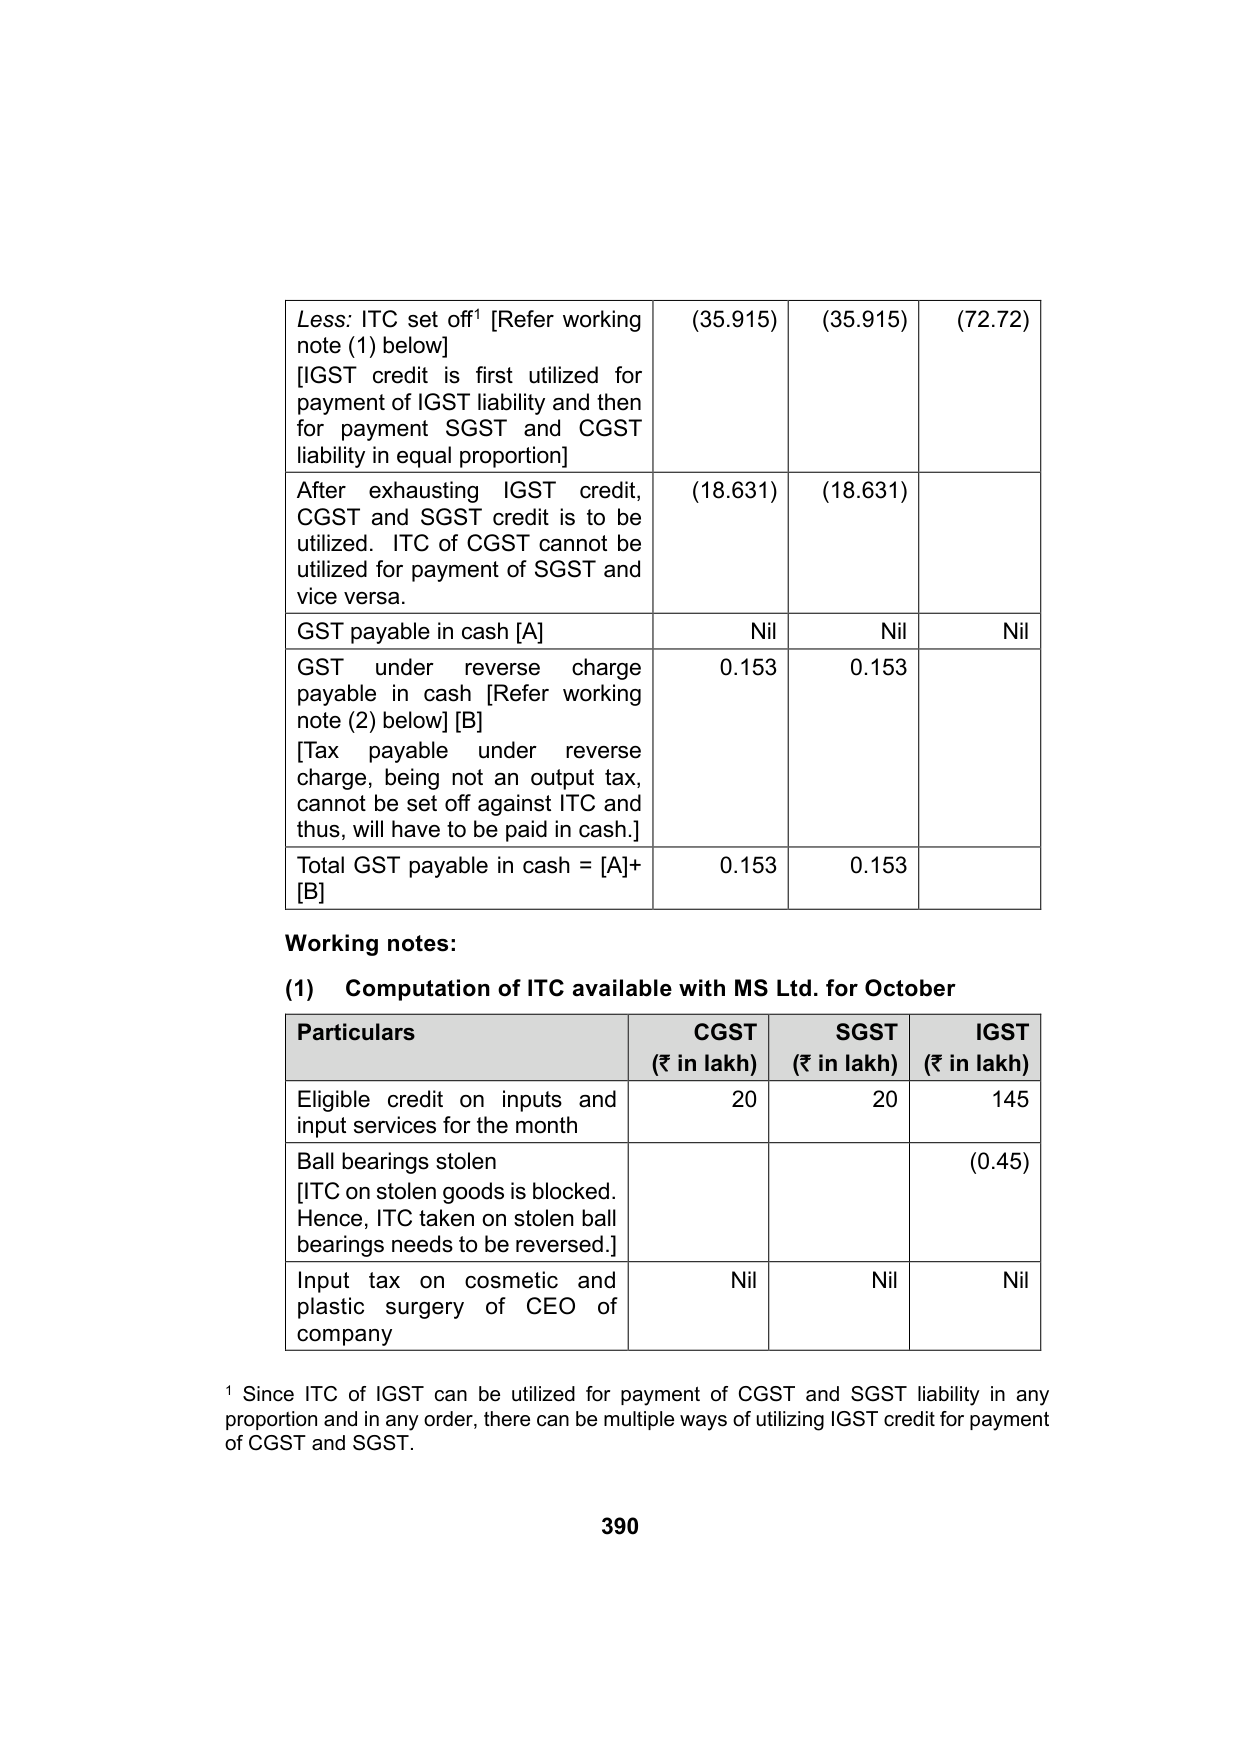
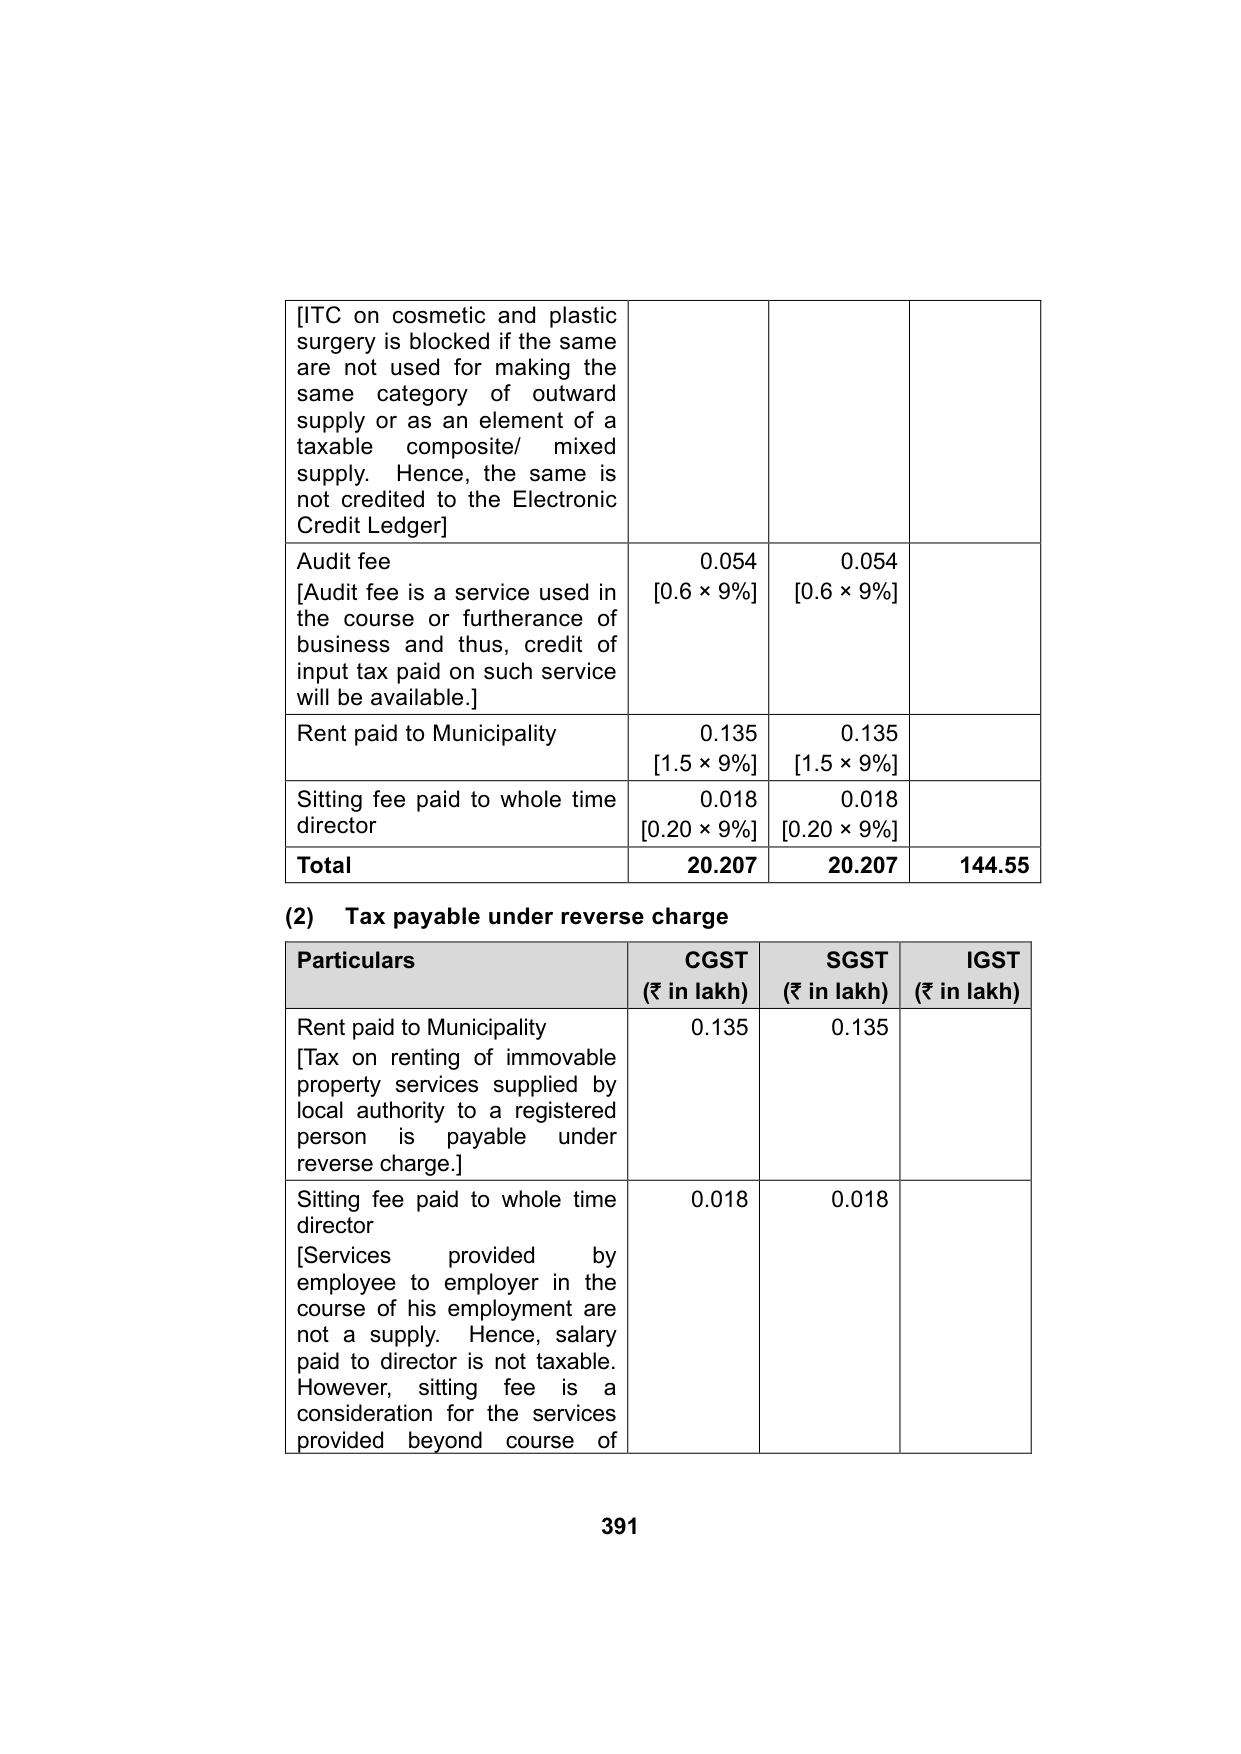
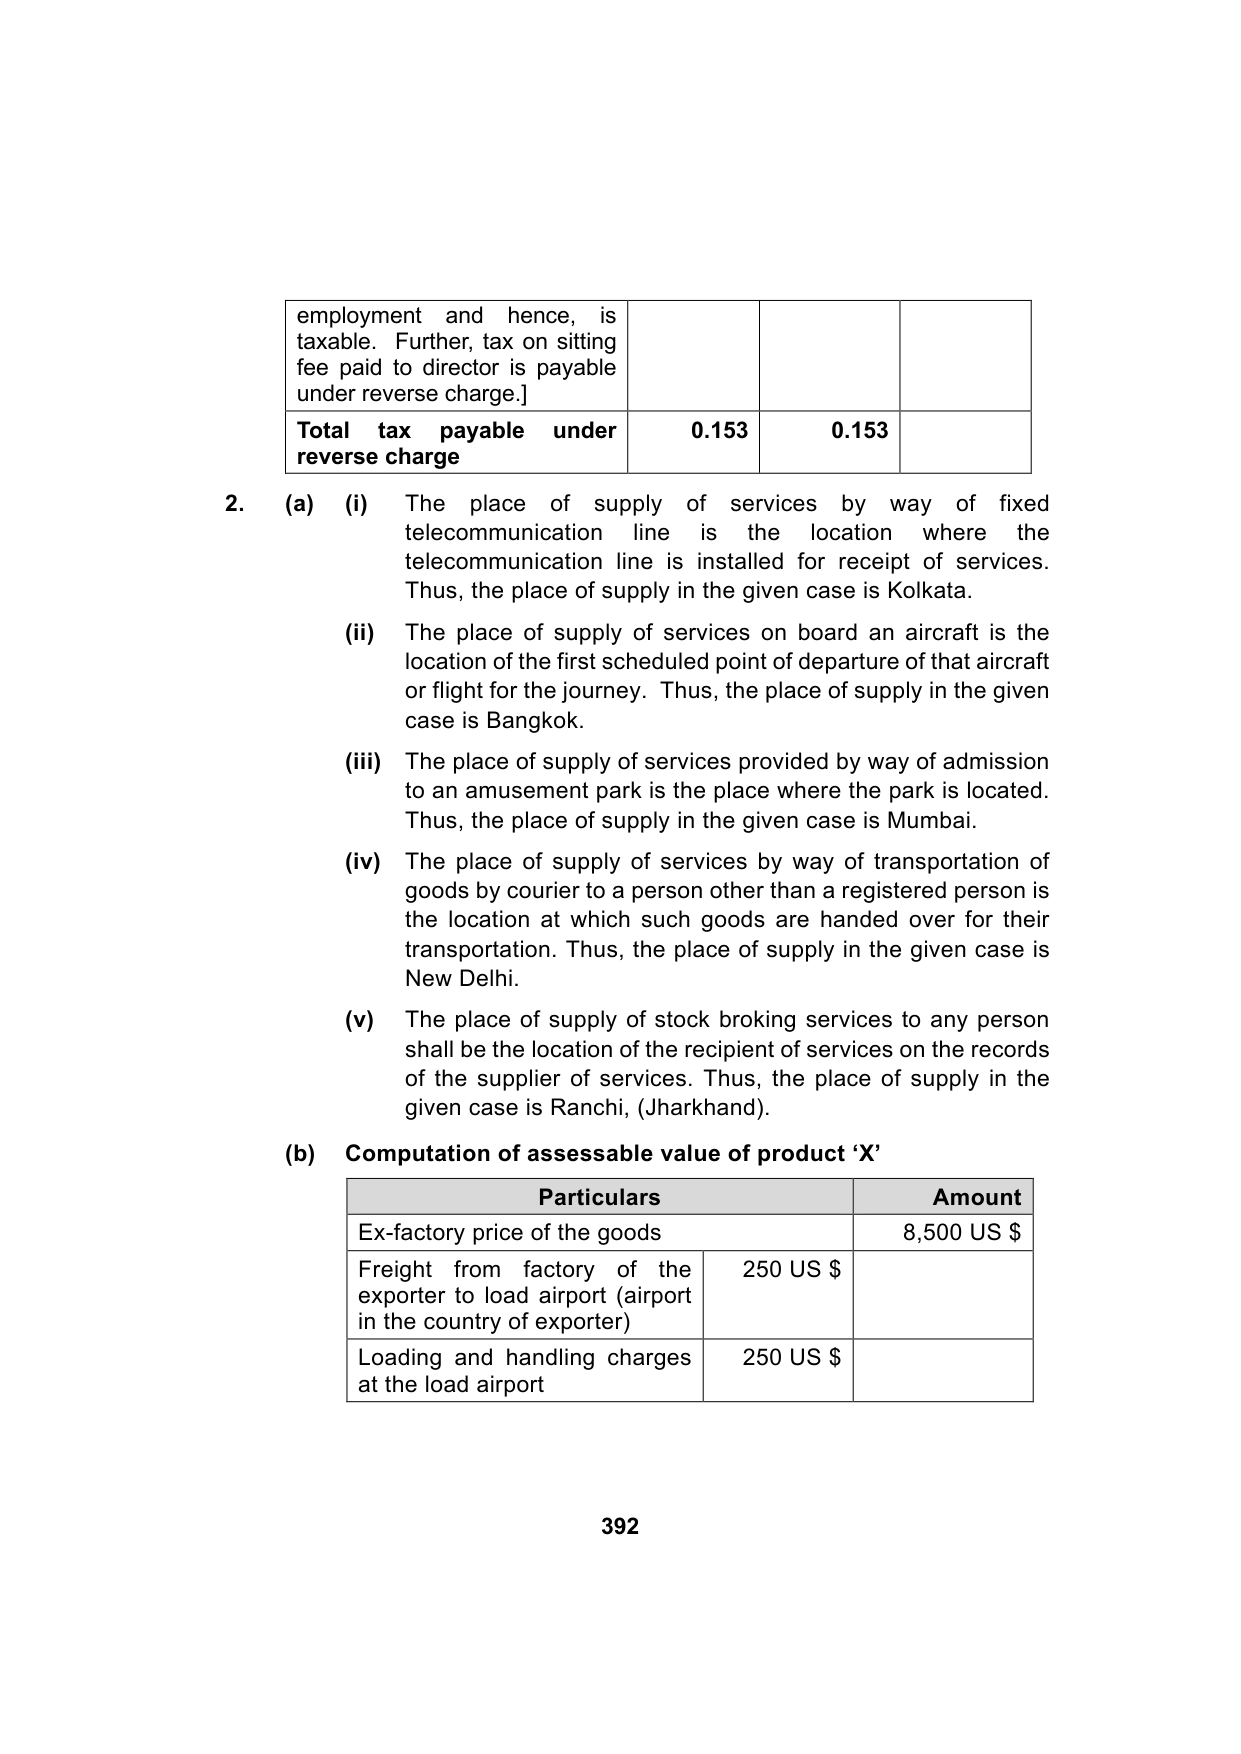
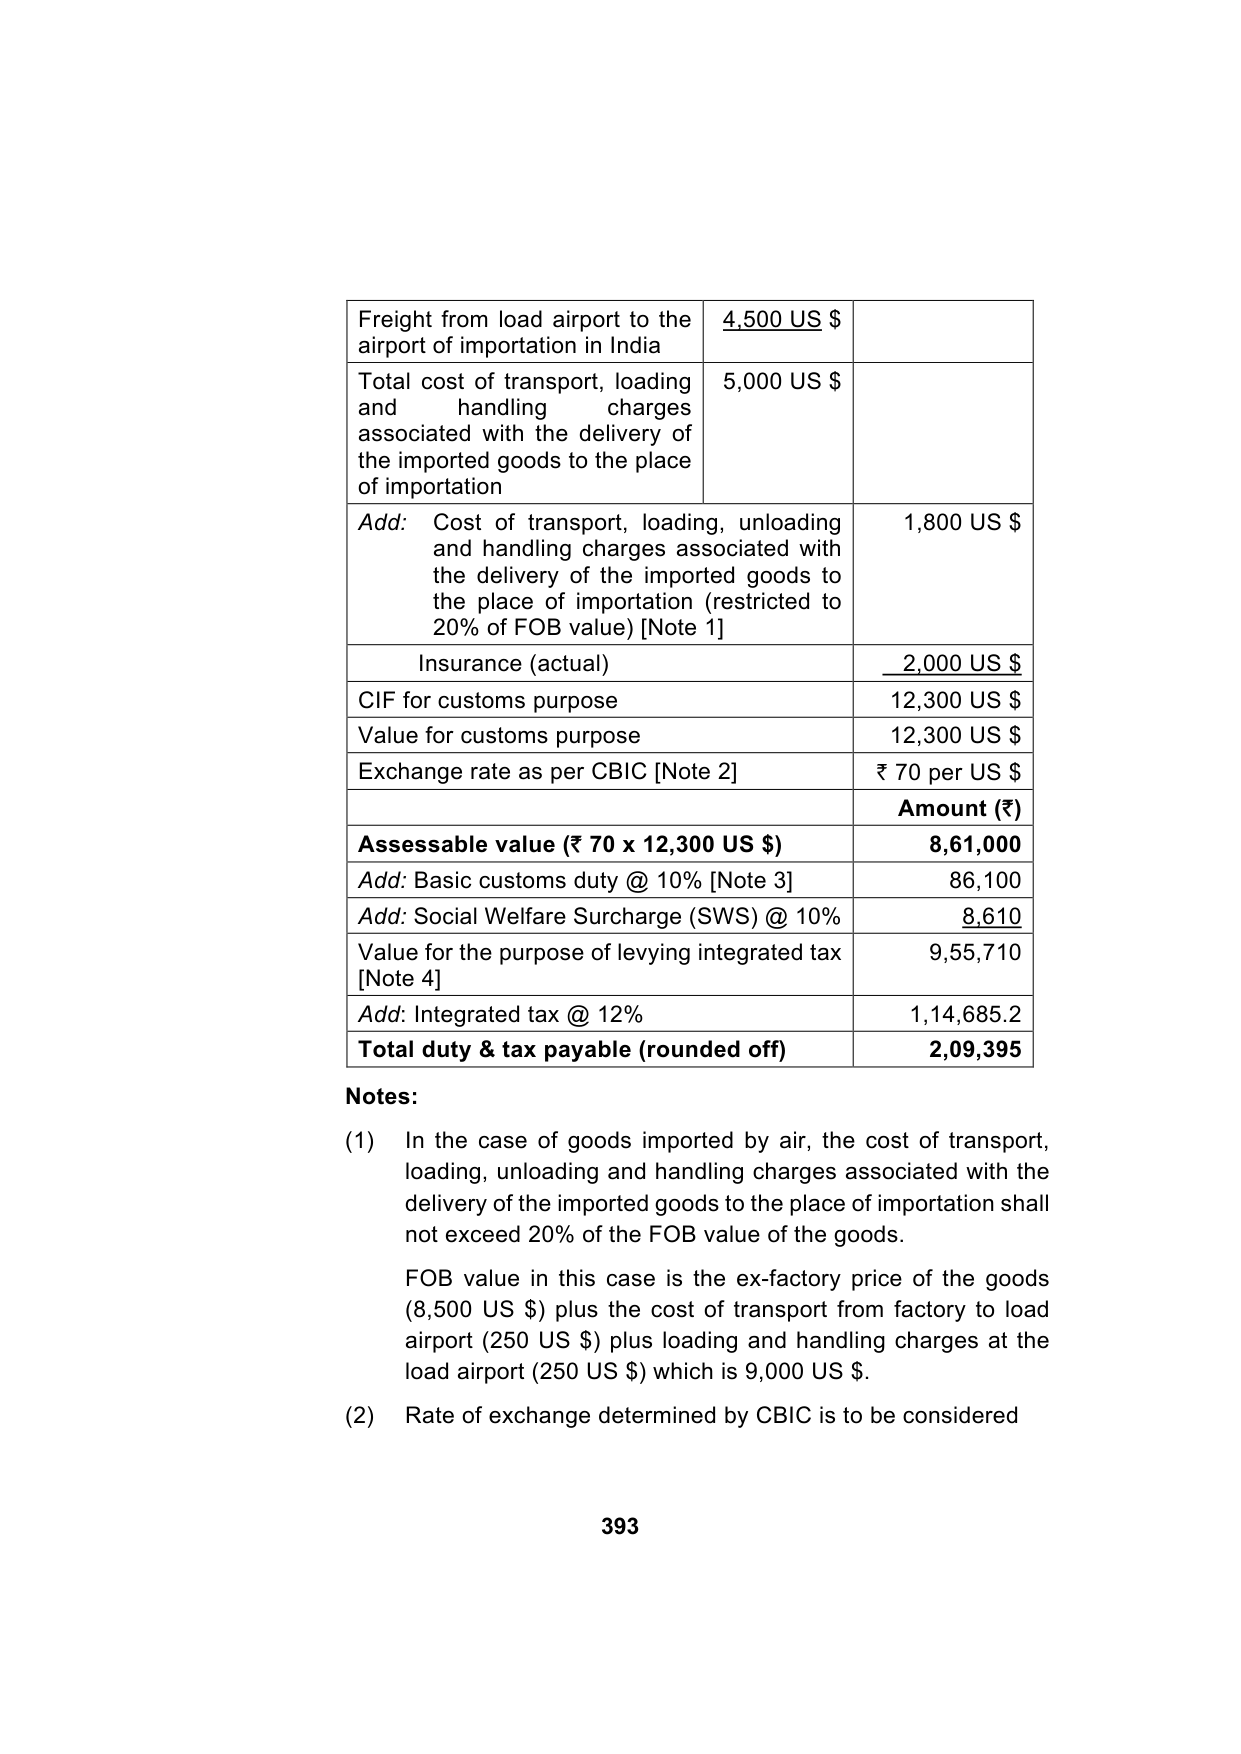
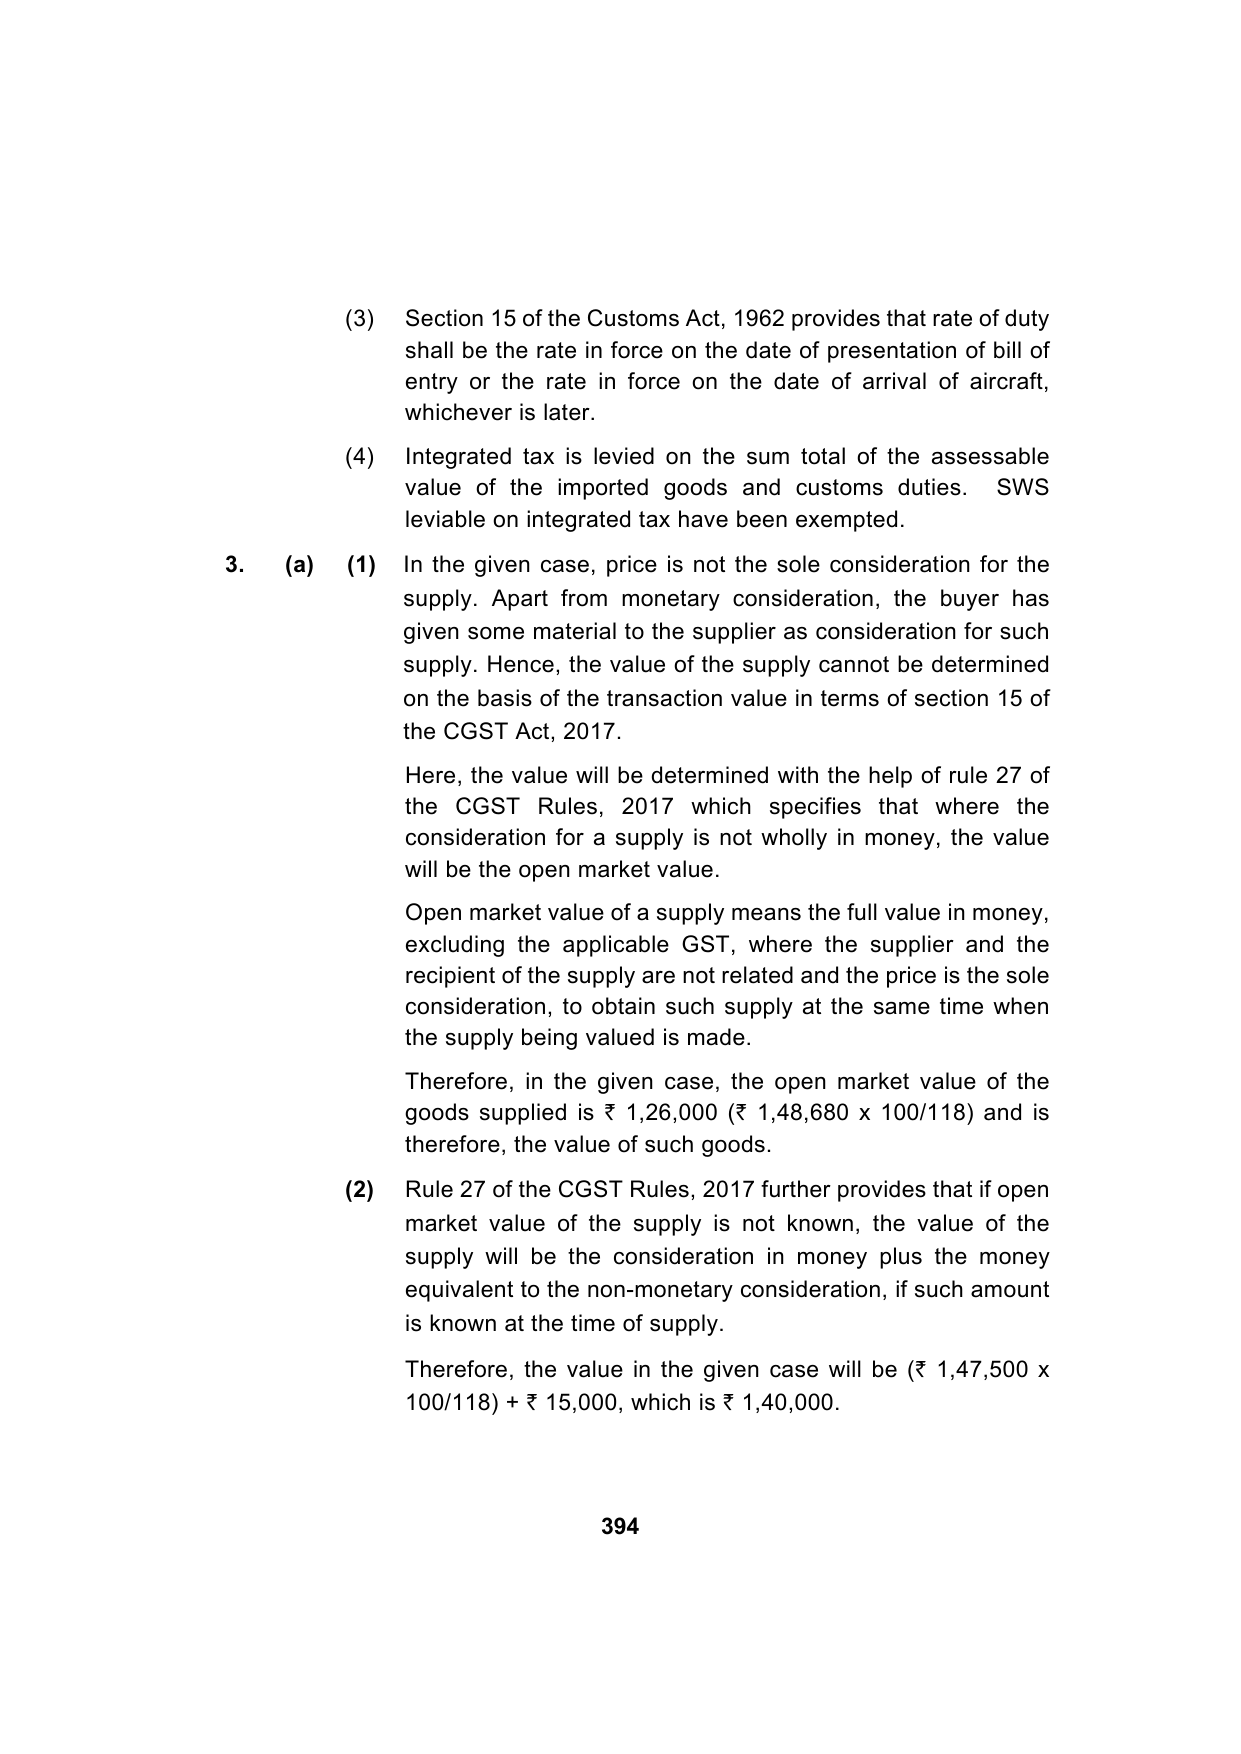
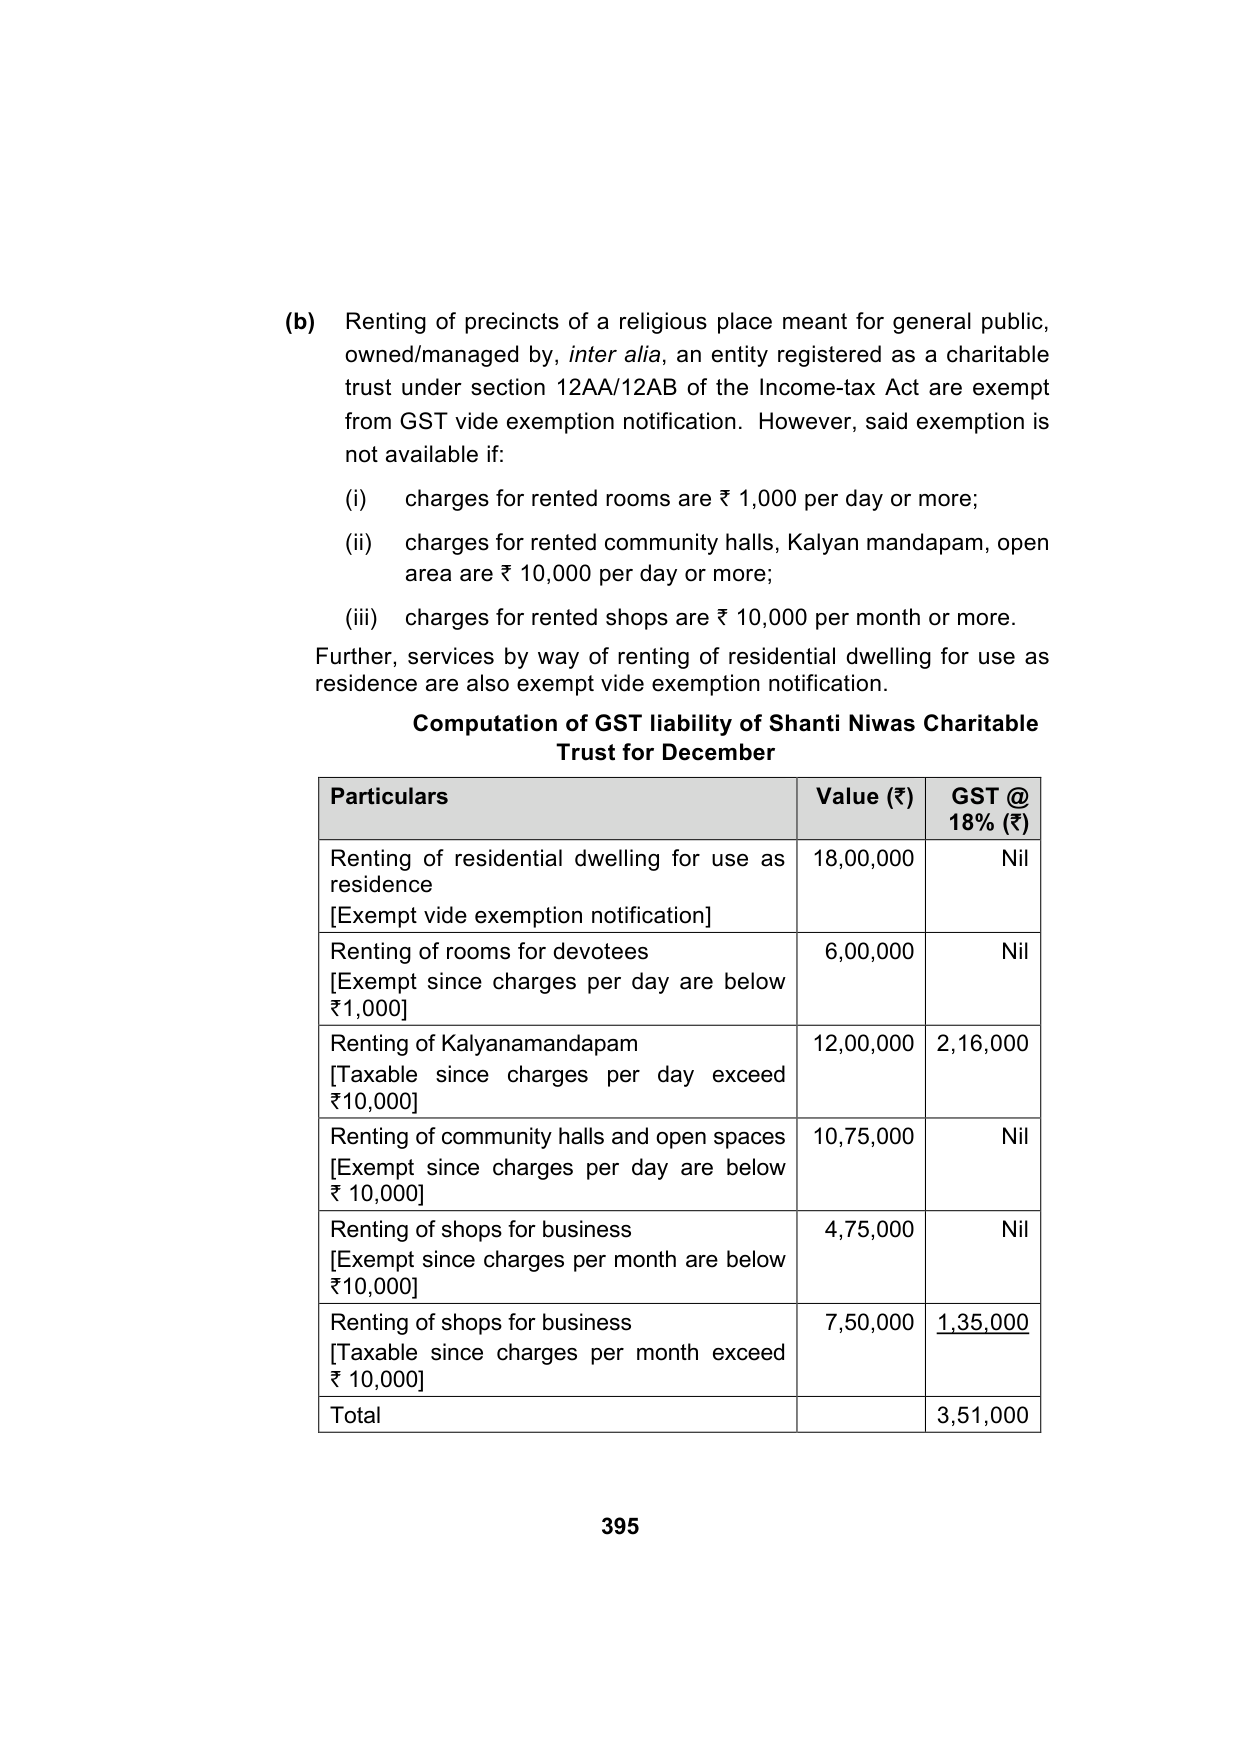
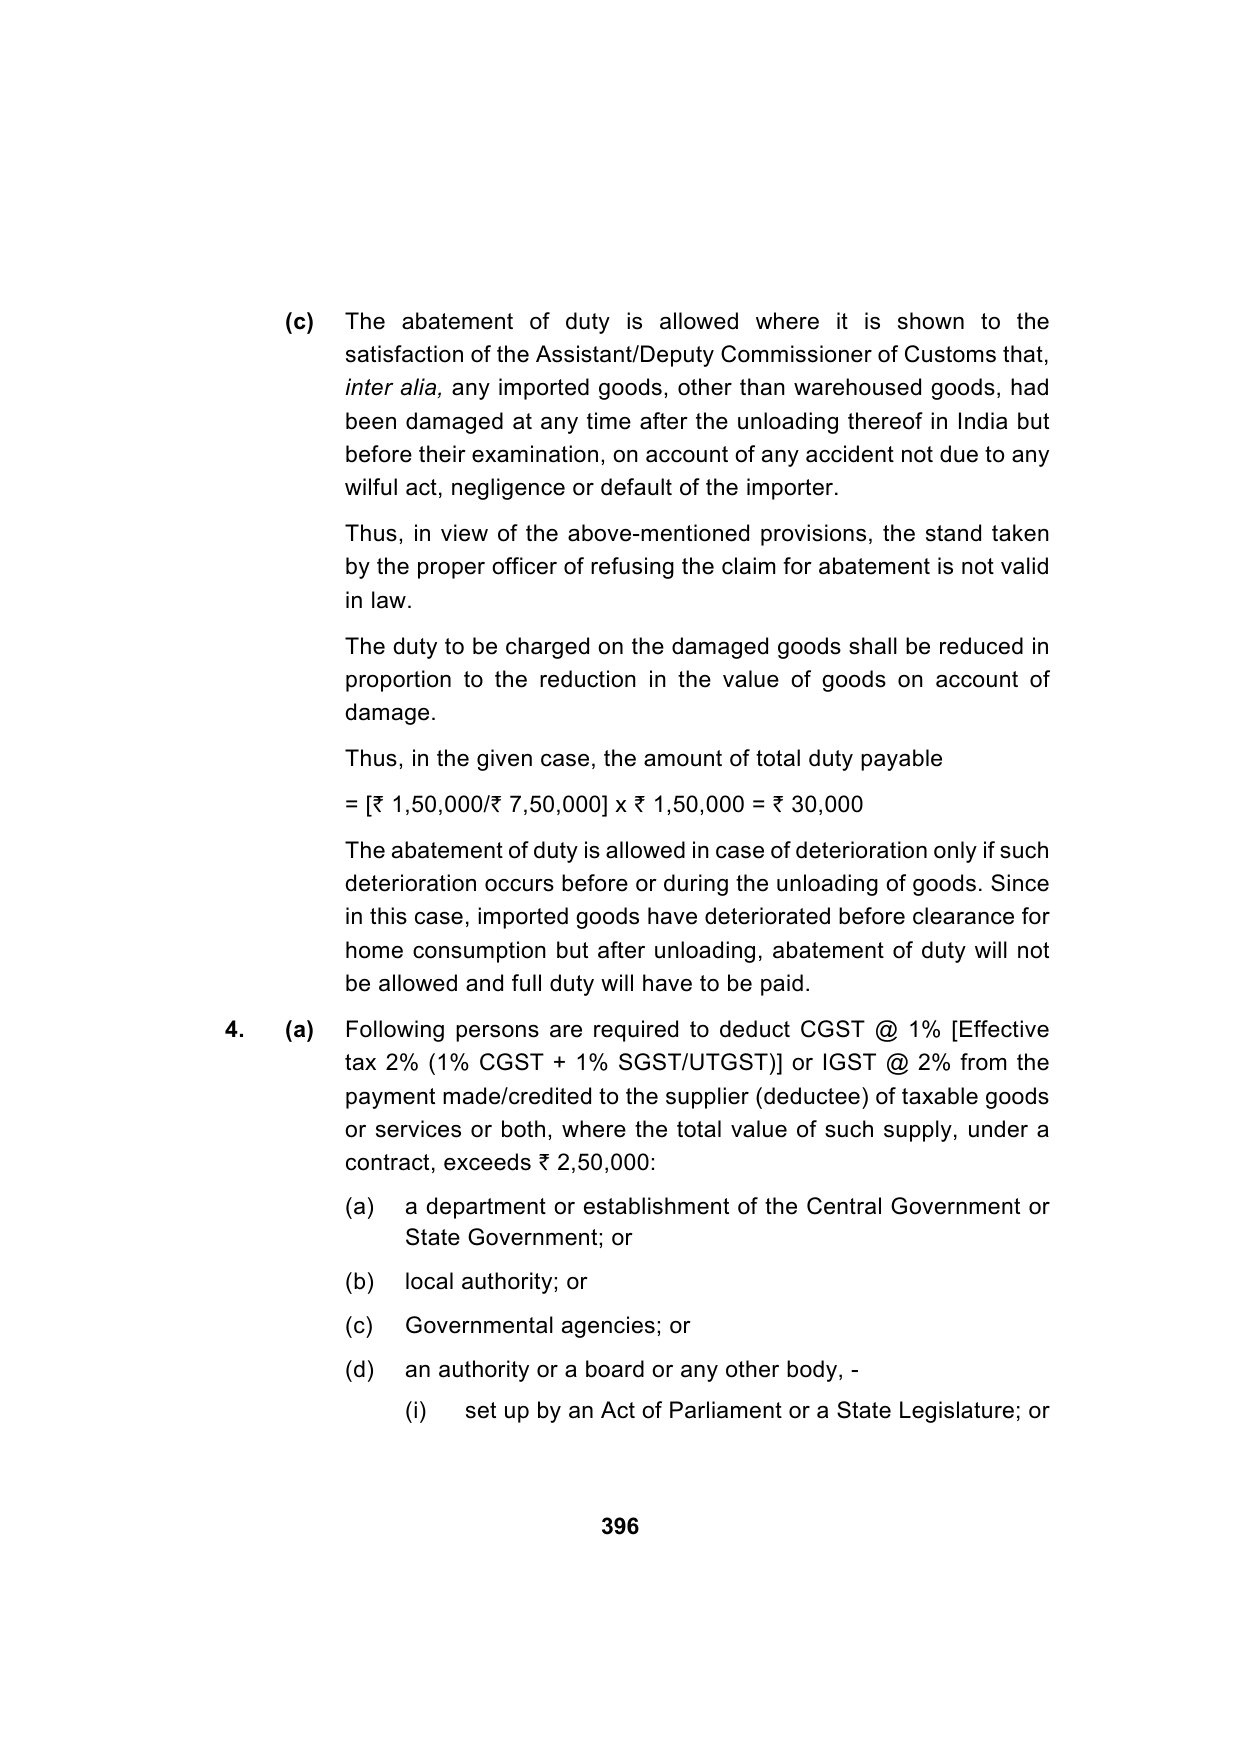
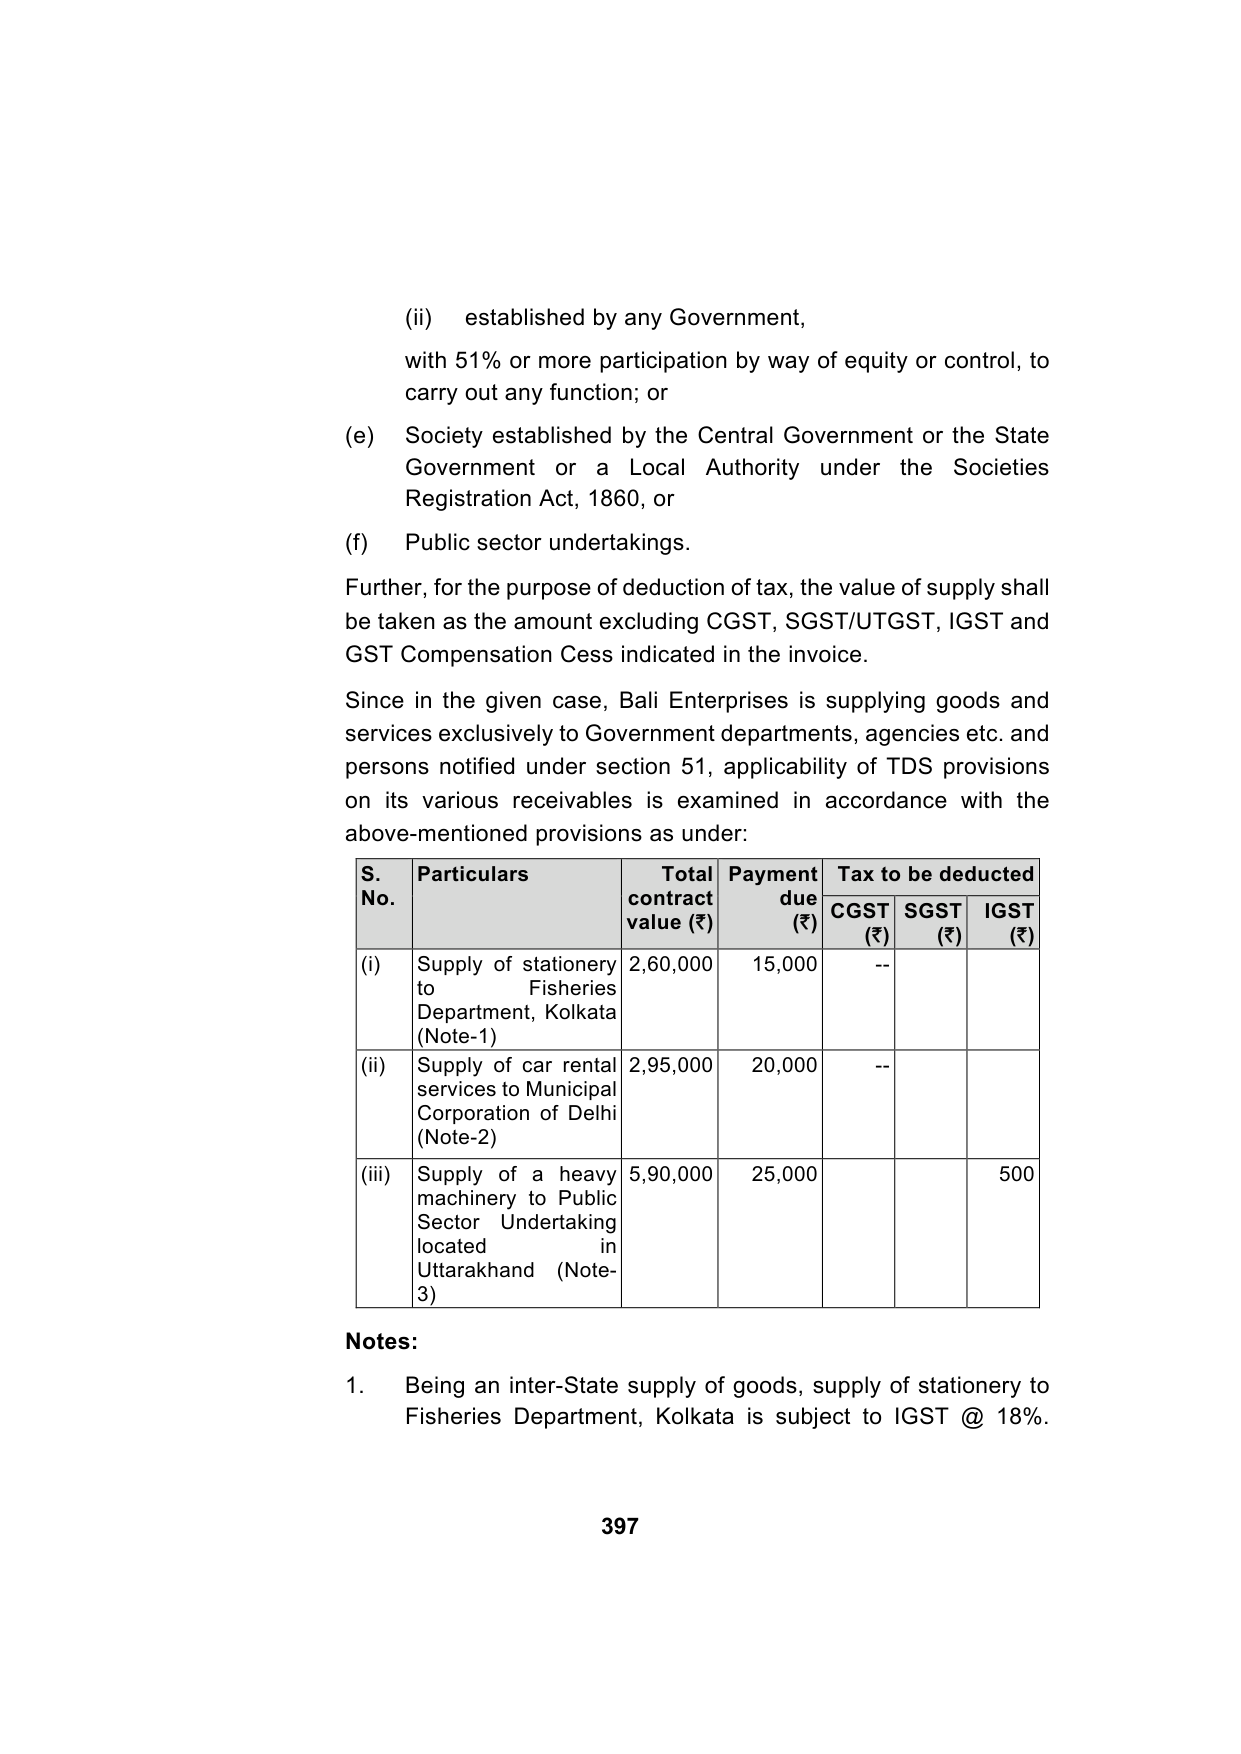
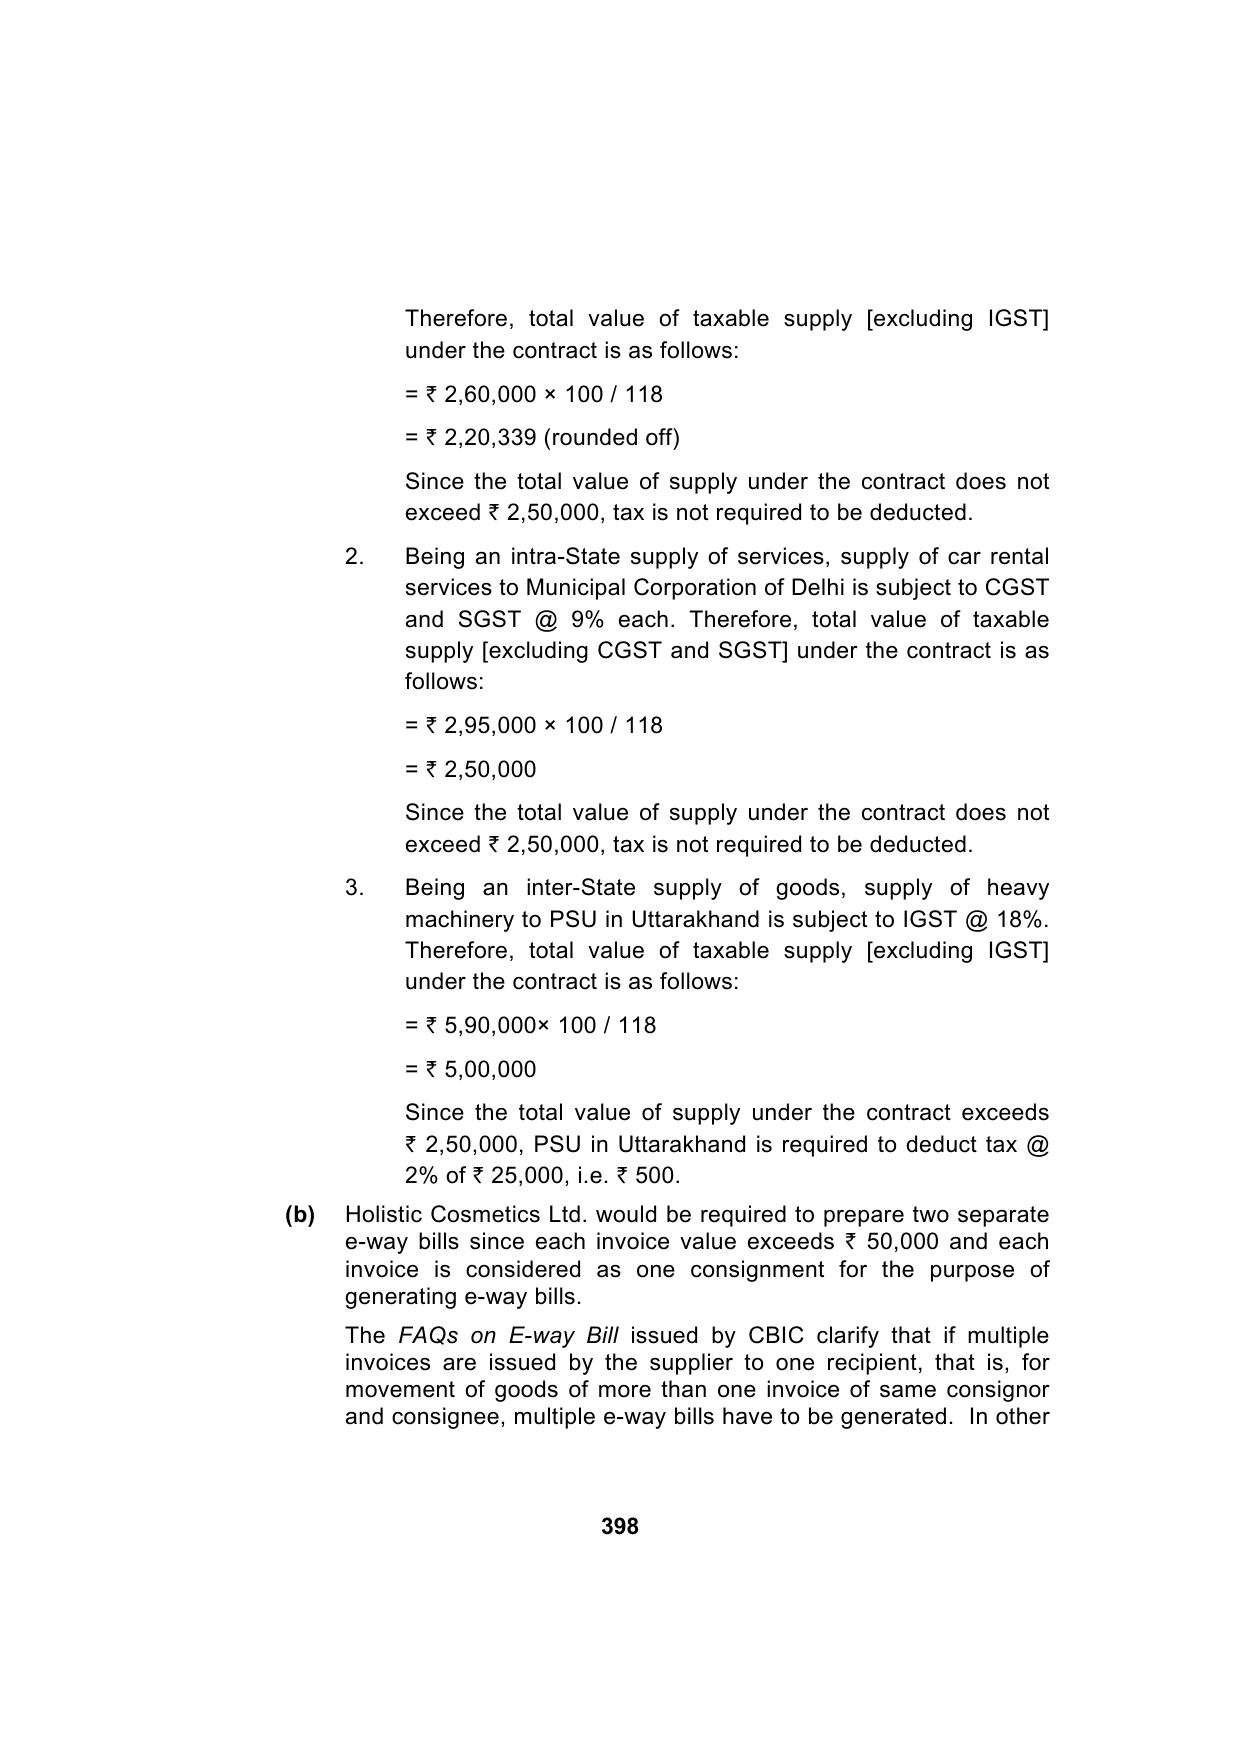
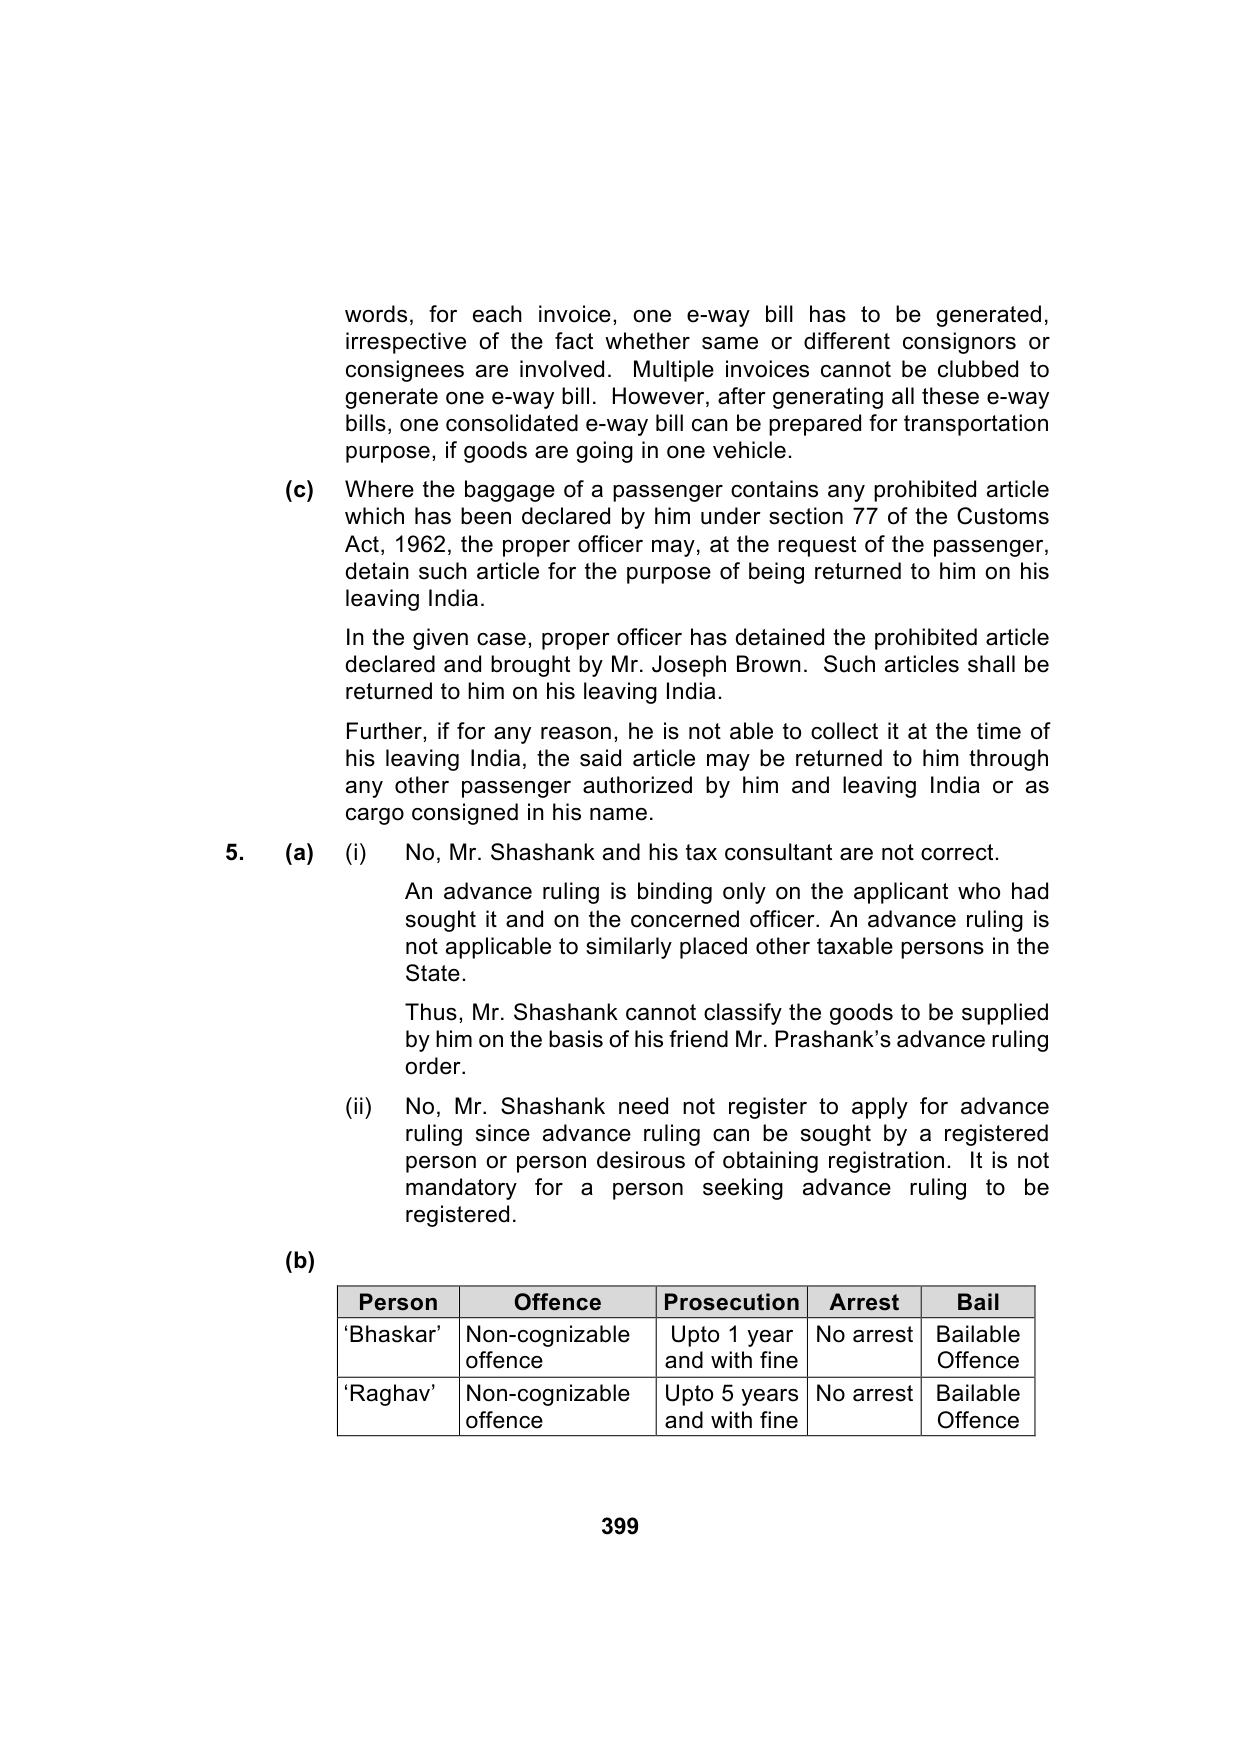
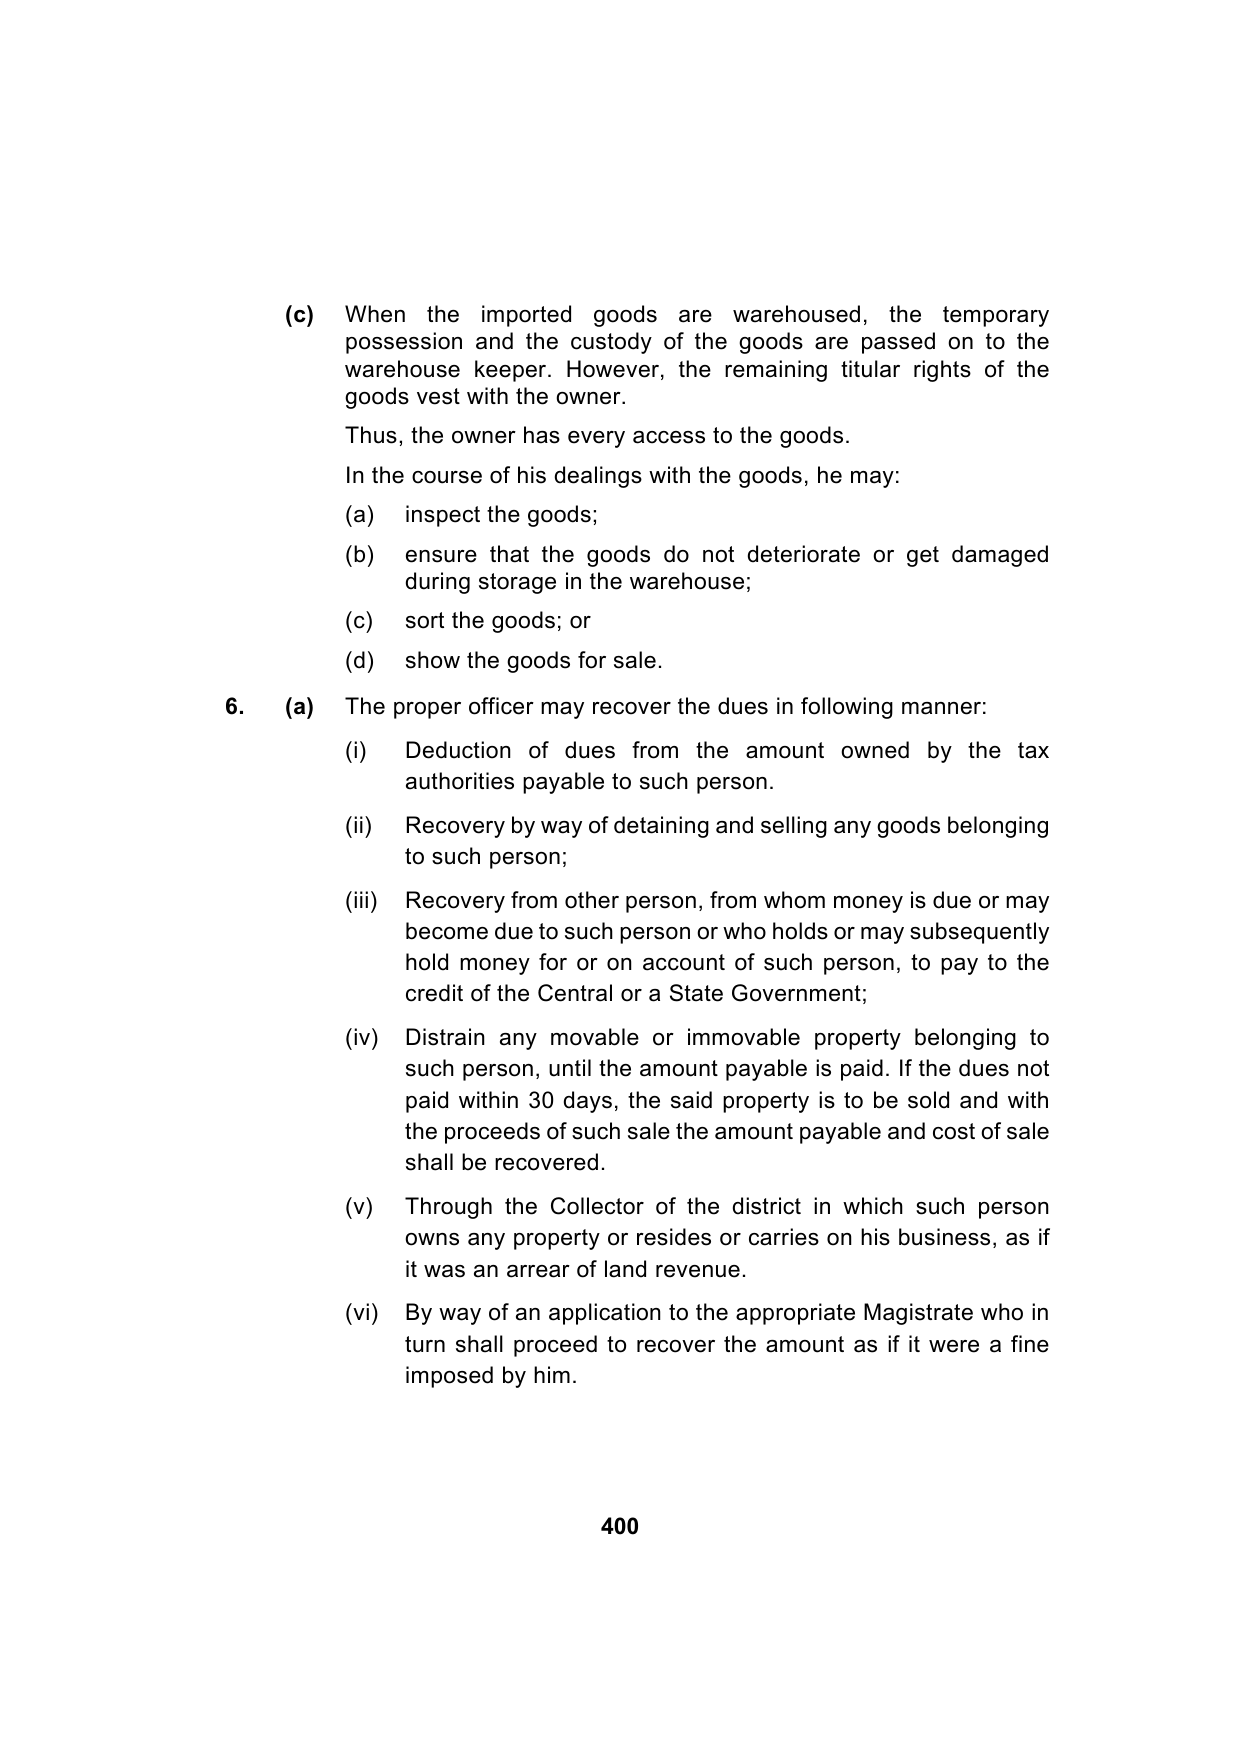
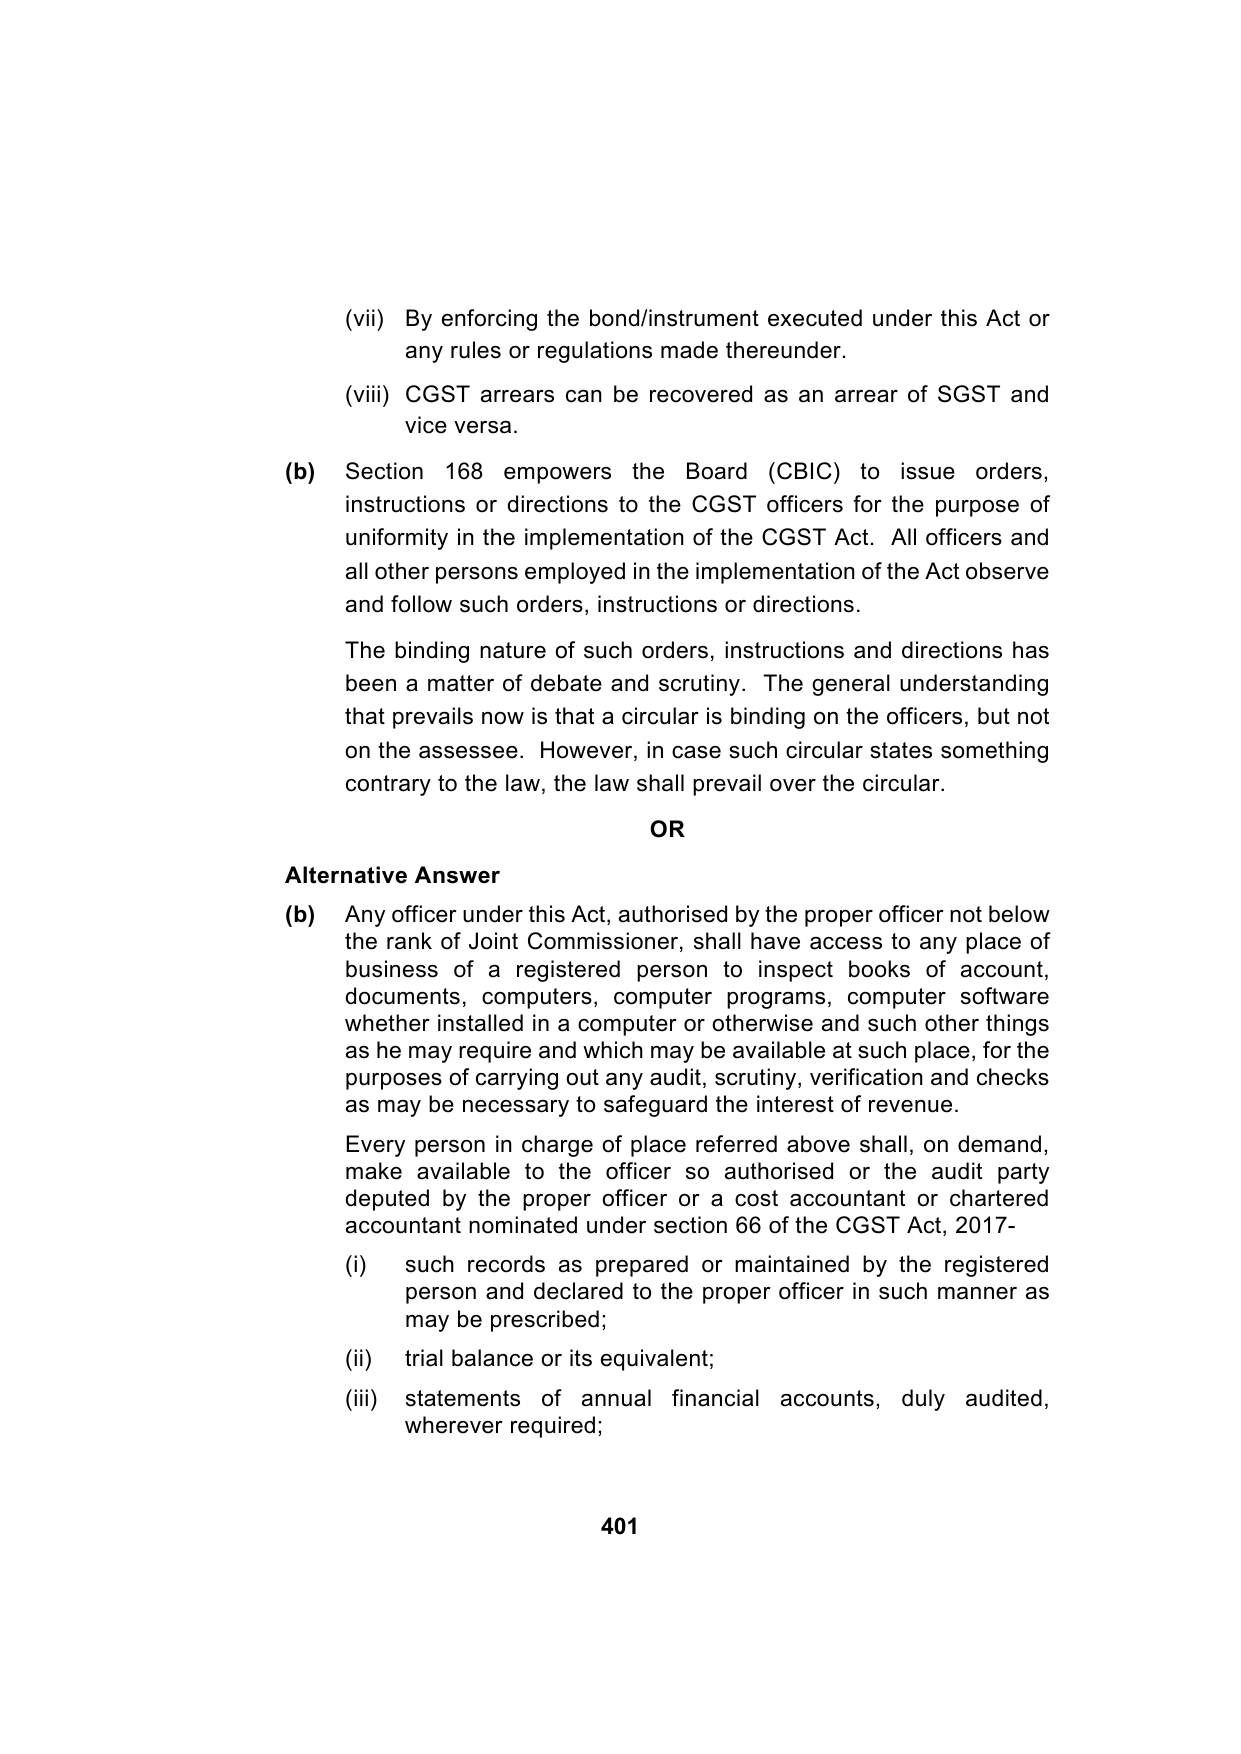
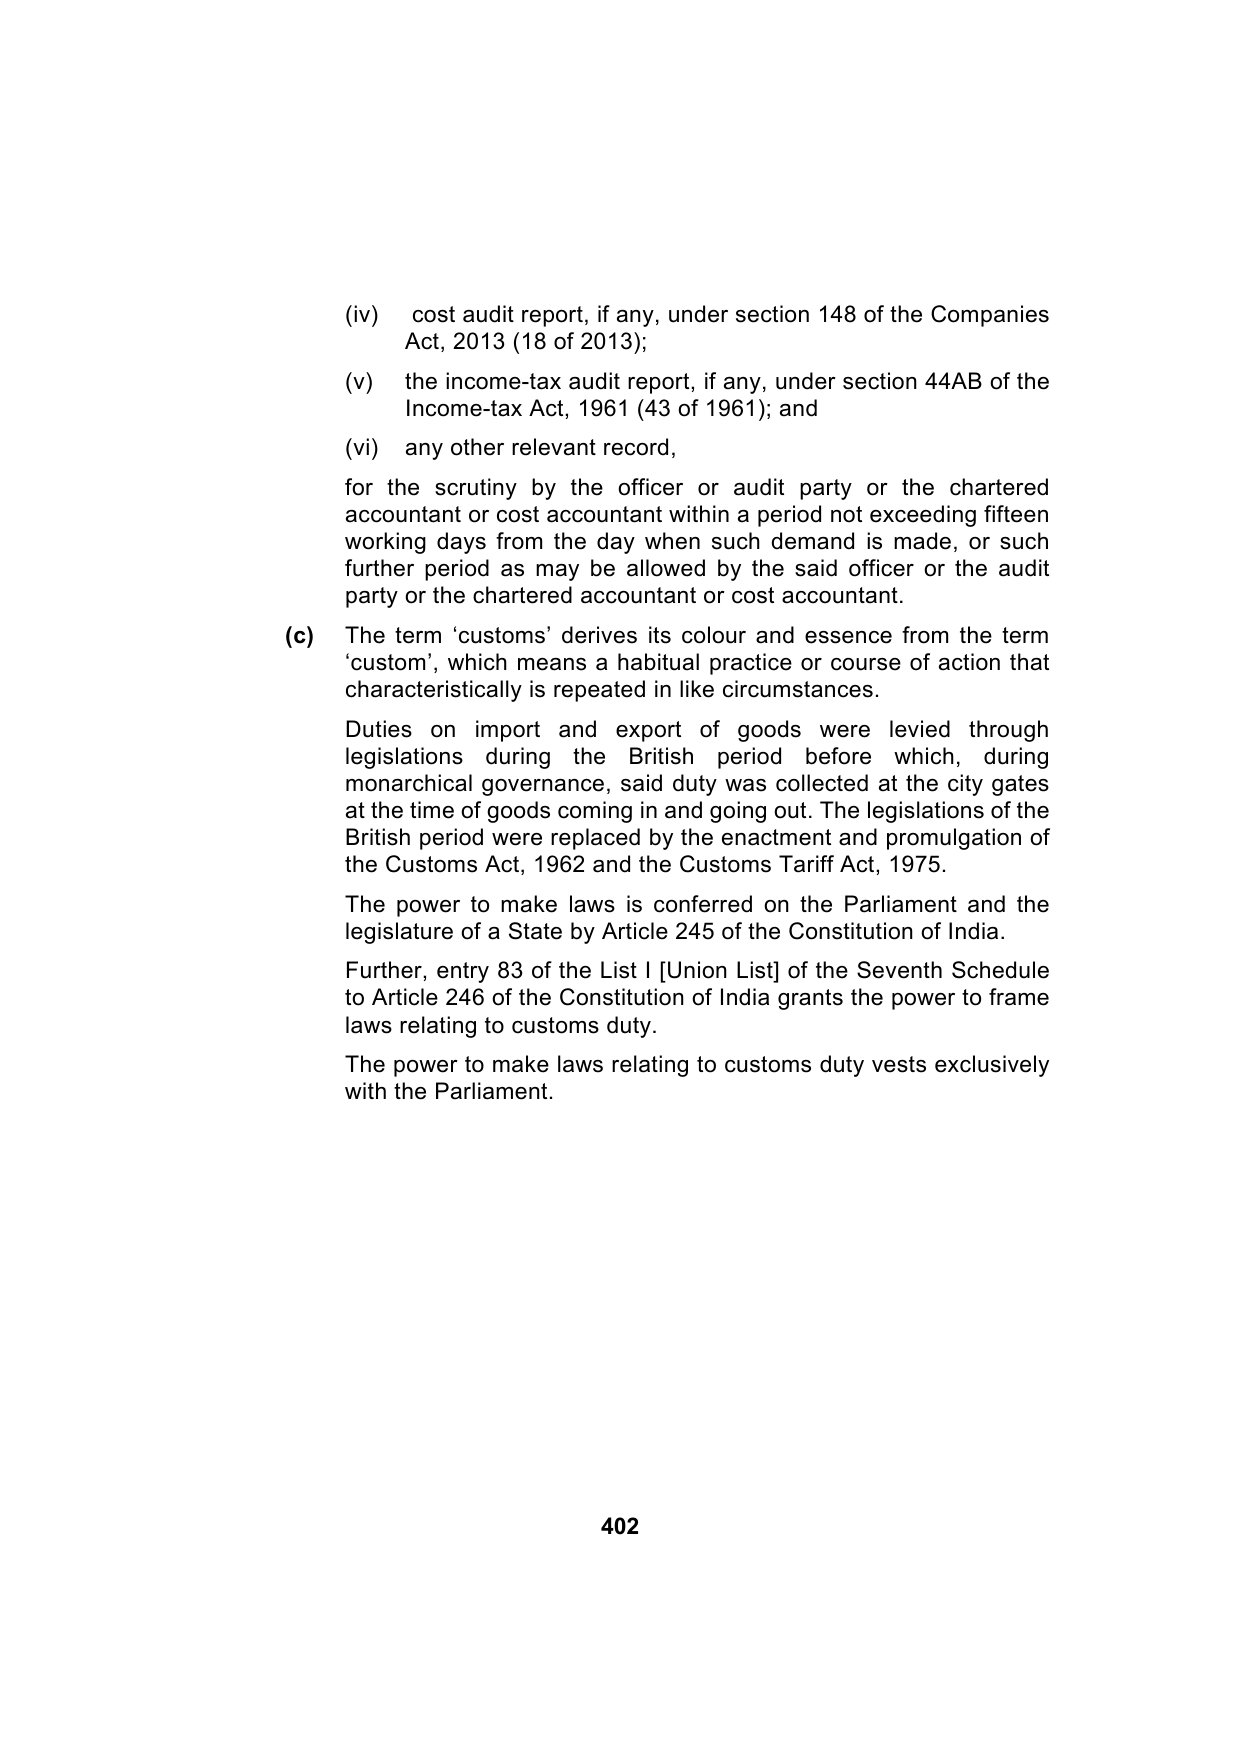
Paper 5: Indirect Tax Laws — Model Test Paper 5 (100 marks)
Question
Answer
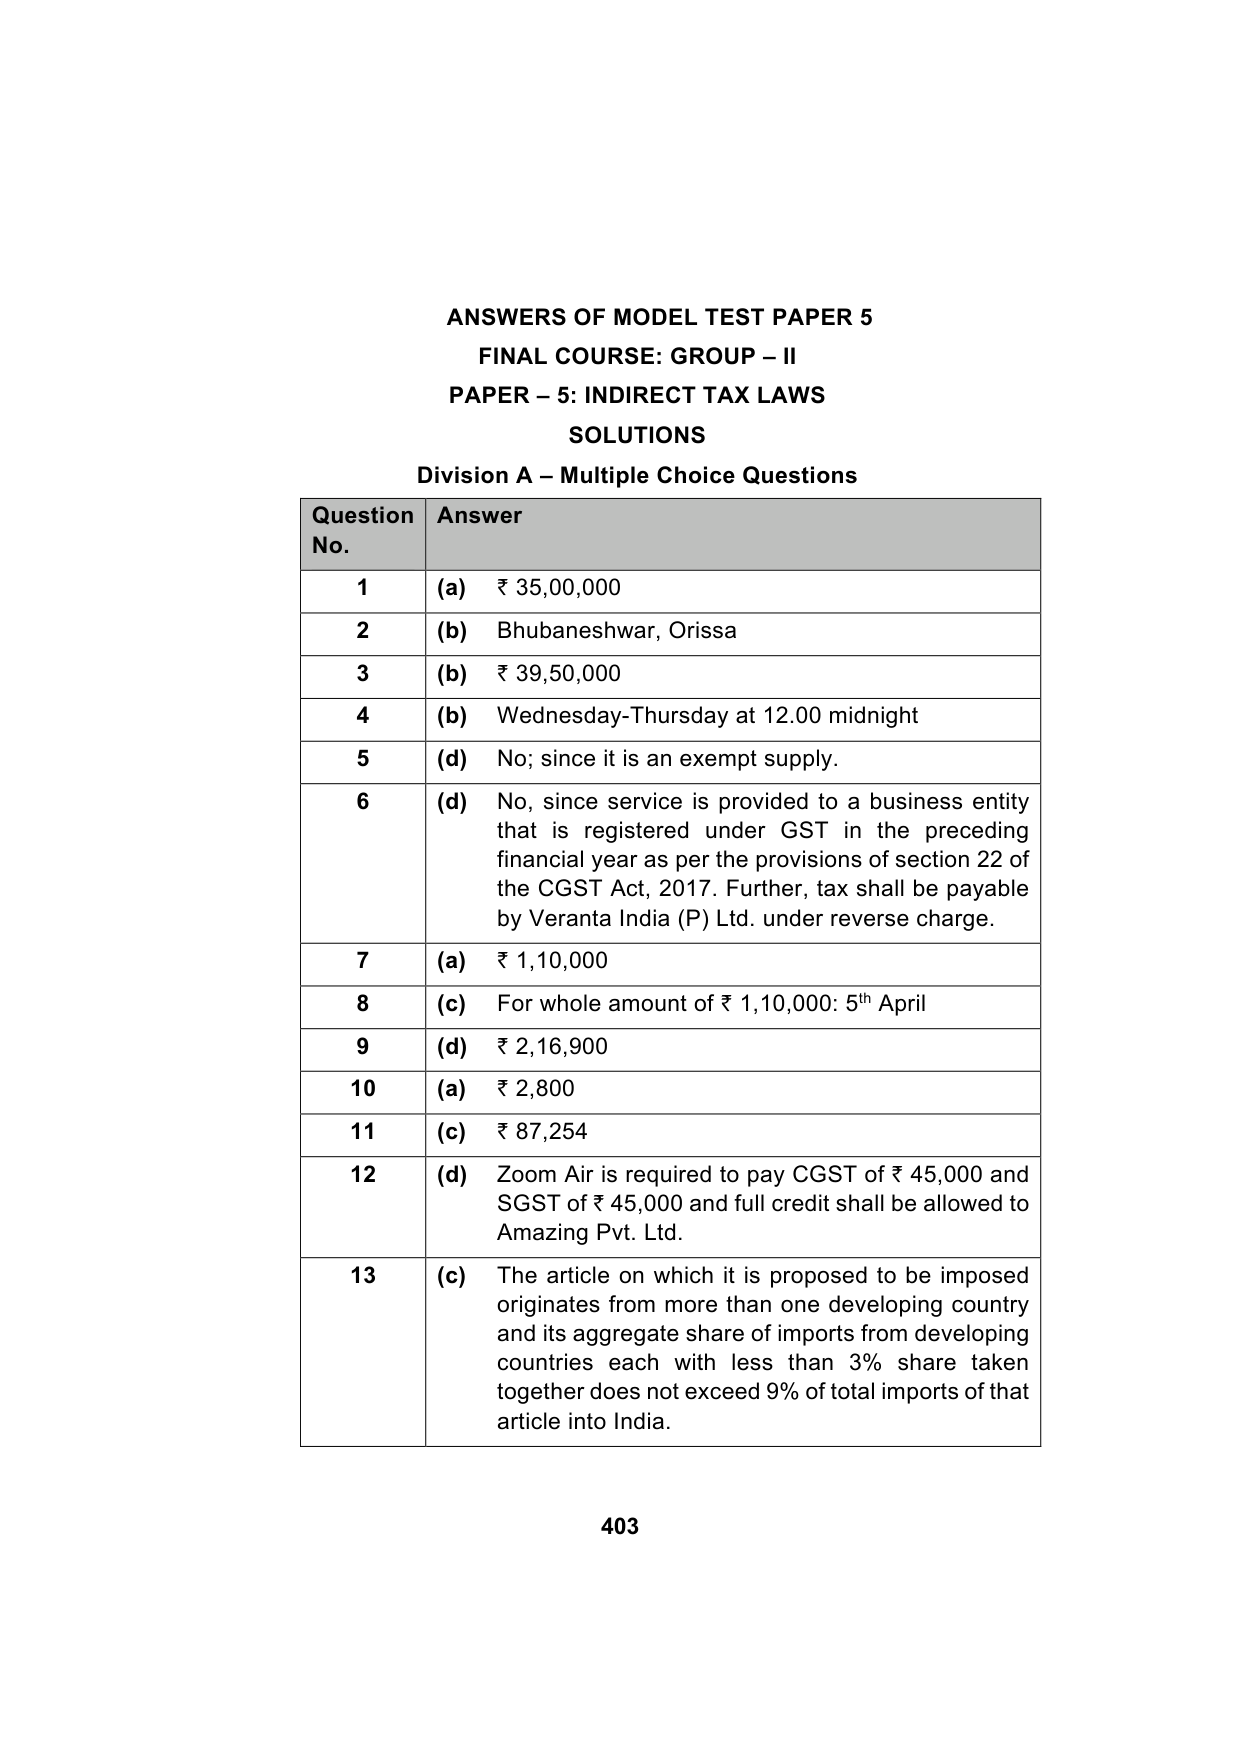
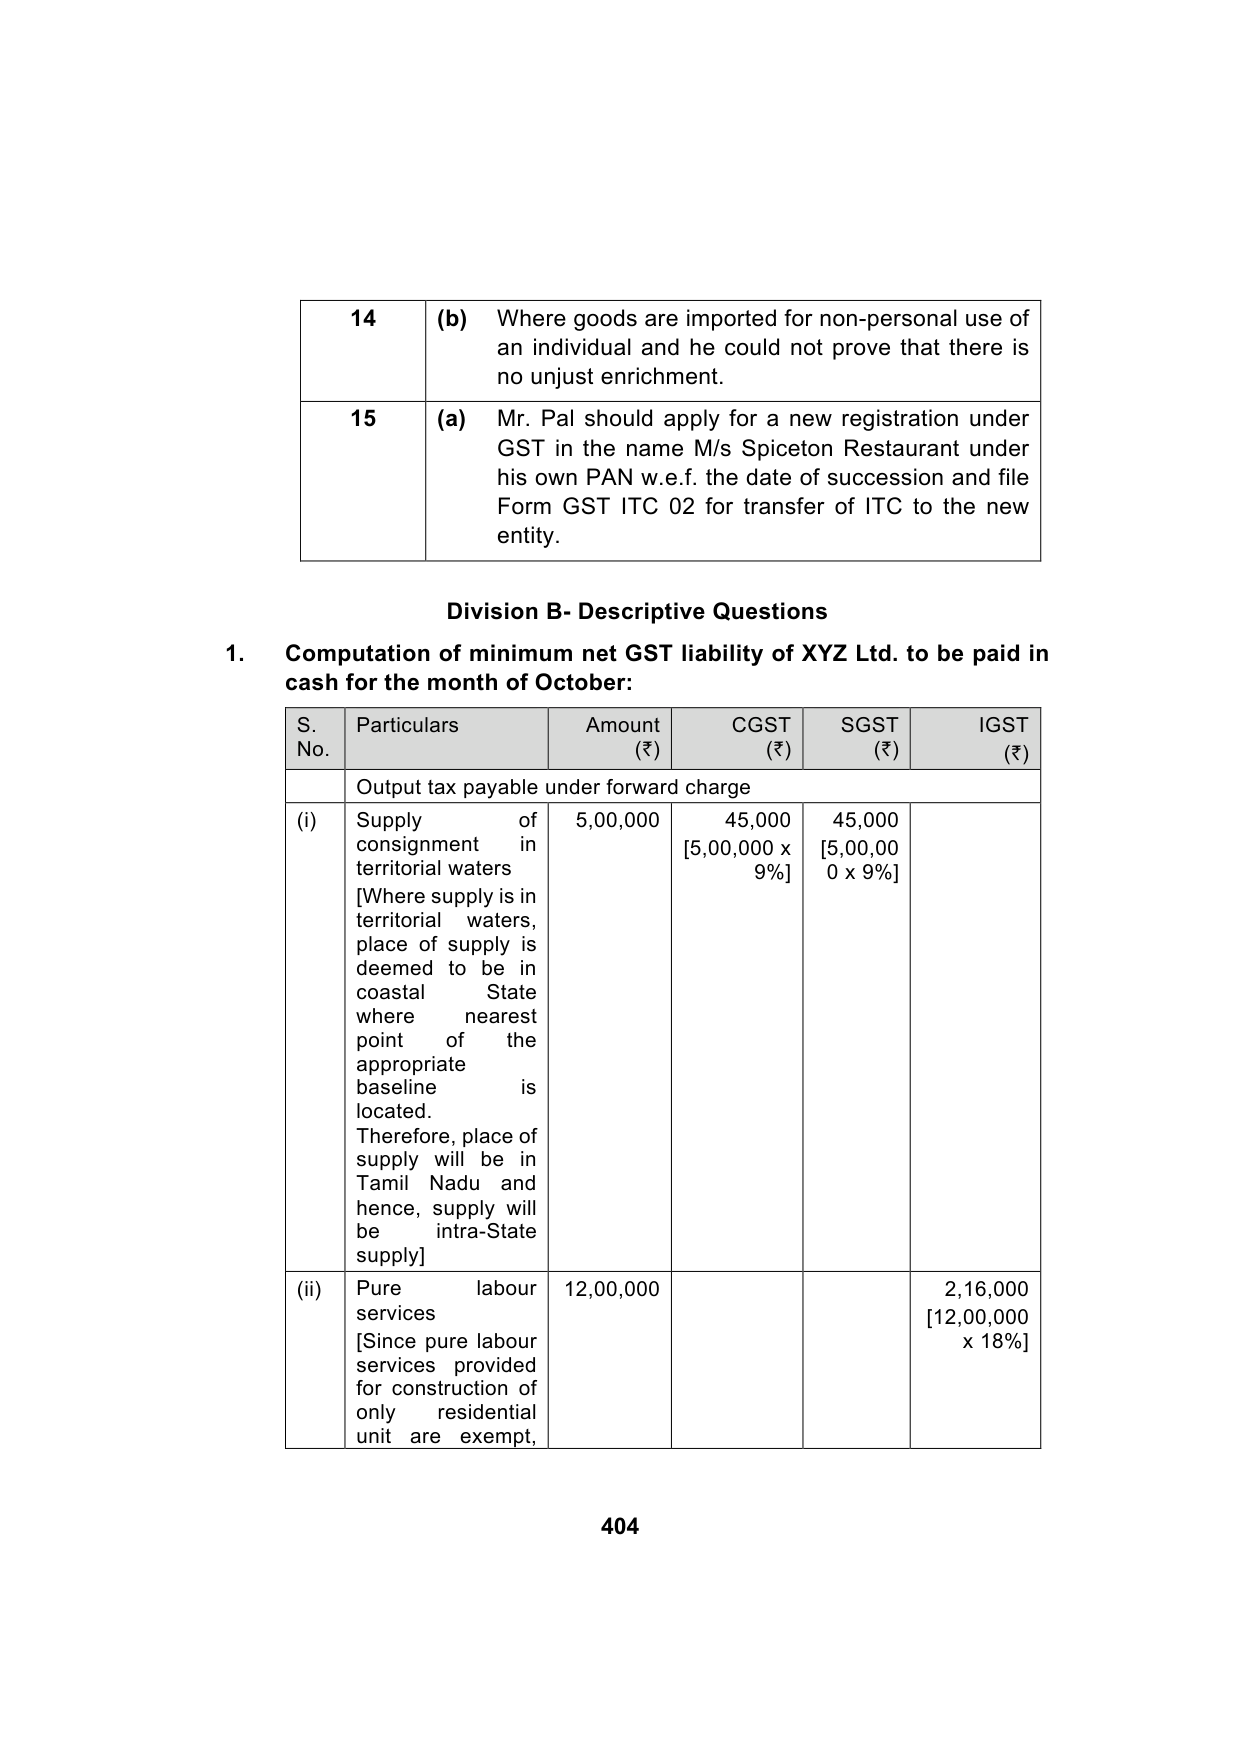
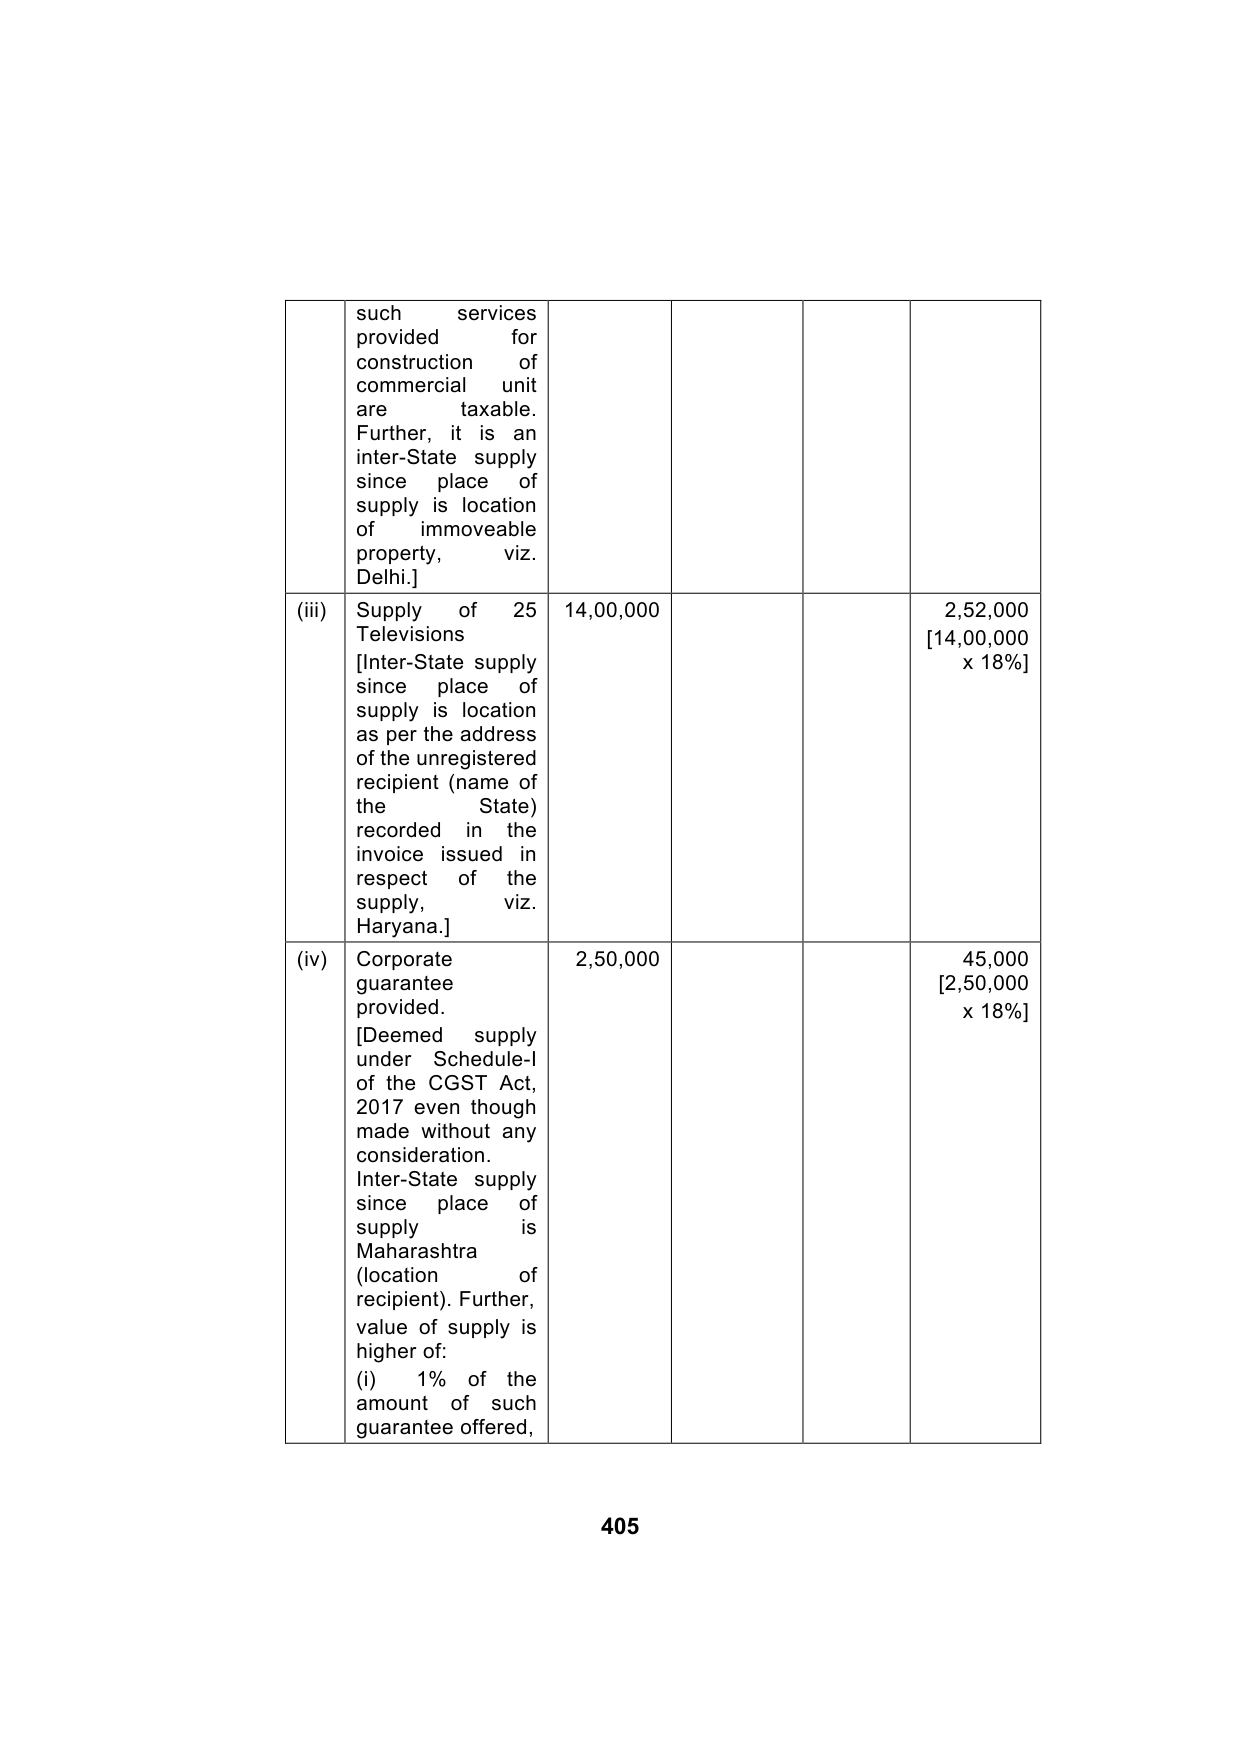
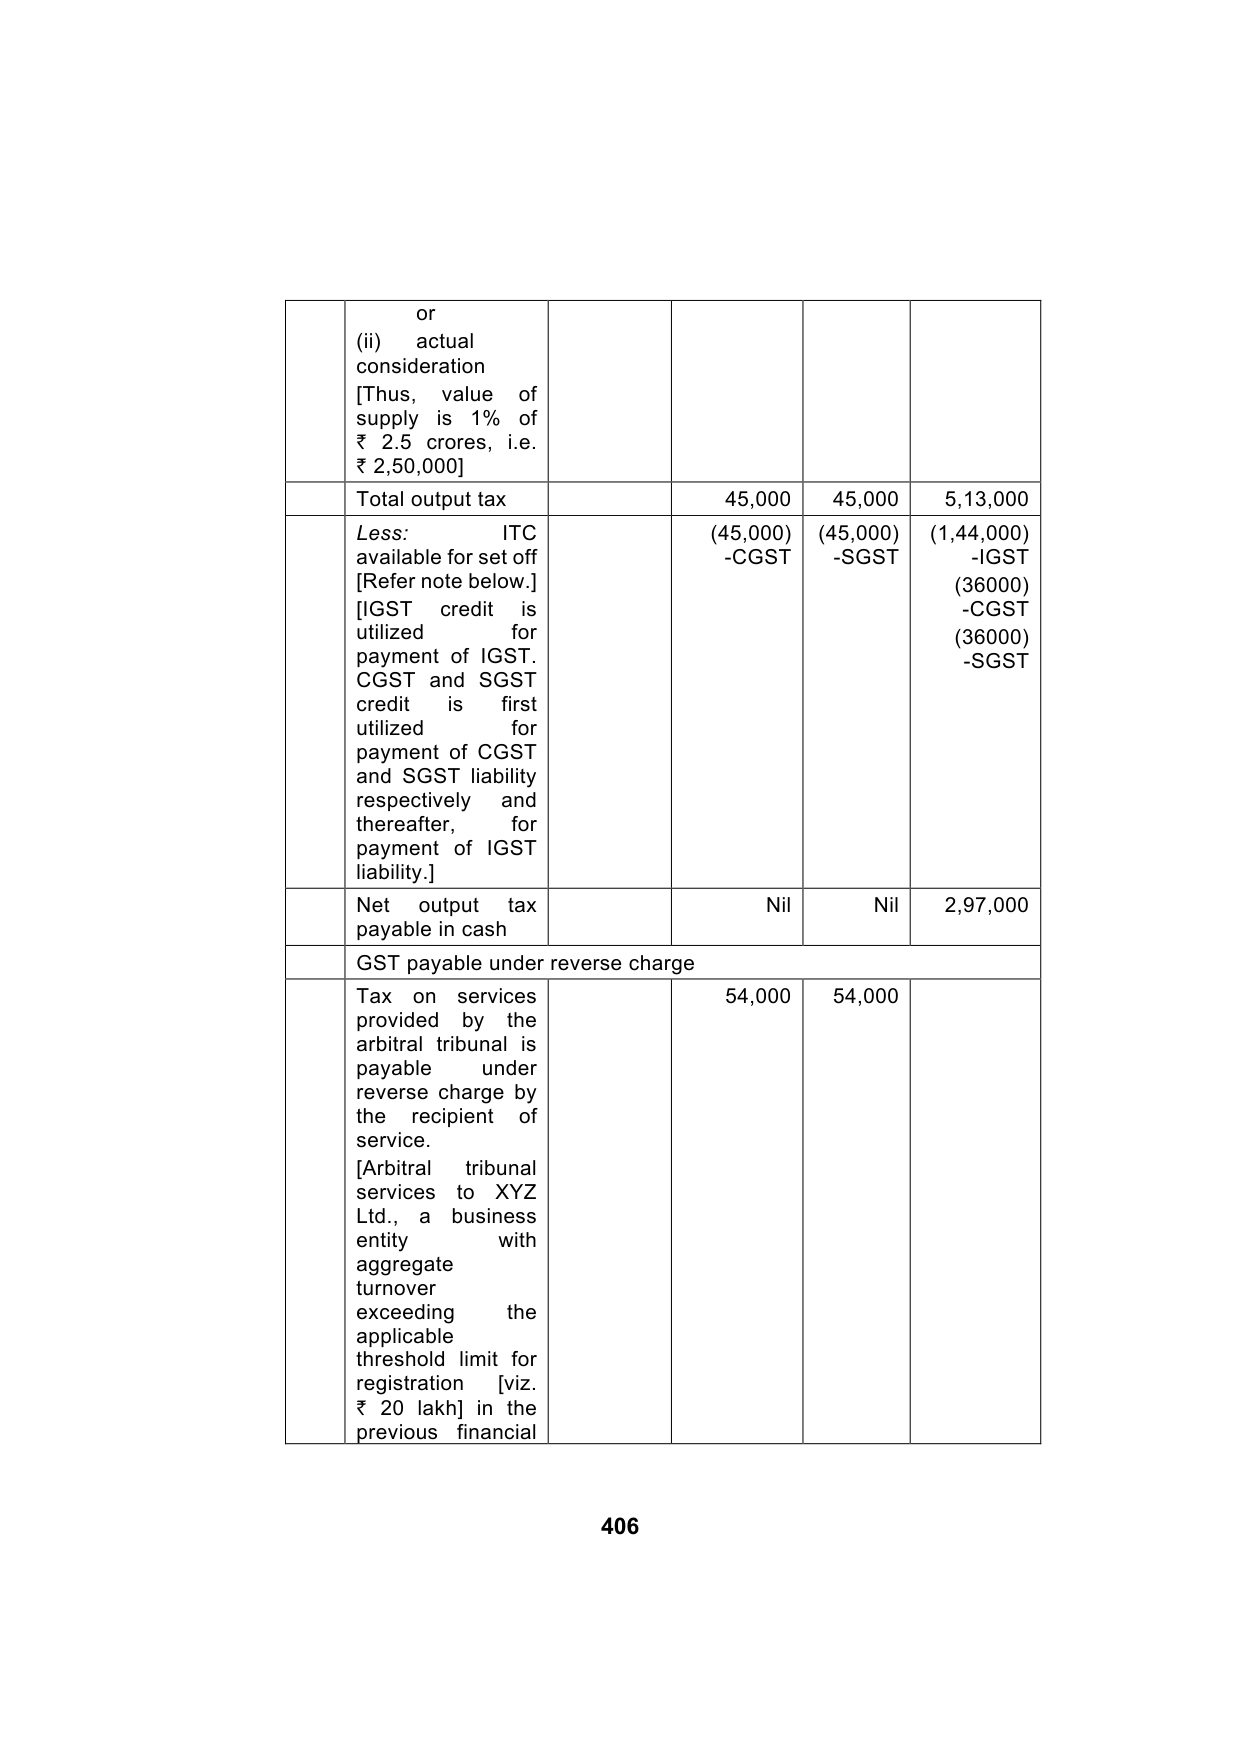
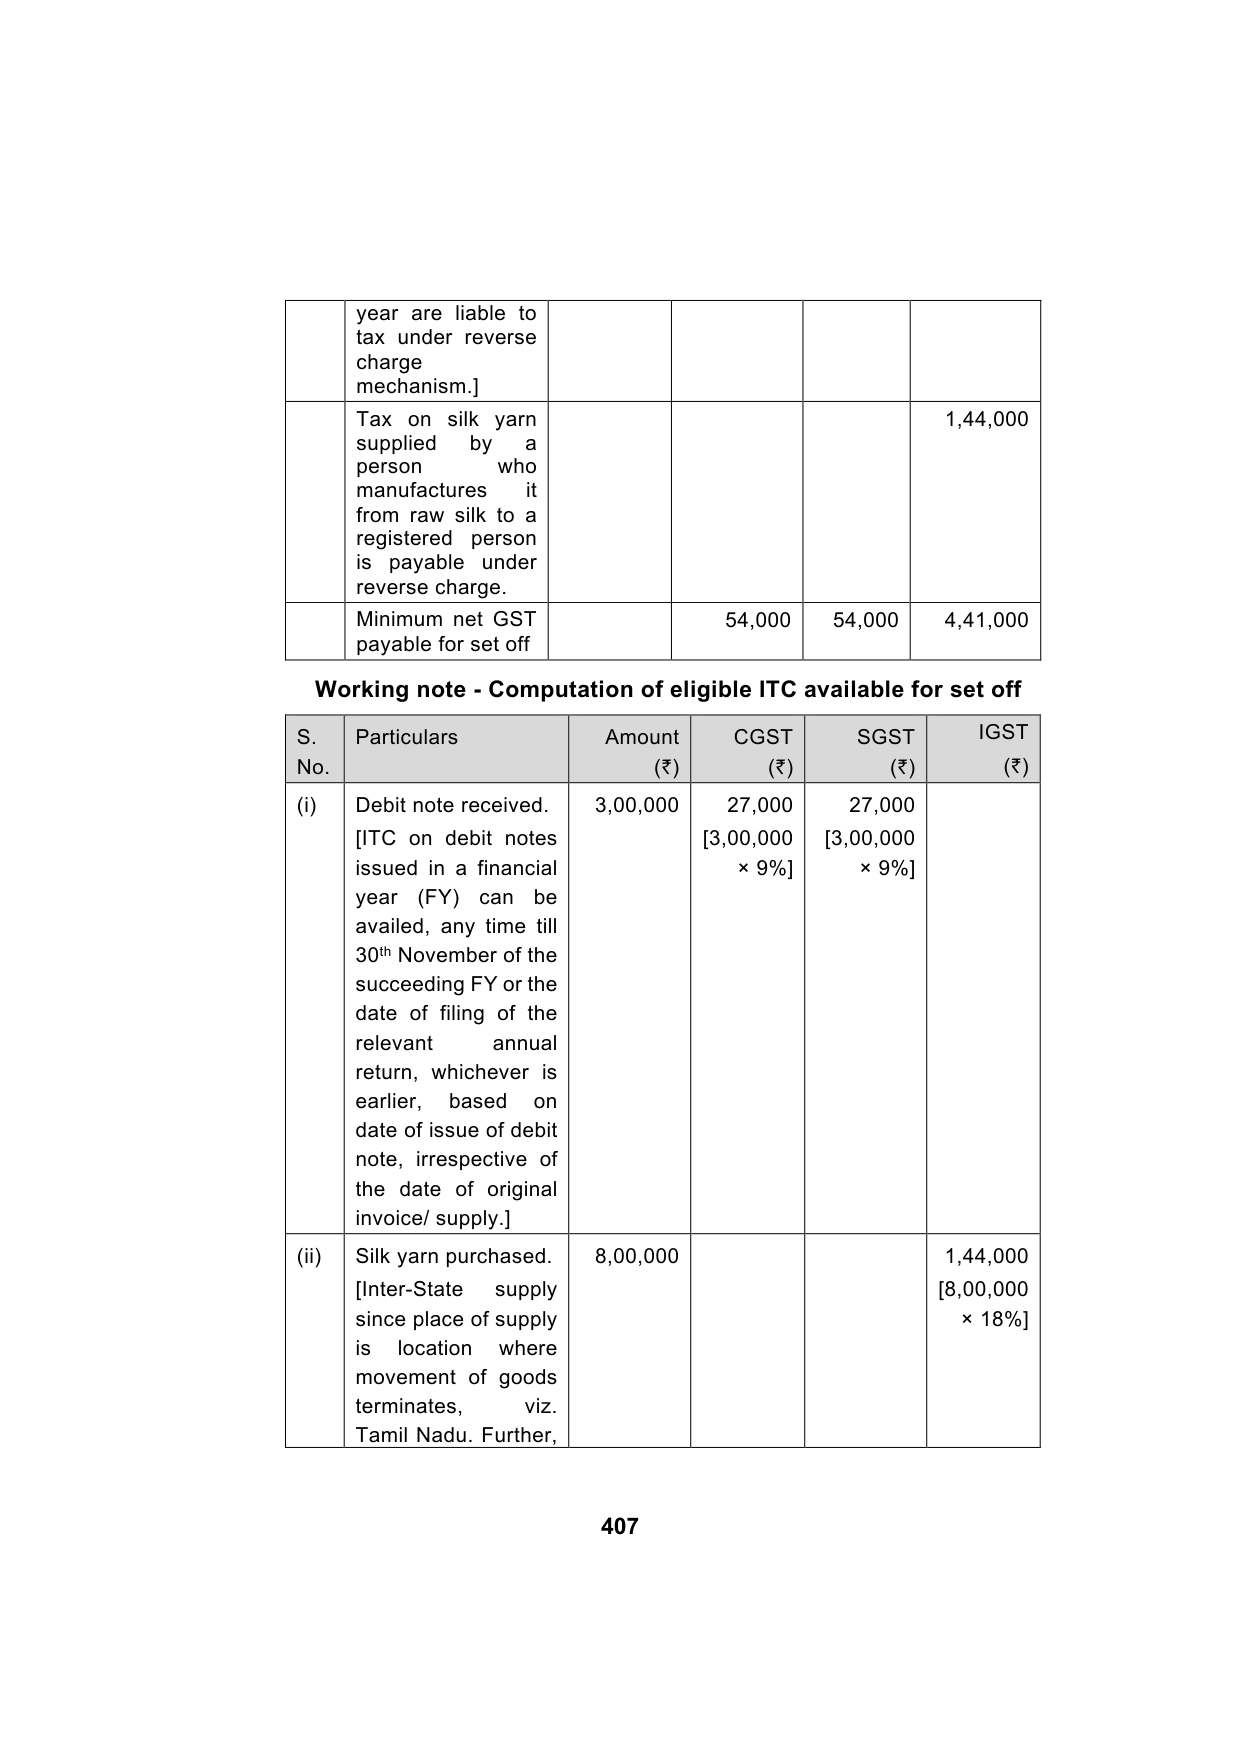
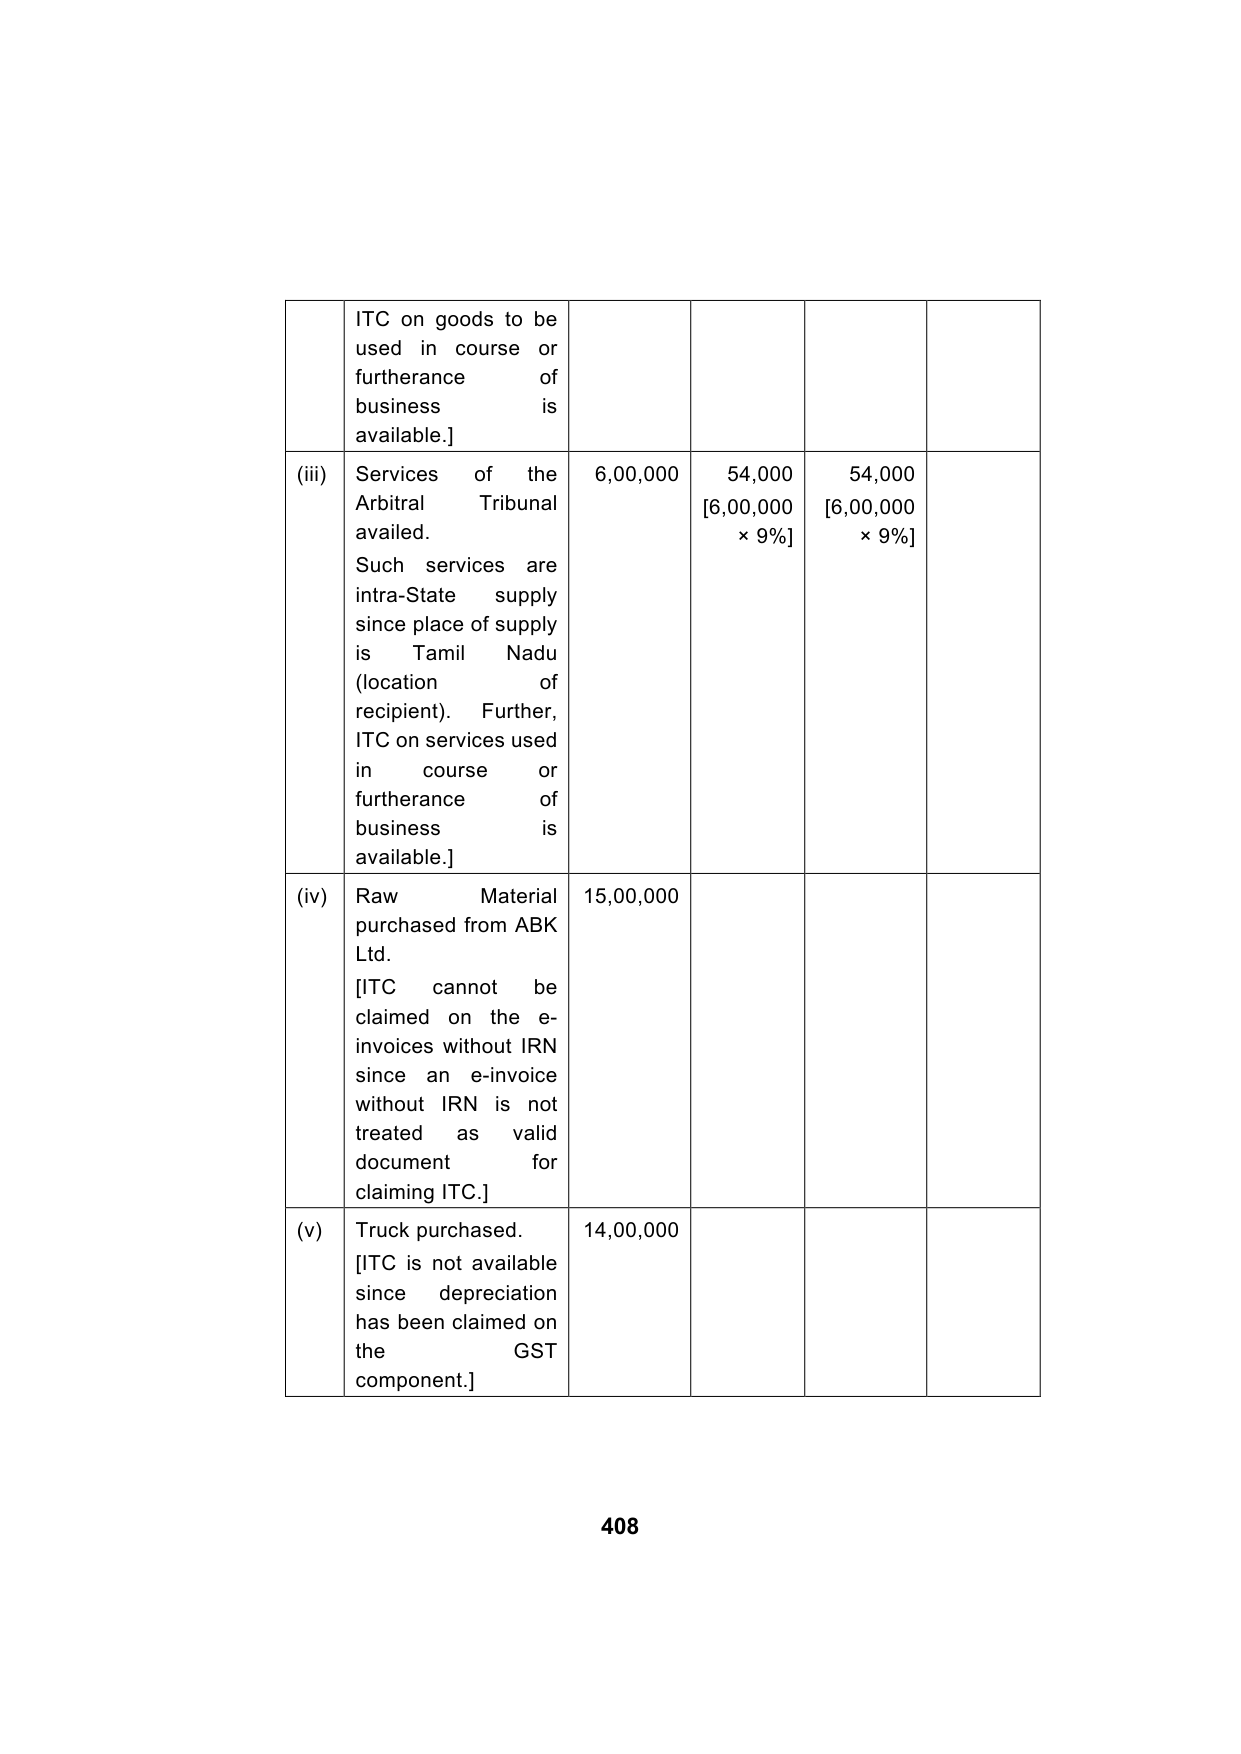
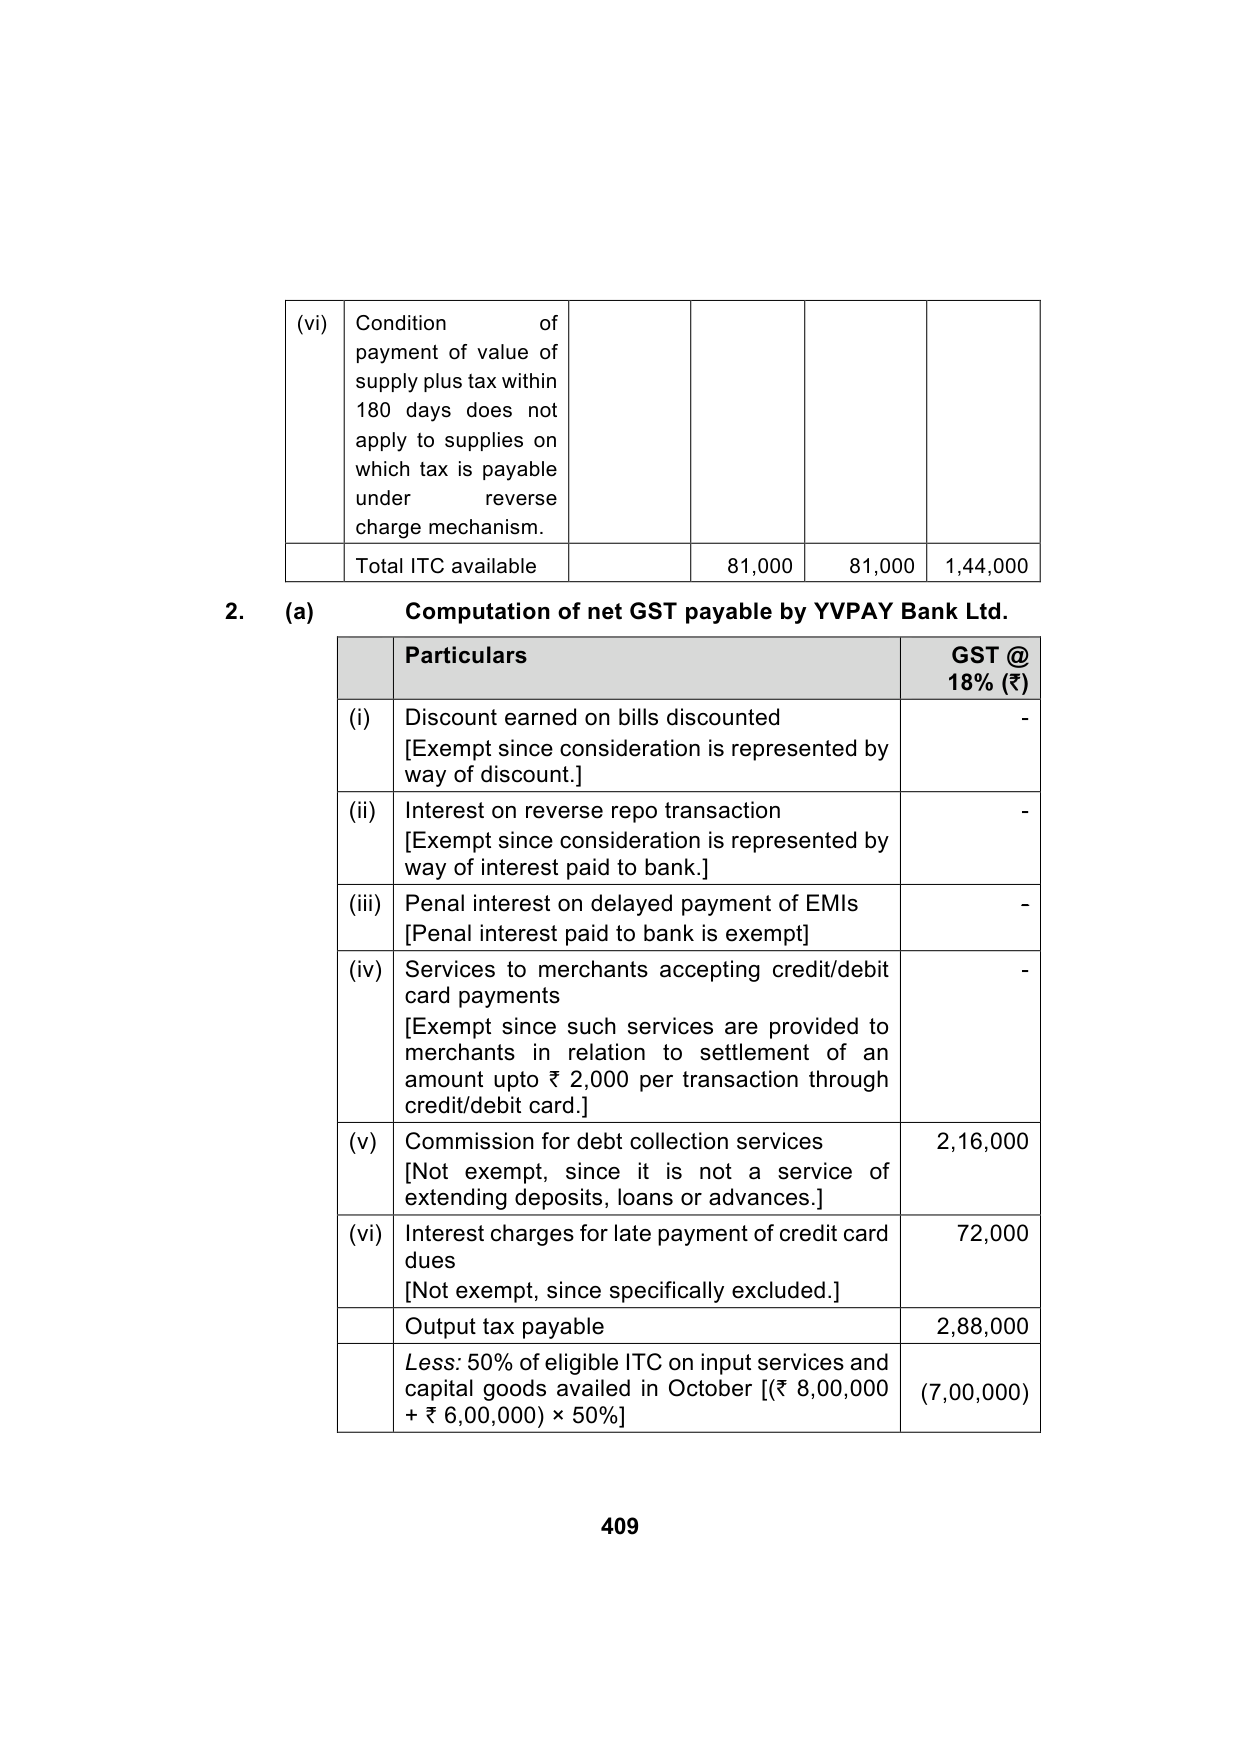
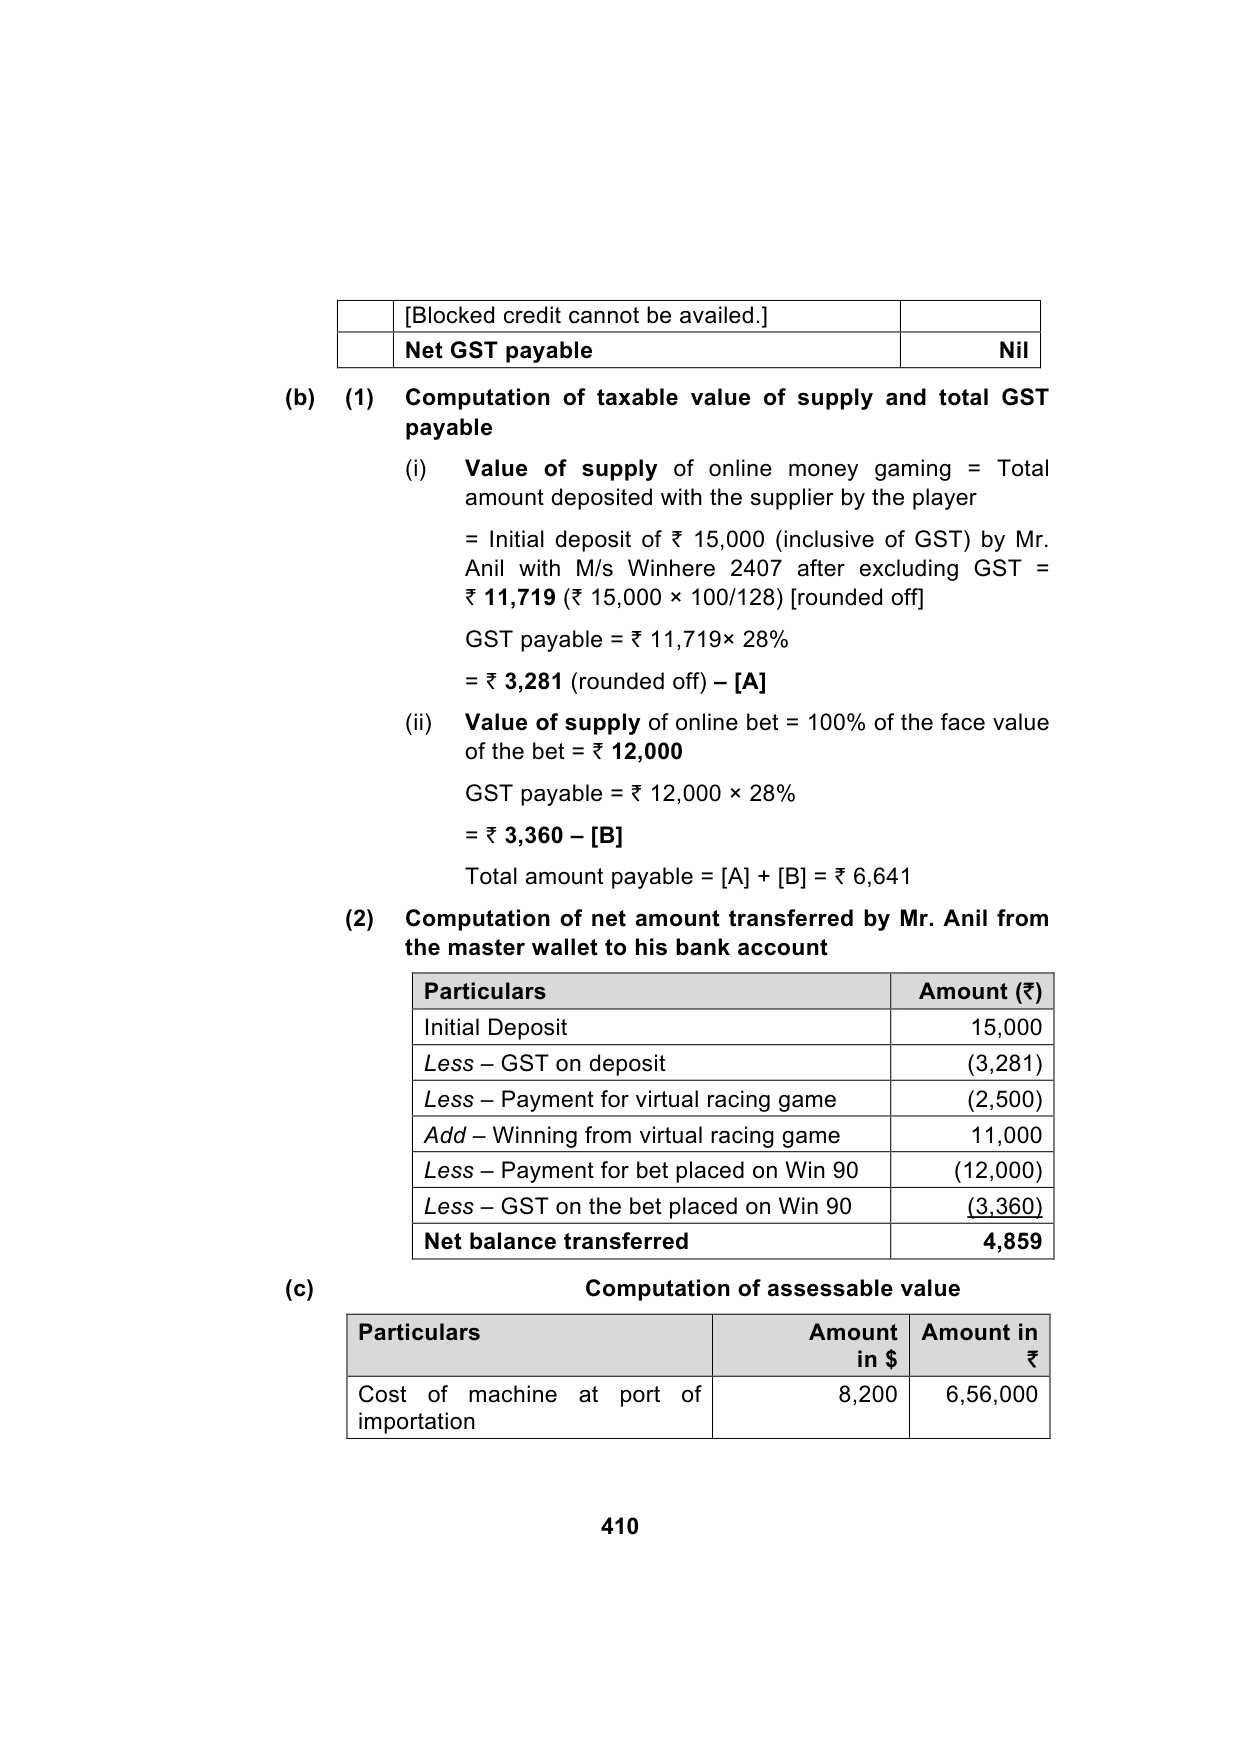
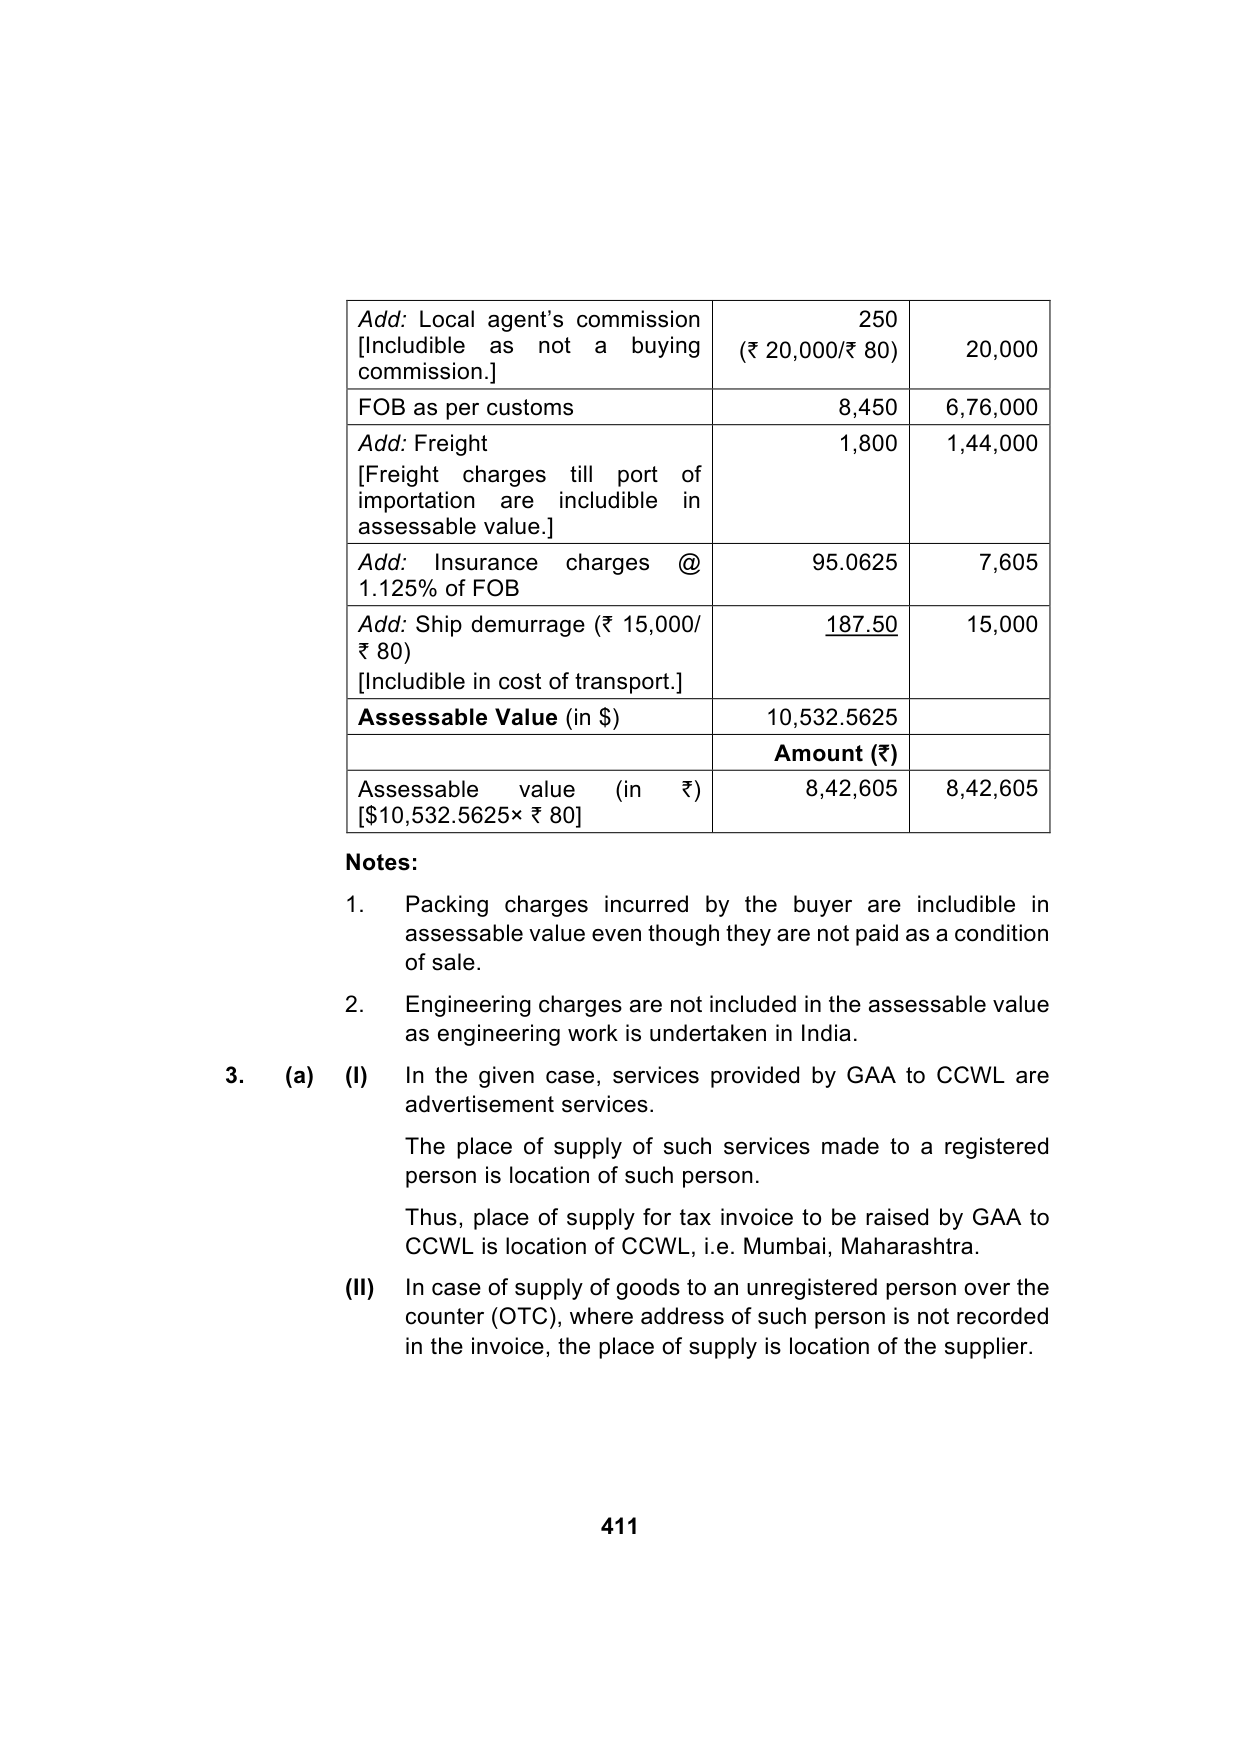
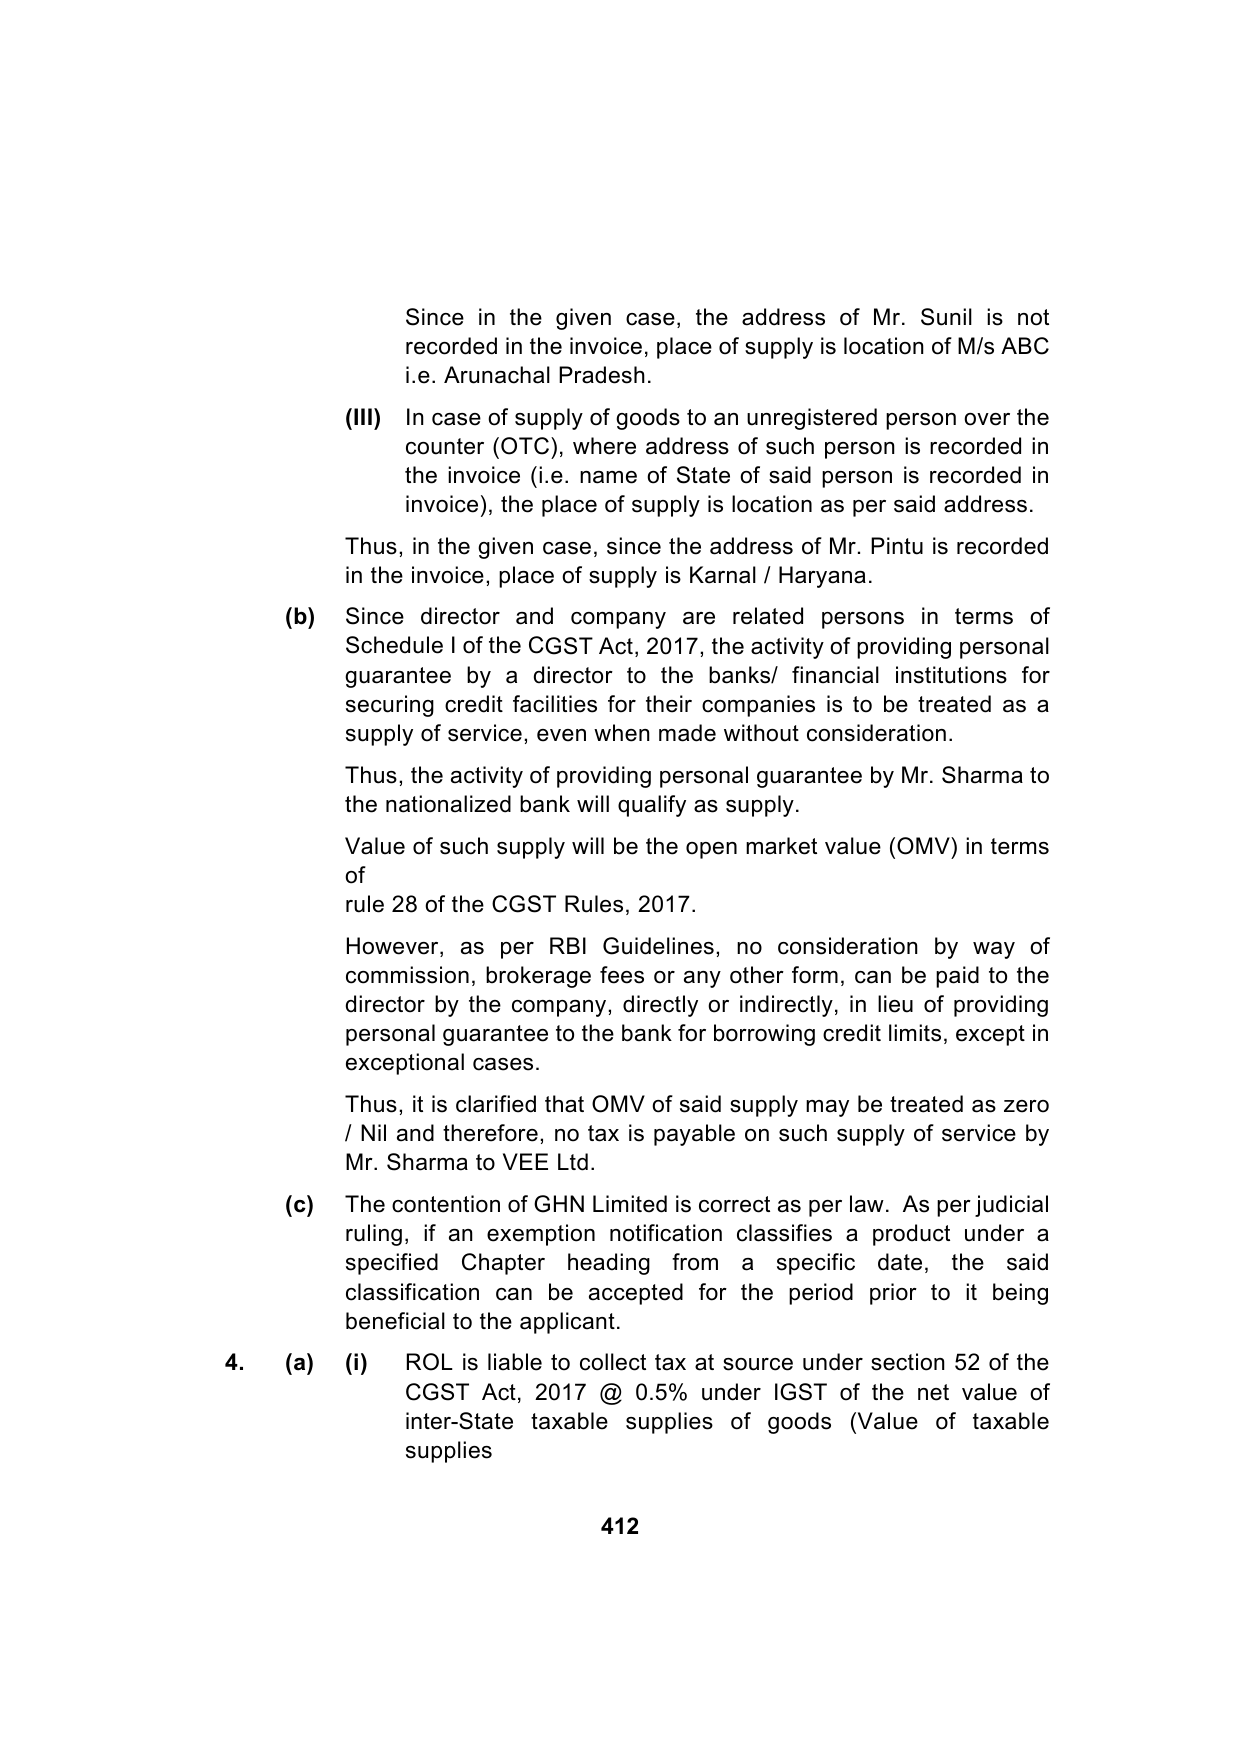
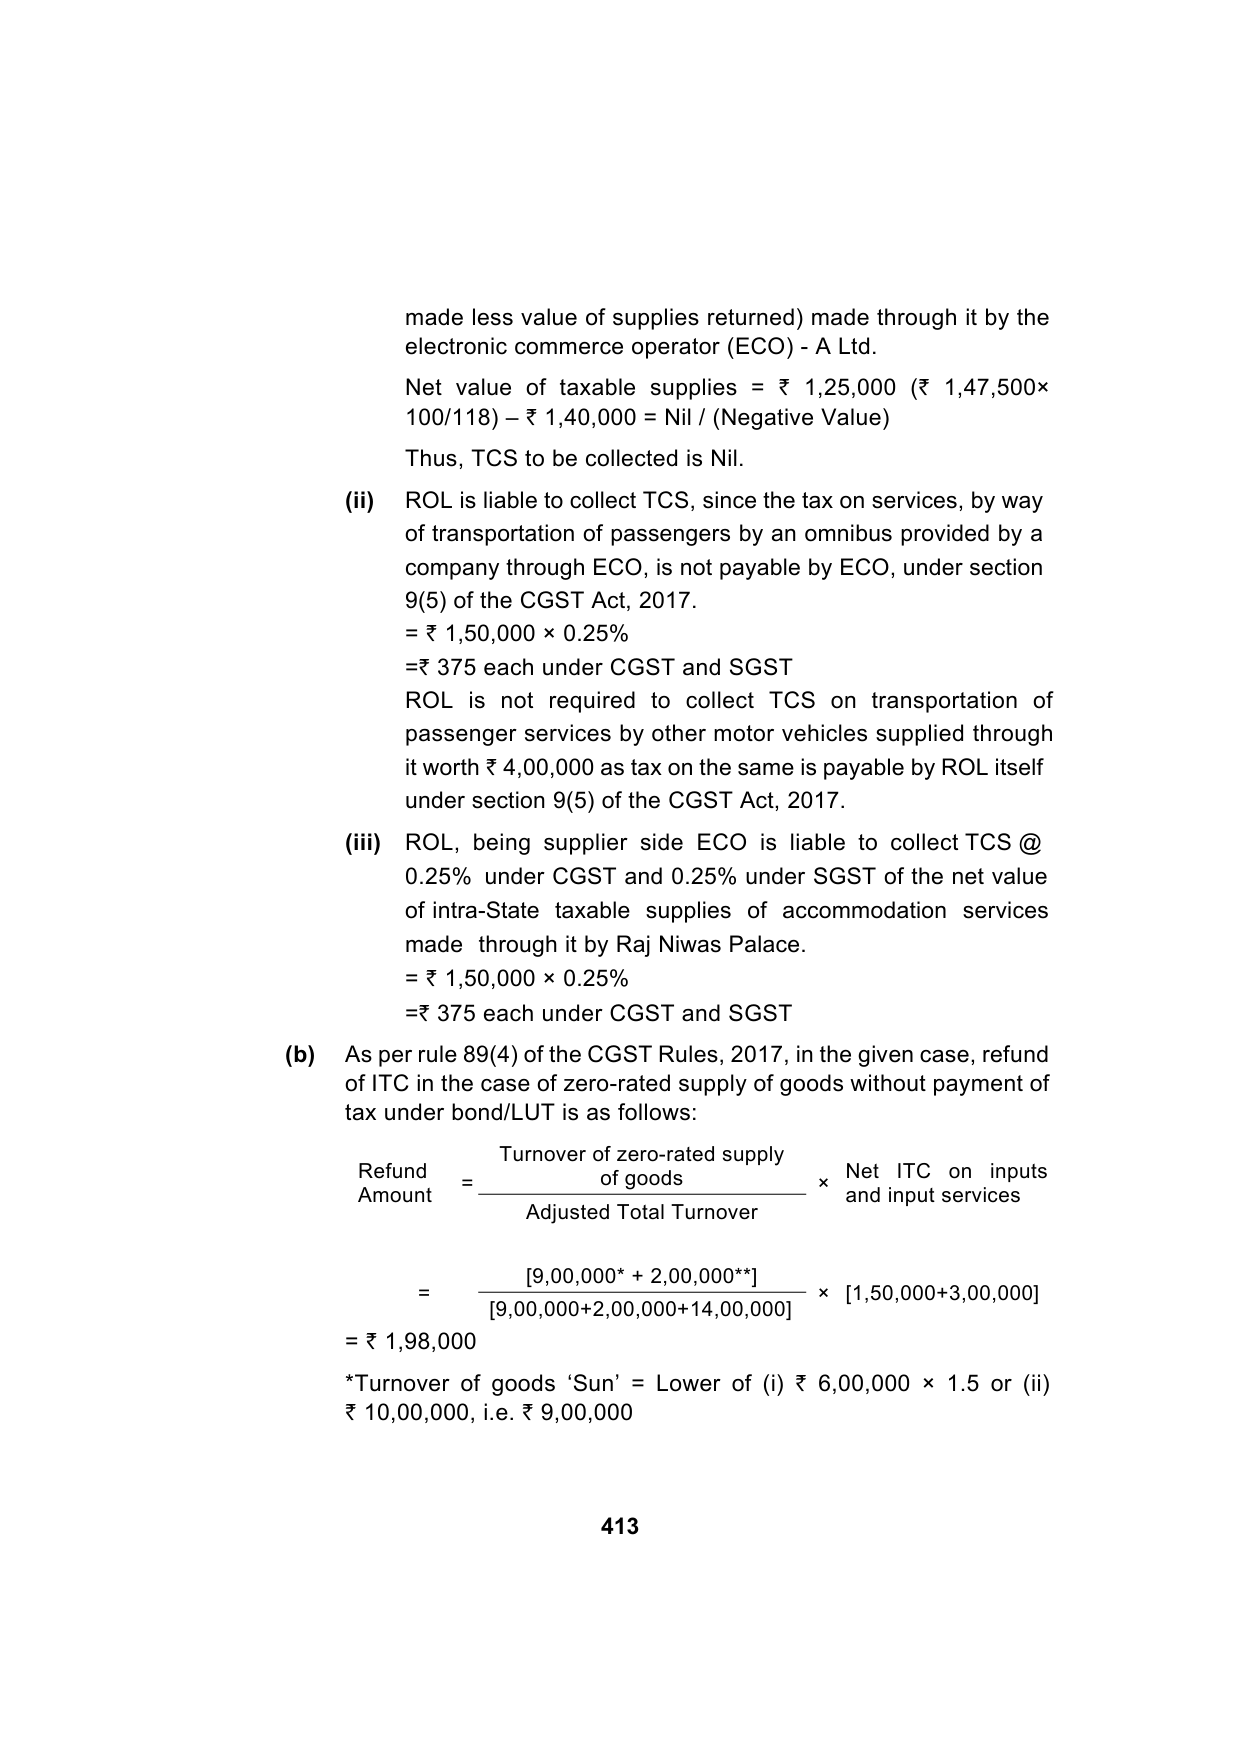
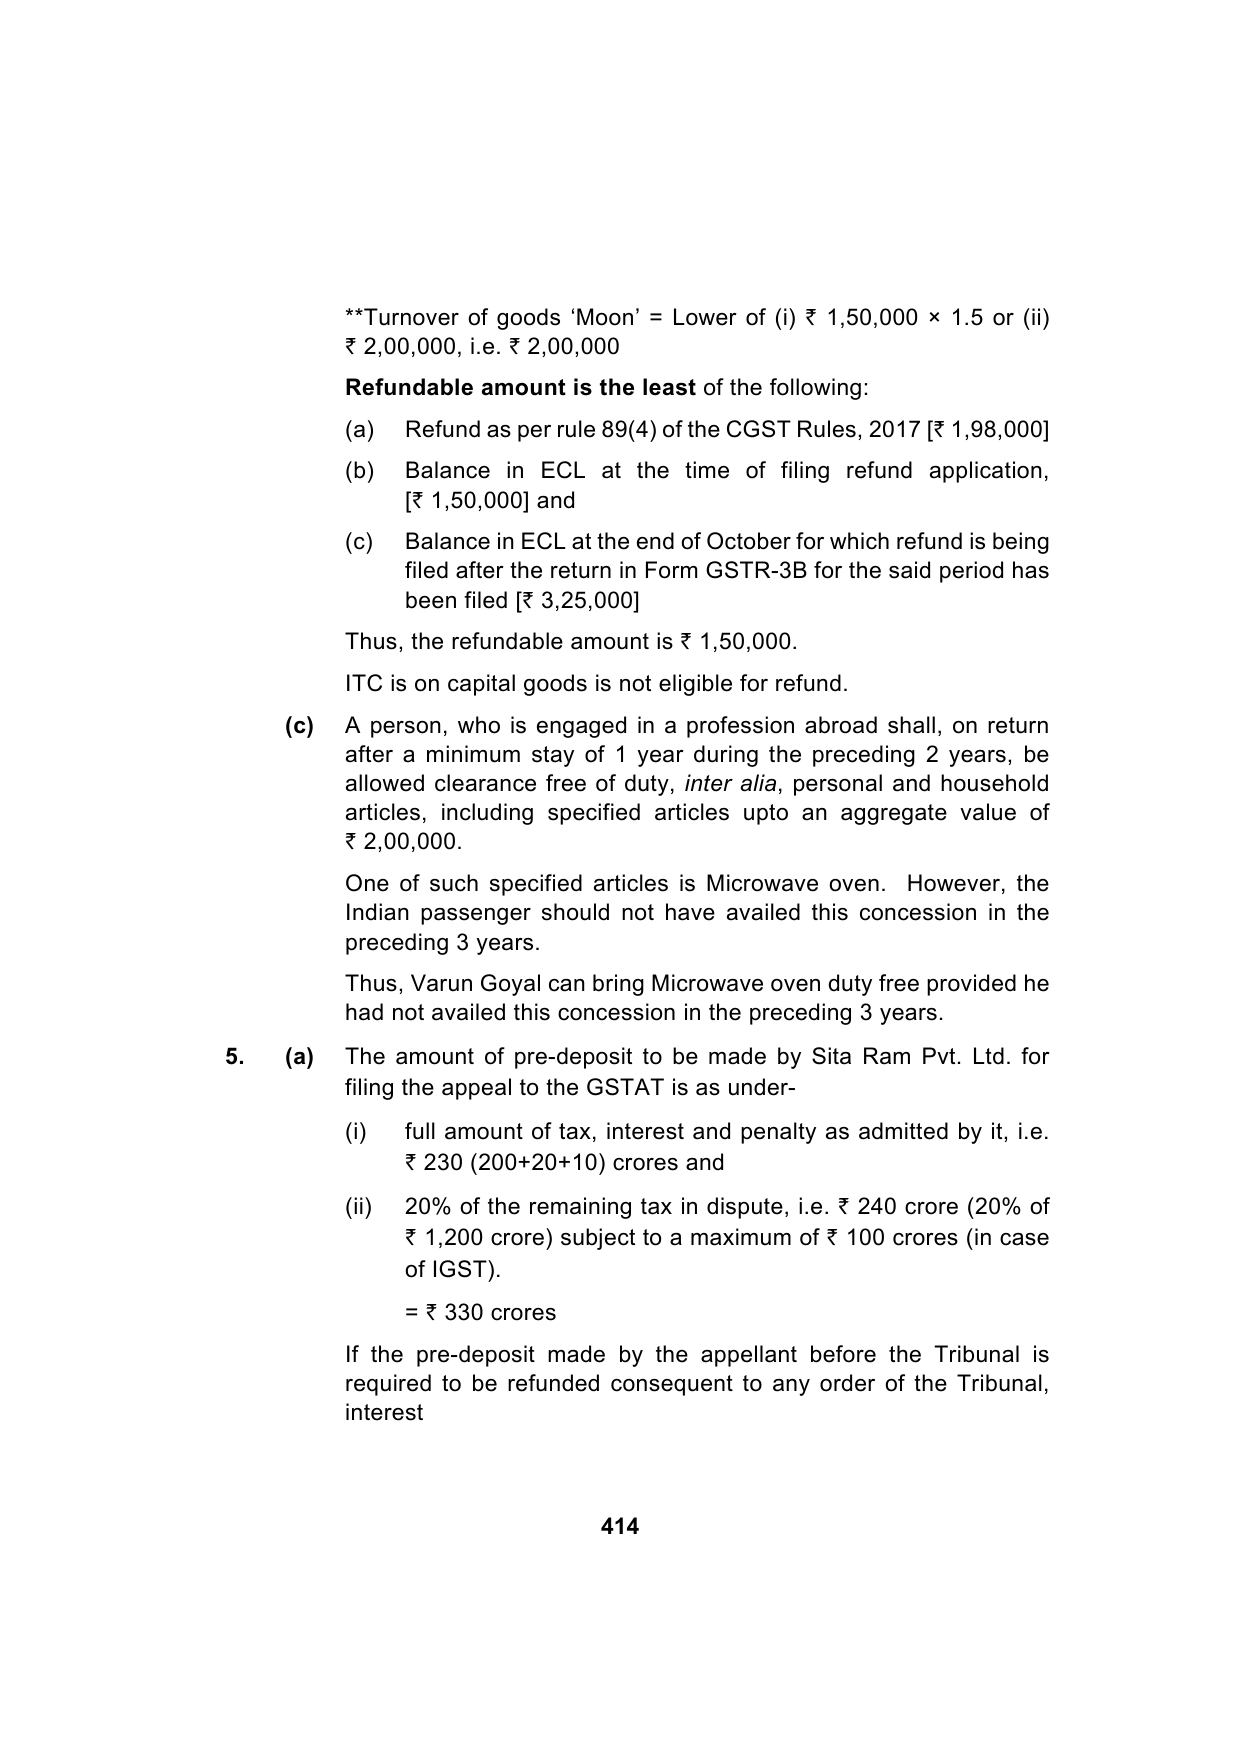
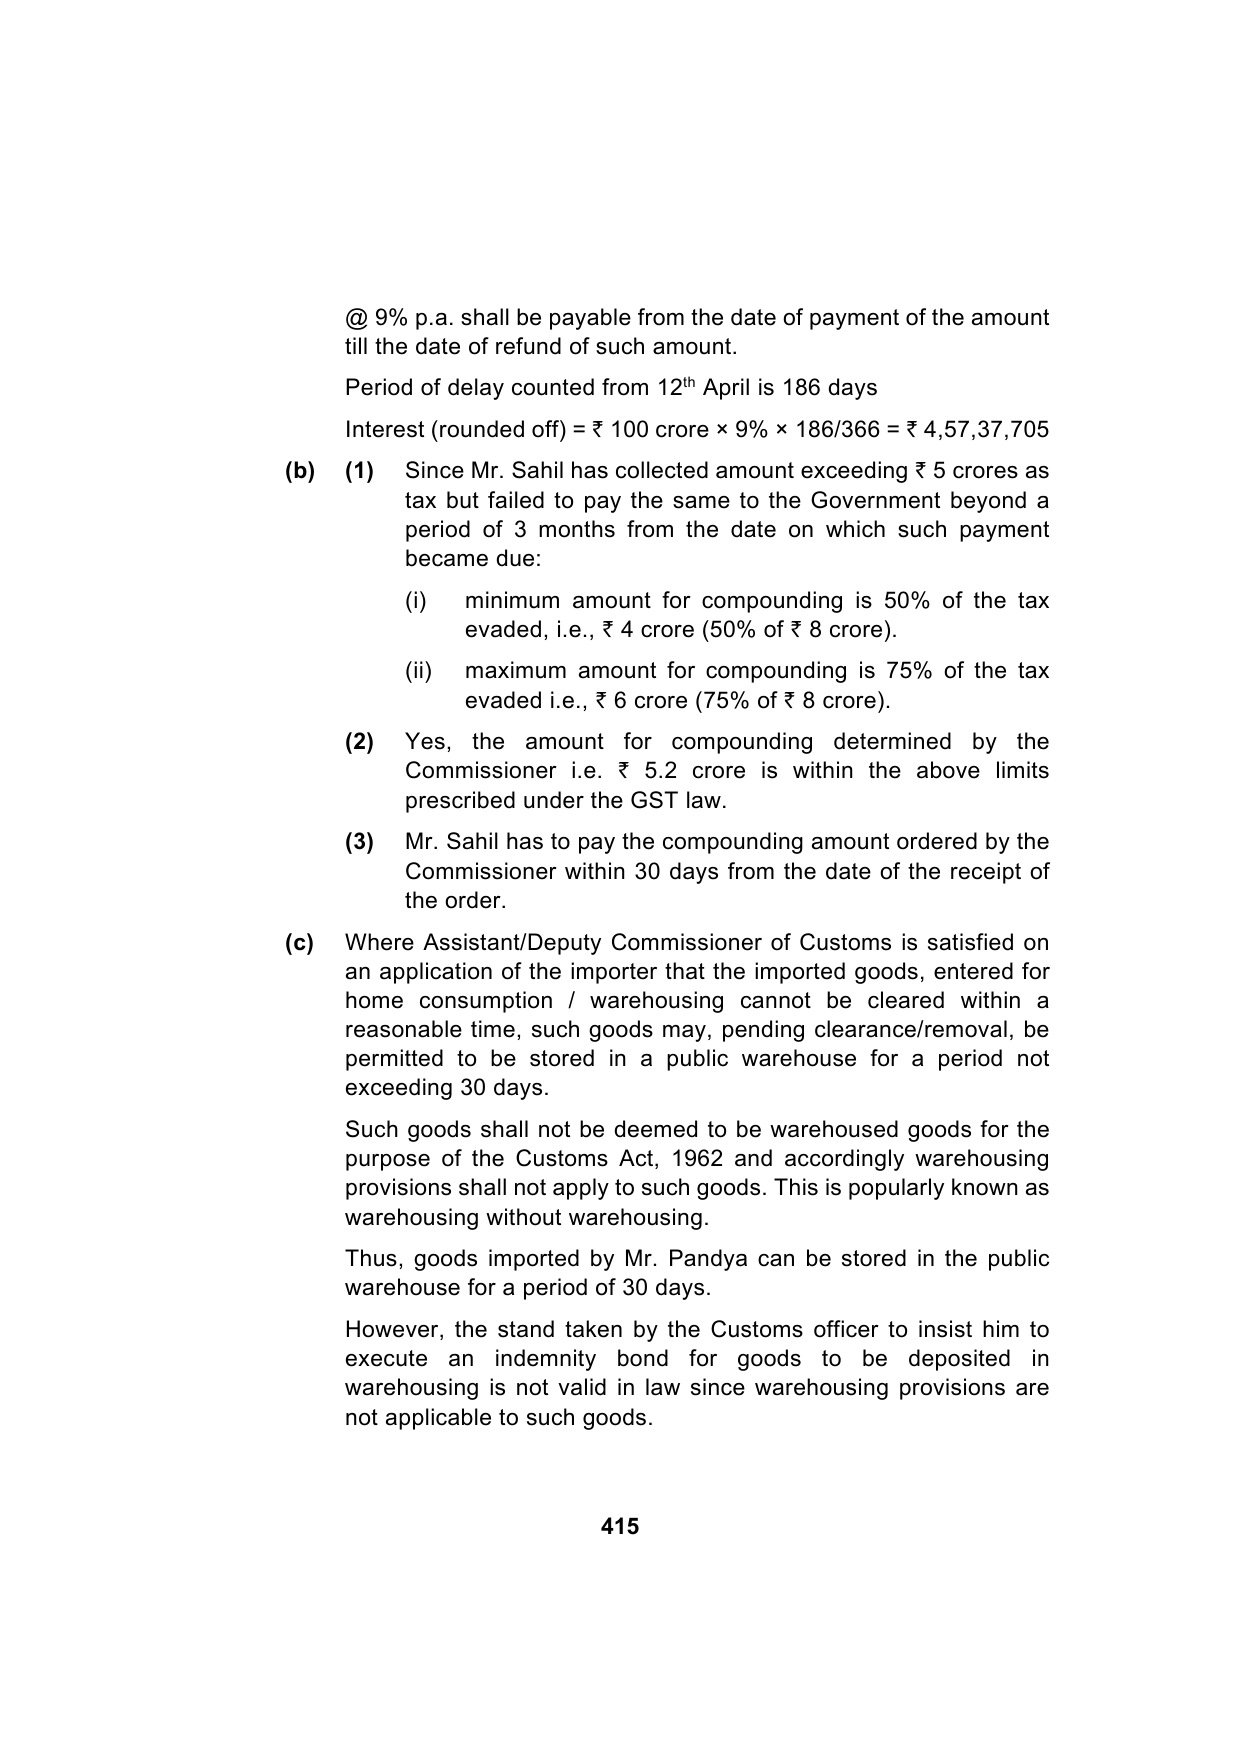
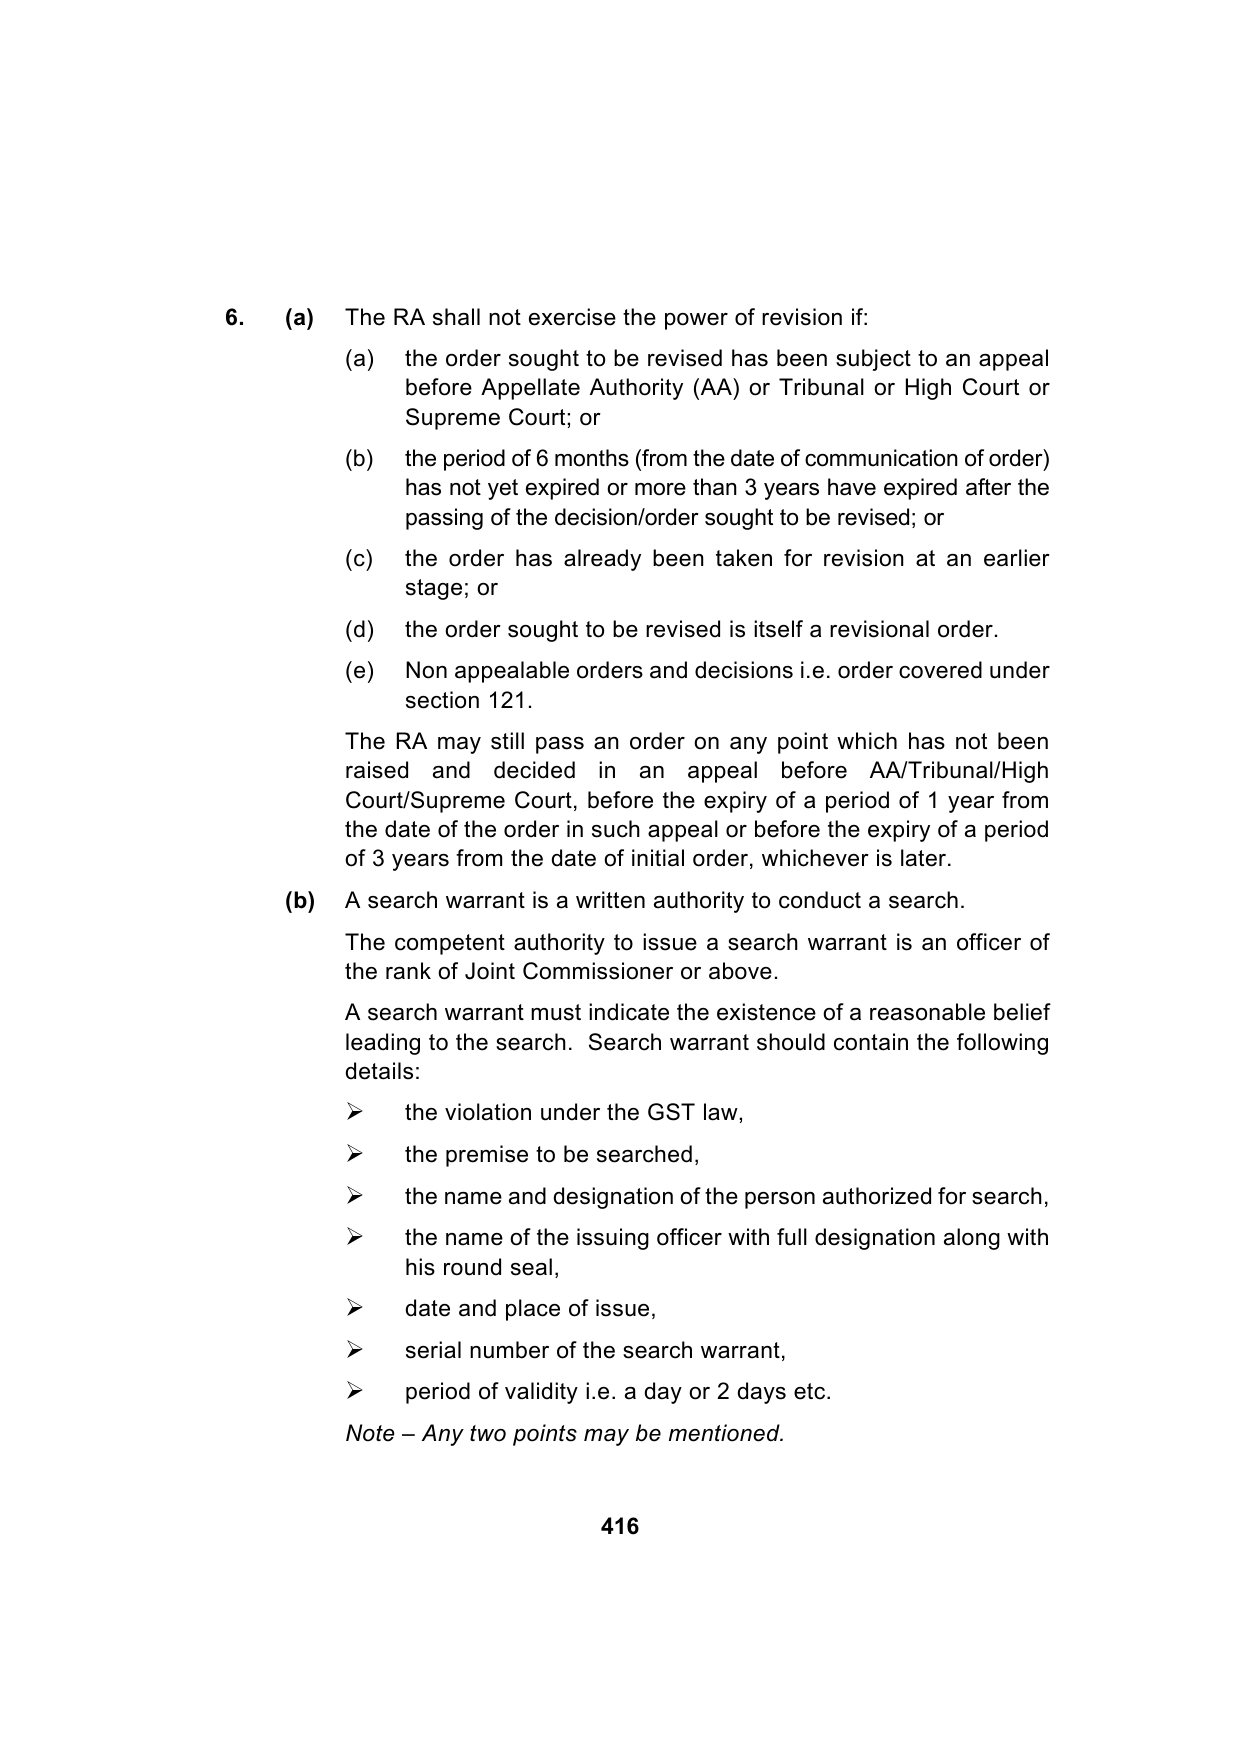
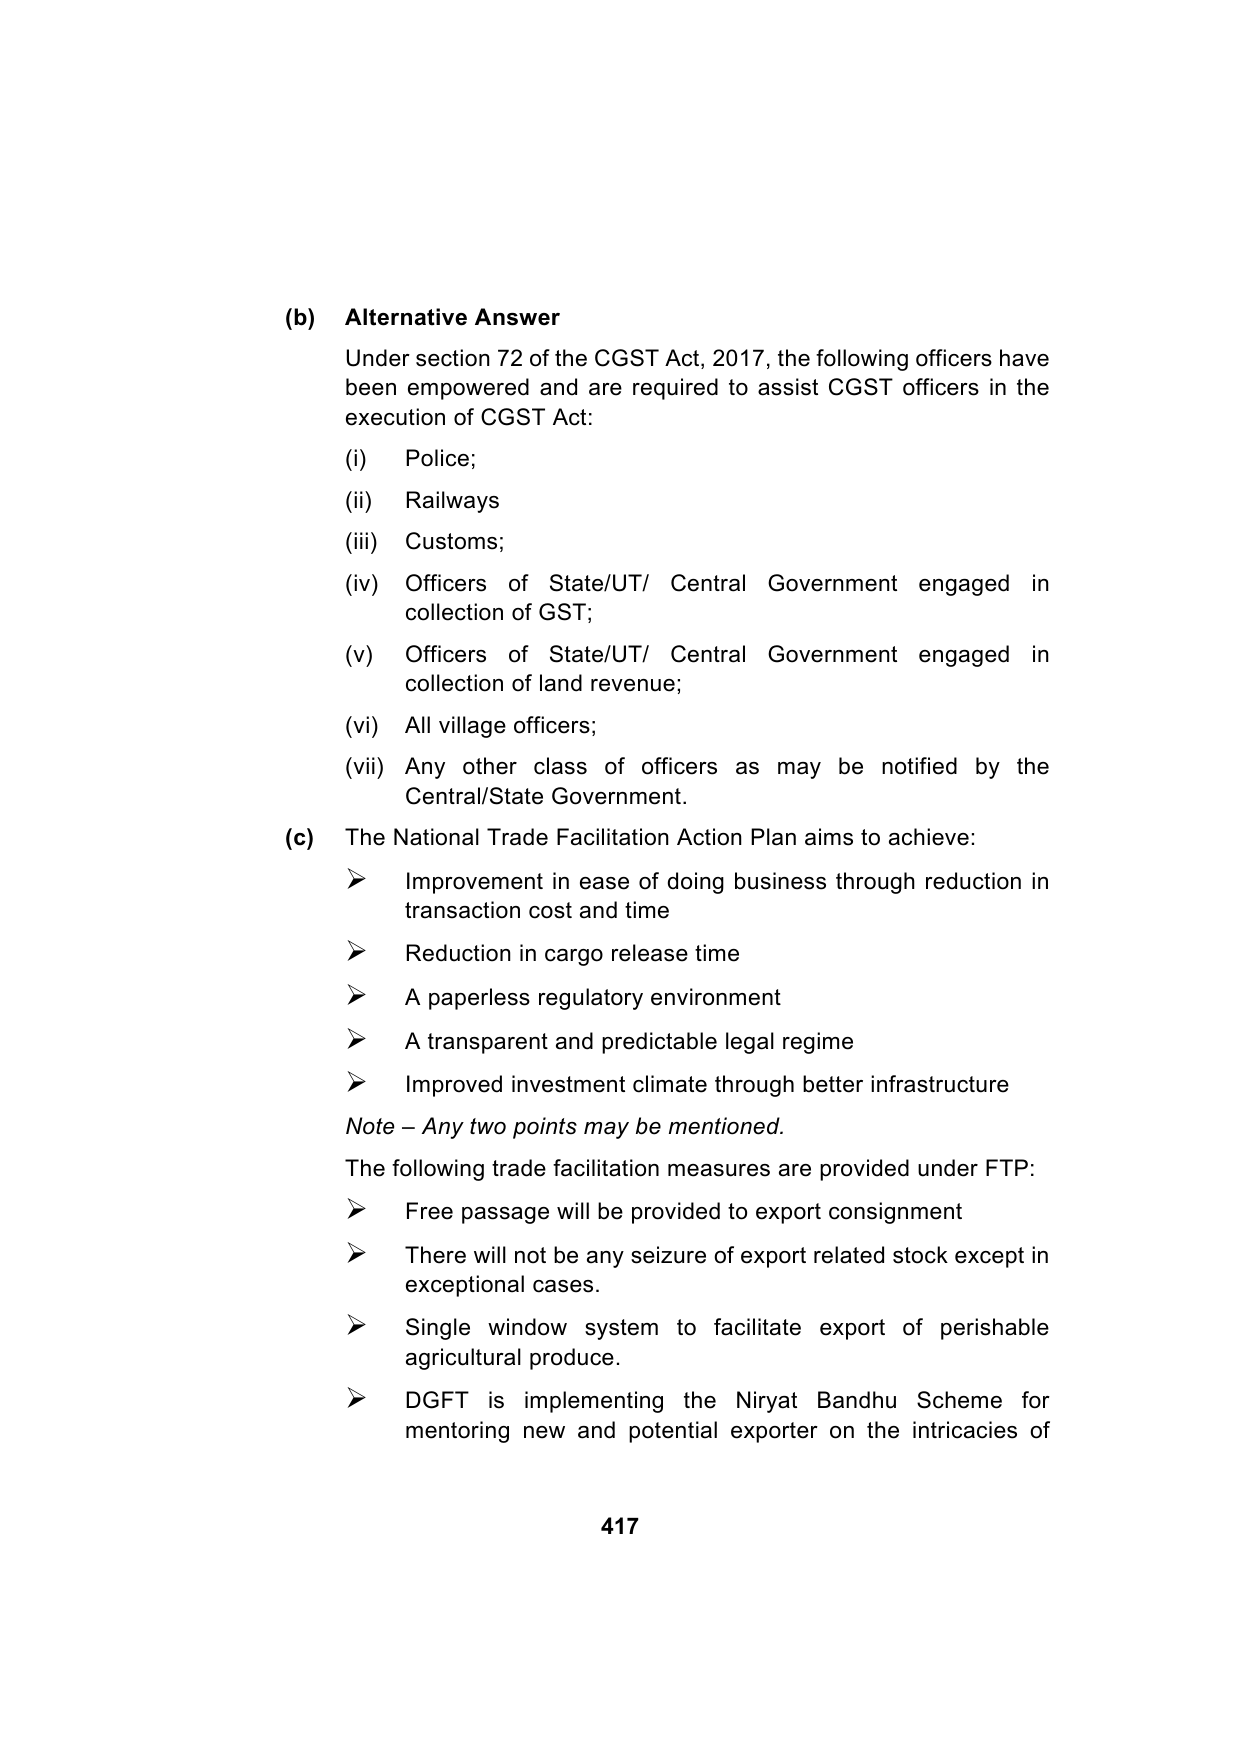
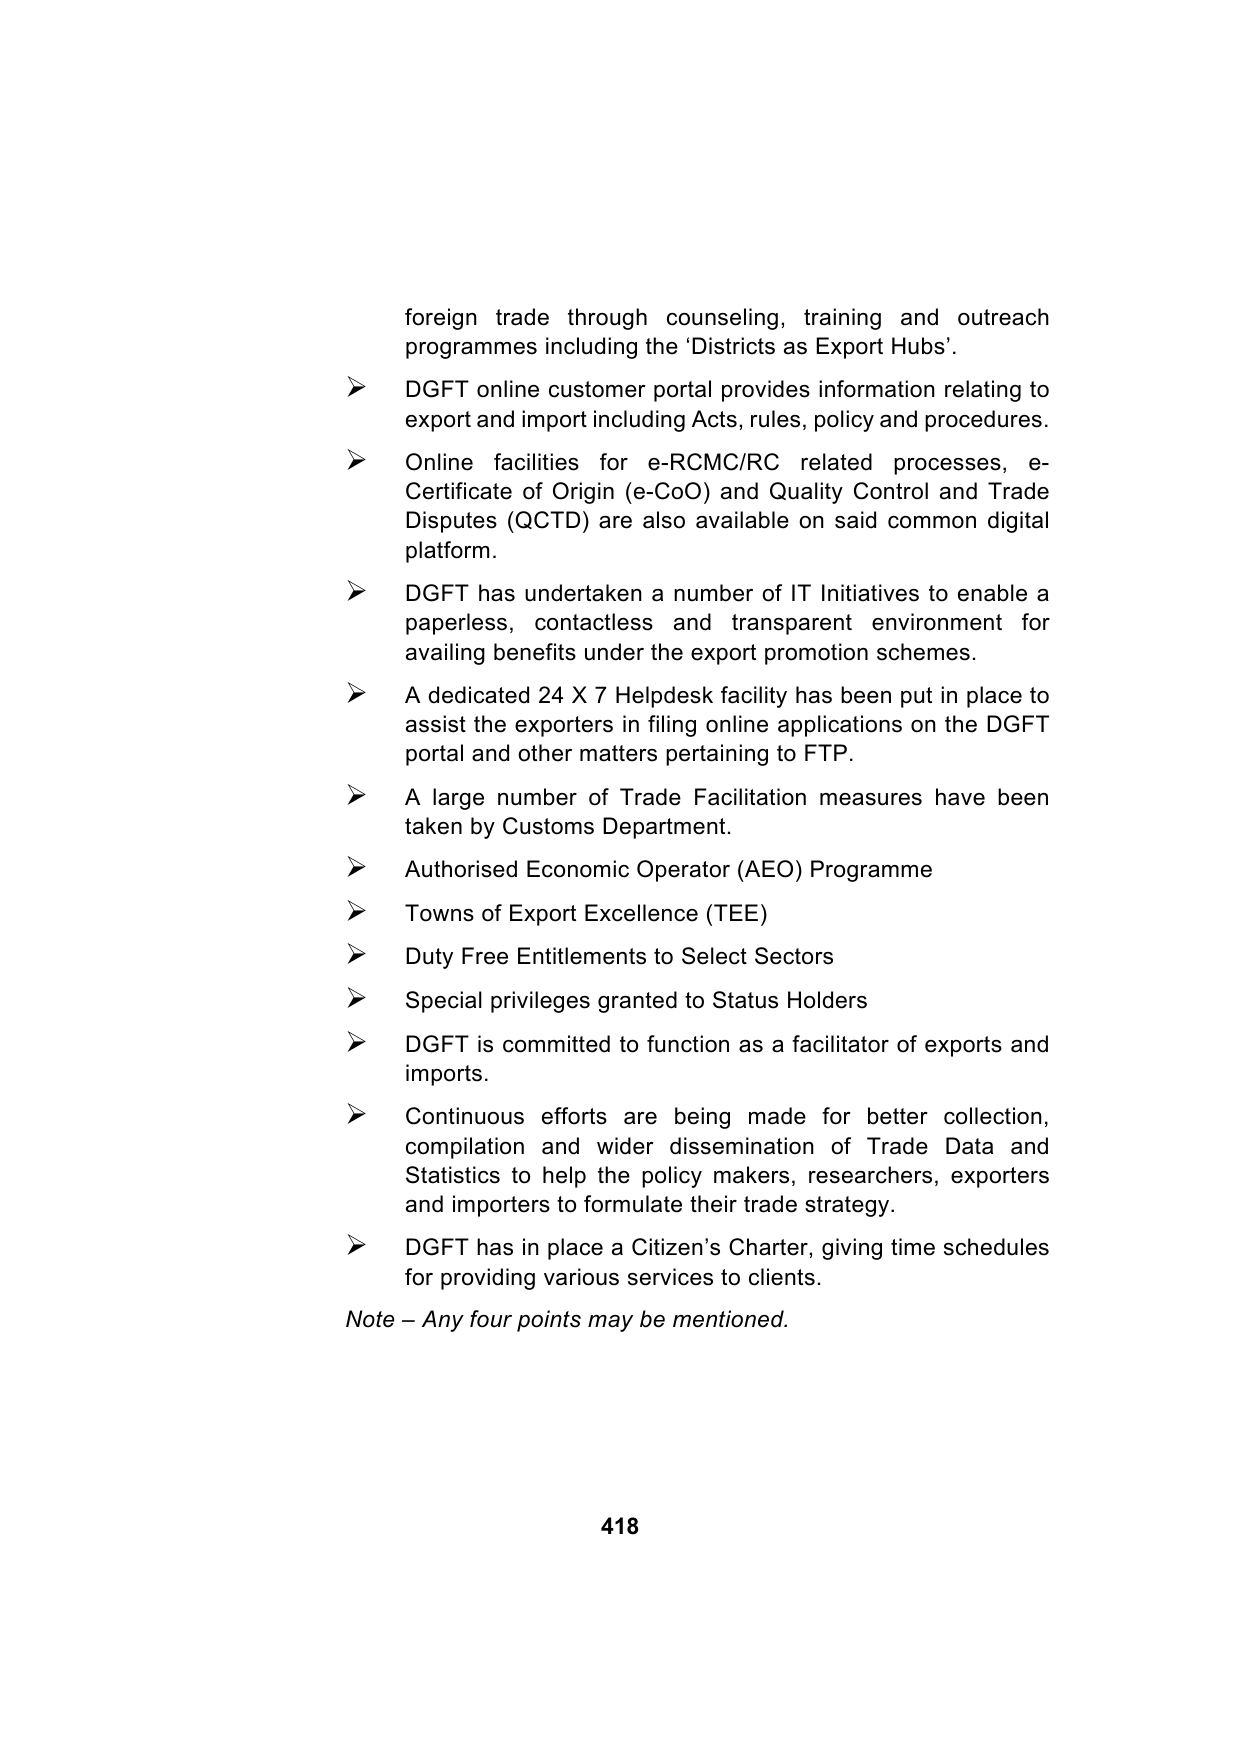
Paper 5: Indirect Tax Laws — Model Test Paper 6
Question
Answer
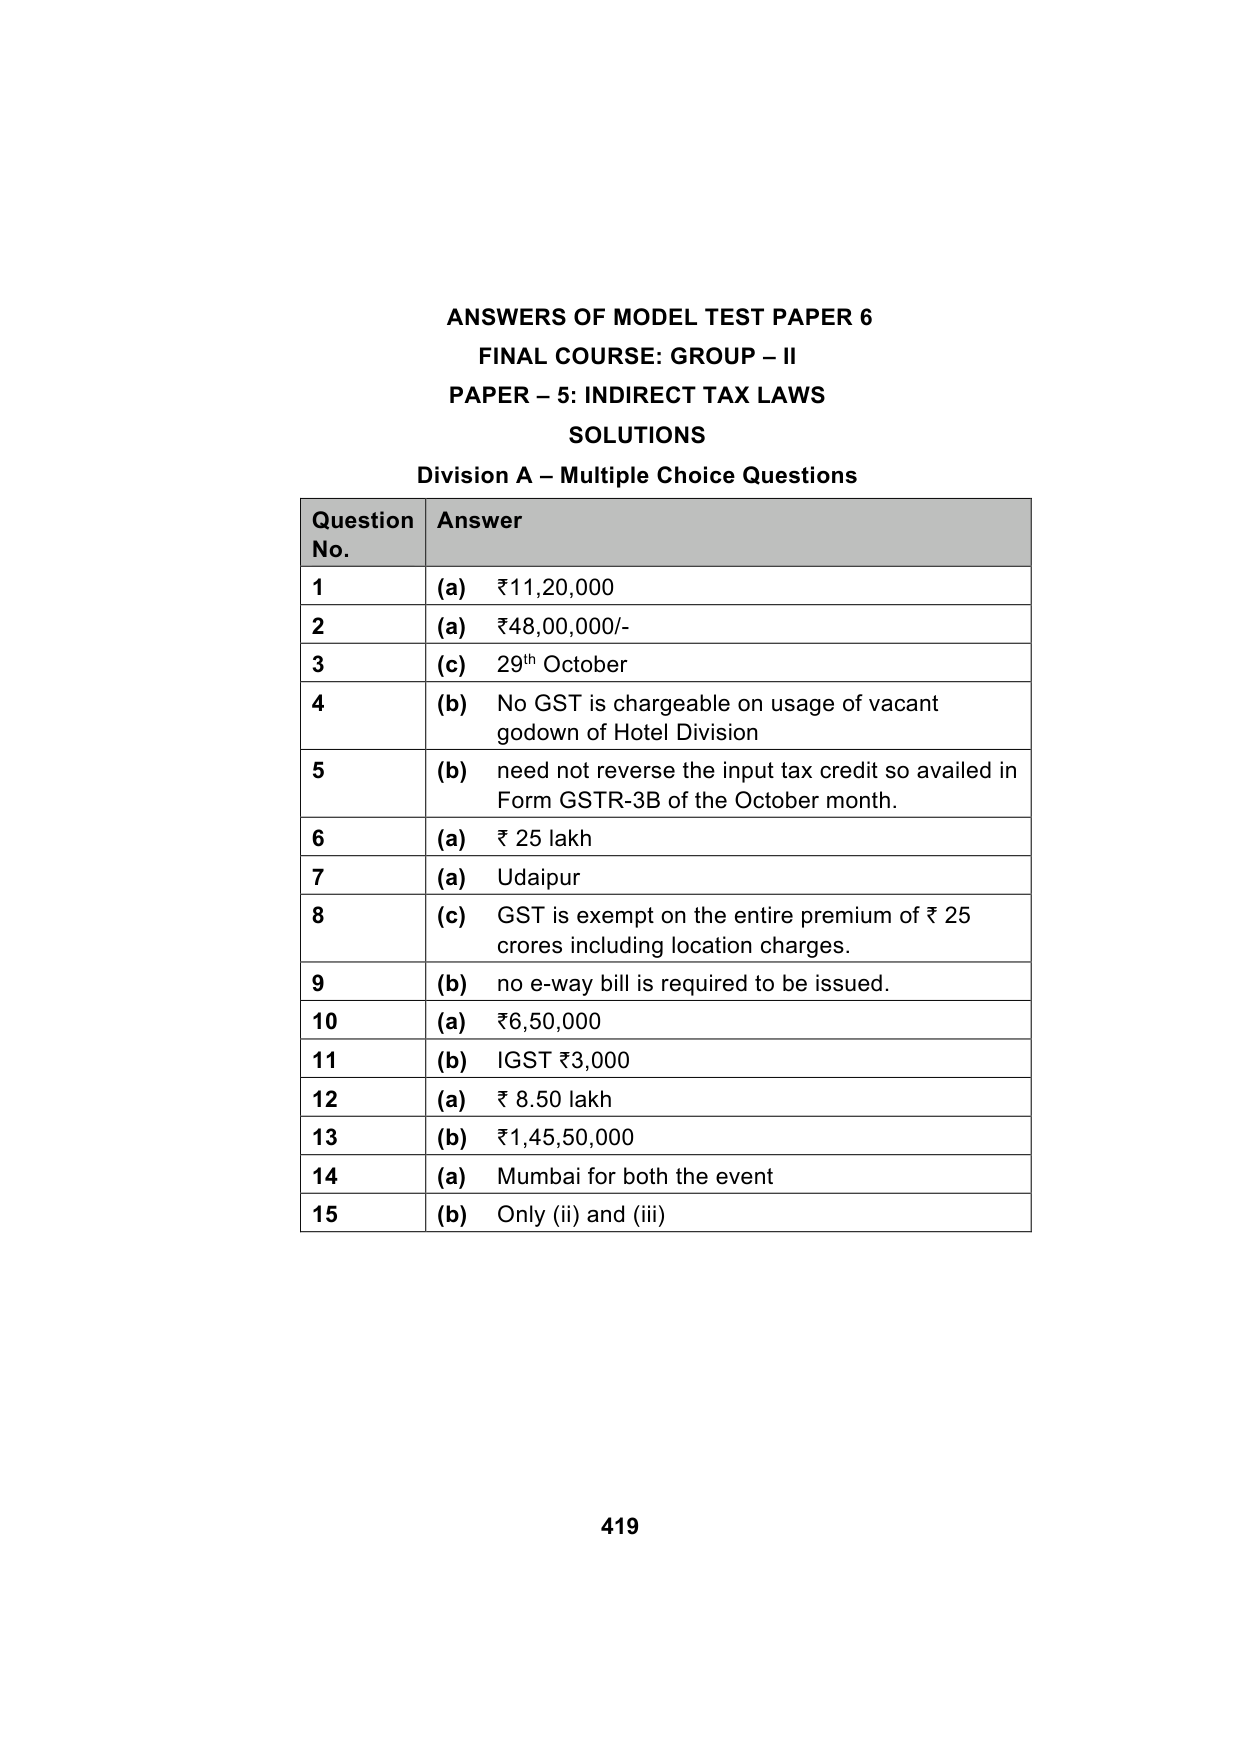
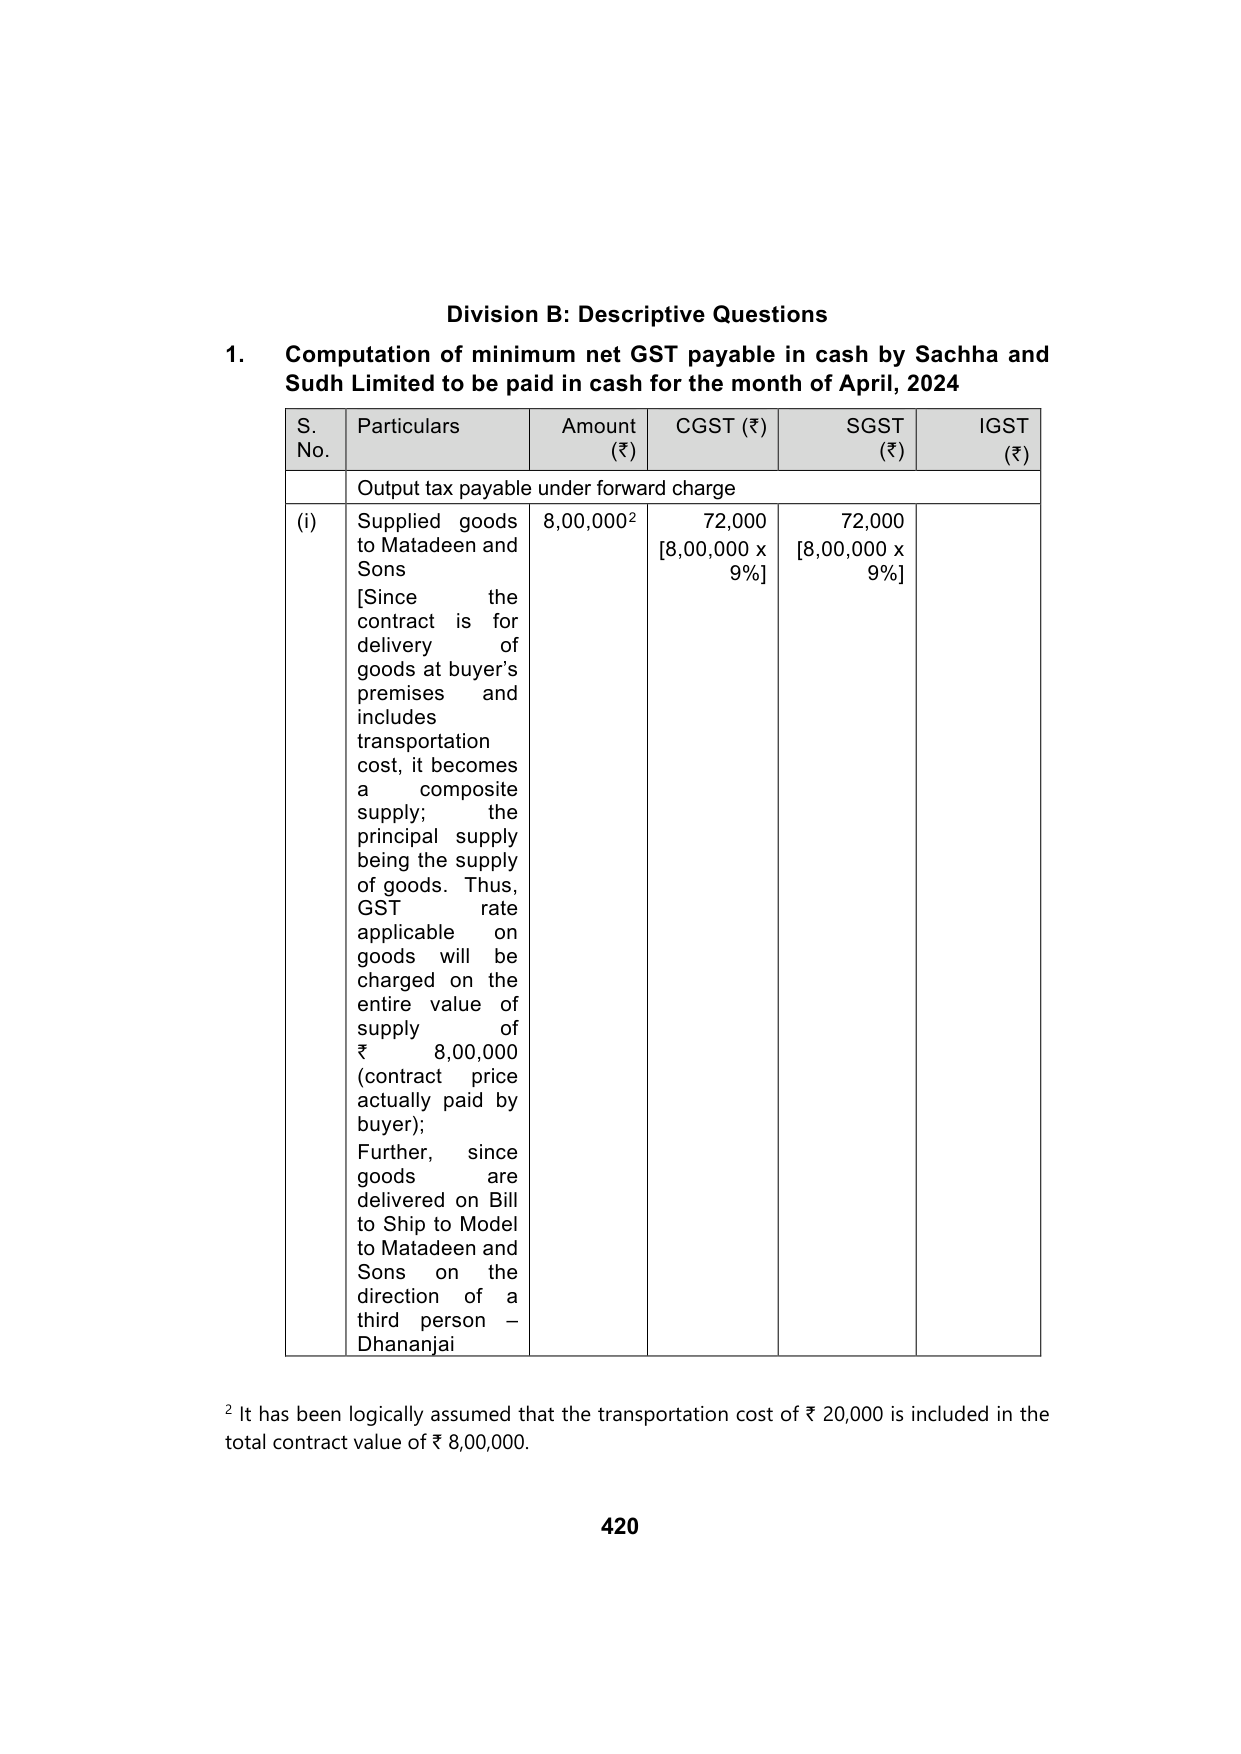
Get Notified About New Papers