Advanced Accounting - Sep Rtp 2025 RTP
Revision Test Paper with Questions
Inside This Paper
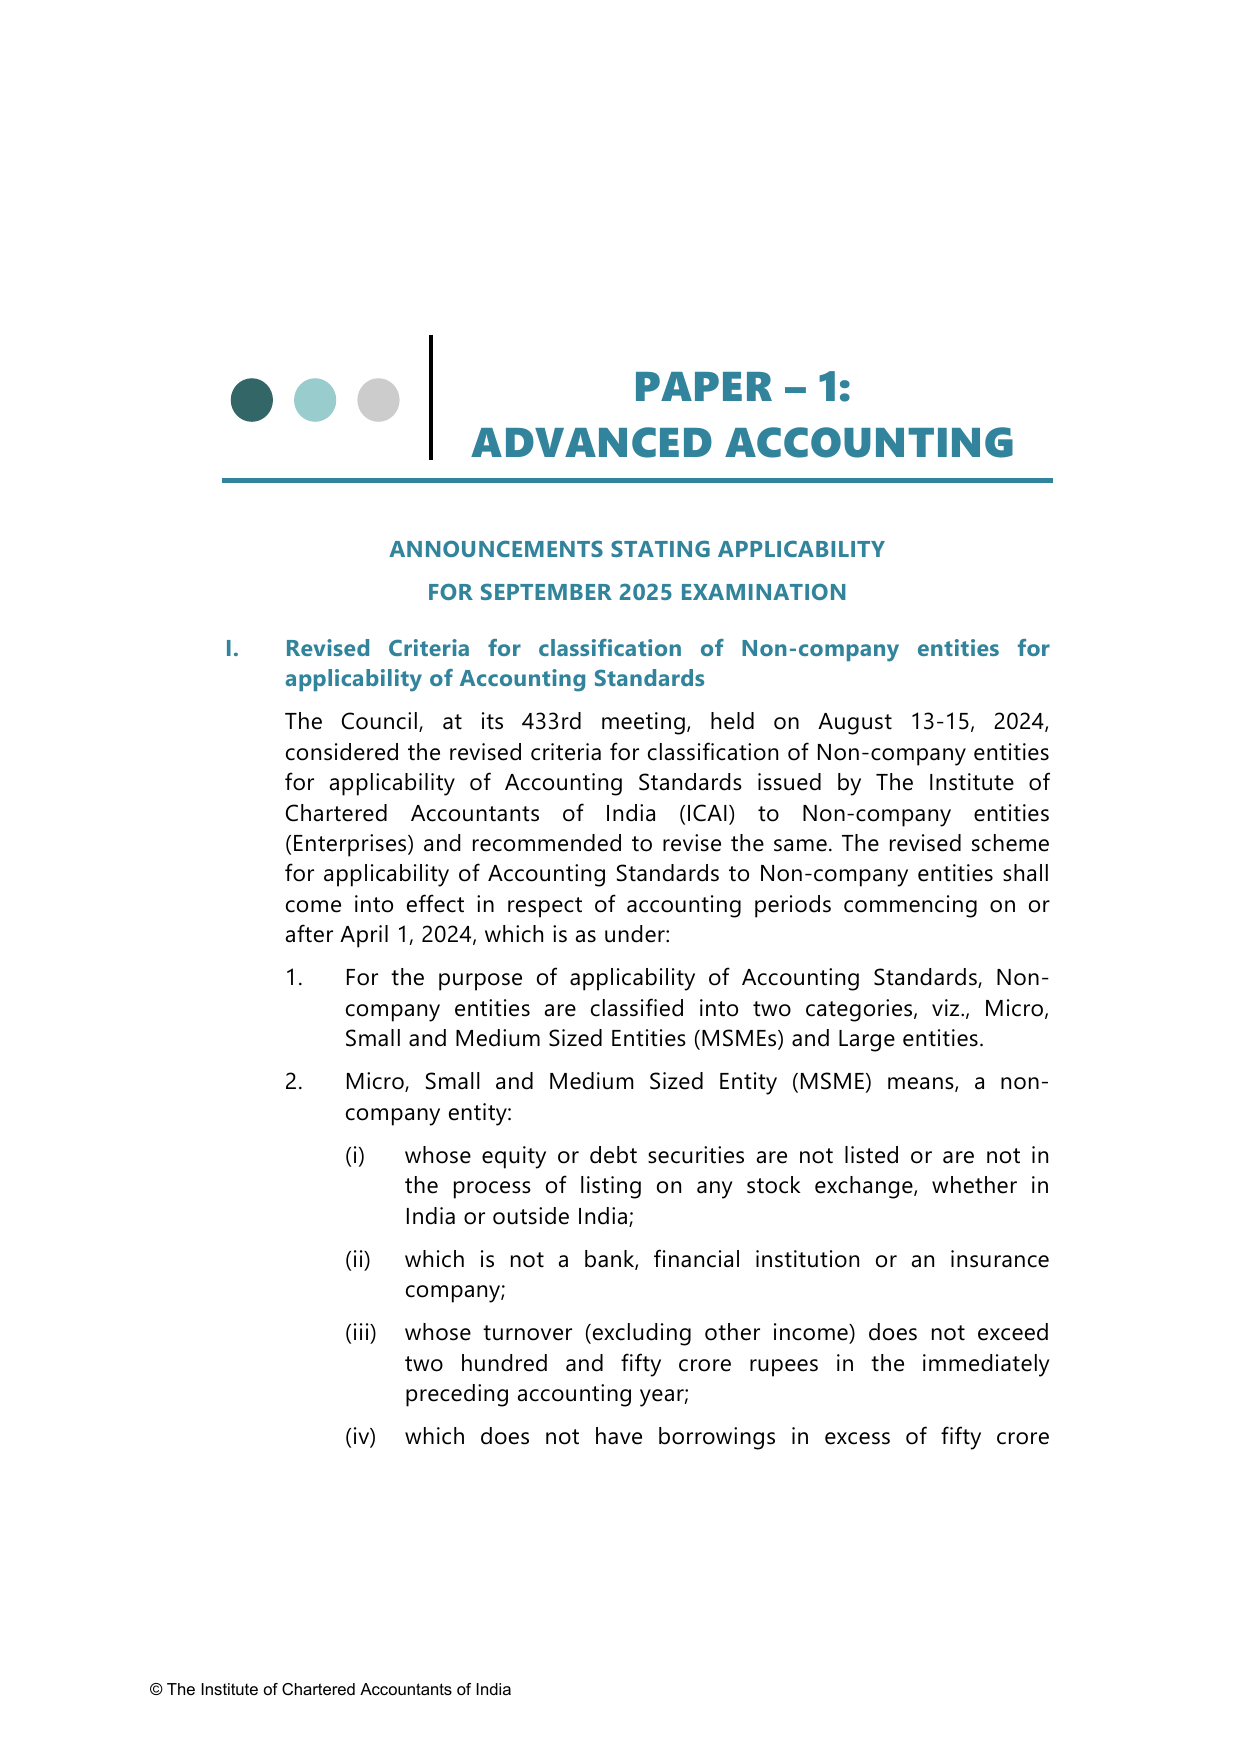
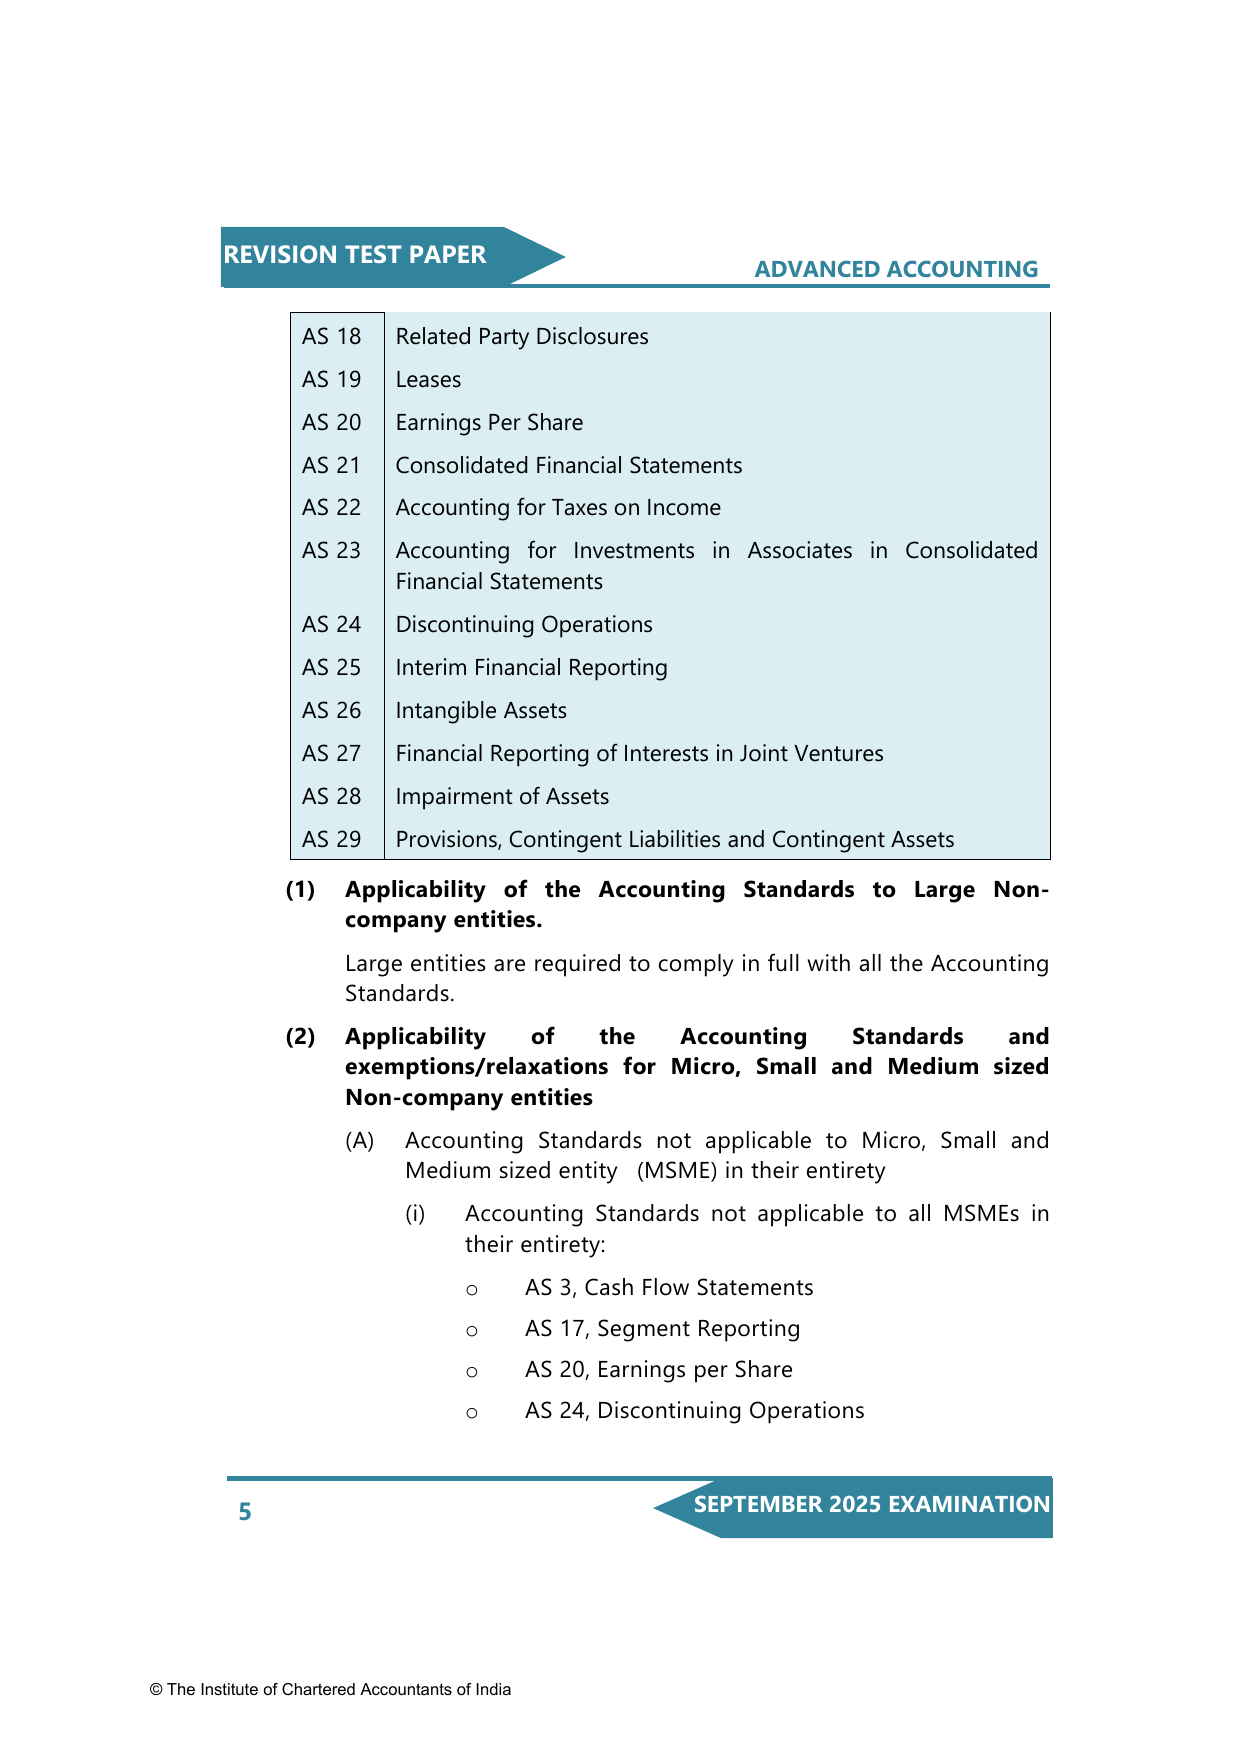
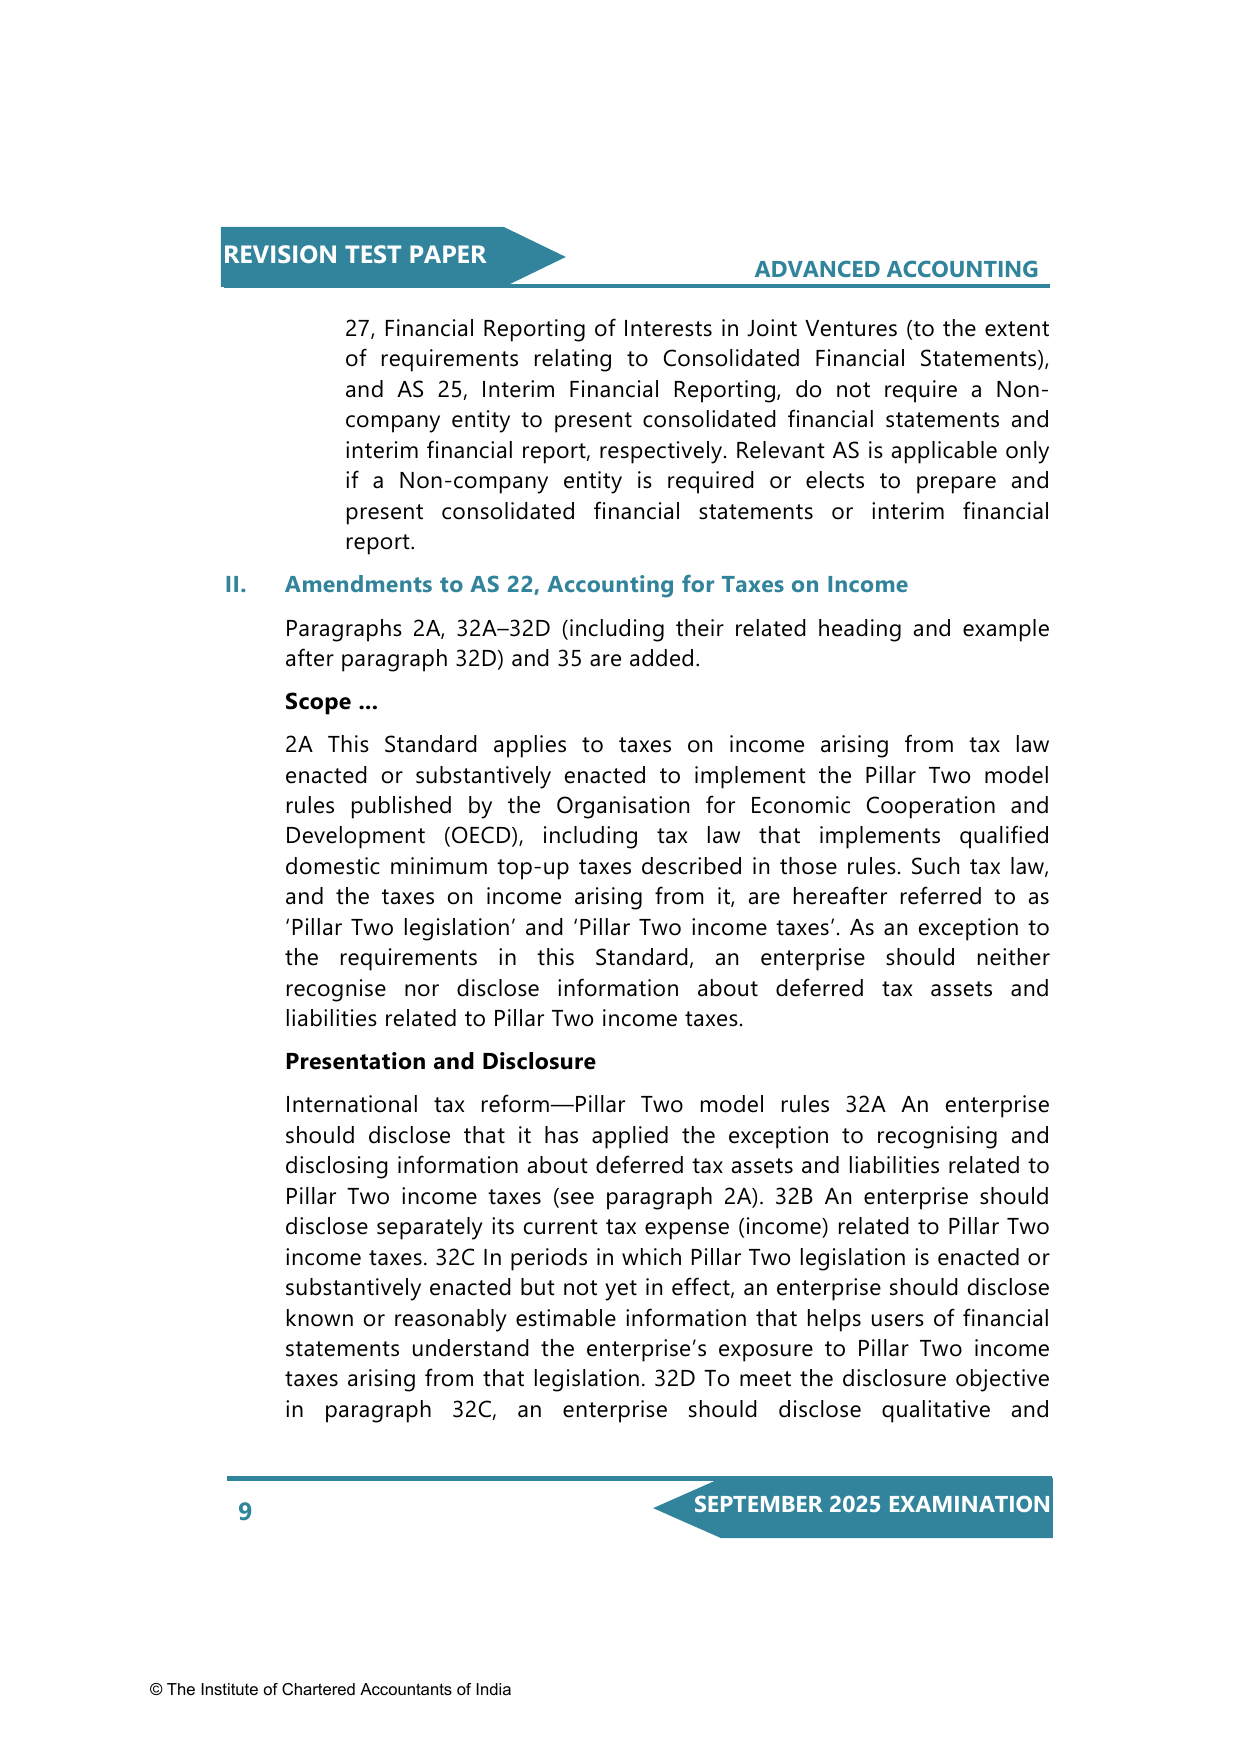
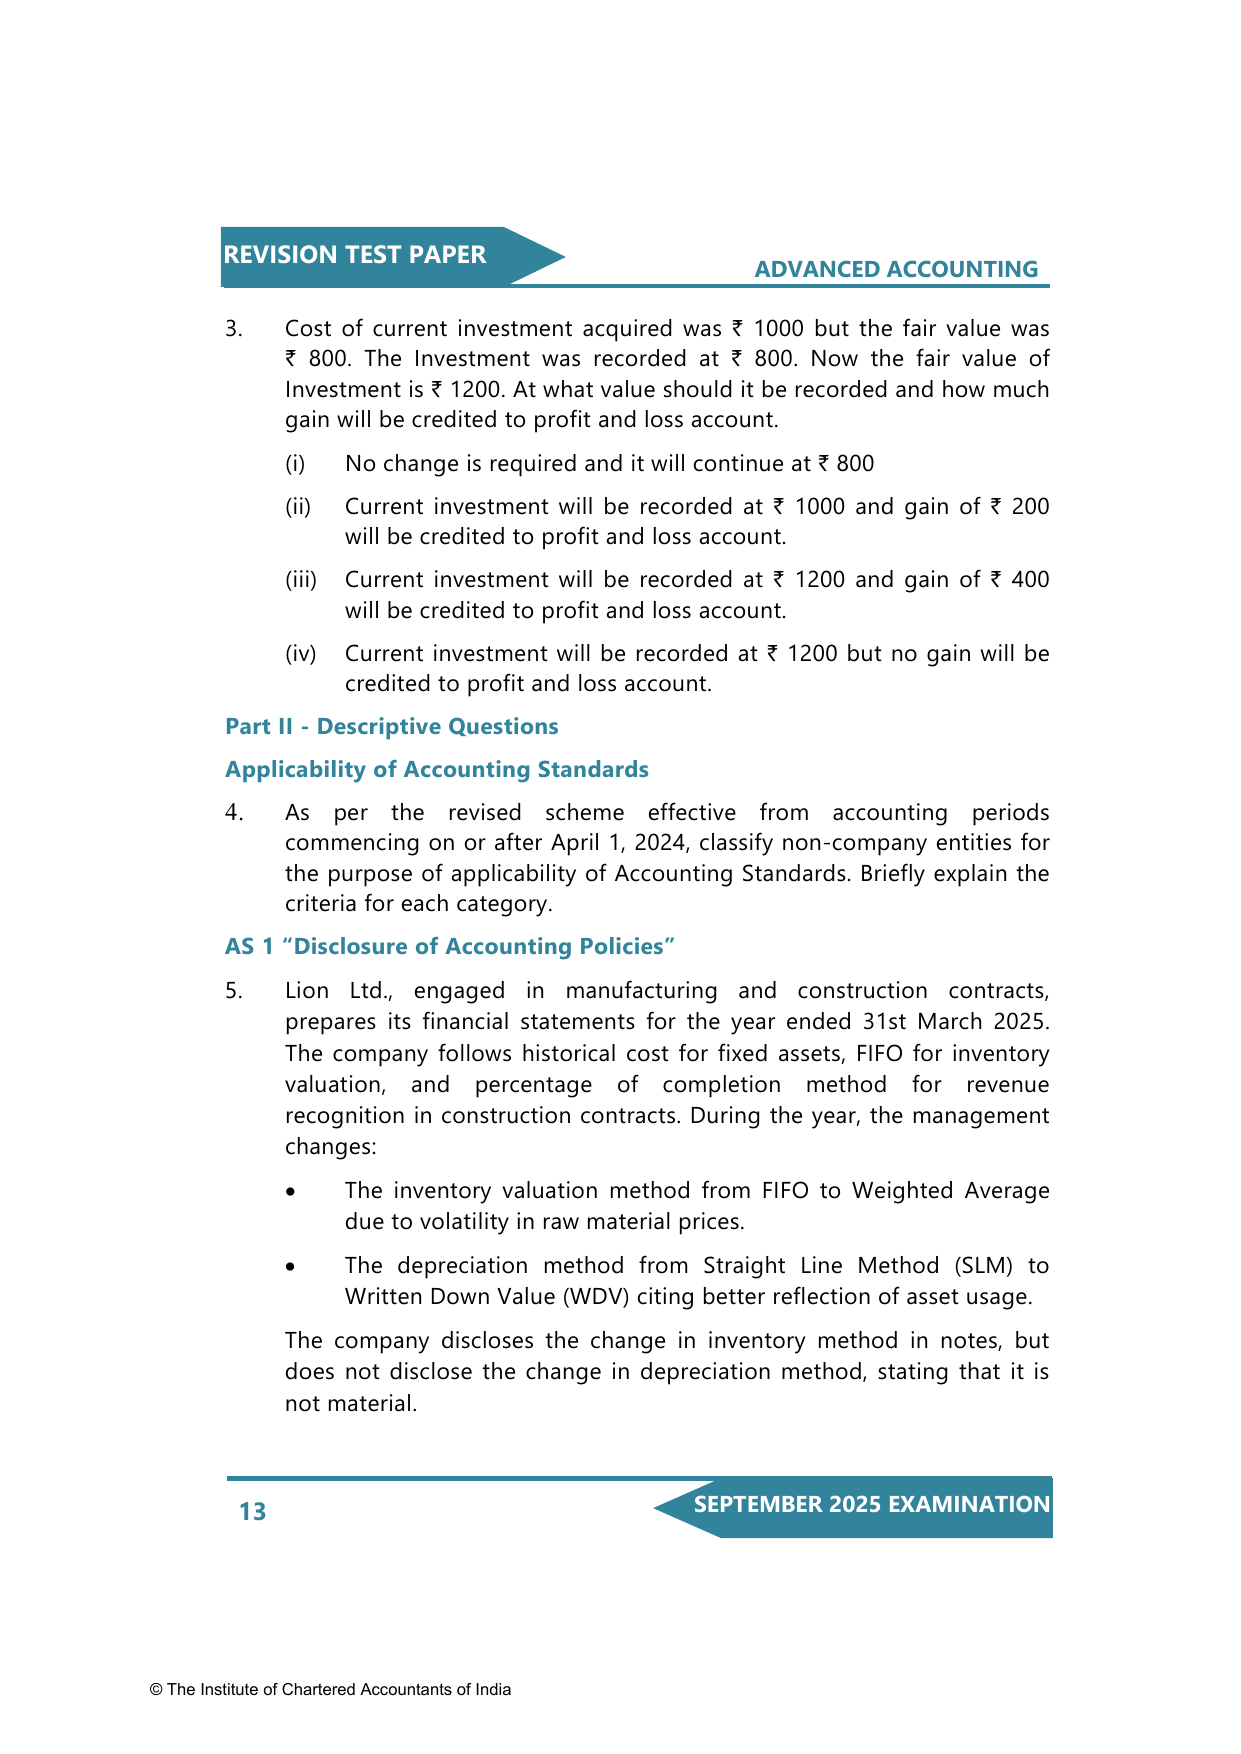
1. For the purpose of applicability of Accounting Standards, Noncompany entities are classified into two categories, viz., Micro, Small and Medium Sized Entities (MSMEs) and Large entities.
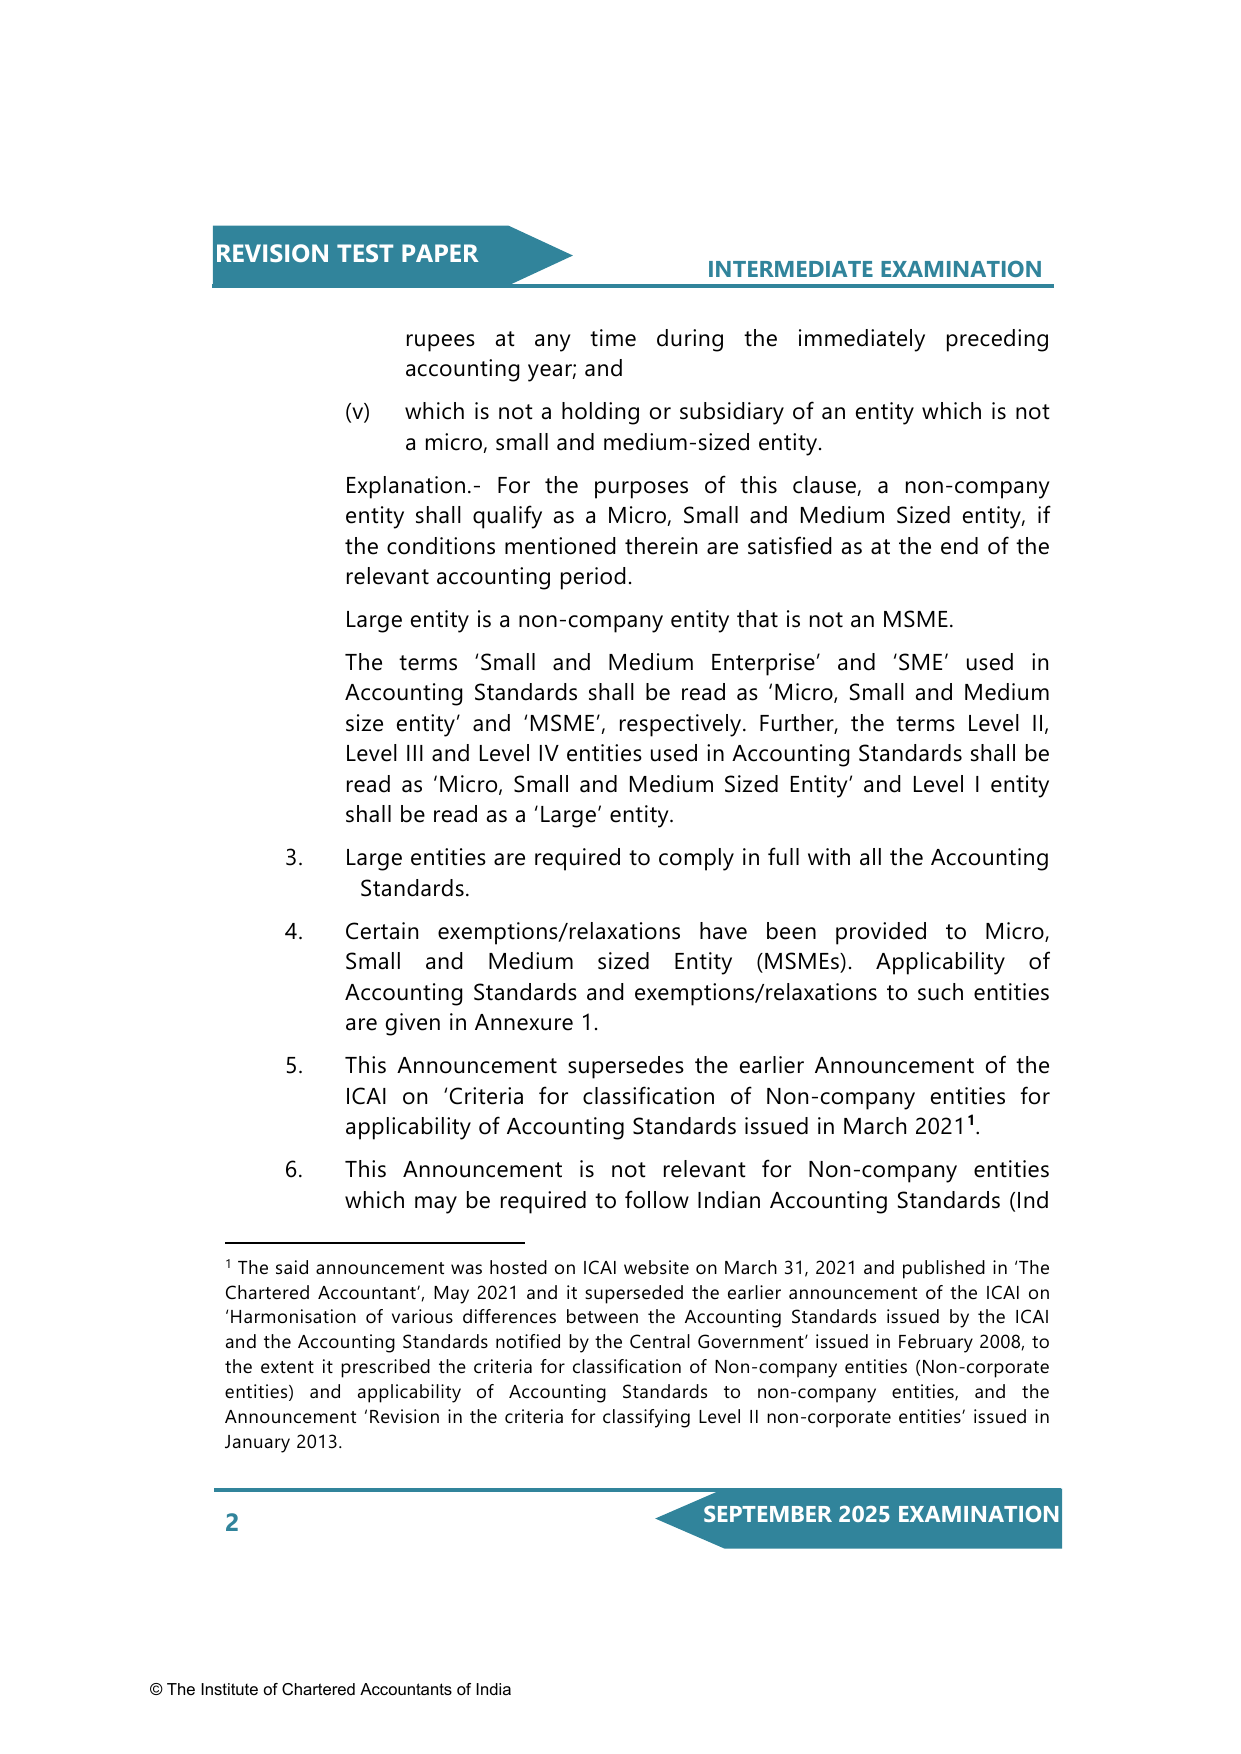
Sized Entity (MSME) means, a noncompany entity: (i) | whose equity or debt securities are not listed or are not in the process of listing on any stock exchange, whether in India or outside India; (ii) which is not a bank, financial institution or an insurance company; (iii) whose turnover (excluding other income) does not exceed two hundred and fifty crore rupees in the immediately preceding accounting year; (iv) which does not have borrowings in excess of fifty crore BEVISIONTESTIES…
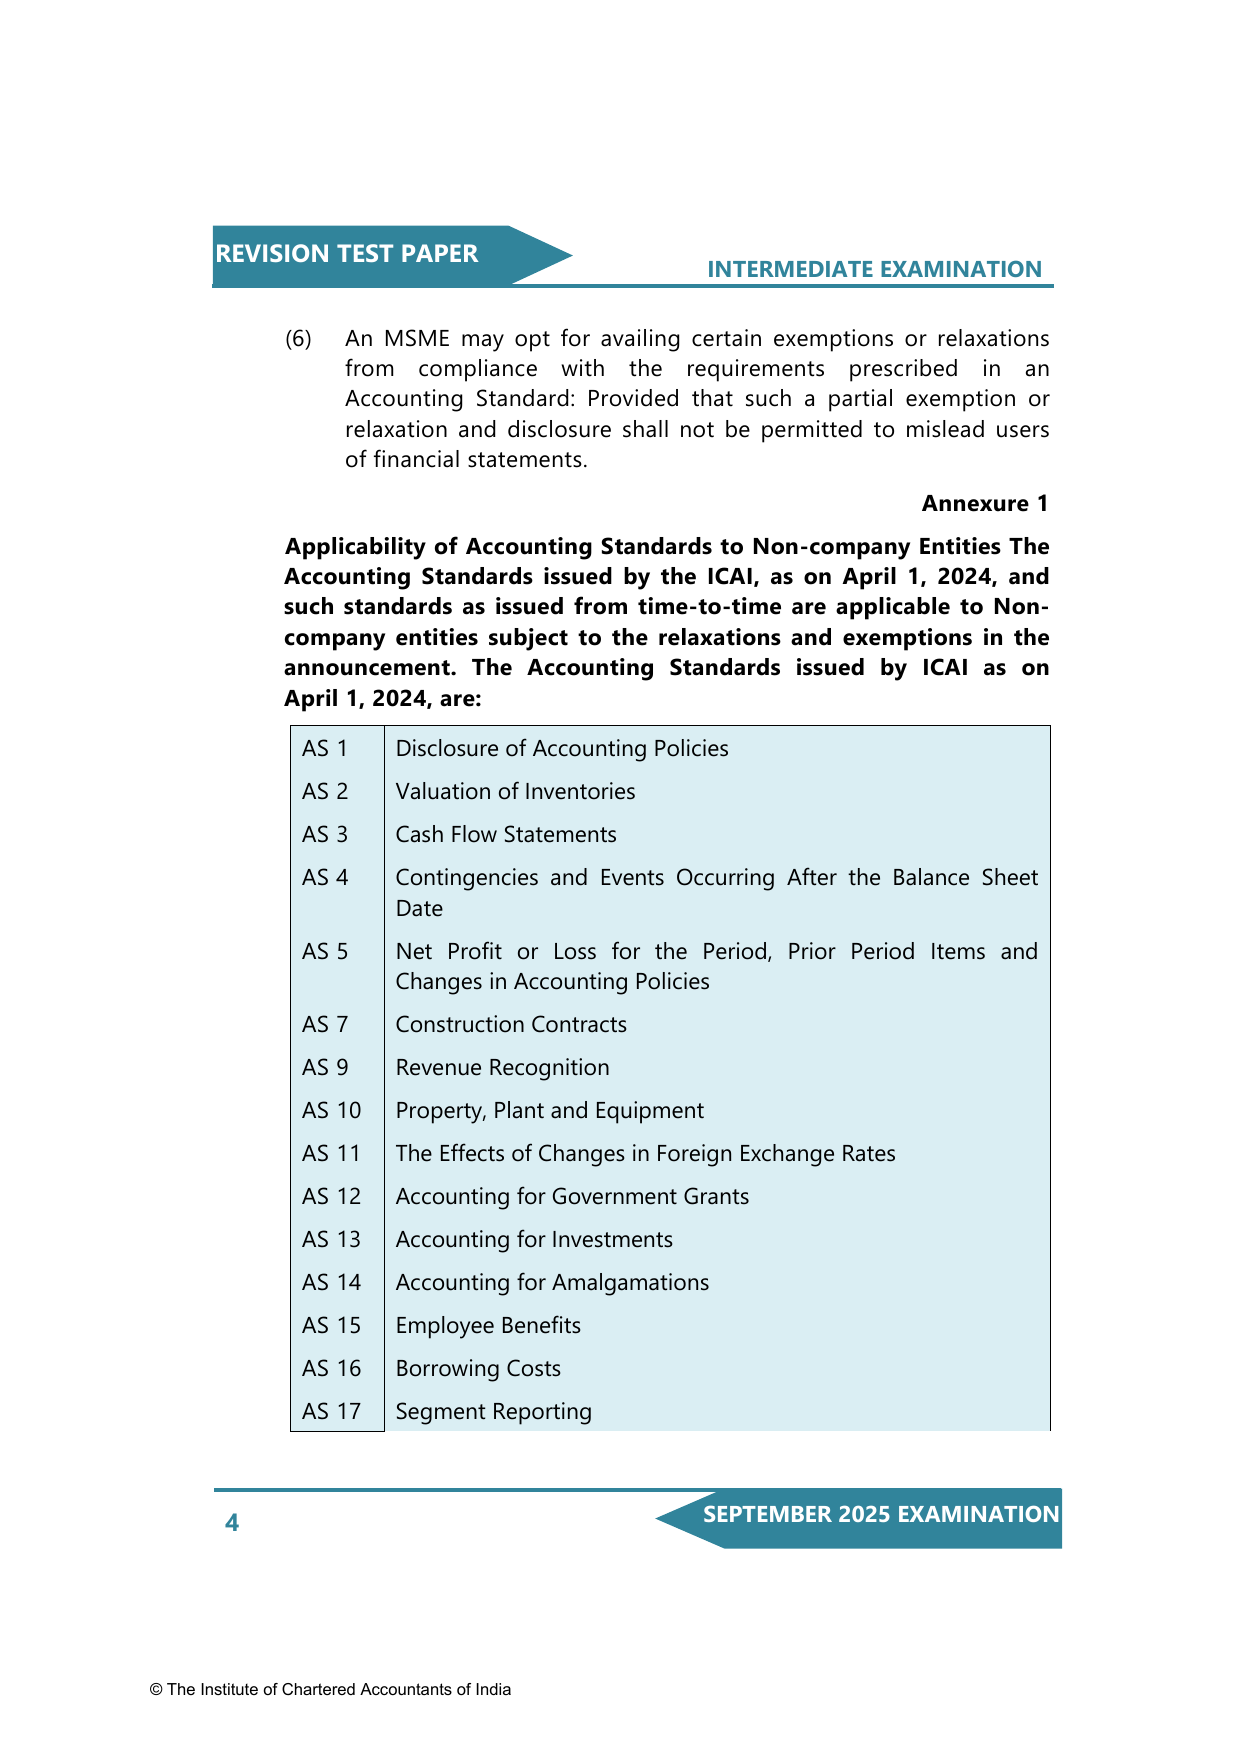
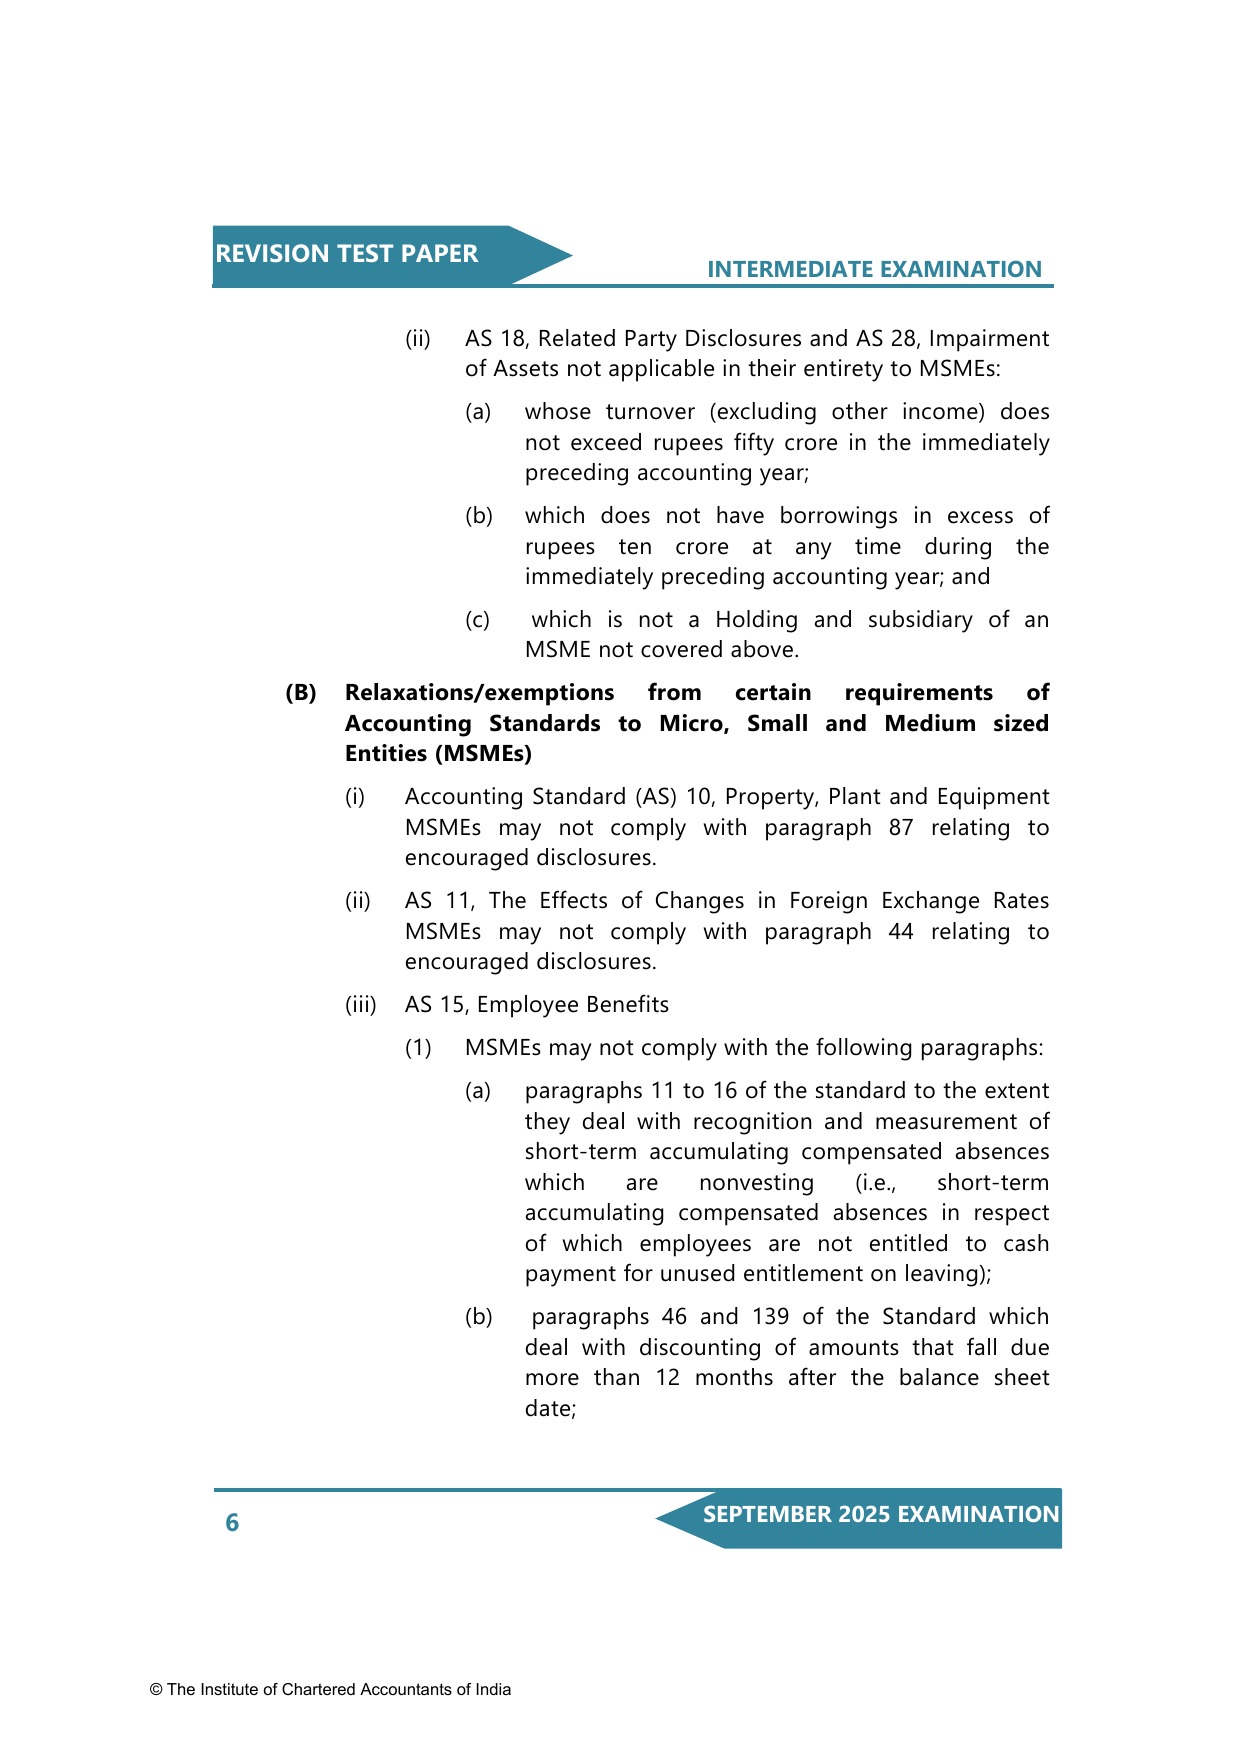
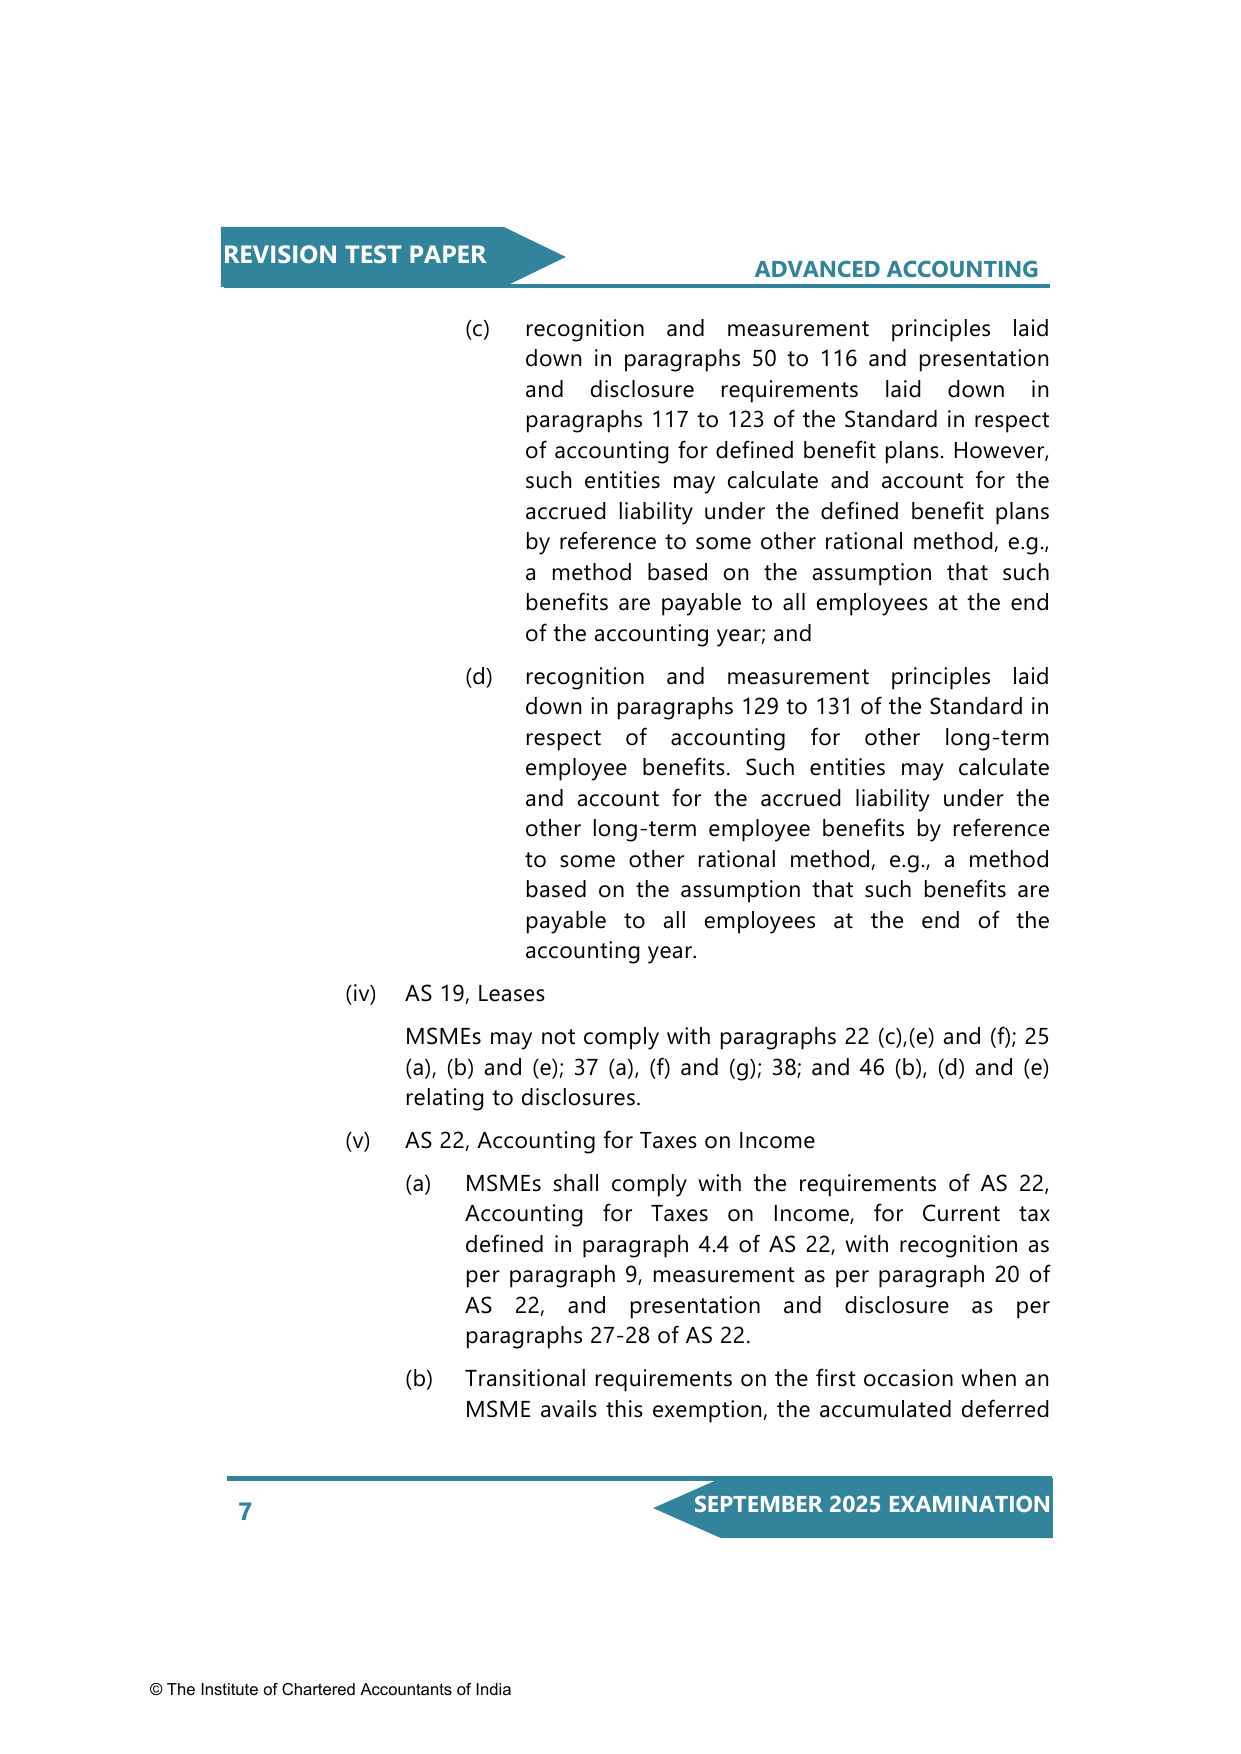
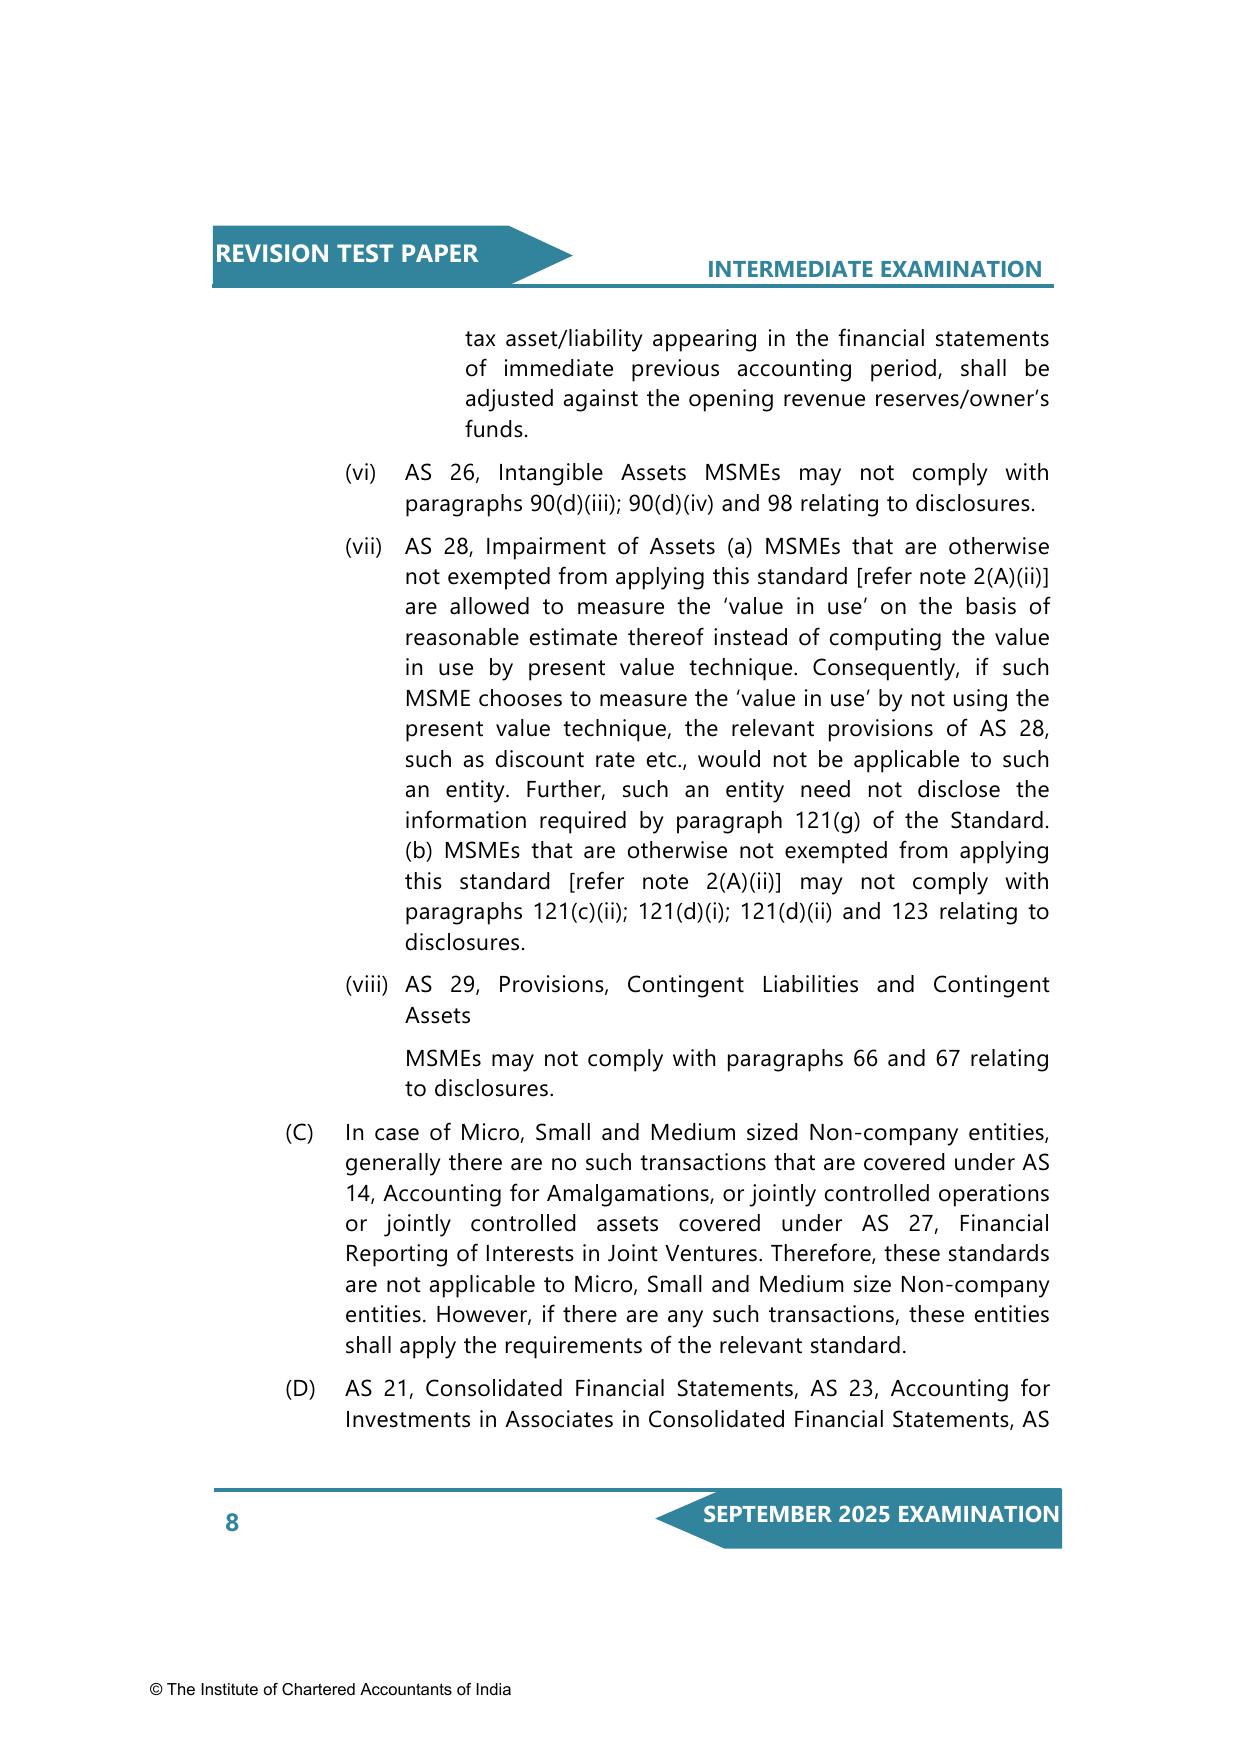
4. Certain exemptions/relaxations have been provided to Micro, Small and Medium sized Entity (MSMEs). Applicability of Accounting Standards and exemptions/relaxations to such entities are given in Annexure 1.
5. This Announcement supersedes the earlier Announcement of the ICAI on ‘Criteria for classification of Non-company entities for applicability of Accounting Standards issued in March 20211.
6. This Announcement is not relevant for Non-company entities which may be required to follow Indian Accounting Standards (Ind 1 The said announcement was hosted on ICAI website on March 31, 2021 and published in ‘The Chartered Accountant’, May 2021 and it superseded the earlier announcement of the ICAI on ‘Harmonisation of various differences between the Accounting Standards issued by the ICAI and the Accounting Standards notified by the Central Government’ issued in February 2008, to the extent it prescribed…
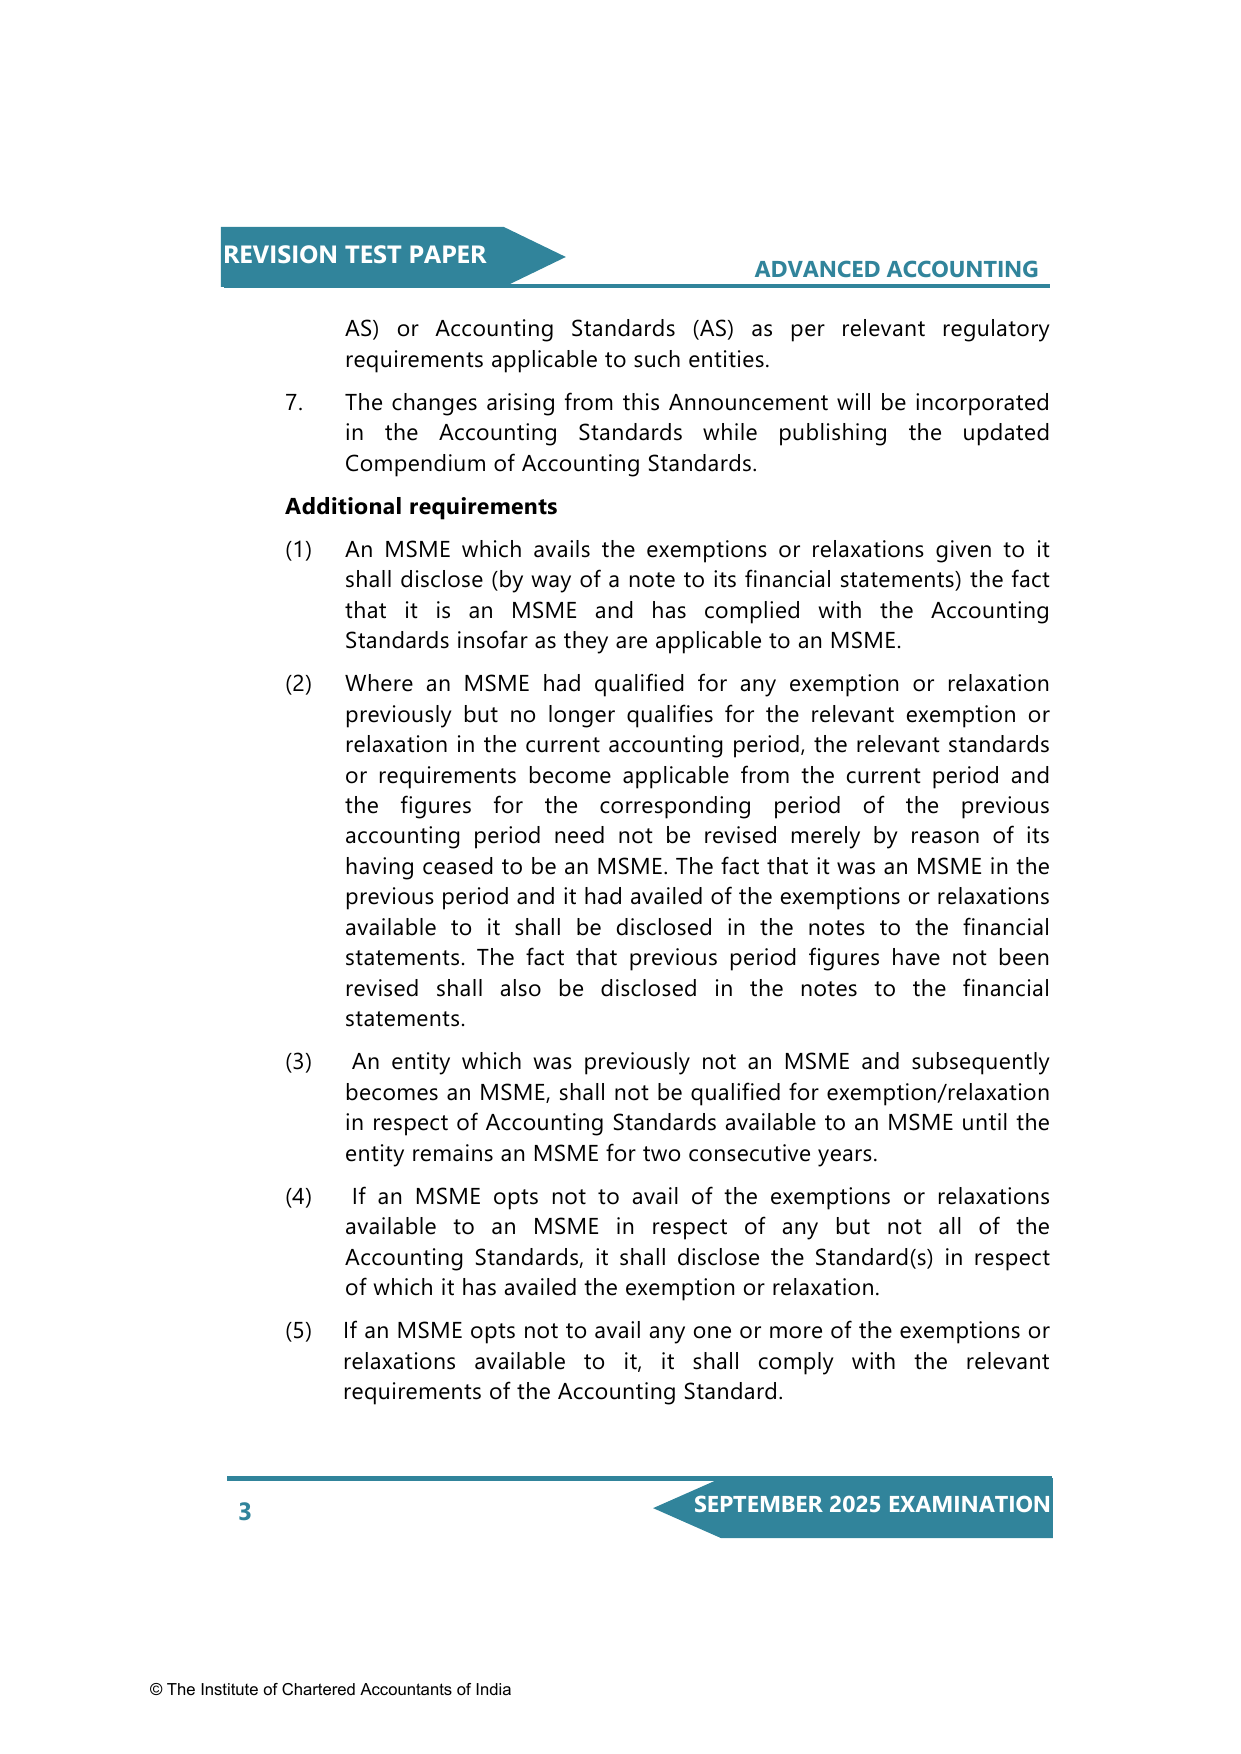
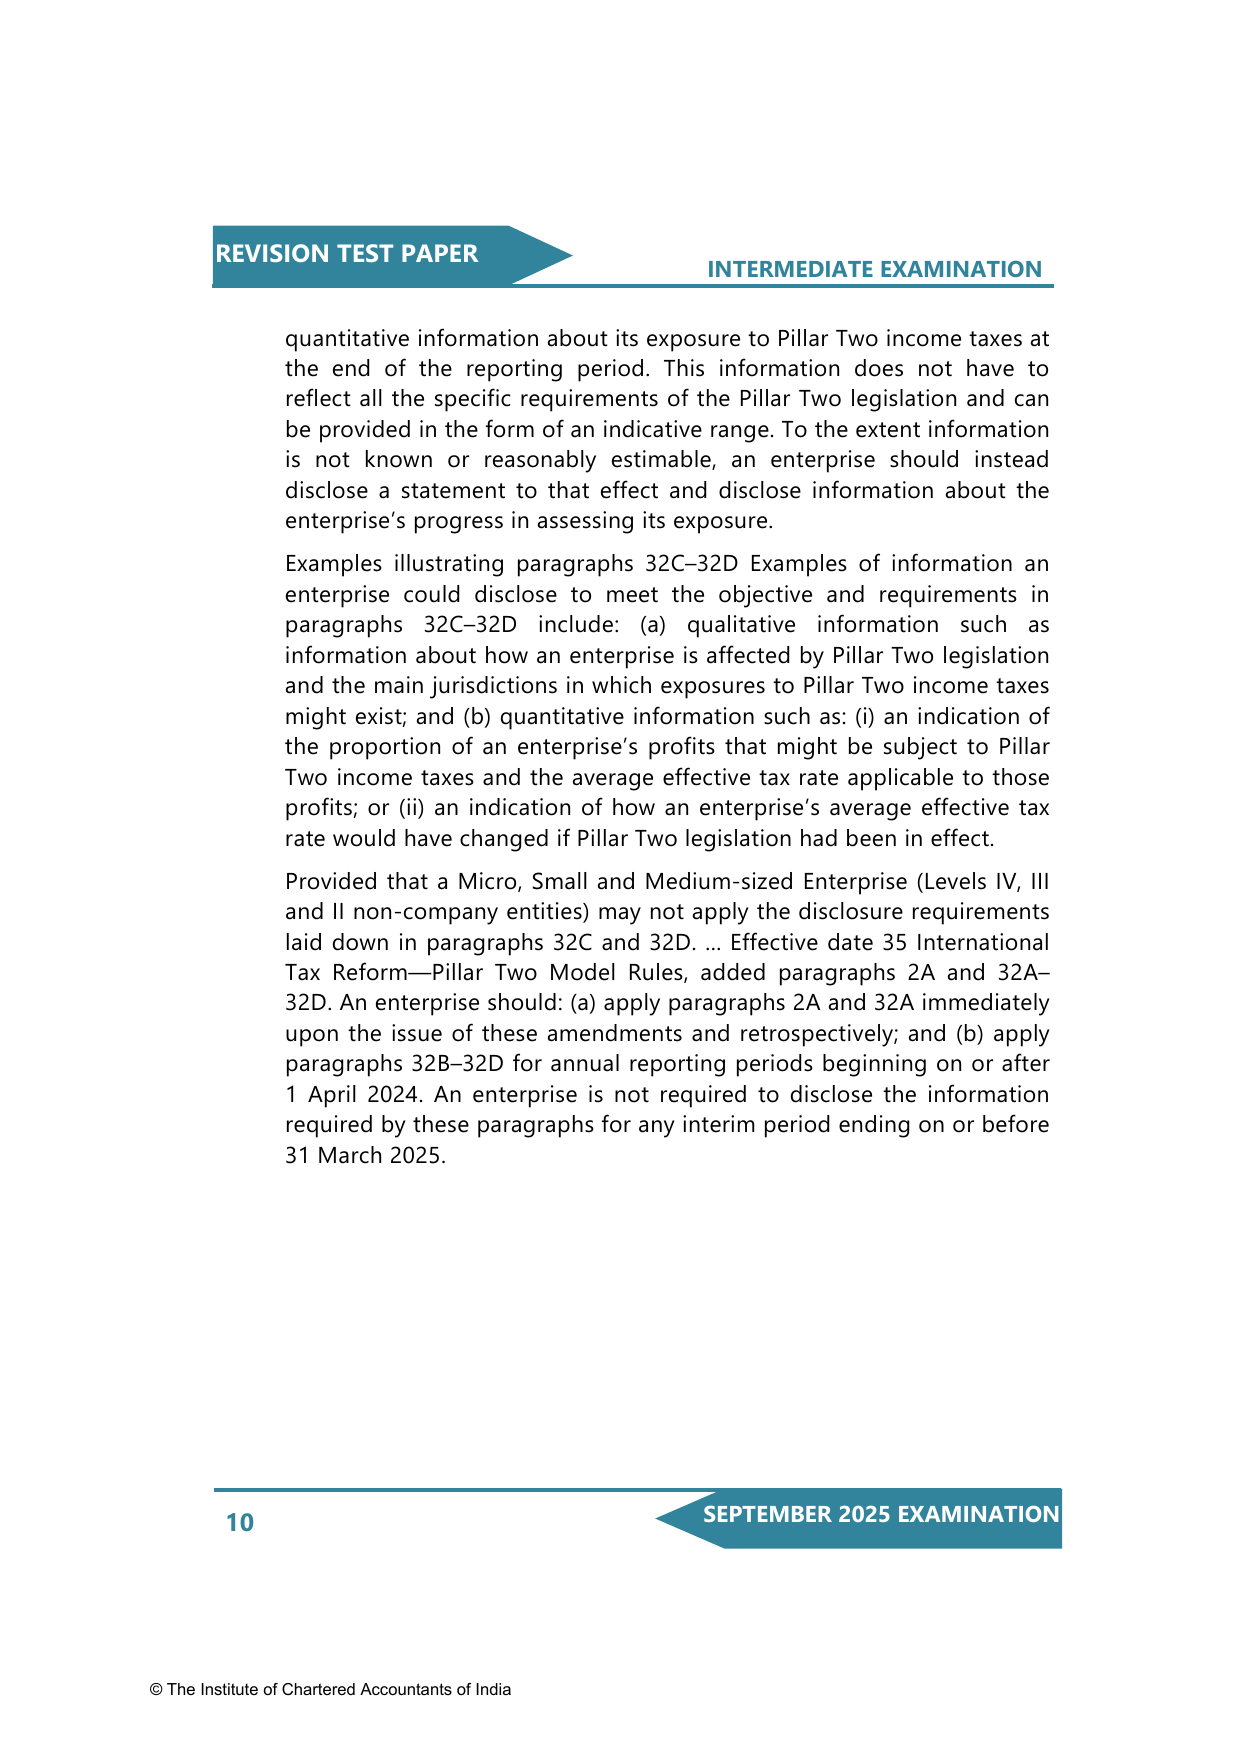
7. The changes arising from this Announcement will be incorporated in the Accounting Standards while publishing the updated Compendium of Accounting Standards. Additional requirements (1) An MSME which avails the exemptions or relaxations given to it shall disclose (by way of a note to its financial statements) the fact that it is an MSME and has complied with the Accounting Standards insofar as they are applicable to an MSME. (2) Where an MSME had qualified for any exemption or relaxation…
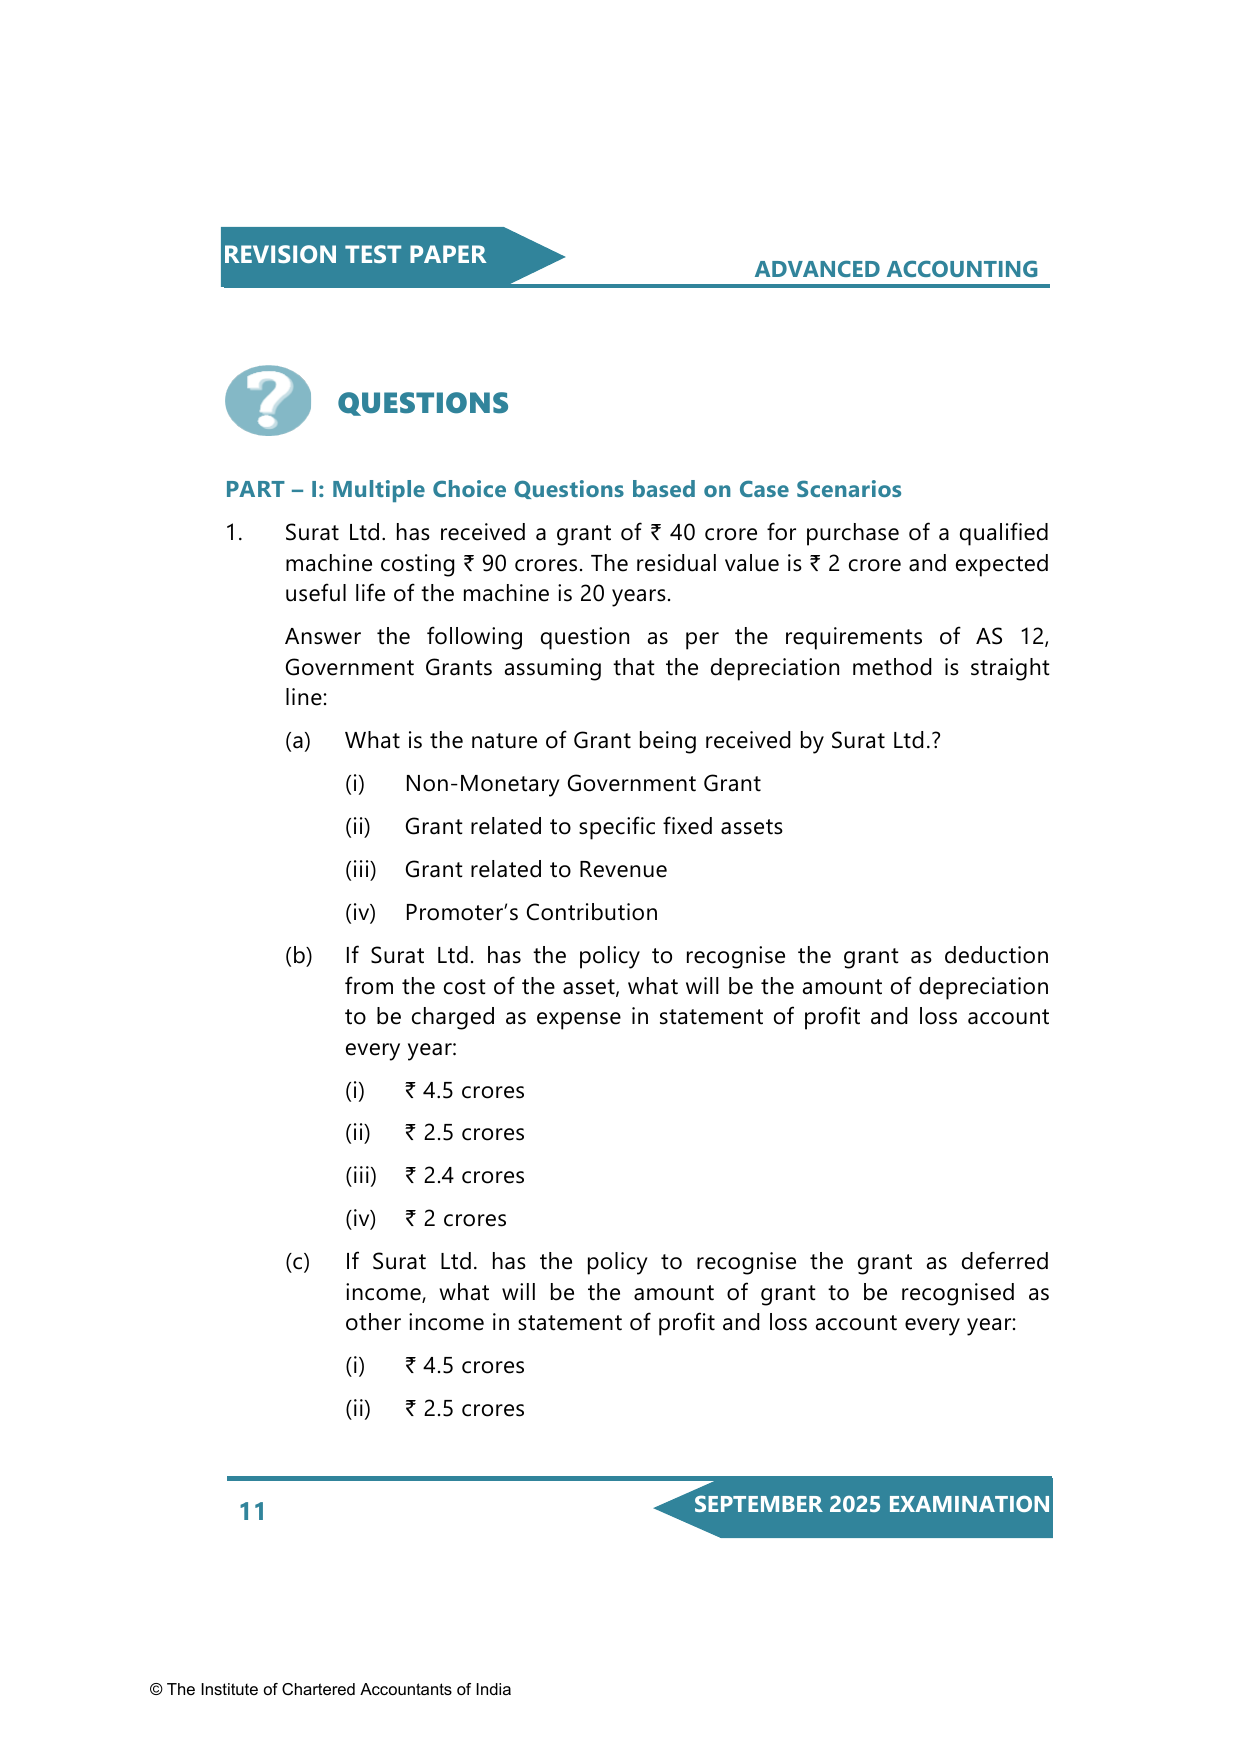
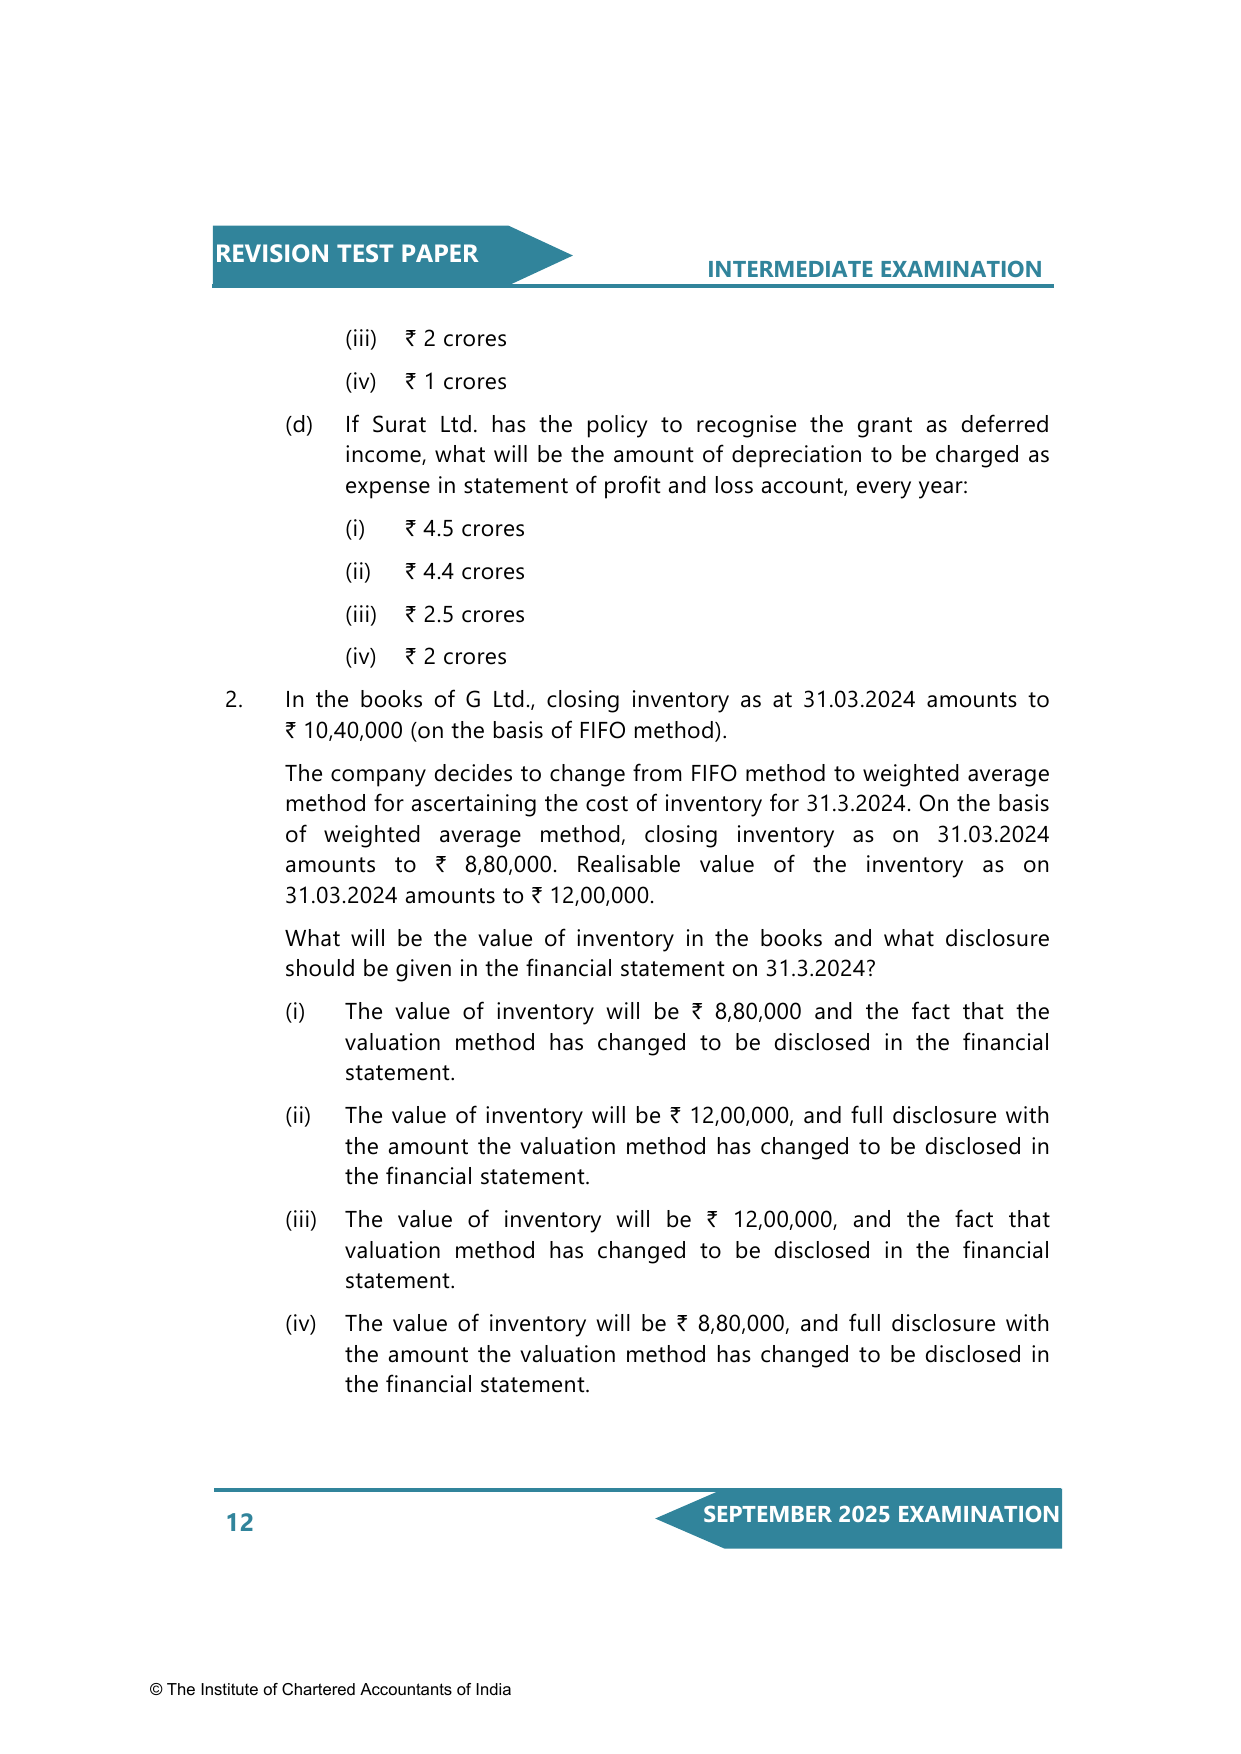
1. Surat Ltd. has received a grant of % 40 crore for purchase of a qualified machine costing ₹90 crores. The residual value is ₹2 crore and expected useful life of the machine is 20 years. Answer the following question as per the requirements of AS 12, Government Grants assuming that the depreciation method is straight line: (a) | What is the nature of Grant being received by Surat Ltd.? (i) Non-Monetary Government Grant (ii) Grant related to specific fixed…
Question previews auto-extracted from the official ICAI paper. Full scanned pages below.
Practice Advanced Accounting MCQs — free
Reinforce this paper with chapter-wise multiple-choice questions and a timed mock test for CA Inter Advanced Accounting, based on the ICAI Study Material.
Question Paper
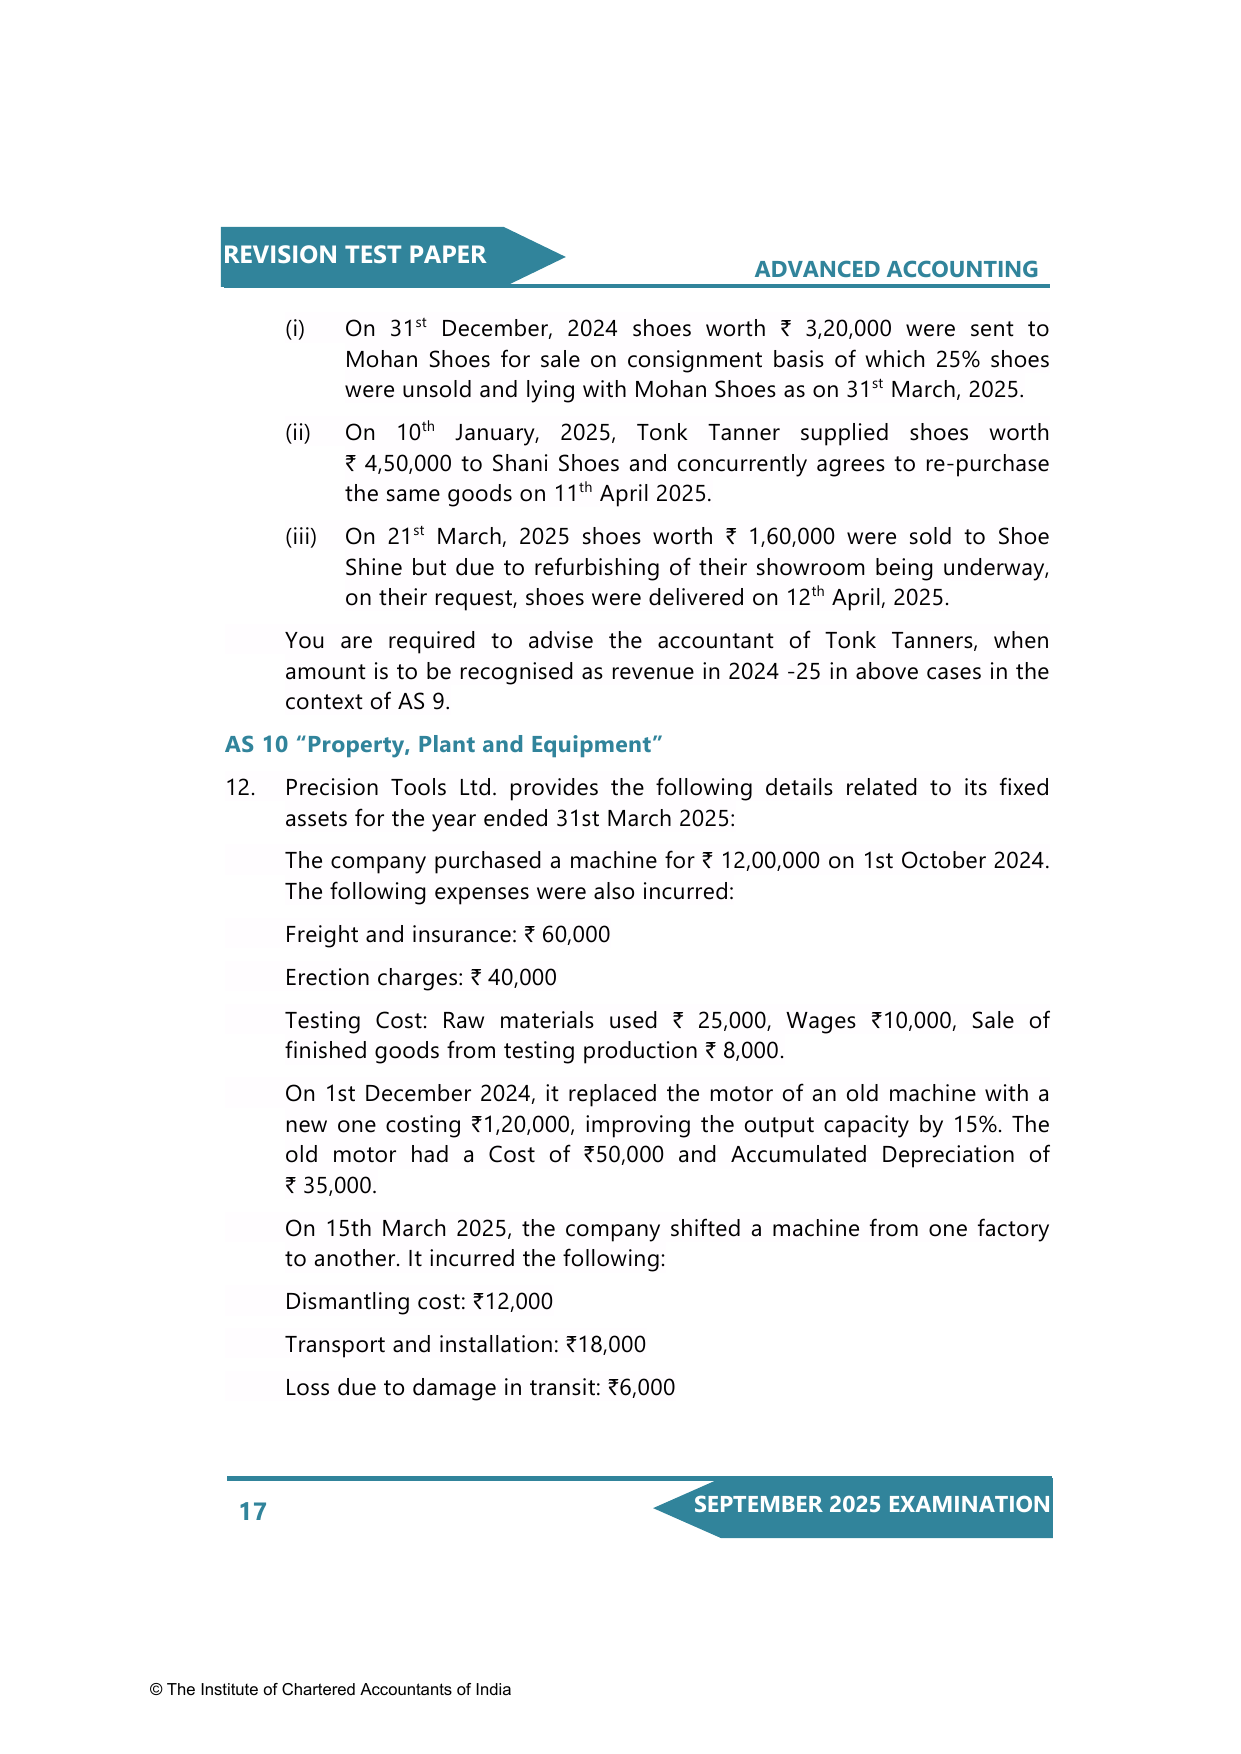
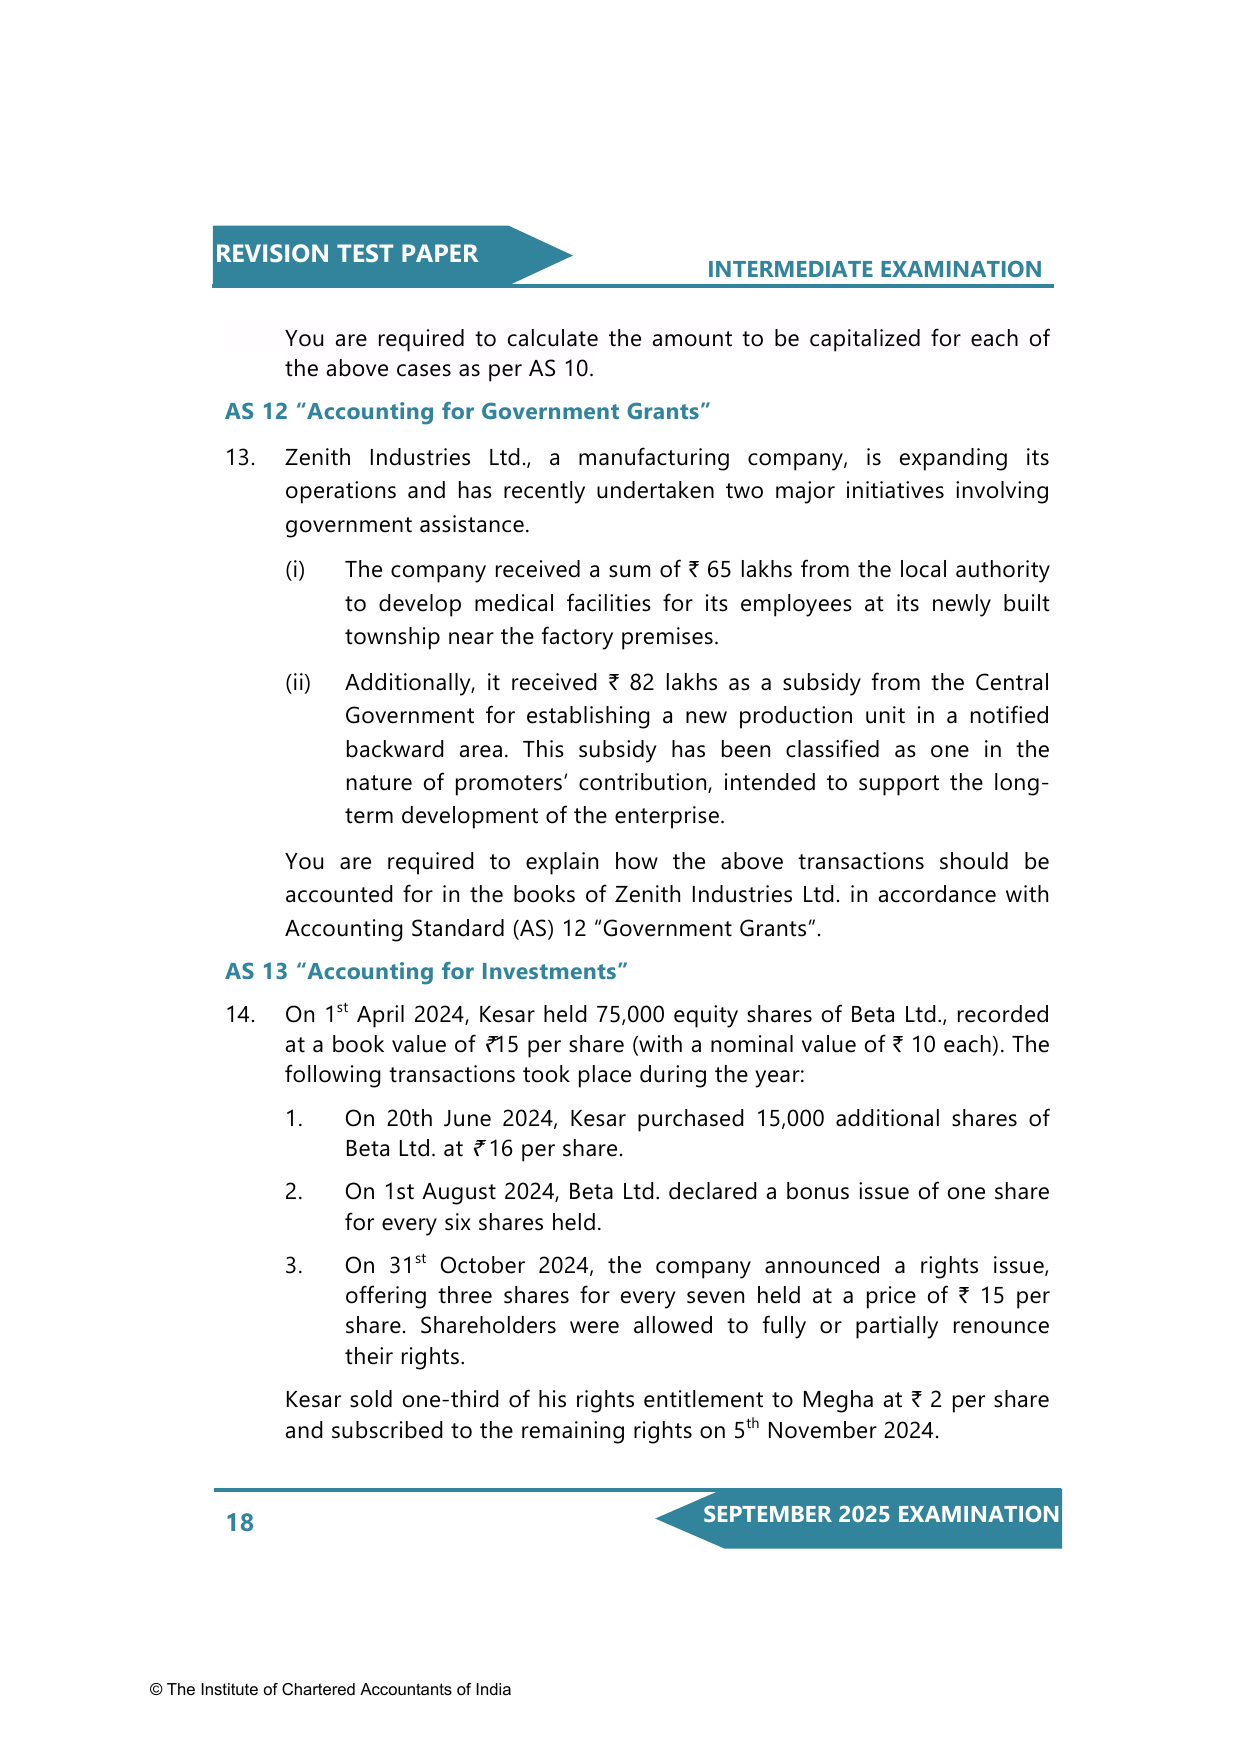
Question Paper
Answer
Answer not available
Related Papers
Get Notified About New Papers